Latest from BCA Research
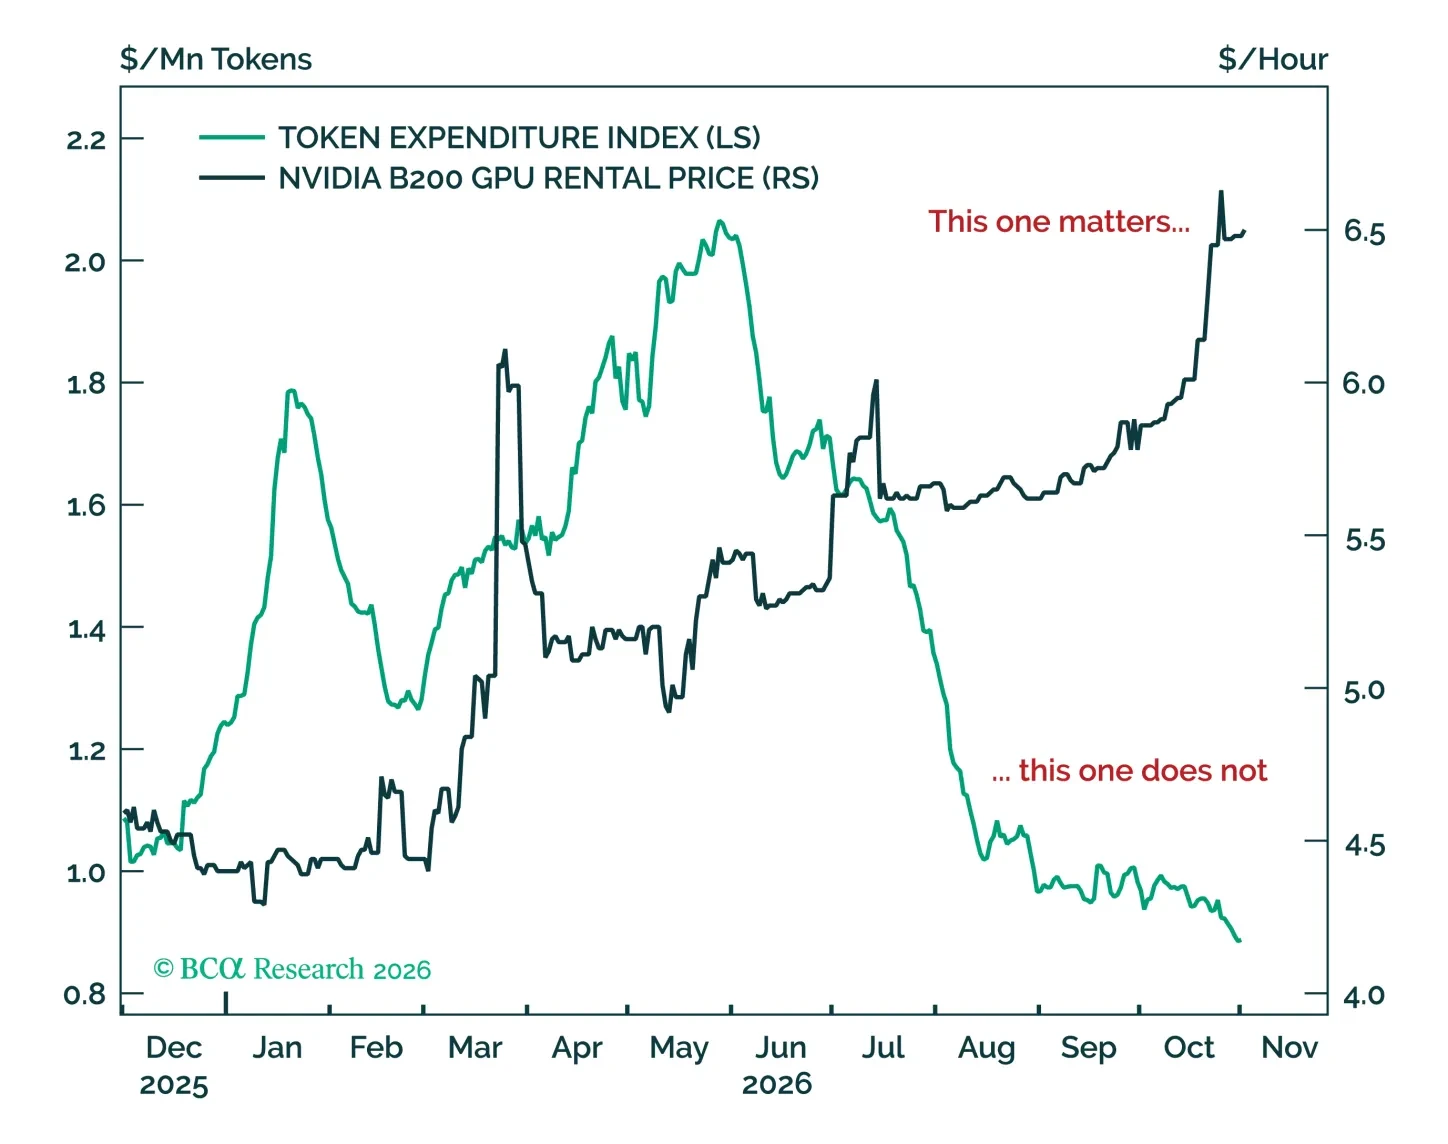
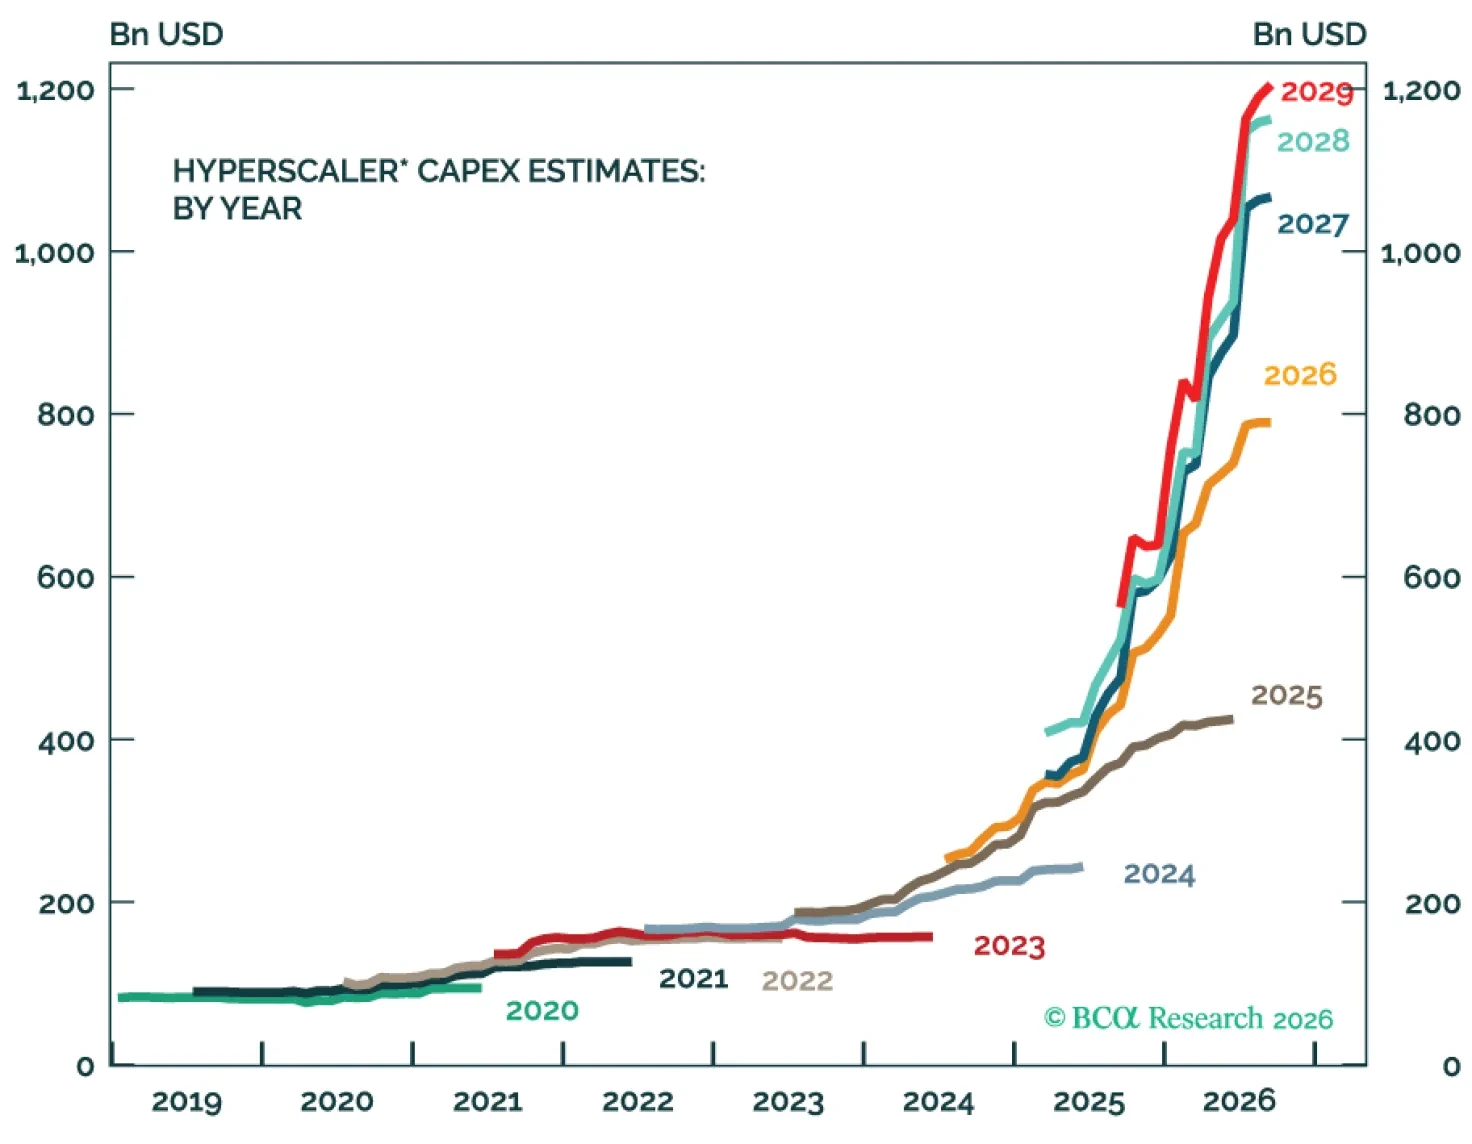
October has been a bad month for equities — particularly AI/tech ones — and a great month for oil. We do not think that the AI supercycle is ending, it has more room to go. Token price decline is a sign of a price war between LLMs, not a decline in demand. In fact, that price war is what is driving datacenter profitability, which is what the bull market is actually based on. As such, what matters on a tactical time horizon is whether Trump capitulates on Iran. If he does not, the market will have to correct. We take the bullish side and expect oil prices to decline imminently, forcing a short squeeze and powering equities higher.
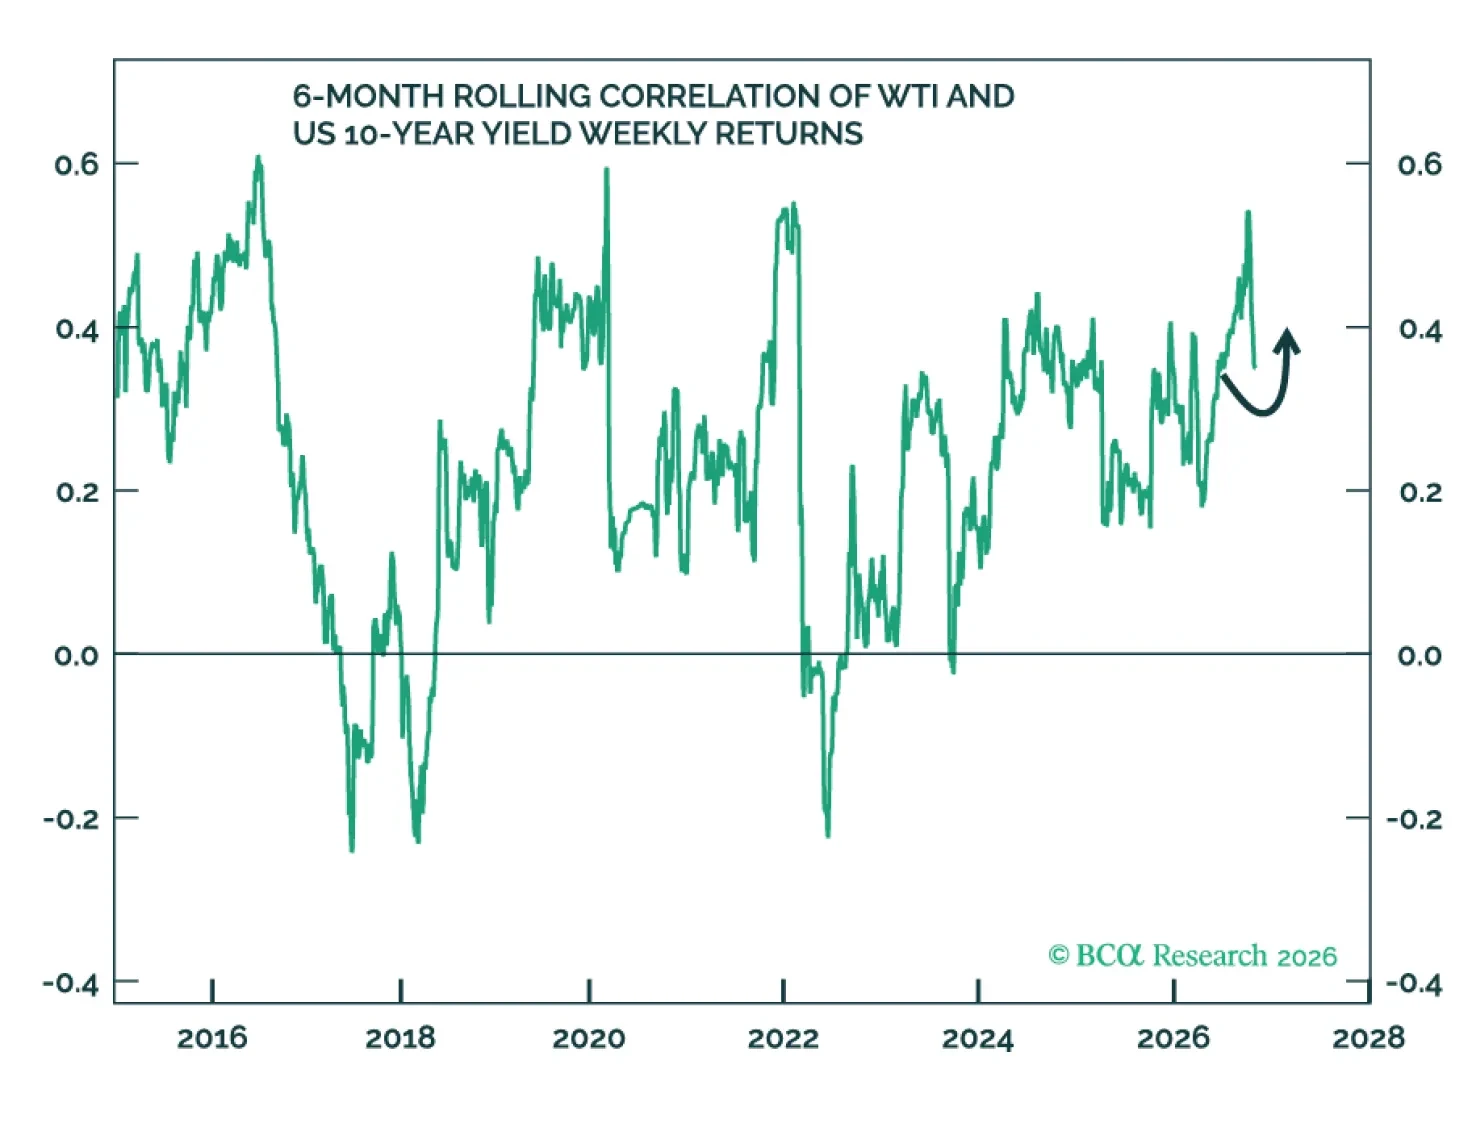
Democrats look to be clinching a Senate victory in the final day of the campaign, but Iran, not the Senate, poses the real risk.
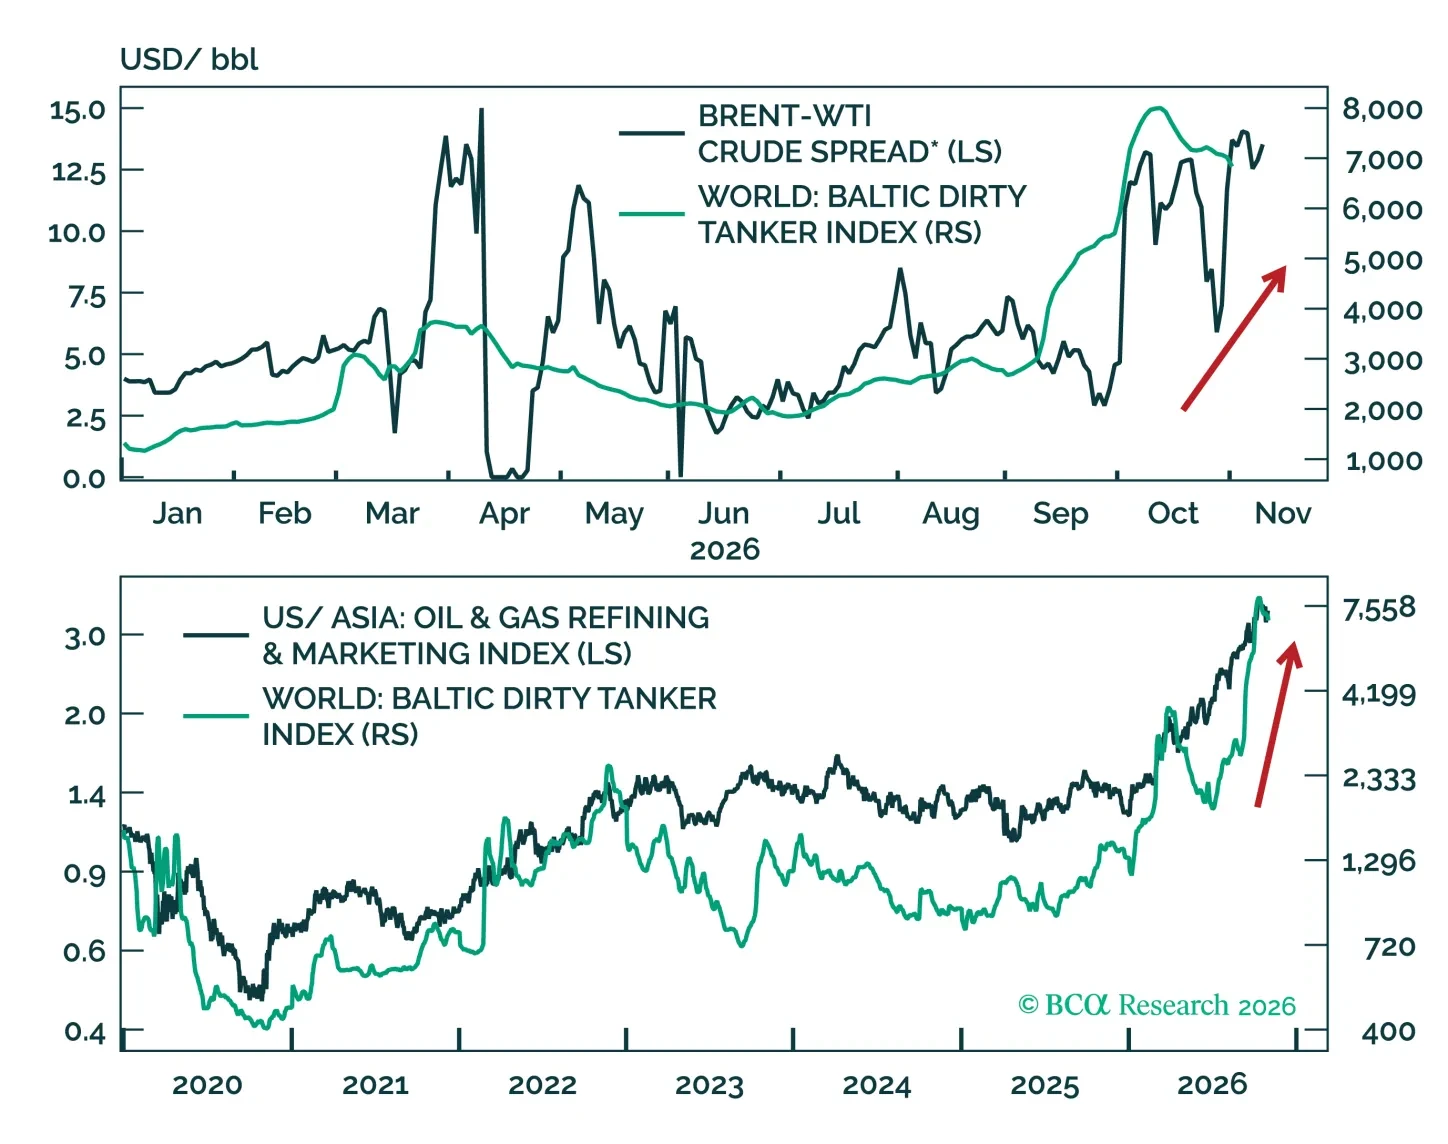
Commodities have diverged sharply in recent months. We explain why energy prices are likely to stay elevated after the US midterms, why gold’s slide should prove limited, and how we are positioning for the months ahead.
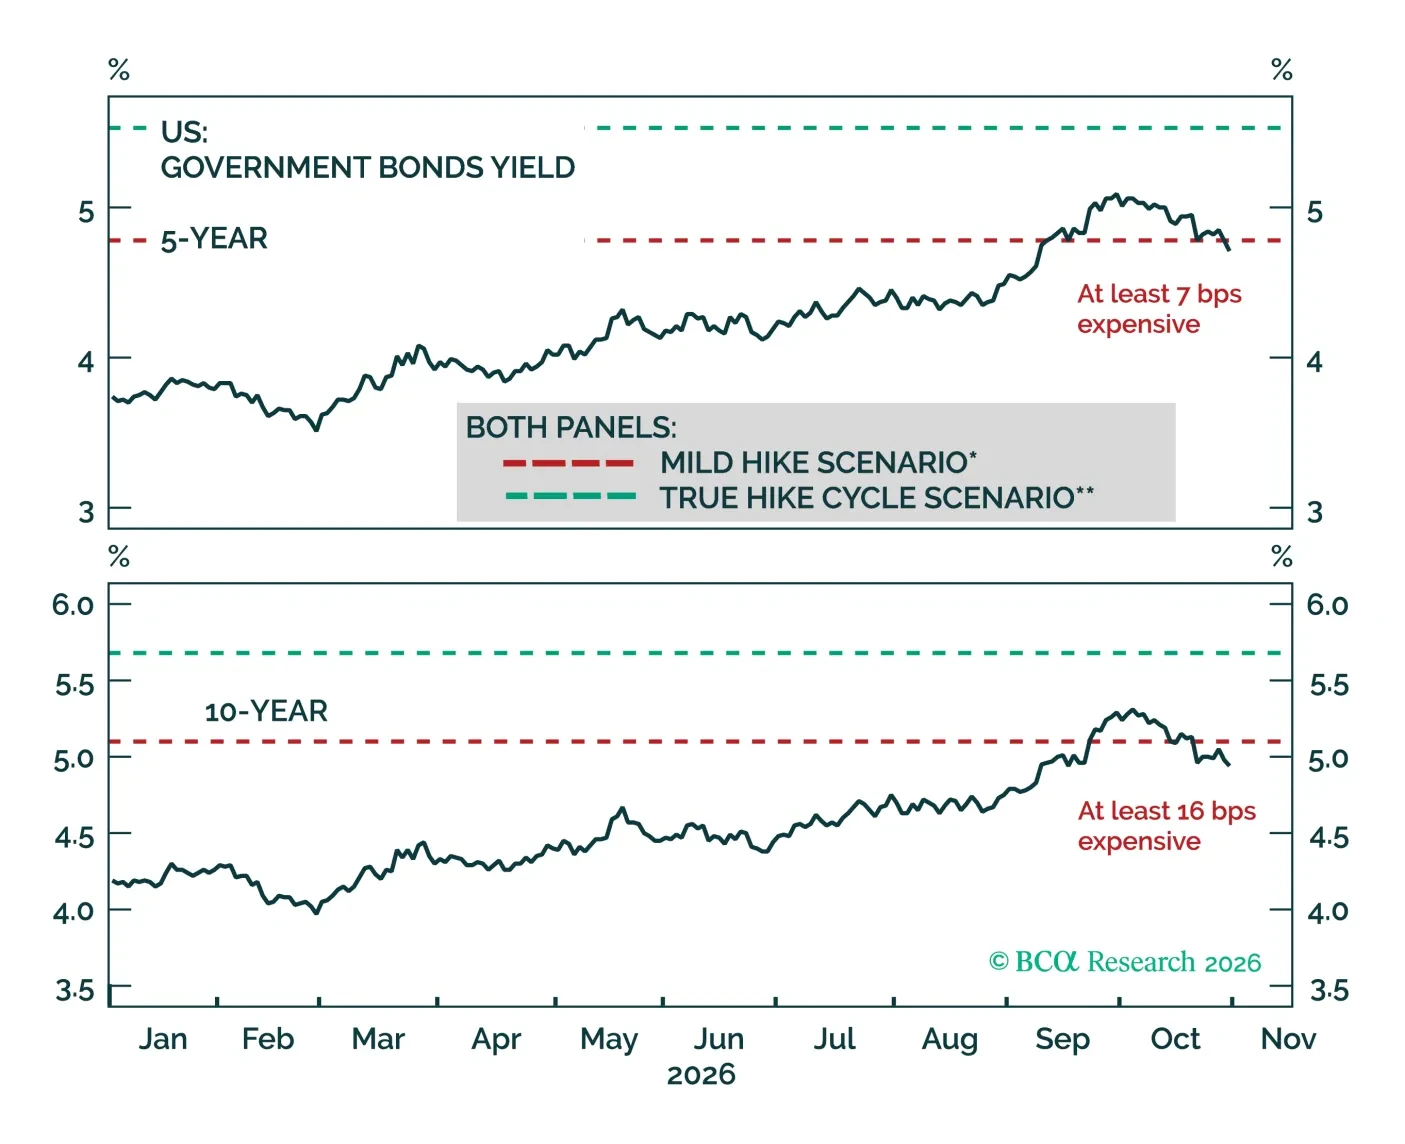
US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.
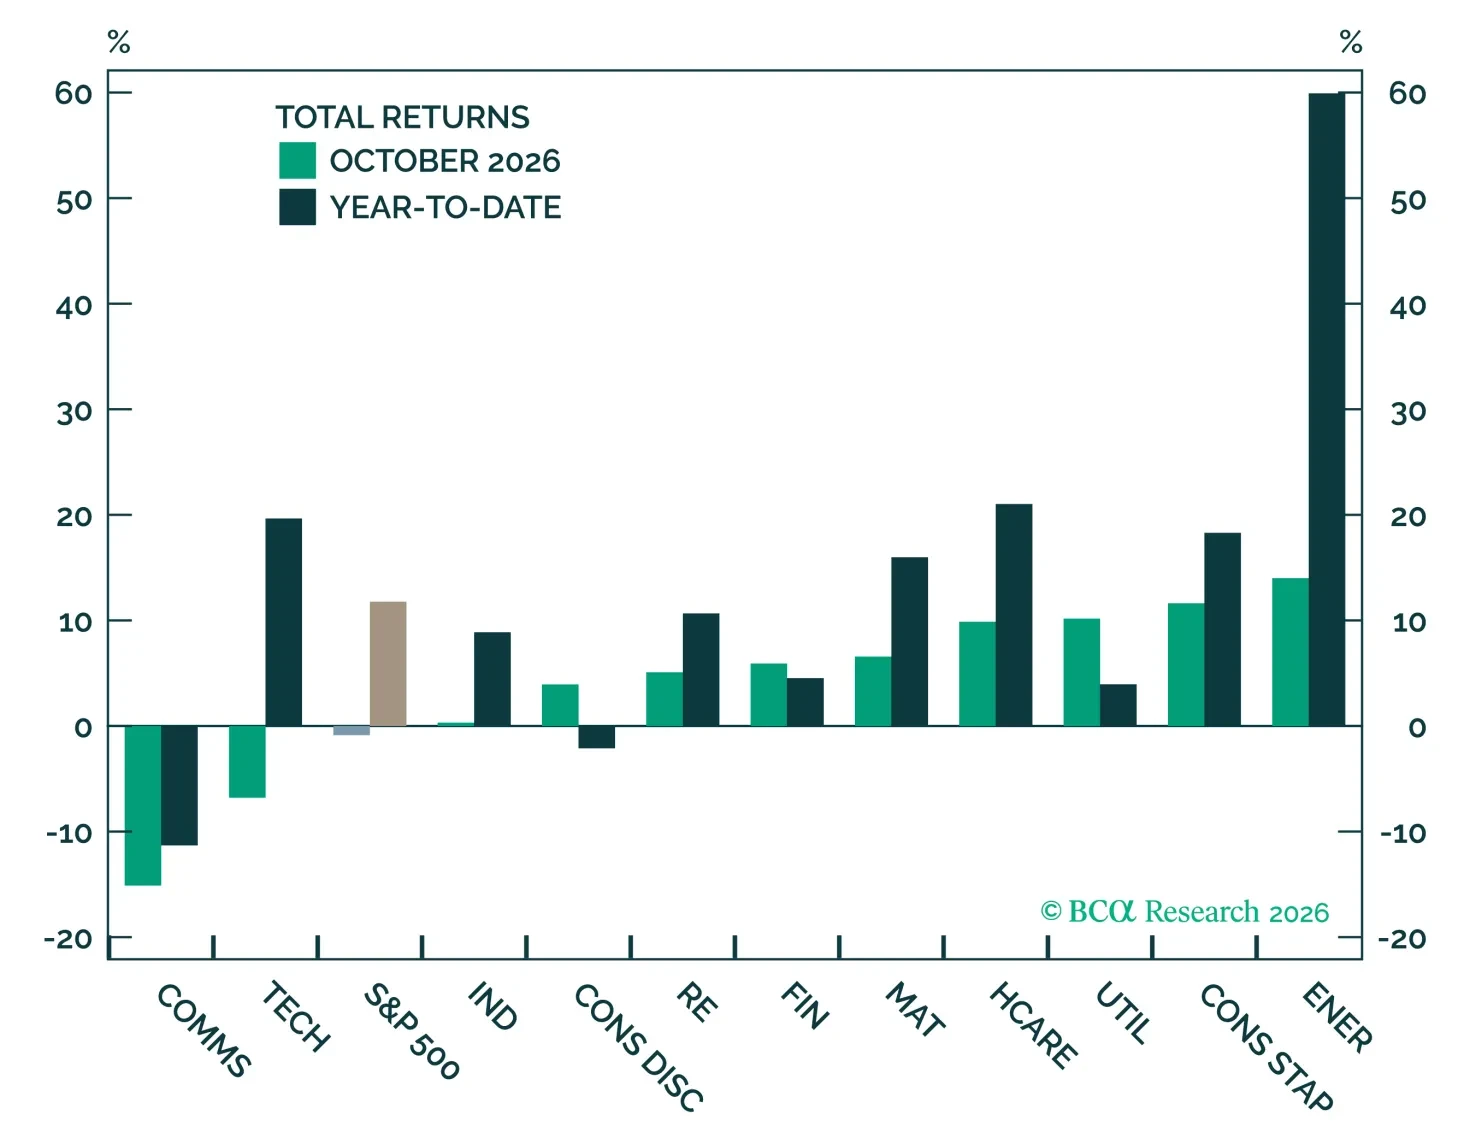
October saw a 0.9% decline in the S&P 500, dragged lower by Communication Services (-15.1%) and Information Technology (-6.8%). All other sectors delivered positive returns, led by traditional defensives – Health Care (+9.9%), Utilities (+10.2%), Consumer Staples (+11.6%) – and Energy (+14.0%). Although our overweight Tech call surrendered some performance during the month, IT has still gained 37% since the view was initiated on March 30, outpacing the S&P 500’s 20% advance.
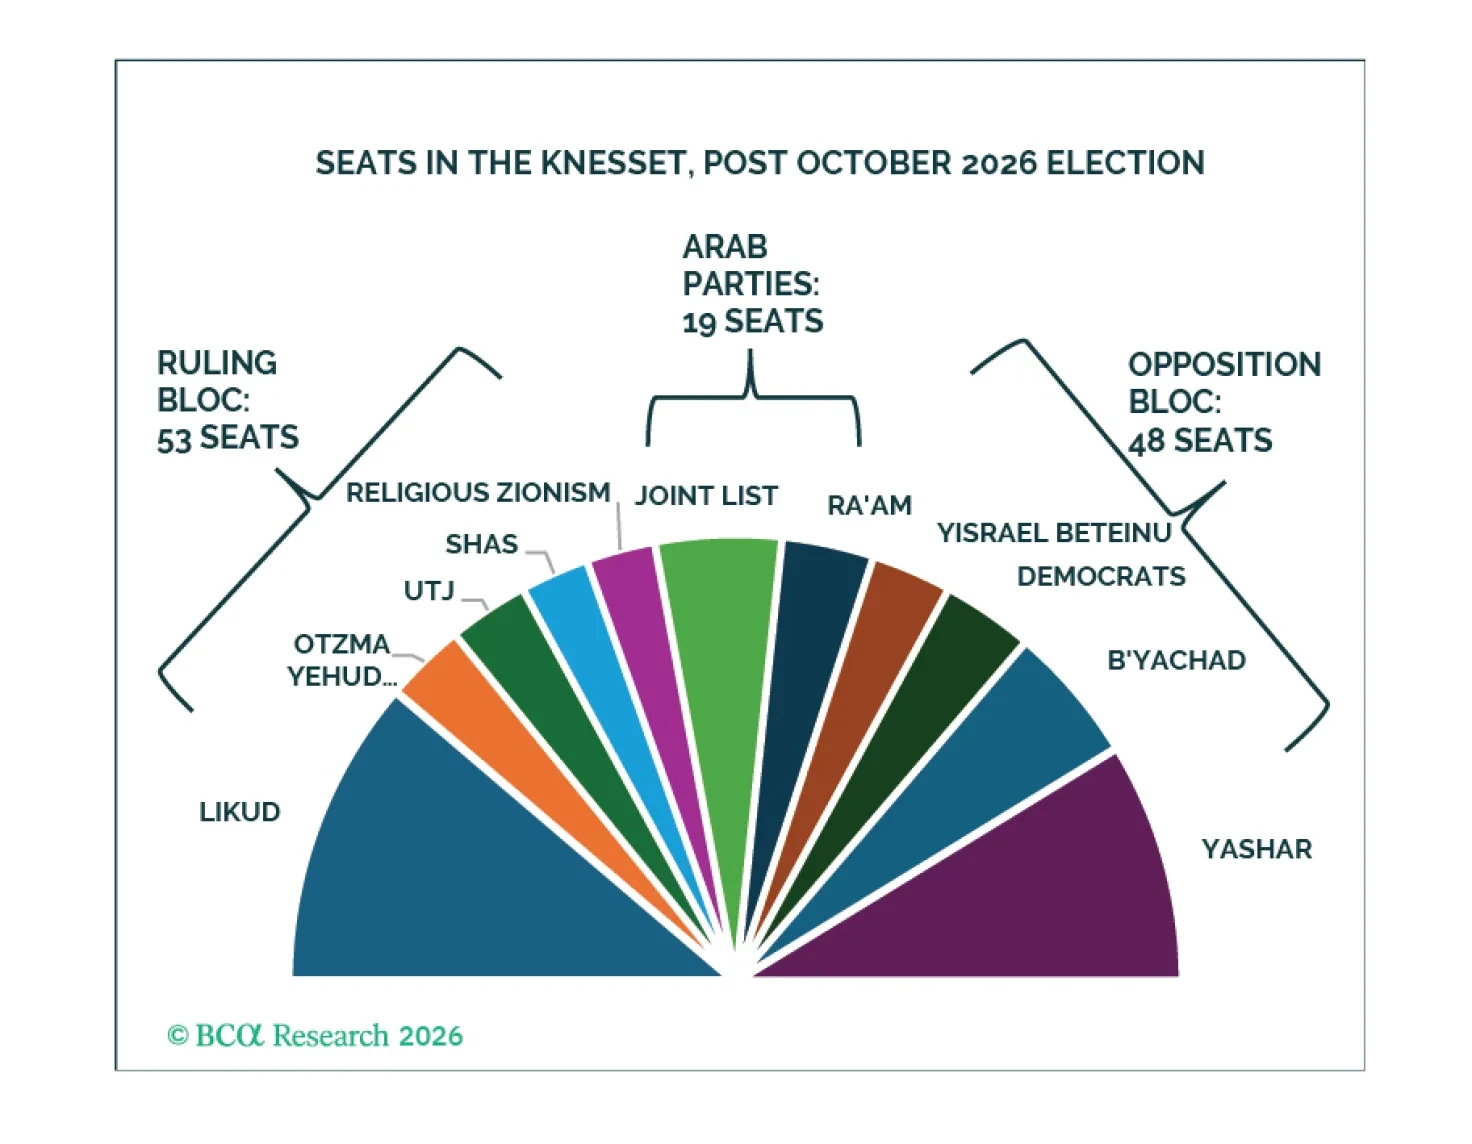
Another Netanyahu-led government would raise the risk of Israeli escalation and a major oil supply shock, while an opposition victory would reduce, but not eliminate, this risk due to its greater coordination with and deference to the US.
Despite October’s AI selloff, indices remain resilient thanks to historically high dispersion. We remain bullish, but with barbells across the portfolio. Hedge equity with equity: Overweight Technology and Healthcare. Remain overweight high yield. Downgrade linkers and upgrade nominal bonds. Upgrade tail risk protection to overweight as a hedge against a resumption of the war.
Today's report examines several of the most interesting ideas we've heard over two weeks of meetings and calls with investors.
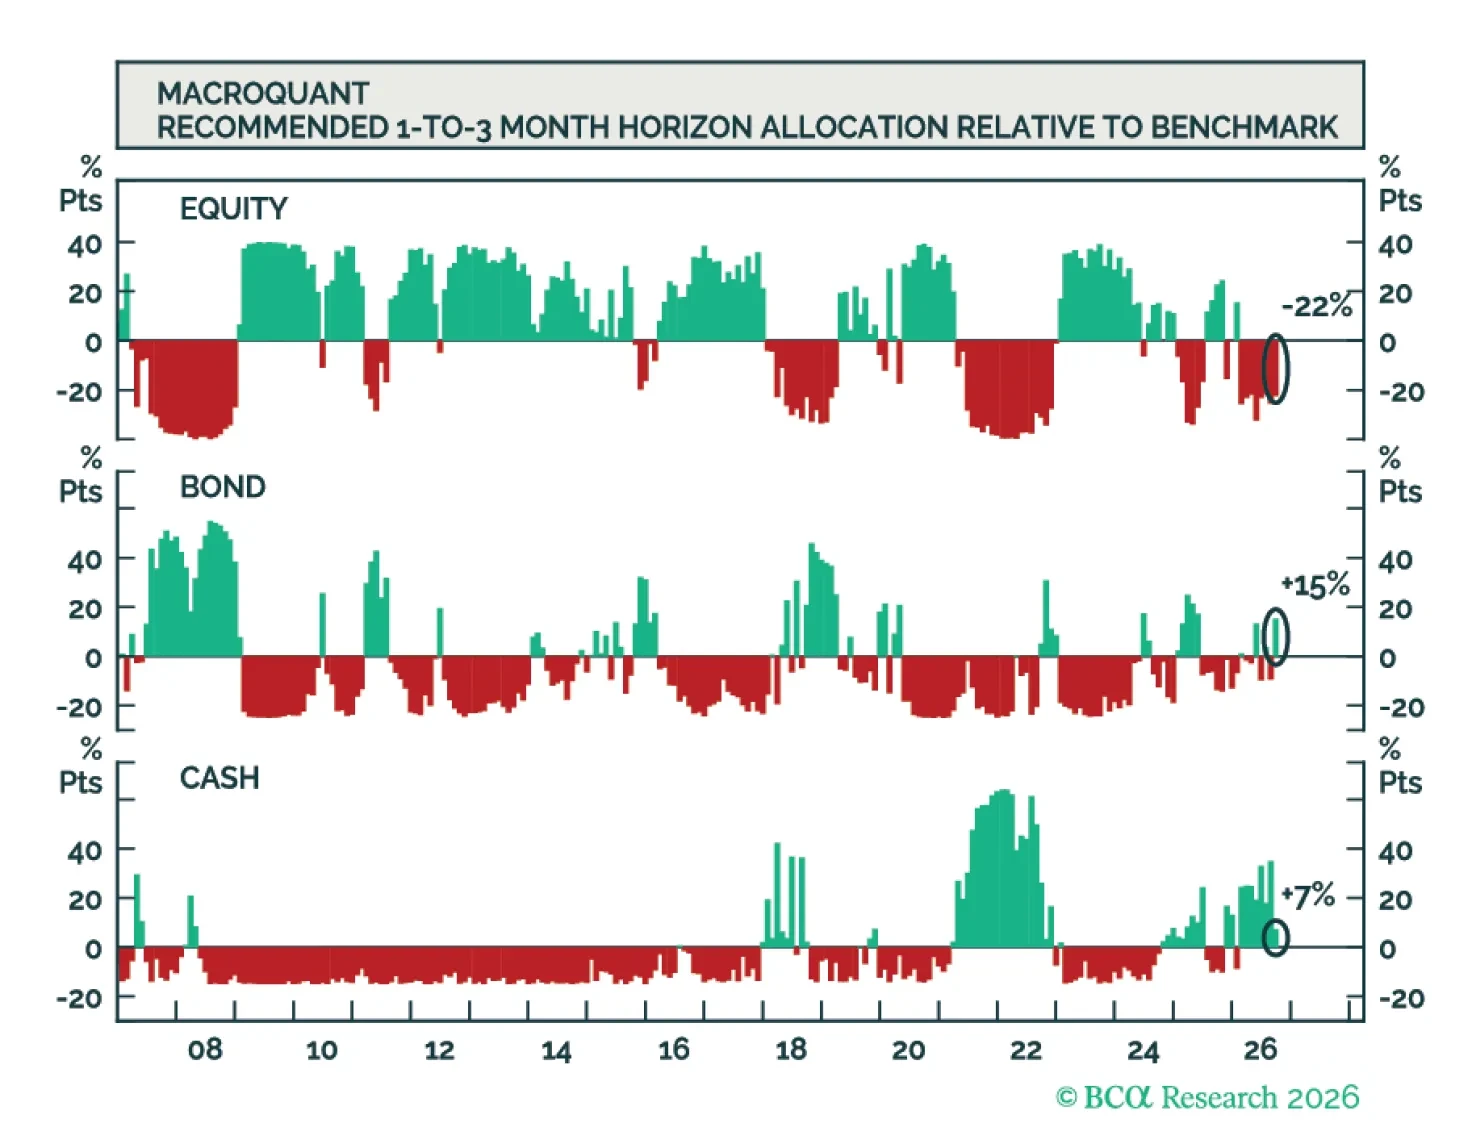
MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.
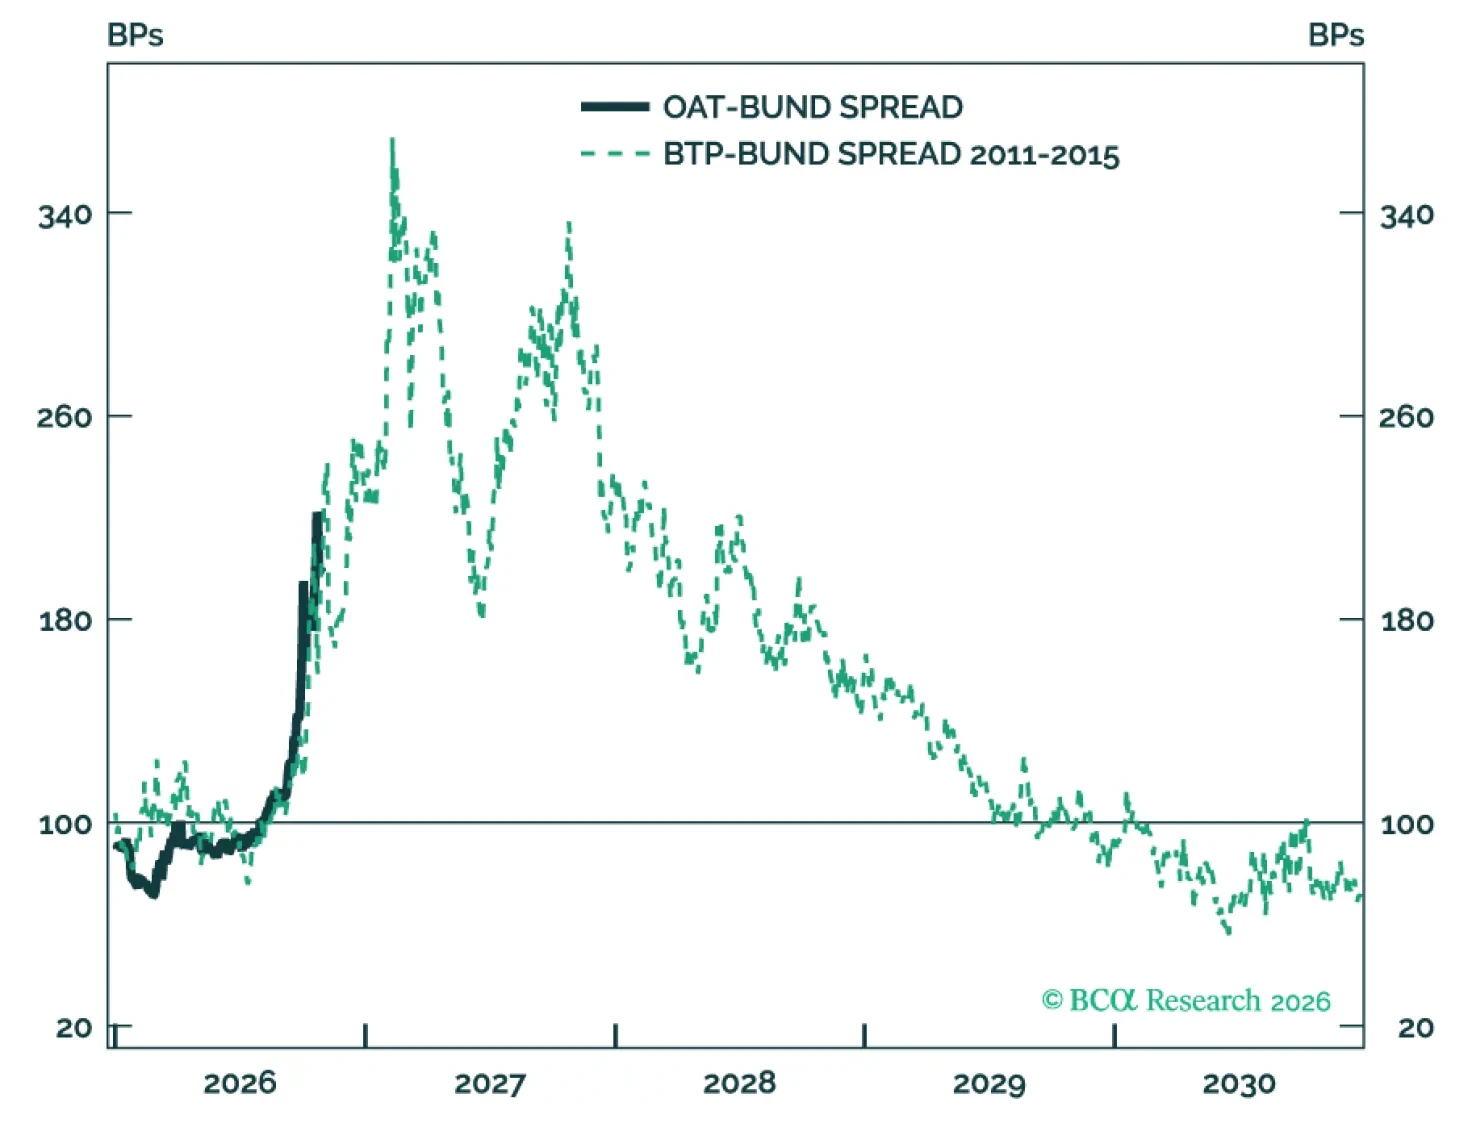
France’s fiscal mess is far from over, but the bond vigilantes may have gotten ahead of themselves. We book profits on short OATs, eyeing another opportunity in early 2027 as election risks resurface. Meanwhile, French equities are too cheap to ignore. We tactically buy on depressed valuations.