Bonds
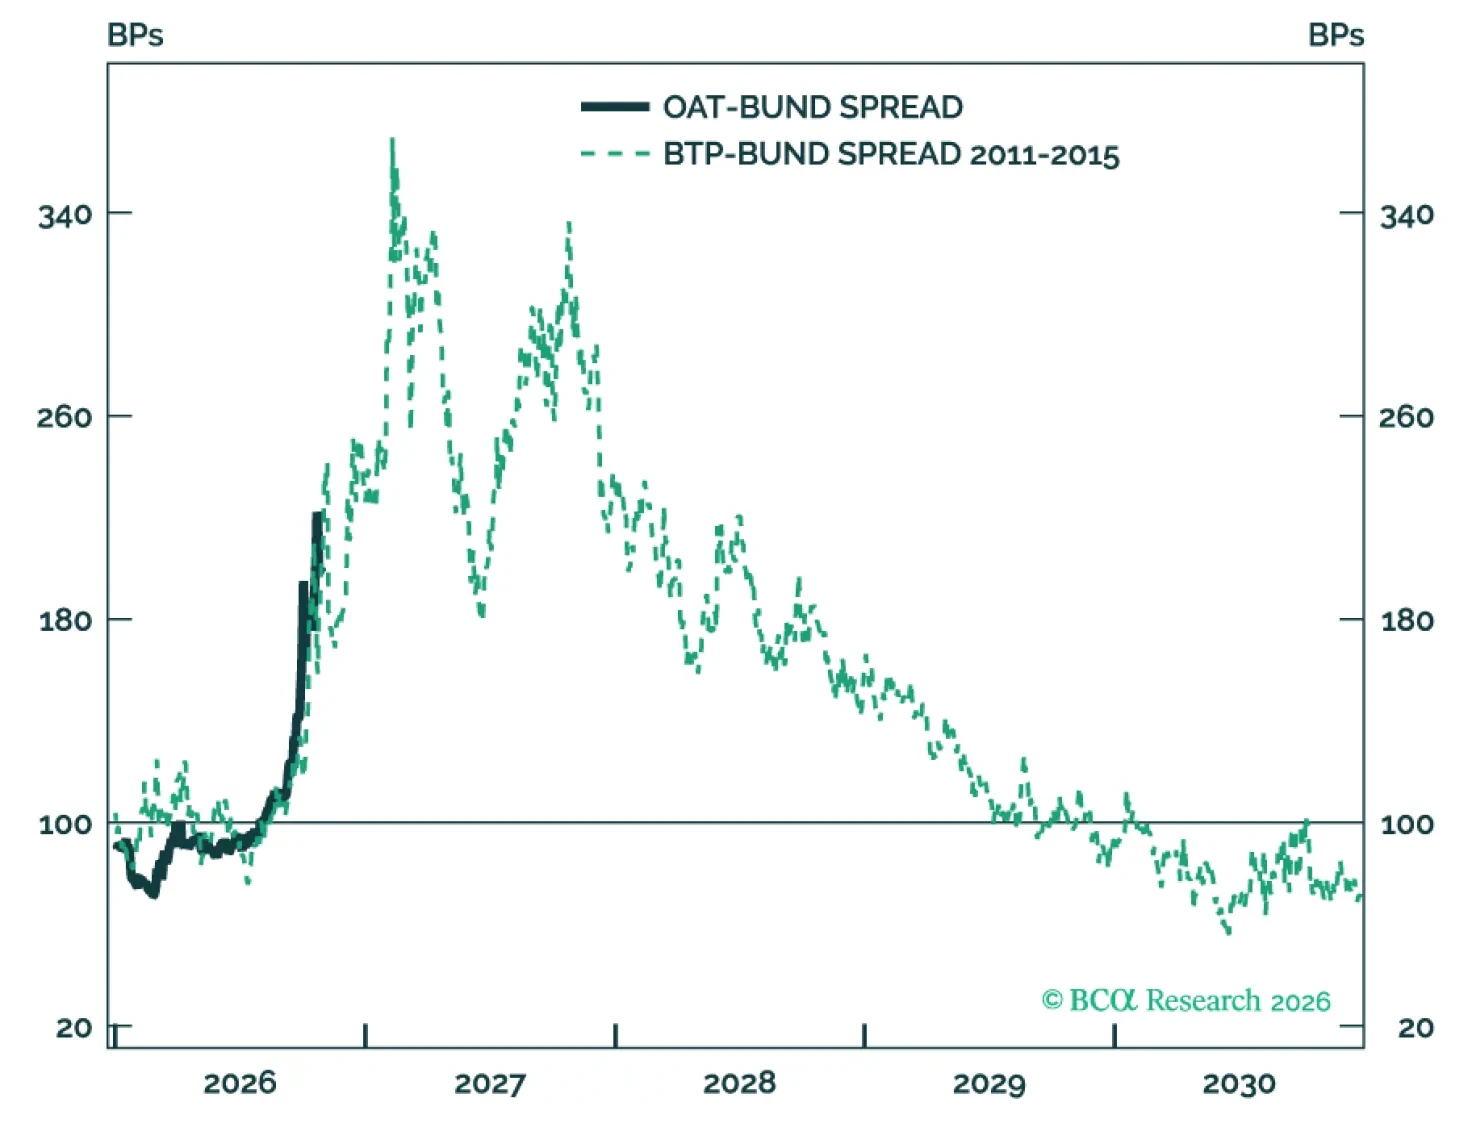
France’s fiscal mess is far from over, but the bond vigilantes may have gotten ahead of themselves. We book profits on short OATs, eyeing another opportunity in early 2027 as election risks resurface. Meanwhile, French equities are too cheap to ignore. We tactically buy on depressed valuations.
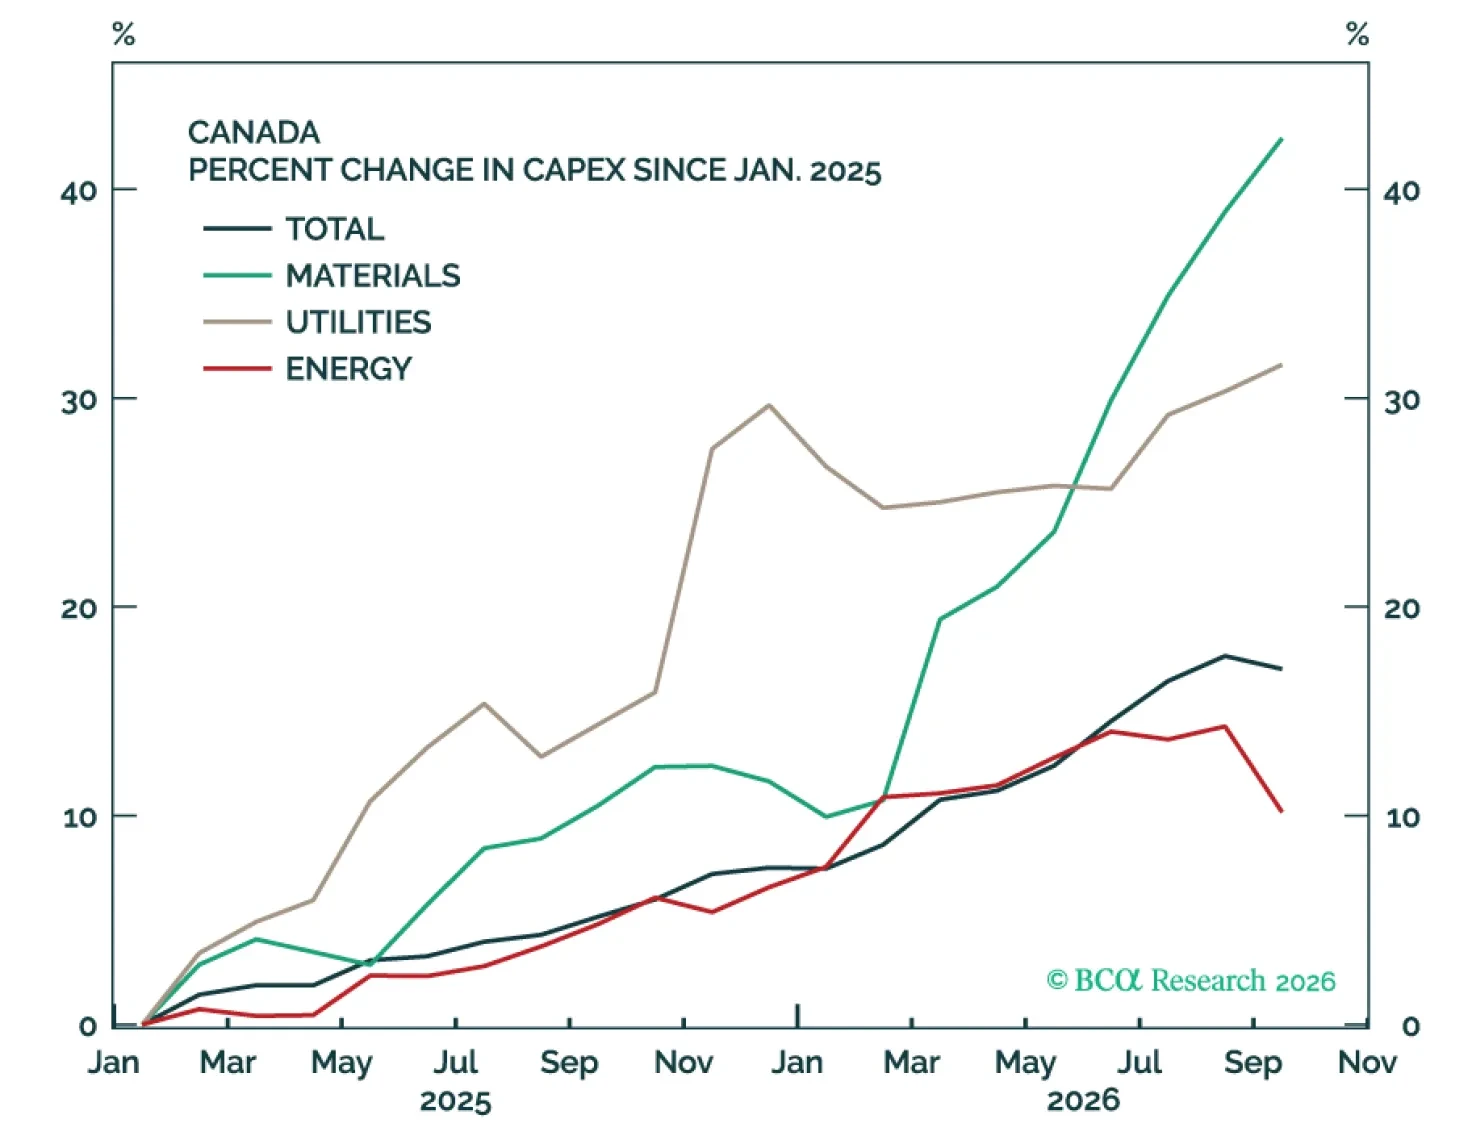
Markets expect the BoC to hike by 100 bps over the next year; we do not. Housing and labor weakness argue for owning Canadian bonds now, while Carney’s reforms and a resource capex wave make the CAD and resource stocks multi-year winners.
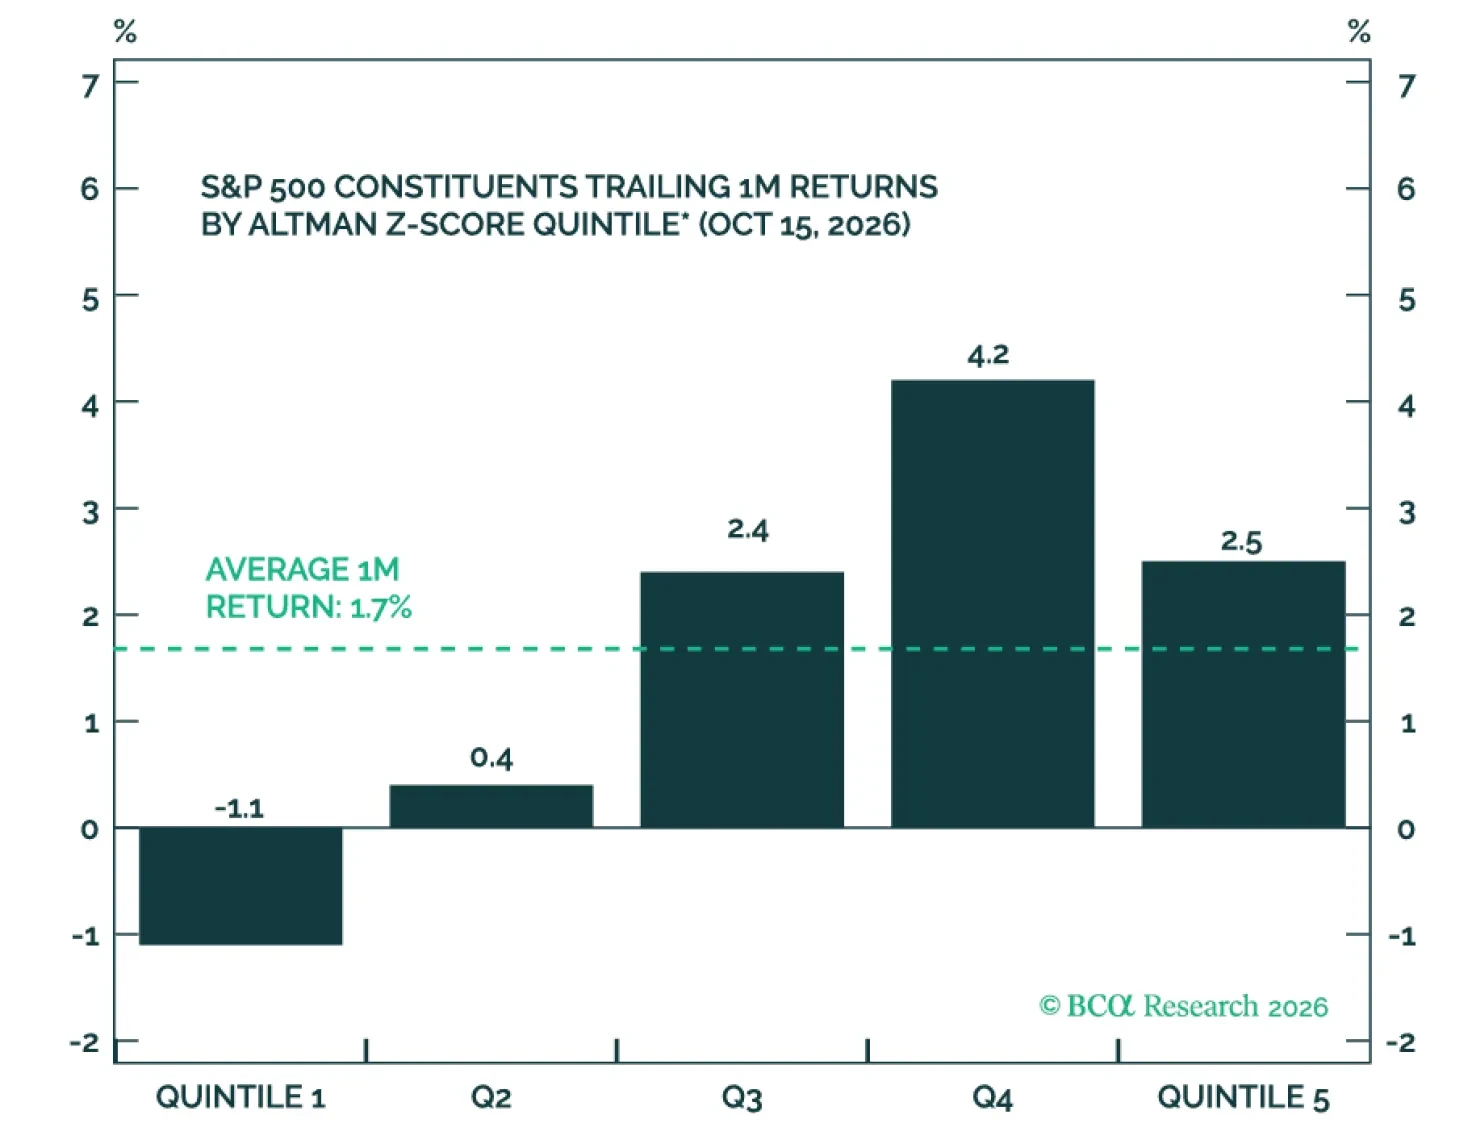
Credit spreads have widened as bond risks intensified, pressuring weak-balance-sheet companies. But the stress is narrow and valuations have already compressed, so equity risks look manageable. Rather than de-risk, we would lean into quality: large over small caps, quality capex, and defensible Tech margins, and look to Q3 earnings for confirmation.
AI capex is supporting the global economy but also generating collateral damage for rate-sensitive sectors such as housing, as well as highly indebted governments. Maintain a benchmark allocation to equities for now and look to get more defensive next year.
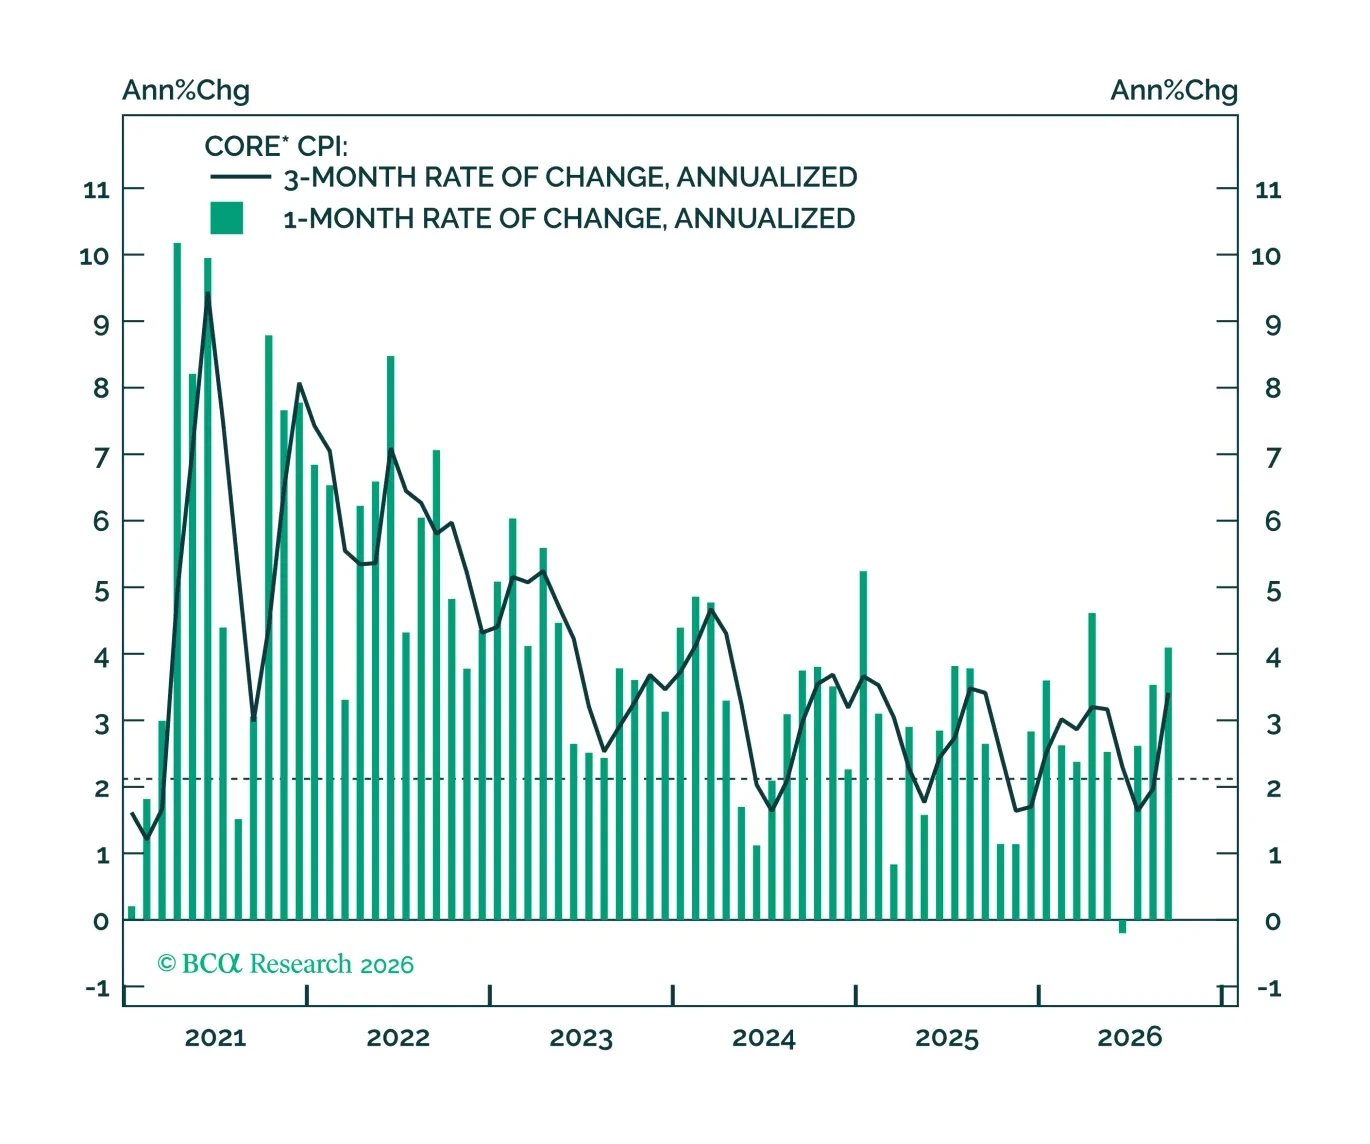
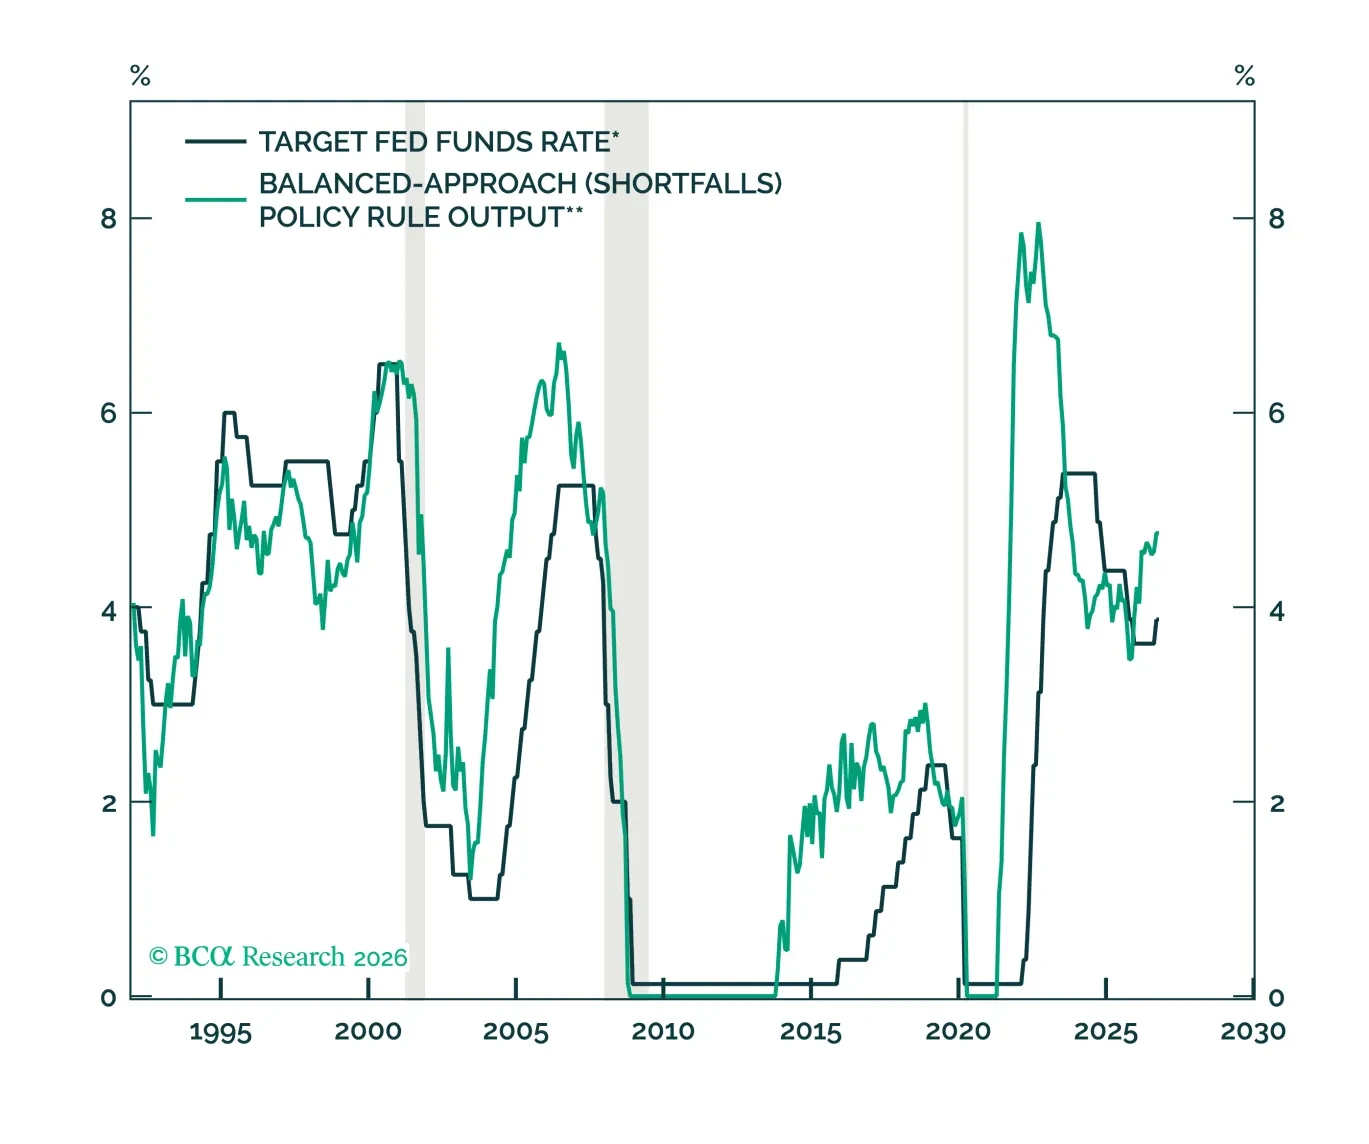
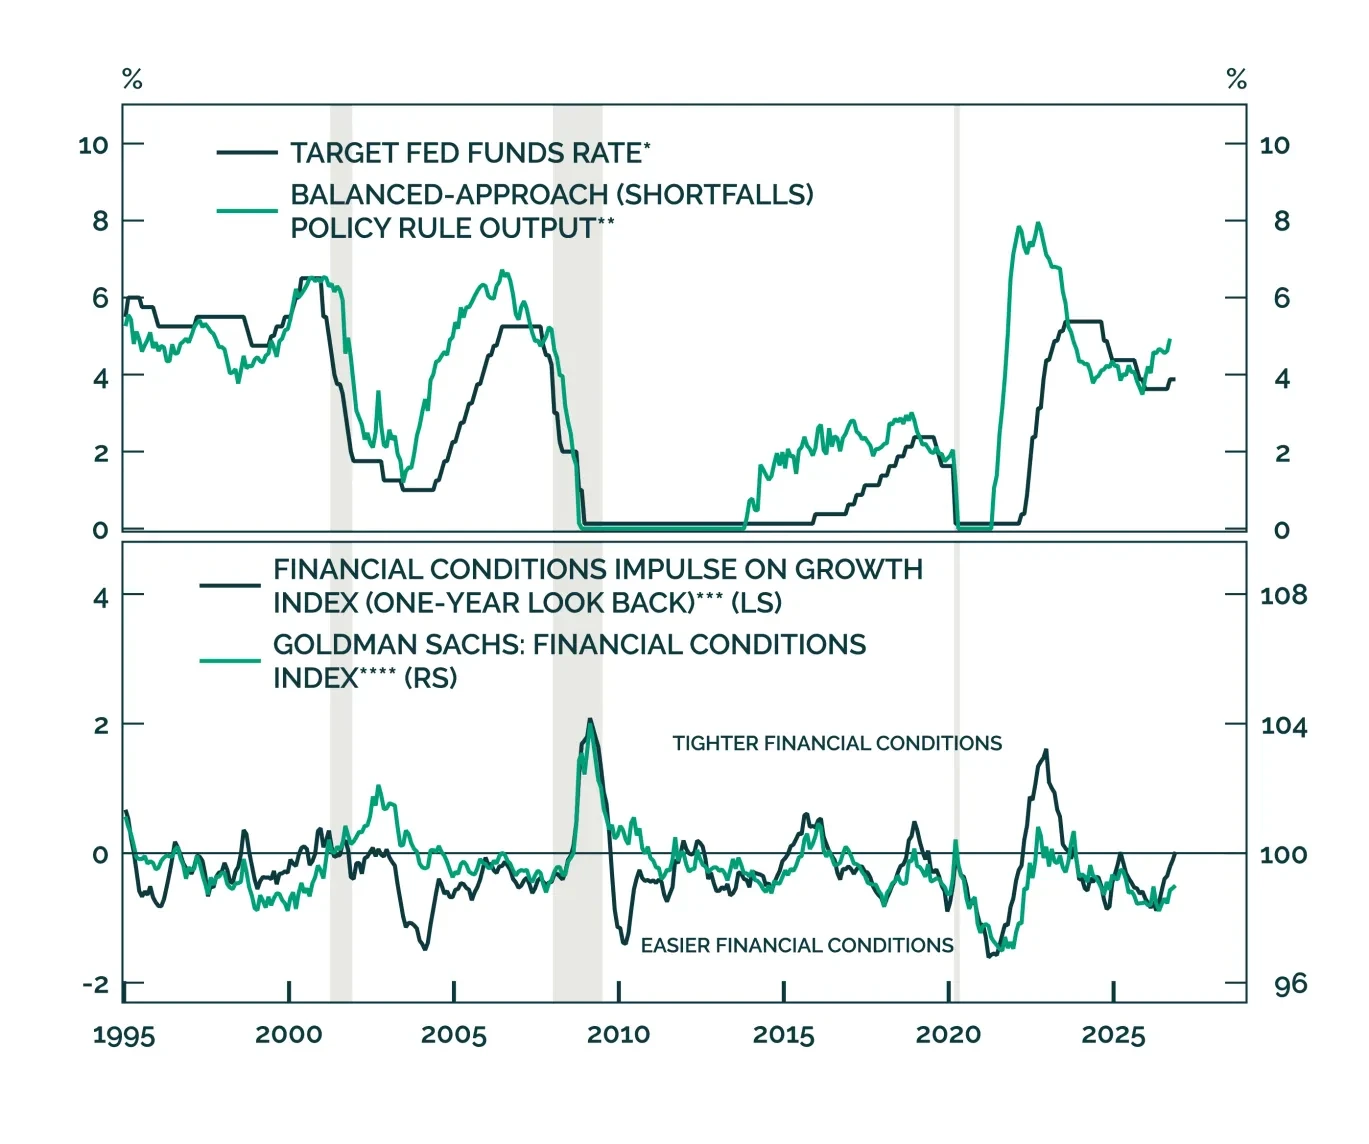
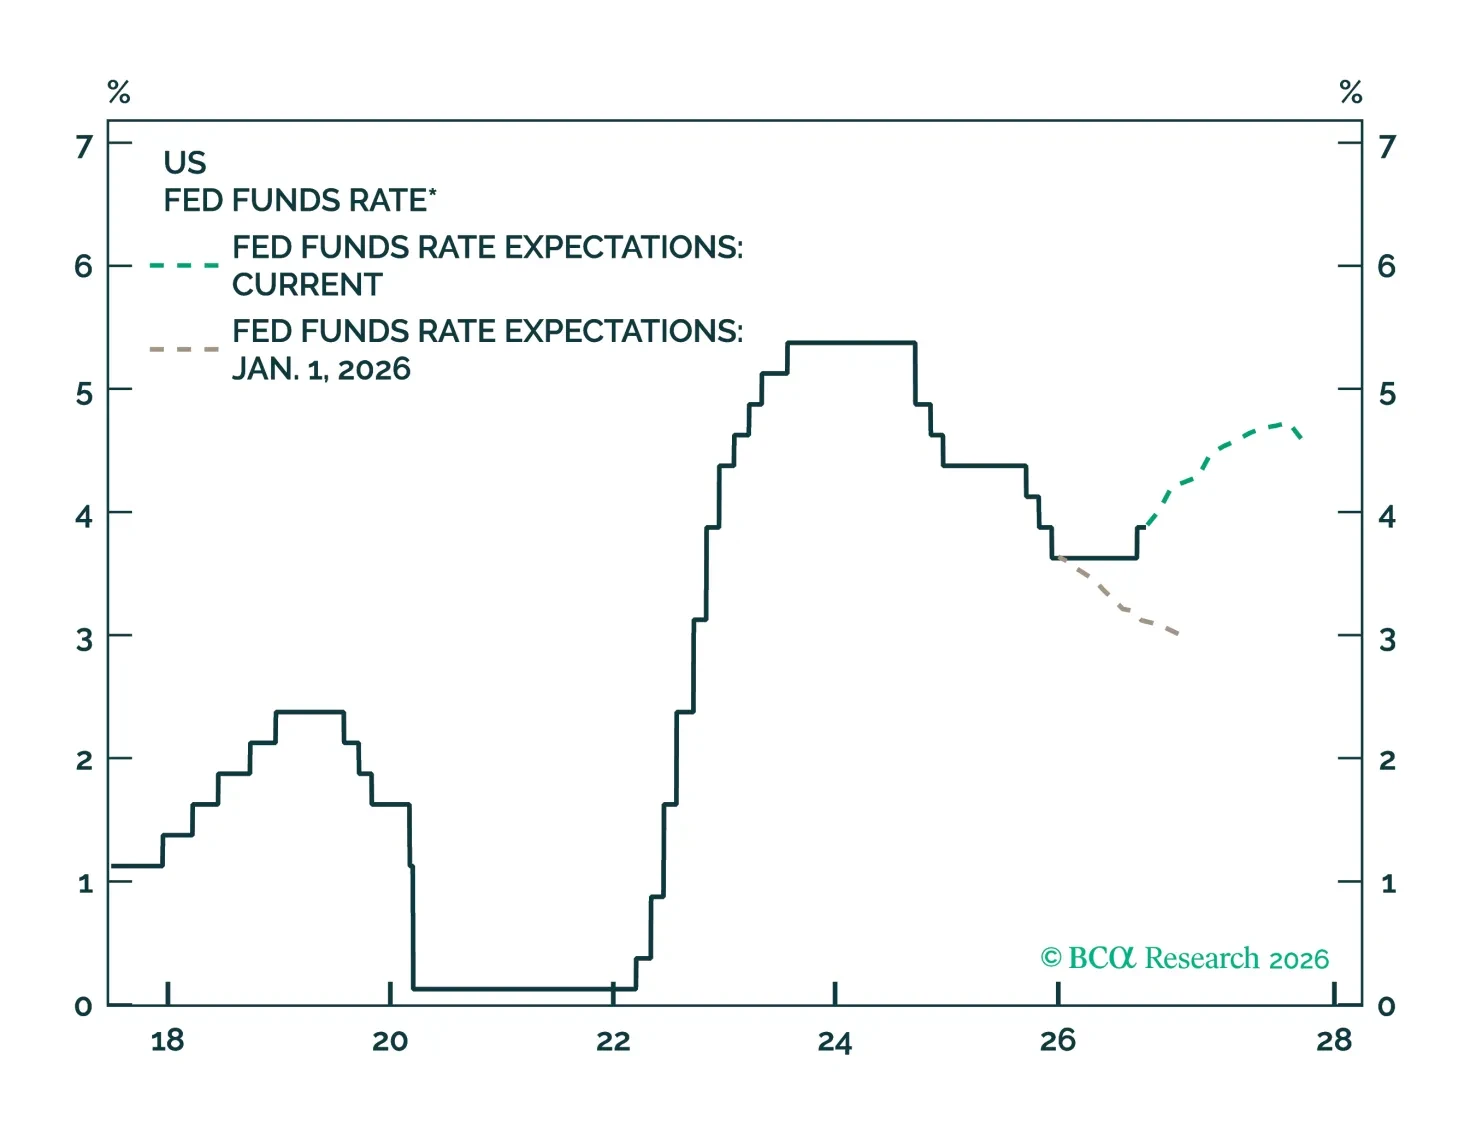
US inflation came in hot for the second consecutive month in September, though probably not hot enough for the Fed to move its next rate hike up to the October meeting.
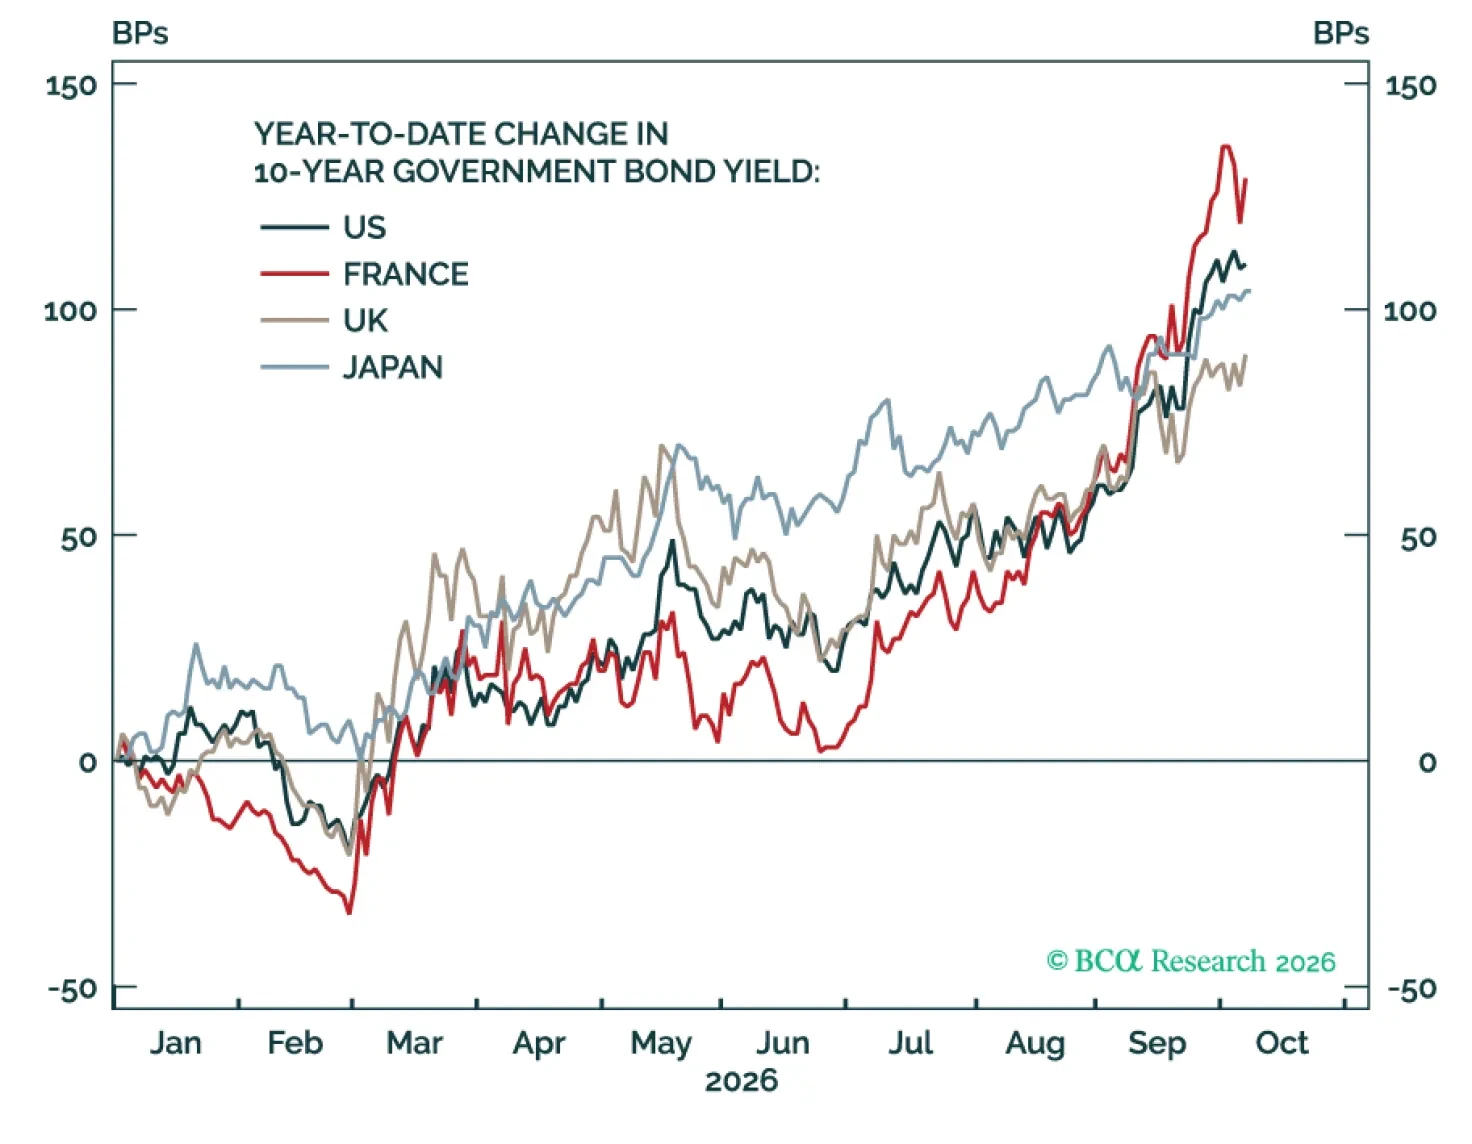
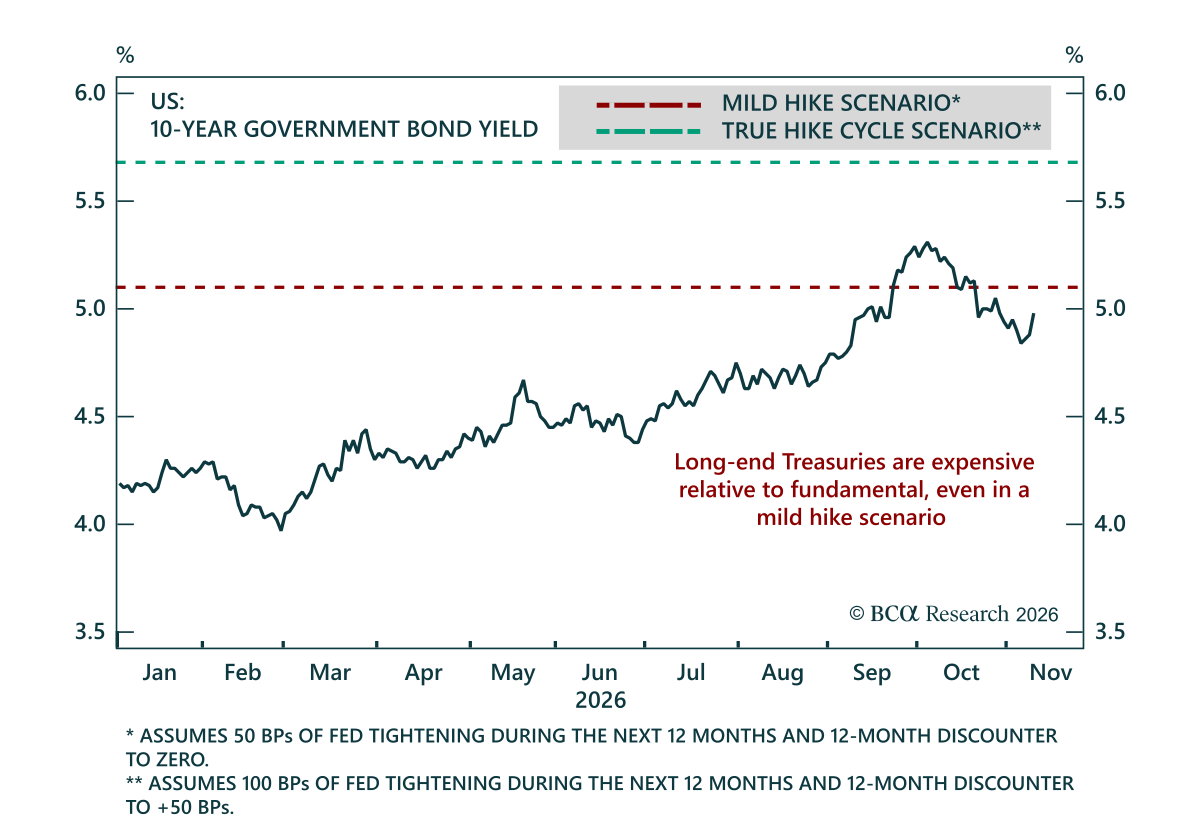
The global bond selloff is not over, but opportunities are emerging. US Treasuries and French OATs remain vulnerable to further selling, while other European government bonds look increasingly attractive. Investors should favor German Bunds and peripheral bonds, particularly on a currency-hedged basis.