Equities
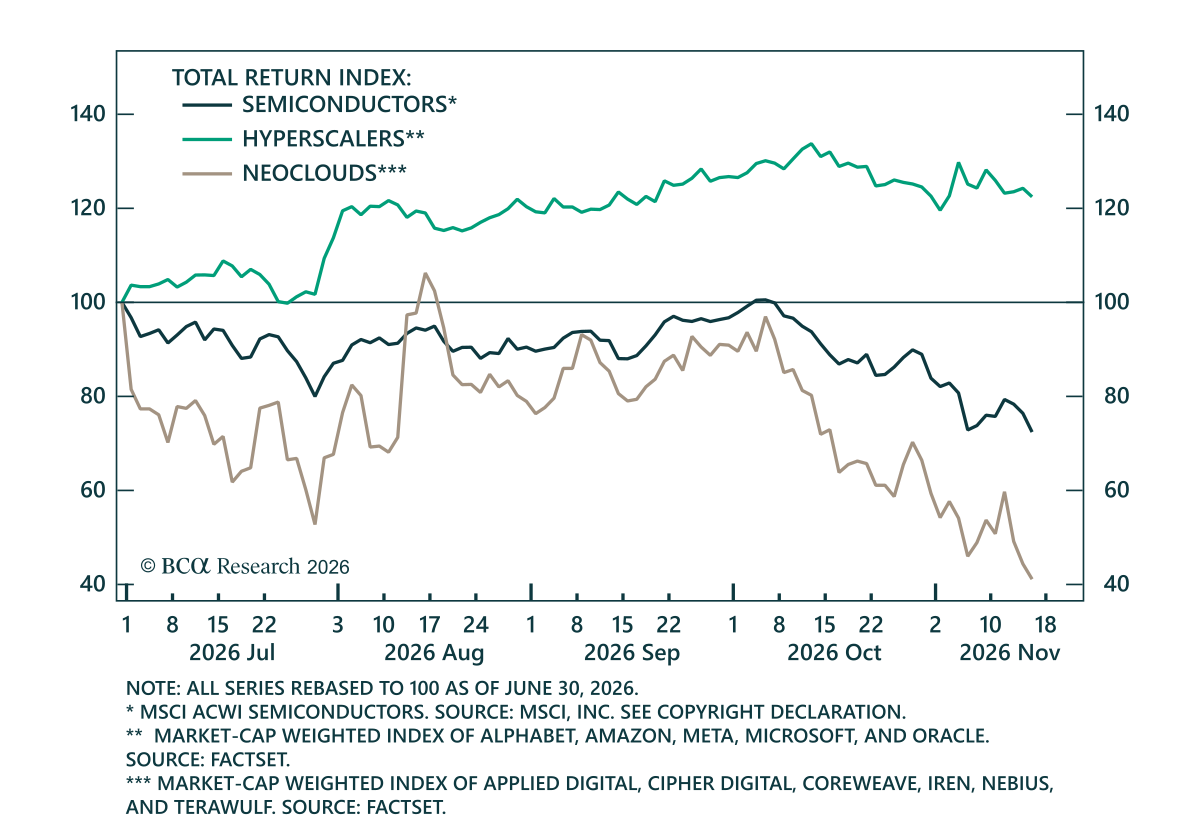
Expect Democrats to heed voters and pursue policies to reduce prices. The ousting of Huang is a blow to the neoclouds but a gift to frontier labs and hyperscalers. Downgrade Health Care and upgrade Consumer Discretionary. Upgrade Europe. Continue to favor the hyperscalers within the AI universe.
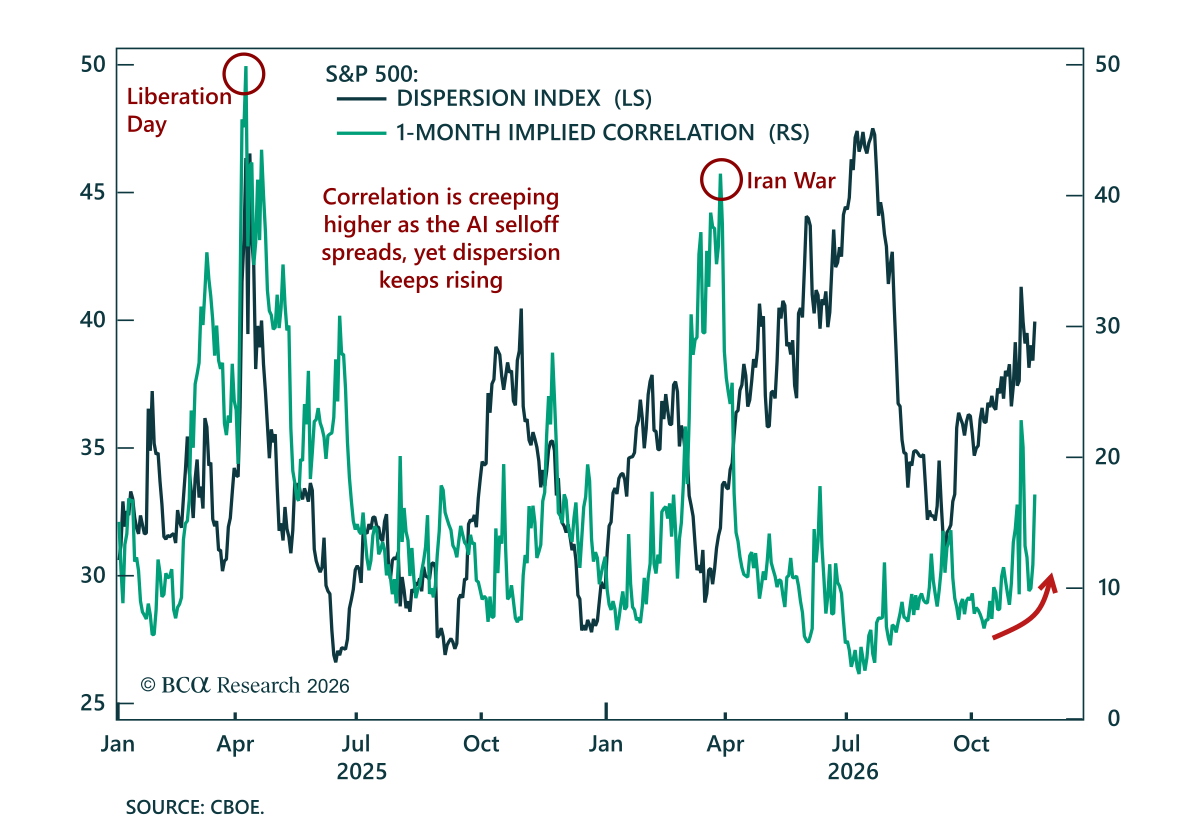
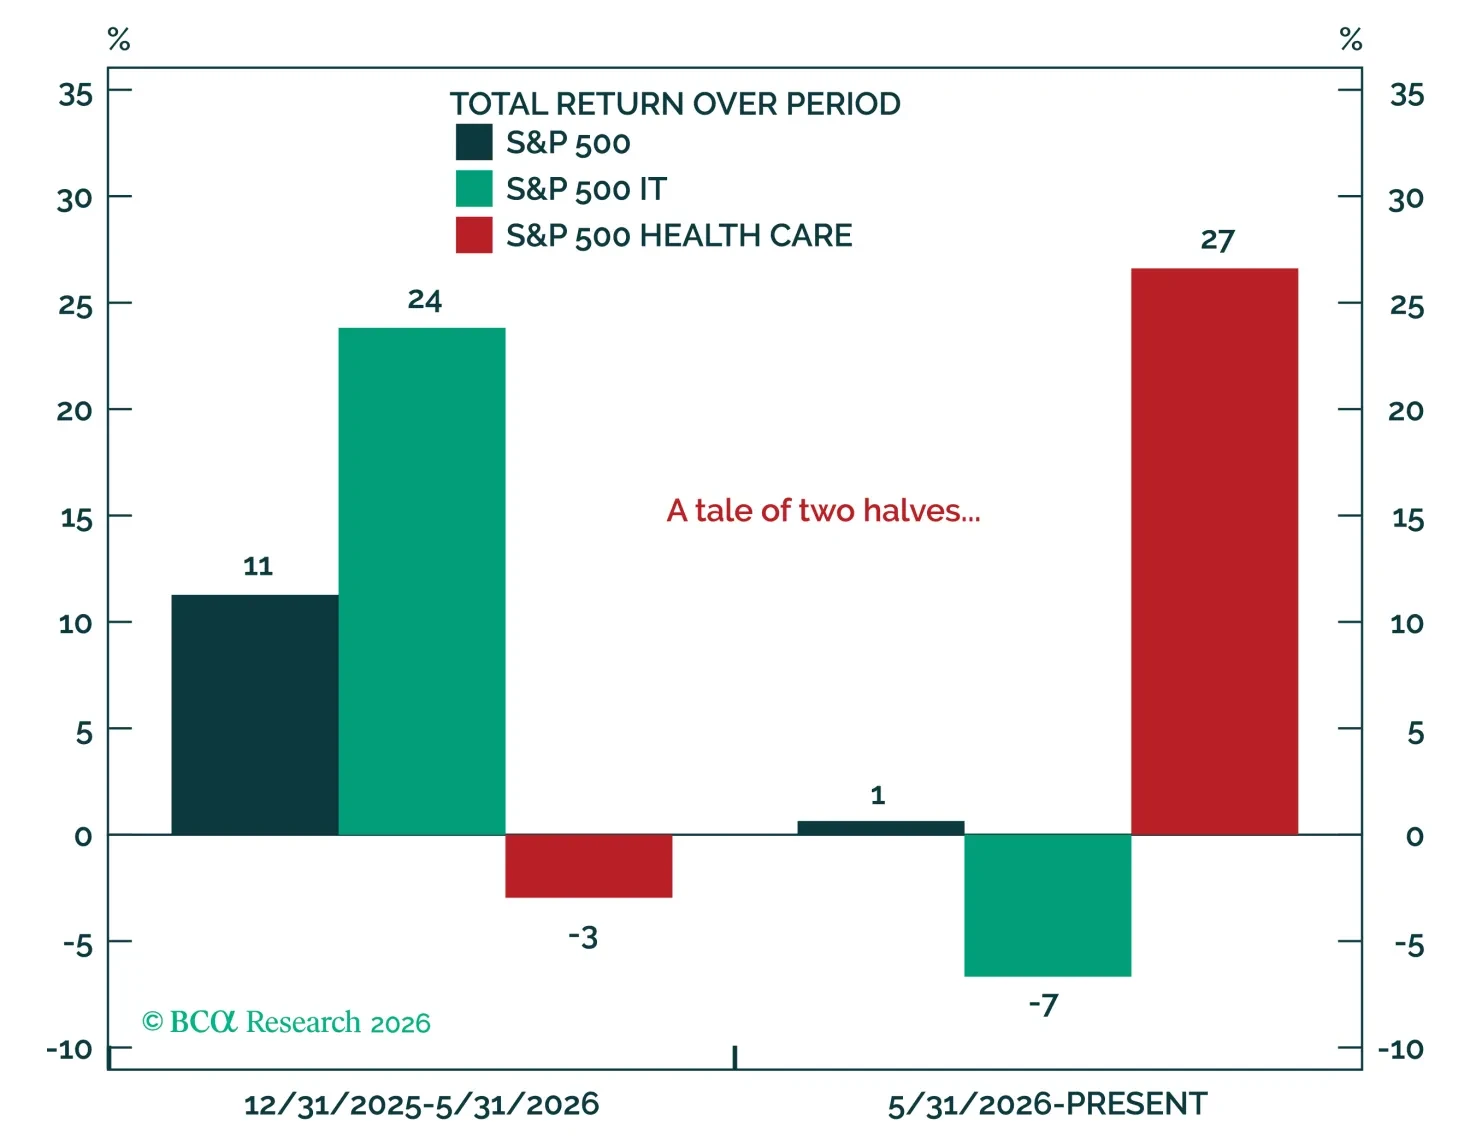
Health Care’s second-half 2026 rally has largely been a defensive rotation, not the start of a new bull market. Health Care leadership is more typical when the economy is slowing/contracting and is hard to sustain in a rising market. With the cycle still firm and our expectation that the market rallies into year end, we are neutral on the sector, though we recognize its hedging value. Within Health Care, we are underweight Providers & Services, overweight Equipment & Supplies, and market weight Pharmaceuticals, Biotech & Life Sciences (“Pharma”).
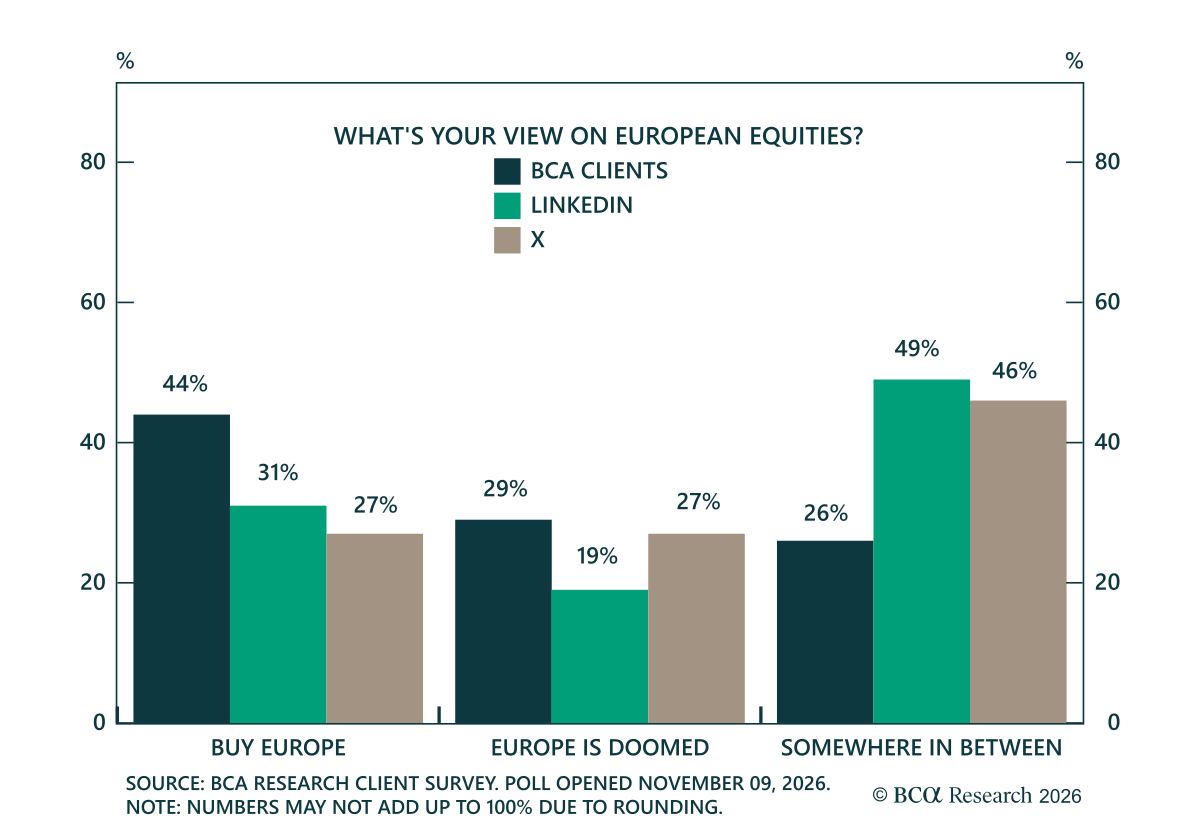
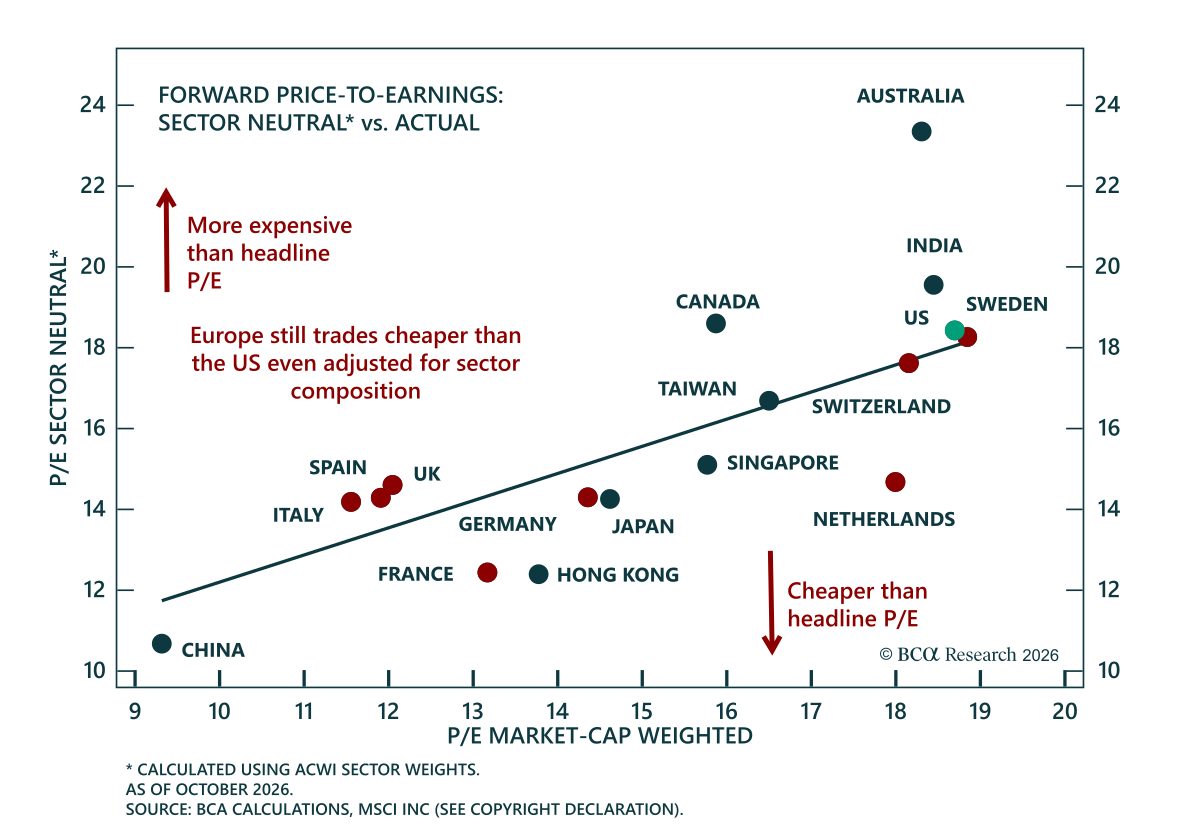
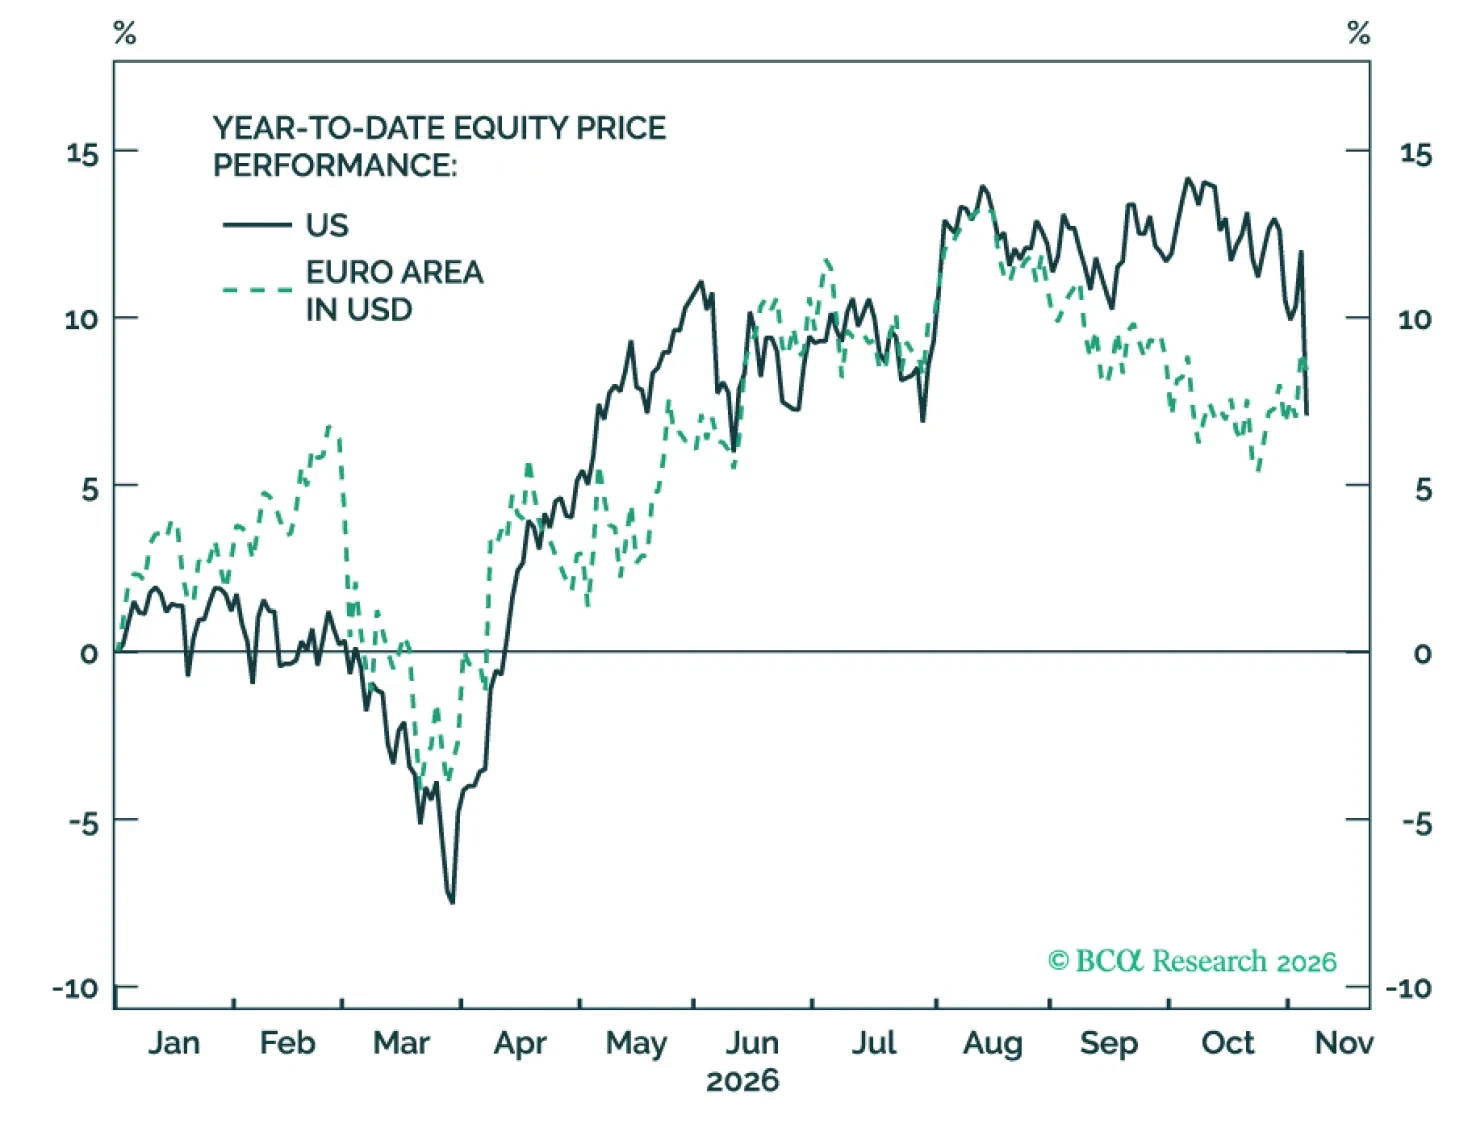
Europe was shunned while AI could do no wrong. That trade is looking tired. Falling energy prices and cracks in the AI boom favor rotating out of US equities and into cheaper European stocks. Favor defensives: Europe can win the relative race even if both markets fall.
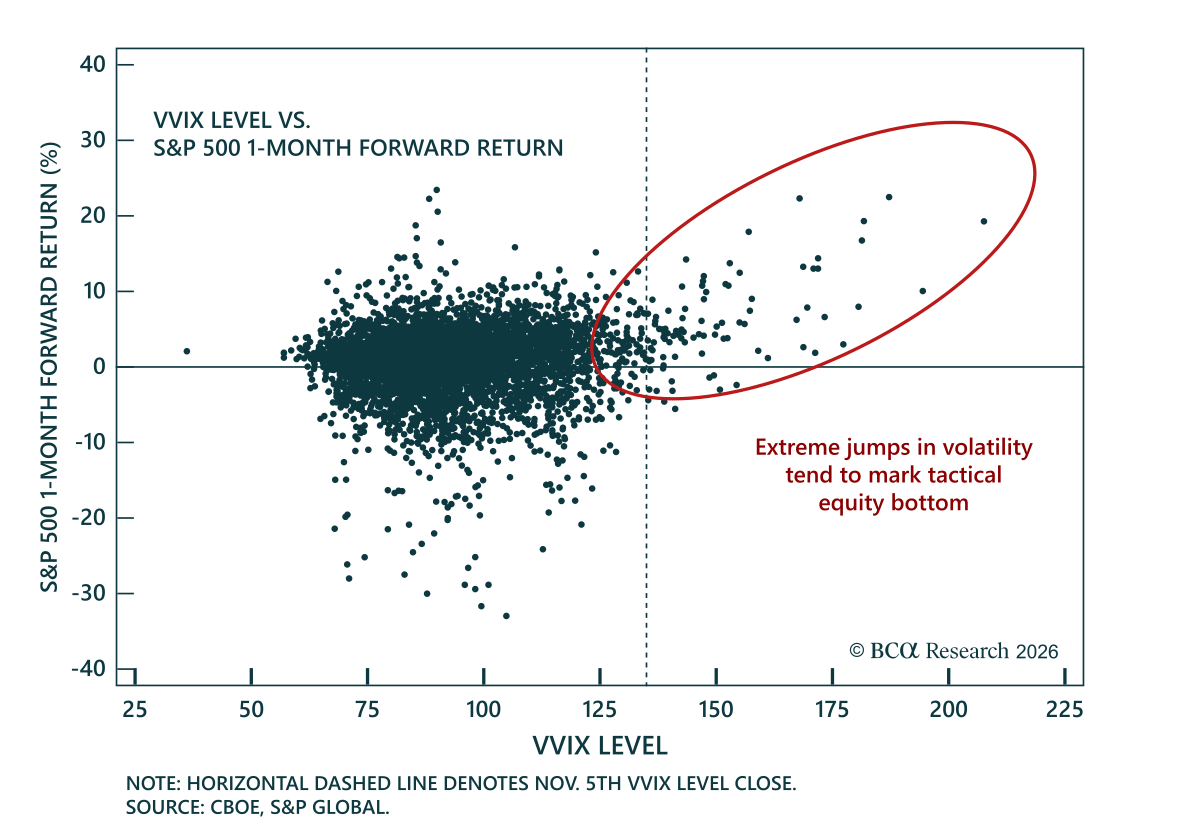
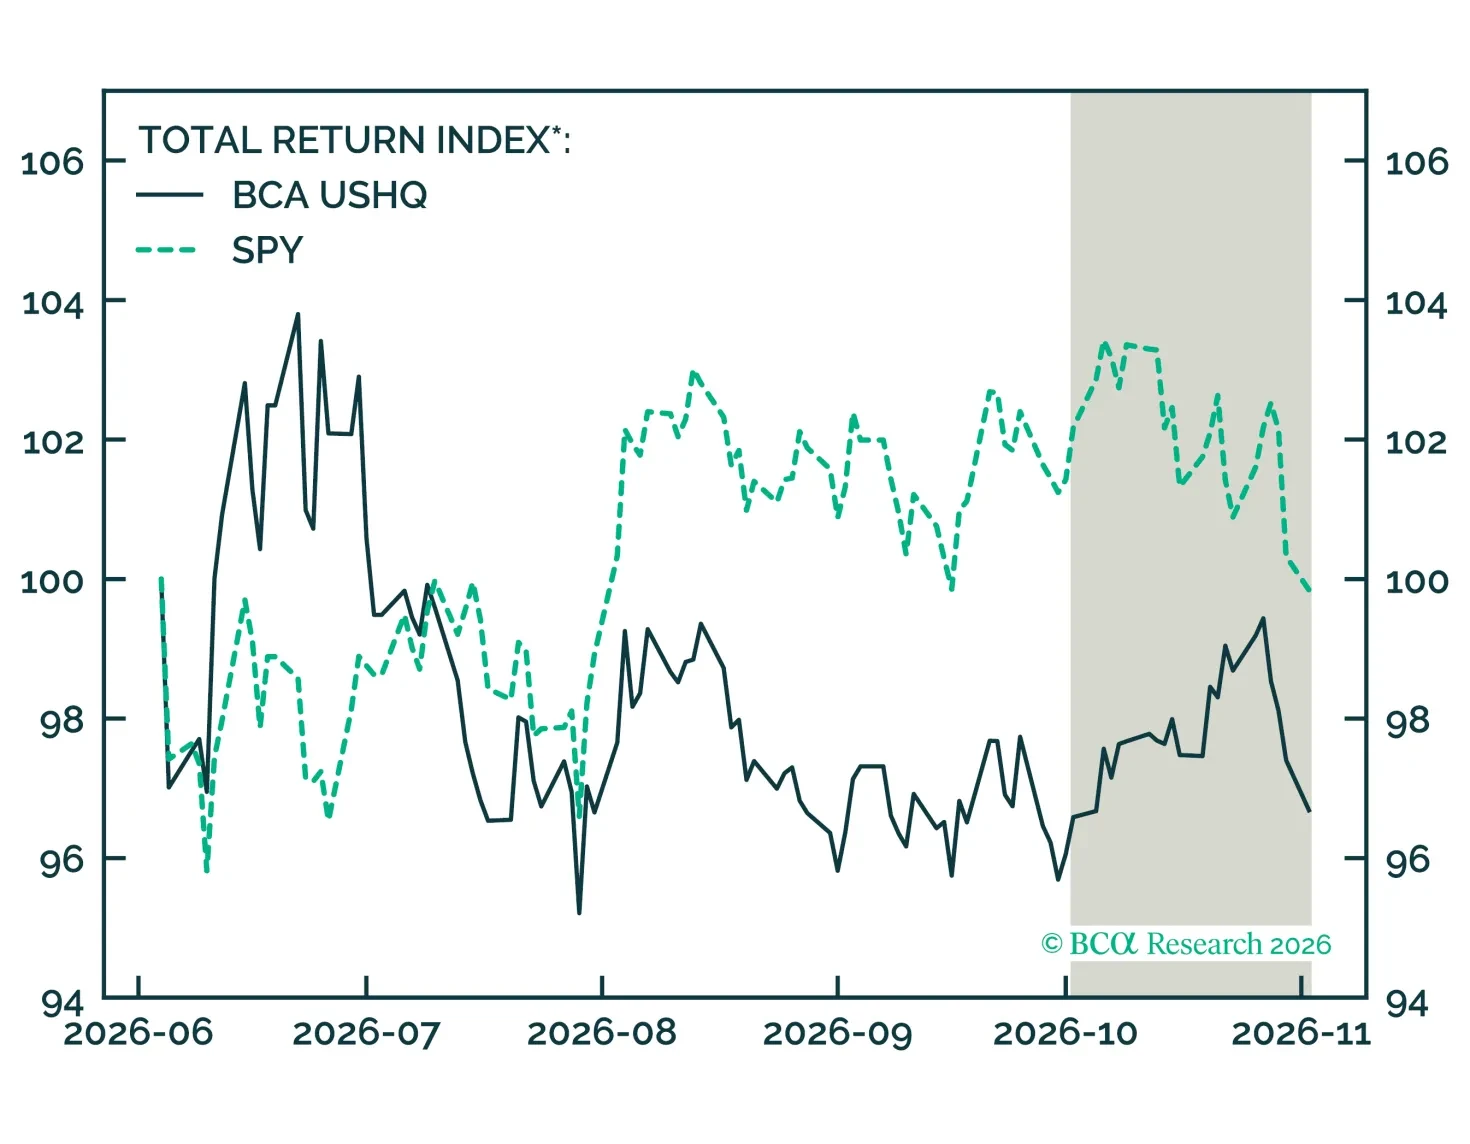
In a month when Tech dragged the market lower, USHQ’s quality tilt paid off, beating the benchmark by 238bps with gains spread across the portfolio. USHQ SMID lagged in October but remains ahead of its benchmark since June.
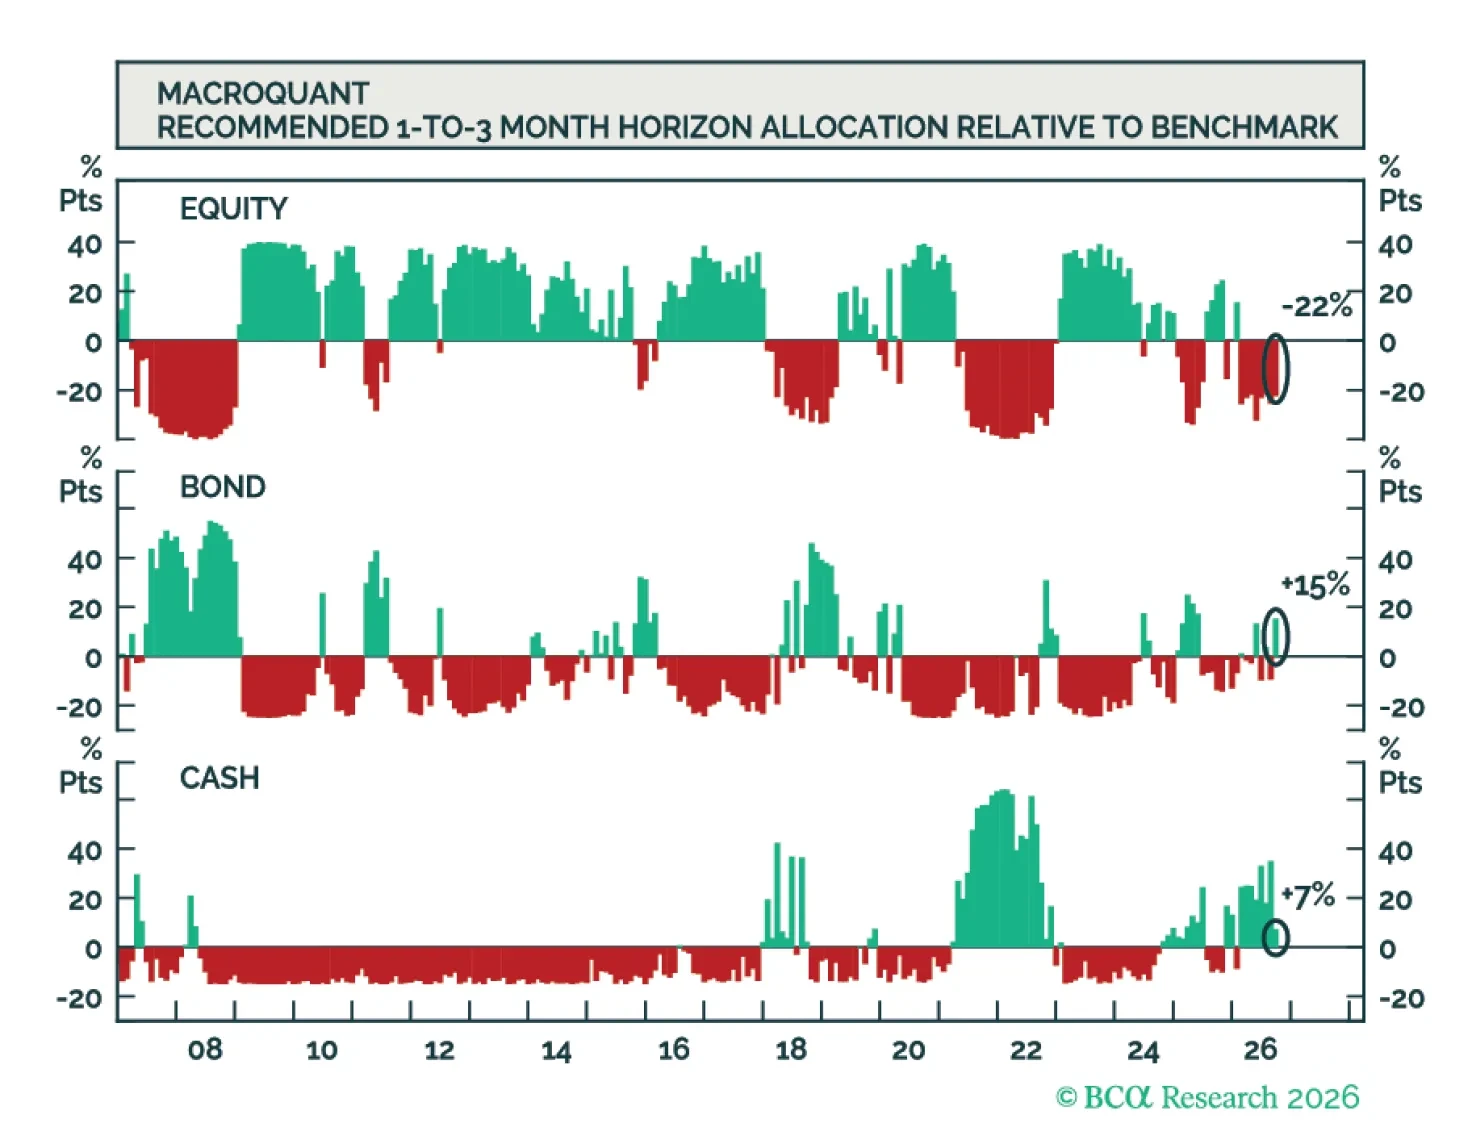
MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.