
Skip to main content

Equities

In an Insight we published yesterday, we highlighted that the S&P 500 rally has recently stopped narrowing with the gap between the market cap-weighted and equal-weighted indices stabilizing over the past month. This has also coincided with a stabilization in…
Thematic investing has become increasingly important for investors over the past few years. And yet, in spite of the popularity of thematic strategies, the vast majority of investors underperform when buying into such strategies. A recent study by Morningstar…

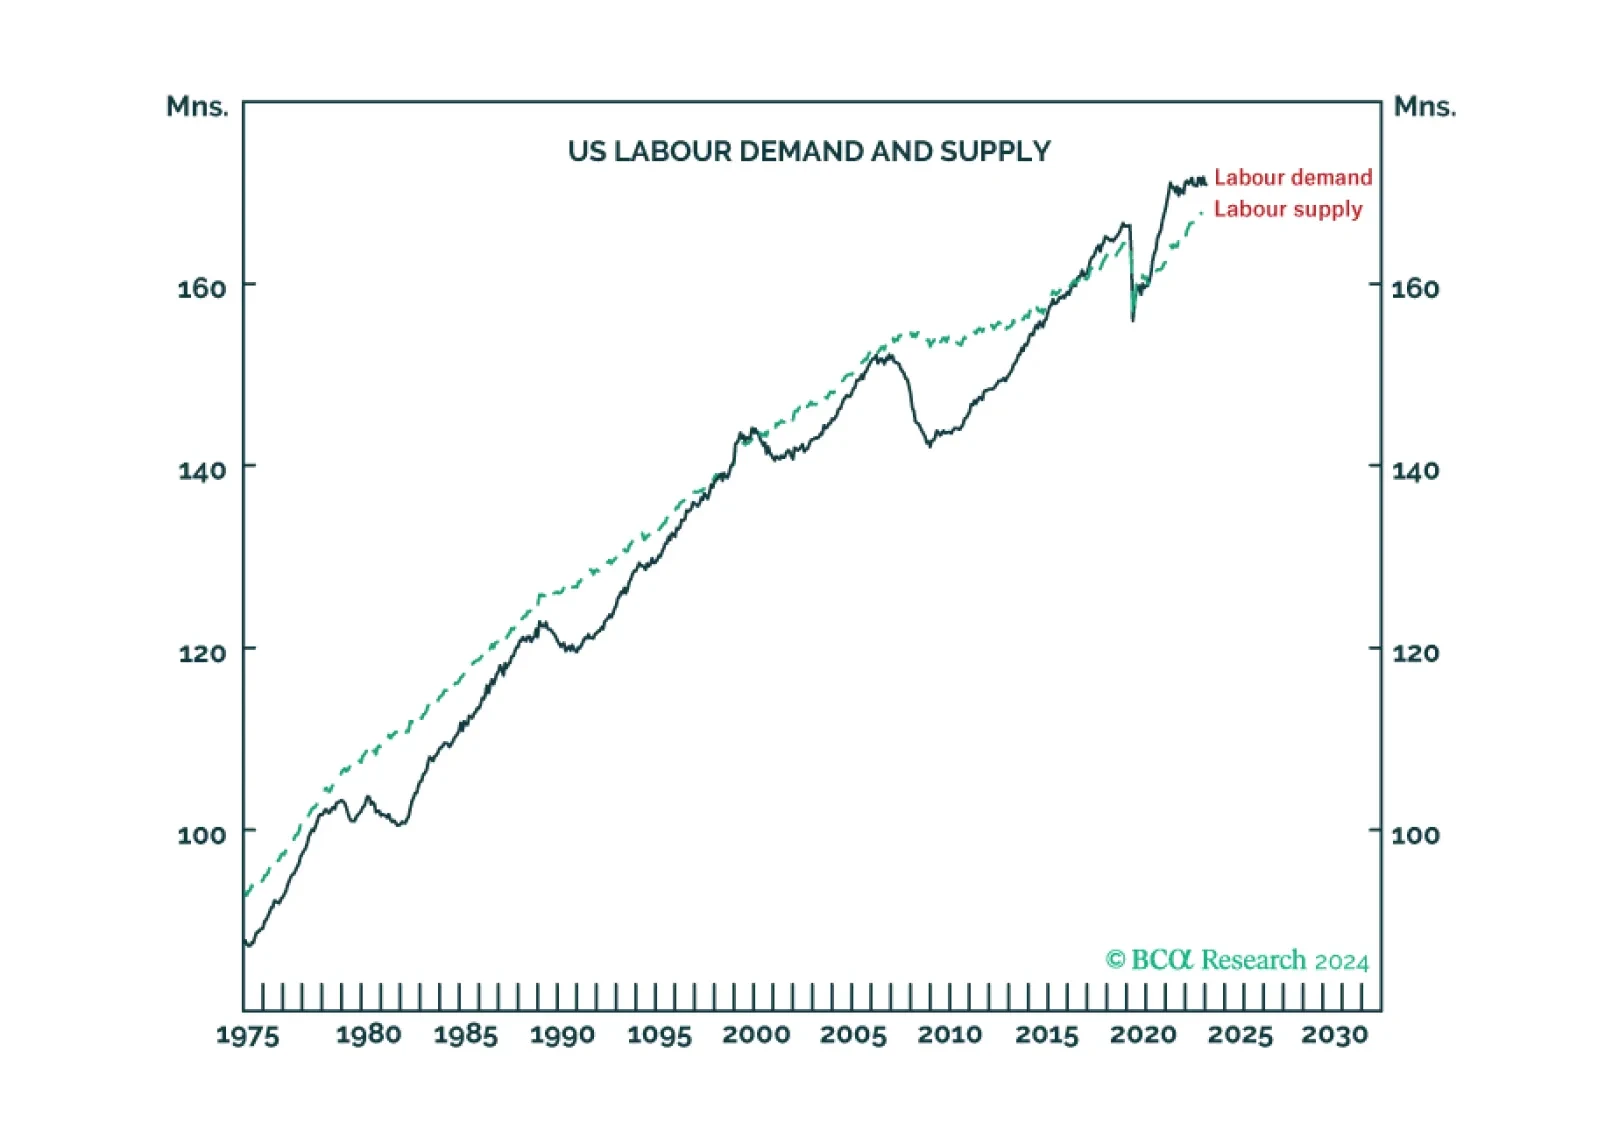
For the first time in at least fifty years, US labour supply is running well below labour demand, meaning the US economy is ‘inverted’. We discuss how and why the economy inverted, and what it means for recession, inflation, and asset allocation. Plus: NVDA is at a consolidation point.
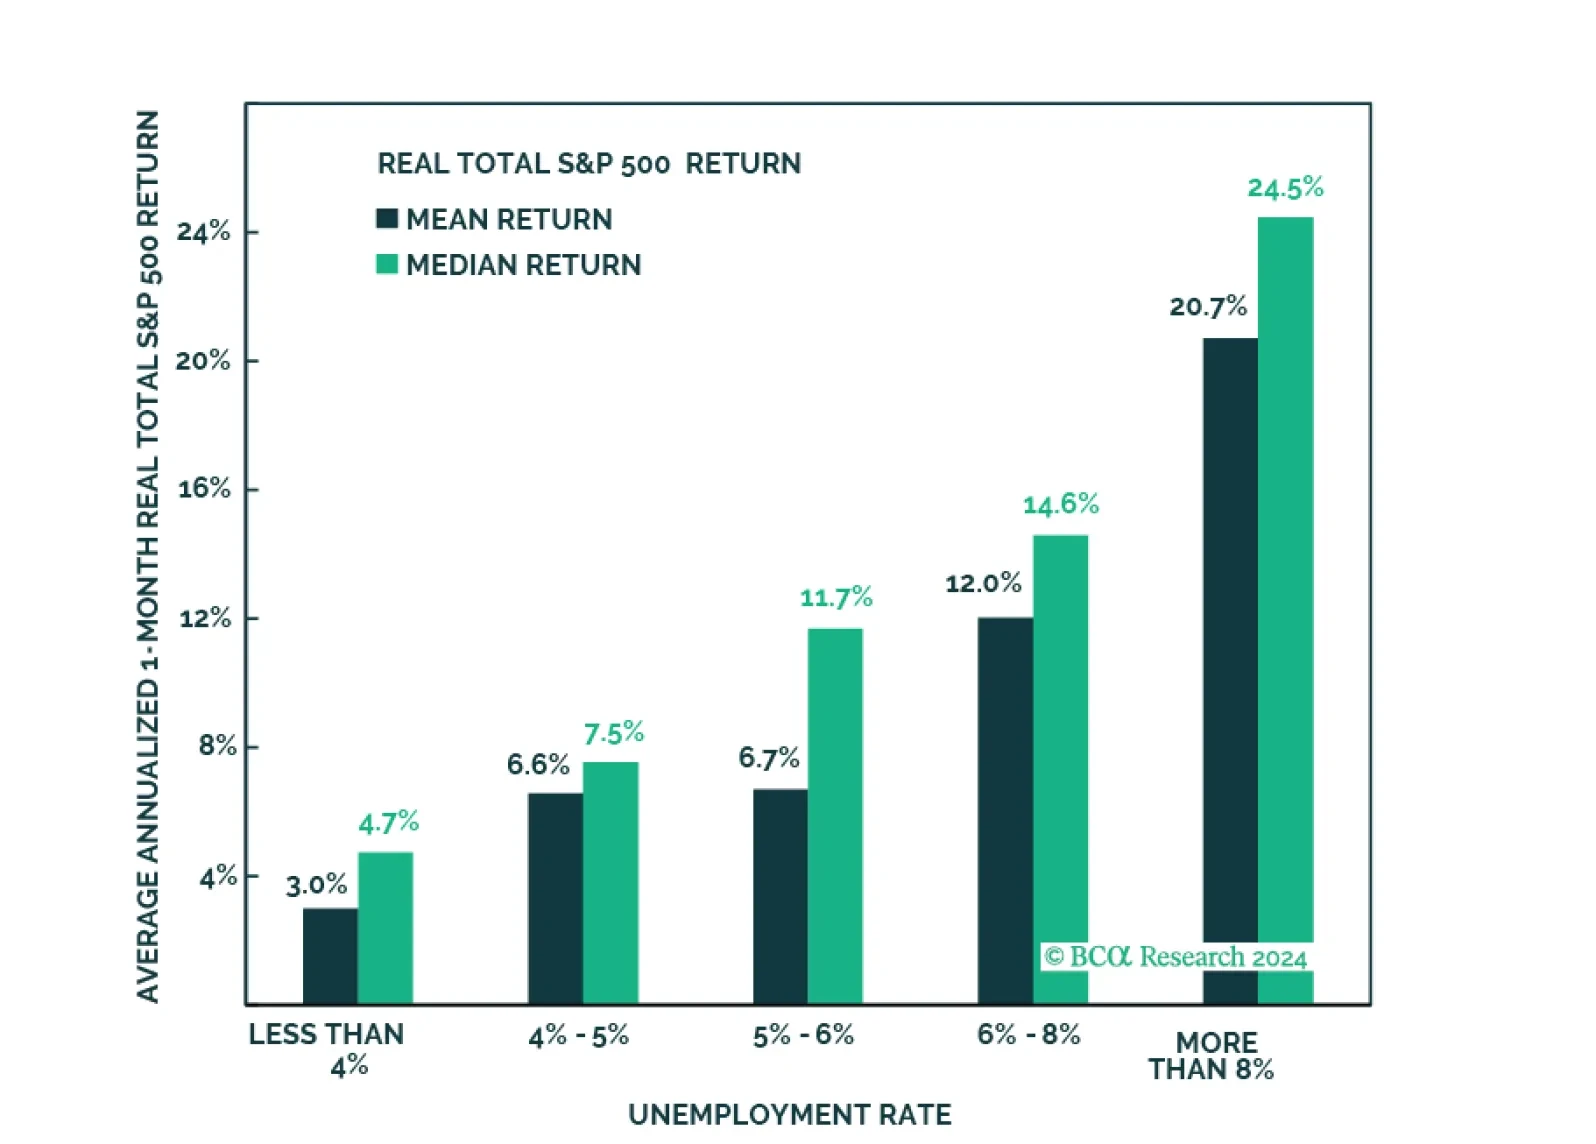
The US equity rally has recently stopped narrowing with the gap between the market cap-weighted and equal-weighted indices for the S&P 500 stabilizing over the past month. Indeed, this has coincided with a shift in market leadership. Energy, Materials,…

In this Strategy Outlook we examine why, contrary to popular perception, the odds of a global recession over the next 12 months are rising not falling.
Special Report

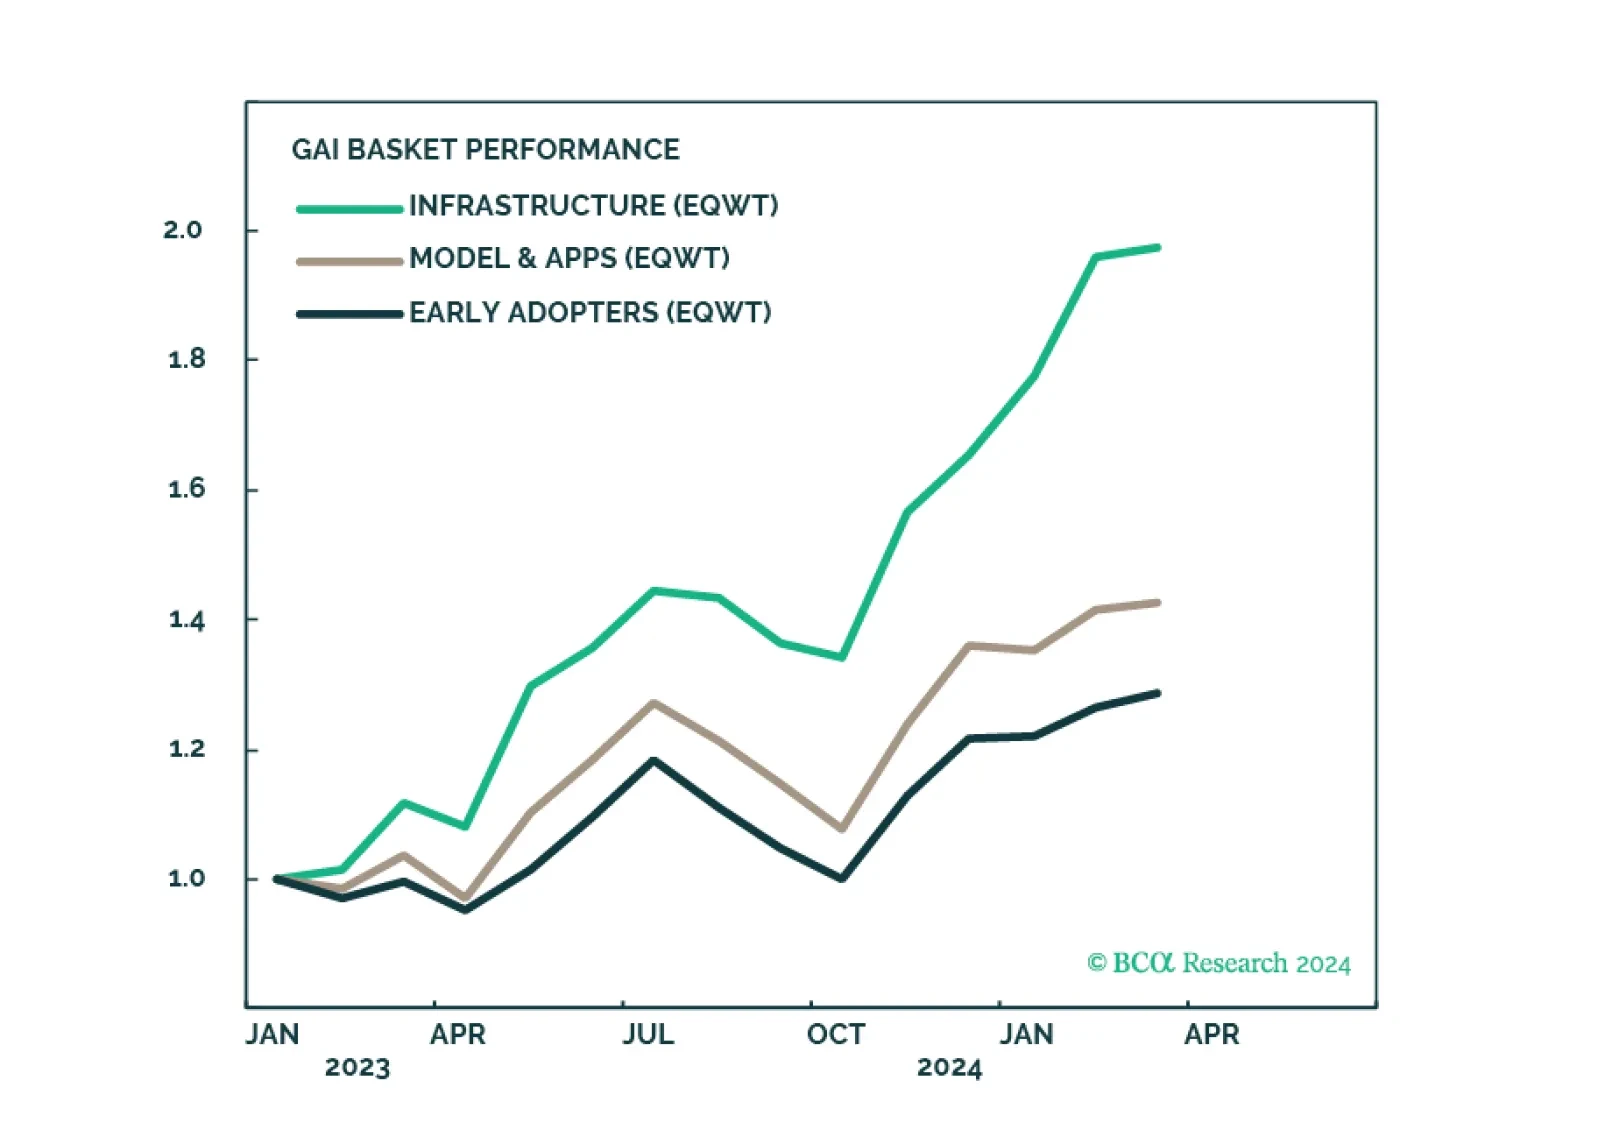
GAI is a powerful force that will revolutionize the global economy and we are sold on this long-term investment theme. To partake in the upward momentum, we recommend a nuanced approach. The GAI infrastructure cohort is now overbought - there should be a better entry point. The models and applications companies and early adopters are less of a crowded trade and offer more opportunities.
According to BCA Research’s Private Markets & Alternatives service, Artificial Intelligence is old news. Given such, it is not prime for Early-Stage Venture Capital (VC) investing. While everyone is distracted with AI, investors should look to Aerospace &…
The steepening of the yield-curve powered the outperformance of the S&P 500 Financials relative to the overall market since the spring of 2023 banking crisis. This sector returned 30.1% over this period, against 27.3% for the S&P 500. Our US Equity…

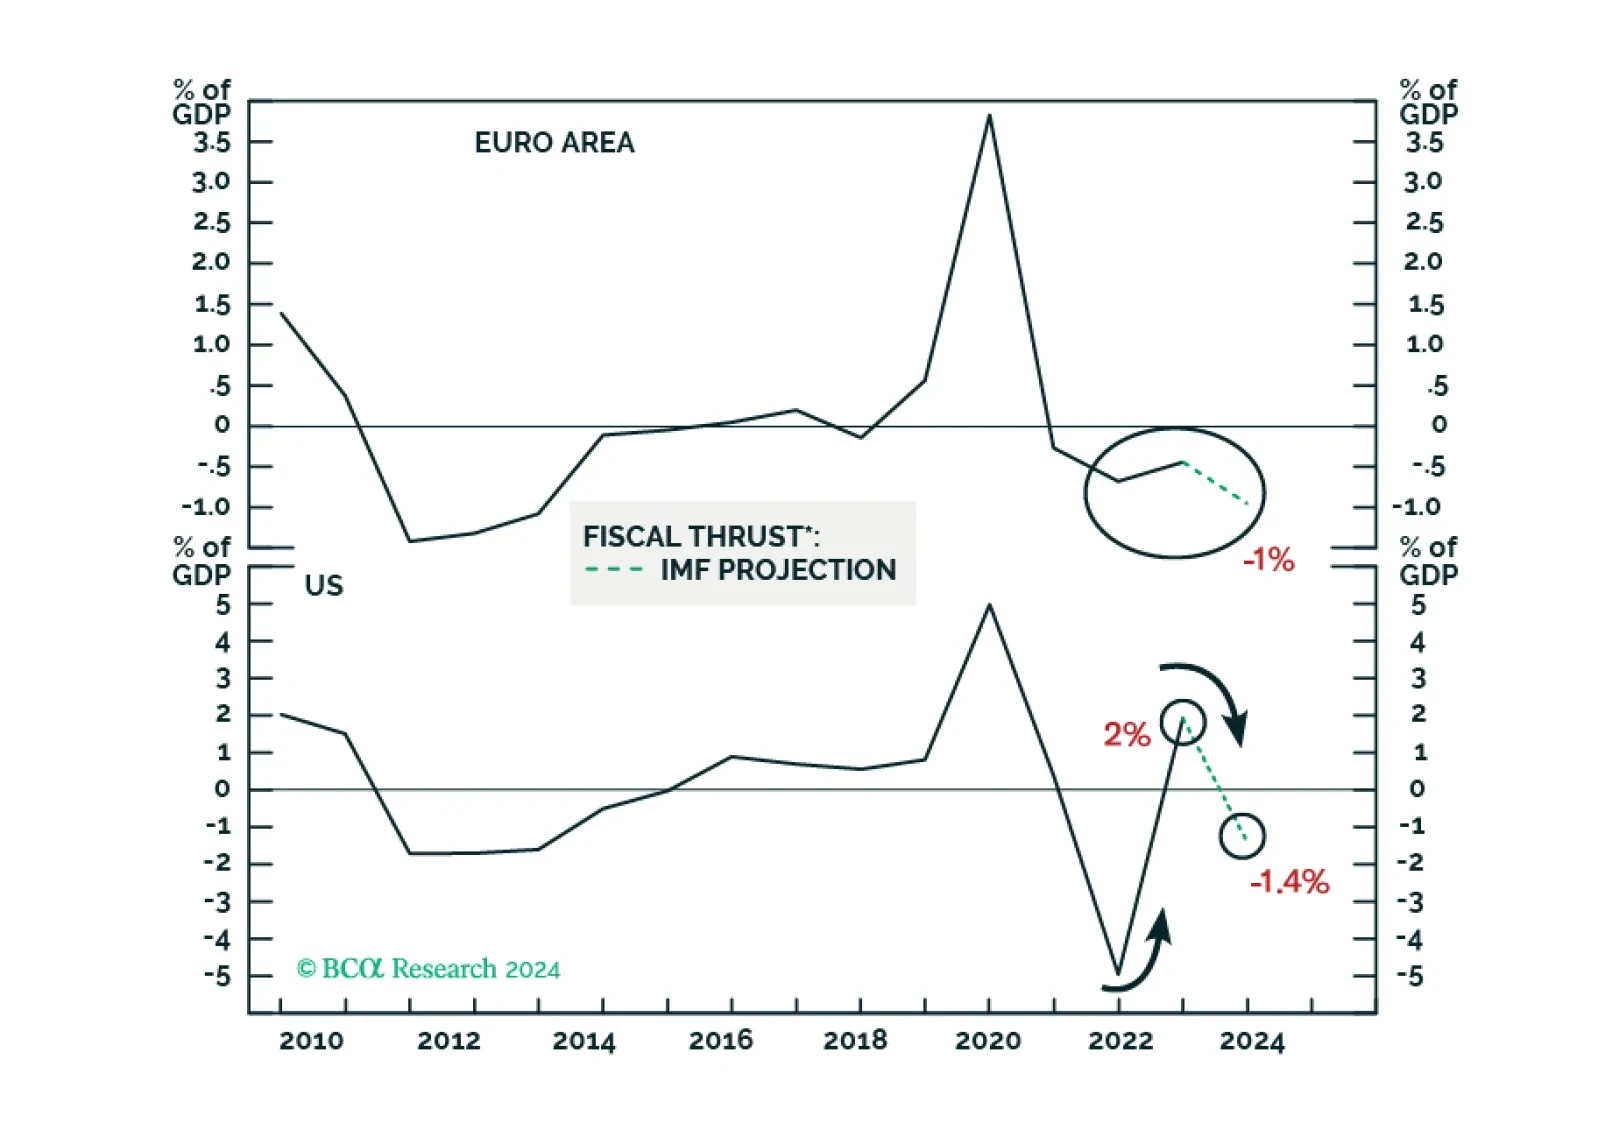
Despite a couple of rate cuts in H2 2024, borrowing costs will remain elevated in real terms amid lower inflation in the US and Europe. This and tightening fiscal policy will hinder domestic demand in advanced economies. Domestic demand in China and EM ex-China will remain very tepid, with risks skewed to the downside.

The 10.4% contraction in Taiwanese export orders for February delivered a negative surprise to expectations that the pace of expansion would slow from 1.9% y/y to 1.2% y/y. However, investors should not read too deeply into this weaker-than-anticipated…