Money/Credit/Debt
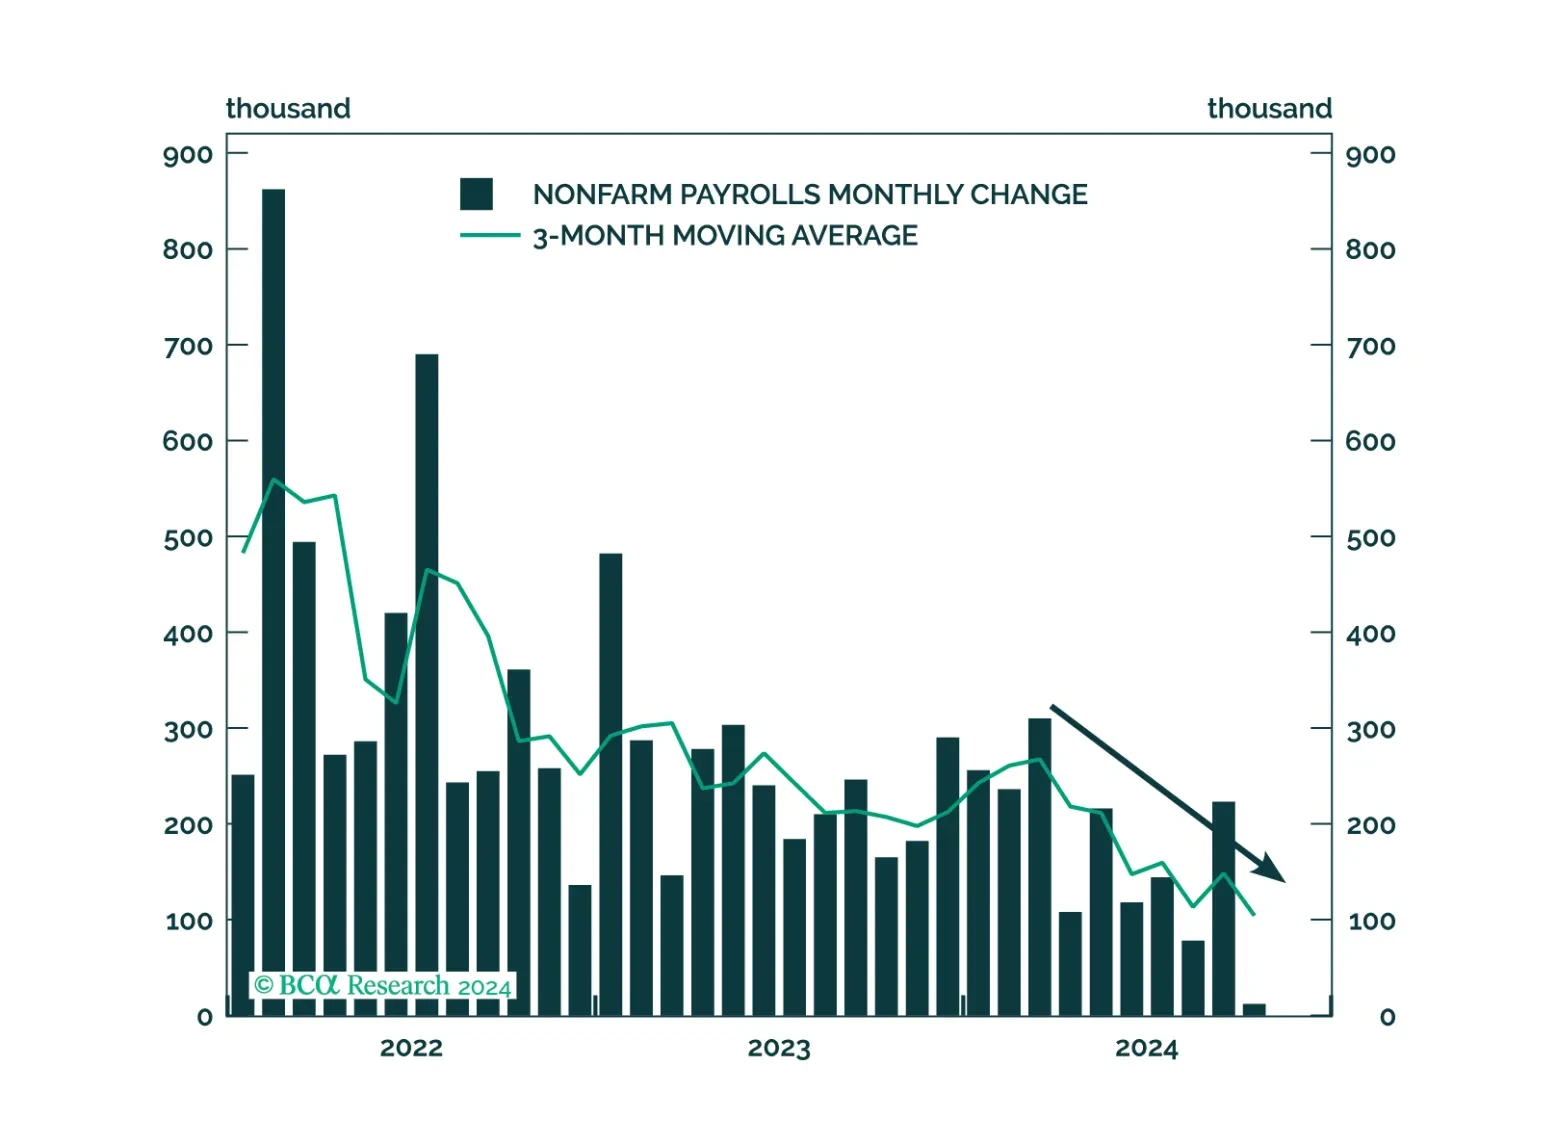
The force of the post-election momentum leads us to believe we could be stopped out of our defensive positioning before the week is out, but we still believe in our recession call. If we are eventually stopped out, we will seek a more opportune entry point to bet against risk assets once the election fever runs its course.
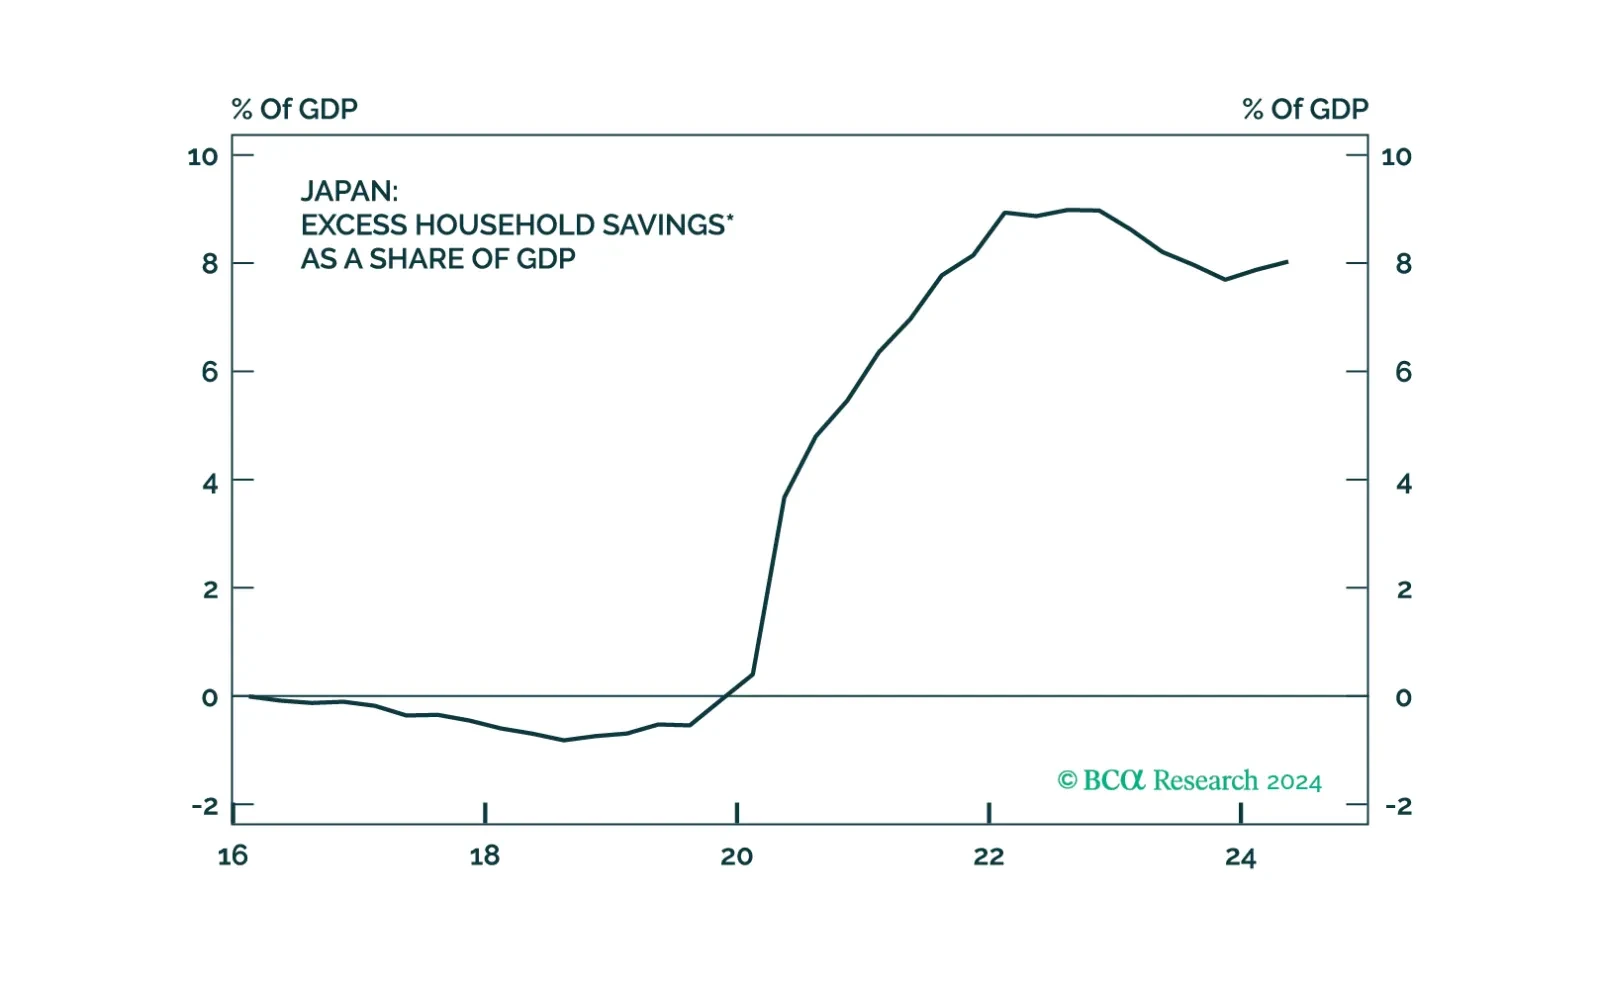
The latest Bank of Japan meeting did not alter our high-conviction views of being long the yen and underweight JGBs.

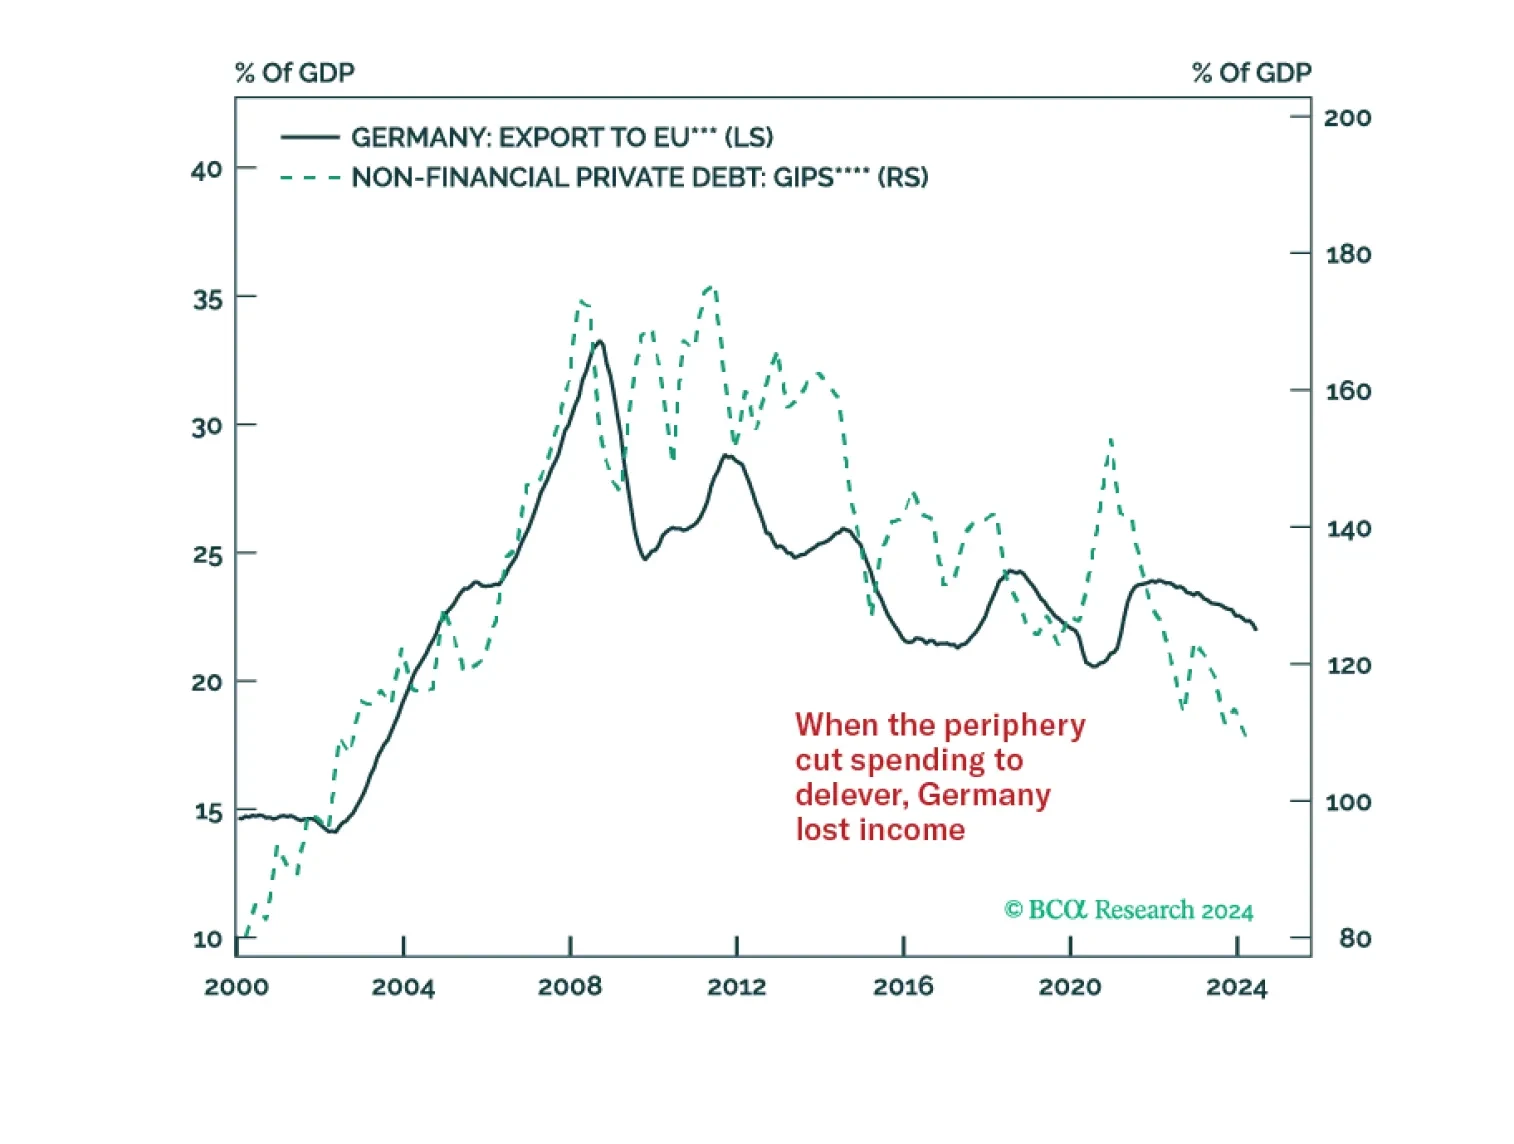
Germany’s economy has lagged that of the rest of Europe for nearly 10 years. So have German stocks. Investors are extrapolating these trends to bet on the country’s deindustrialization. Could Germany manage to beat dismal expectations?
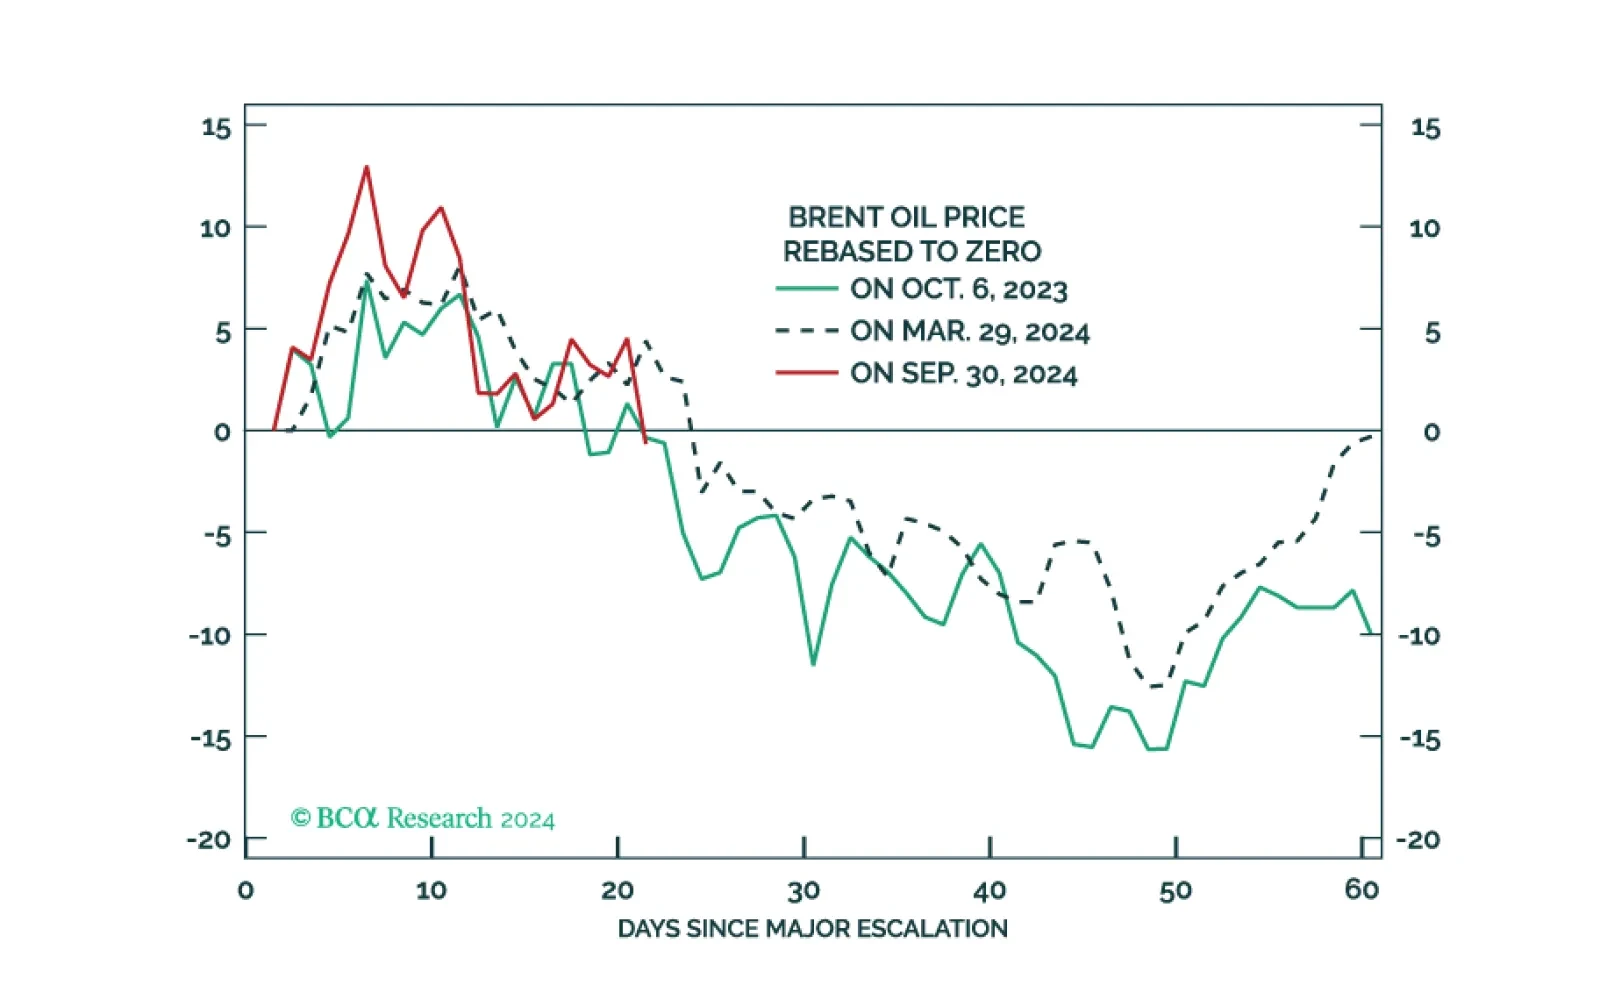
The global political system is destabilizing and the US will turn more hawkish in foreign policy, trade policy, or both, regardless of the election outcome. Tactically go long the dollar.
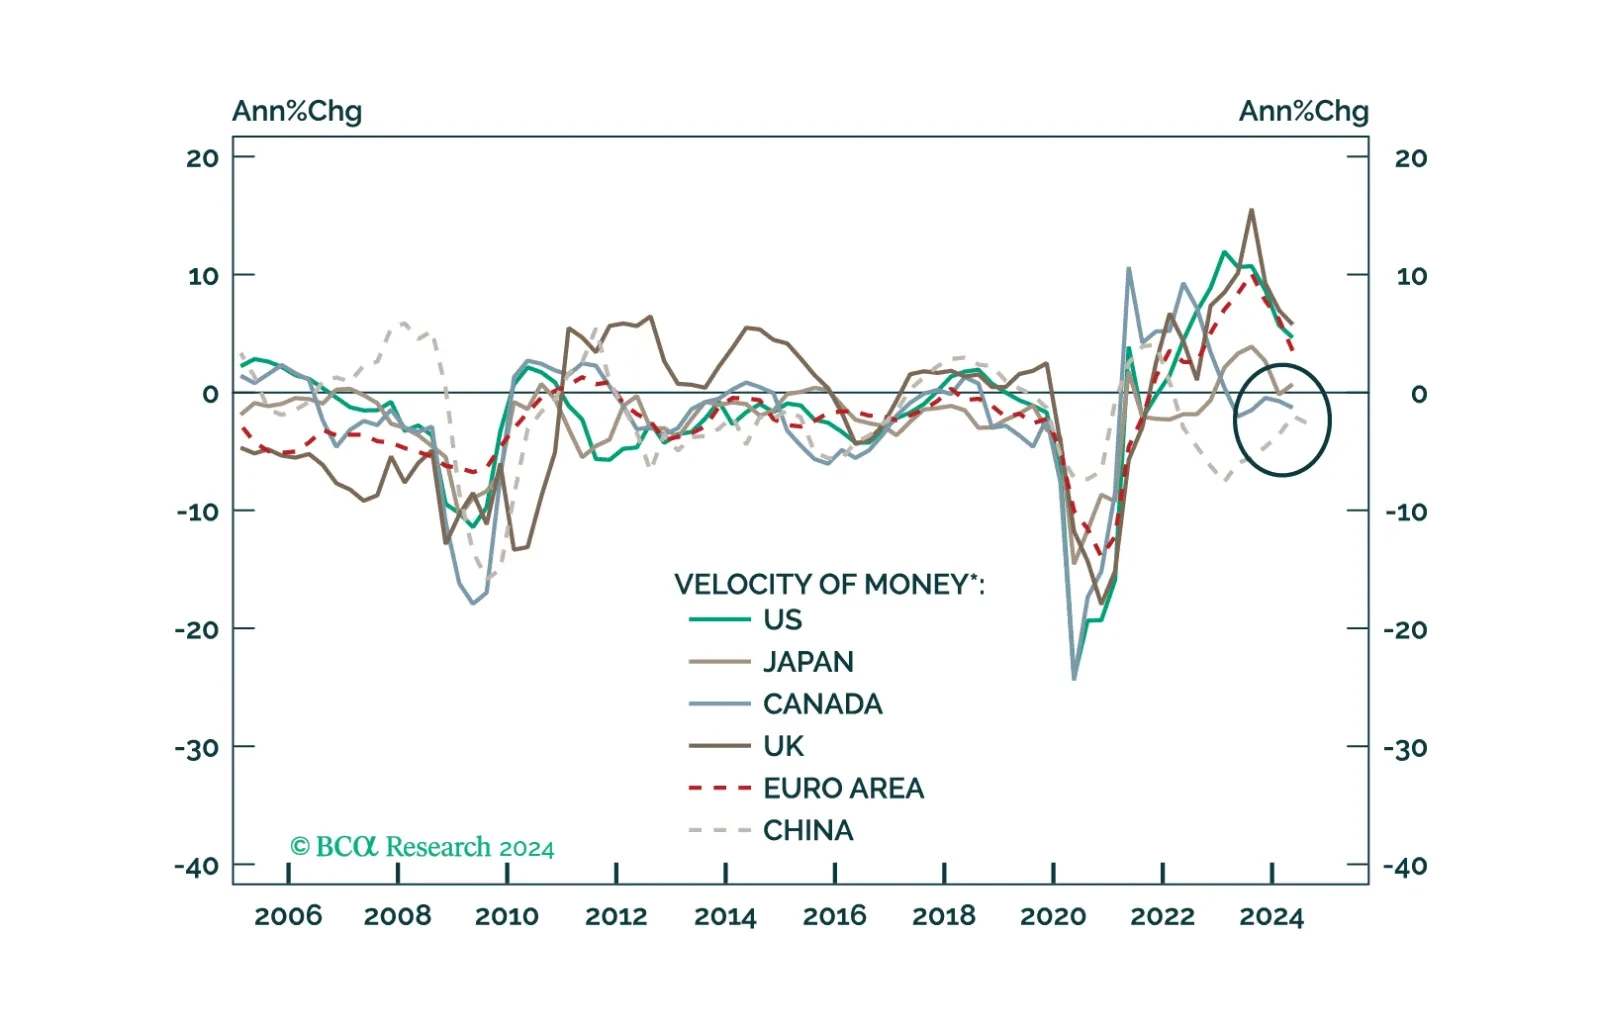
This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.
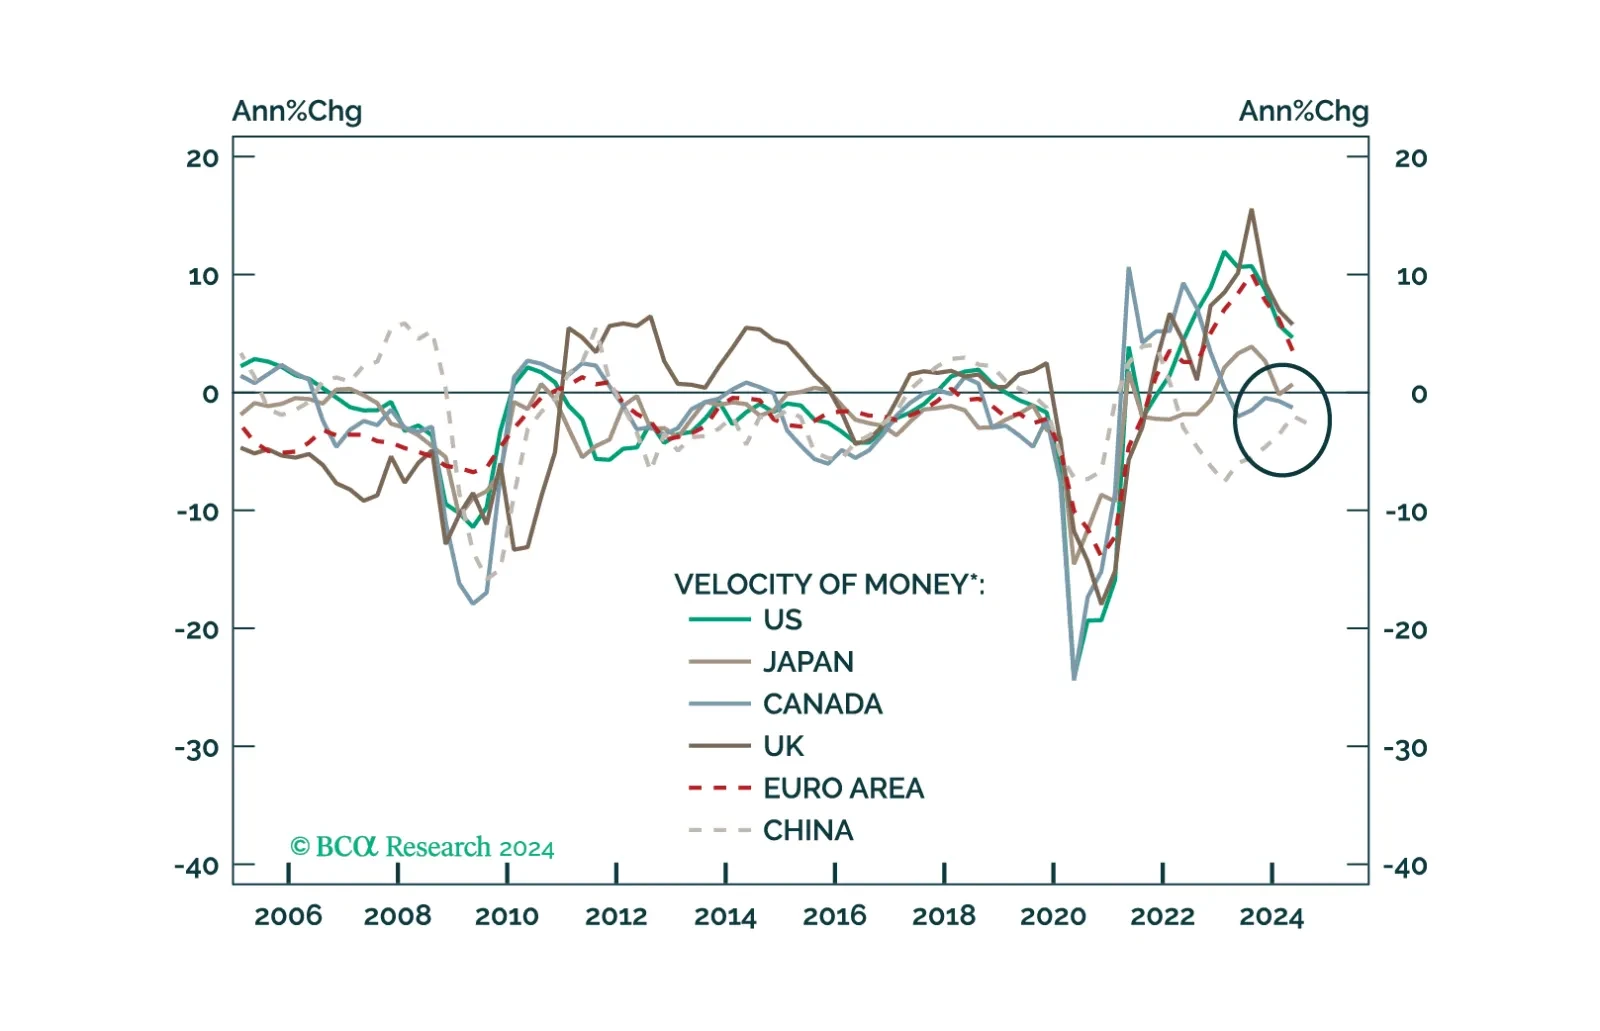
This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.