 Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
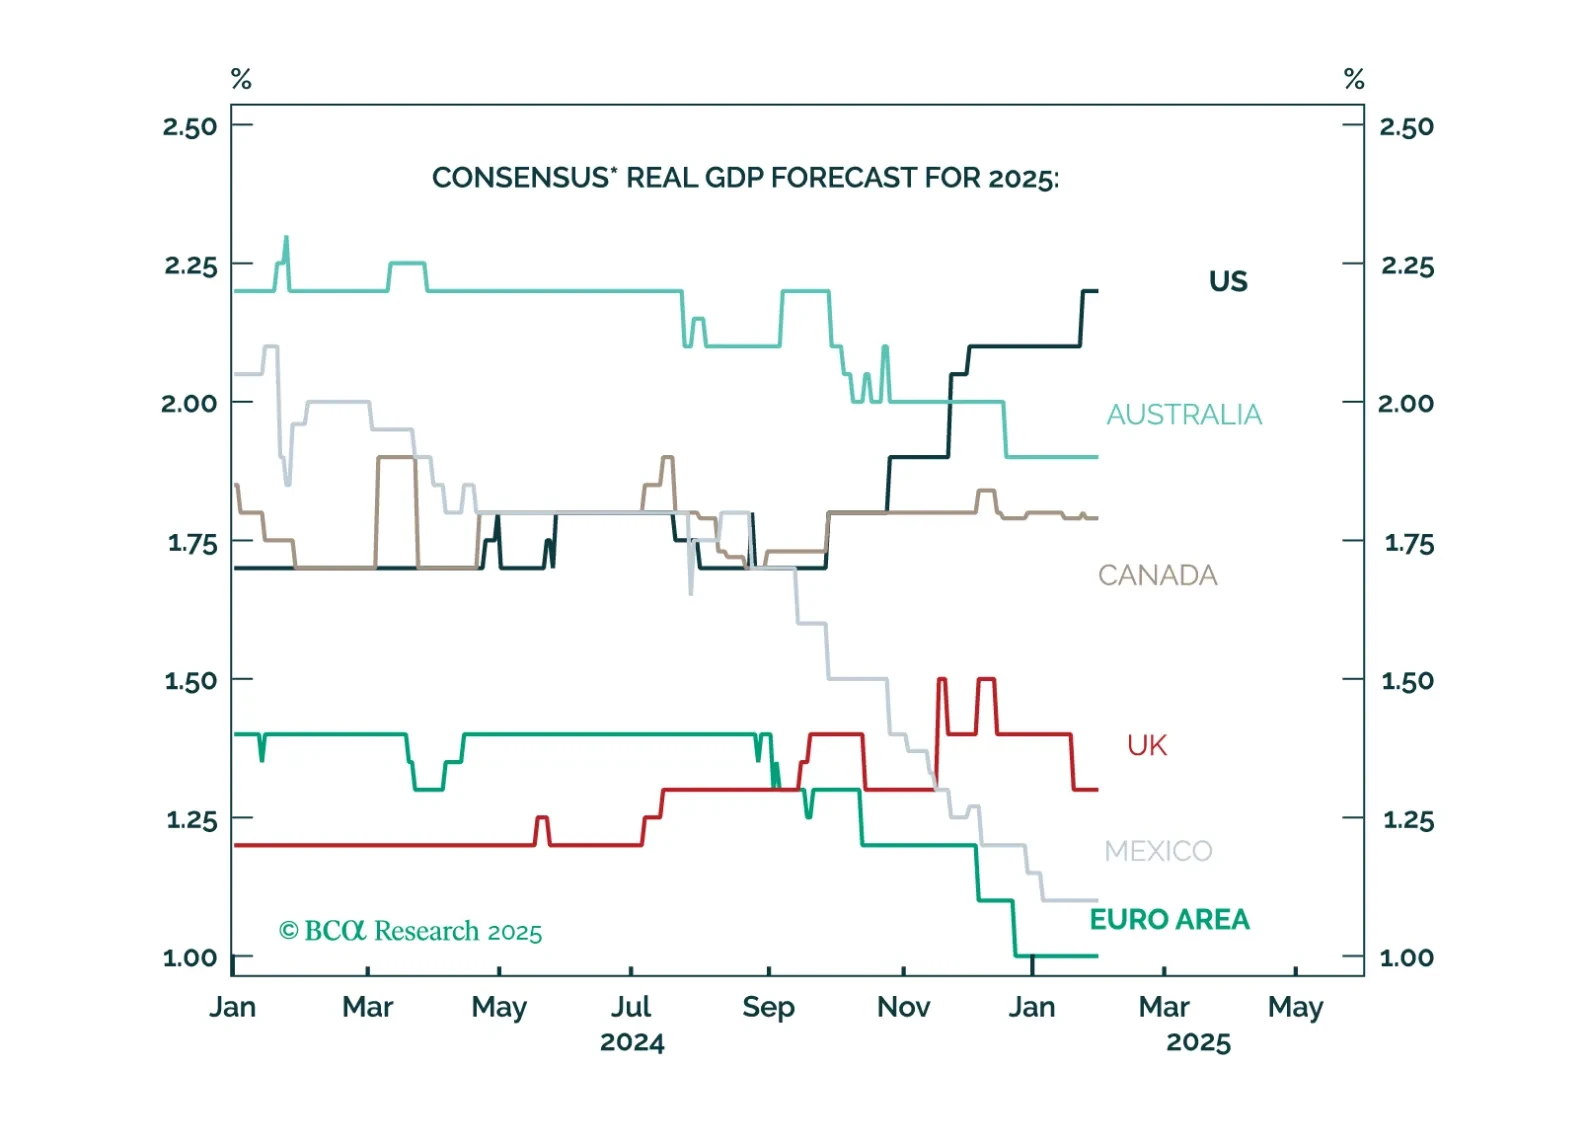
Markets and forecasters anticipate a “Golden Age” for Trump’s America, with US growth expectations soaring while the rest of the world lags. However, this extreme optimism means that there is a lot of room for disappointment. Cooling income growth, weak housing and less deficit spending than expected will result in US growth underperforming expectations. Maintain a modest underweight to equities and modest overweight to fixed income. US markets have become more expensive relative to the rest of the world even as quality differentials have stabilized. Prepare to downgrade US equities to underweight and to upgrade Euro Area and China to overweight. We will wait to pull the trigger until we have more clarity on trade policy and when the dollar's momentum turns negative.
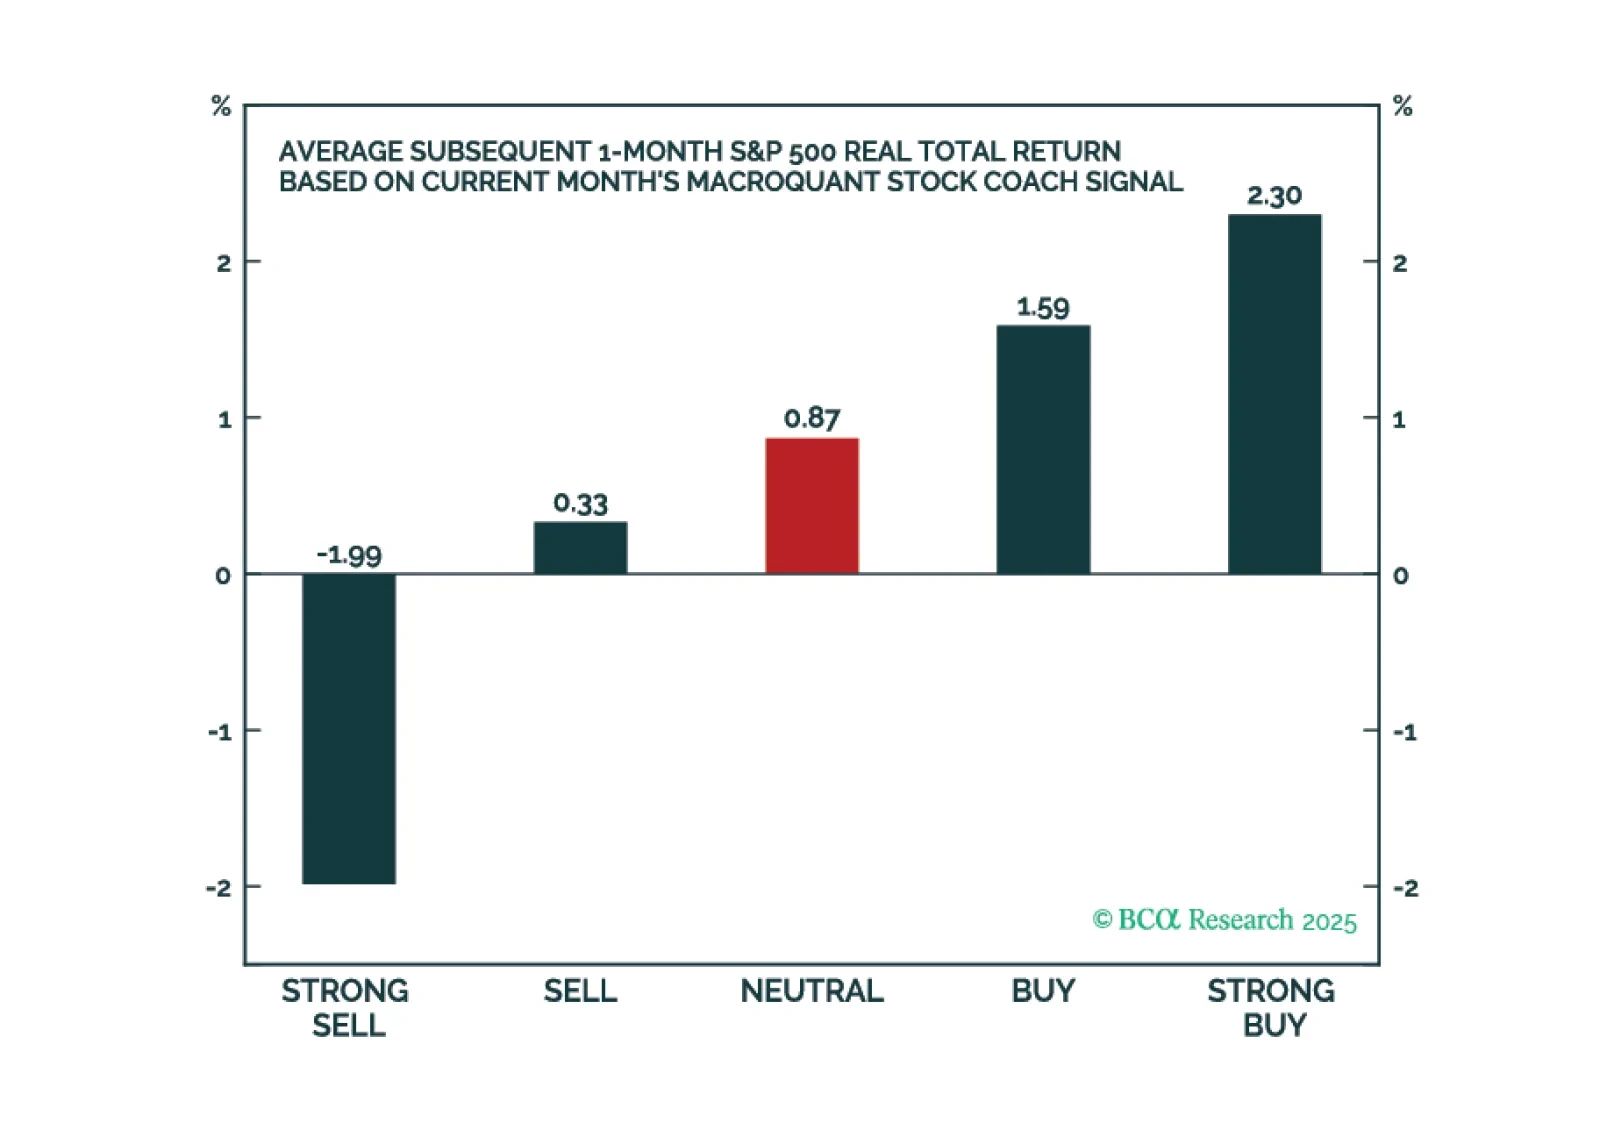
The latest version of the MacroQuant model suggests that the bull market in US stocks is winding down. The model expects Treasury yields to fall later this year but is not ready to go long duration just yet.
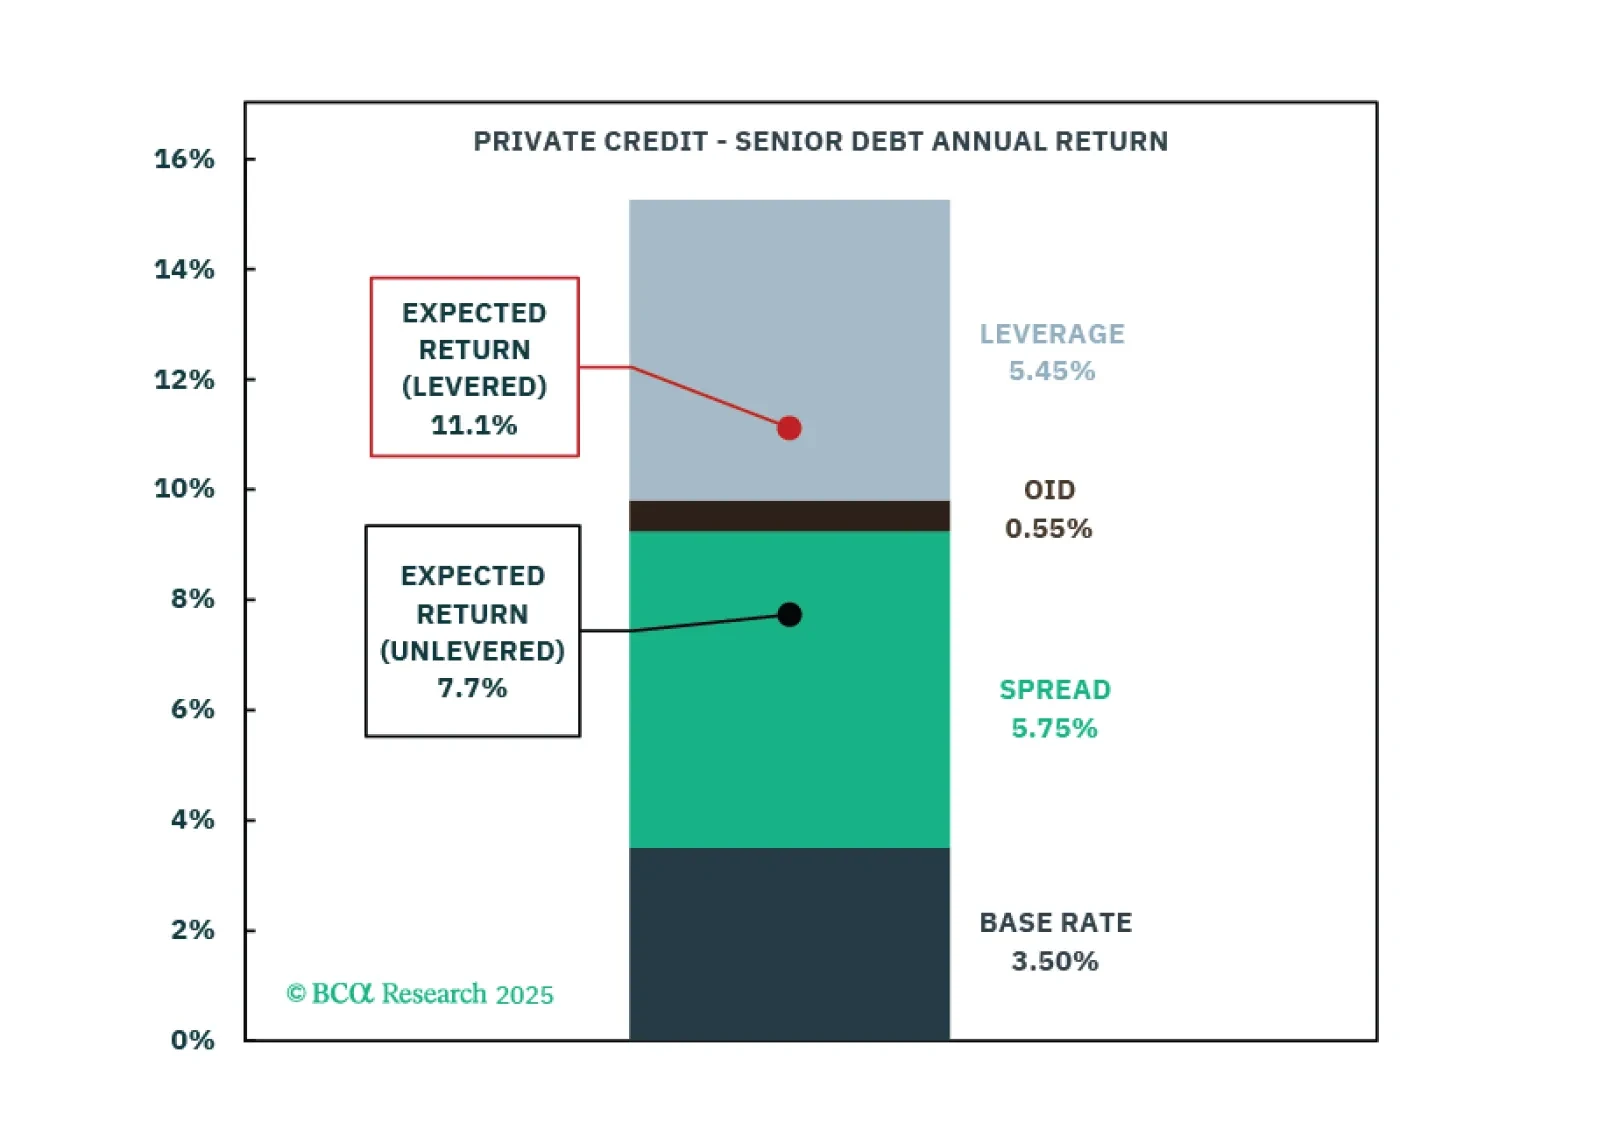
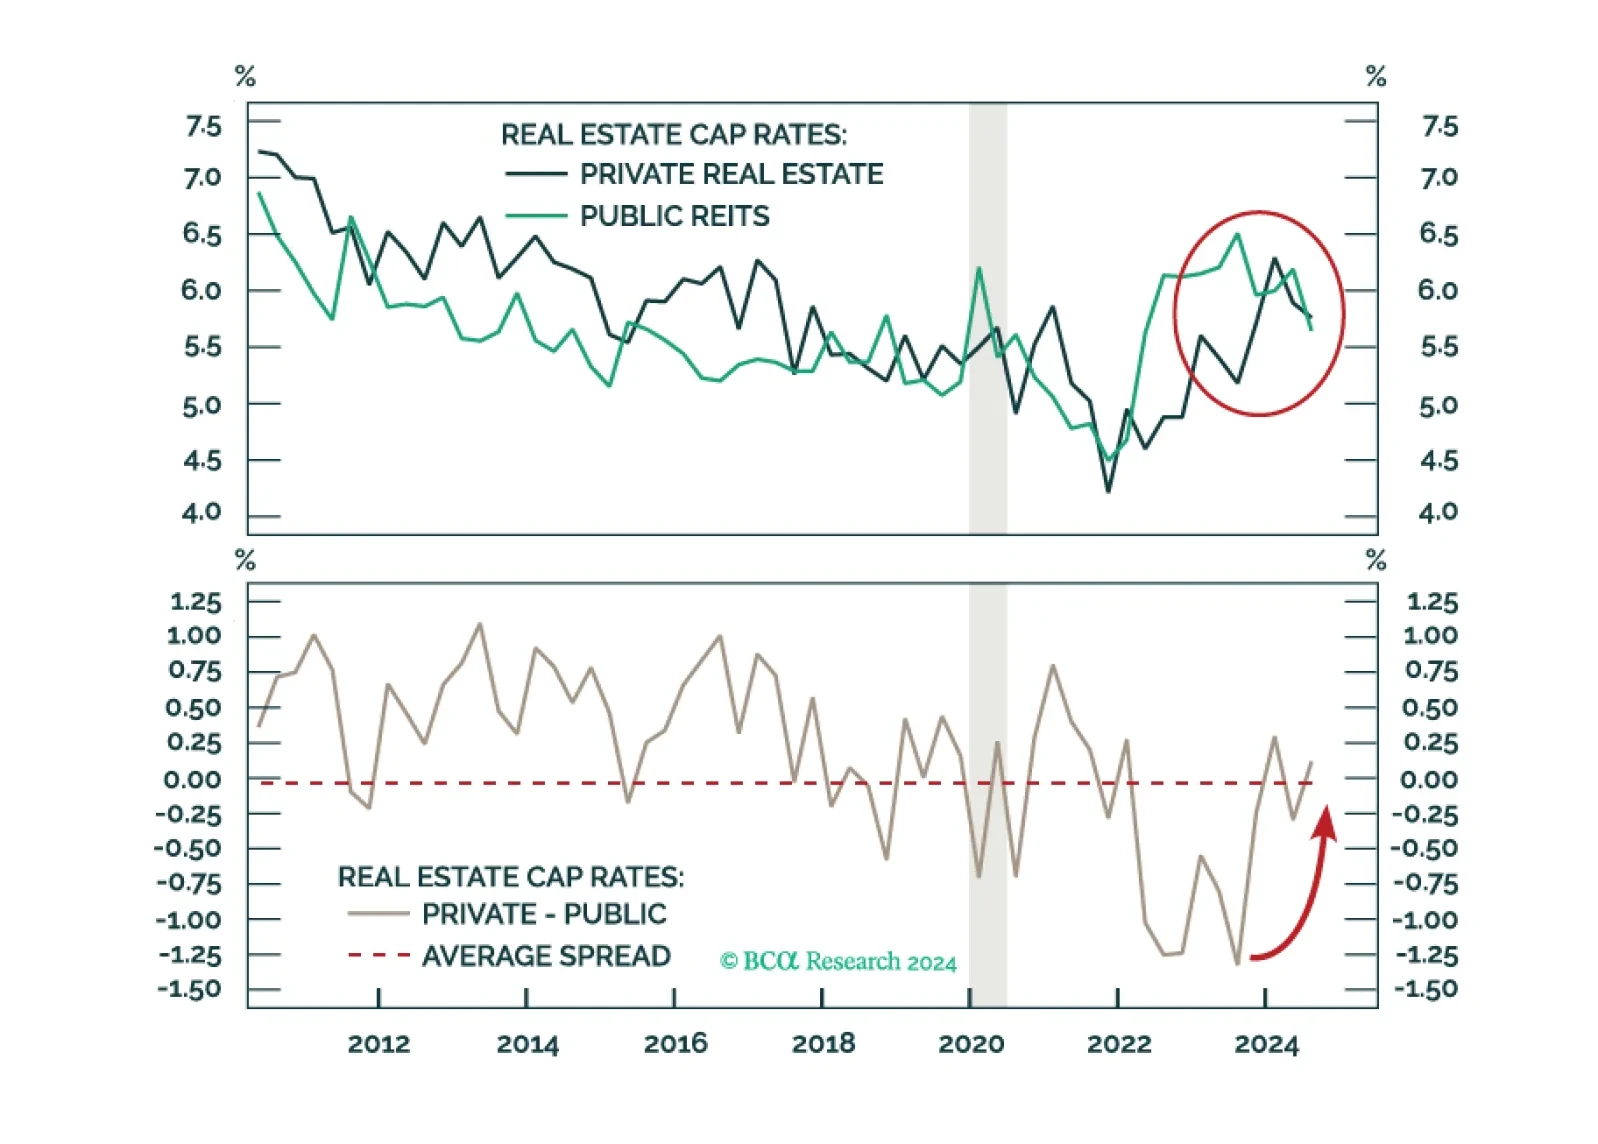
Asset class expectations show mixed shifts from 2024, with Real Estate seeing substantial upgrades and Private Equity benefiting from Venture Capital improvements. Private Credit return expectations decline from 2024 but remain relatively attractive. Infrastructure shows varied dynamics across sub-strategies, with Value-Add offering strong return potential. Within Hedge Funds, Long-Short Equity shows higher tactical returns while Multi-Strategy leads strategic projections.
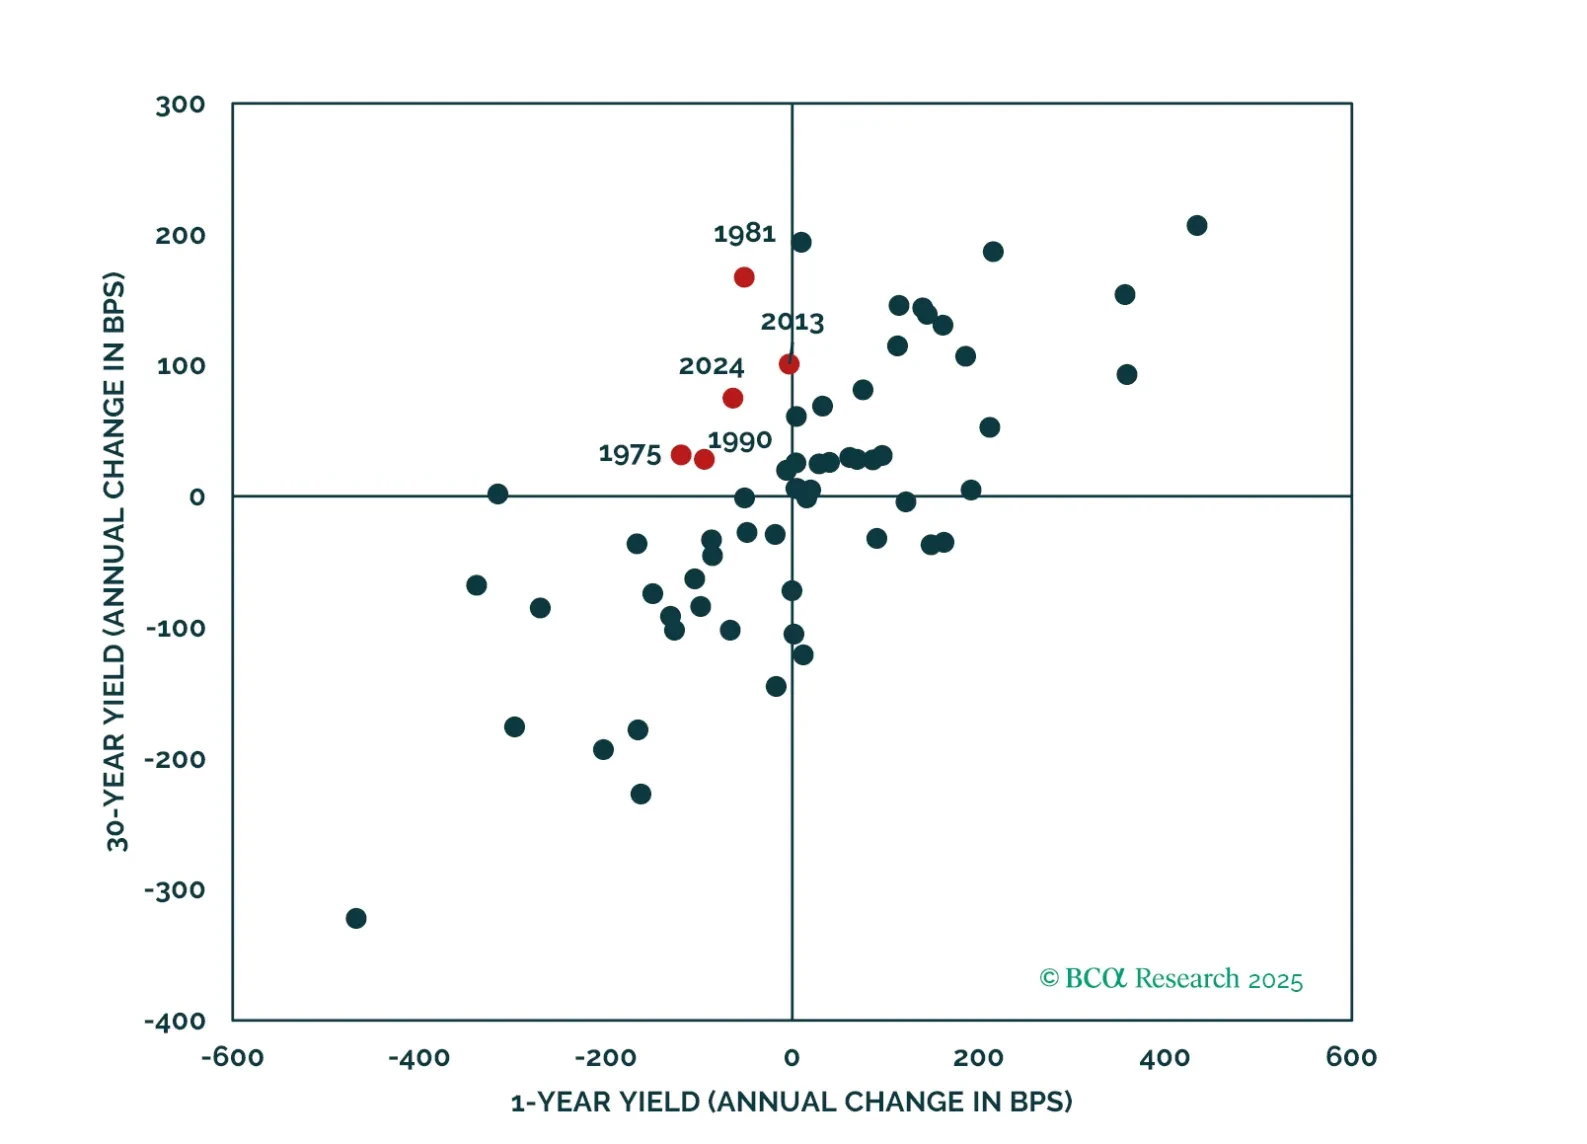
Paradoxically, raging optimism on the US economy is making a reacceleration in growth less likely in 2025. The reaction of the bond market has made the Fed rethink its cutting campaign. Markets are also constraining Trump’s agenda. US manufacturing will not recover with a surging dollar. Fears of inflation and debt sustainability have made moderate House Republicans push back against the President Elect’s wishes. Given the sky-high optimism embedded in asset prices, we believe a defensive portfolio stance is warranted on a 12-month horizon. Overweight gold to hedge the risk of a fiscal crisis.
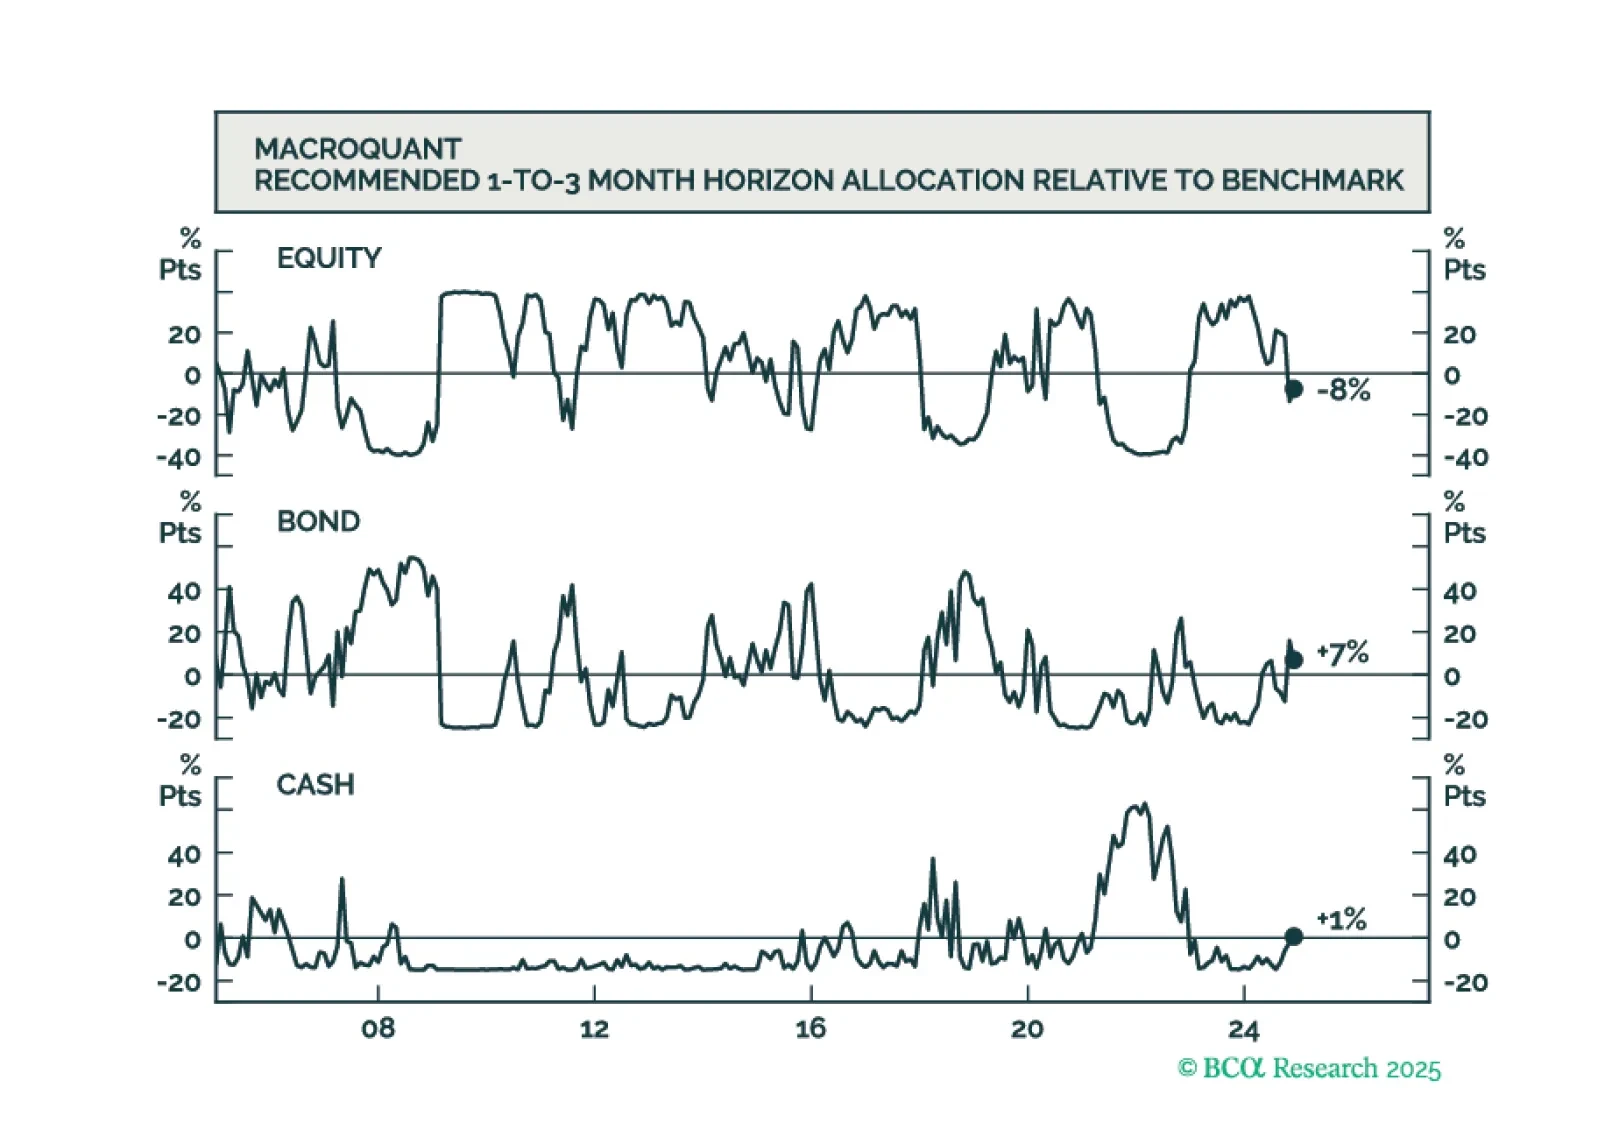
The latest version of the MacroQuant model sees the near-term risks to stocks as slightly tilted to the downside. It is neutral on bond duration and expects the US dollar to continue strengthening in the near term.
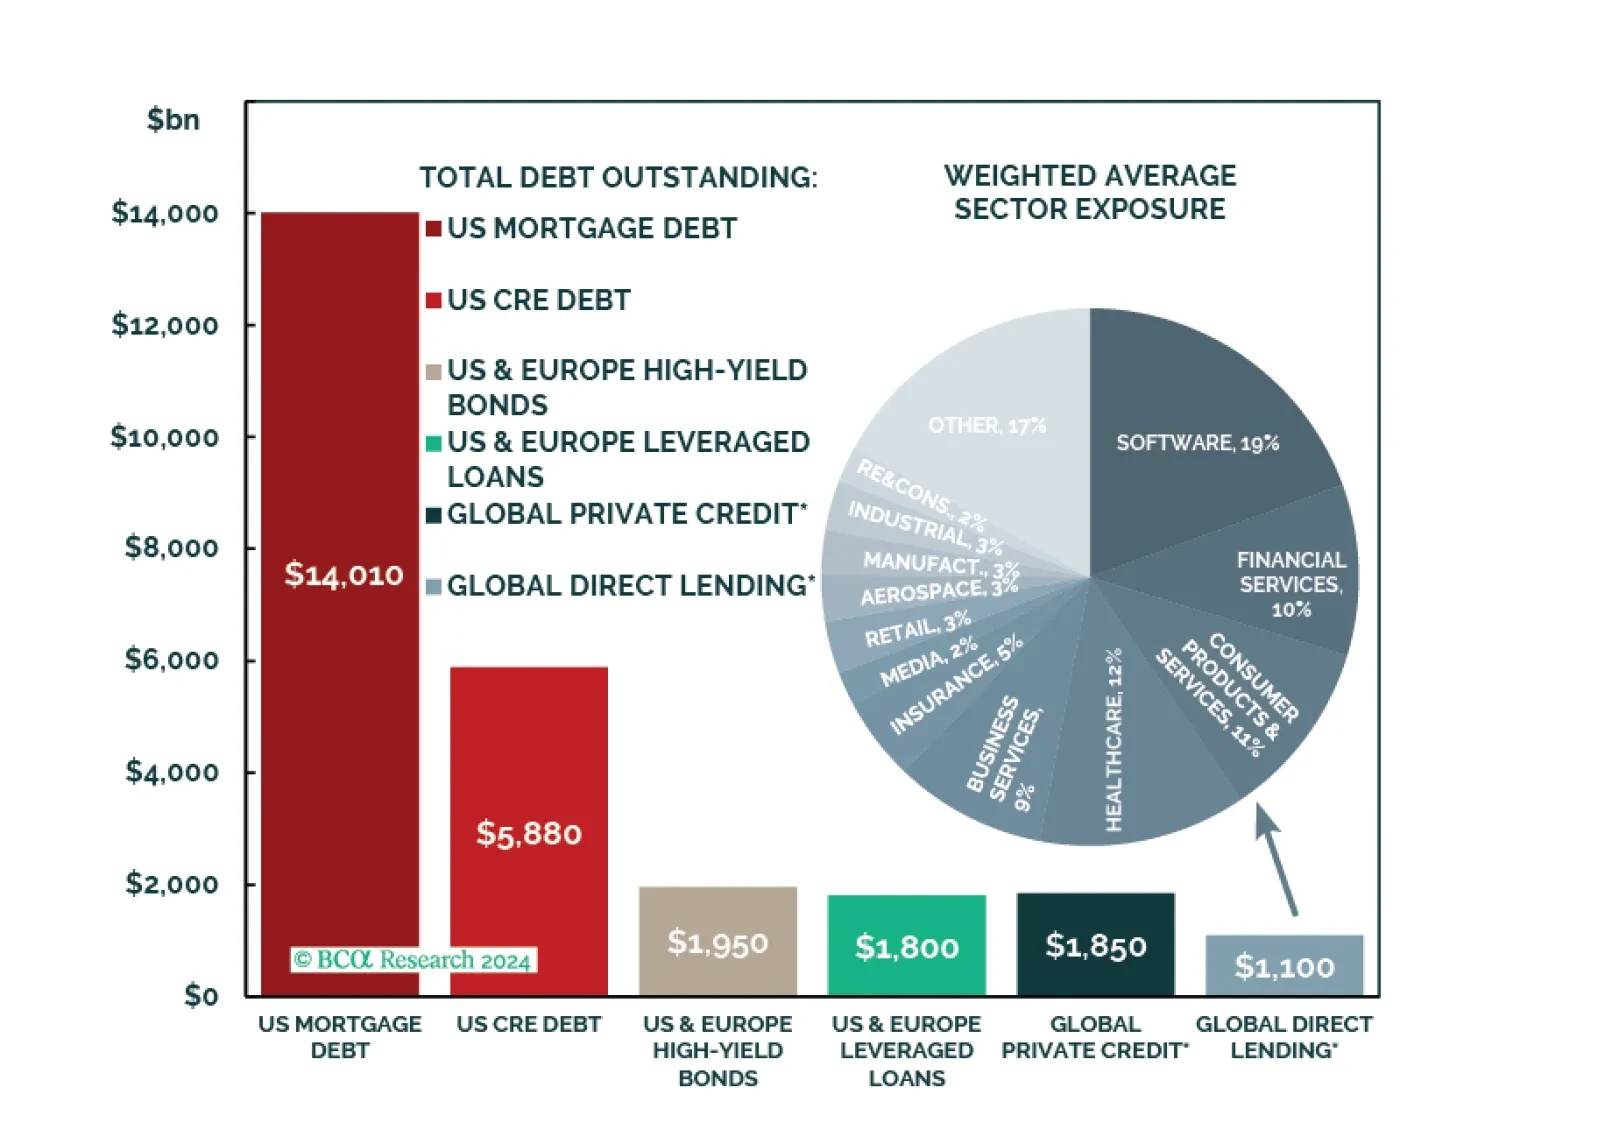
Understanding the risks across Private Credit will enable investors to be offensive, not just with sizing but across their total portfolio. Senior Direct Lending is not risk-free, Private Credit is not systemic, and a liquidity crisis will not be born in this asset class.
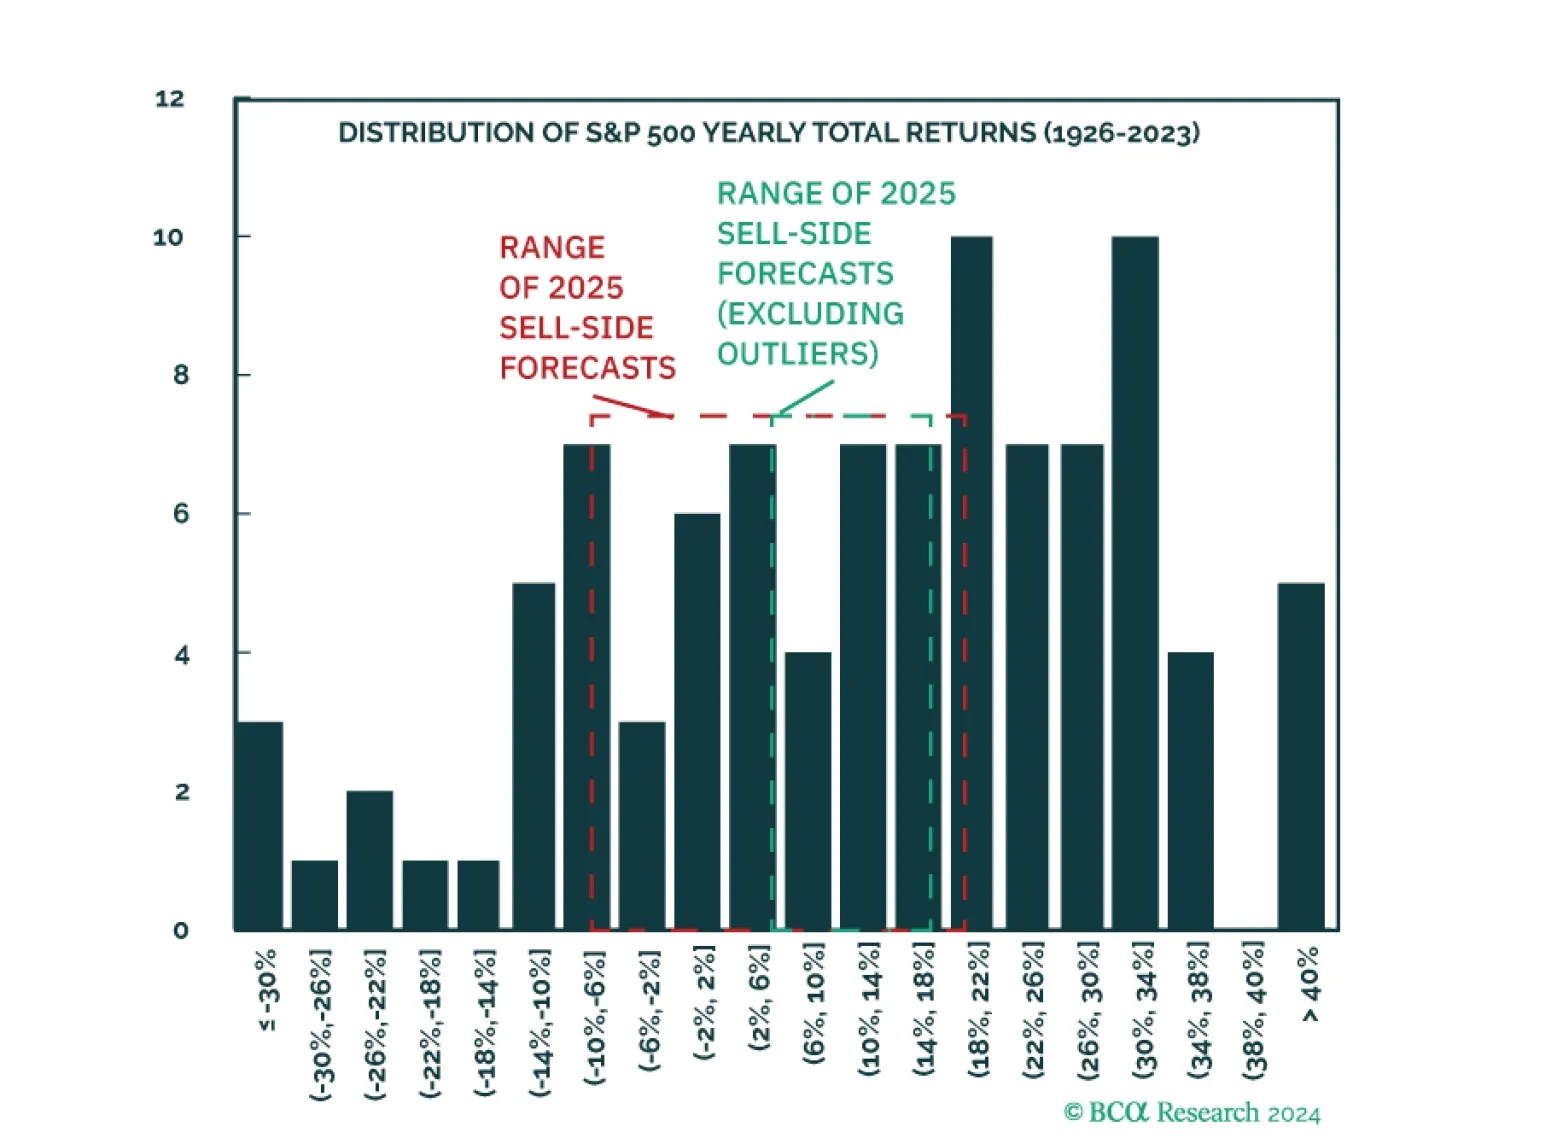
The range of forecast for the S&P 500 is too narrow. While most strategists are predicting an average year for the S&P 500, average returns do not happen often. The S&P is more likely to fall to below 5500 or rise above 7100, than to stay within the range of forecast. As a result, our negative view will either be spectacularly right or spectacularly wrong.
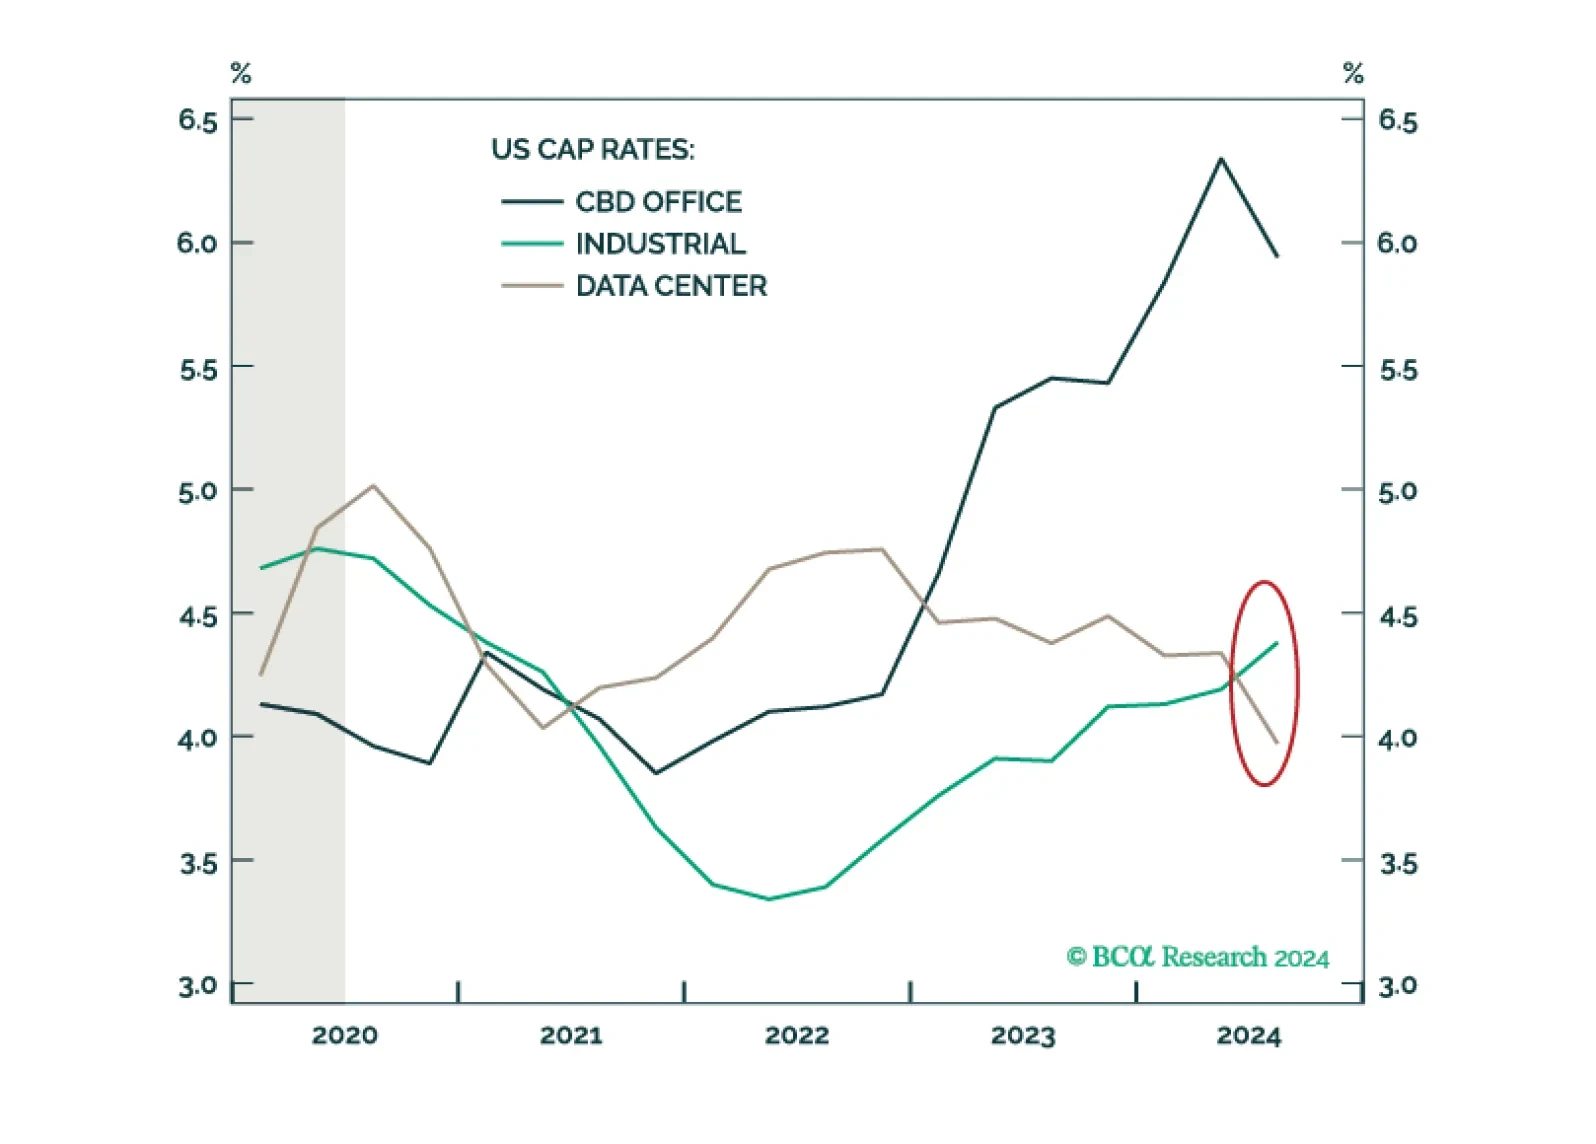
While AI deployment creates compelling investment opportunities, hyperscale facilities are not the only path forward. Investors should consider Office conversions into colocation Data Centers as the next dollar opportunity.