Latest from BCA Research
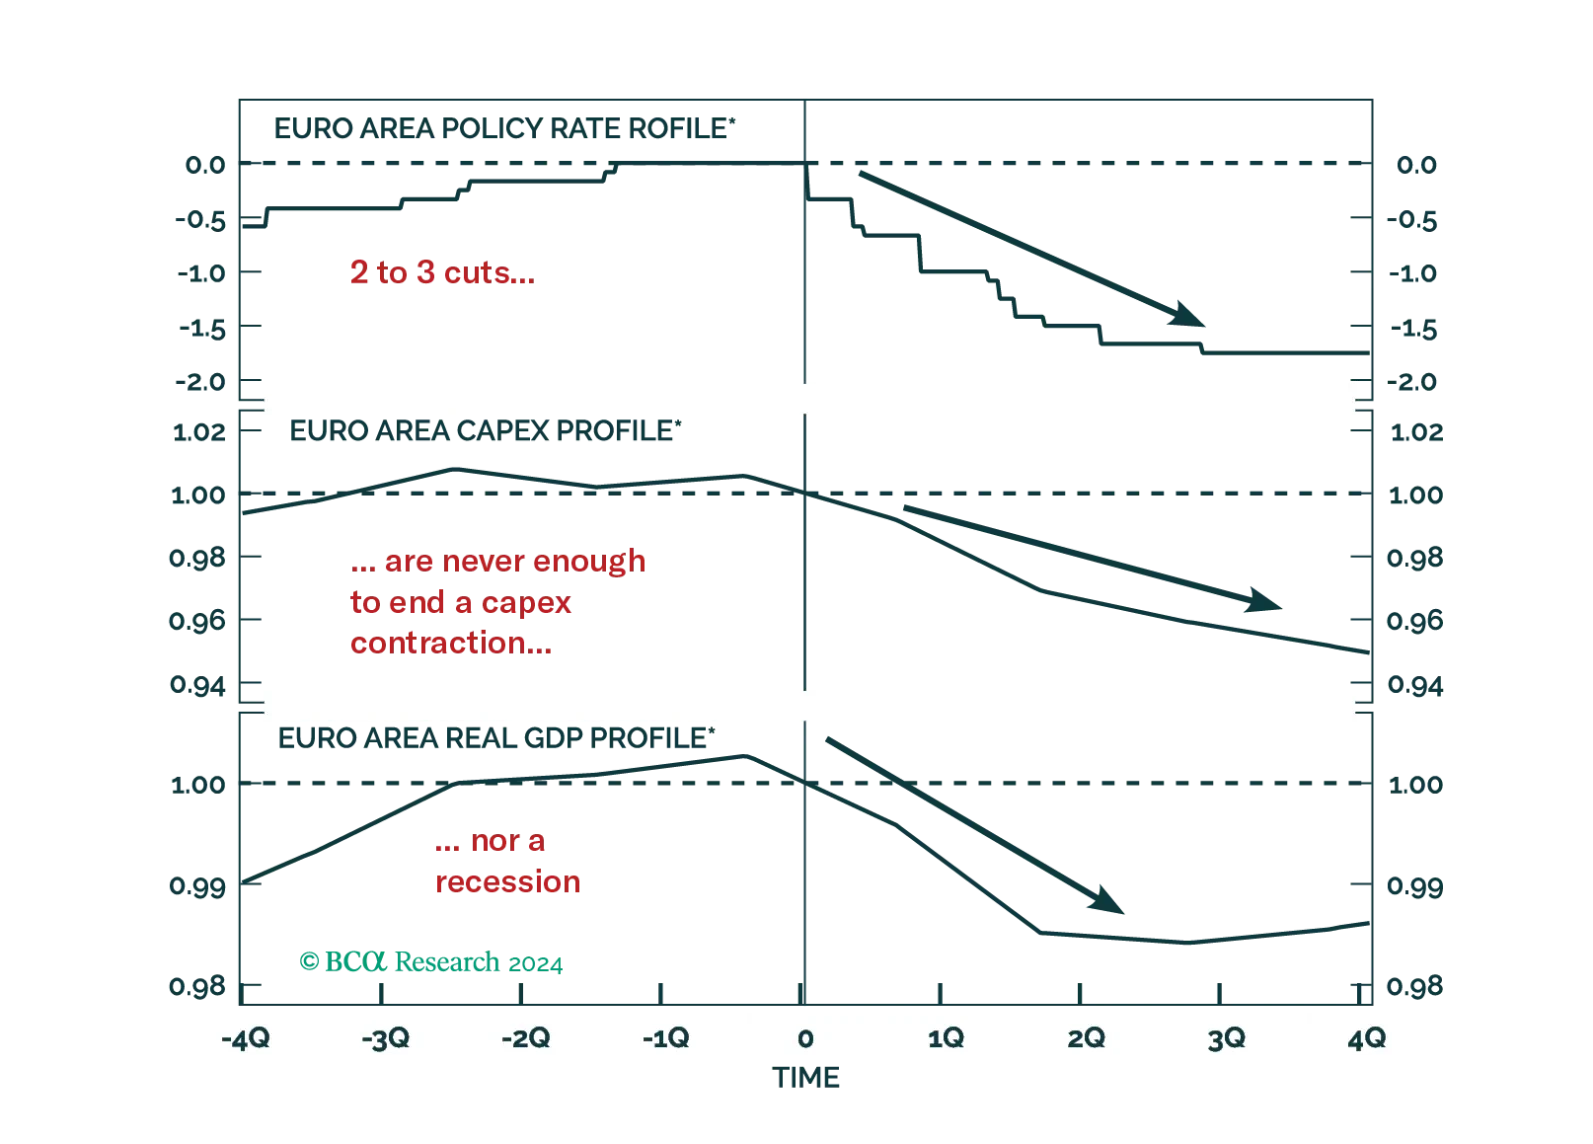
Investors hope that the ECB rate cuts priced into the curve will be sufficient to achieve a soft landing in Europe. History argues against this view, but will this time be different?
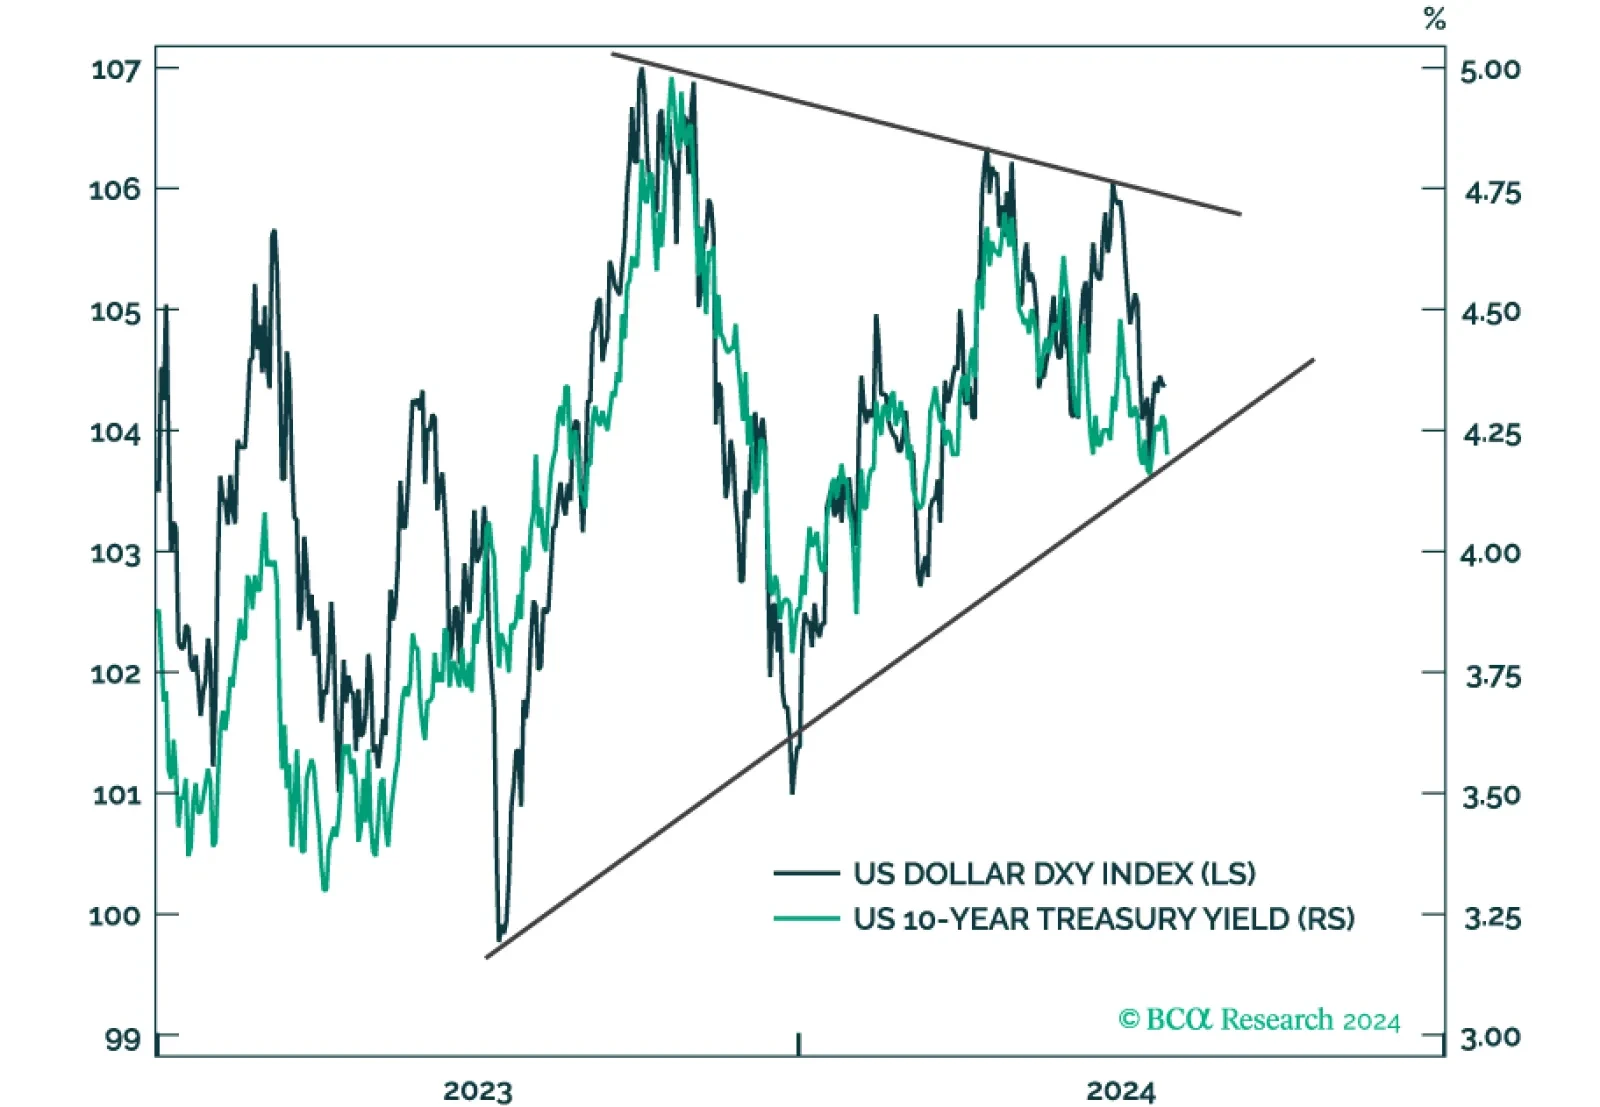
This report takes a look at bond and FX market technical indicators and calibrates the decision to increase portfolio duration and get long the US dollar.
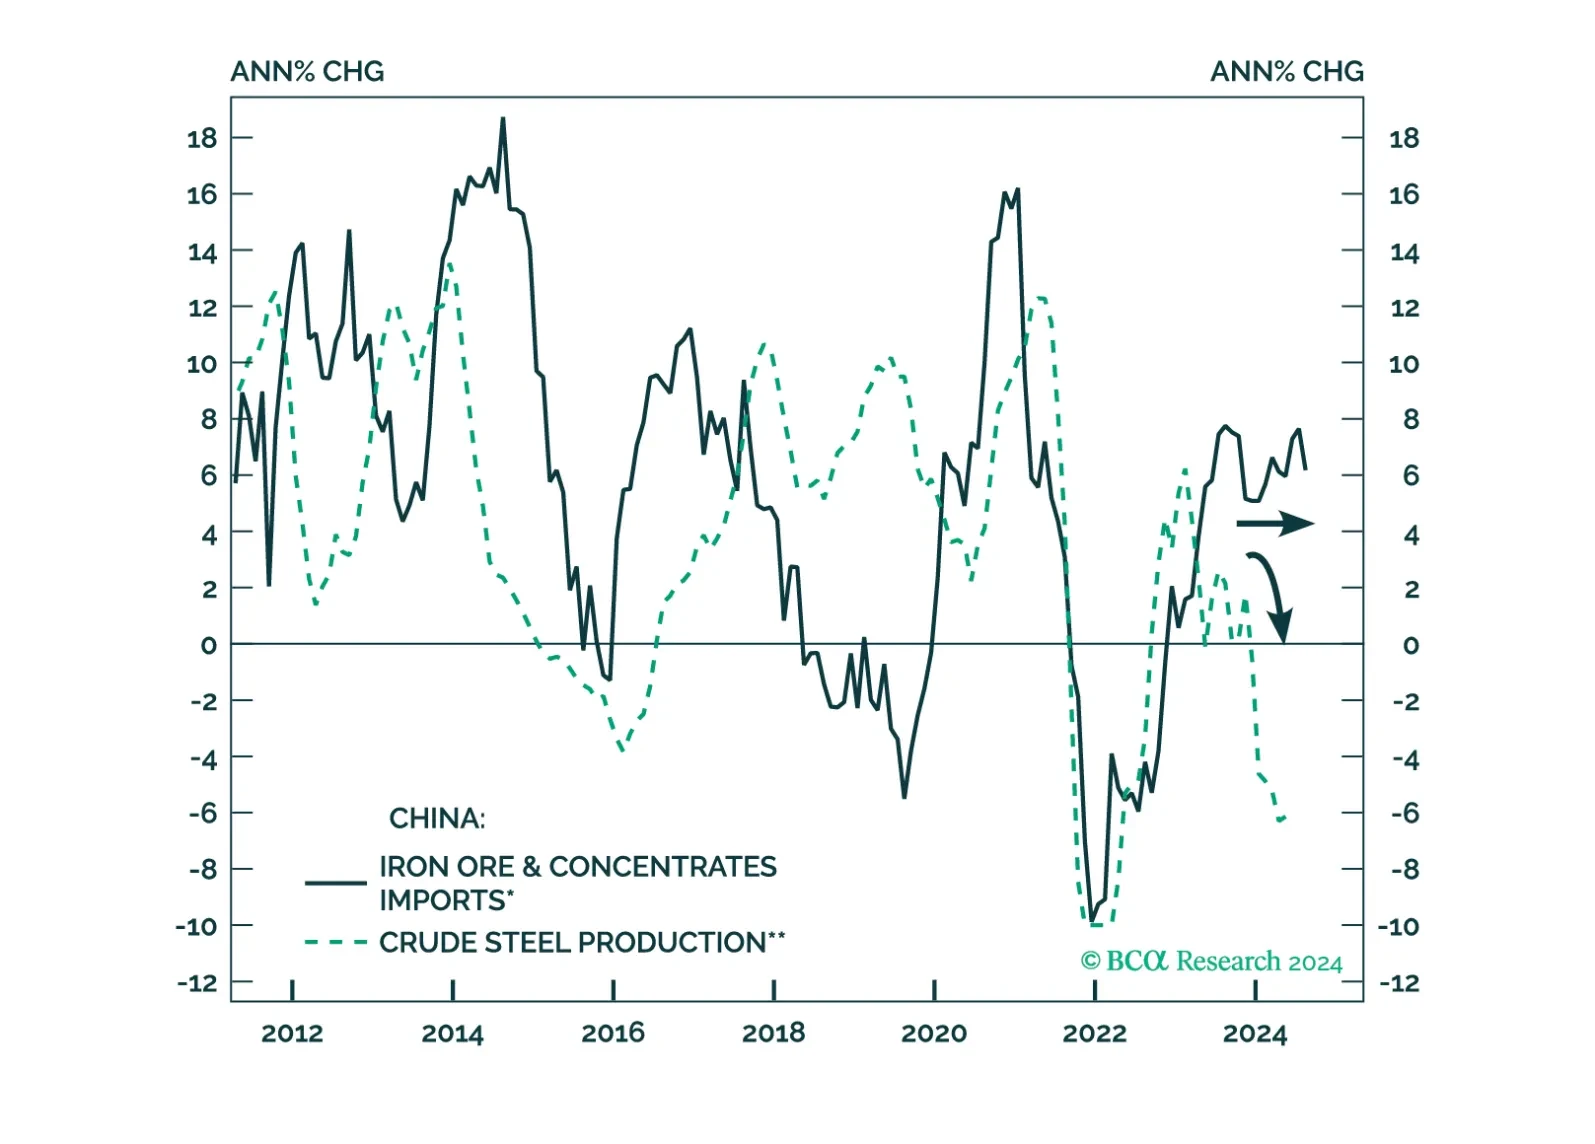
The absence of a catalyst that will boost Chinese steel demand dims the odds that iron ore and steel prices will recover over the coming six-to-nine months. Instead, we expect ferrous metals to face further downside into year-end.

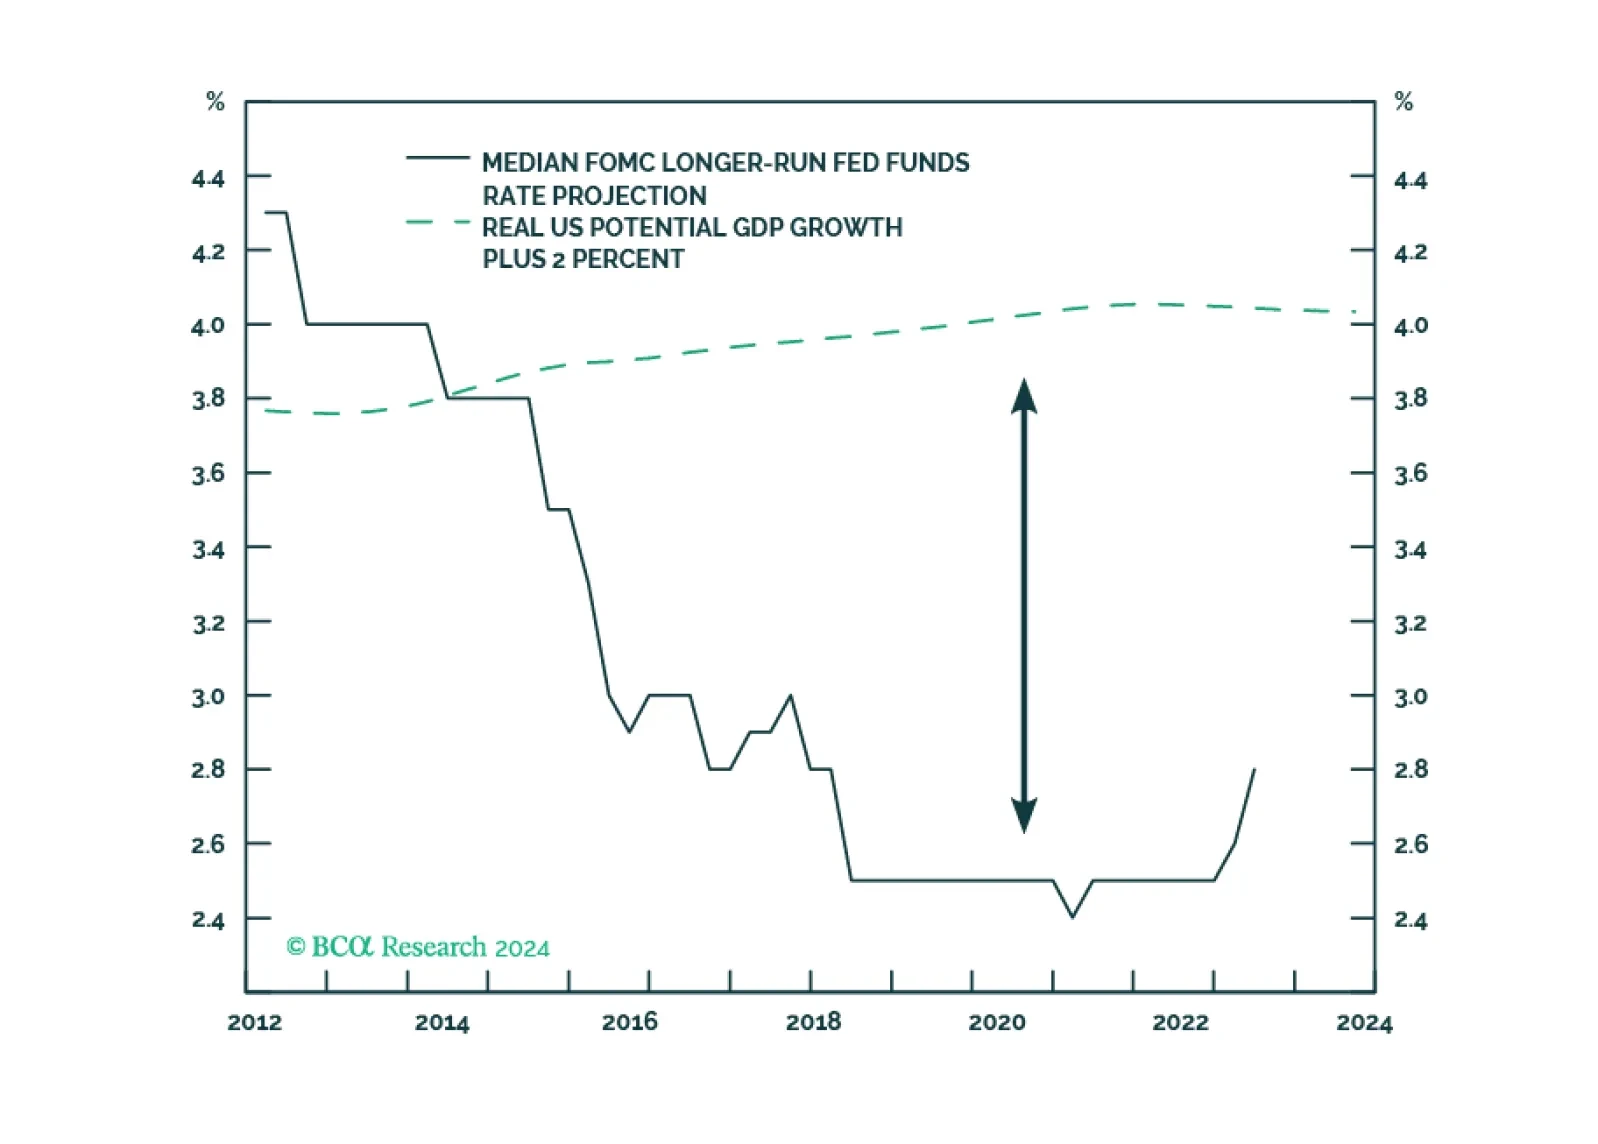
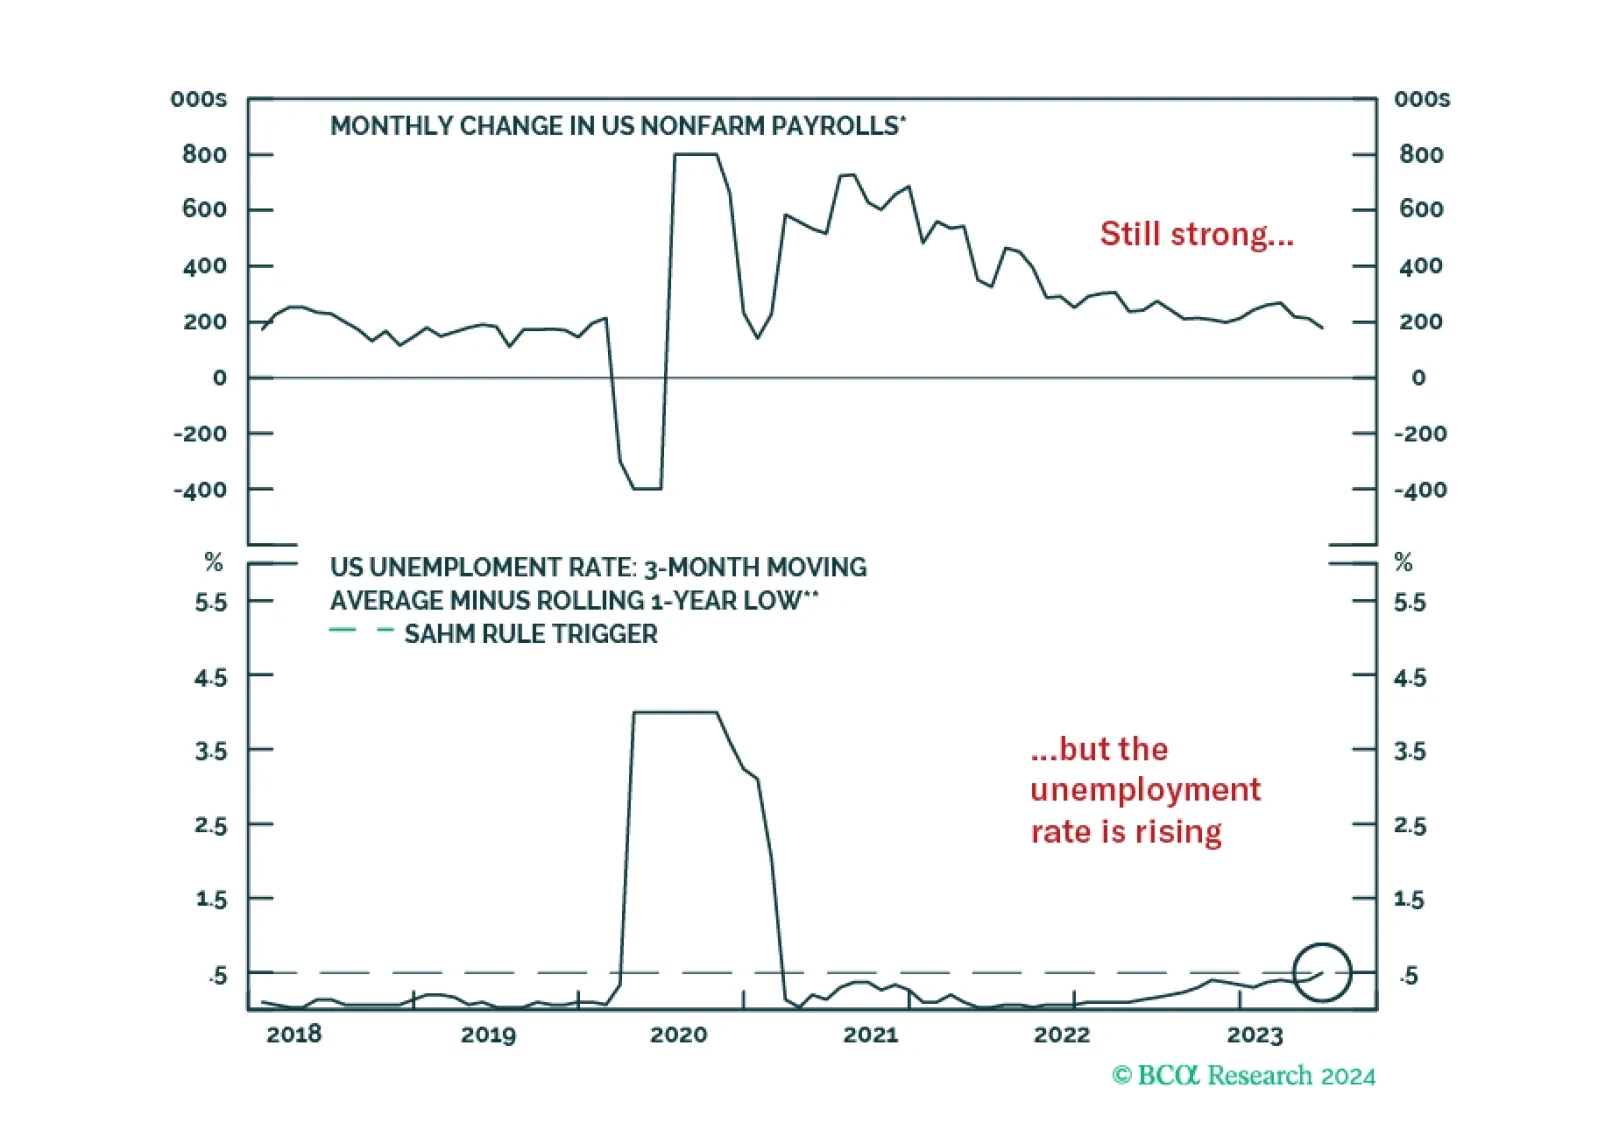
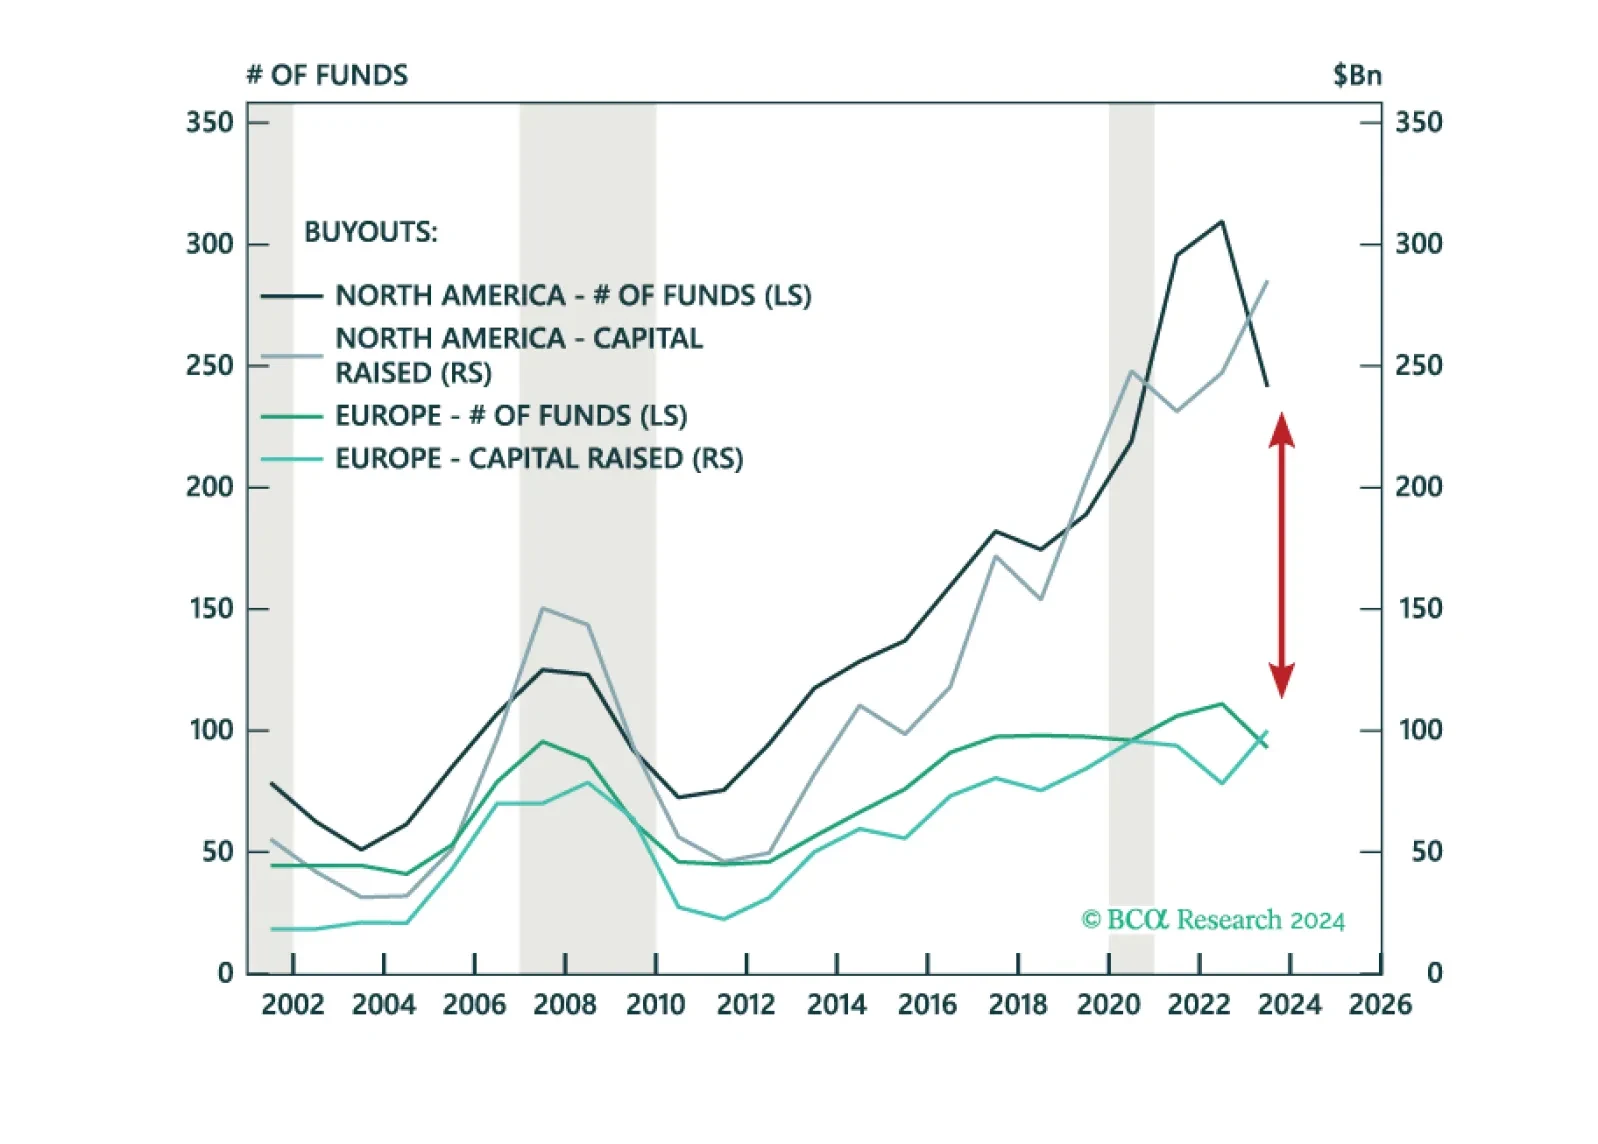
We are growing positive on Growth assets with recession expectations increasing our optimism on entry points. Equities are led by APAC Private Equity, North America Venture Capital, and Europe Buyouts. Our outlook continues to improve on CRE within the Inflation & Diversification bucket while we are underweight Multi-Strategy amongst Hedge Funds. We maintain an overweight to Senior Direct Lending for Income with a preference for North America.
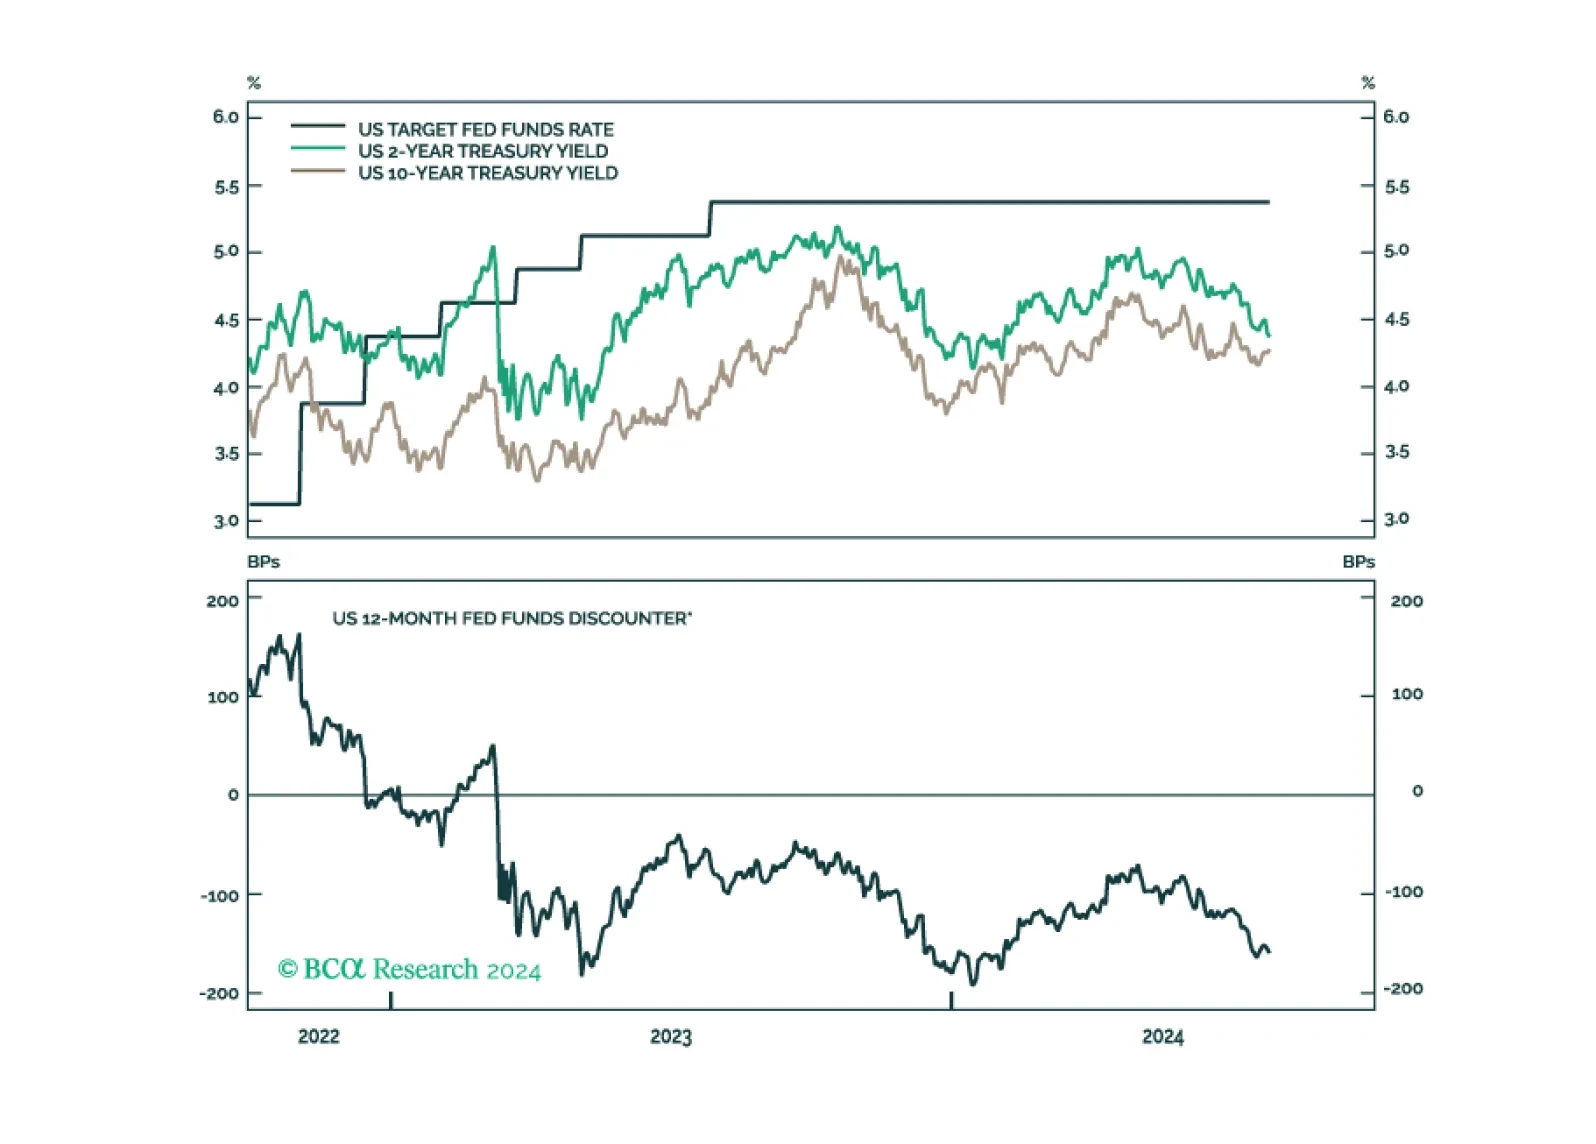
After this morning’s jobless claims number, we have now seen enough deterioration in our preferred labor market indicators to increase portfolio duration from “at benchmark” to “above benchmark”.
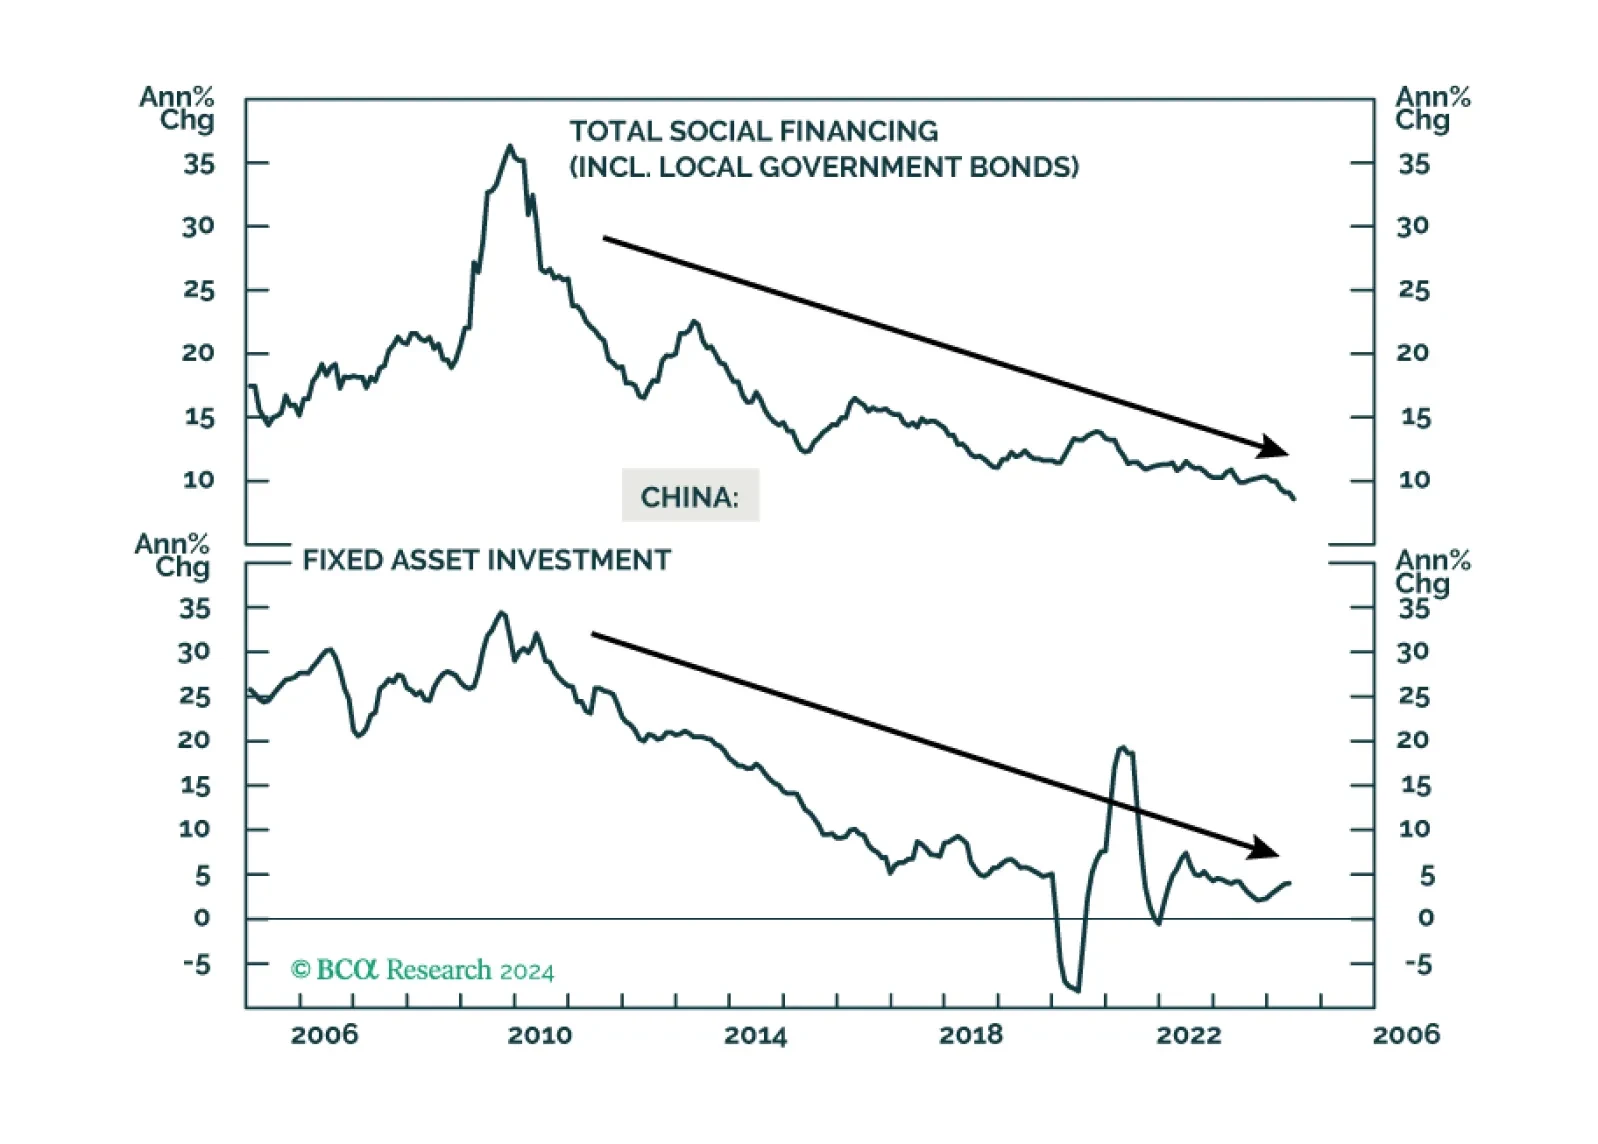
This report provides our framework for interpreting the messages from last week’s Third Plenum, and the potential implications for the economy and investors.