Latest from BCA Research
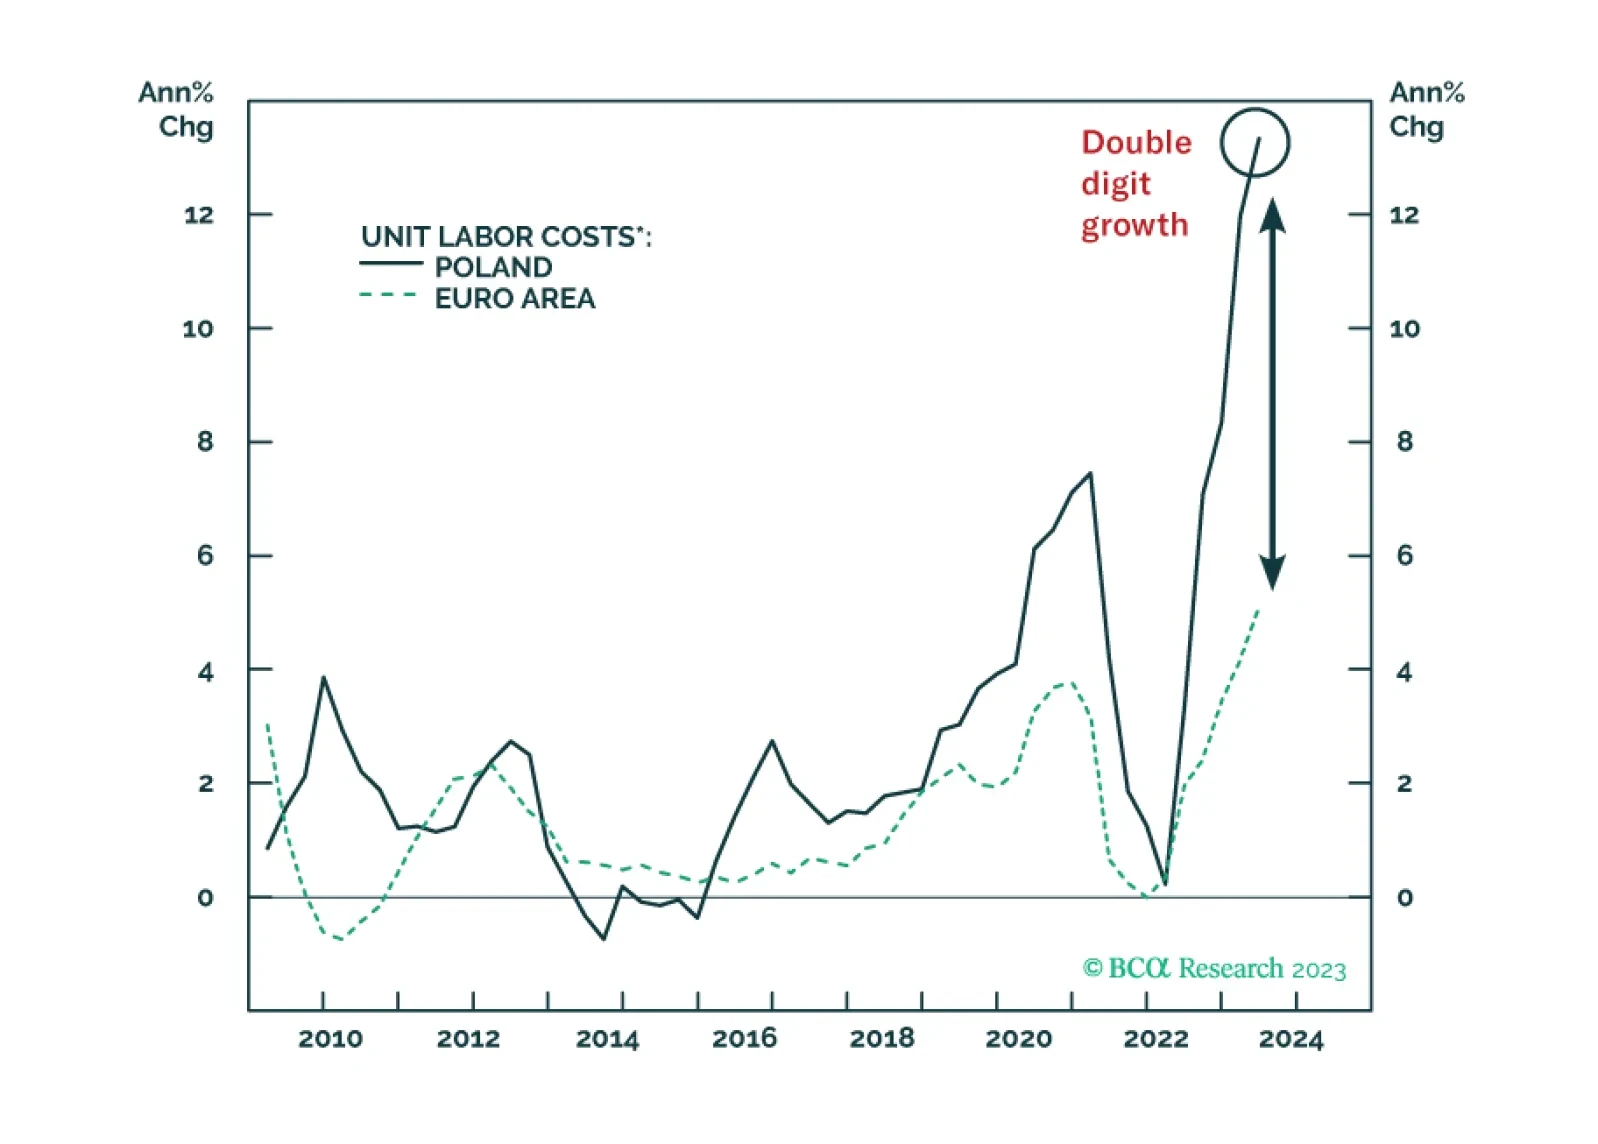
Poland’s inflation will stay elevated. And yet, its return to the European mainstream has improved its financial market outlook. Accordingly, we are recommending new trades on Polish equity, fixed income, and currency.
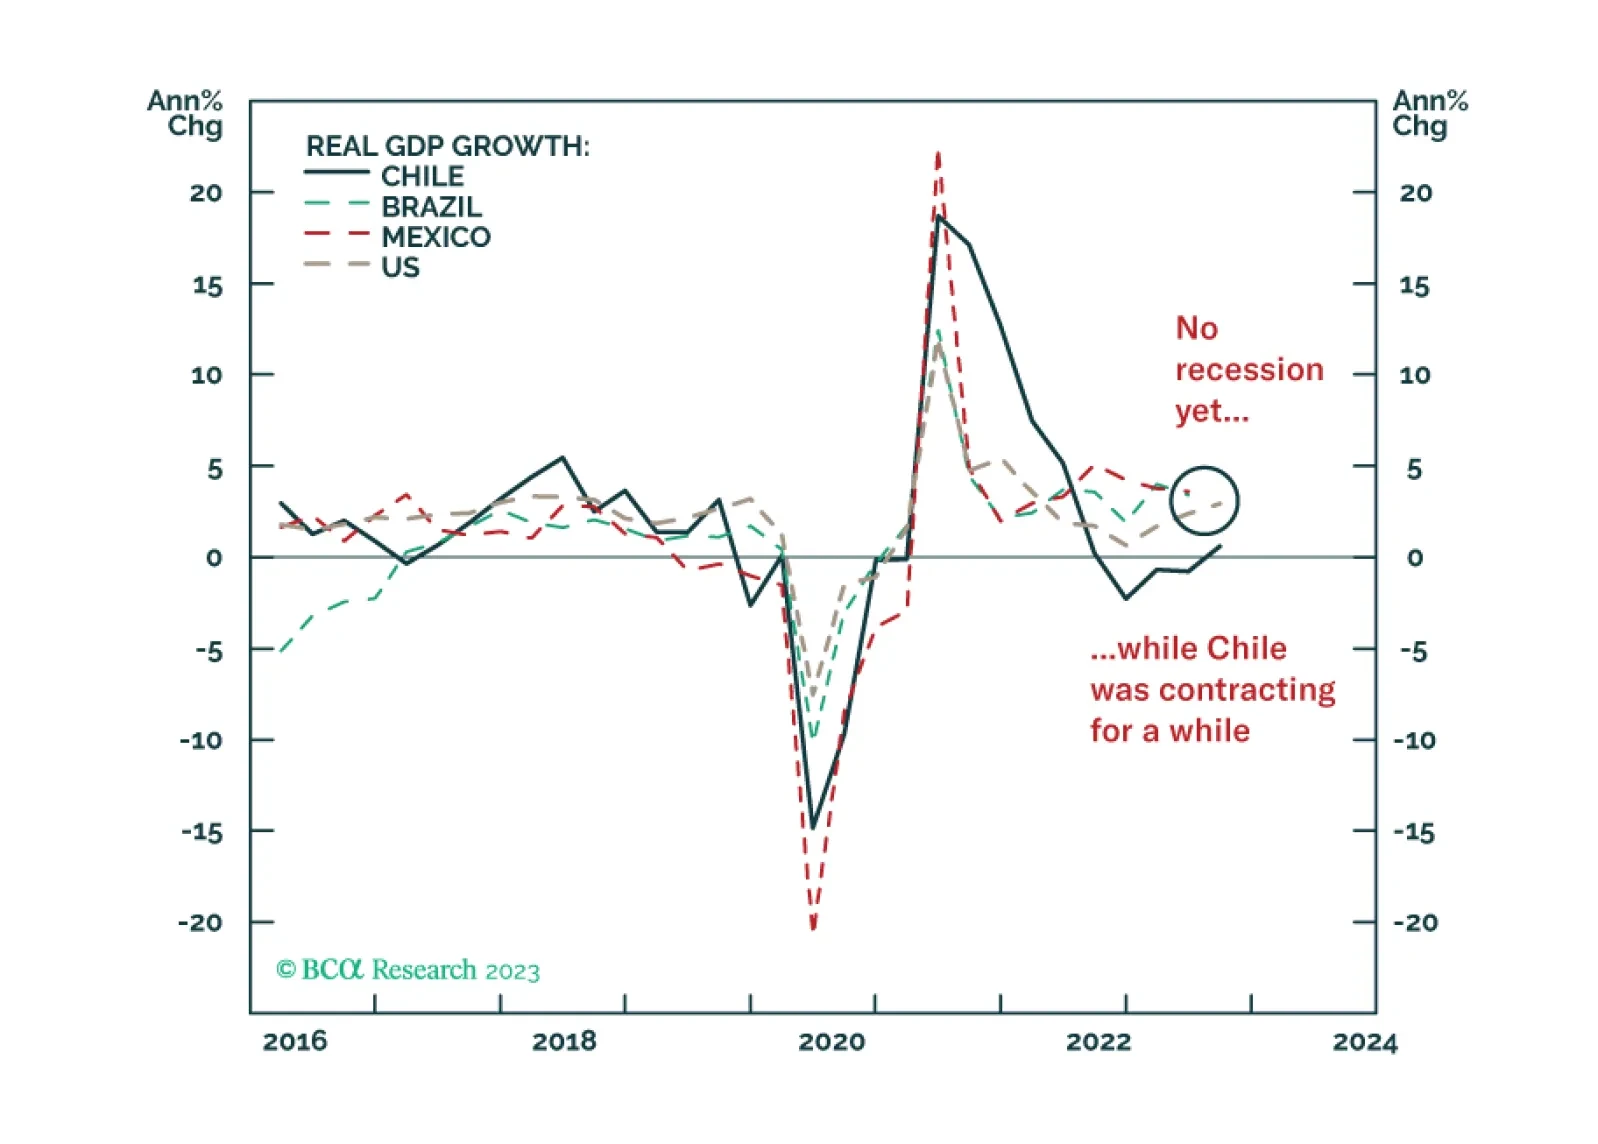
The Chilean economy is in a unique position worldwide: as it is the first to enter a recession, it will be the first to recover. Together with historically cheap valuations, this will lead to a sustained outperformance of Chilean stocks relative to their EM peers.
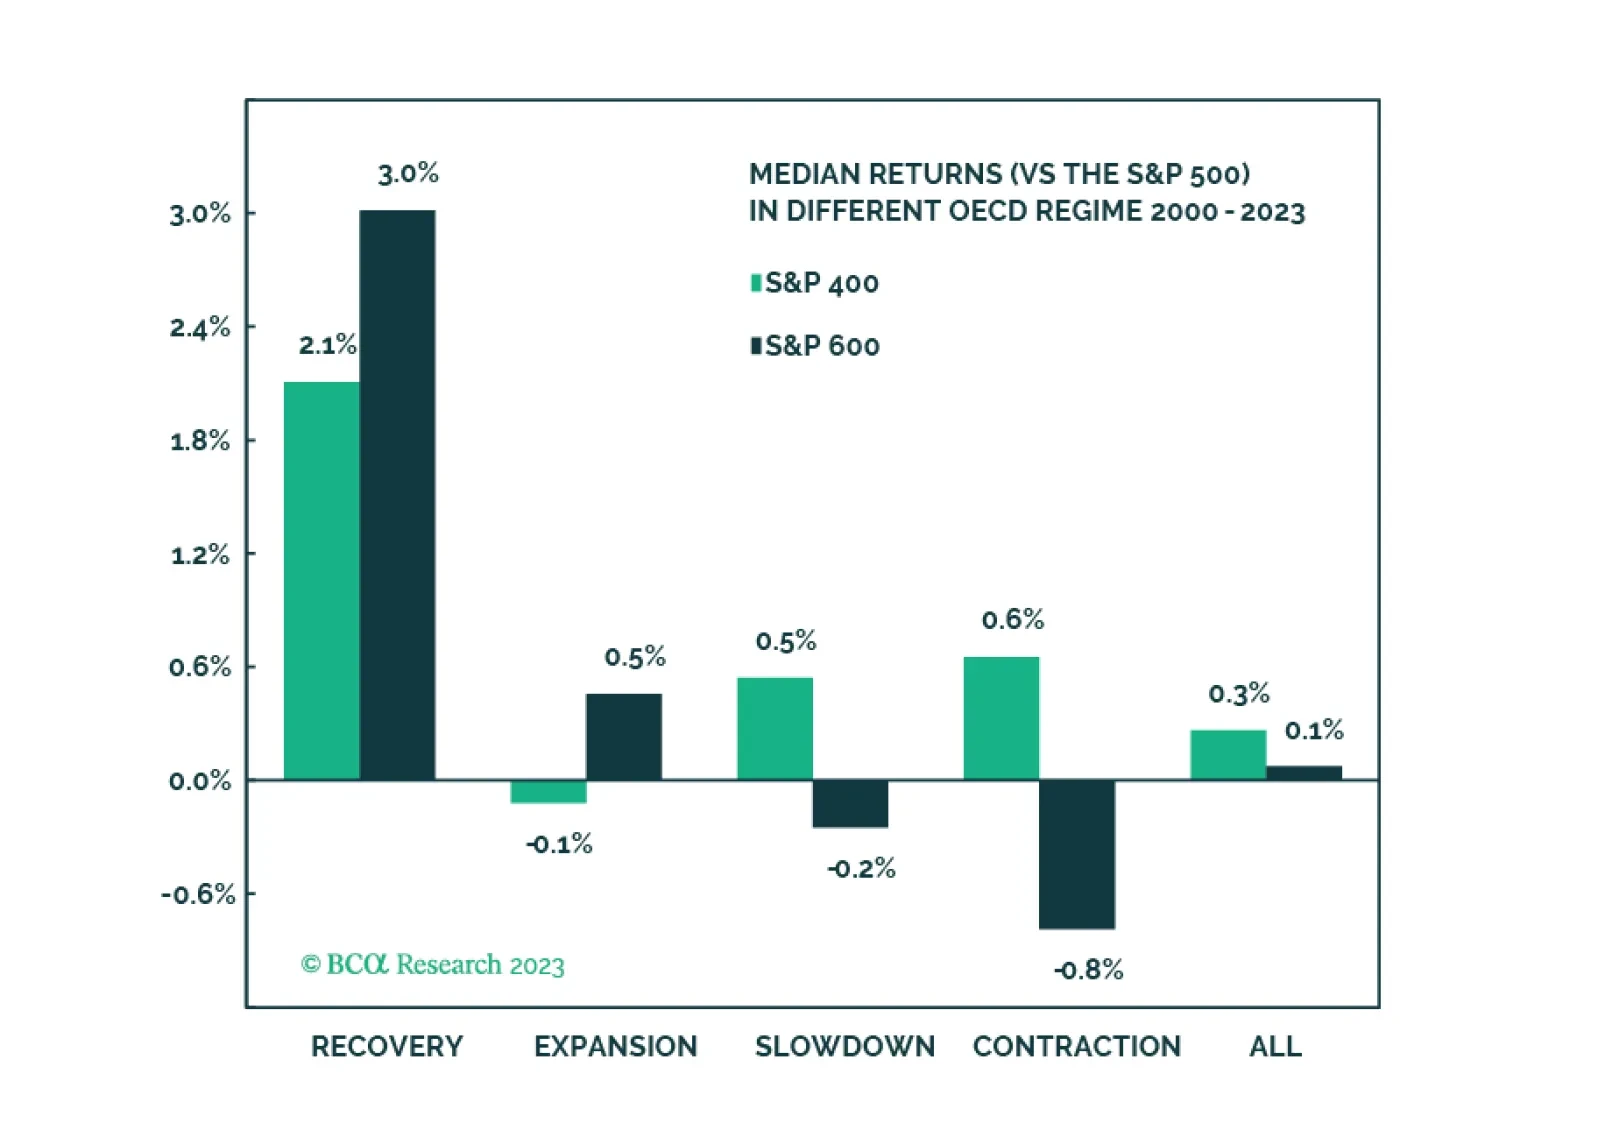
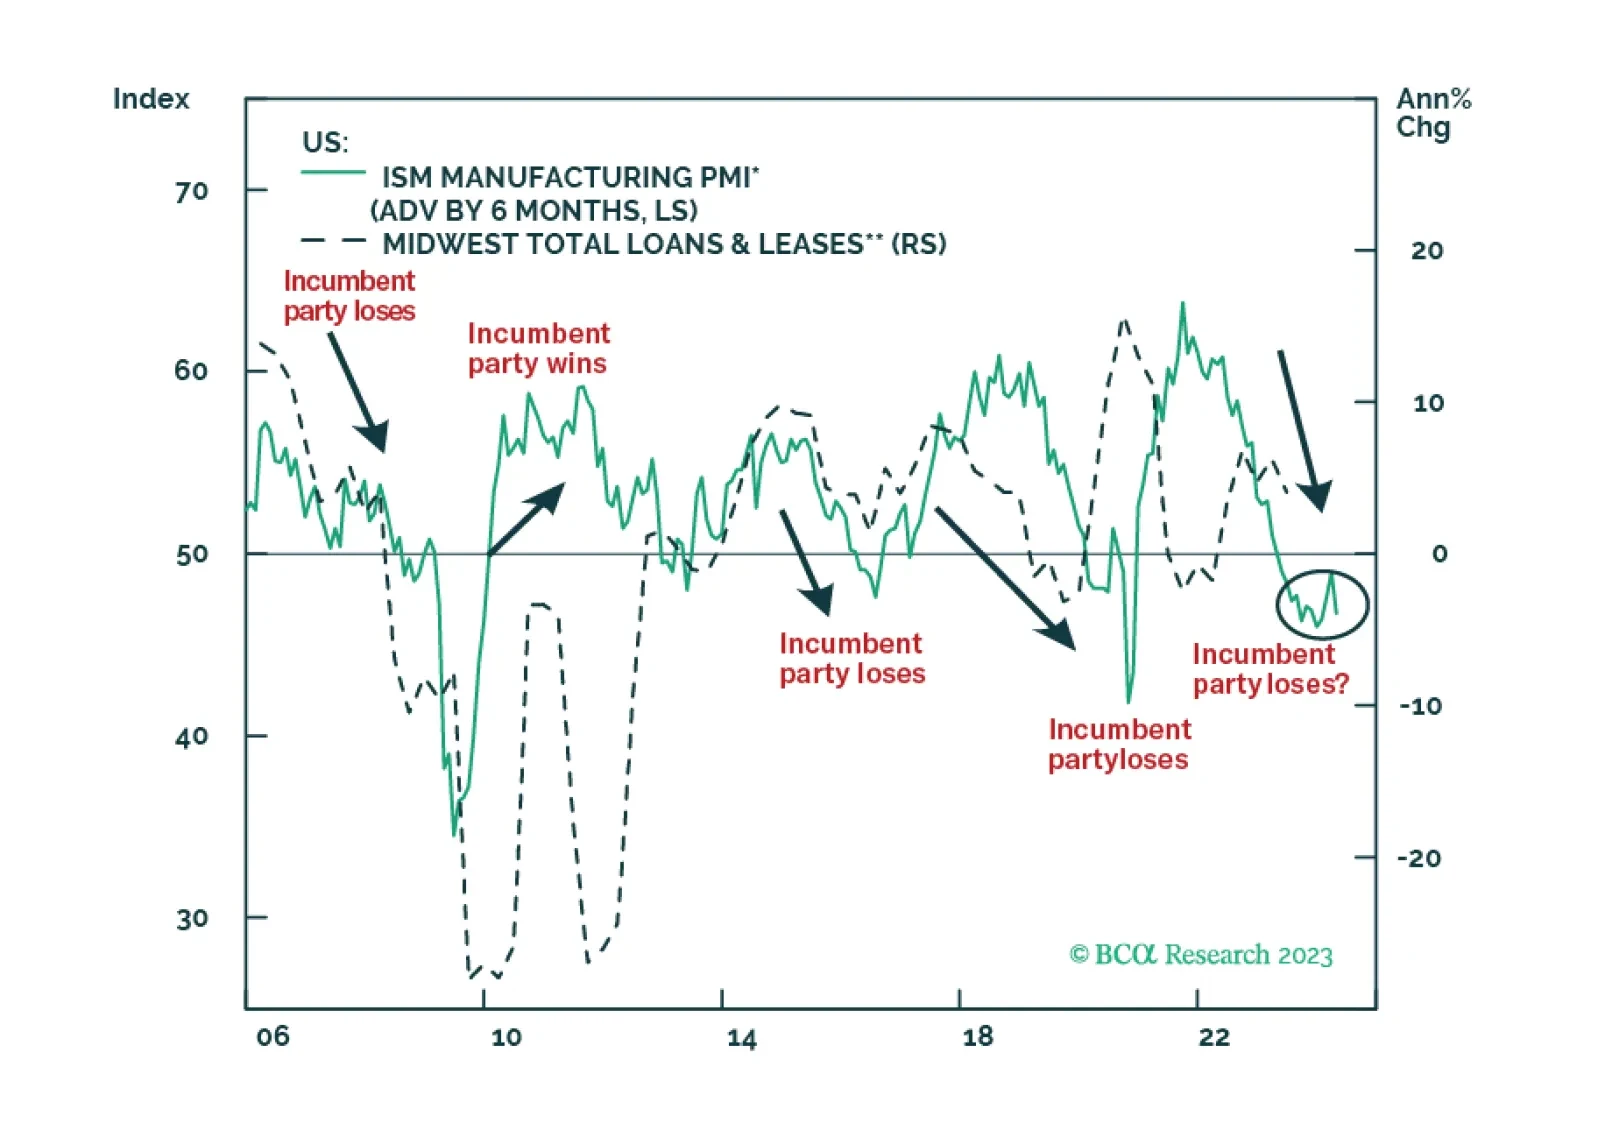
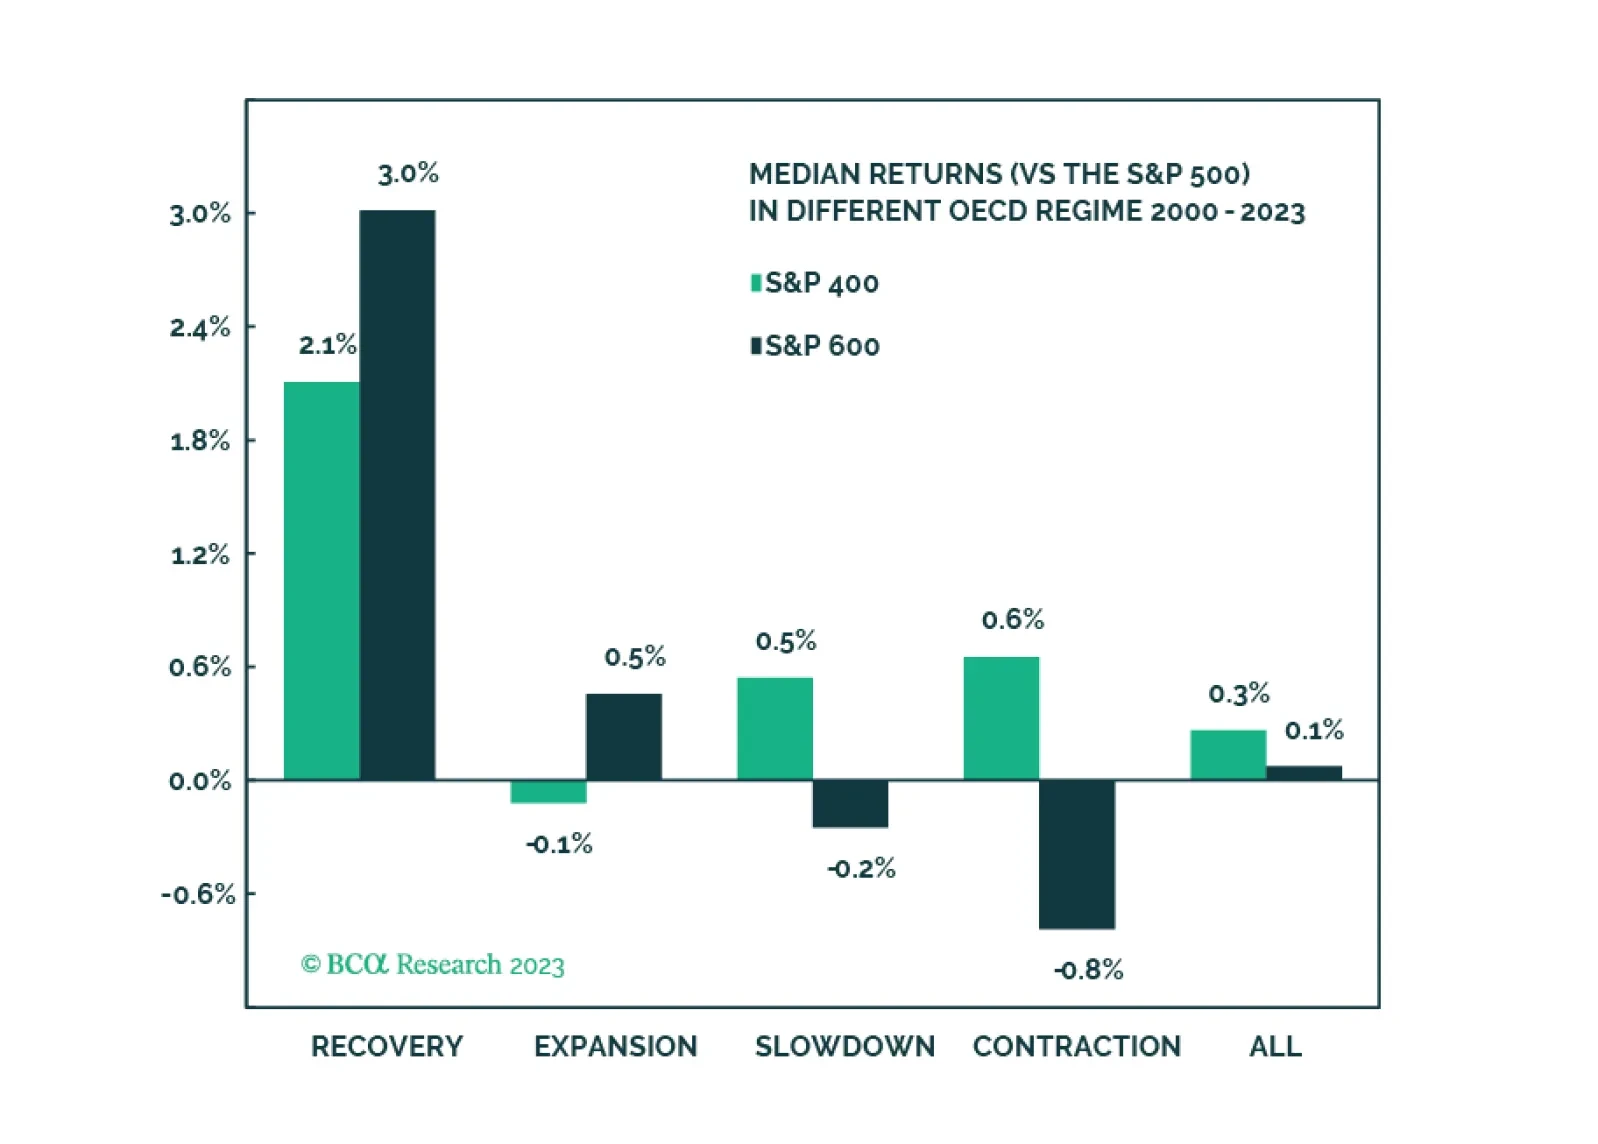
Mid-caps are the best of both worlds and are an excellent strategic overweight thanks to their size premium, but also better financial quality and higher dividend yield than Small. We are bullish on Mid near term and believe that this may be a great trade. We will initiate a position in the S&P 400 as a tactical overweight but will monitor it very closely.
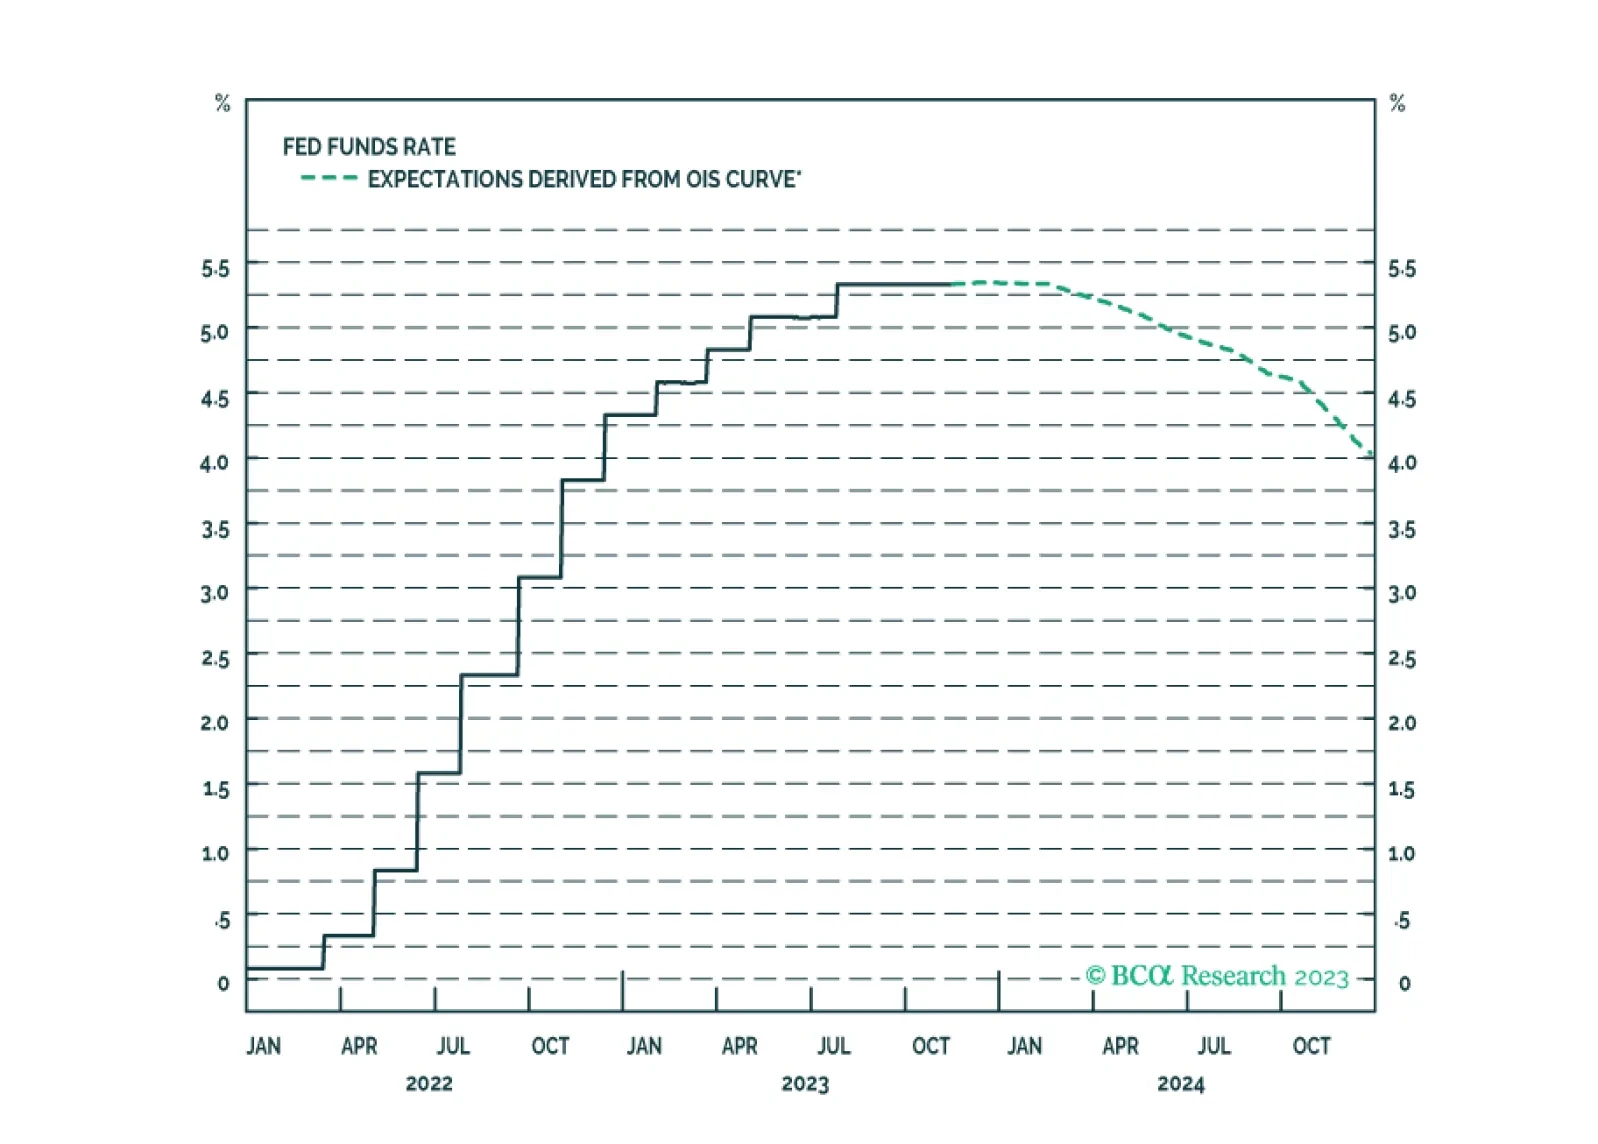
The soft-landing narrative has gotten nowhere at BCA but appears to be making some headway with broker-dealers and investors. We are preparing to lean against it once it pushes equity prices a little higher.
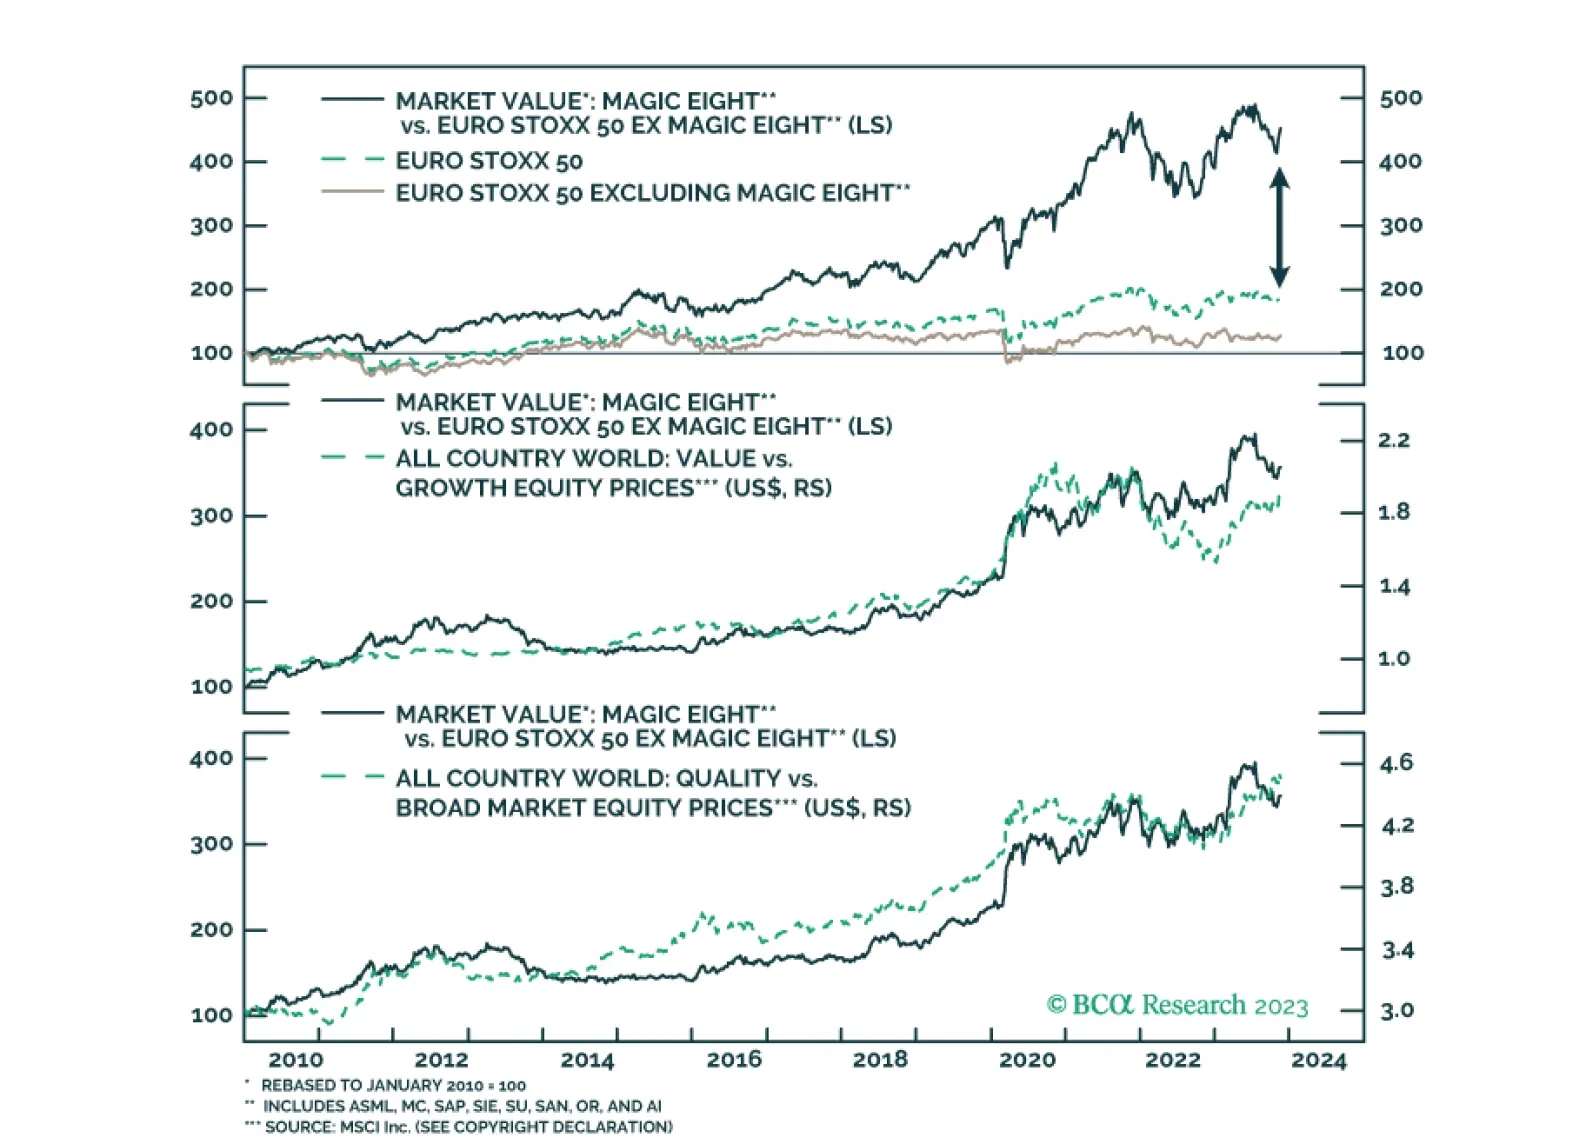
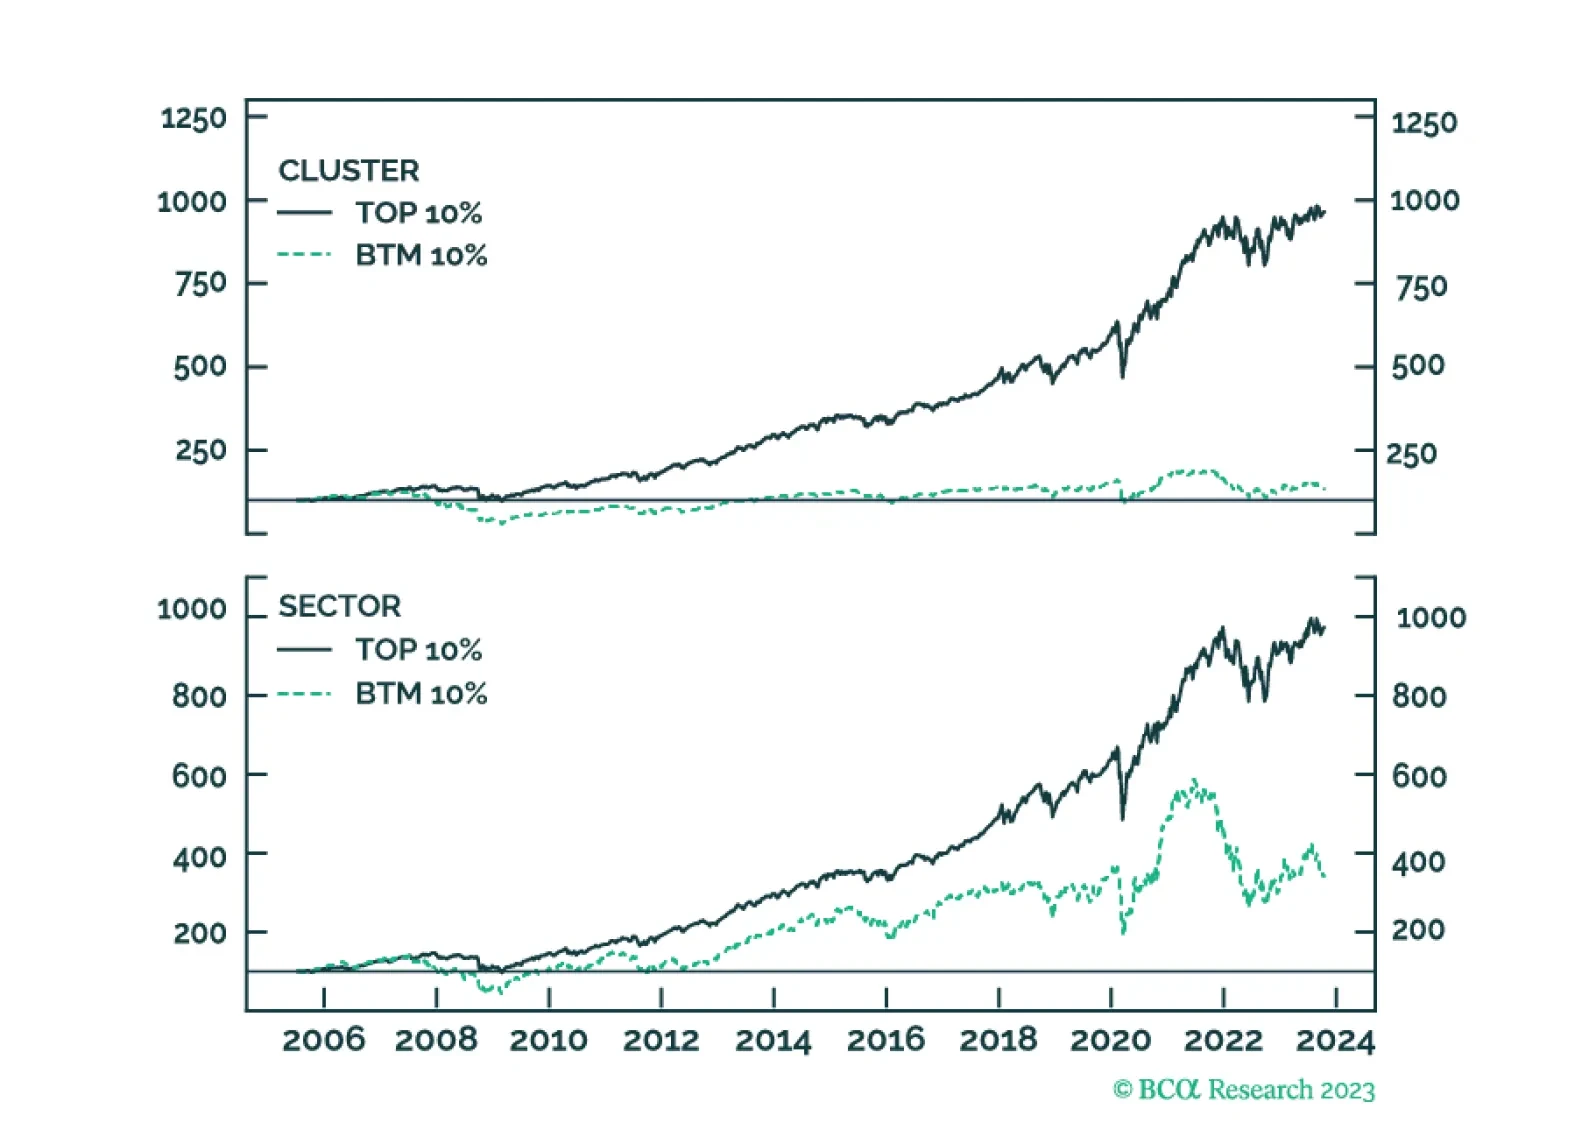
The US has the Magnificent Seven, Europe has the Magic Eight. What drives the performance of those eight stocks crucial to the European market?
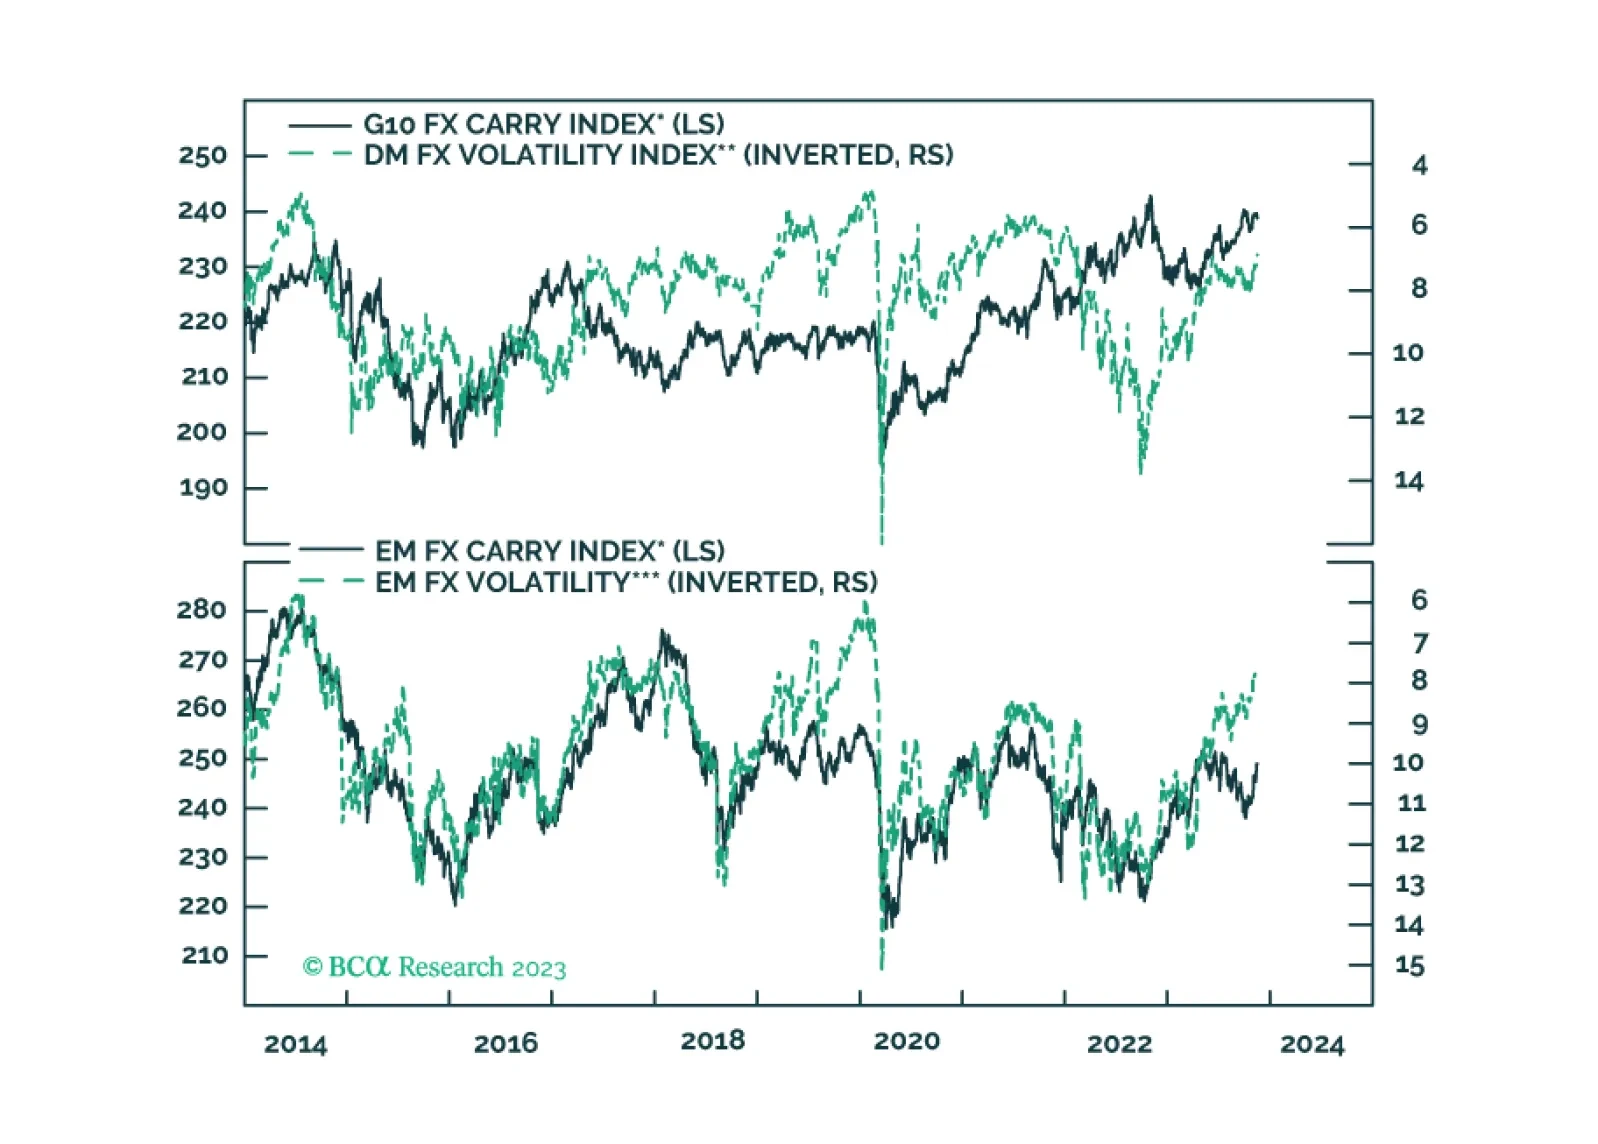
In this report, we evaluate the risk to carry trades in the coming months.
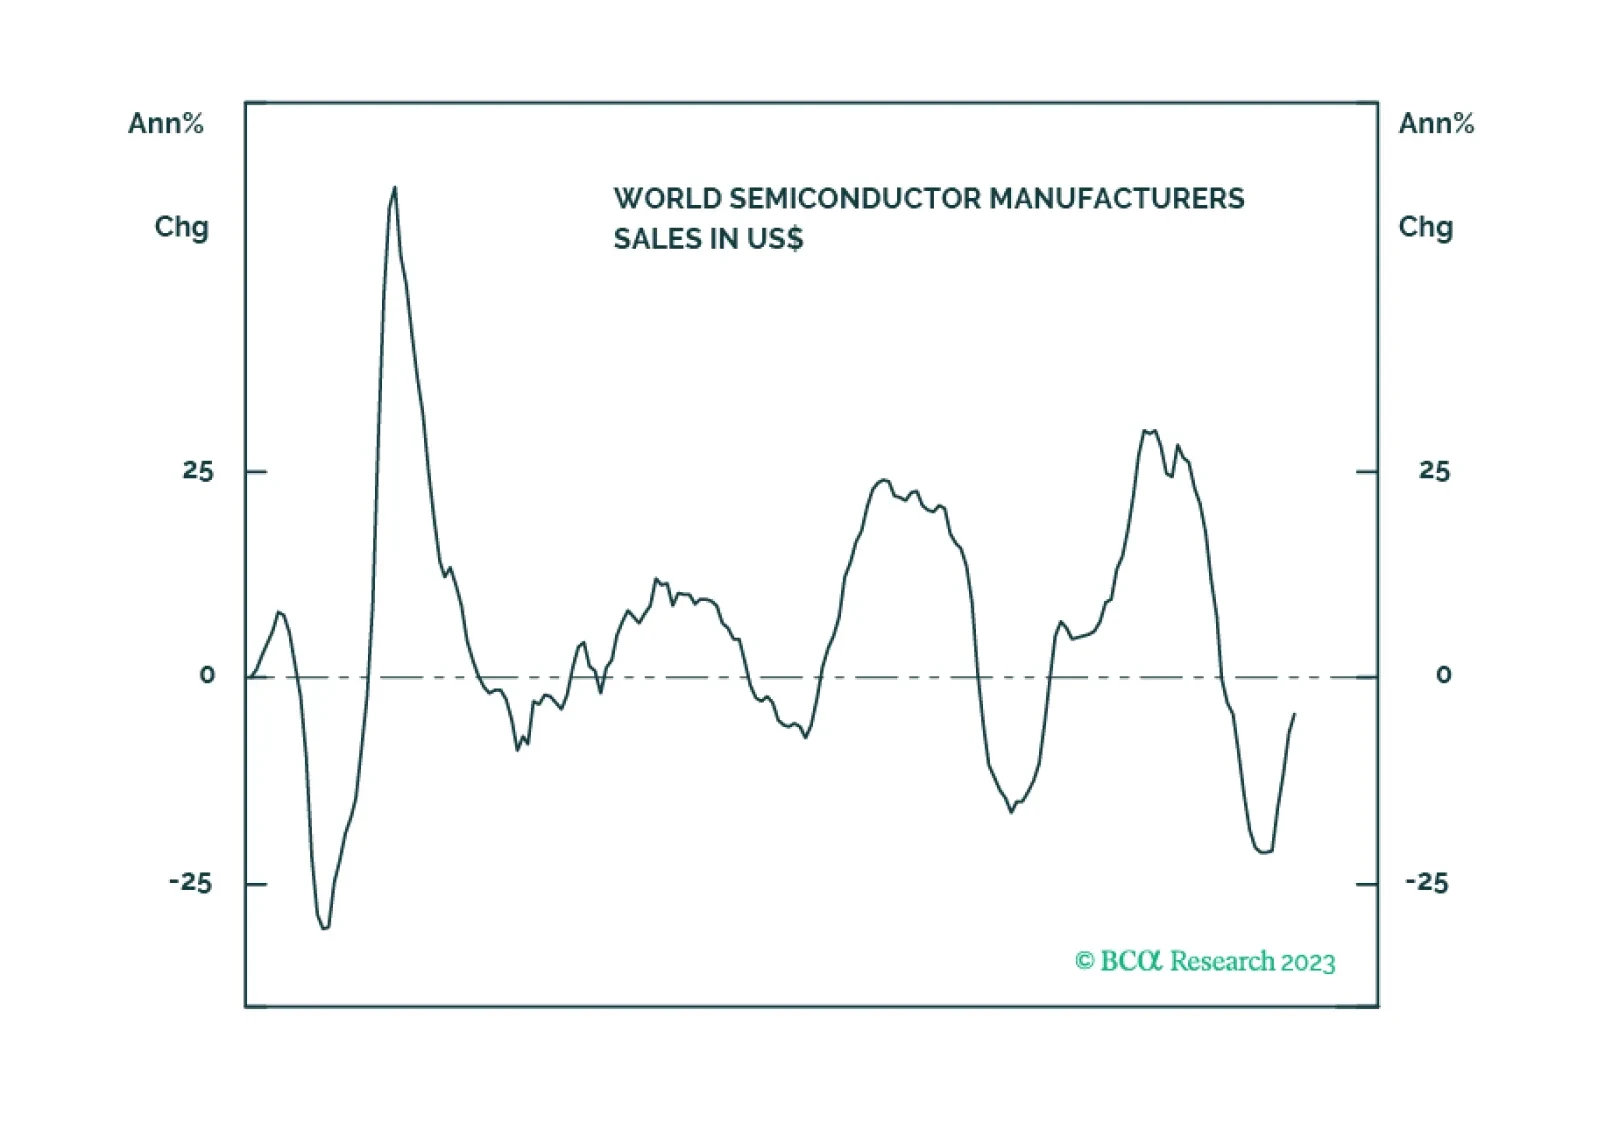
After a prolonged slump, there are early signs that demand for chips has bottomed and is showing signs of life. Meanwhile, corporate demand for future GAI chips is still a significant industry tailwind. In line with our call for an overweight of the Magnificent Seven, upgrade Semis to equal weight from underweight on a tactical basis. Longer-term outlook is neutral to negative as we expect the economy to slow in 2024, while growth expectations may be too high.