
Skip to main content

Equities

China’s official NBS PMI indicates that growth conditions remain sluggish. Although the composite index ticked up from 50.3 to 50.9, it is still barely in expansionary territory. Notably, the manufacturing PMI – which inched up by 0.2 points in January –…

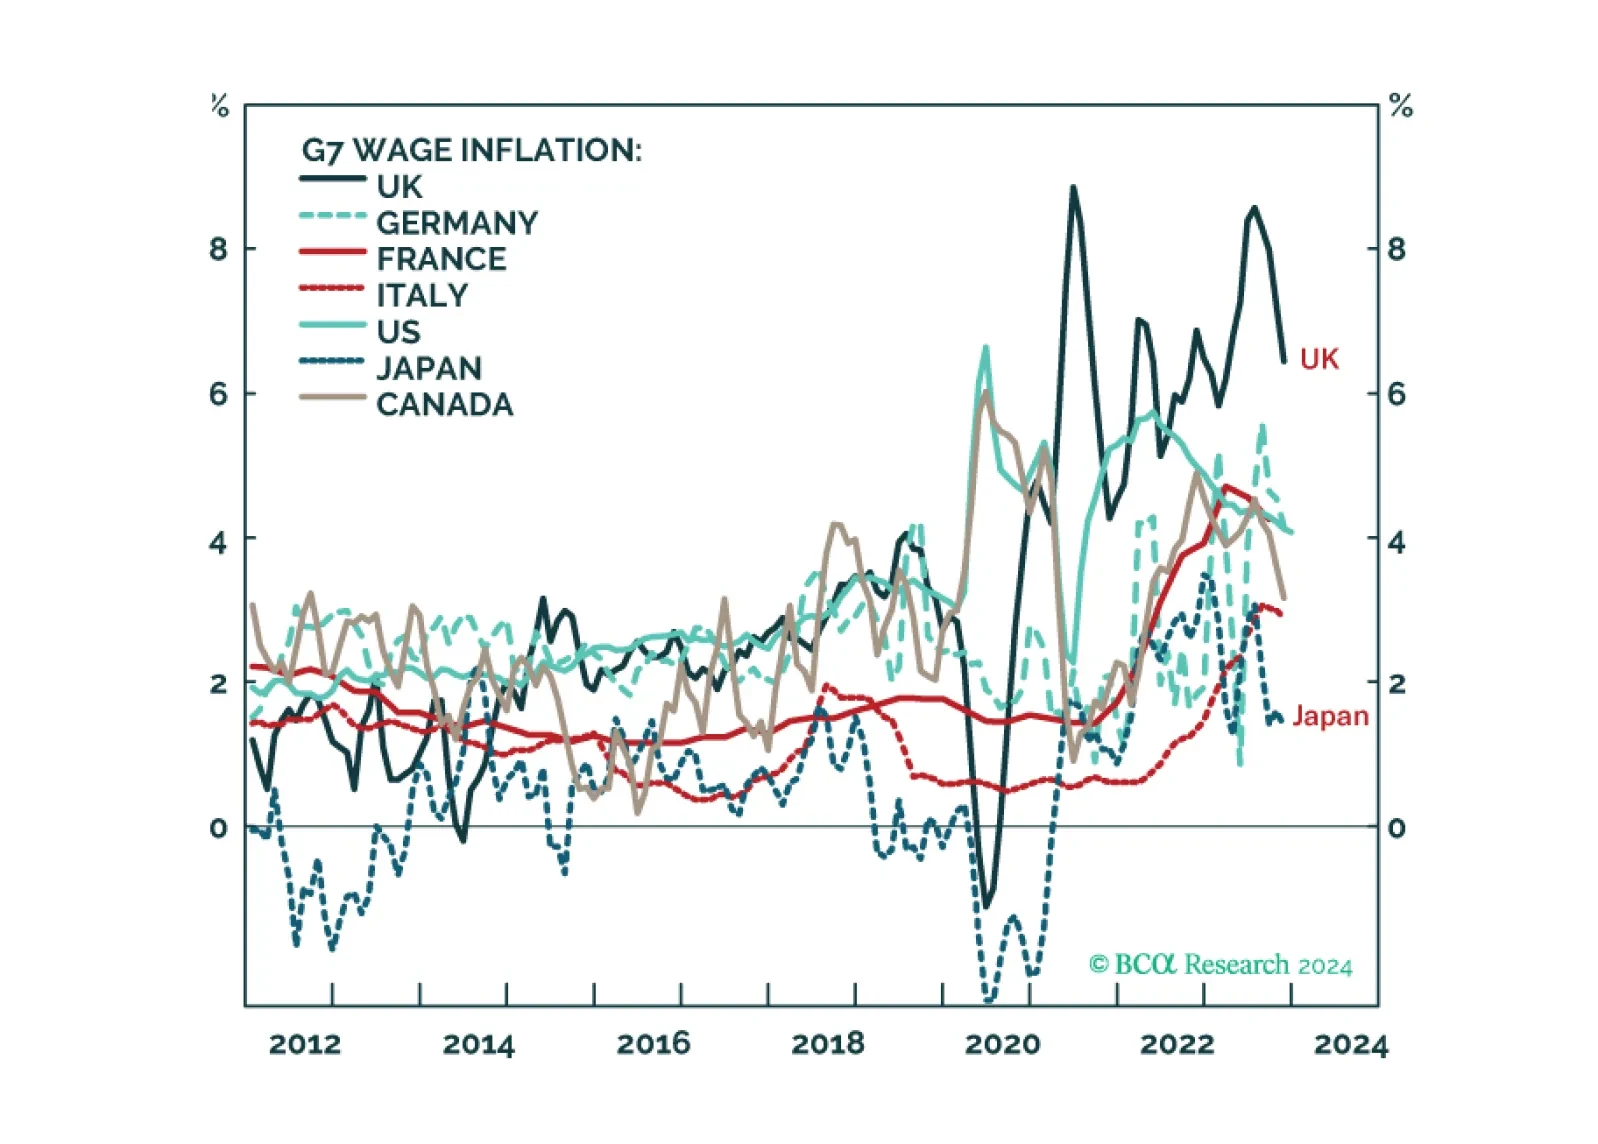
We describe and explain the wide disparity of wage inflation across G7 economies, and discuss what it means for the Fed, ECB, BoE, and BoJ policy moves in the coming year. Plus: we highlight two investments ripe for reversal, and two investments ripe for rebound.
S&P 500 operating margins have been in a downdraft for nearly two years – but the consensus is still penciling in expansion for 2024. How likely is that? Our US Equity Strategy colleagues have addressed this question in their recent “Marginally Better or…
BCA Research’s Global Investment Strategy service has officially launched its MacroQuant 2.0 Model. The platform consists of a variety of modules, all of which communicate with each other to produce economically sensible and internally consistent…
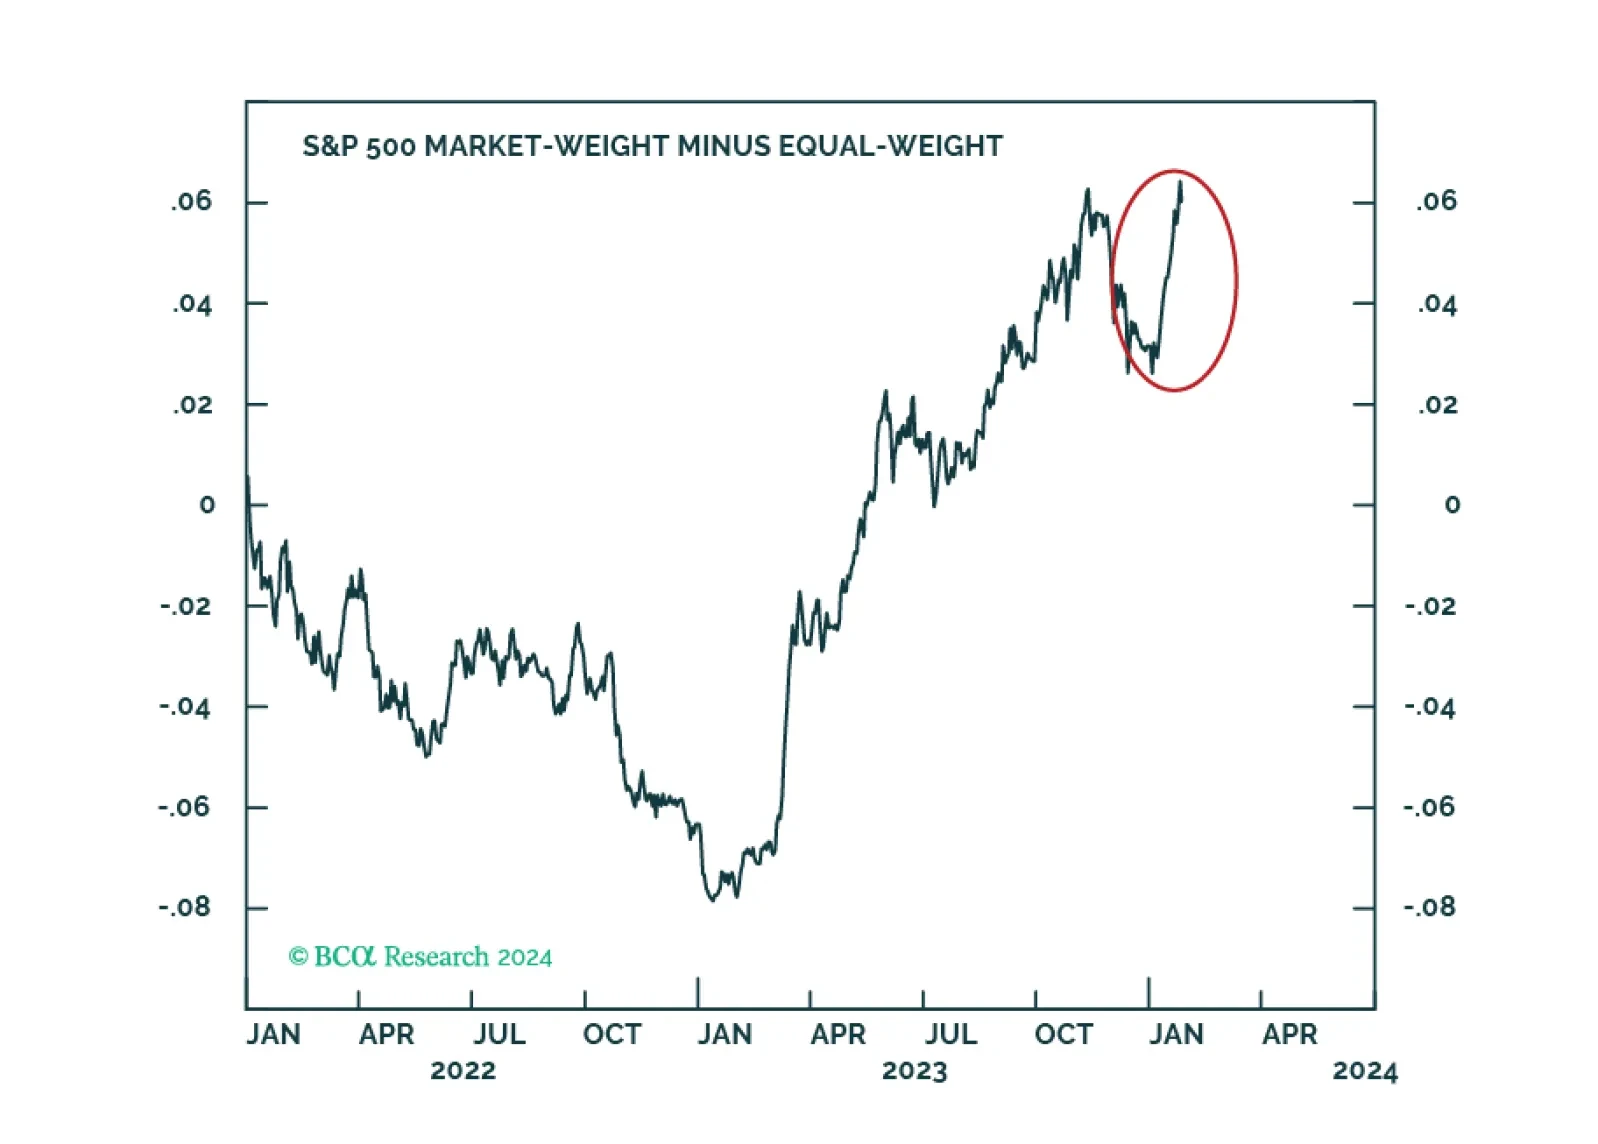
Since the low of 27 October last year, MSCI US has rallied by 19.1% and this rally has been firmly driven by cyclical sectors. Performance-wise Information Technology (IT), Communication Services and Financials and Real Estate have been the top performing…
This week is set to be a busy one for the US market. On the policy front, there is the Wednesday FOMC meeting which will give insight into the Fed’s latest thinking regarding the timing of rate cuts. On the data front, there is the Friday Jobs report which…
China’s industrial profits registered their second consecutive annual contraction last year, falling by 2.3% in 2023. The full year contraction comes despite a surge in industrial profits near year-end. Profit growth came in at 16.8% y/y in December following…

A recent slew of macroeconomic data has reassured us that the runway to a recession is longer than many thought. However, that positive realization comes with two caveats. First, the Fed pivot is not imminent, and the magnitude of rate cuts may disappoint. Second, the recession has been delayed but not avoided. Further, geopolitical risk is elevated. We will overweight Tech on the next dip and upgrade Retail to an overweight.
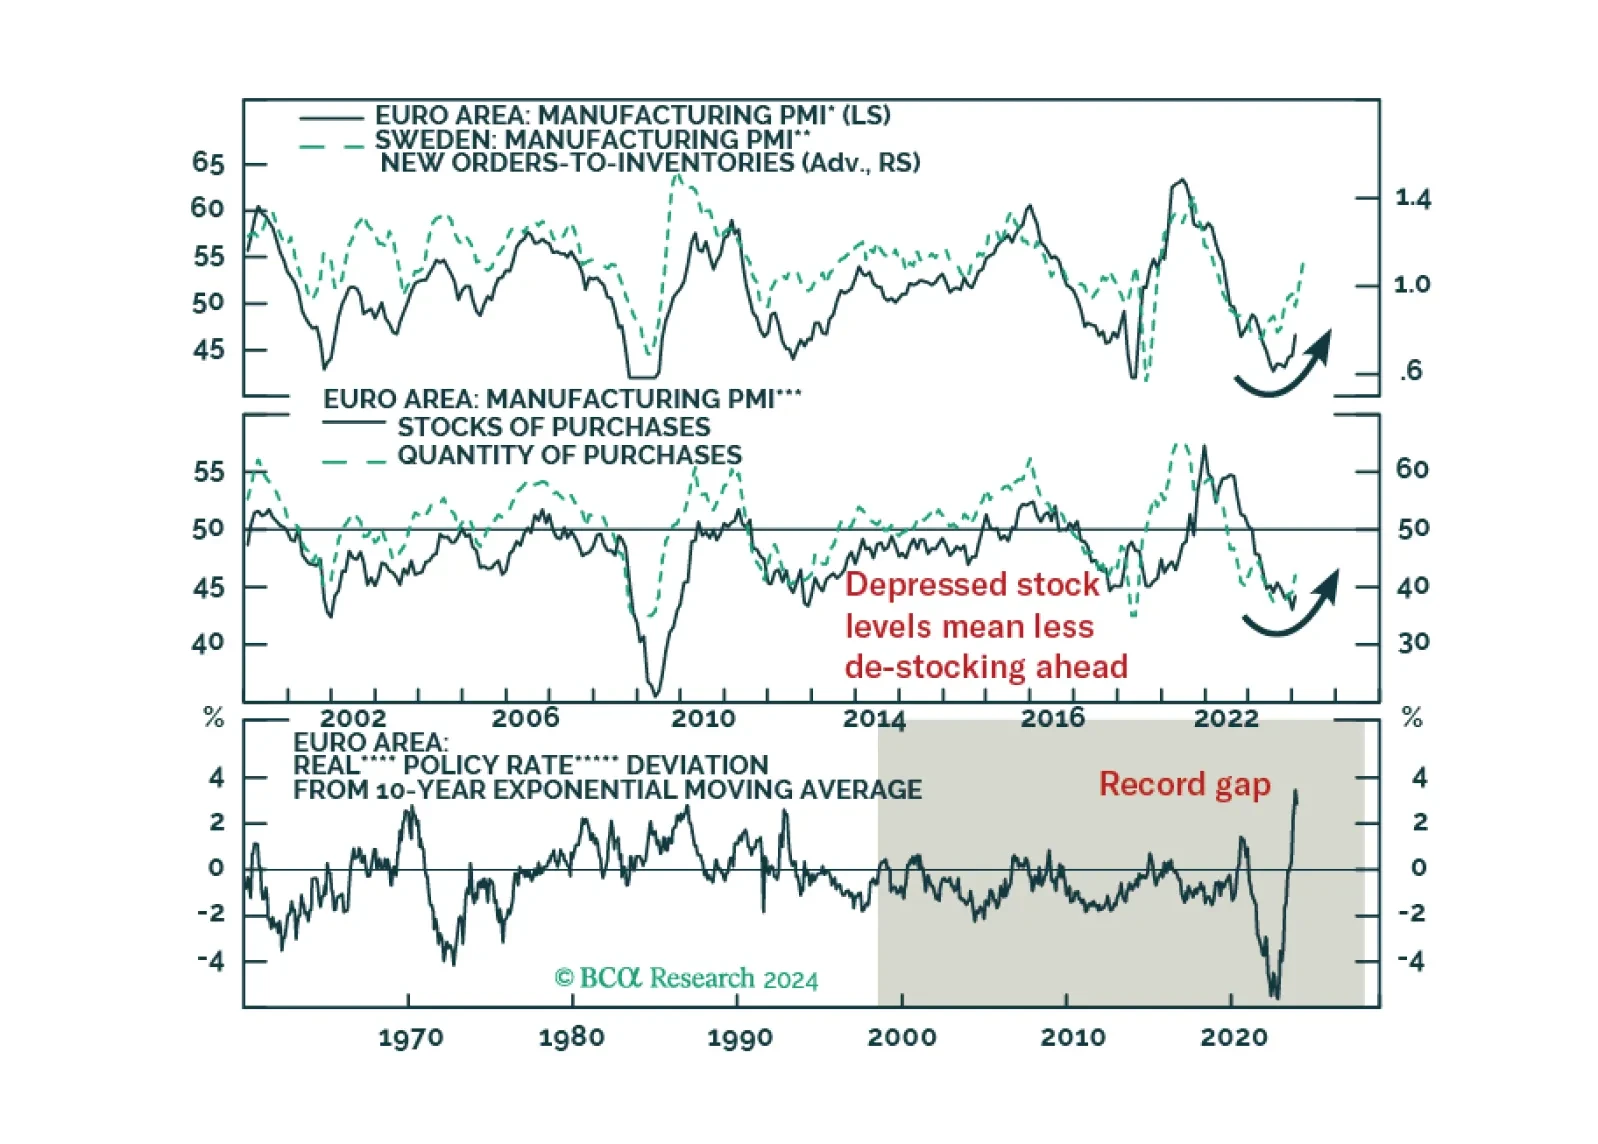
Is the rebound in European PMIs enough to boost the appeal of European risk assets?
Special Report

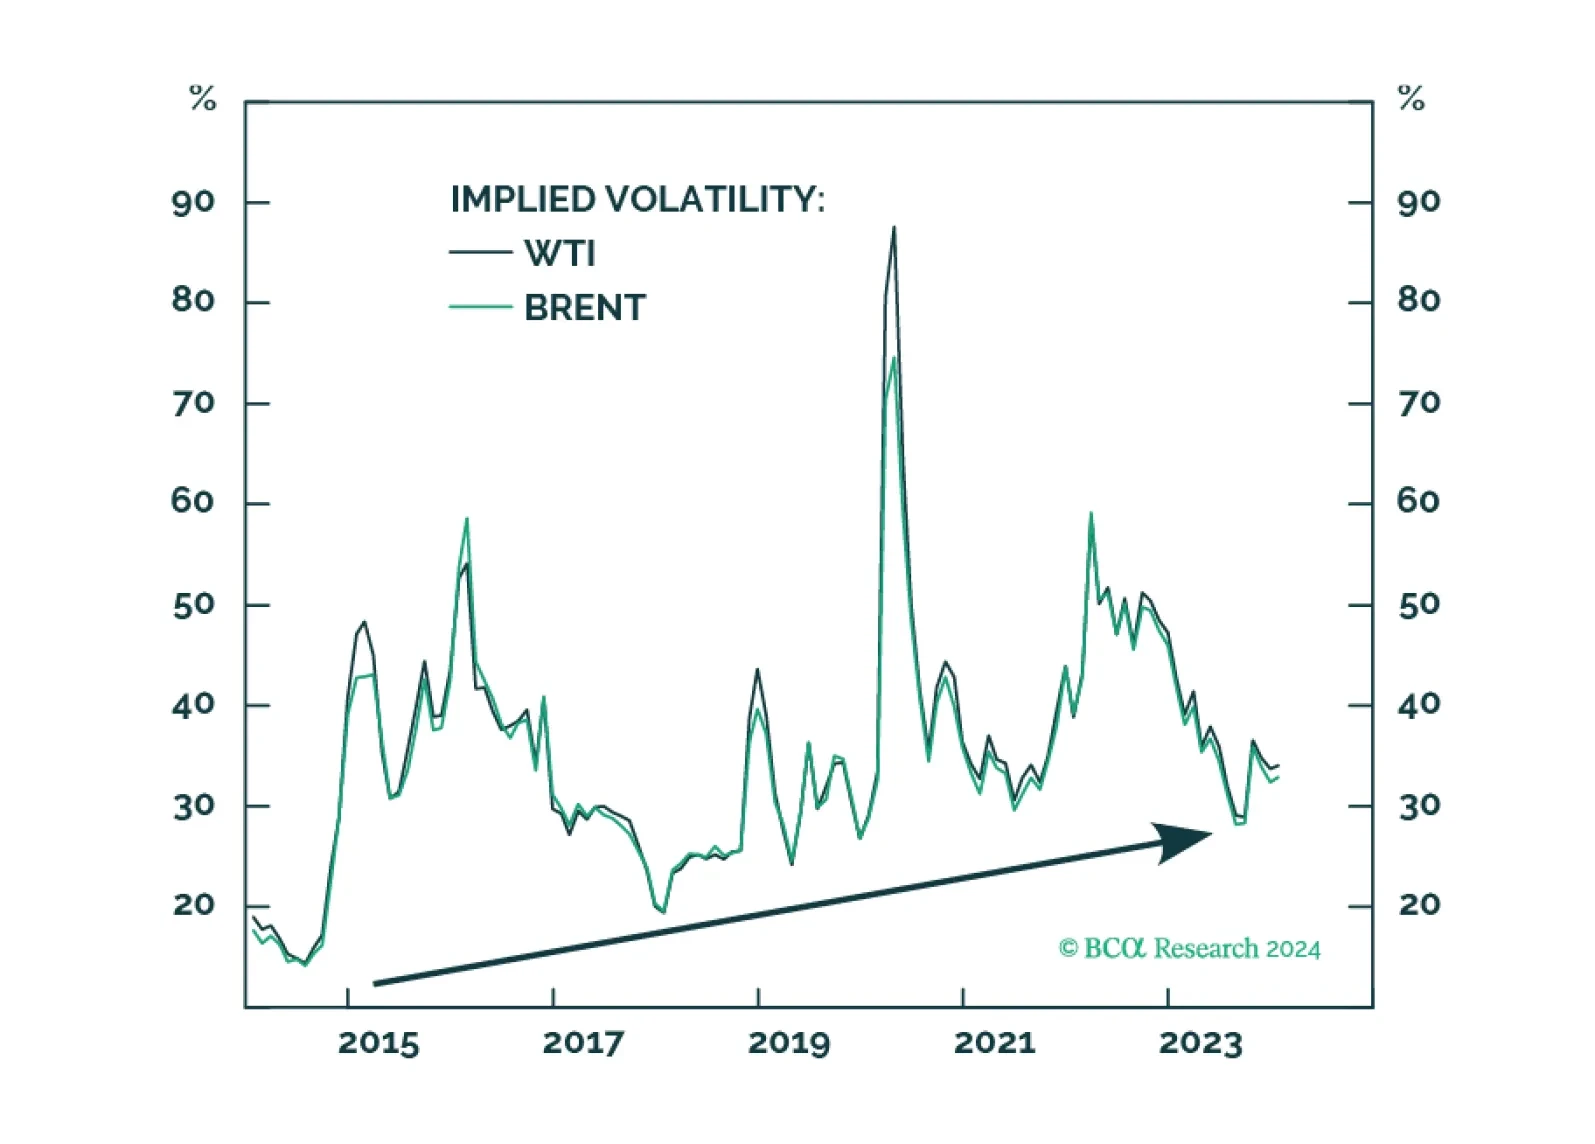
Commodity volatility will continue its rising trend since 2014. The US is on the brink of a major election, the outcome of which could reduce its willingness to engage with the outside world. So, states seeking to carve out their own spheres of influence are incentivized to raise the economic costs to the US and discourage its influence in their regions. These states can do this by interfering in key trading routes in their regions. As a result, geopolitical threats to maritime chokepoints are a structural as well as cyclical problem and will persist due to the revival of superpower competition.