
Skip to main content

Labor Market

Japanese equities and government bonds sold off on Monday and the yen strengthened following the release of the revised Q4 GDP report showing the economy expanded by an annualized 0.4% q/q in Q4 2023 versus earlier estimates of a 0.4% contraction. A…
According to BCA Research’s European Investment Strategy service, last week’s ECB meeting confirmed their long-held view that the most likely date for the first ECB rate cut would be June. The ECB continues to acknowledge that the European economy is soft and…
According to Factset, analysts are forecasting S&P 500 earnings and revenues to grow by 11.0% y/y and 5.0% y/y respectively in 2024 (an acceleration from 0.9% and 2.8% in 2023). Information technology and communications services (broadly-defined tech) are…

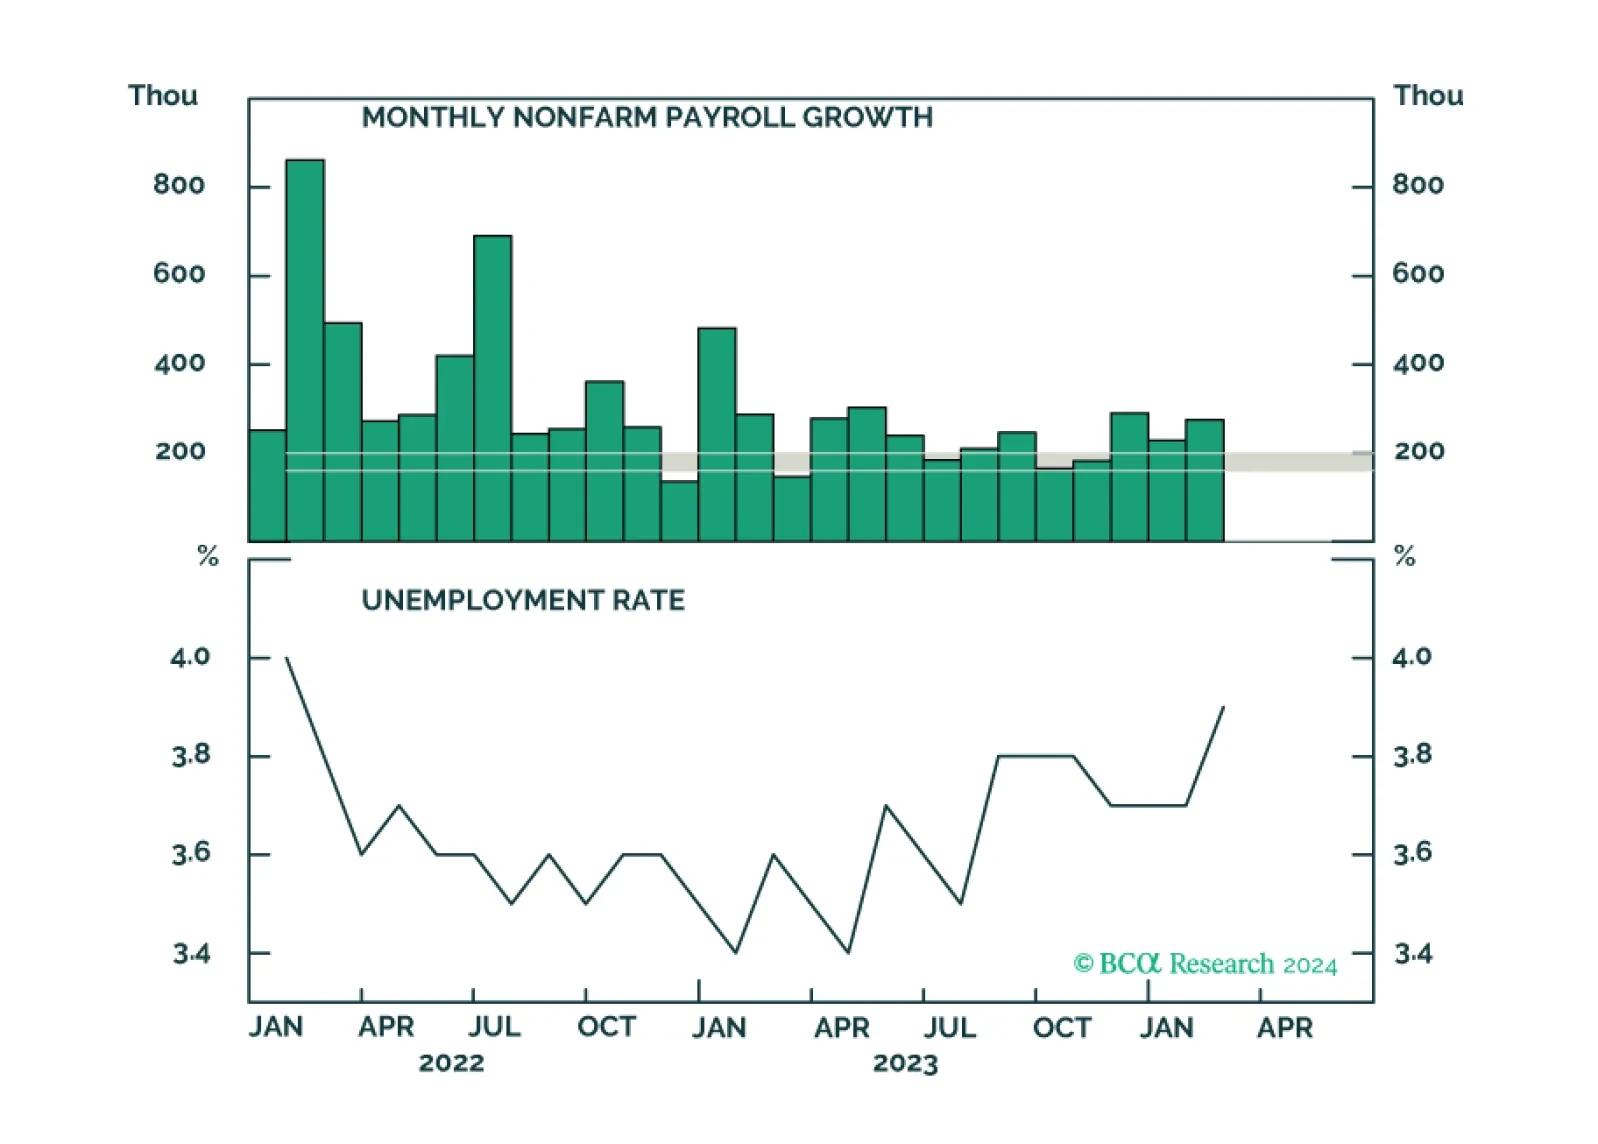
We update the indicators in our duration checklist following this morning’s employment report.
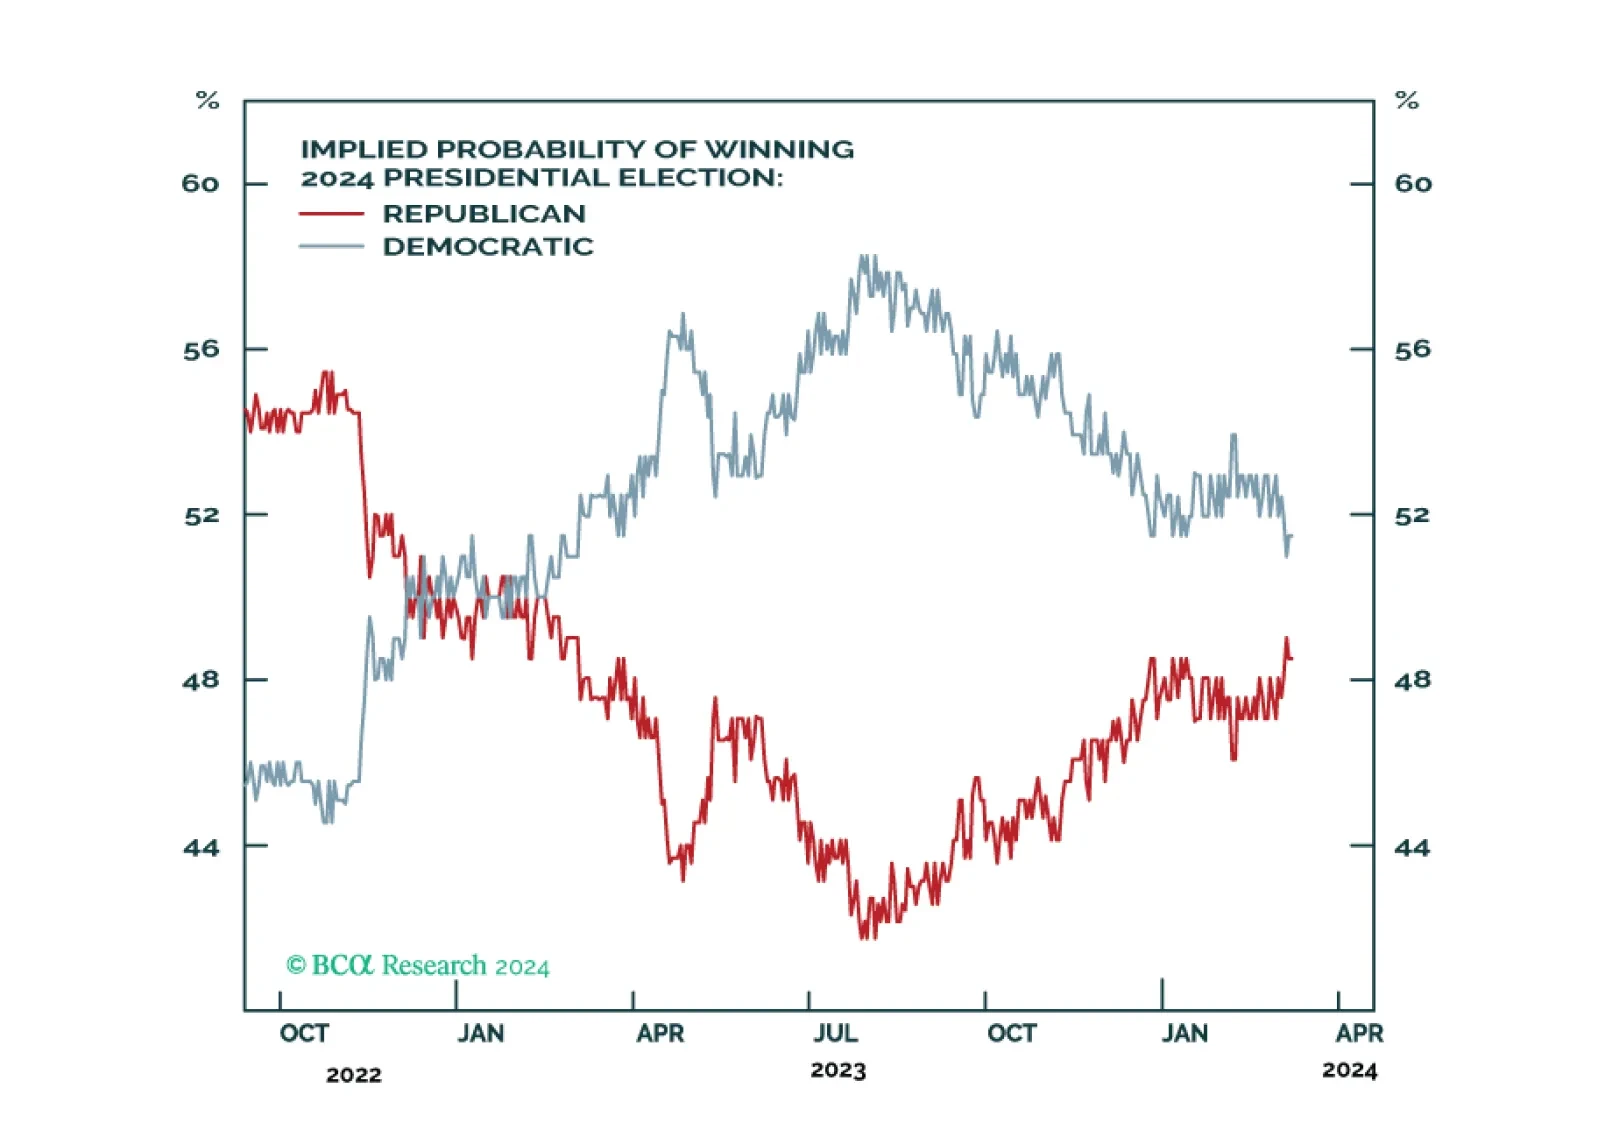
Democrats are still slightly favored for reelection as the incumbent party is presiding over a growing economy. However, Biden’s strong showing in the primary election is not lifting his popular approval yet, and that is a worrying sign. Policy uncertainty should rise sharply, which is marginally negative for the stock market.
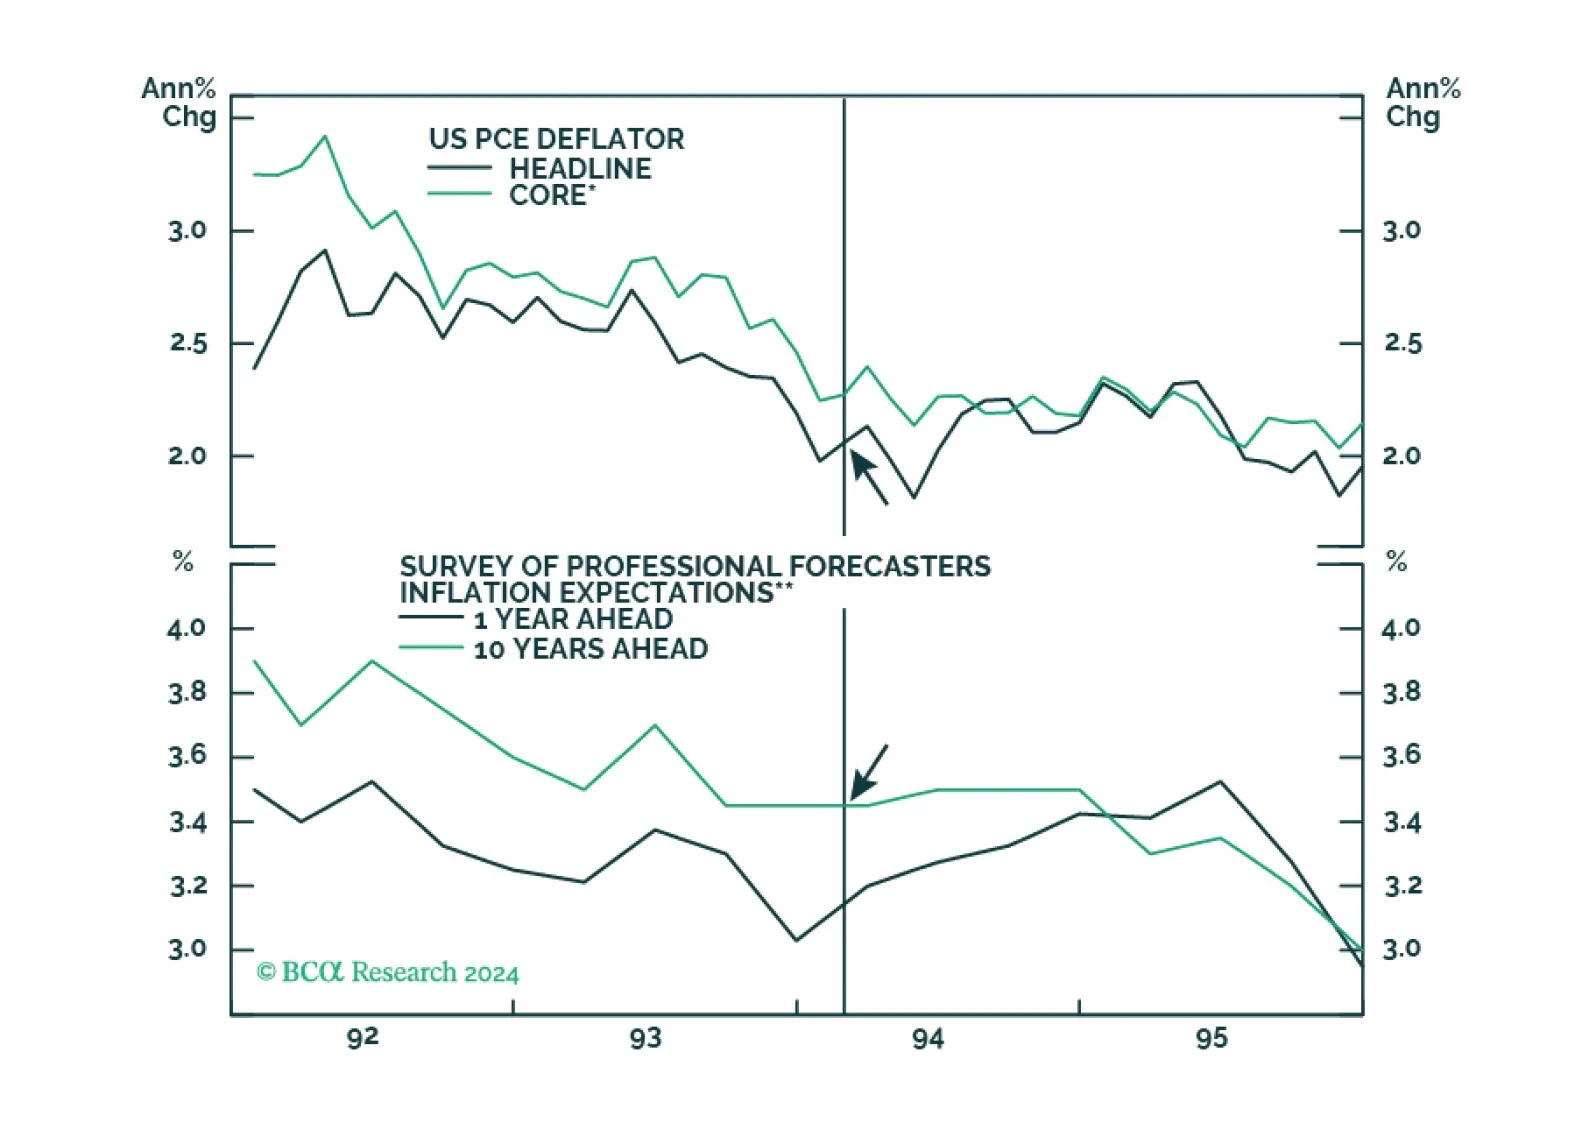
Many investors have cited the 1994 tightening cycle as an example of how the Fed managed to raise rates without triggering a recession. However, the unemployment rate was 6.5% in early 1994, which meant that inflation was less of a risk than it is today. Productivity growth also accelerated starting in the mid-1990s. While something similar may happen again thanks to AI, so far this is not visible in the aggregate productivity data.

The US January JOLTS data released yesterday was in line with expectations, with job openings clocking in at 8.86 million versus a downwardly-revised 8.89 million in December. Importantly, US job openings are likely to continue trending lower in February…
The US ISM Services PMI declined slightly to 52.6 in February, just below expectations of 53. Overall, the service sector continues to expand, however, the recent ISM suggests that growth is slowing down. In fact, most of the components of the ISM worsened,…
Data out of Norway is becoming increasingly positive, and there is a strong investment case to be made for the country, with bullish implications for both equities and the currency: Retail sales remain robust and are catching up to the improvement we have…
Our US Investment Strategy service examines the state of consumer finances in the context of their view that a recession will materialize this year with a double-digit peak-to-trough decline in S&P 500 earnings expectations. They expect the pandemic-era…