 Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.

We are upgrading Europe Private Equity, predominantly driven by Buyouts, from underweight to neutral. Our outlook towards Global Buyouts is improving, with Europe benefiting from enhanced credit availability and an earlier recession. Non-domestic investors may also be advantaged by an appreciation in the EUR and GBP over the next market cycle.
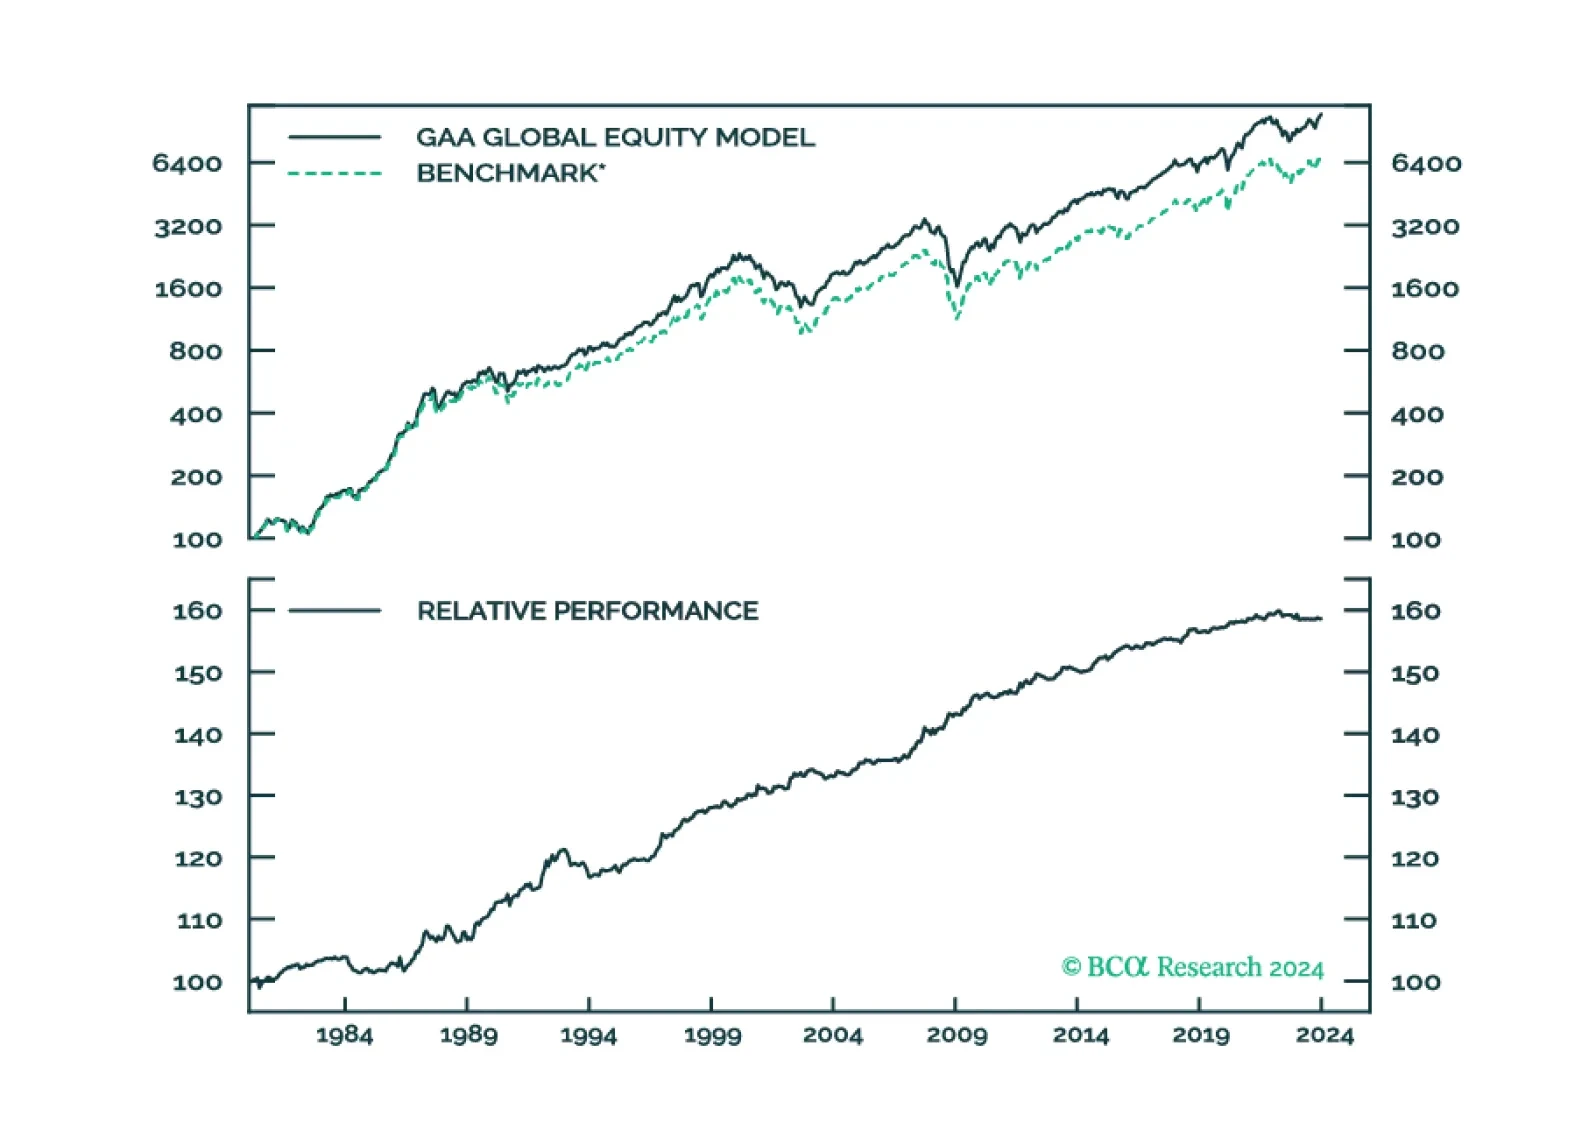
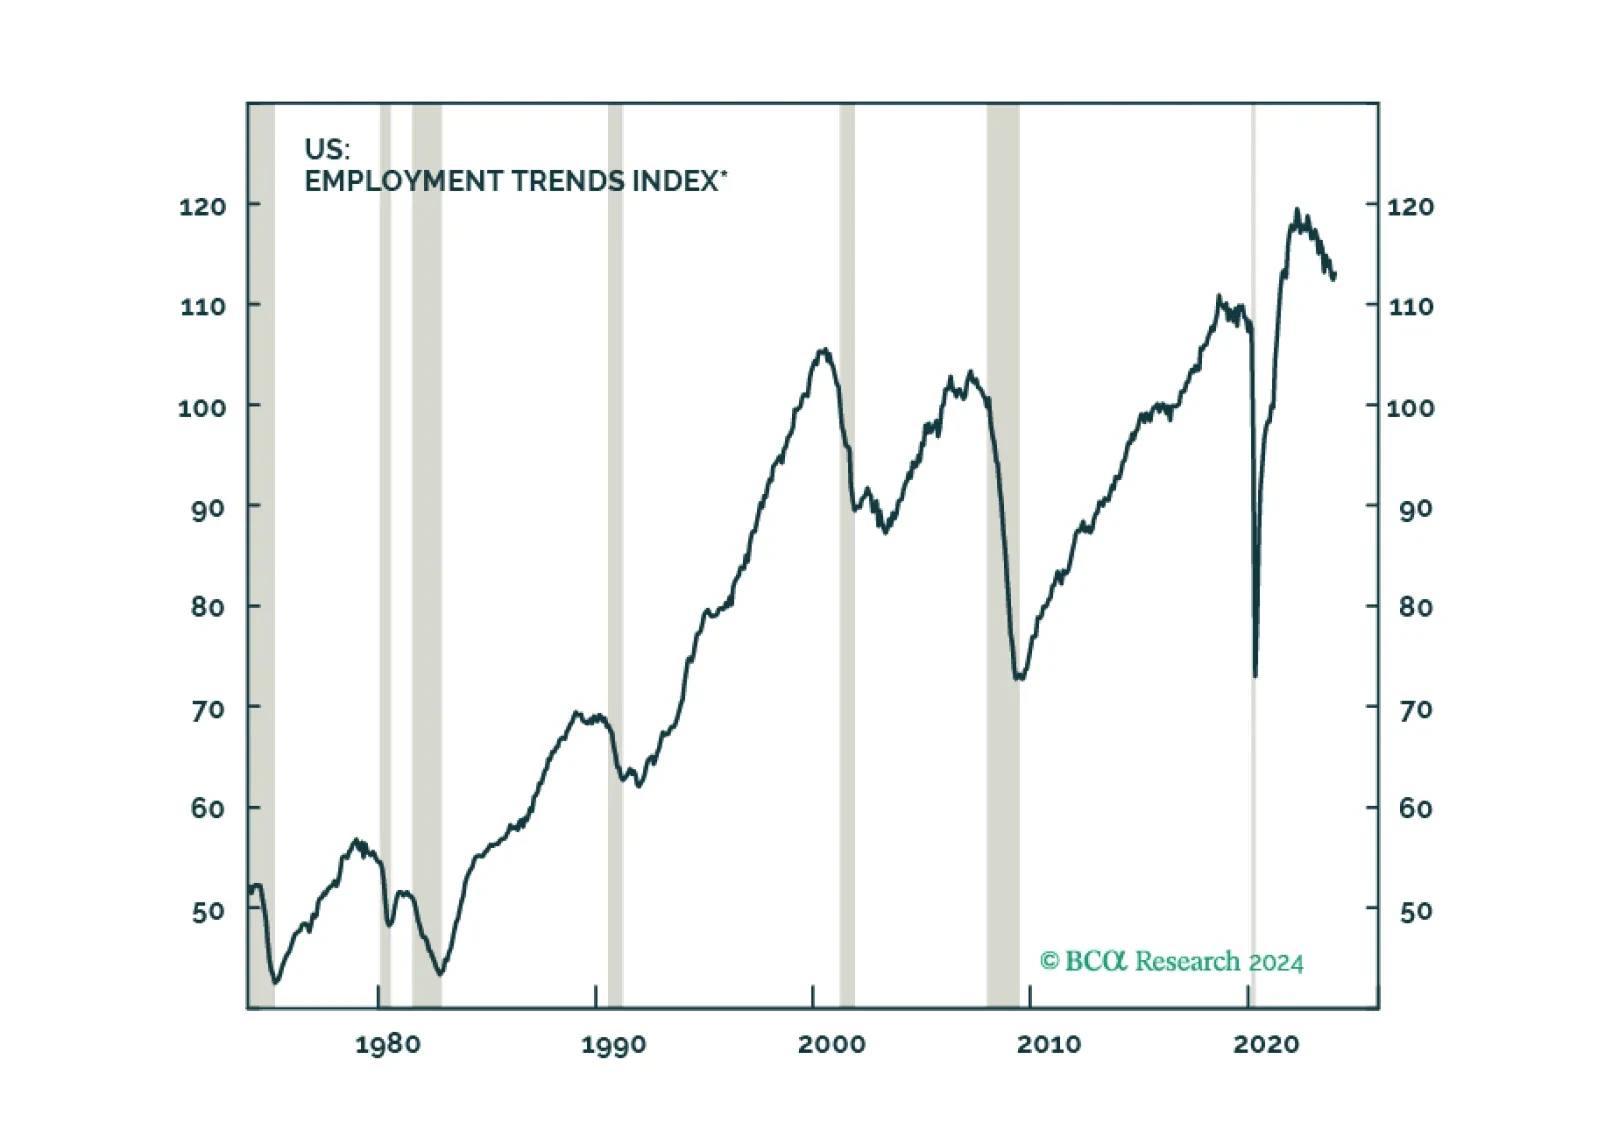
When will the US also buckle under high rates? We expect a US recession to begin around mid-year. Stay defensive.
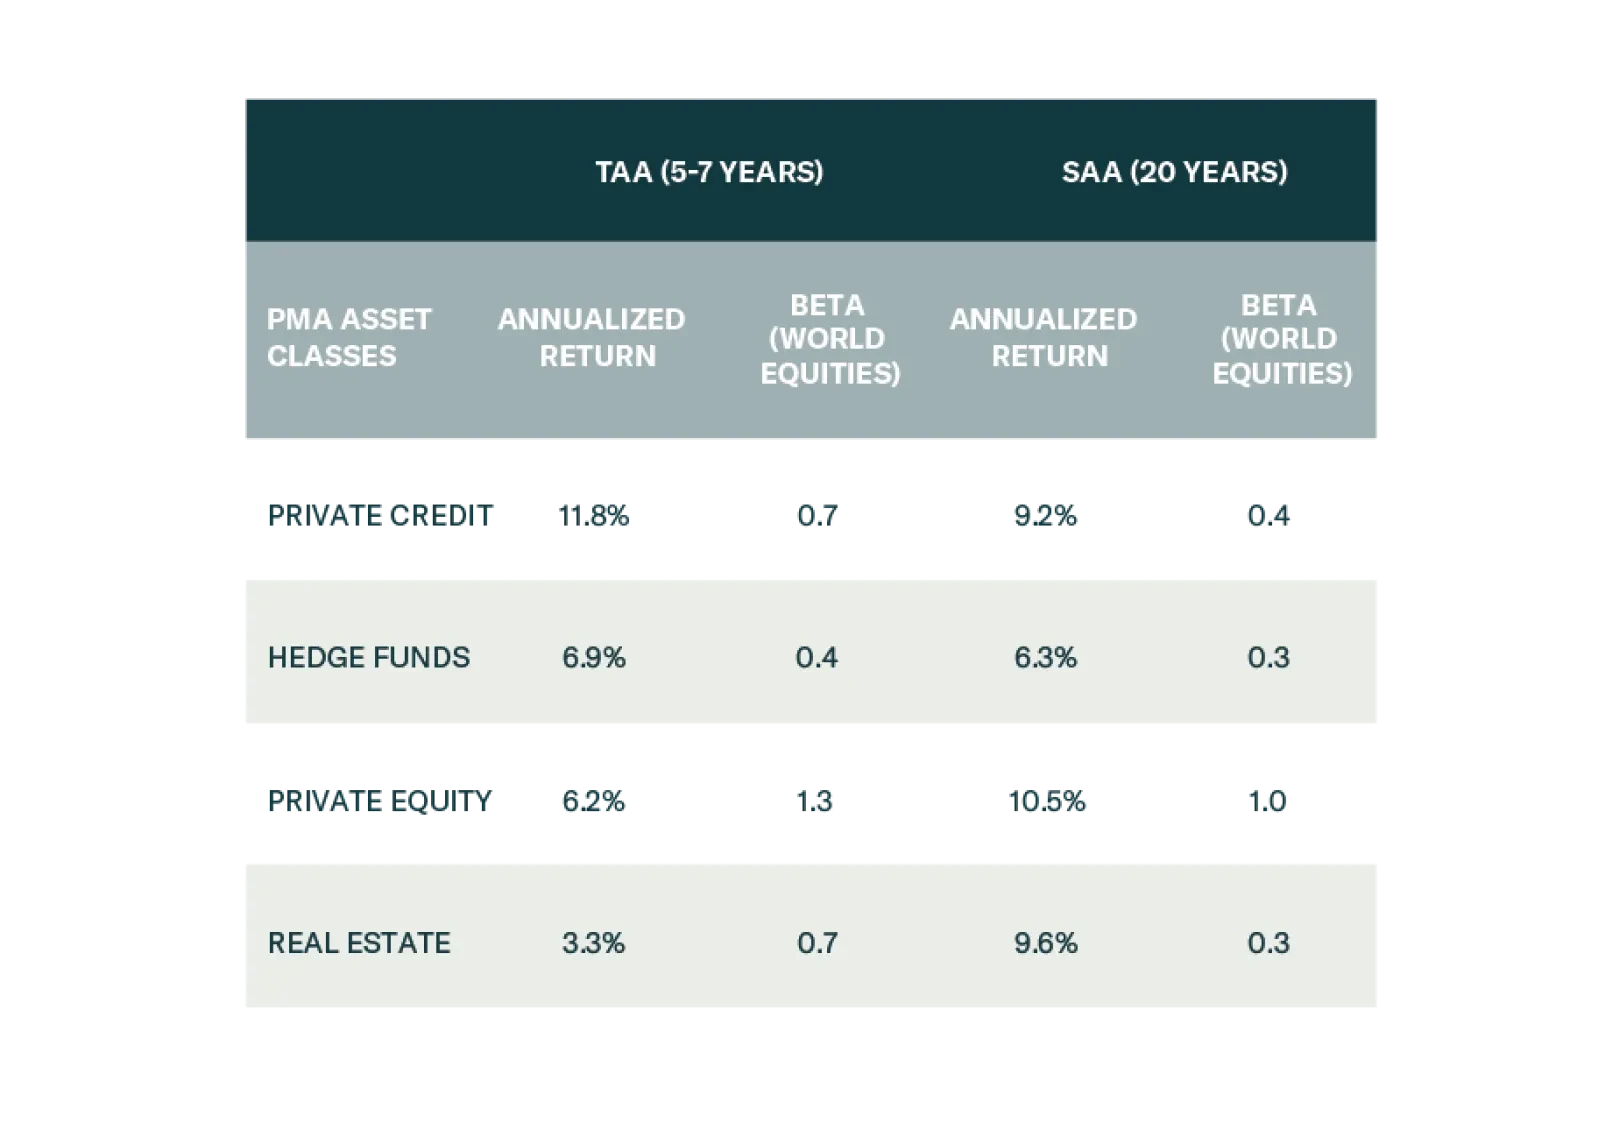
Investors should be tactically tilting allocations towards Direct Lending, Distressed Debt, and Directional Hedge Fund strategies at the expense of Real Estate, Private Equity, and Diversifier Hedge Funds. Structural opportunities are emerging in Real Estate and Venture Capital.
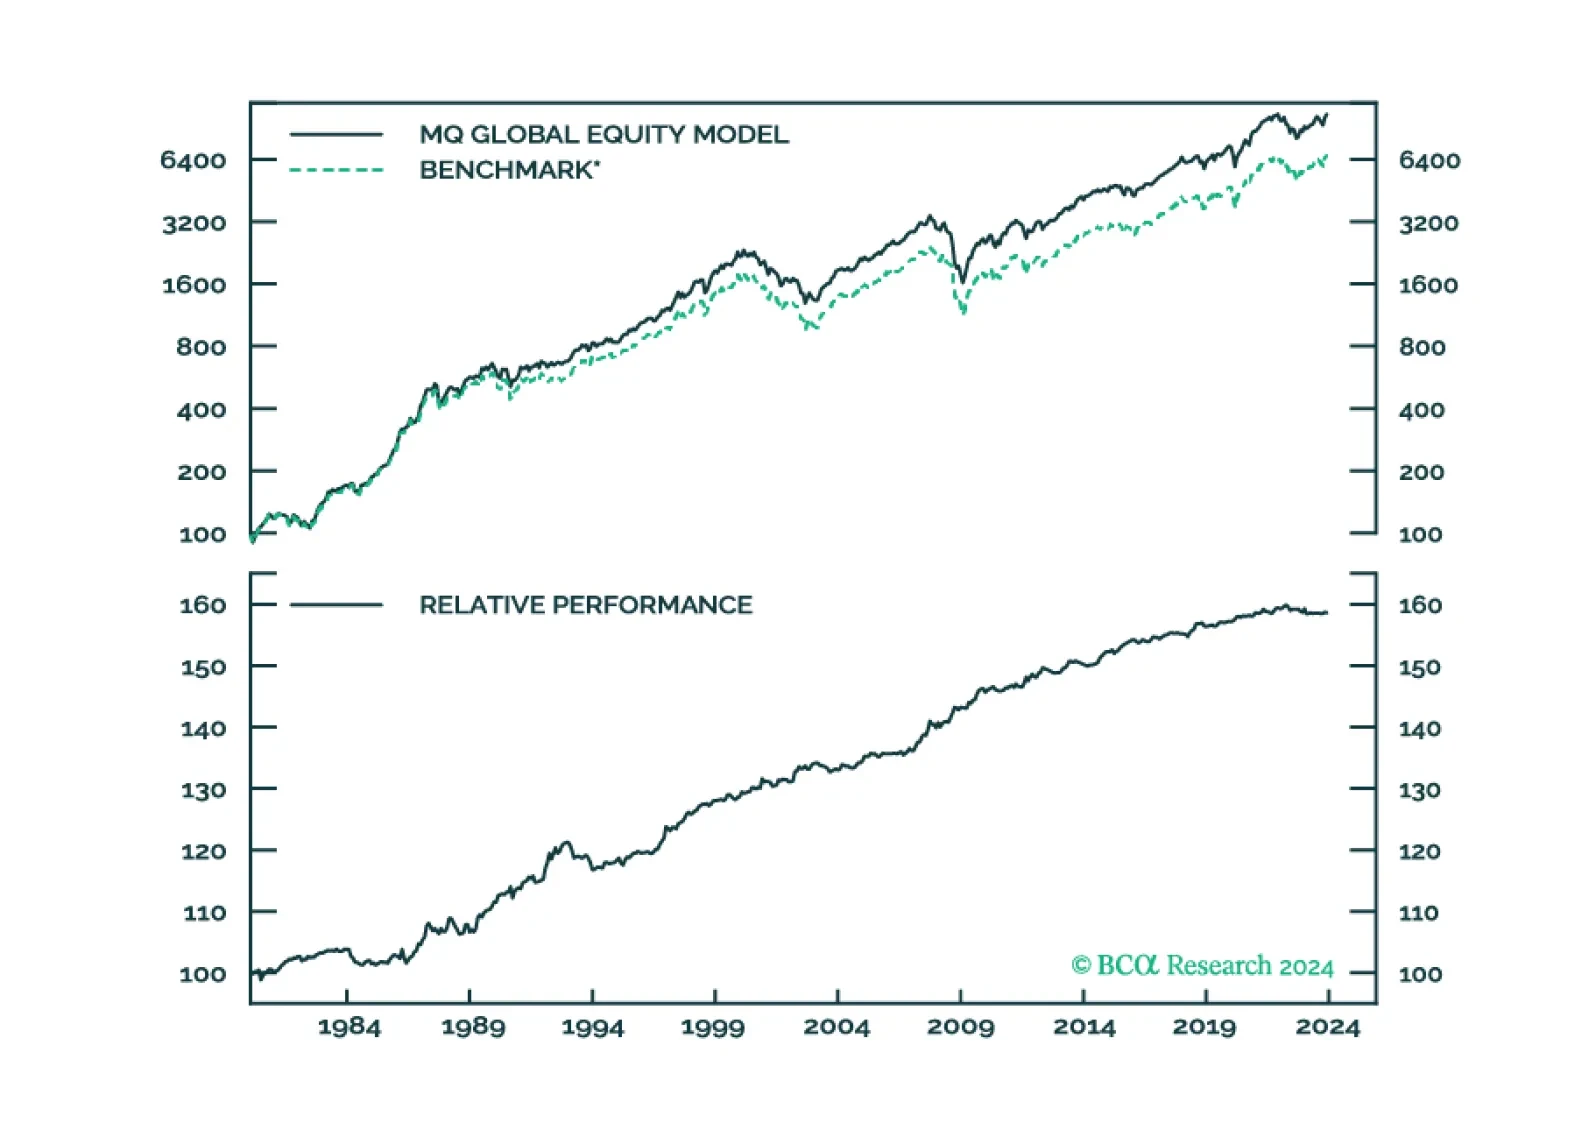
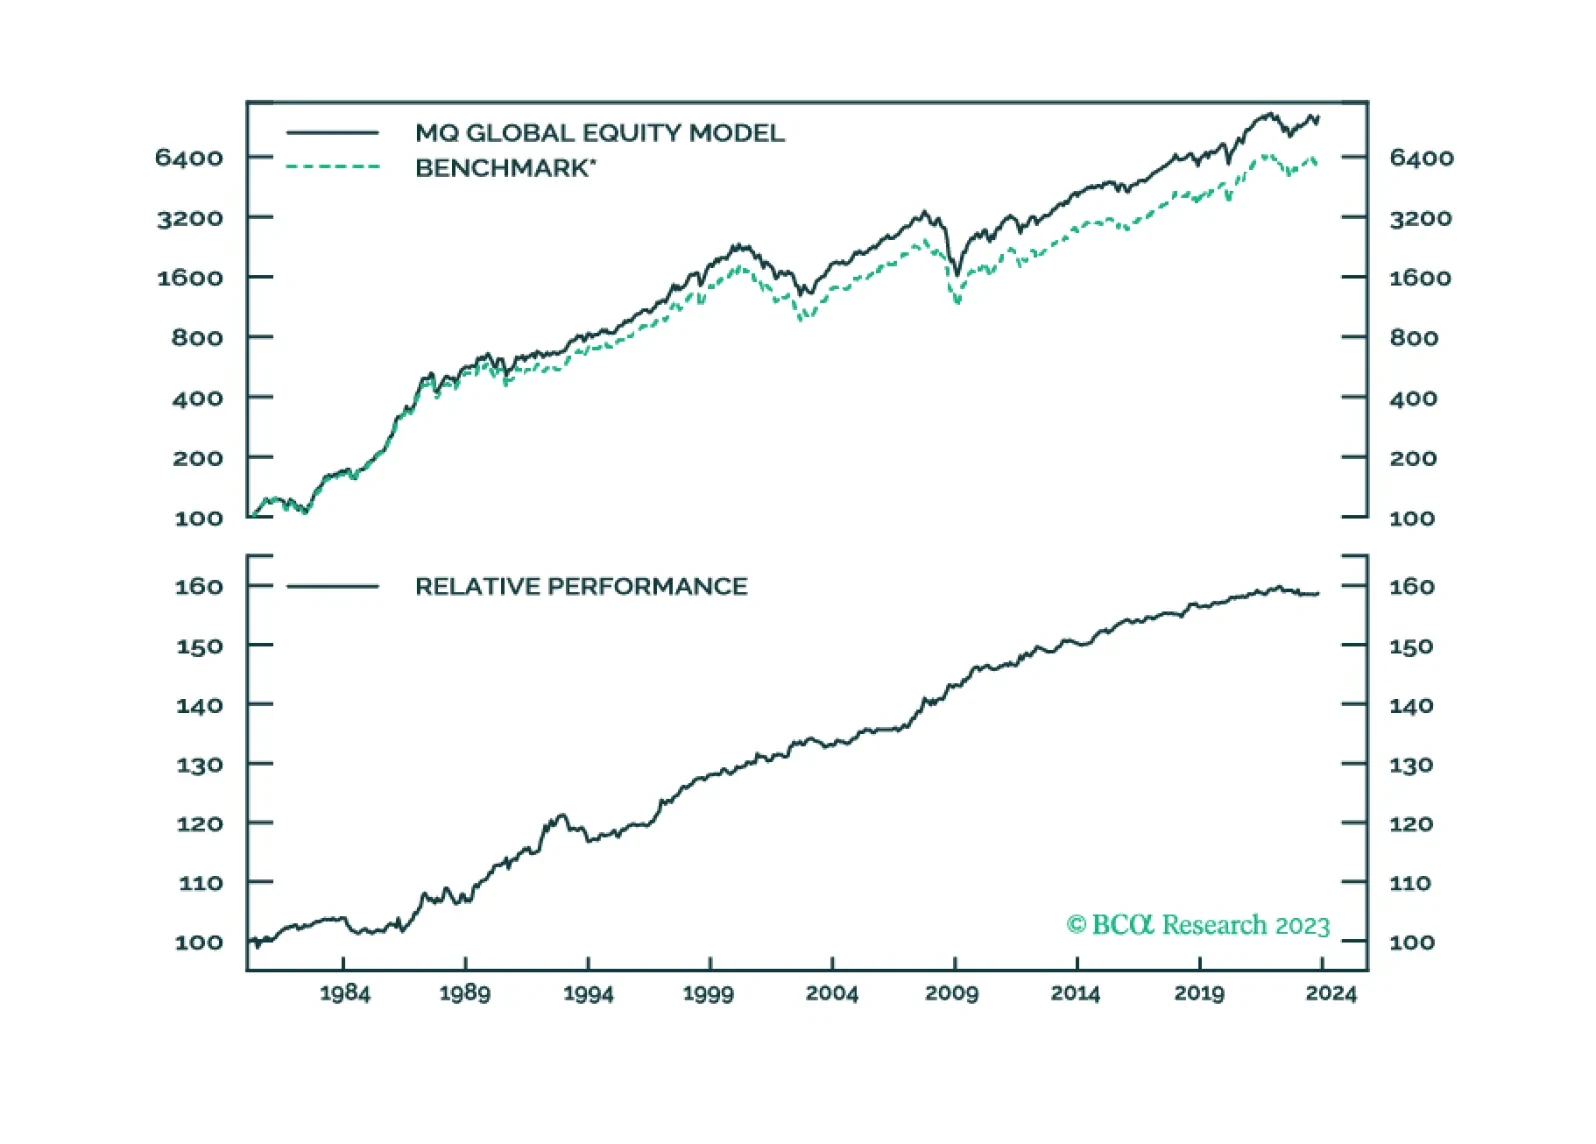
MacroQuant has upgraded equities to overweight at the expense of bonds. Cash remains neutral.
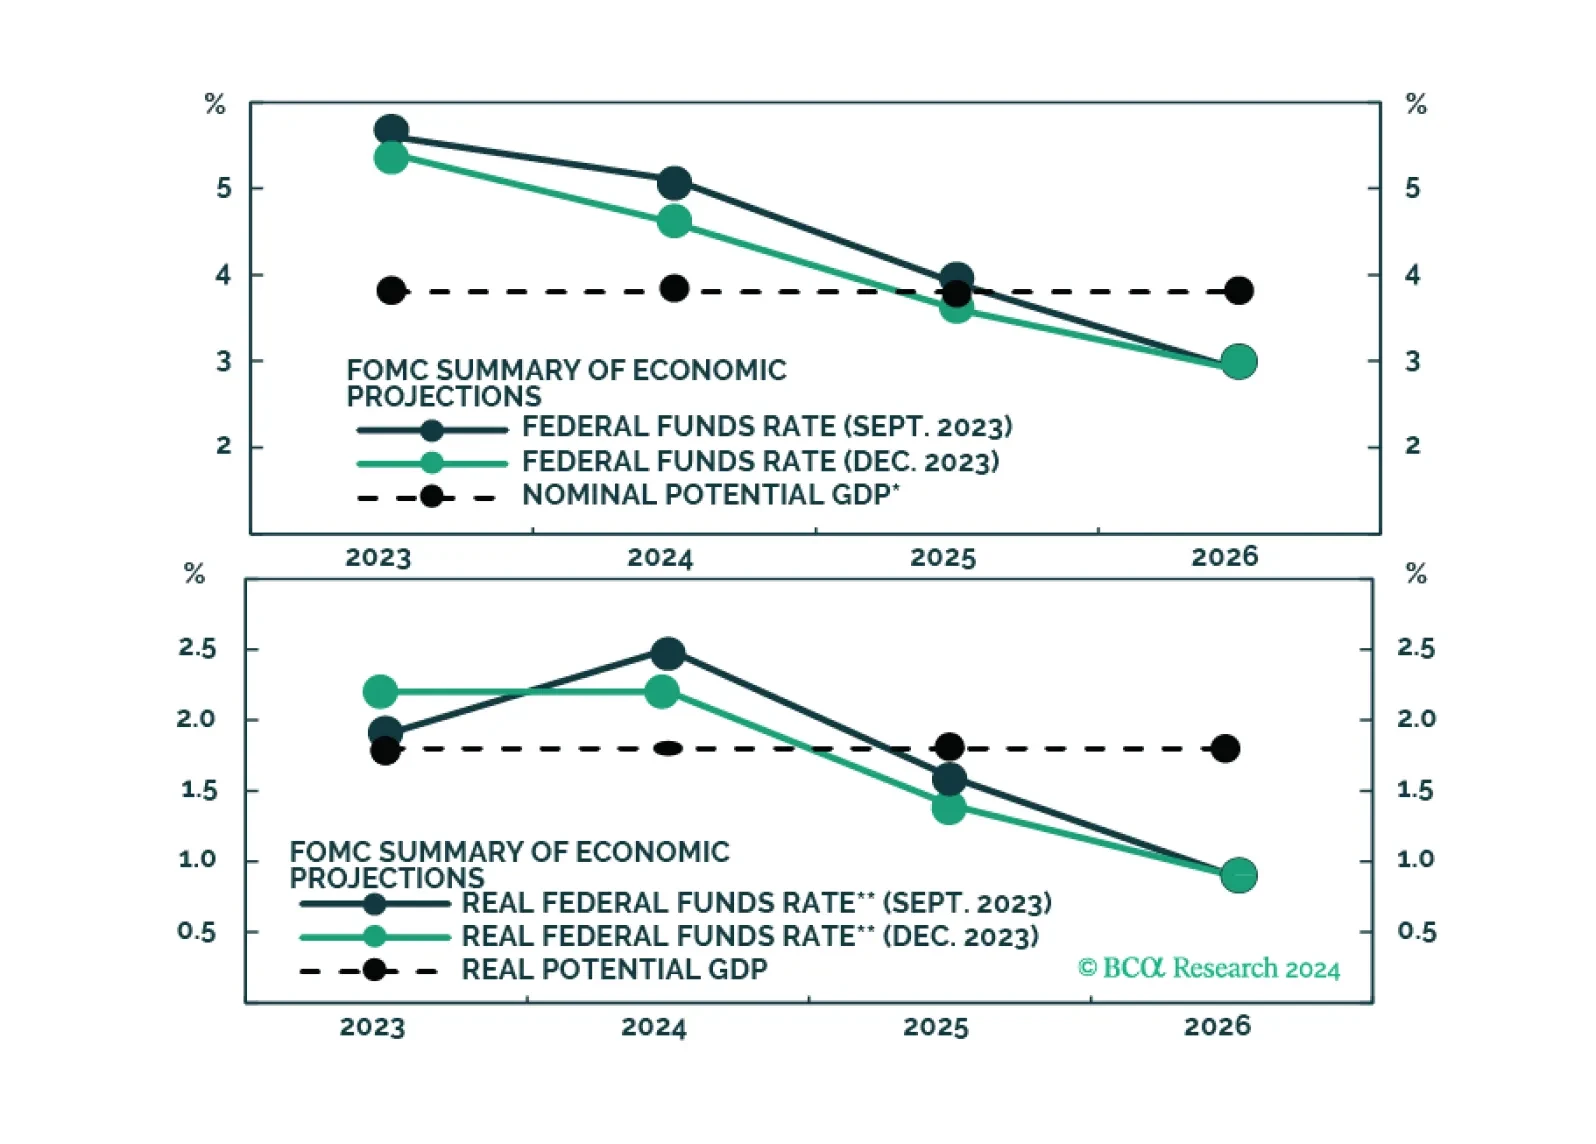
The market is excited by the idea that the Fed will cut rates early this year, even without a recession. But is that likely, with inflation still set to be around 2.8% mid-year?

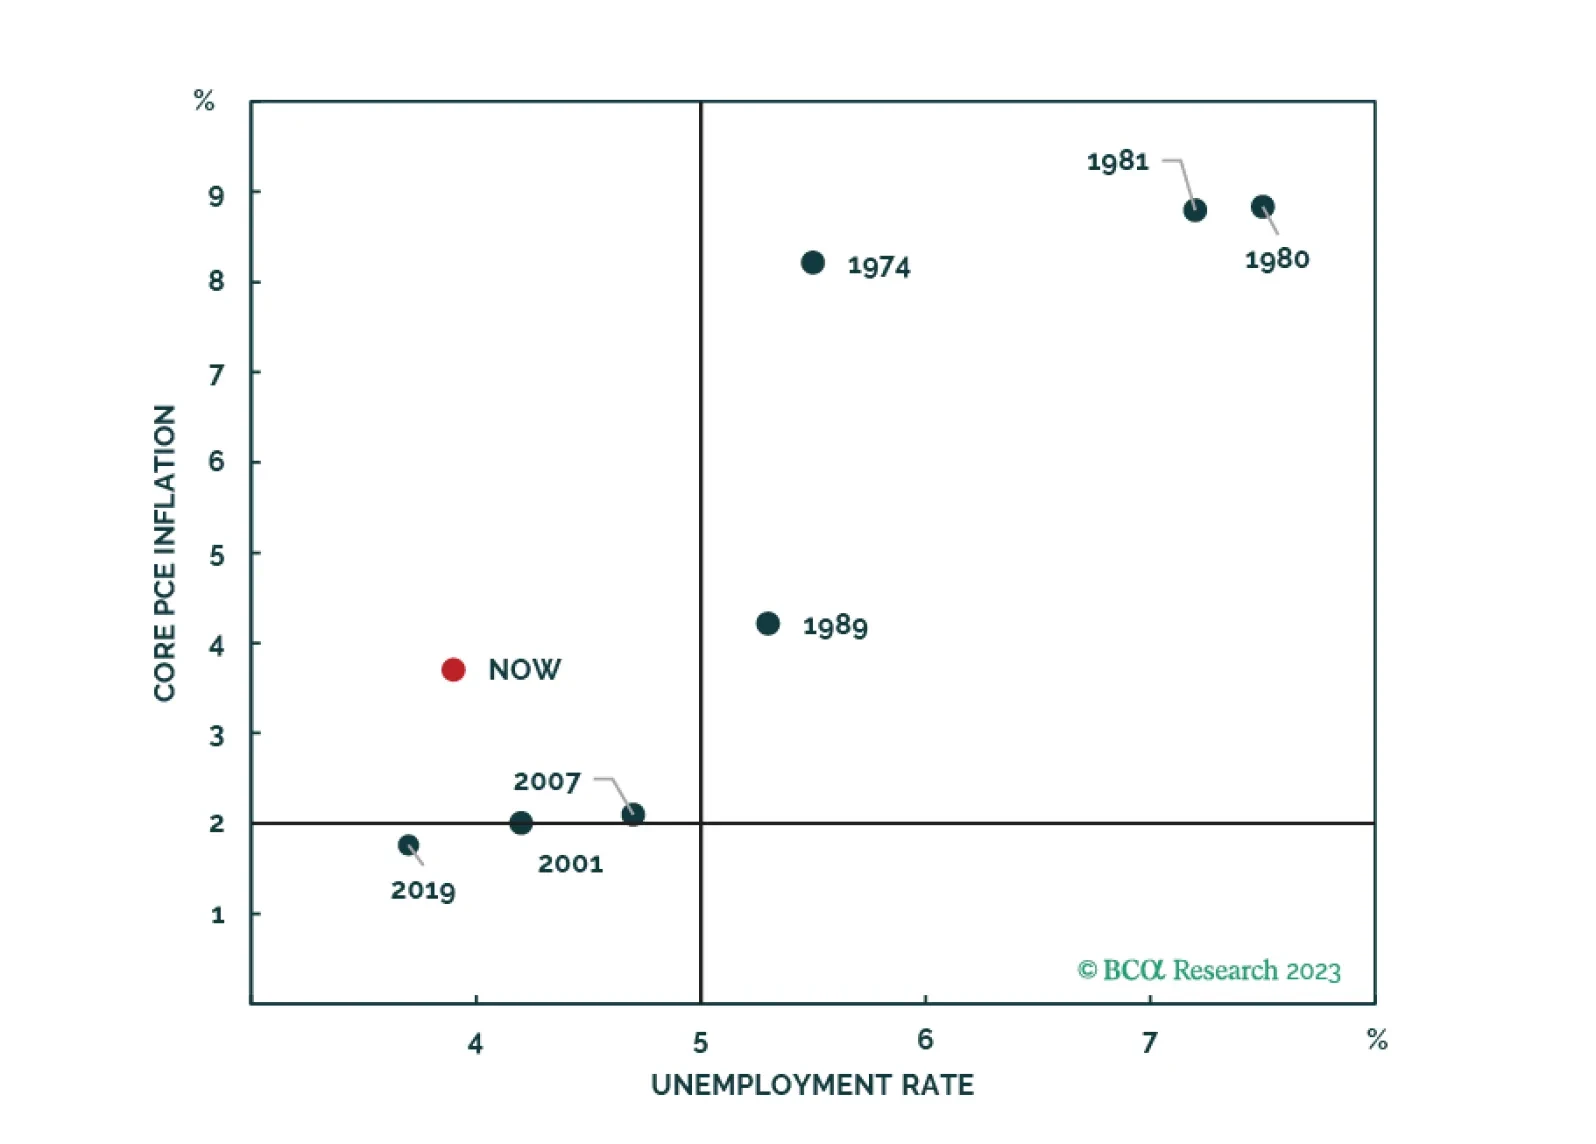
Inflation won’t fall fast enough for the Fed to cut rates preemptively before recession arrives. The risk/rewards balance is unfavorable for risk assets. Stay overweight bonds versus equities.