Latest from BCA Research
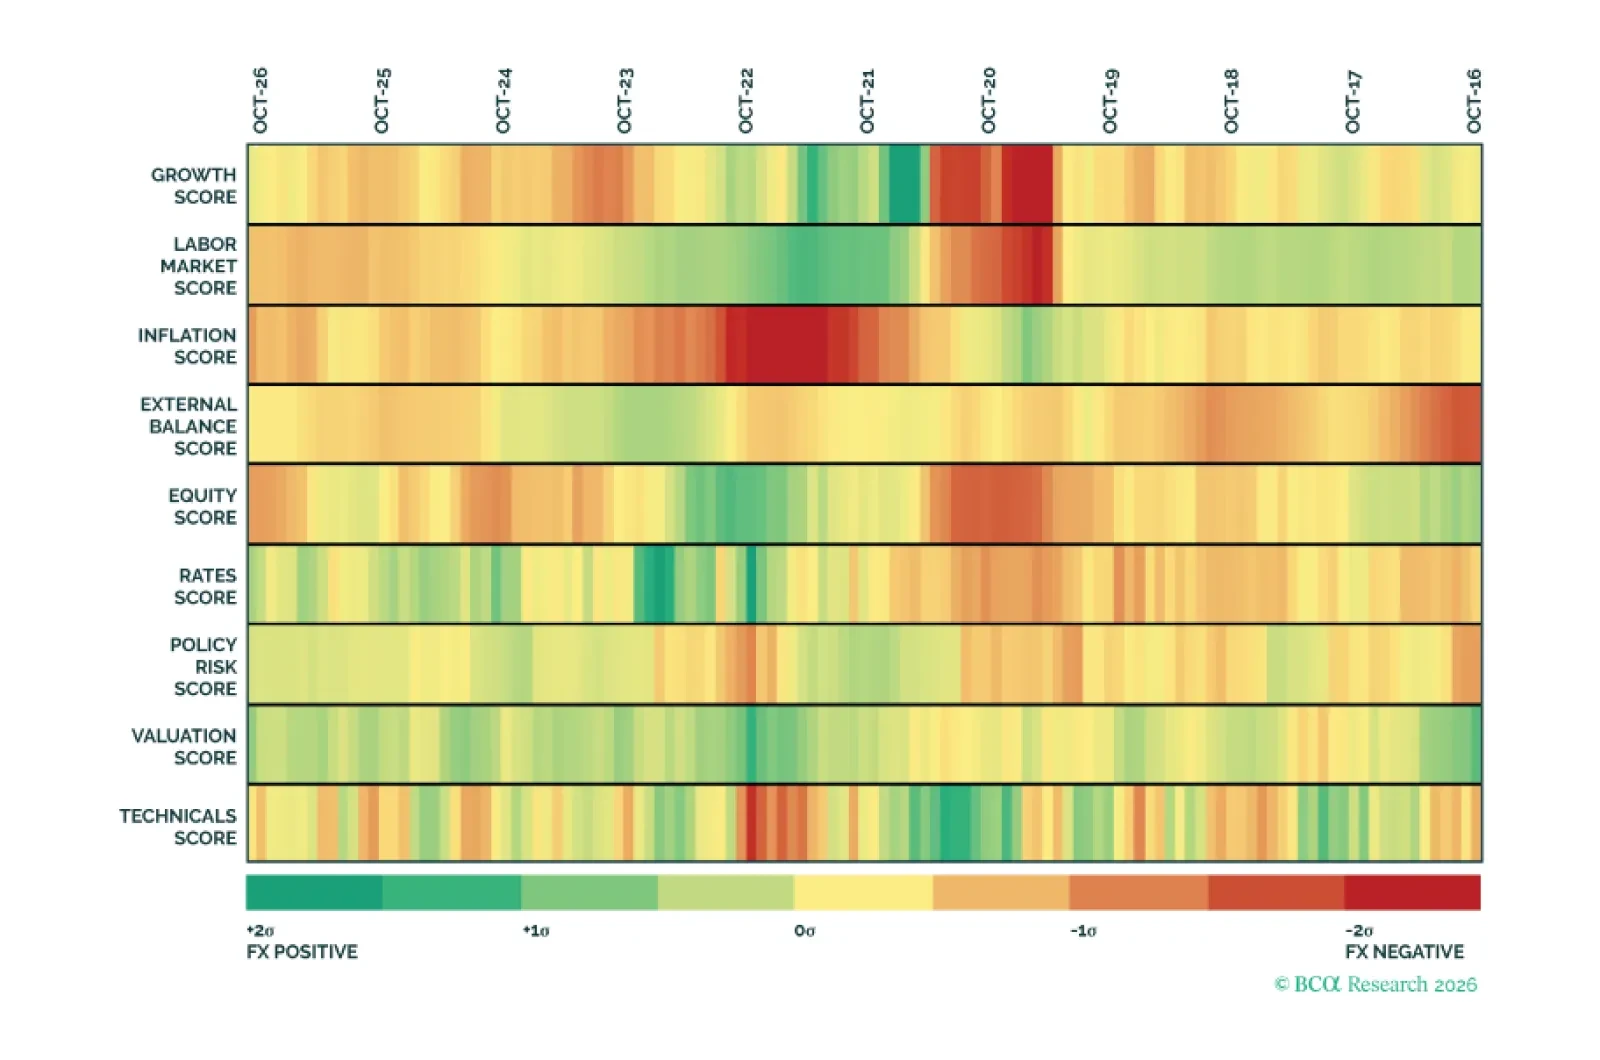
GBP offers attractive carry today, but the market’s aggressive rate hike pricing is likely to turn into a headwind within 12 months. Our latest Currency Chartpack examines the valuation, growth, rate, and policy drivers of the pound, showing why the long-term outlook is less rosy than near-term data implies.
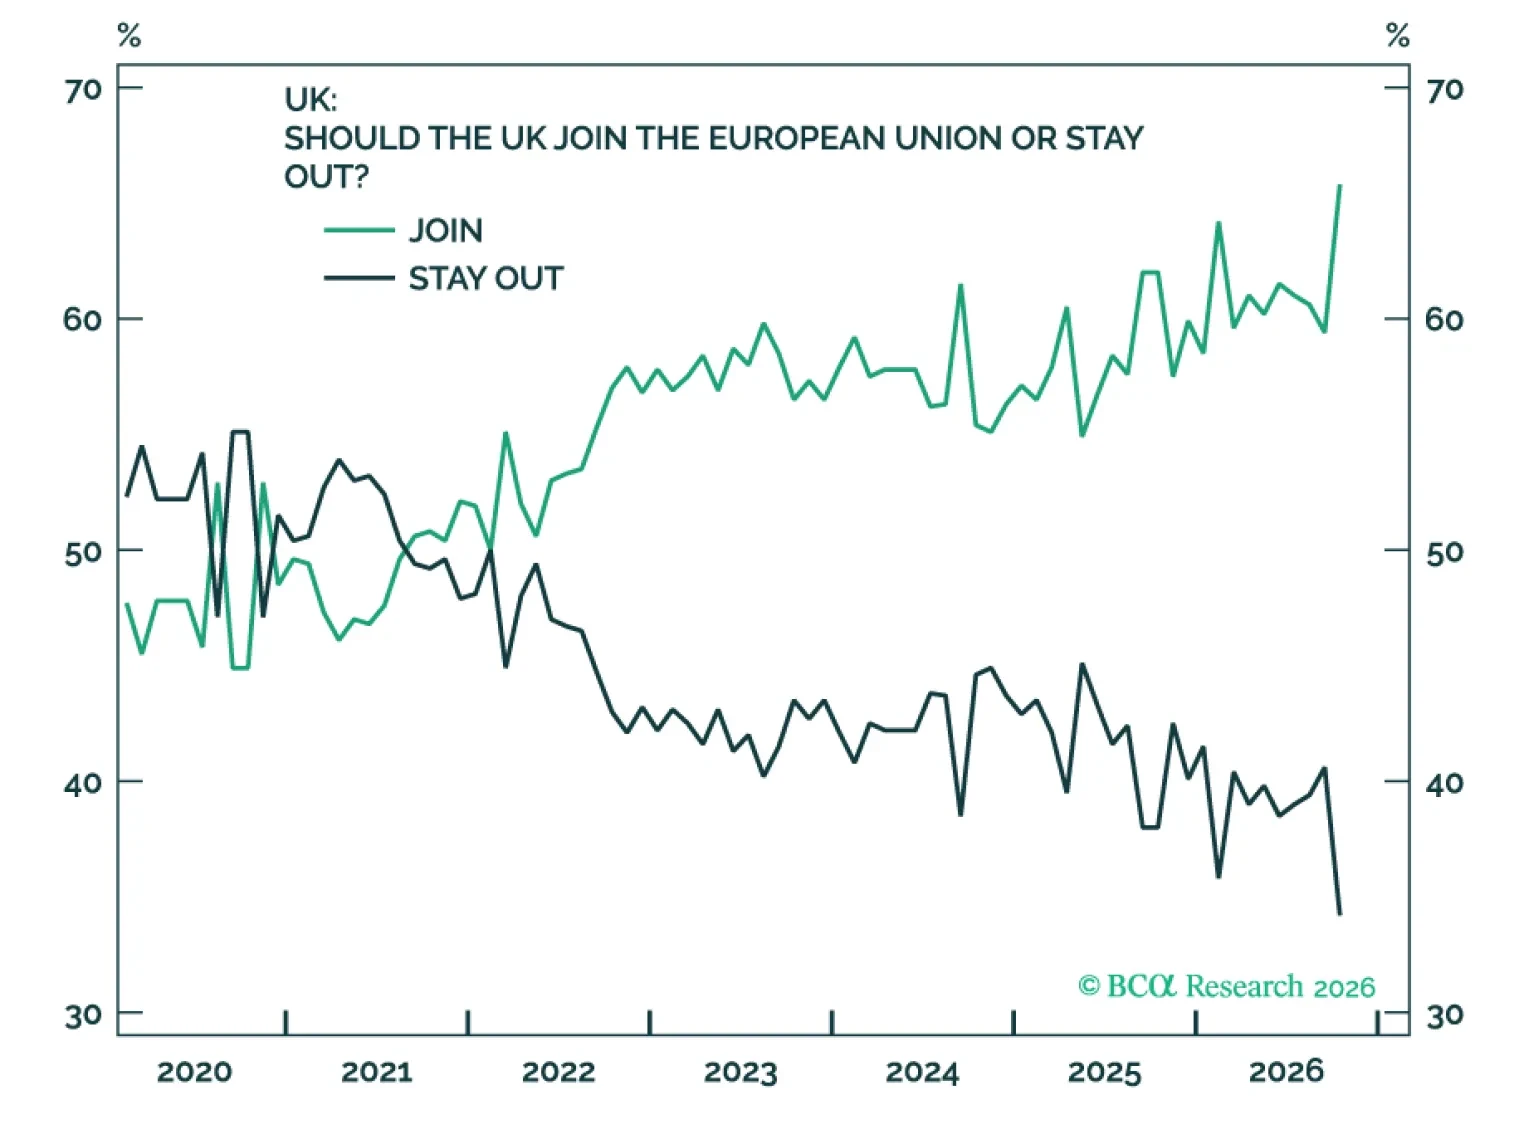
The UK faces many challenges but secessionism can be contained.
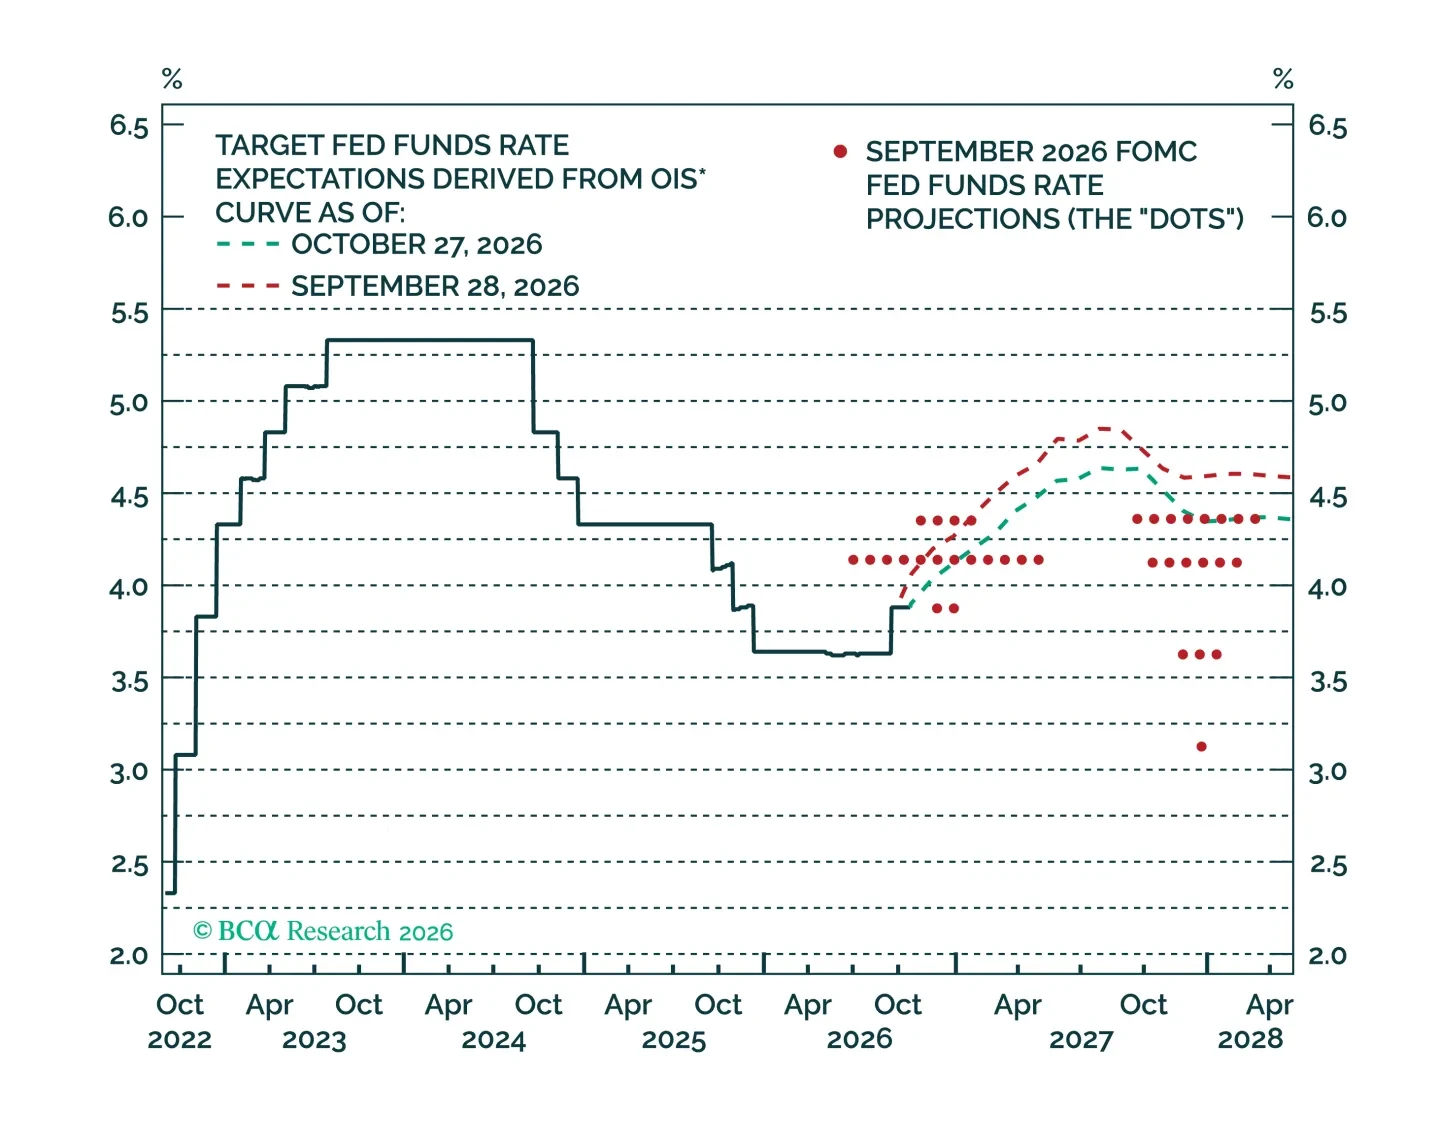
The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.
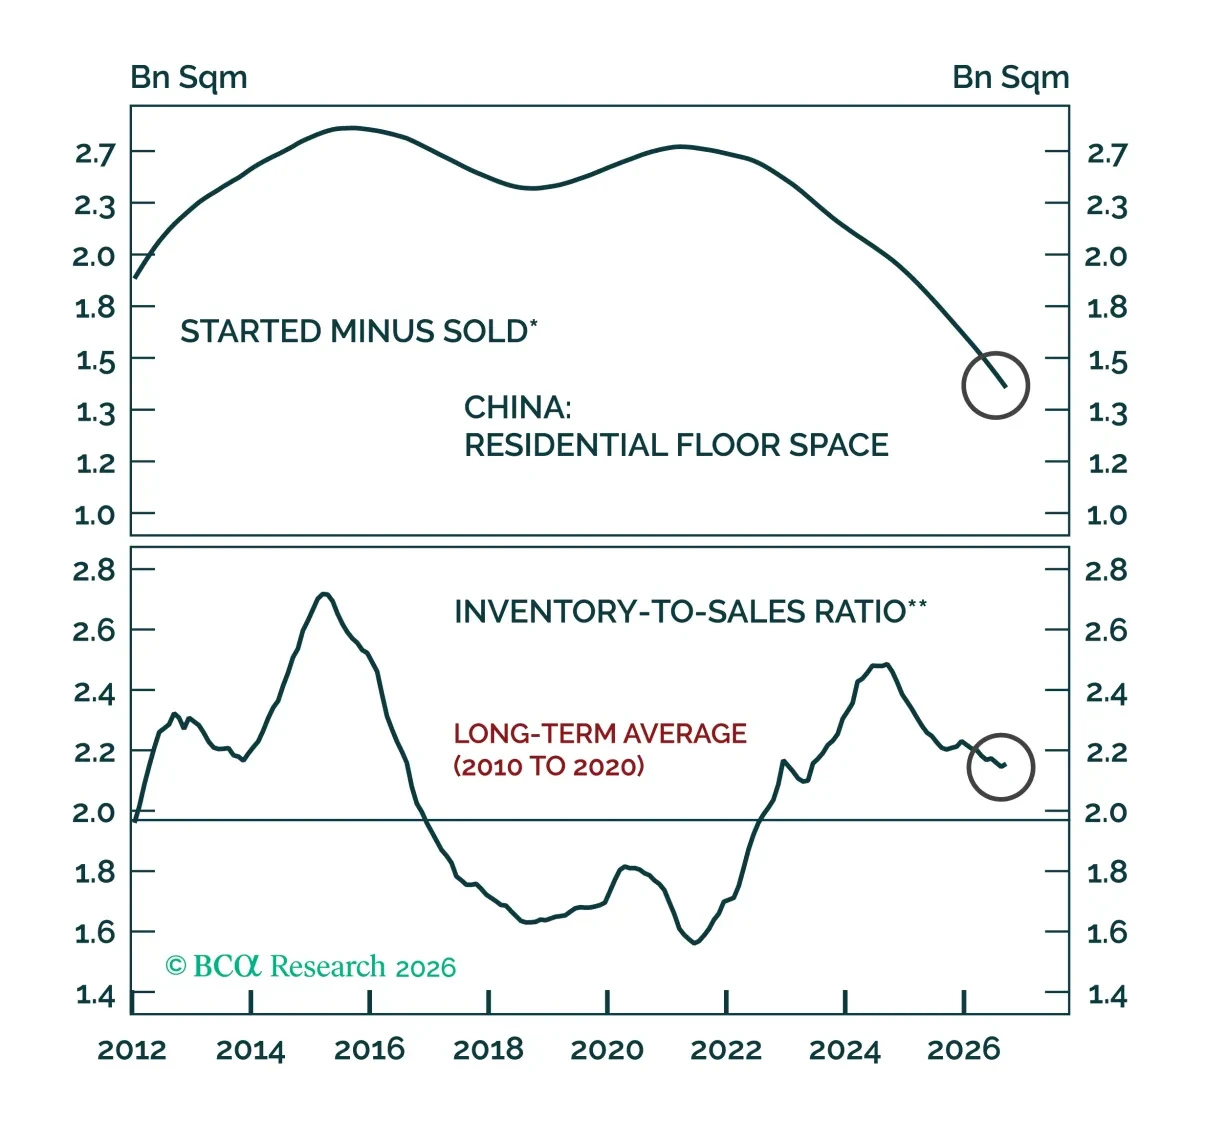
After a sharp five-year correction, China's top-tier housing markets will likely bottom out late next year. The rest of the country, however, will keep struggling with oversupply.
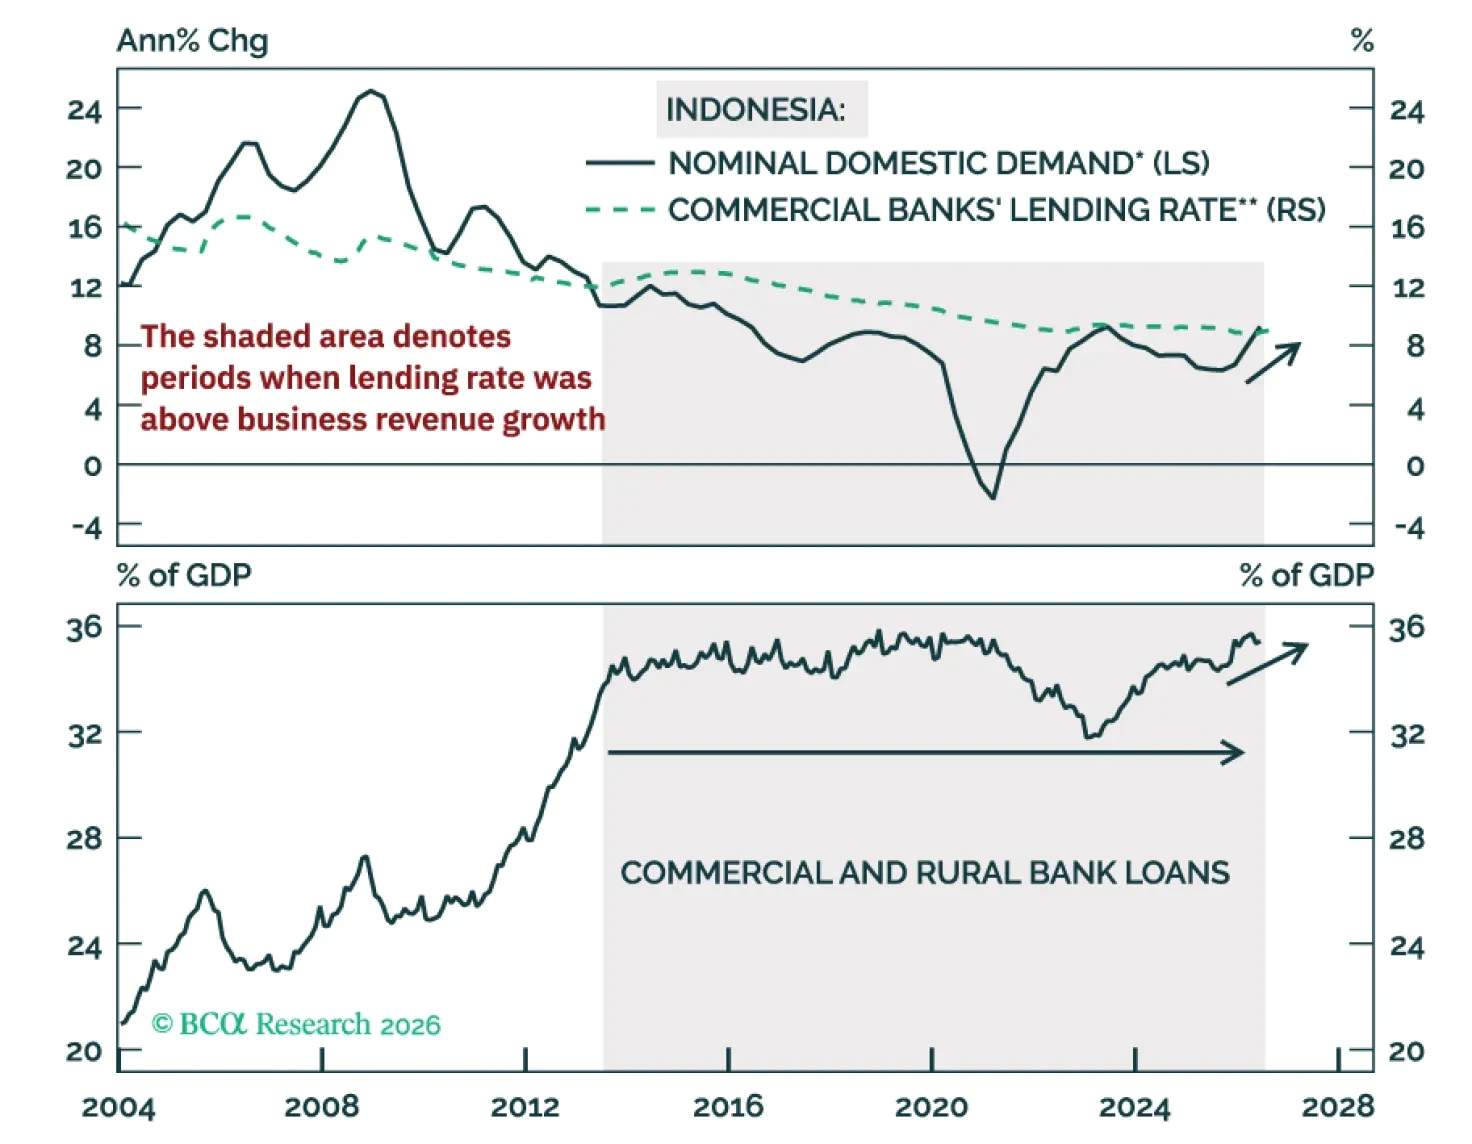
Given that the economy’s productive capacity is limited, government stimulus will lift nominal growth but do little to increase real output growth. The upshot will be rising inflation and wider twin deficits. This is bearish for the currency, bonds, and stocks.
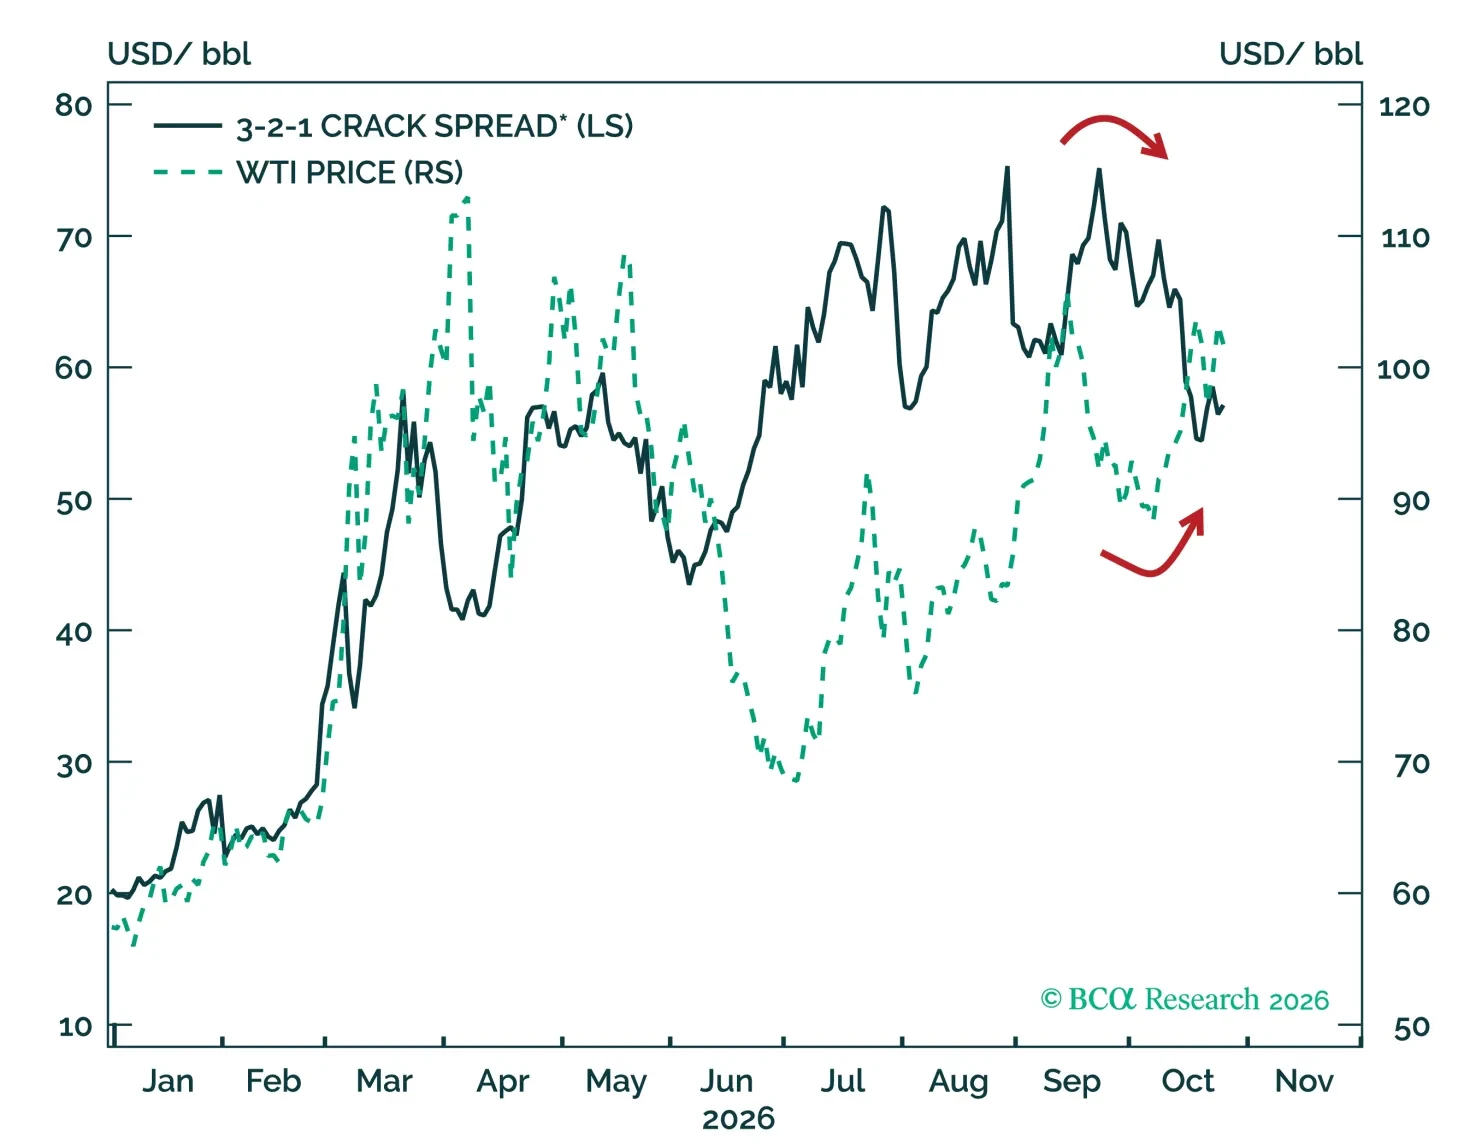
Crude has led the latest rally, leaving refined product prices behind and crack spreads narrower. We explain why the spread compression is unlikely to continue and why product prices will follow crude.
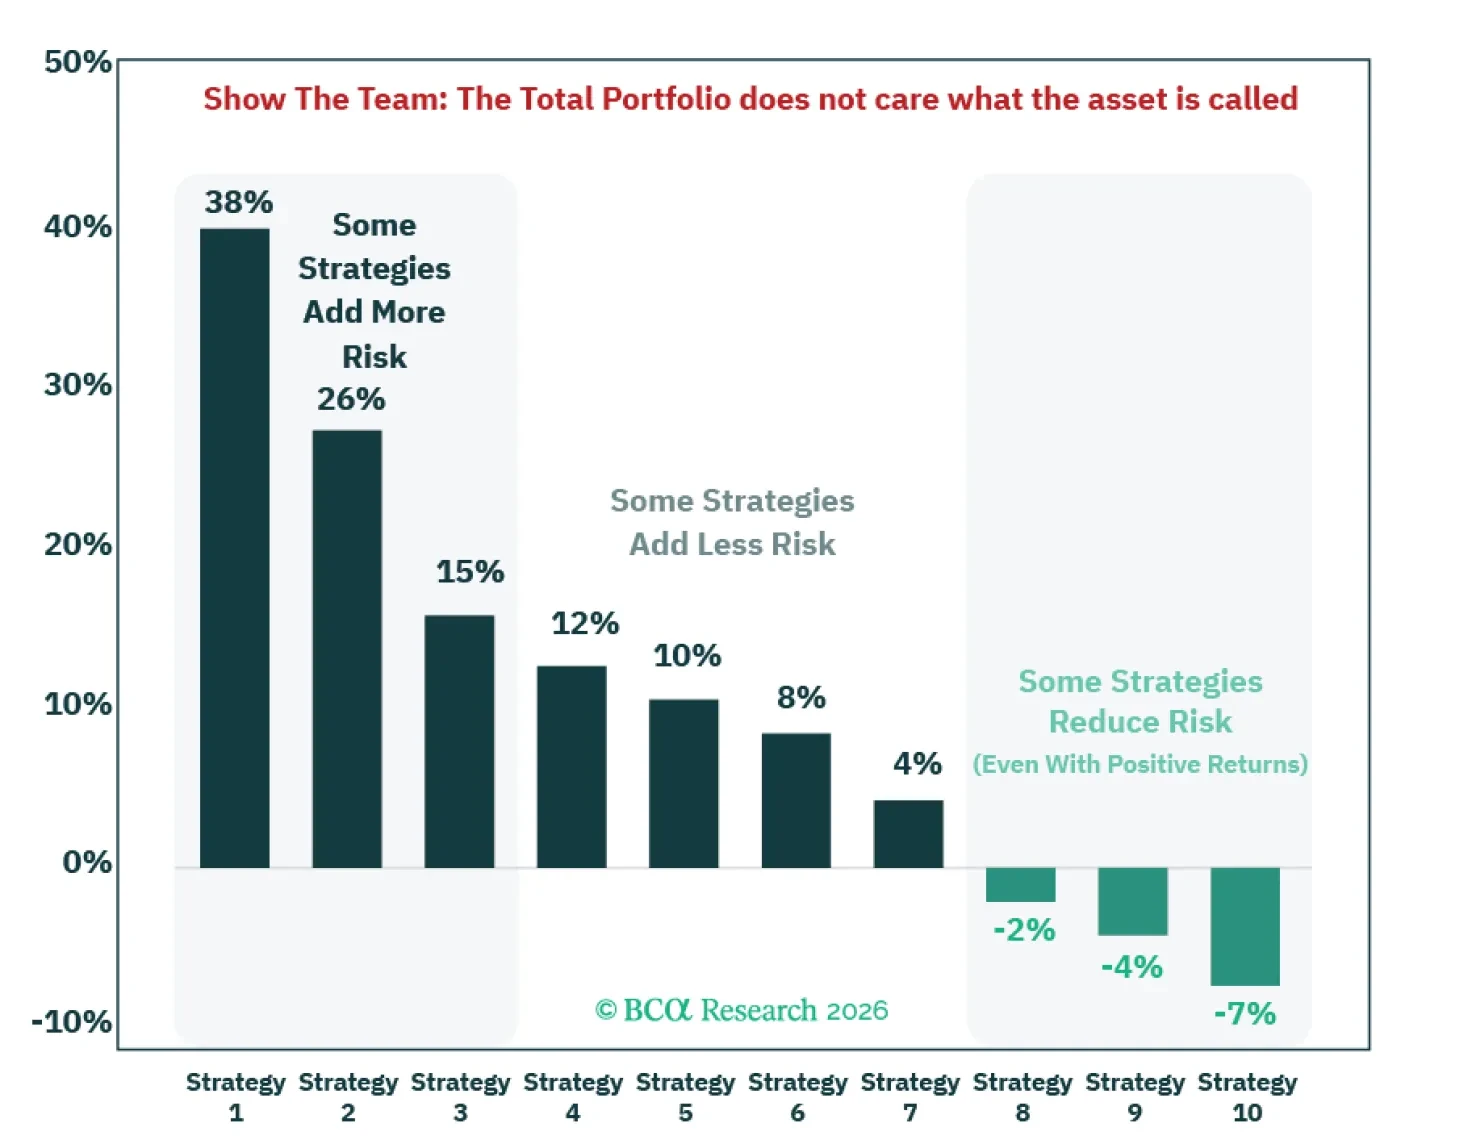
The Total Portfolio Approach stumbles really on one thing: the team. Everyone says it, but nobody has prescribed the fix. We provide three logistical principles that close the gap. And they work for SAA investors too.
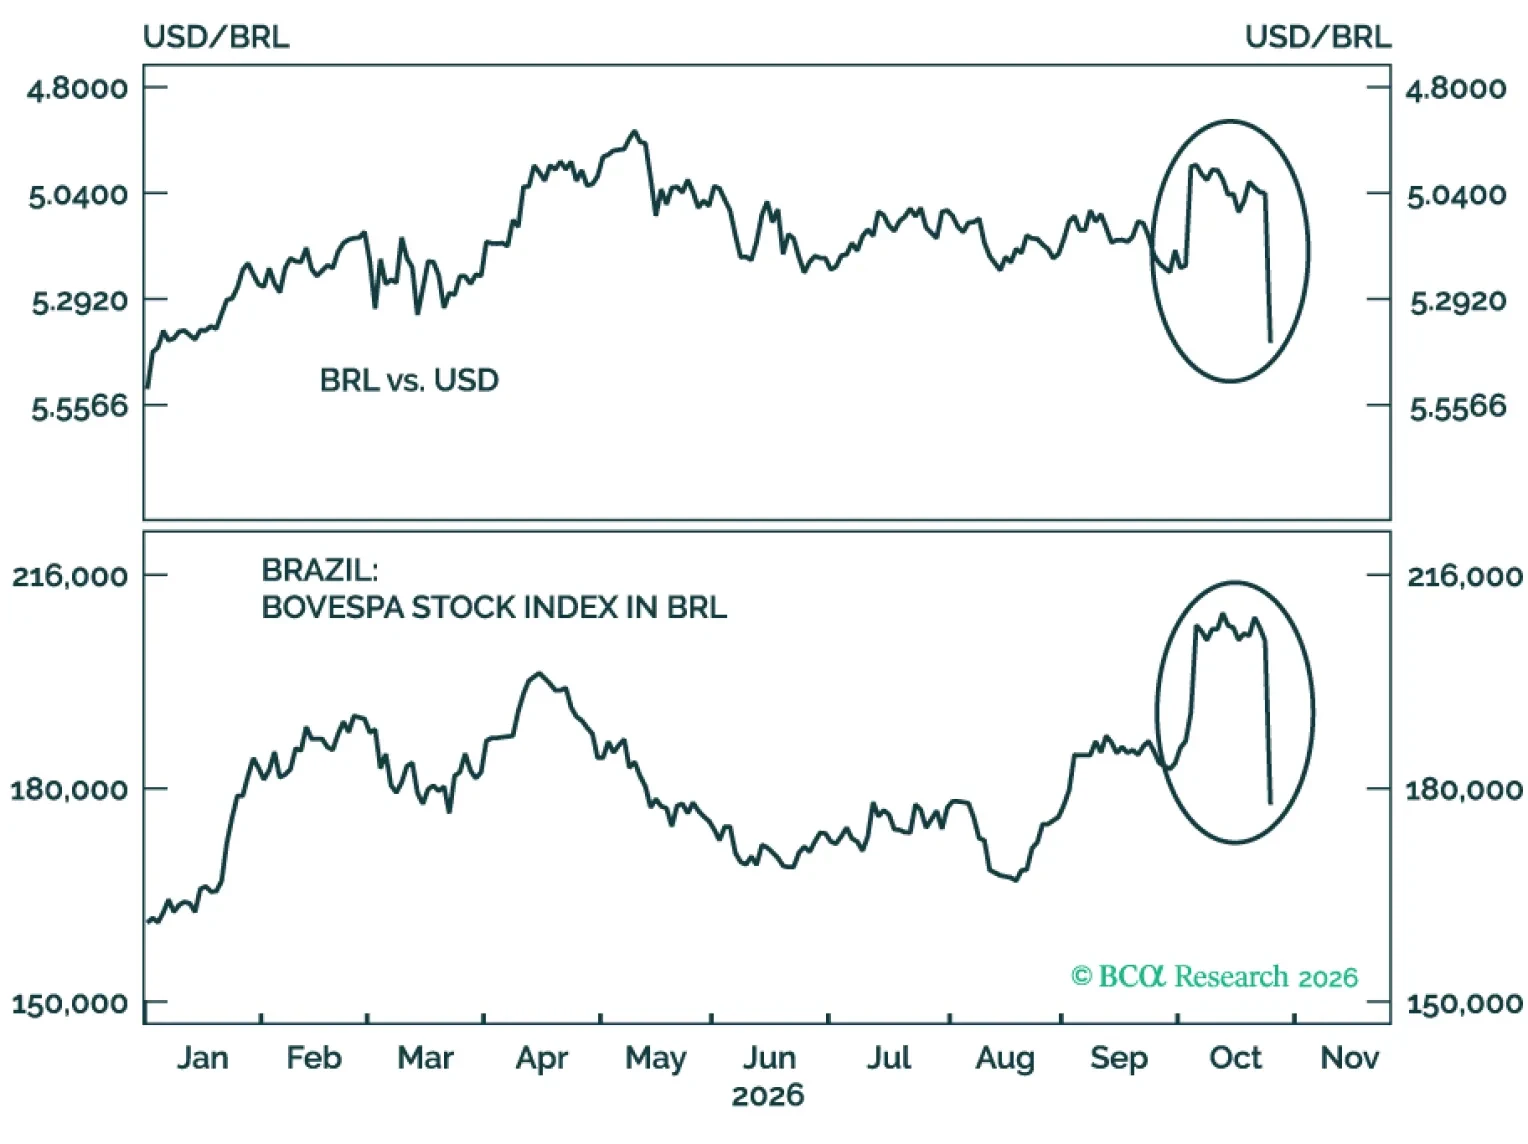
Brazil’s elections have turned into a game of roulette for investors. Bulls and bears were each wrong-footed between the first and second rounds of elections. We are downgrading Brazilian equities, local bonds, and sovereign credit to underweight within their respective EM portfolios.