Latest from BCA Research
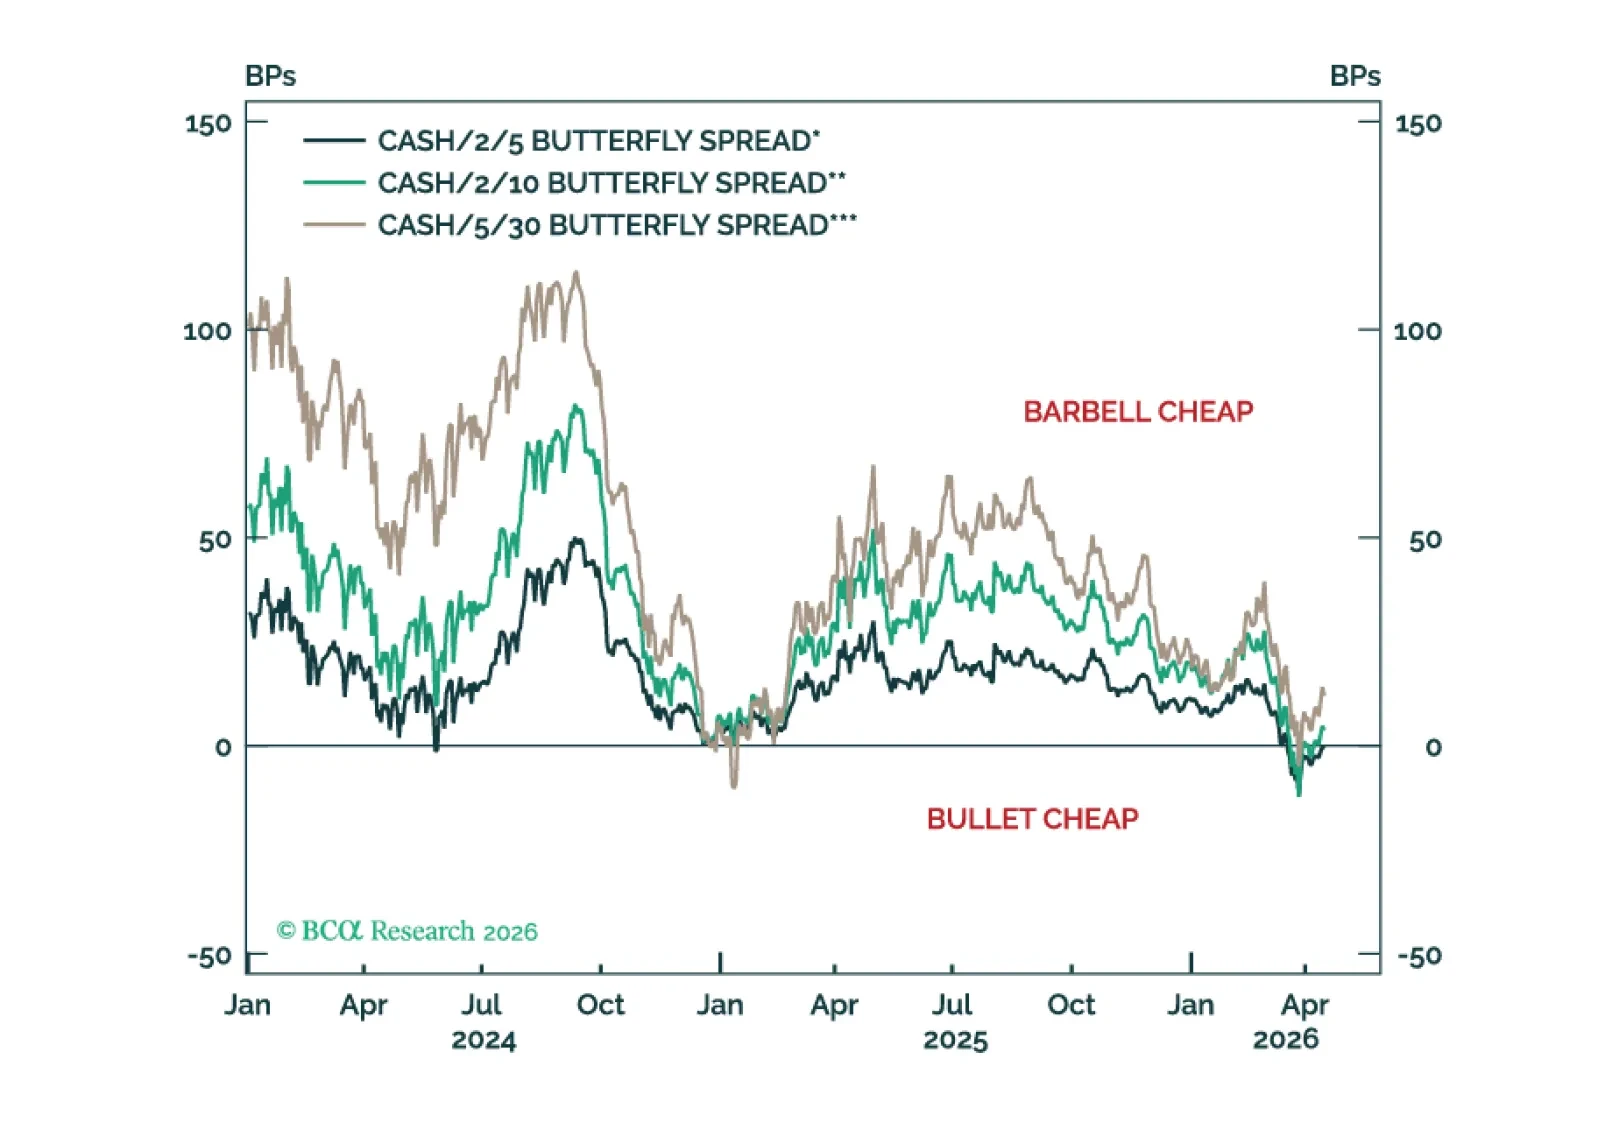
The rates market is moving back into a low vol regime, but with yields at a higher level. This argues for maximizing carry across the Treasury curve.
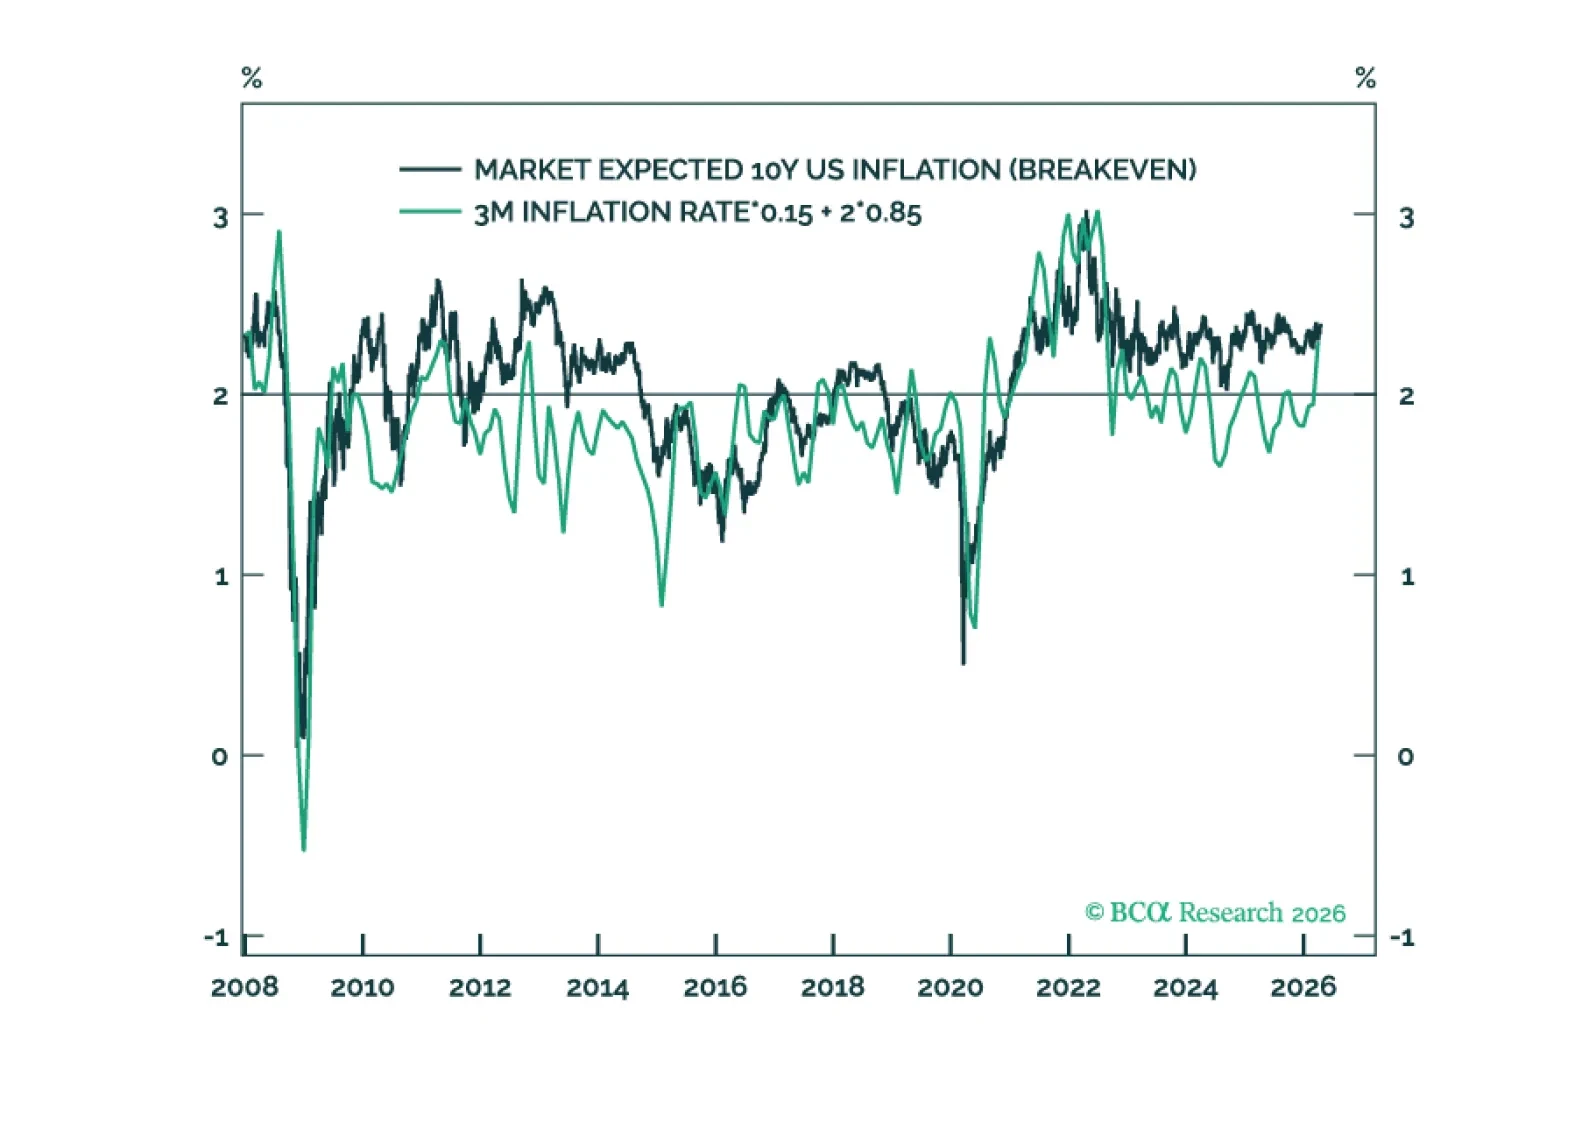
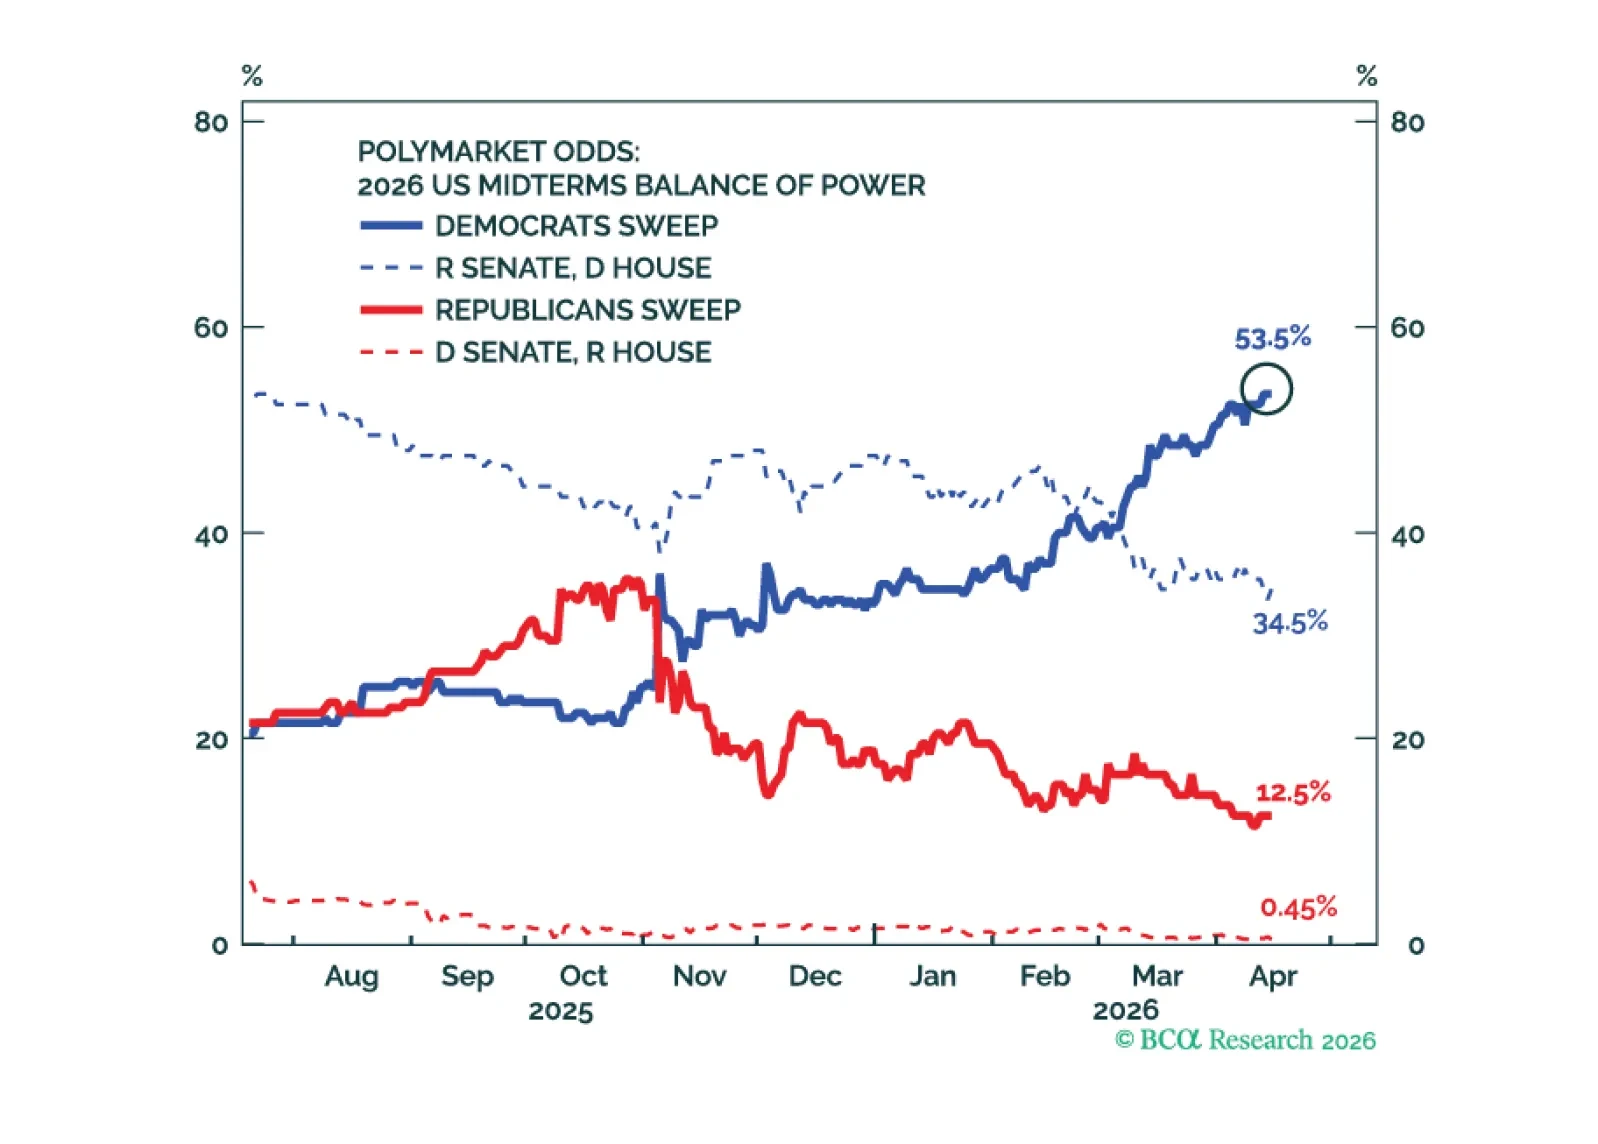
Markets may be underpricing a bifurcated political outcome. Unless the Iran deescalation succeeds, the delayed economic fallout from the energy shock could materially worsen Republican prospects and raise the probability of a Democratic Senate victory.
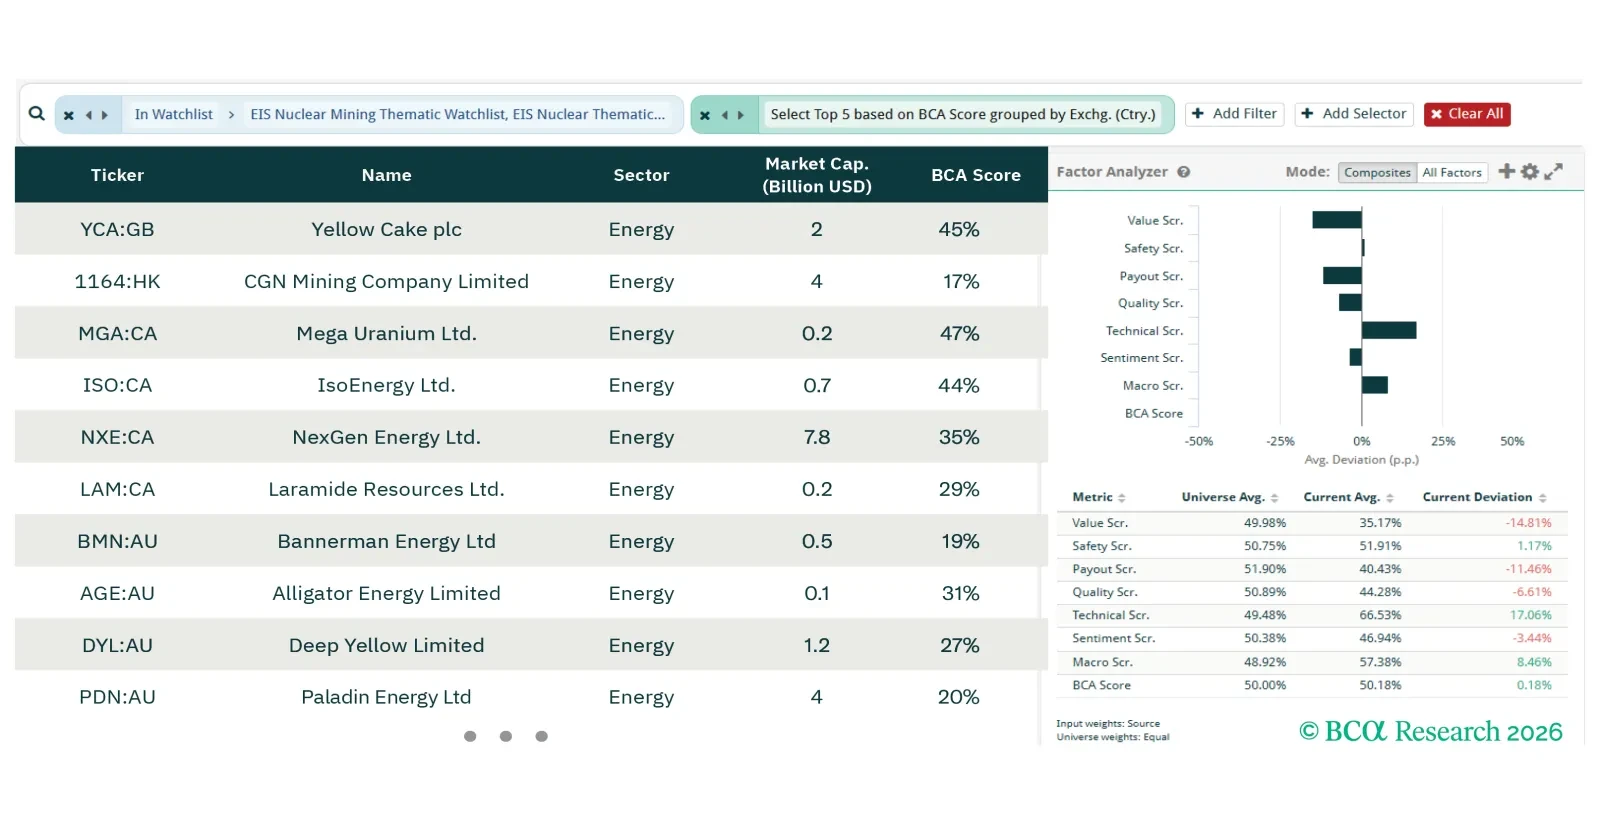
In this screener report, we explore opportunities in nuclear theme, geopolitical hedge, and winners from AI productivity boom.
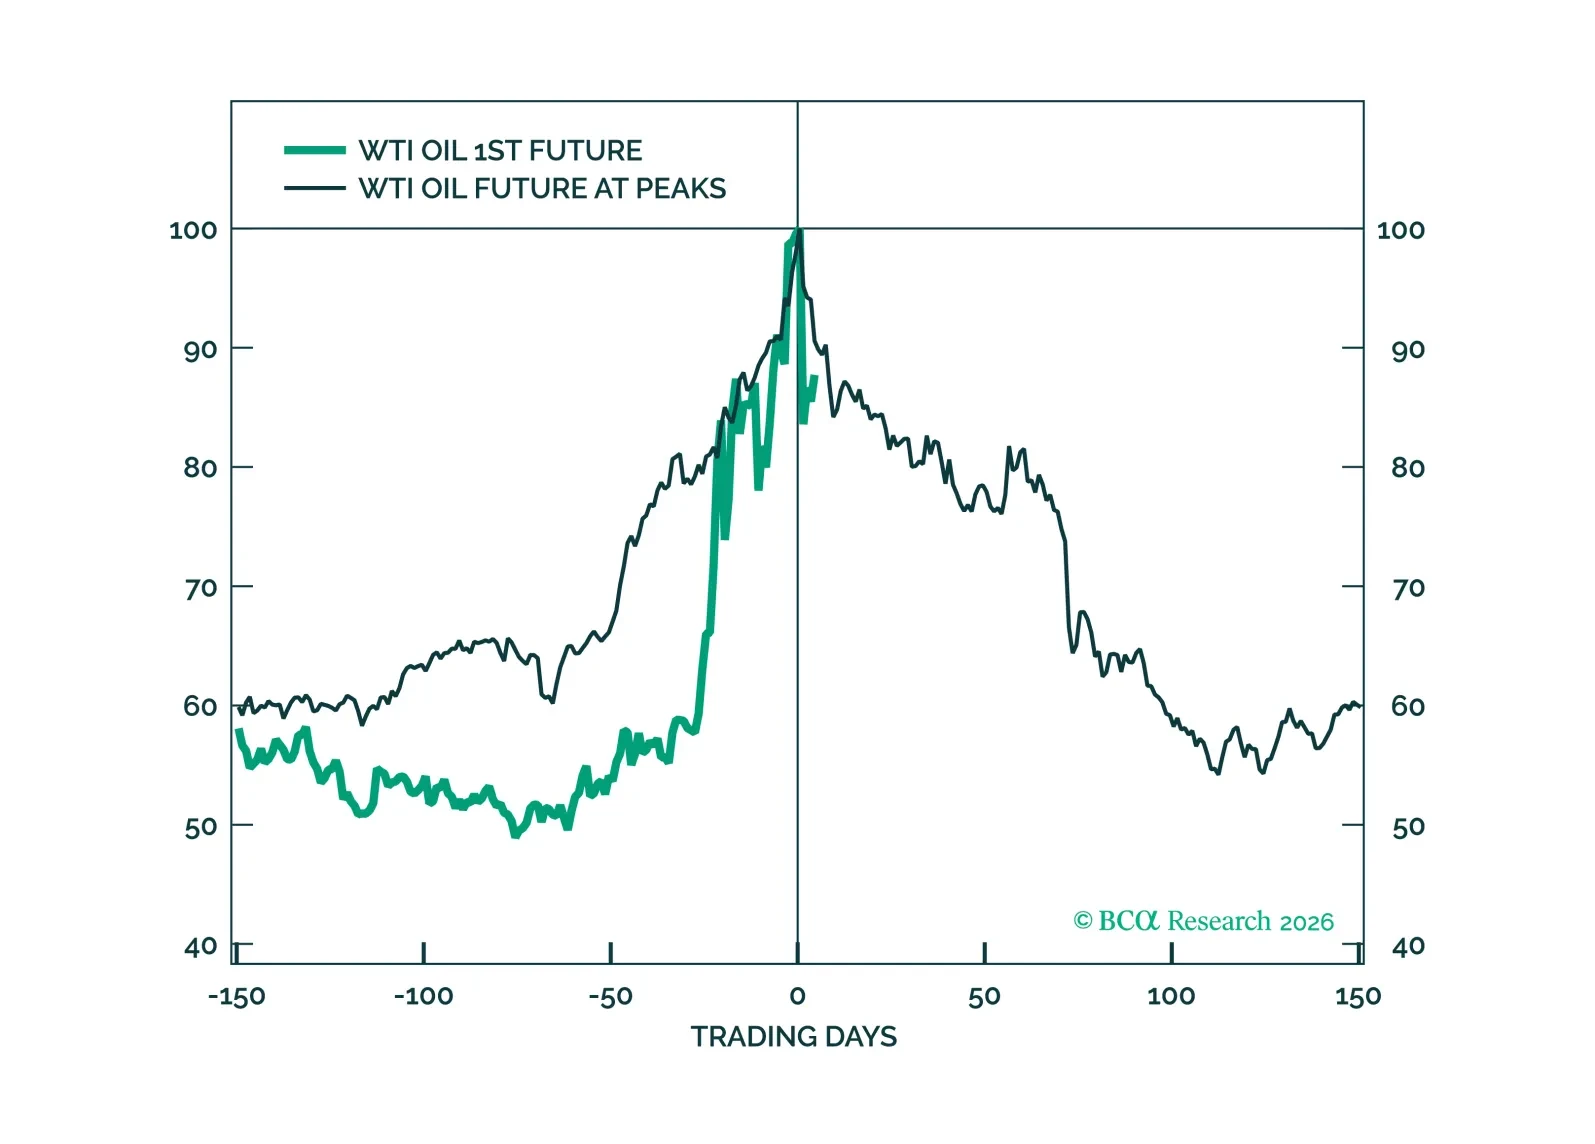
In this chartpack, we present the logic behind our sanguine view and why we think that oil has peaked. We also elucidate our three main scenarios from here on out.
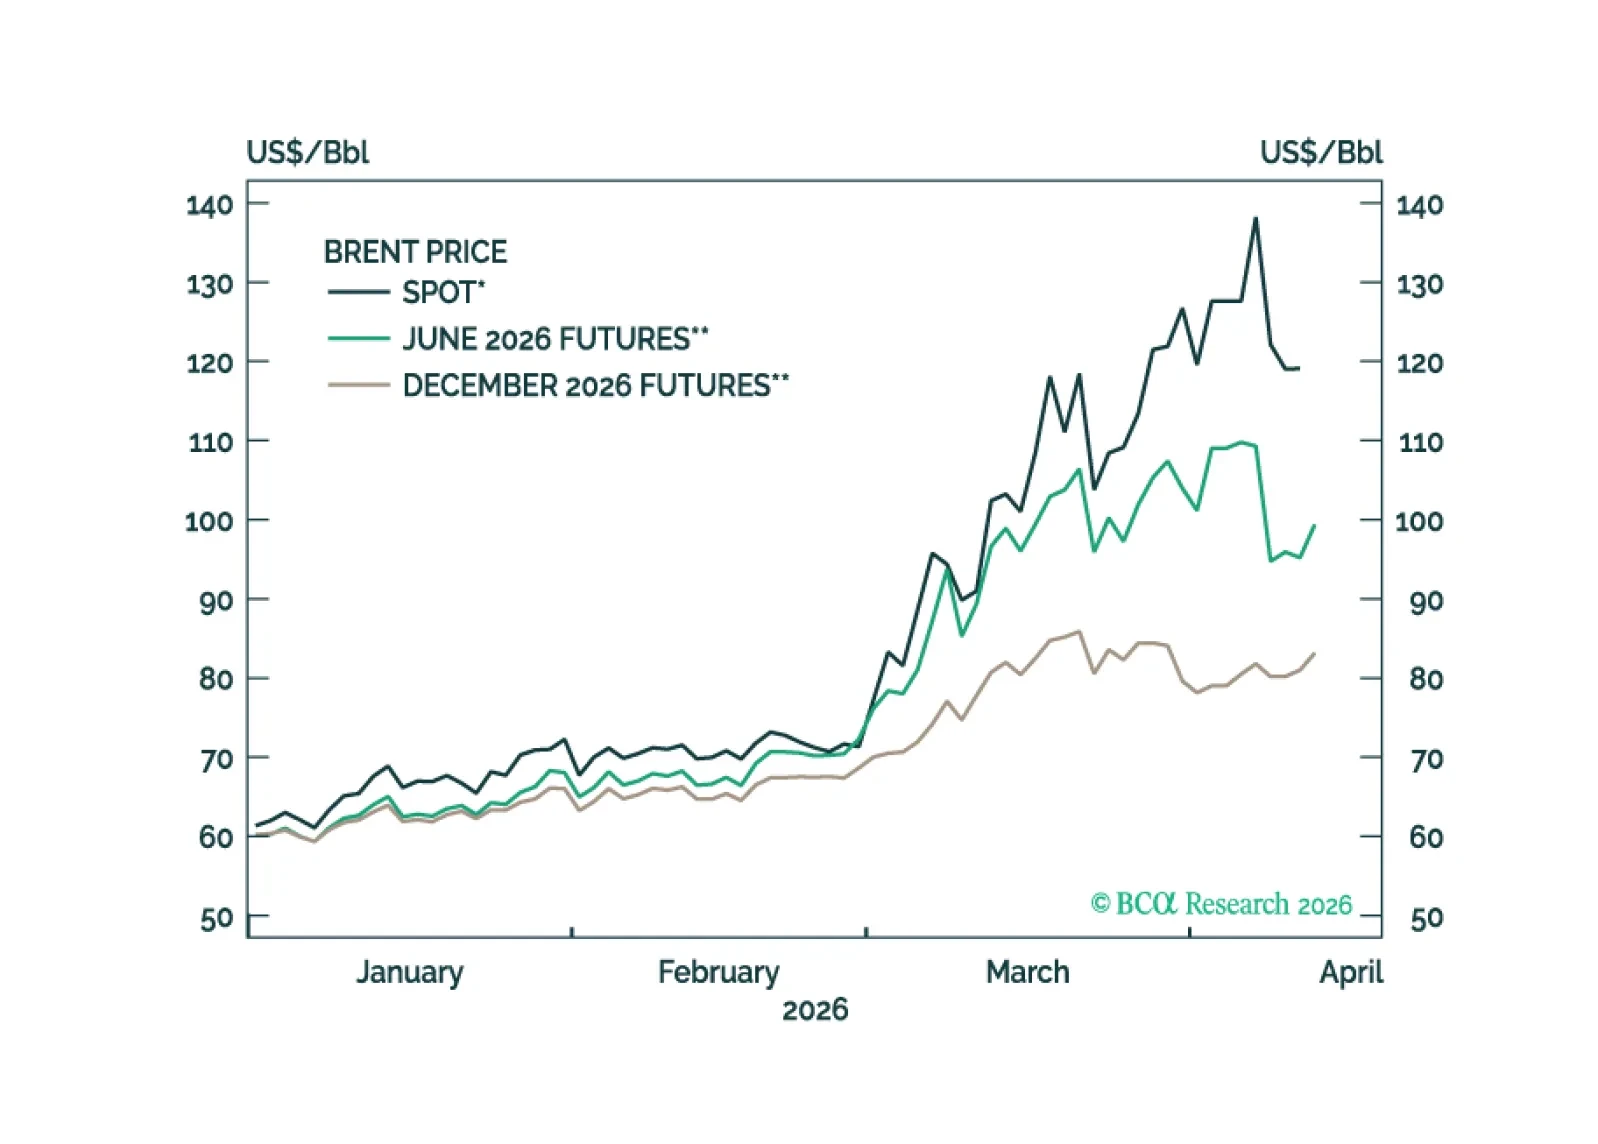
The main reason the oil shock has not caused stocks to crash is that investors do not expect the shock to last very long.
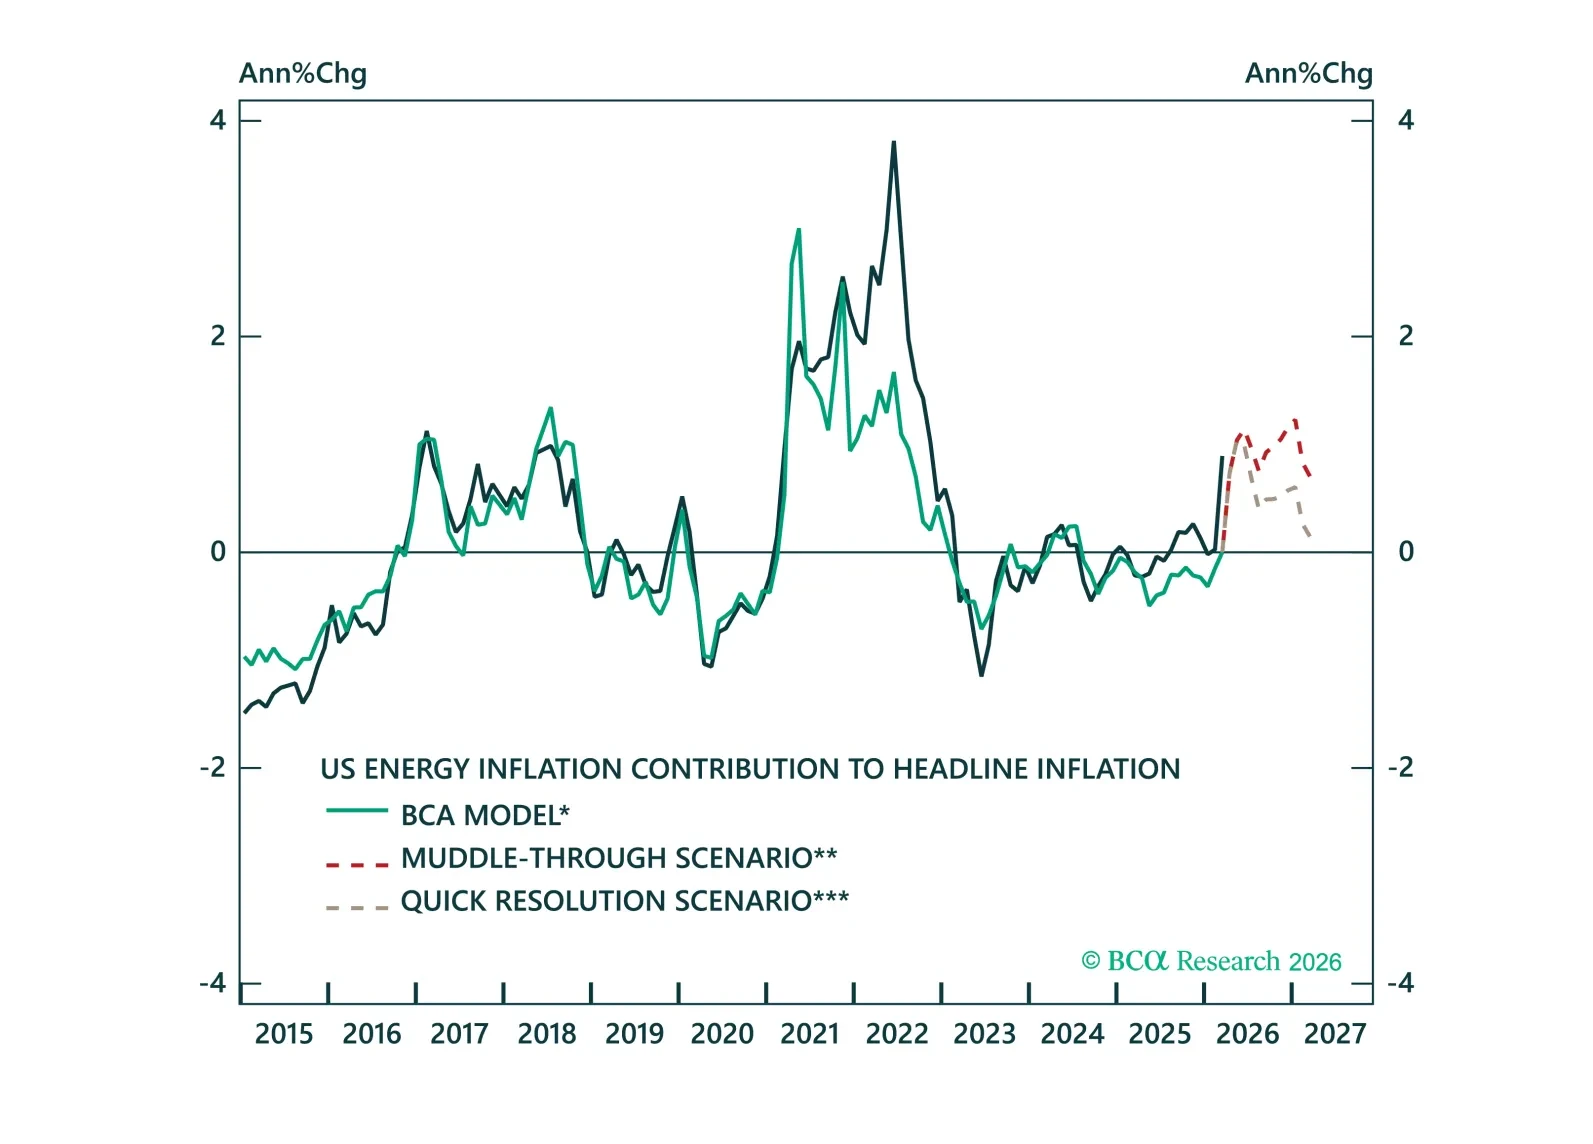
Volatility is high, but the path for yields is clearer than it looks. Across three oil scenarios, we show how policy responses shape fixed income markets and why the balance of risks still points to lower yields.

When the ceasefire between Iran and the US was announced on April 8, several clients told us that their geopolitical consultants were pitching a bearish narrative. The US had set up the two-week ceasefire to surge more material and troops to the region, so as to set up the next phase of the conflict. One such advisory firm also pointed out that it was unlikely that the US would hold back on further conflict since it had “already amassed ground troops to the region.”
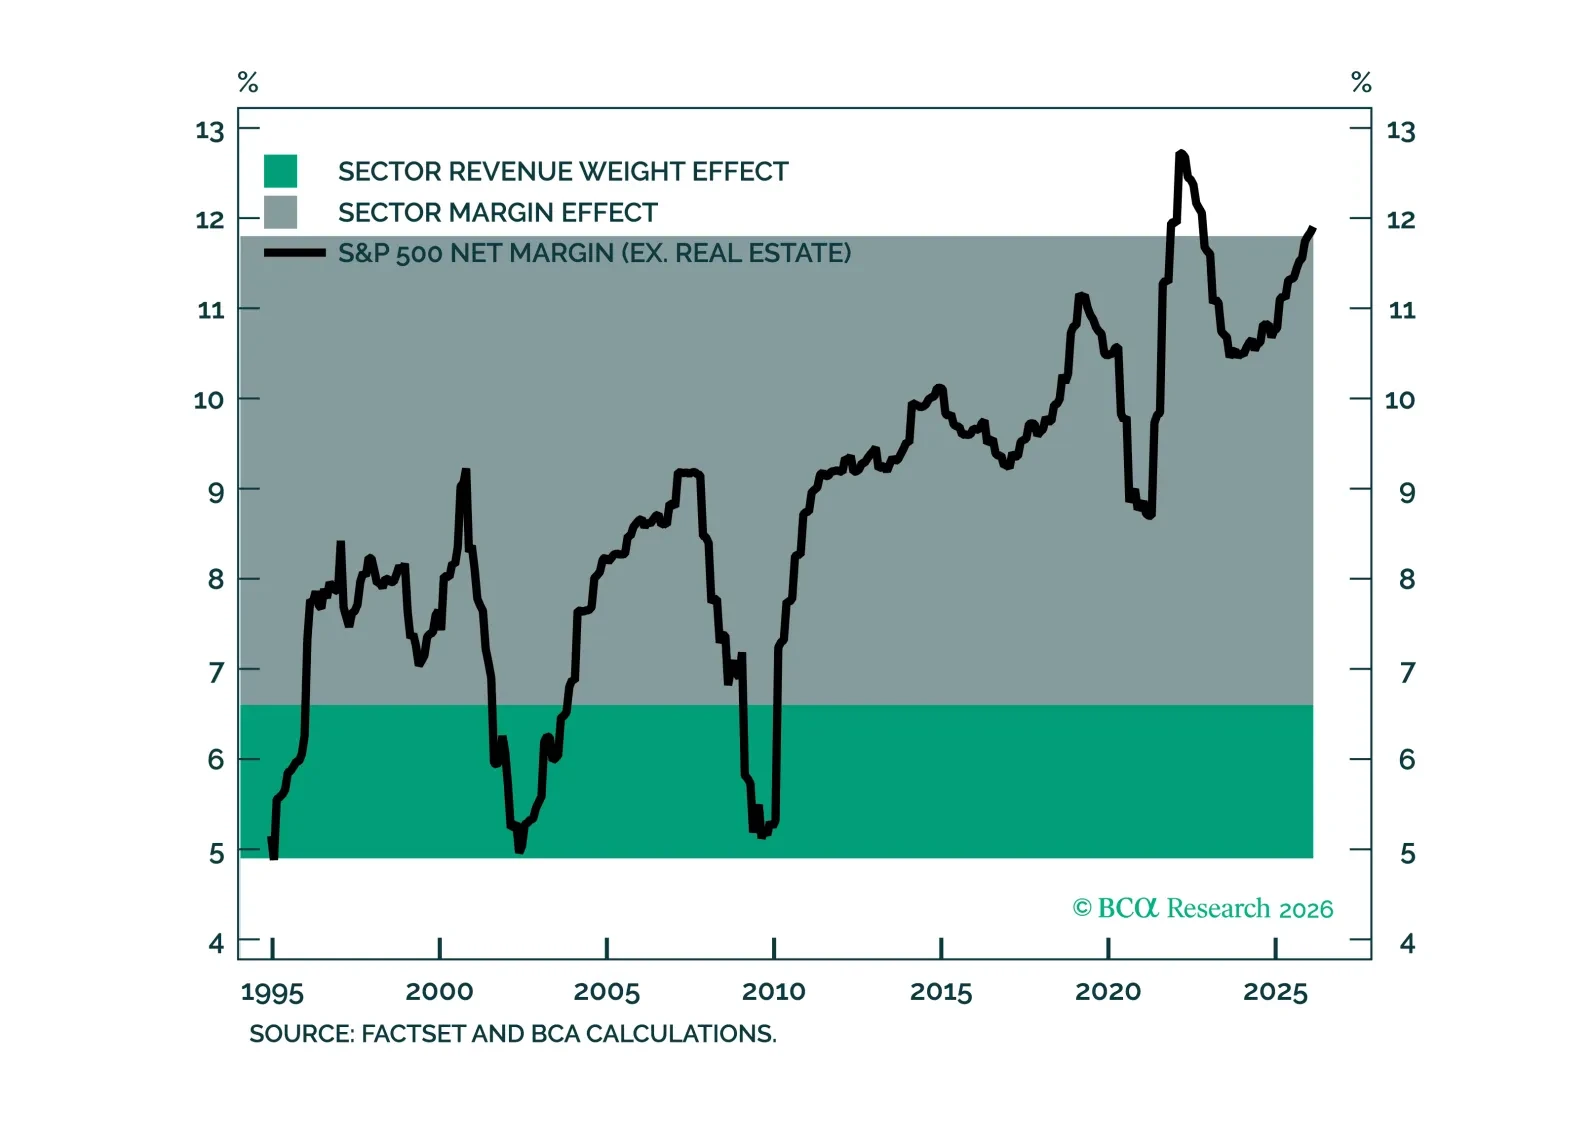
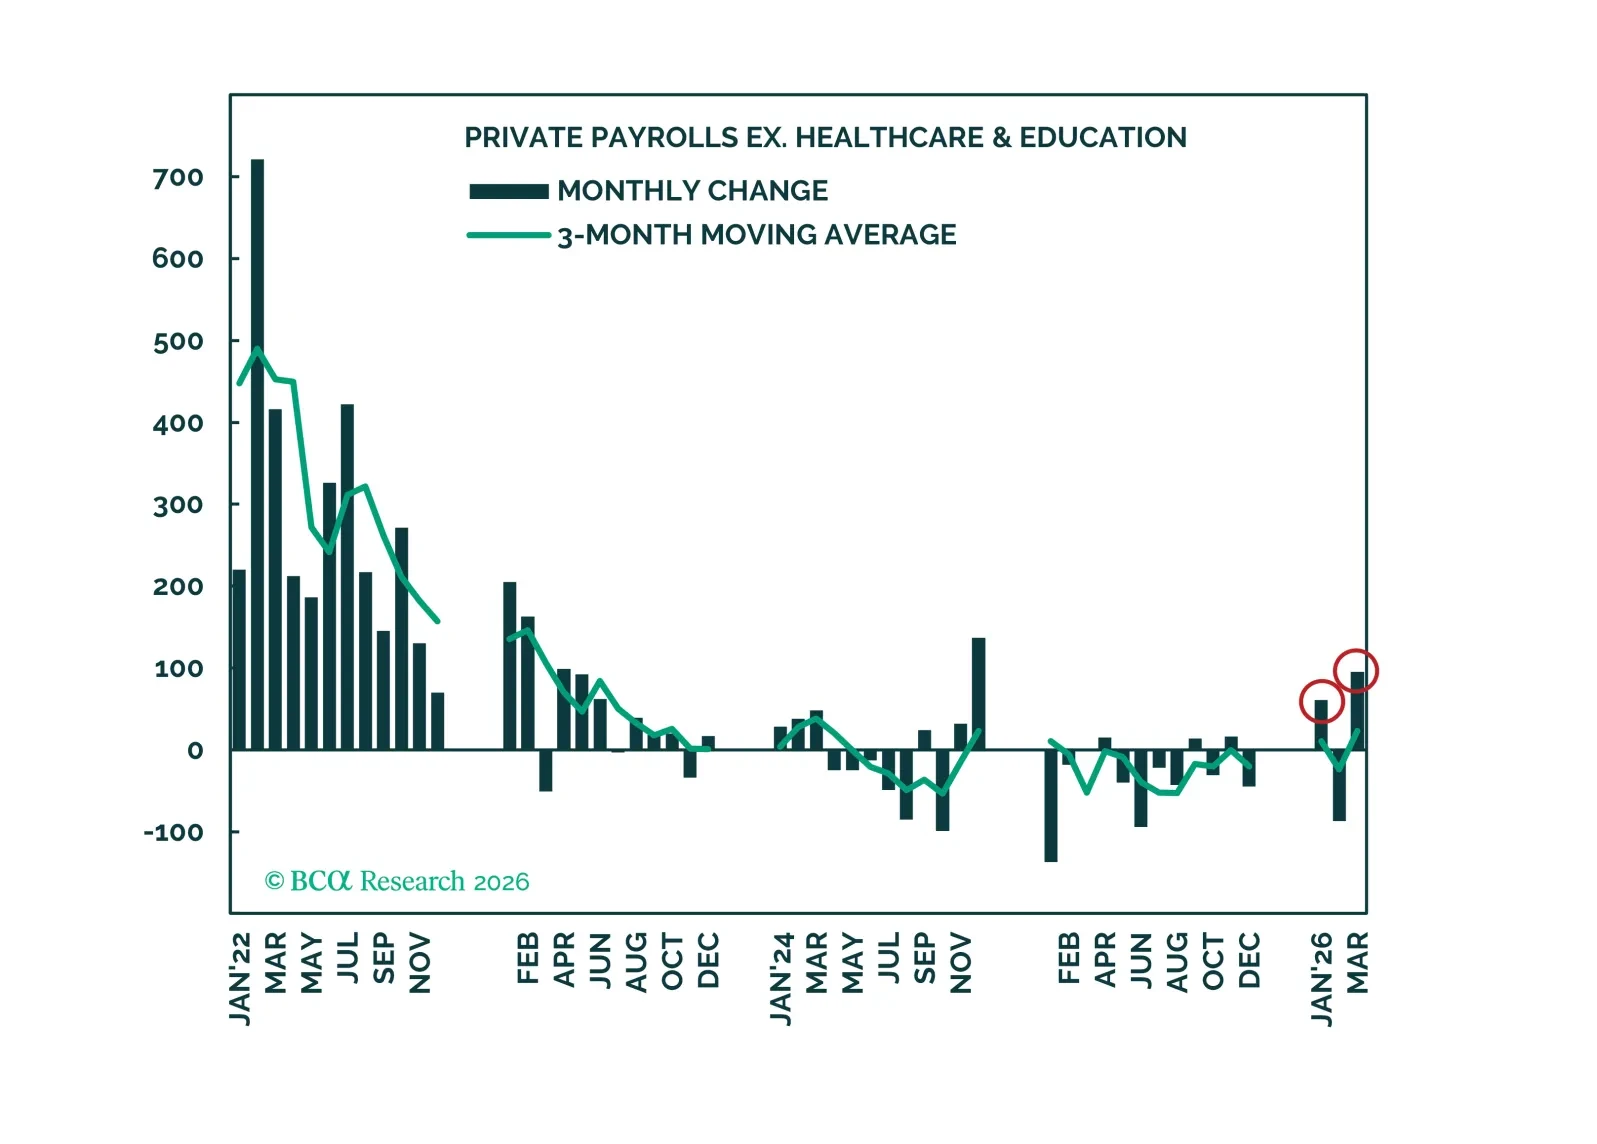
The labor market showed signs of reviving in the first three months of this year, but it is yet to be determined how consumers will react to the energy supply shock. We reiterate our benchmark asset allocation recommendations, but are skeptical that S&P 500 earnings growth will meet outsized expectations over the rest of 2026.