Latest from BCA Research
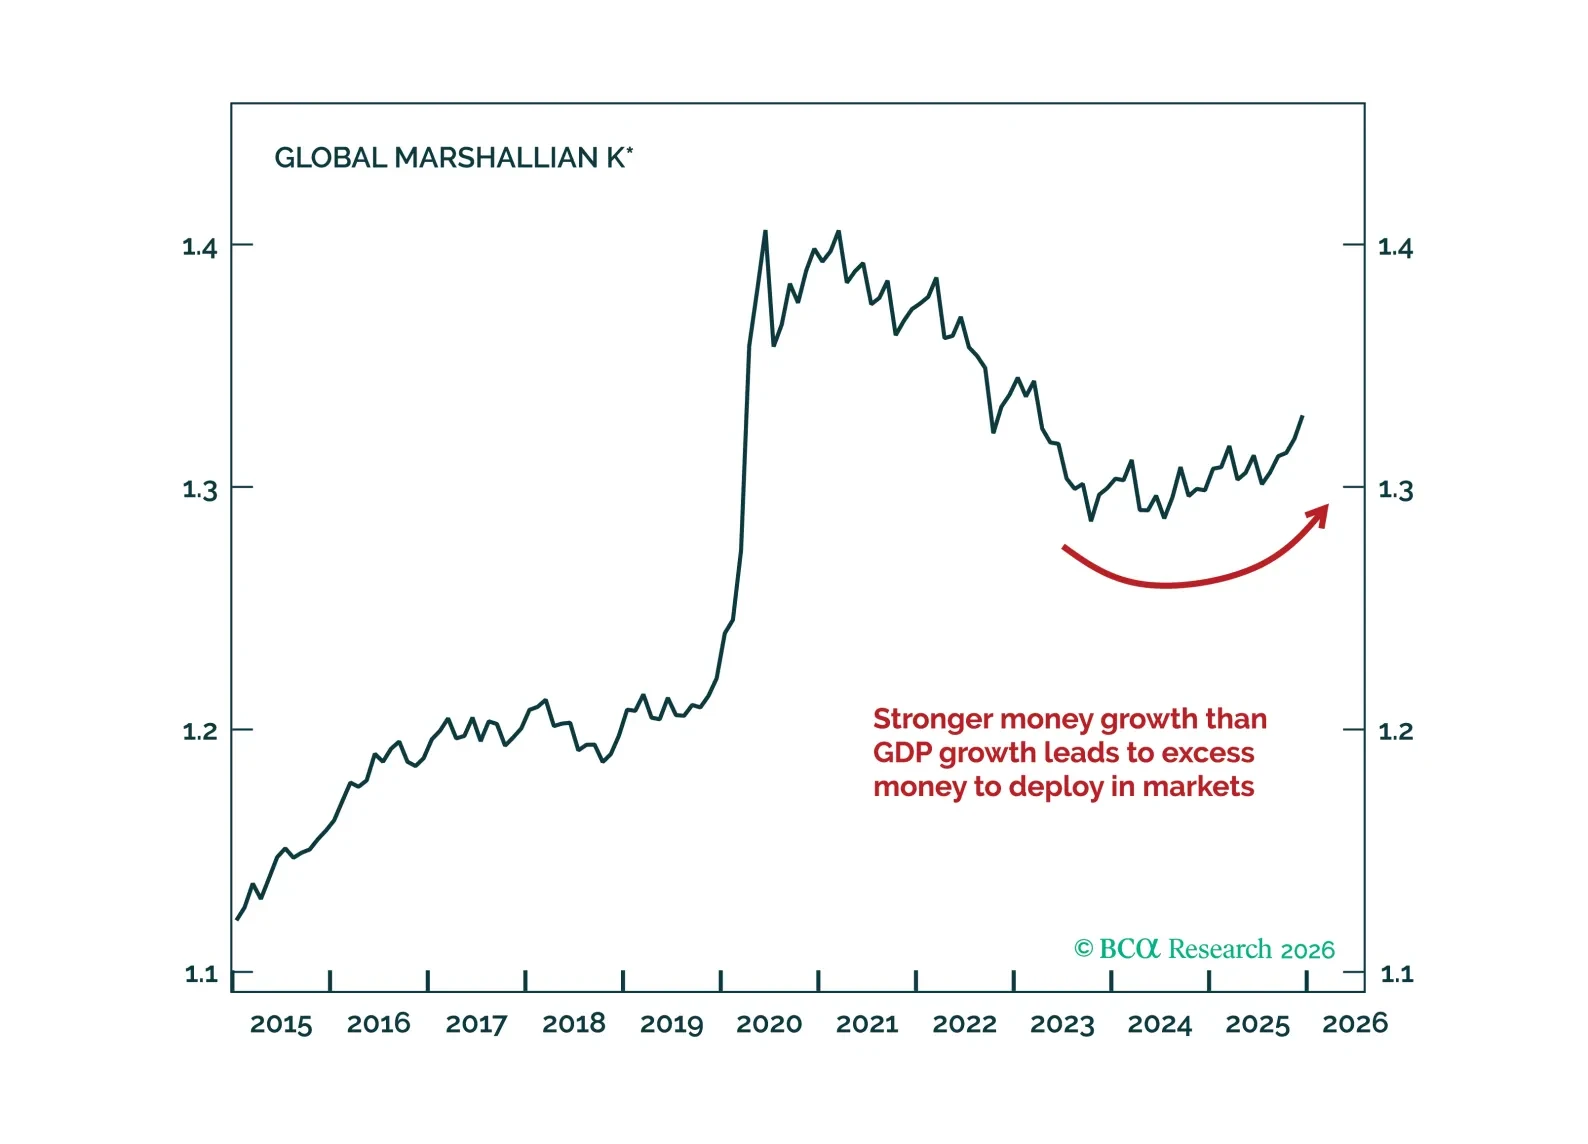
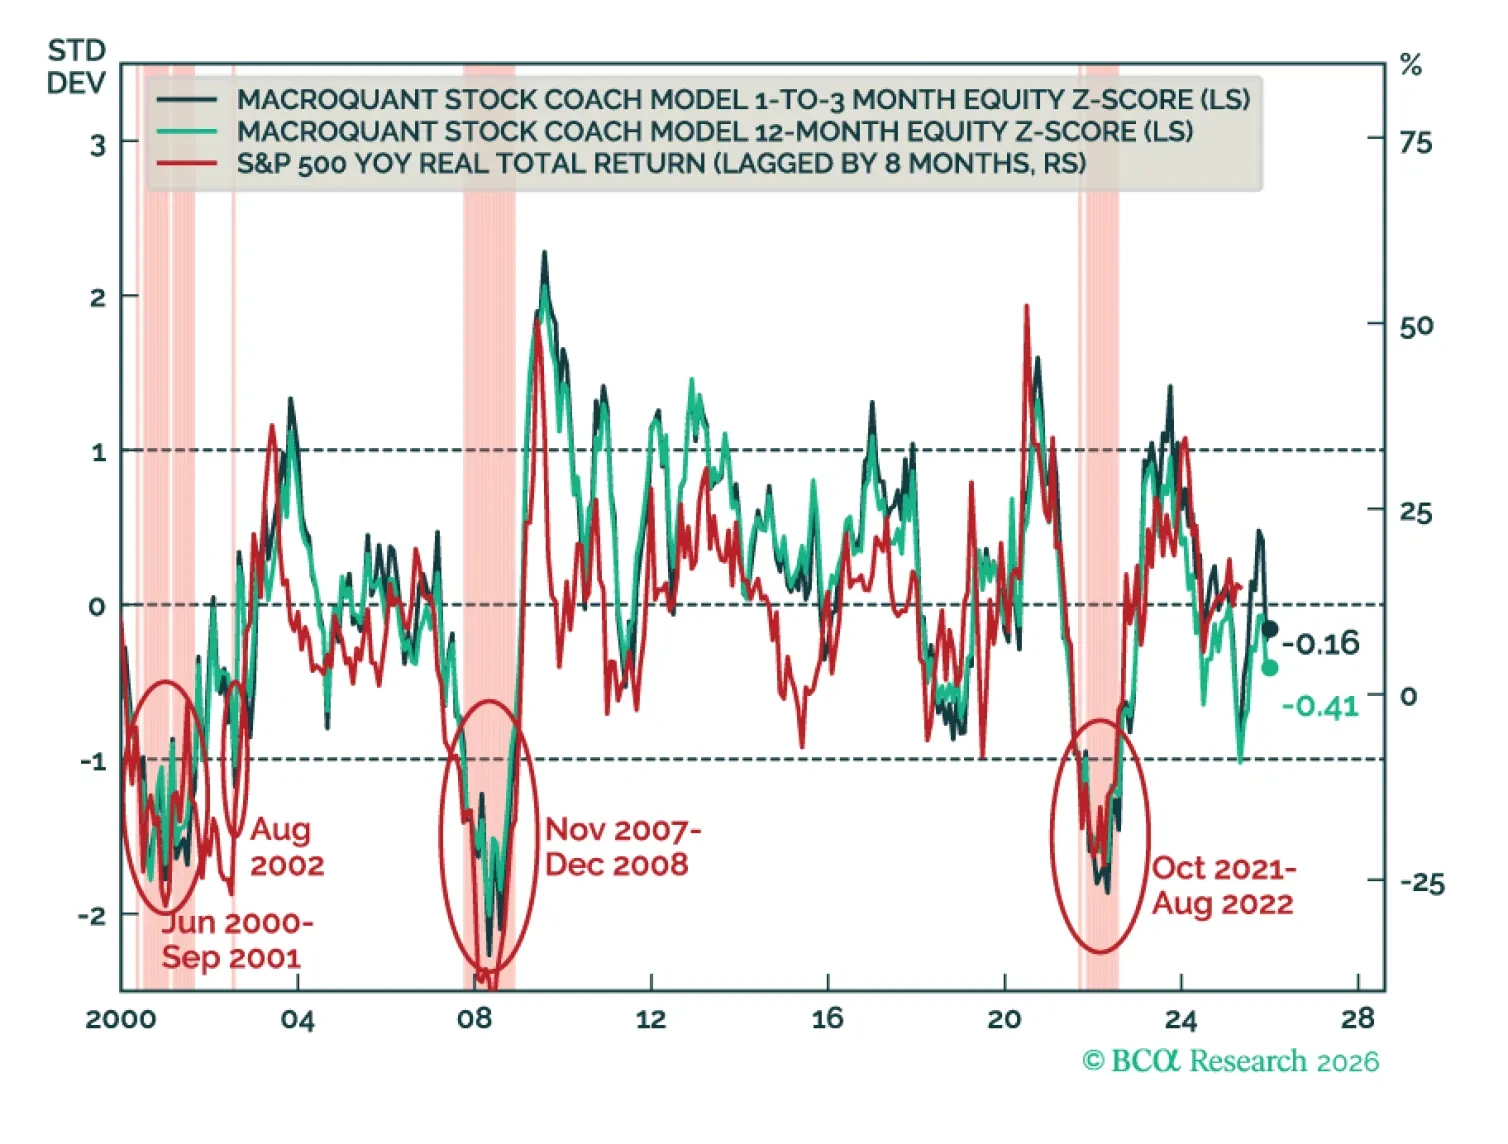
MacroQuant recommends a slight underweight in equities, favors a below-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, has upgraded oil and copper to overweight, and is bullish on gold.
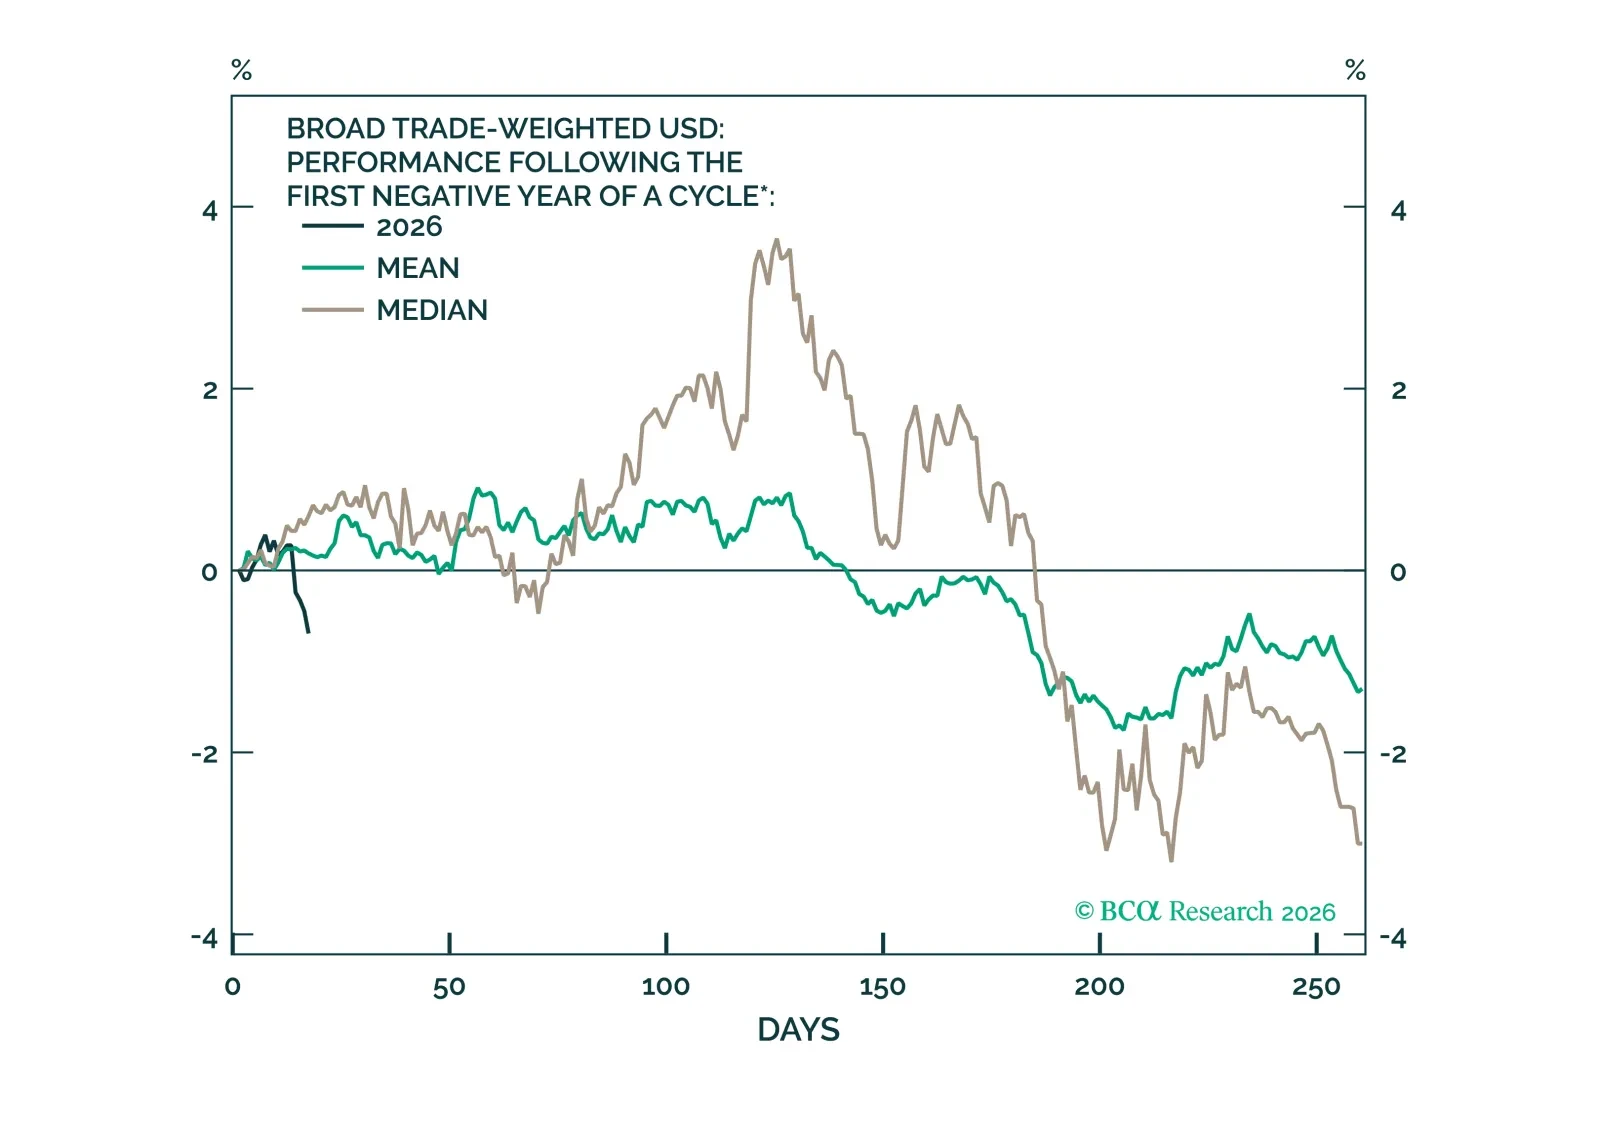
FX markets have dominated headlines over the past week, with a meltdown in the dollar and a surge in the yen. This week’s note unpacks the forces behind these moves and assesses whether recent price action marks a temporary dislocation or the start of a more durable FX shift.
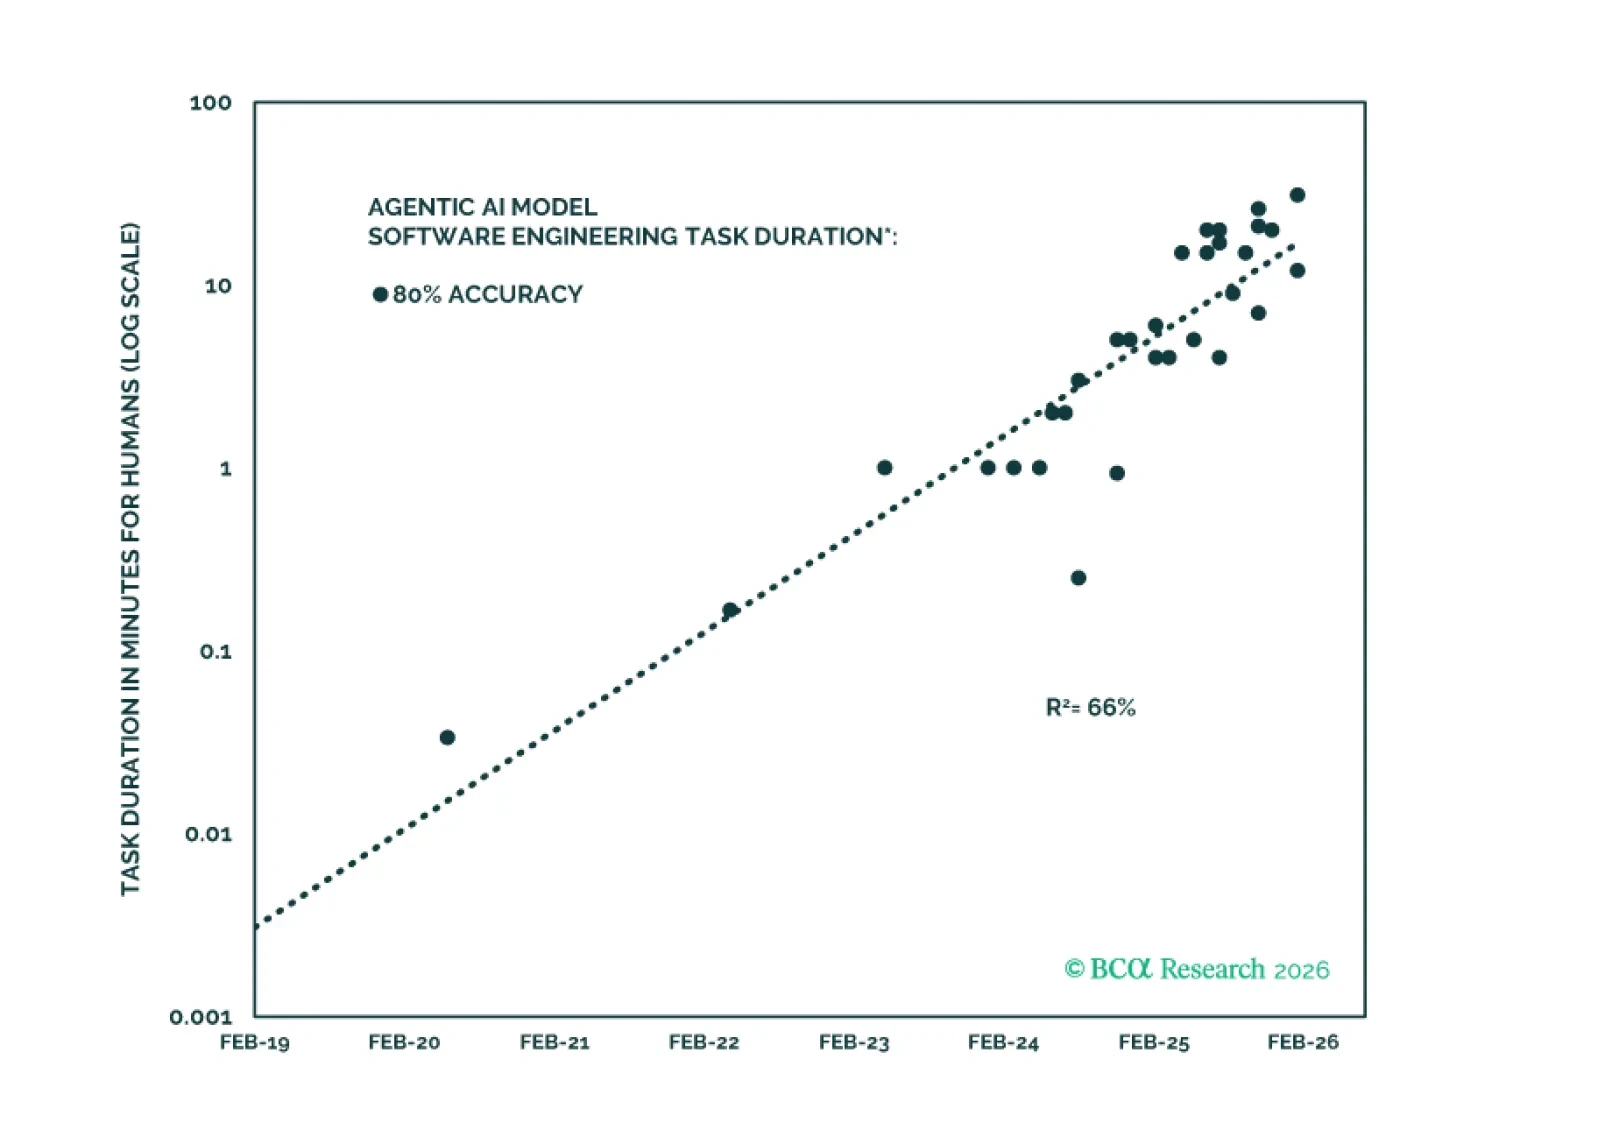
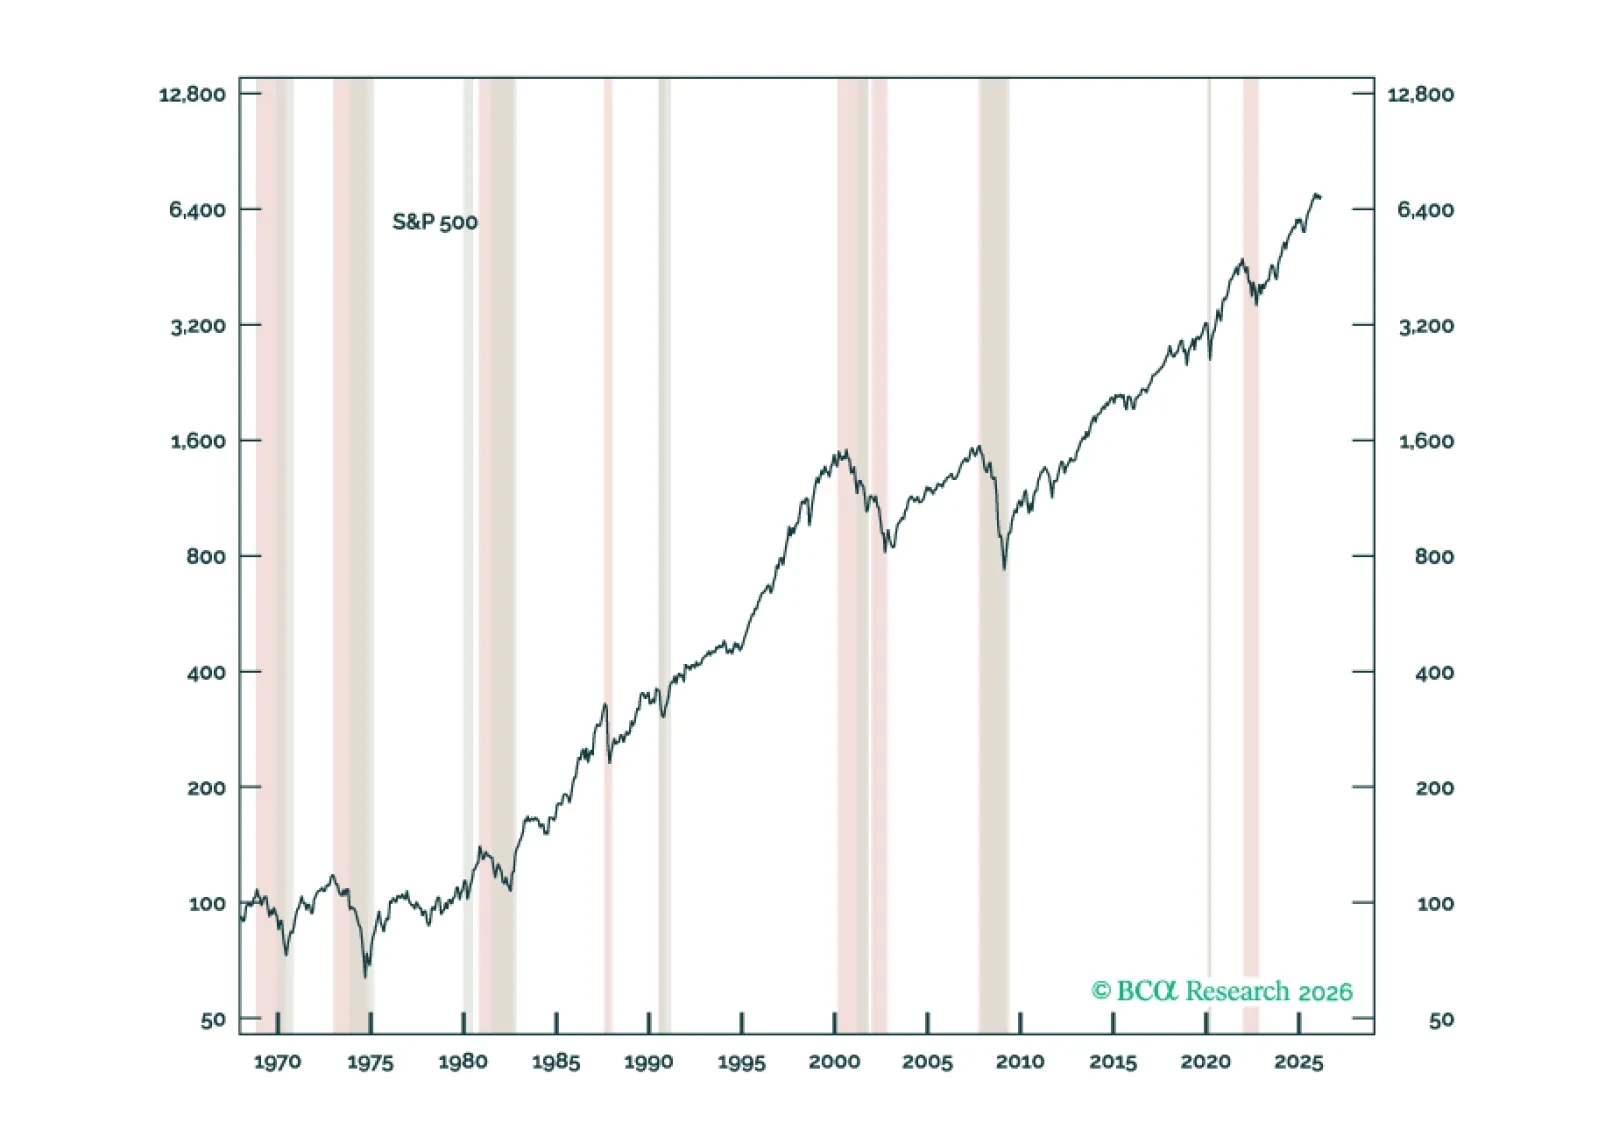
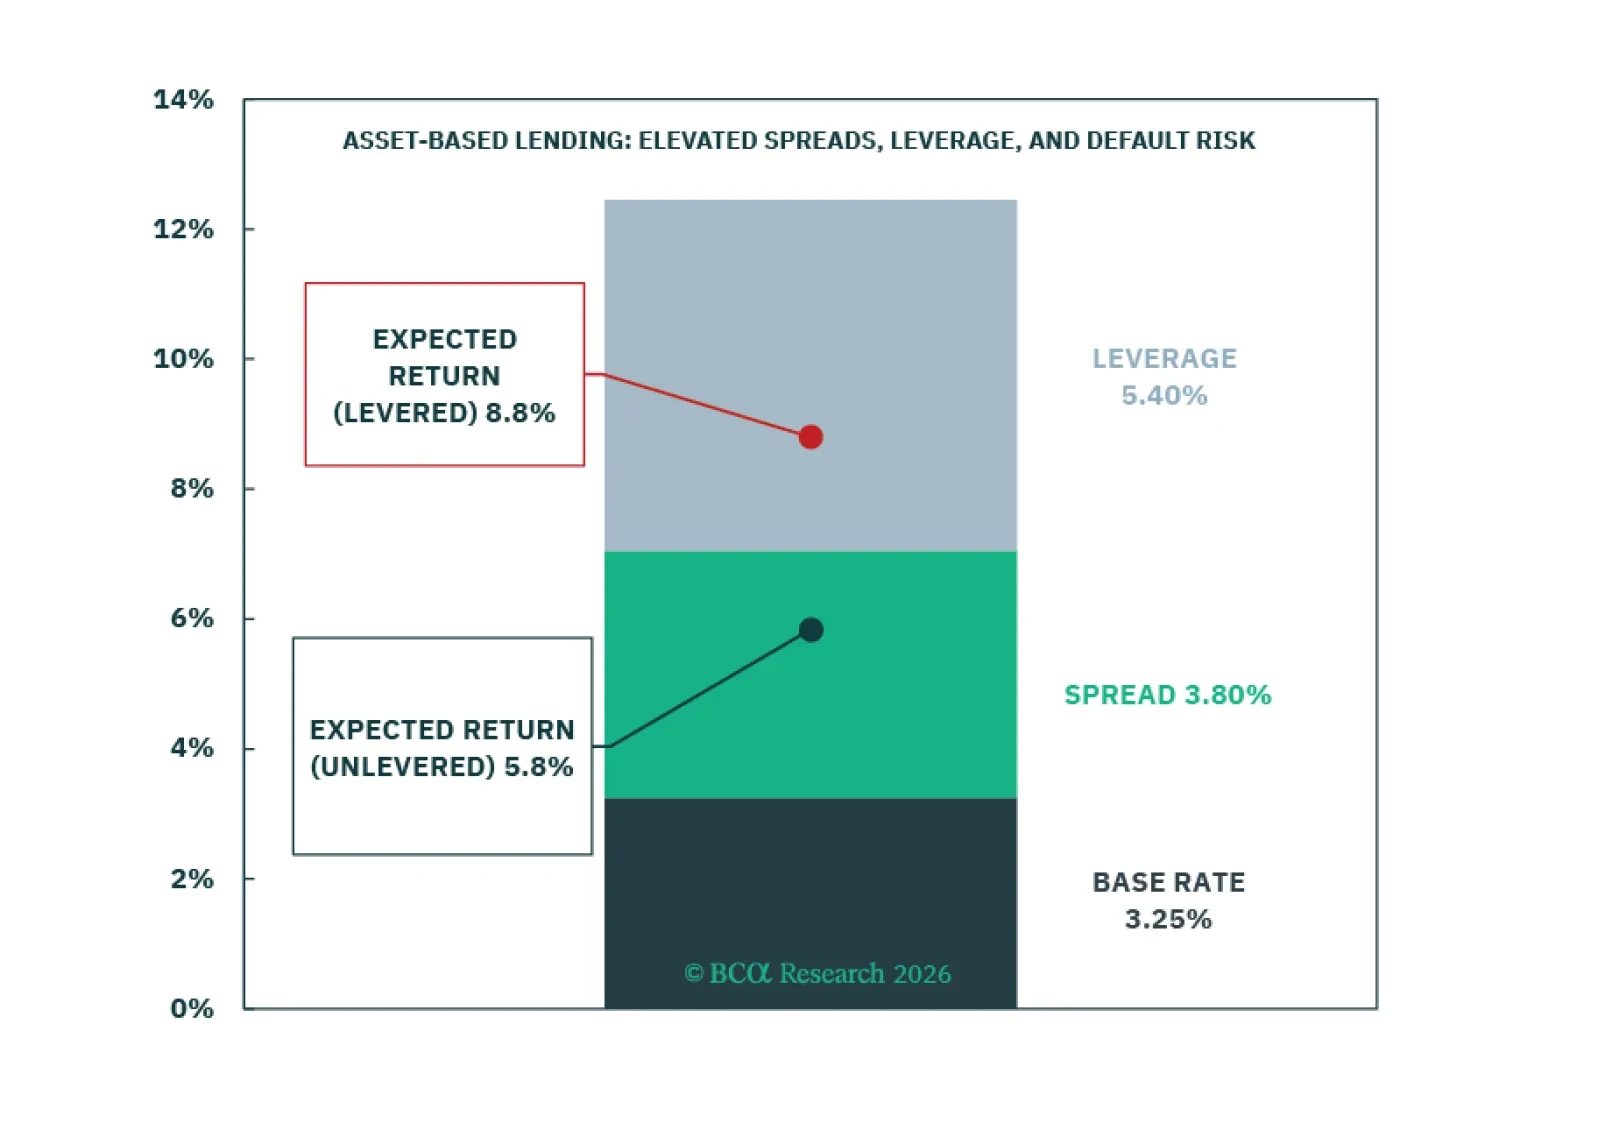
Our new Private Credit taxonomy adds granularity to the opaque lending universe and introduces Asset-Based Lending—attractive entry points, elevated risks. Private Real Estate delivers the largest upgrades from 2025, while Public REITs and Public Infrastructure present compelling opportunities that investors should not overlook.
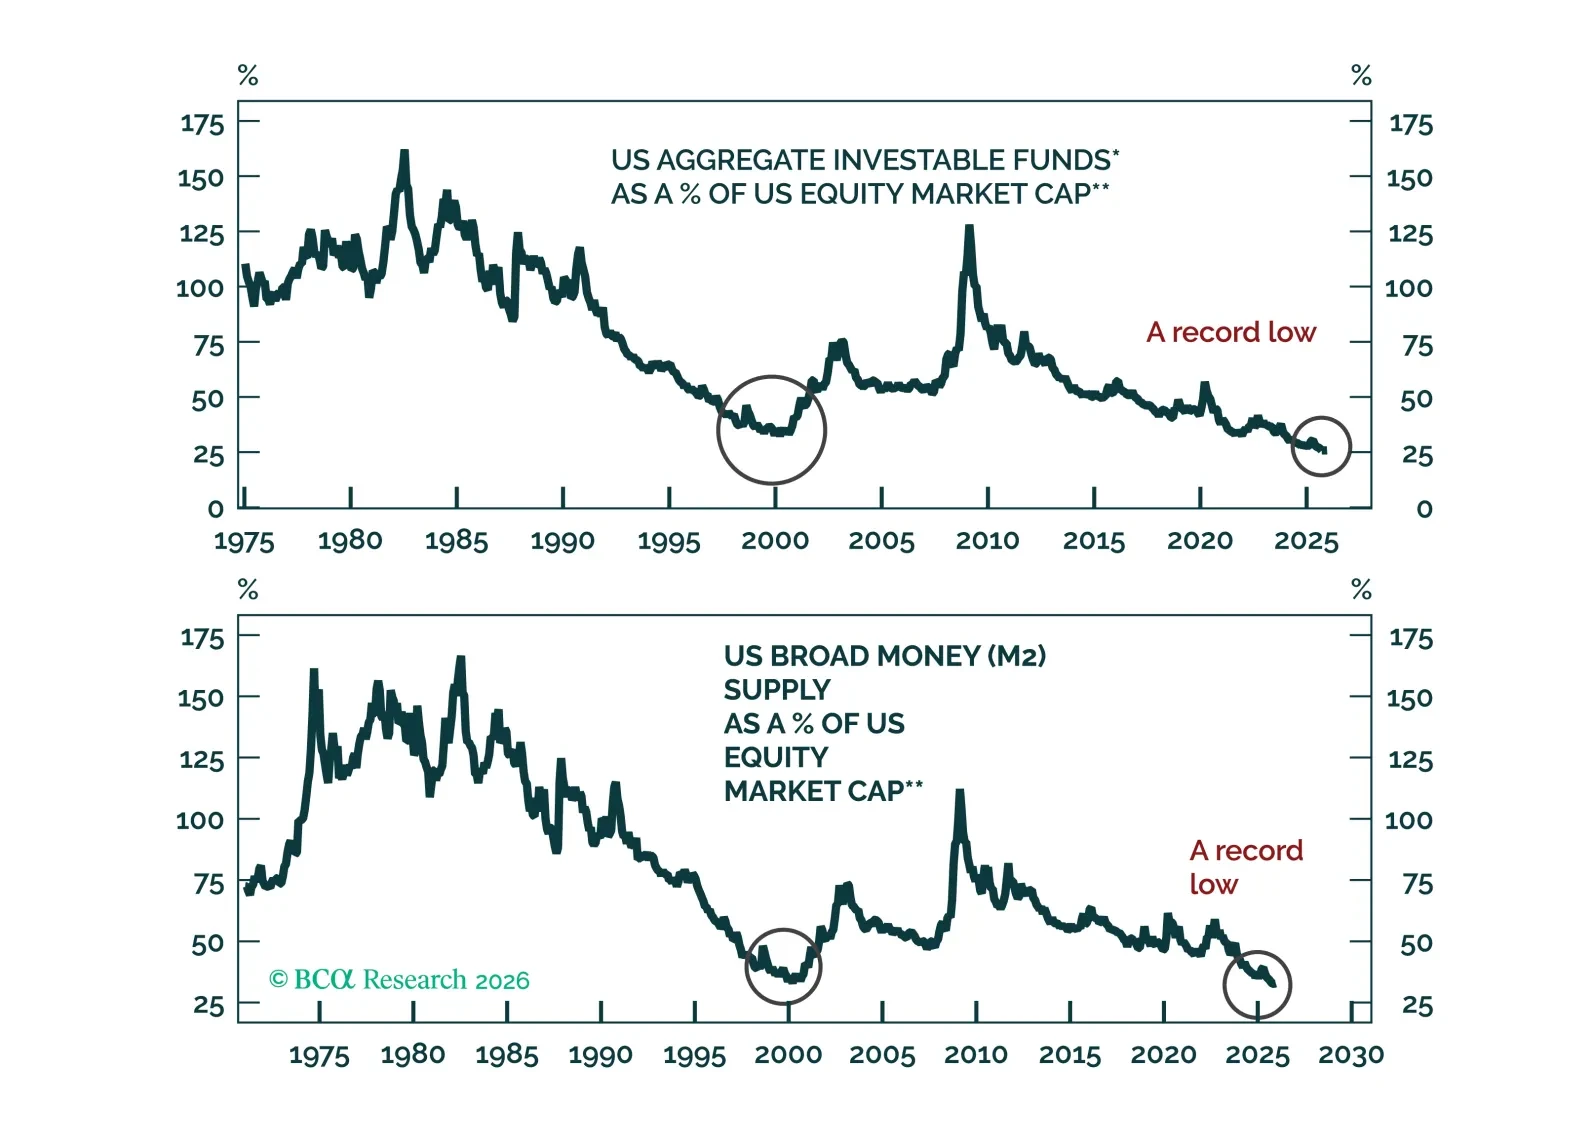
Contrary to widespread narratives, there is little cash on the sidelines. The aggregate amount of investable funds-to-equity market cap ratio is at an all-time low in the US and very low in other developed markets.
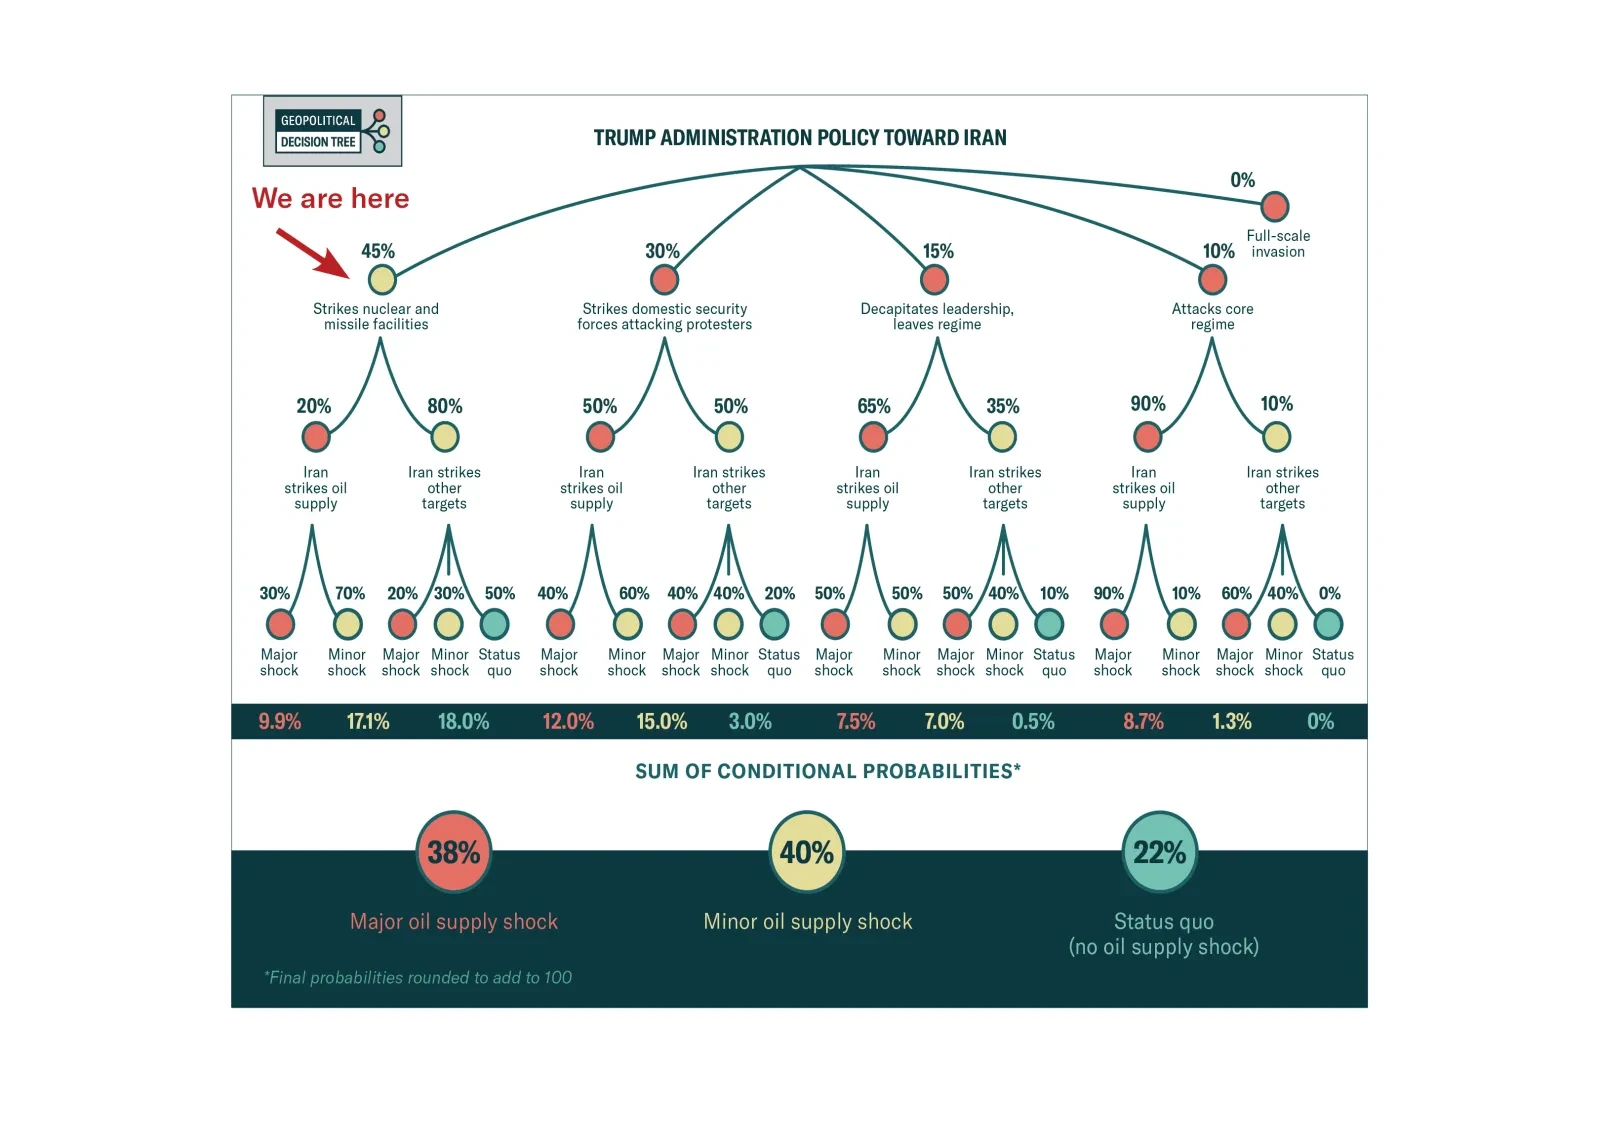
The US is likely to take significant military action in Iran, justifying our 40% risk of a major oil shock. Tactically go long Brent crude.
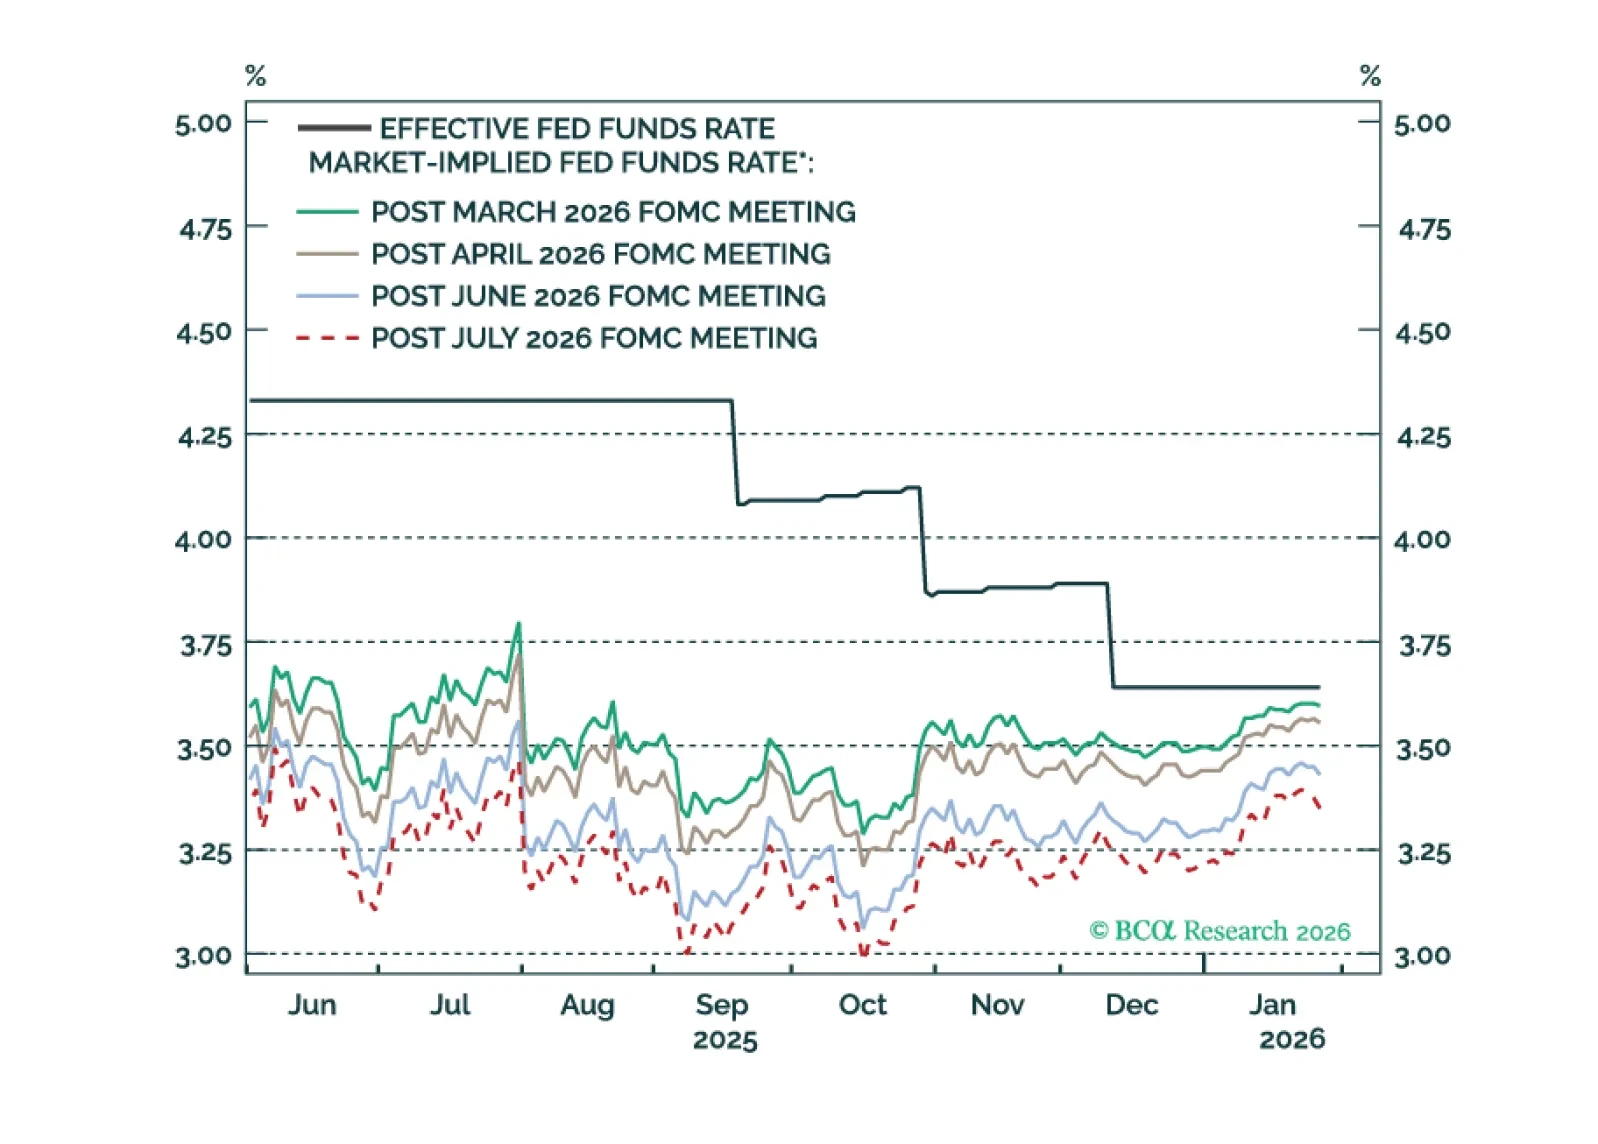
The Fed will keep rates on hold in H1 2026, but dovish policy surprises are likely in the second half of the year.
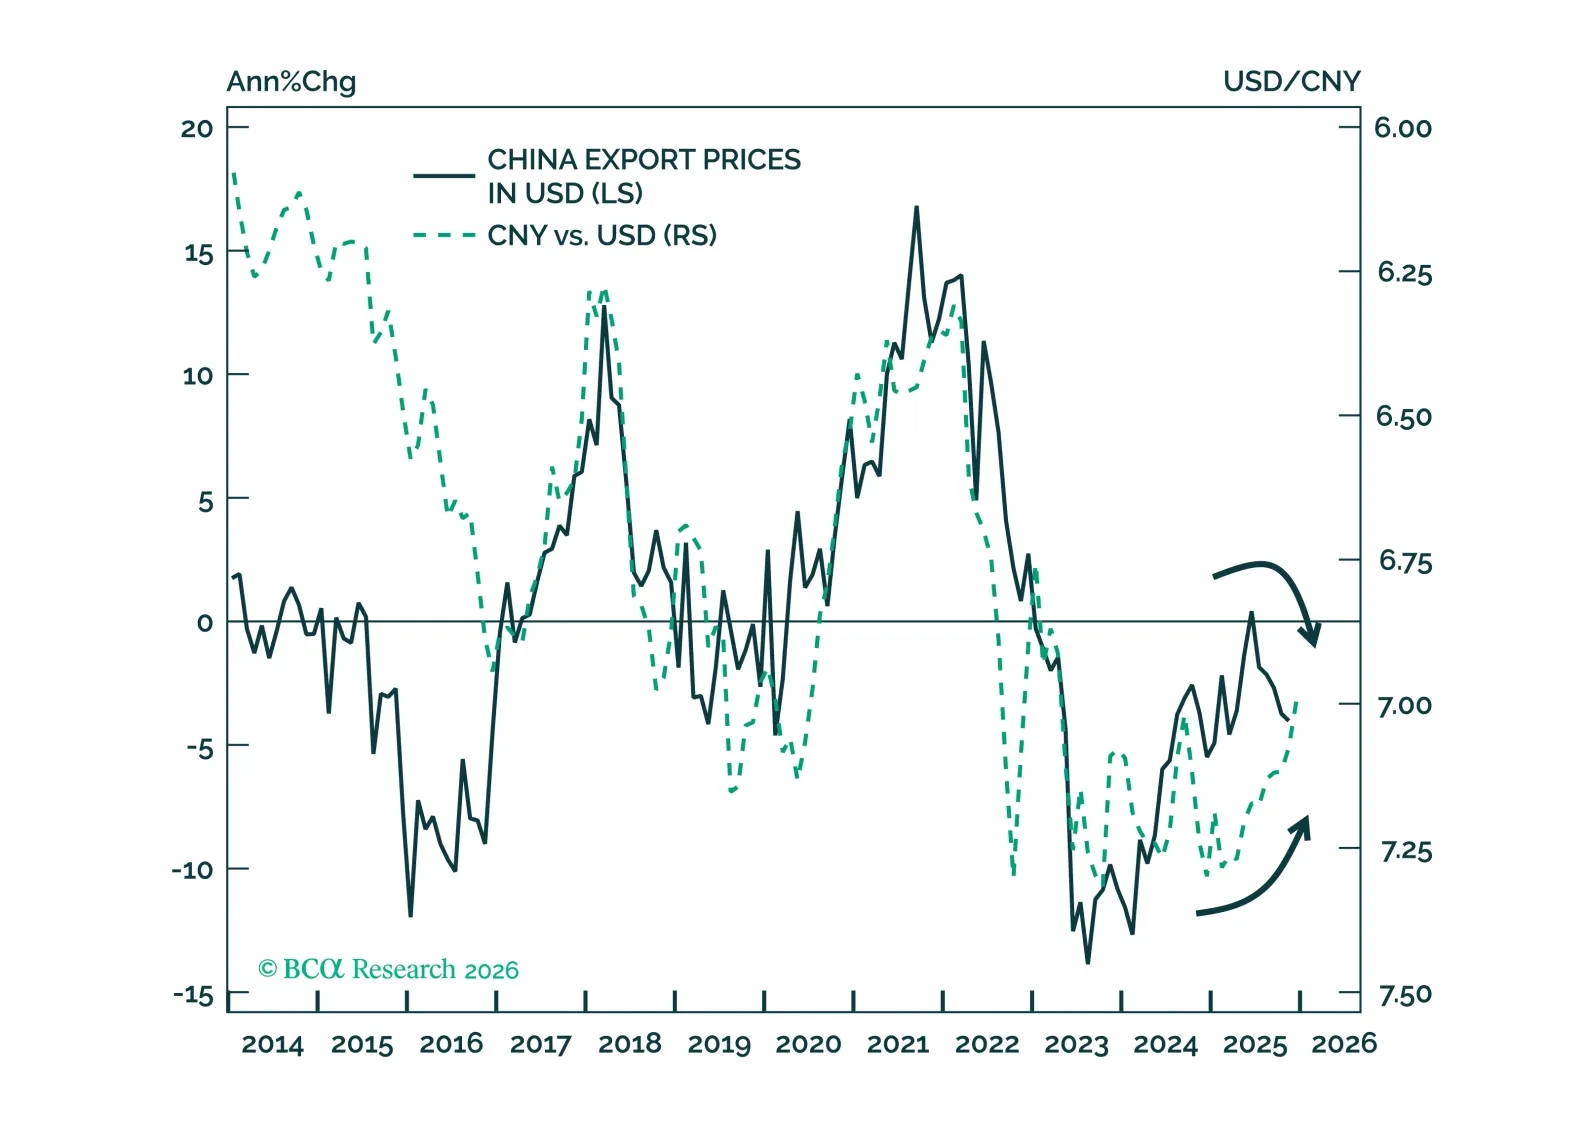
Our first release of the China High-Frequency Indicators for 2026 suggests that economic growth will continue to decelerate in Q1, leading us to adopt a tactically cautious stance on Chinese equities.