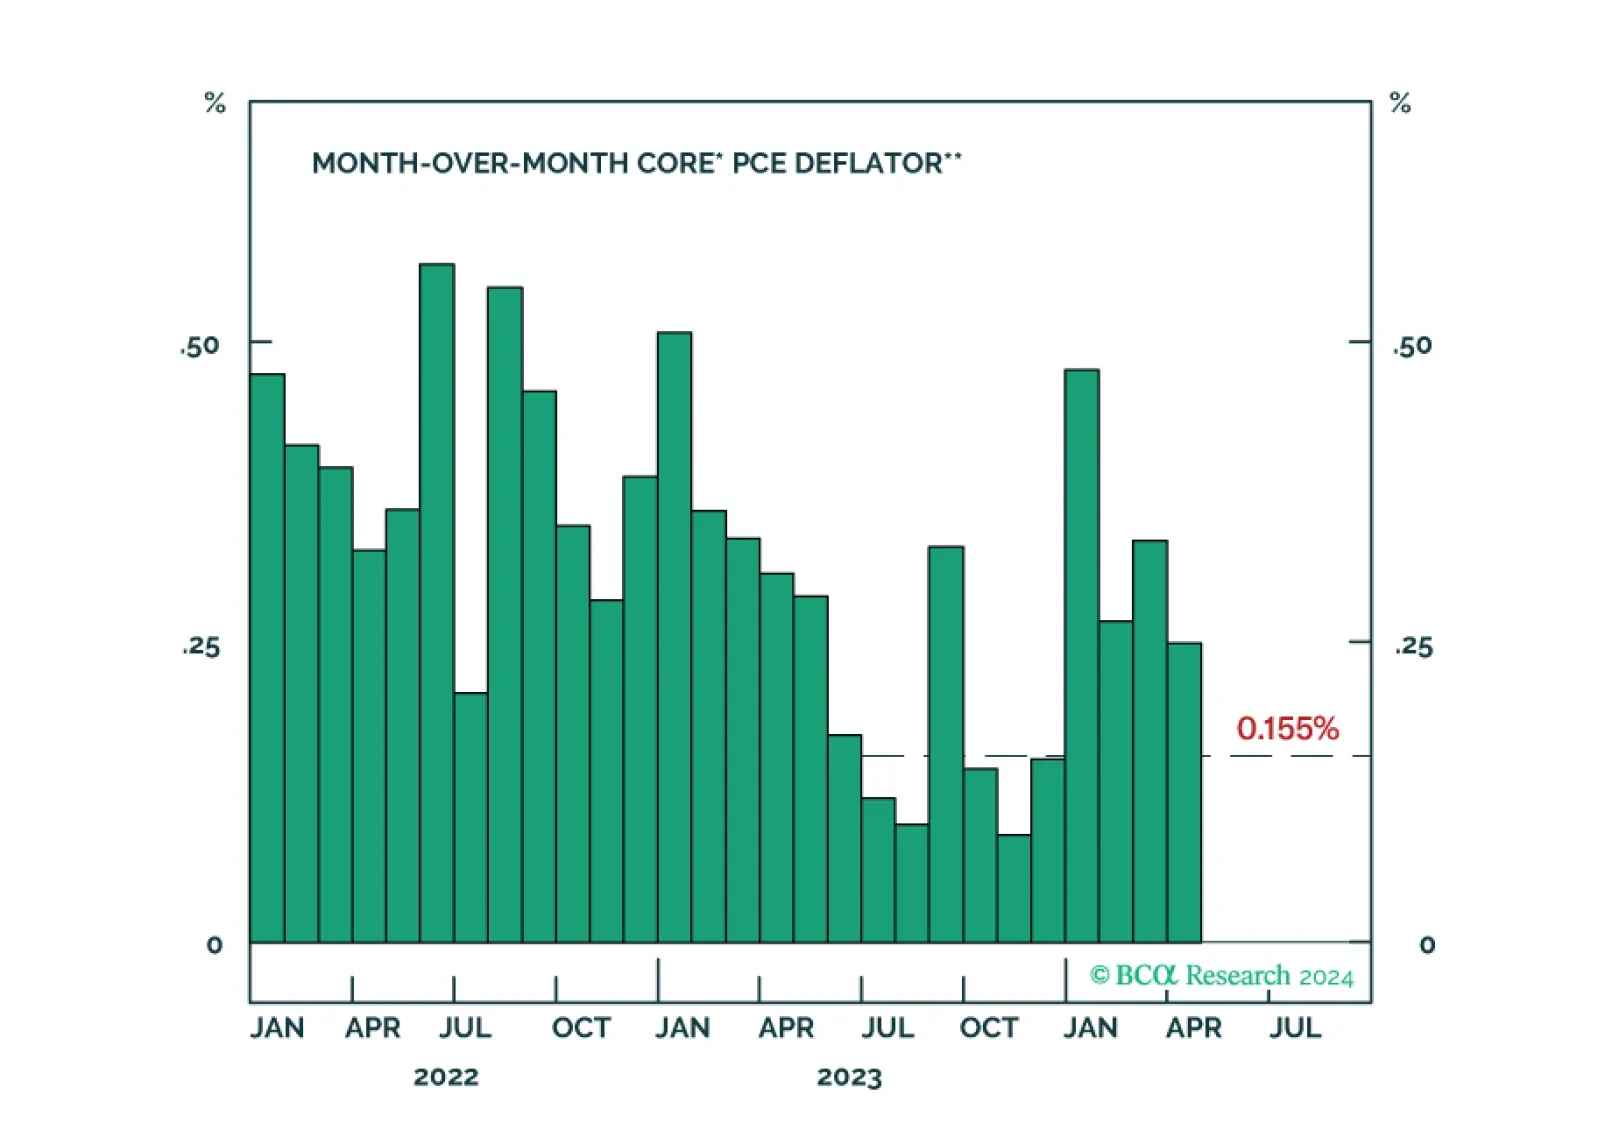
High-Yield
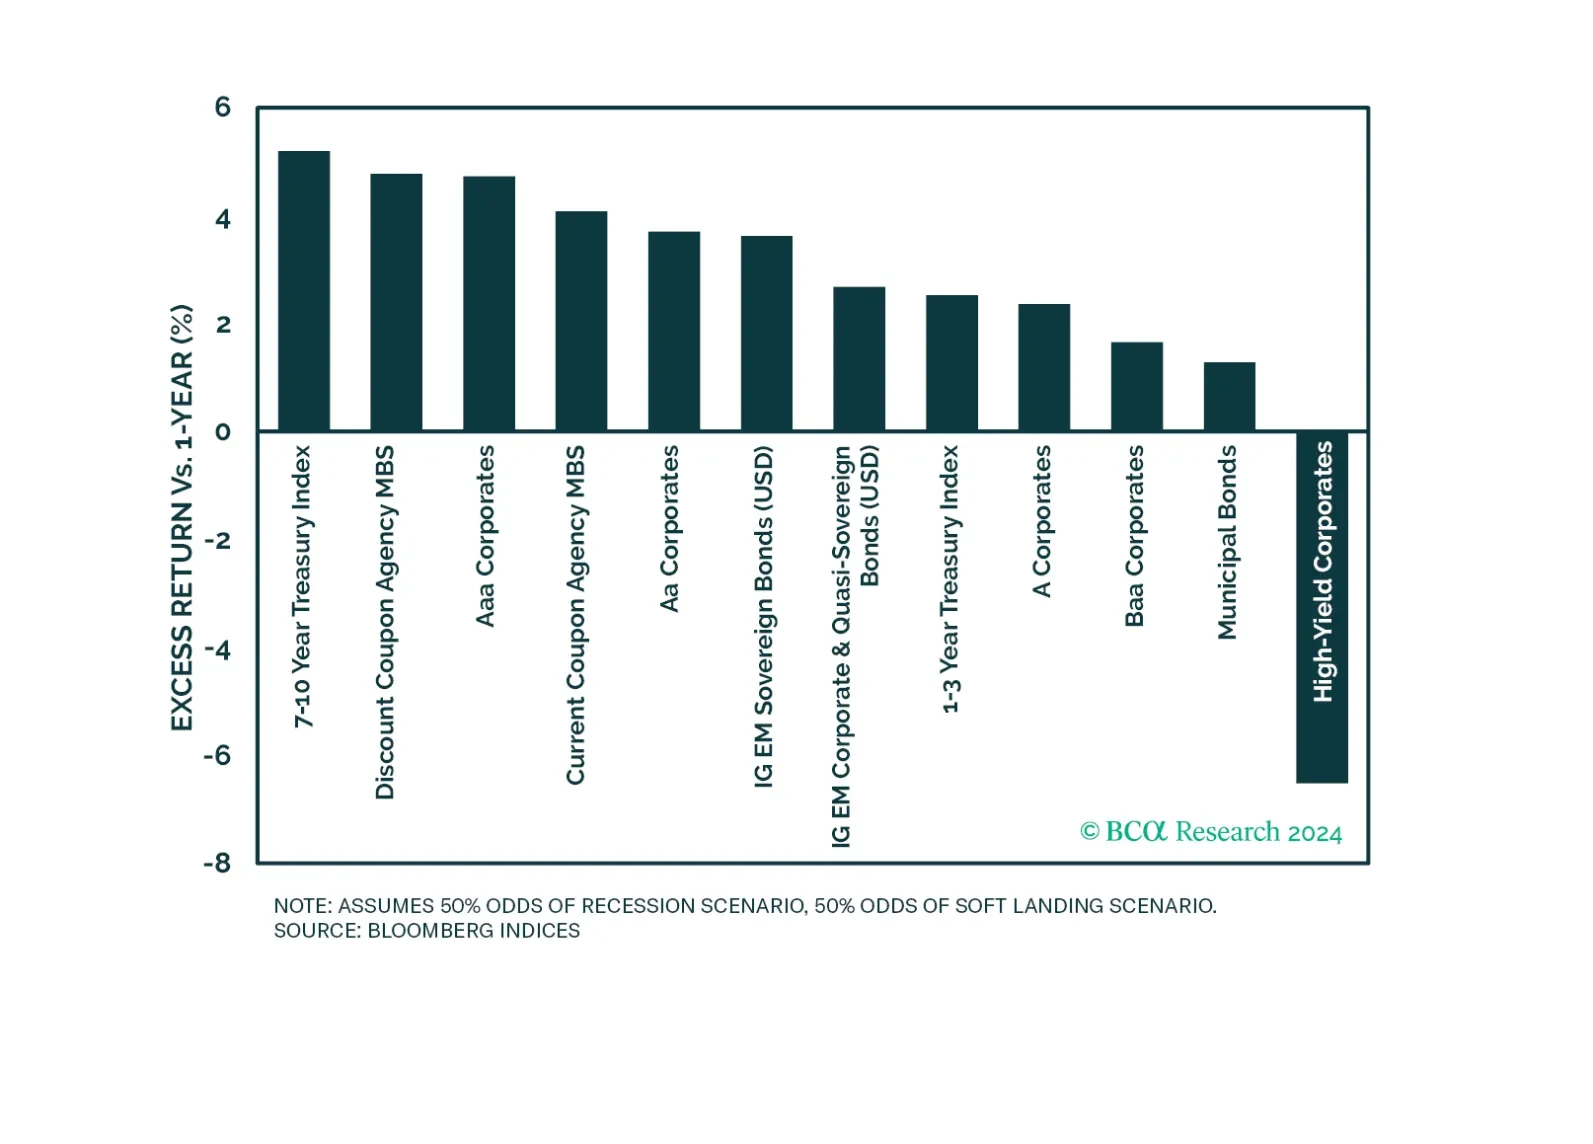
We update our 12-month return projections for different US fixed income sectors in soft-landing and recession scenarios.
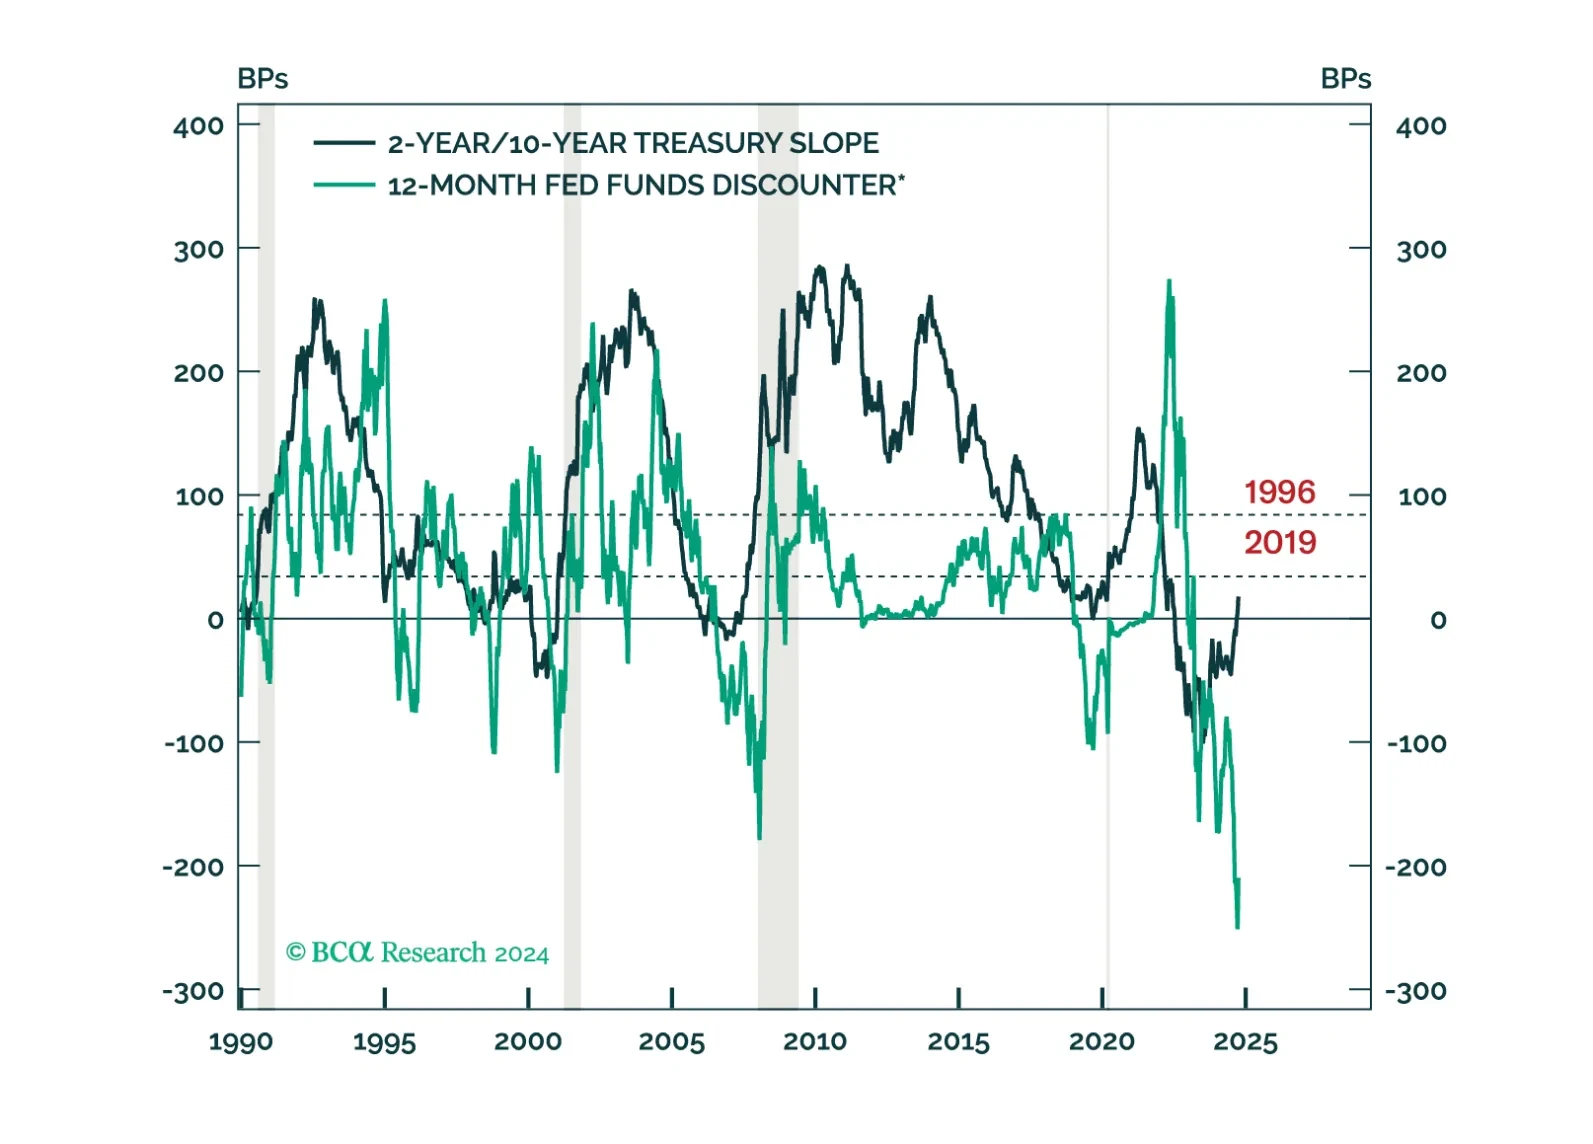
Our Portfolio Allocation Summary for October 2024.
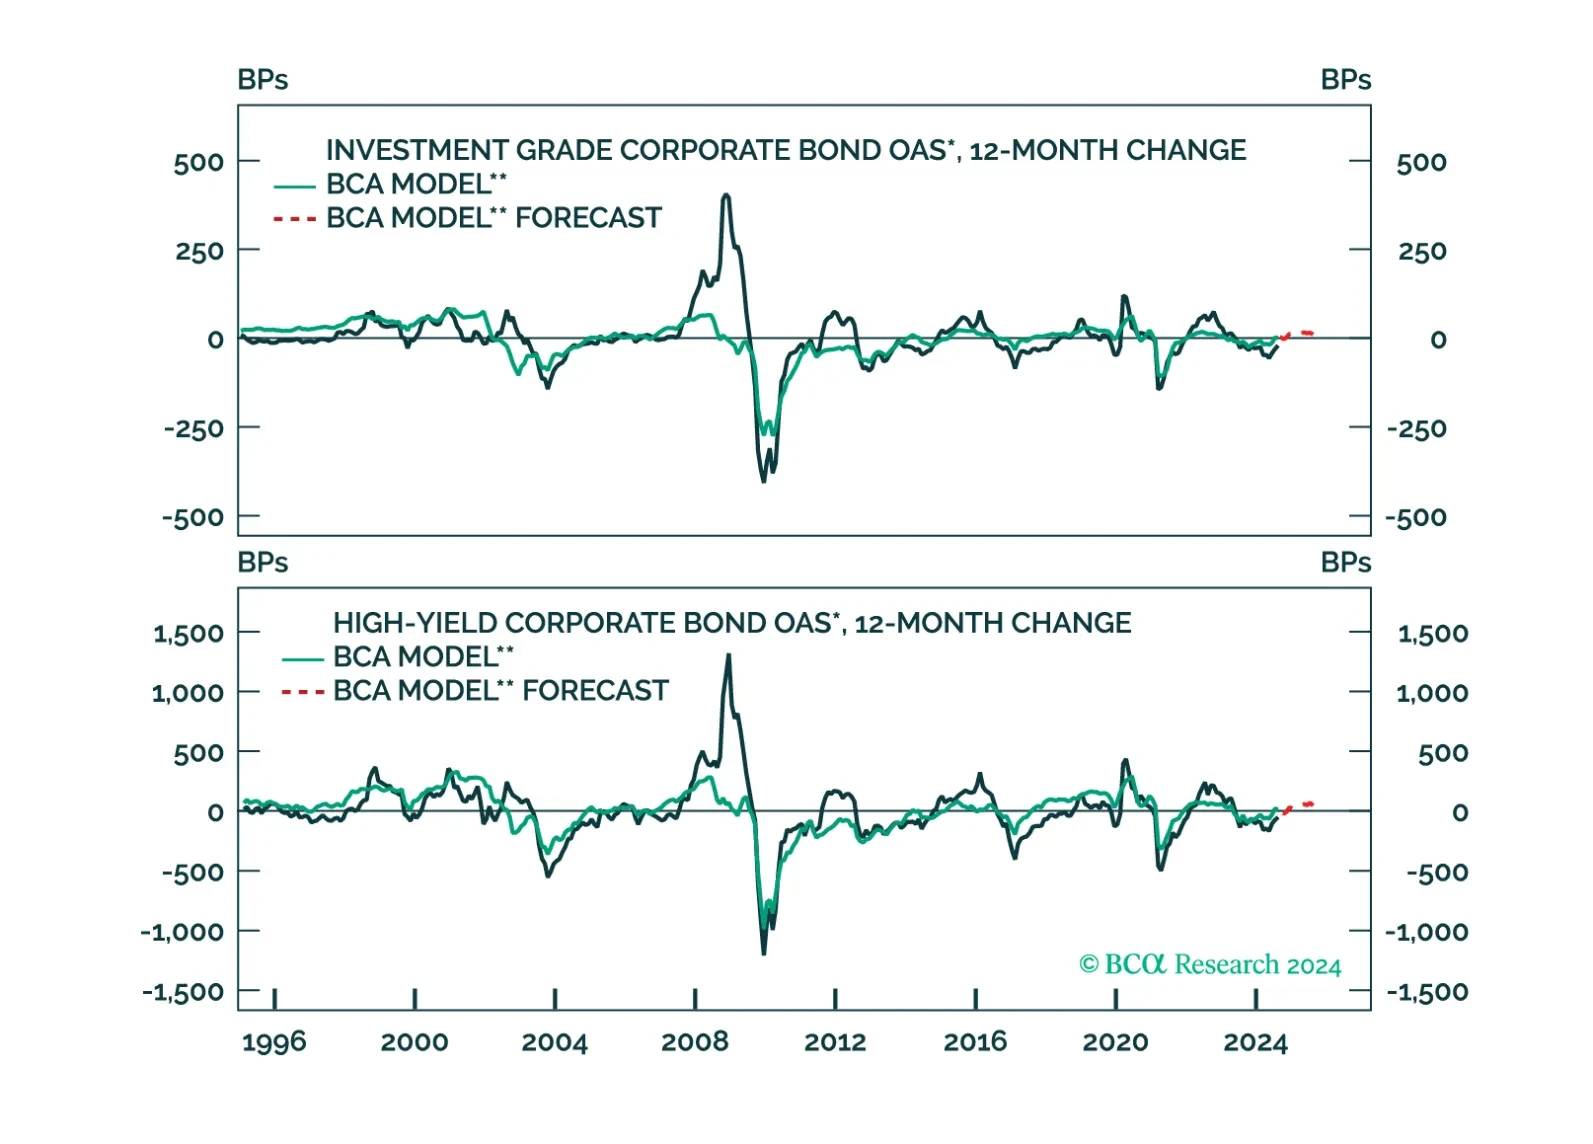
We update our corporate default rate model and consider the implications for corporate bond spreads.

The pro-cyclical Eurozone economy is highly exposed to a global downturn, which we expect will materialize by early 2025. The ECB is behind the curve and we thus expect it to ease more aggressively than markets expect next year. A dovish surprise in 2025 is…
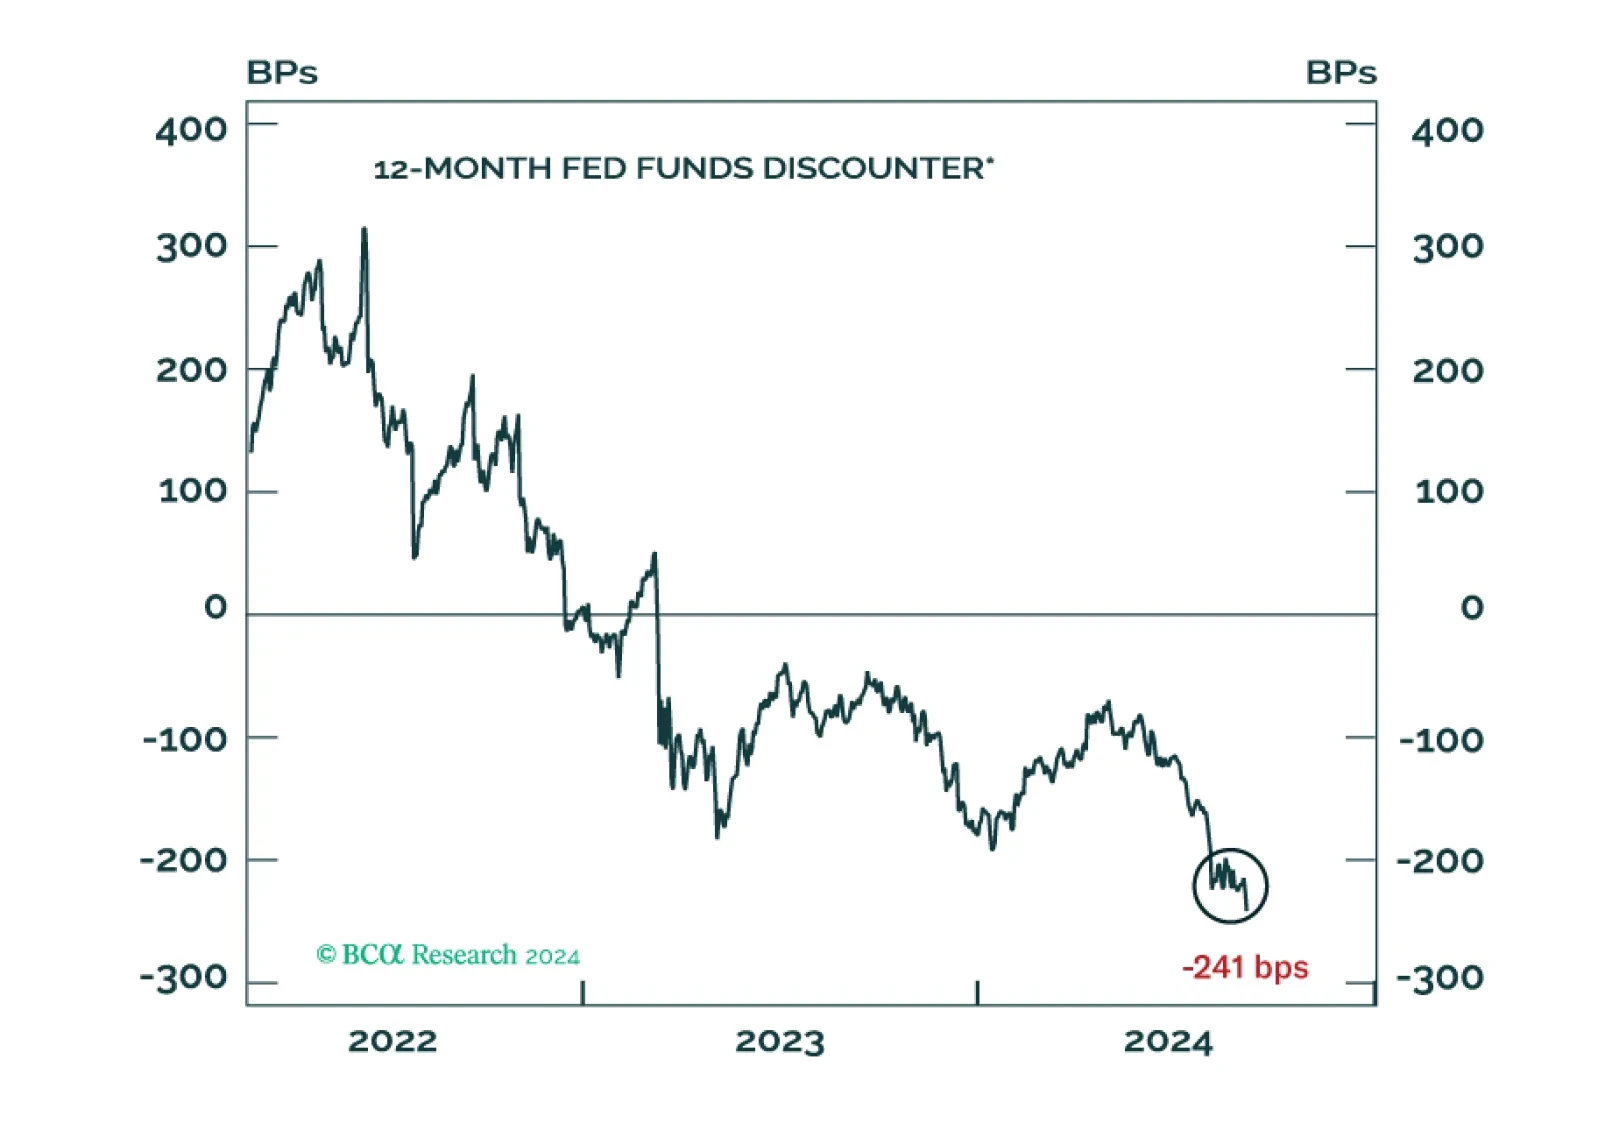
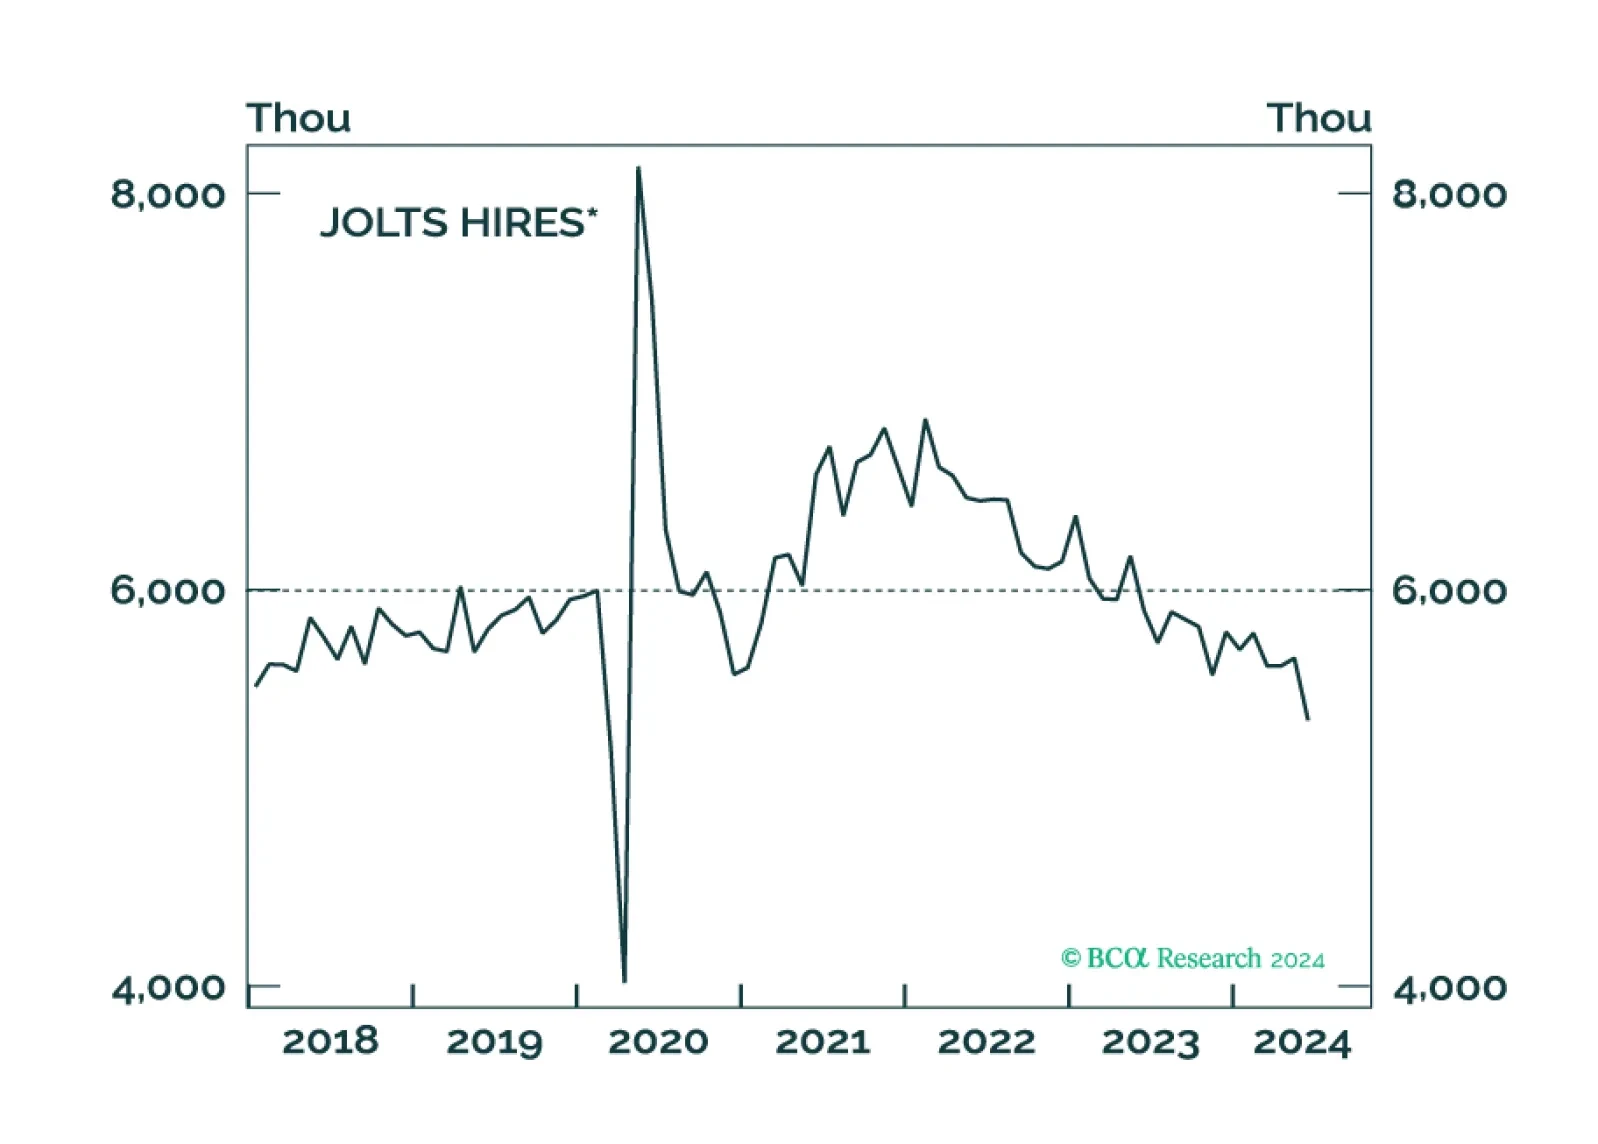
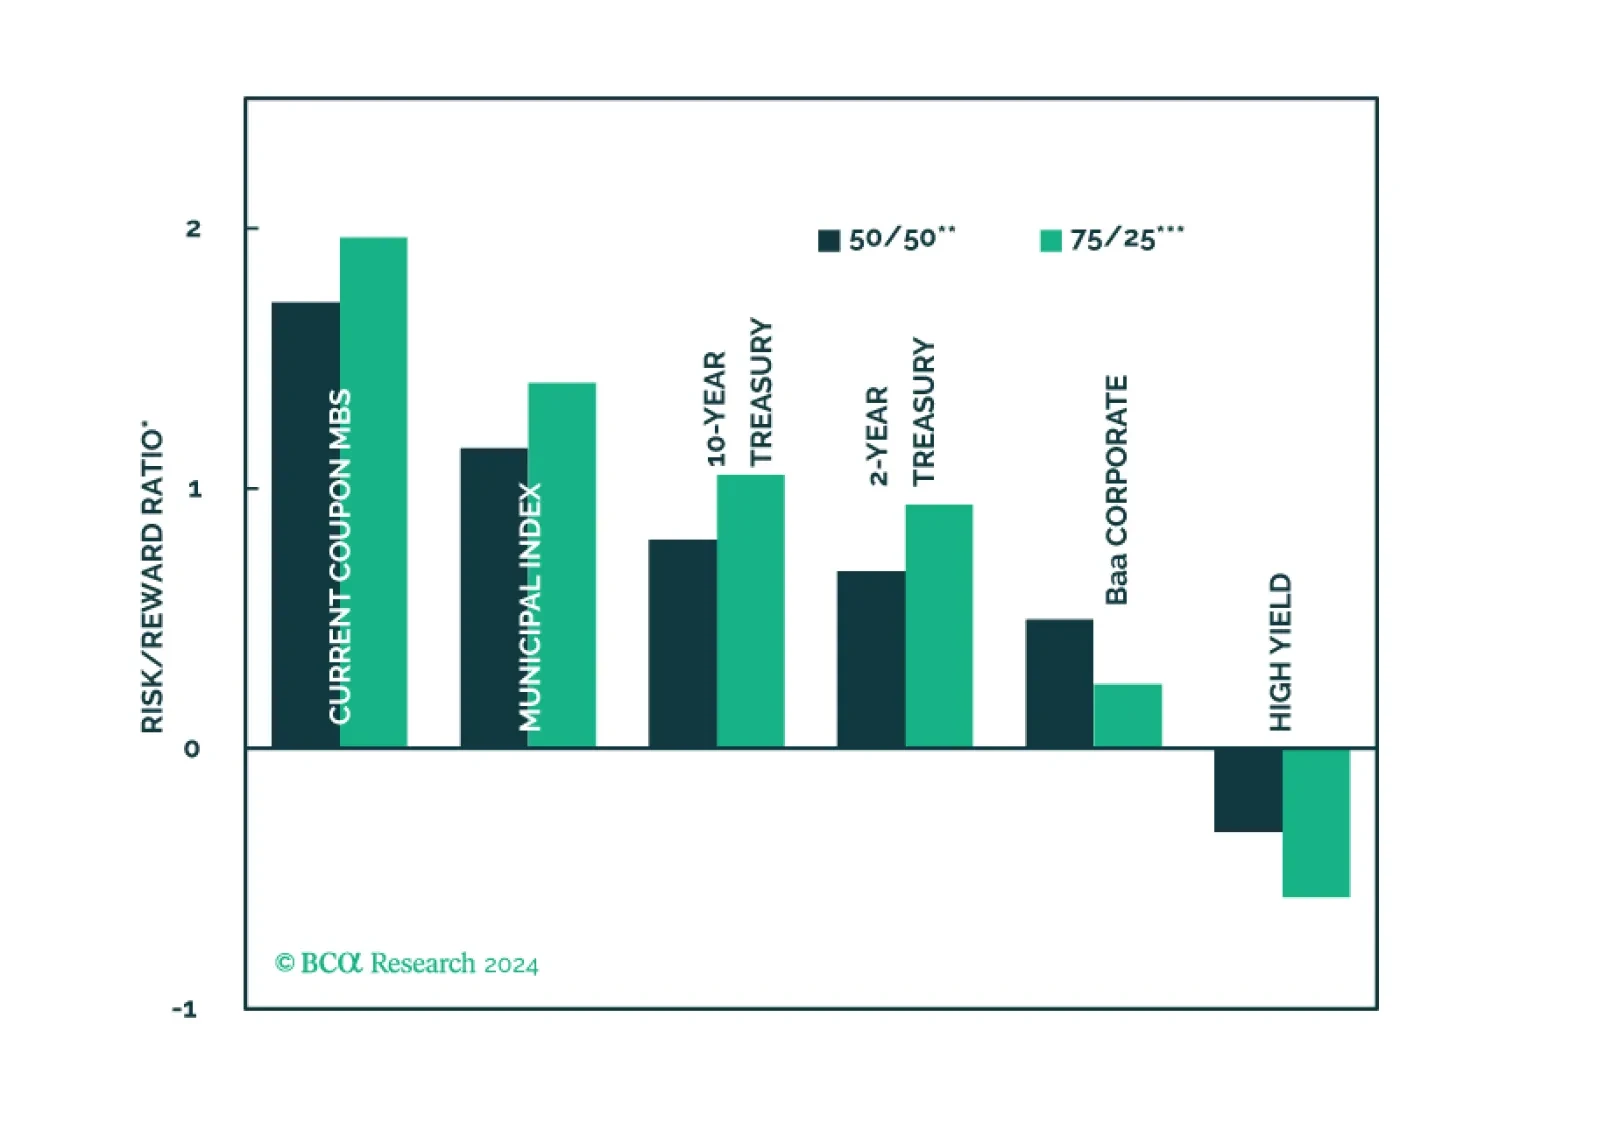
We calculate expected returns for several different US fixed income sectors with a focus on how municipal bonds stack up against the investment alternatives.
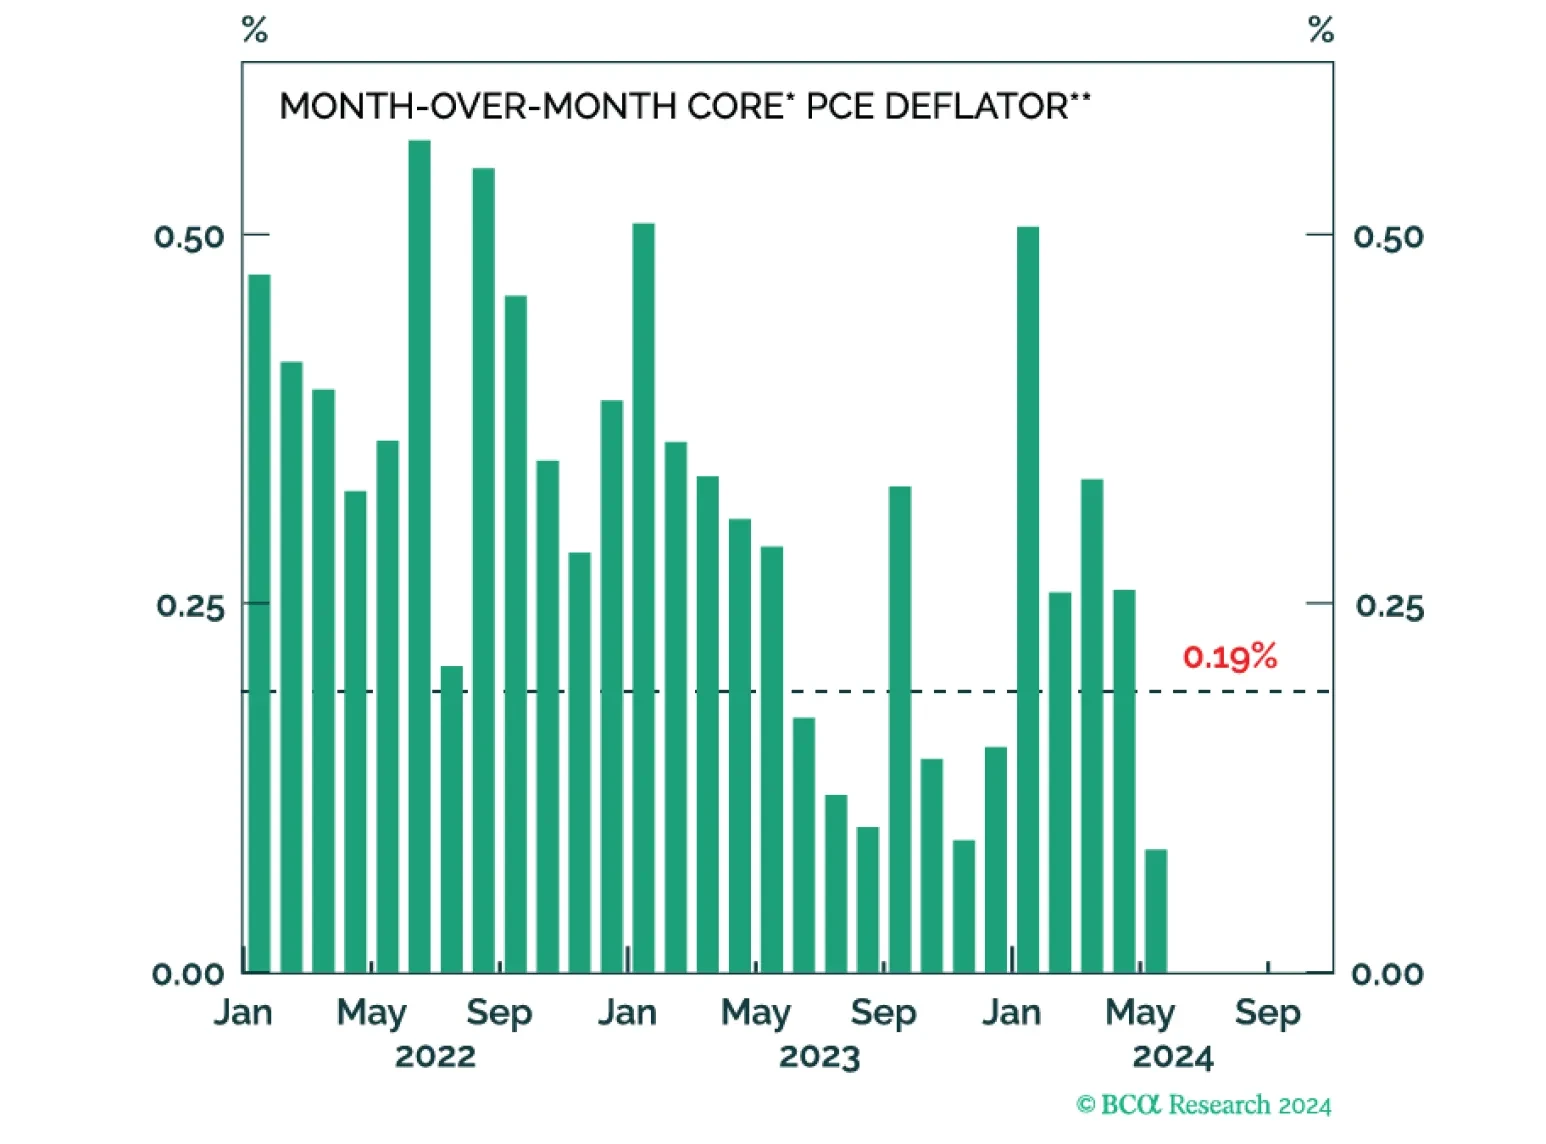
Corporate and junk bonds are the fixed-income sectors that are most exposed to an economic downturn. We’ve highlighted that markets continue to price in a Goldilocks scenario, with spreads narrowing despite ongoing deterioration in the labor market. Spreads…