 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
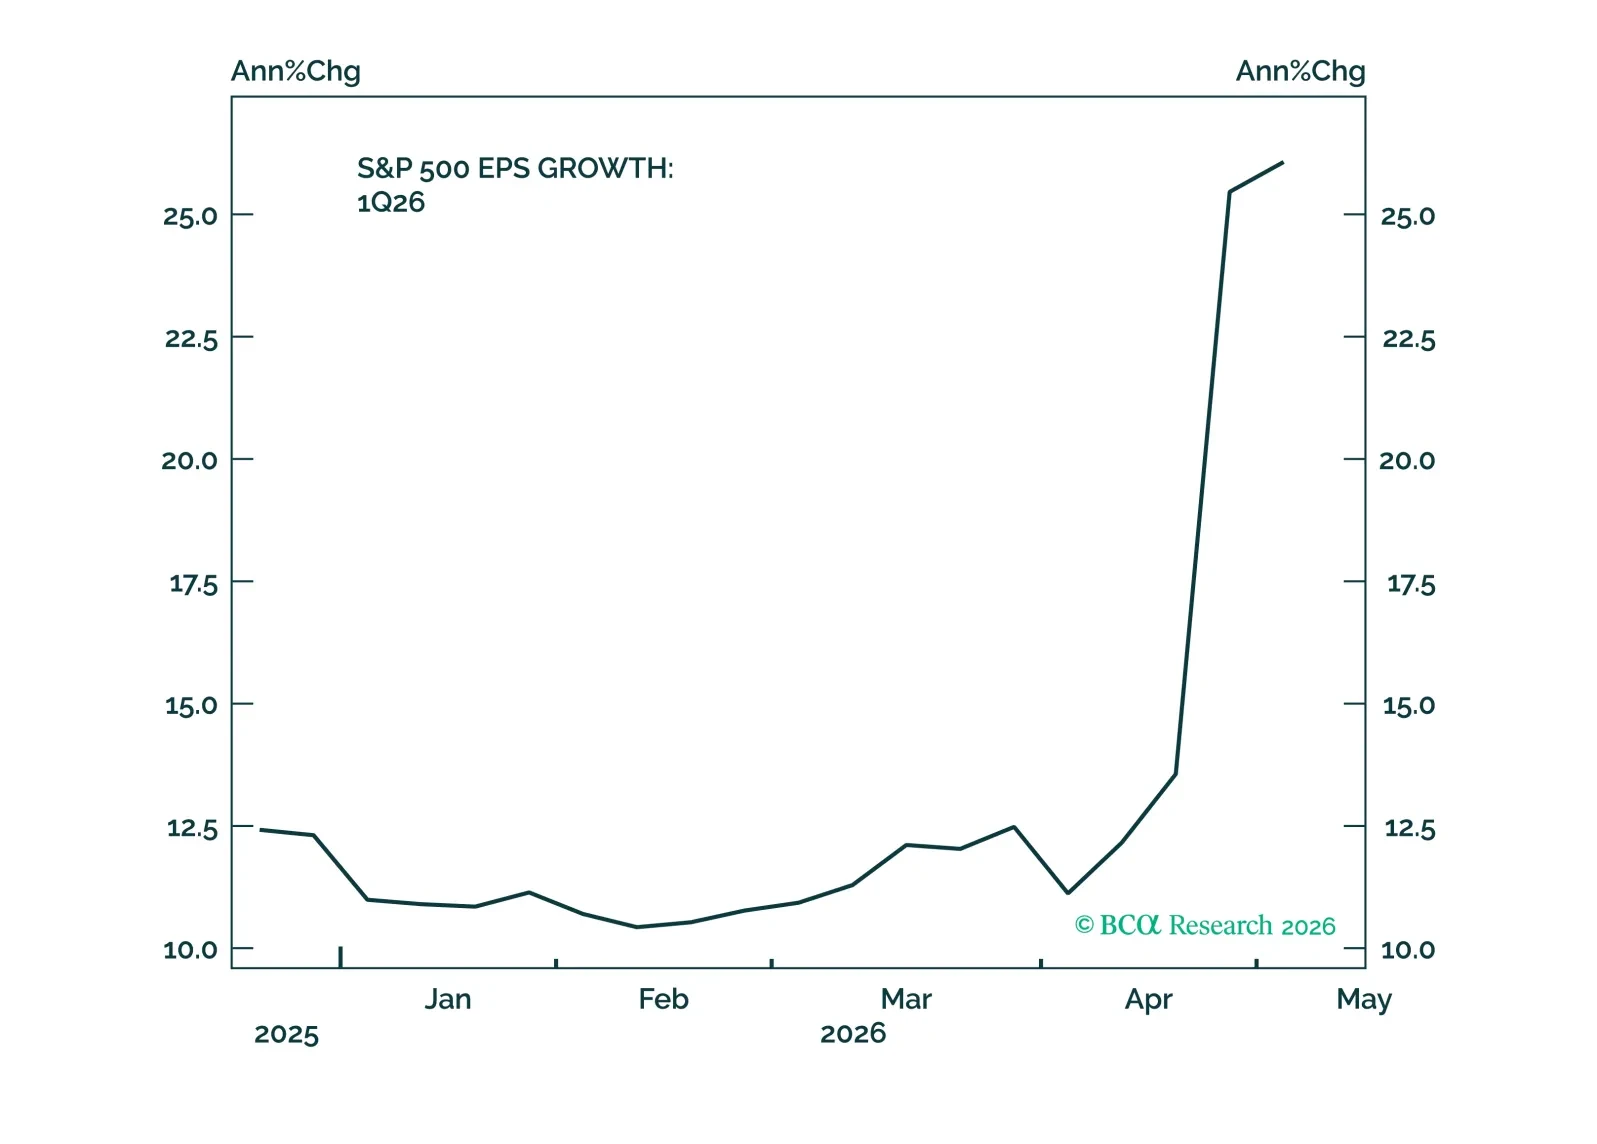
We take stock of earnings, AI capex and the labor market and explain why we think the repeated new highs in the S&P 500 are justified.
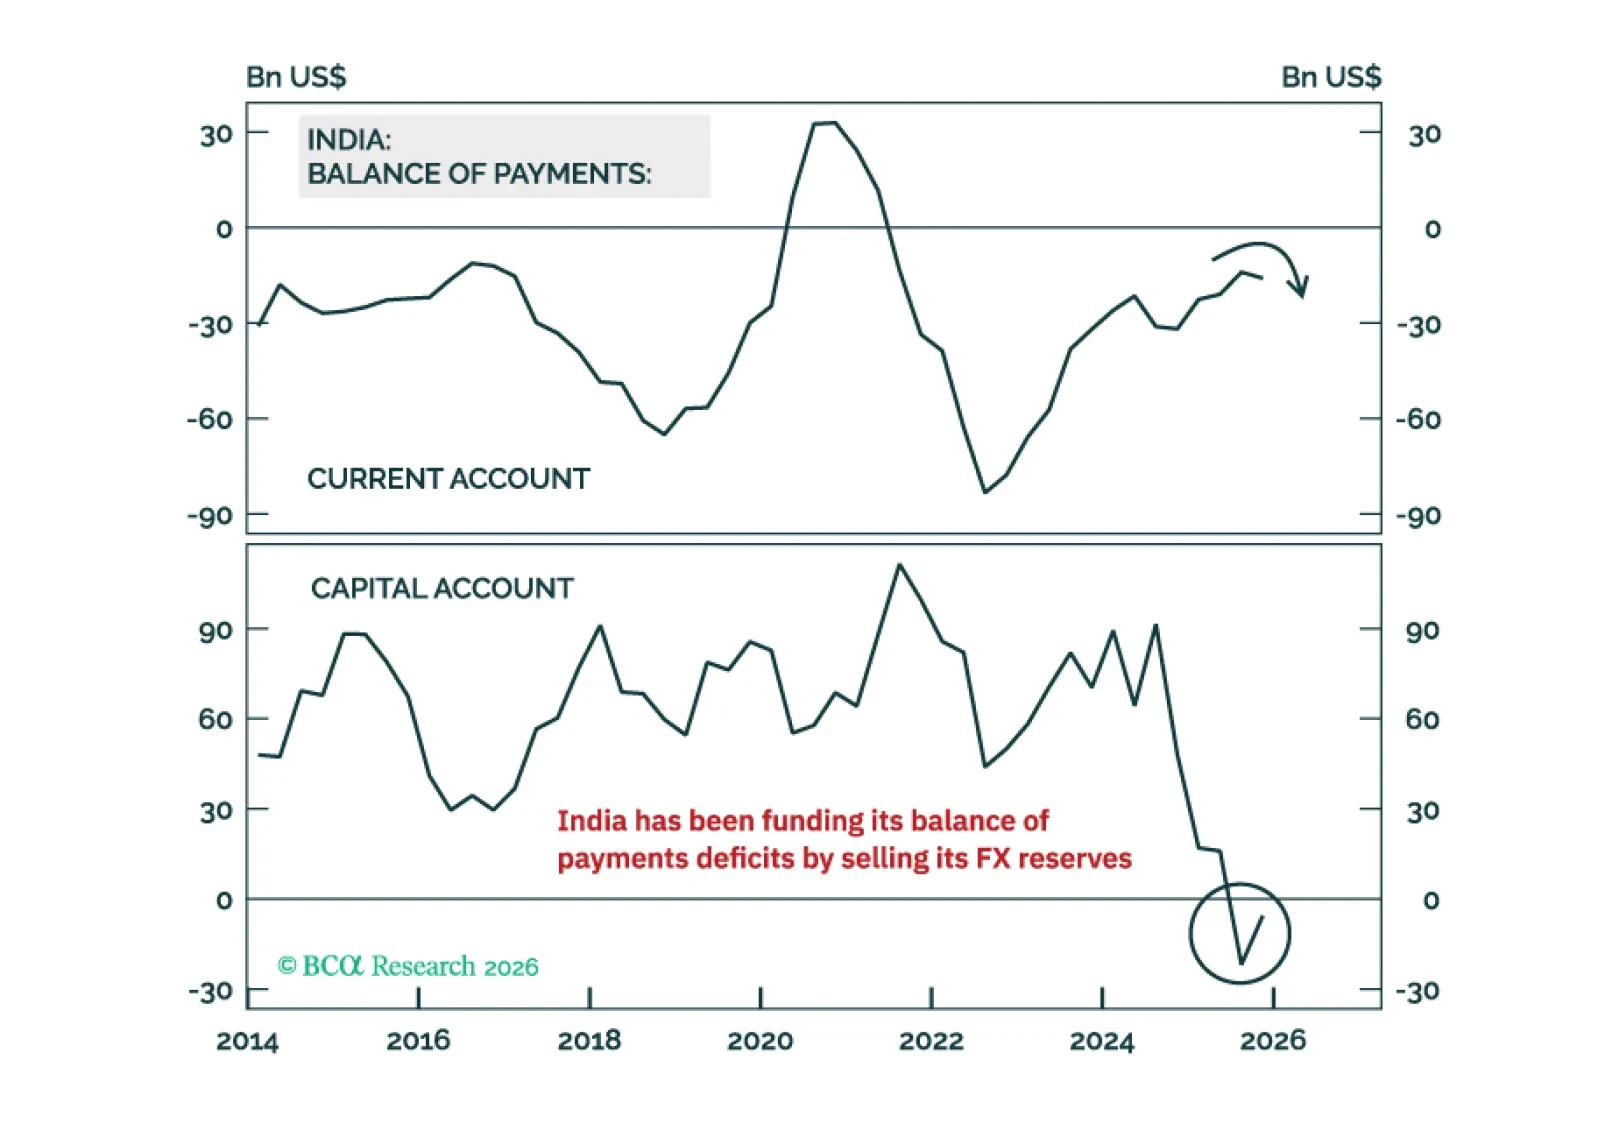
India is probably the most vulnerable among the G-20 economies should the Strait of Hormuz not reopen fully by the end of this month. Growth will slow, while inflation will rise materially. Investors should brace for further weakness in the currency and stock prices.
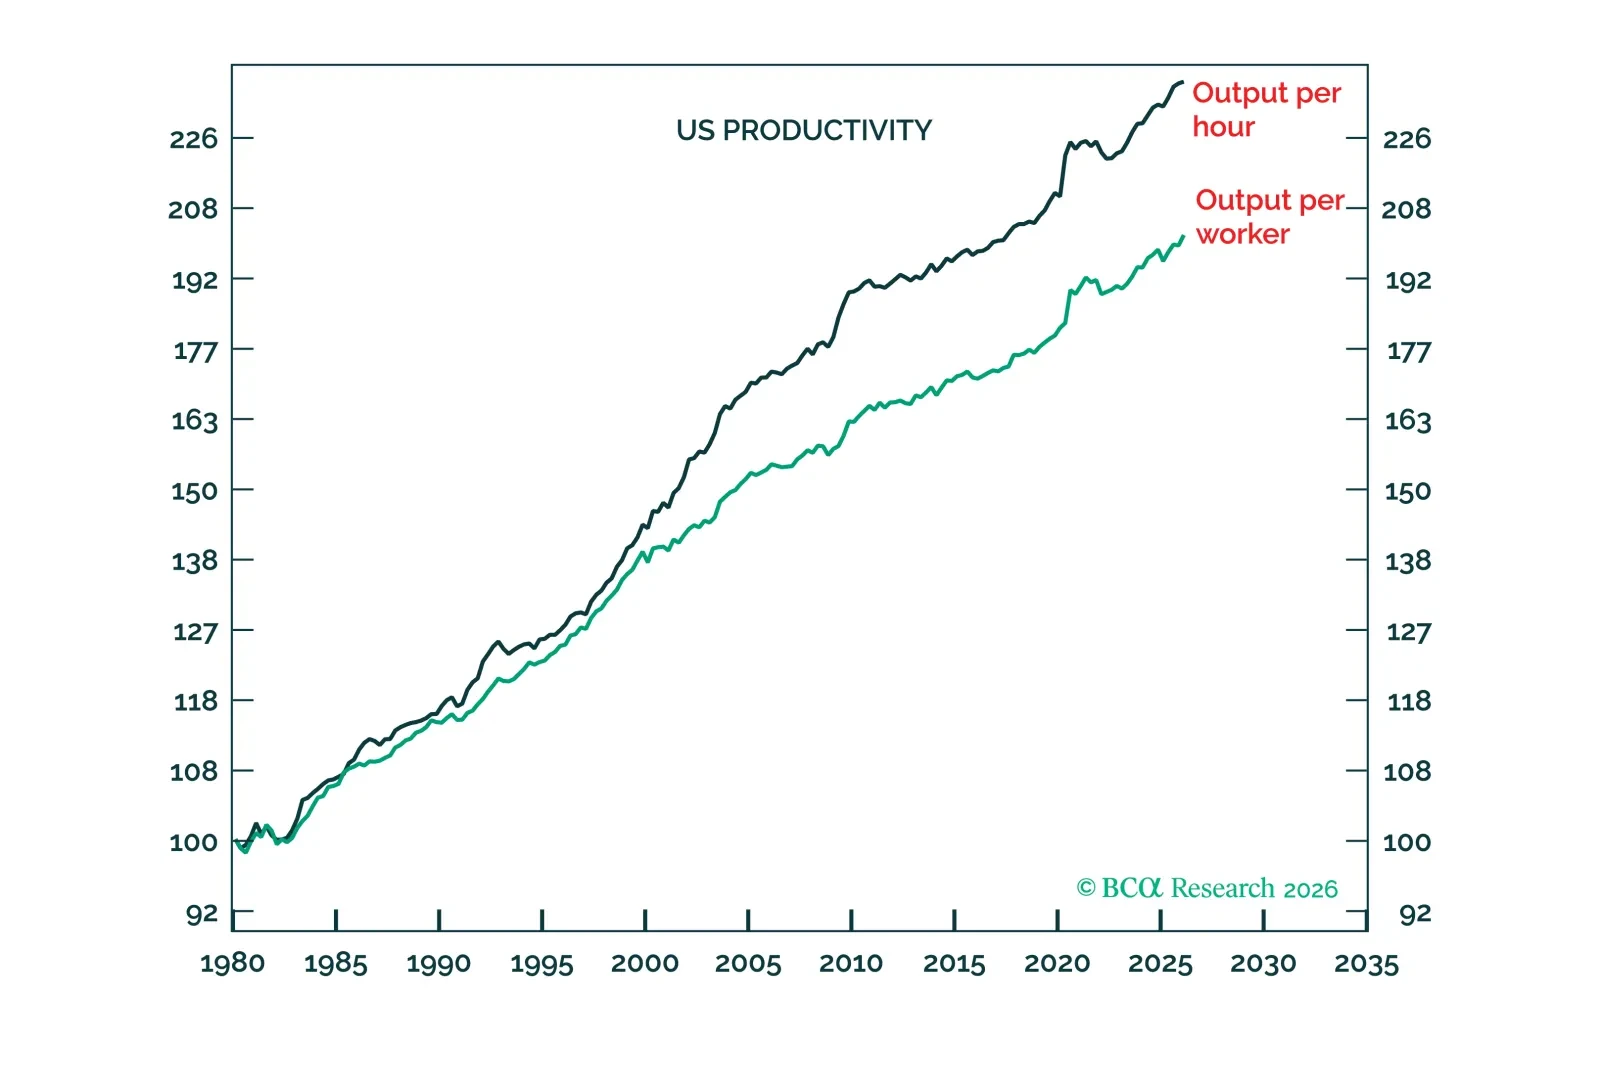
New Fed Chair, Kevin Warsh, is betting that an AI-driven productivity acceleration will get the Fed out of jail for persistently missing its 2 percent inflation target. But history informs us that while new technology adoption is exponential, total productivity growth is not. So, if Warsh’s bet goes wrong, as is likely, the US inflation overshoot will persist. We discuss the investment implications. Plus, a new trade is short cotton.
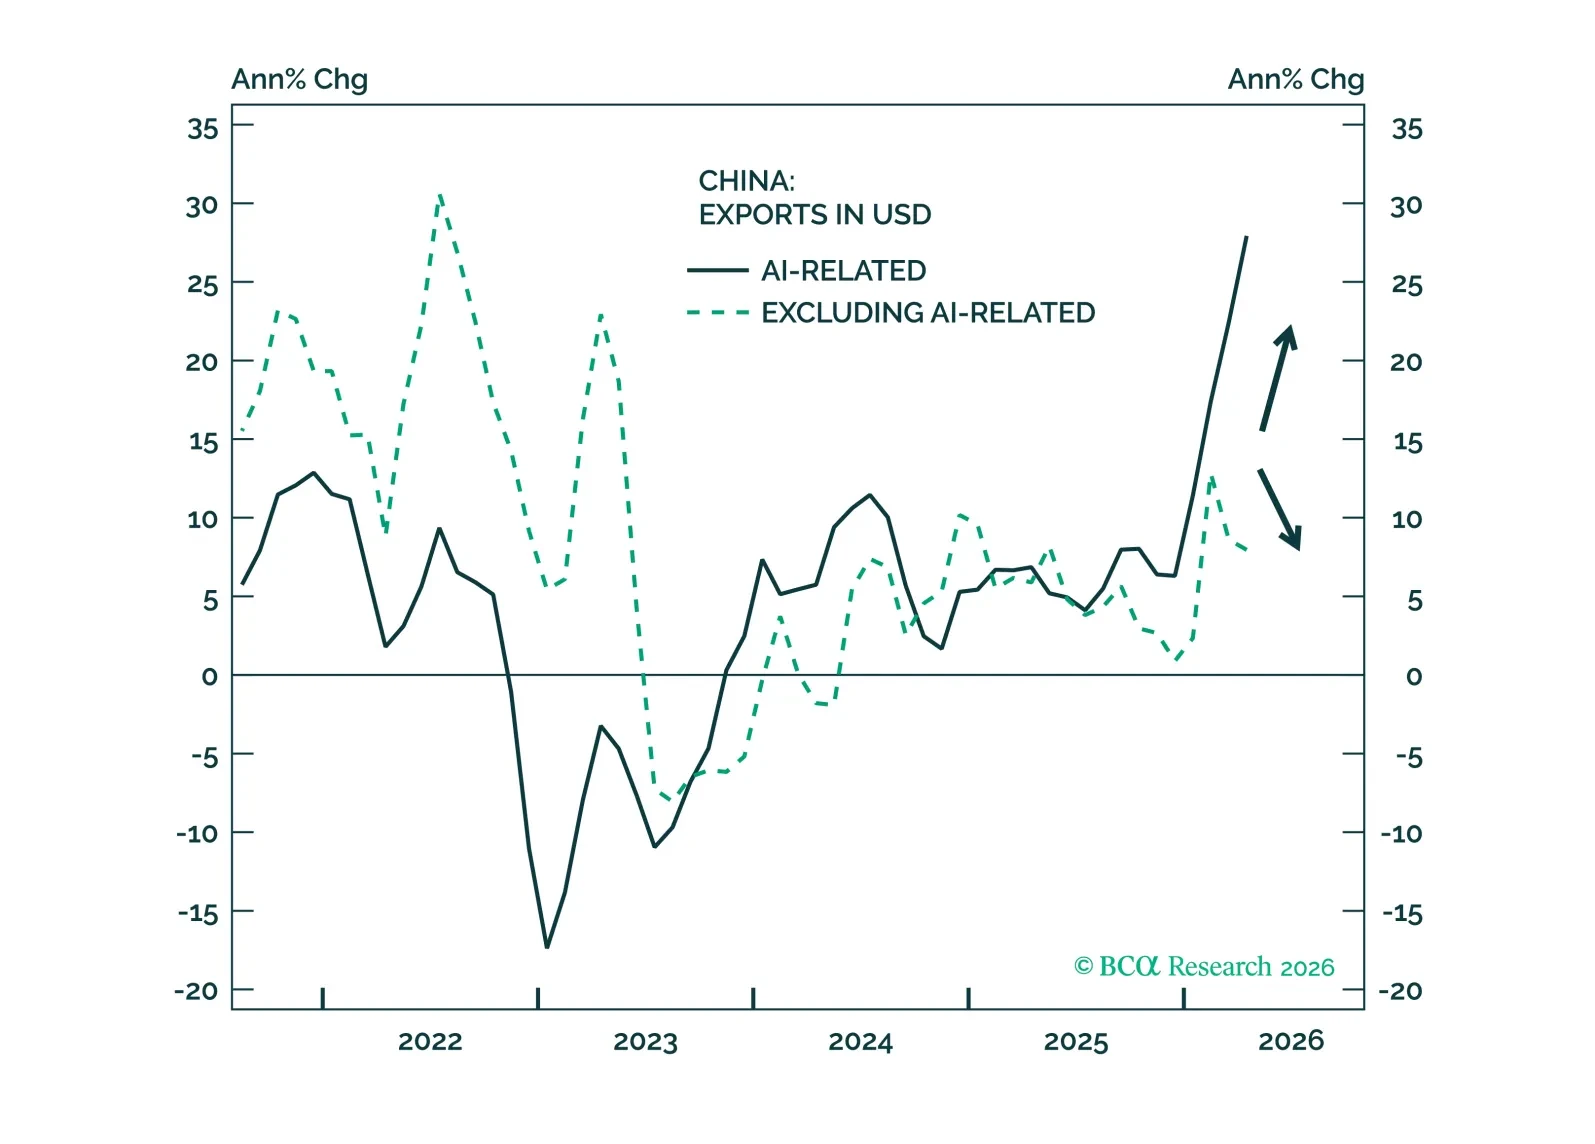
China’s K-shaped economy is widening, with resilient exports and subdued domestic consumption. Over the next 6–12 months, we see a higher probability that global capex momentum persists than China delivers meaningful consumer-focused stimulus.
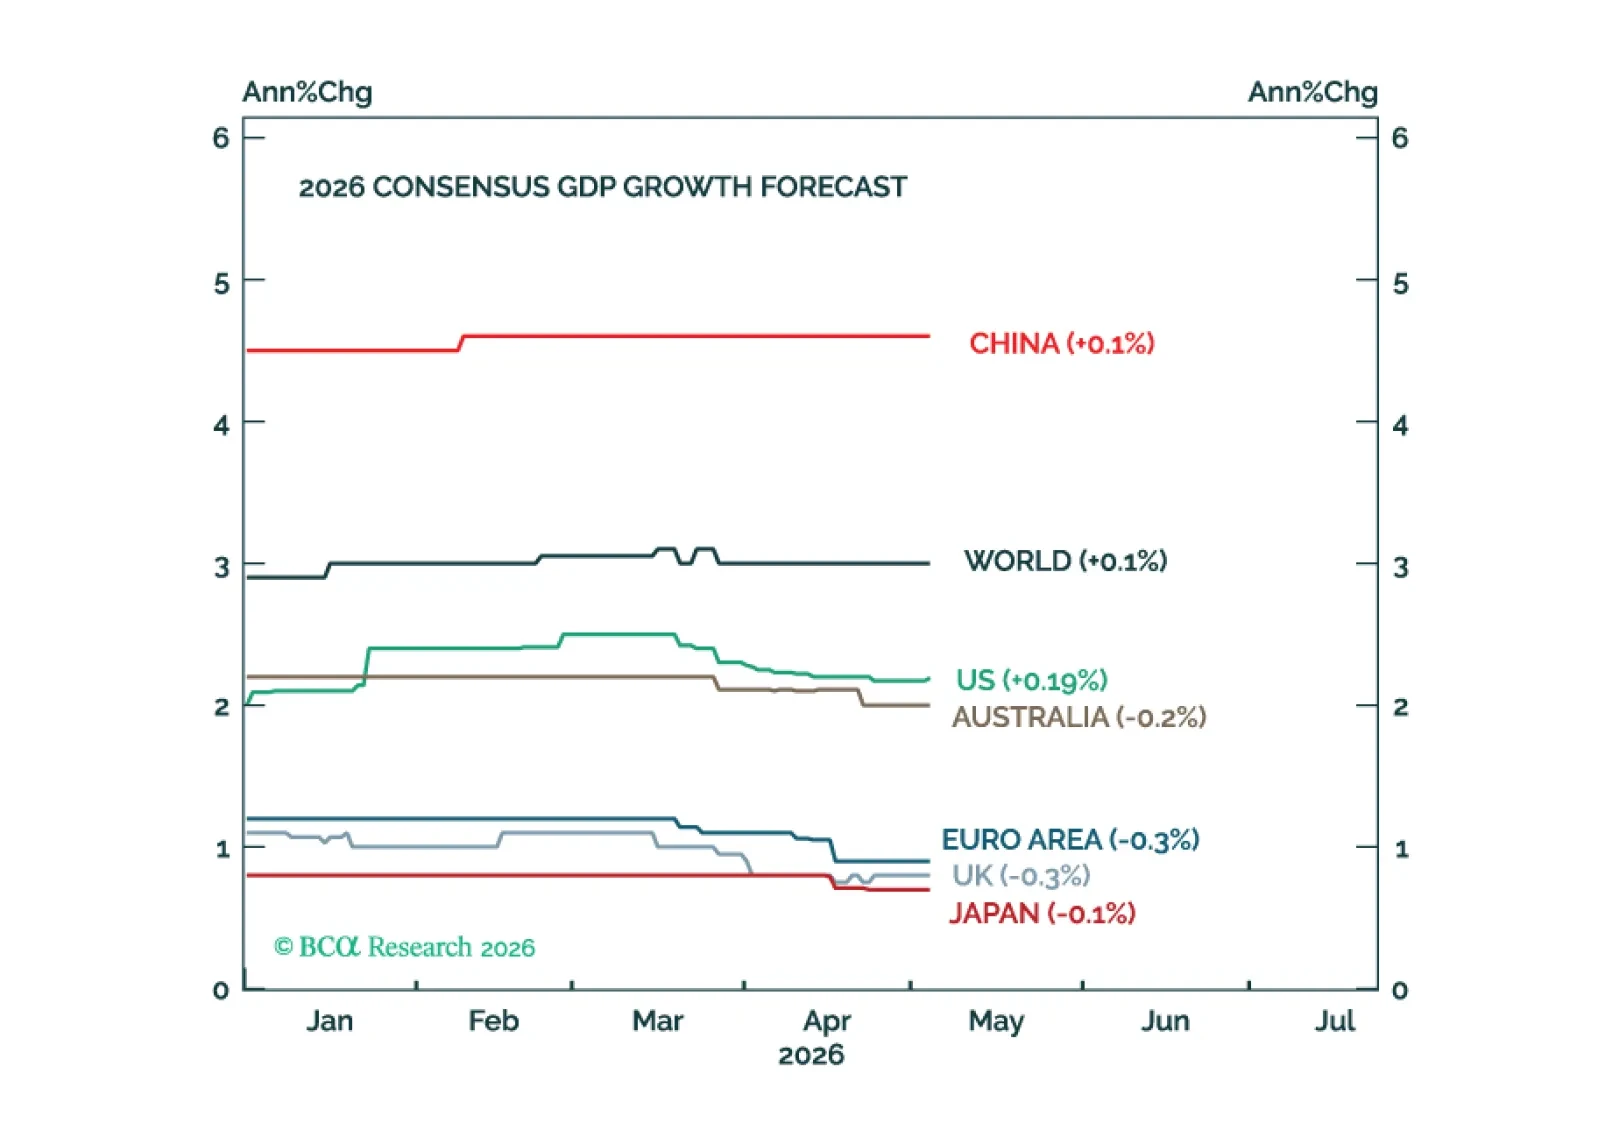
The global economy has weathered the oil shock reasonably well so far. However, the risk of a recession will increase meaningfully if the Strait of Hormuz remains closed into June.
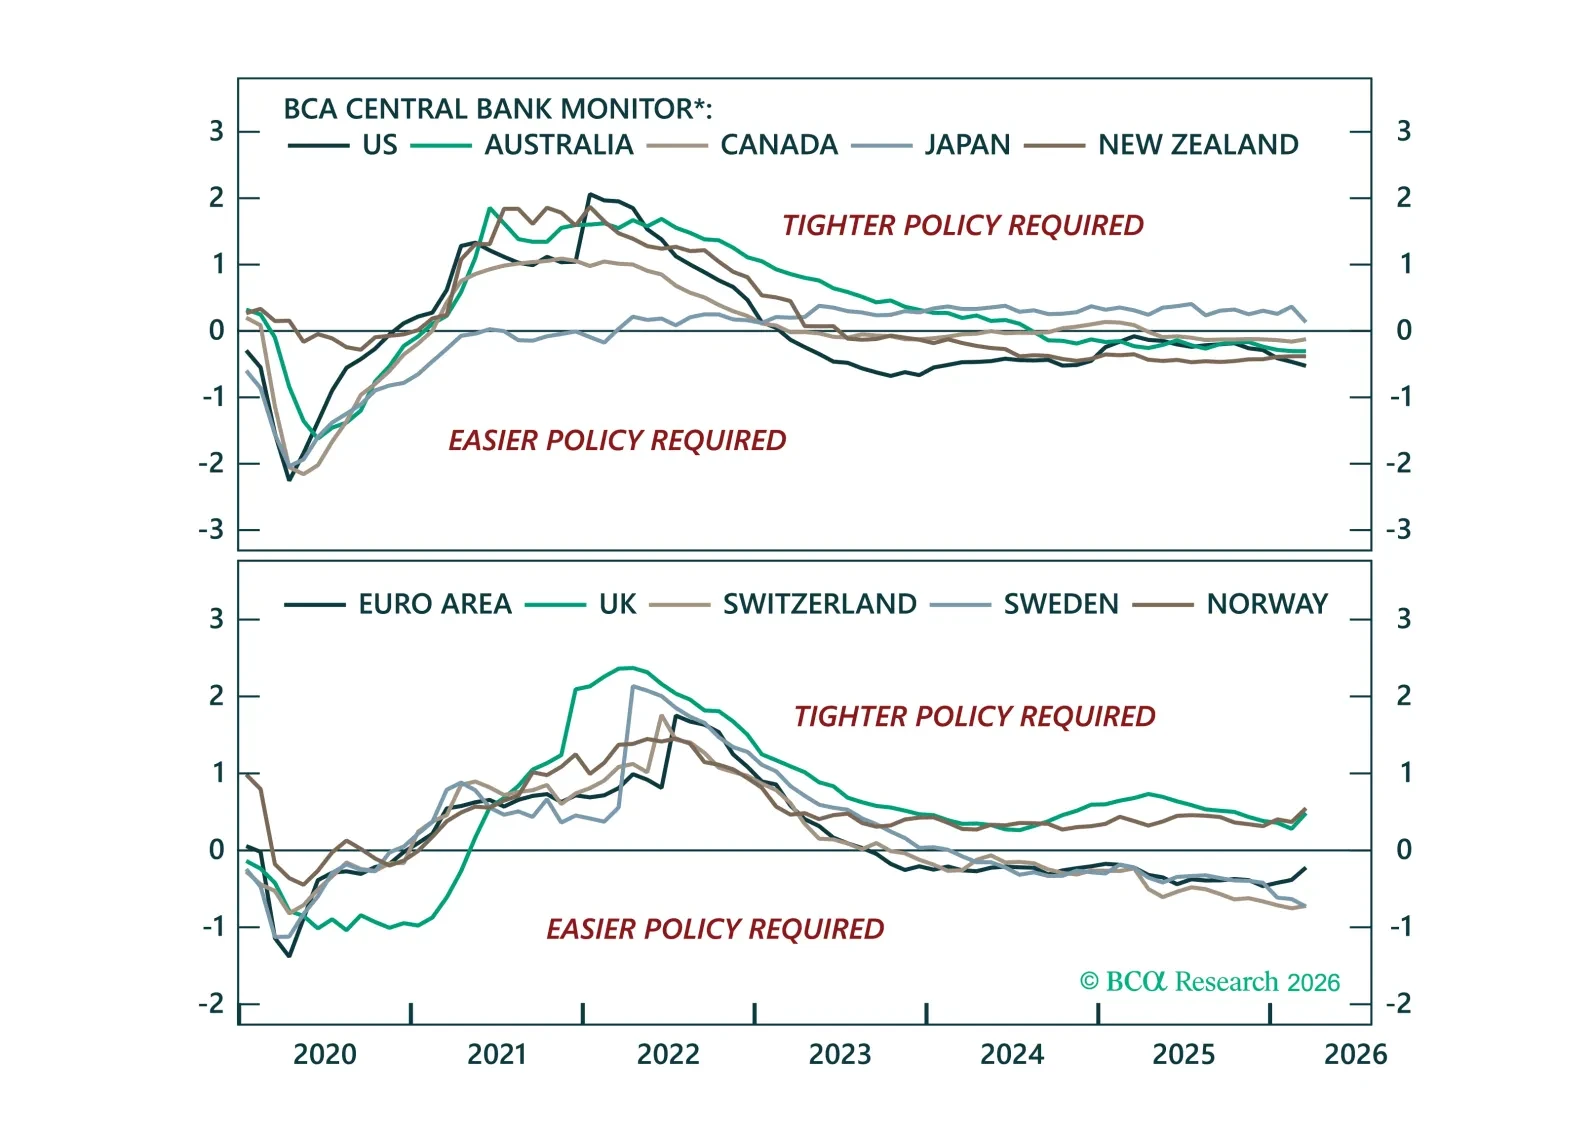
Central banks remain on hold amid heightened uncertainty. We rely on BCA’s Central Bank Monitors to assess the current policy stance of major central banks, and highlight the tactical opportunities across bond markets and currencies.
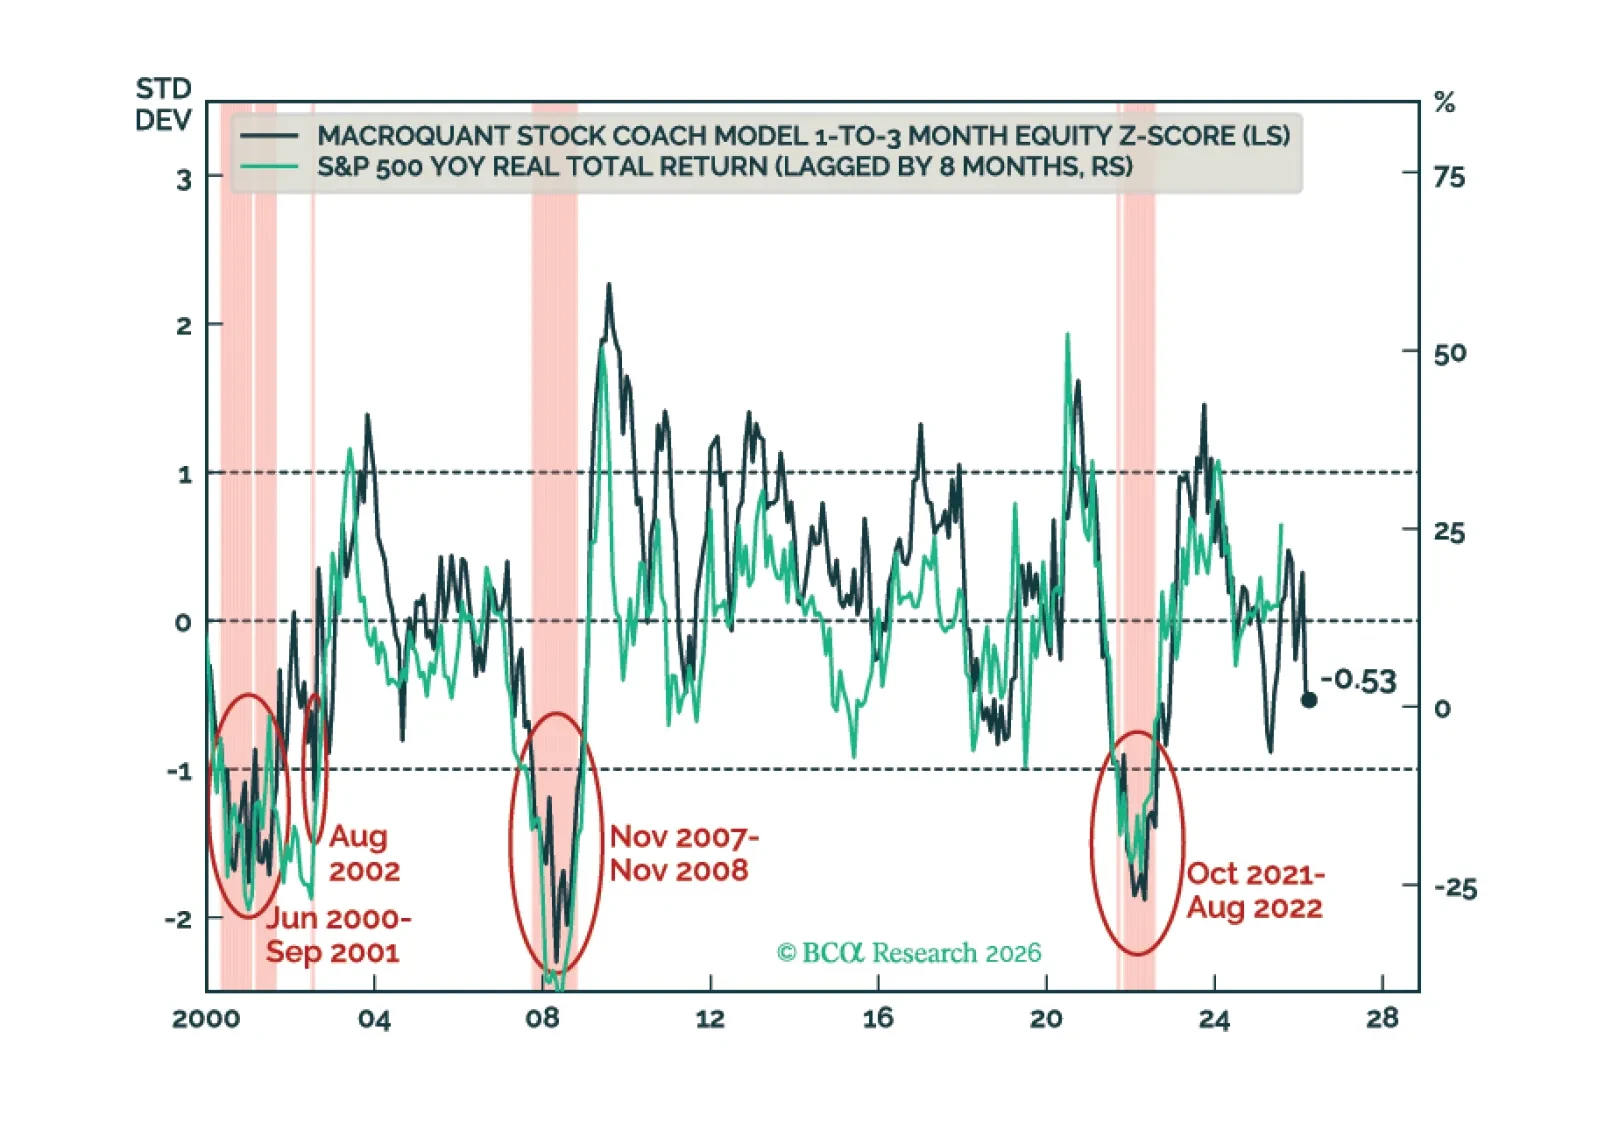
MacroQuant recommends an underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is neutral-to-slightly positive on the US dollar, remains neutral on gold, upgrades copper to neutral, and is very bullish on oil.
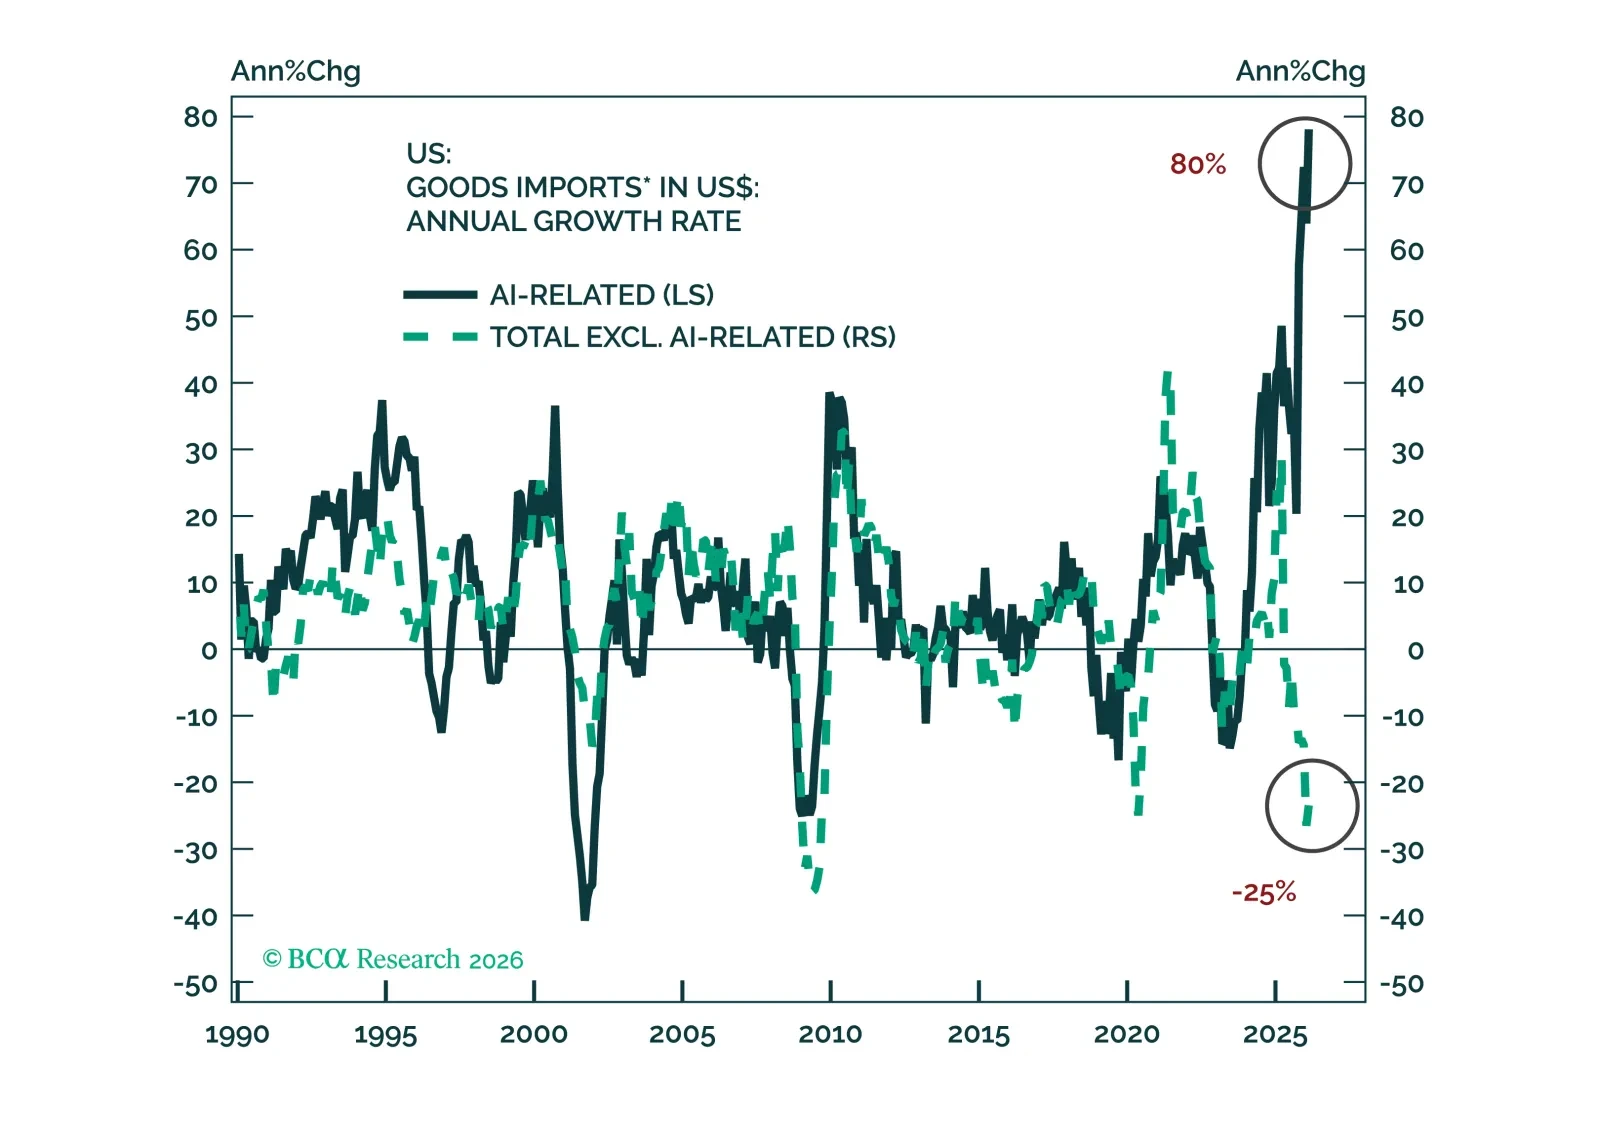
Global trade has held up despite US non-AI import volumes contracting by 25% over the past 12 months. The strength in global trade has concentrated in two areas: (1) imports of AI-related hardware and (2) developing countries’ imports, especially from China. Will these continue?
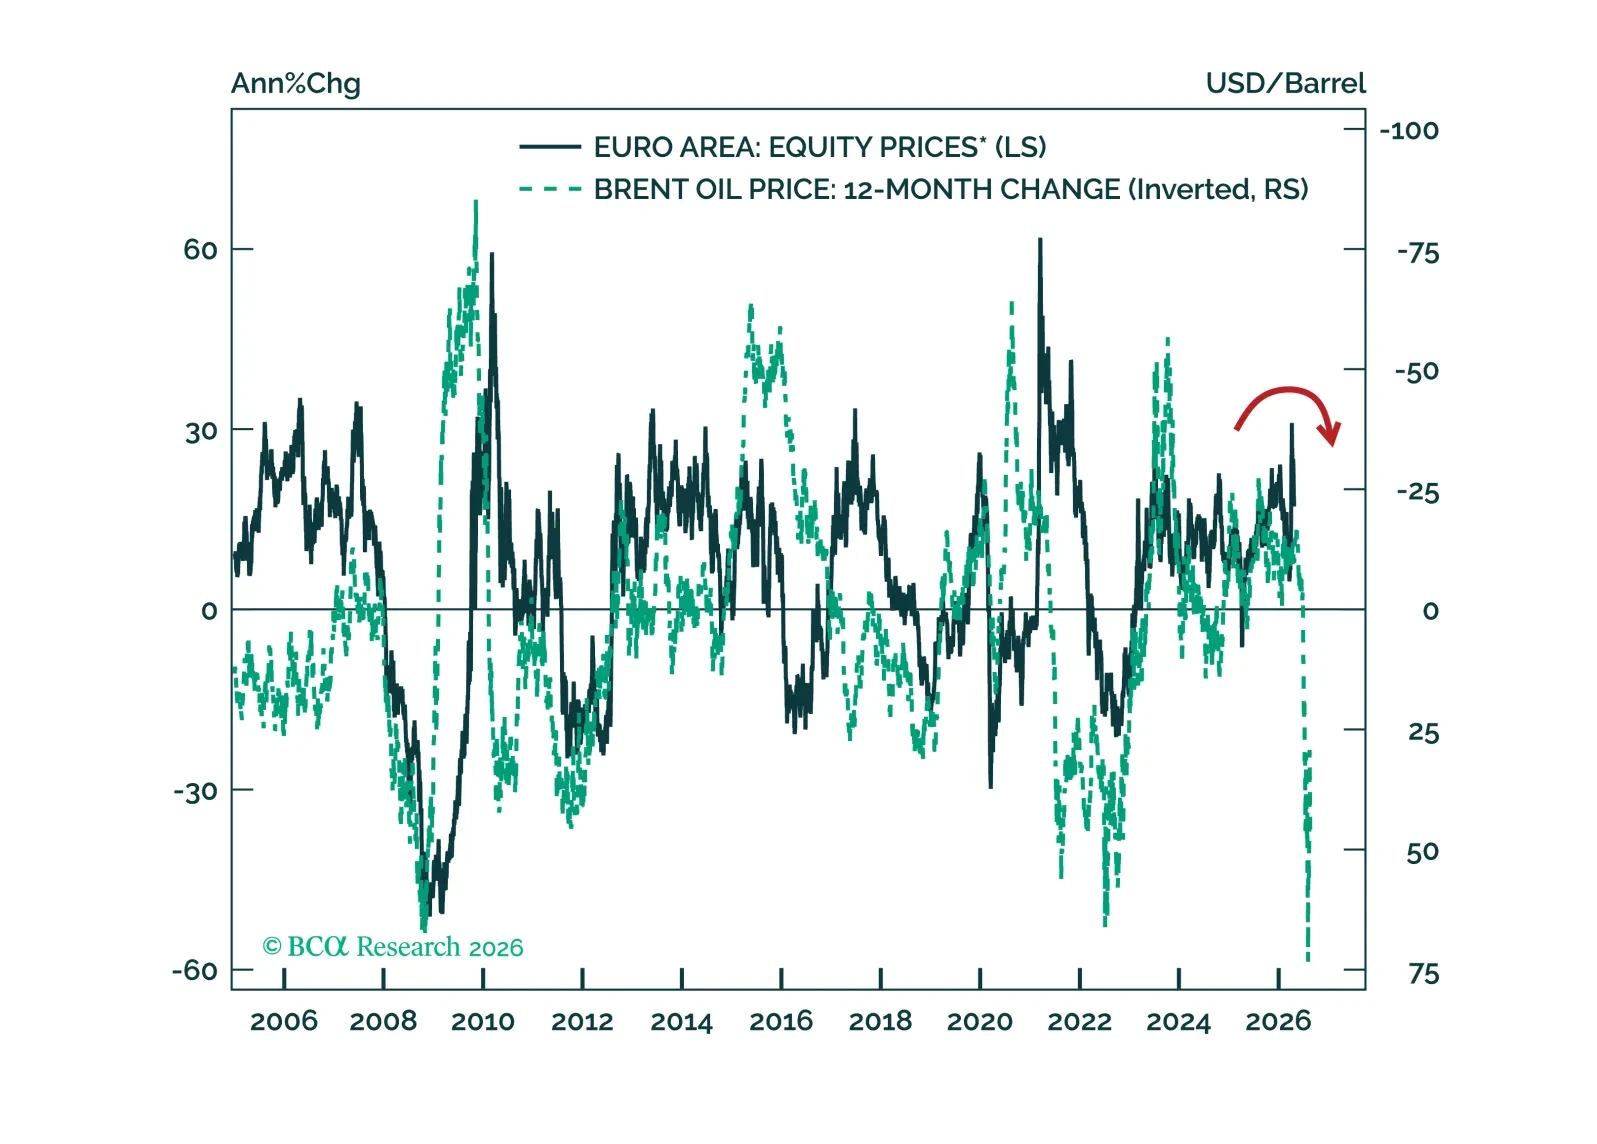
The longer the Strait of Hormuz remains closed, the more likely the Eurozone will experience an economic recession, as higher energy prices, supply chain disruptions, and weaker global demand slowly grind the European economy to a halt. The relief rally is running out of time. Investors should add exposure to the best-performing sectors following past oil supply shocks: Energy, pharma, and utilities.
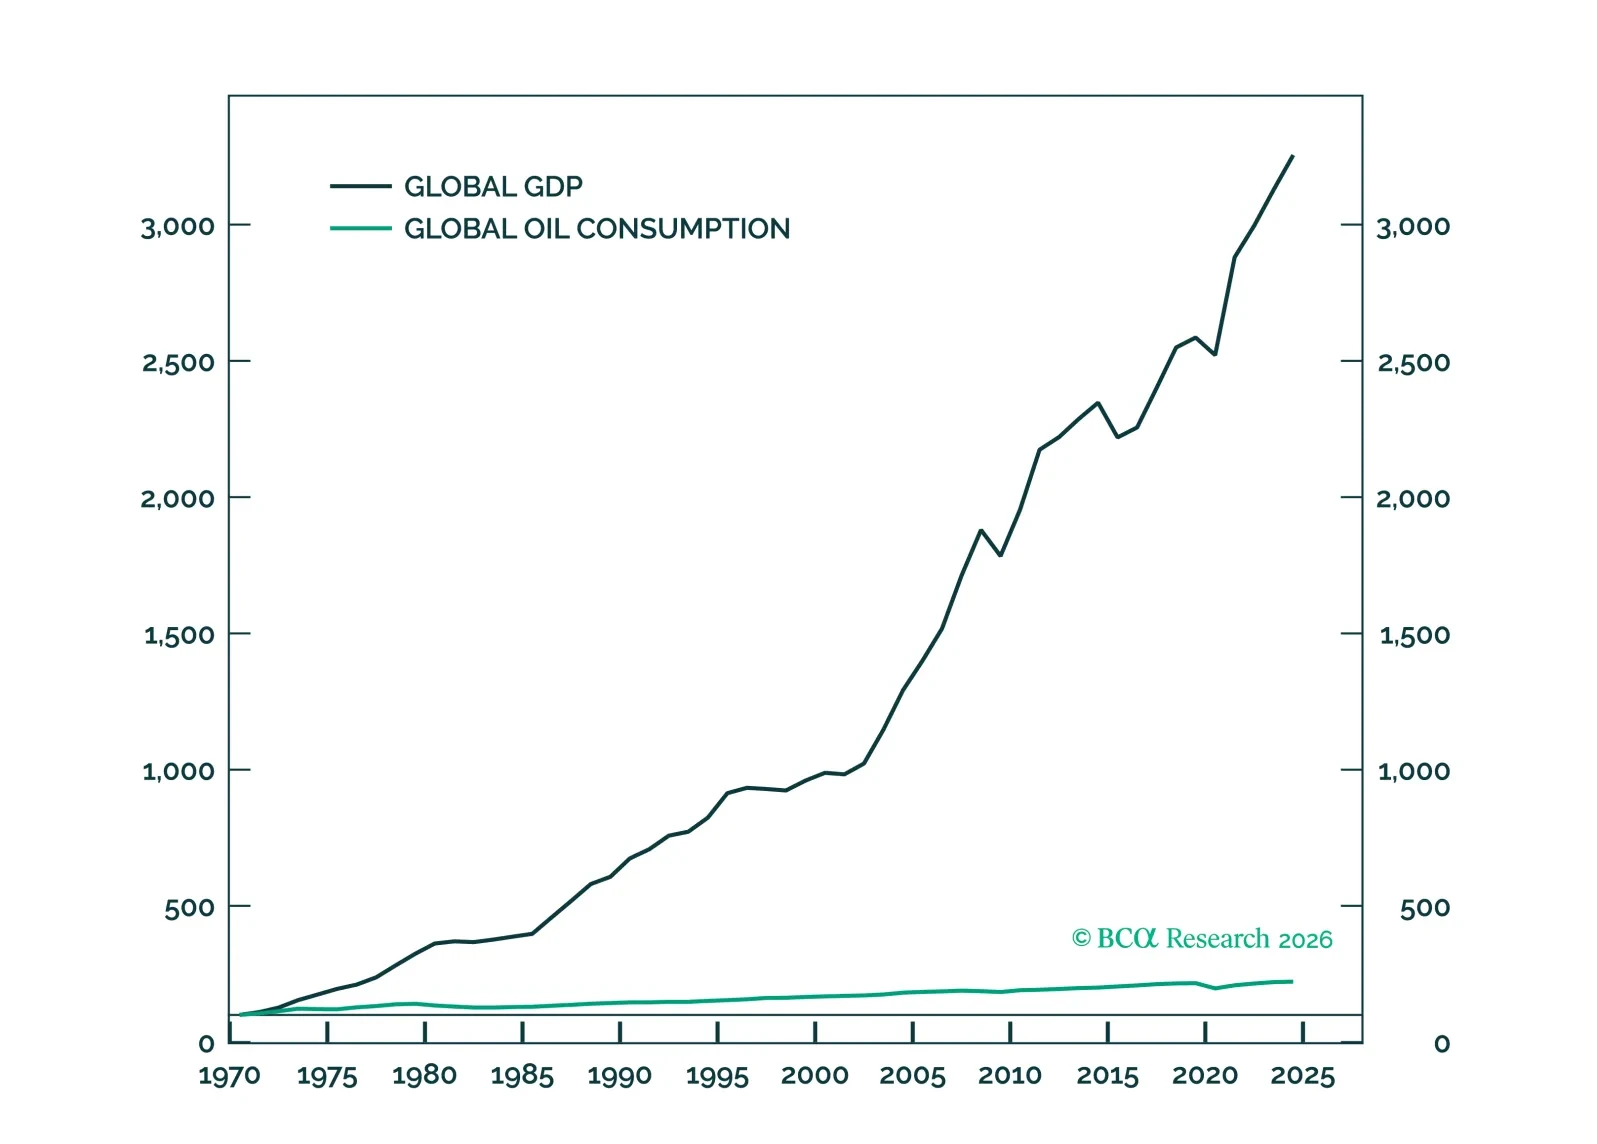
The S&P 500 finished last week at an all-time high as optimism over earnings has pushed the Iran conflict out of the spotlight. Despite uncertainty in the Strait of Hormuz, we do not think investors have enough evidence to justify underweighting equities and other risk assets.