 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
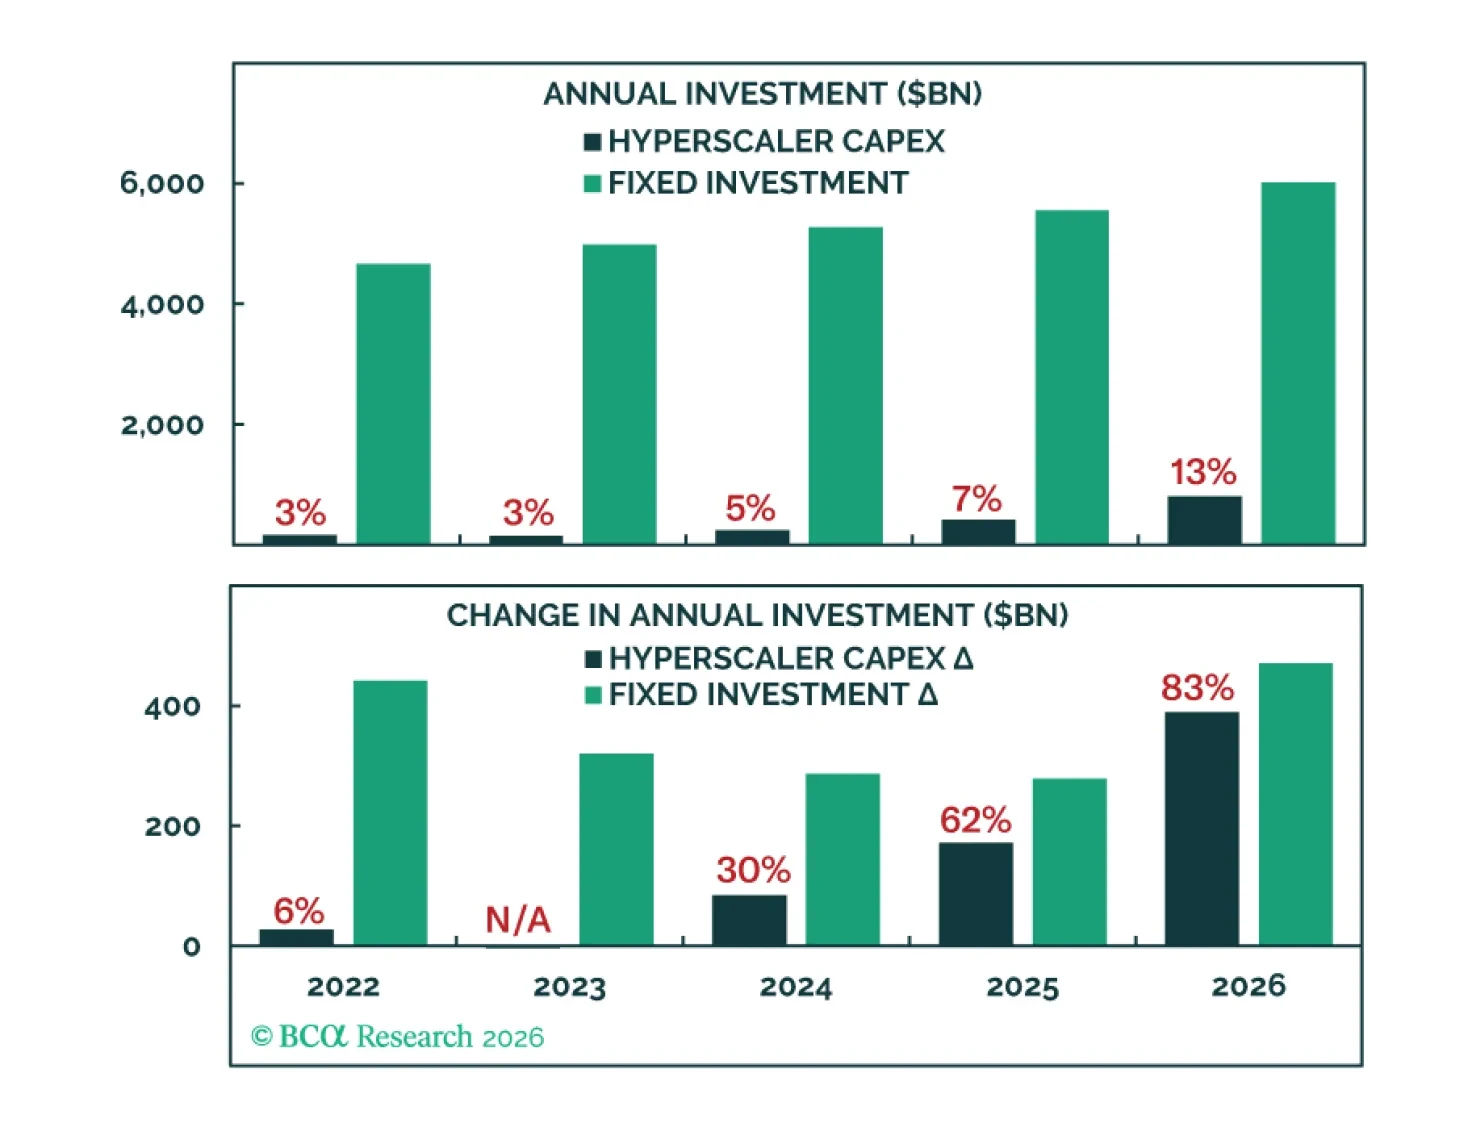
Data centers have swallowed aggregate US investment to such an extent that even a modest hyperscaler capex pullback could sink the expansion and bull market.
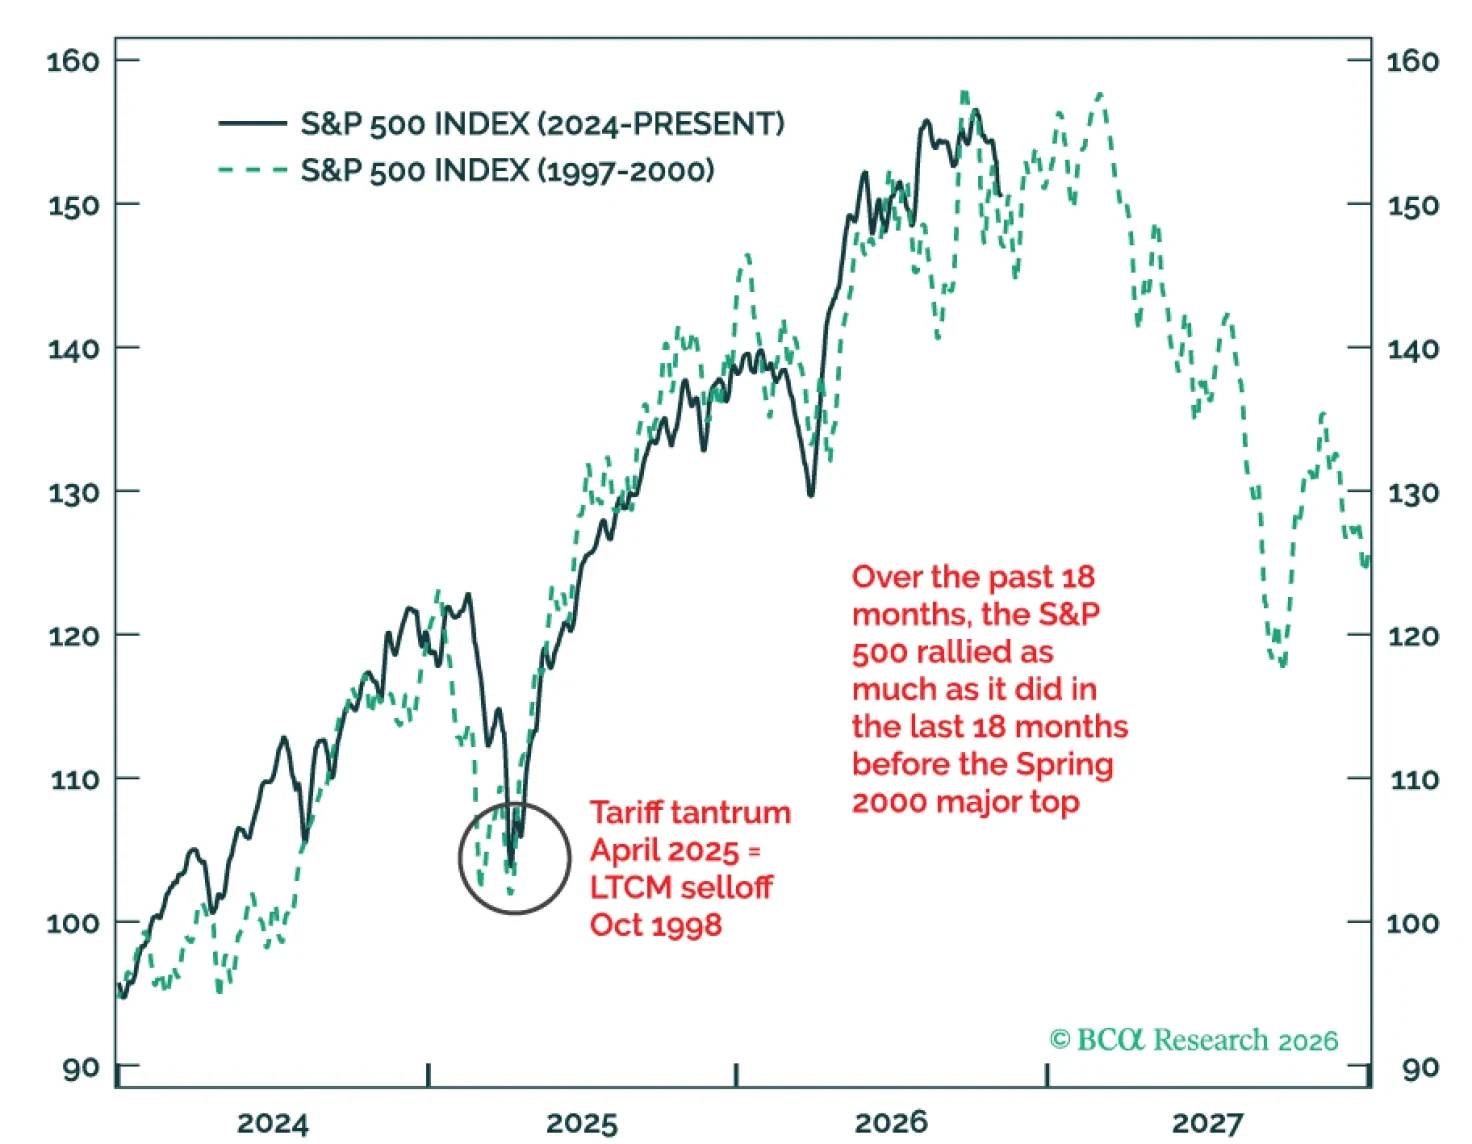
Resist buying the equity dip: a major global market top may already be behind us. Sell the US dollar on strength. Accumulate bonds on weakness, favoring those in countries with current account surpluses.
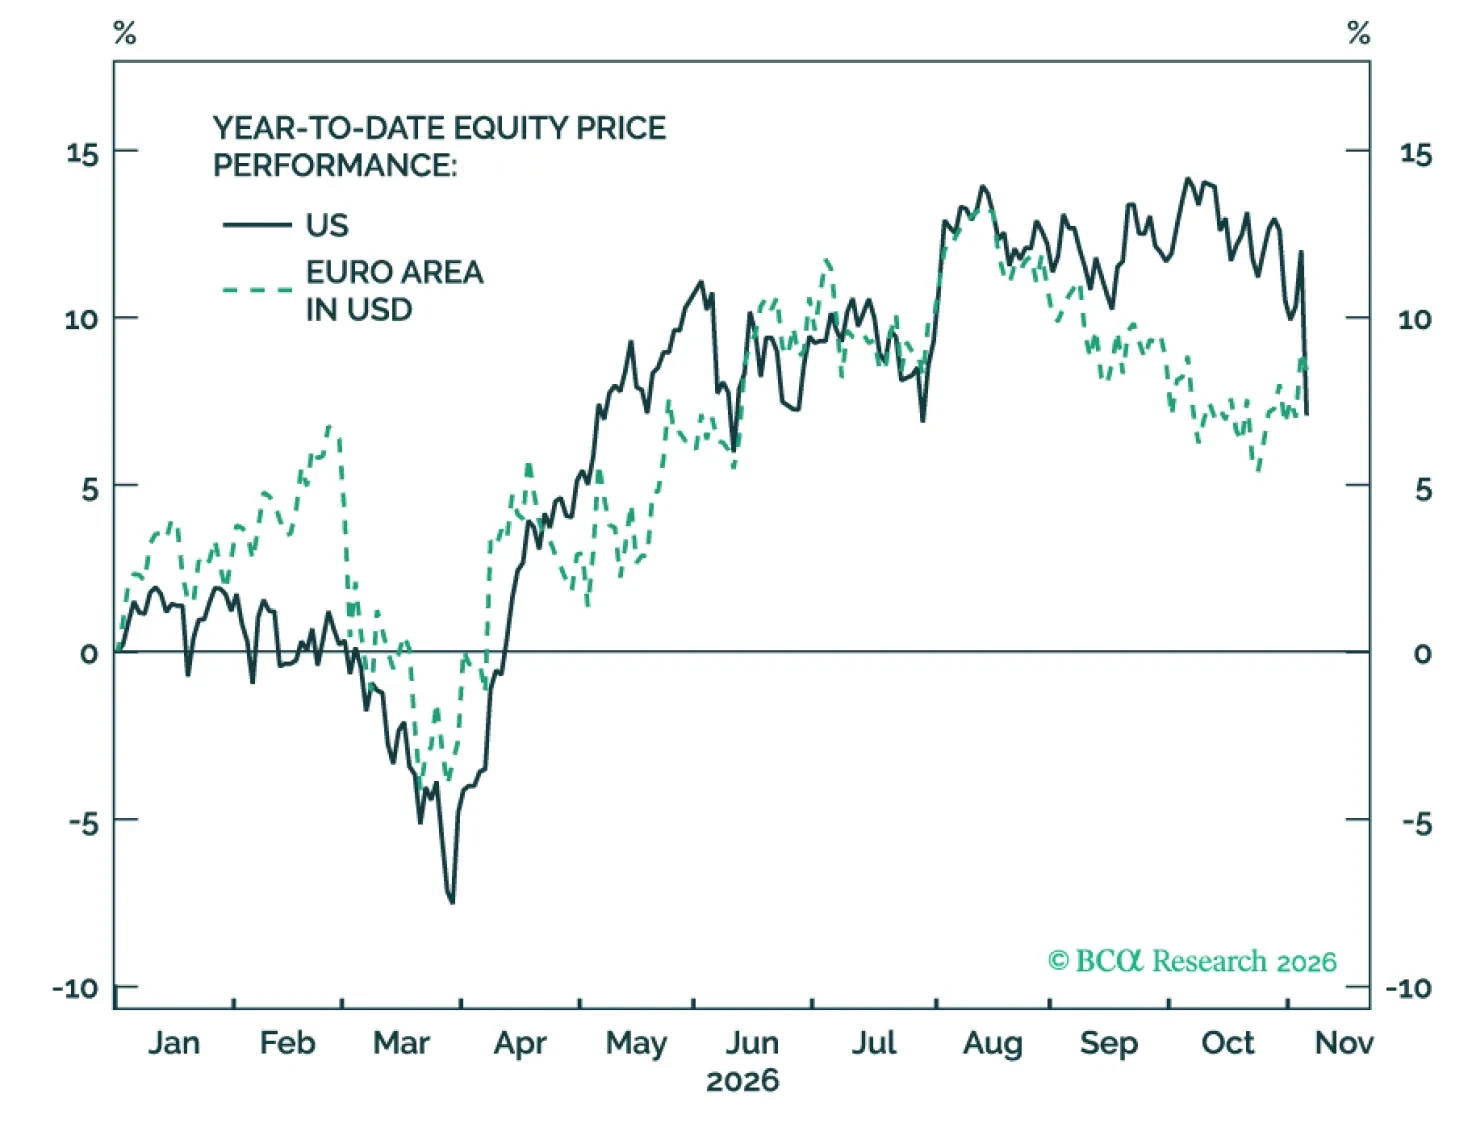
Europe was shunned while AI could do no wrong. That trade is looking tired. Falling energy prices and cracks in the AI boom favor rotating out of US equities and into cheaper European stocks. Favor defensives: Europe can win the relative race even if both markets fall.
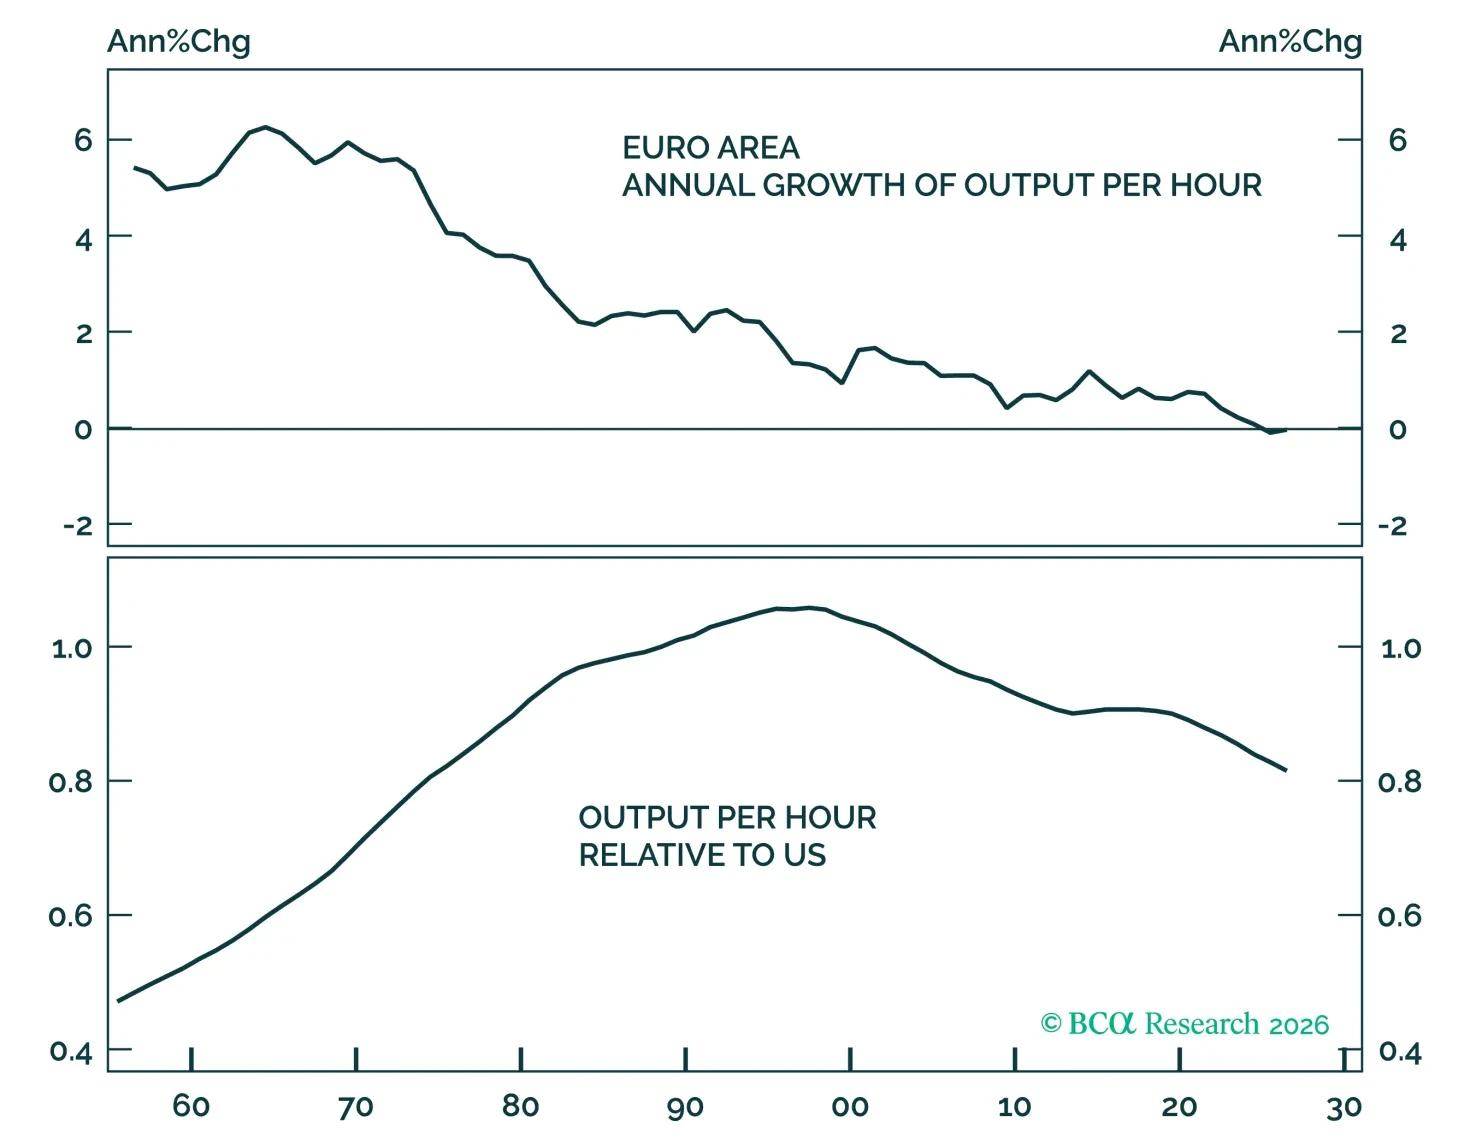
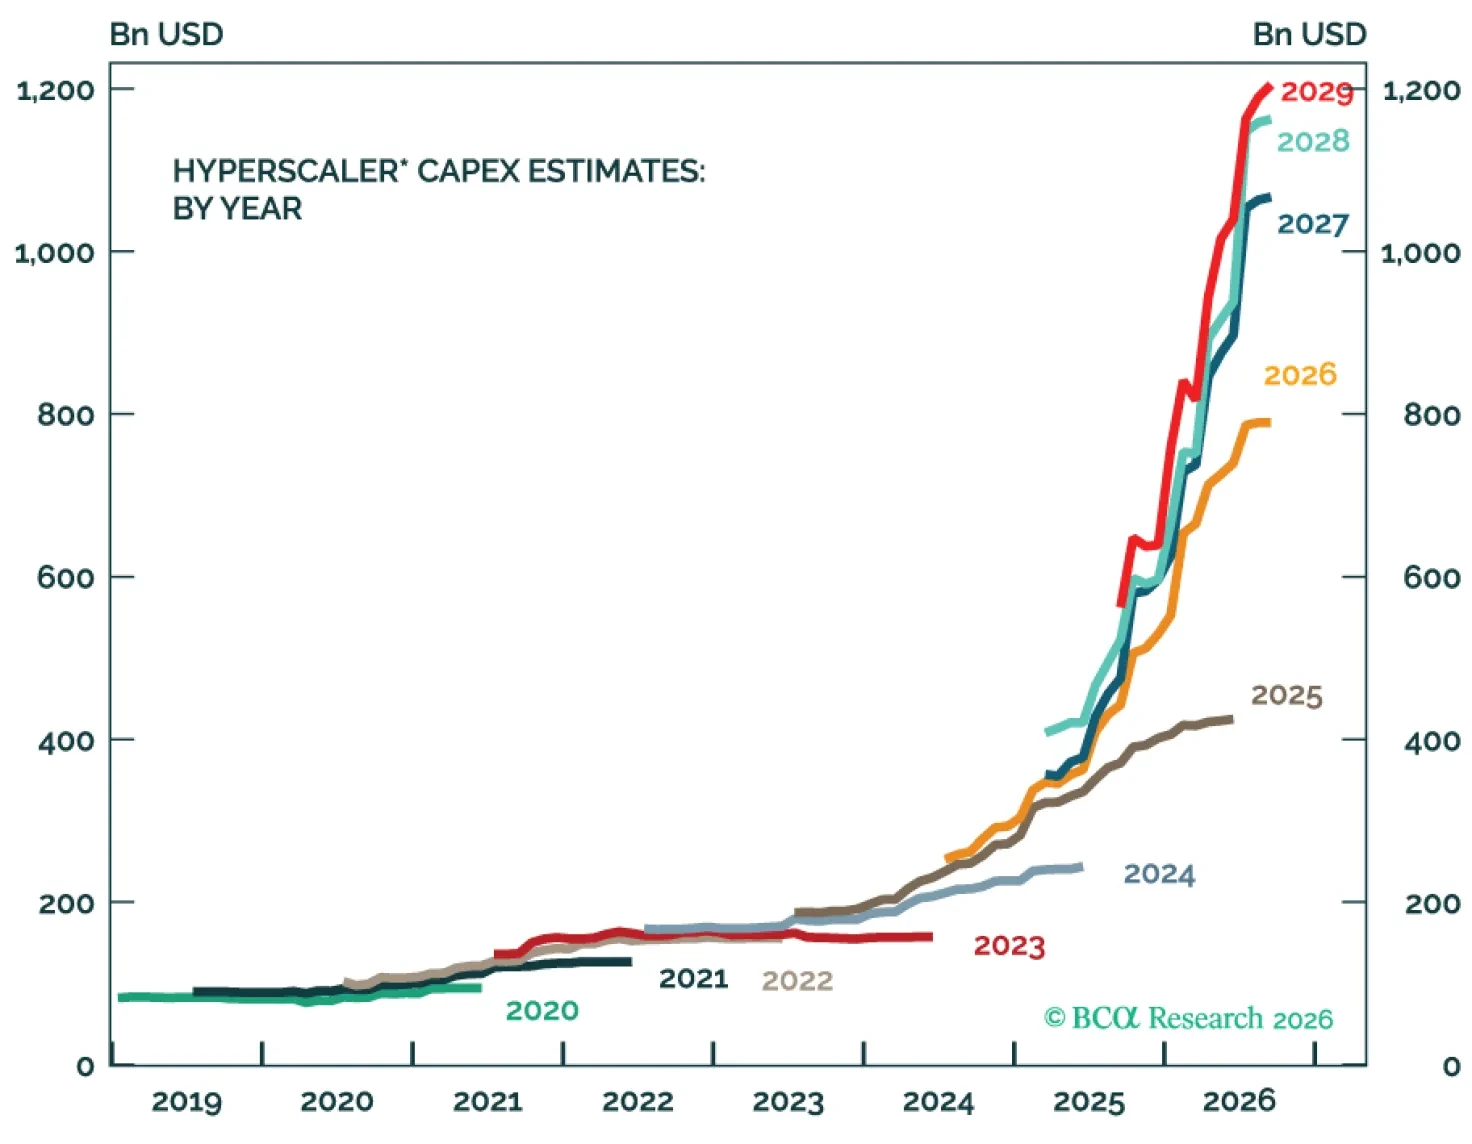
Today's report examines several of the most interesting ideas we've heard over two weeks of meetings and calls with investors.
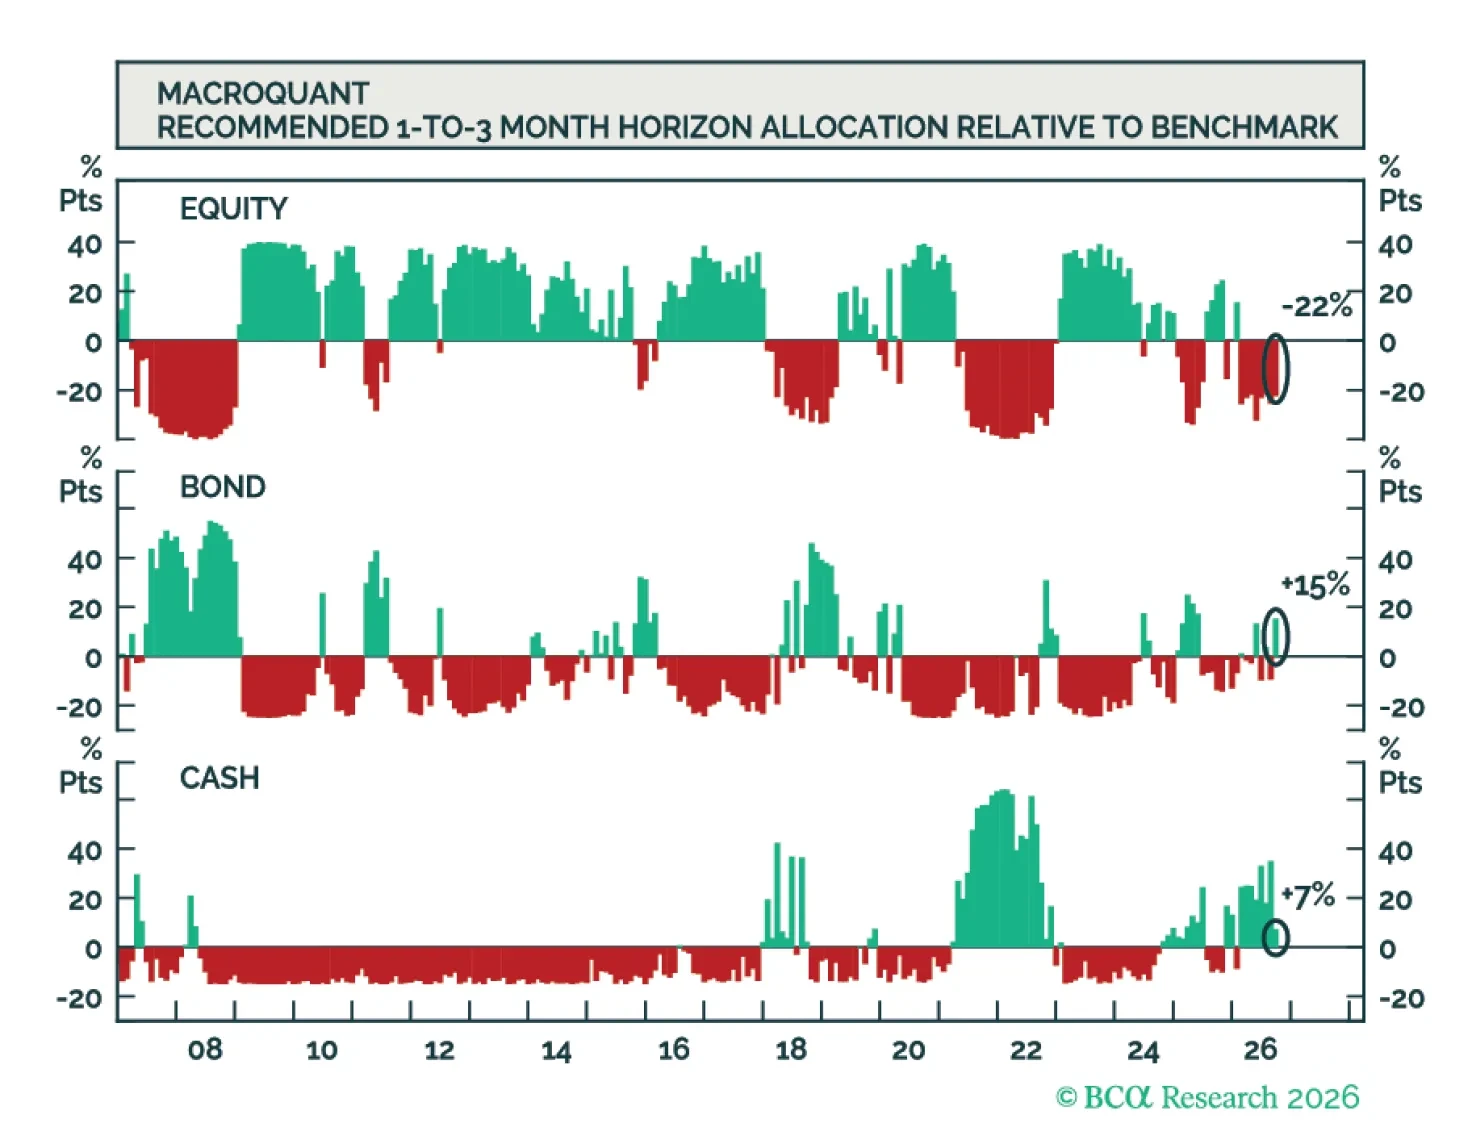
MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.
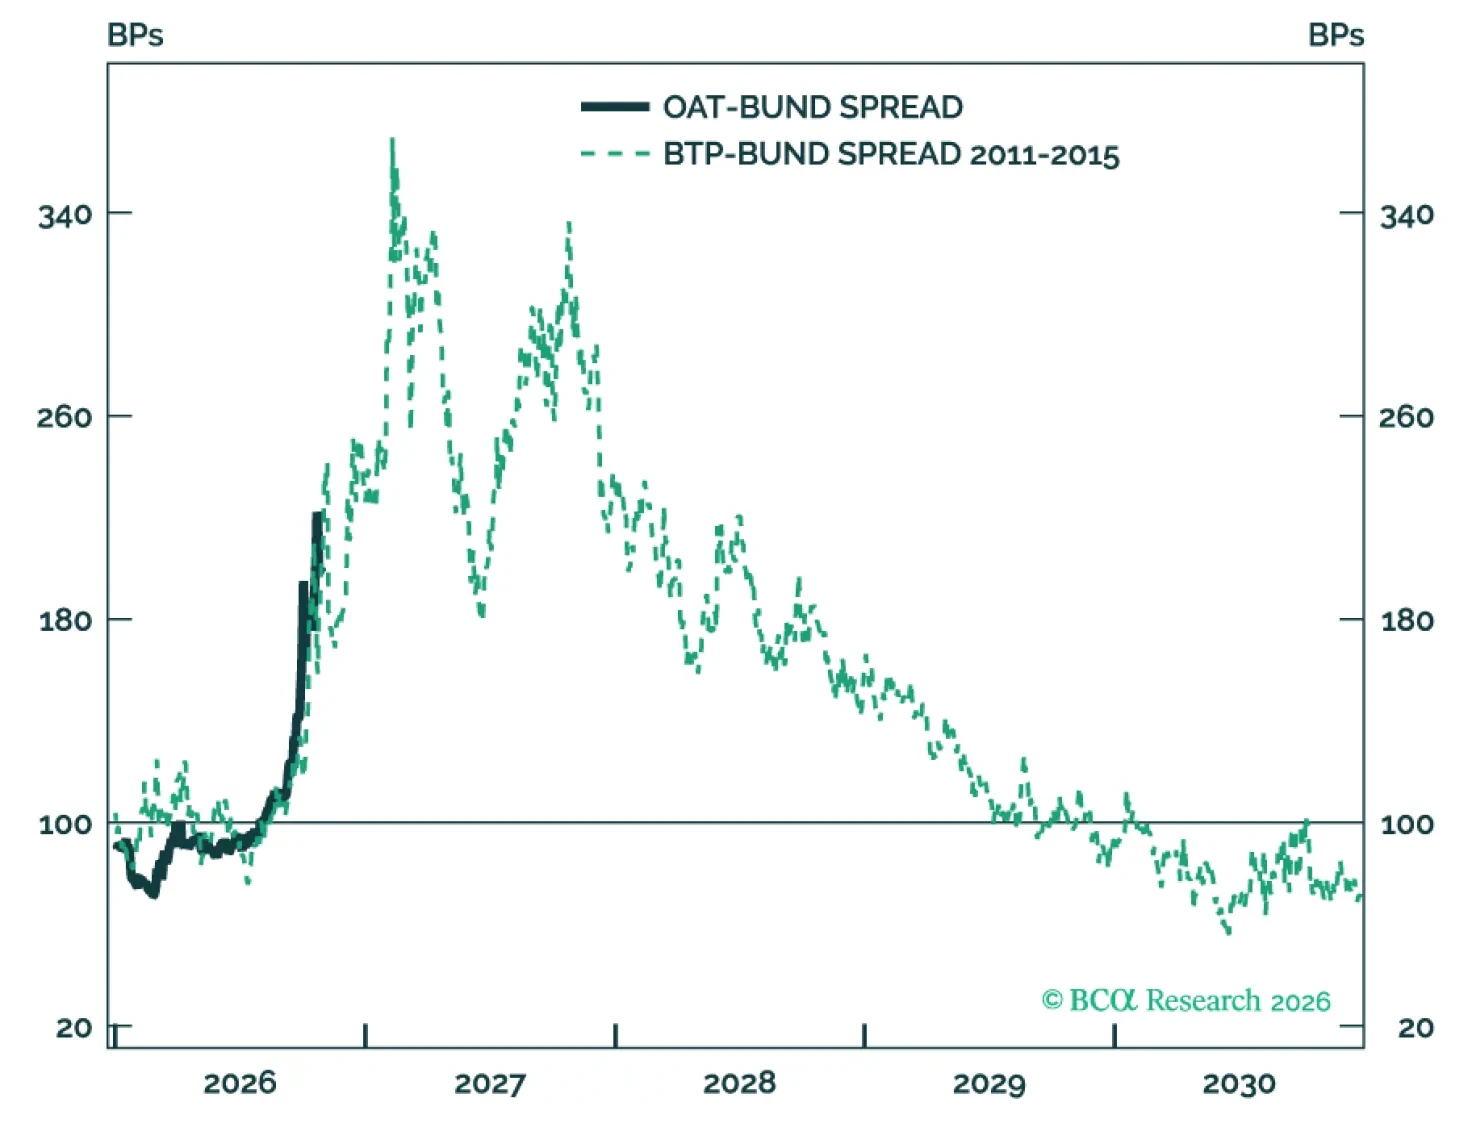
France’s fiscal mess is far from over, but the bond vigilantes may have gotten ahead of themselves. We book profits on short OATs, eyeing another opportunity in early 2027 as election risks resurface. Meanwhile, French equities are too cheap to ignore. We tactically buy on depressed valuations.
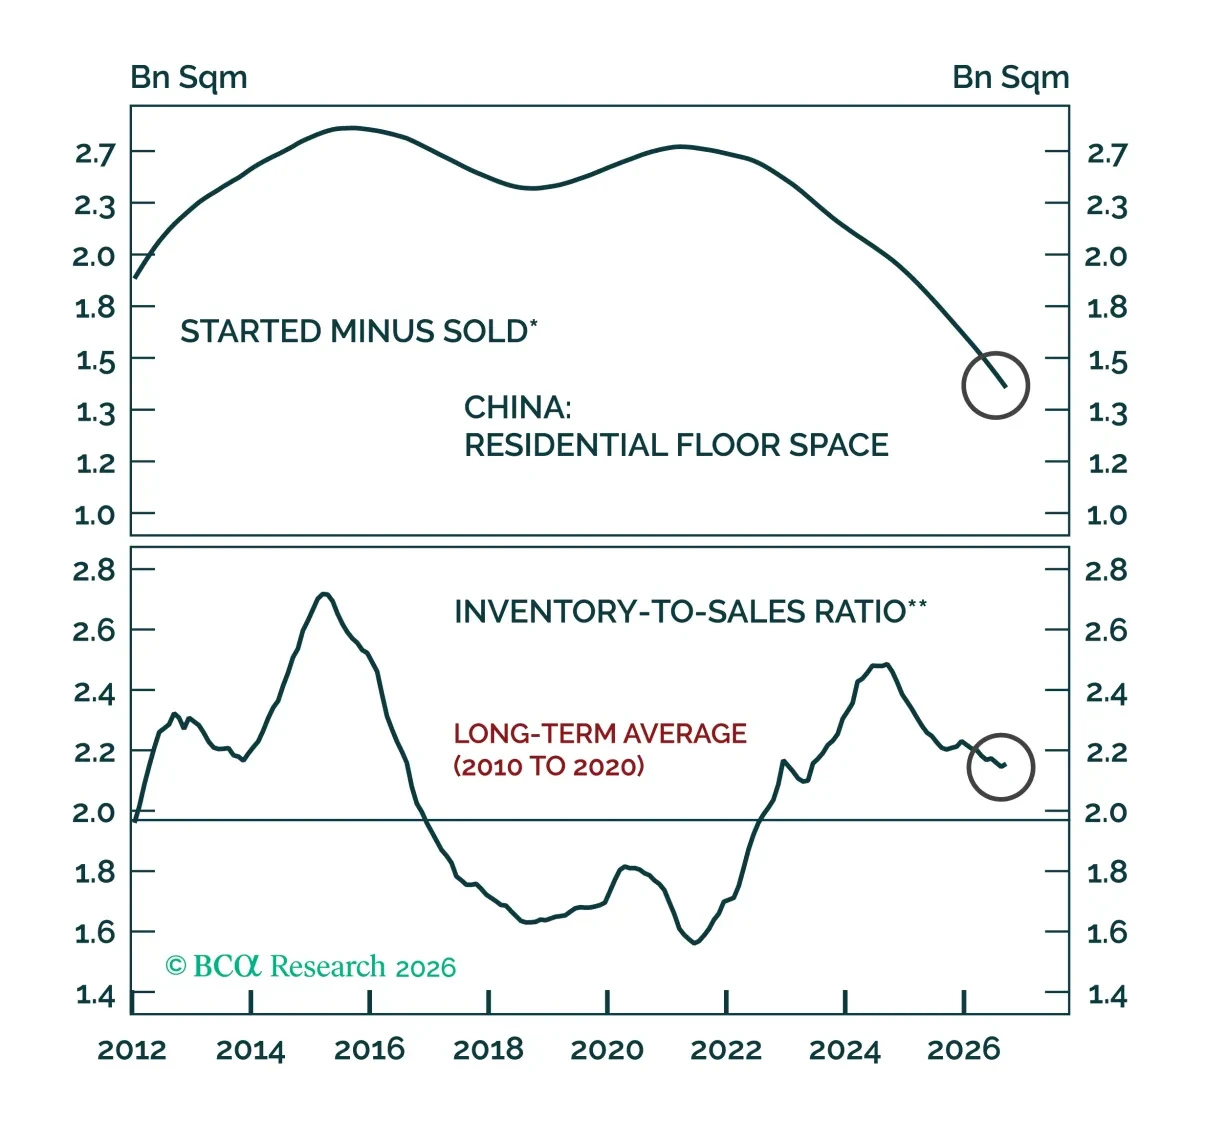
After a sharp five-year correction, China's top-tier housing markets will likely bottom out late next year. The rest of the country, however, will keep struggling with oversupply.
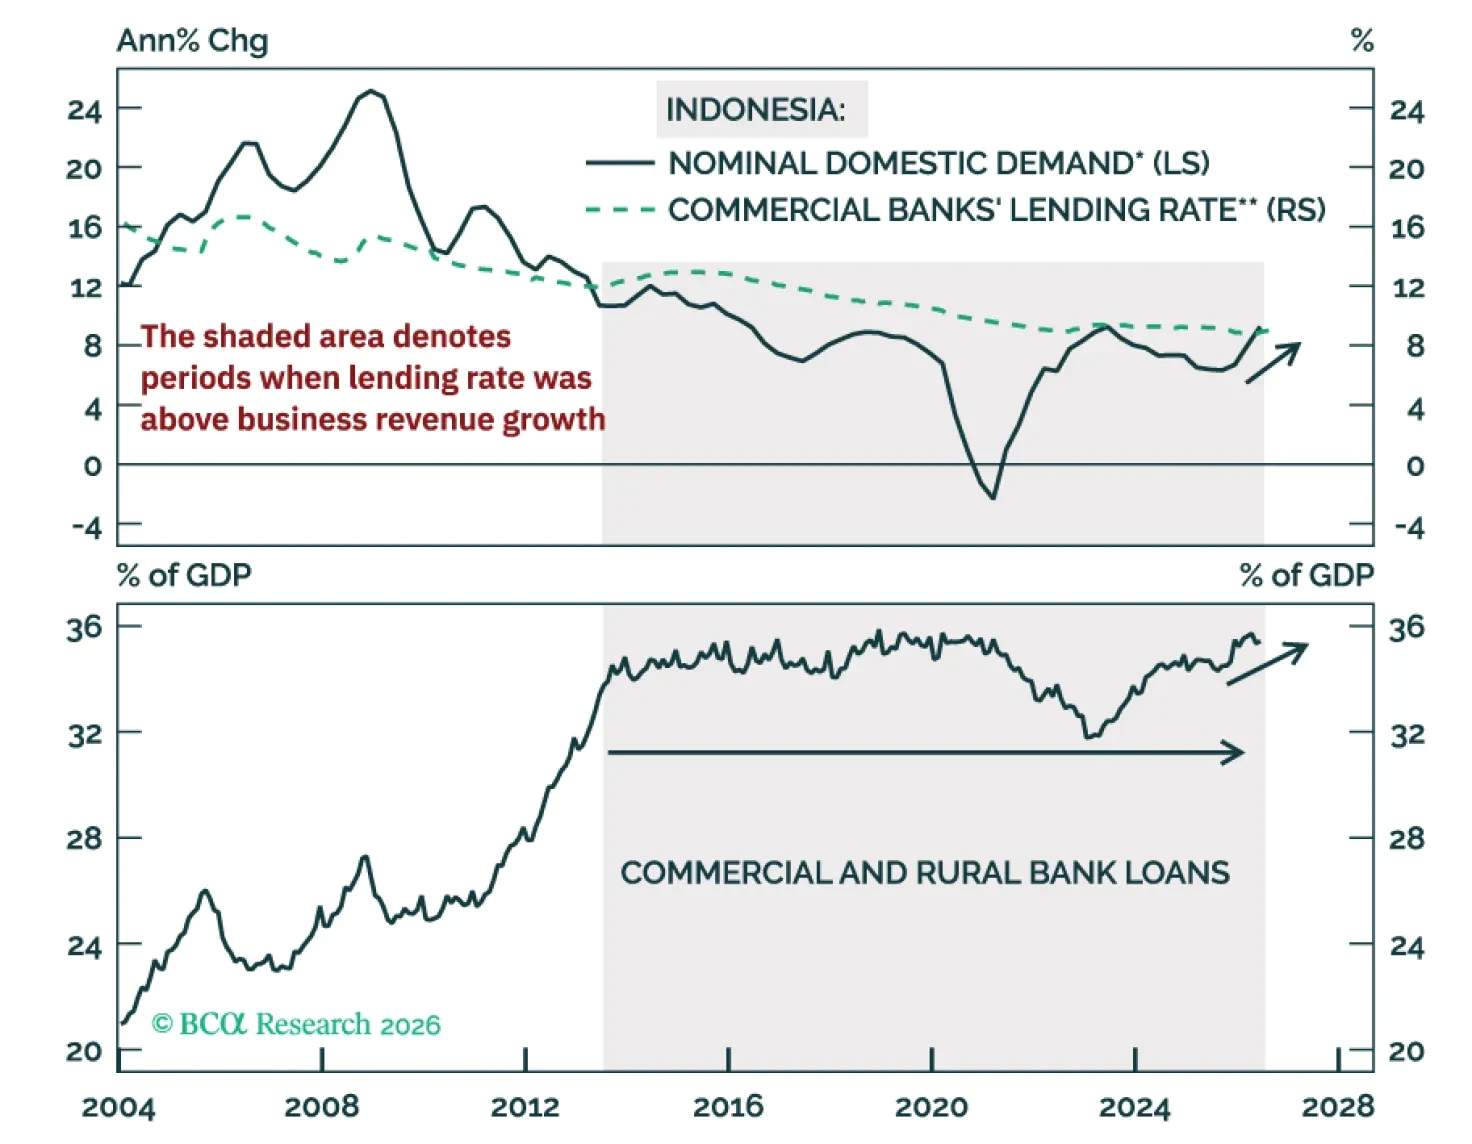
Given that the economy’s productive capacity is limited, government stimulus will lift nominal growth but do little to increase real output growth. The upshot will be rising inflation and wider twin deficits. This is bearish for the currency, bonds, and stocks.
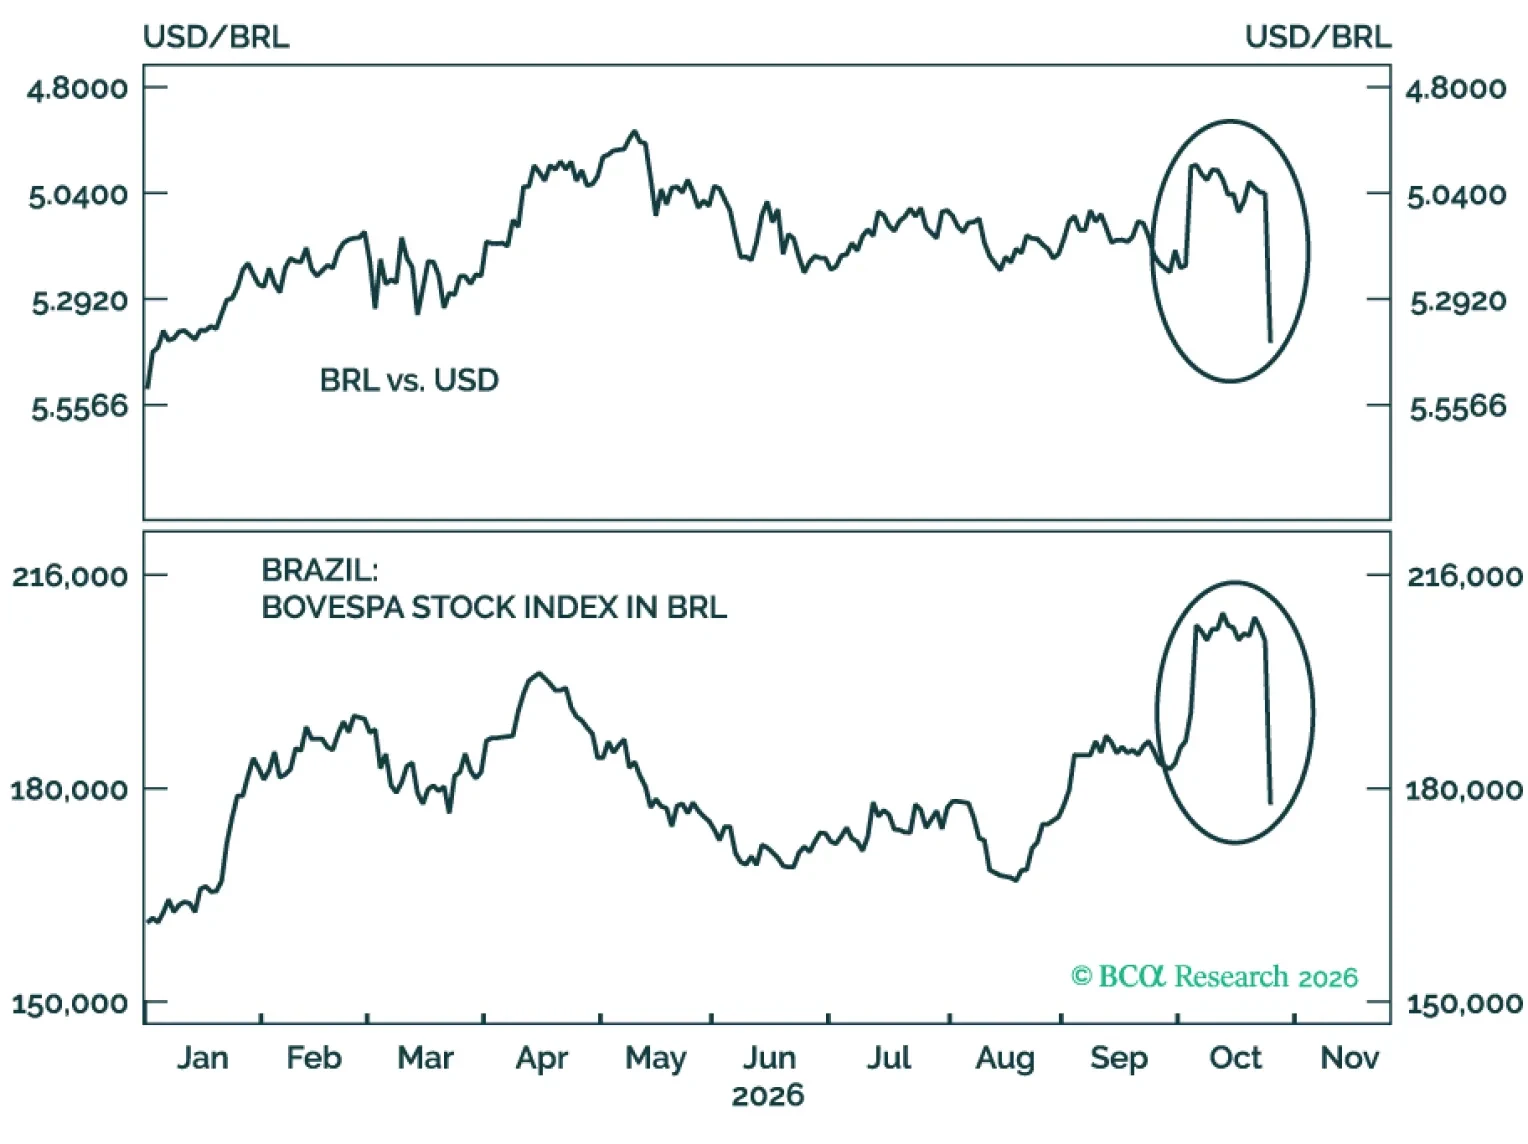
Brazil’s elections have turned into a game of roulette for investors. Bulls and bears were each wrong-footed between the first and second rounds of elections. We are downgrading Brazilian equities, local bonds, and sovereign credit to underweight within their respective EM portfolios.