 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
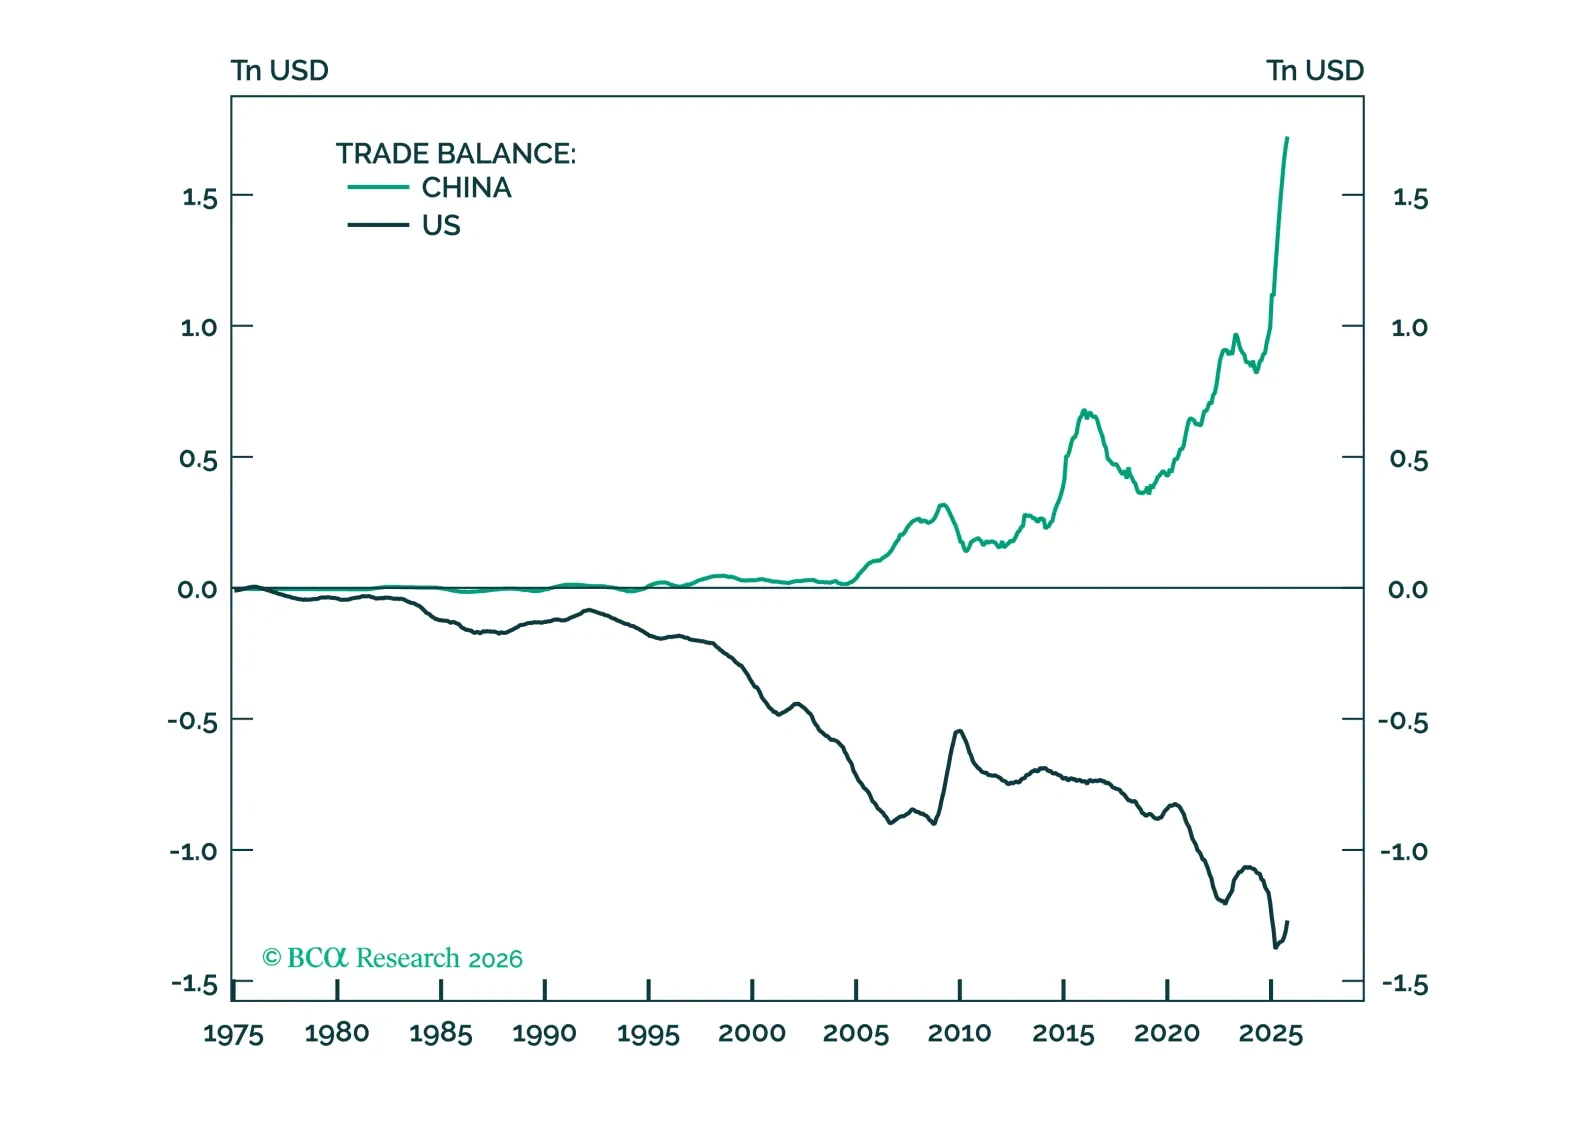
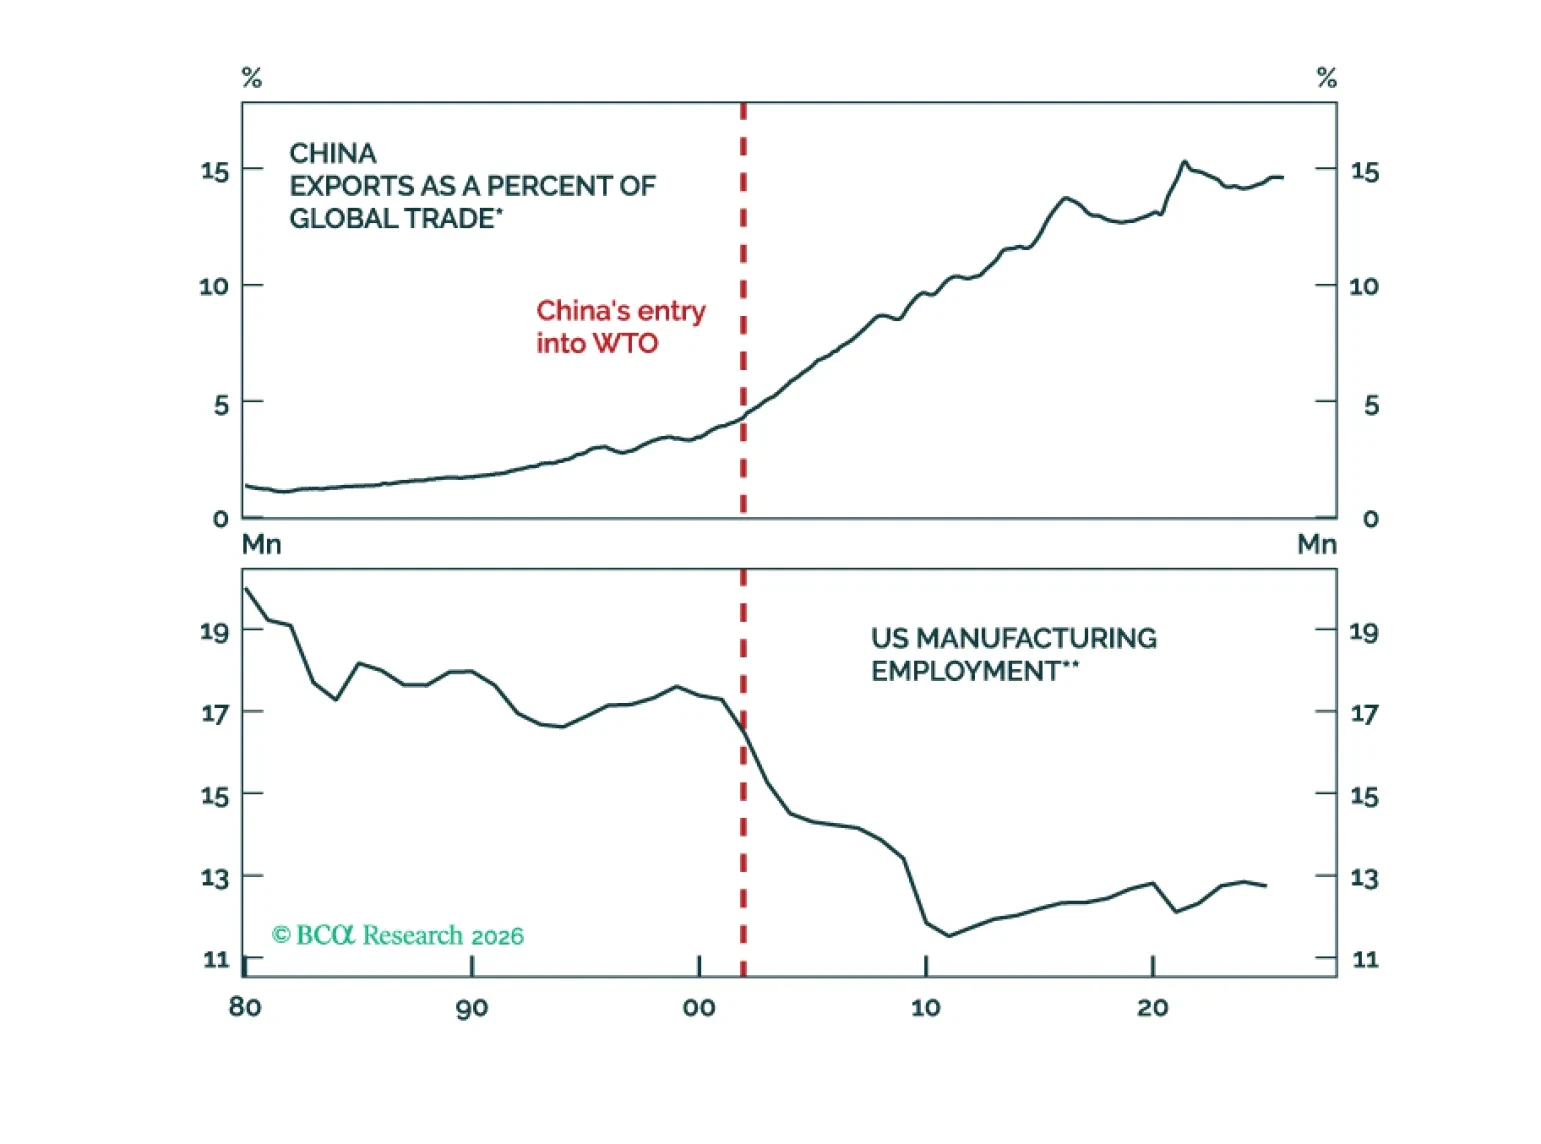
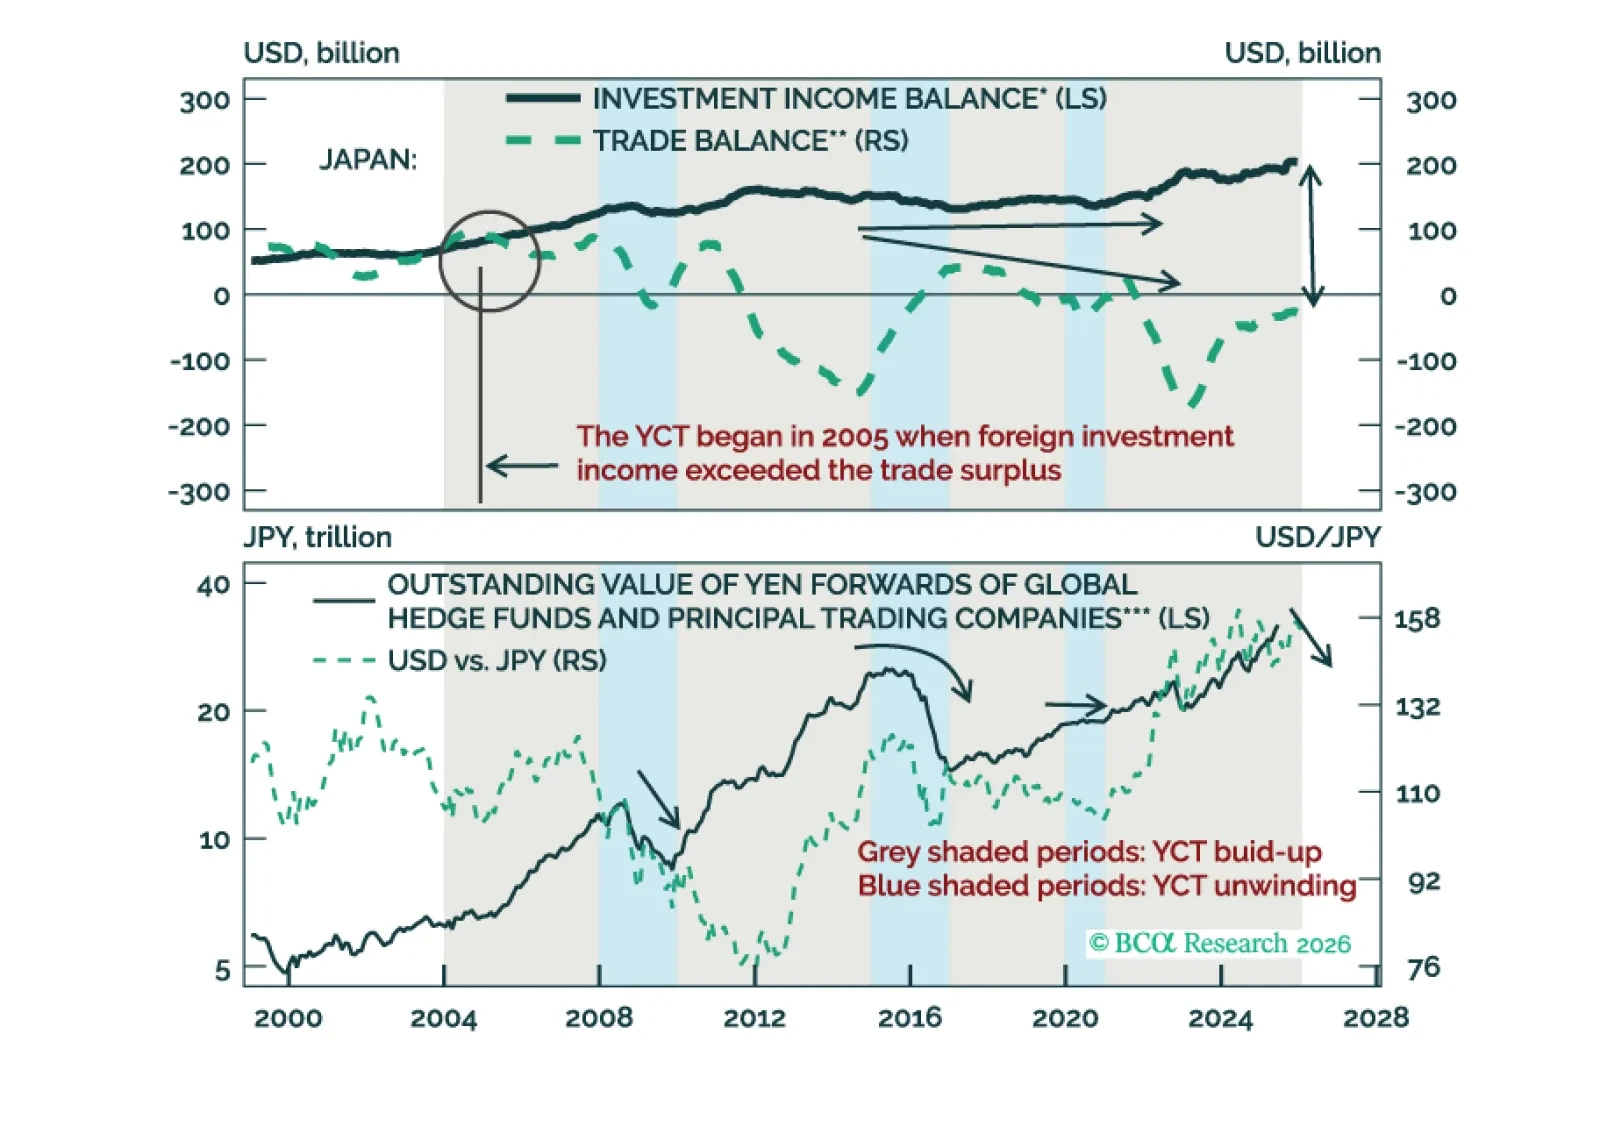
The CNY is undervalued and highly competitive. This gives China room to let the currency appreciate while remaining an export-driven powerhouse, gradually shifting from export intensity toward stronger domestic consumption. This achieves two objectives. First, it narrows the capital account deficit and strengthens the CNY’s role as a global anchor. Second, it enhances Beijing’s geopolitical autonomy by reducing reliance on foreign final demand.
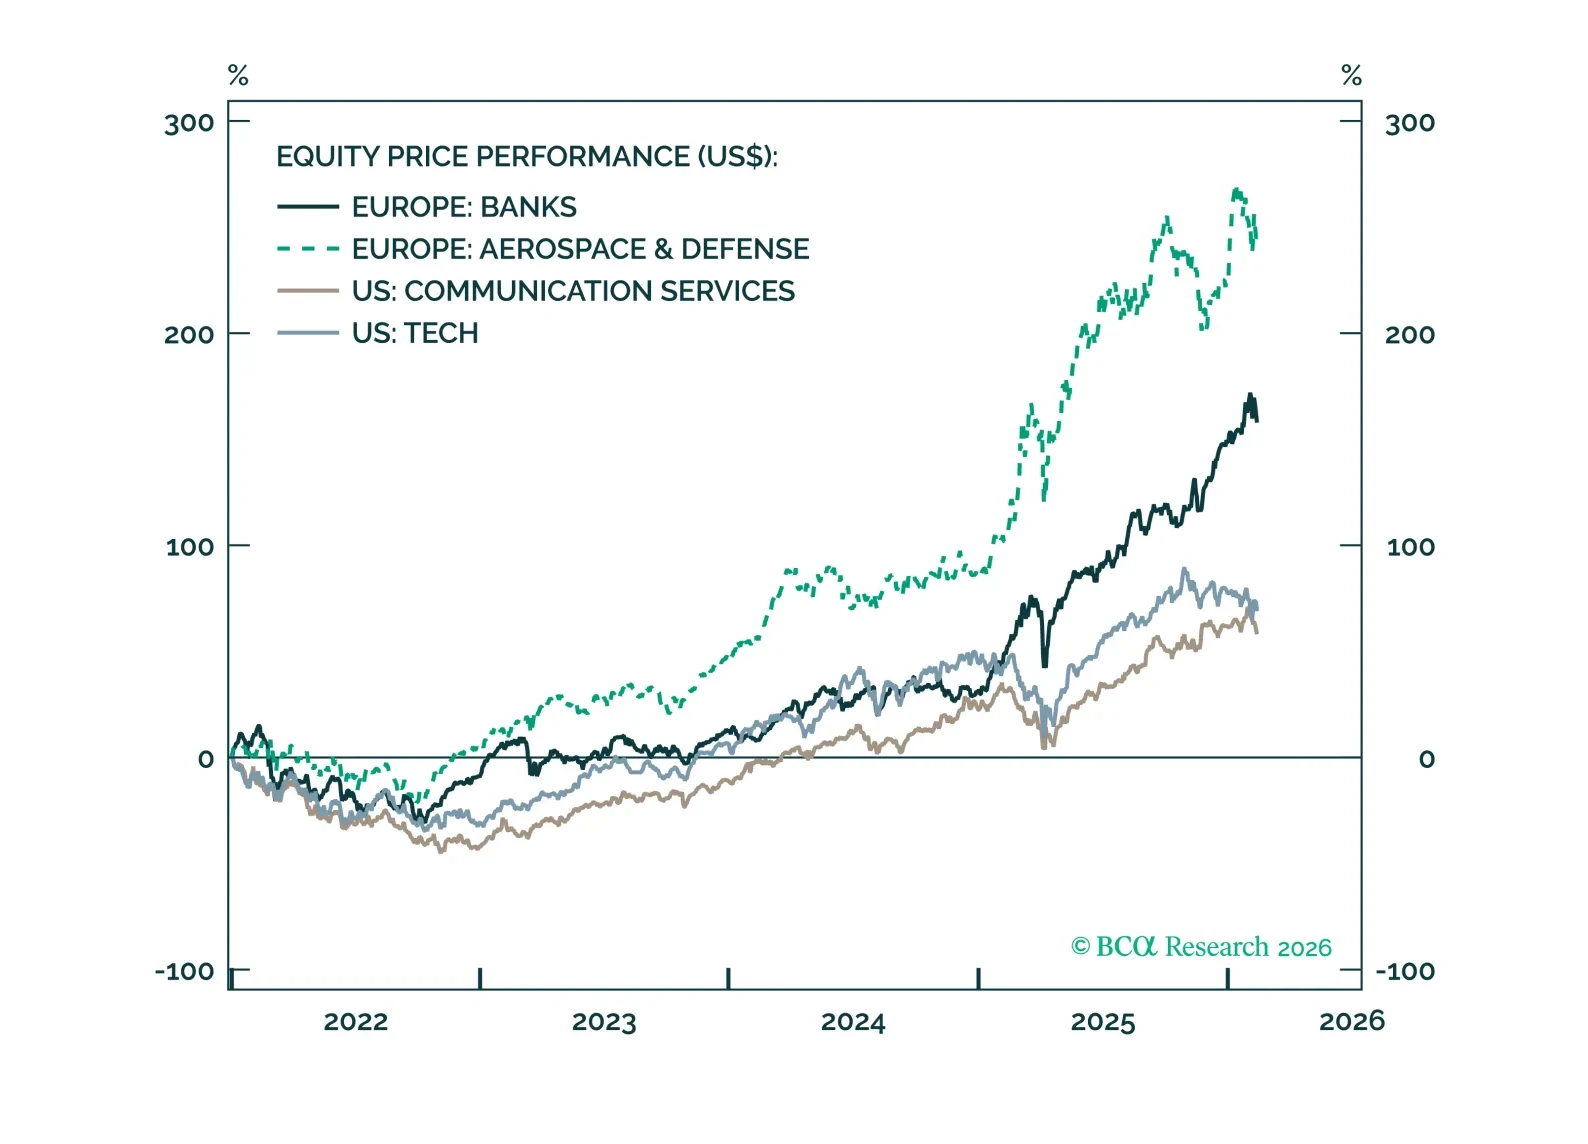
The near-term outlook is less supportive for European banks and defense equities. We downgrade banks to neutral and continue to expect defense stocks to trade in a “sell the rumor, buy the news” pattern.
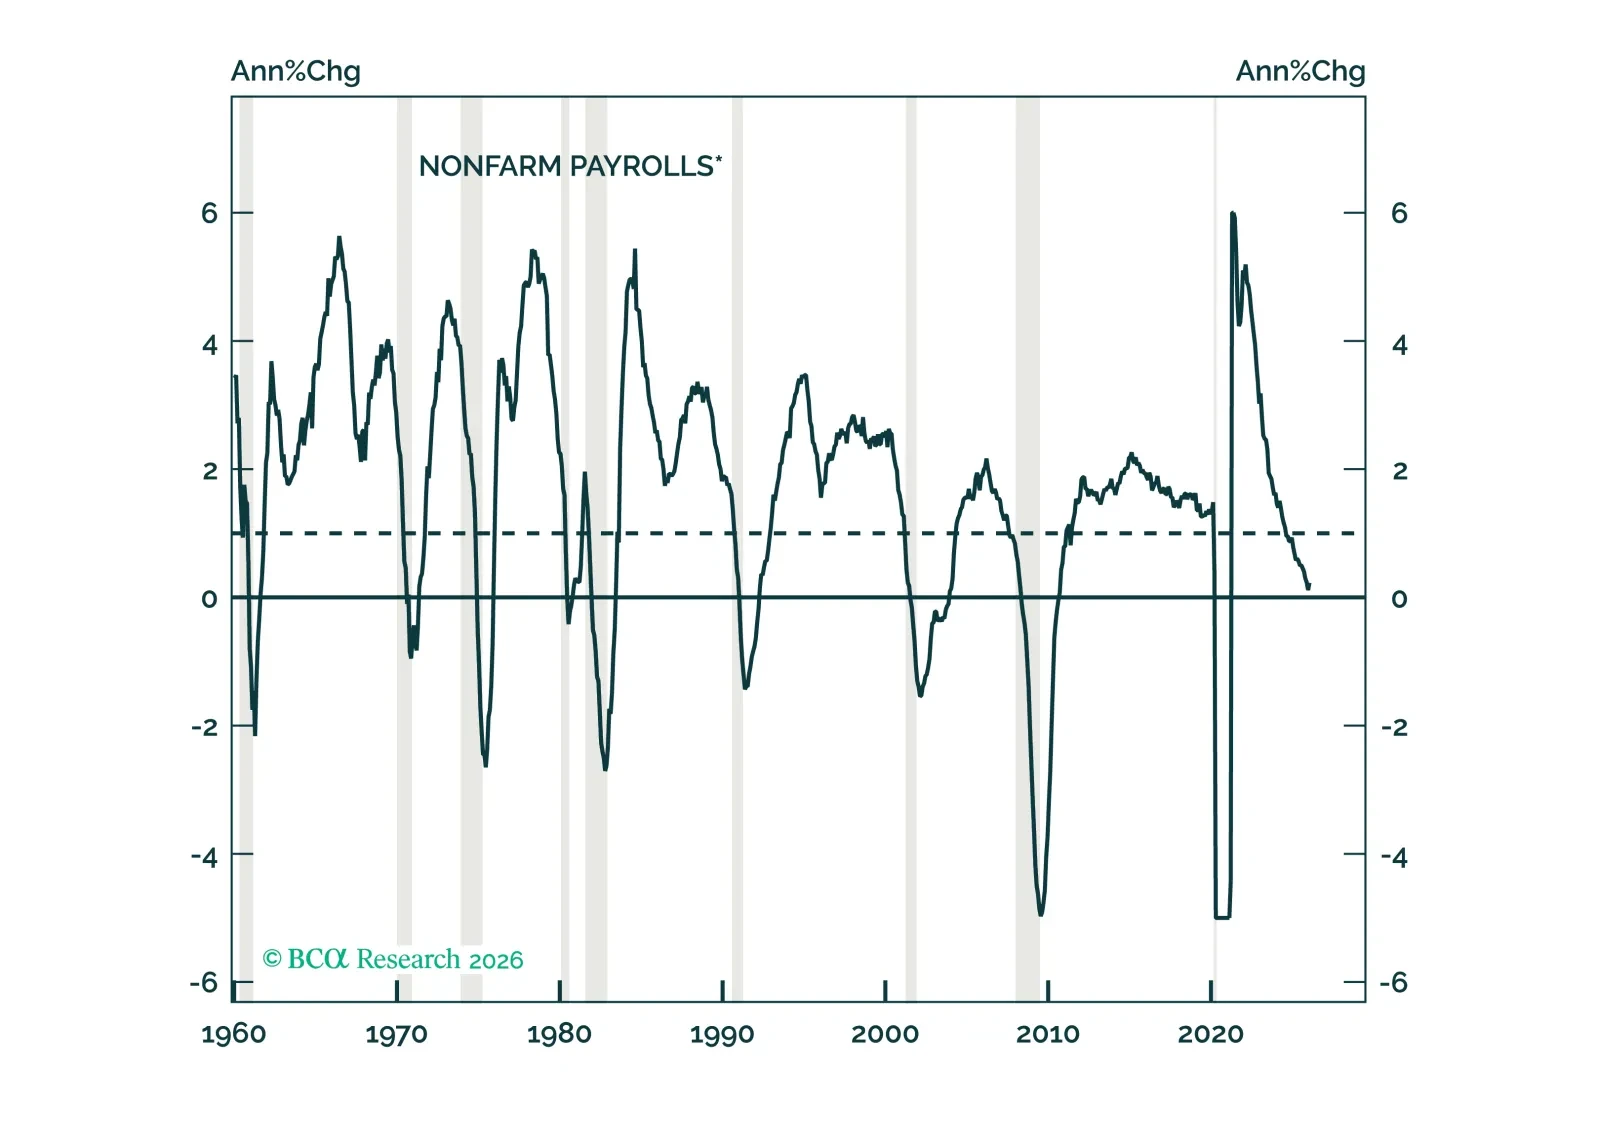
The annual benchmark payrolls revisions revealed that the labor market has been weaker for longer than initially reported. The probability that a crack in consumption is just around the corner is much reduced and we have therefore dialed back our recession expectations. Though our asset allocation recommendations remain neutral across the board, we are more optimistic than we were at the beginning of the year.
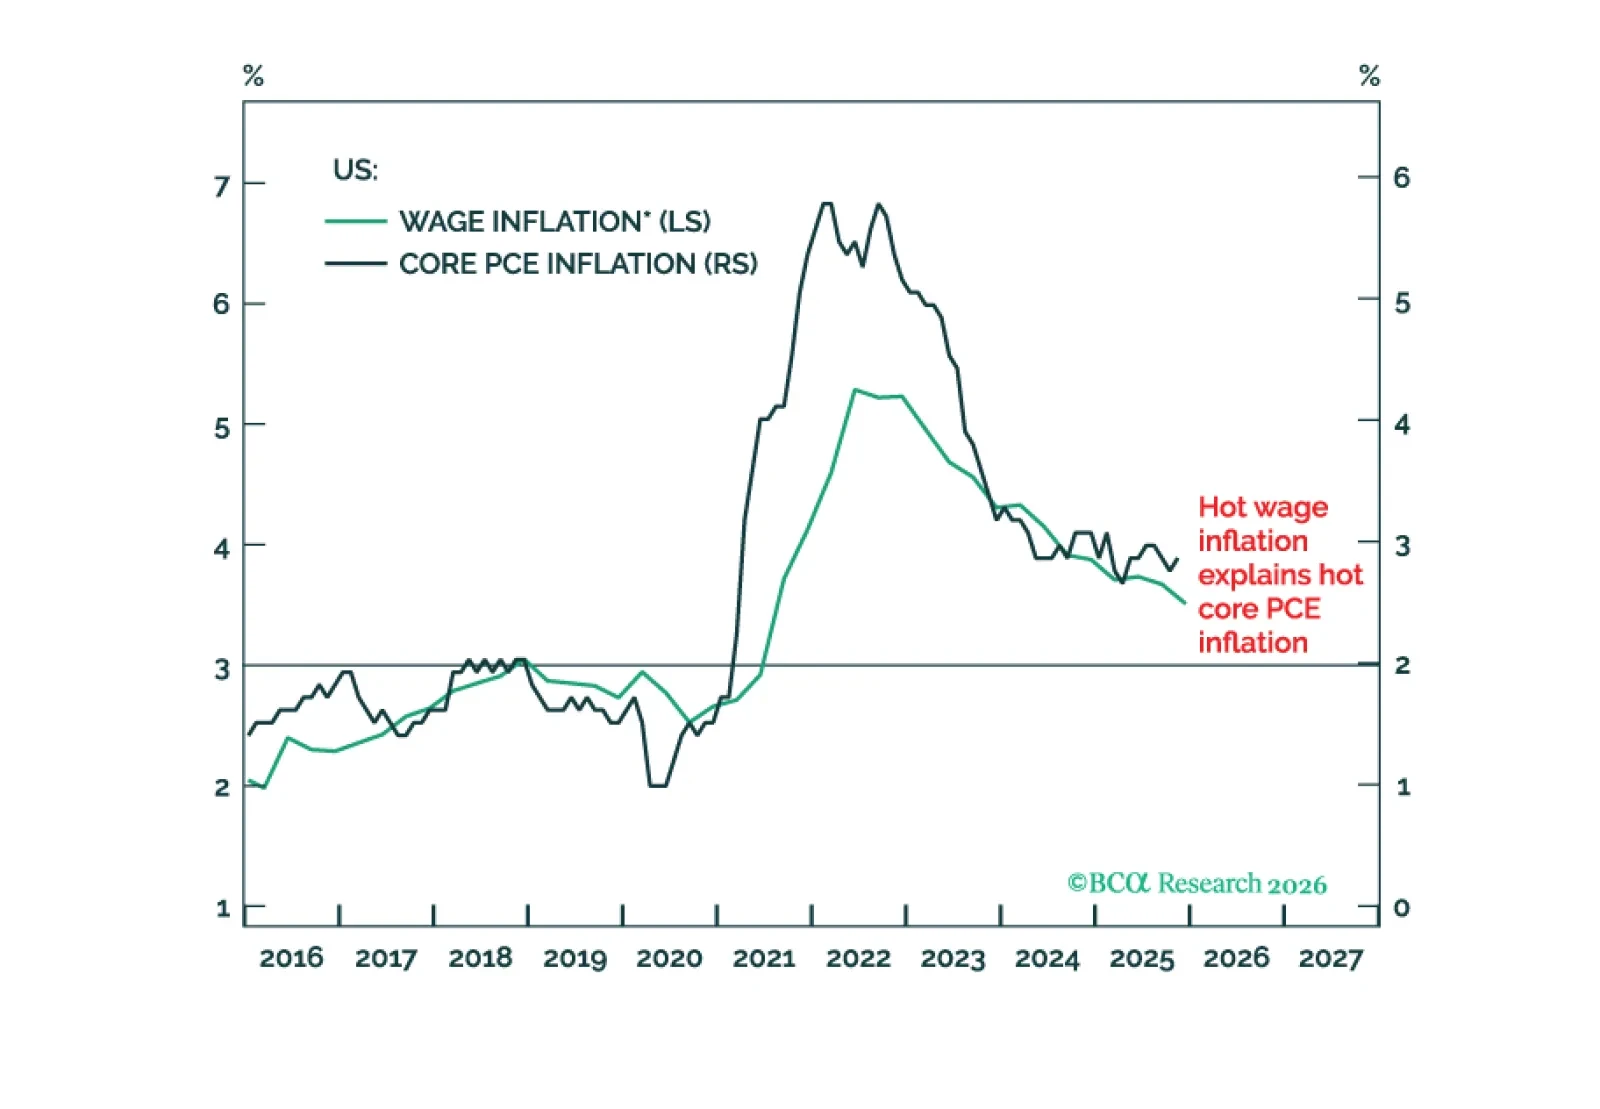
The Warsh Fed will run the US economy hot. This is bad for T-bonds and the dollar, but good for stocks. Plus, a new tactical trade is overweight Consumer Discretionary (RXI) versus Industrials (EXI).

The January jobs report was unambiguously strong. Although the 172K gain in private payrolls will almost certainly be revised down, the message from the "ratios" was reassuring: The unemployment rate fell for a second straight month, the labor force participation rate increased, the share of workers who are involuntarily part-time declined, and the prime-age employment-to-population ratio rose back to its all-time high. Unlike the payroll survey, the household survey from which ratios are calculated is subject to minimal revisions.
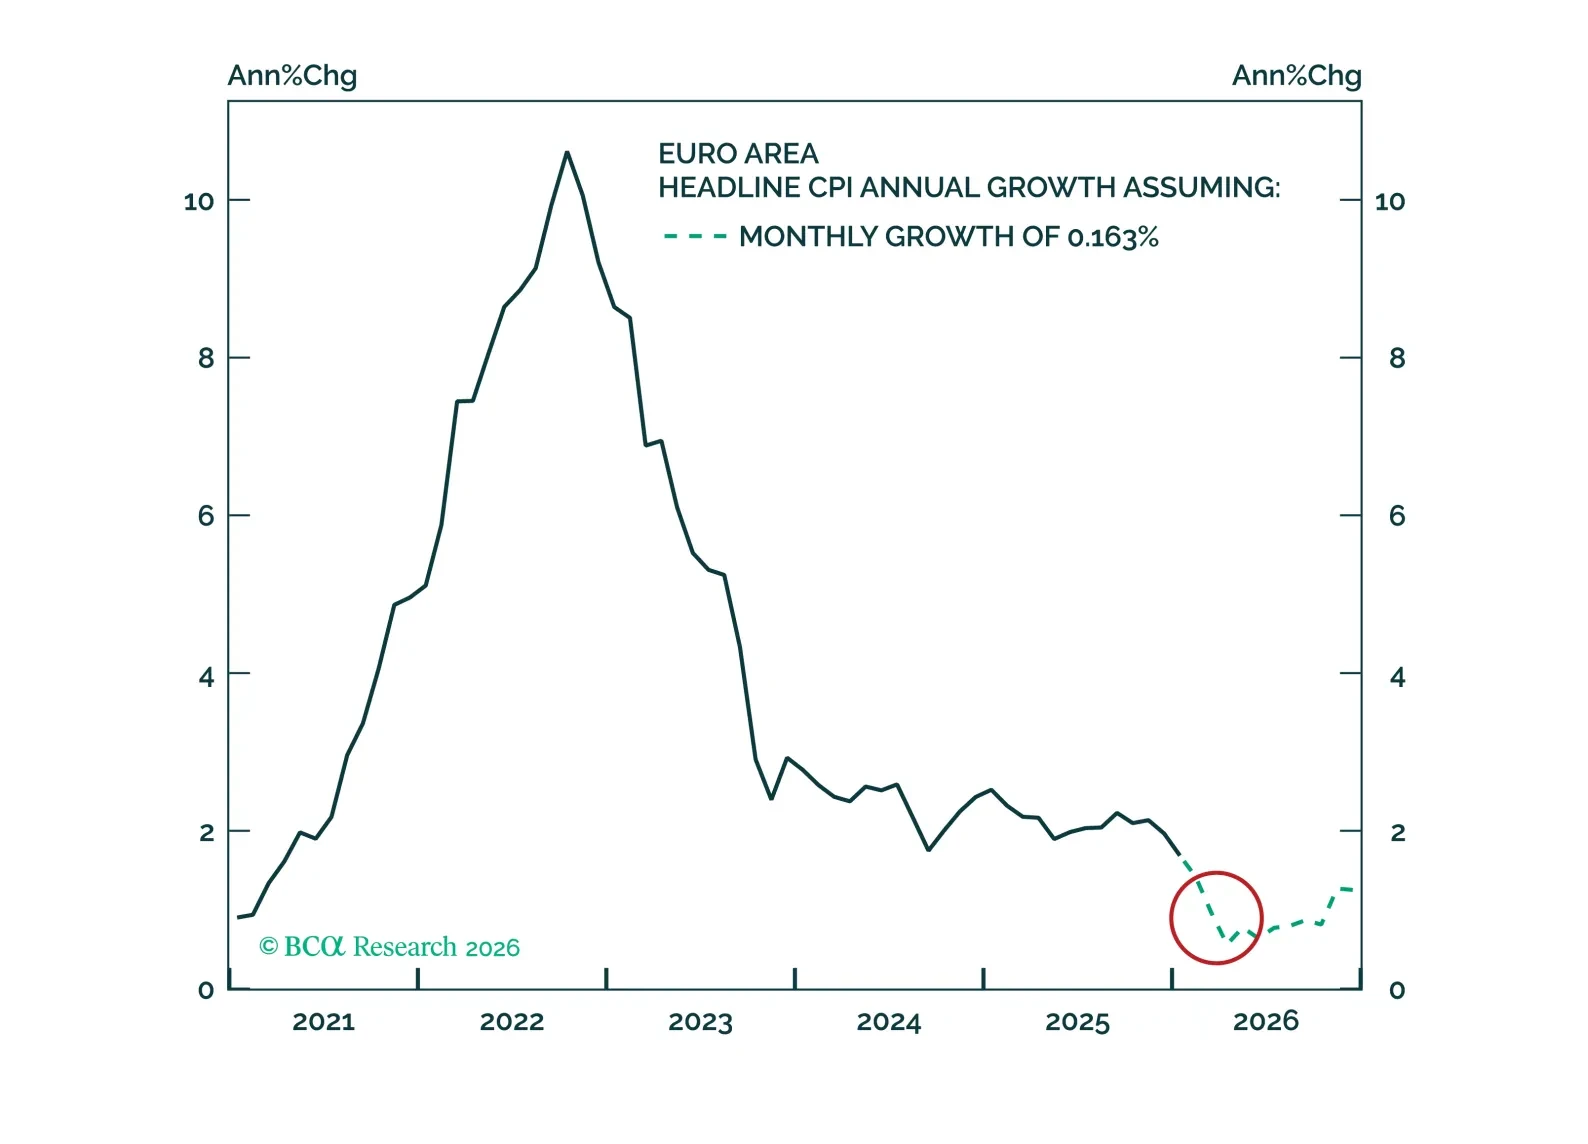
The ECB is about to make its first policy mistake in the current cycle by being complacent about the downside risks to inflation. The confluence of base effects, a stronger euro, food and energy deflation, and rapid services disinflation will push headline inflation closer to 1% in the first half of the year. This significant undershoot will force the ECB to deliver reflationary cuts. Go long the September 2026 3-month Euribor futures and tactically reduce exposure to inflation-linked bonds in the Eurozone.
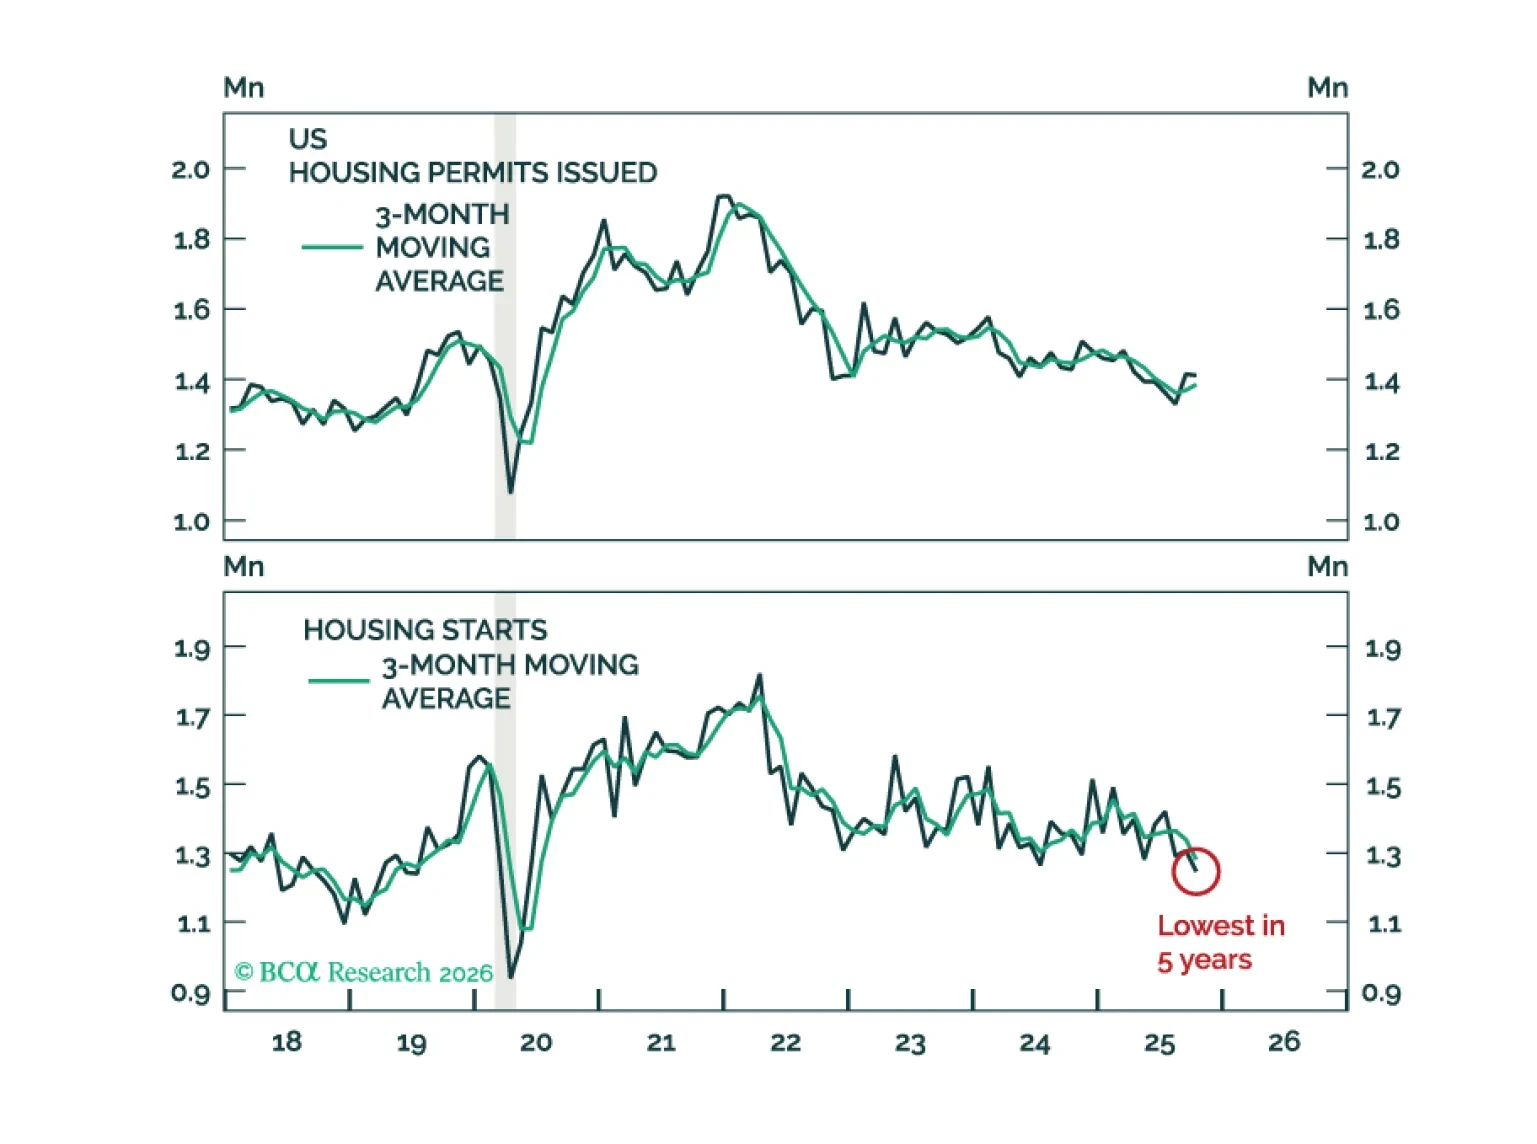
The US residential real estate market remains soft. While the decline in mortgage rates is a positive, it is too early to bet on housing becoming the engine of growth for the US economy this year.