CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
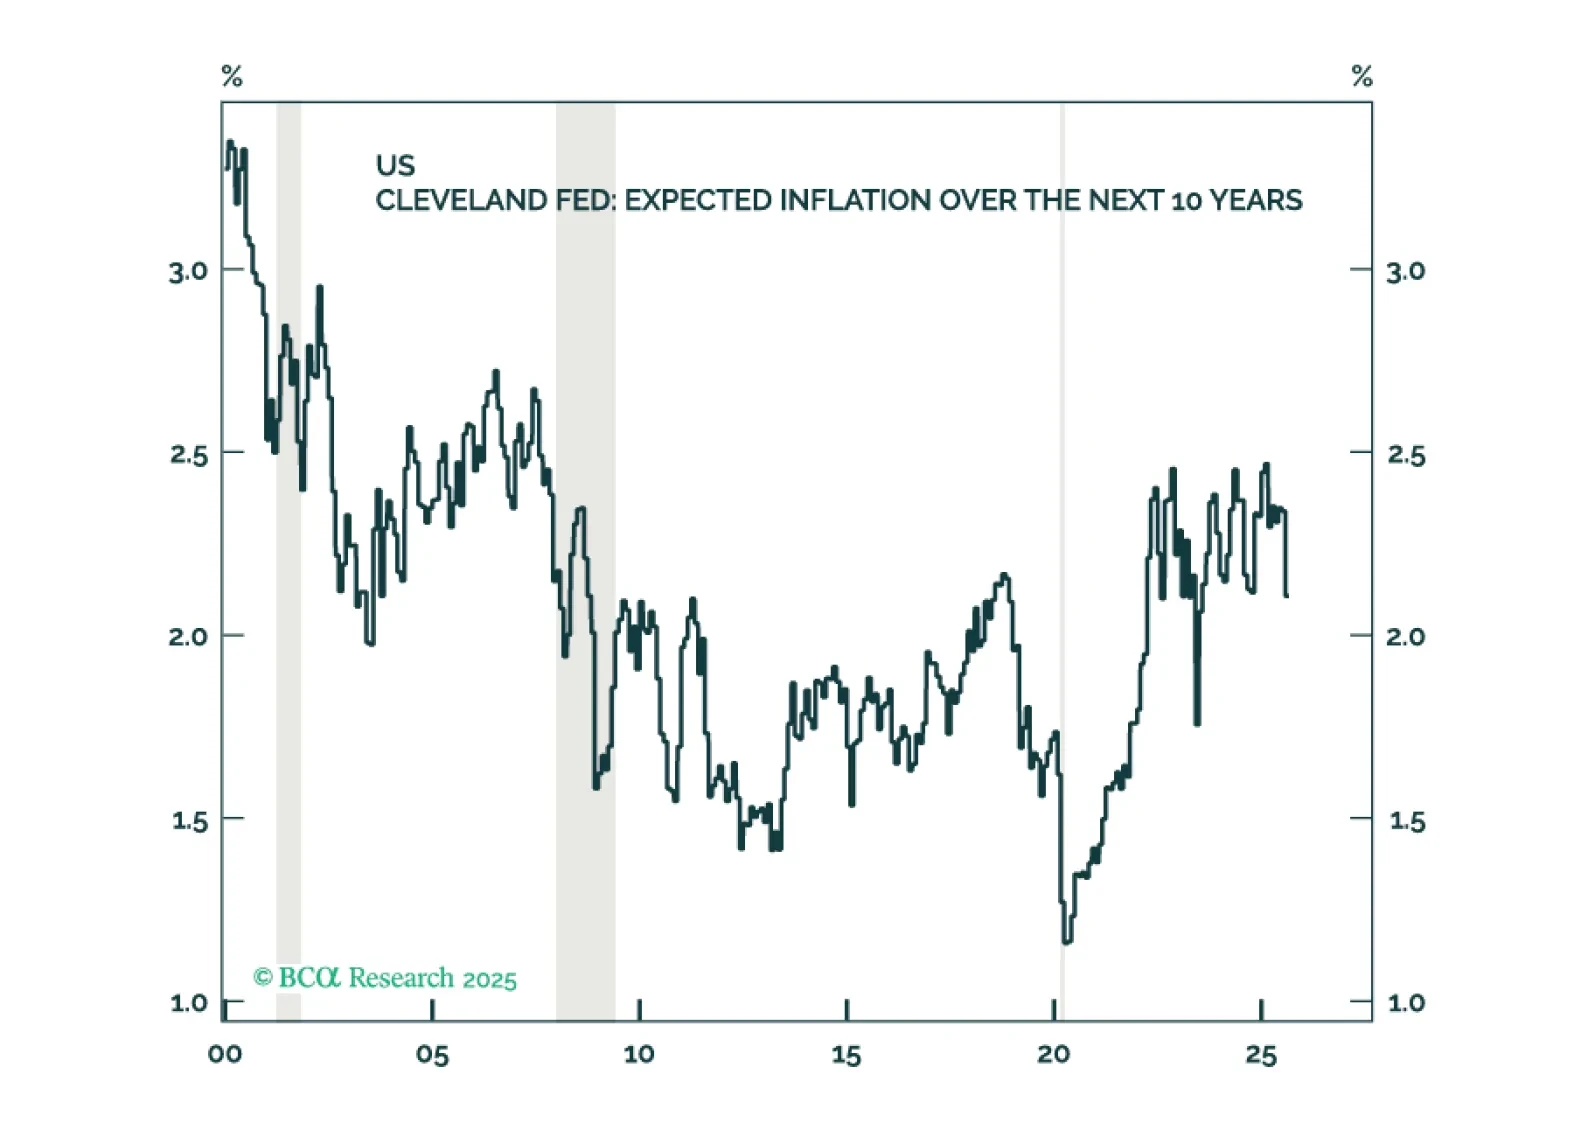
Inflation expectations in the US remain reasonably well anchored and there are few signs of a brewing wage-price spiral. Thus, the near-term risks to growth outweigh the risks of higher inflation. Looking beyond the next year or two, however, we are worried about stagflation.
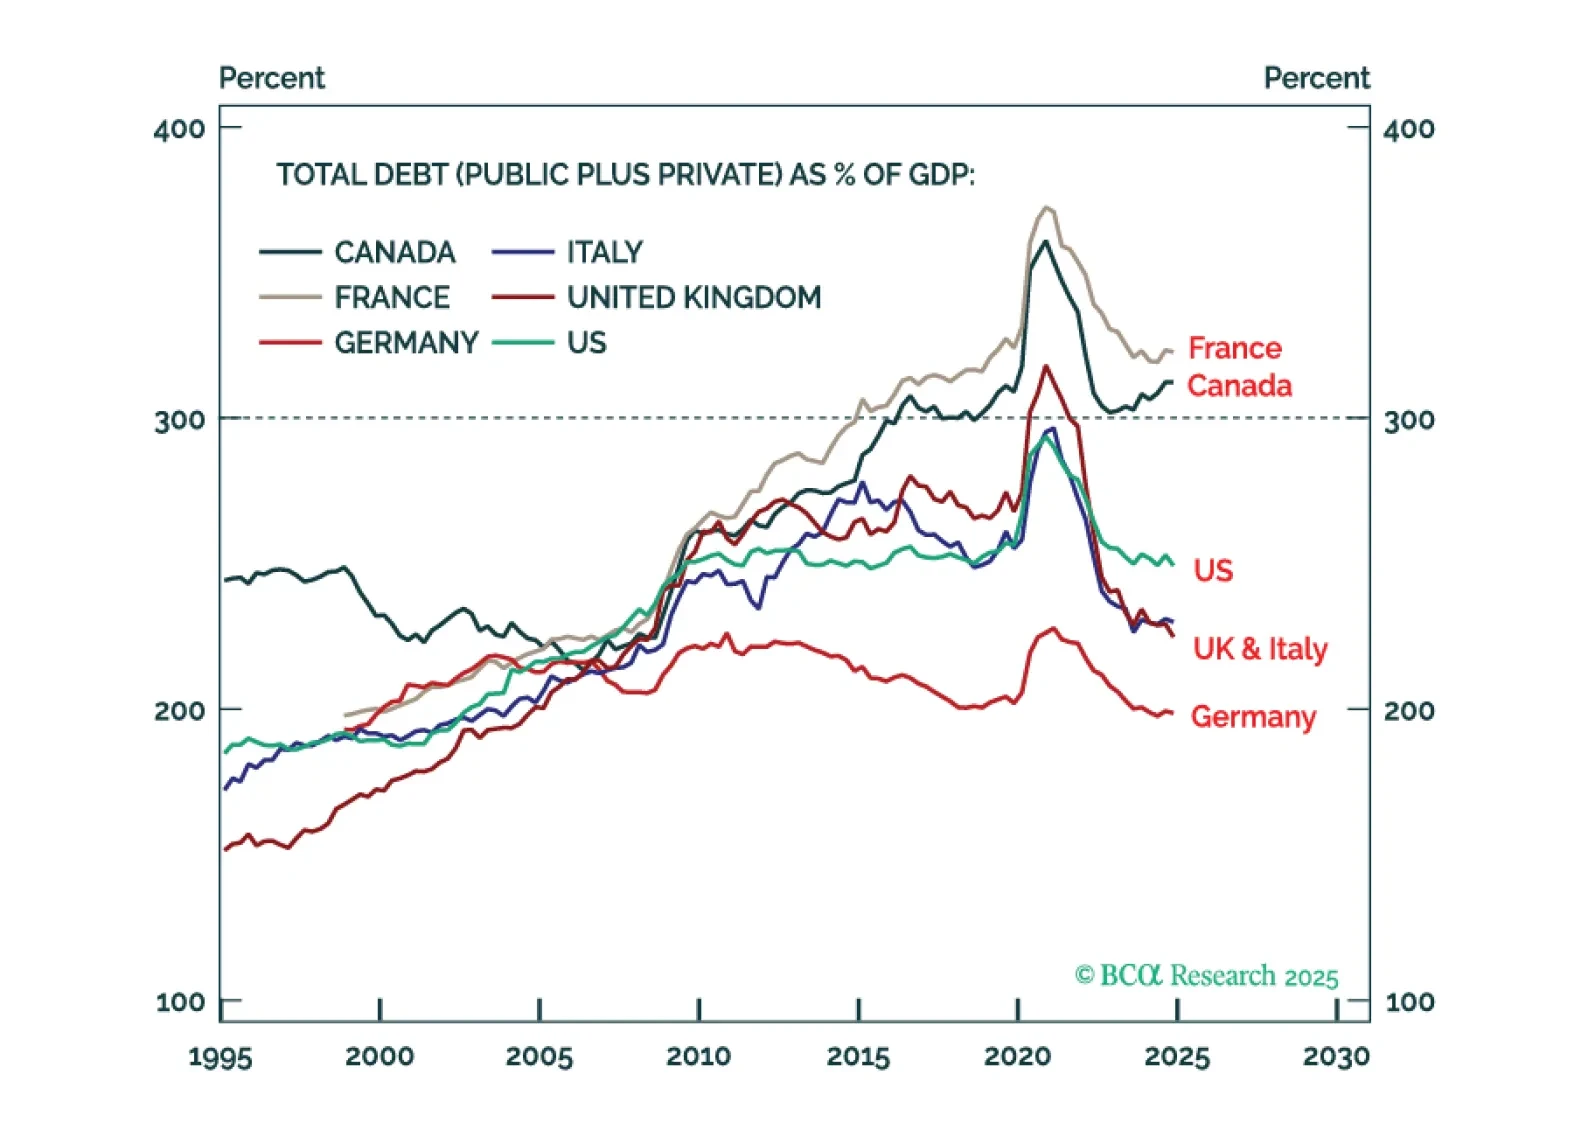
The bond vigilantes are circling over several targets right now: France, the UK, and Japan. But France is the most vulnerable because of a toxic combination: a total debt ratio well above 300 percent plus the worst primary deficit in the G7 plus political gridlock, which will get even worse if Prime Minister Francois Bayrou loses the September 8th vote of confidence in his minority government. We explain why the ECB cannot save France, and the investment implications. Plus, we unveil our brand-new complexity ‘heat map’ for global asset allocation which leads to a new tactical trade to underweight world communication services (WTEL).
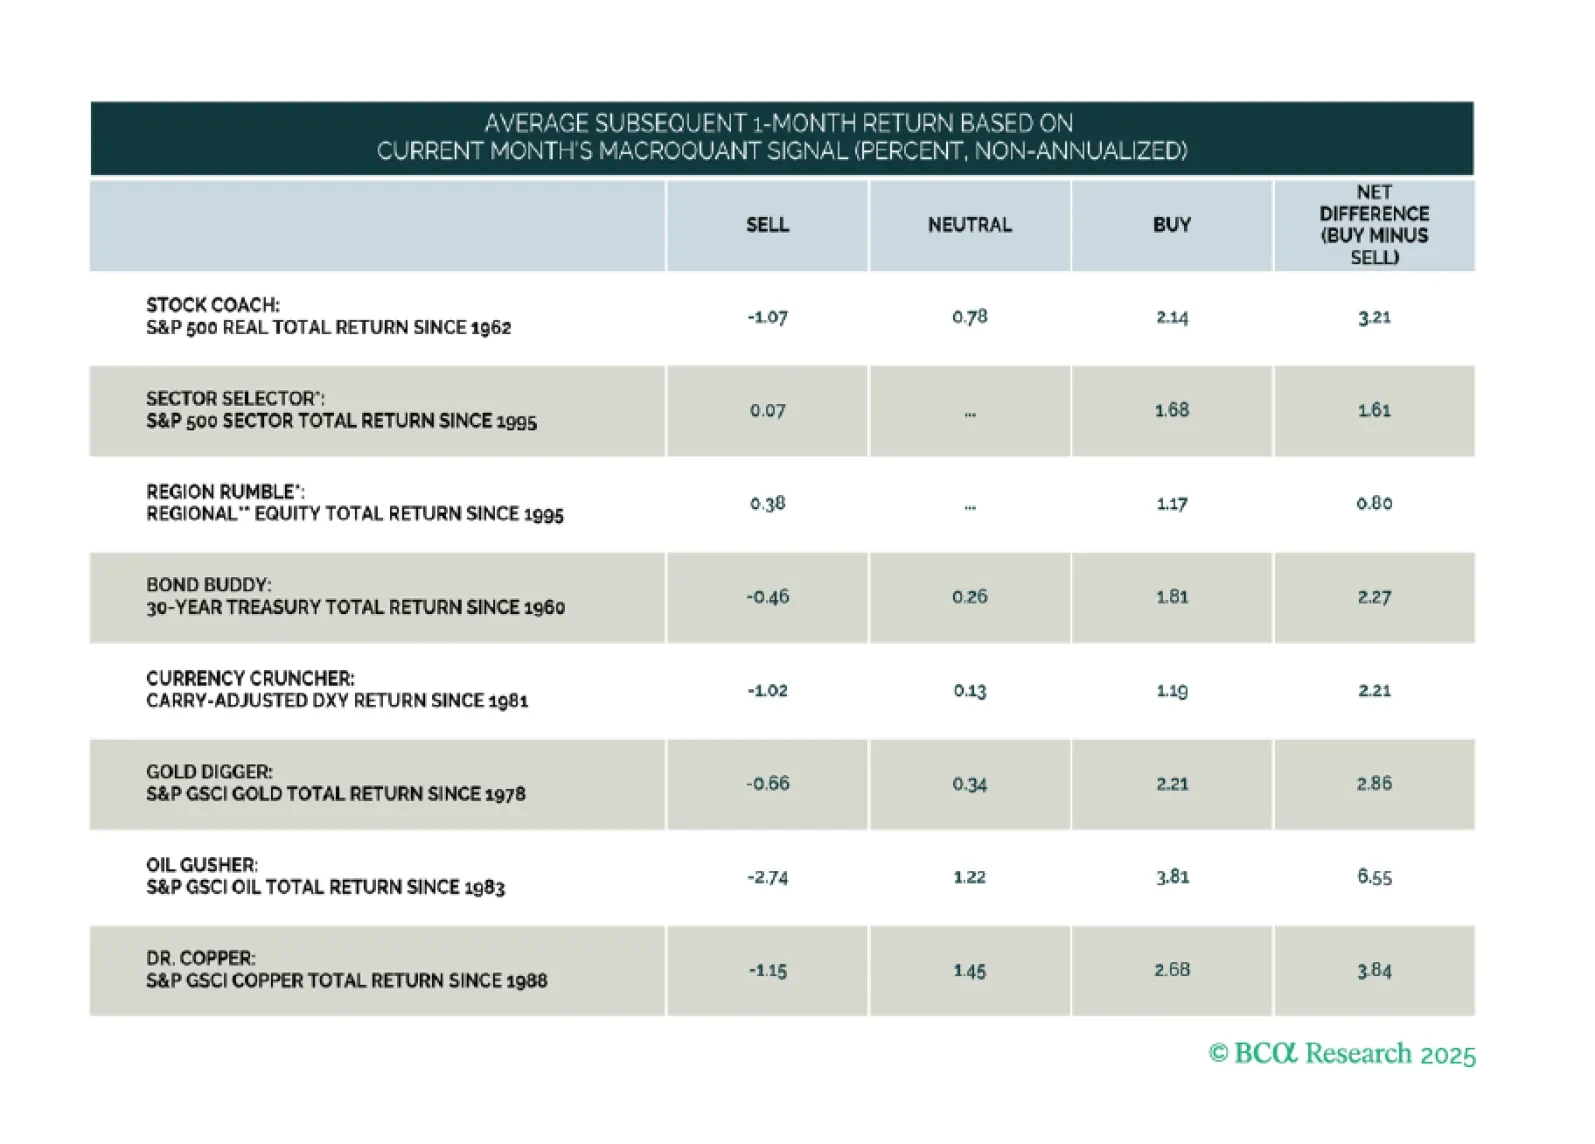
I am pleased to announce the launch of PowerTrades, an exclusive new service for Global Investment Strategy subscribers that delivers our top trading insights directly to your inbox.
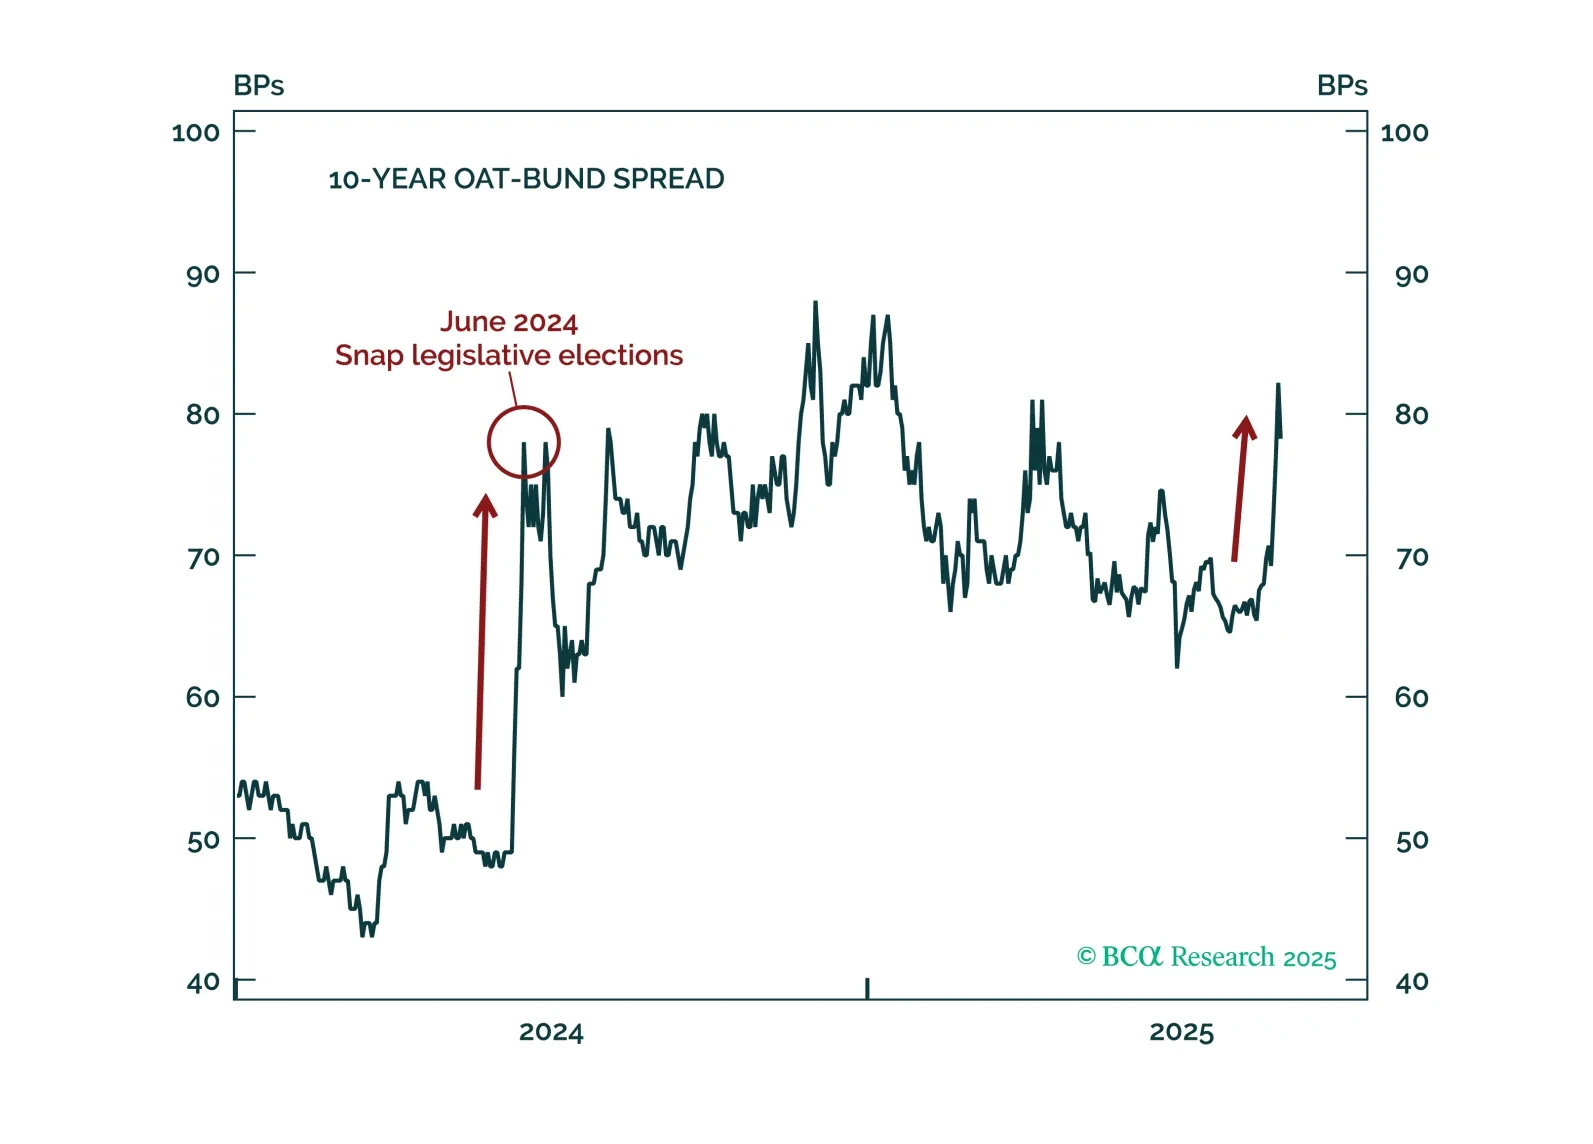
Political instability will persist in France as PM François Bayrou loses the confidence vote. The nomination of a new PM will not end the country’s political paralysis and will further fuel fiscal fears. Investors should remain underweight French OAT. French equities, especially French banks, should be bought on dips.
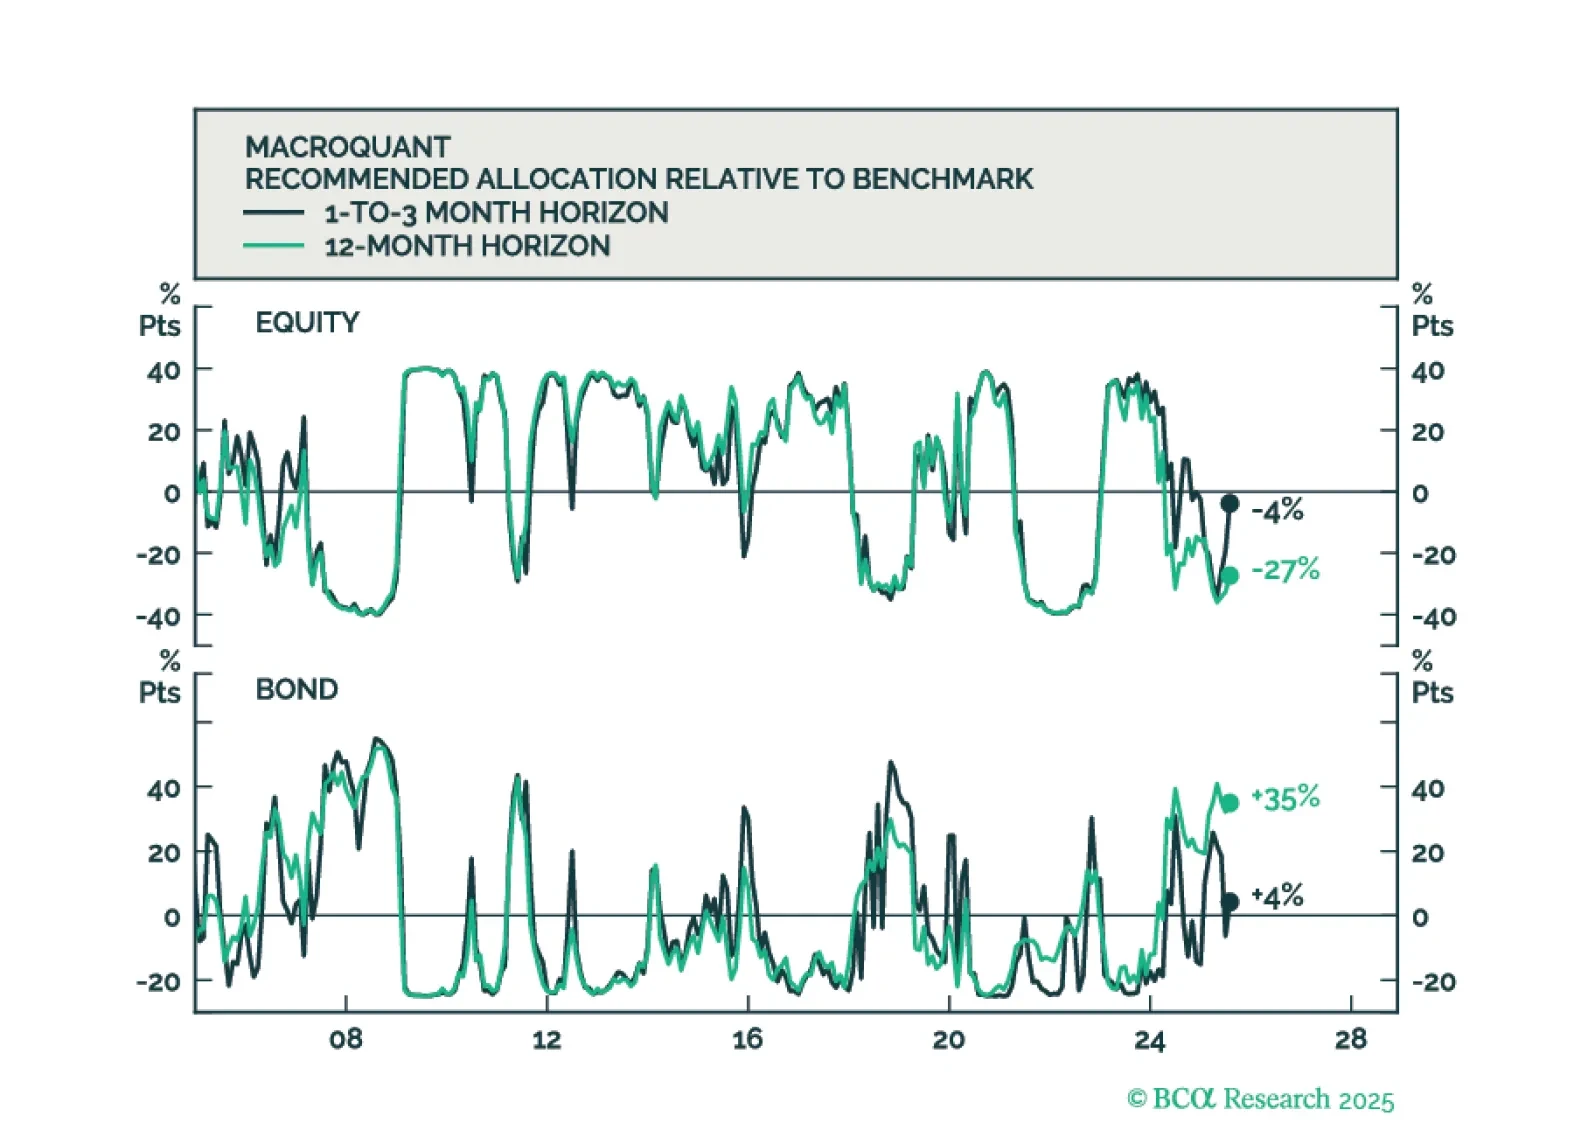
MacroQuant sees downside risks to stocks over a long-term horizon but is not yet saying that we are at imminent risk of an equity bear market.
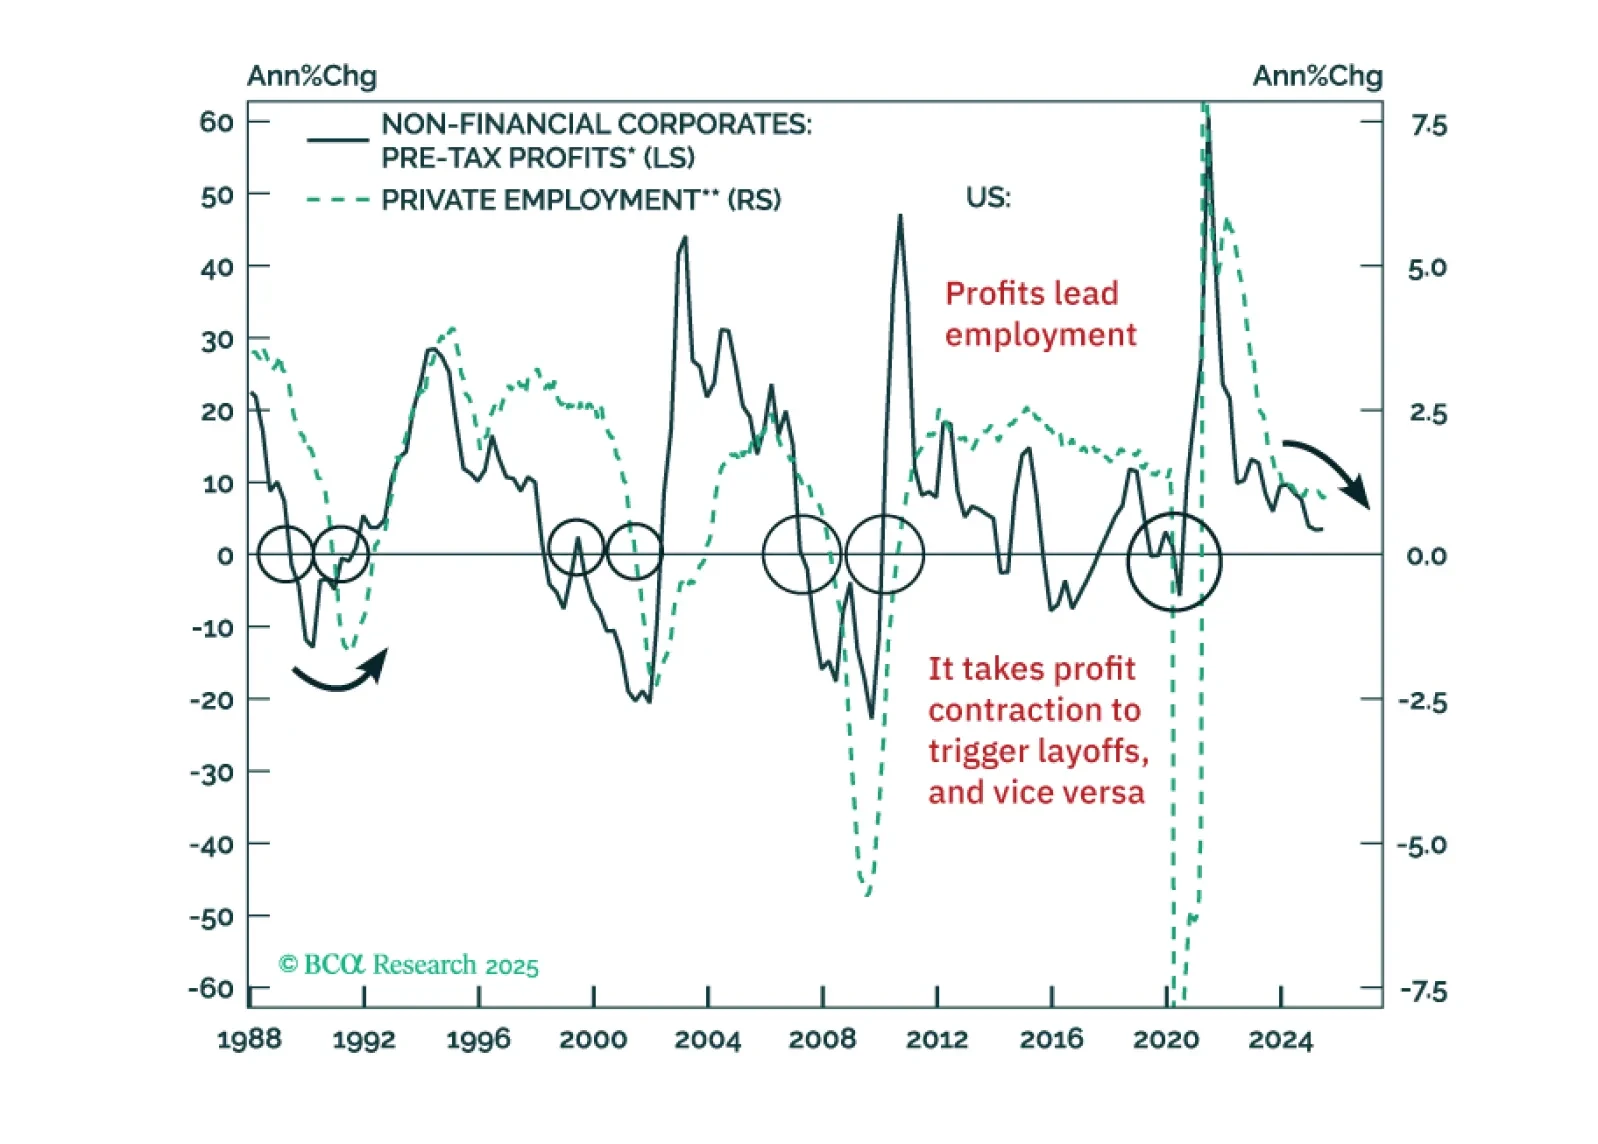
We see two risks that could spoil the rally in US risk assets: (1) a tariff-driven stagflation, and (2) a US Treasury tantrum. Our negative view on EM risk assets is primarily driven by the outlook for global trade, which is set to shrink in Q4 this year.
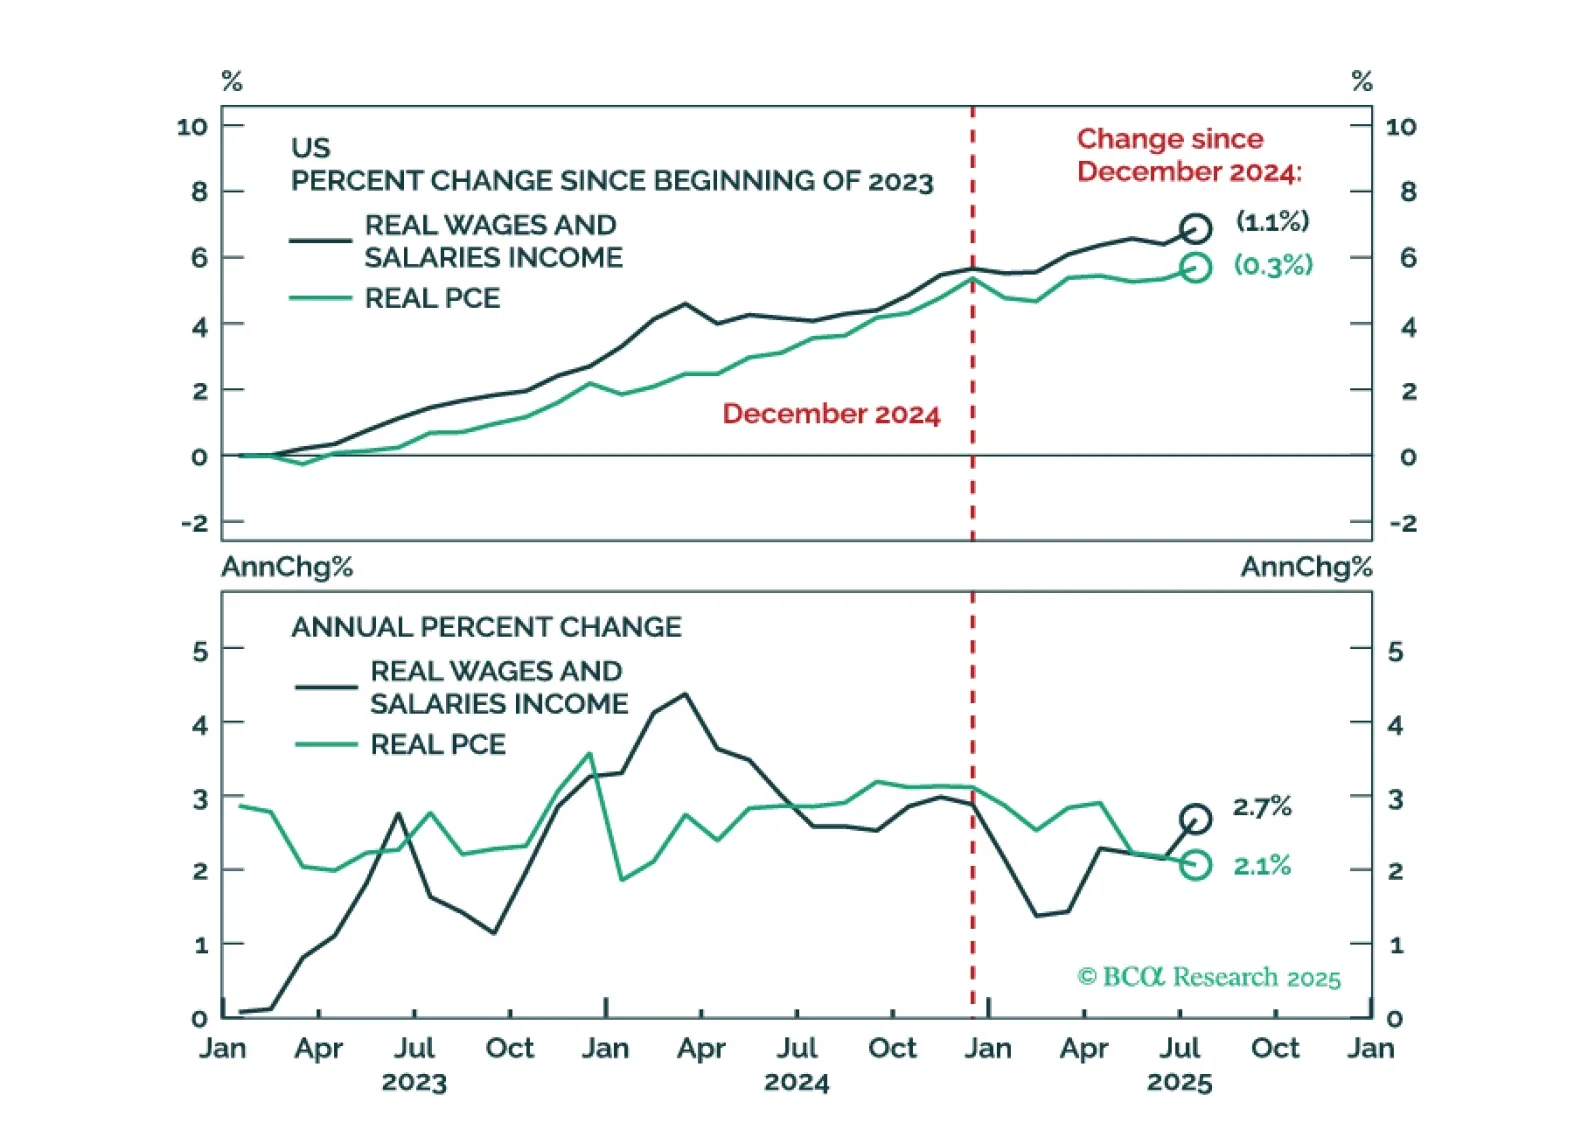
Today’s PCE report was broadly in line with expectations. Real consumer spending rebounded in July but remains only 0.3% above where it was in December.