 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
Weak employment will push out the timing of rate hikes to something closer to BCA's view of a September increase. It is also supportive of our asset allocation call two weeks ago to overweight Treasuries.
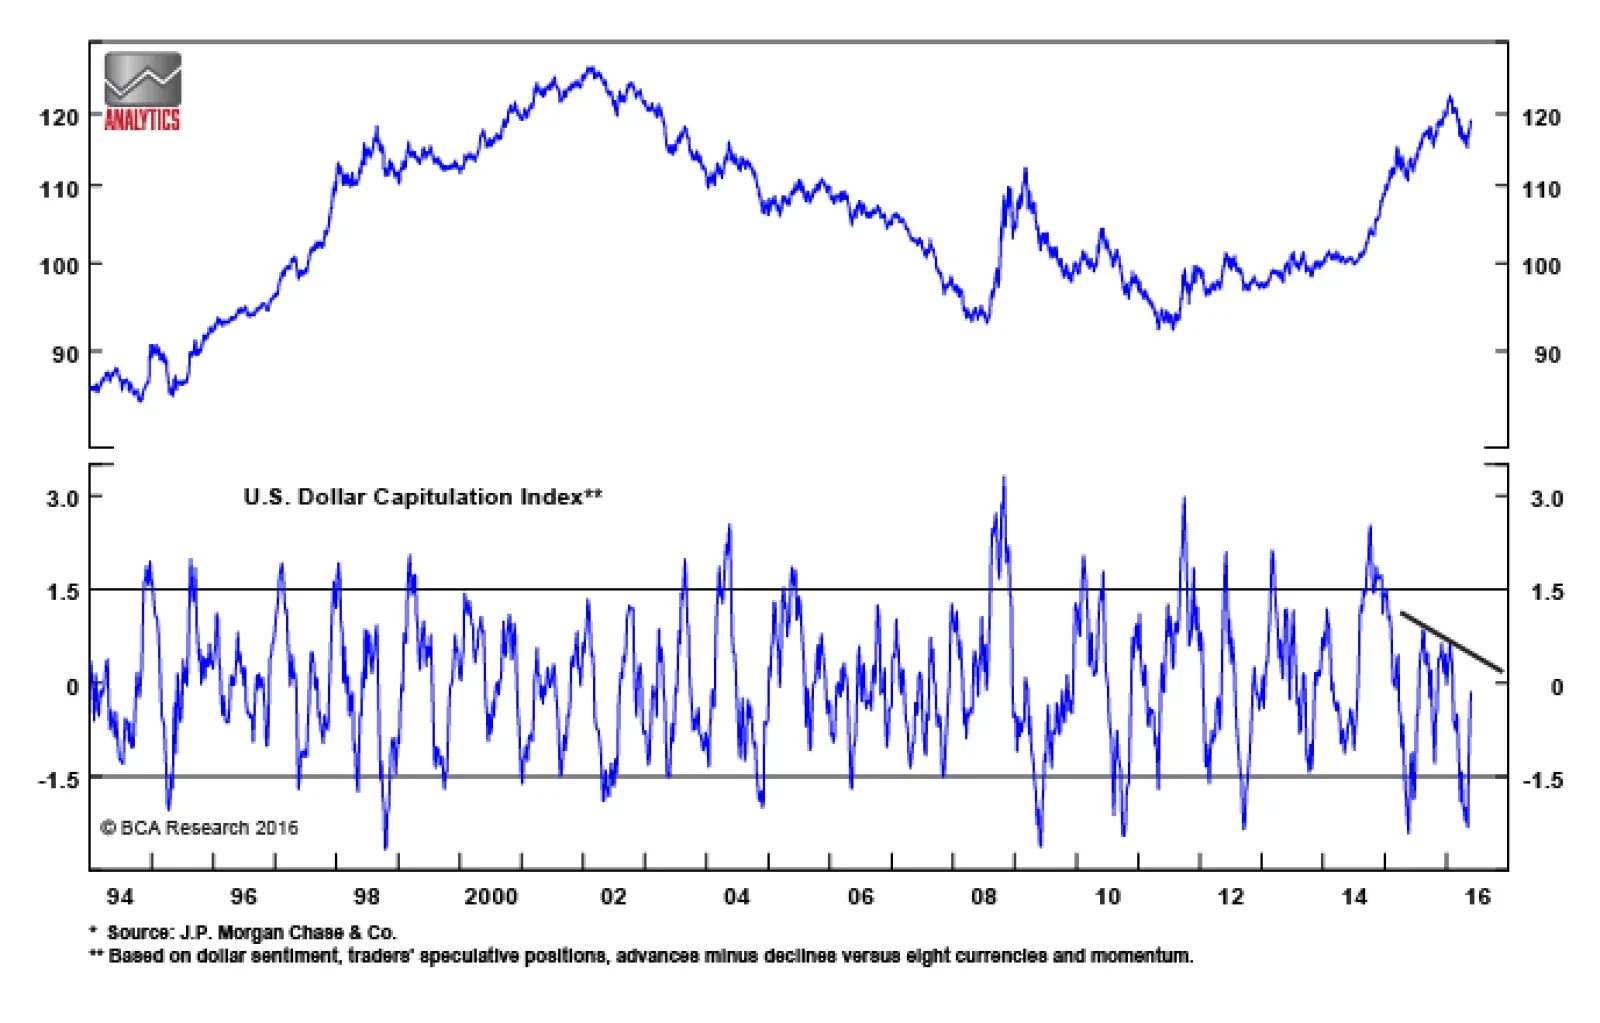
All three of Trump's signature policy proposals - increased deficit-financed infrastructure spending, a more restrictive immigration policy, and trade protectionism - are dollar bullish. These policies could cause the U.S. economy to overheat, forcing the Fed to raise real rates more than it otherwise would. Equities could rally in the near term following a Trump victory, but are likely to face stiff longer-term headwinds. Treasurys would still suffer modest losses, while, ironically, the one asset that could suffer the most from a Trump victory is gold.
The window for "stealth" RMB depreciation is likely closed for now. The Chinese authorities are stepping up efforts to boost infrastructure construction with several major announcements last month. Capital spending on transportation infrastructure will likely accelerate at least through next year.
Both hawks and doves at the Federal Reserve, including Chair Yellen, have stepped up efforts to condition financial markets for a rate hike as early as June.
For the month of May, the model underperformed both global equities and the S&P 500. For the month of June, the model is further paring back its risk exposure.
The latest conclusions from the sector-based (right) way to pick stock markets. Plus some important conclusions for credit markets.