CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
Rising demand for U.S. dollars in EM and further yen depreciation, if it transpires, assures global exchange rate volatility will rise. Rising currency volatility, especially in the RMB, will push the global risk premium higher, weighing on global share prices. In Turkey, a wage-inflation spiral is unfolding and the central bank is behind the curve; the currency will plummet further.
Any recovery in risk assets and selloff in safe havens is unlikely to extend into the cyclical horizon.
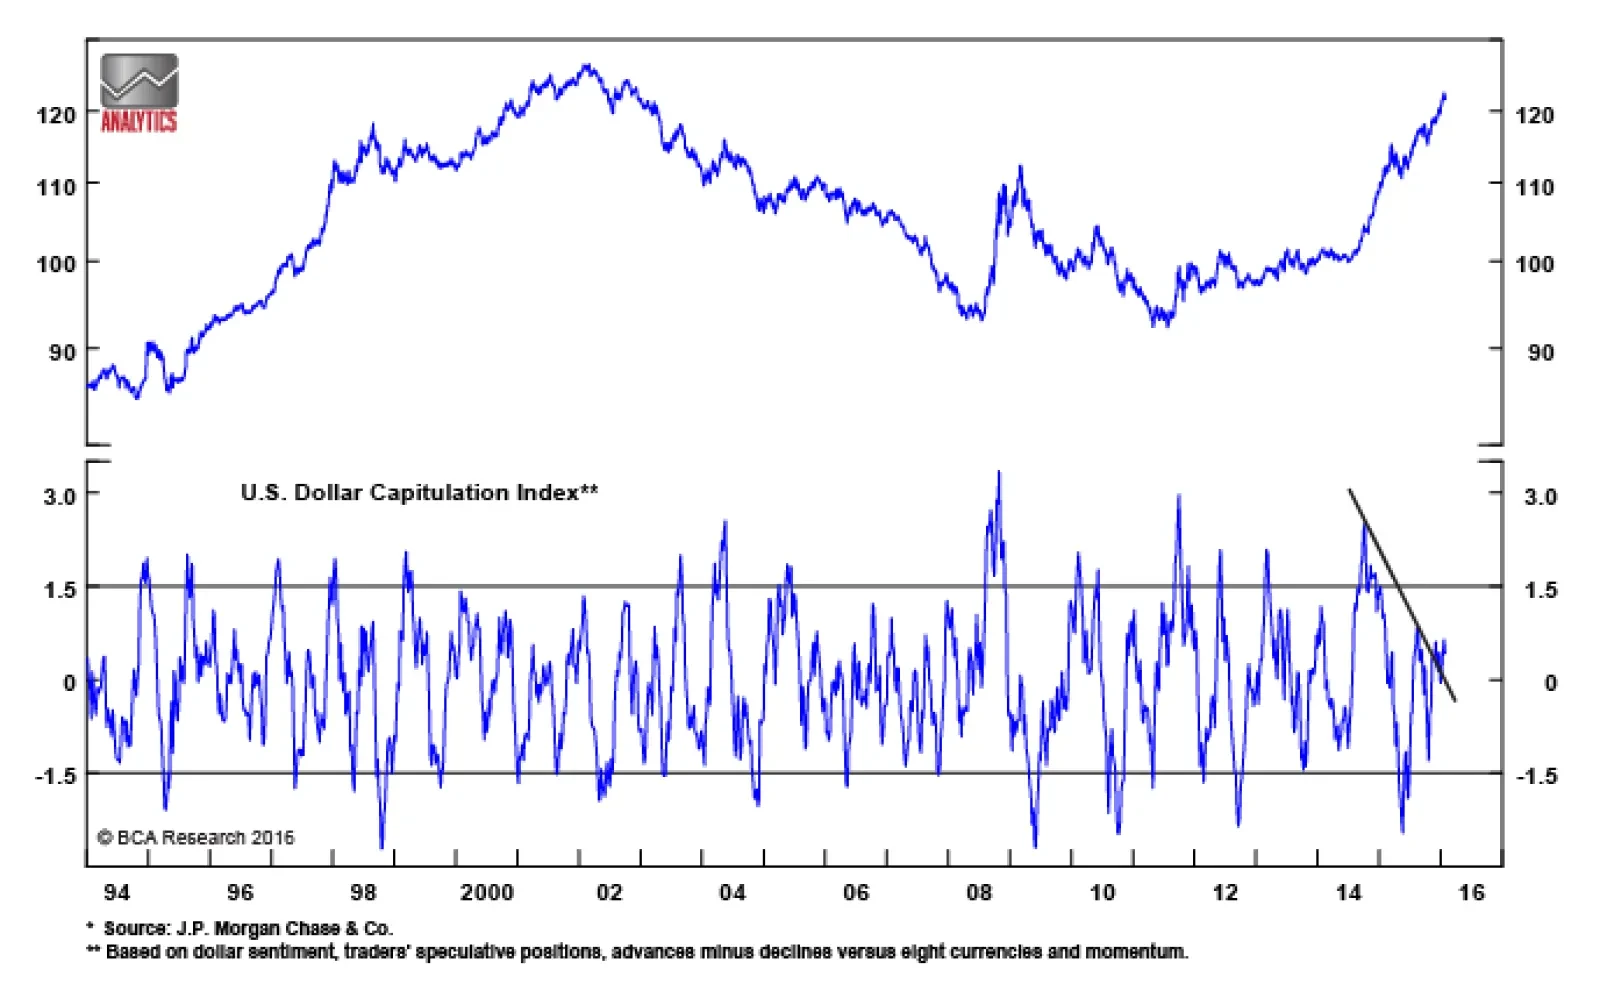
Last month, the model outperformed both global and U.S. equities in local-currency and U.S.-dollar terms. For February, the model is aggressively increasing its risk exposure and has included a bet on commodities for the first time since 2012. For equities, the largest overweight remains Europe, but EM and Canada enjoyed significant upgrades. For bonds, the model favors the European periphery.
Central banks follow backward-looking indicators but economies follow forward-looking indicators. So which indicators should investors follow? And what is the current message? Also, we see signs that London is cooling.
Corporate profits are more sensitive to selling prices than to volumes. Falling prices even amid mildly rising volumes could produce a meaningful profit contraction. Stay with deflation trades. In particular, maintain the short EM stocks / long U.S. 30-year Treasurys position. Indian stocks are still pricey and will deflate further in absolute terms.
There are no signs of broader financial stress in the Chinese corporate sector. The most recent financial market turmoil has had no systemic damage to corporate sector balance sheets. We are leaning against being overly bearish. Current valuation readings, particularly for Chinese H shares and Hong Kong stocks, on a historical basis have never been sustainable.
Equity selloff alone will not catch the Fed's eye unless there is an outright crash.