 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
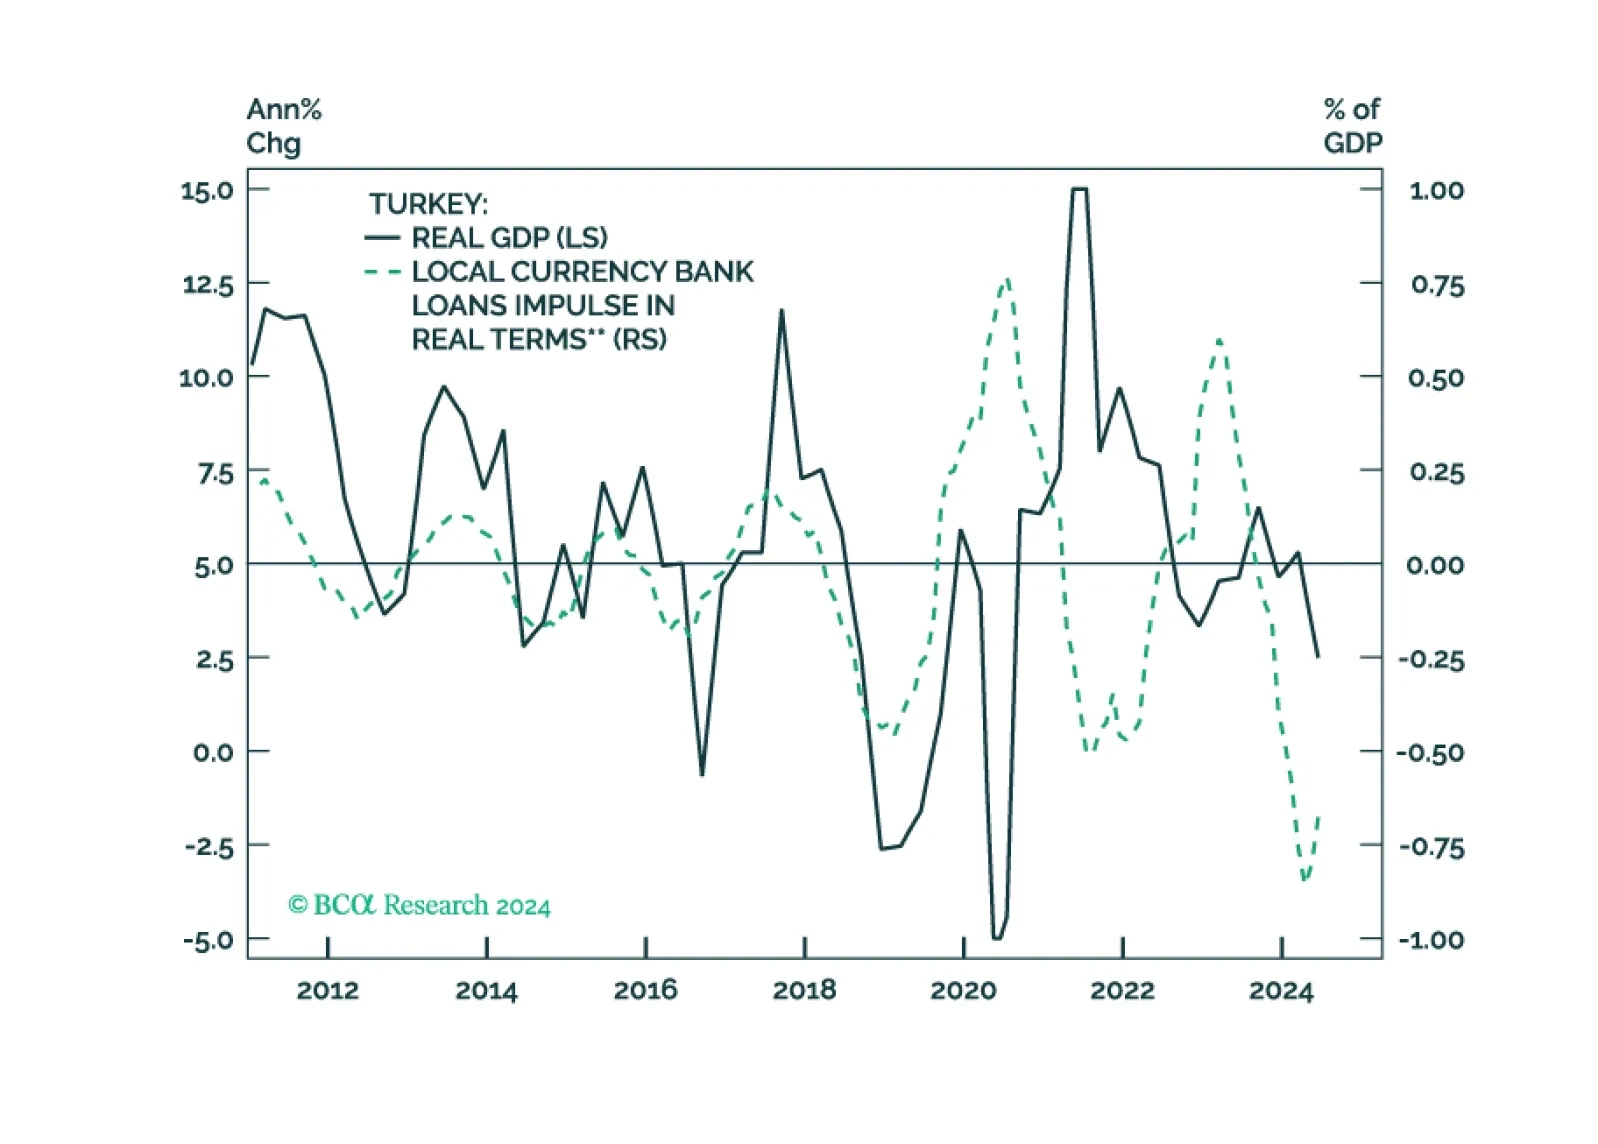
Turkey has a path toward sustained disinflation. But that will require tight macro policies for an extended period. The question is, will the authorities tolerate the consequent growth slowdown, even a recession, and surging unemployment, as the necessary cost to break the back of inflation?
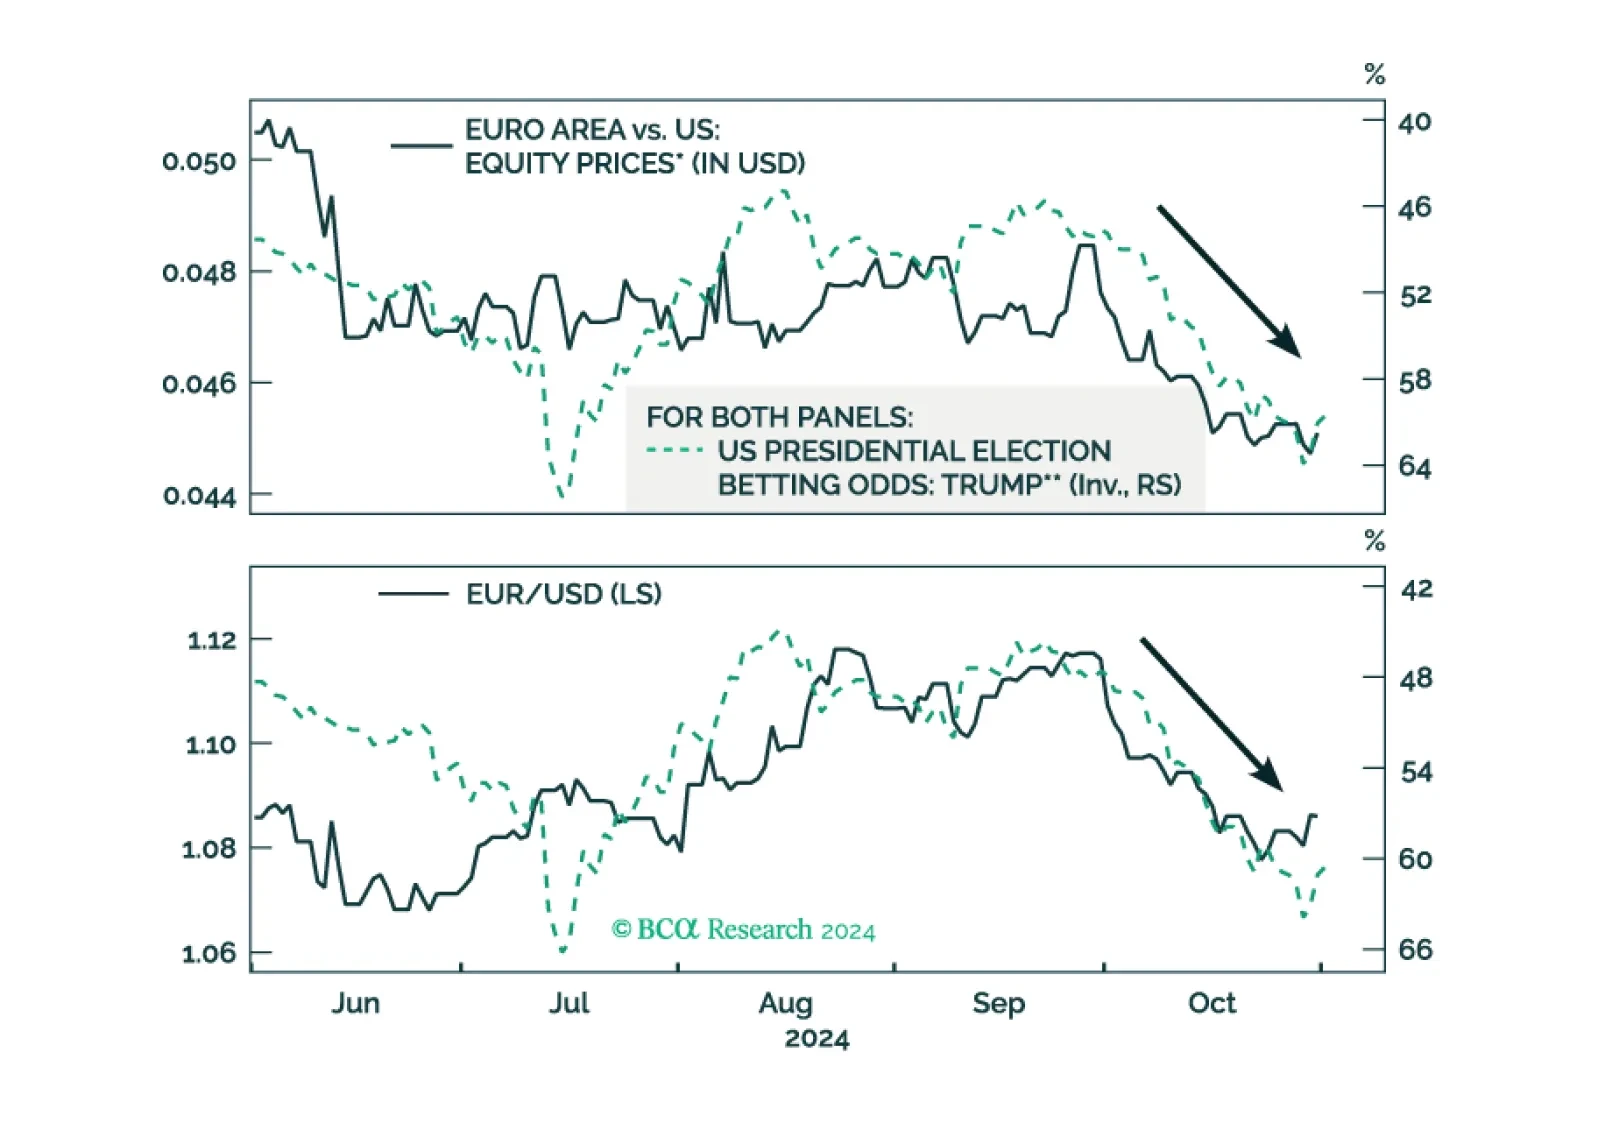
As the odds of a Trump victory rise, European assets underperform US ones. What would be the immediate impact of a Trump victory on European stocks?
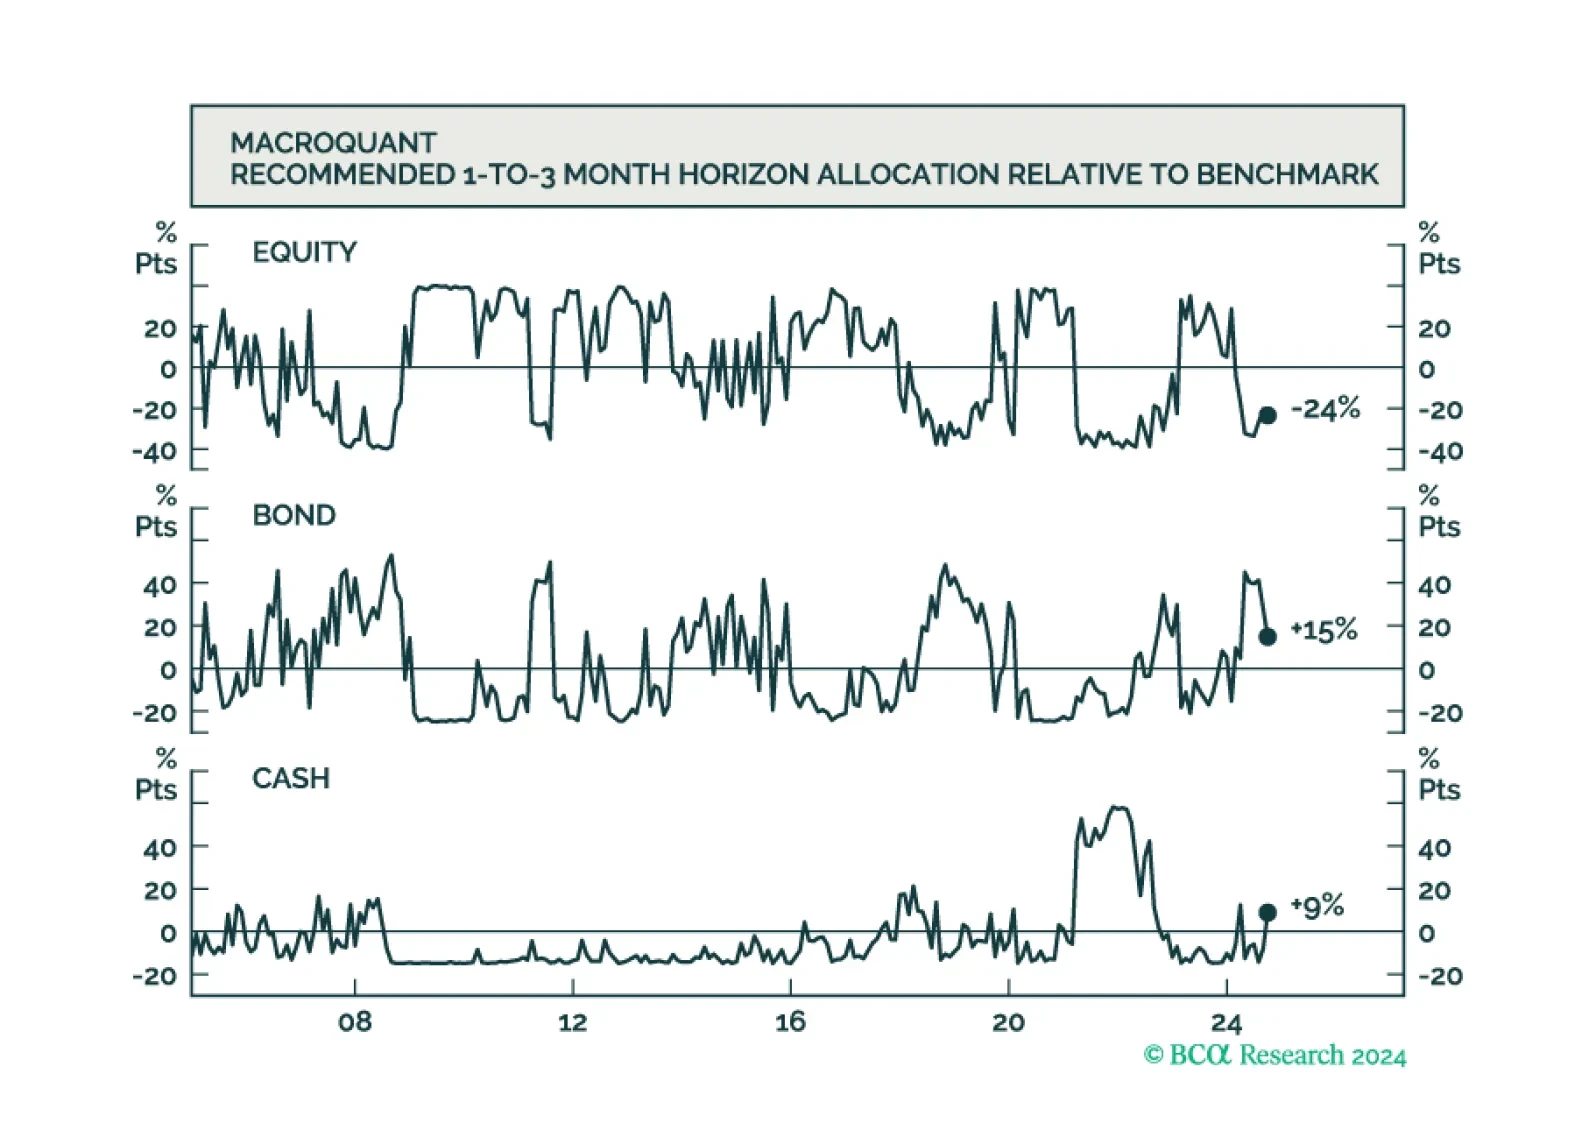
MacroQuant expects global equities to weaken in November. As such, the model recommends underweighting equities and overweighting bonds and cash.
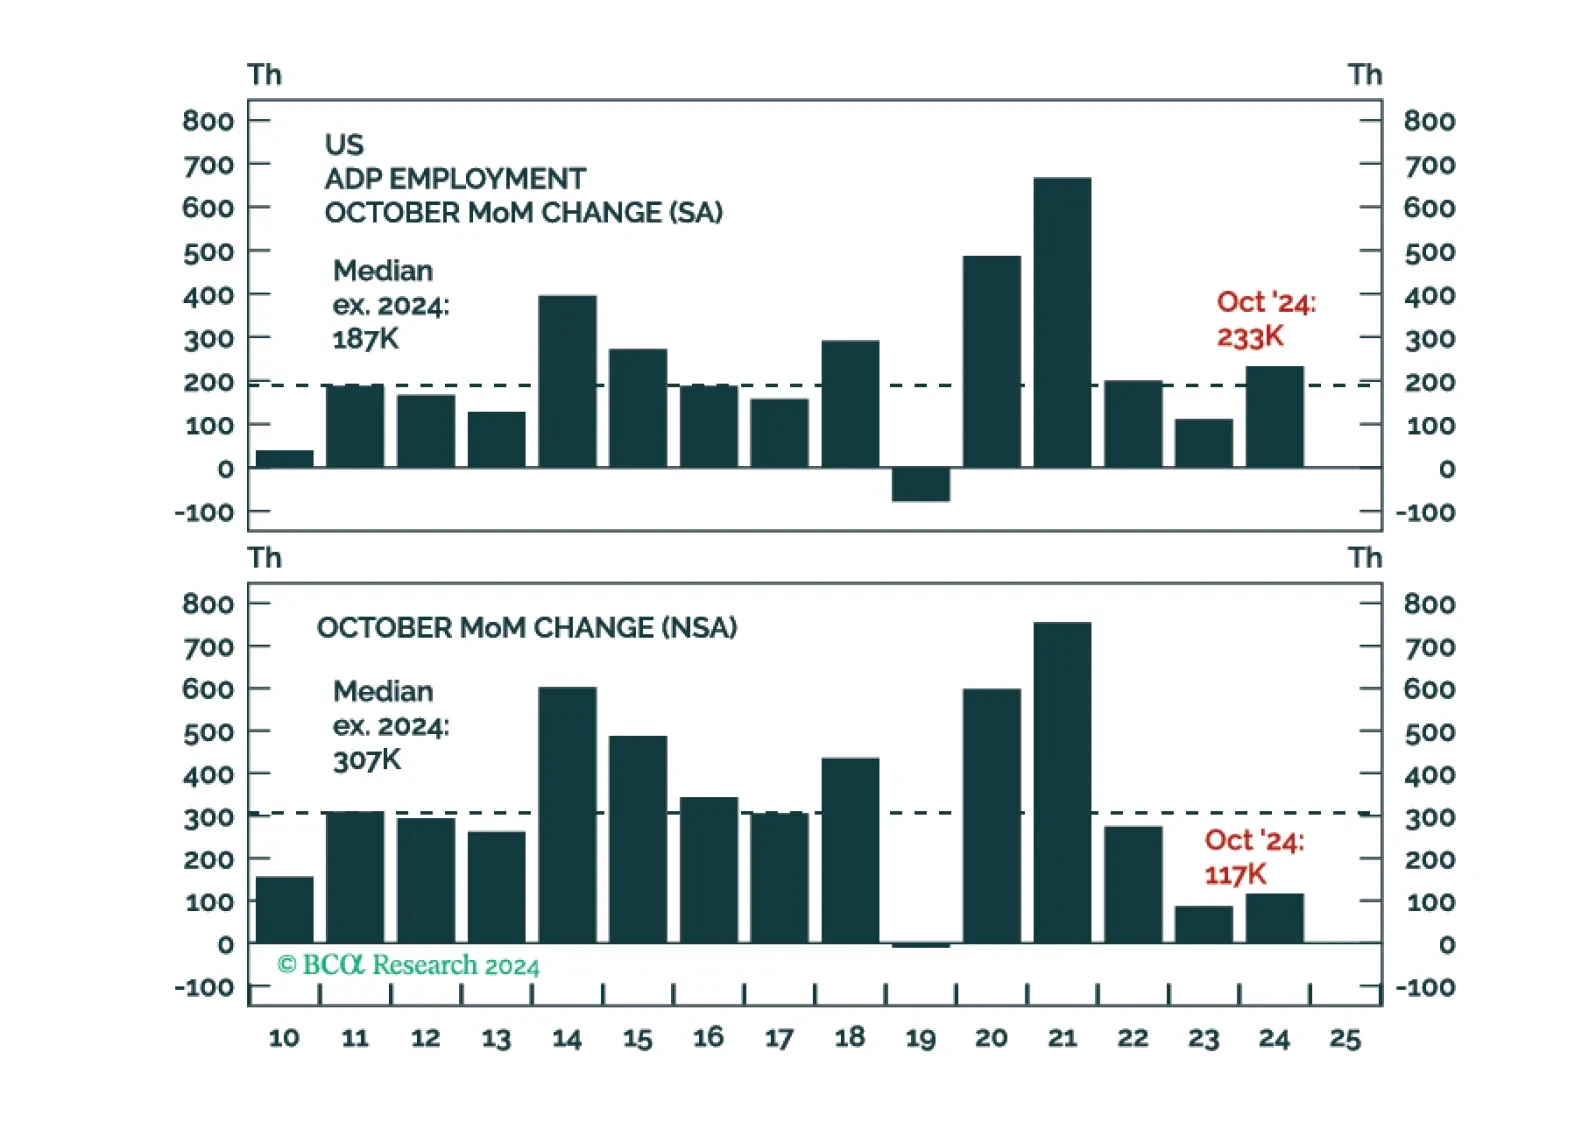
ADP's estimate of private payrolls rose by 233K on a seasonally adjusted basis in October, blowing away the consensus estimate of 111K.
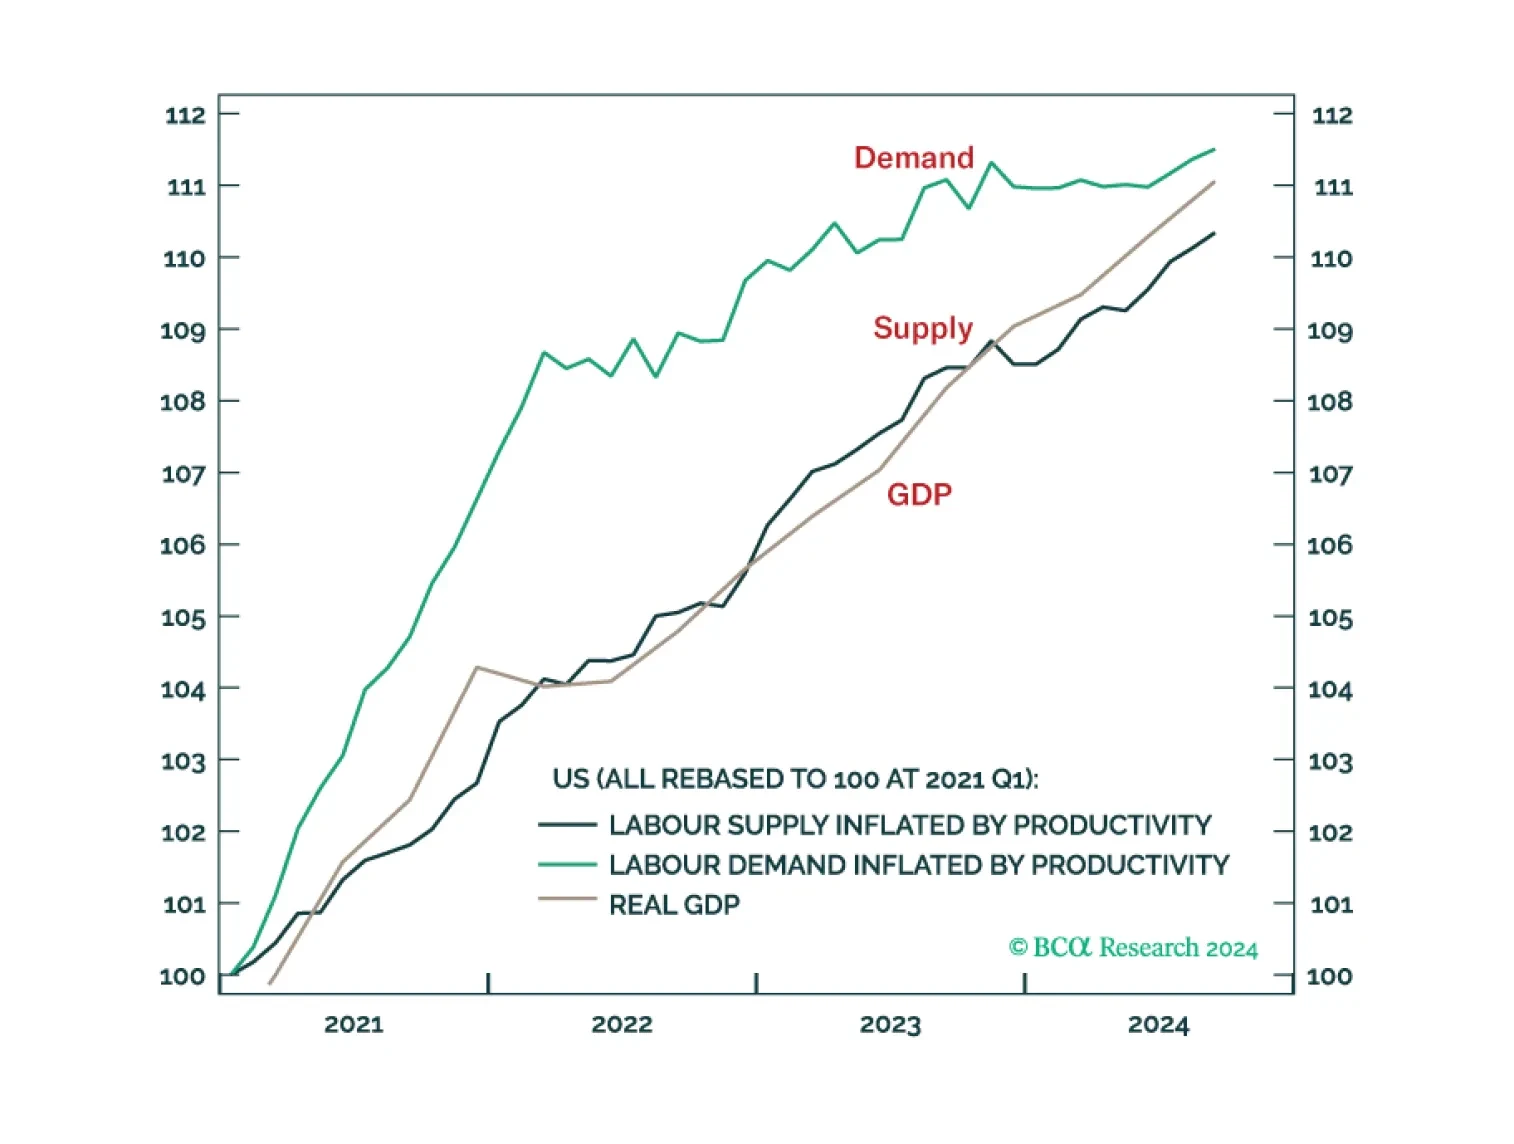
A Trump victory offers a buying opportunity for bonds; a Harris victory offers a selling opportunity for bonds. We explain why.
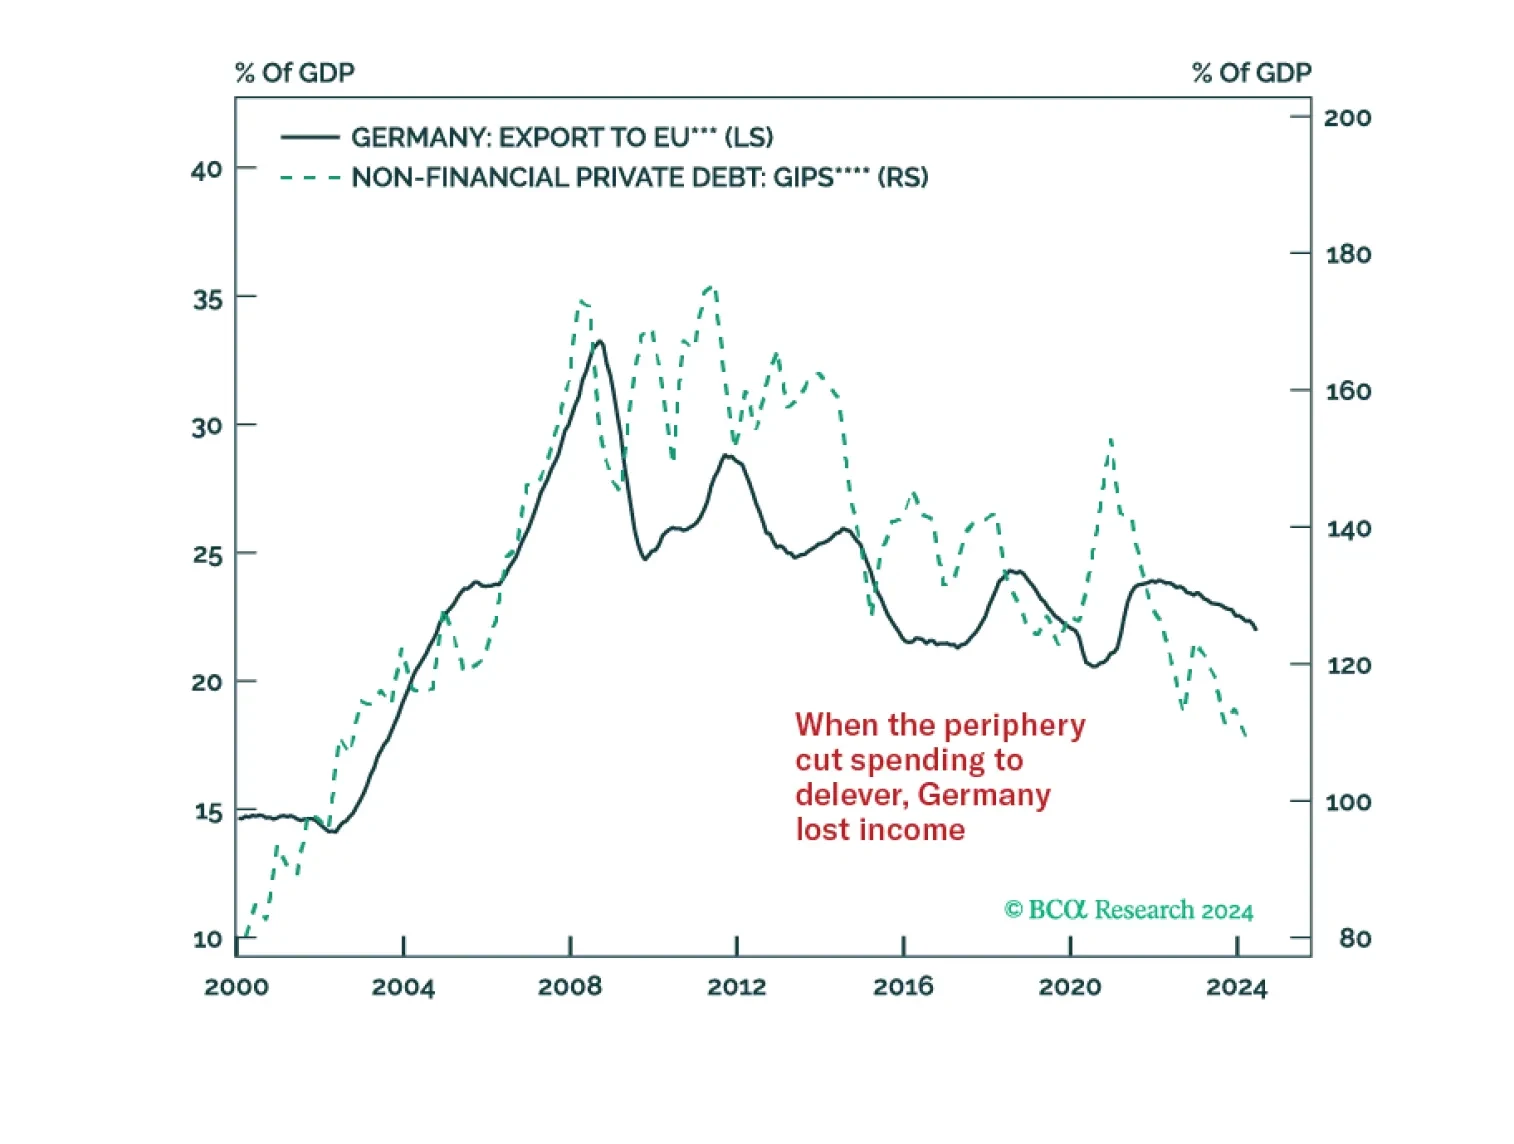
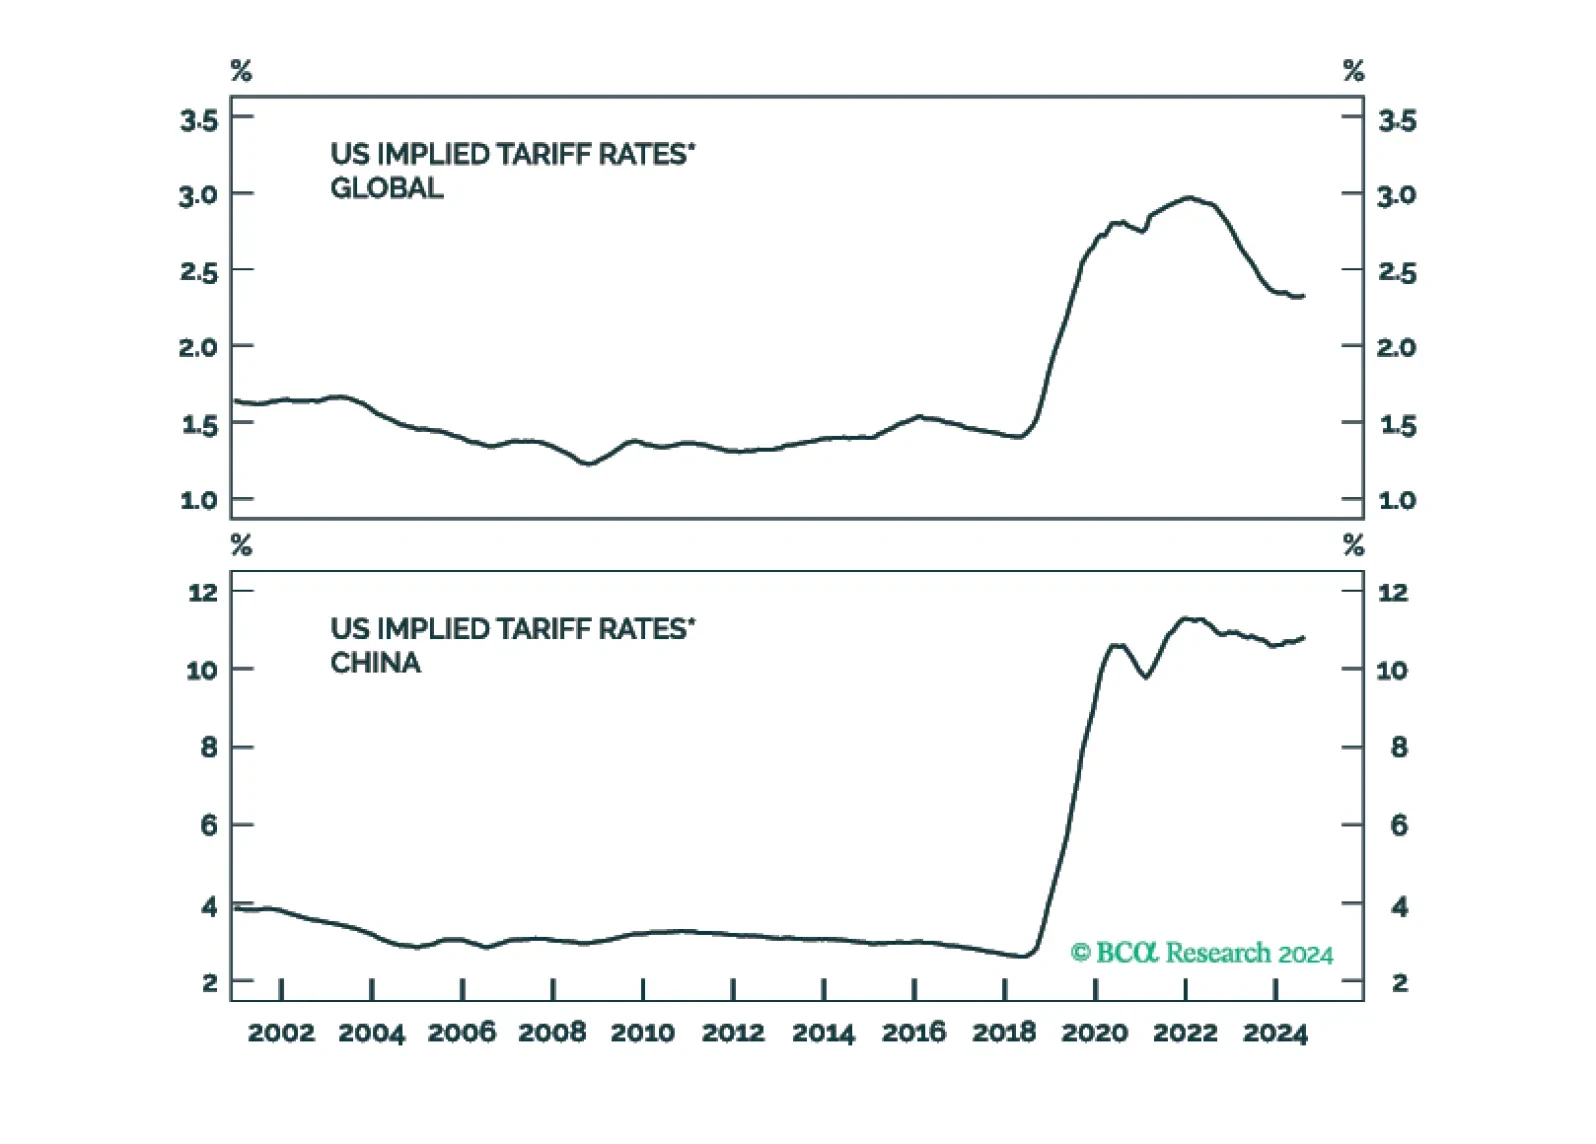
Back in 2016, there was widespread concern that if Donald Trump became president, he would start a trade war. As it turned out, Trump did become president and he did start a trade war, but the US economy continued growing anyway. In a study published in August 2019, the Congressional Budget Office concluded that Trump's tariffs reduced the level of US real GDP by 0.3% - not immaterial but not earth-shattering either.
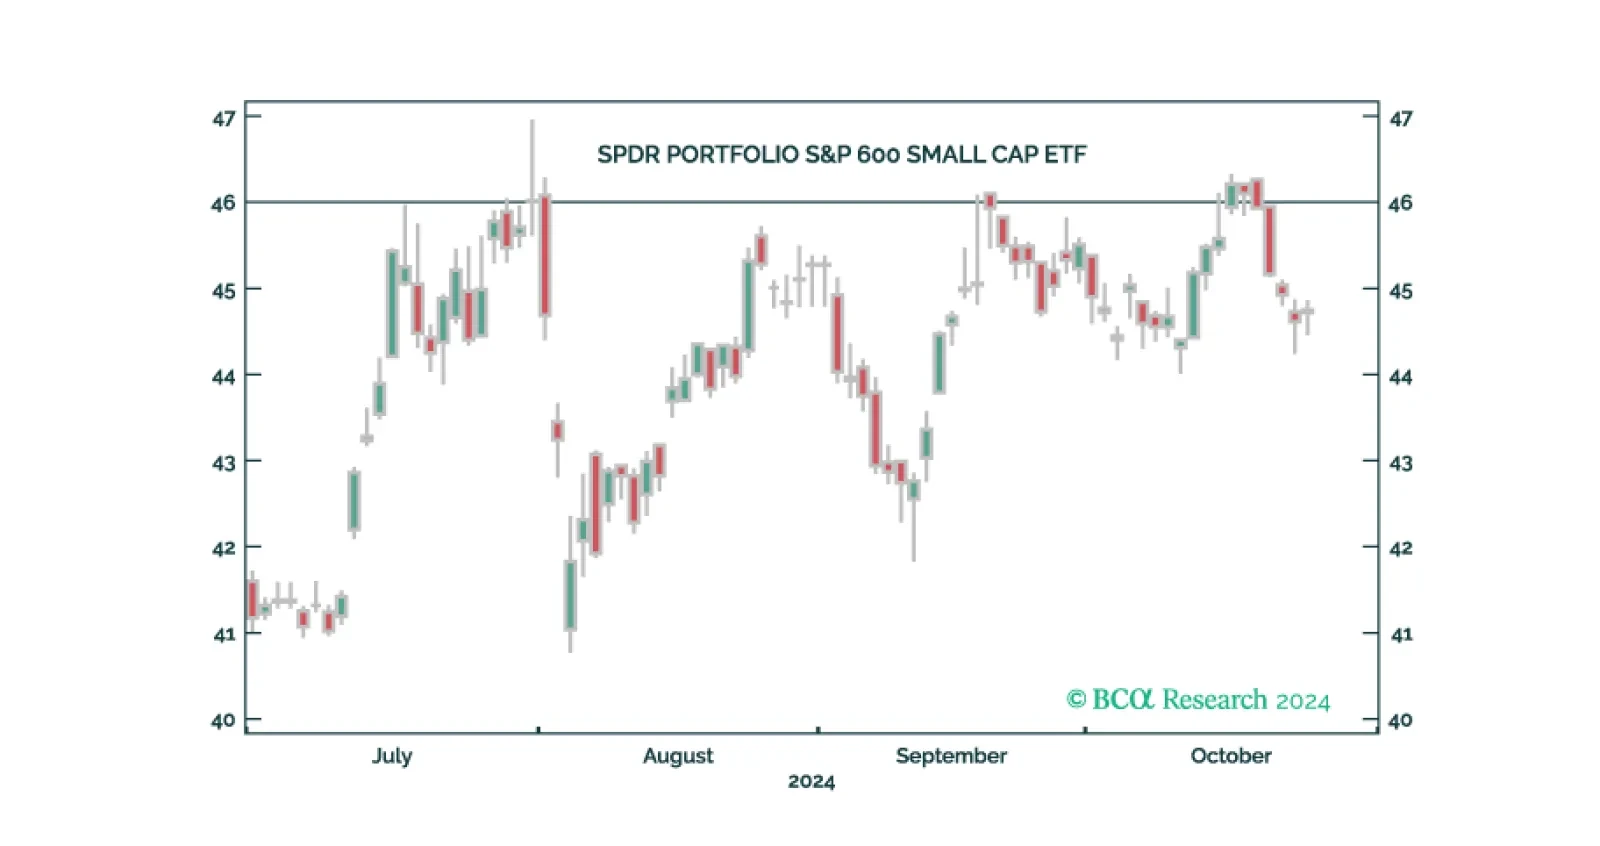
Middle-aged households have lagged youngish and older households since the pandemic and the 40-to-54 cohort is worse off than it was at the end of 2019. The fragmenting of the seemingly monolithic US consumer widens the path to a recession and we reiterate our defensive asset allocation recommendations.
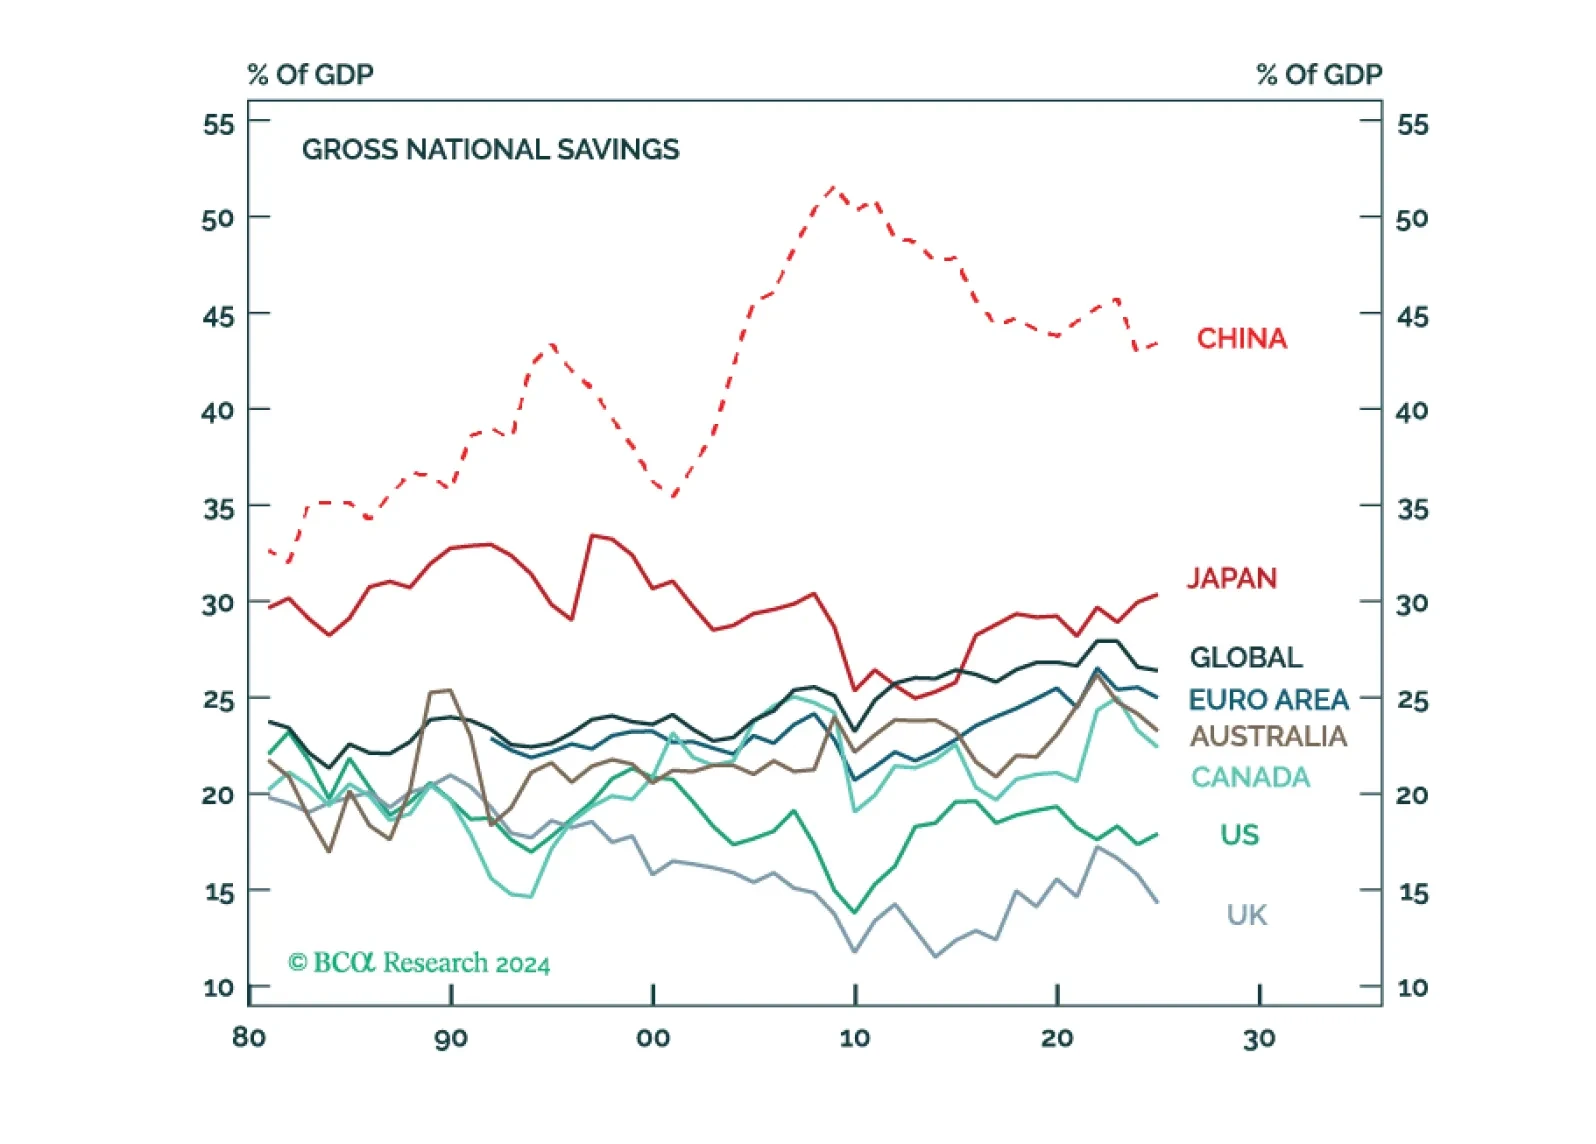
In this report, we discuss why we are lifting our US recession probability from 60% to 65% and explain why China’s latest stimulus announcements are welcome, but probably are “too little, too late.”