CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
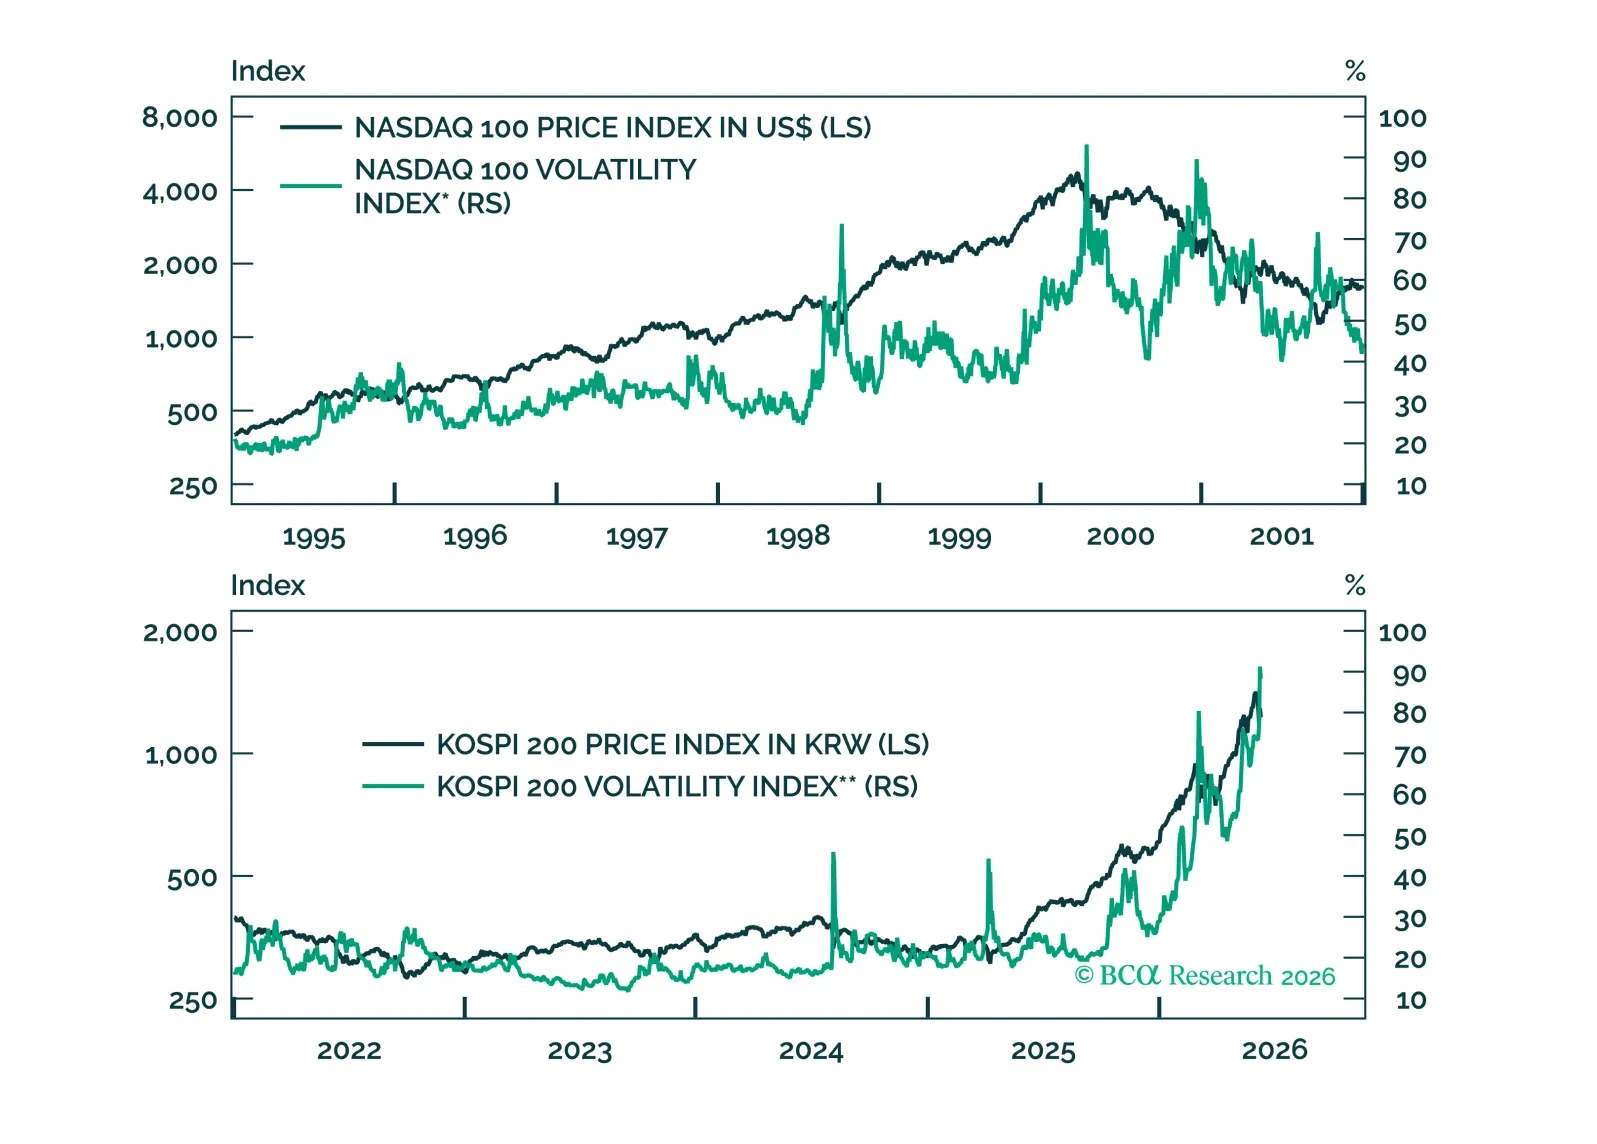
Rising volatility in Korean markets captures a late-cycle surge in which euphoria and drawdown risk are rising together. While KOSPI momentum remains intact, the bigger opportunity may be emerging in the increasingly mispriced KRW, which could rally meaningfully as portfolio flow headwinds fade.
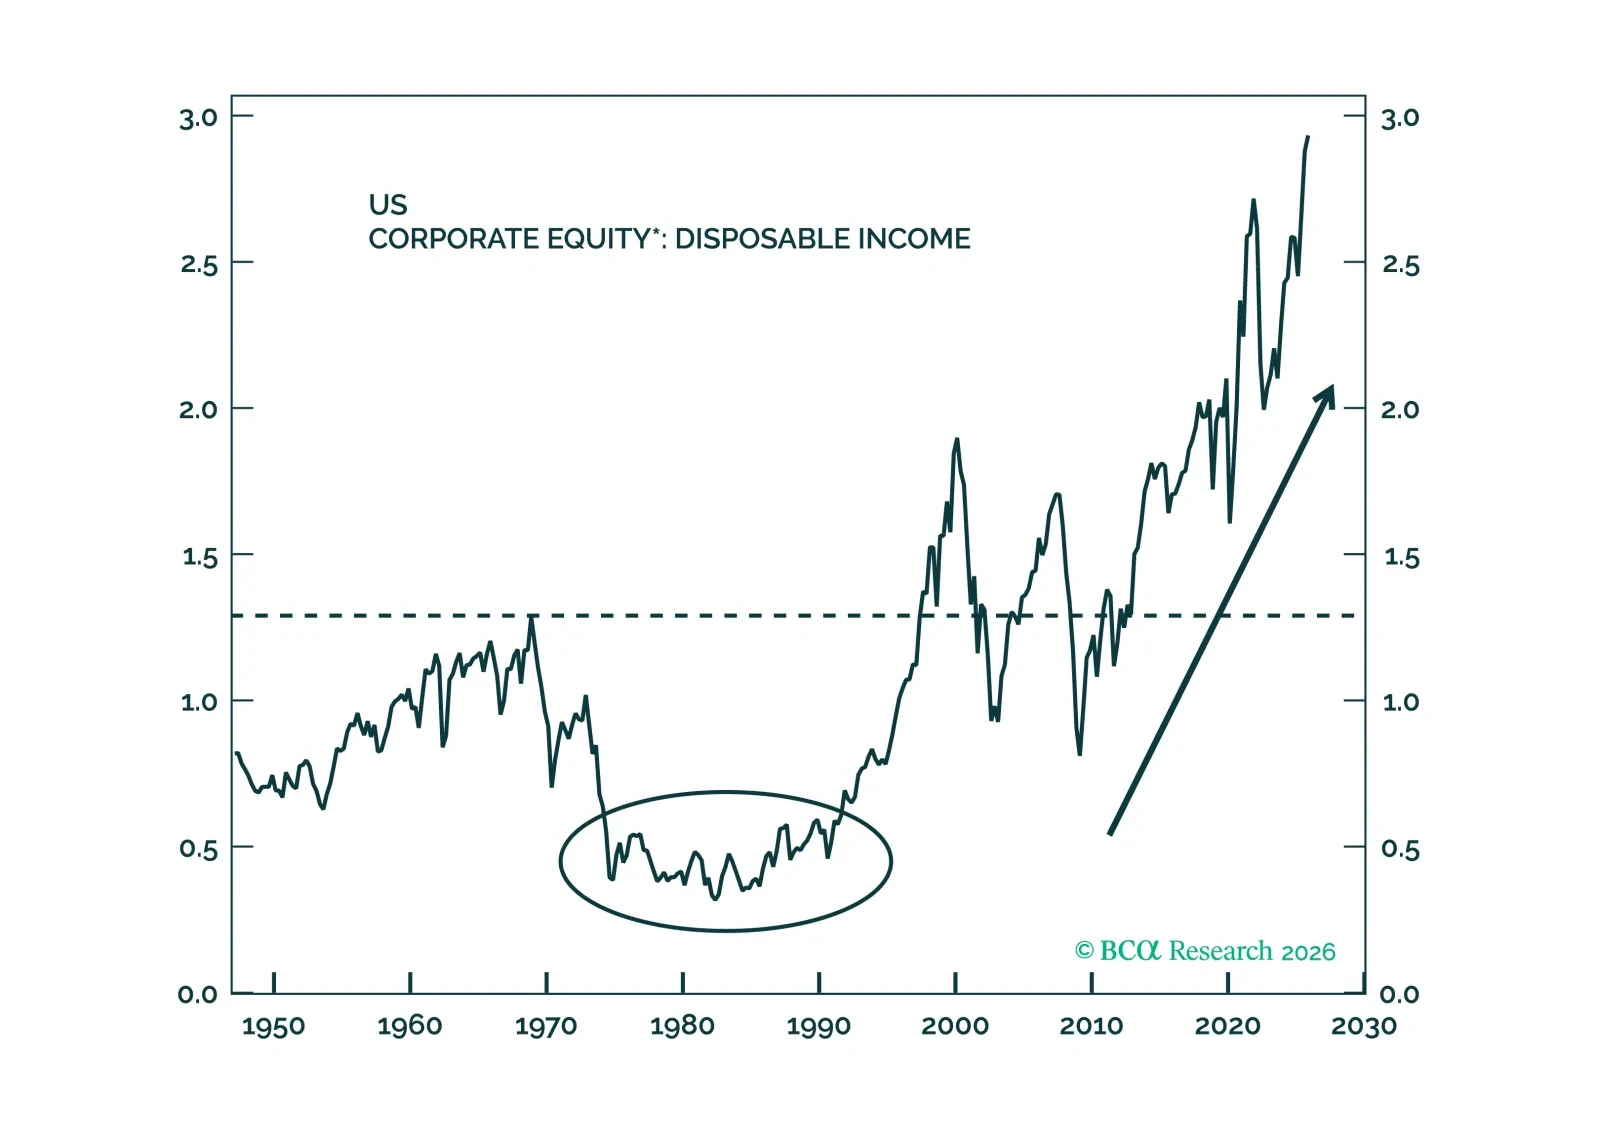
Although the multi-decade surge in the value of households’ equity holdings has made US activity more vulnerable to a stock selloff, the latest income, spending and employment data suggest that consumption growth can carry on at a 2% inflation-adjusted pace.
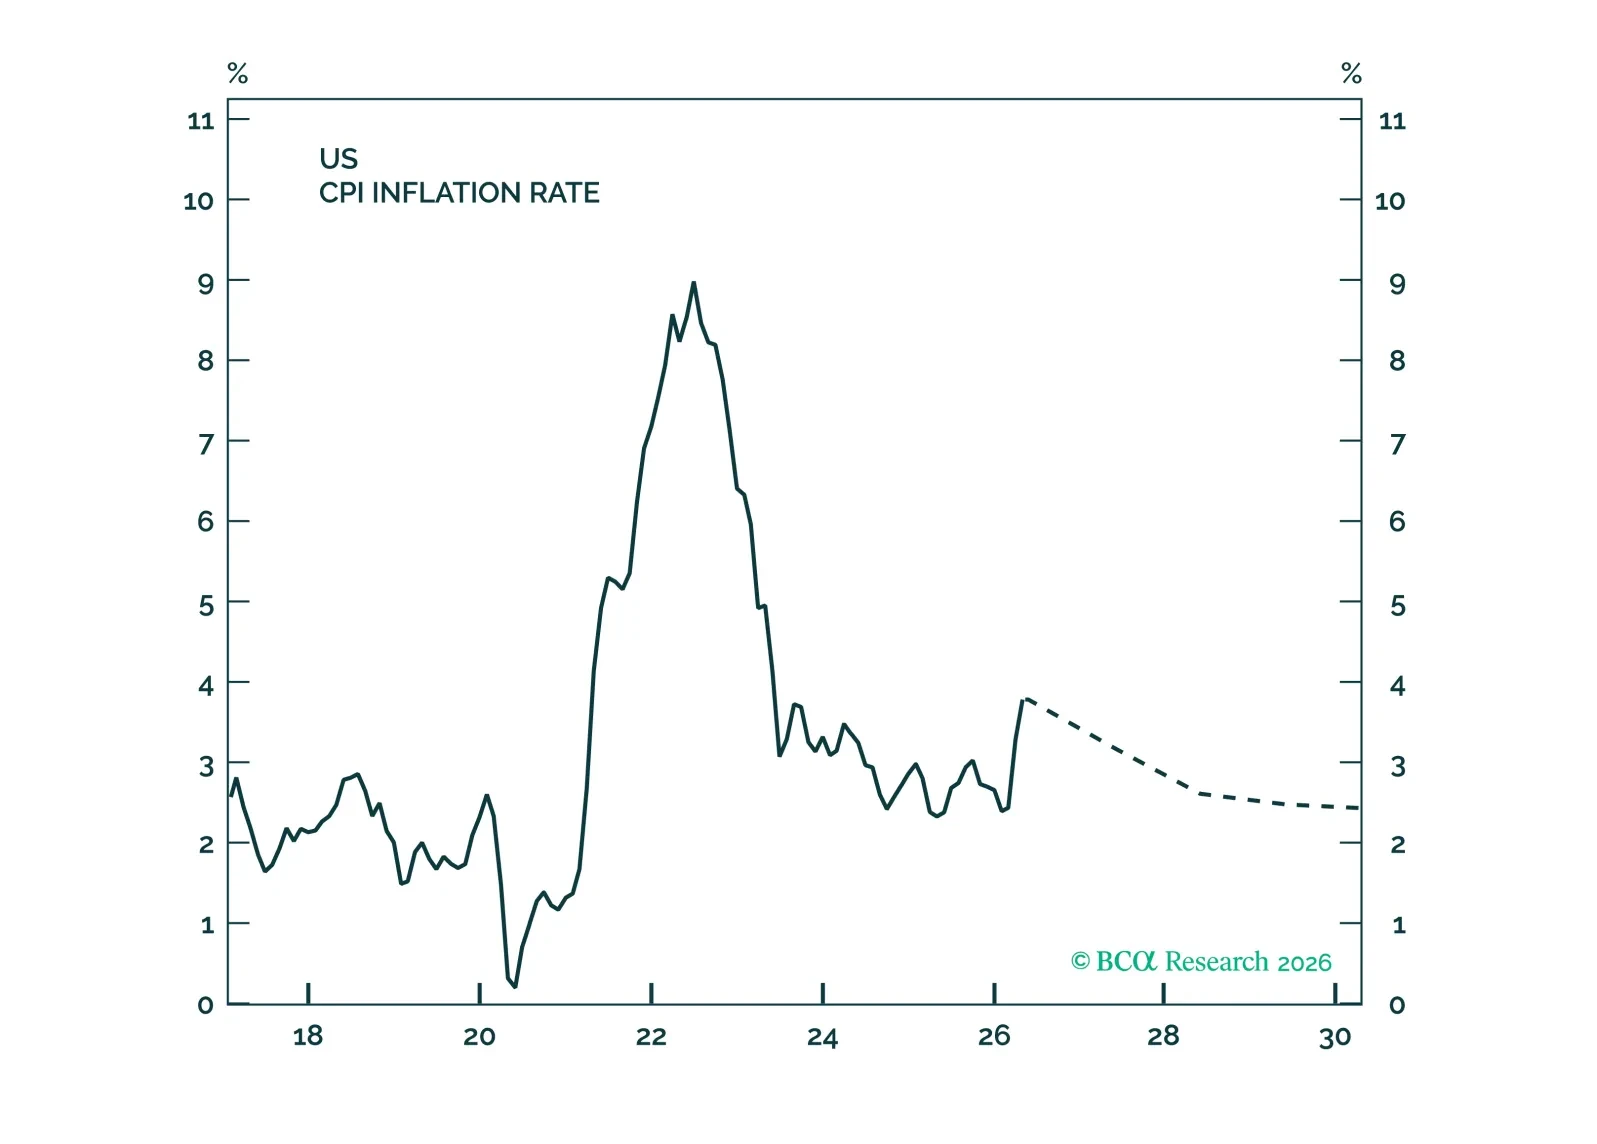
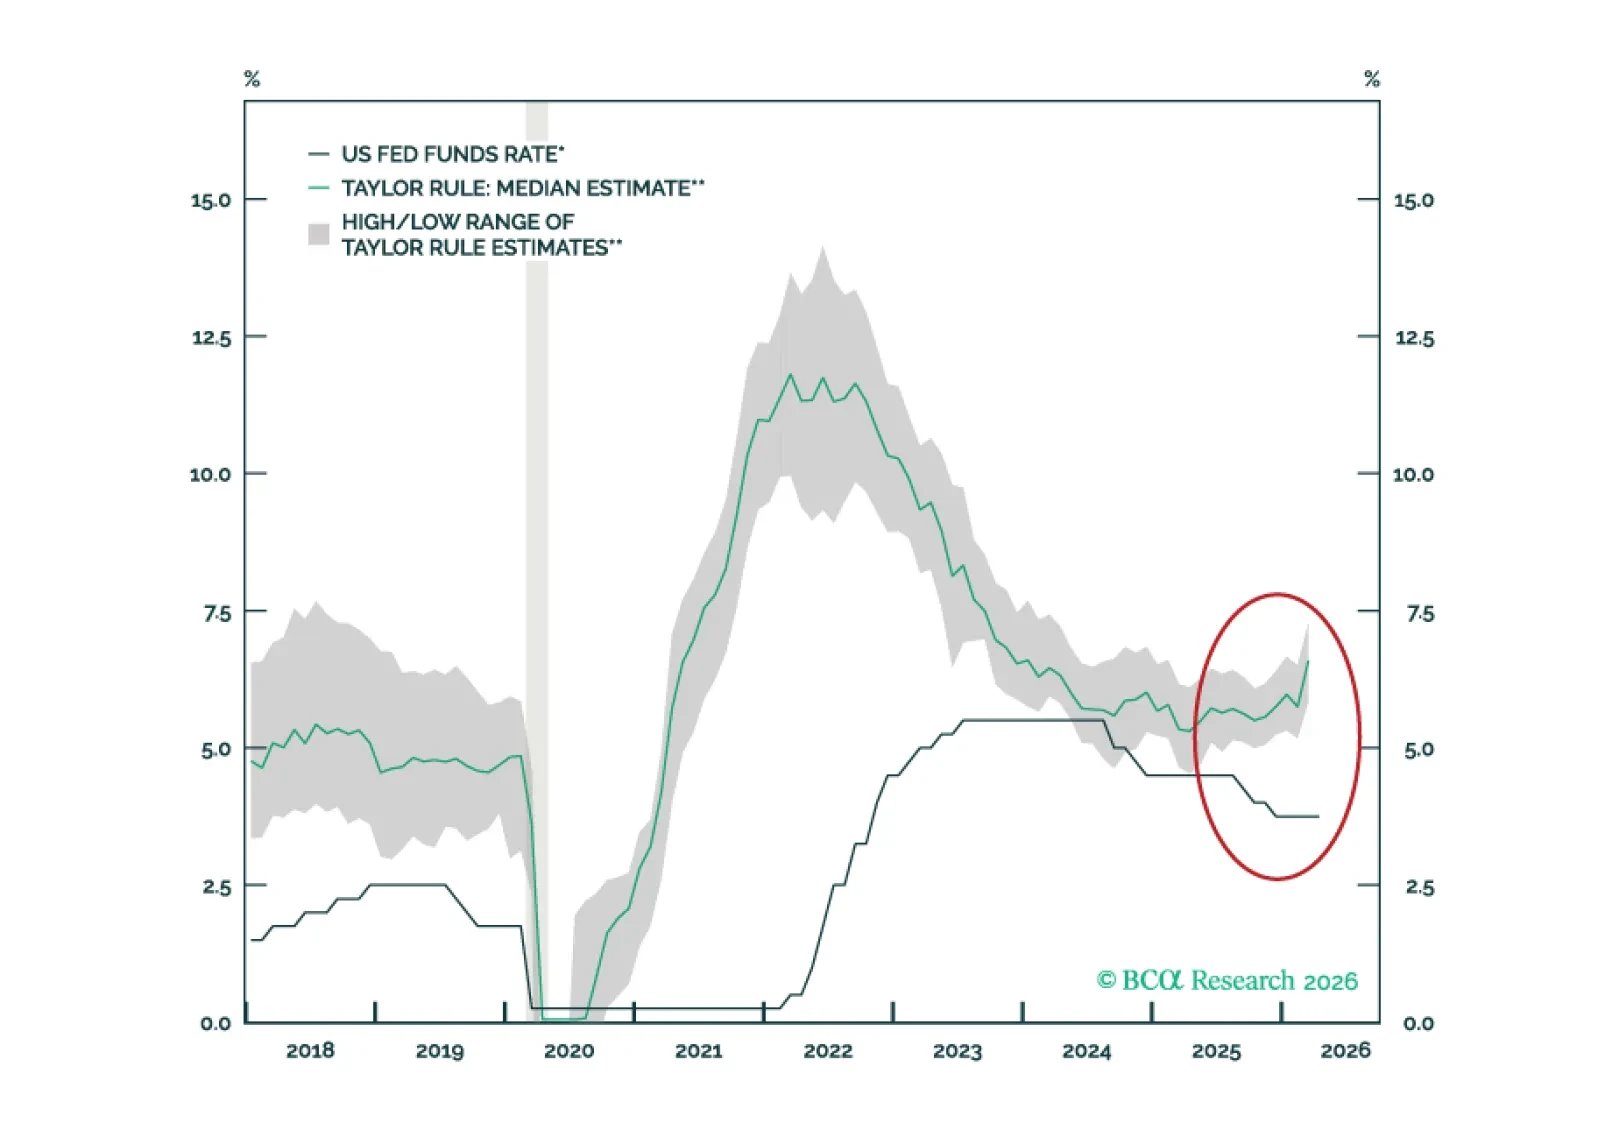
The AI boom will increase inflation in the near term and could also raise it over the long term. The Fed’s reluctance to hike rates is understandable, but it risks amplifying what may already be a brewing stock market bubble.
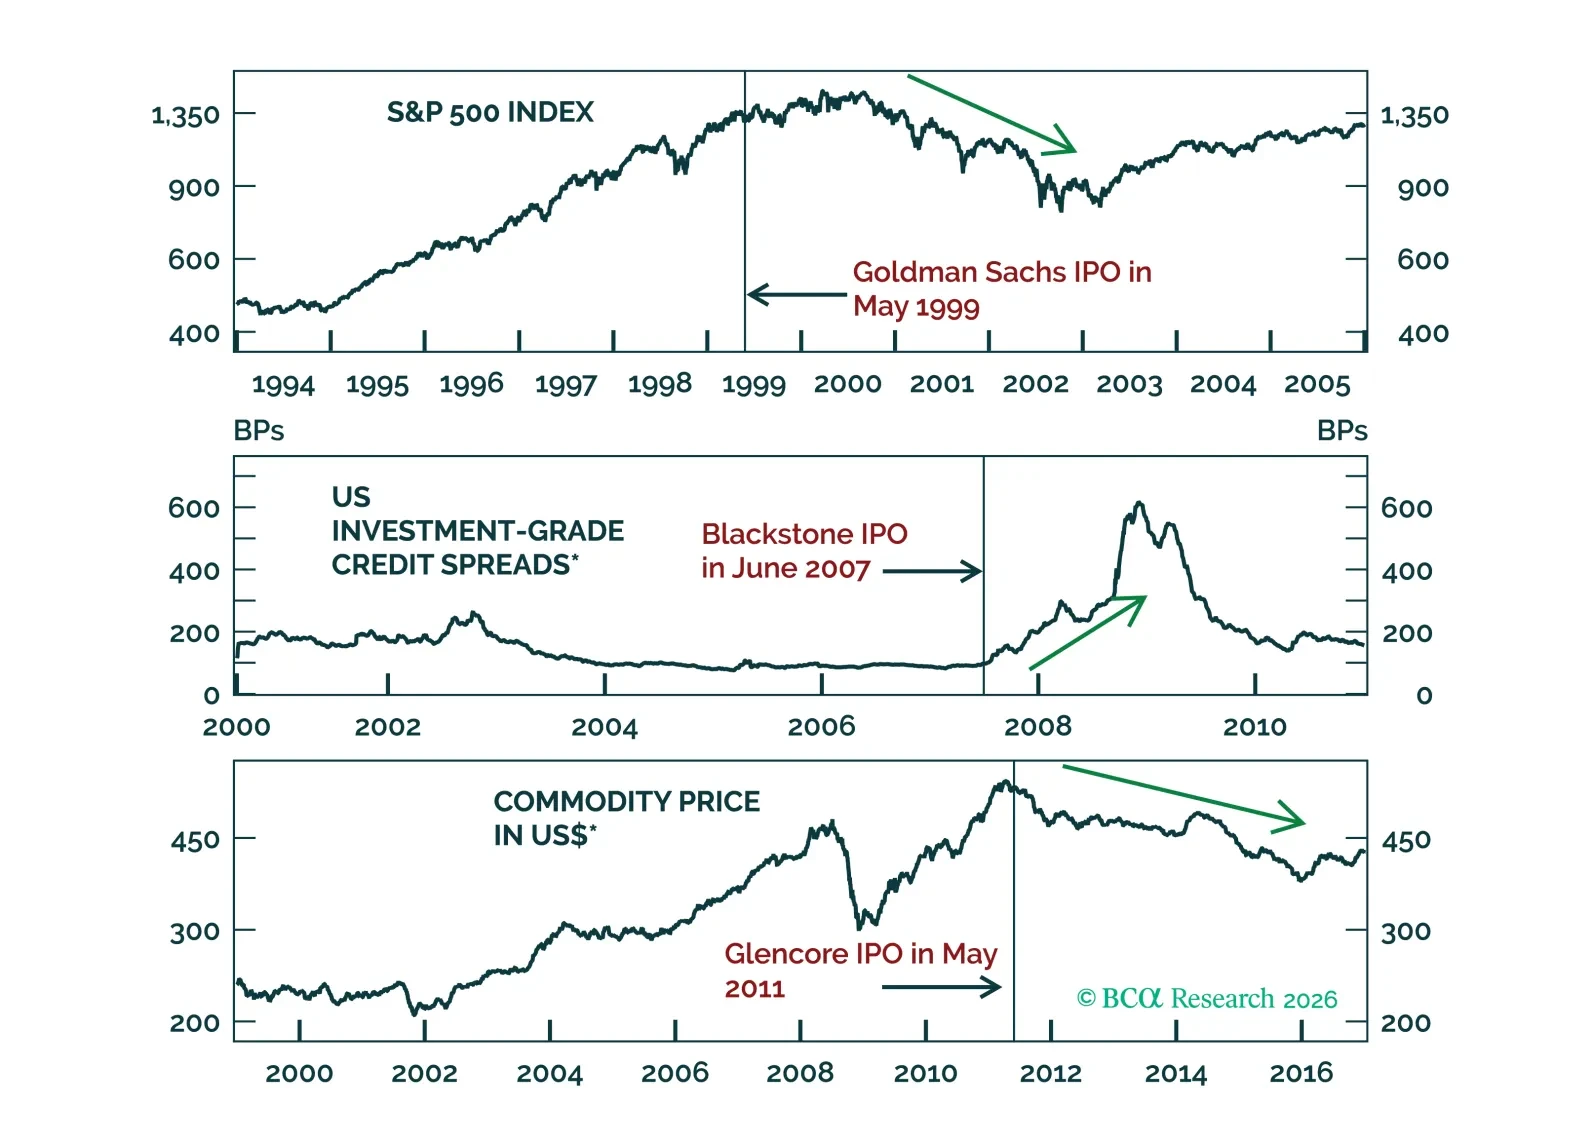
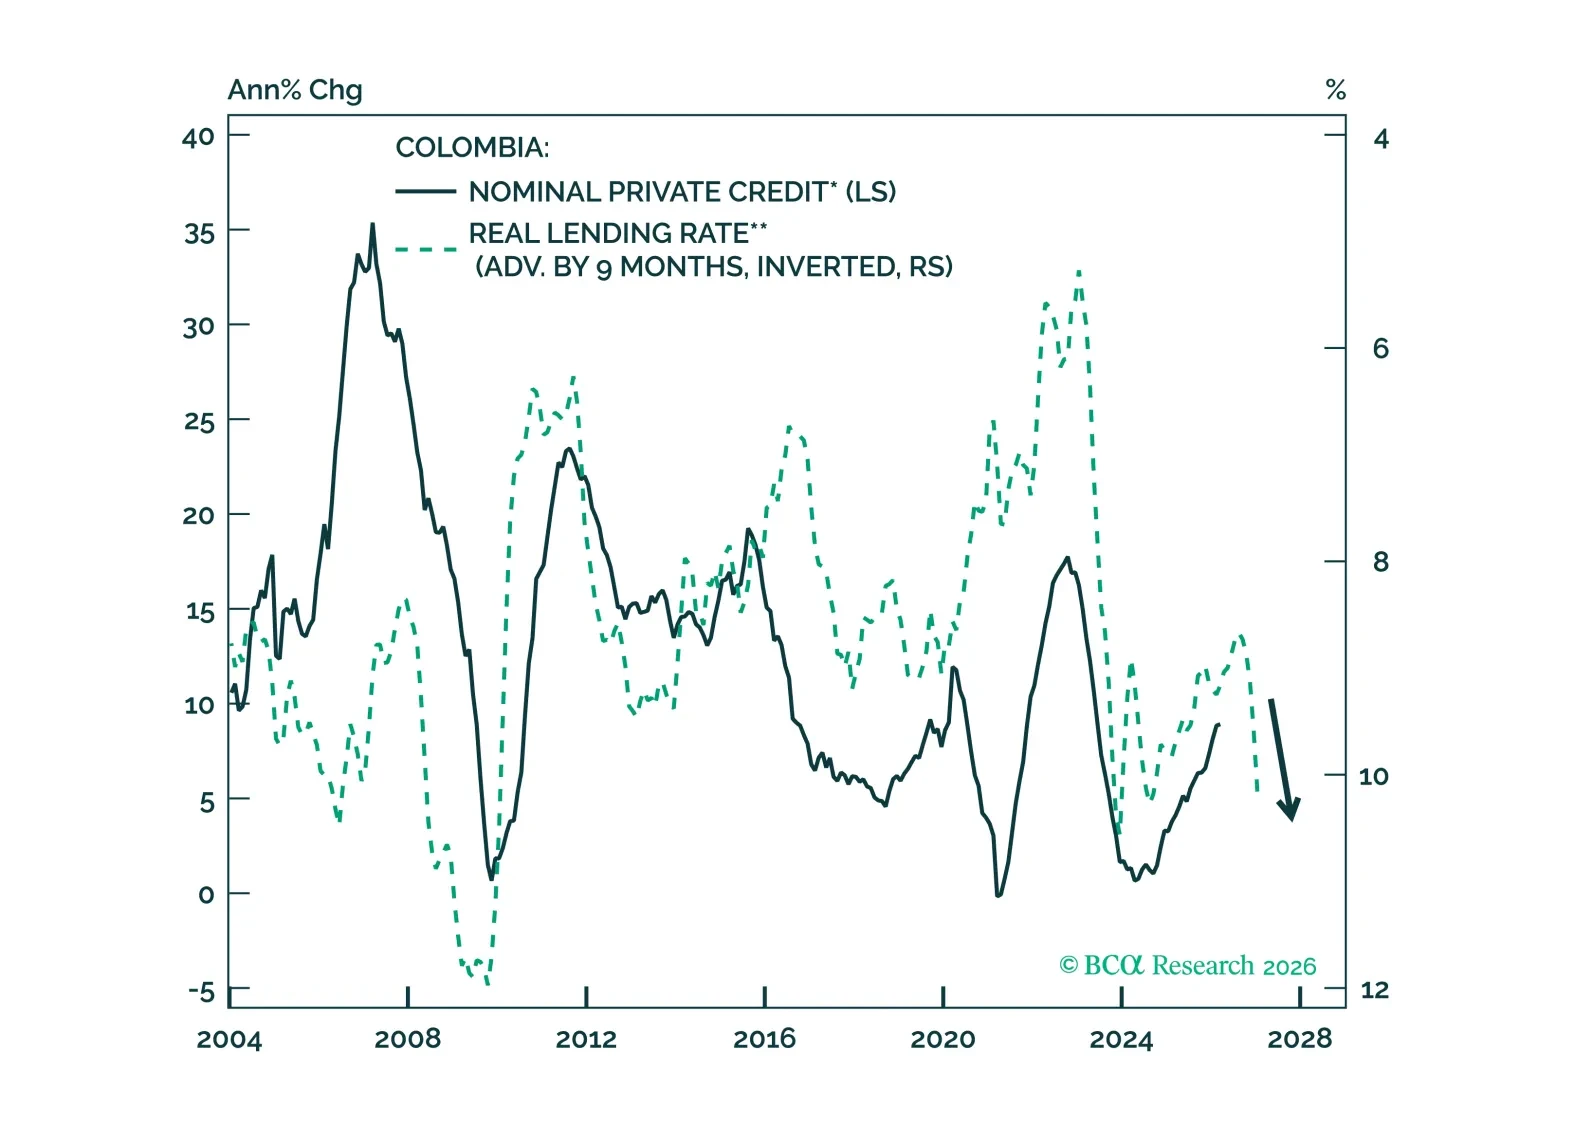
The rally in Colombia’s financial markets has a short shelf life. The election will bring a right-wing government, but it cannot fix inflation, fiscal arithmetic, or balance-of-payments vulnerabilities. Use the near-term rally to downgrade Colombian fixed income and equities.
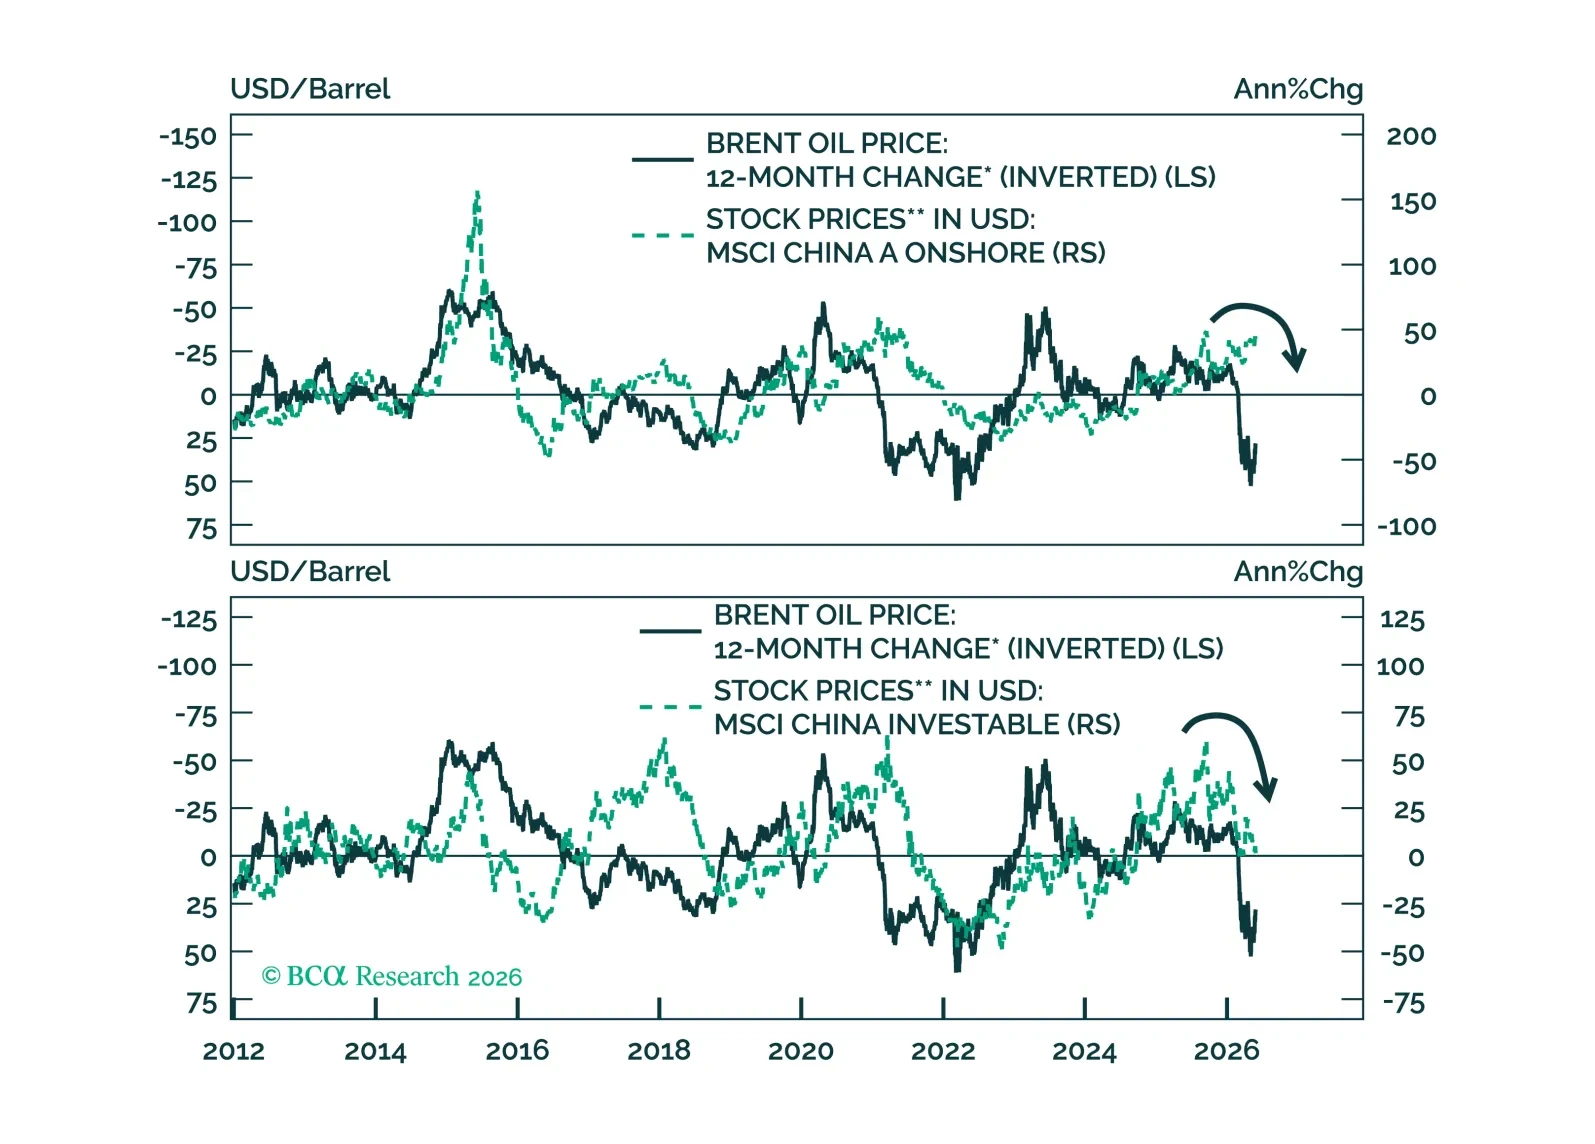
Oil shocks hit economies with a lag. China will feel the delayed pain of surging oil prices, pushing Beijing toward infrastructure spending as its main tool to prop up growth.
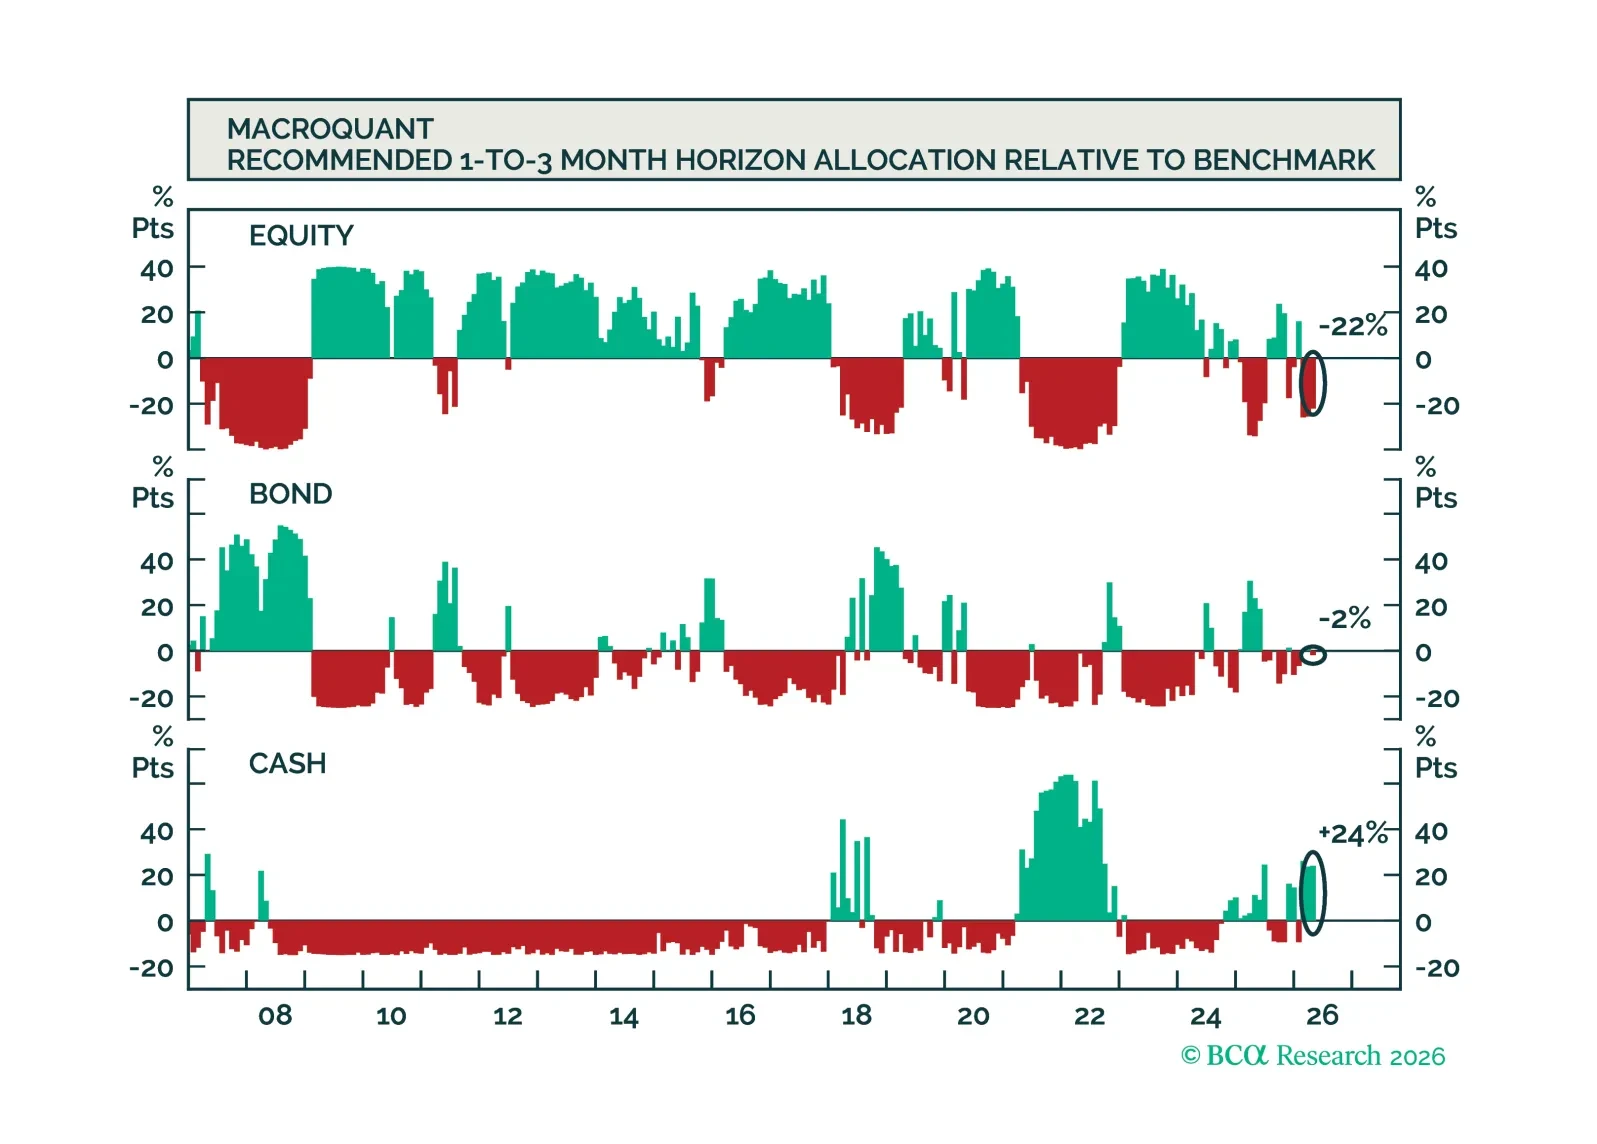
MacroQuant recommends a slight underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is very positive on the US dollar, downgrades gold to underweight, upgrades copper to overweight, and remains very bullish on oil.
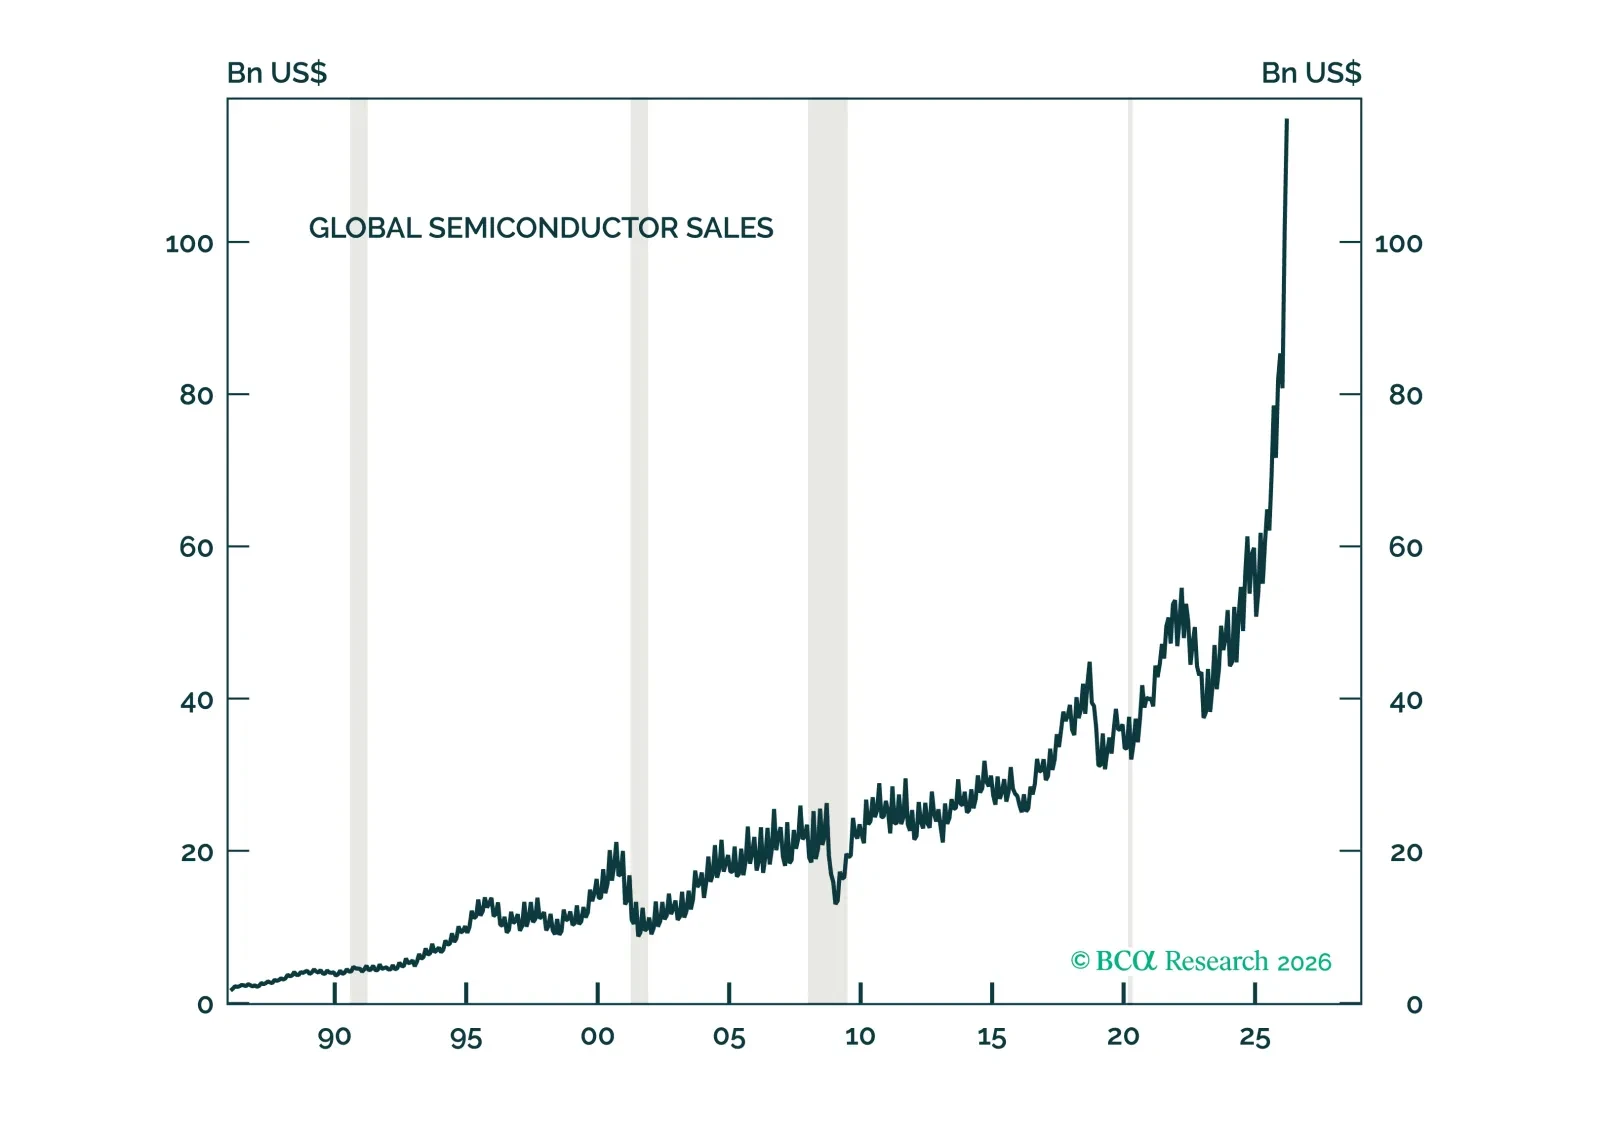
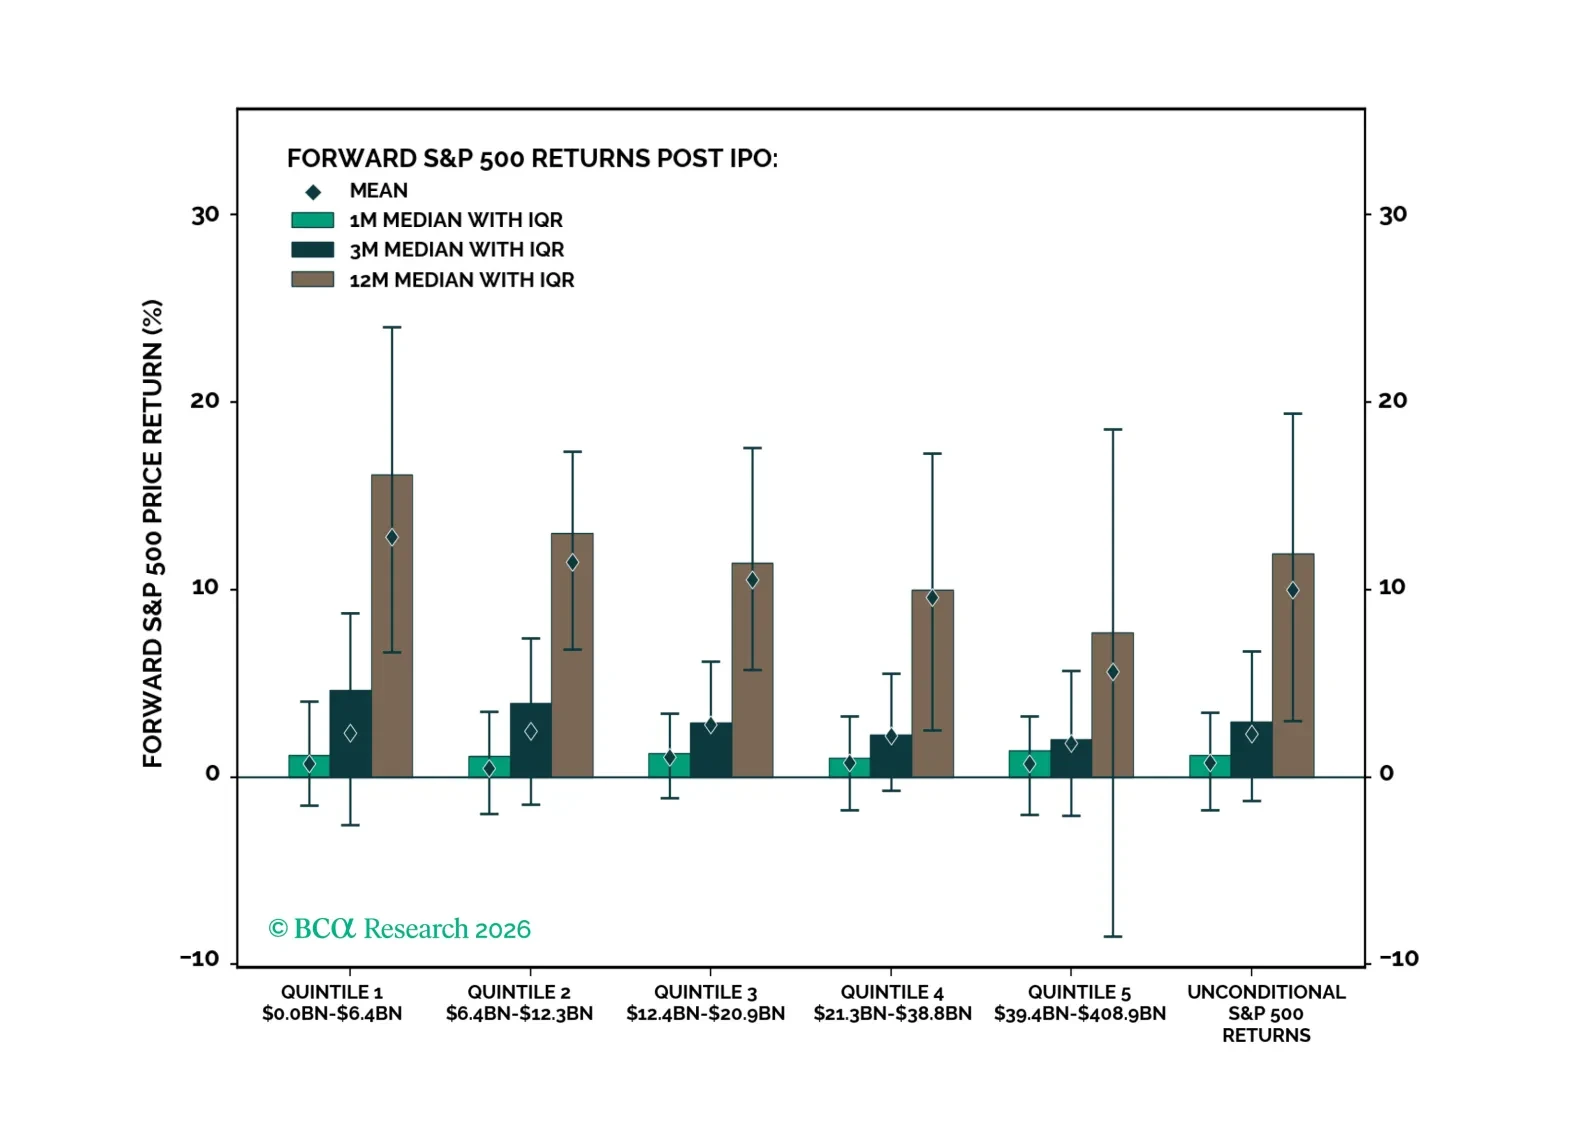
The AI bubble is a different type of bubble. It is primarily an earnings bubble rather than a valuation bubble. Like all bubbles, the AI bubble will burst. For now, however, our AI demand indicators do not suggest that this is imminent.