CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
Last week's blowout jobs report had the beautiful combination of strong growth and flat/rising underemployment rates. This supports our expectation of a Fed hike in December rather than one in September.Accelerating growth when the economy is approaching full employment suggests that the equity bull market is not over, though we are entering a more volatile phase.
The Chinese manufacturing sector has remained under downward pressure, but the stress level has alleviated compared to a few months ago. The Chinese labor market will likely continue to deteriorate, which will force policymakers to stay accommodative. Despite the recent rally, Chinese investable stocks remain exceptionally cheap.
The odds of an inflation "mini-scare" are rising, although deflationary tail risks from abroad cannot be dismissed.
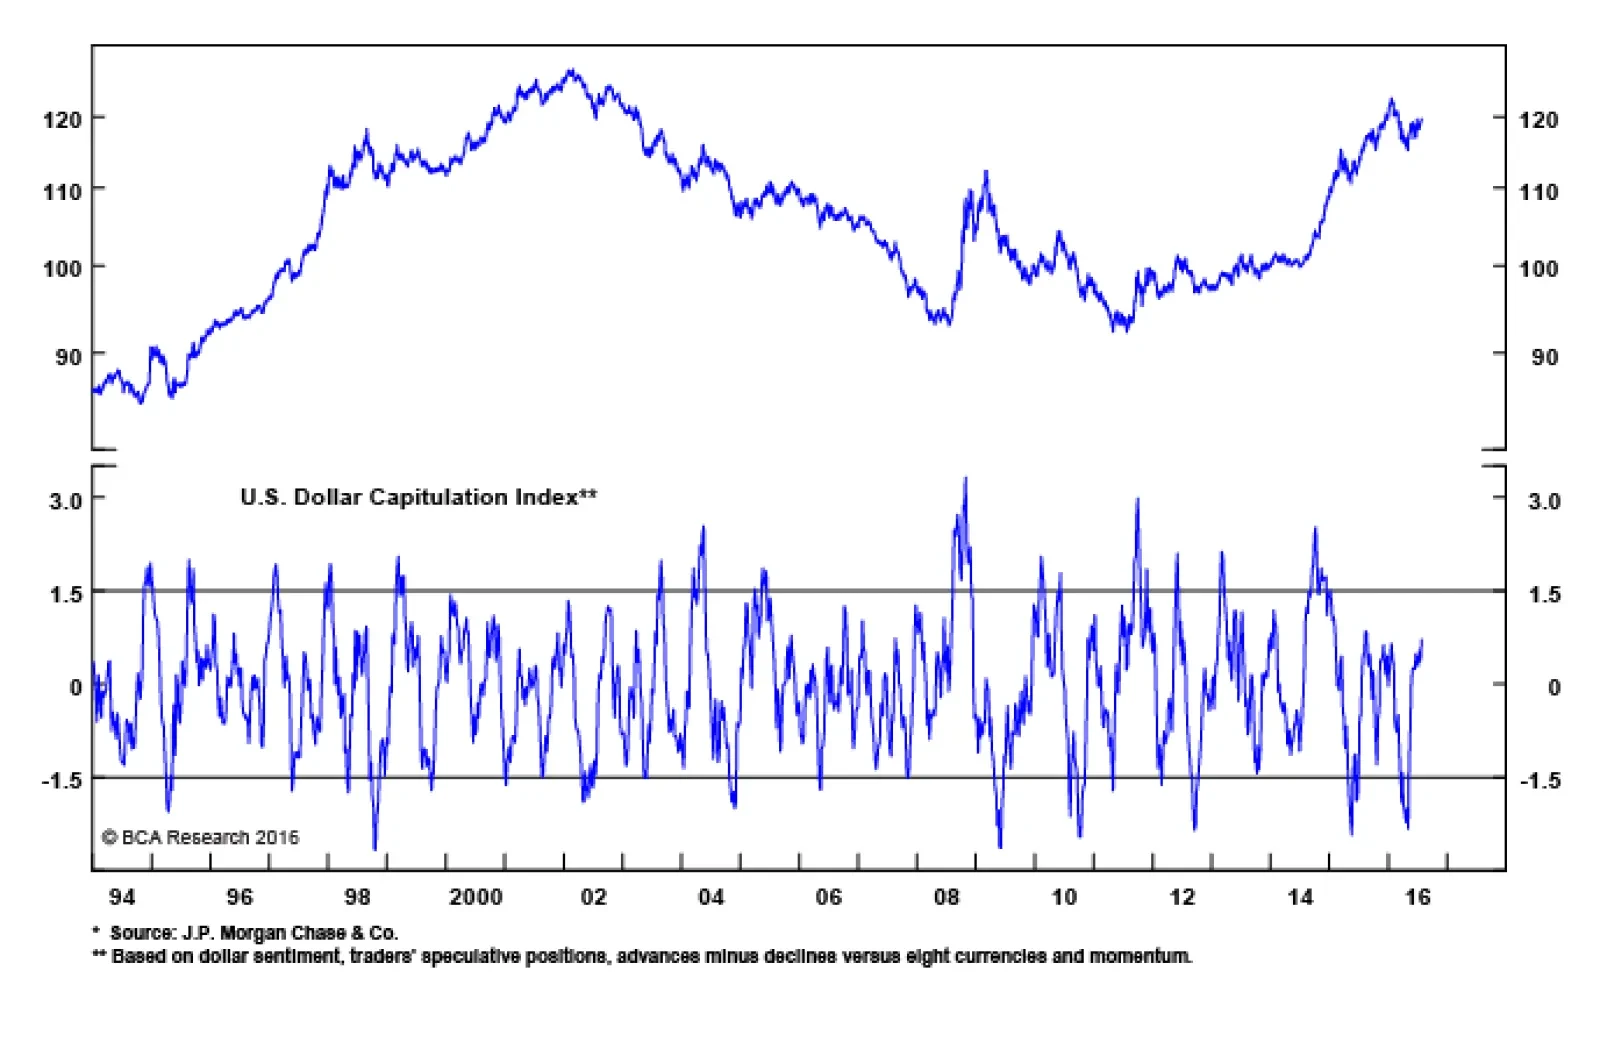
In July, the model outperformed both global equities and the S&P 500 in local-currency terms, while underperforming in U.S. dollar terms. For the monthly of August, the model made no changes to overall risk exposure.
The contours of a deal to solve Italy's banking problems are starting to emerge. This is good news for European risk assets. Nevertheless, reviving Italian growth will require even more ECB easing. The appetite for radical measures is low at present, but this will change if euro area growth remains lackluster and efforts by Japan to introduce helicopter money policies prove successful.
A collection of 10 important charts to monitor closely through the summer months.