 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
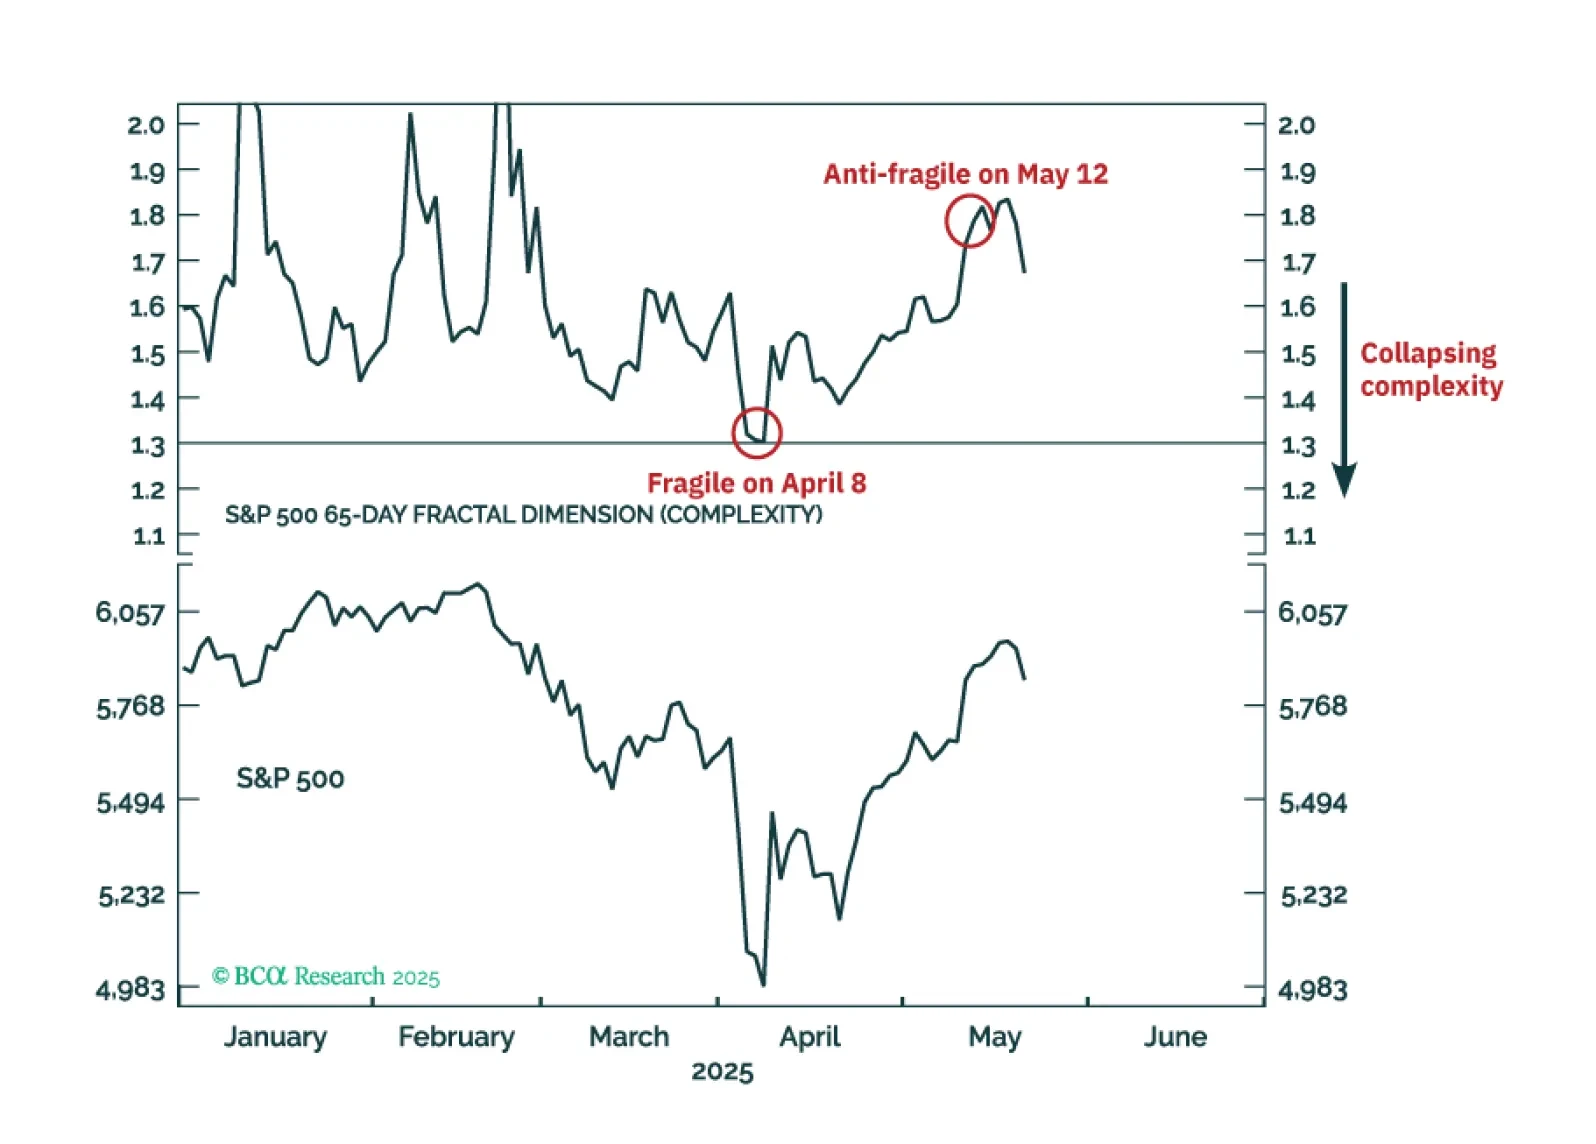
Right now, the major stock and bond markets are more ‘anti-fragile’ than fragile, and the Joshi rule recession indicators signal that a US recession is not imminent. This justifies a neutral, or default, tactical weighting to both stocks and bonds until a major market does become fragile, or until recession risk elevates. The one major price trend that is fragile is the 65-day selloff in the US dollar, which justifies a tactical overweighting to the dollar.

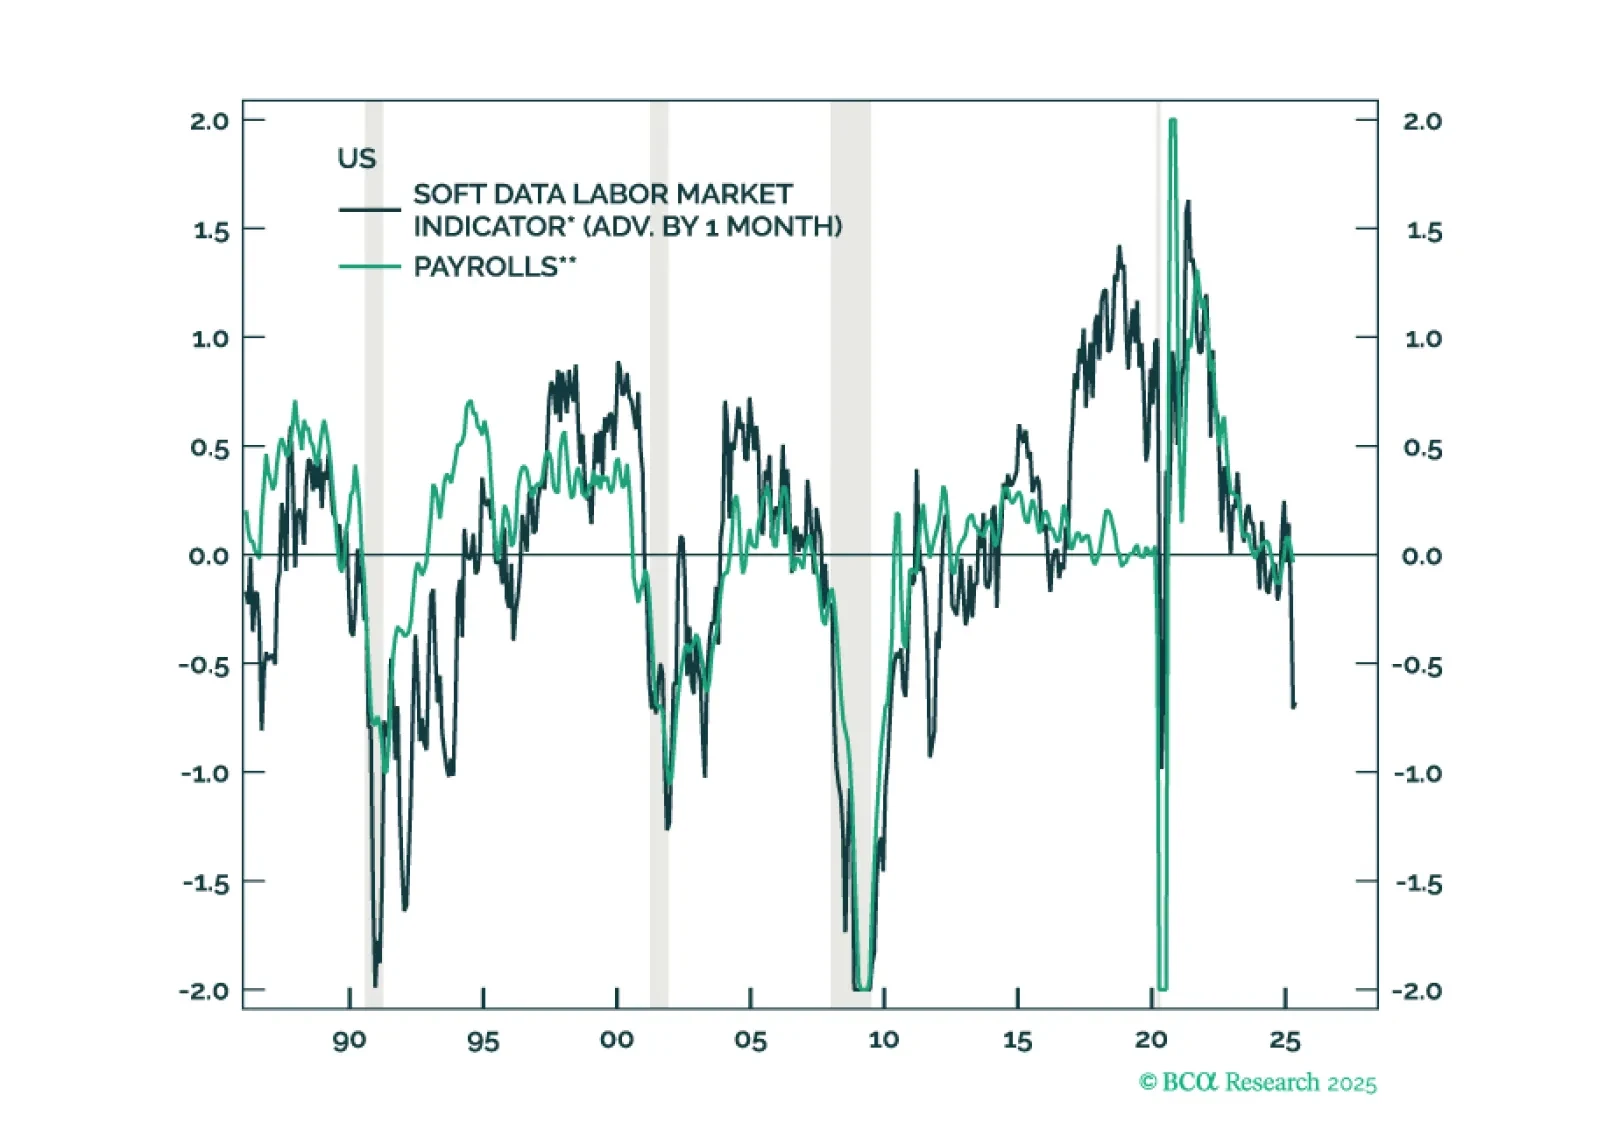
Risk assets rallied hard following the Great Geneva De-escalation, but we are not enamored of risk assets’ risk-reward profile. Forward-looking survey data remain awful on balance and we continue to recommend a defensive asset allocation profile.
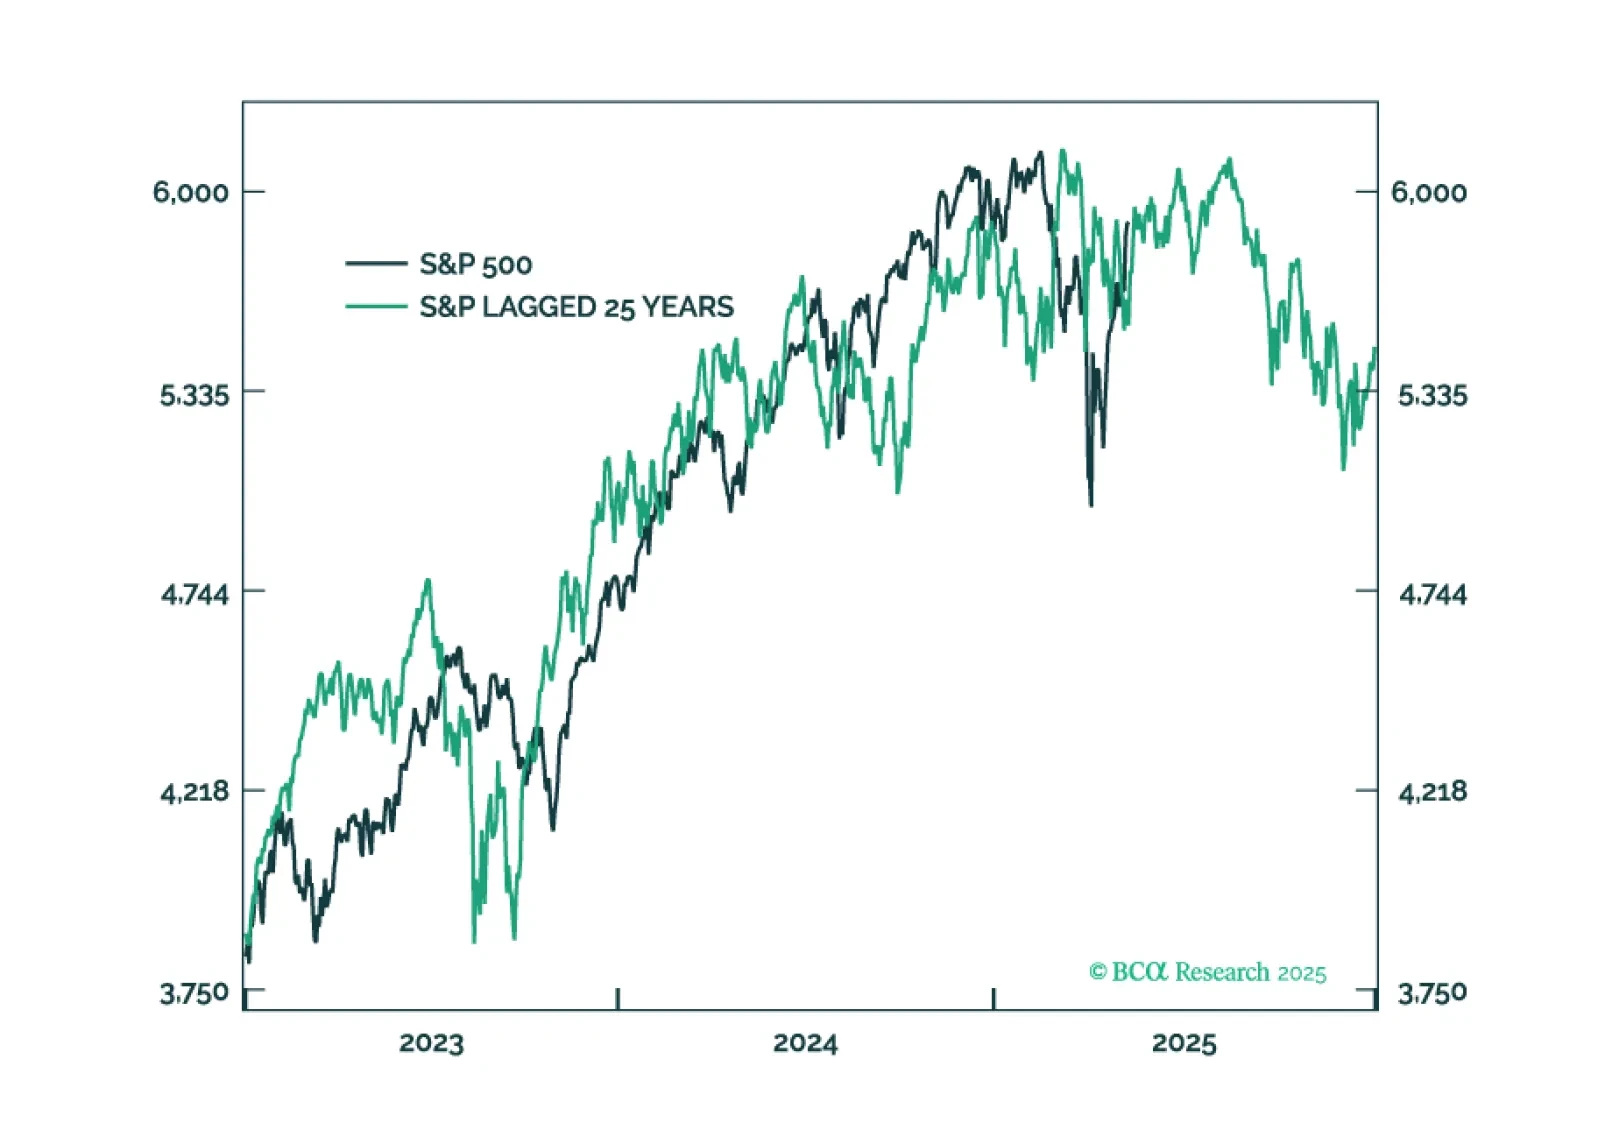
This year’s plunge in tech stocks followed by the recent strong countertrend rally is eerily reminiscent of 2000. But the market and economic parallels between 2025 and in 2000 run much deeper. This report lists 10 striking parallels between 2025 and 2020, then highlights some important differences, and ends by describing how the rest of 2025 might unfold based on a playbook that is: 2025 = ‘2000 with some tweaks.’
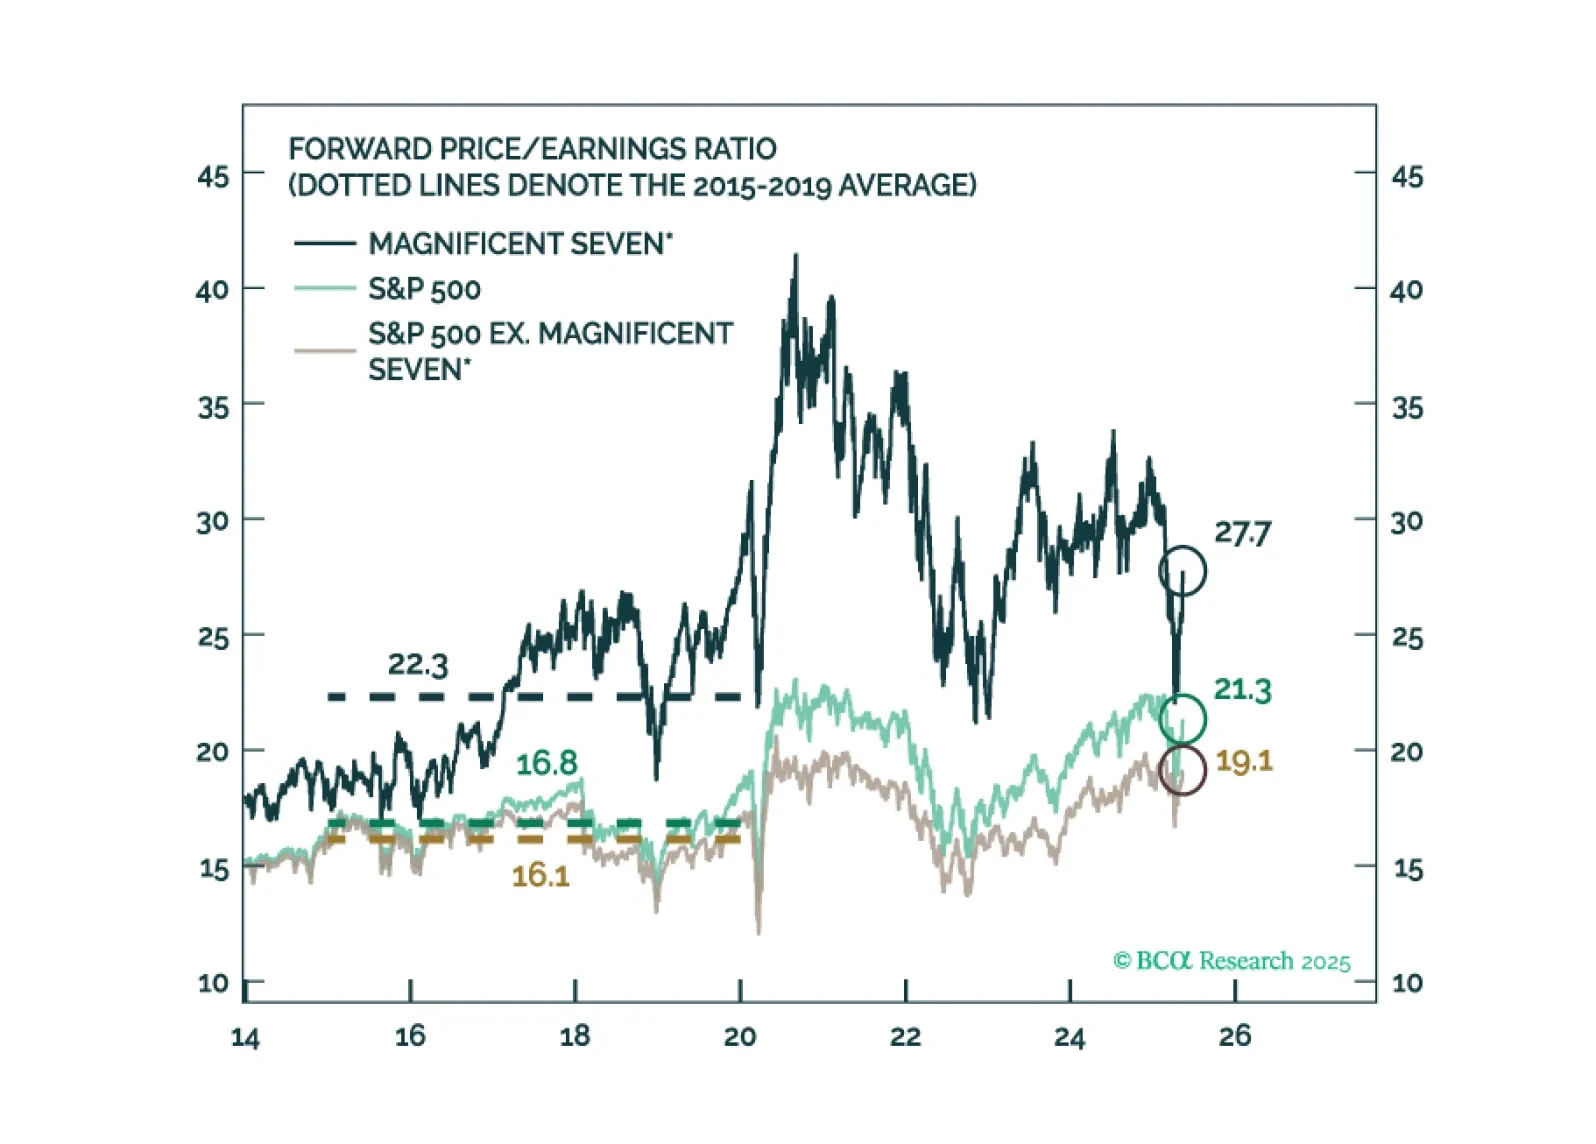
Although tariffs have receded, they are still high enough to weigh on growth, especially given that underlying economic momentum in the US was weakening going into 2025. The possibility of a fiscal crisis only adds to the risks.
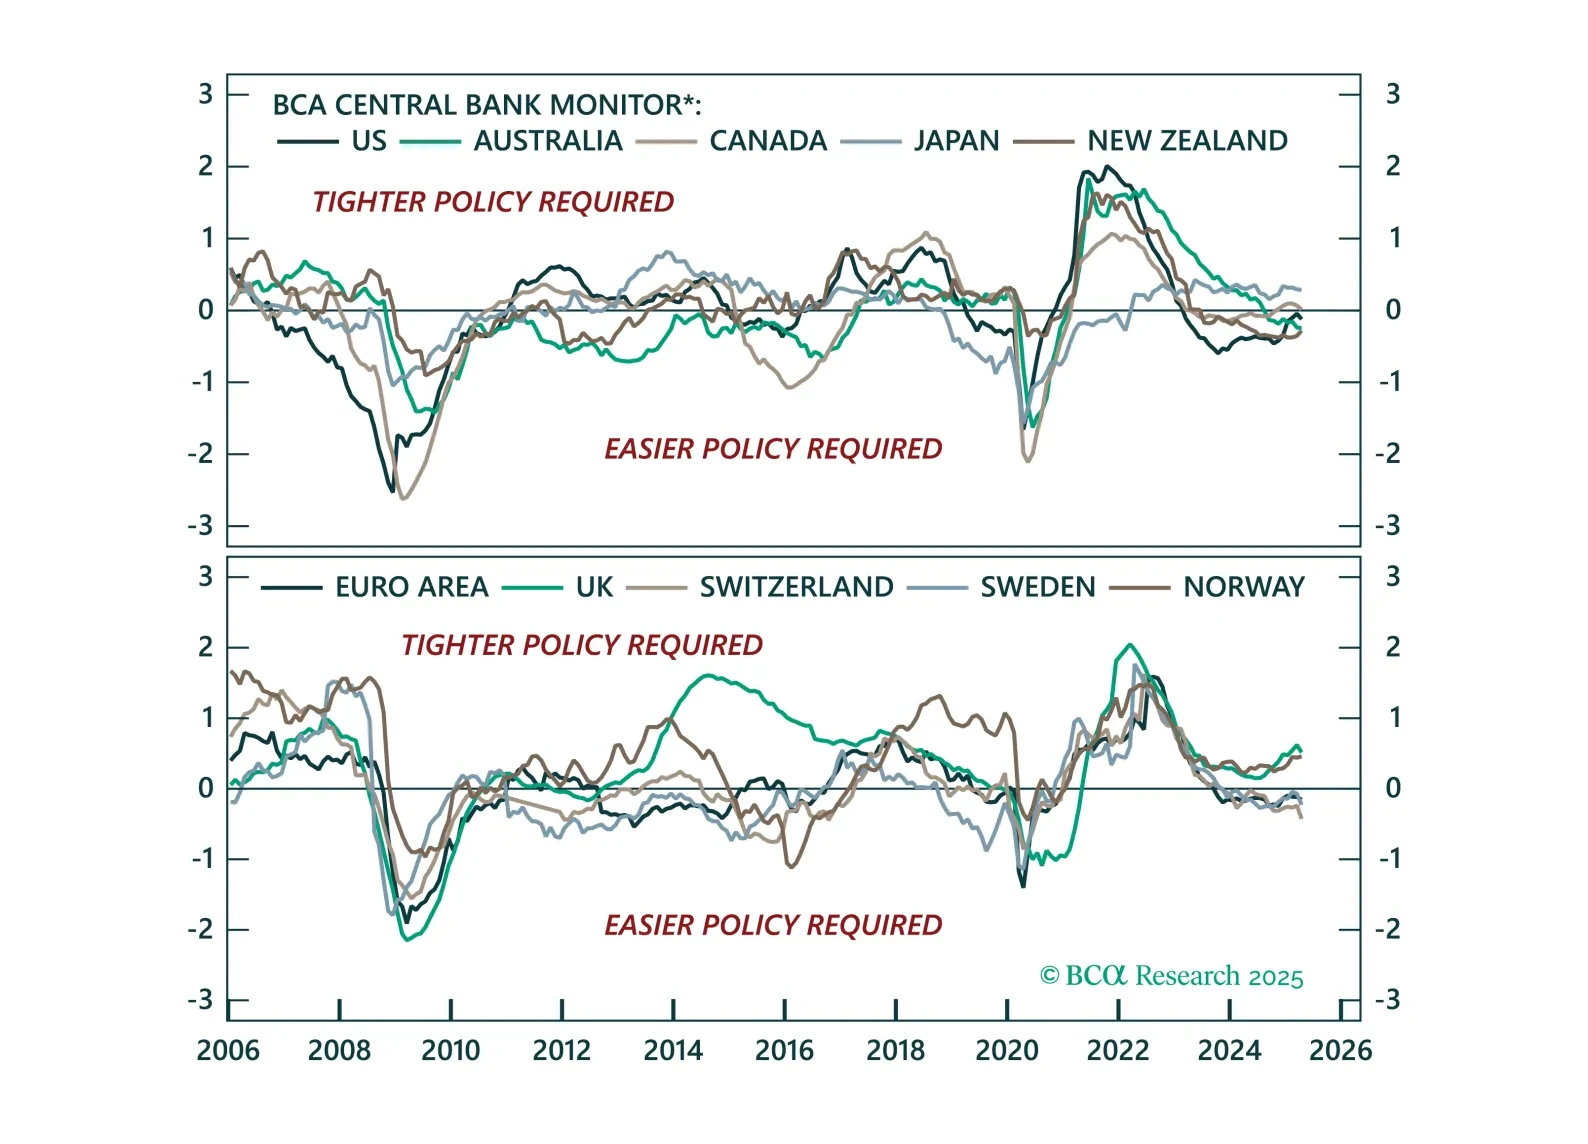
The easing bias remains, but not all central banks are equal. This Central Bank Monitor update reveals who is ready to cut more and who is still pretending not to.
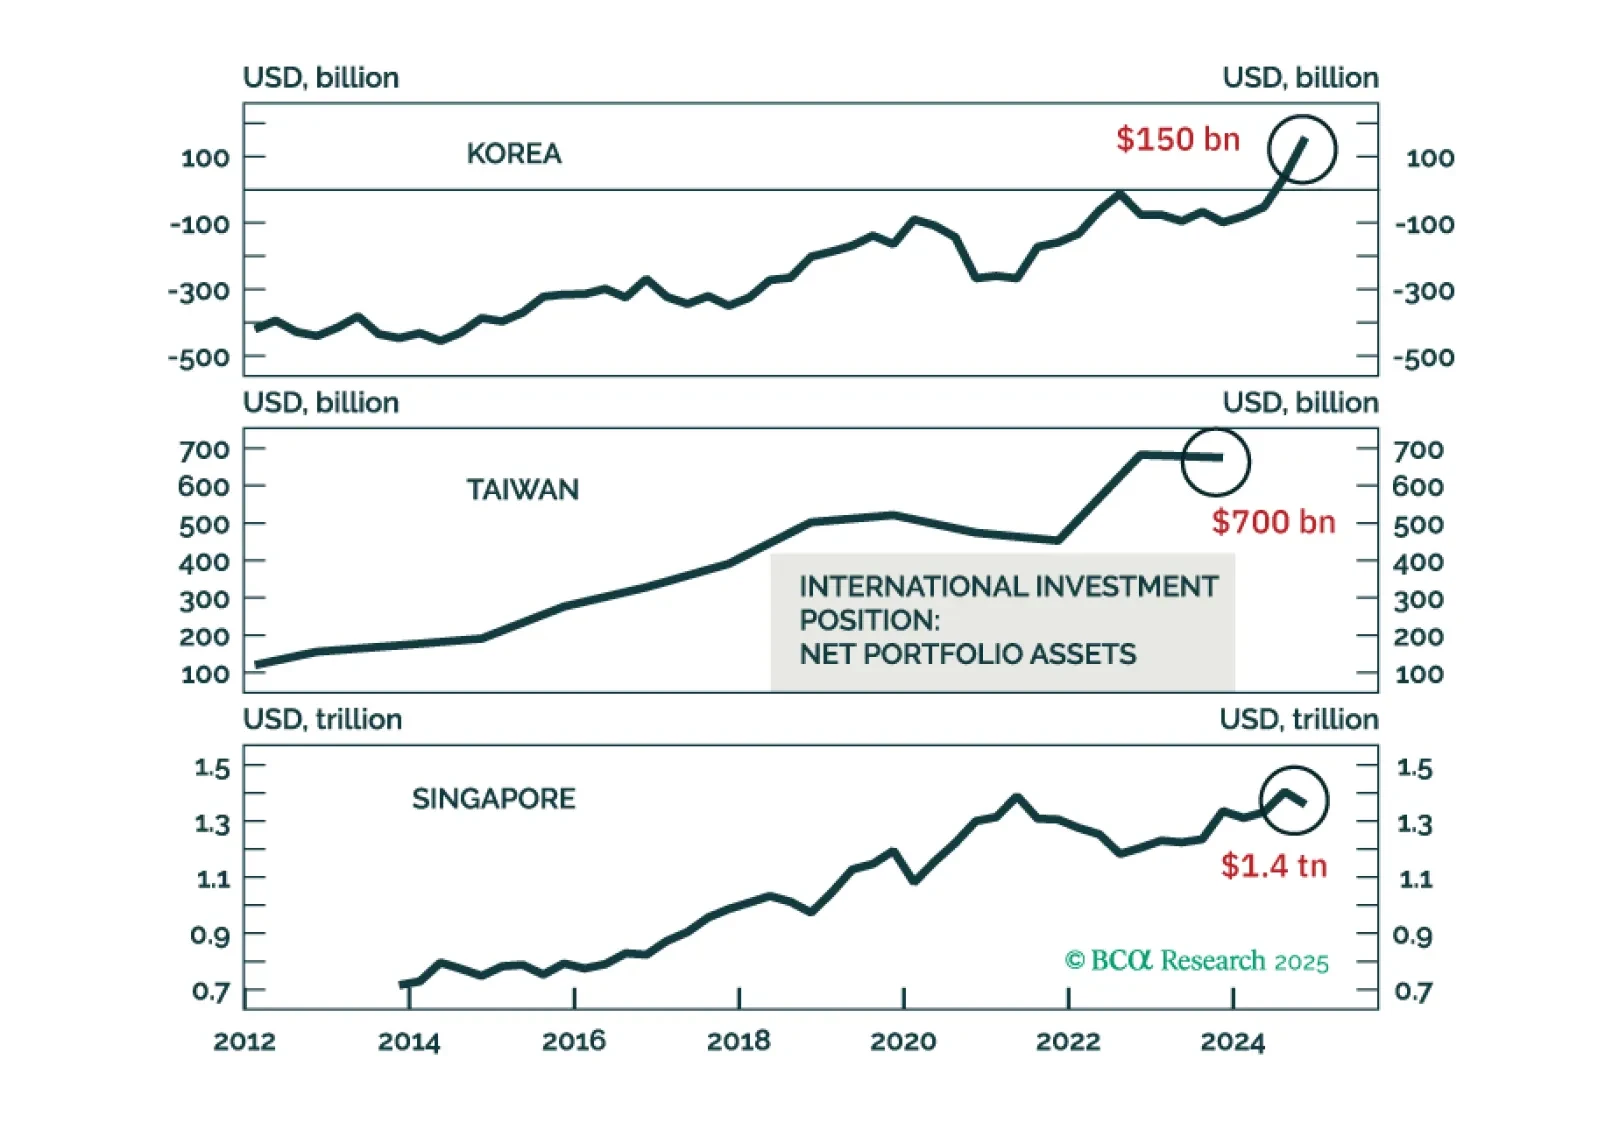
Taiwan, Singapore, and Korea's currencies might appreciate versus the USD, driven by capital repatriation from domestic private investors away from the US. This thesis is less pertinent to India, Indonesia, and the Philippines because they have large net foreign portfolio liabilities. Malaysia and Thailand fall in the middle, while China is an exception. Investors should play intensifying deflationary pressures in Asia by betting on lower interest rates in the region.
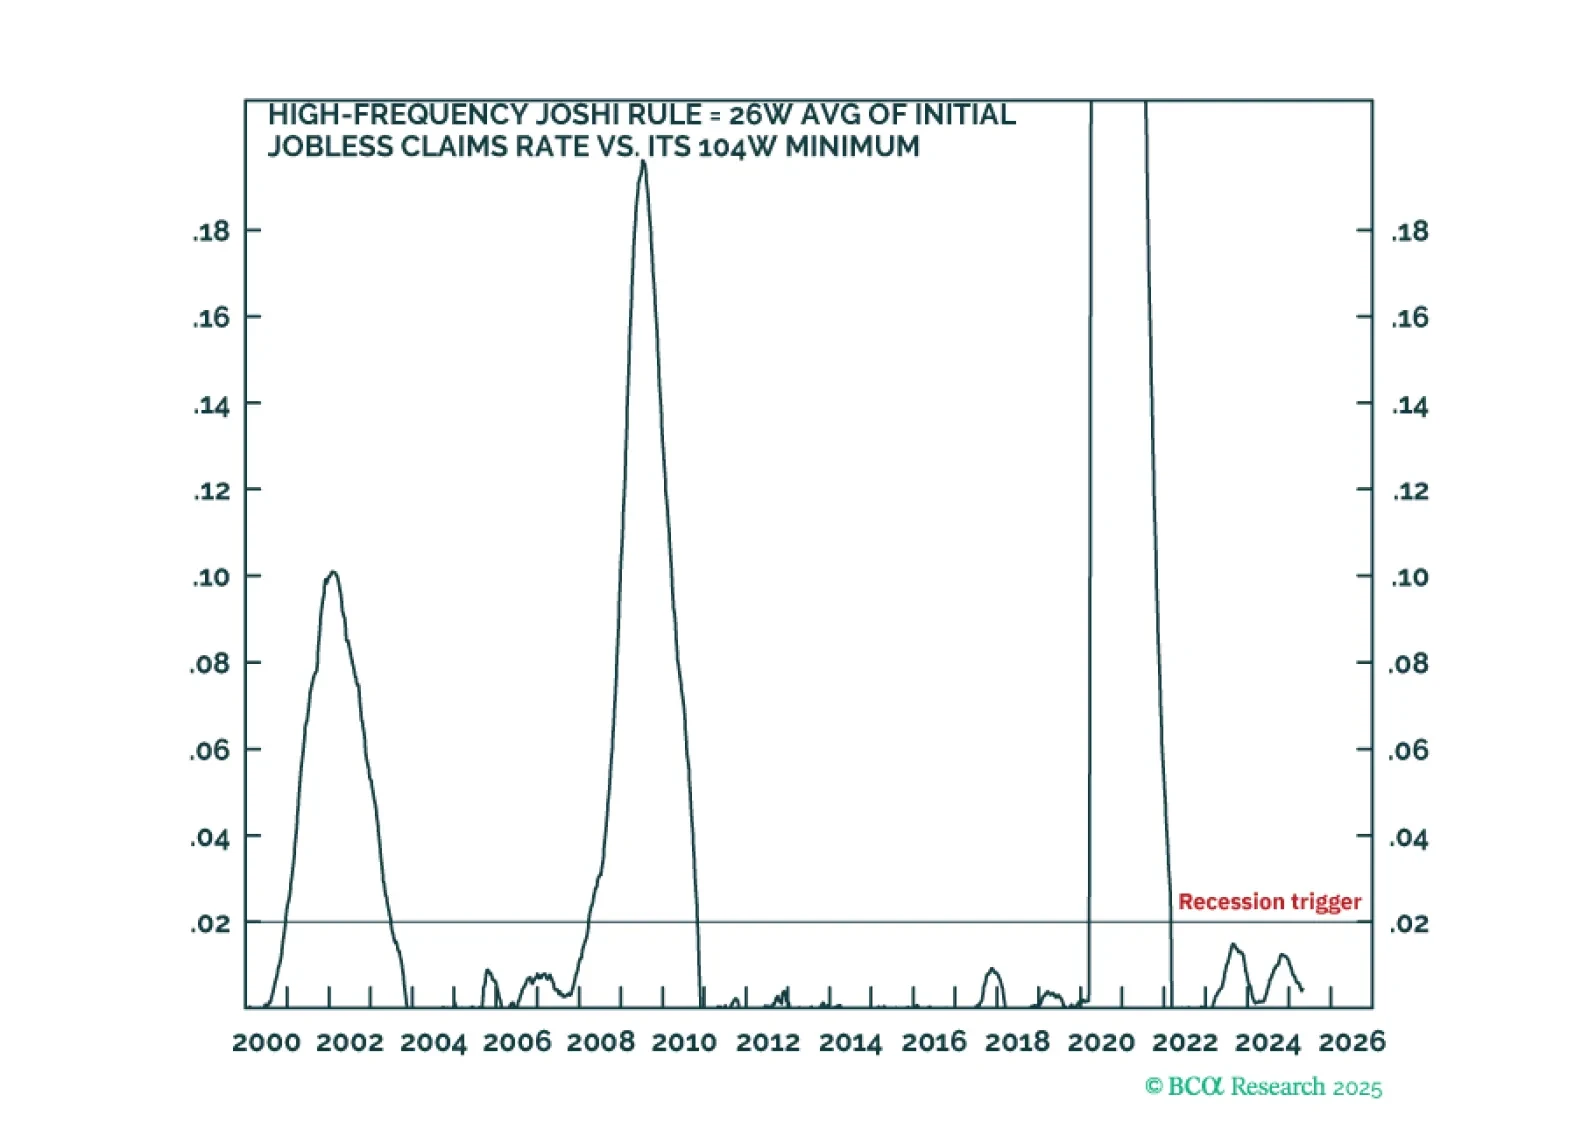
Today, we are introducing an additional ‘high-frequency Joshi rule’ which is updated weekly. The Joshi rules tell us that a US recession is not imminent. Until the Joshi rules are triggered, overweight non-US government bonds, and especially UK gilts, versus US T-bonds. And shift cyclical asset allocation from overweight to neutral-weight bonds. Plus: tactically long USD/GBP and tactically underweight global industrials (EXI).