CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
In his latest Thoughts Of The Day, Peter Berezin discusses the different moving parts of the global economy today and the potential impact of Trump's policies.
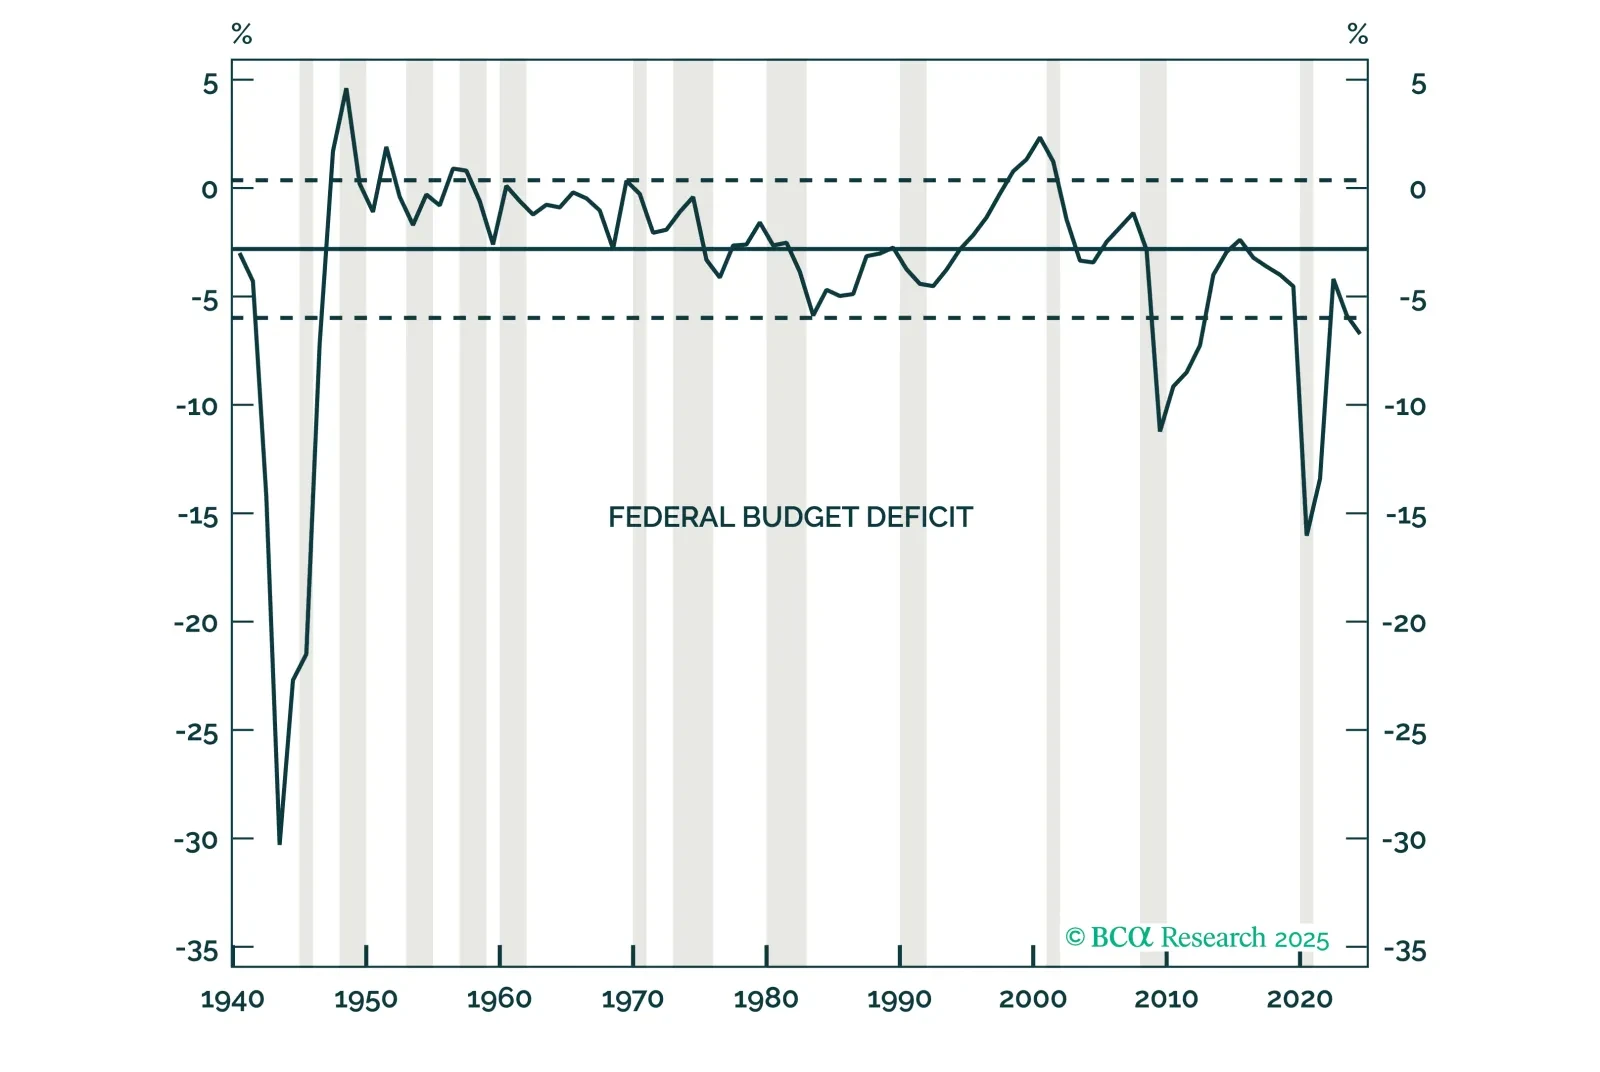
The 3-3-3 plan pitched by Treasury Secretary Scott Bessent will need several improbabilities to break its way if it is to meet its goals. We think it is much more likely that the plan will disappoint. Defensive asset allocations will outperform once it becomes clear that 3-3-3 will fall short, but we are currently neutral across the board because the disappointment may be months away.
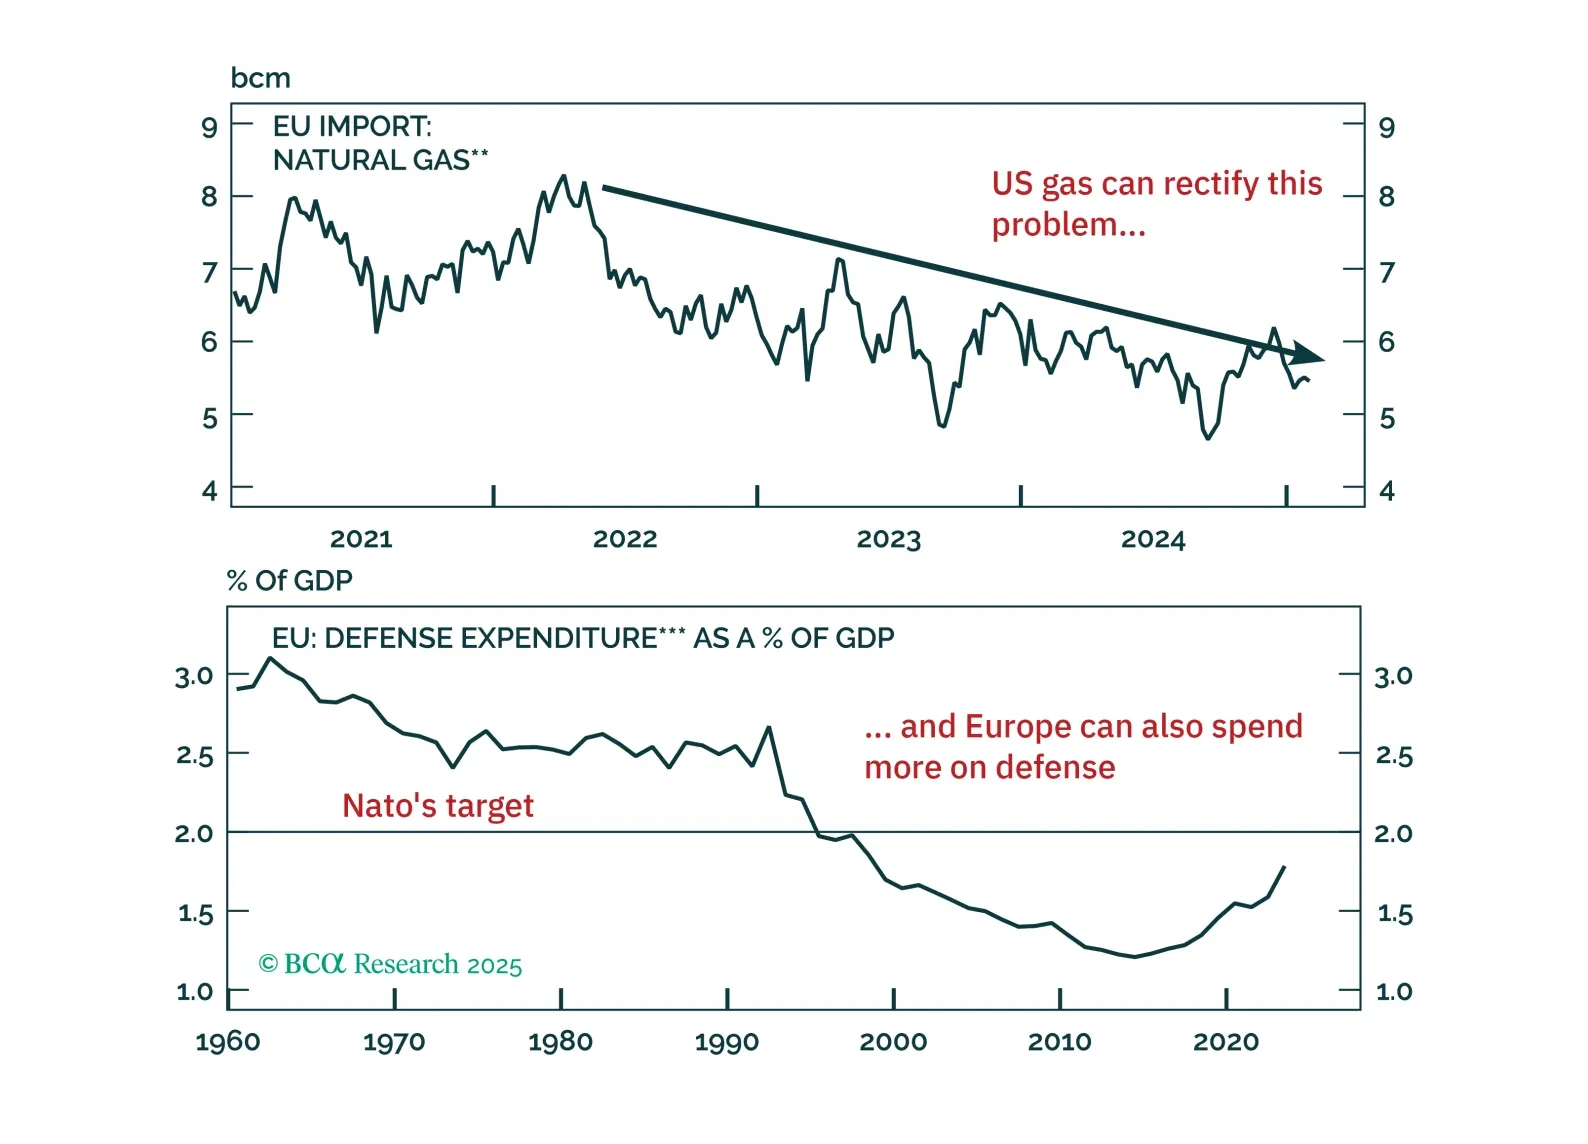
Europe is about to become President Trump’s next target. The good news: a US/EU trade war will be short as common ground to achieve a deal exists. The bad news: European assets remain at the mercy of heightened uncertainty. How should investors position themselves in this tricky context?
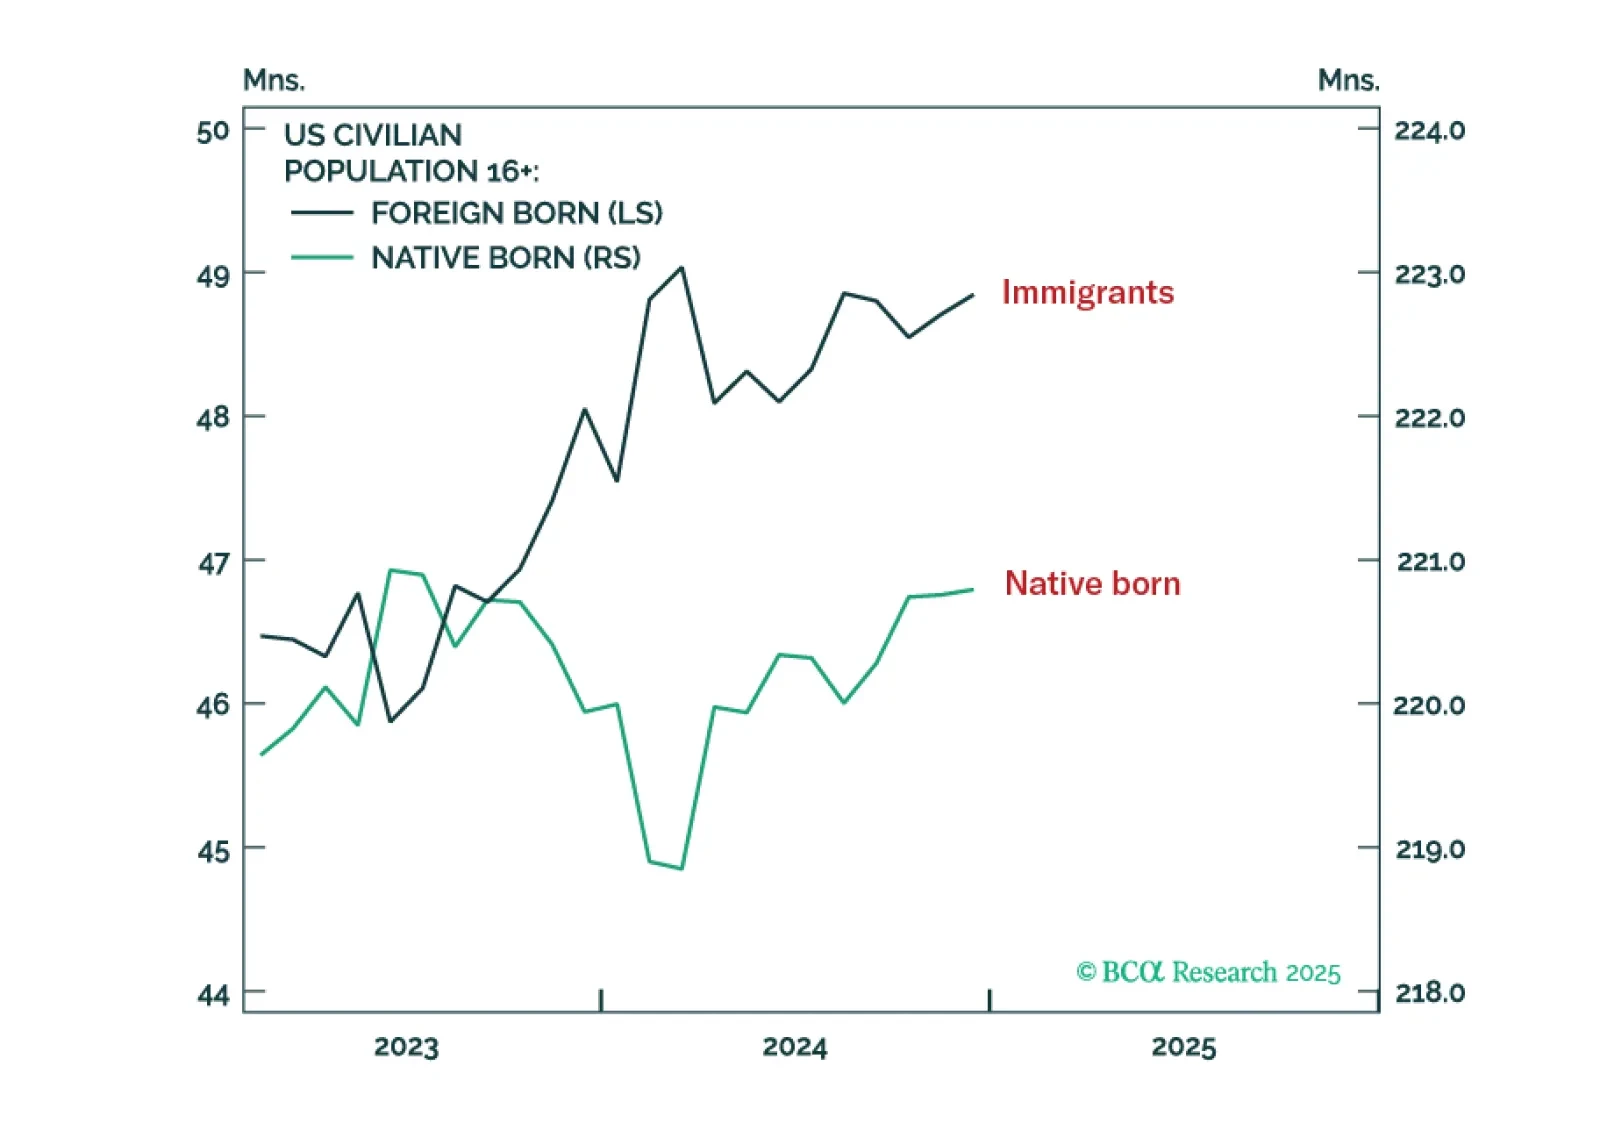
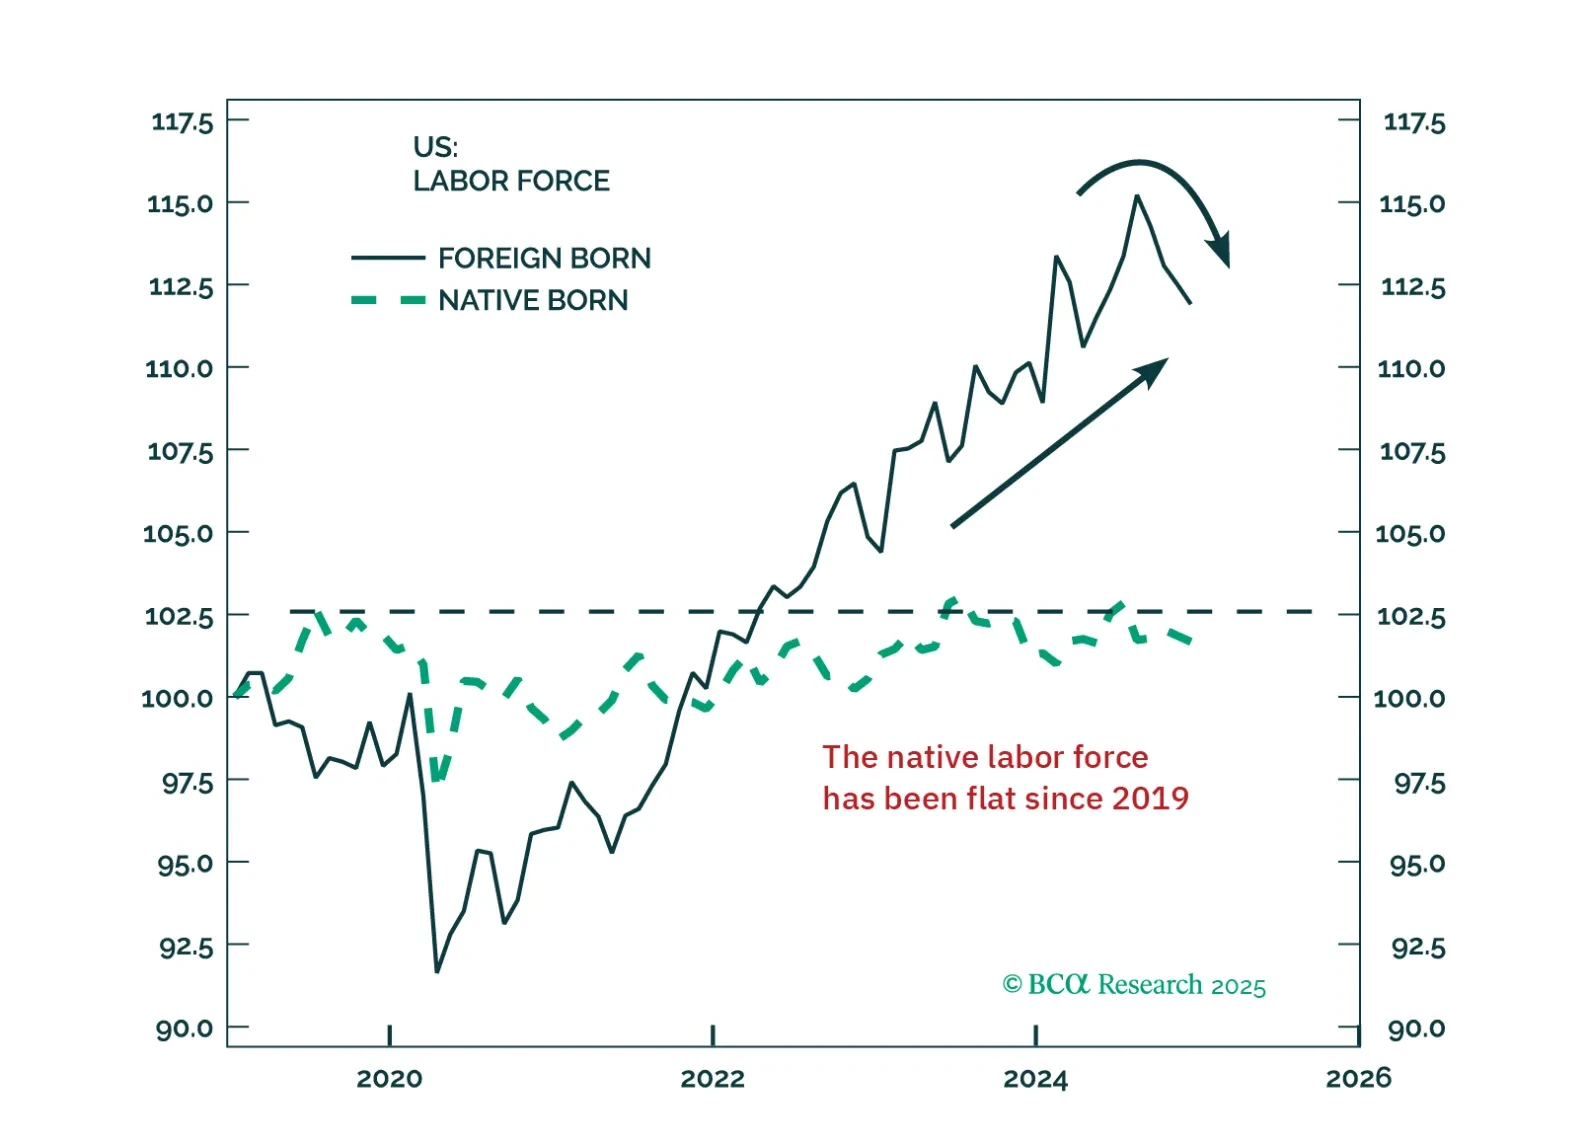
All the growth in the US labour supply since mid-2023 has come from immigration. This means if net immigration comes to a grinding halt, as Trump wants, it will hurt economic growth as well as keep the labour market supply-constrained. An increase in productivity growth could save the day, both to maintain growth and to kill inflation. Yet hopes that AI is about to usher an imminent and sustained boost to productivity growth are misplaced. Hence, expect a slowdown in US growth combined with inflation stuck close to 3 percent, a combination that I call a ‘mini stagflation’. We go through the investment implications. Plus: Tactically overweight Portugal versus Europe.
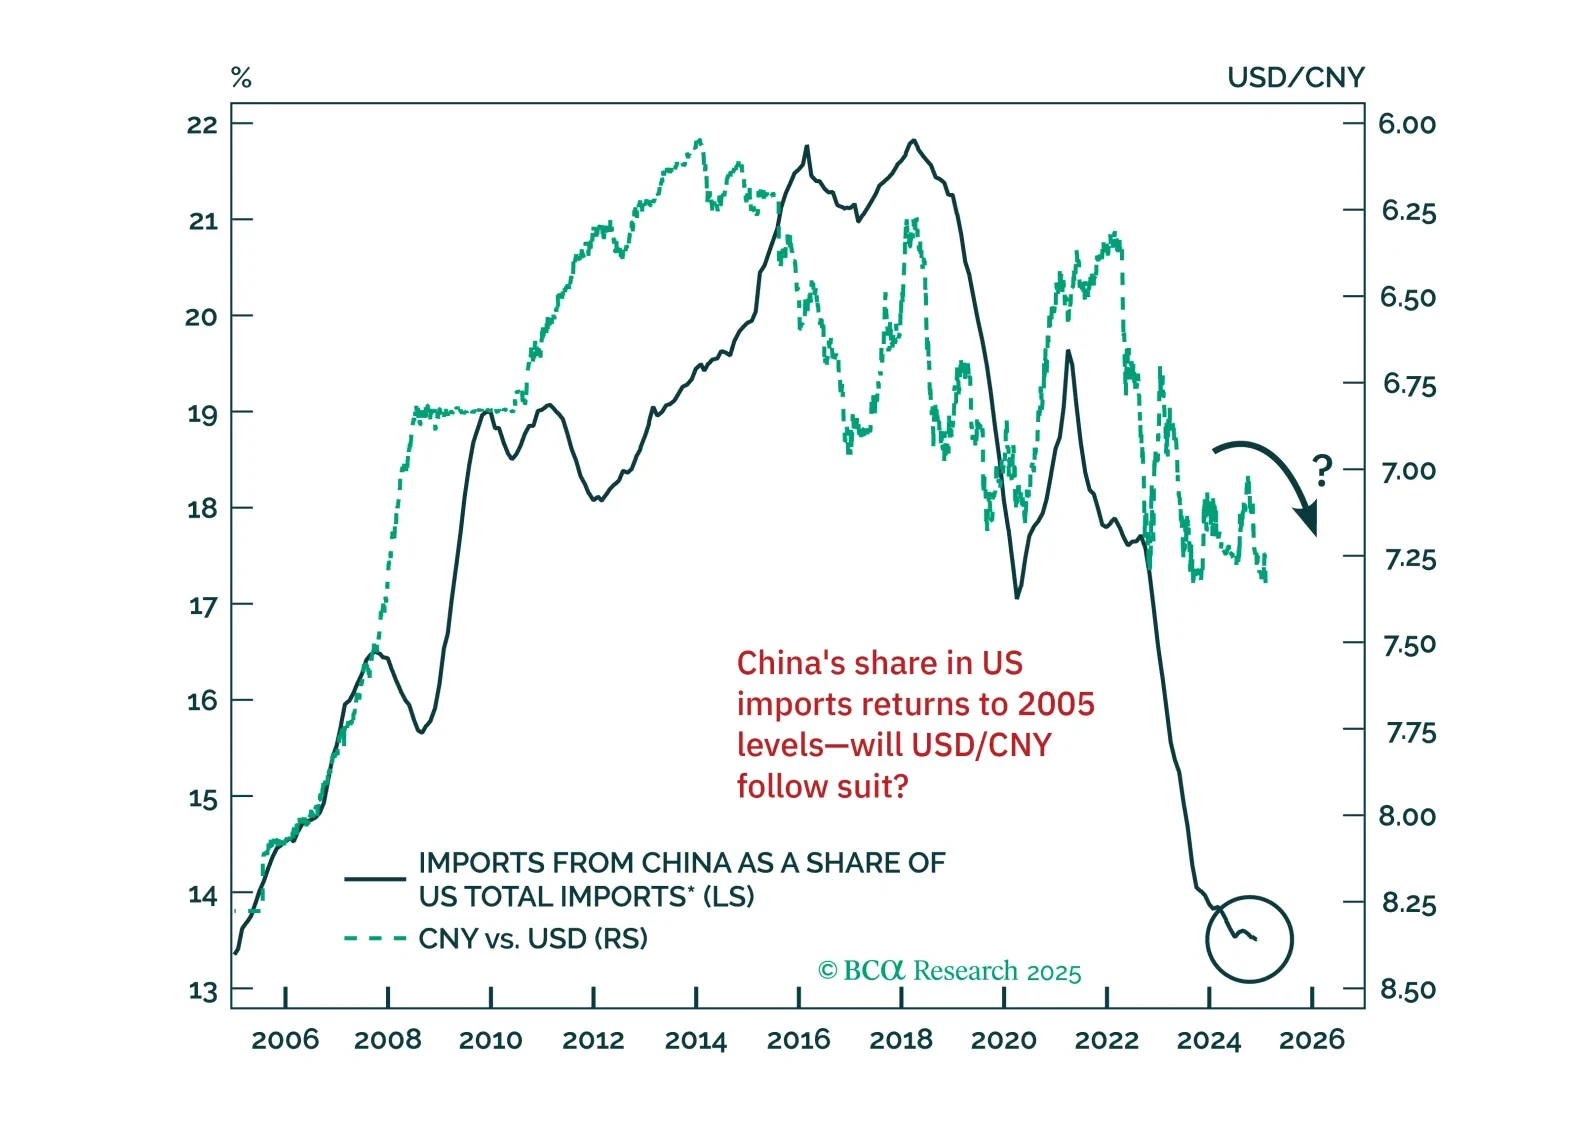
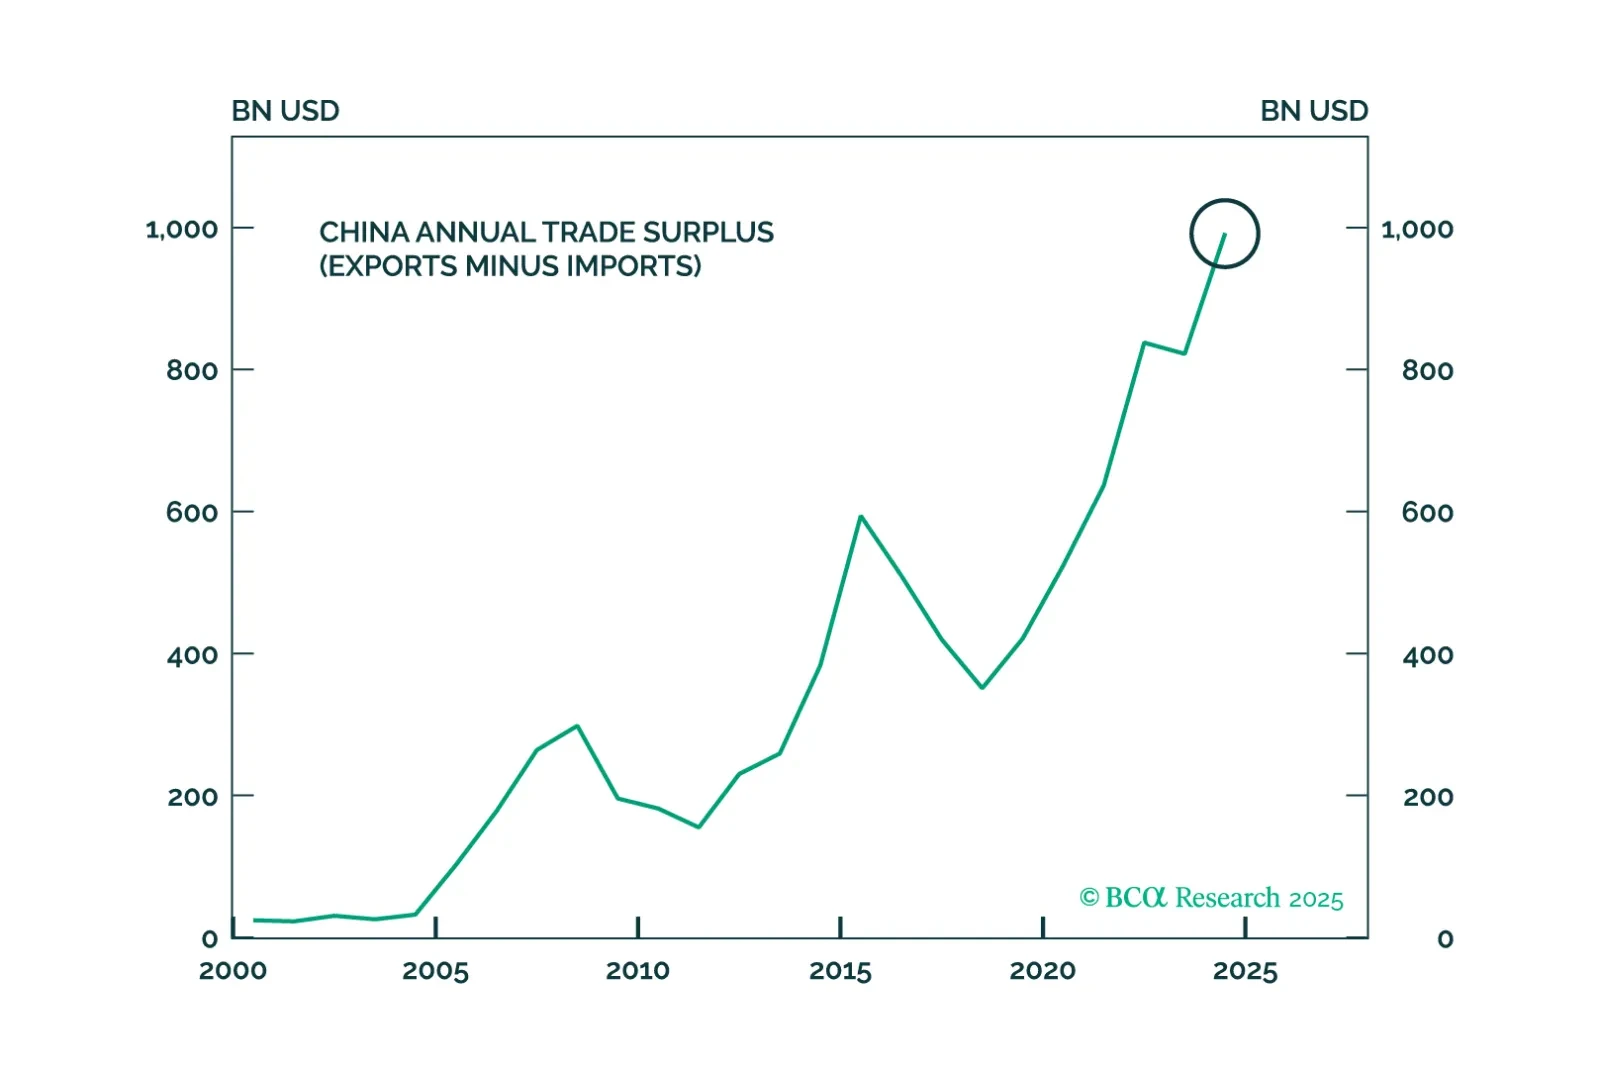
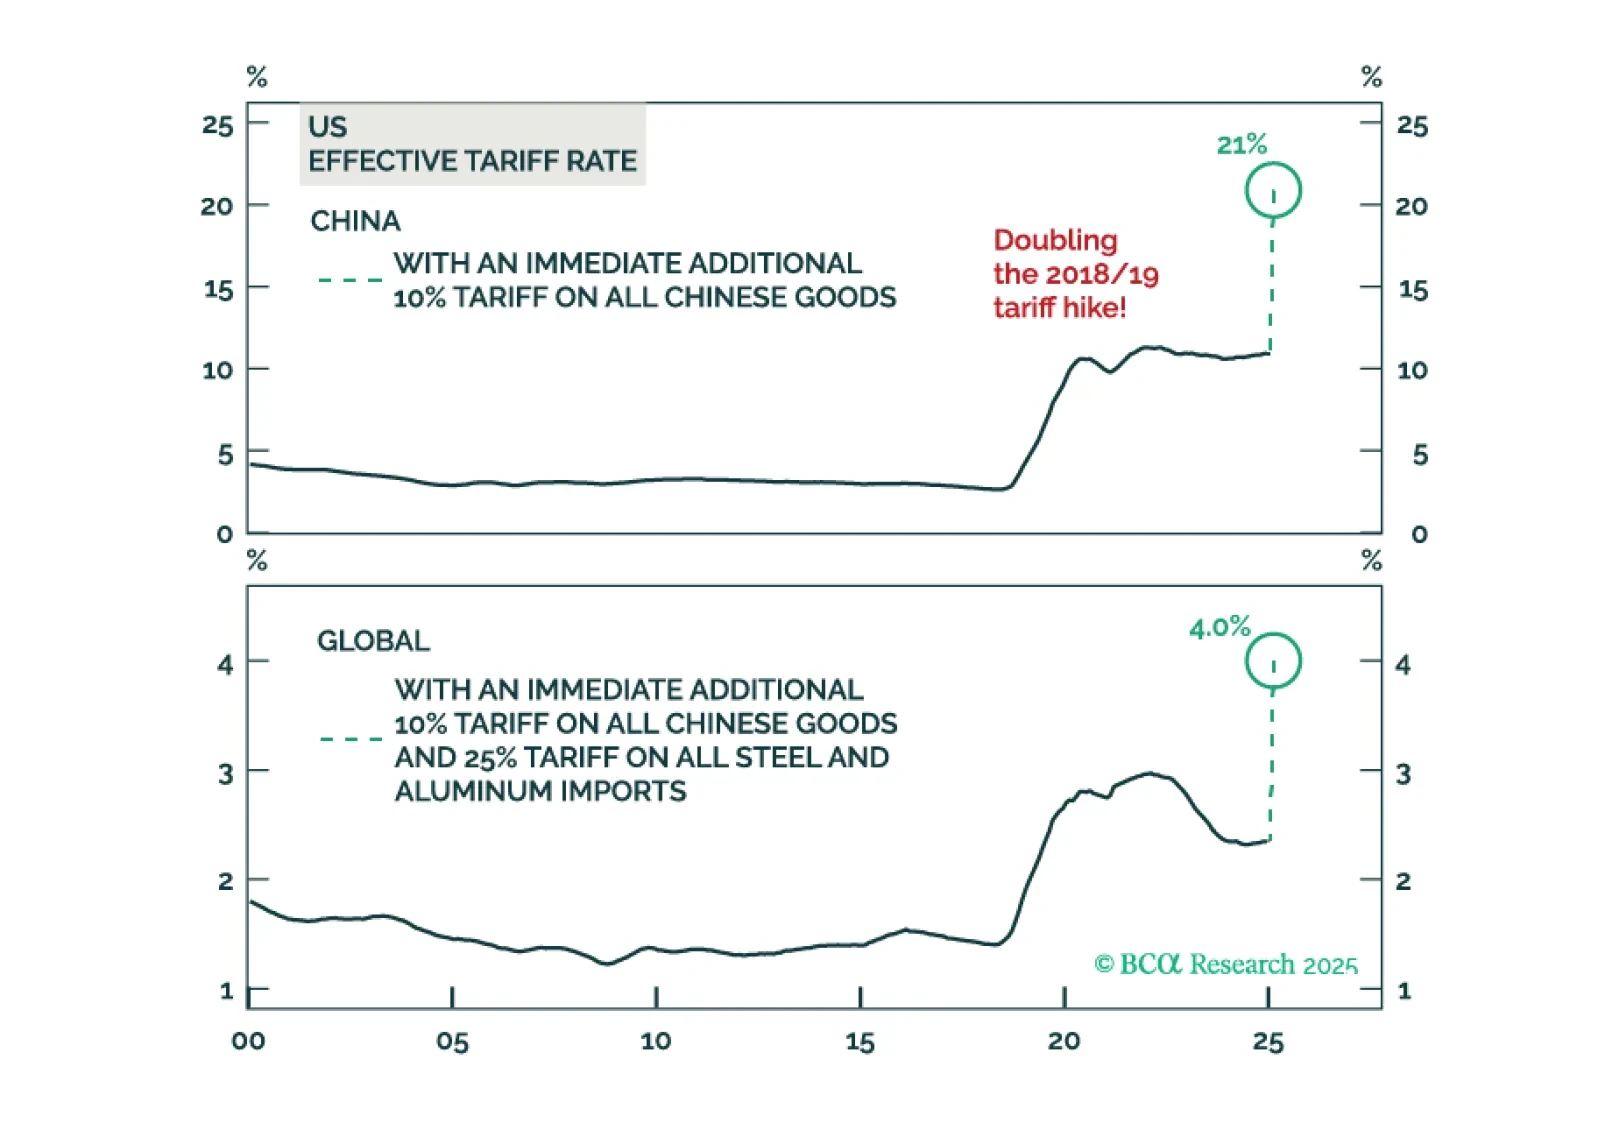
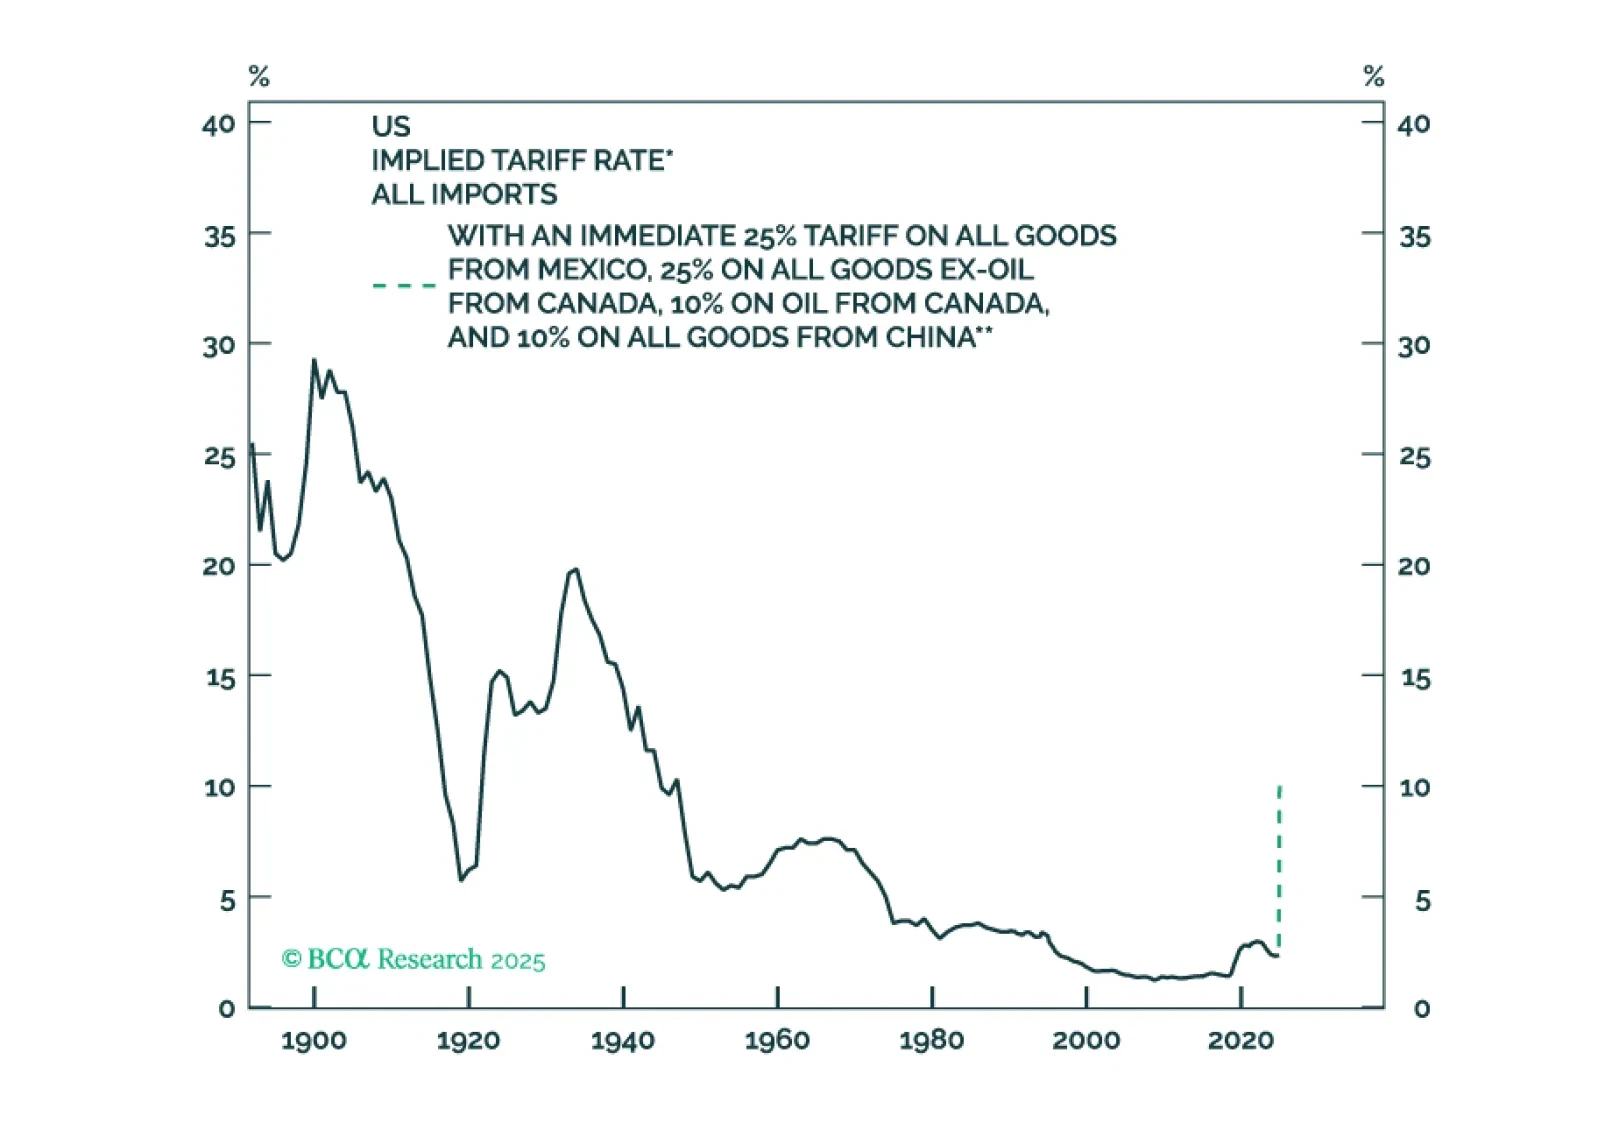
The 10% tariff hike announced on Saturday will likely serve as the opening salvo in a broader wave of protectionist measures. In this report, we assess the increase in US import tariffs on China. While the direct impact on China’s overall economy may be manageable, the country’s economy faces significant risks from potential disruptions in global trade.
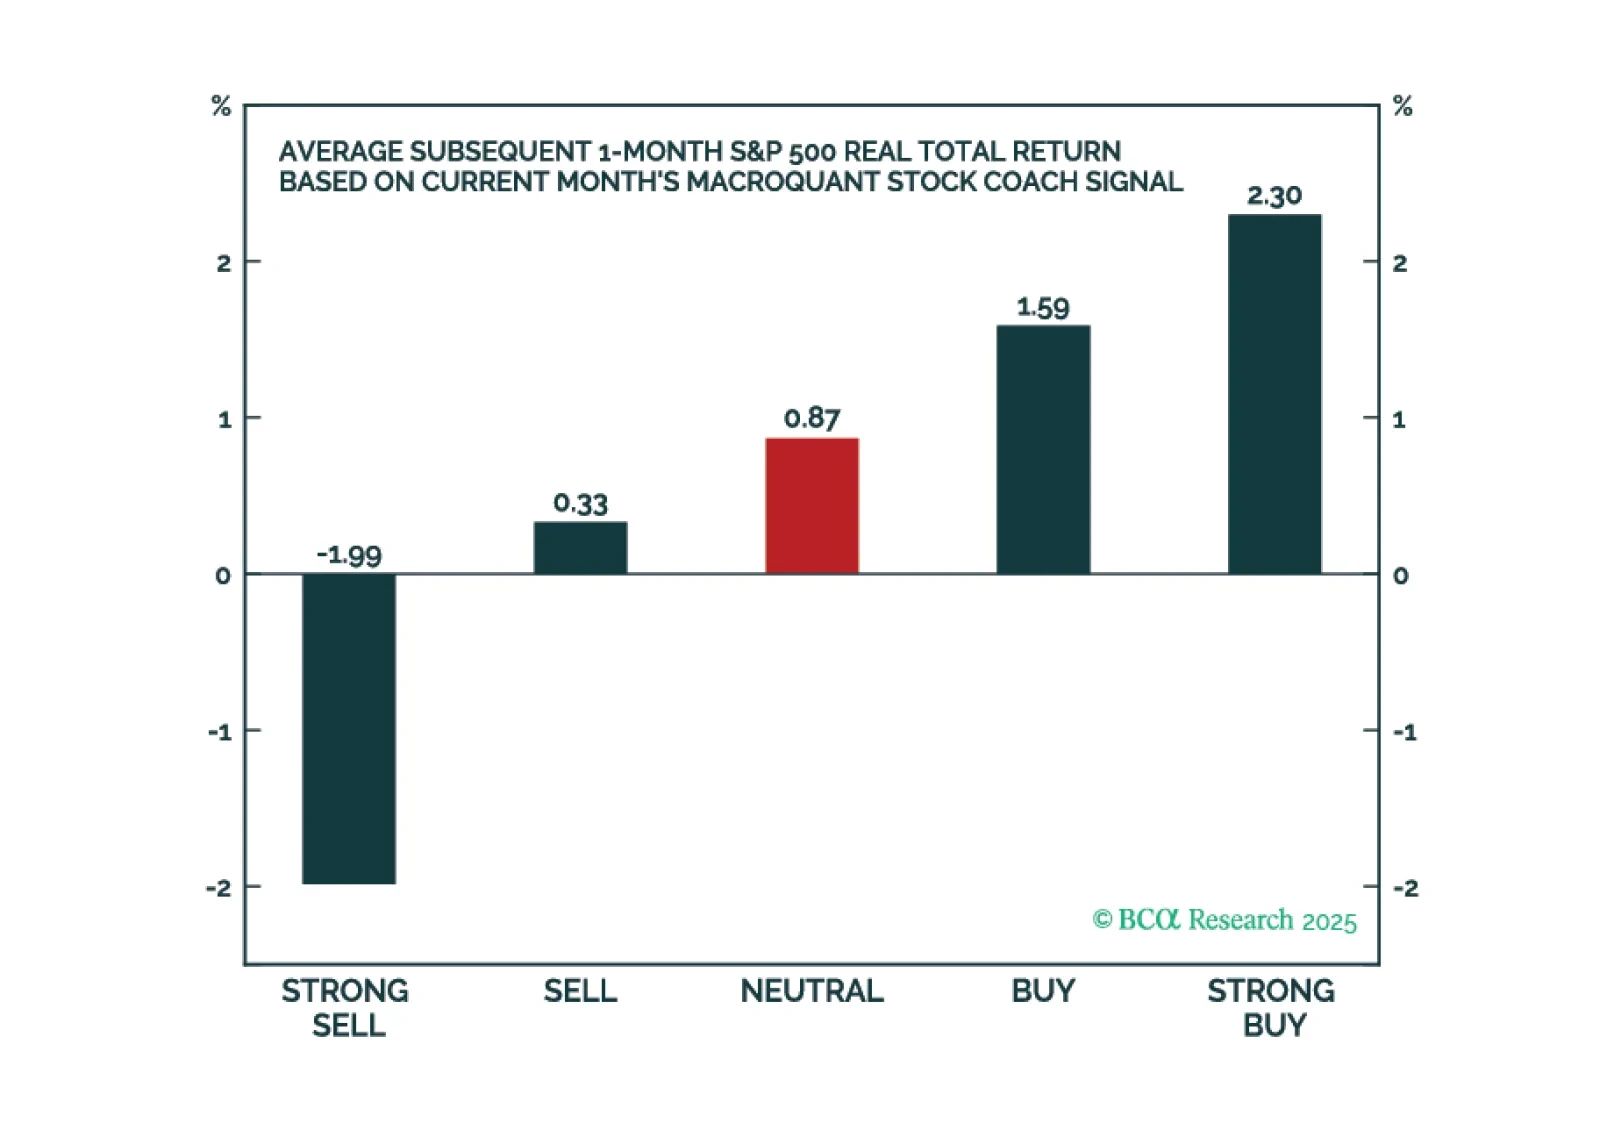
The latest version of the MacroQuant model suggests that the bull market in US stocks is winding down. The model expects Treasury yields to fall later this year but is not ready to go long duration just yet.