 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
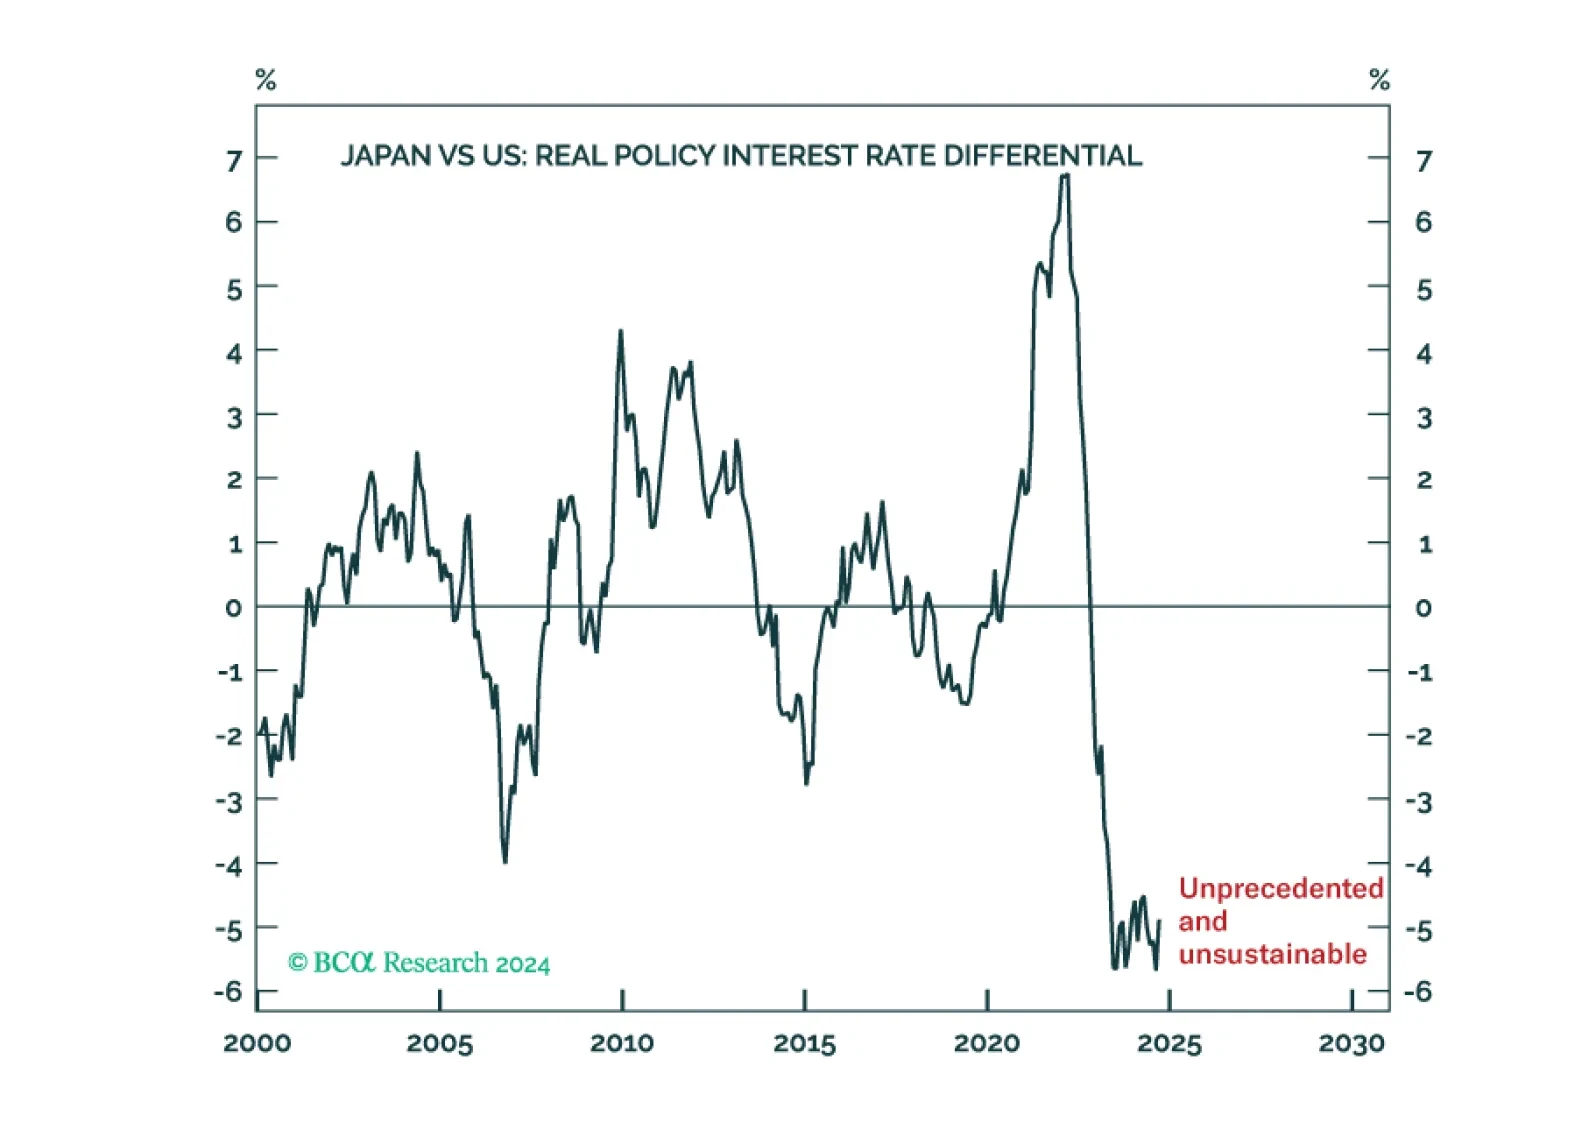
The biggest risk to the equity bull market is not a US recession. The biggest risk is the end of the deeply negative real rates in Japan versus the US that have caused the rampant post-2022 inflation in US tech stock valuations. We go through the investment implications. Plus: bond prices have further tactical downside whoever wins the US election.
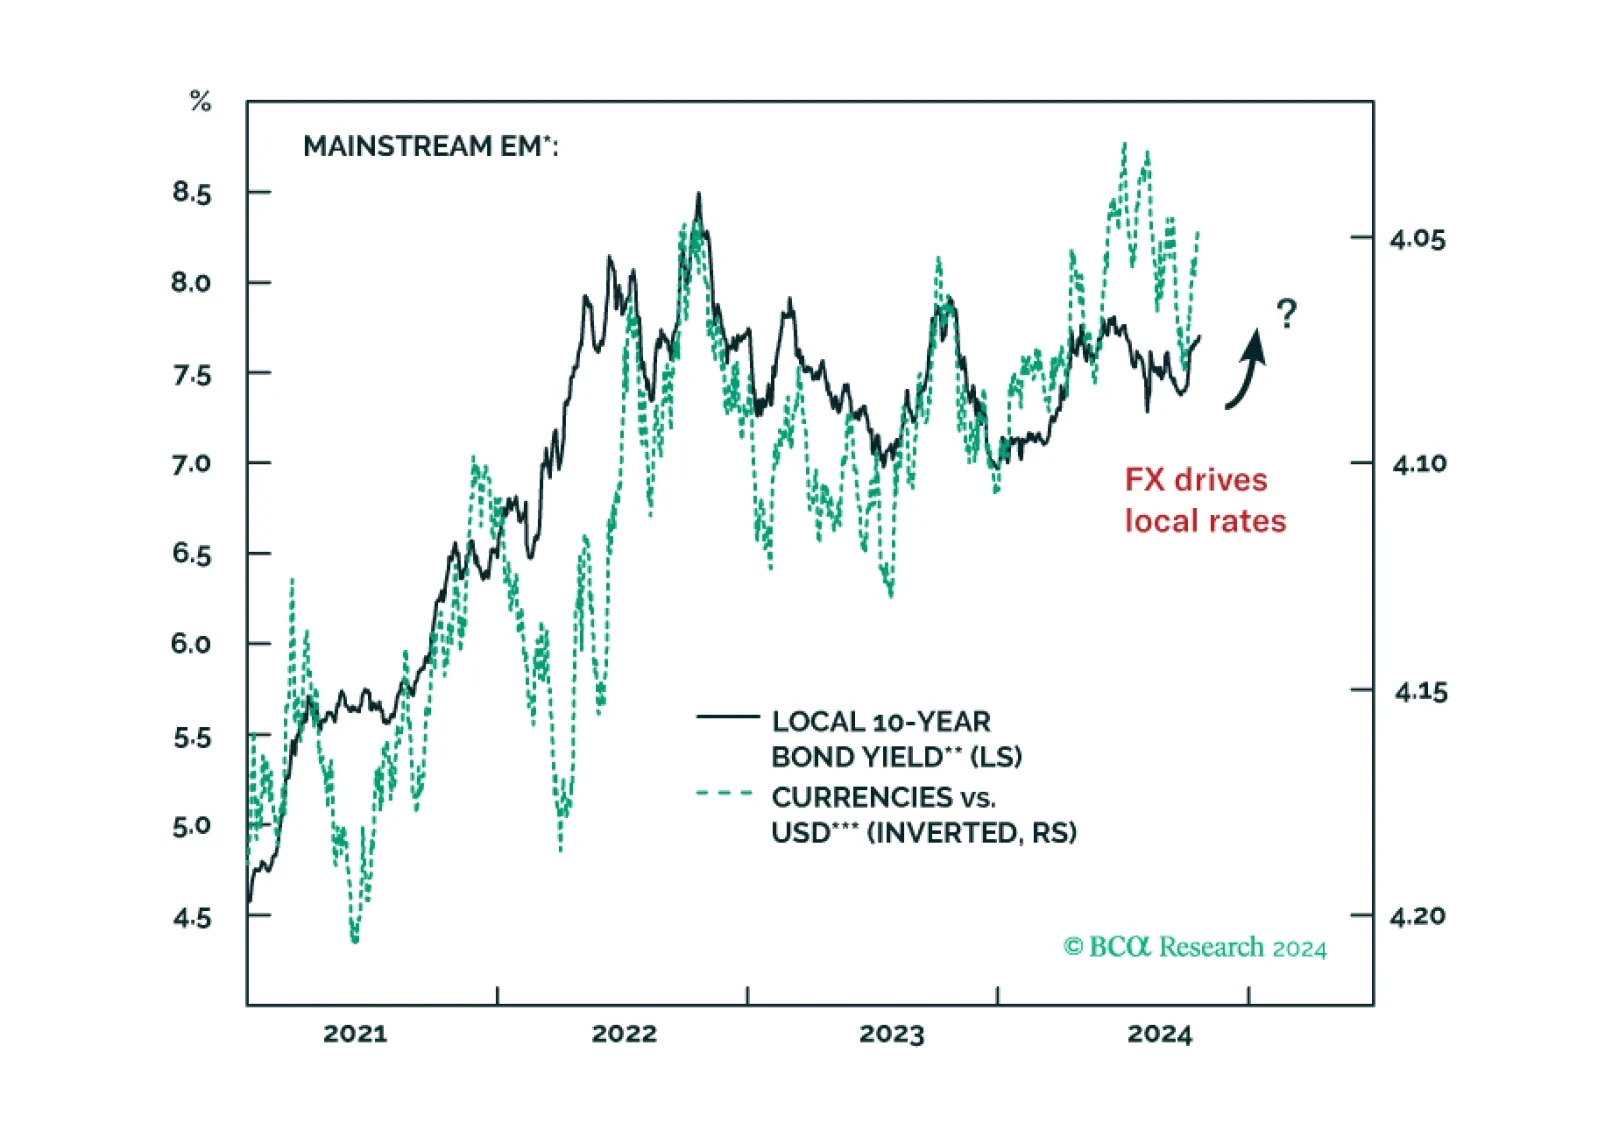
As the odds of a Trump victory increase, there are indications that the “Trump trade” has commenced in global financial markets, with negative short-term implications for EM. In short, the US dollar will strengthen, and US bond yields will rise in the lead-up to and after the election if Trump wins. In response, EM countries’ currencies will depreciate, and their fixed-income and equity markets will suffer over the coming months.
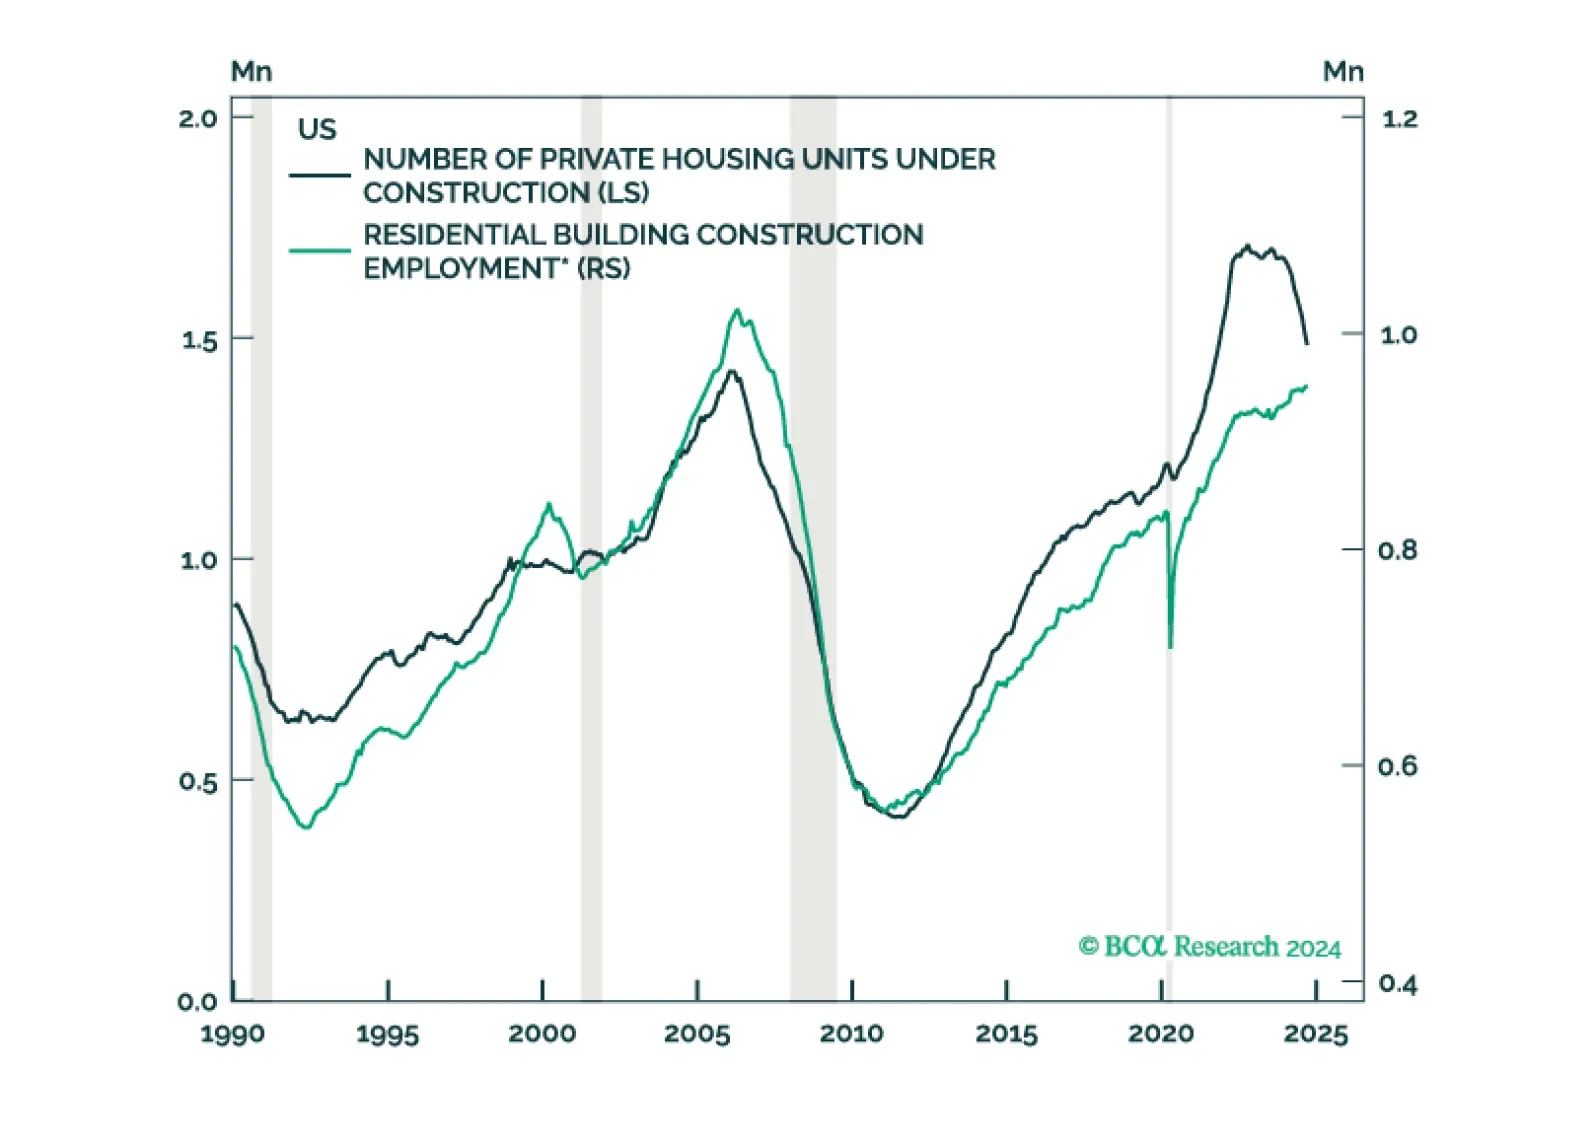
In August 2007, Ed Leamer famously presented a paper entitled Housing IS the Business Cycle at the Jackson Hole symposium. I was reminded of this paper after seeing today's US housing data.
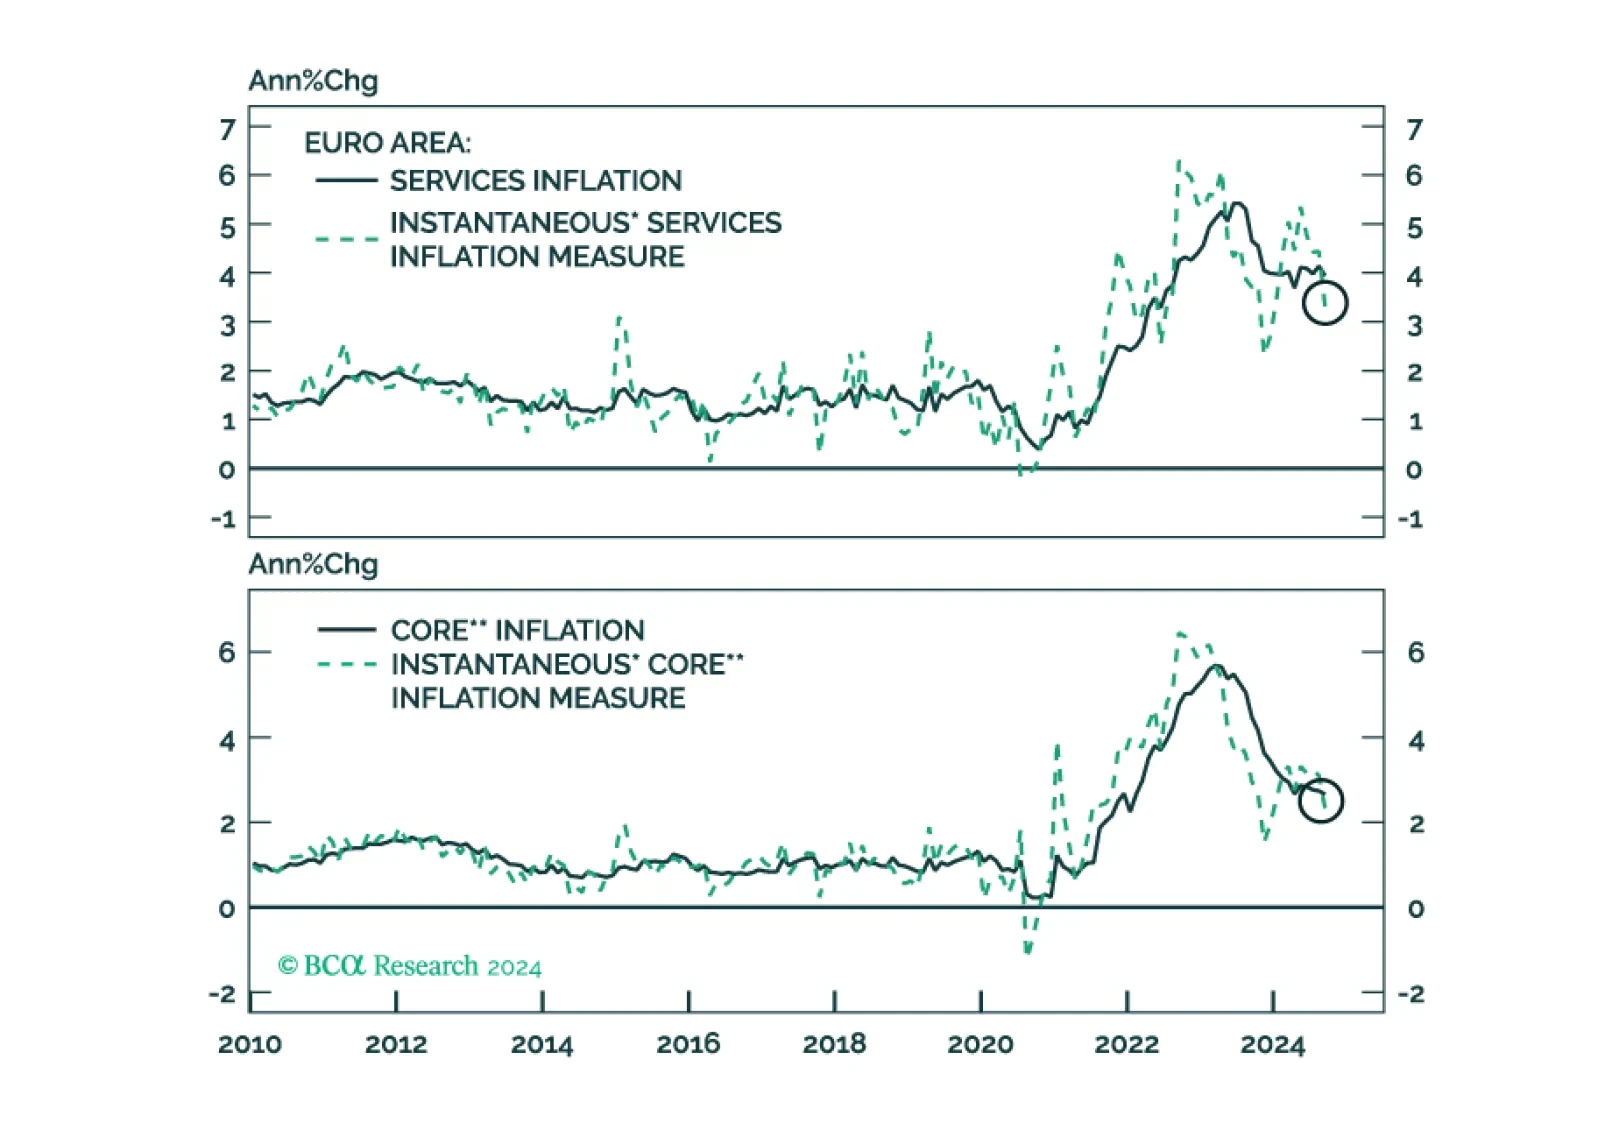
Yesterday, the ECB solidified its recent dovish tilt in response to weaker growth and decreasing inflationary pressures. It is now set to cut rates 25bps each meeting. How low will the ECB deposit rate ultimately go and what does this imply for yields and the euro?
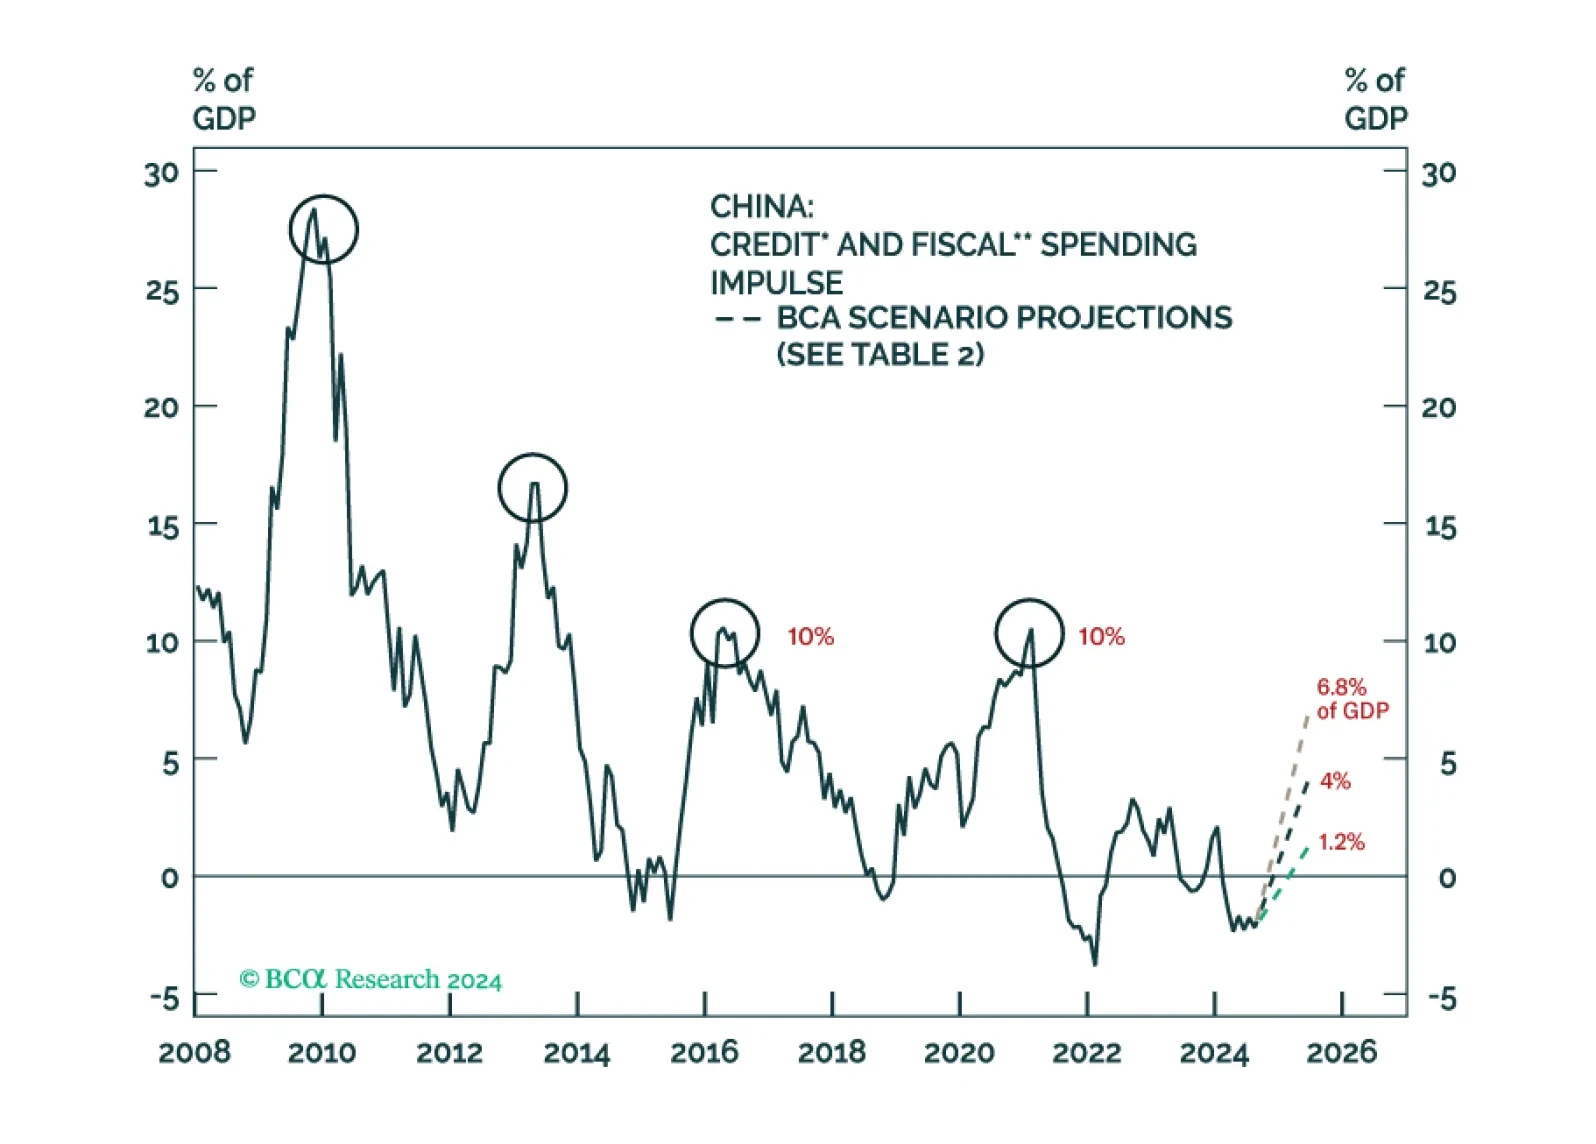
To produce a moderate economic recovery, at least RMB 3 trillion in additional government expenditures is needed in H1 2025. Our bias is that Beijing is not yet ready to launch such a massive fiscal support measure. Hence, volatility-adjusted equity returns in China will be poor.
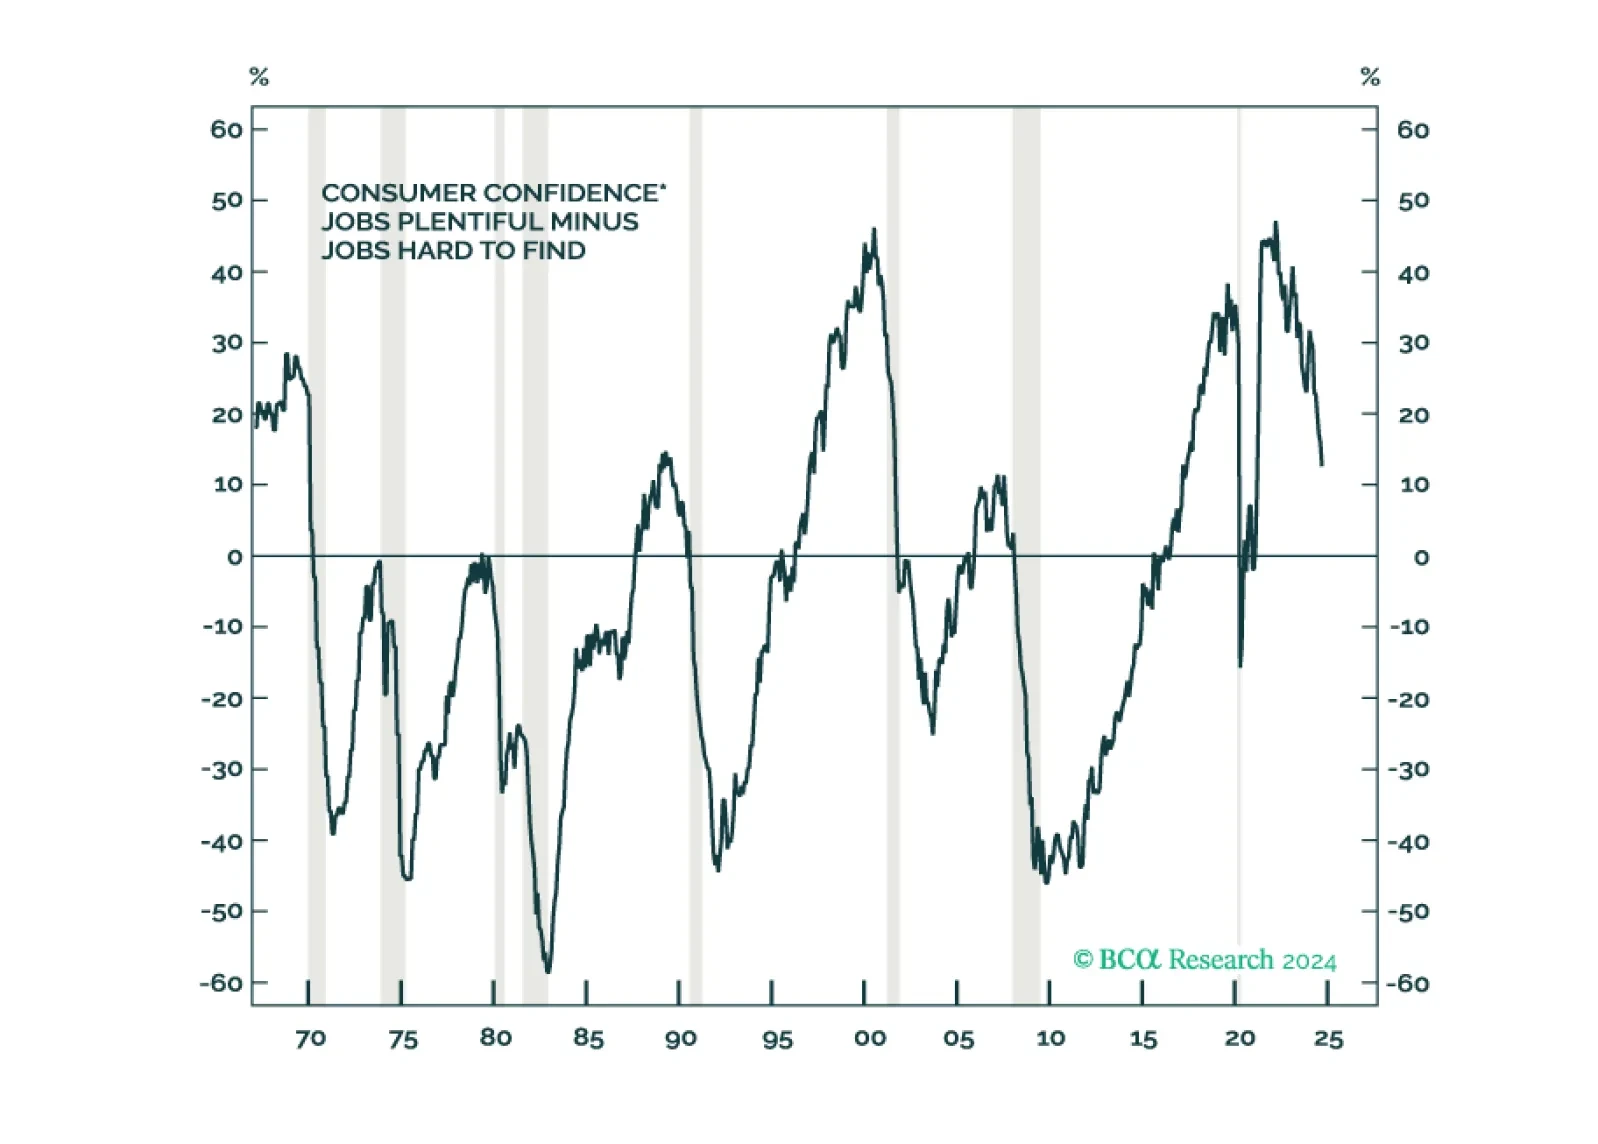
Rising stock prices and improving economic data have us re-examining our bearish thesis, but we still see deterioration in leading labor market indicators and expect it will eventually culminate in a recession. We reiterate our defensive investment recommendations.

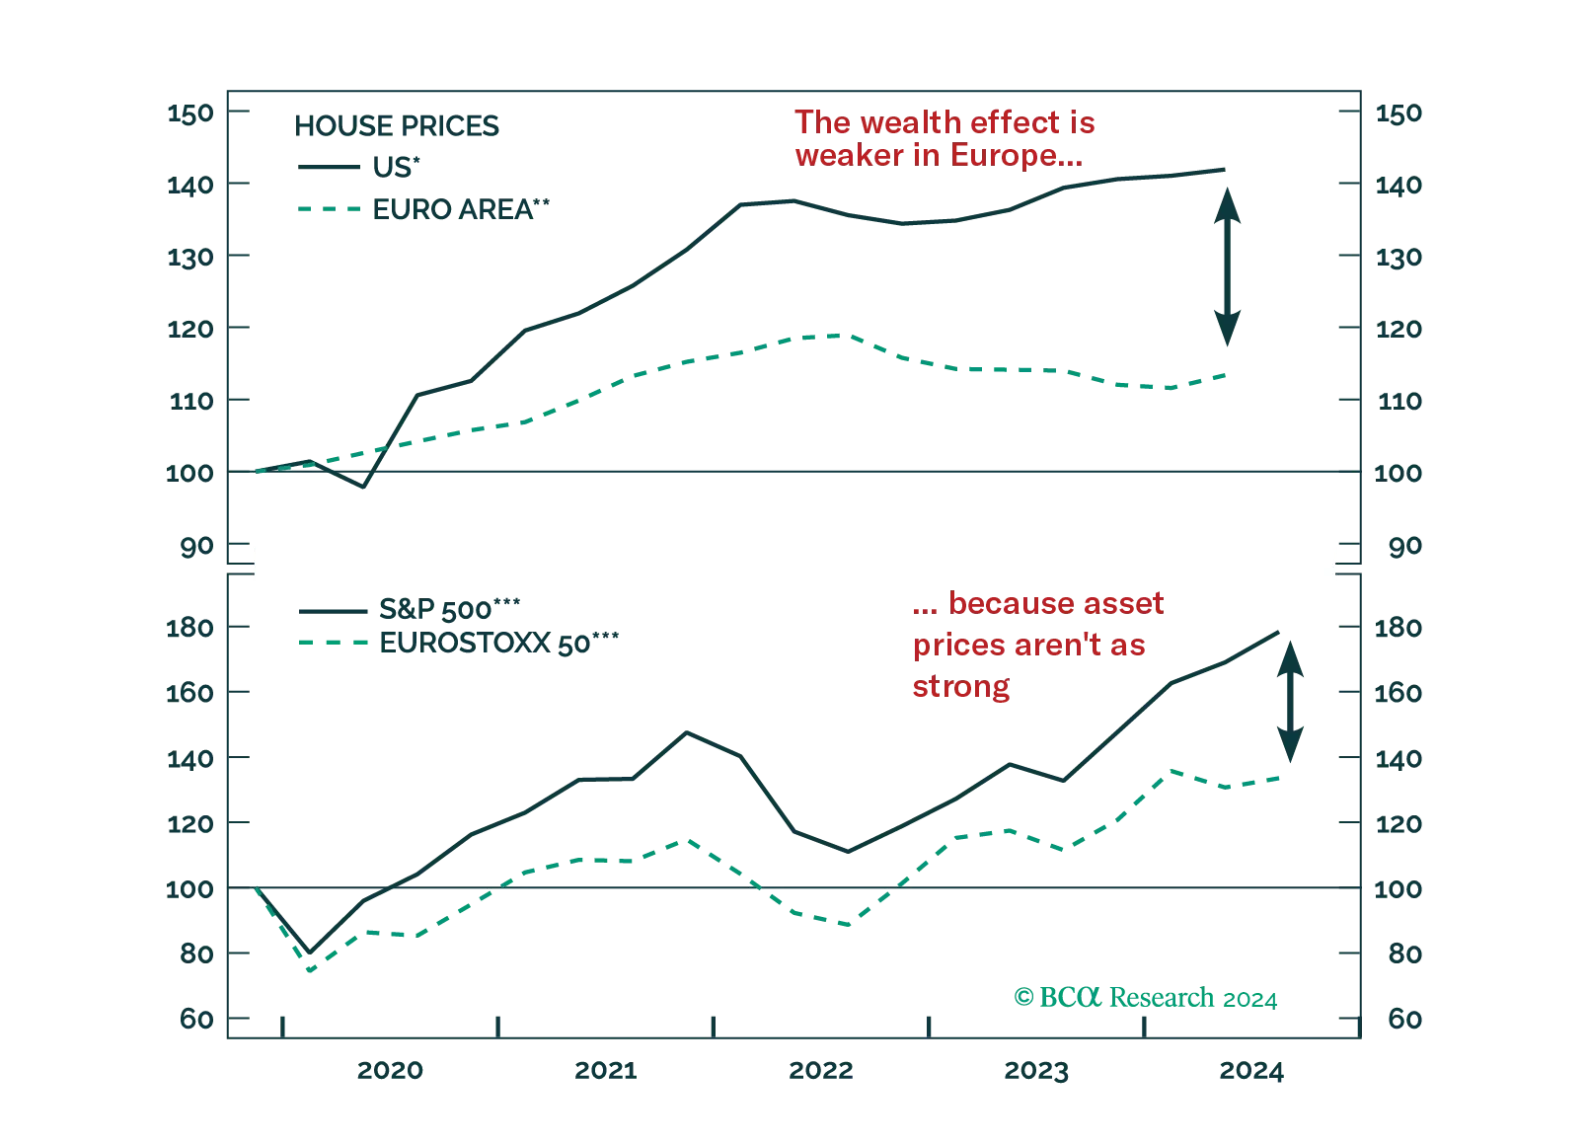
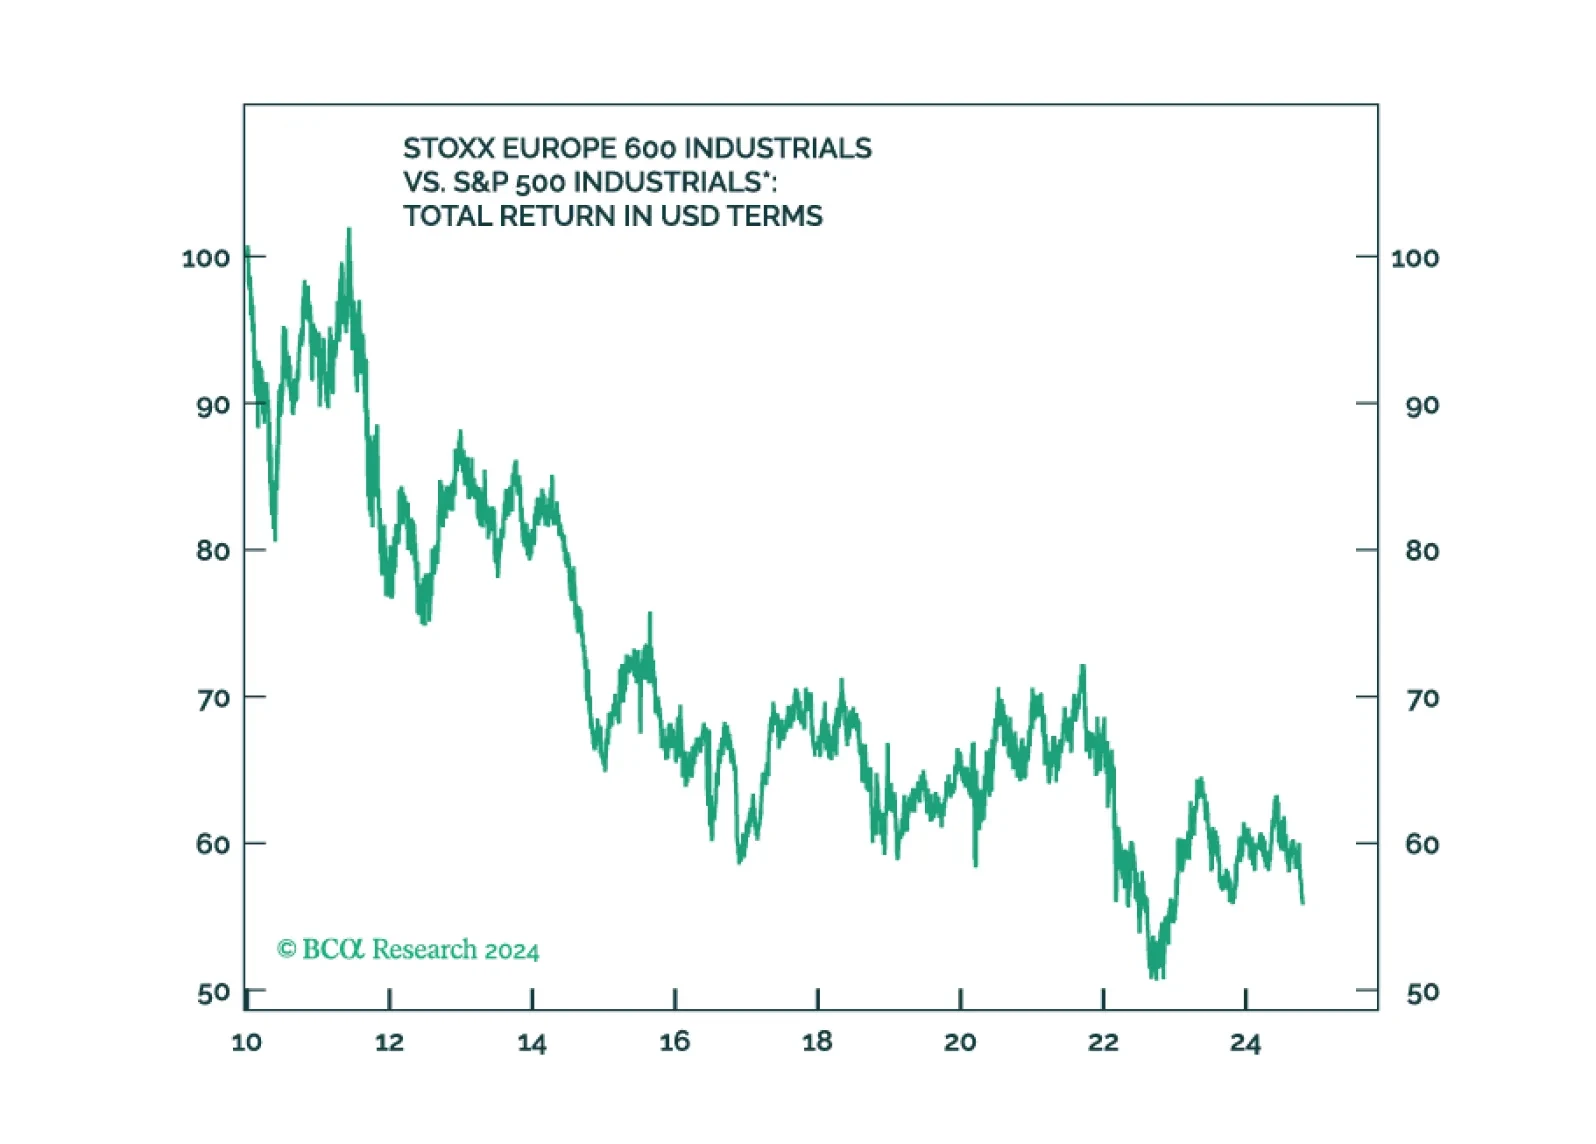
This week, we cover the main questions we fielded during our latest client trip in Europe. Among the many topics broached are Europe’s recession odds, the impact of China’s stimulus, and the outlook for European markets.
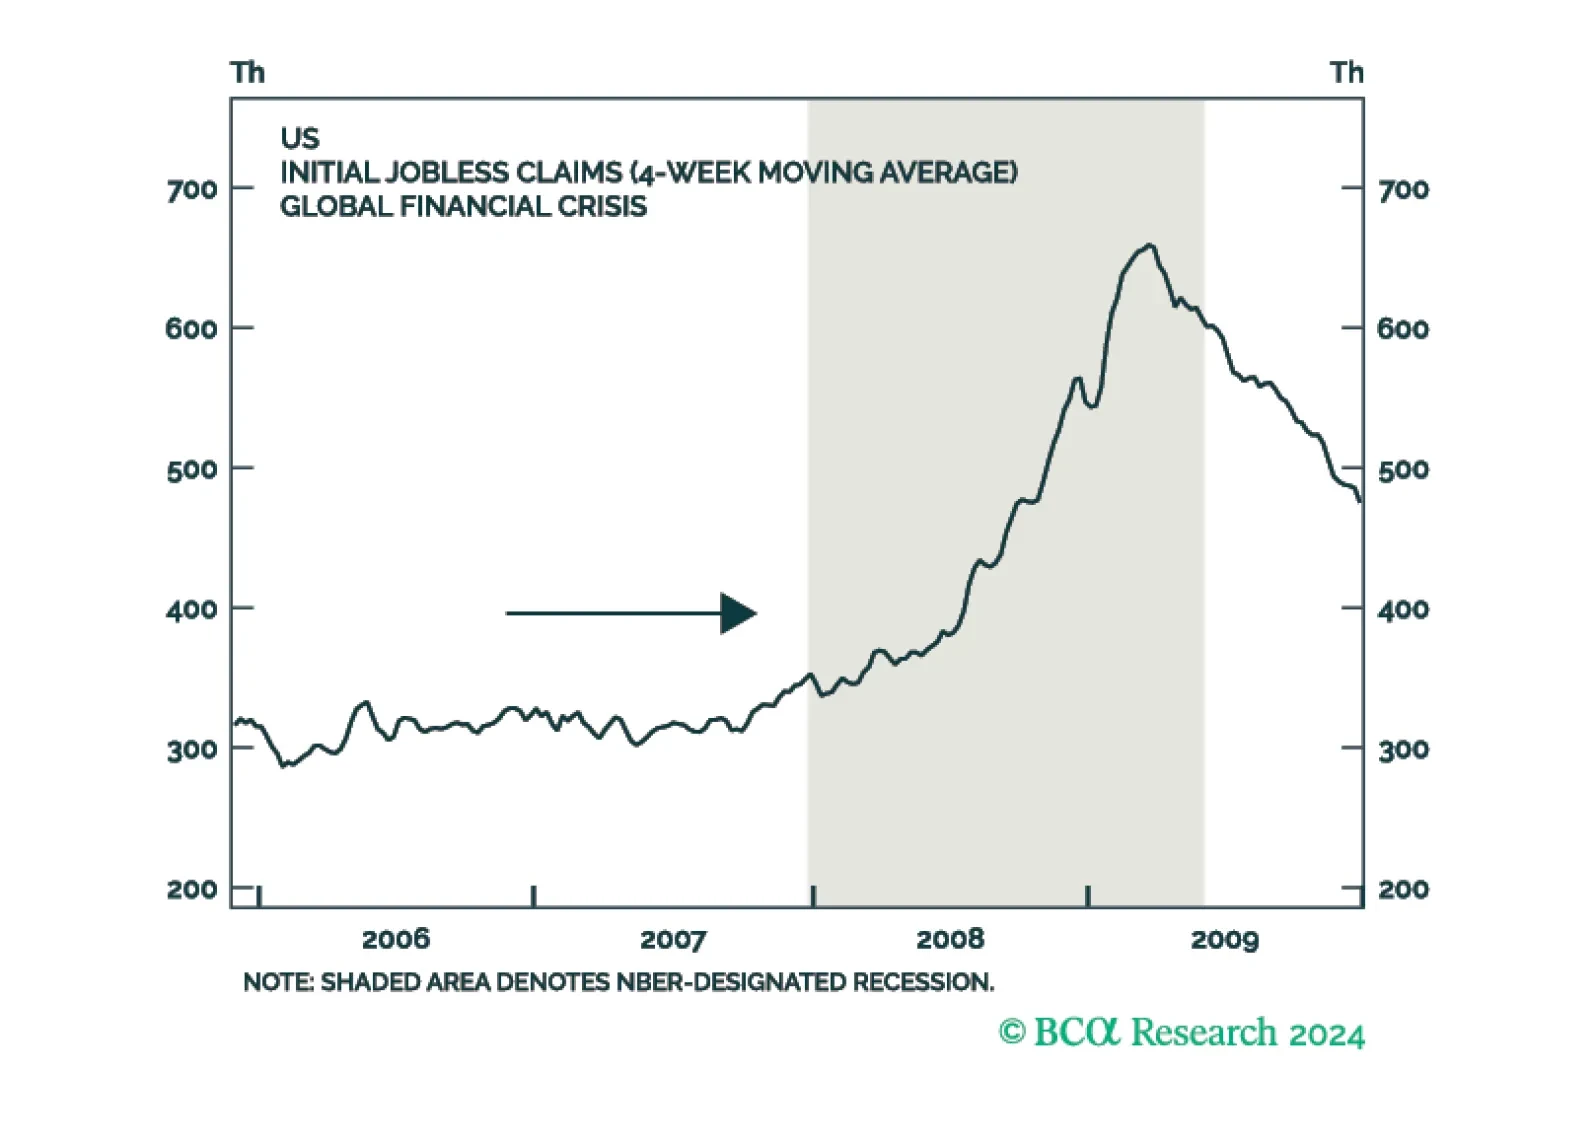
Whenever I present a skeptical view about the strength of the US labor market, I am often reminded that layoffs remain very low.