 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
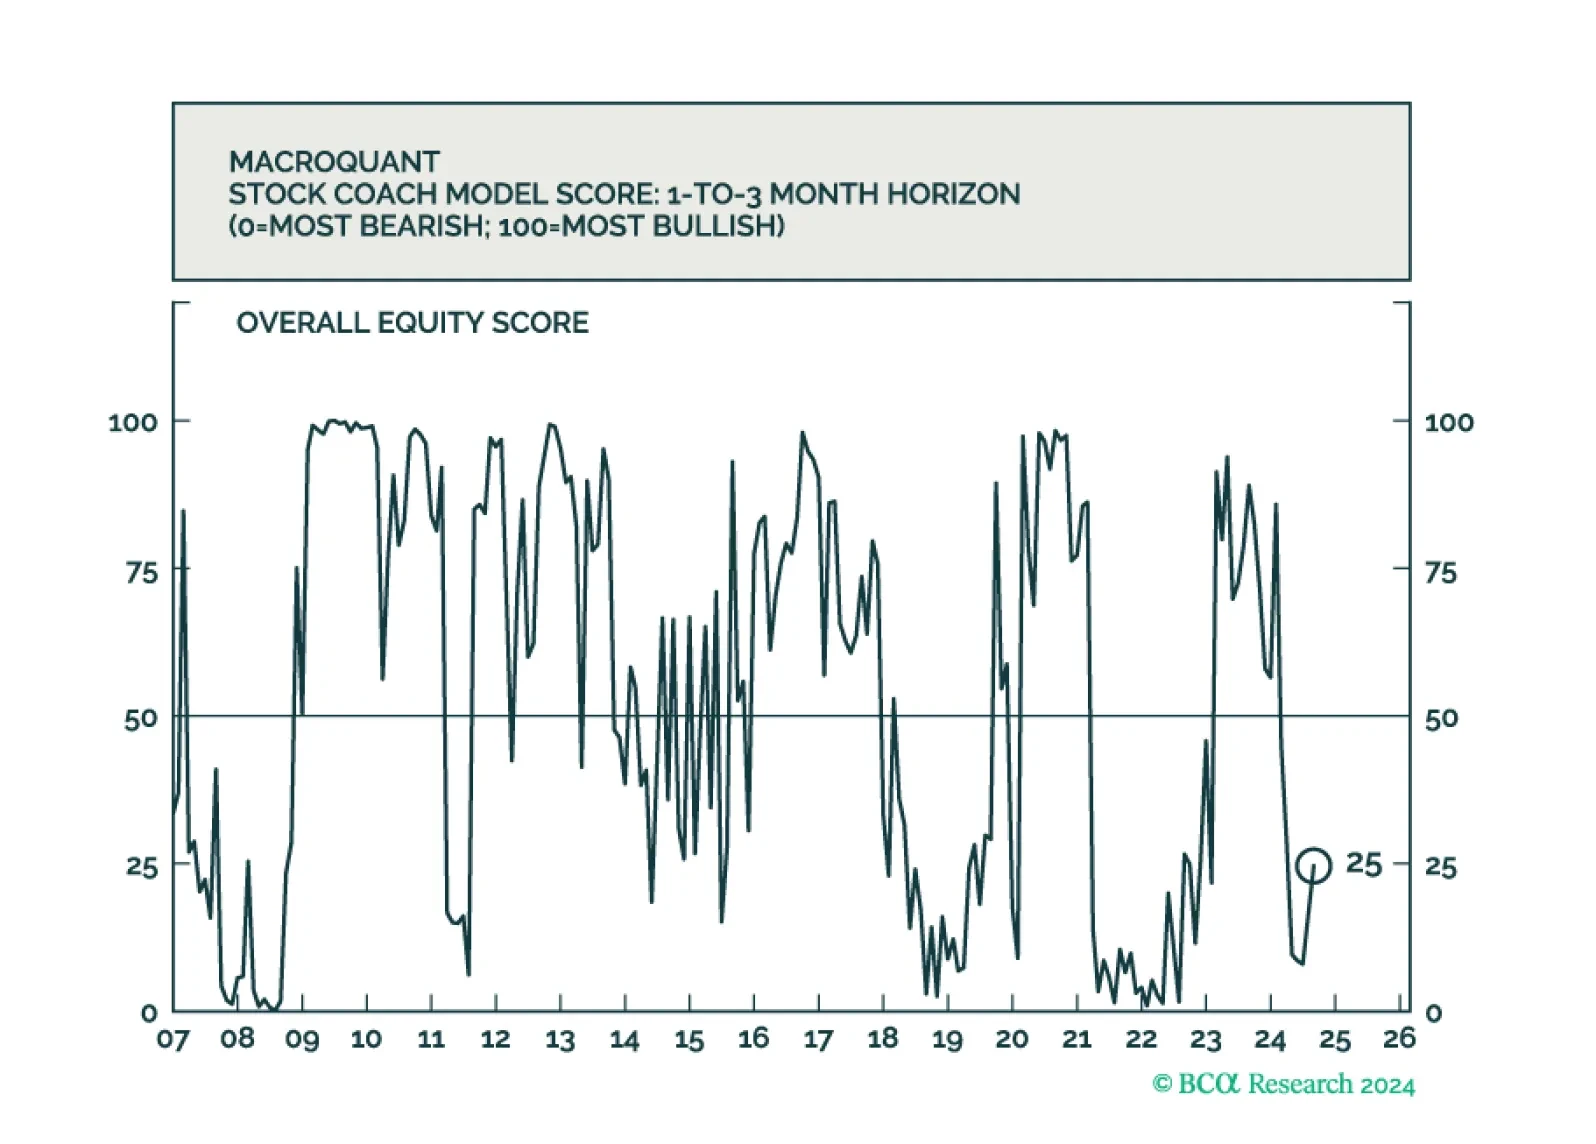
Despite the recent easing in financial conditions and hopes around Chinese stimulus, MacroQuant sees a heightened risk that the US will fall into a recession over the next 12 months. As such, it recommends an underweight to stocks, counterbalanced by an overweight to bonds.
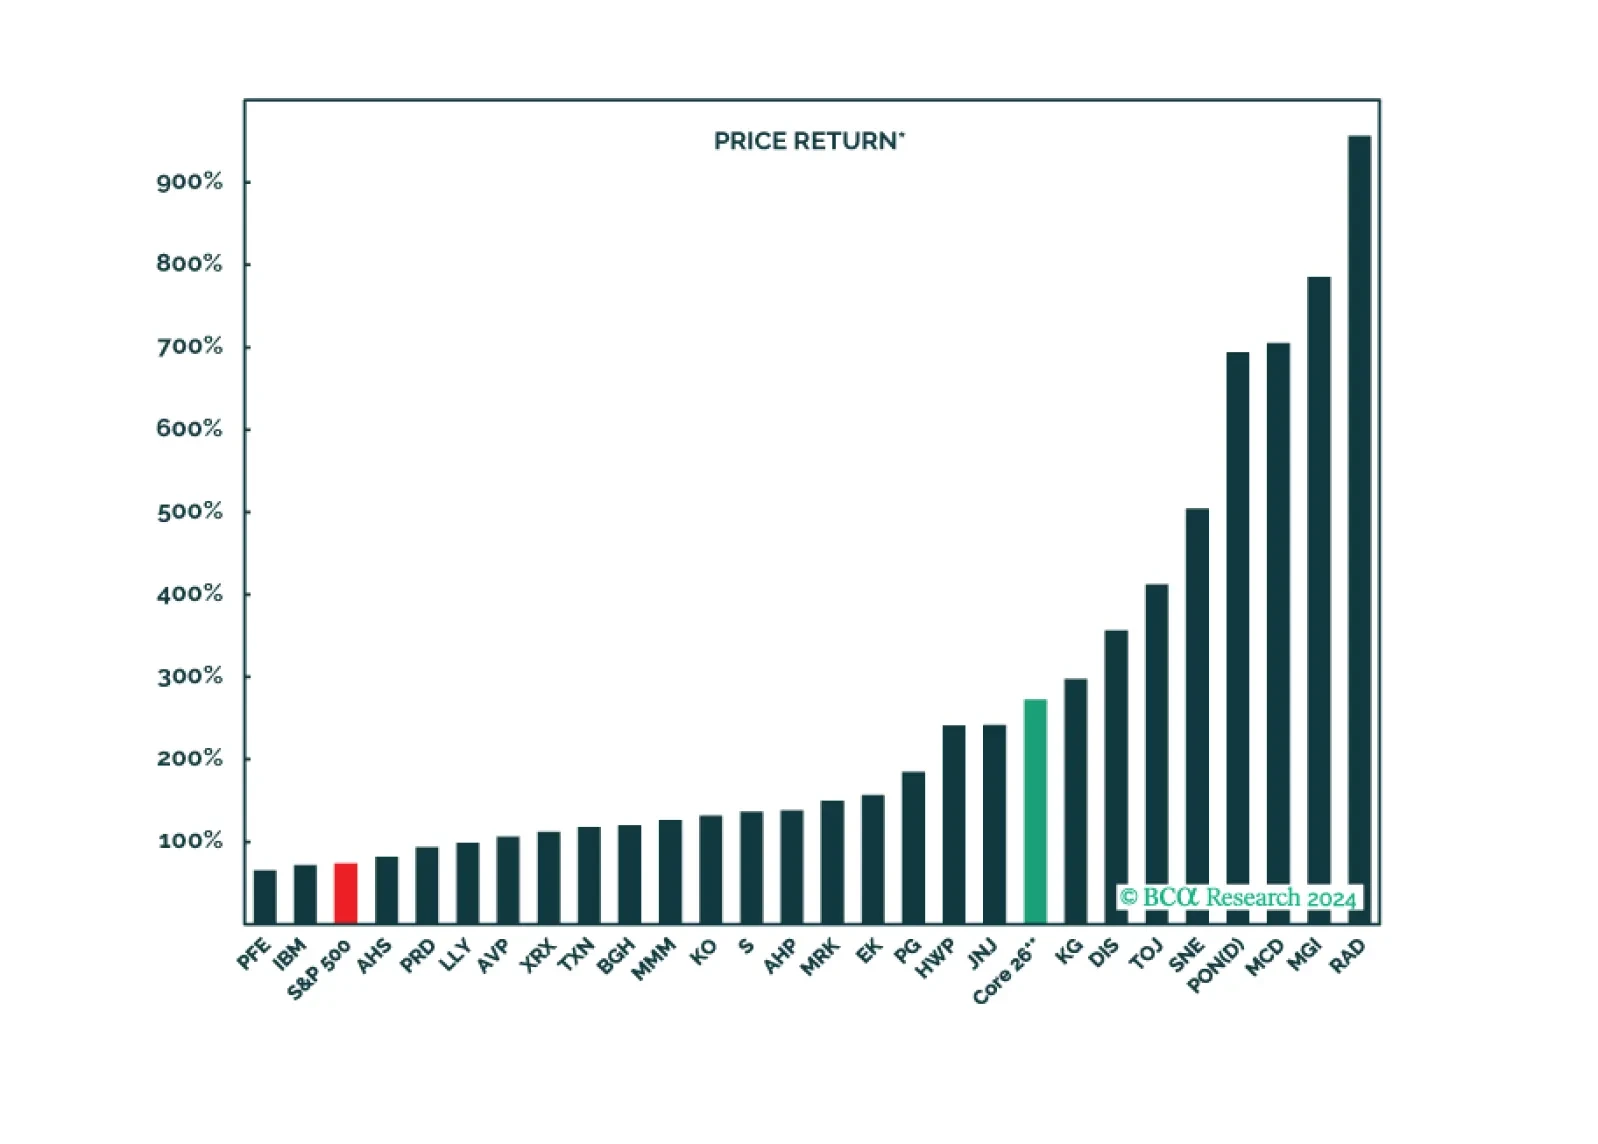
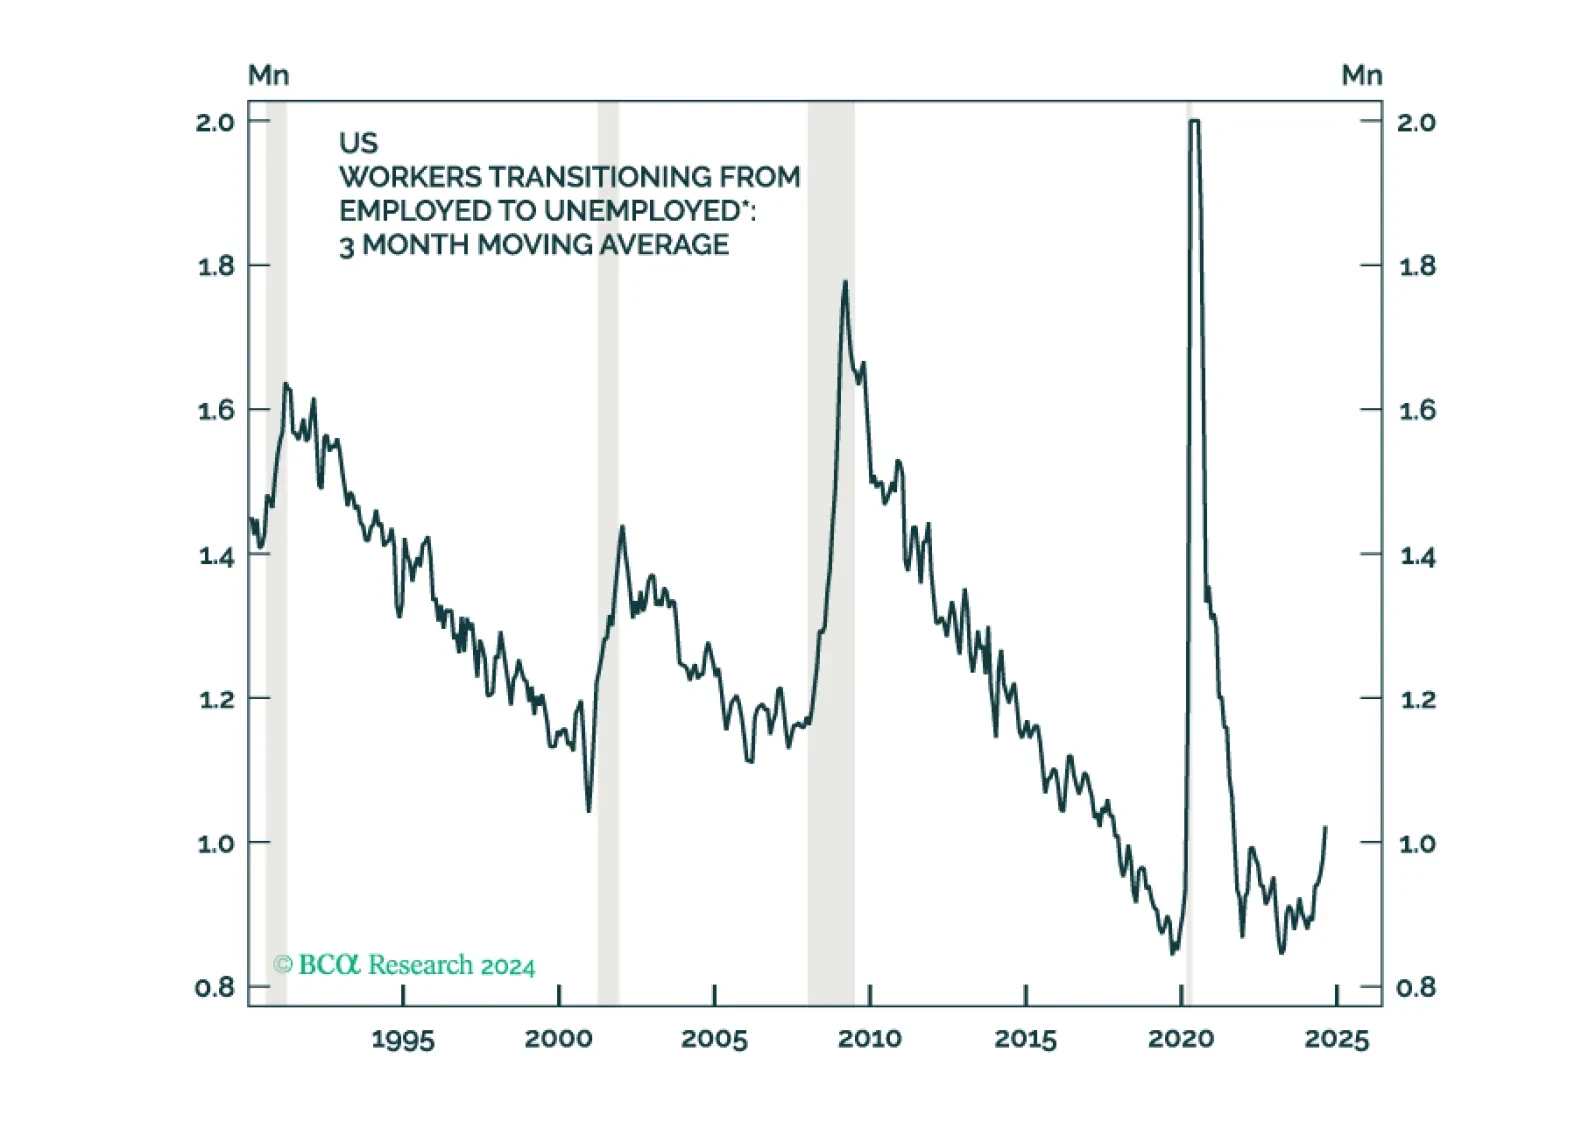
Back in 2022, when Jamie Dimon was predicting an economic hurricane, I was one of the few strategists reassuring clients that the US was not at imminent risk of a recession.
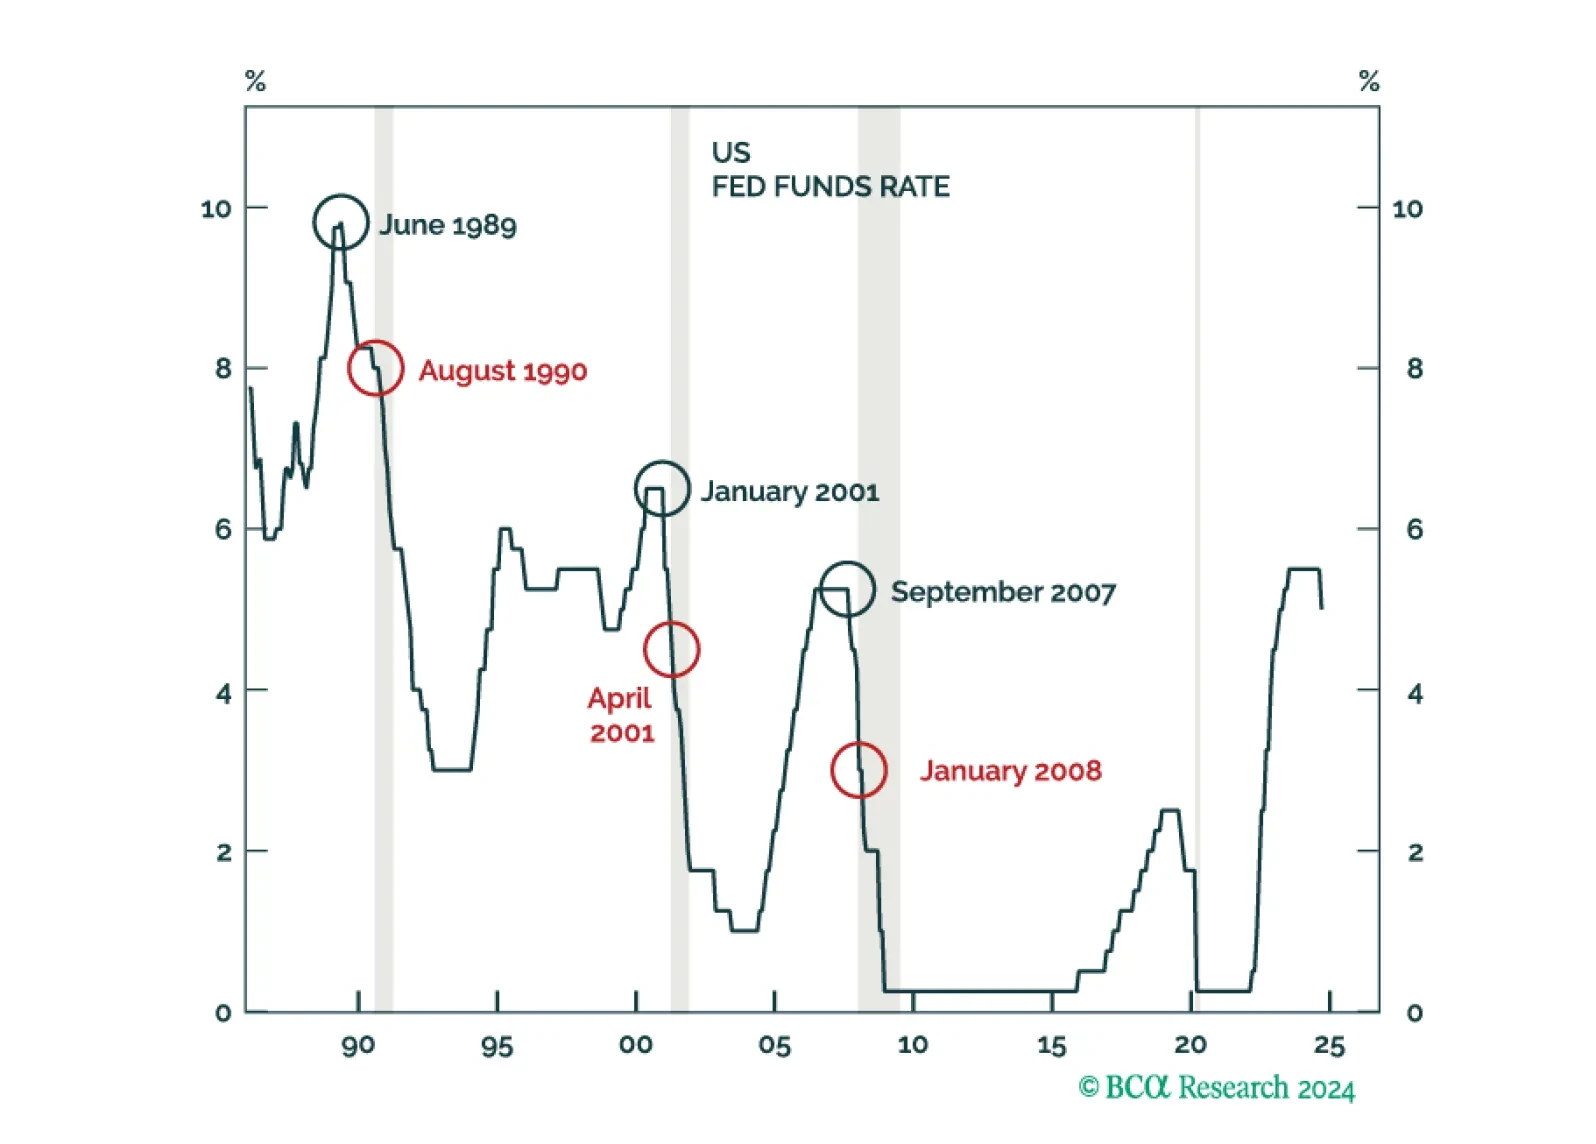
After resisting the consensus narrative in 2022 that a US recession was imminent, and then predicting an immaculate disinflation for 2023, the Global Investment Strategy team has joined the dark side and is now expecting a recession to start in the US within the next six months. Accordingly, we recommend that investors underweight stocks and overweight government bonds.
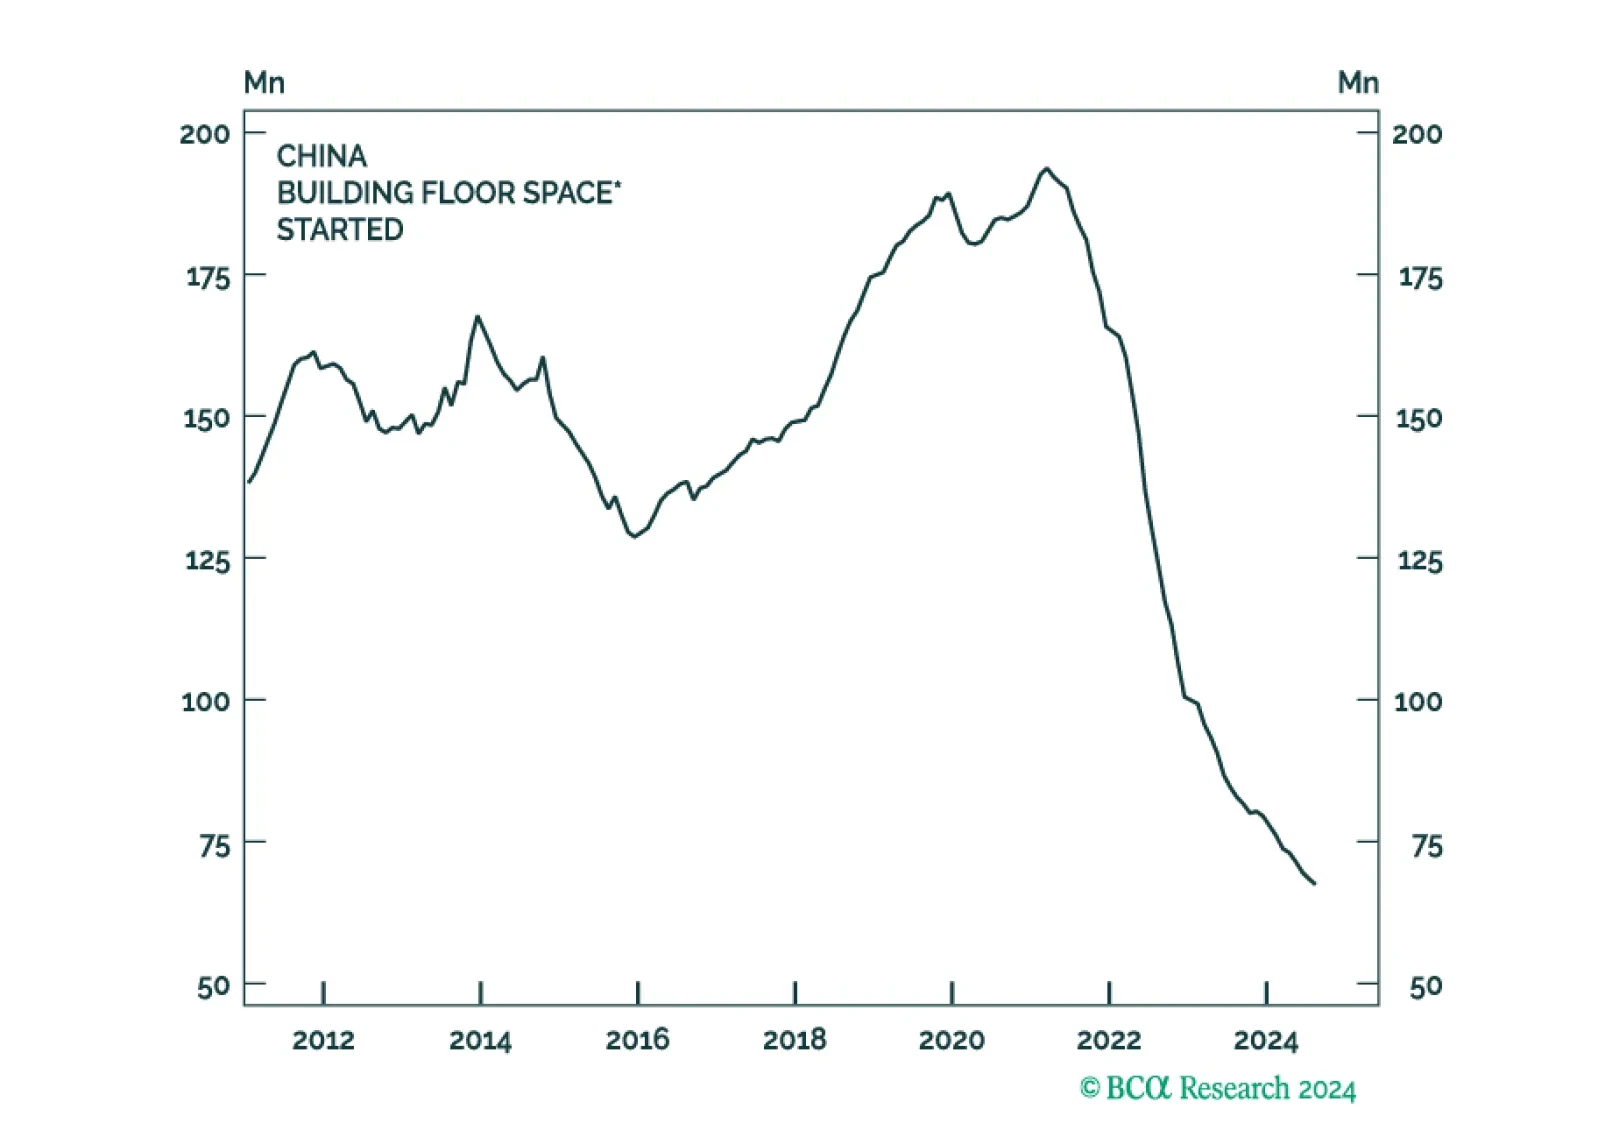
The Chinese government had no choice but to act this week. Housing starts are down 65% from their peak.

The adrenaline from the recent policy stimulus might be sufficient to produce a window of outperformance for Chinese equities and China-plays in financial markets. However, this adrenaline will not extend to China's real economy. Net-net, we are upgrading the allocation to EM in a global equity portfolio from underweight to neutral.
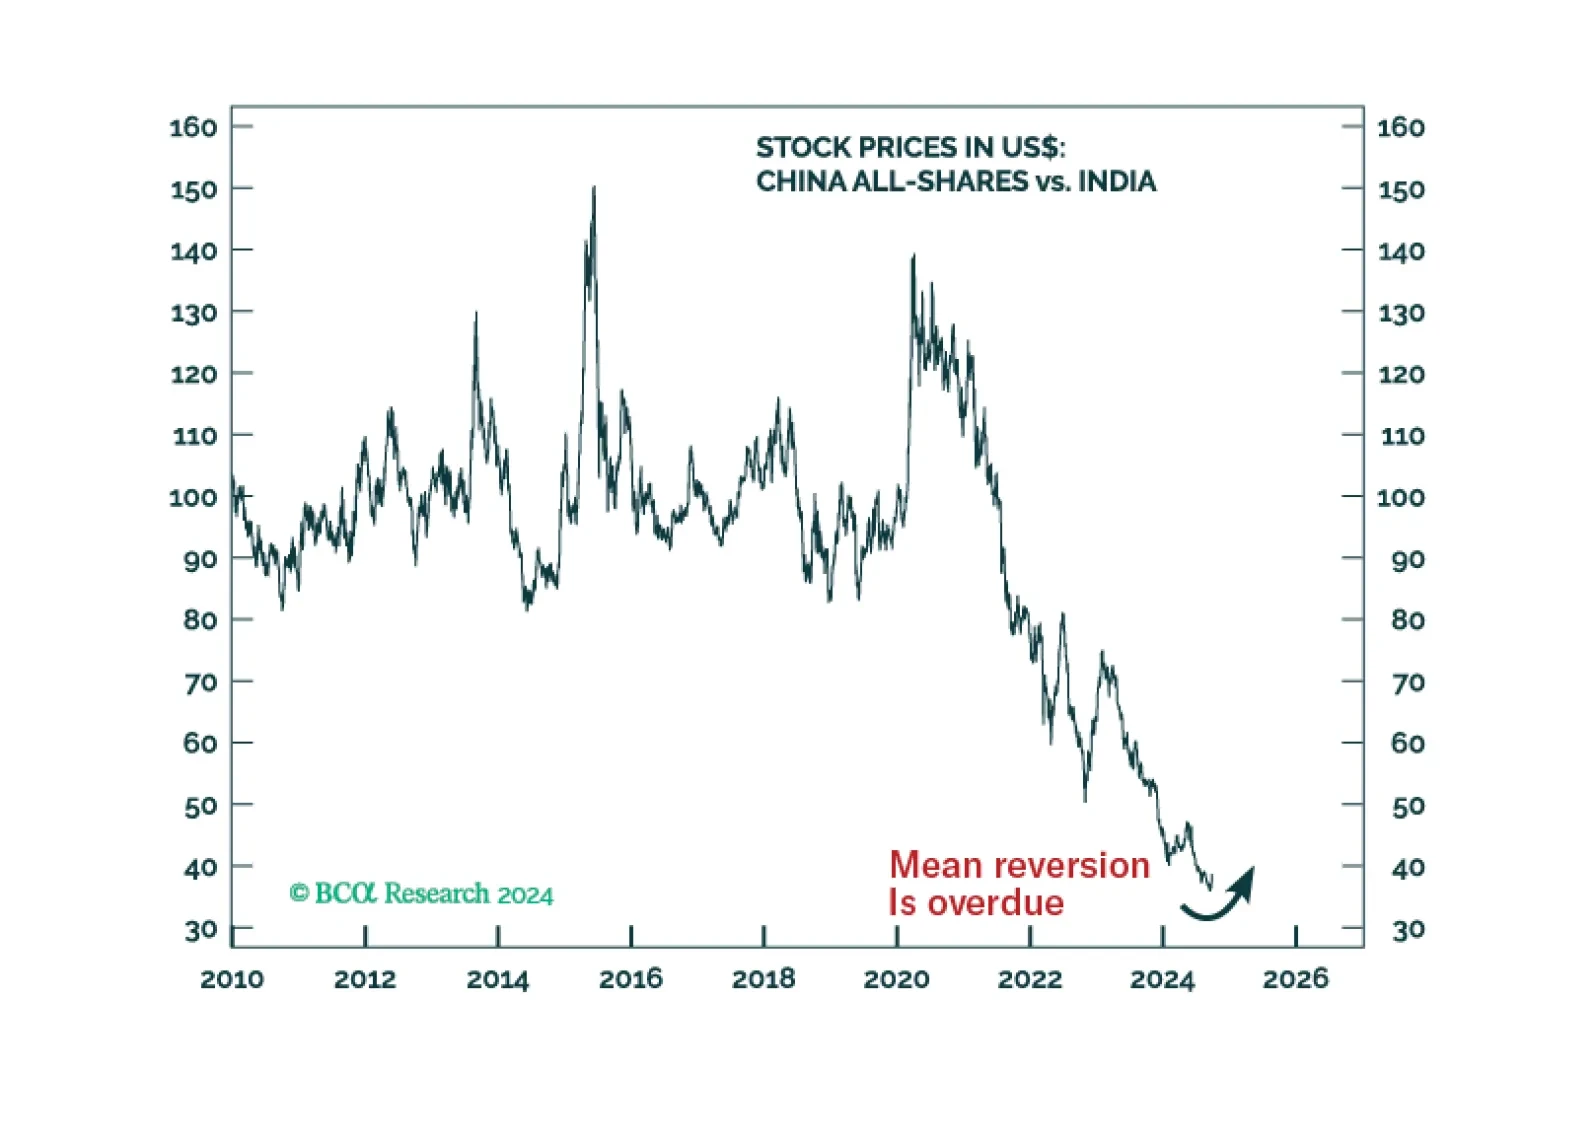
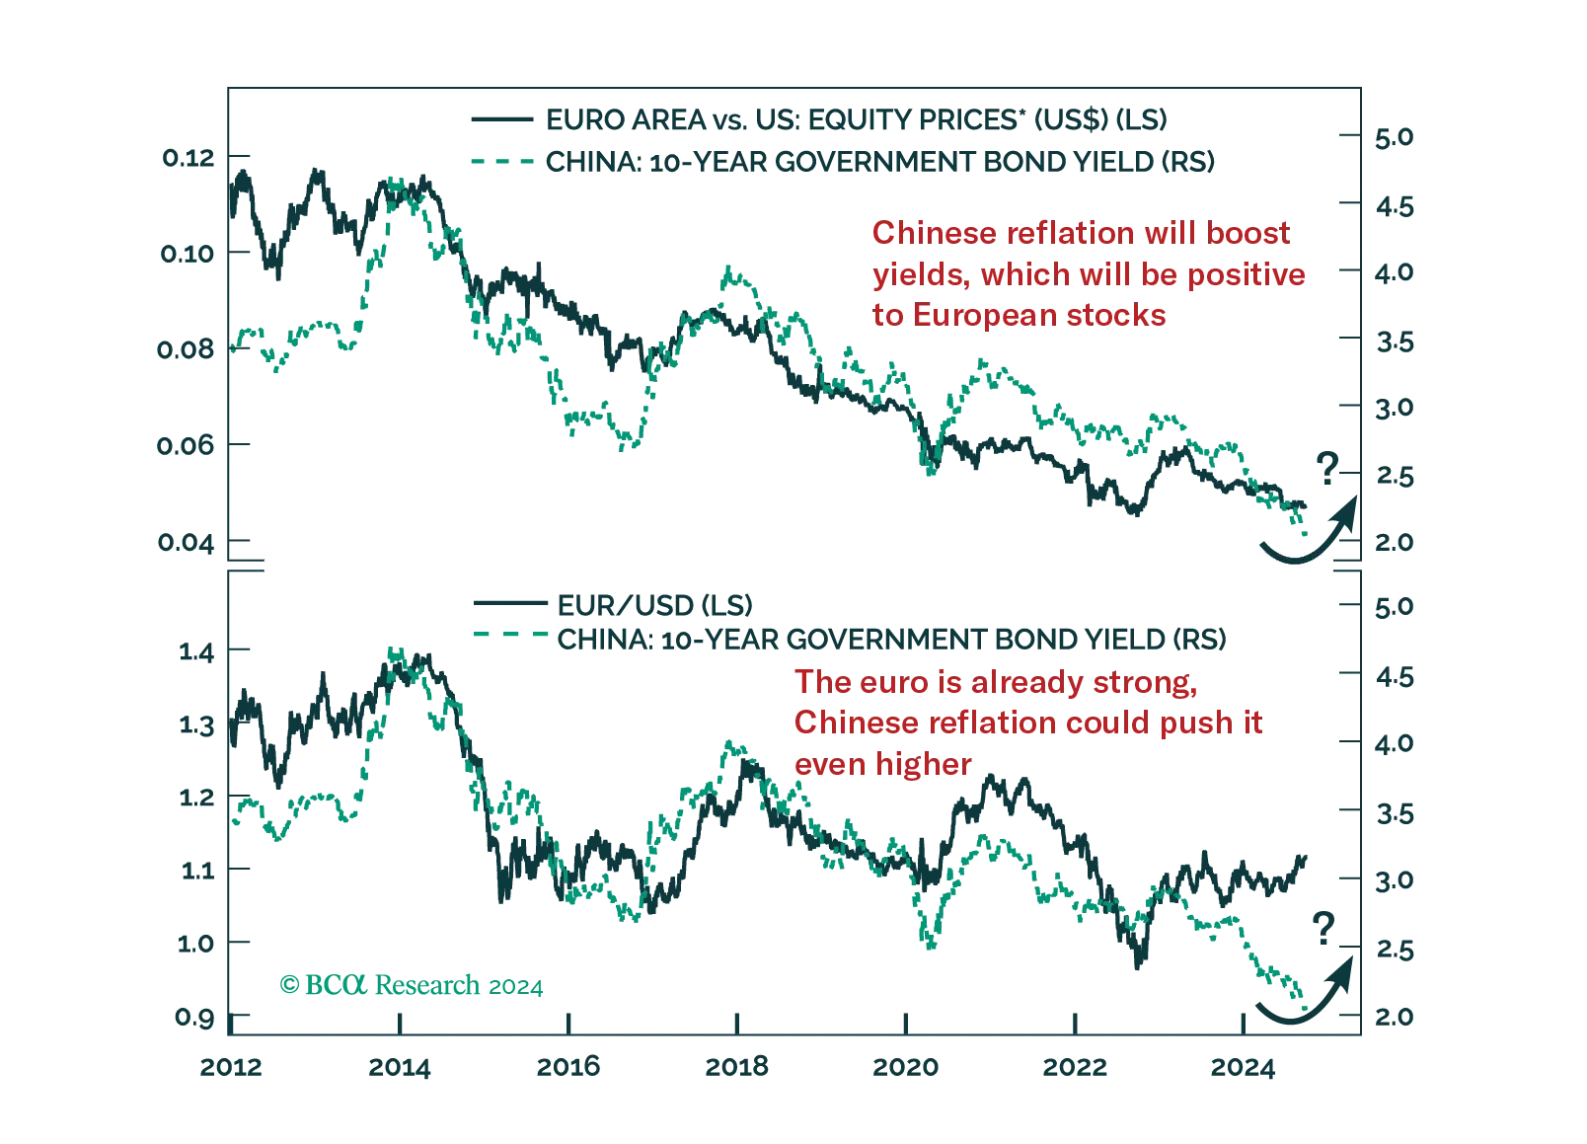
China’s Politburo announcement is likely to lead to a repricing of China’s growth in the near-term. Read how investors can hedge against this potent threat to our defensive investment stance.
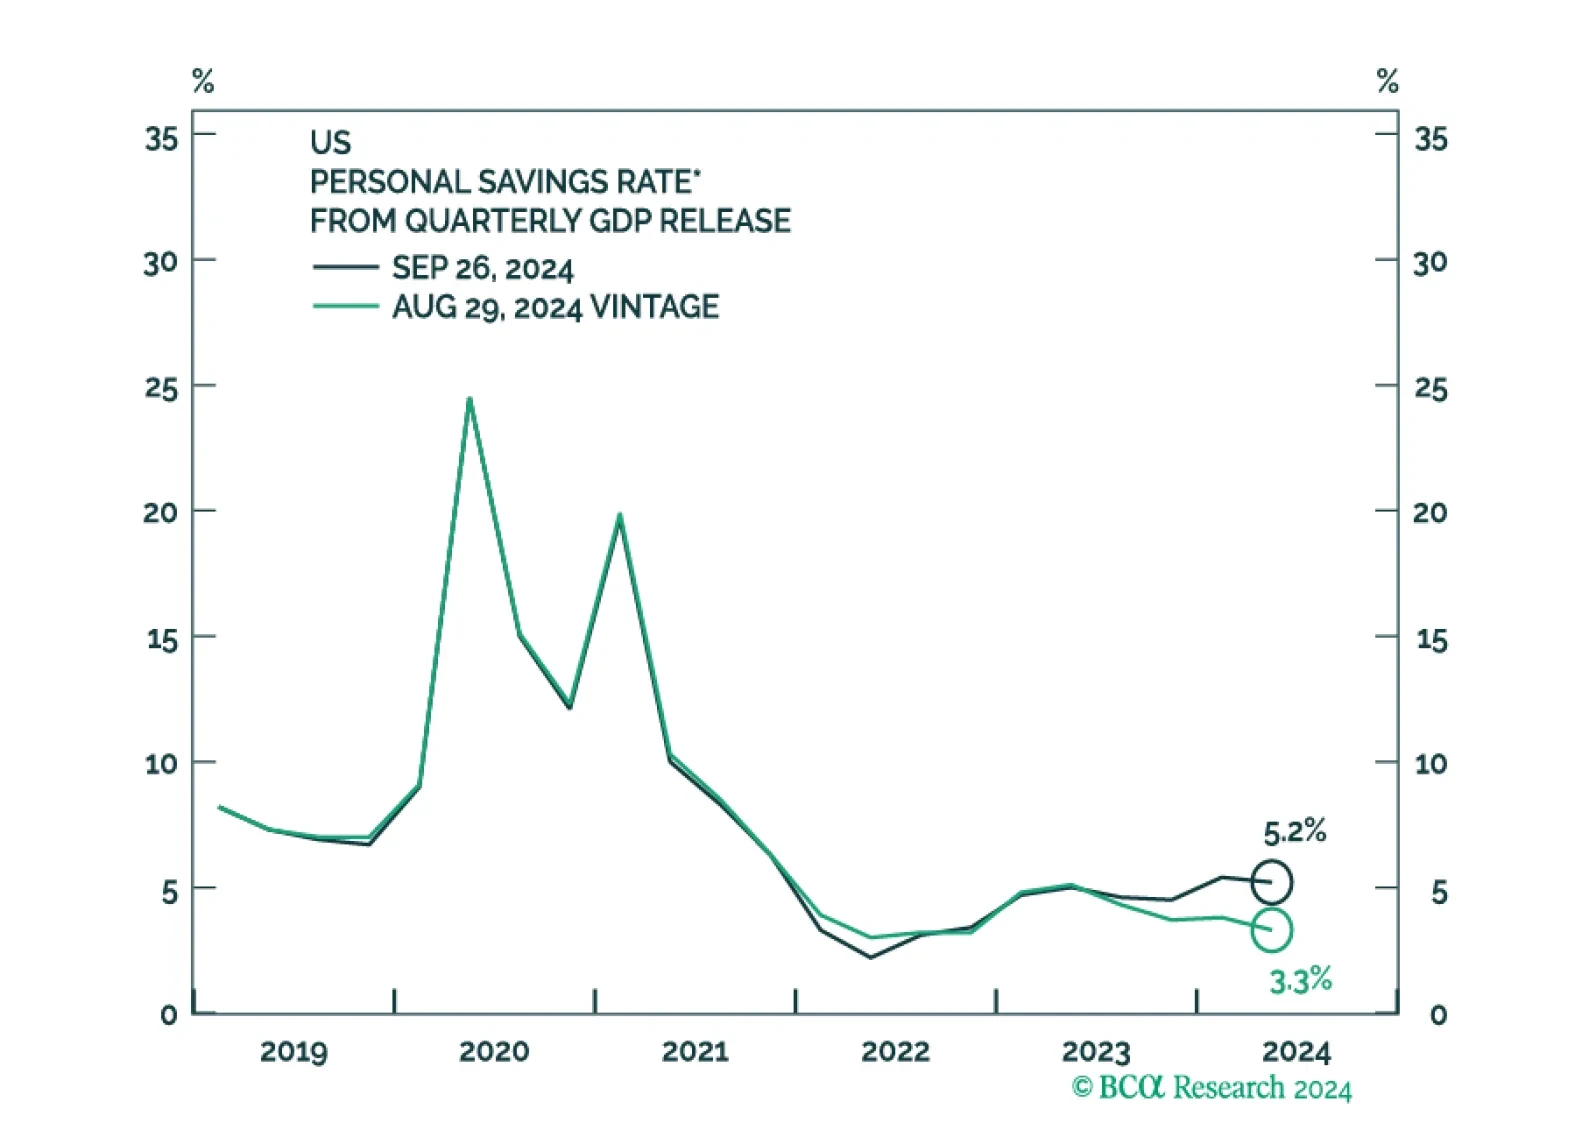
In my view, the revisions resolve a big puzzle that has developed over the past two years, which is how employment growth could have been so strong while personal income growth was so weak. Well, as it turns out, income growth was quite strong too.
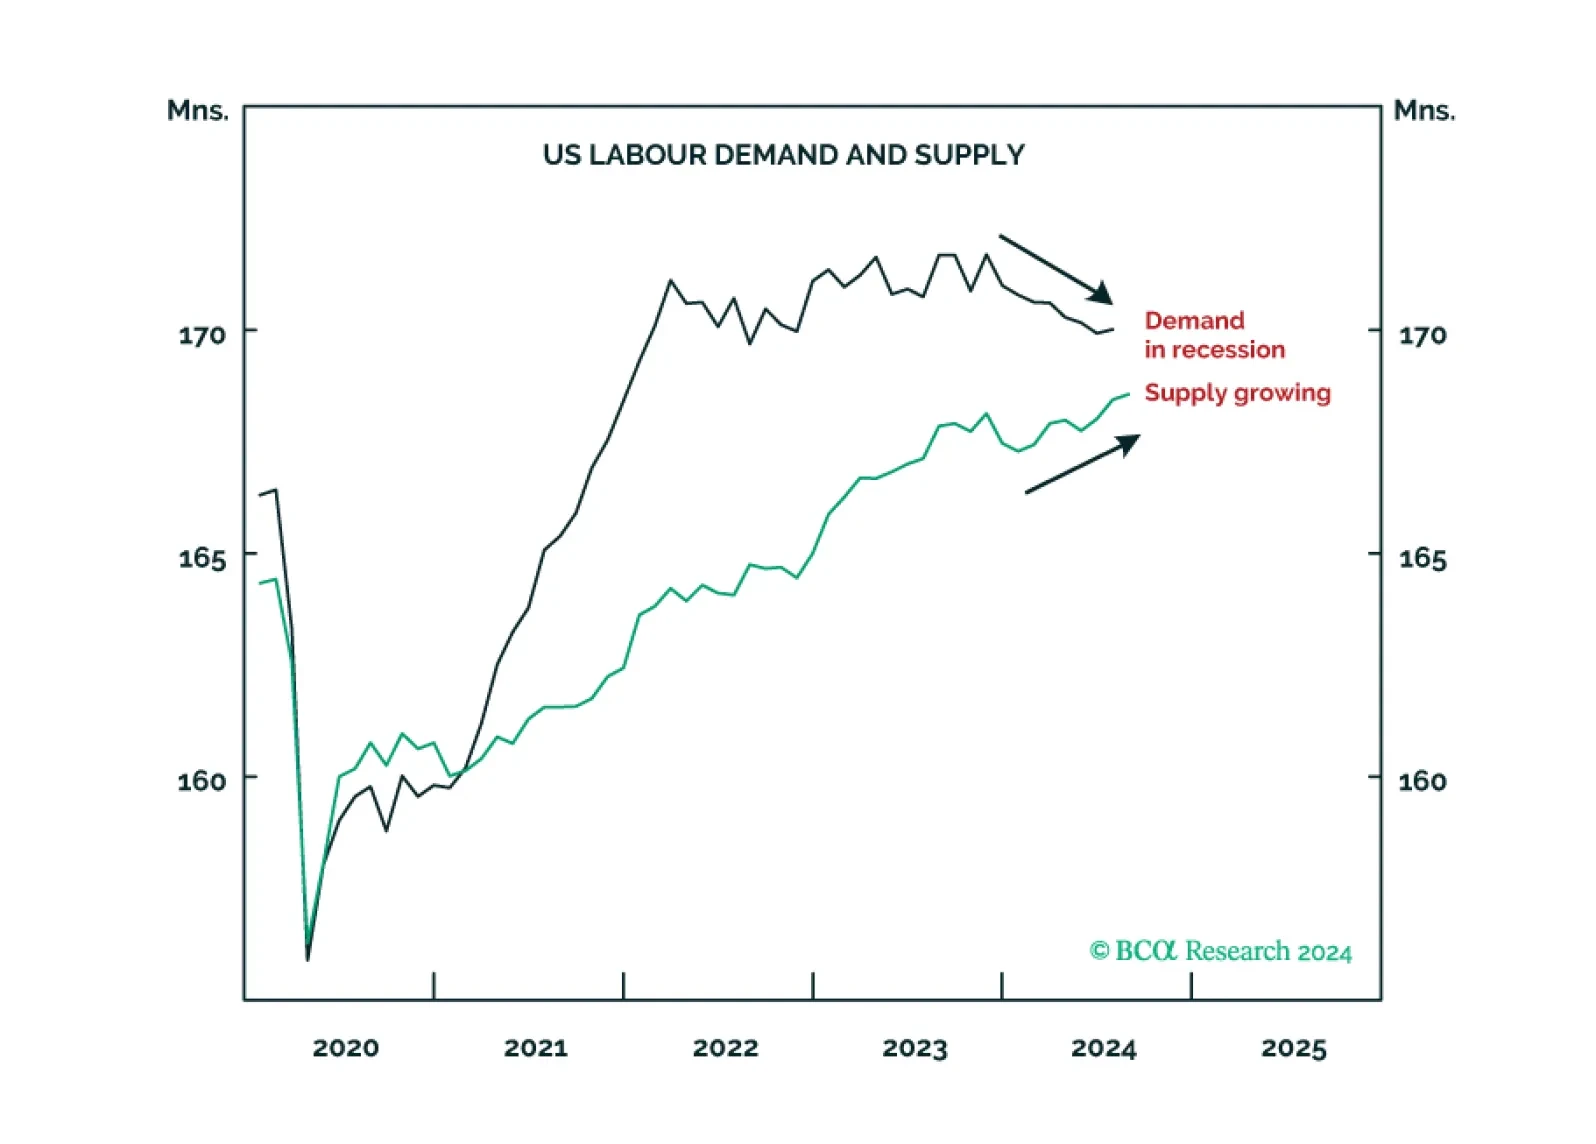
Just like the market for Oasis 2025 reunion tour tickets, the US labour market is ‘supply-constrained’. This means the US will not go into a GDP recession in the next few months and has a good chance of cheating one for longer. Without a GDP recession, there is unlikely to be an economy-wide profits recession. This leads to three recommendation changes on a cyclical (12-month) horizon which we highlight. Plus: the tactical rally in Chinese stocks can continue.