 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
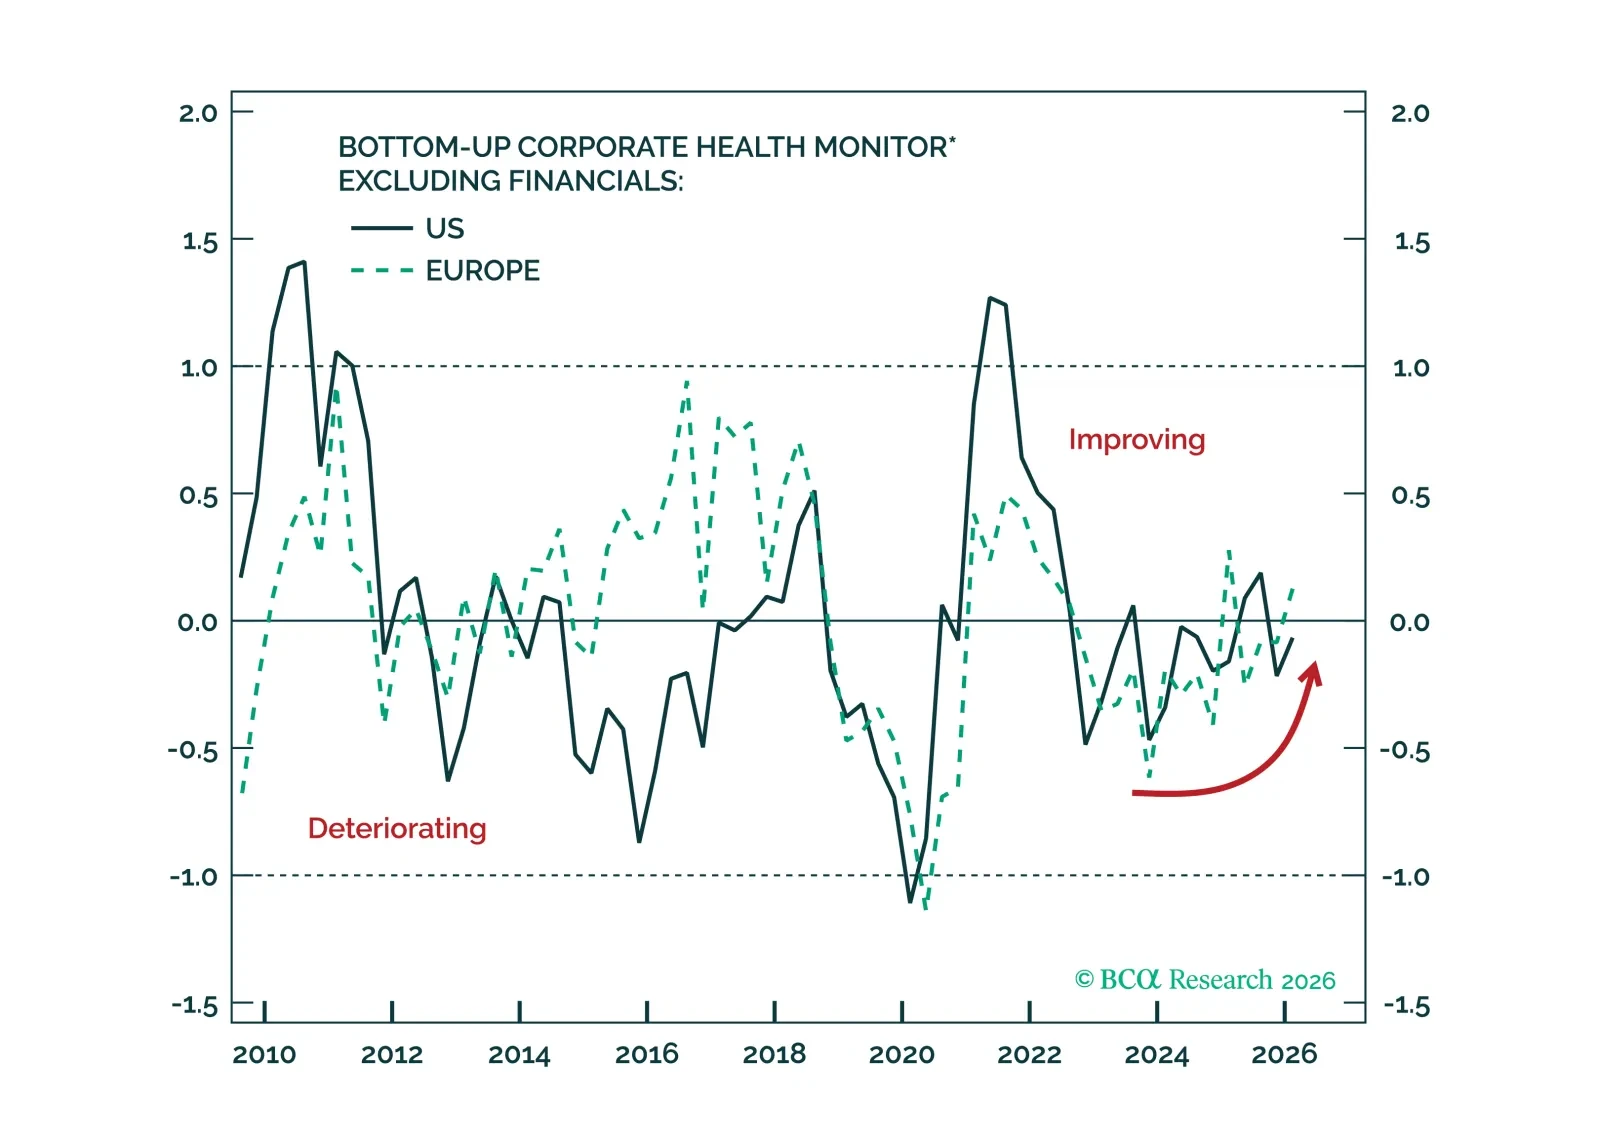
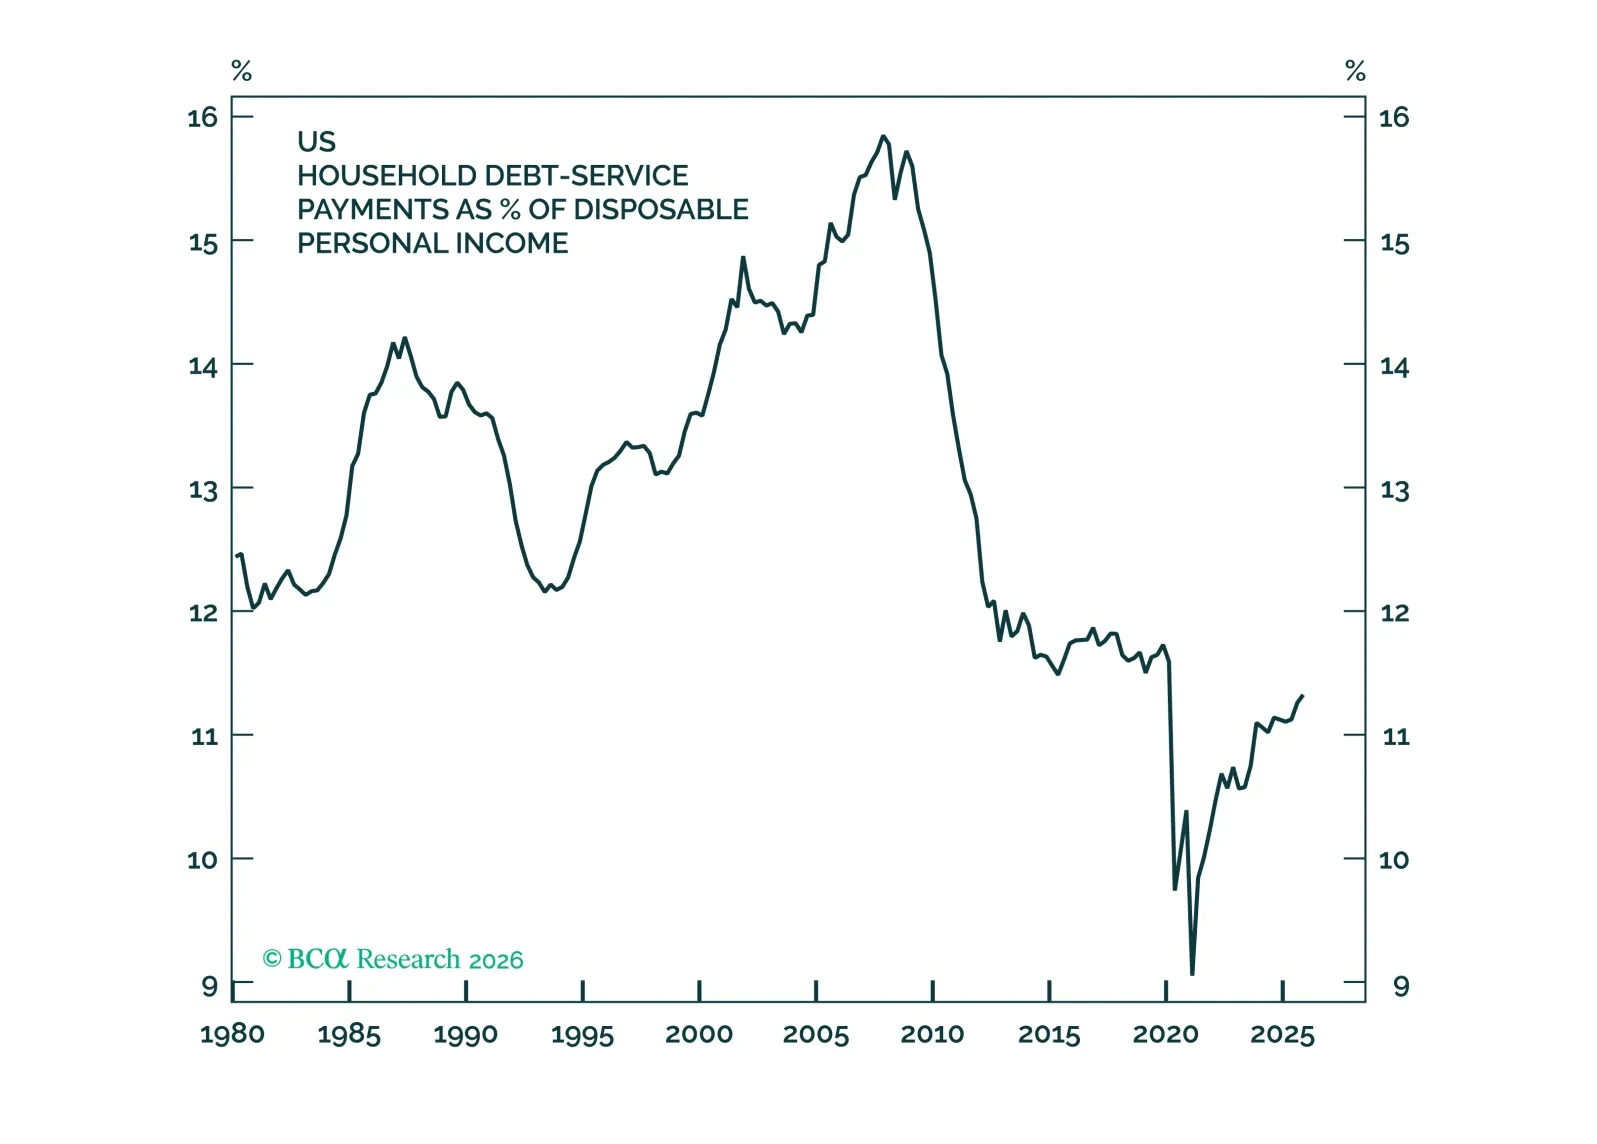
The most vulnerable households have whittled down their real debt balances while achieving significant real wealth gains. The combination has made consumption more resilient to income hiccups than in past cycles.
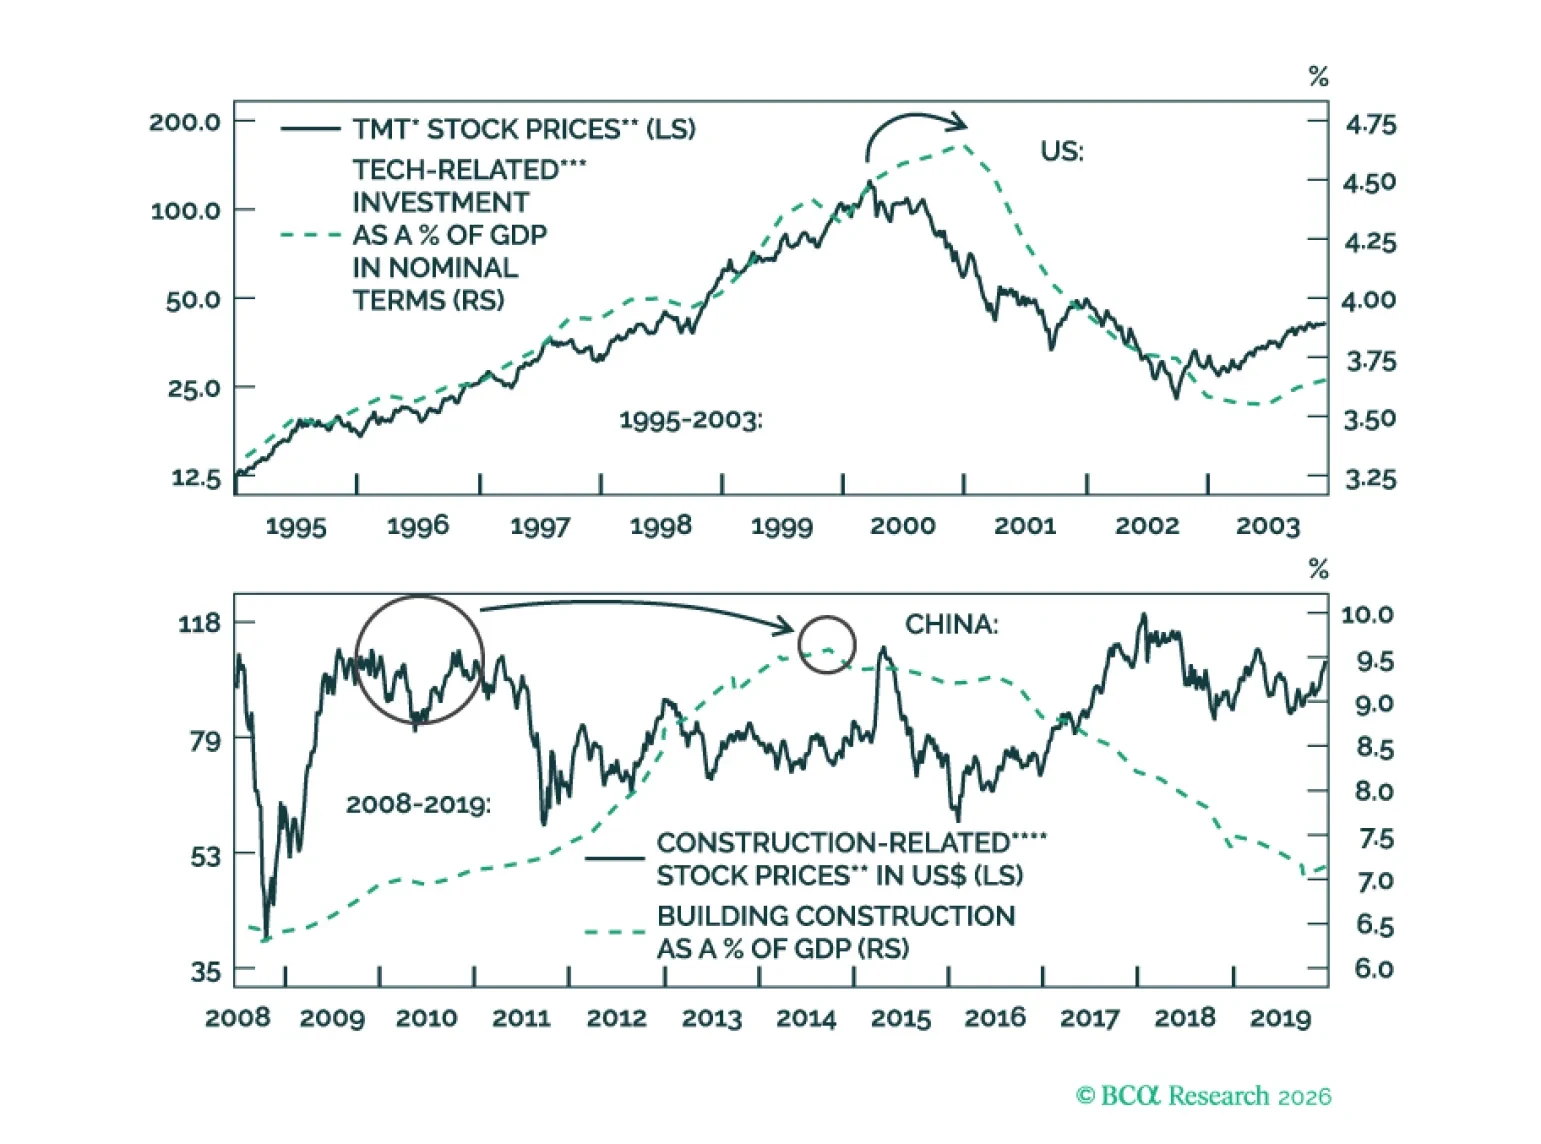
AI is transformative, yet tech stocks may not produce positive returns. Market cycles have not disappeared. Greed and fear will still produce large share price fluctuations. Meanwhile, US inflation is the key near-term risk. Global non-tech capex aspirations also look overstated.
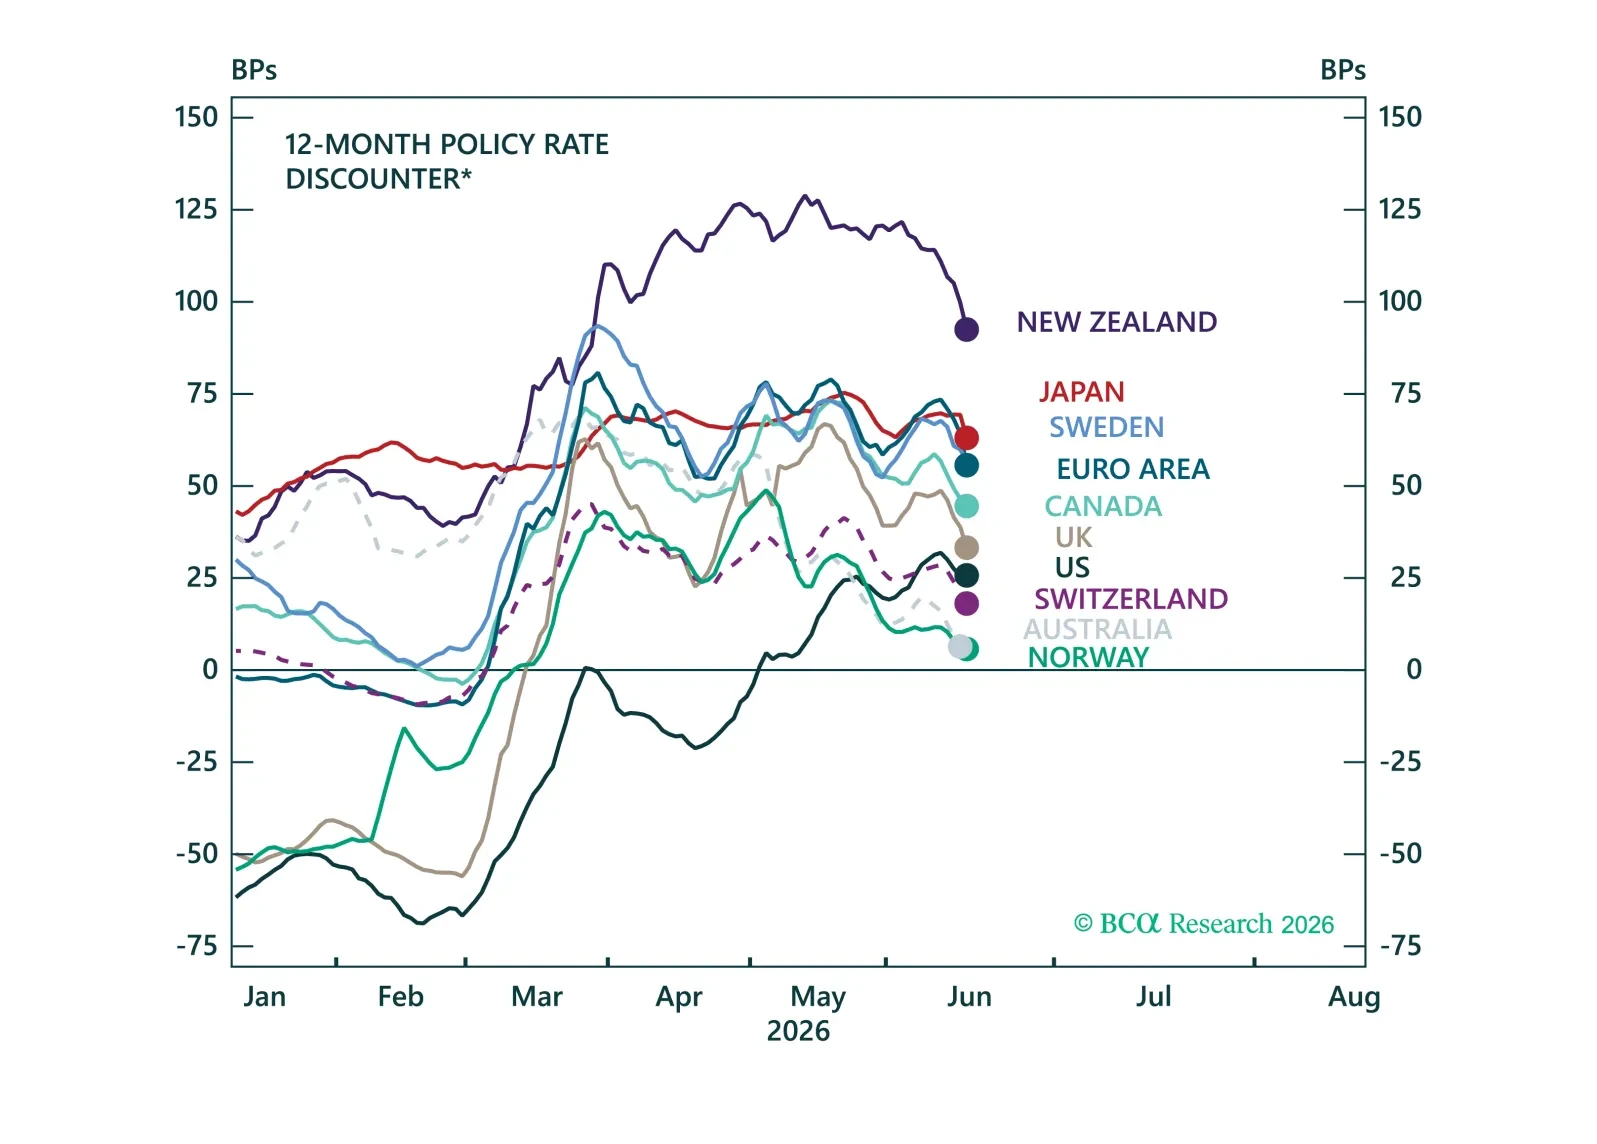
We react to DM central bank meetings this week and highlight the opportunities emerging across global fixed income and currency markets.
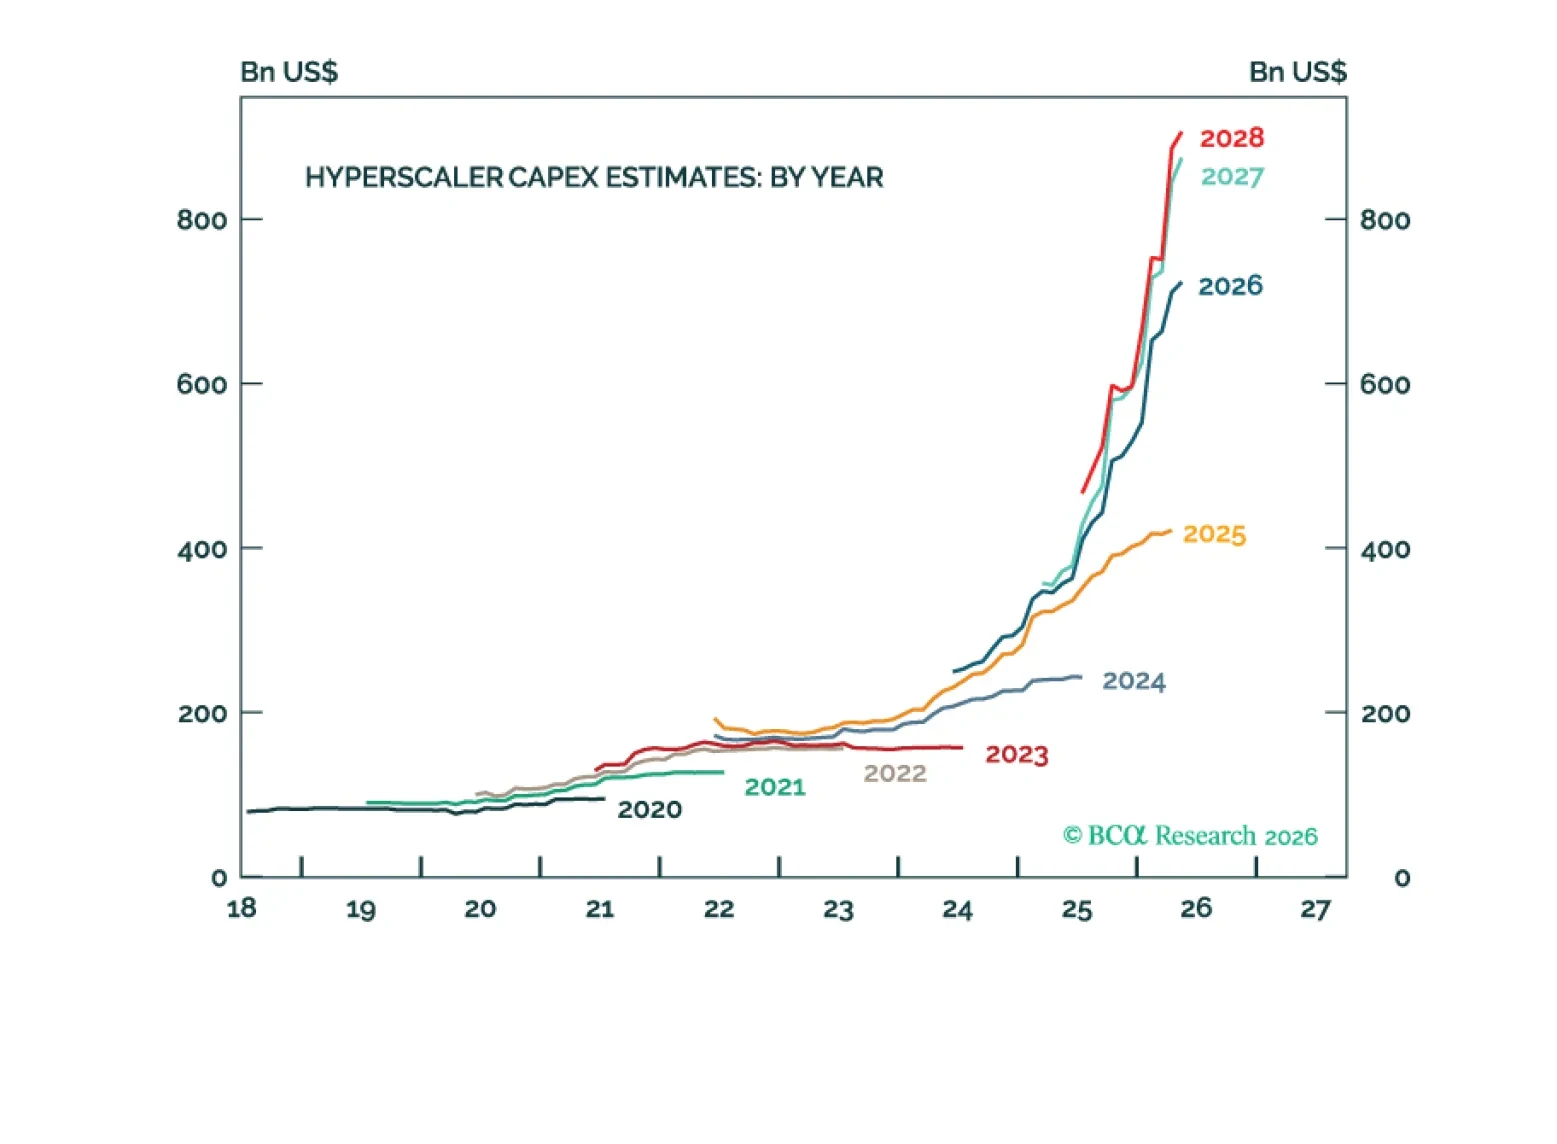
A surefire way to make money is to buy stocks in industries experiencing shortages. AI supply-chain bottlenecks will persist for the next few years but markets will price in relief before then.
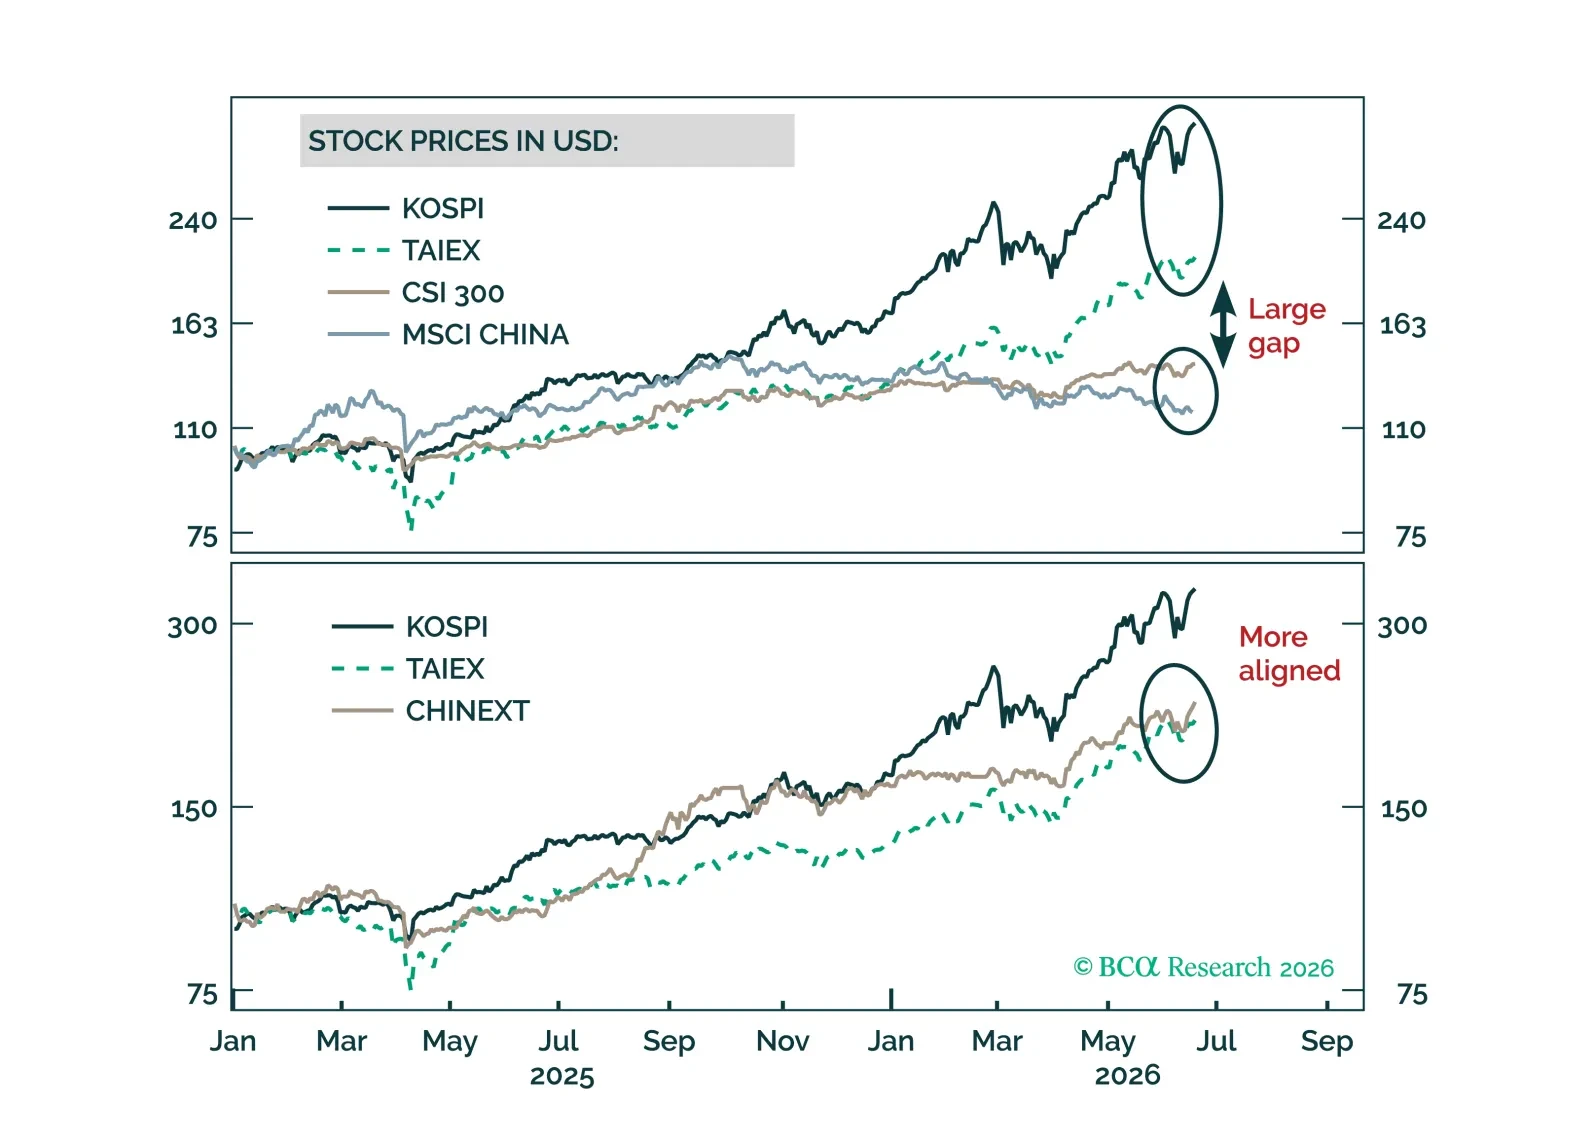
This report addresses five frequently asked questions from our Greater China clients over the past few months.
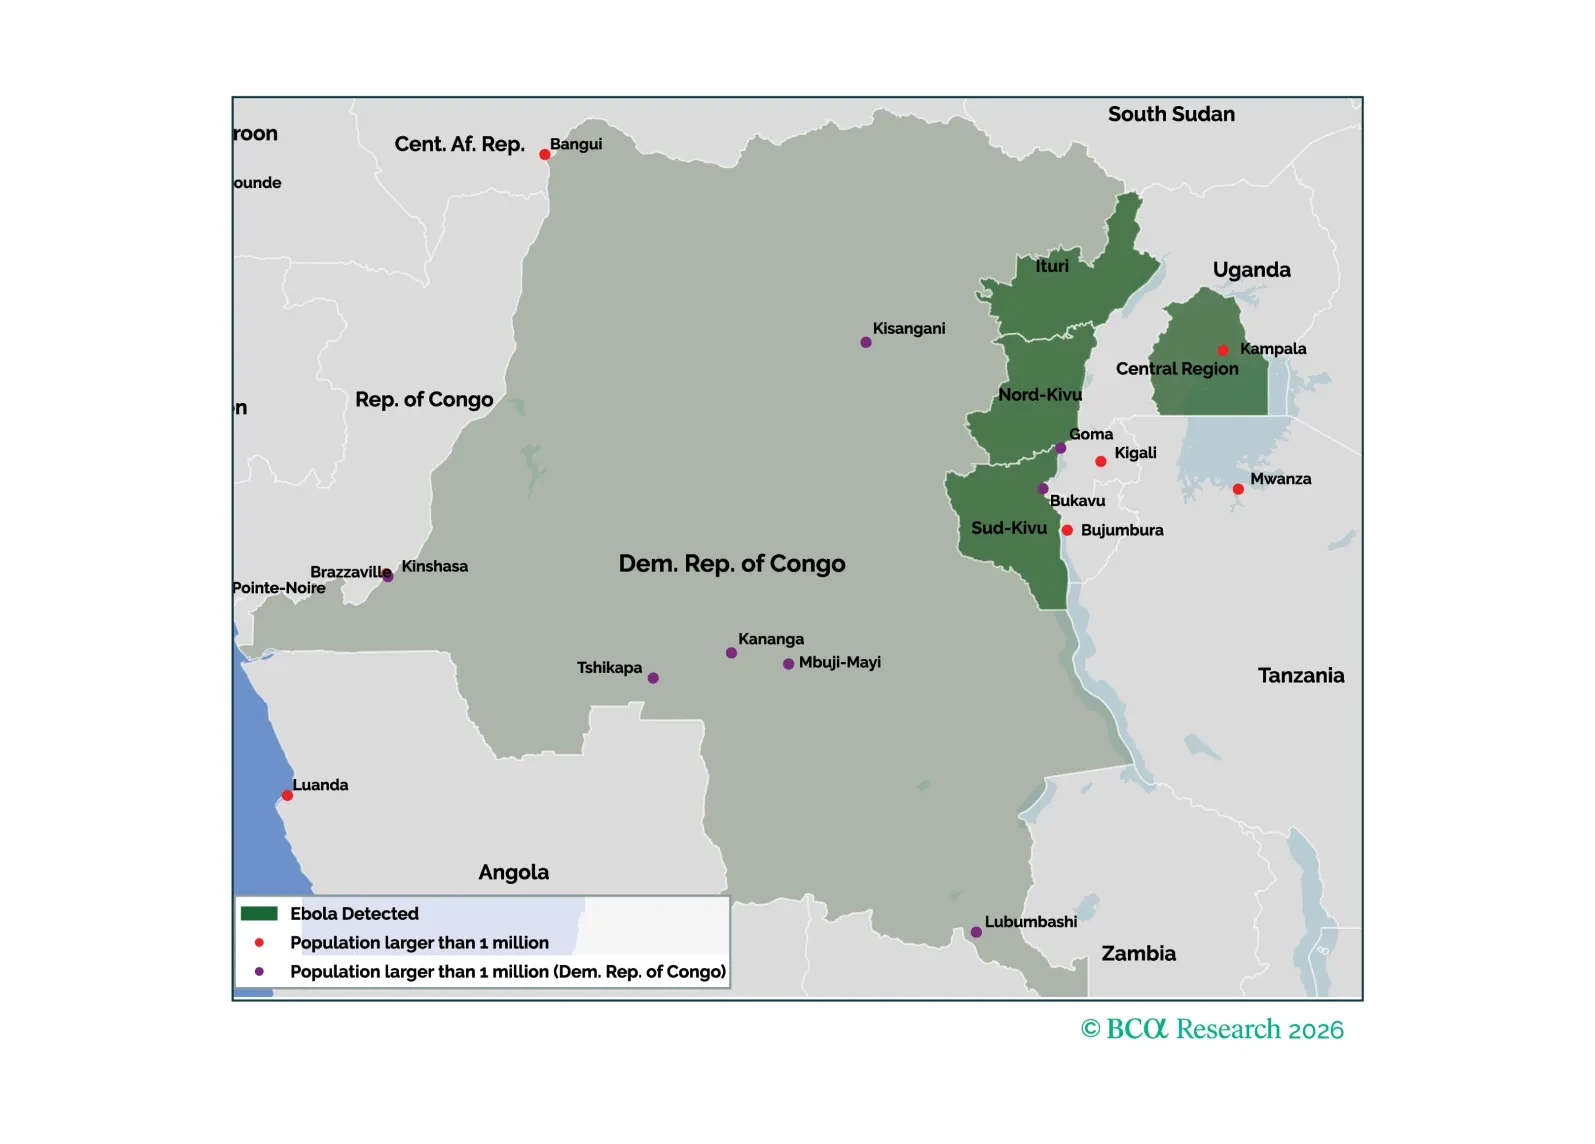
Ebola remains one of the world's deadliest viral diseases, but it is far less transmissible than COVID-19 or influenza. The most likely outcome remains containment rather than a global pandemic.
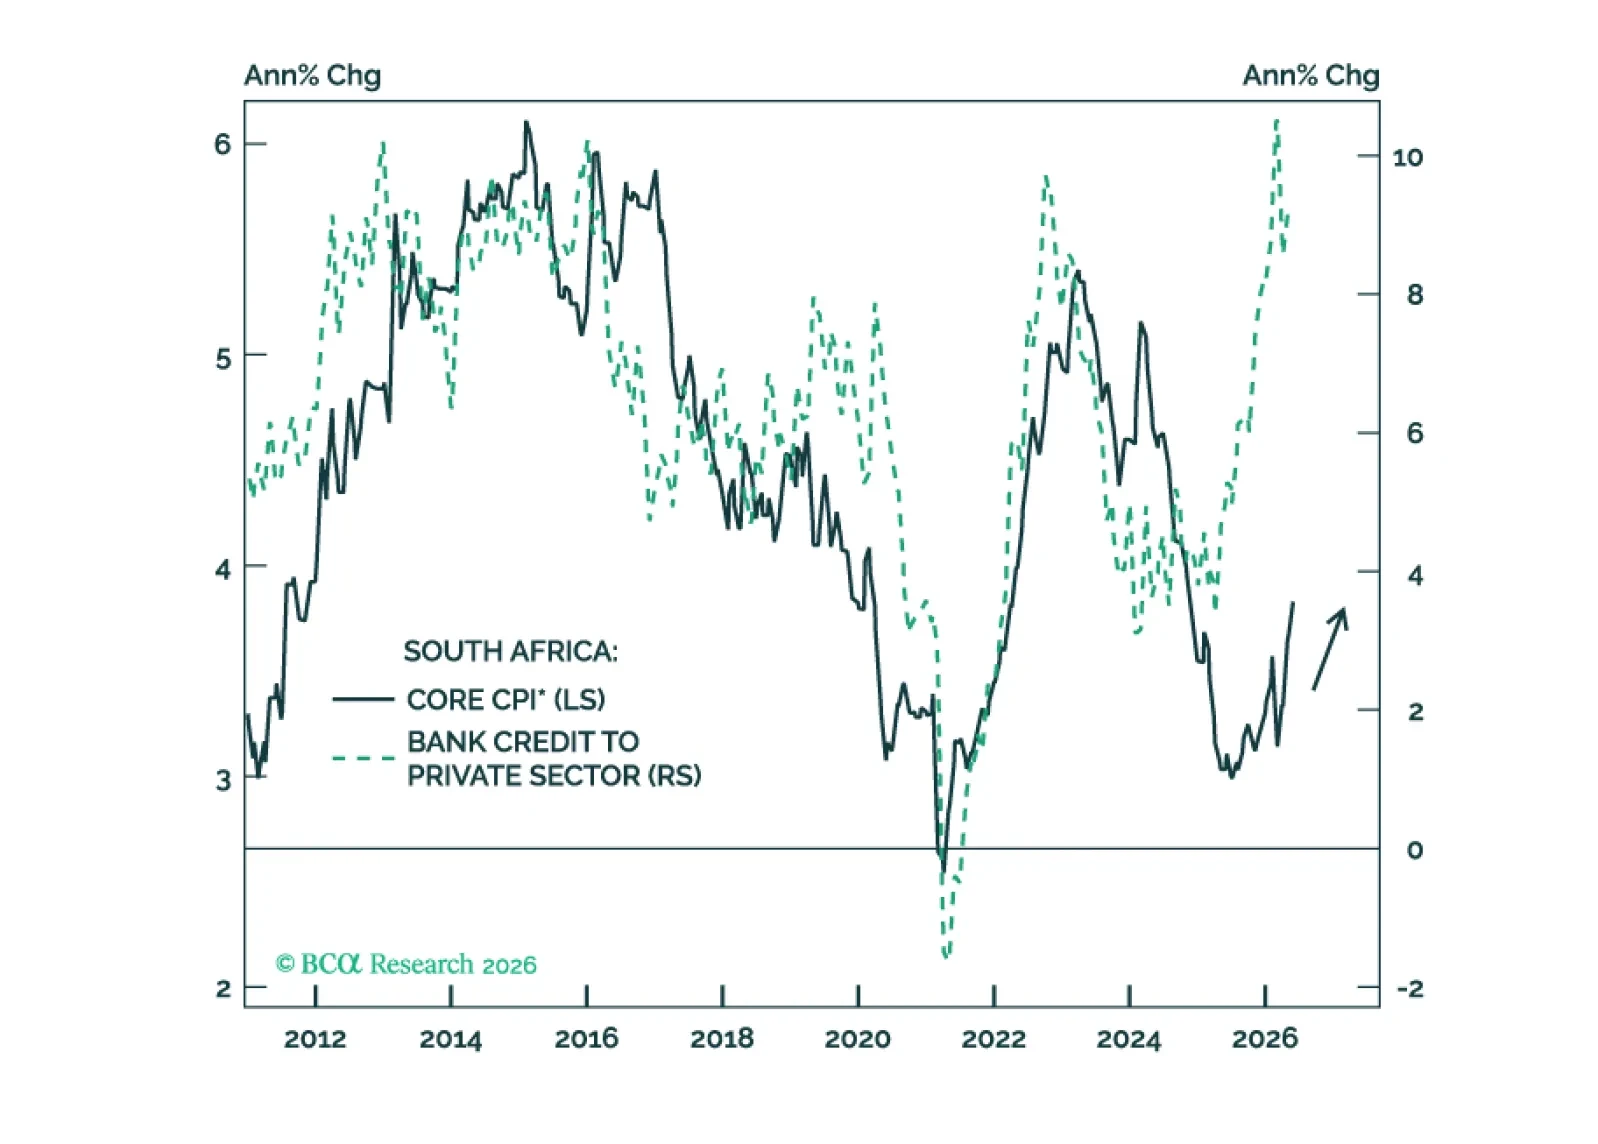
South Africa’s ambitious reform agenda will take time to bear fruit. Meanwhile, the country faces a stagflationary squeeze as inflation rises while growth slows. South African stocks, bonds, and currency are all vulnerable.
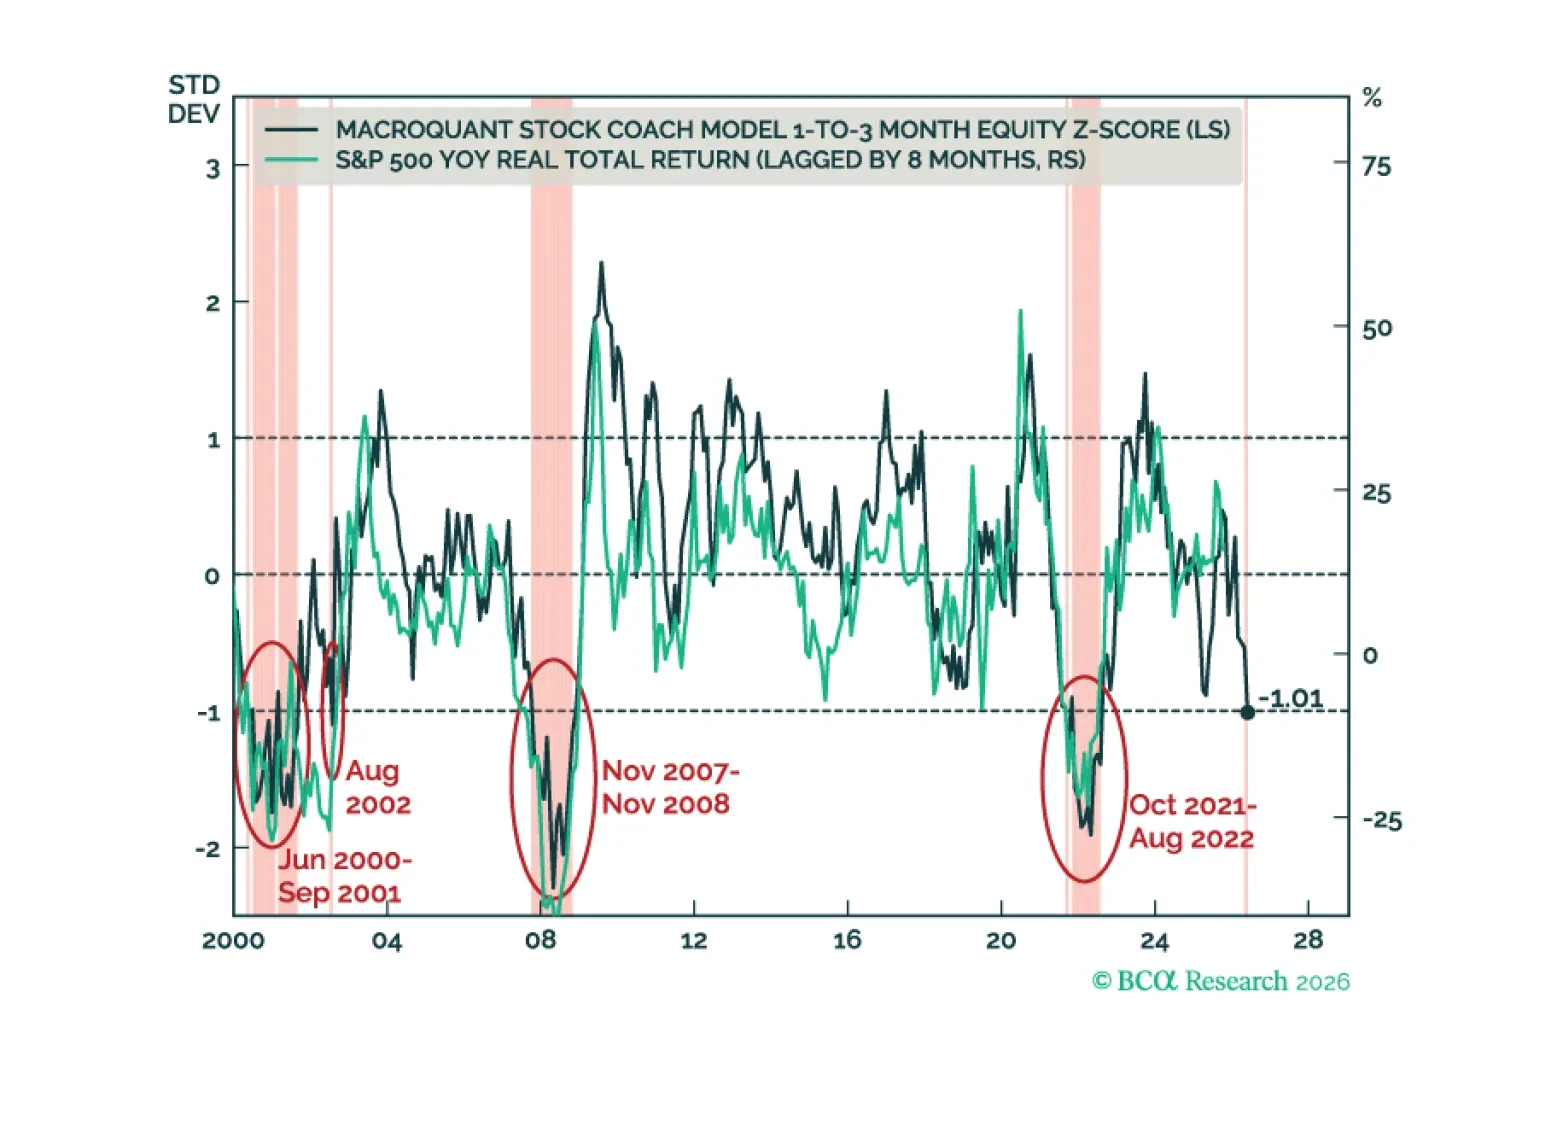
On Friday, the MacroQuant equity z-score fell to -1.01, below the critical -1 threshold that often coincided with bear markets in the past. With that in mind, today, I am downgrading stocks to a slight underweight on both a 3-month and a 12-month horizon.
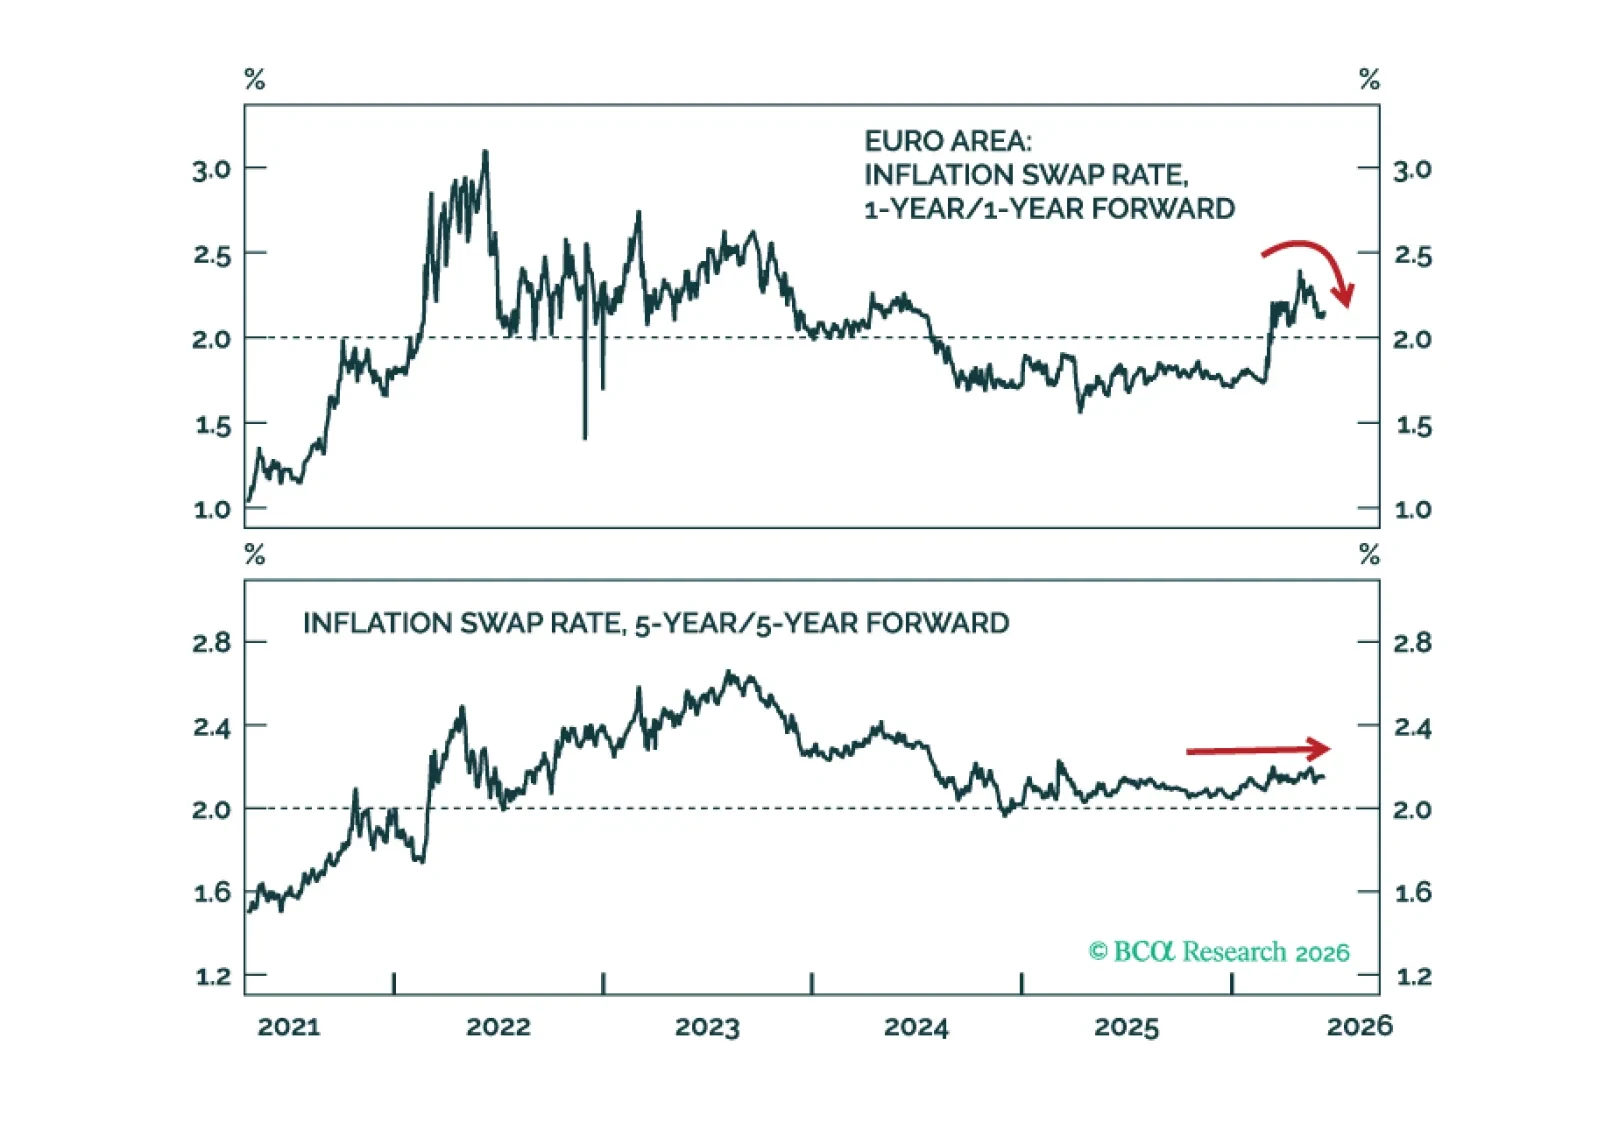
Today’s ECB rate hike is not the beginning of a hiking cycle. Growth concerns will soon move to the forefront of ECB policy decisions, preventing further tightening.