 Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
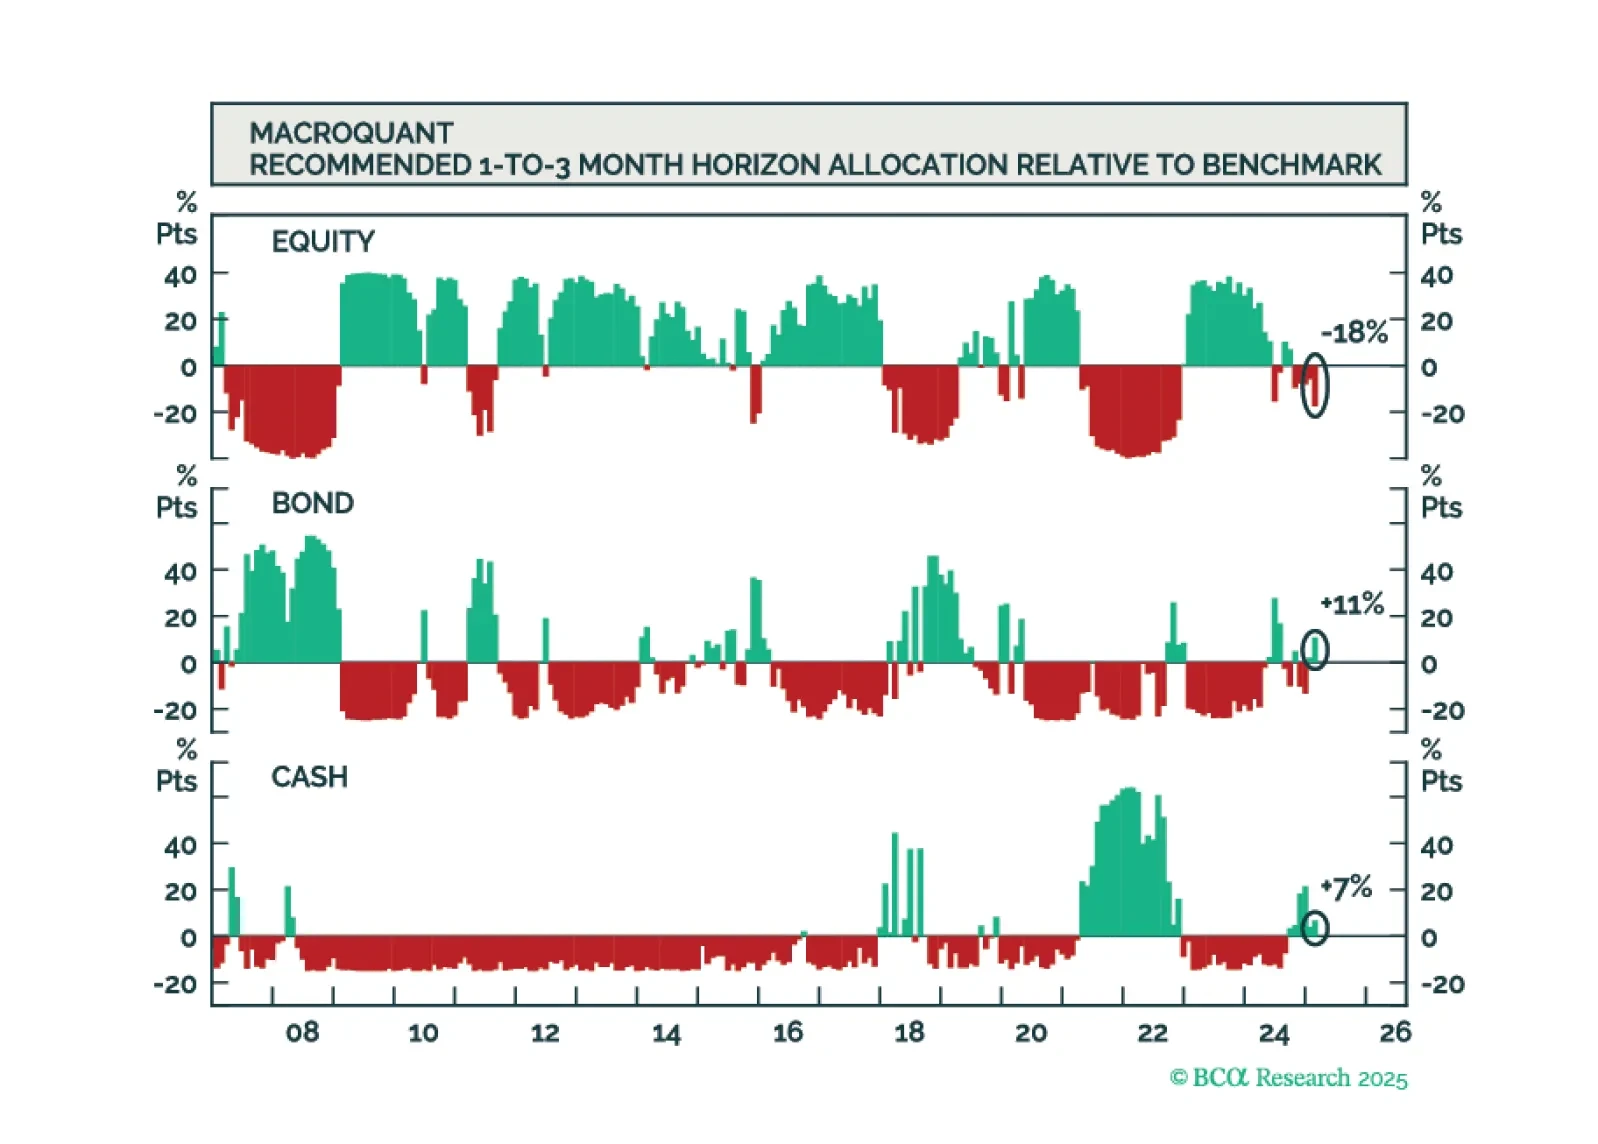
Going into April, MacroQuant recommends a modest underweight on stocks, offset by an overweight on bonds and cash. While MacroQuant is modestly bearish on stocks, we suspect that the downside risks to equities may be greater than what the model assumes.
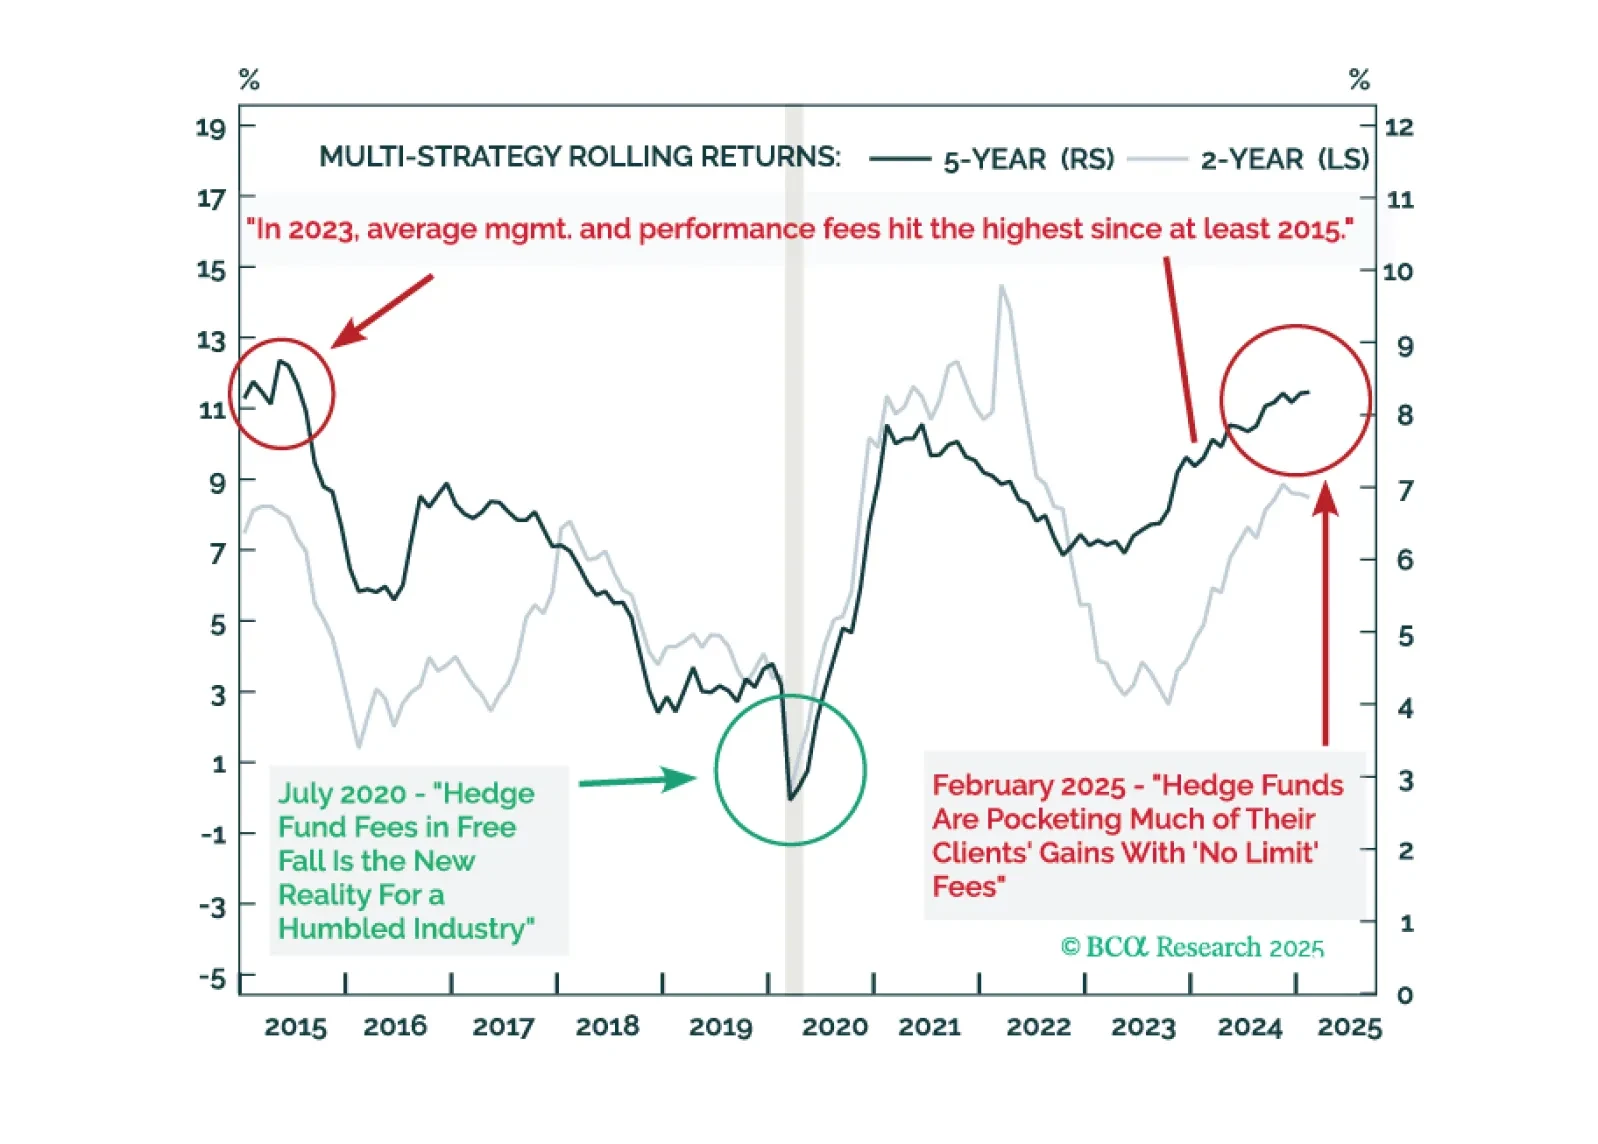
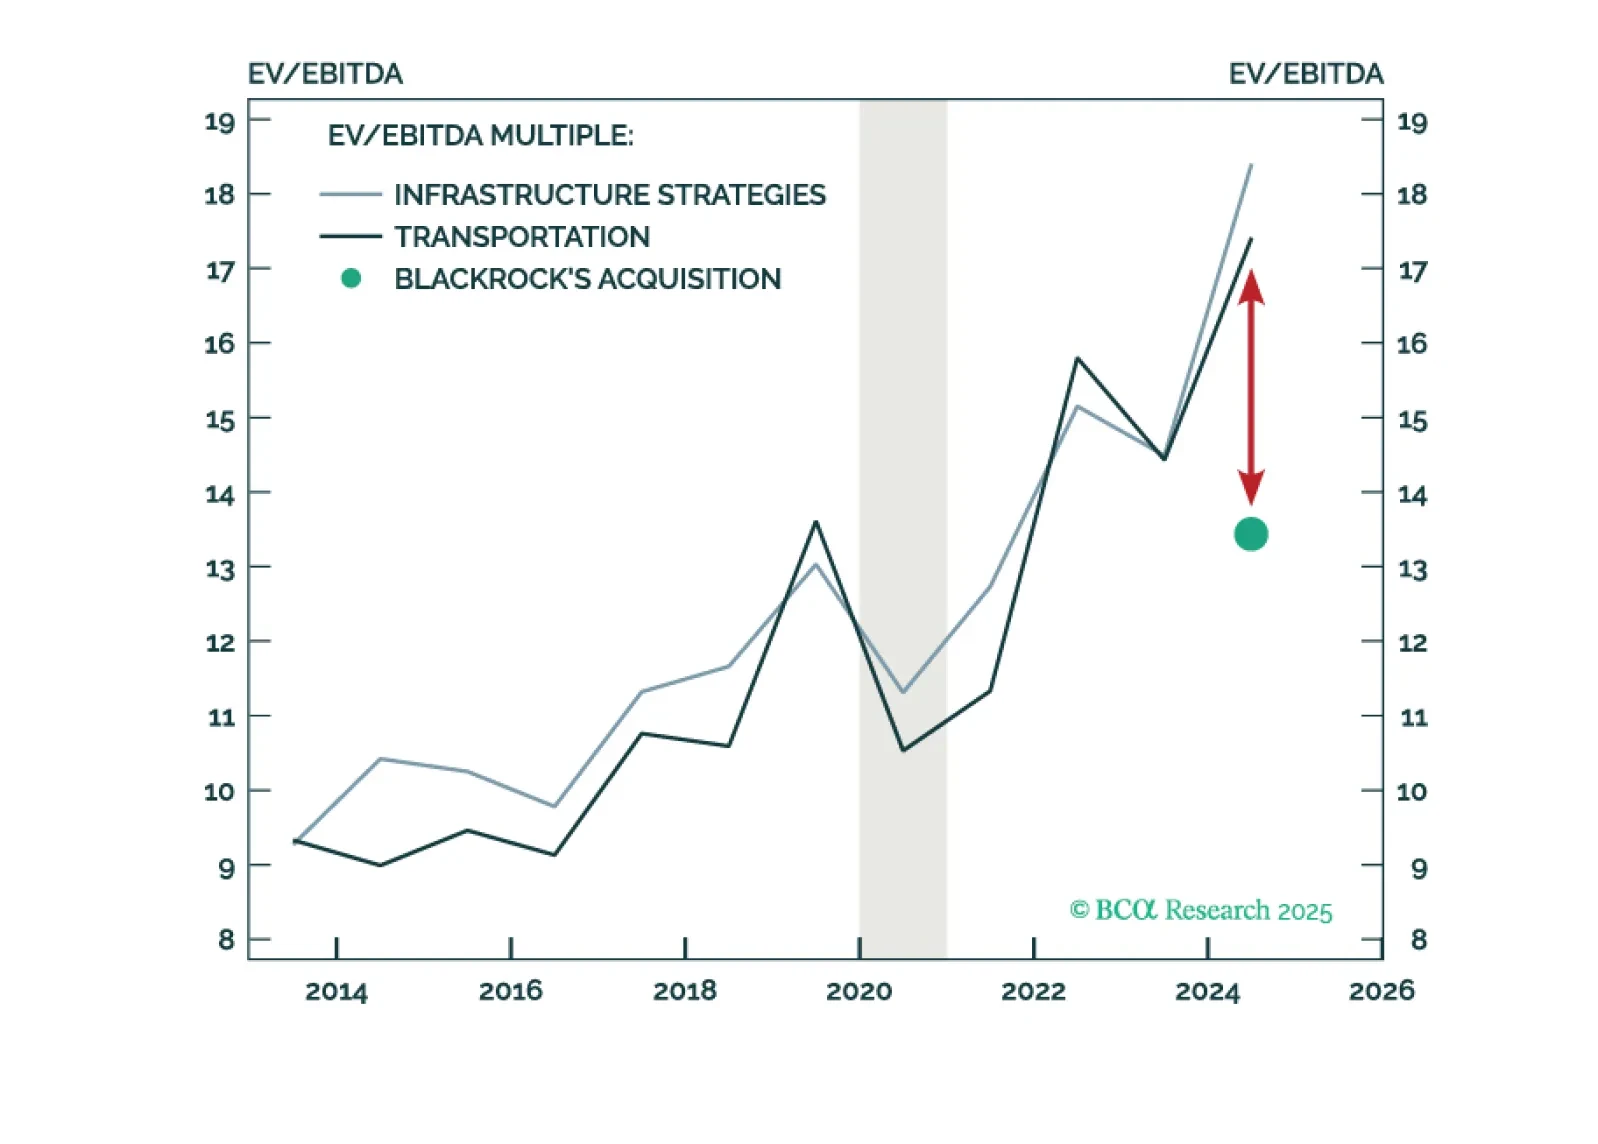
The ports that BlackRock acquired on both sides of the Panama Canal appear to be a bargain in terms of the entry valuation. But are the risks being appropriately compensated? In this prefatory report, we prepare investors for our upcoming Infrastructure reports, which will highlight geopolitical risk factors in this private asset class rarely encountered in others.
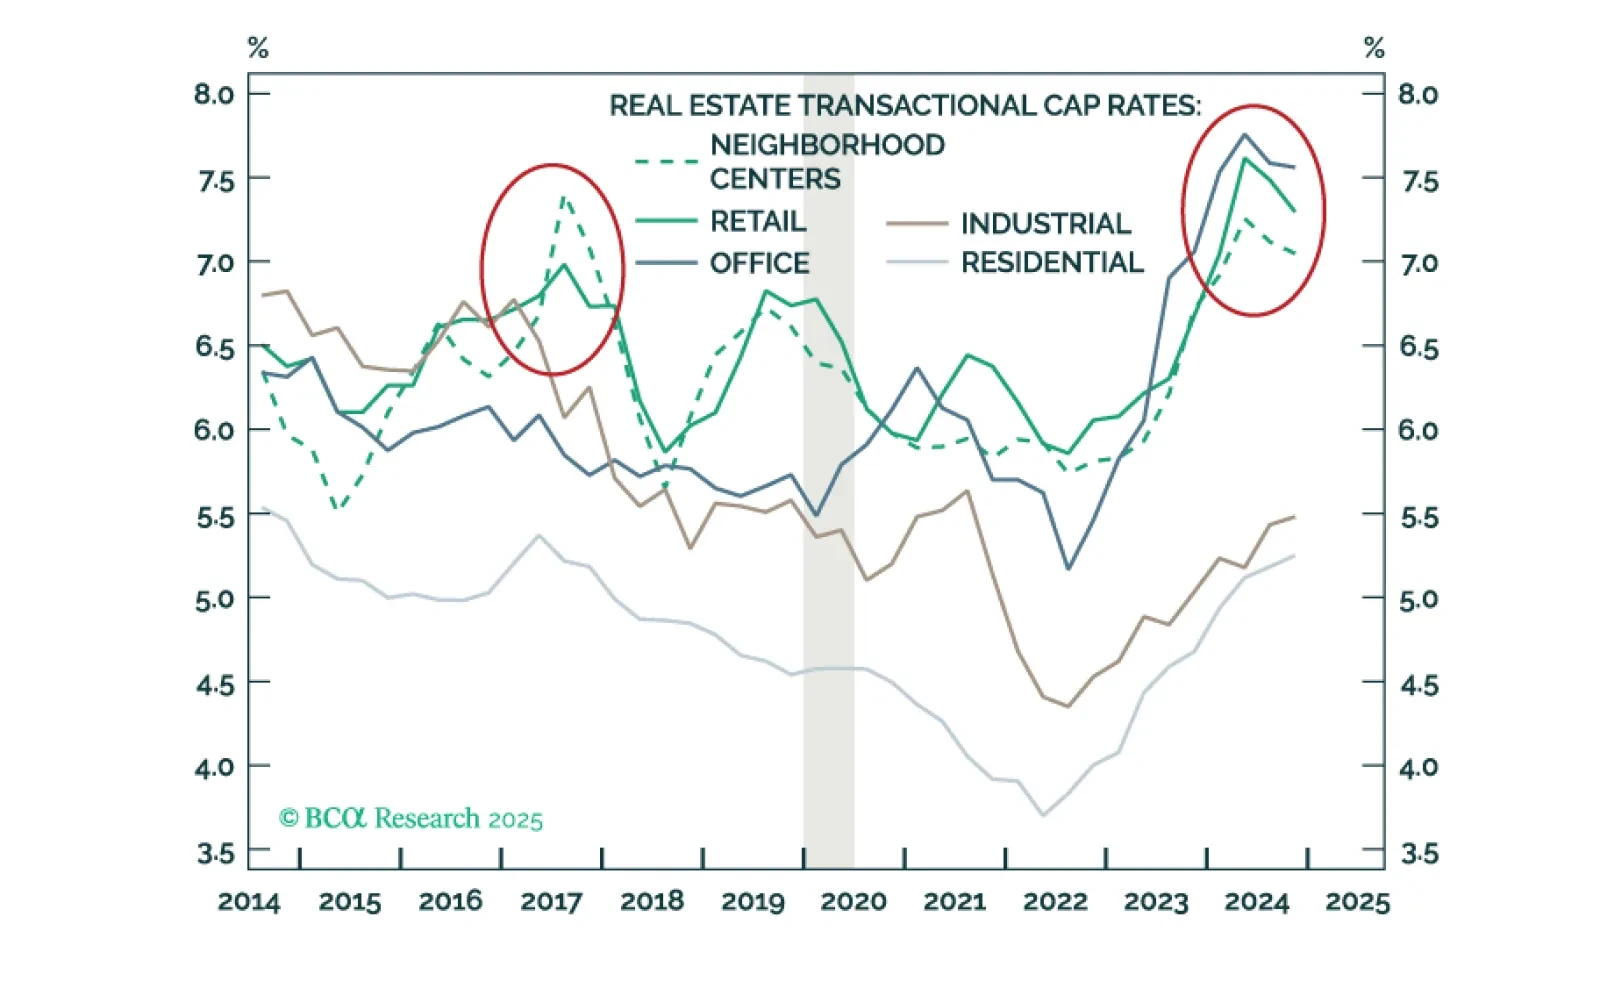
It is time to bet on brick-and-mortar again. The next time you step around your partner's Amazon package on your way to a physical store, consider this: Rock-bottom investor expectations, attractive initial fundamentals, and ongoing demographic shifts make Retail Real Estate a buy for the first time in a decade.
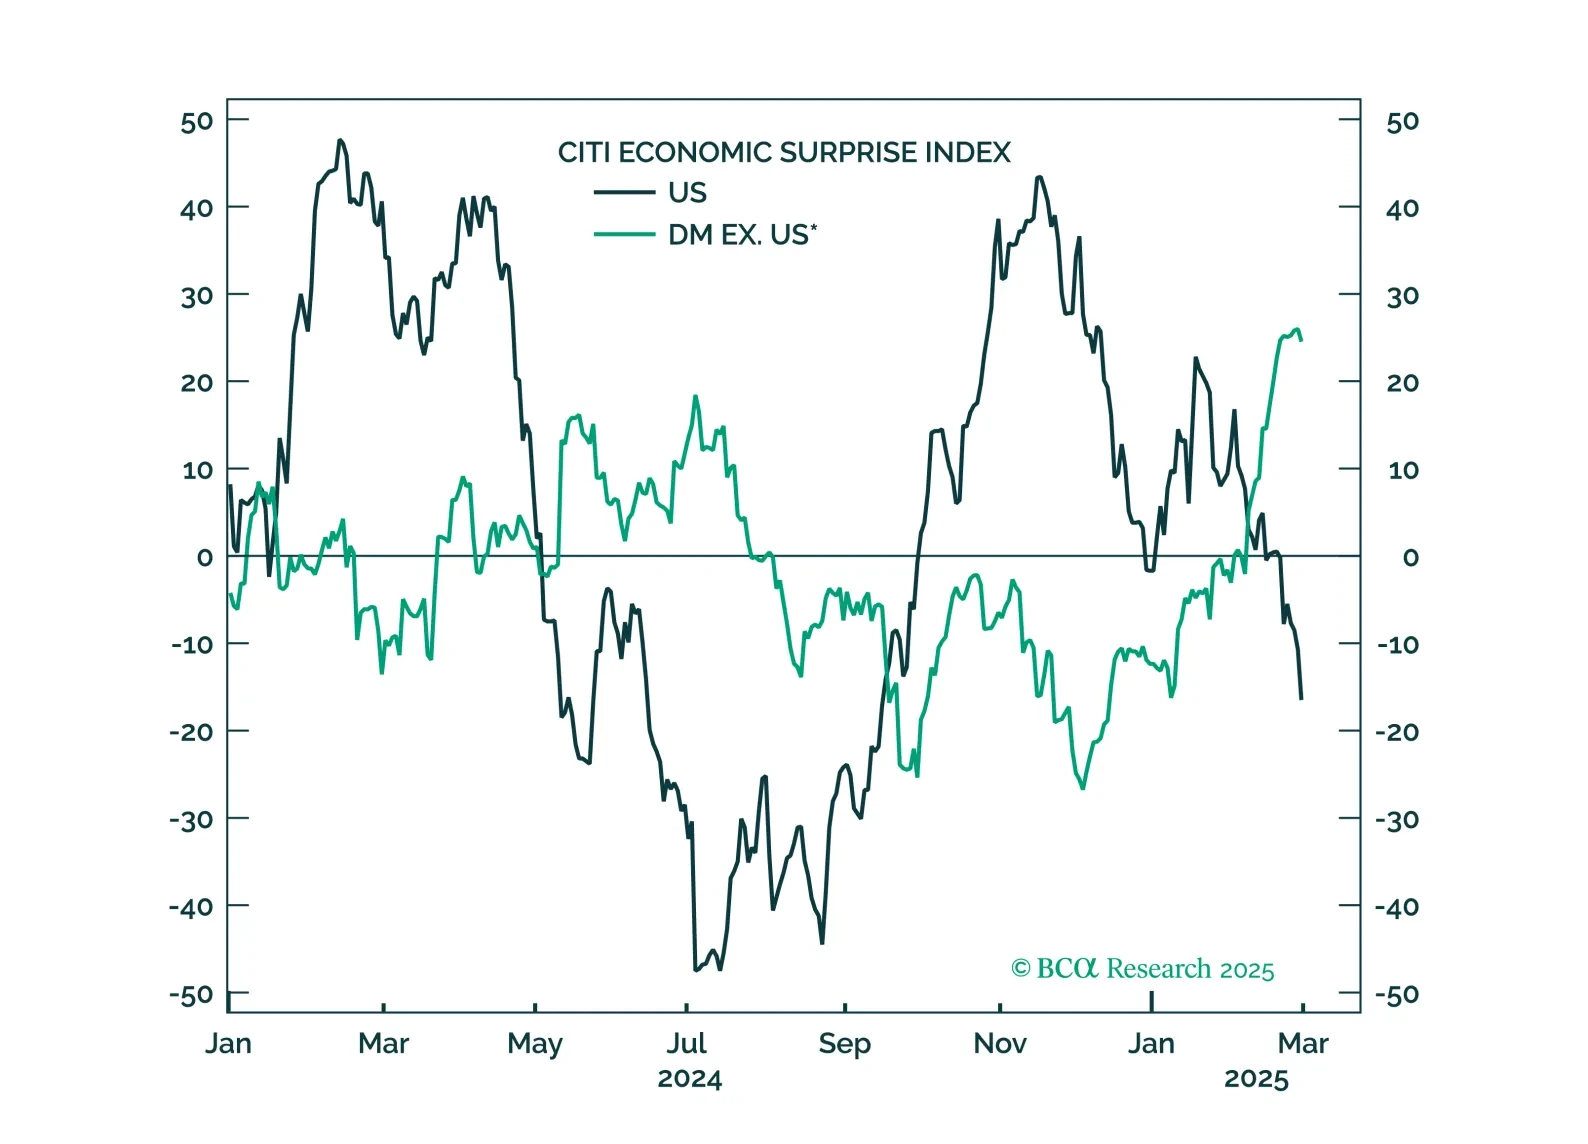
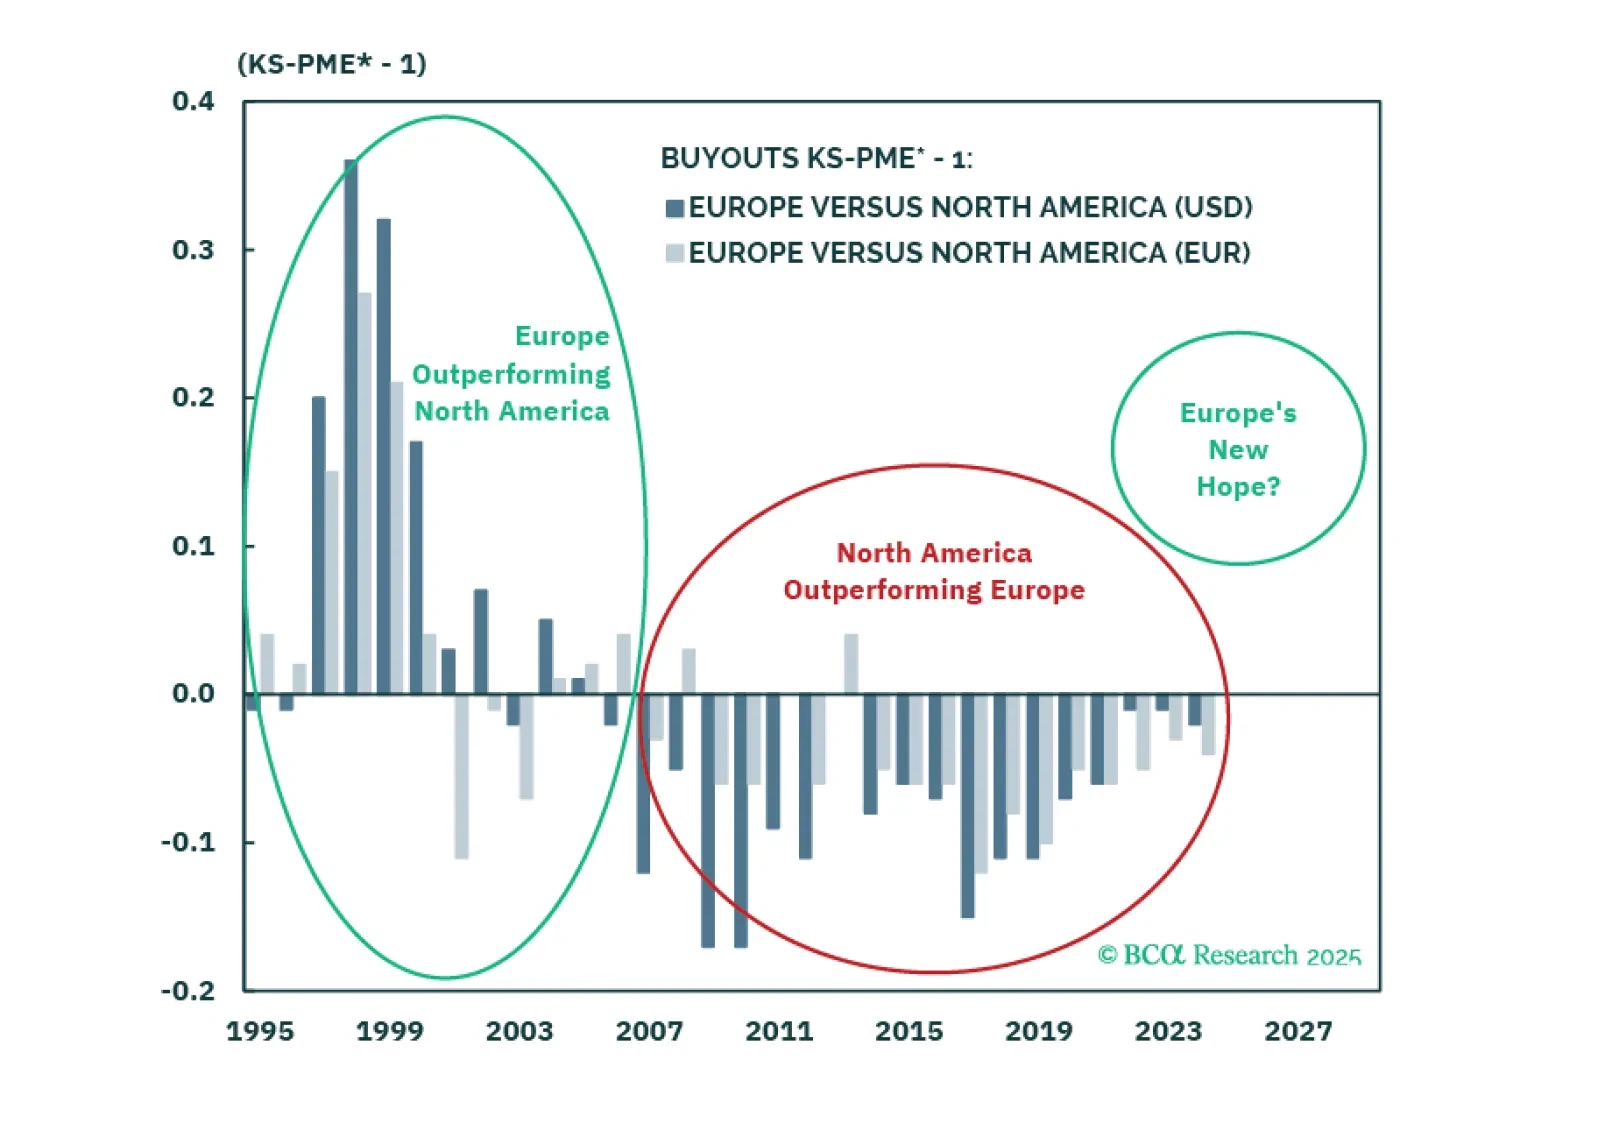
Investors see Europe as a museum: A continent stuck in the past, with no ability to innovate, much less generate profits. But is this view accurate? In this report we argue that the structural headwinds to European profitability are a thing of the past. Political change and improving sentiment are also a tailwind for Europe. Meanwhile, in the US, economic uncertainty brought about by Trump’s policies have reversed the surge in animal spirits that followed the election. All of this is happening within the context of weakening growth. We upgrade European equities from neutral to overweight and downgrade US equities from neutral to underweight.
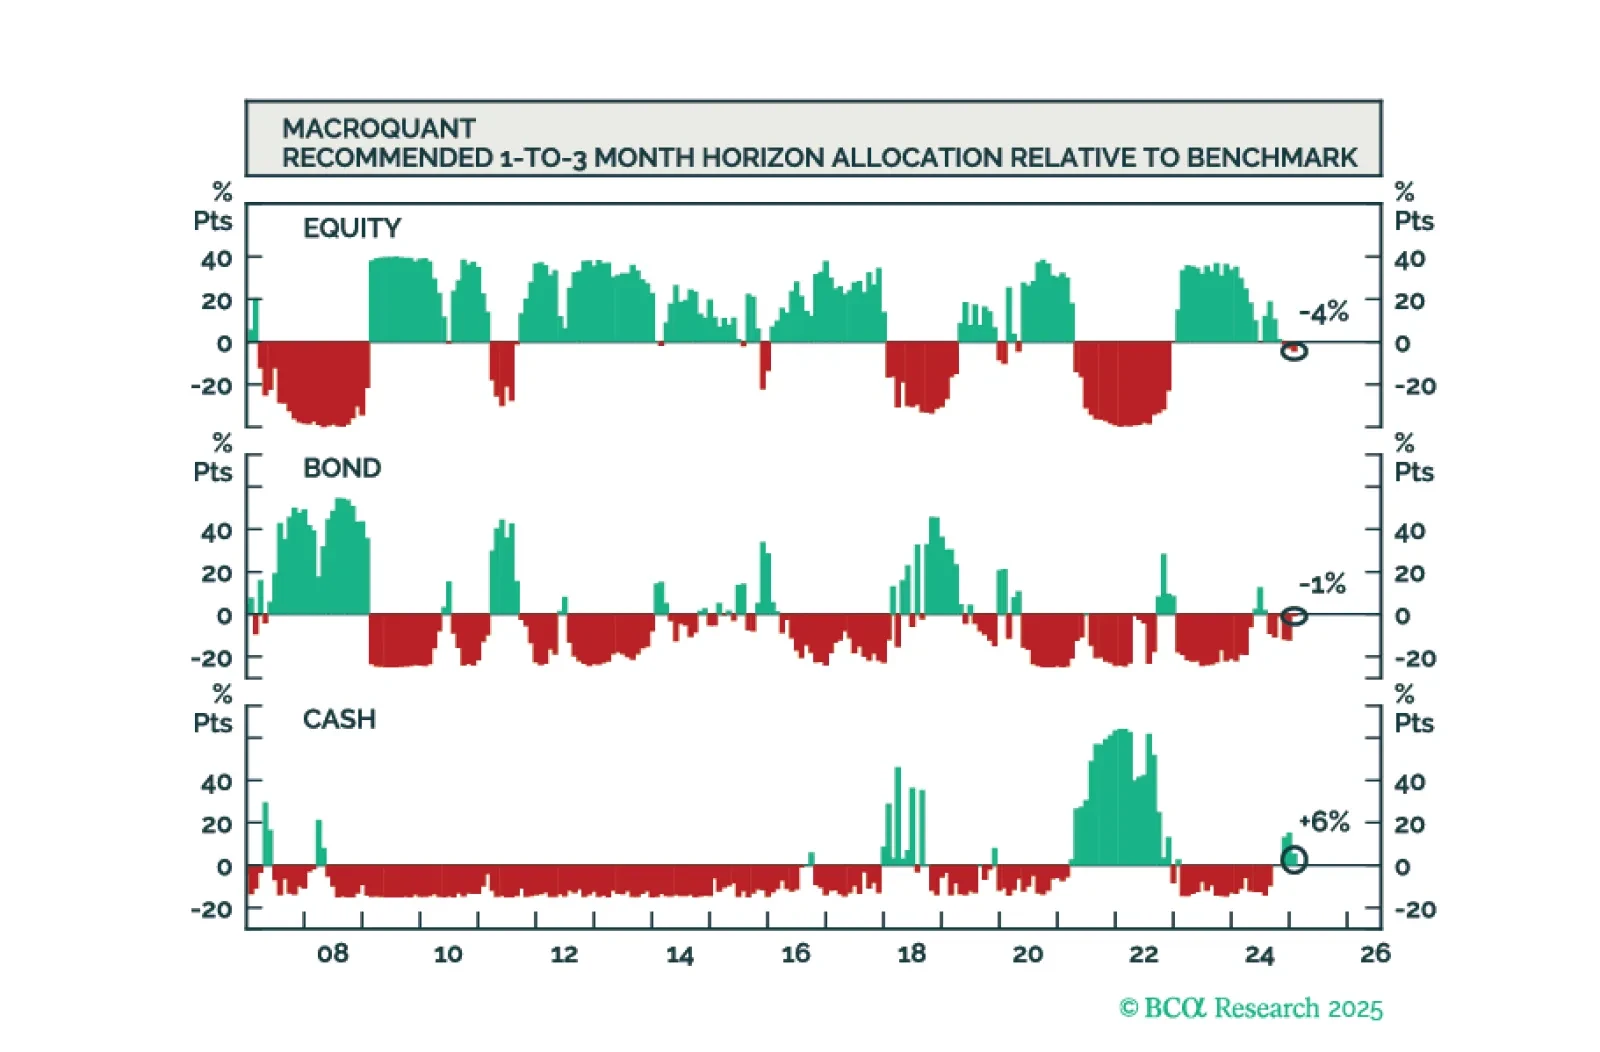
The MacroQuant model is no longer bullish on stocks but is not yet prepared to turn underweight. Subjectively, the Global Investment Strategy team is more bearish on equities than the model.

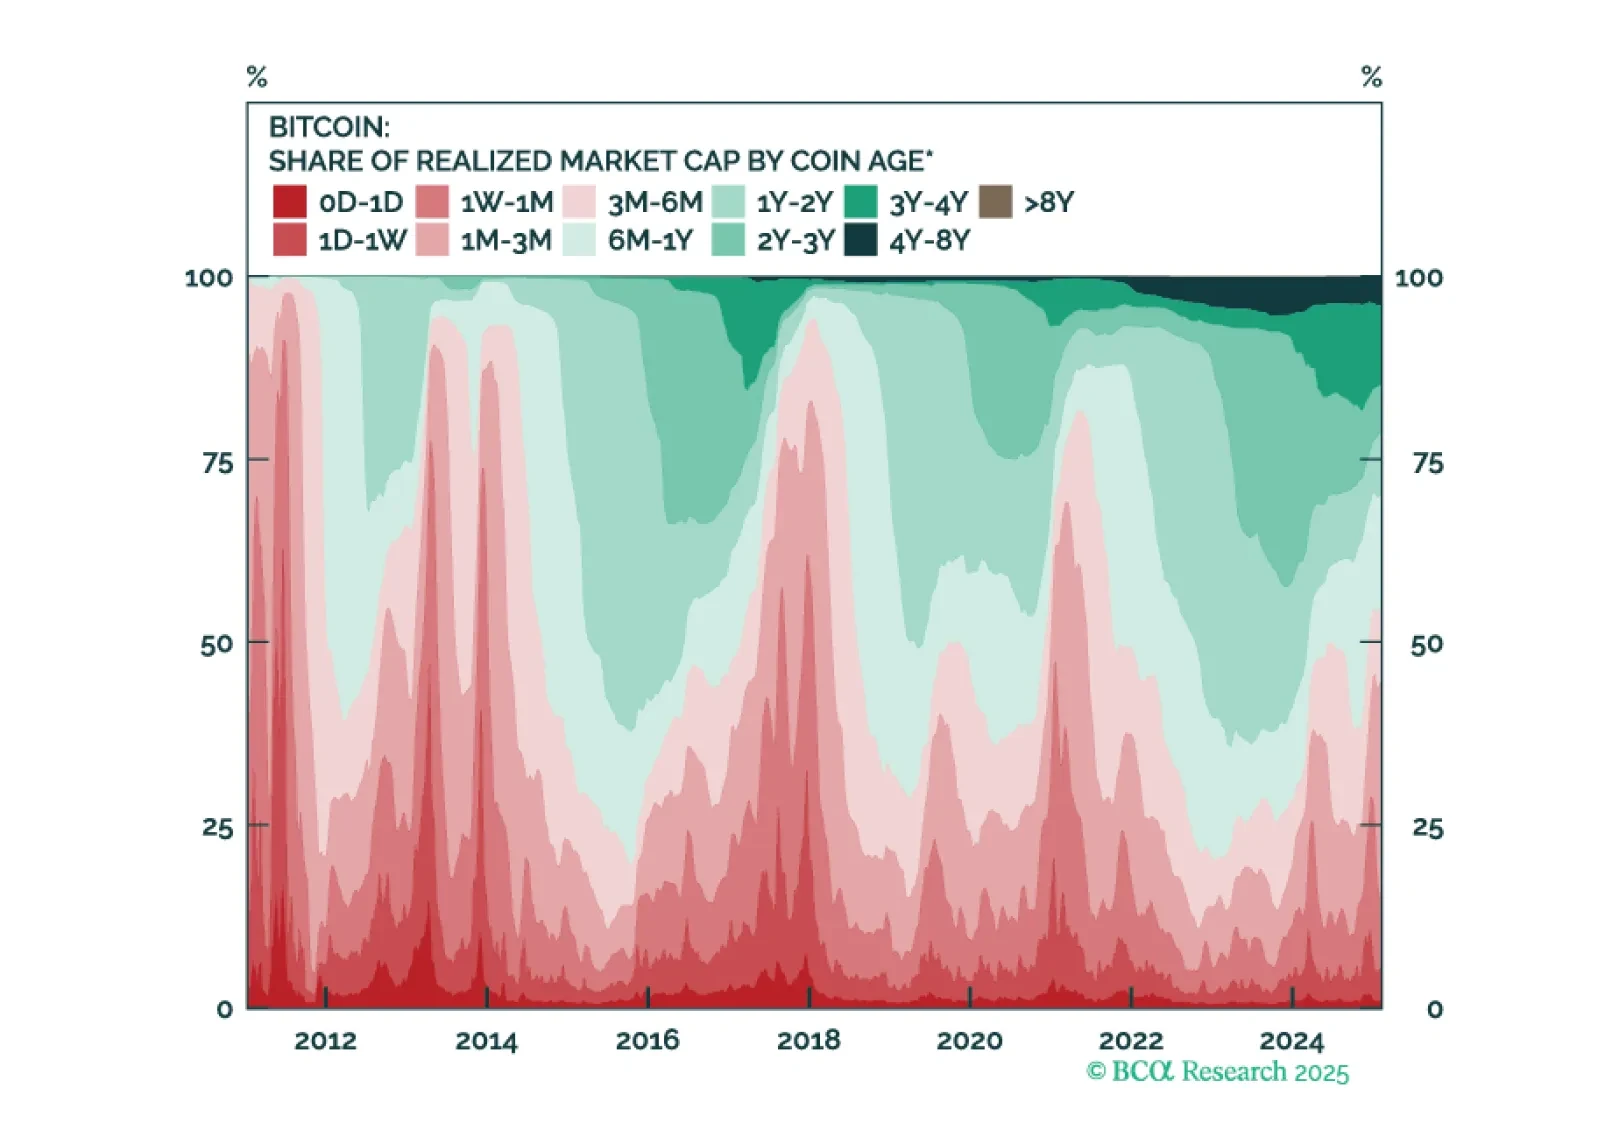
In this report, we reassess our bullish stance on crypto from early 2023, following Bitcoin’s recent all-time highs. While institutional adoption is broadening, there are also signs of excessive exuberance, speculation, and optimism. Given these conditions, a near-term correction appears likely. We are booking profits and will look to re-enter the market at $75,000.