CoreMacro
| Emerging Markets
Research on emerging economies, from in-depth country reports to calls on EM stocks, bonds, and currencies.
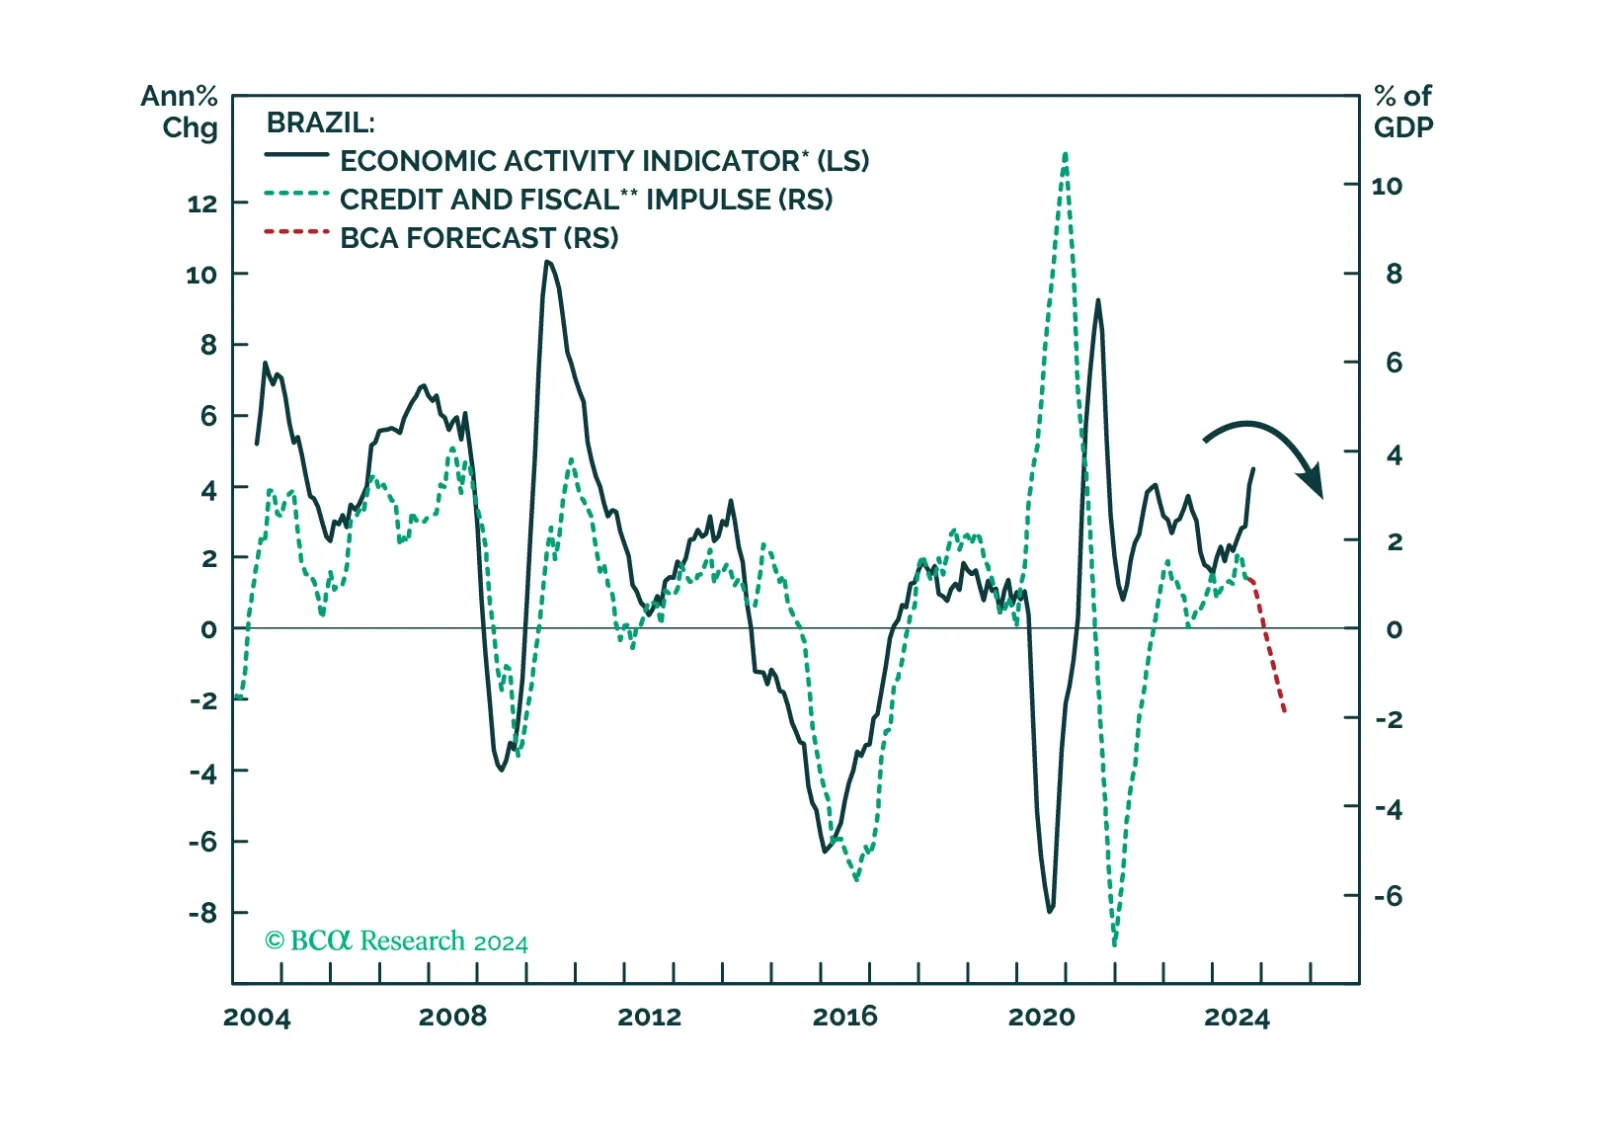
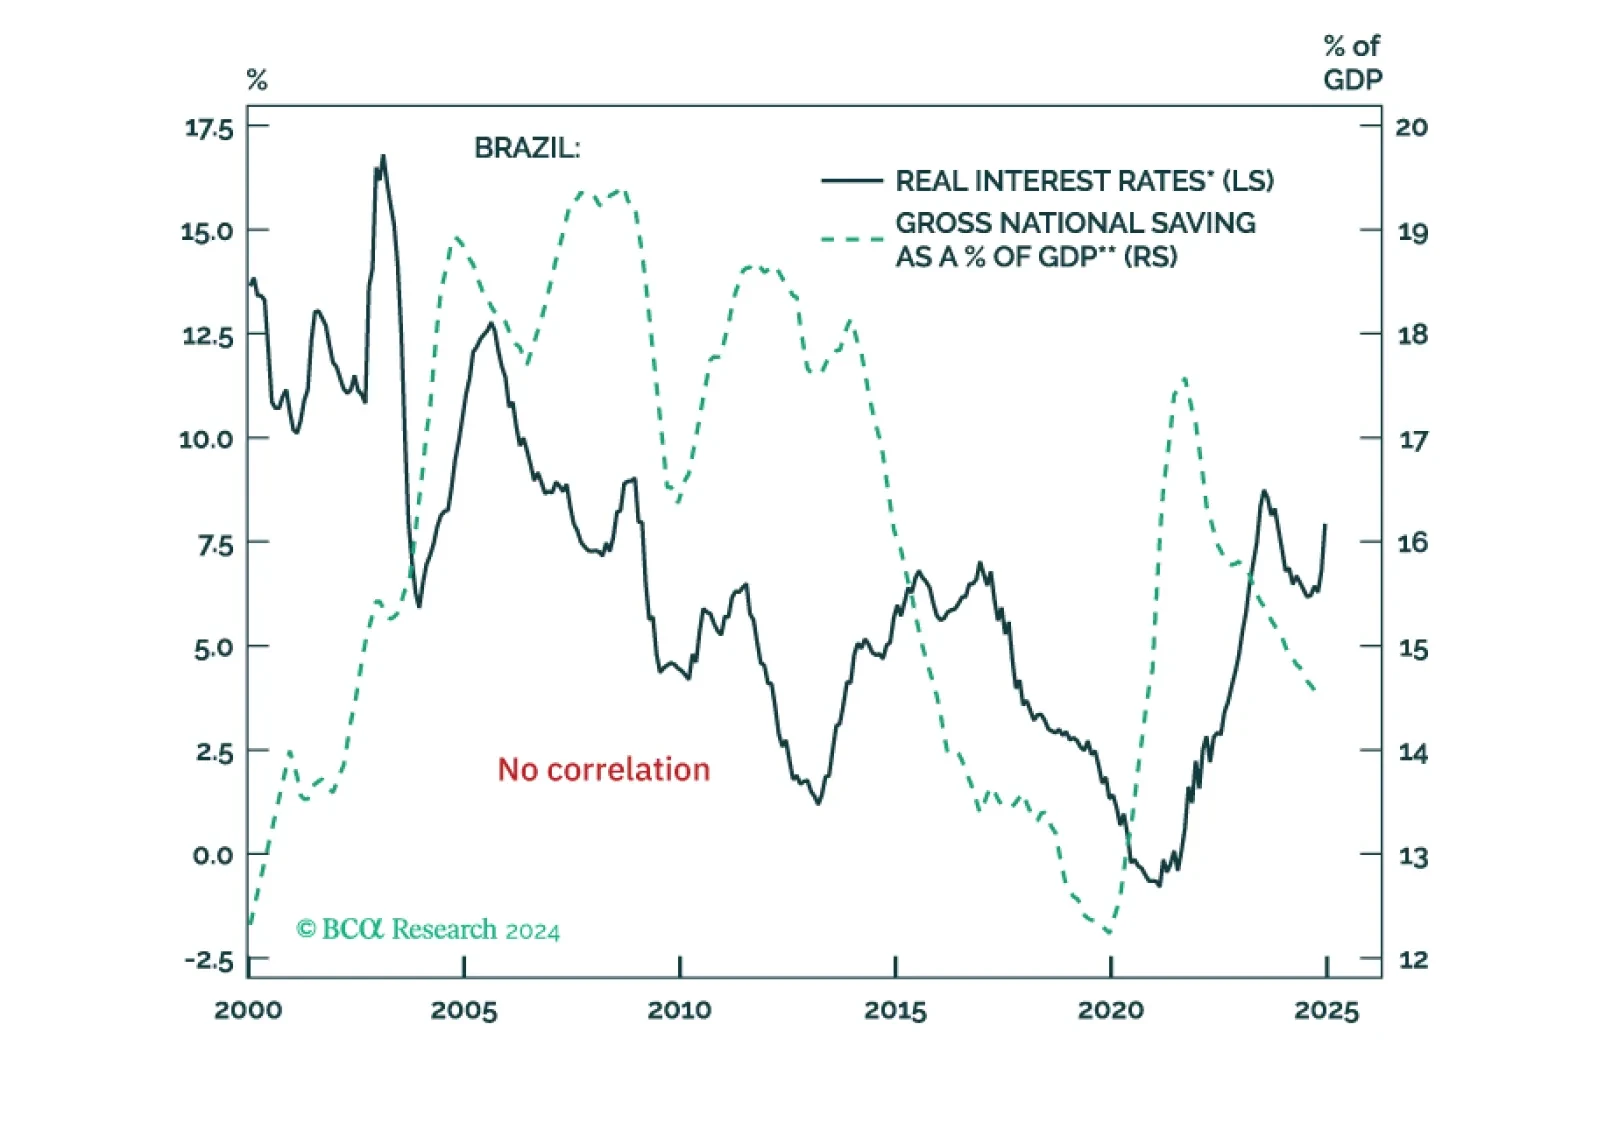
Any additional fiscal tightening and further rate hikes might serve as a band-aid, but not a cure, to Brazilian markets. The country’s risk assets and the currency will continue to face headwinds from an impending recession, a strengthening USD, weak commodity prices, and worsening public debt dynamics. Investors should fade out any relief rallies in Brazilian markets for now.
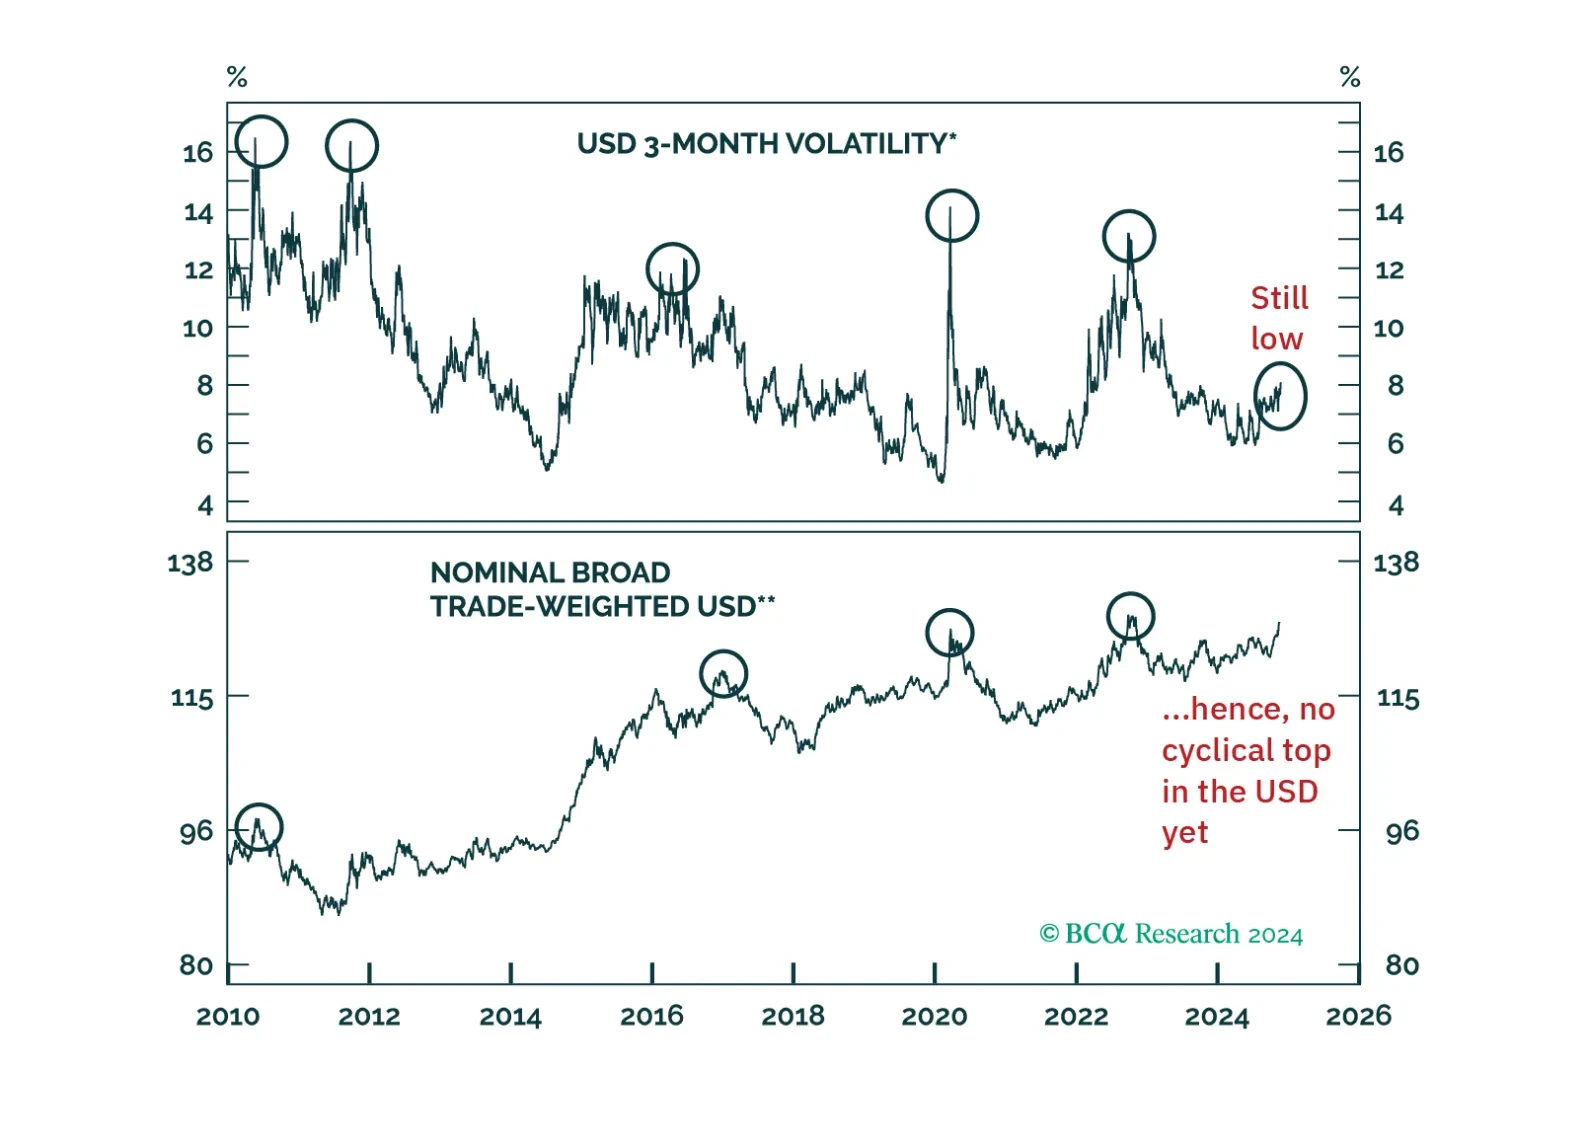
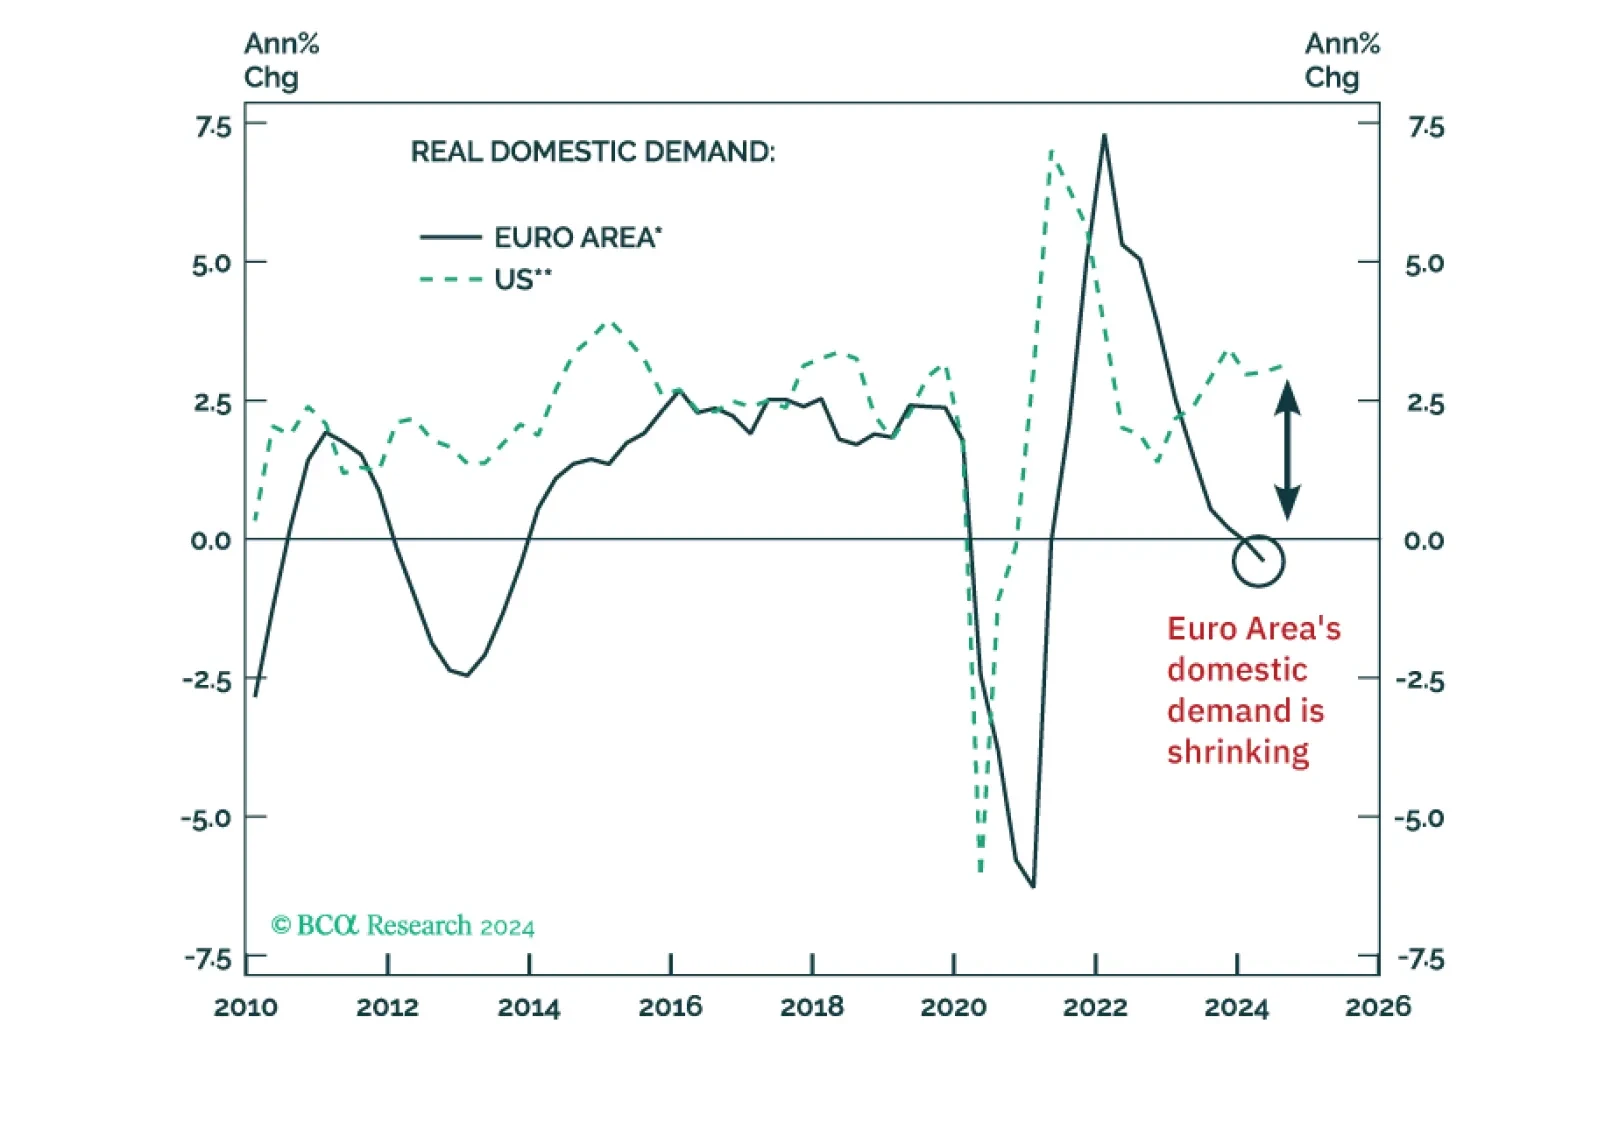
The threat of import tariffs and US growth outperformance versus the rest of the world will continue supporting the US dollar rally over the near term. Nevertheless, the Trump administration’s medium- to long-term goal will be a US dollar devaluation to boost the country’s manufacturing competitiveness. We will recommend upgrading EM stocks and bonds when we downgrade our US dollar view.
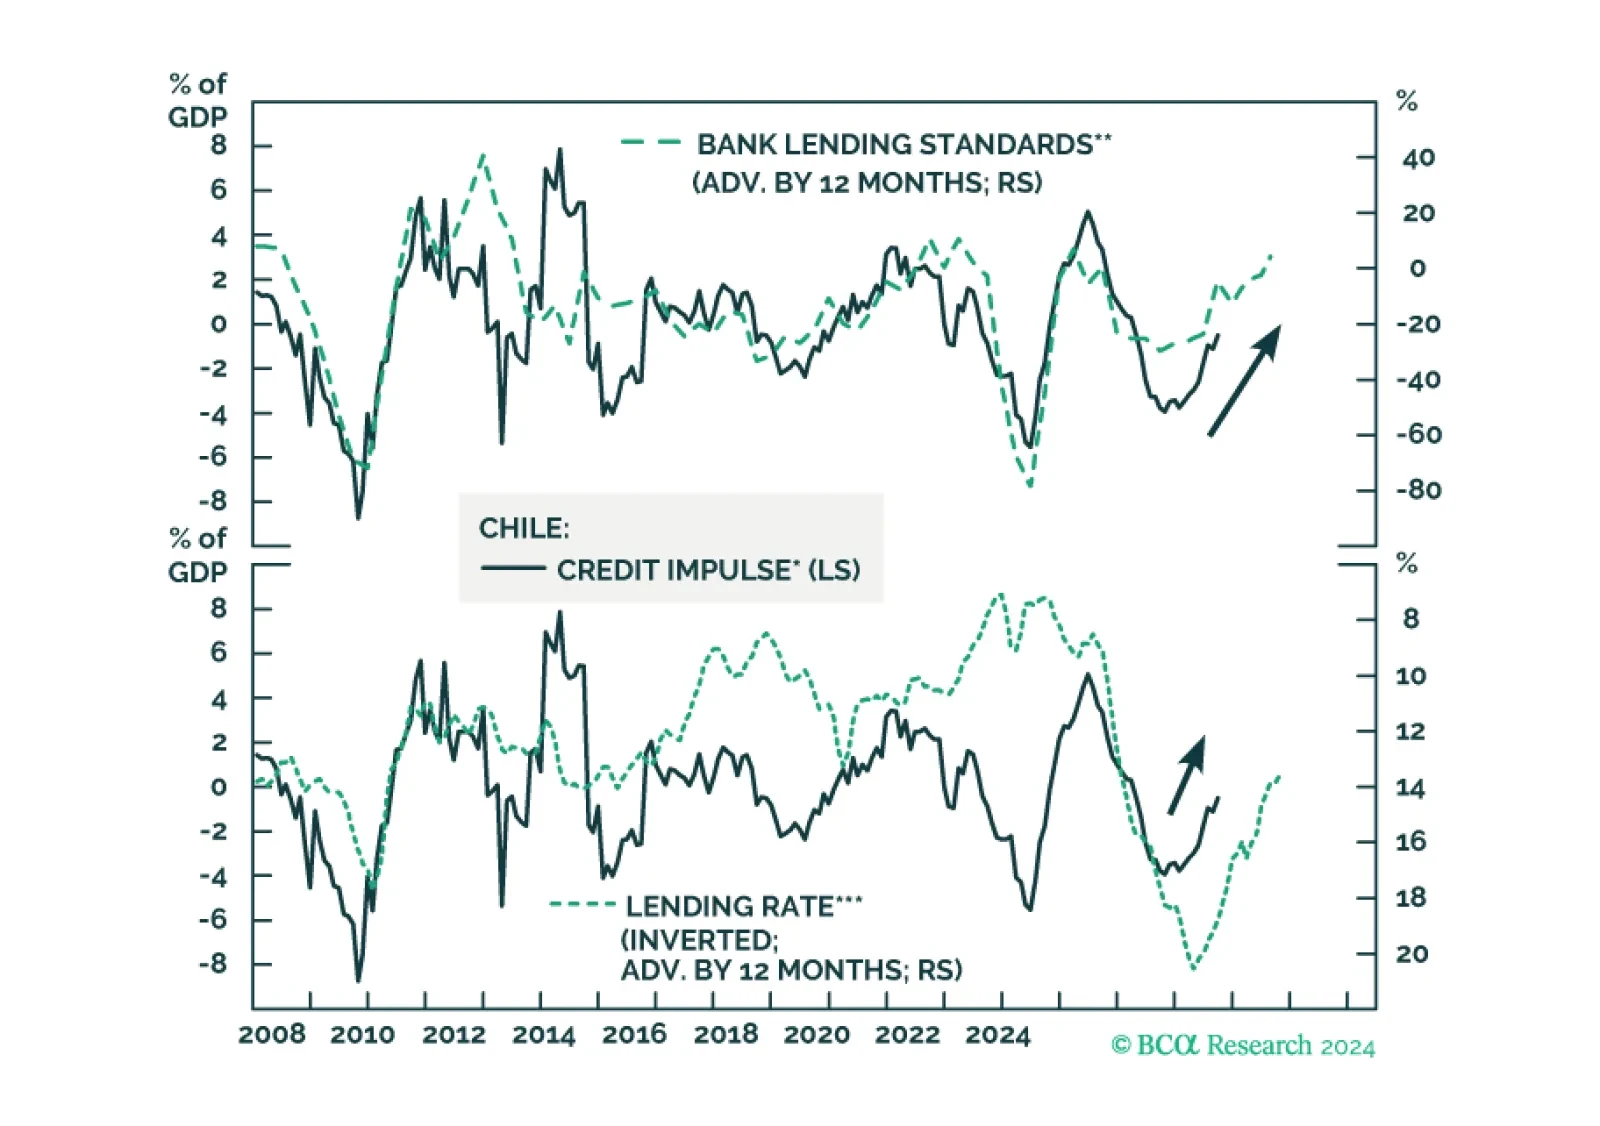
In absolute terms, Chilean markets and the currency will fall given a strengthening trend in the US dollar and weak global trade. However, Chile’s economy can withstand the global trade slump relatively well due to substantial monetary easing at home, which will help Chilean markets outperform EM peers. Moreover, a favorable and improving political backdrop and attractive valuations will benefit Chilean equities and the peso versus their EM counterparts.
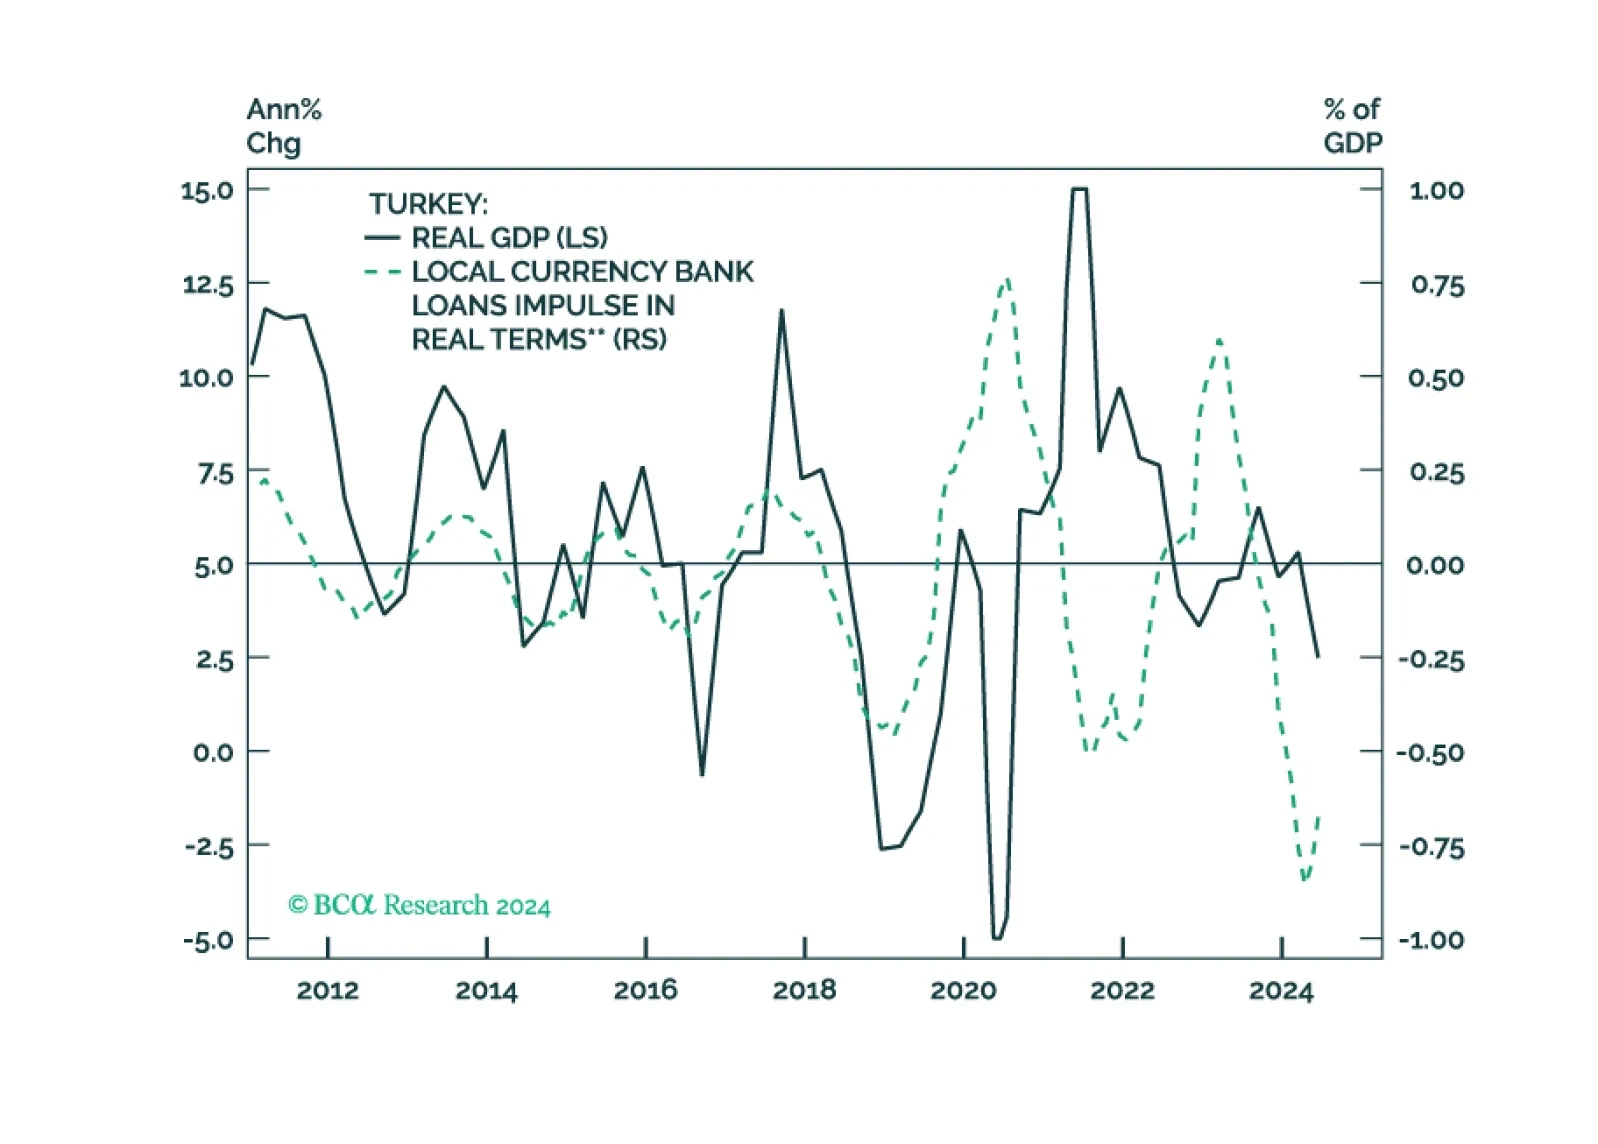
Turkey has a path toward sustained disinflation. But that will require tight macro policies for an extended period. The question is, will the authorities tolerate the consequent growth slowdown, even a recession, and surging unemployment, as the necessary cost to break the back of inflation?