 CoreMacro
| Emerging Markets
Research on emerging economies, from in-depth country reports to calls on EM stocks, bonds, and currencies.
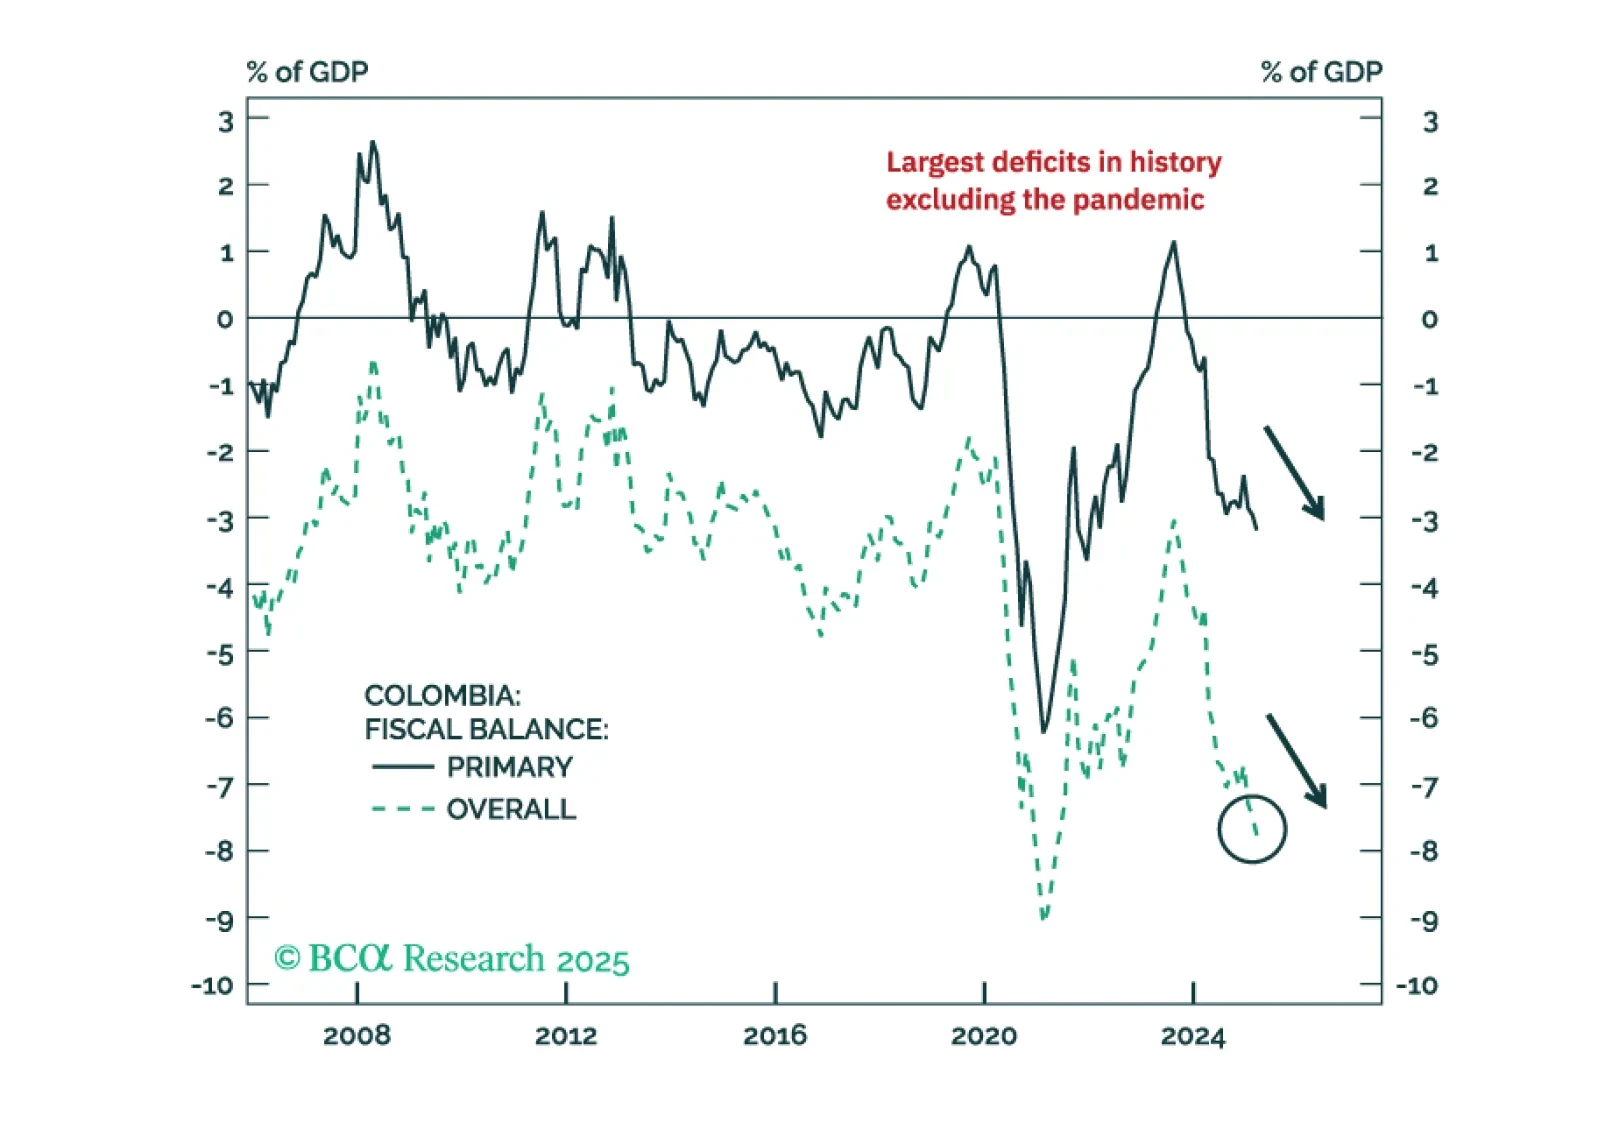
Colombian markets will be torn between expectations of future orthodox policies and the reality of a worsening macro backdrop in the next 12 months. To balance risks, we are upgrading Colombian equities, local bonds, and sovereign credit from underweight to neutral versus their respective EM benchmarks.
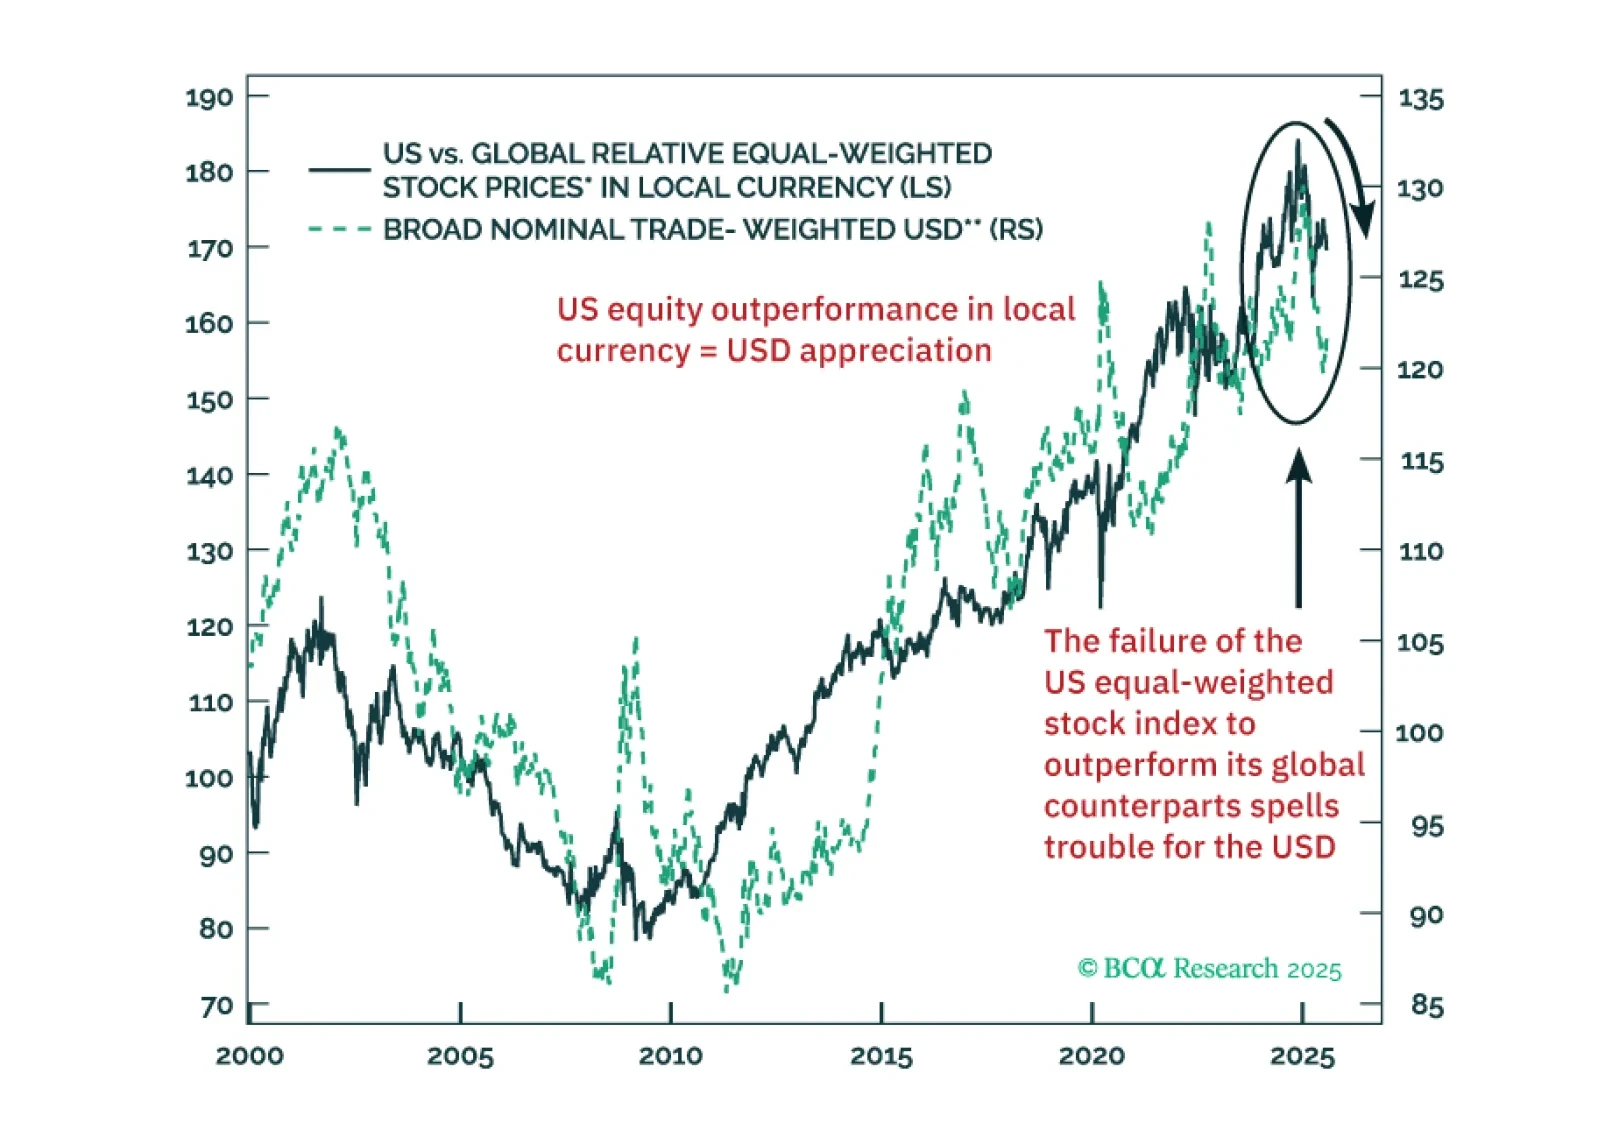
US TMT stocks have been delivering miraculous profit performance. Yet, outside US large tech, global equity fundamentals and technicals are troublesome. A near-term USD rebound should be faded.
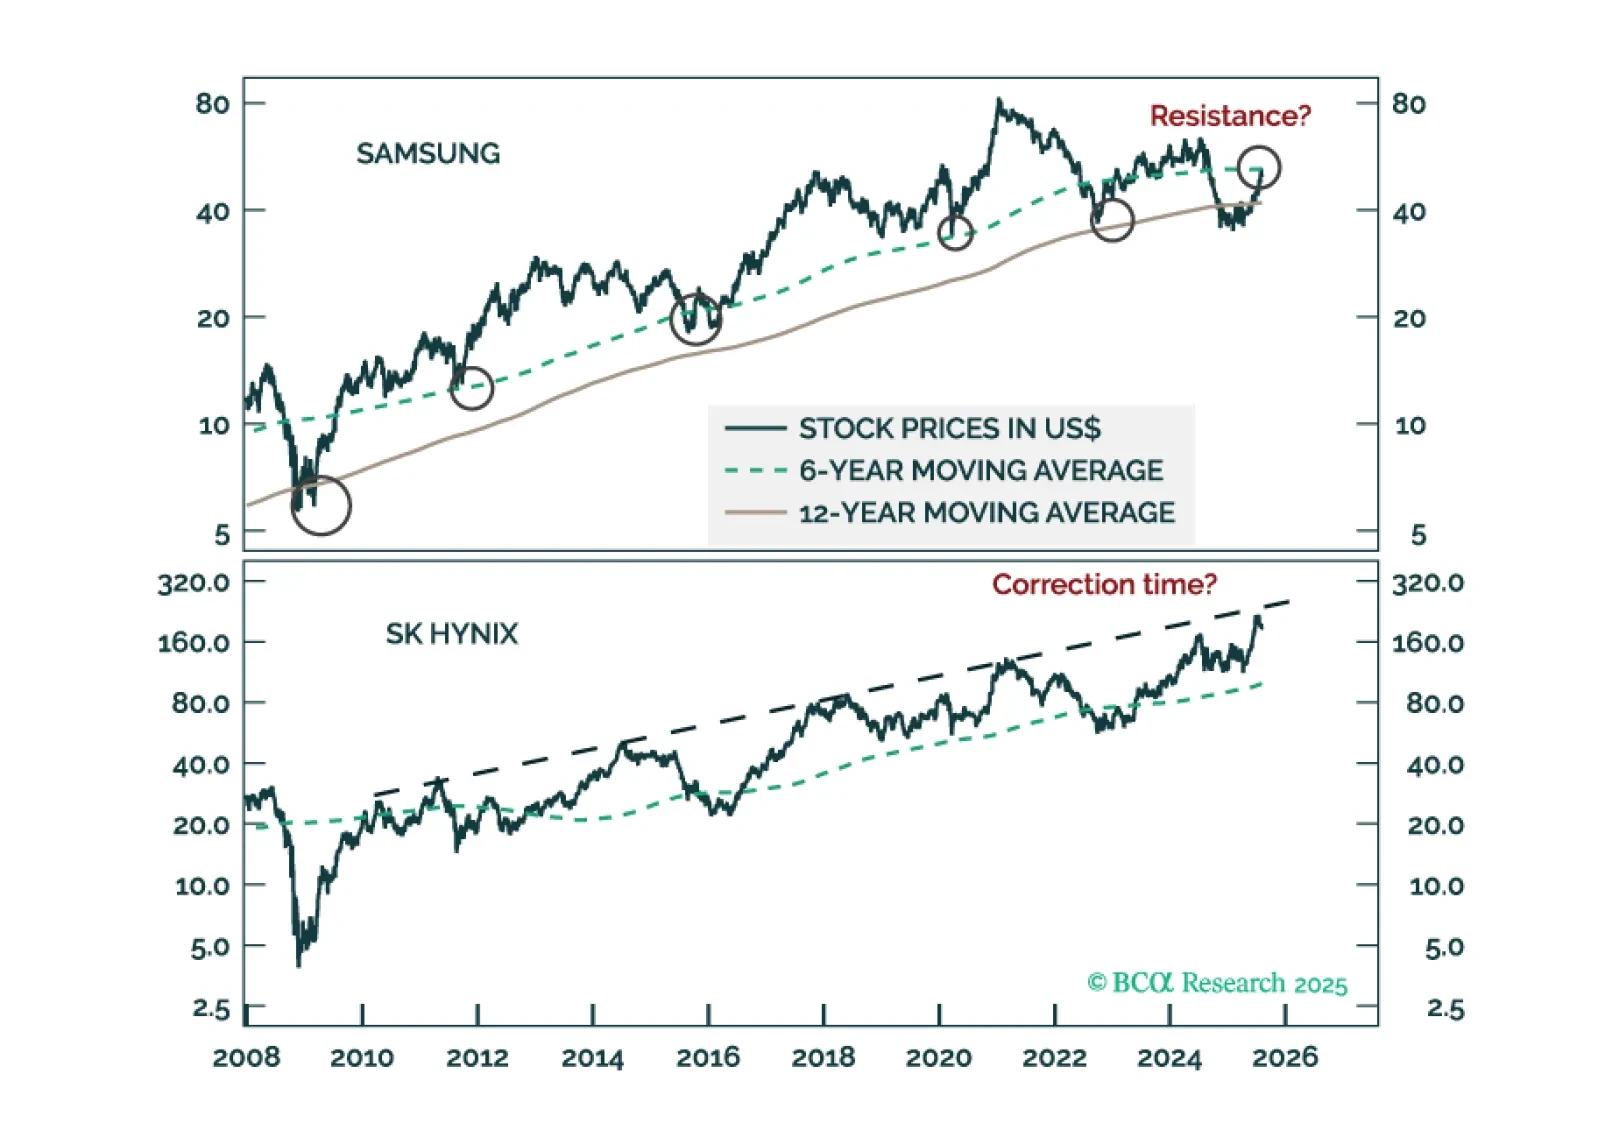
A deflationary shock from shrinking exports will ripple throughout the Korean economy. We are downgrading the KOSPI from overweight to neutral and reiterating a long position in 10-year domestic bonds, currency unhedged.
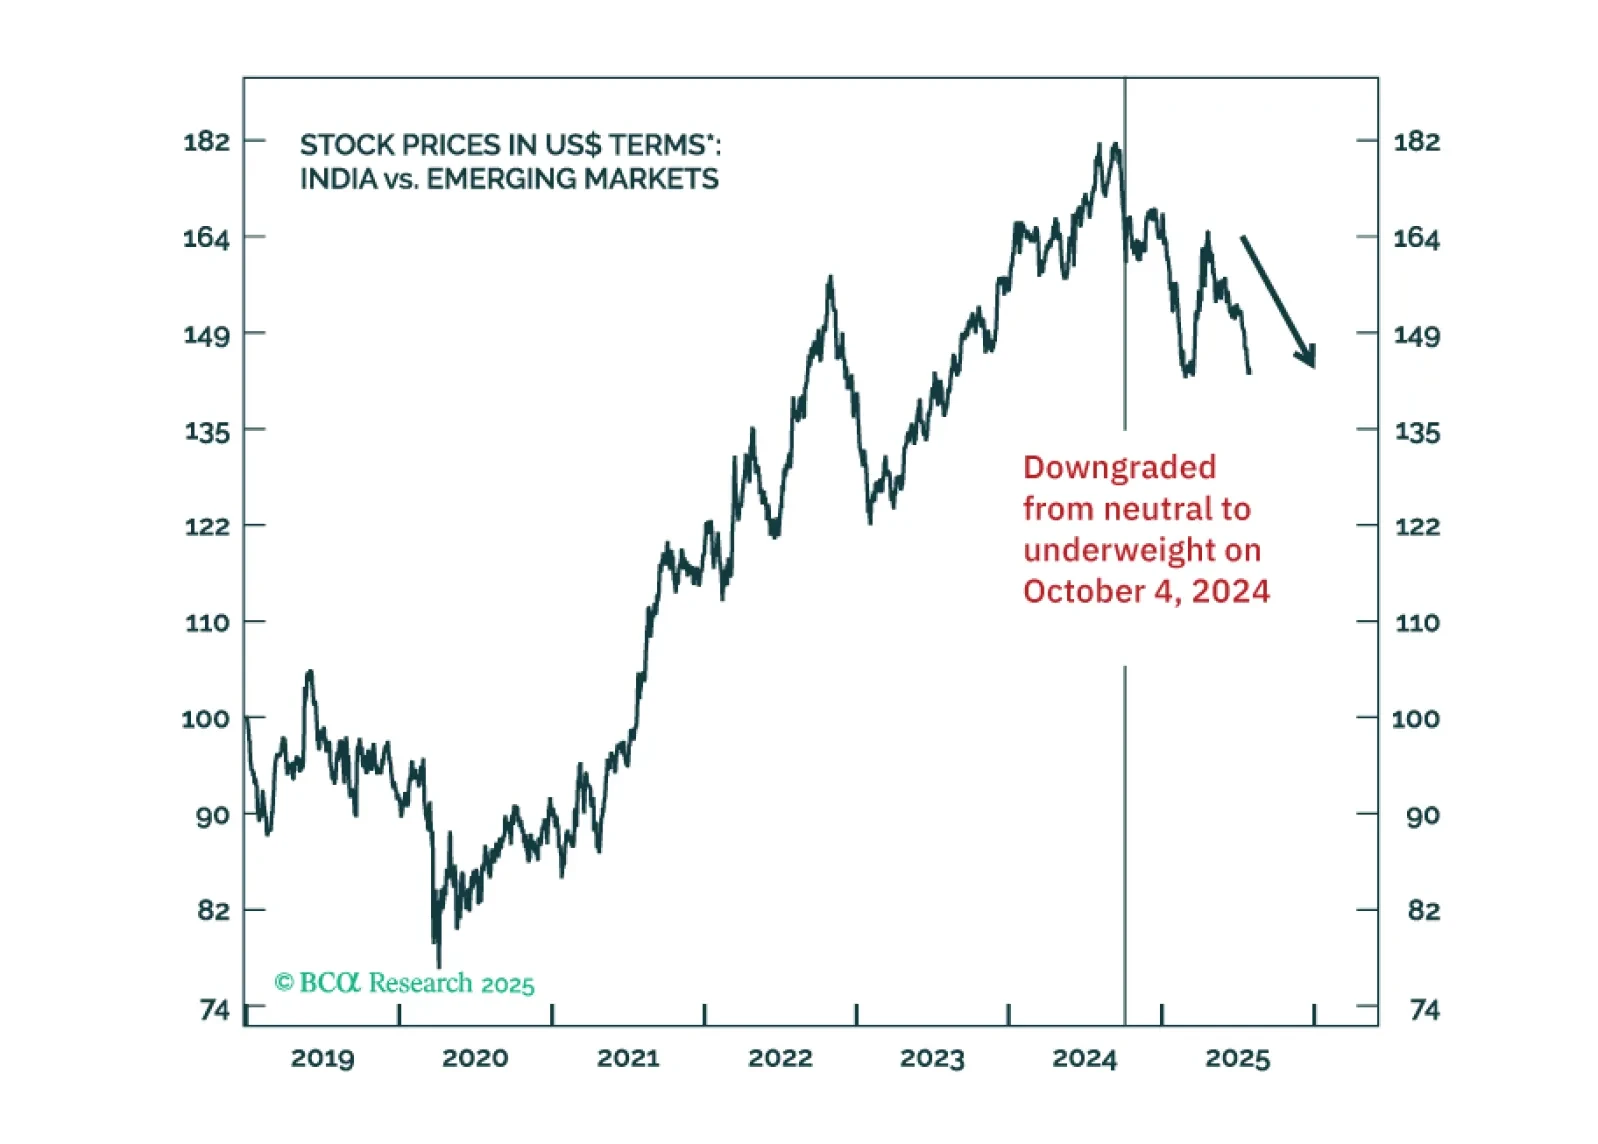
A high US tariff and the lingering uncertainties on the US-India trade deal will hurt investors sentiment. This and contracting corporate profits will push share prices lower. Stay underweight Indian stocks.
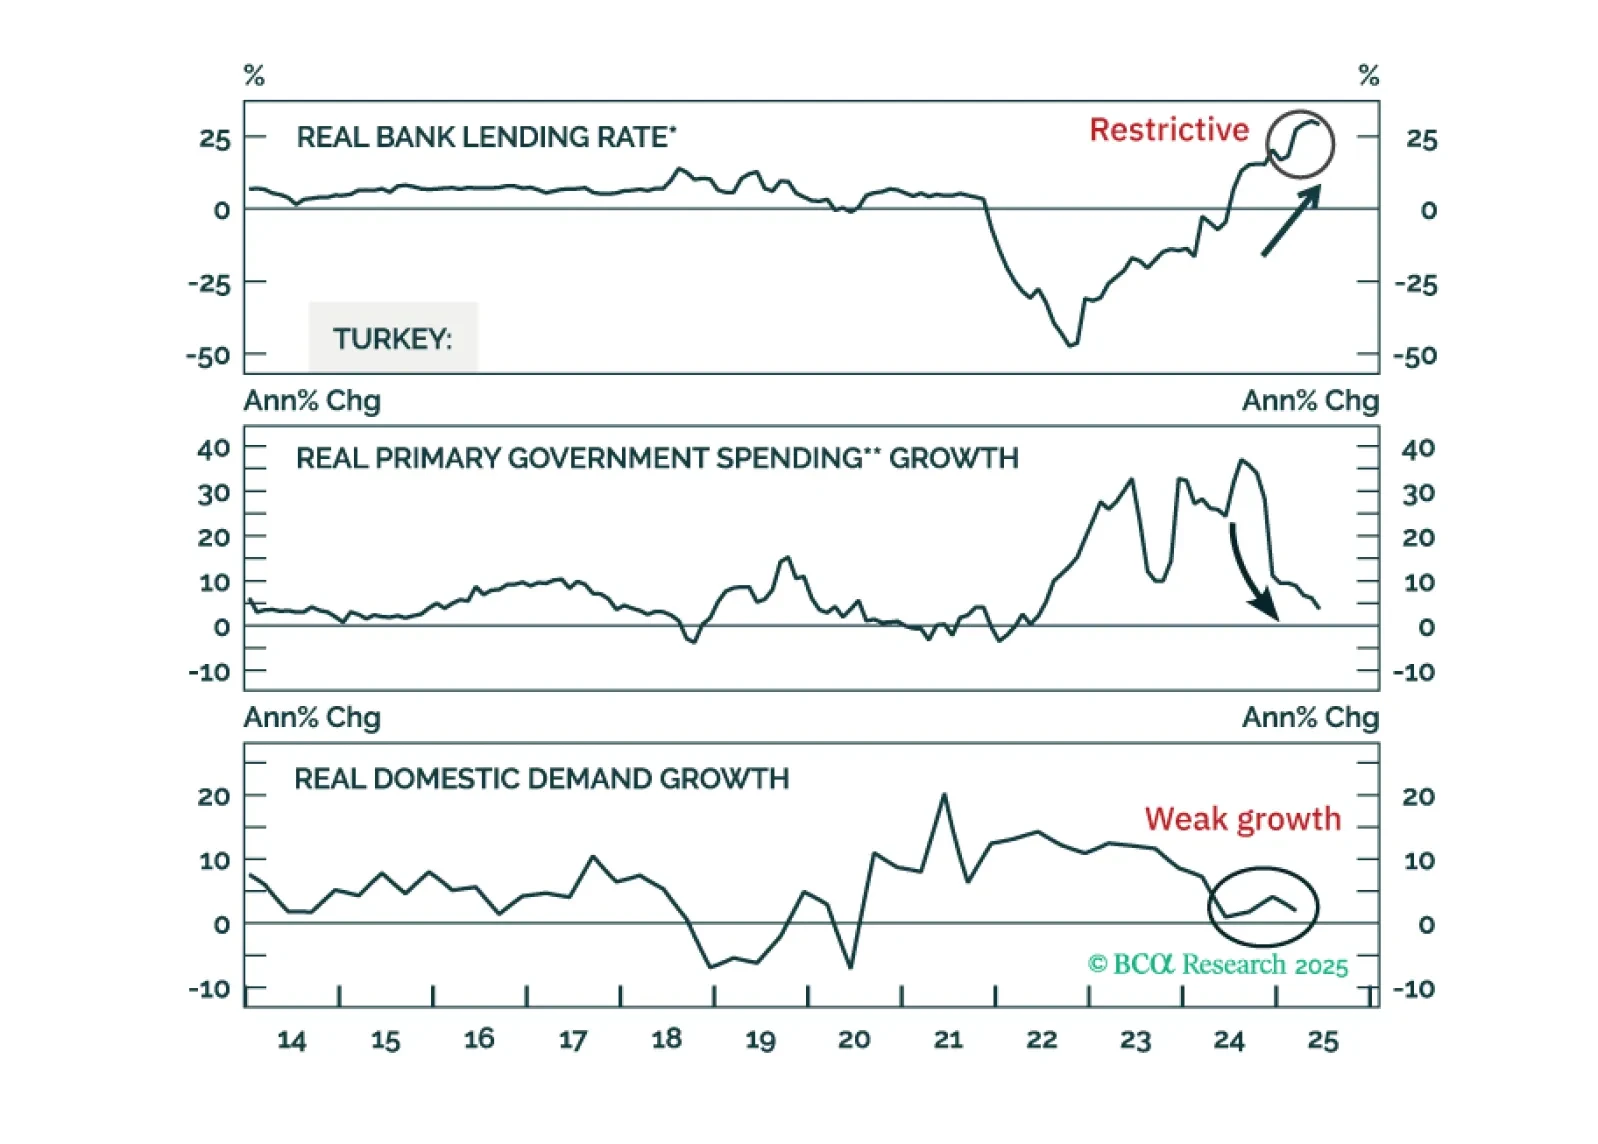
Thanks to the tight monetary and fiscal policies so far, inflation and growth are heading lower in Turkey. Buy 2-year local currency bonds, currency unhedged. Also, upgrade Turkey's domestic bonds from neutral to overweight and stocks from underweight to neutral within their respective EM portfolios.
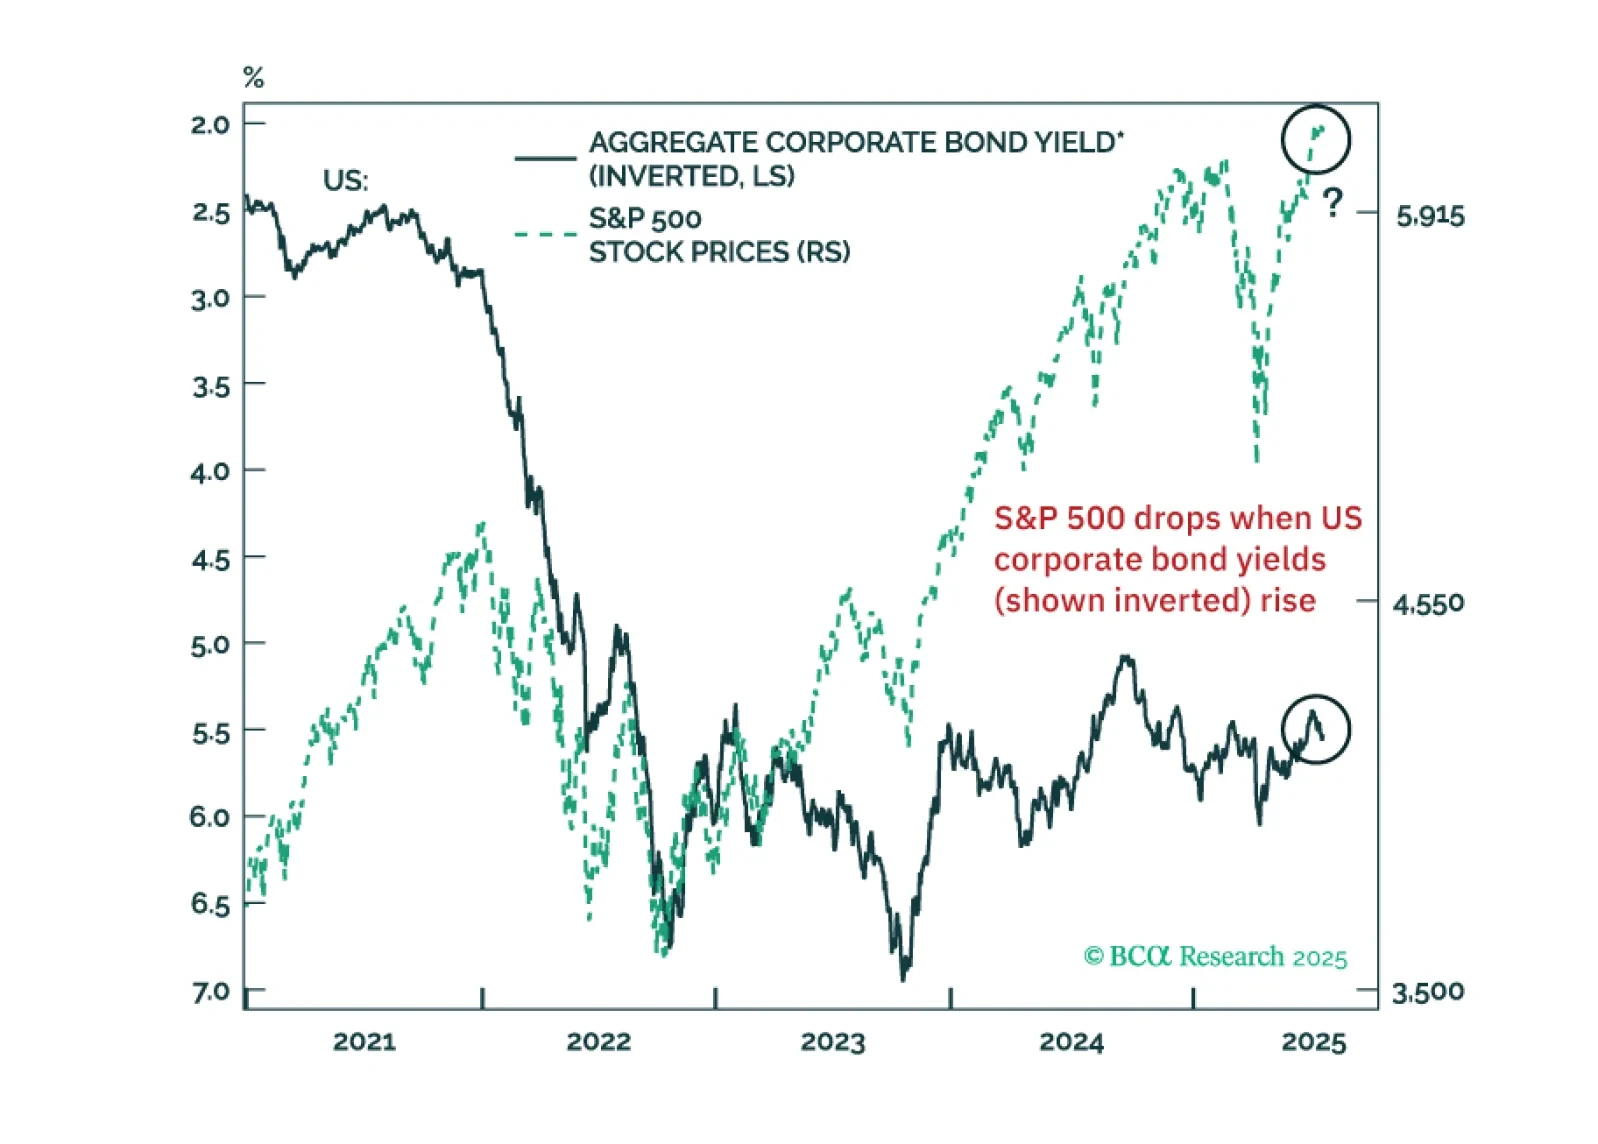
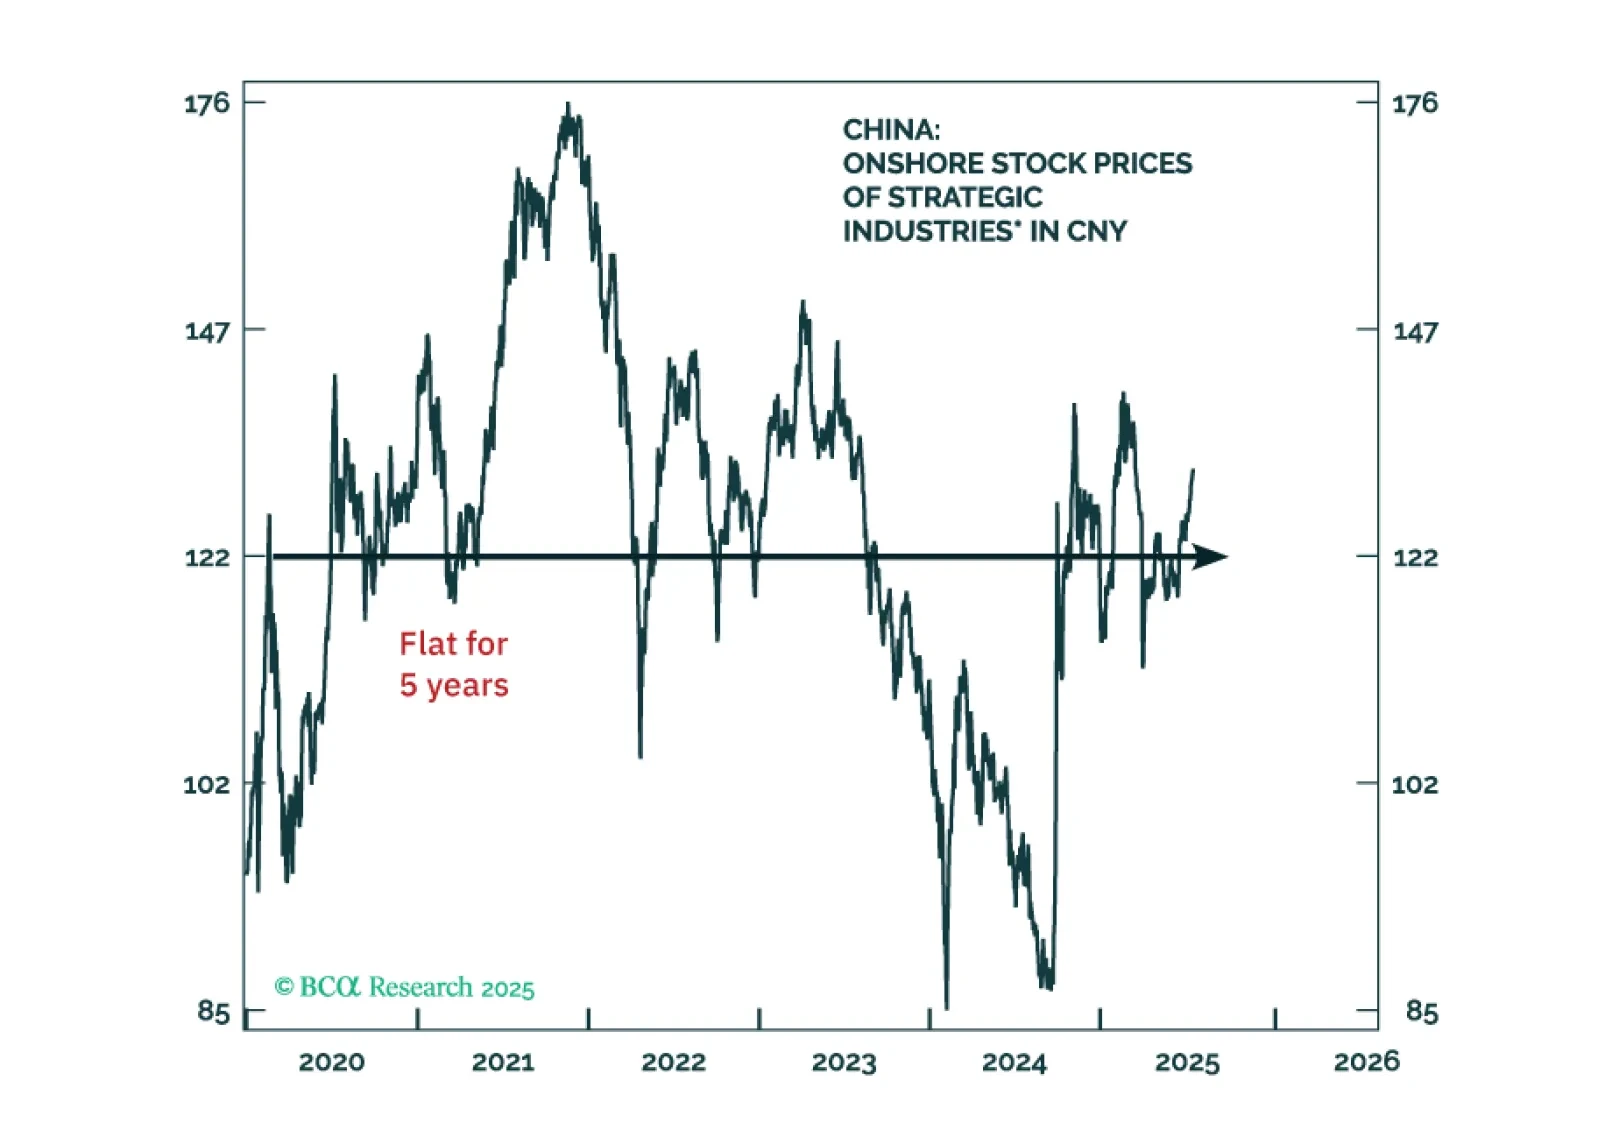
US equity investors should heed warning signals from US corporate bond yields. There are early red flags for EM share prices. Global trade will shrink in H2 2025. China’s economic tailwinds from H1 2025 – fiscal and export frontloading – are coming to an end.
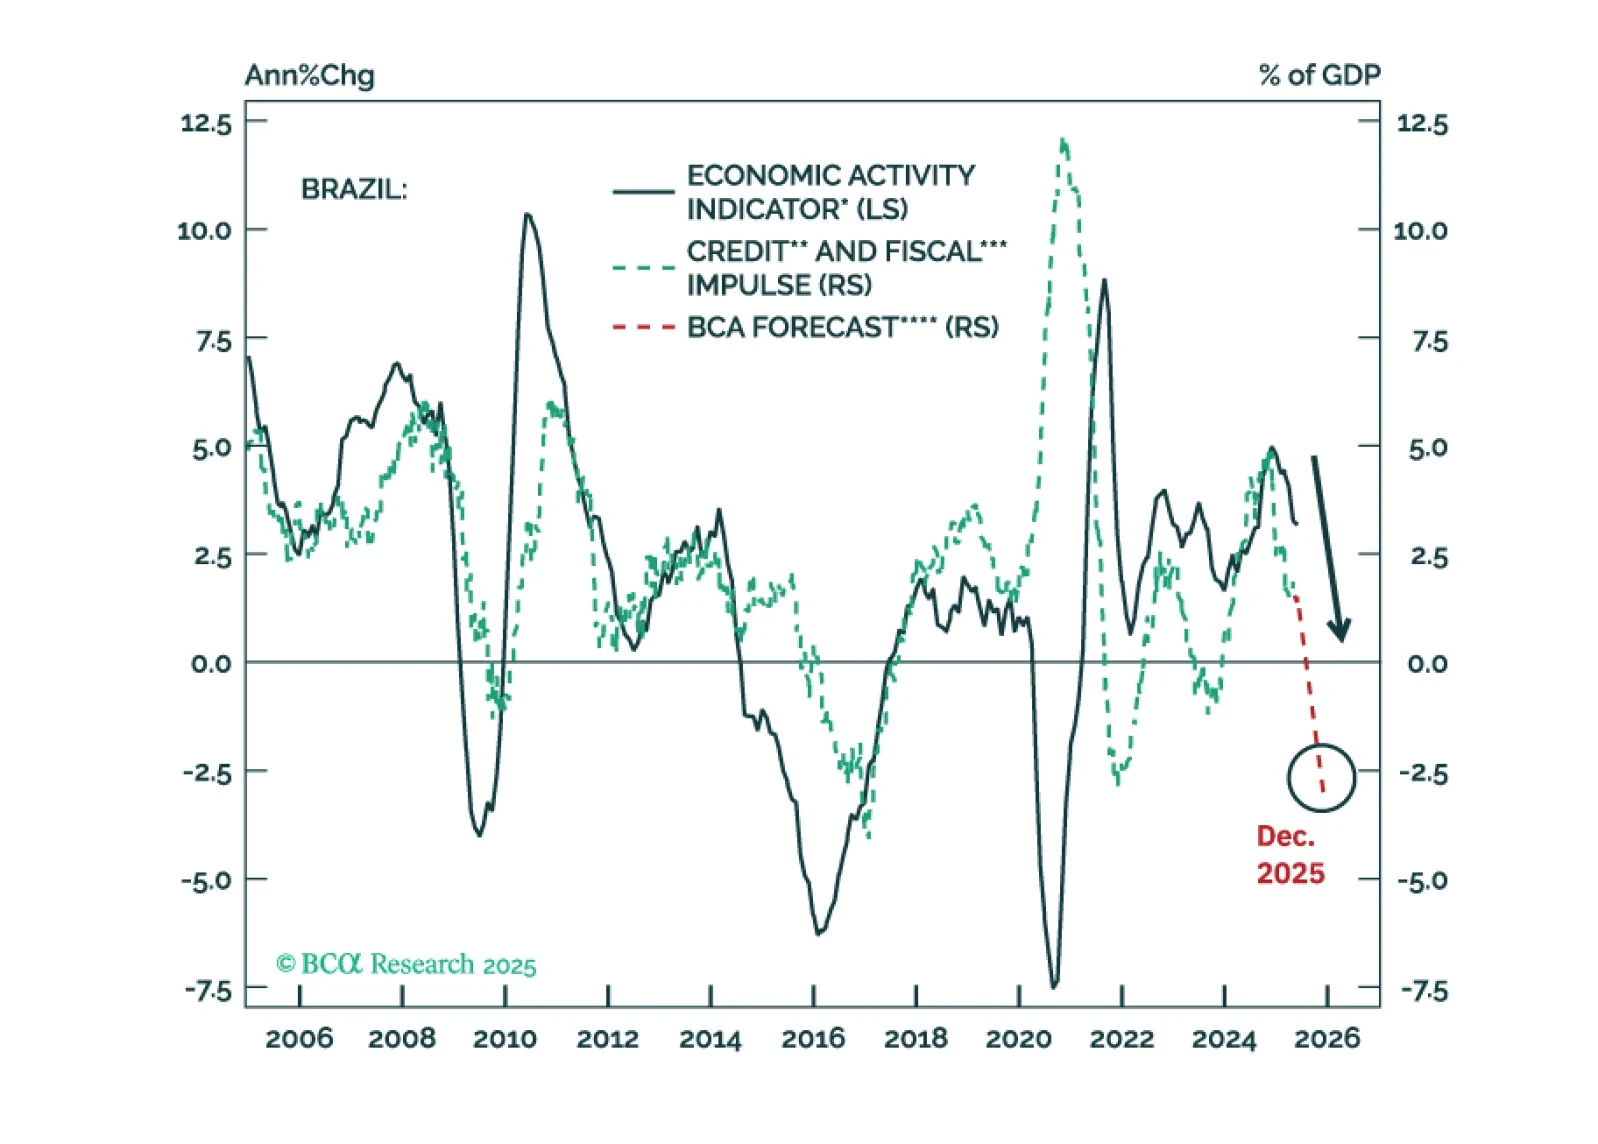
A potential right-wing government in 2027 will not stabilize the trajectory of the public debt-to-GDP ratio. Unsustainable public debt, a large current account deficit, and a sharp growth slowdown will lead Brazilian markets to underperform EM. Yet, to benefit from a quickly decelerating economy, we recommend receiving 2-year swap rates.
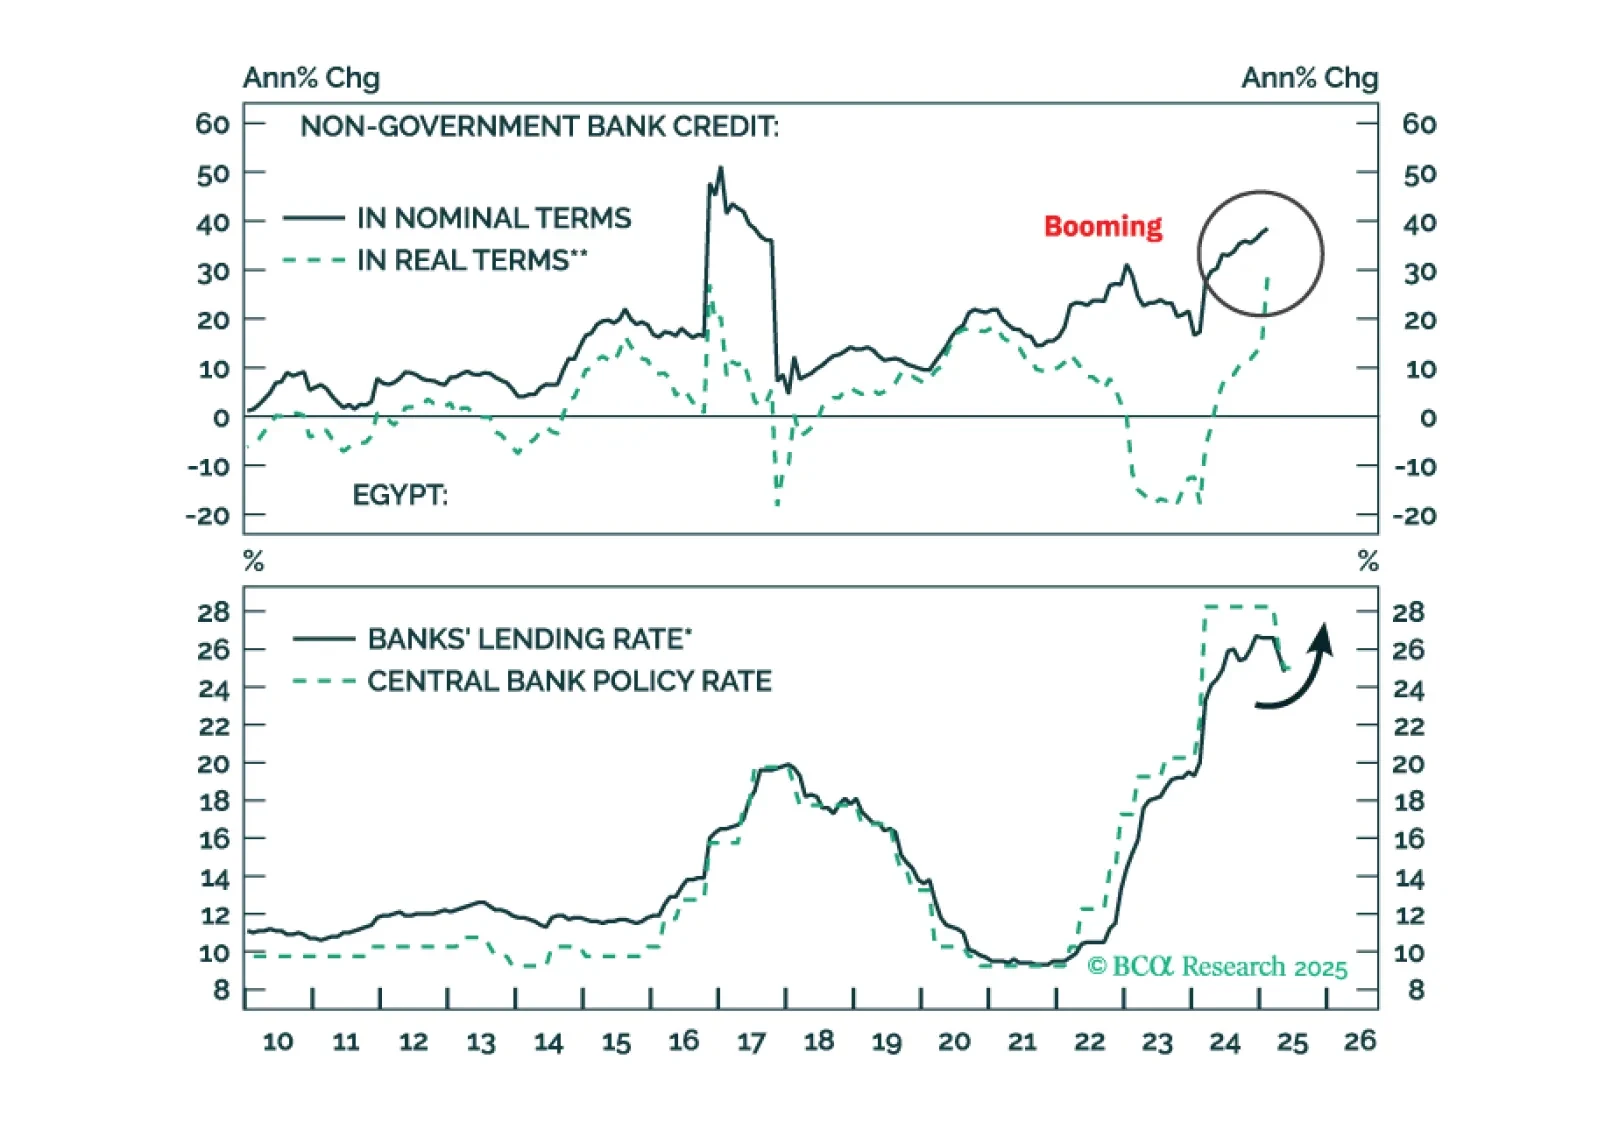
Downward pressure on the pound will rise in the coming months. Inflation will go up, so will bond yields. It’s time to book profits on Egyptian domestic bonds.