CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
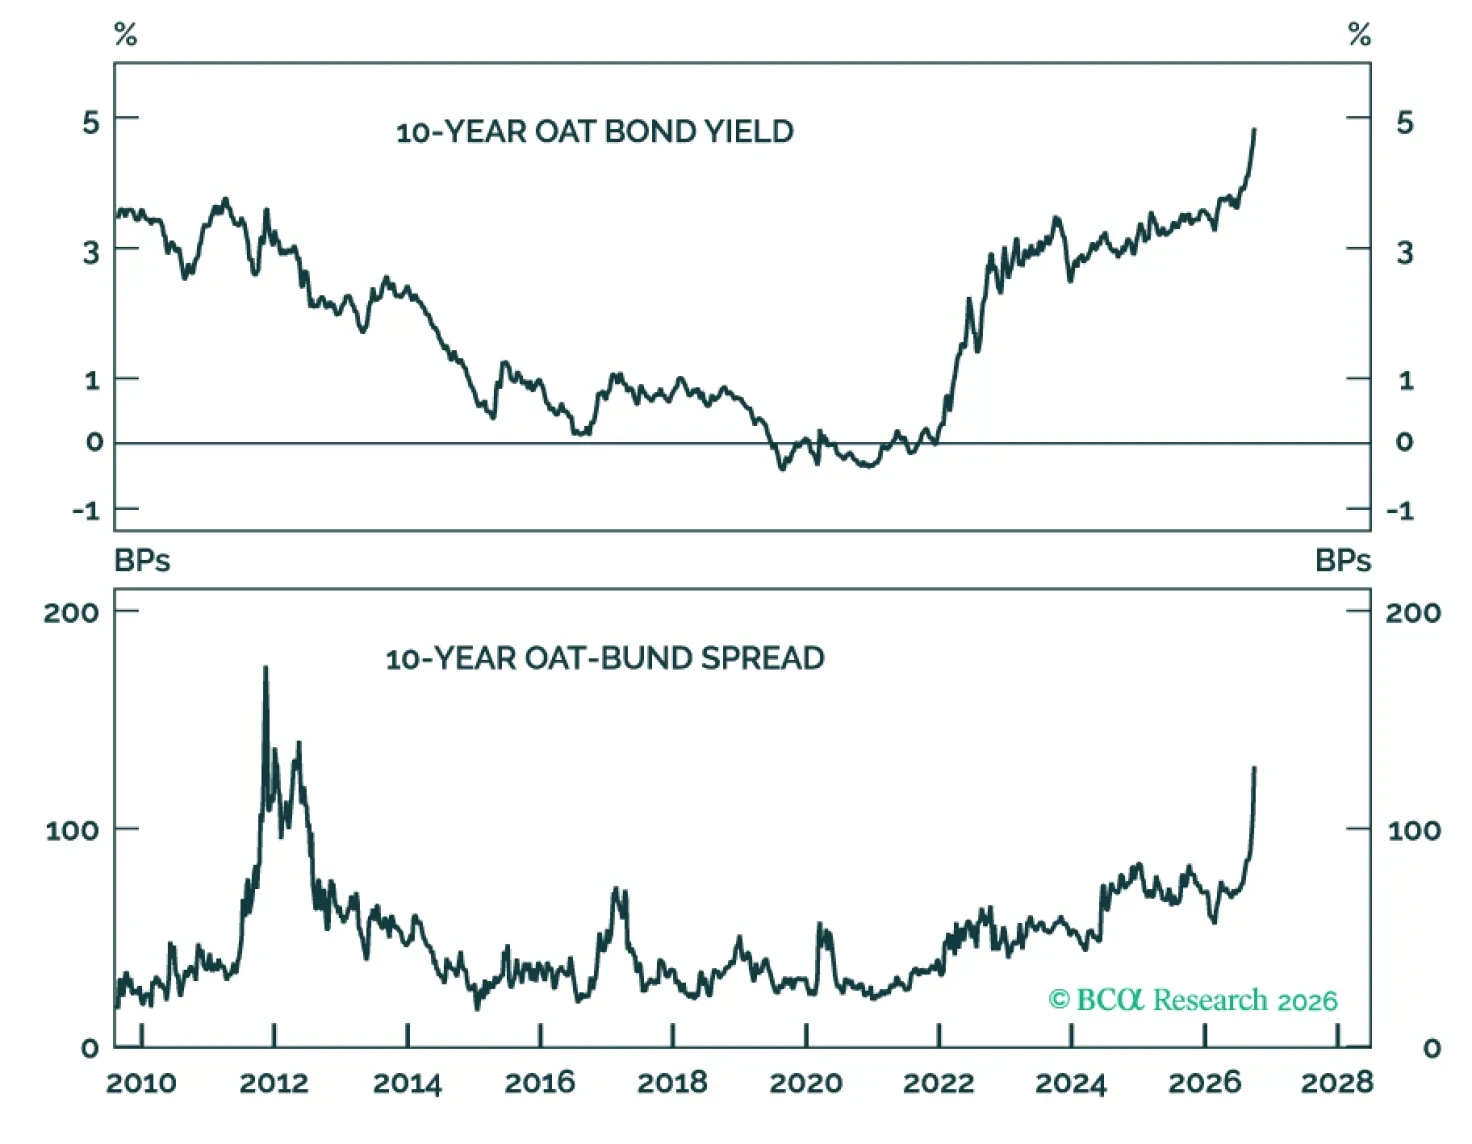
Forced selling may be approaching a pause, but France’s fiscal and political adjustment has barely begun. Maintain an underweight in OATs and use relief rallies to reduce exposure. Contained contagion is reassuring for Europe; it is not a buy signal for France.
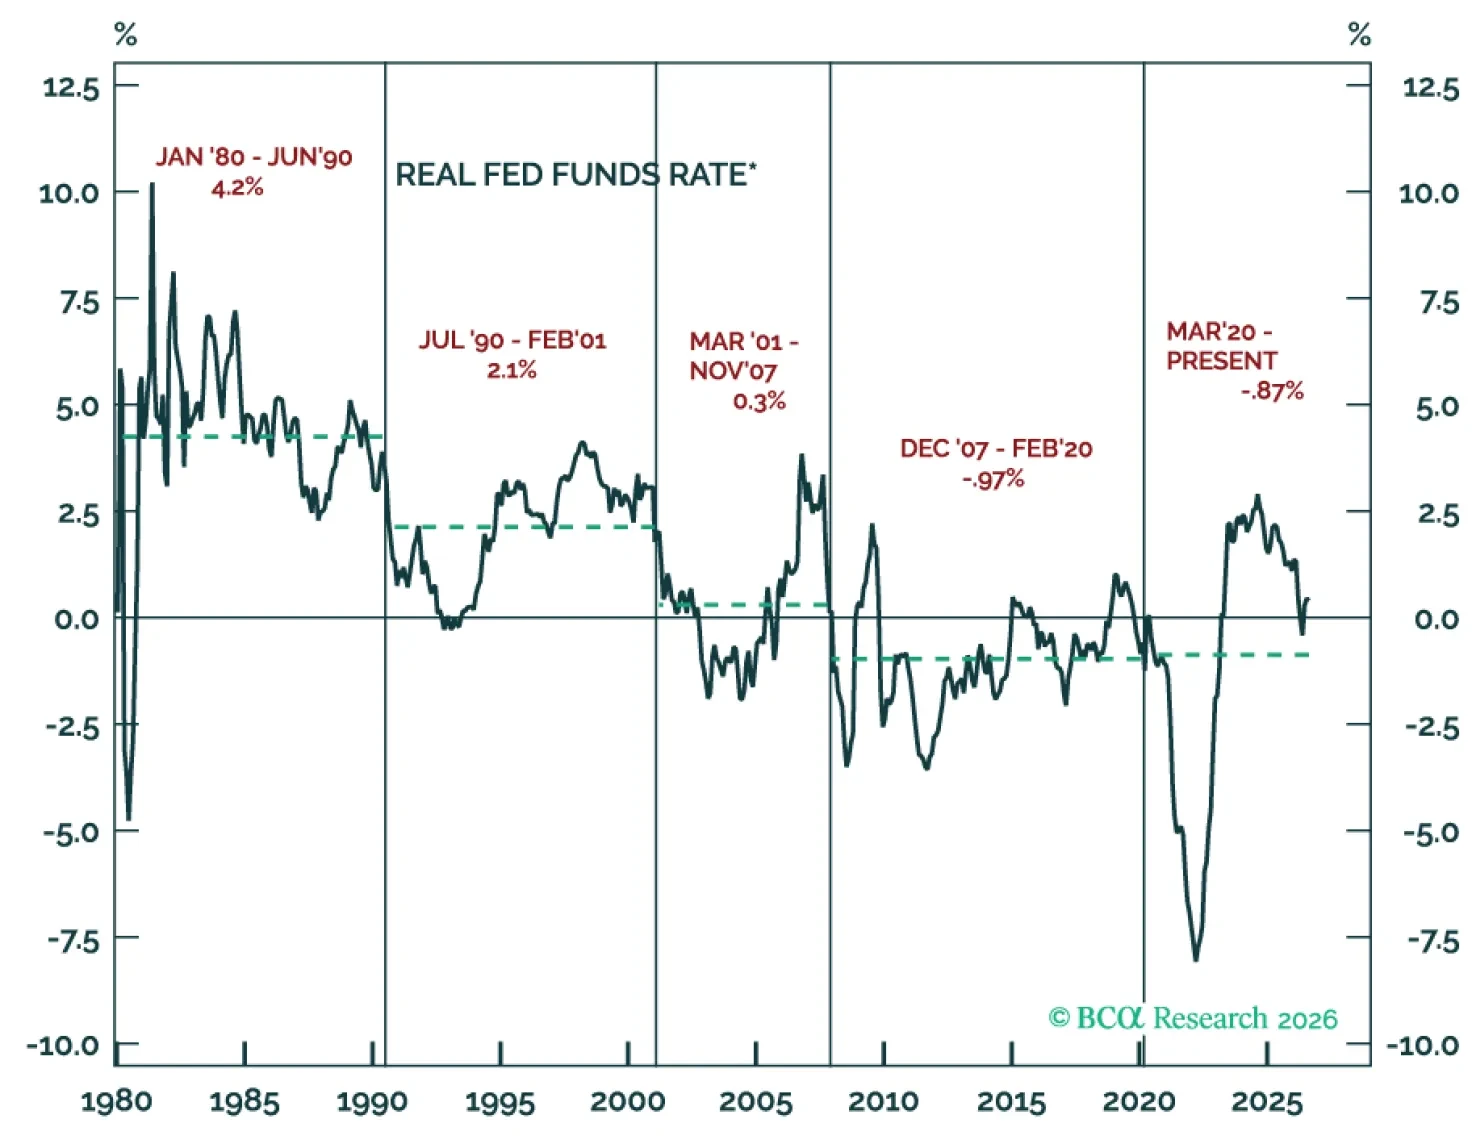
Rising rates don’t halt bull markets but real yields exceeding the economy’s potential long-run growth rate could. That relative level could lead to a stock-bond collision if it persisted long enough to slow the economy.
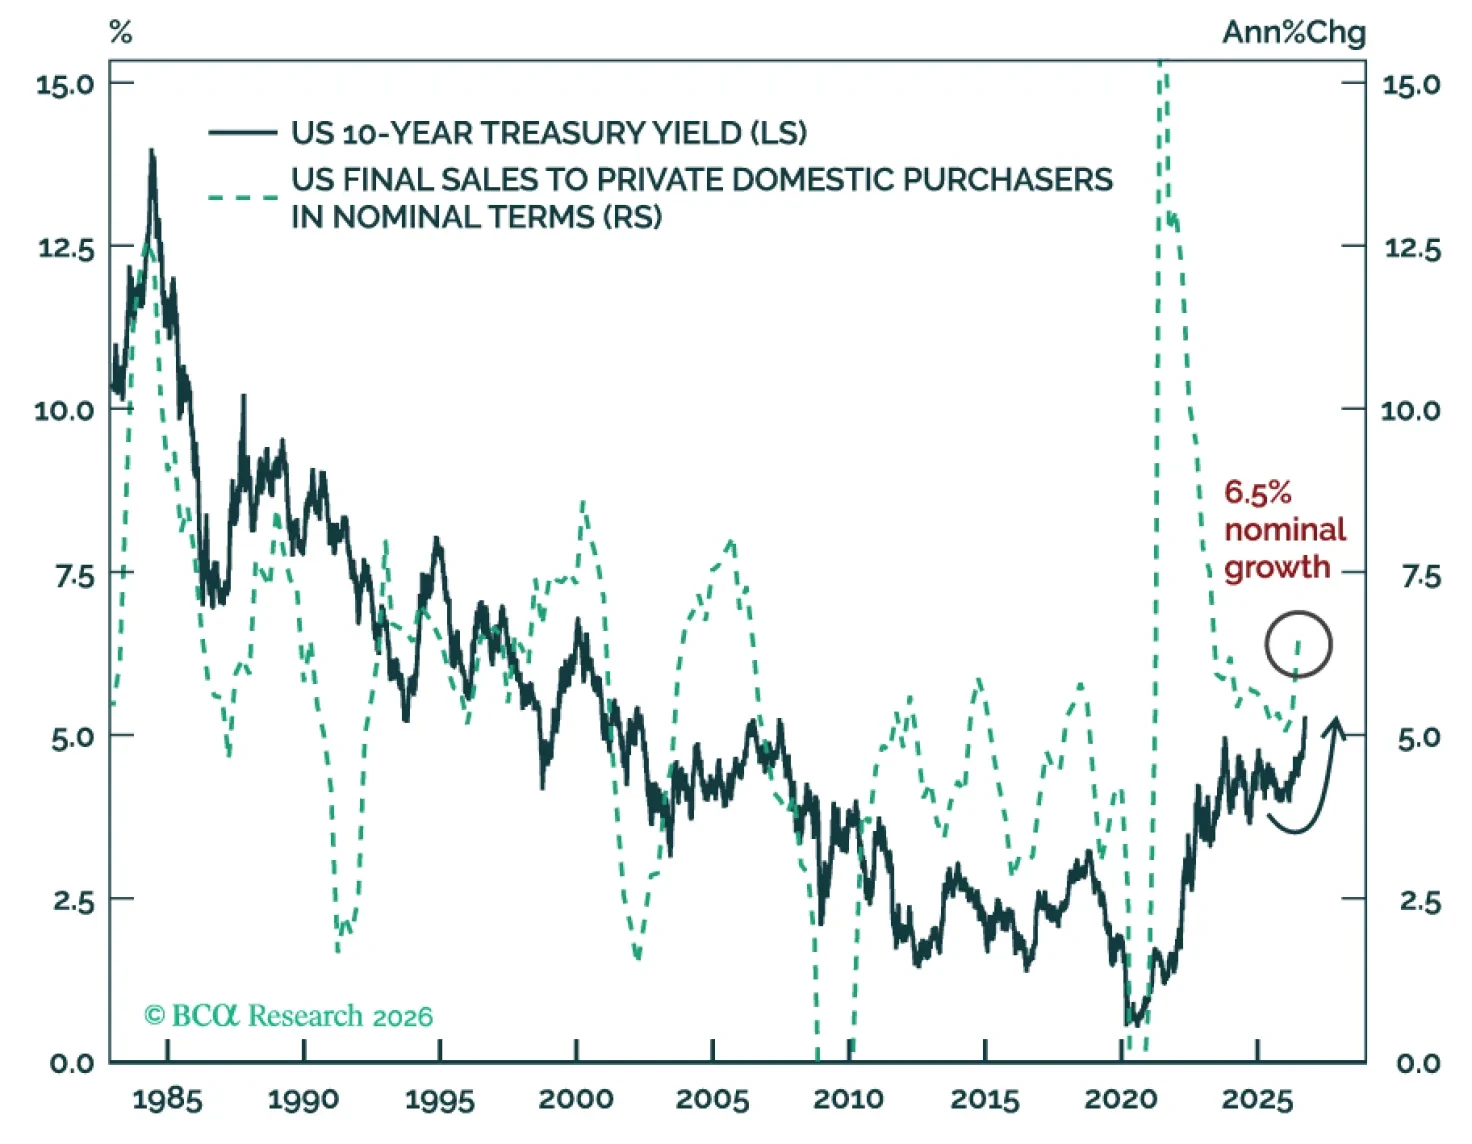
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
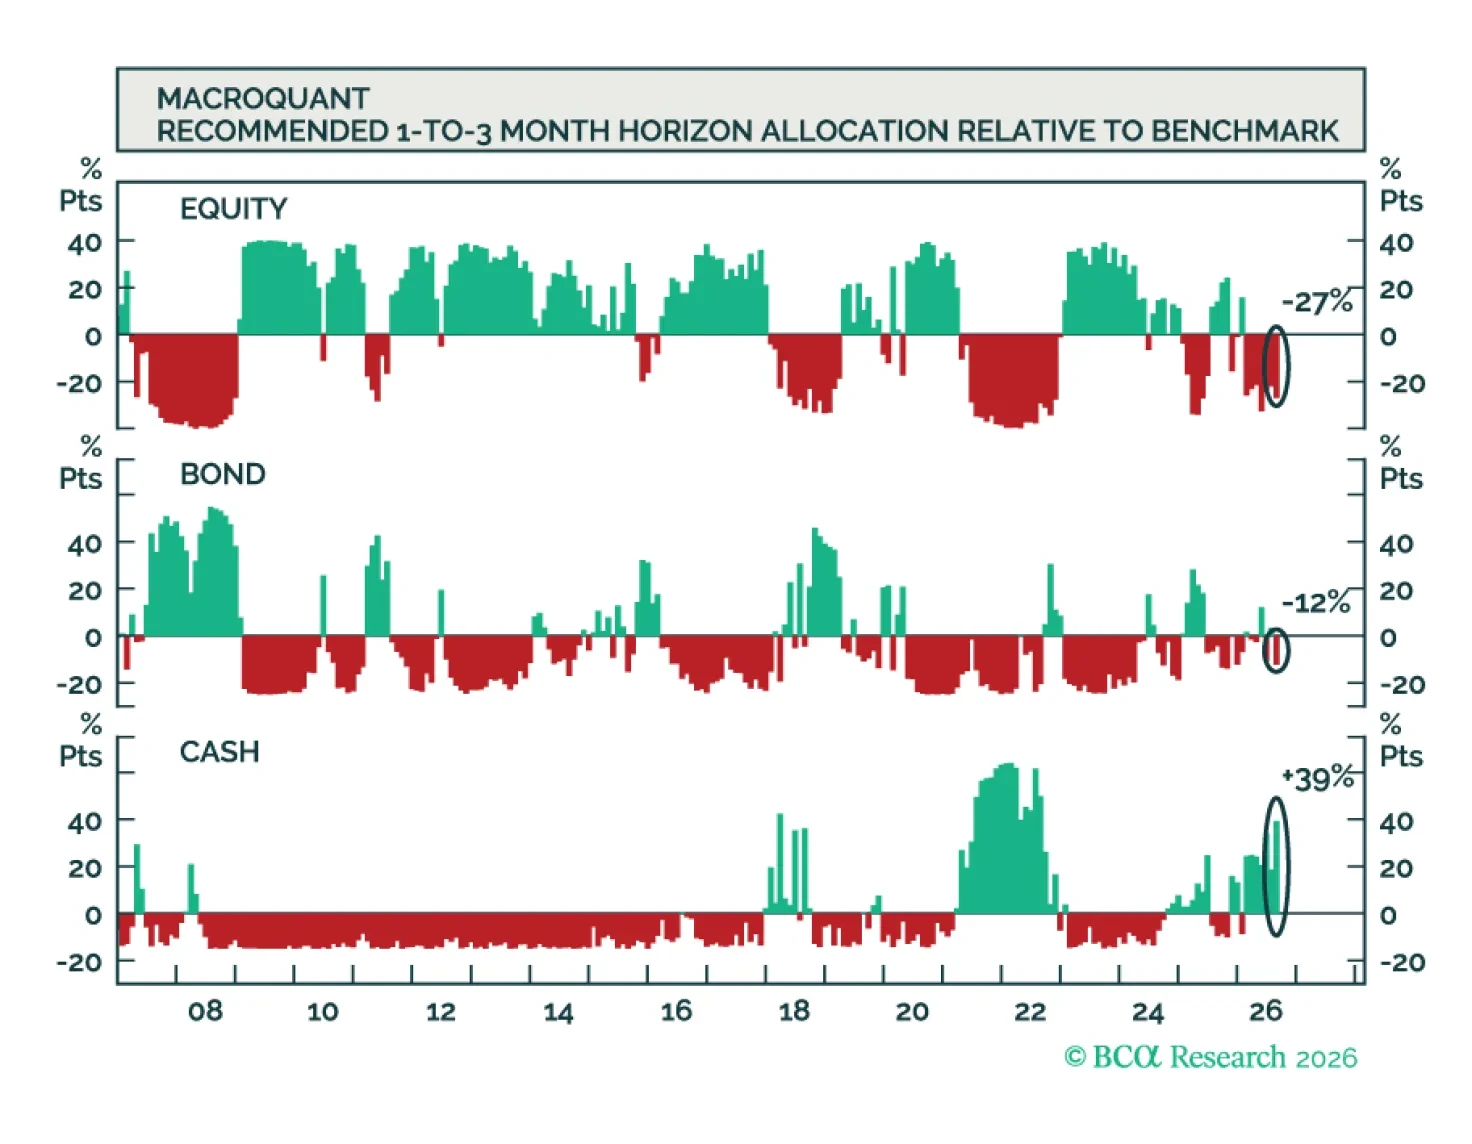
MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
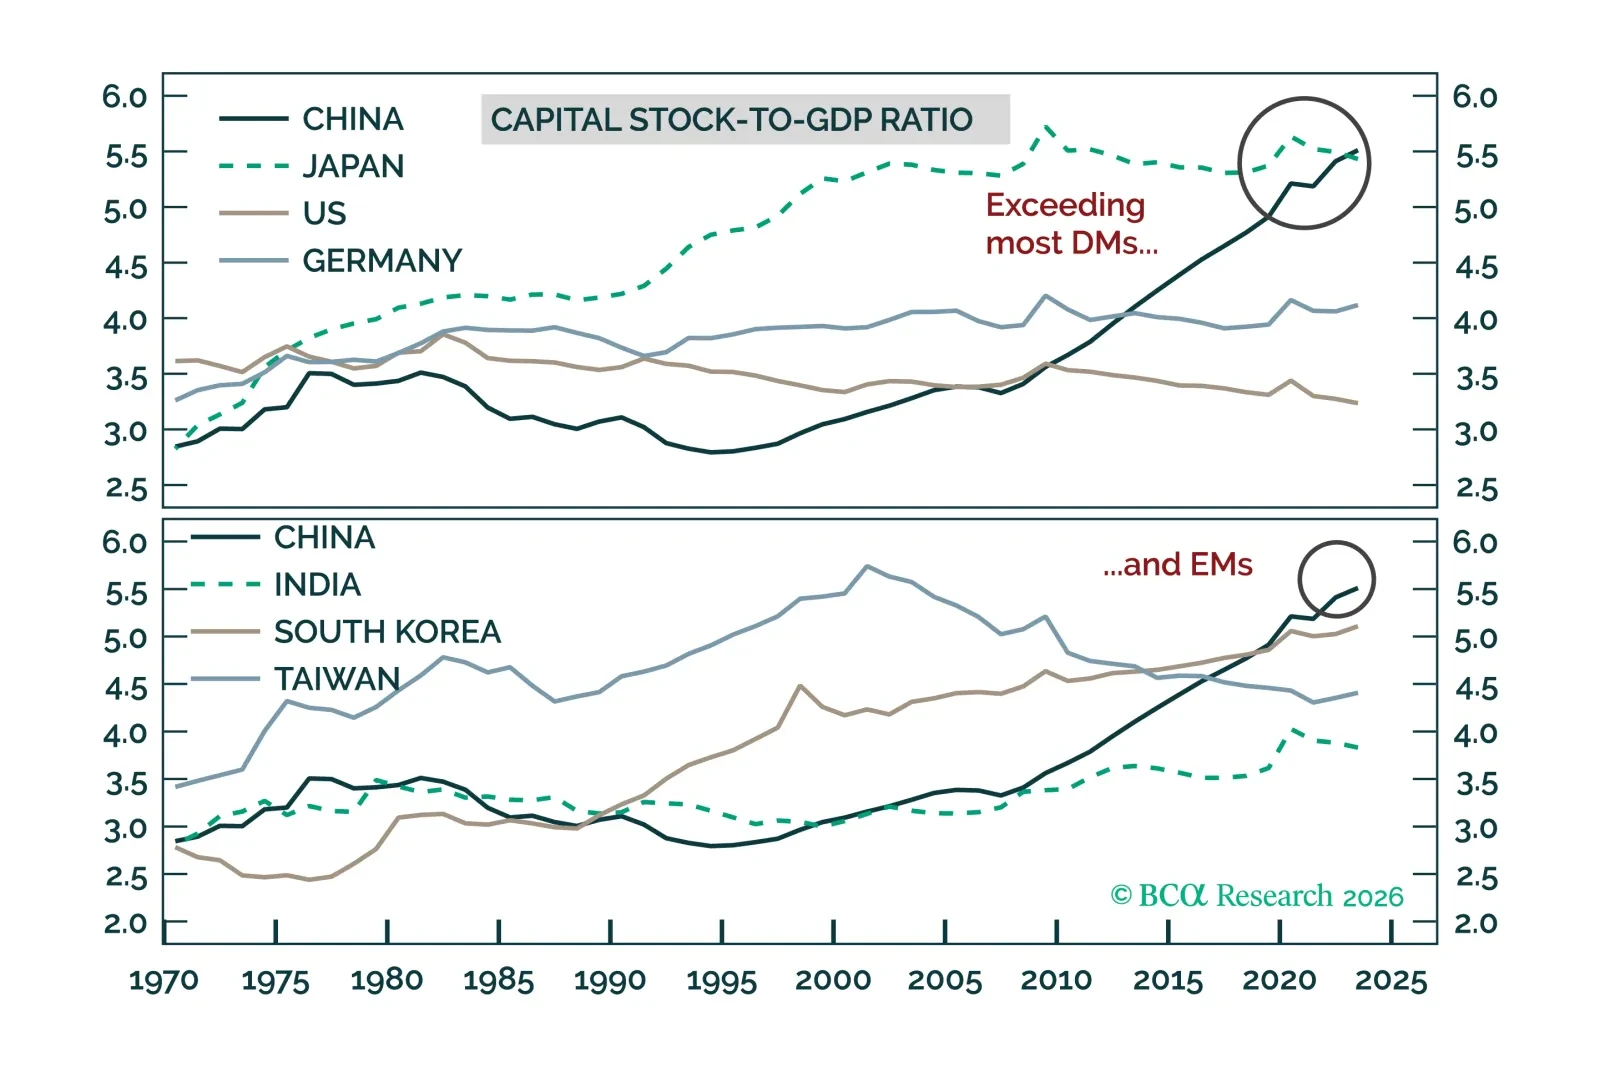
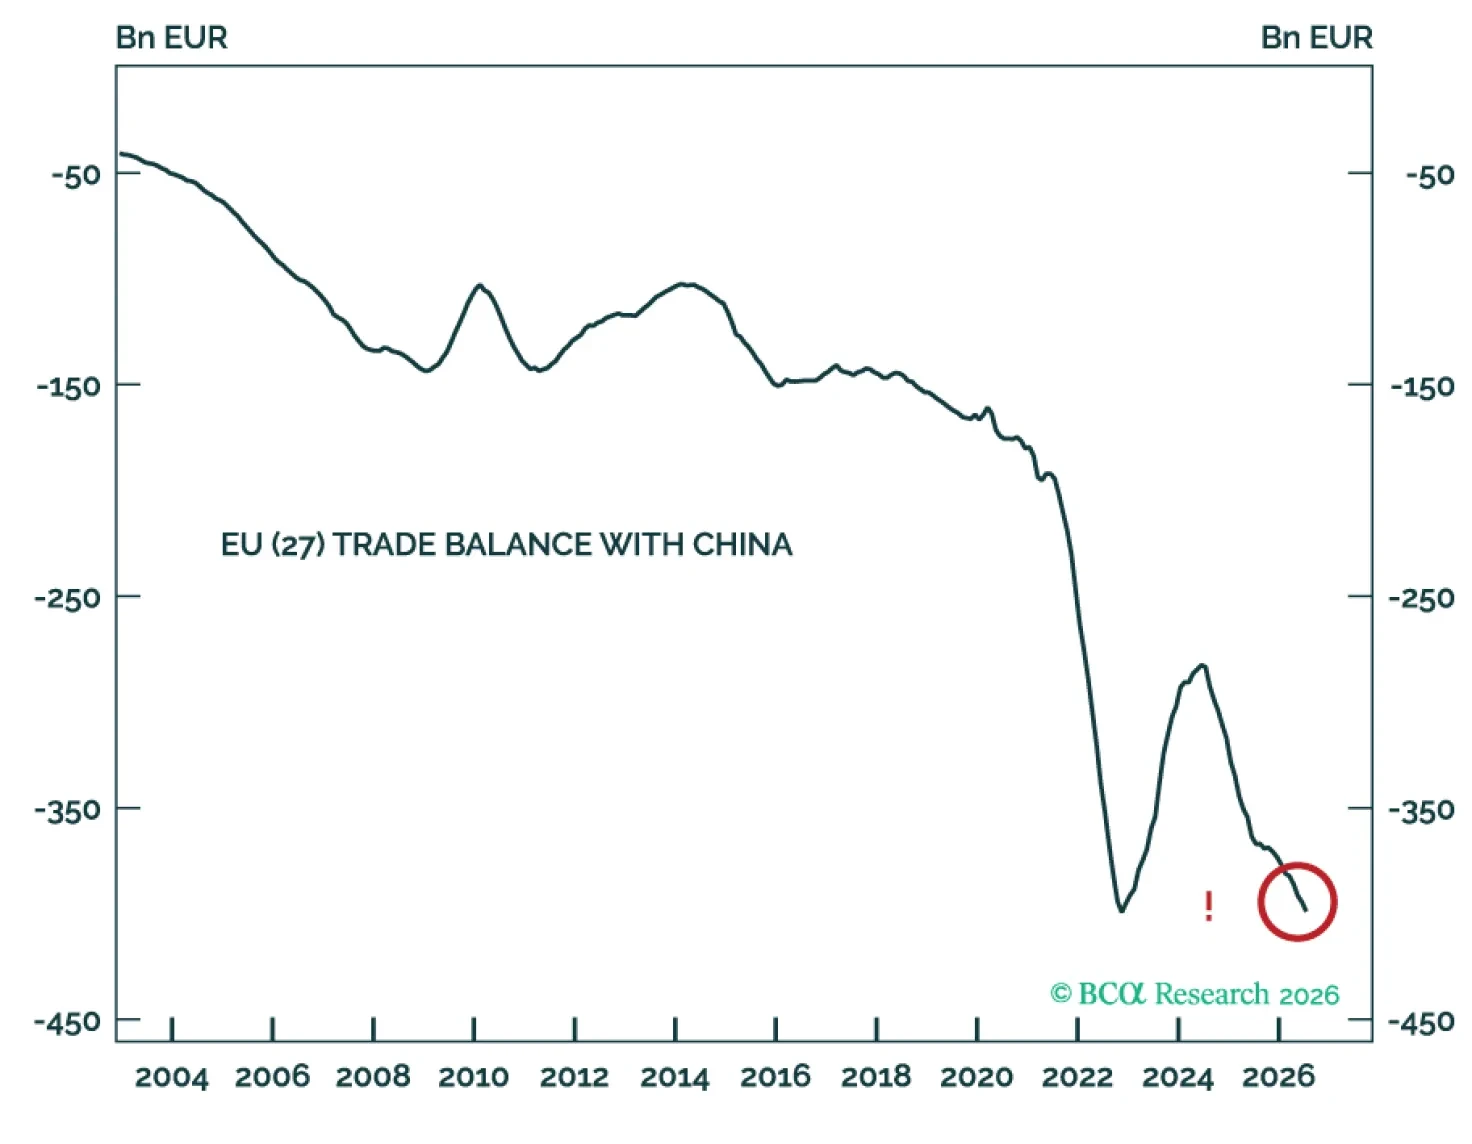
China’s investment has hit cyclical and structural limits. Mounting economic pressures will likely push Beijing toward a more aggressive, consumer-focused reflationary stance over the next one to two years.
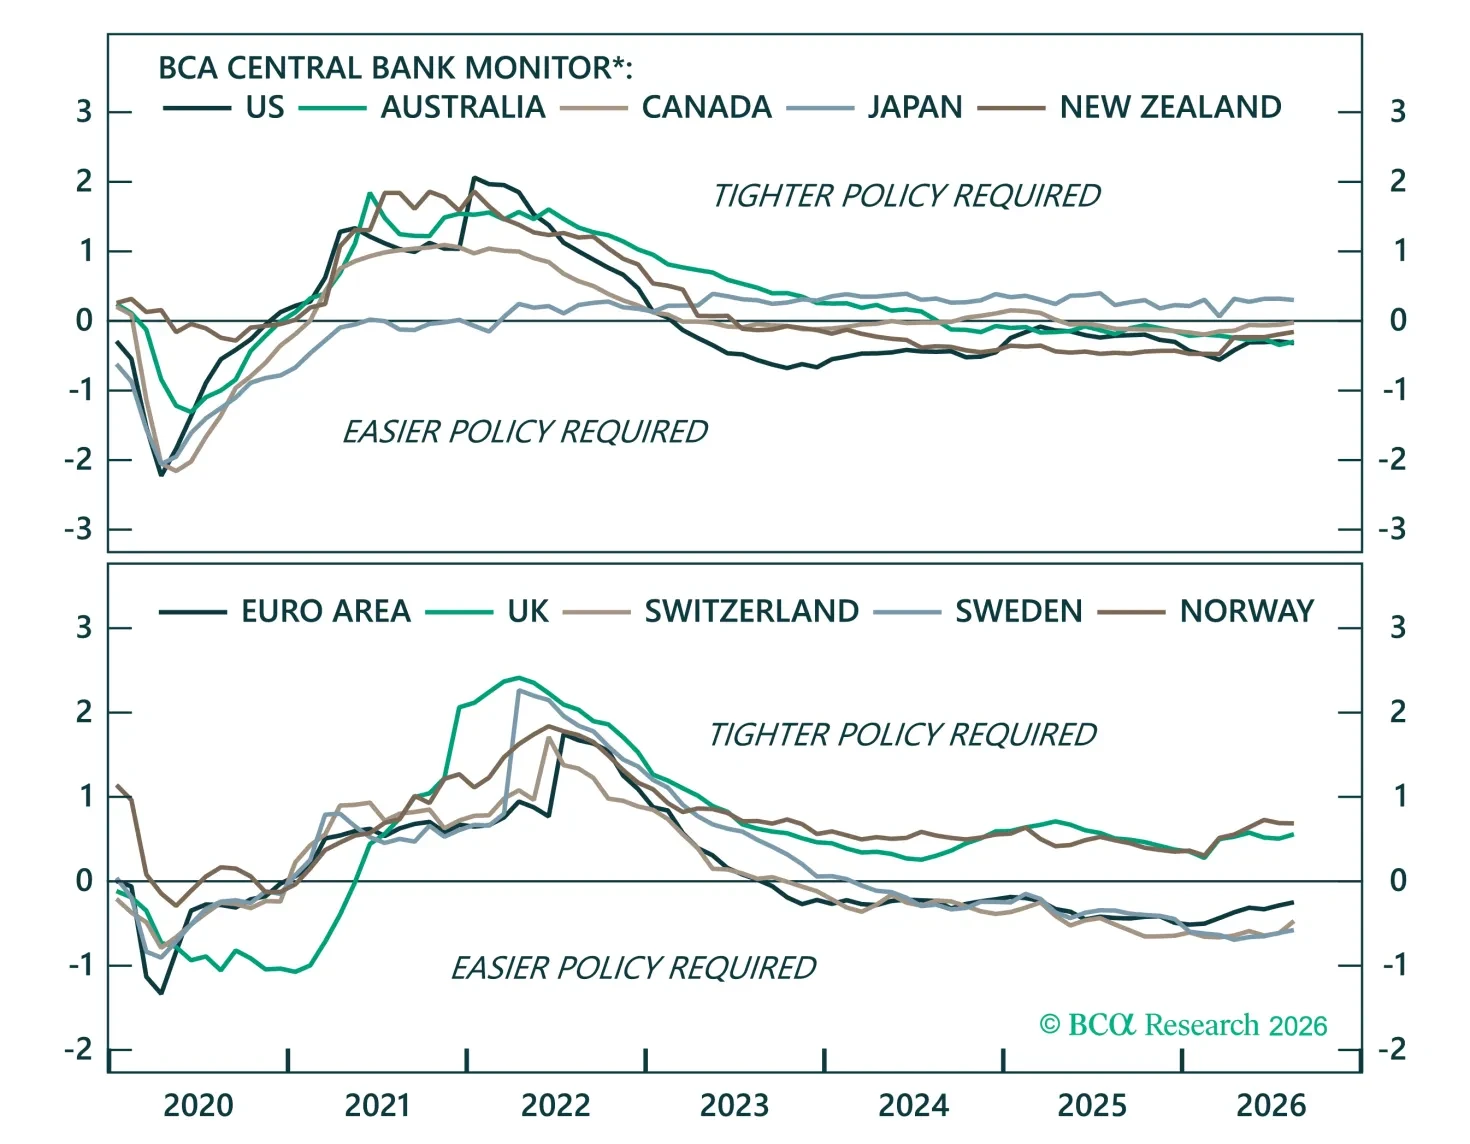
Central banks have begun a mild tightening cycle as elevated energy prices raise concerns about second-round inflation effects. We use BCA’s Central Bank Monitors to test whether hawkish market pricing is justified and identify tactical opportunities across global bond and currency markets.
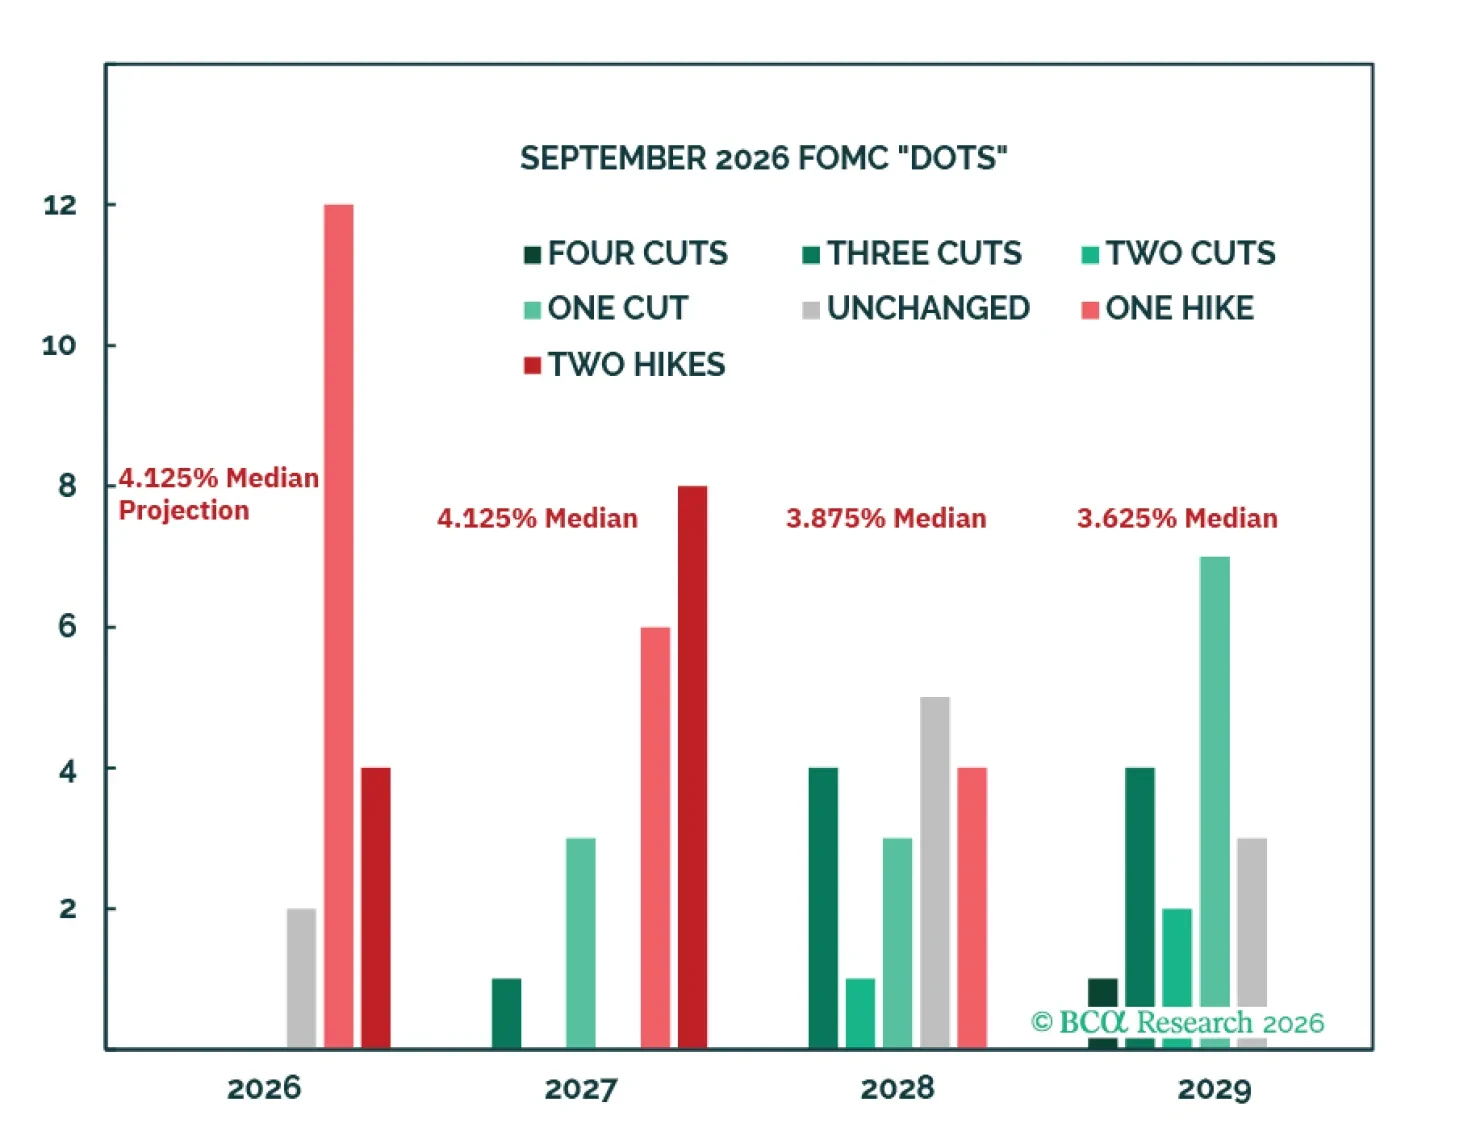
The Fed hiked rates last week, but Fed officials expect this tightening cycle will involve no more than three 25-basis point hikes, contingent on inflation coming down quickly in 2027. We’re inclined to agree.
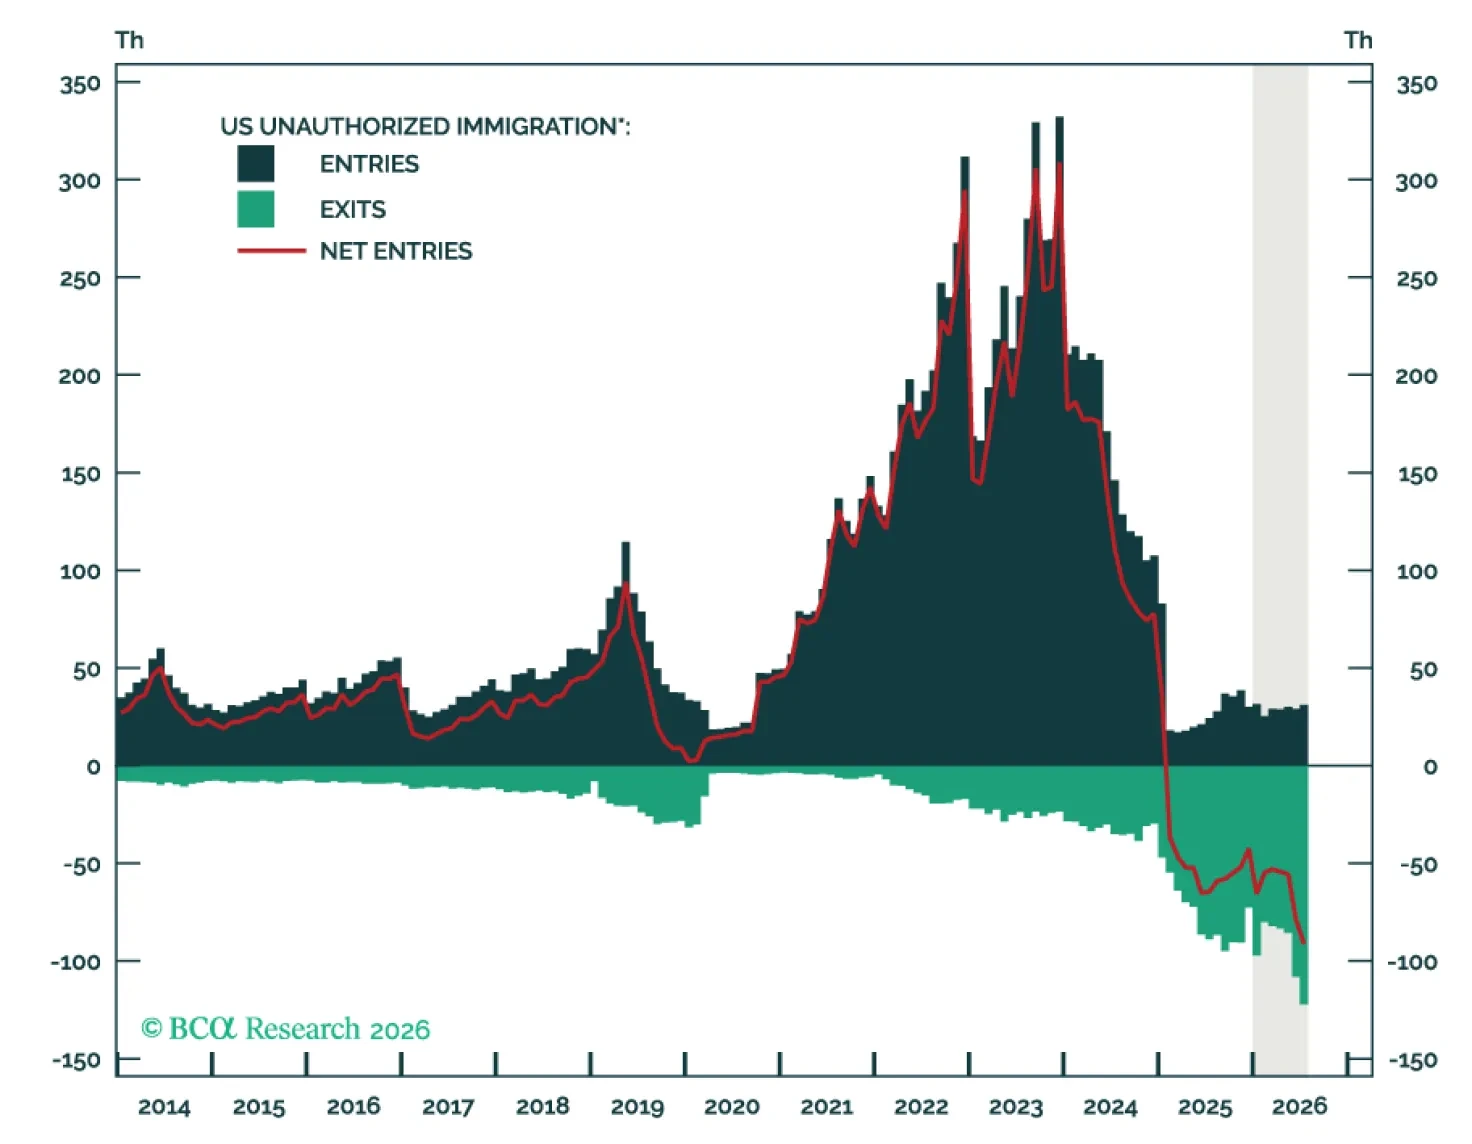
Labor supply is not meaningfully boosting inflation today, but the net exit of unauthorized immigrants has lowered the bar for stronger labor demand to turn inflationary. Hawkish monetary policy surprises over the coming year are possible.