Equities
| US Equities
US equity research, from the S&P 500 to sectors and factors, on where stocks are heading next.
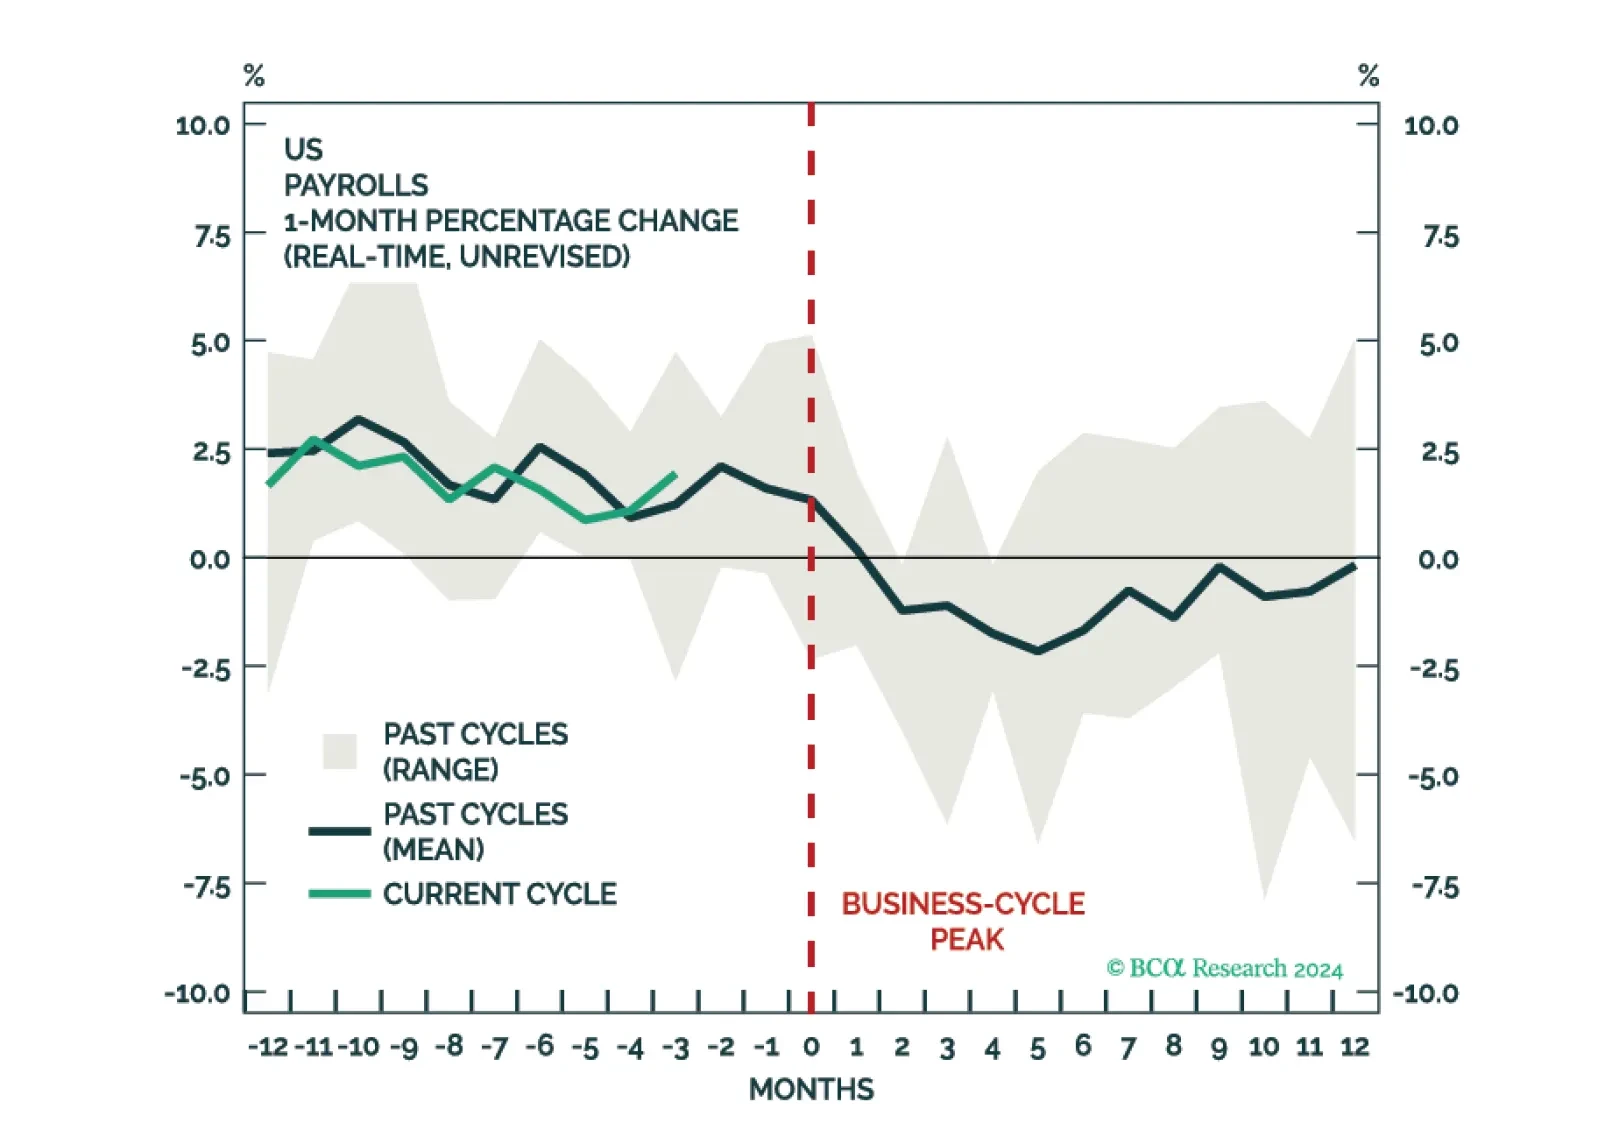
It is too early to say that the US labor market has turned the corner. We assign a 60% chance that the US will enter a recession over the next 12 months, with the downturn likely to begin in the first half of 2025. Accordingly, investors should underweight equities.
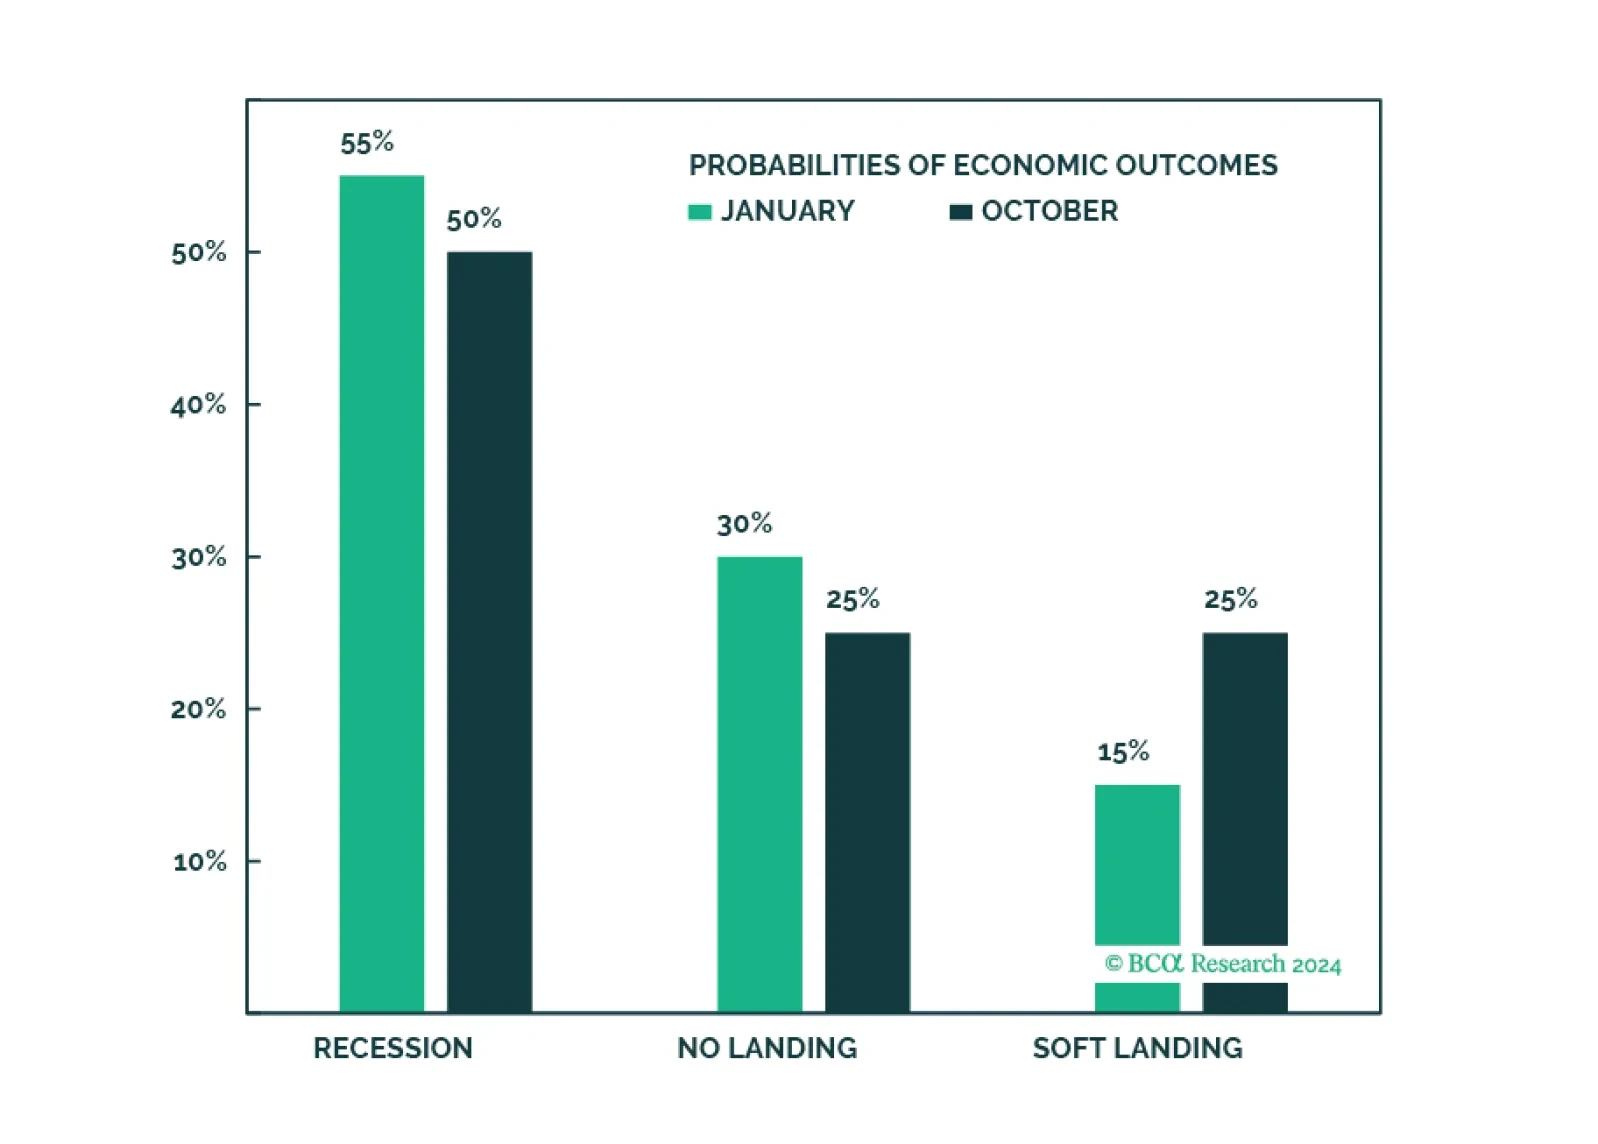
Recent data releases and revisions indicate that the US economy is stronger than initially reported, reducing the odds of a recession. While we harbor concerns about the reliability of the data, for now, it appears that aggressive monetary easing is taking place against the backdrop of a strong economy. If that is indeed the case, the economy may overheat again. This warrants portfolio rebalancing away from sectors that offer downside protection in a downturn, such as Telecom and Utilities, to sectors that outperform in a no-landing scenario, such as Energy.
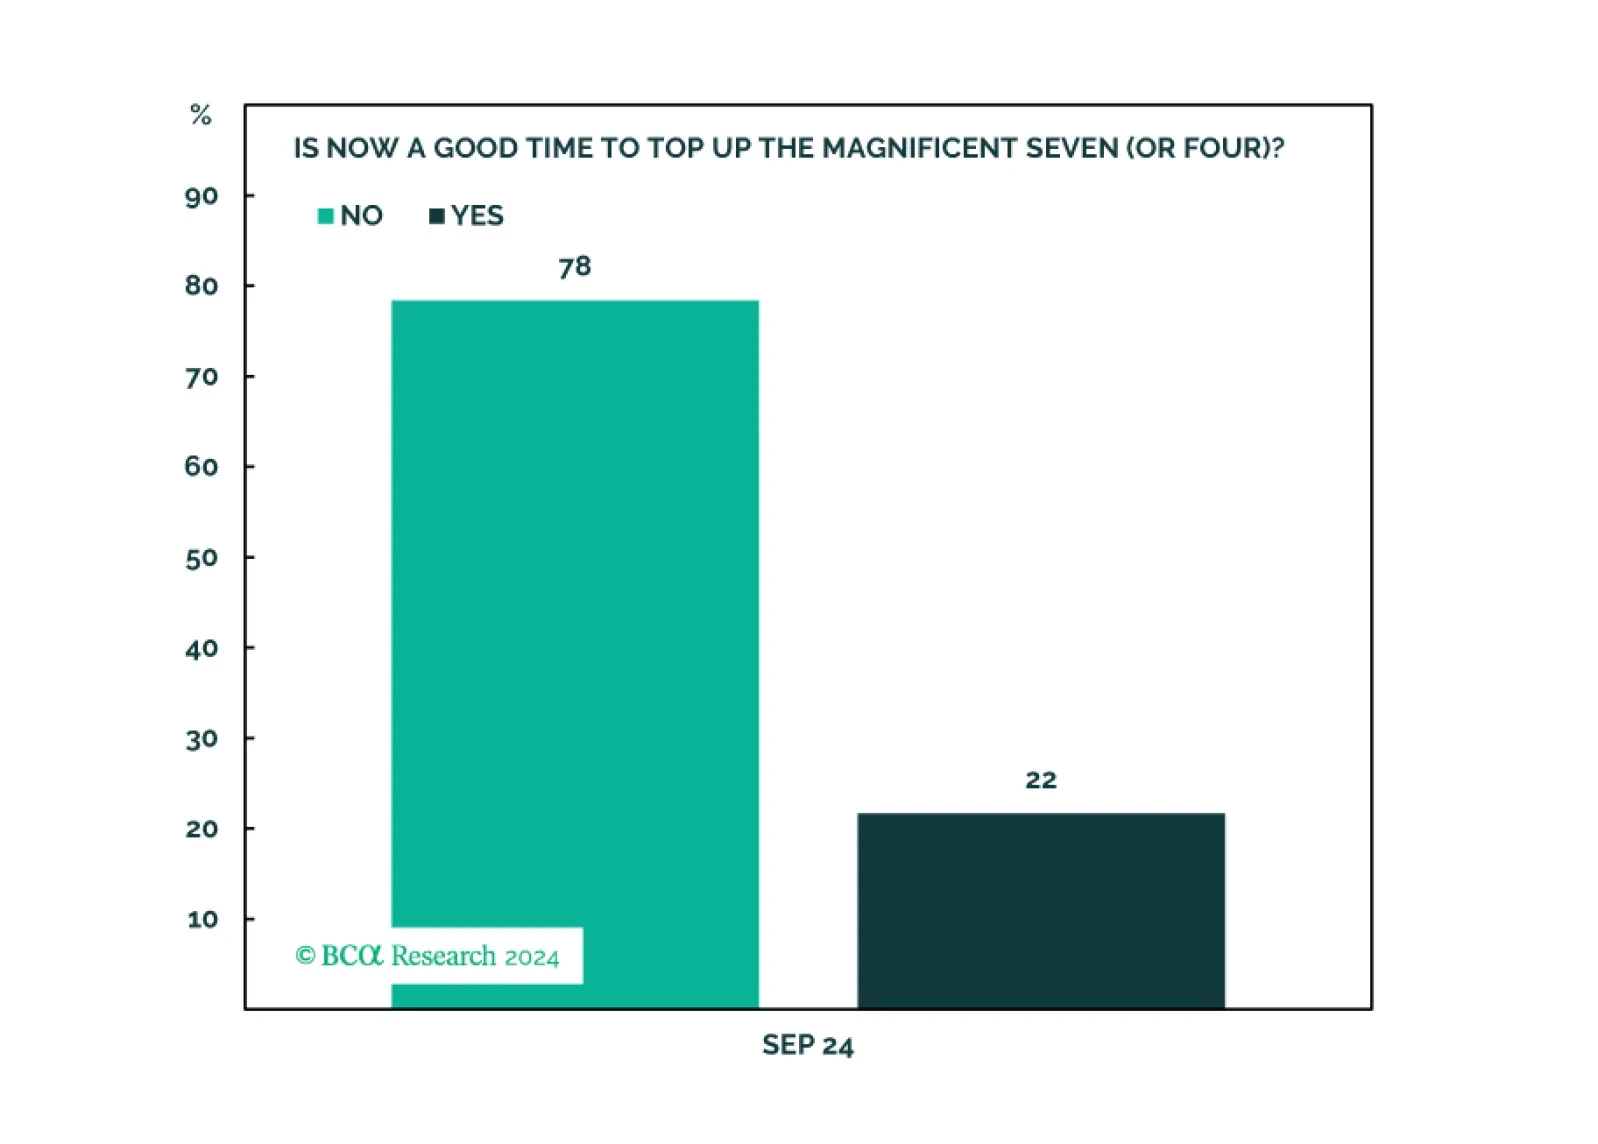
In this report, we follow up on the Roundtable that we hosted on September 11. We summarize the results of the client polls and answer a few questions on top of investors’ minds.
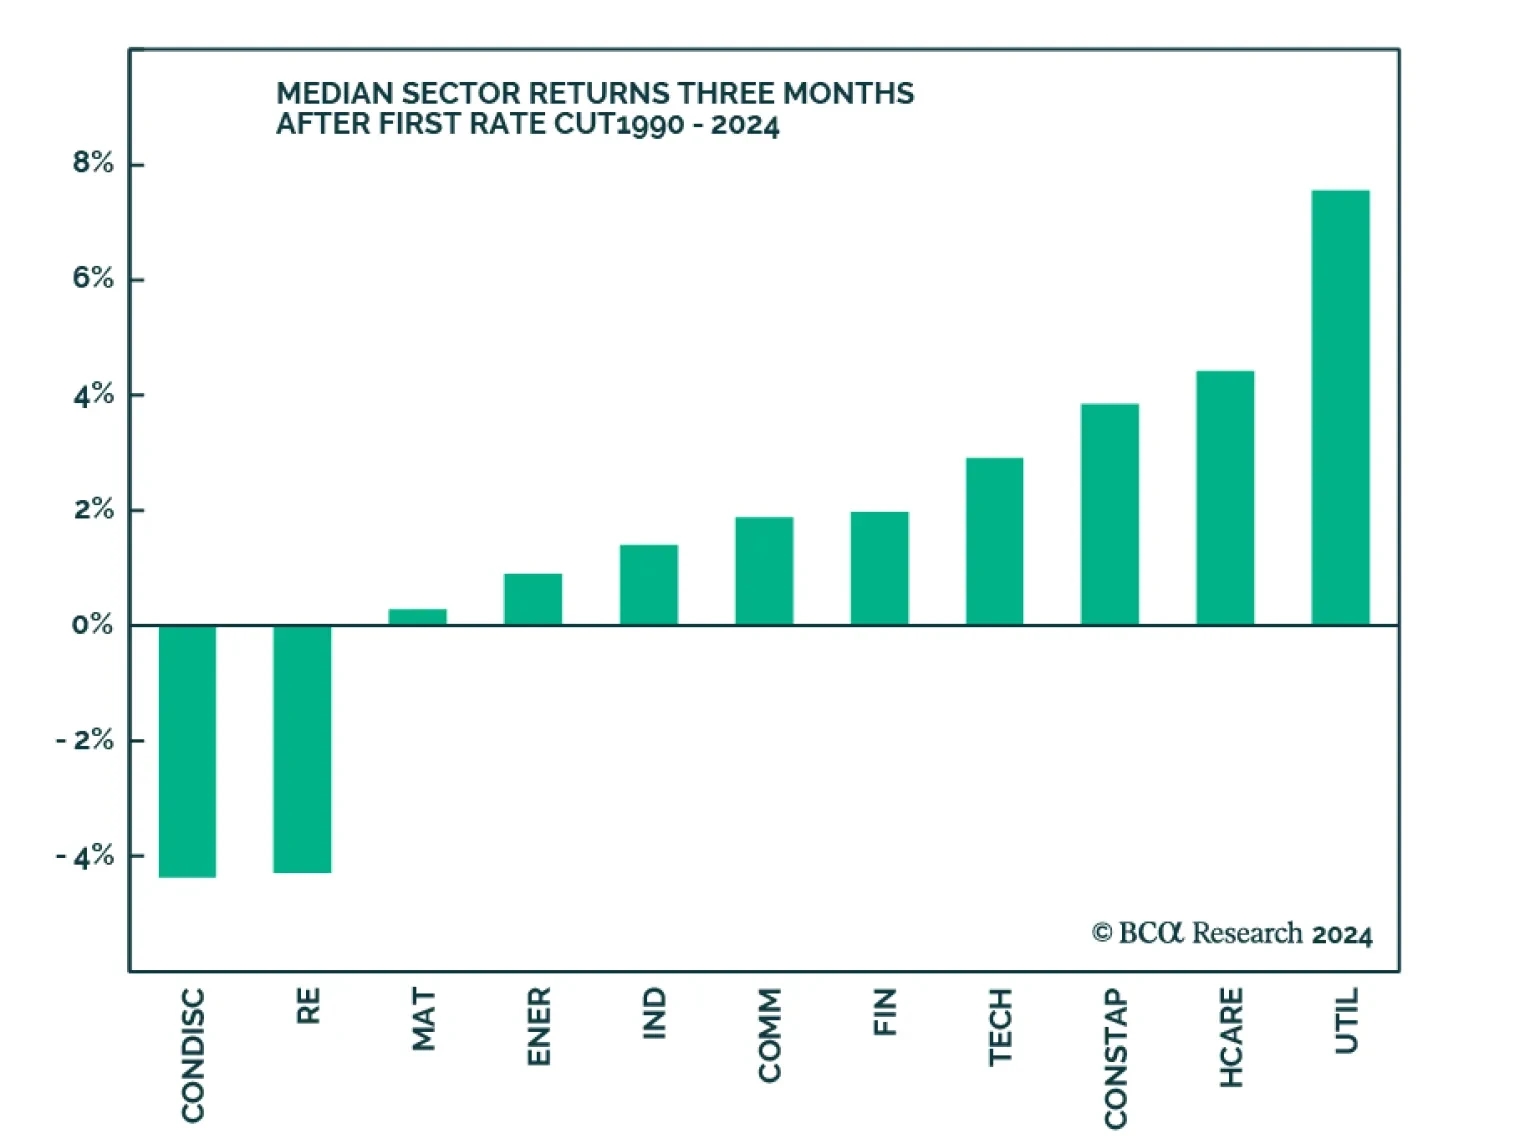
The economy is not in a recession, and the Fed is not behind the curve. A 50 bp rate cut at the September meeting is unlikely, but 25 bp is certain. However, economic growth is slowing, and a recession at the end of the year is still the most likely outcome. The S&P 500 earnings are projected to grow, but our model predicts that the growth rate will roll over. The S&P 500 remains expensive and crowded, but the most extreme technical positioning across sectors has unwound. We recommend lowering portfolio beta with defensive sectors, and under-weighing Tech, and Consumer Discretionary.
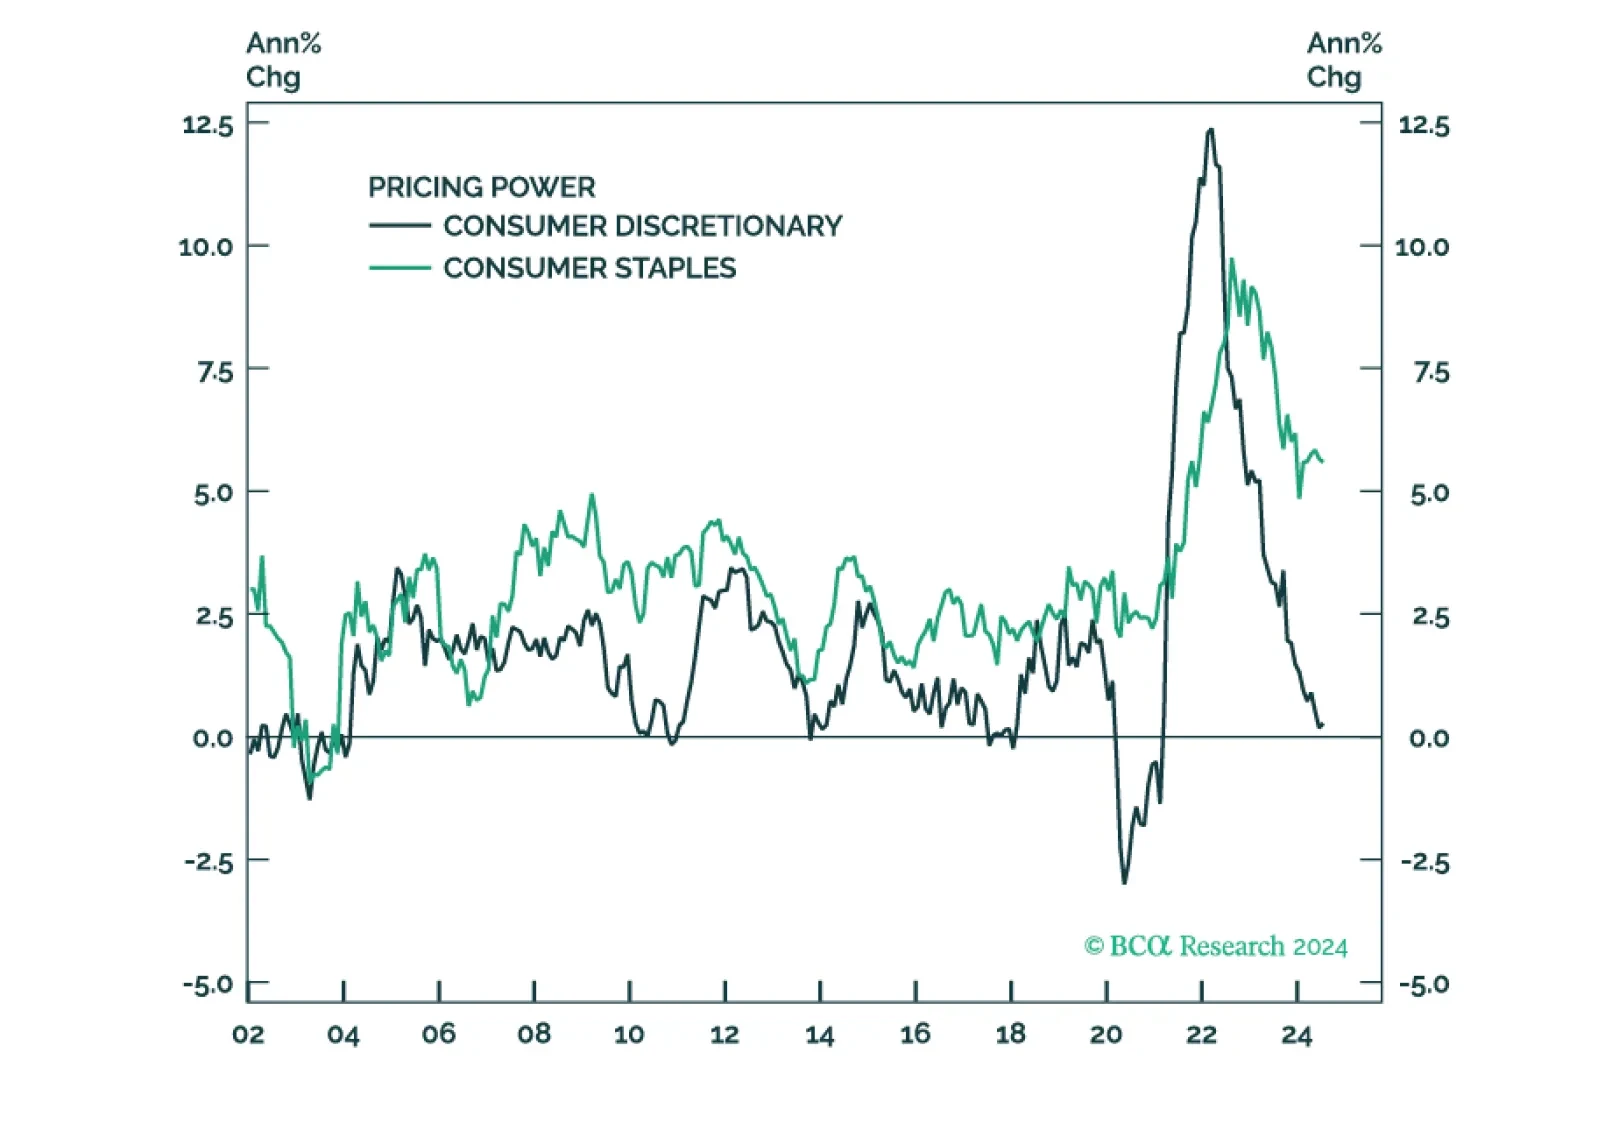
Q2 Earnings season has been strong, with sales and earnings growth accelerating and broadening across sectors. However, companies' results and commentaries are stoking some concerns. GAI monetization will take longer than most investors expect. Companies are also reporting that lower- and middle-income US consumers are strapped. We recommend defensive positioning, as solid earnings growth is insufficient to rule out a recession later this year.
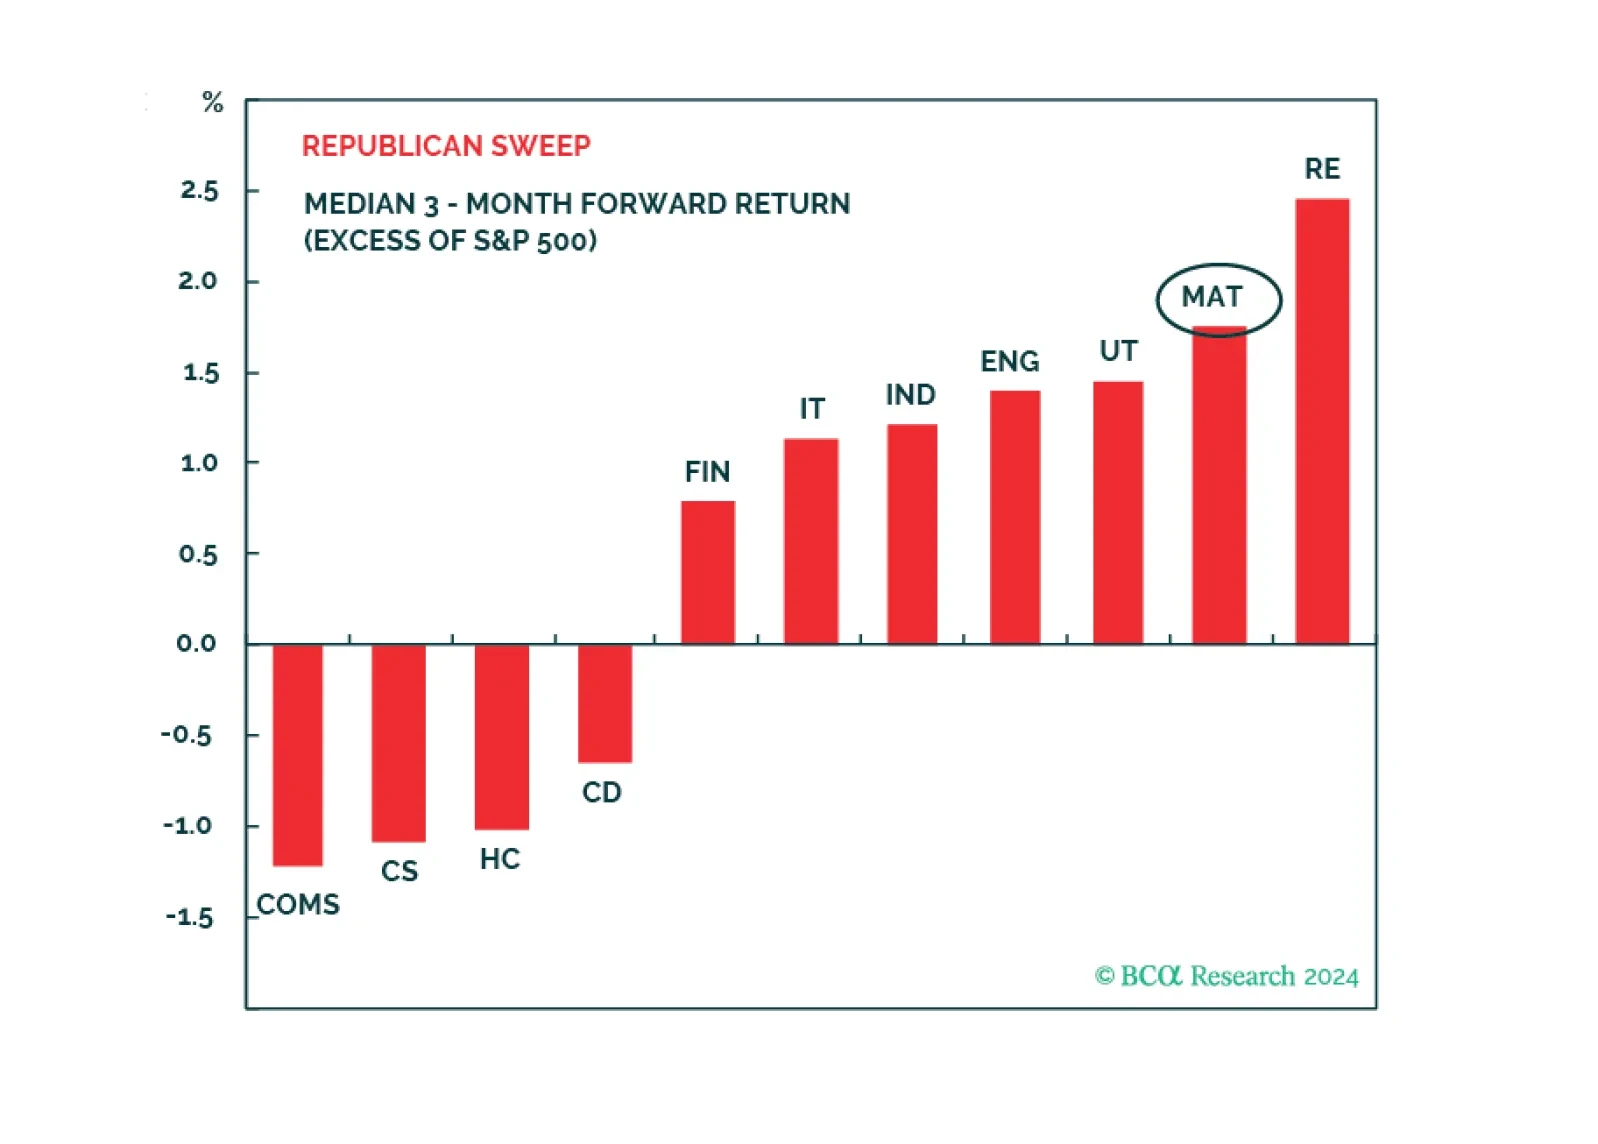
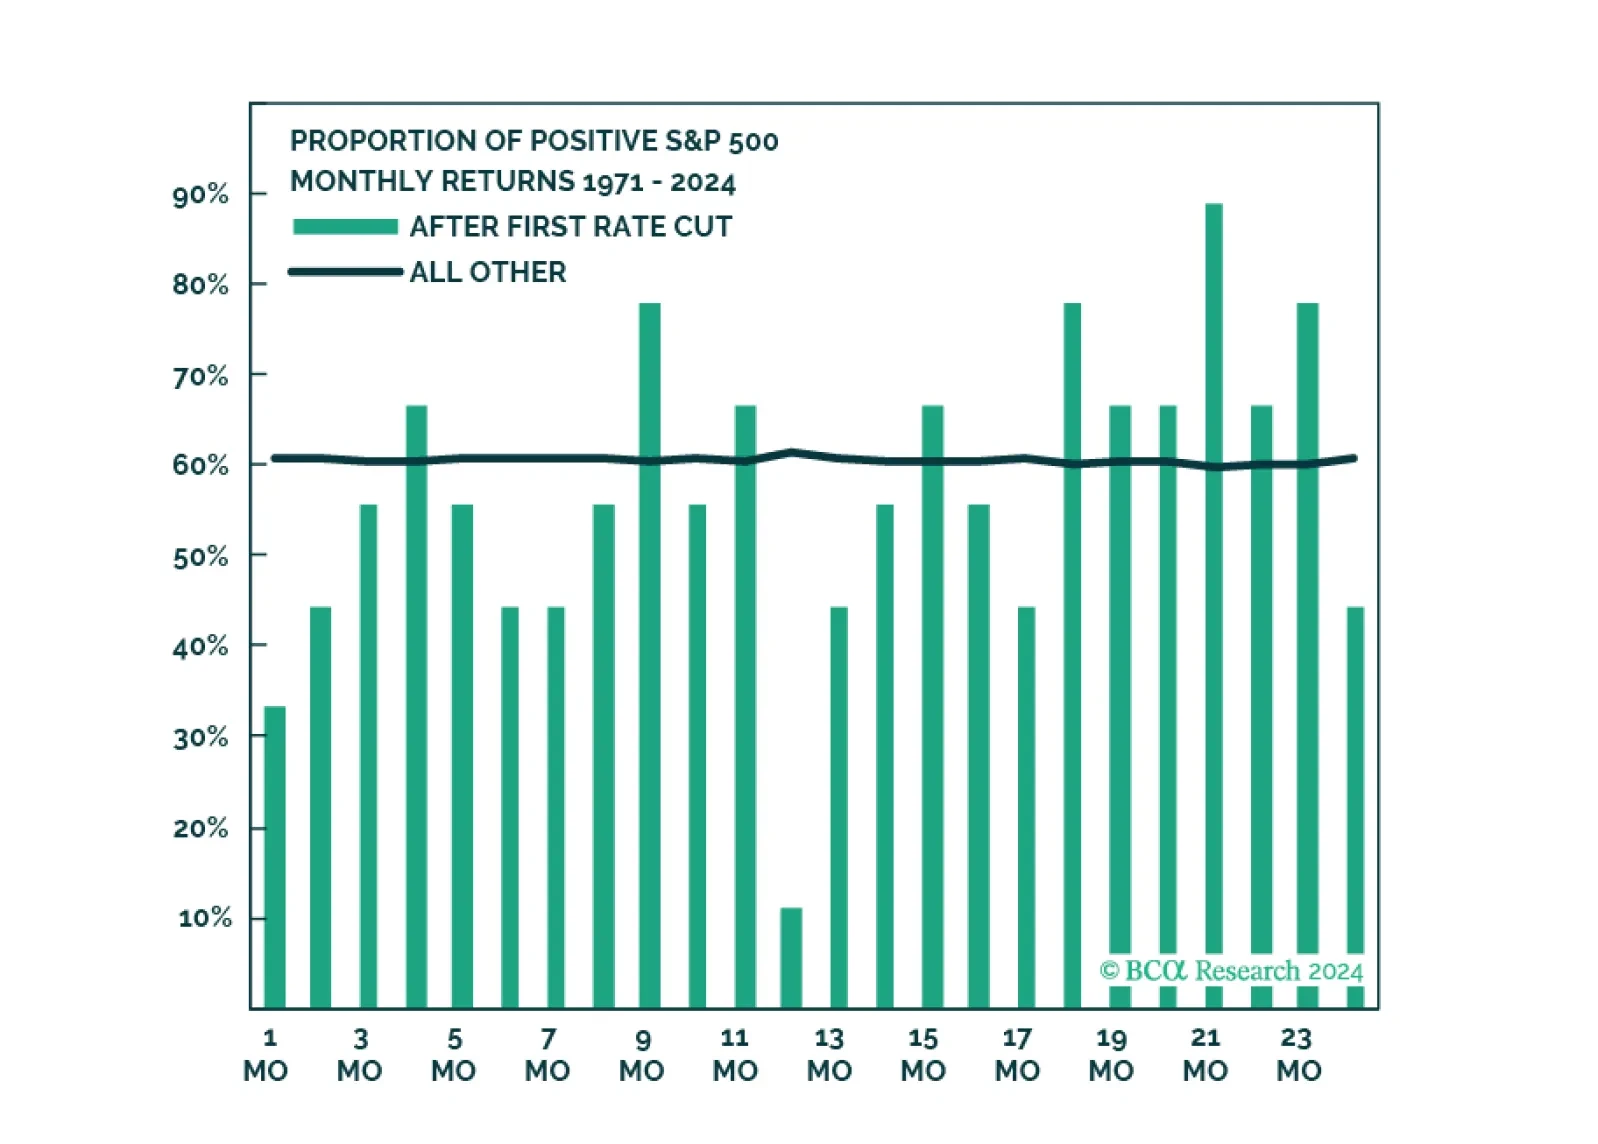
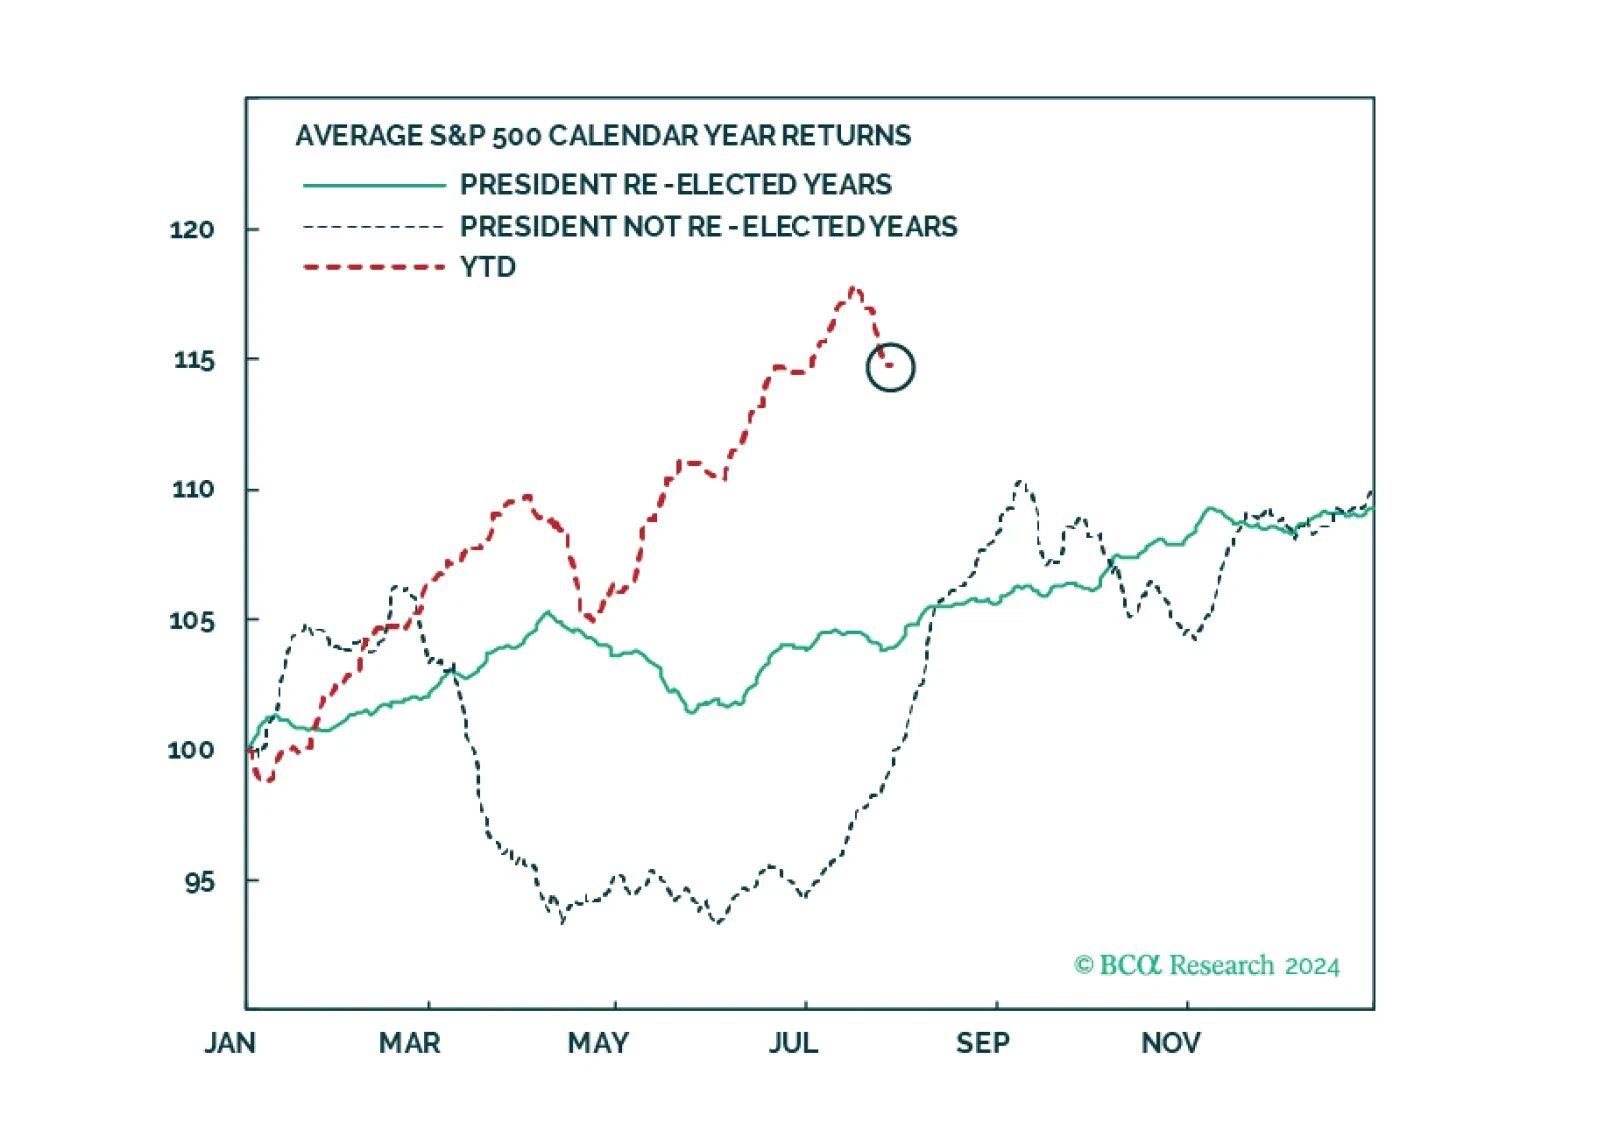
Over the next three months, US equity investors face slowing economic growth, the unwinding of carry trades, skepticism about GAI, uncertainty about the Fed easing campaign, and a run-up to the Presidential election. Empirically, each event has led to lower returns and heightened volatility. A combination of them all is bound to be toxic. It is not too late to take profits and lower portfolio beta.
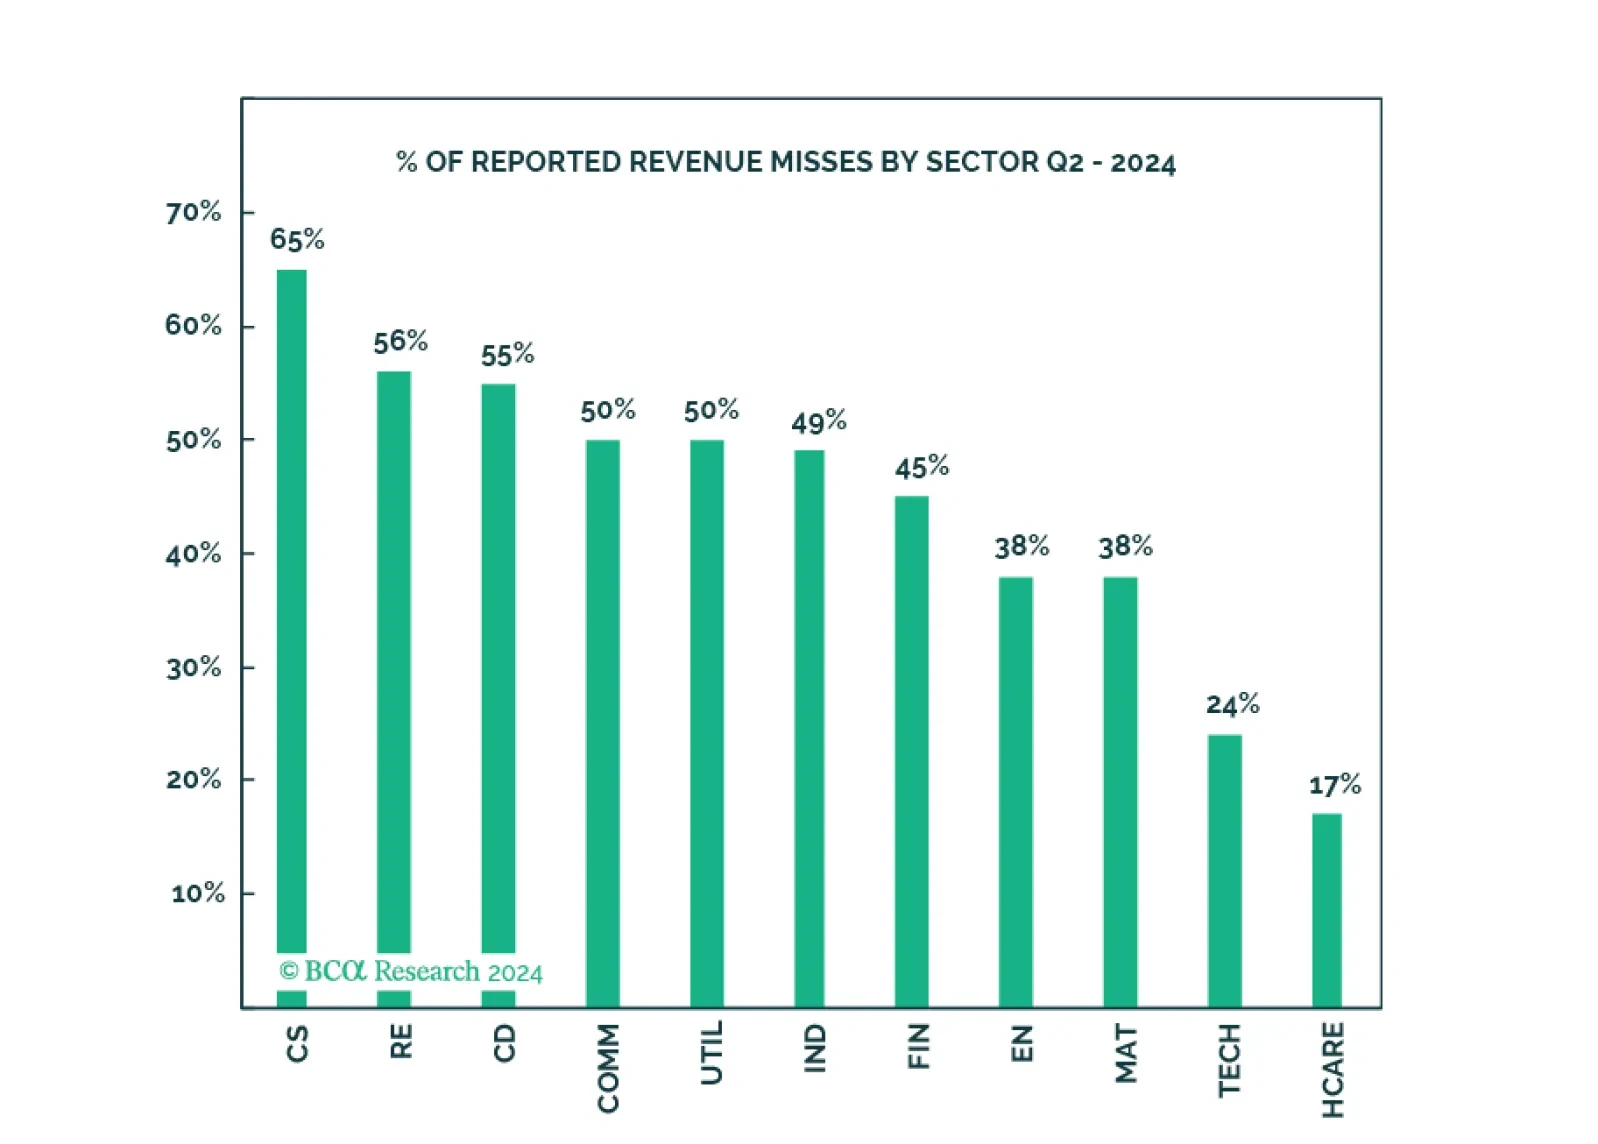
The second half of the year will be challenging for equity investors because economic growth is clearly deteriorating. Election uncertainty is adding to volatility. Bad news is now bad news, and equity markets will likely pull back, anticipating a hard landing. The GAI trade has run its course and now attracts more scrutiny. Take profits from recent winners. Don’t buy on a dip (at least not yet). Defensive and other laggards offer downside protection and will deliver positive relative returns. Close overweights or even go underweight in the Magnificent Seven sectors.