 Equities
| US Equities
US equity research, from the S&P 500 to sectors and factors, on where stocks are heading next.
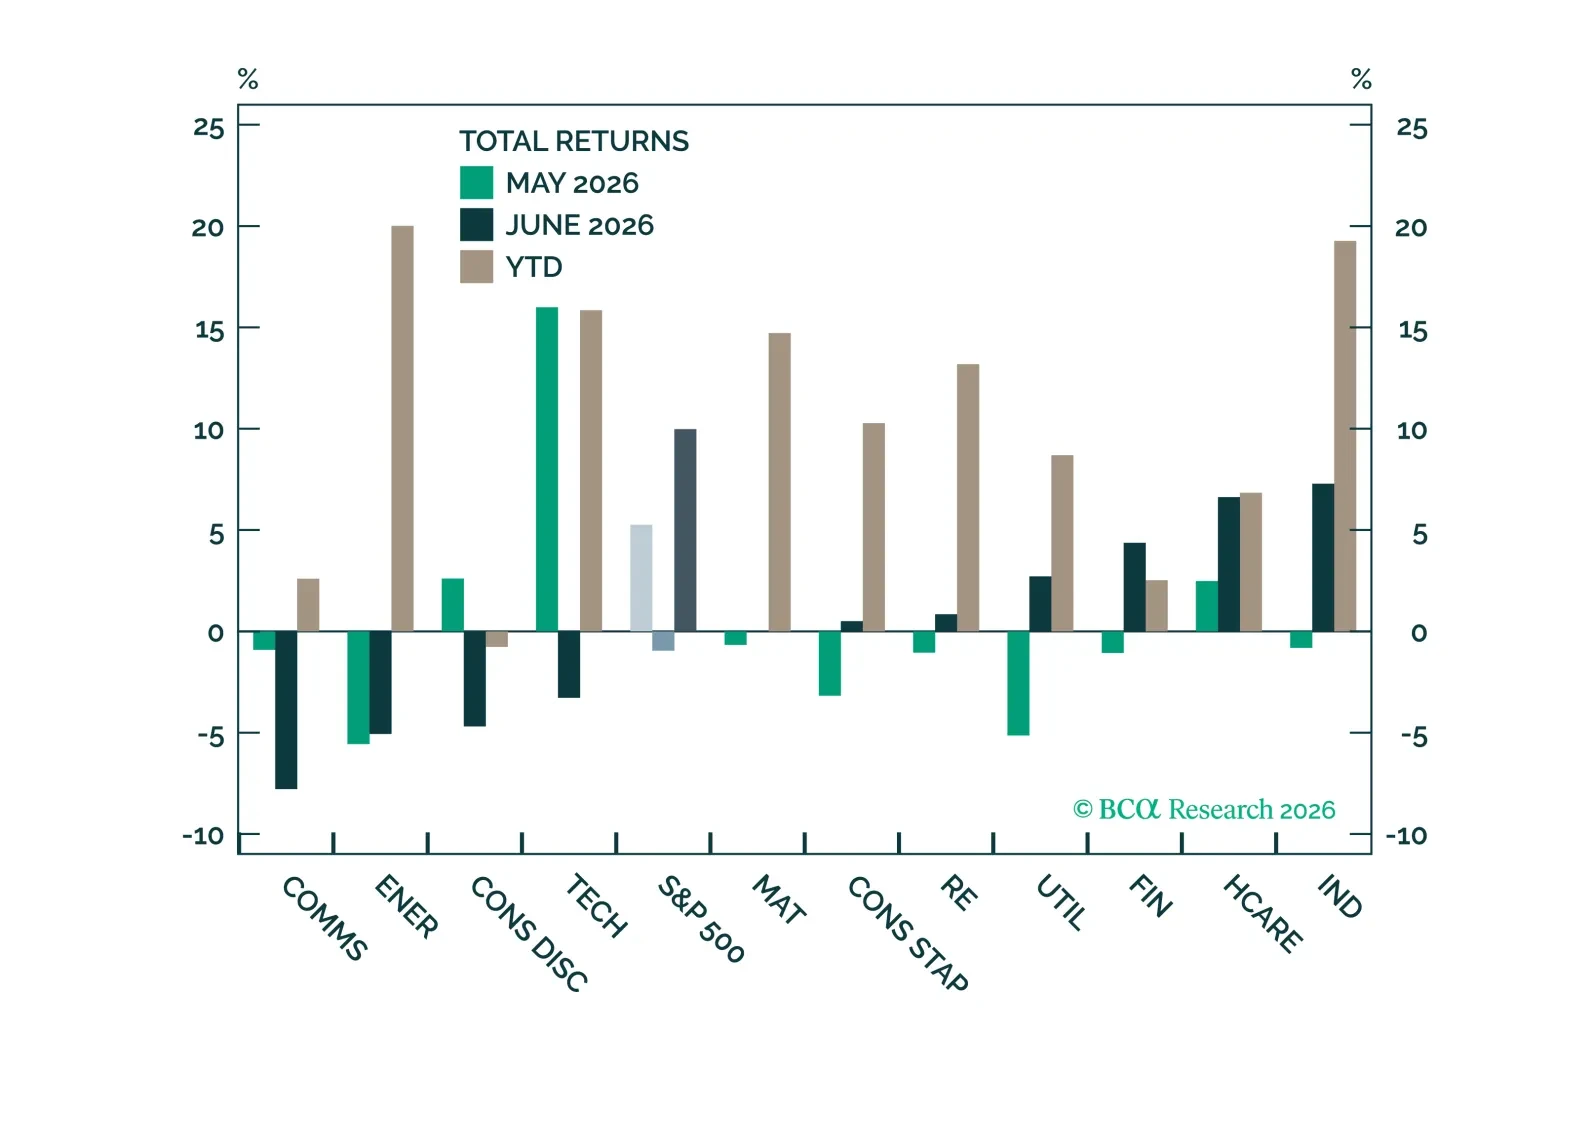
S&P 500 performance rotated in June, but fundamental growth remains strong across sectors, with earnings and revenue growth extending well beyond the largest mega-cap companies.
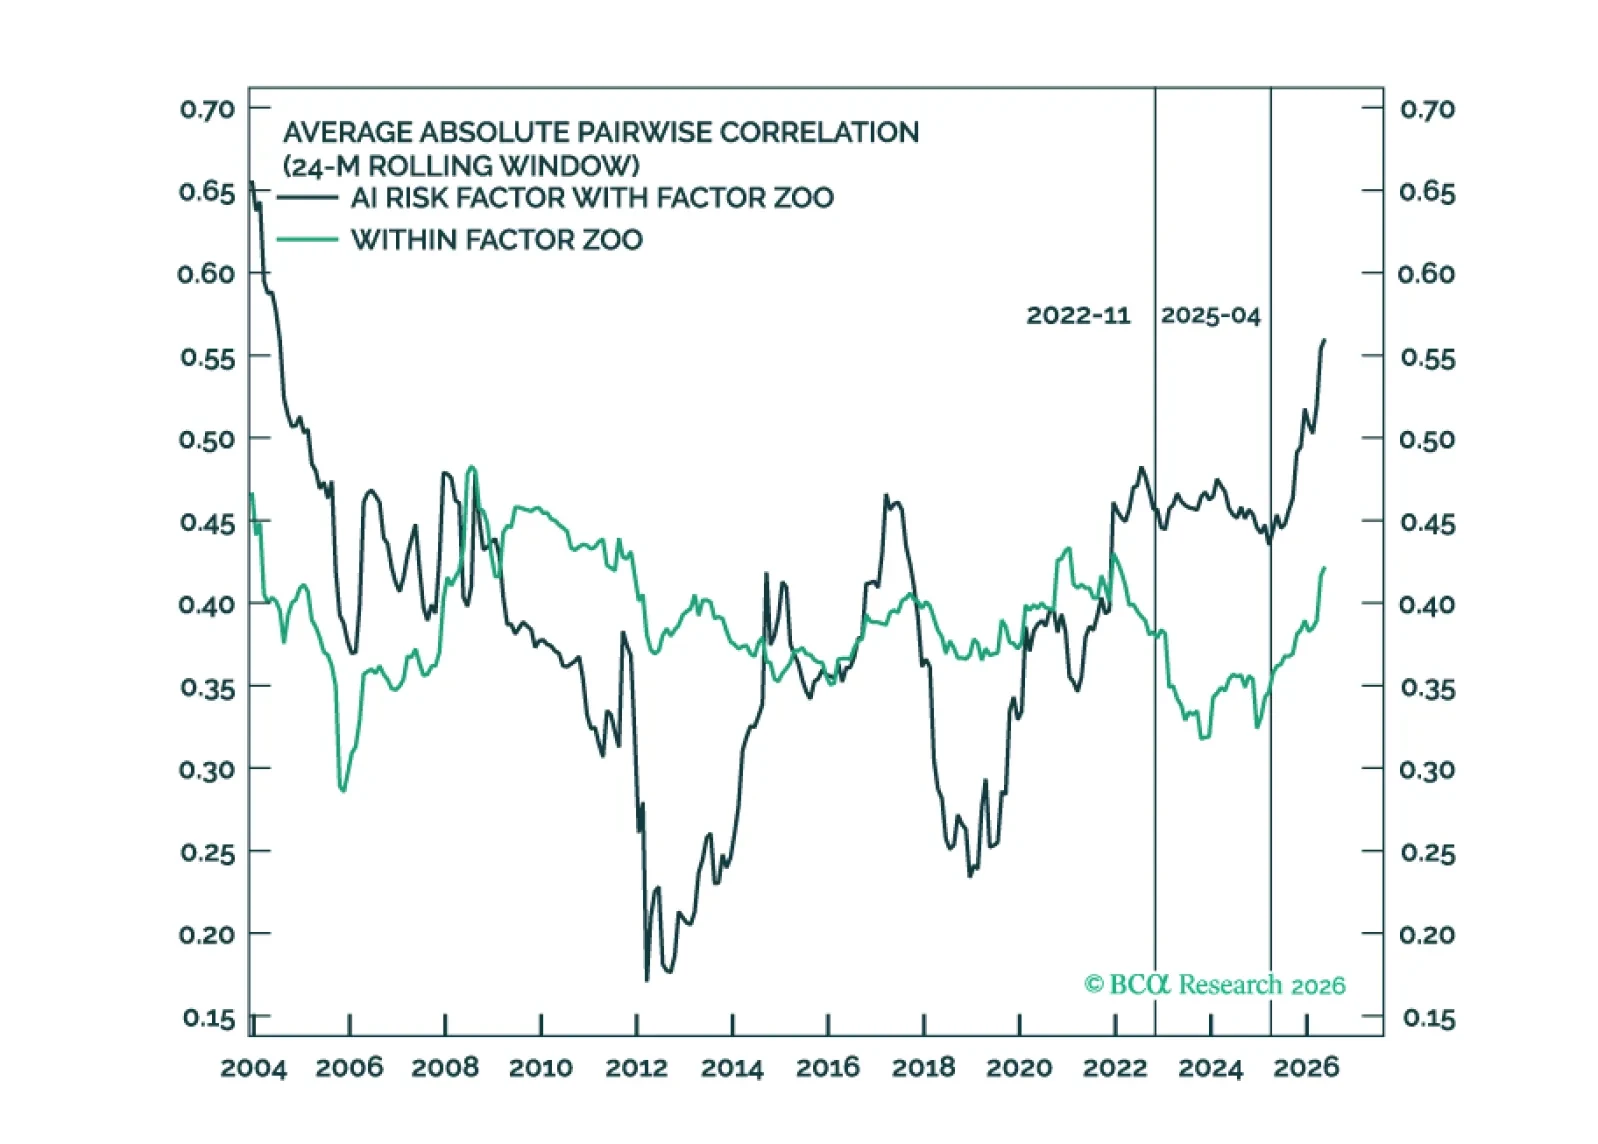
The S&P 500 has become increasingly concentrated. We know that. But the critical question is not how many stocks are driving the market; it is how many factors are driving stocks. We define an AI risk factor to test whether AI has become the dominant common exposure throughout much of the factor zoo.
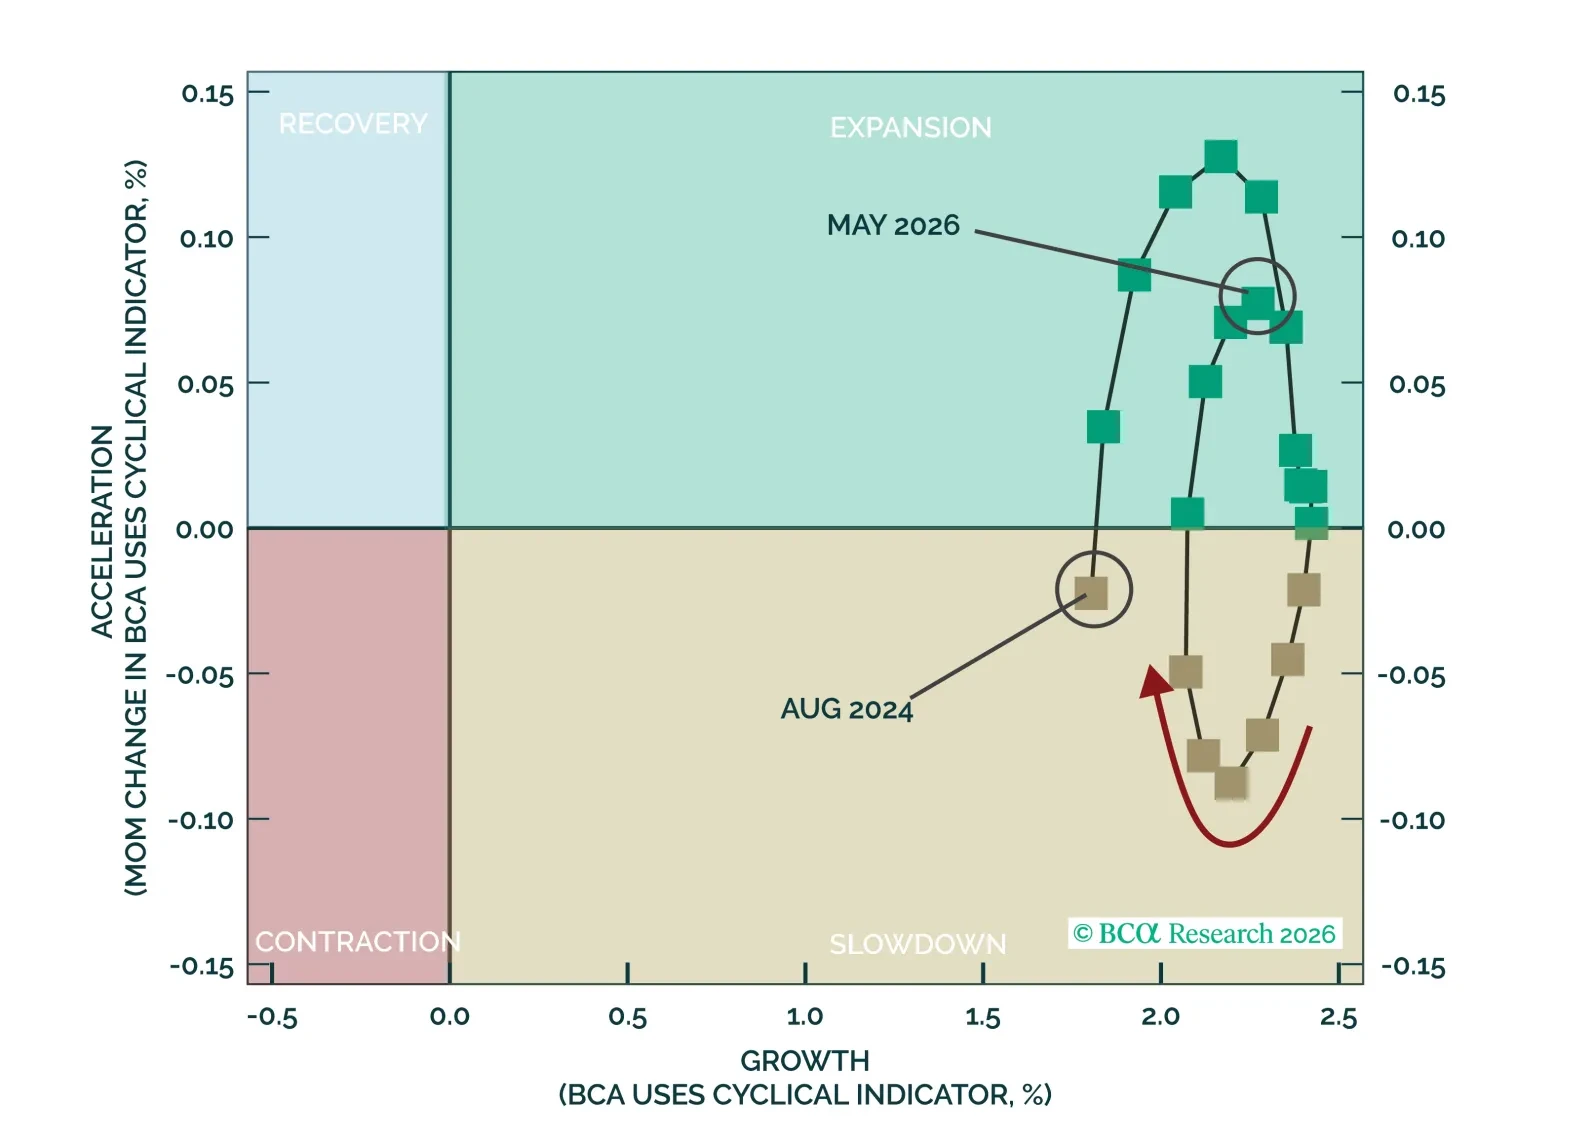
The economy has shifted into Expansion, earnings growth is broader and stronger than we expected, and we are raising our 2026 S&P 500 target to 8100 on $330 of EPS. However, we are also cutting our year-end multiple to 24.5. From here, returns will need to come from earnings growth, not multiple expansion.
The June swoon looks like a rotation and rebalancing-driven air pocket, not a regime break. Economic growth, earnings revisions, and AI-driven capex demand remain firm, but rising yields, inflation concerns, Fed uncertainty, and a looming IPO wave are likely to constrain further multiple expansion. But progress toward a resolution of mid-east tensions, rallying bonds, and falling oil prices, have motivated us to add a tactical long consumer discretionary trade.
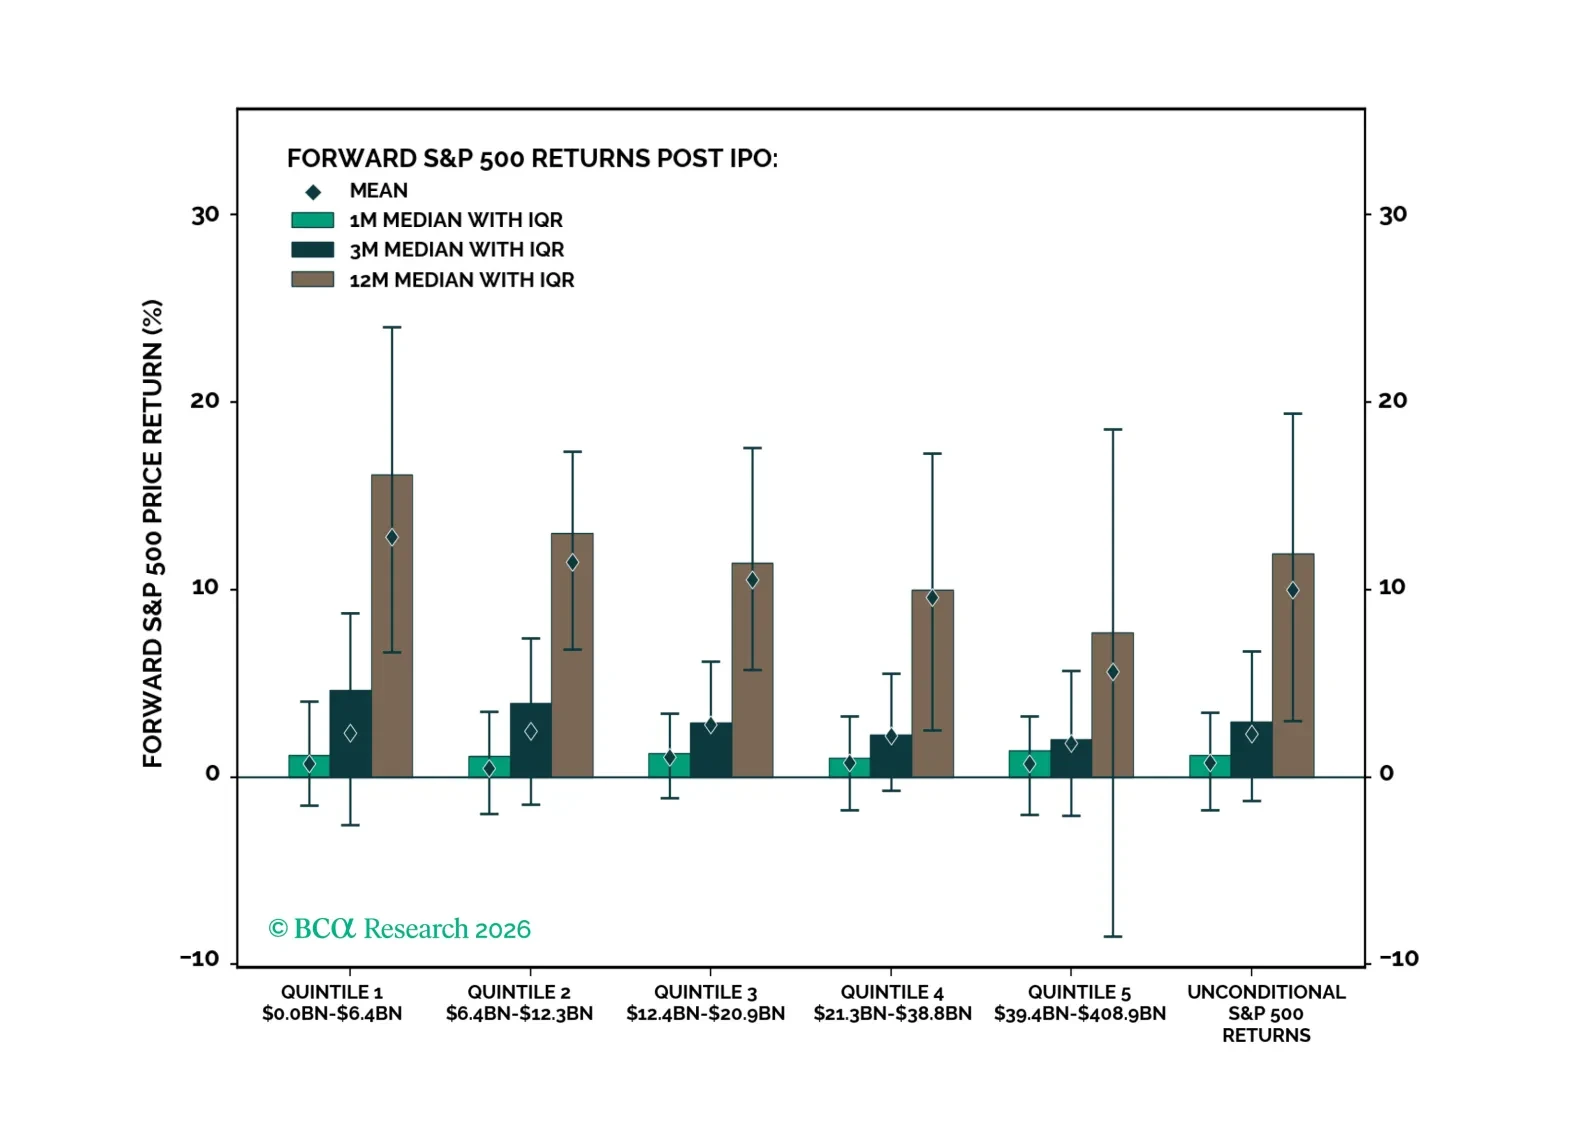
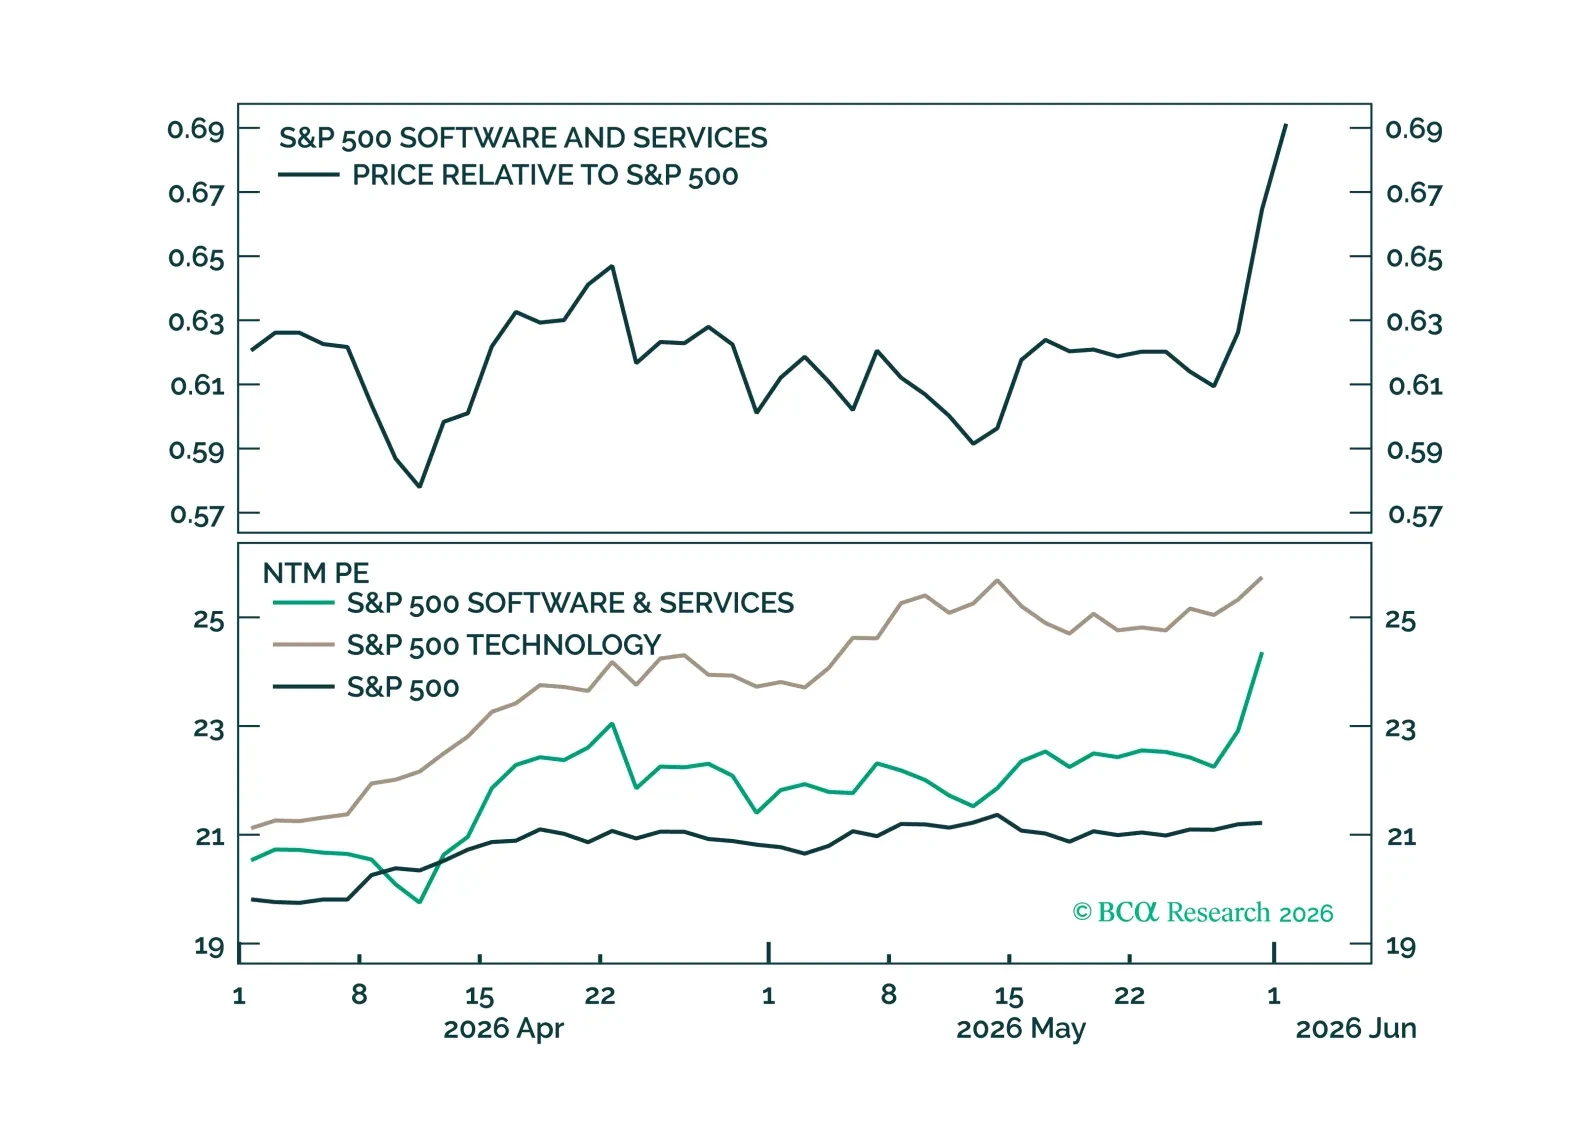
The US economy is moving back toward Expansion, supported by strong investment, improving earnings, and record margins. We are taking profits on our tactical Software long after achieving our target and rotating into Materials, where commodity strength and earnings momentum continue to support the sector.
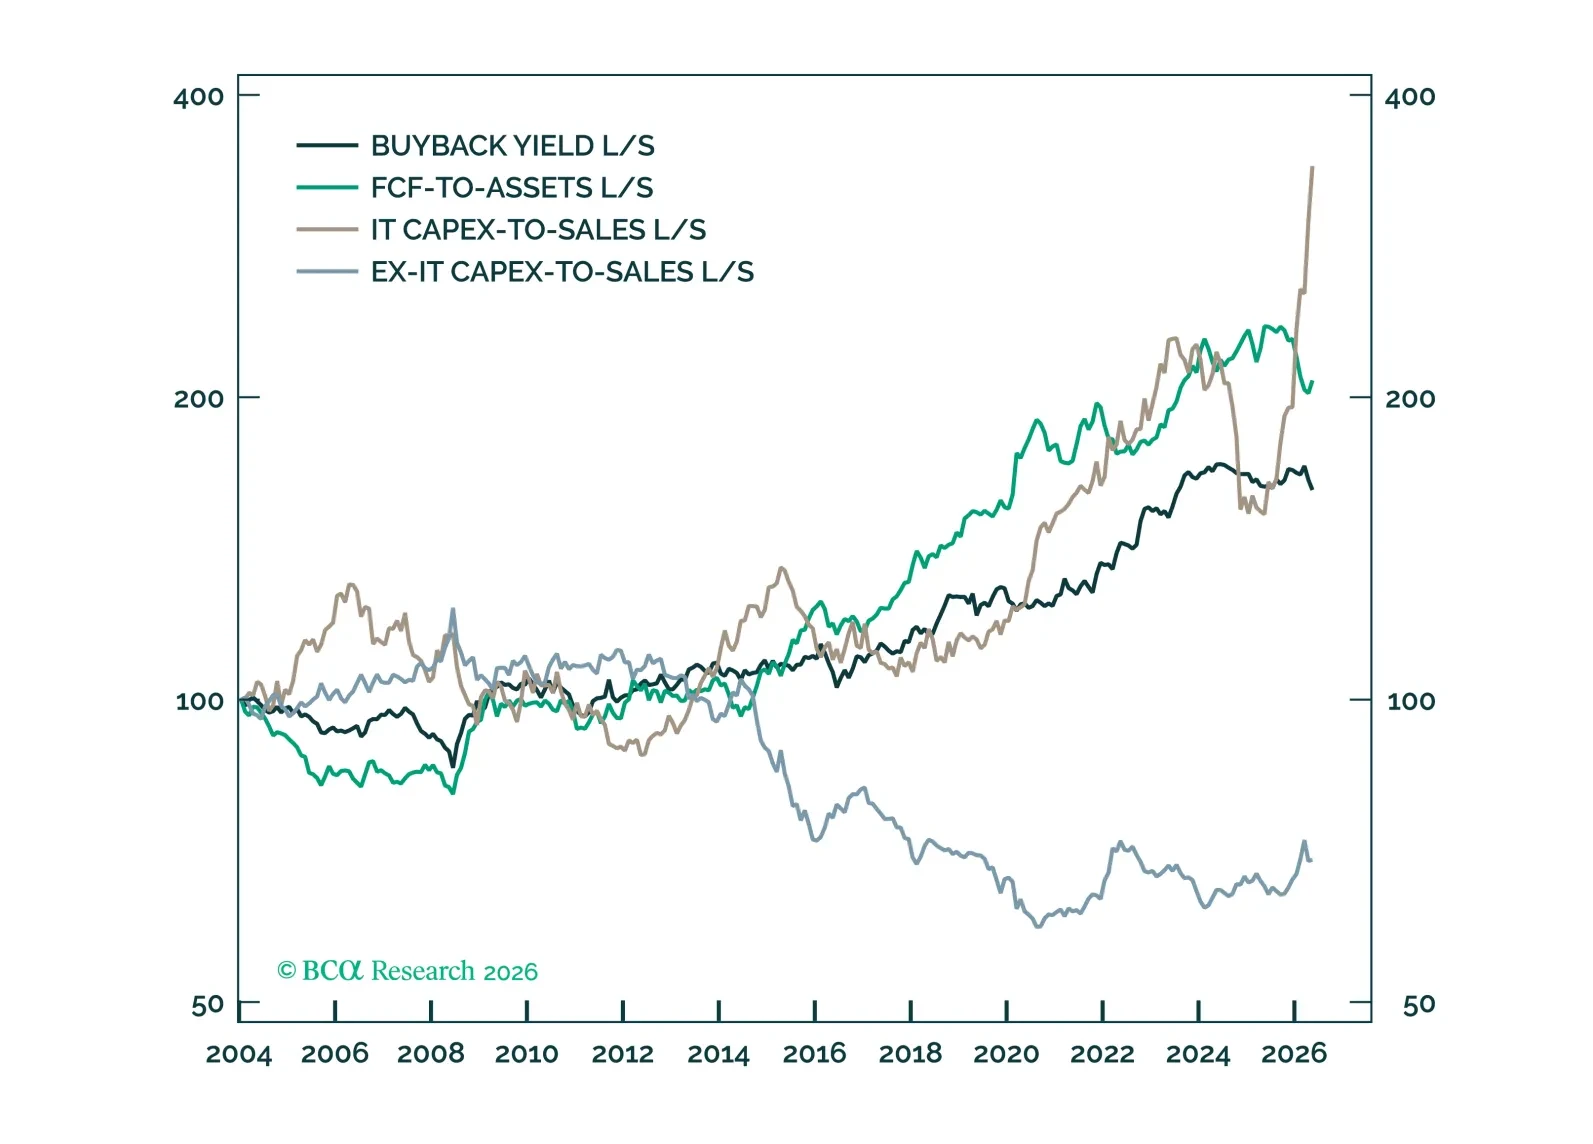
Tech, and increasingly the market, is moving from a cash-return regime to a reinvestment regime. After the GFC, investors rewarded companies that returned cash to investors. In the AI cycle, they are rewarding companies that put that cash back to work. This is not just a story of falling free cash flow; it is the mirror image of a market rewarding reinvestment. Tech has defined both regimes, revealing the old cash-flow “stars” as sector bets masquerading as alpha.
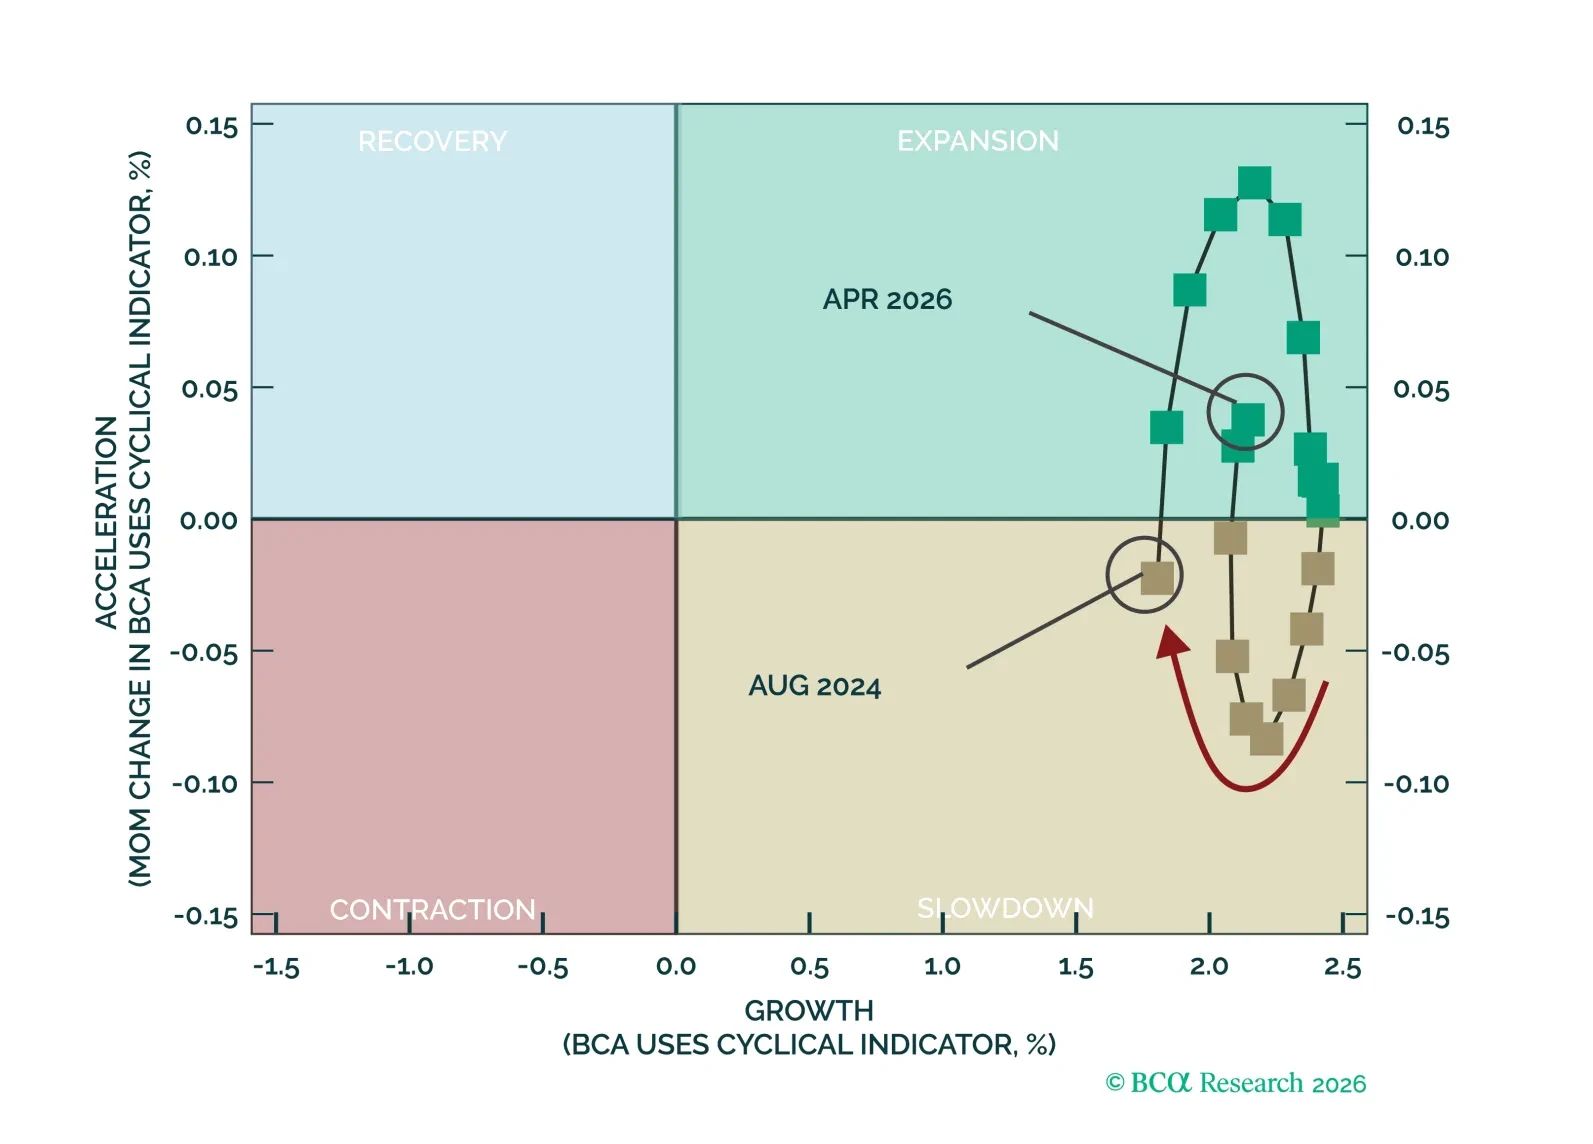
US growth remains positive and is now improving, with the economy seemingly exiting Slowdown and proceeding into Expansion. Markets are reflecting the shift, rewarding revenue growth and capex growth, while earnings expectations continue to advance. The backdrop remains supportive, but expectations are rising and risks from financial conditions linger.
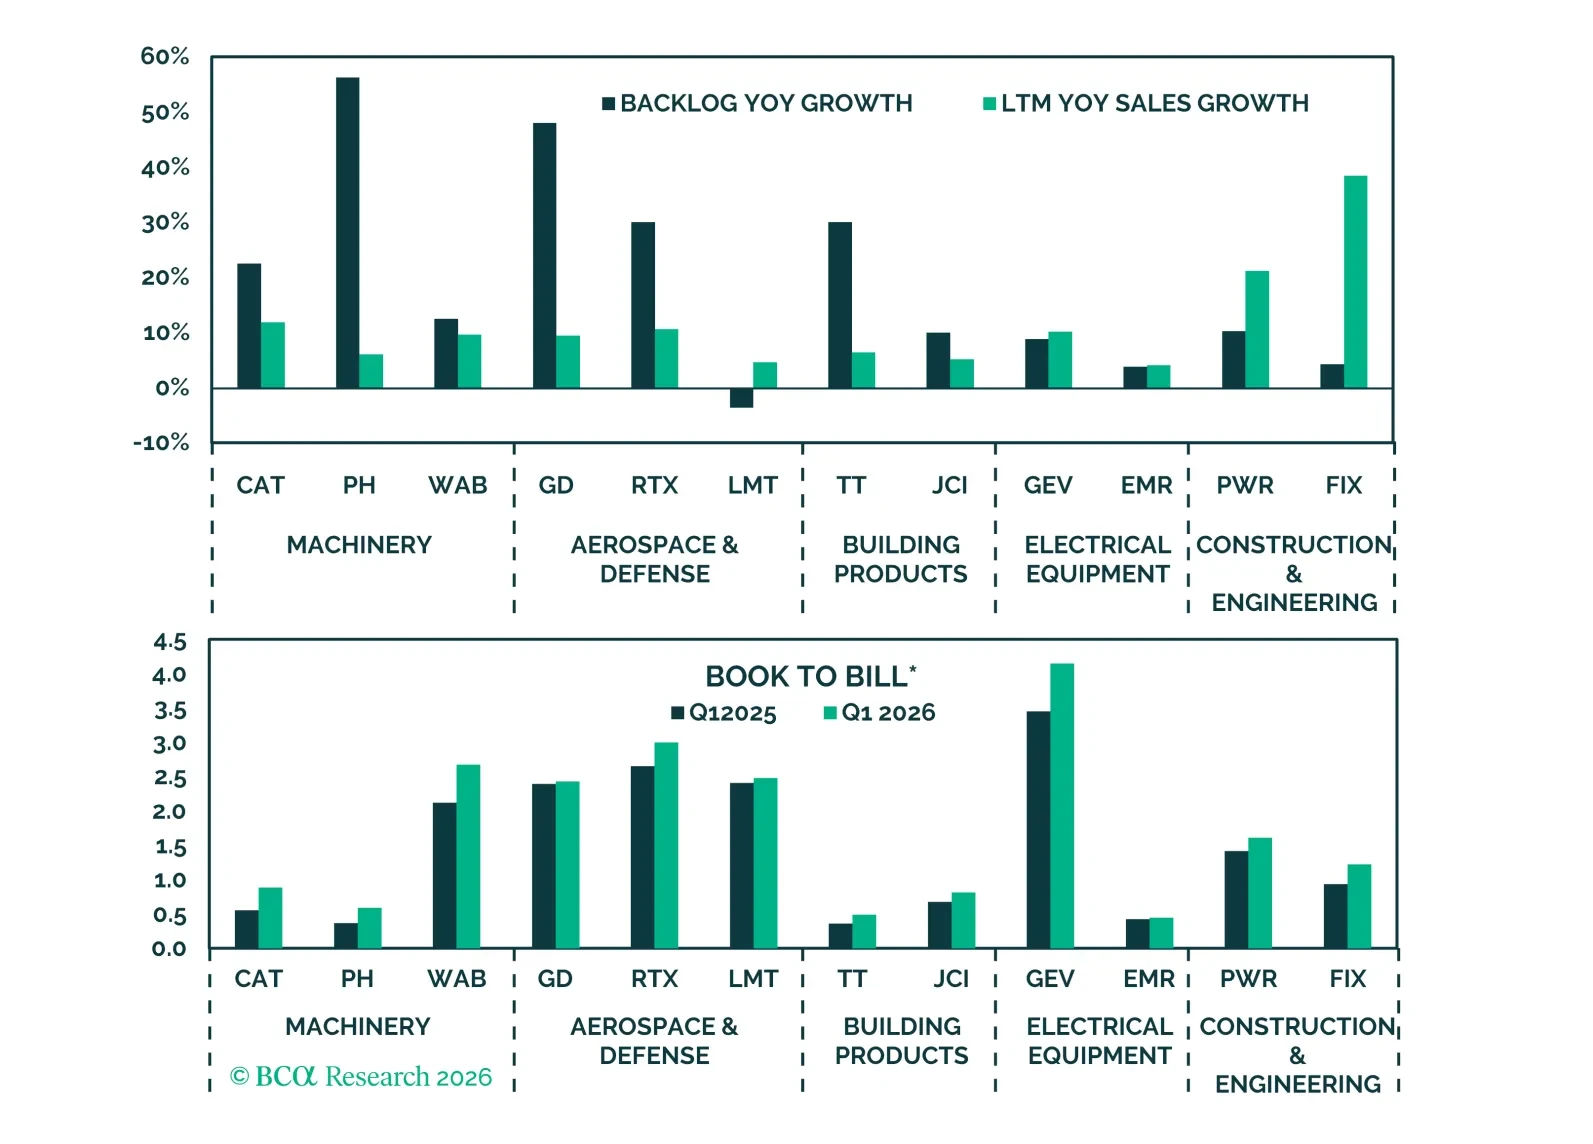
The investment cycle remains firmly intact, driving equity prices and fundamentals, as confirmed by both Q1 data and corporate commentary. Upside surprises, expanding margins, and rising capex expectations point to resilient demand. Companies confirm that AI-related demand is broad and visible, while geopolitical and credit risks remain contained and not yet systemic.
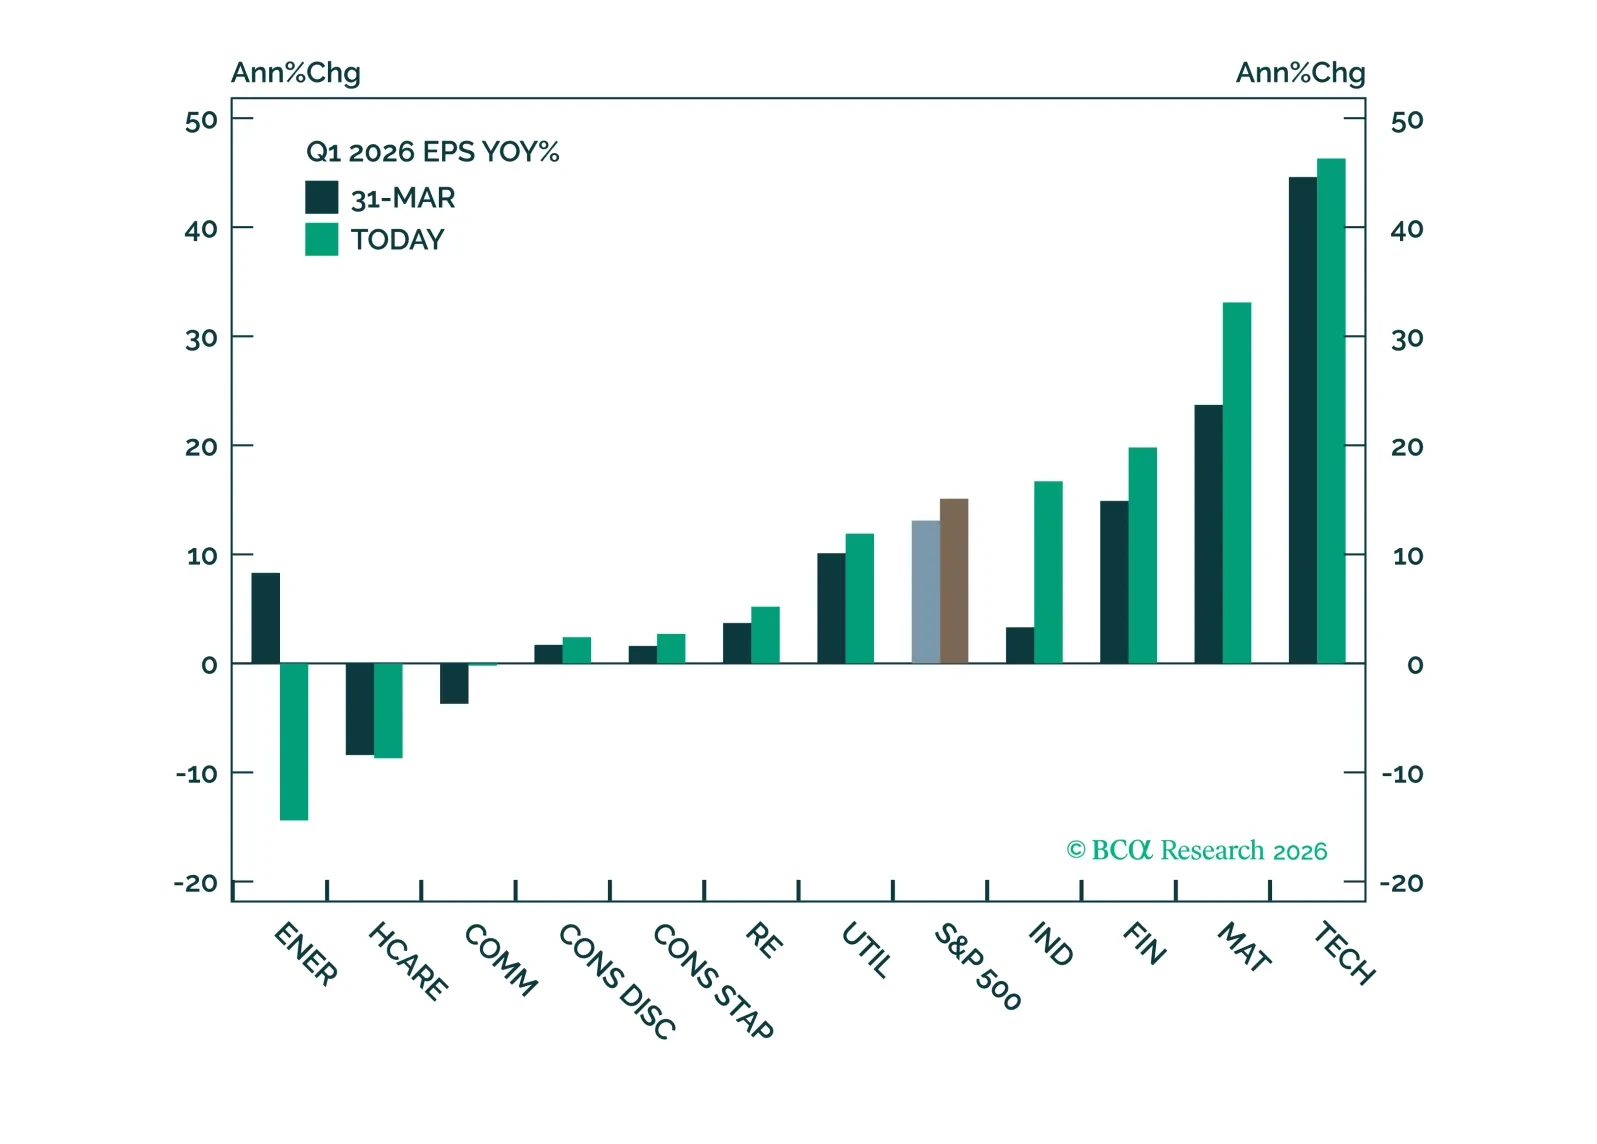
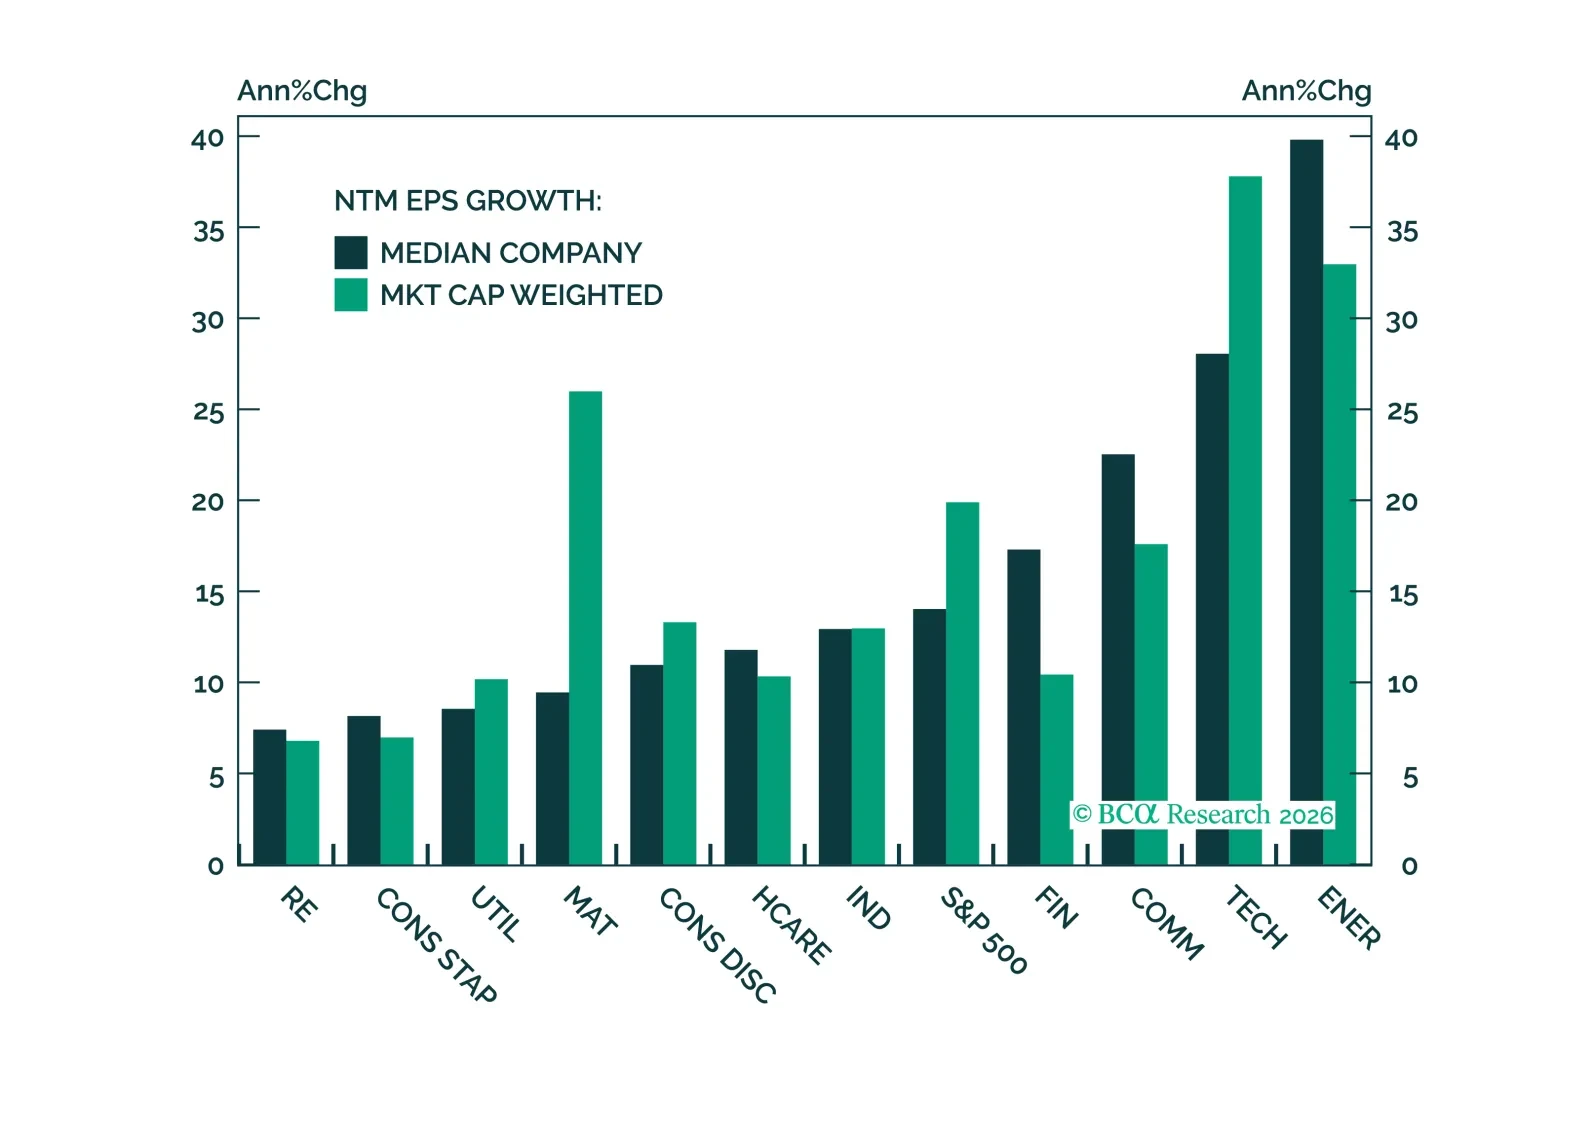
Leadership has rotated toward investment-driven sectors, reflected in both EPS growth and price performance. Expanding margins suggest the cycle may have longer to run, as productivity gains start to work their way through fundamentals. We continue to see upside for the S&P 500, with no change to our sector outlook.