 Equities
Macro, fundamental, and quantitative analysis translated into actionable equity views across sectors, factors, themes, and baskets.
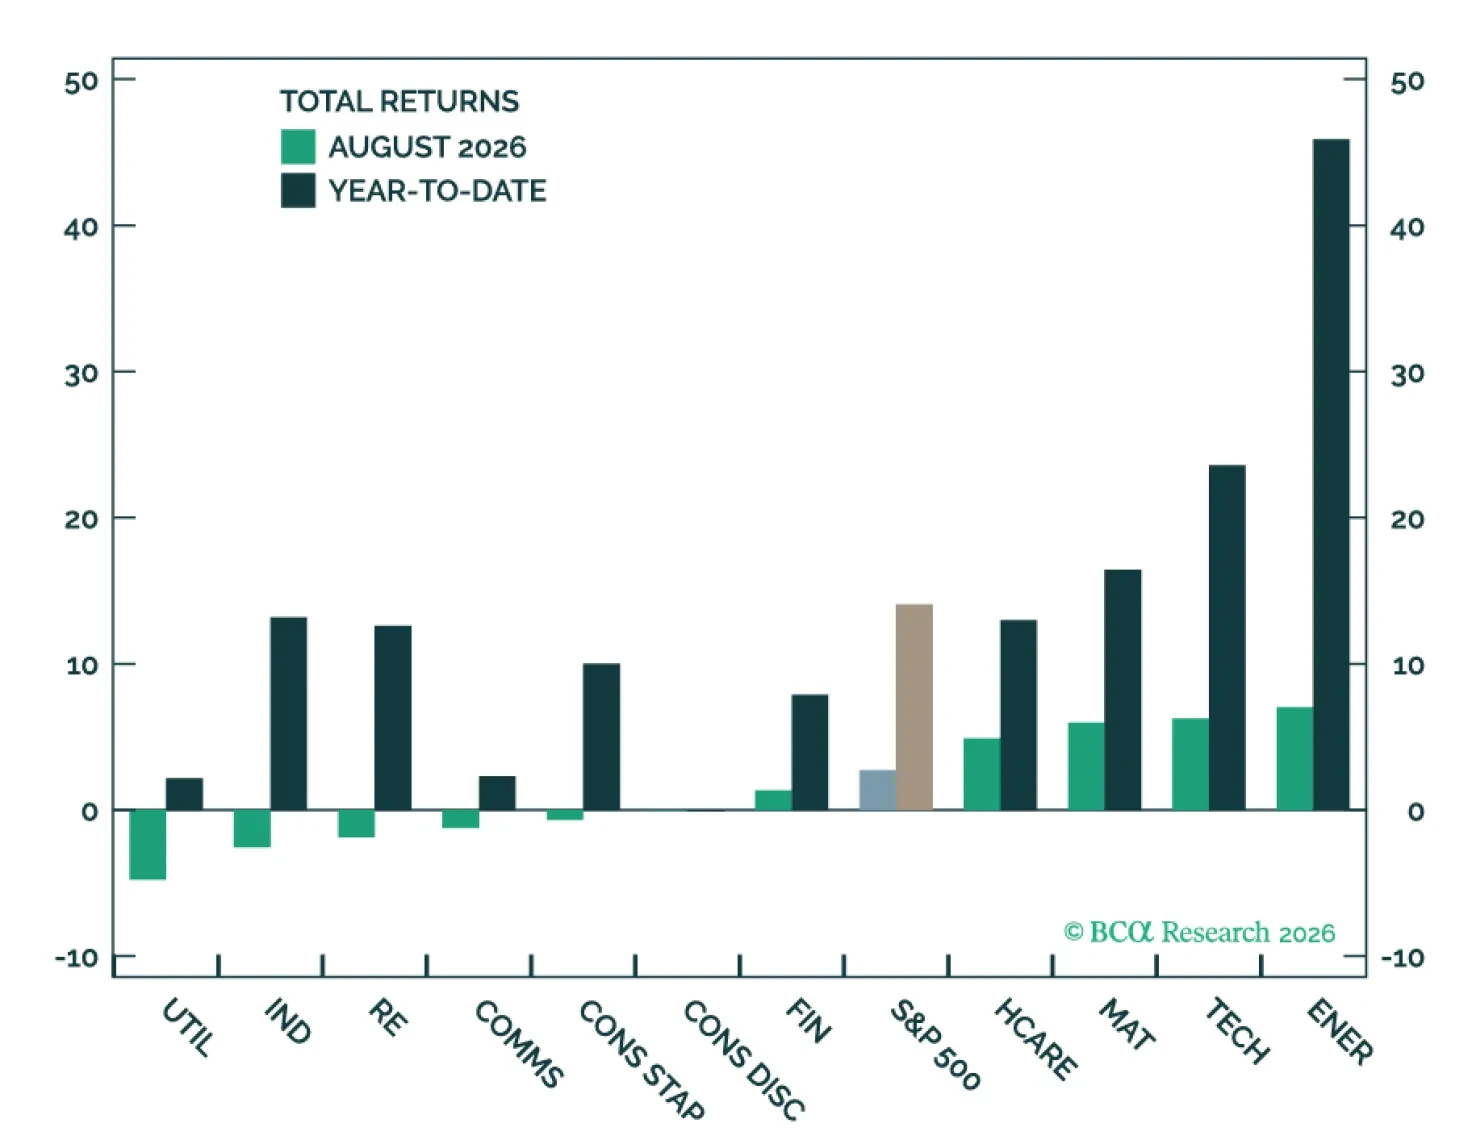
Strong second quarter earnings suggest that the AI story is intact. Buoyed in part by this strength, tech stocks have recoupled with healthy fundamentals after a late-July swoon, posting solid August gains. We continue to see upside for the S&P 500, favoring the cyclical and AI exposure of tech, materials, and industrials. But rising bond yields remain the dominant headwind.
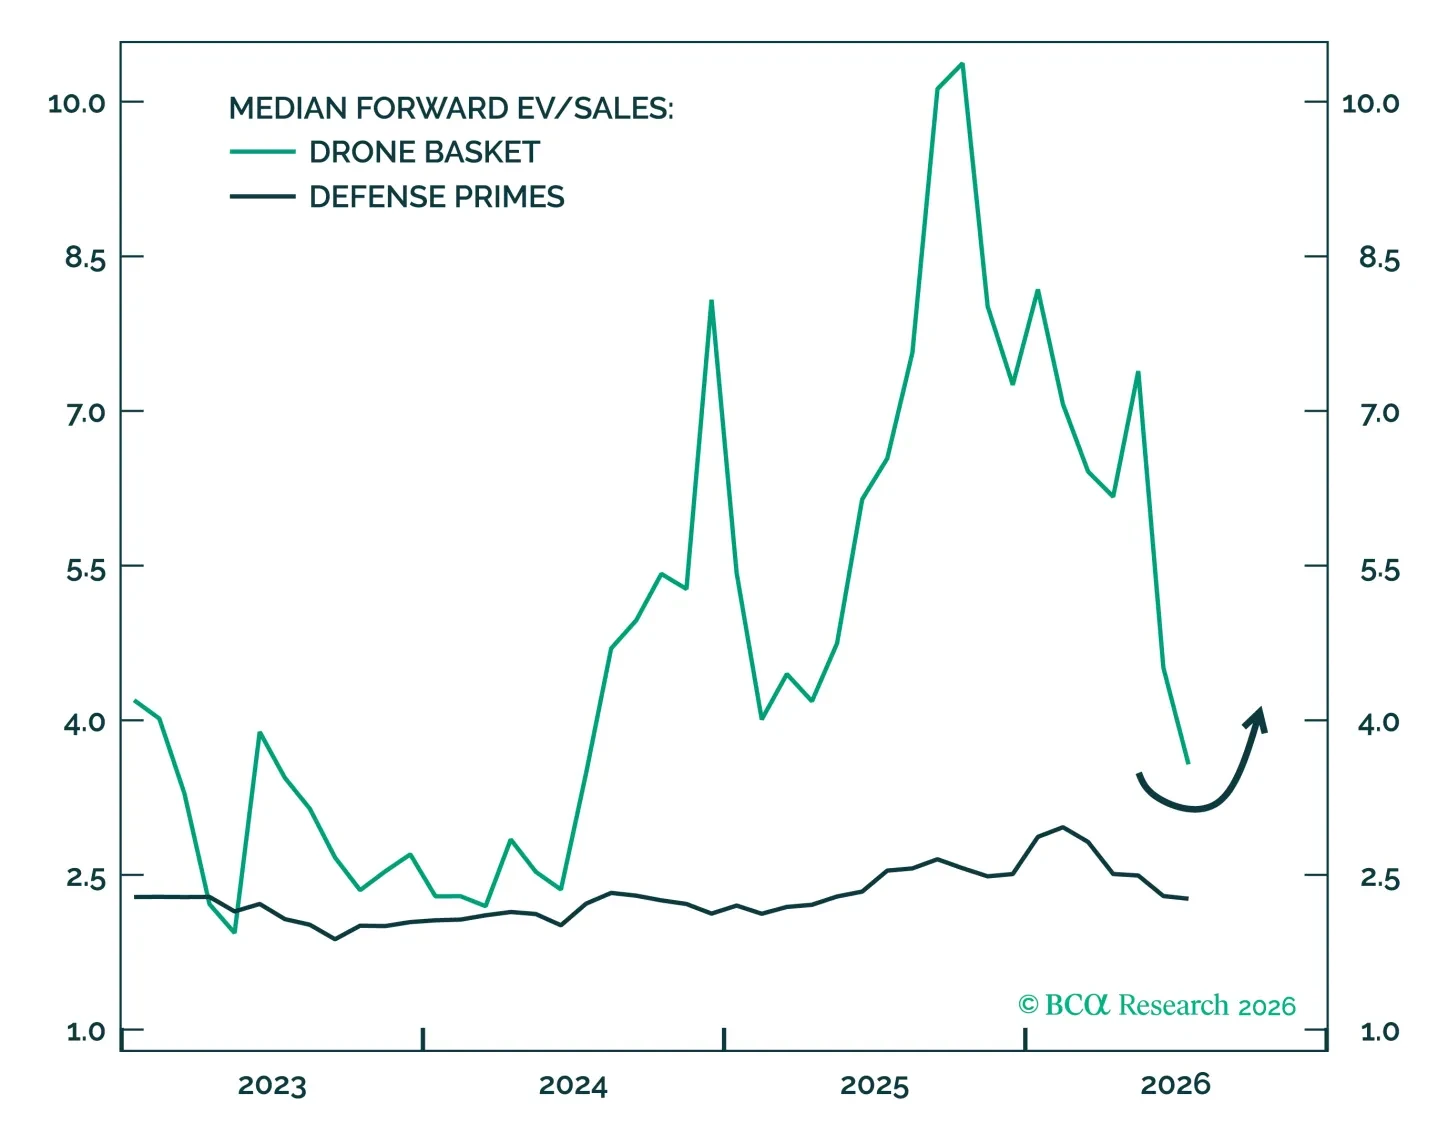
US aerospace and defense stocks still have a structural tailwind from geopolitics, but face rising cyclical challenges from macro and market fundamentals, as well as eventual Iran and Ukraine ceasefires and political change in the United States.
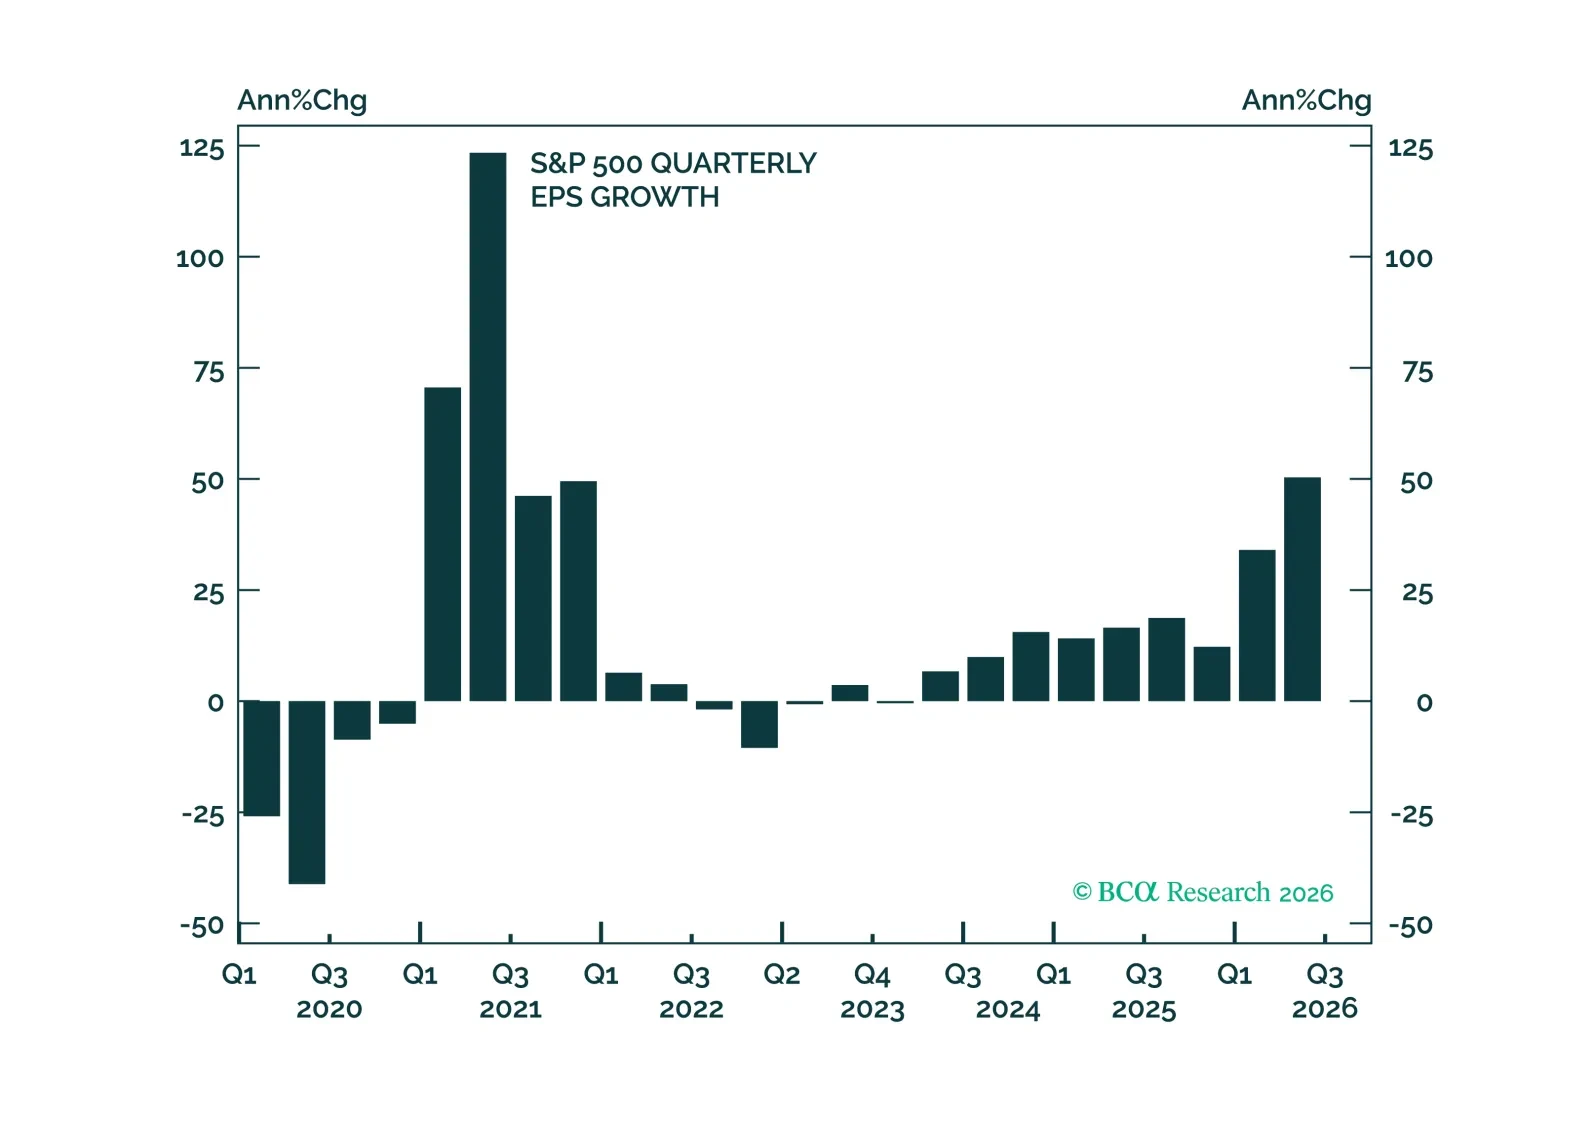
Q2 earnings confirm broad-based strength, but the bond market remains the key risk to equity multiples given today's positive stock/bond correlation regime. We close our tactical GDX long for a 16% gain, though we continue to view goldminers as a valuable structural hedge.
In this report, we explore opportunities in goldminer equities, AI infrastructure monetization, and Japan's tactical outperformance window.
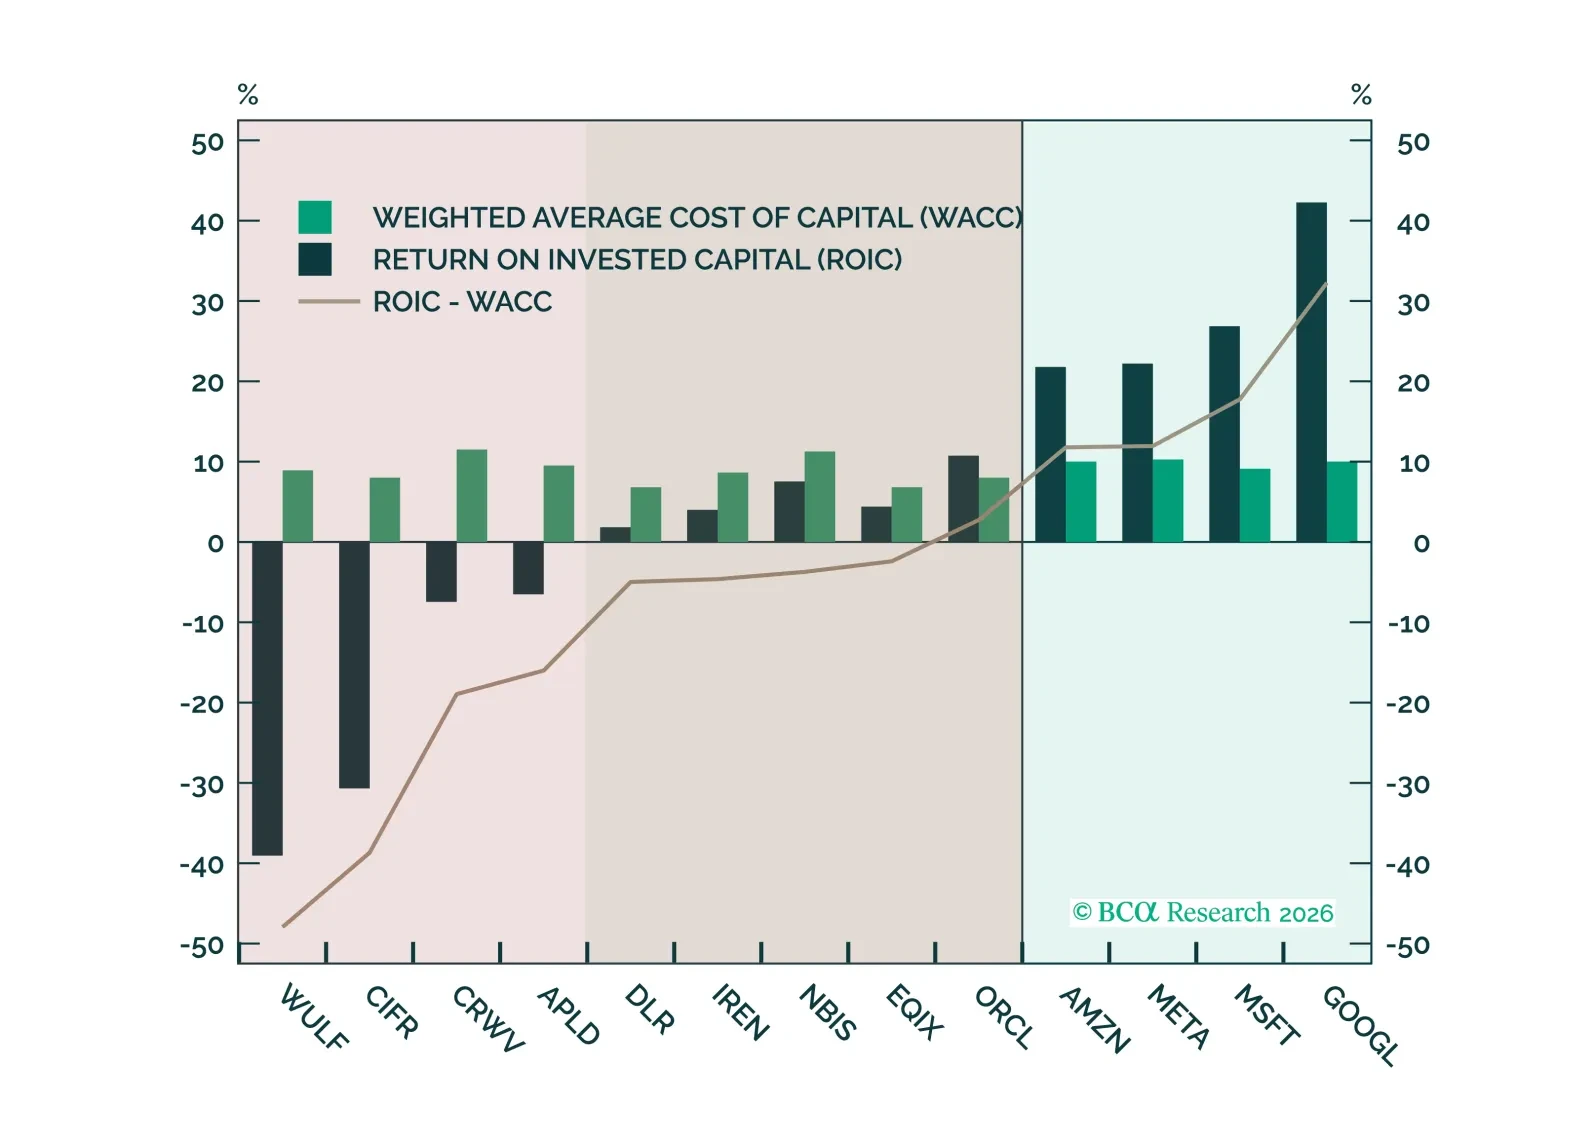
AI demand remains strong, but the capex boom is creating a growing divide within Tech. Hyperscalers combine superior margins, capital efficiency and financing capacity with multiple paths to monetize AI investment. Neoclouds rely more heavily on leverage and scarcity economics, potentially making them more vulnerable should capacity expand and compute pricing normalize.
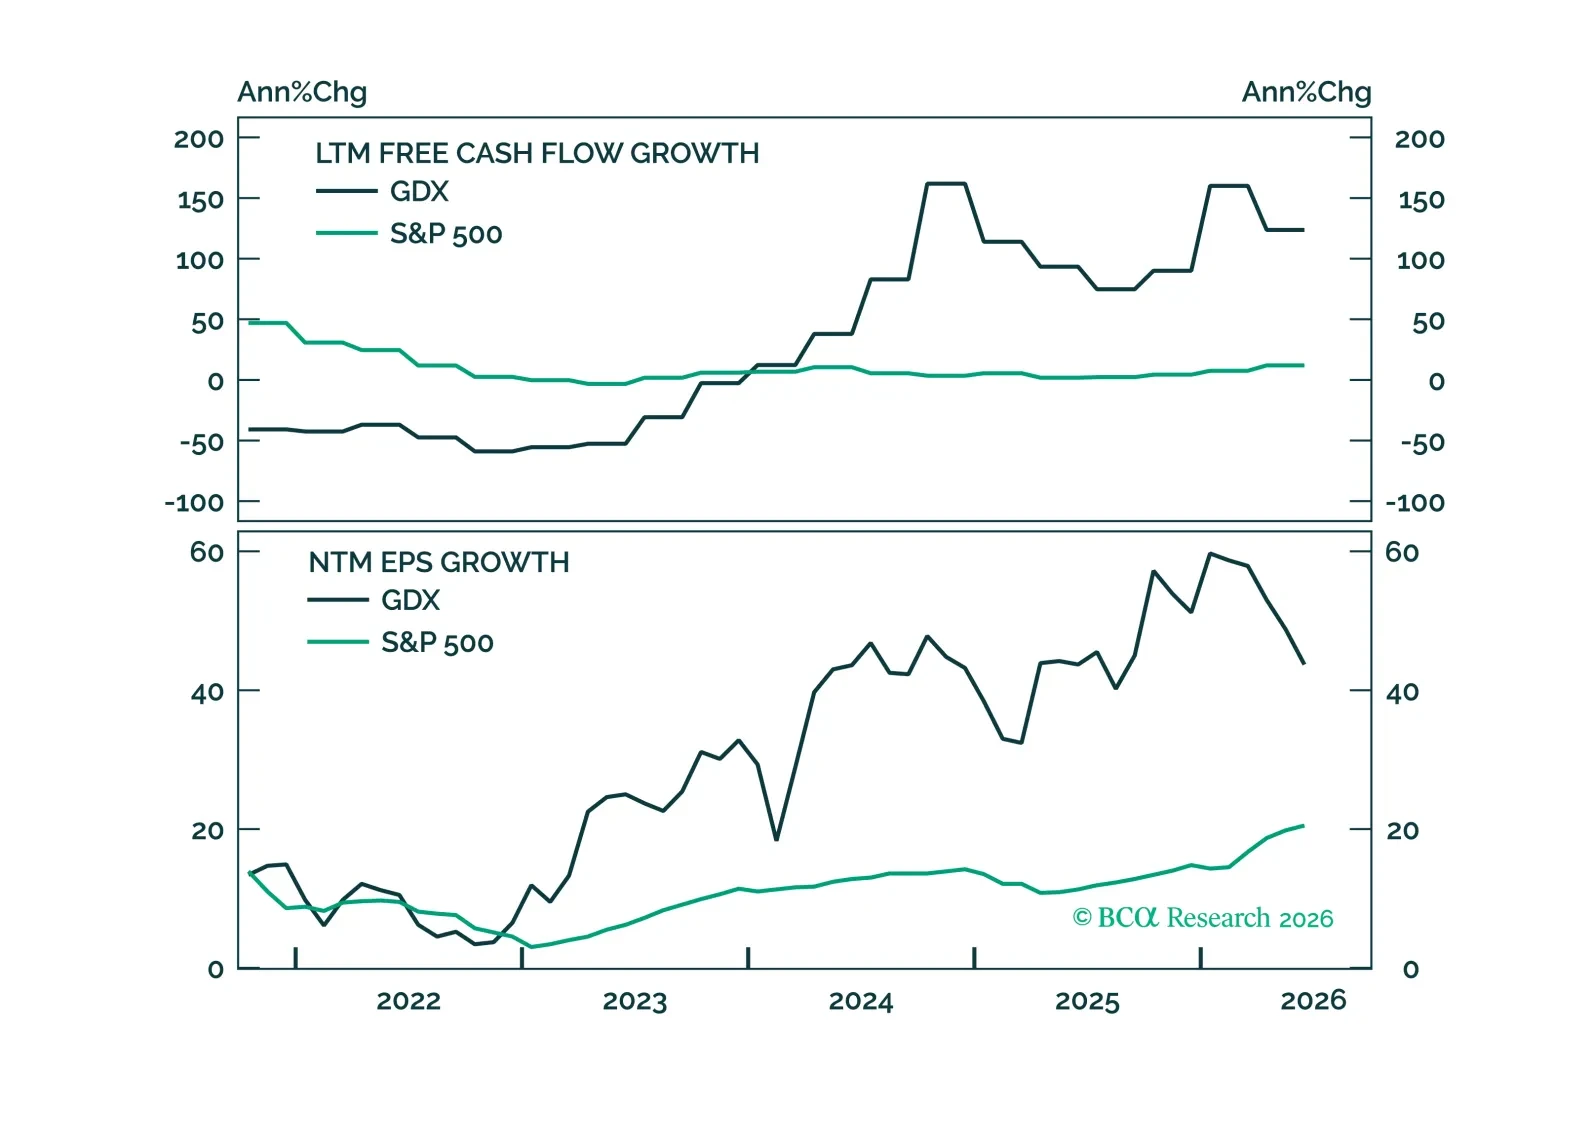
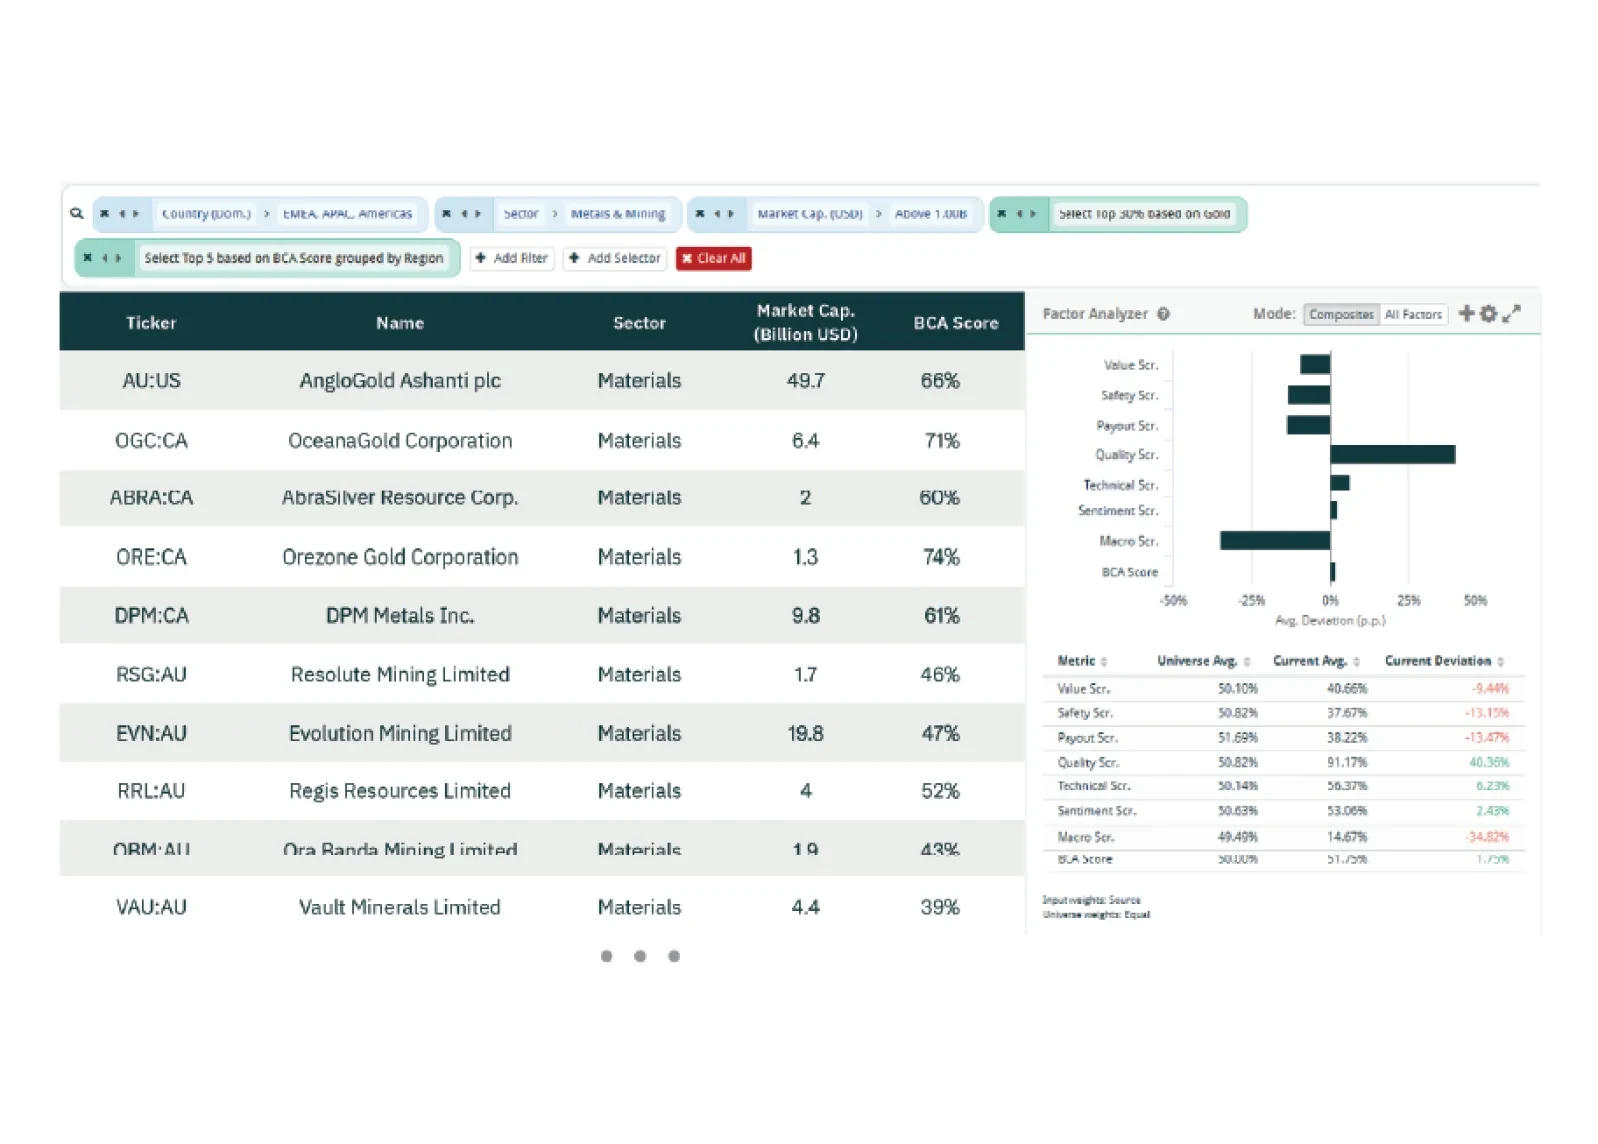
Gold and goldminers have corrected 25% from January highs. With our commodity team bullish gold, we are getting long GDX. Goldminers offer a gold-linked hedge against macro outcomes that would likely be damaging for equities, while improvements in profitability, capital discipline, and balance-sheet quality make the sector attractive in its own right, and it is largely independent of AI risk.
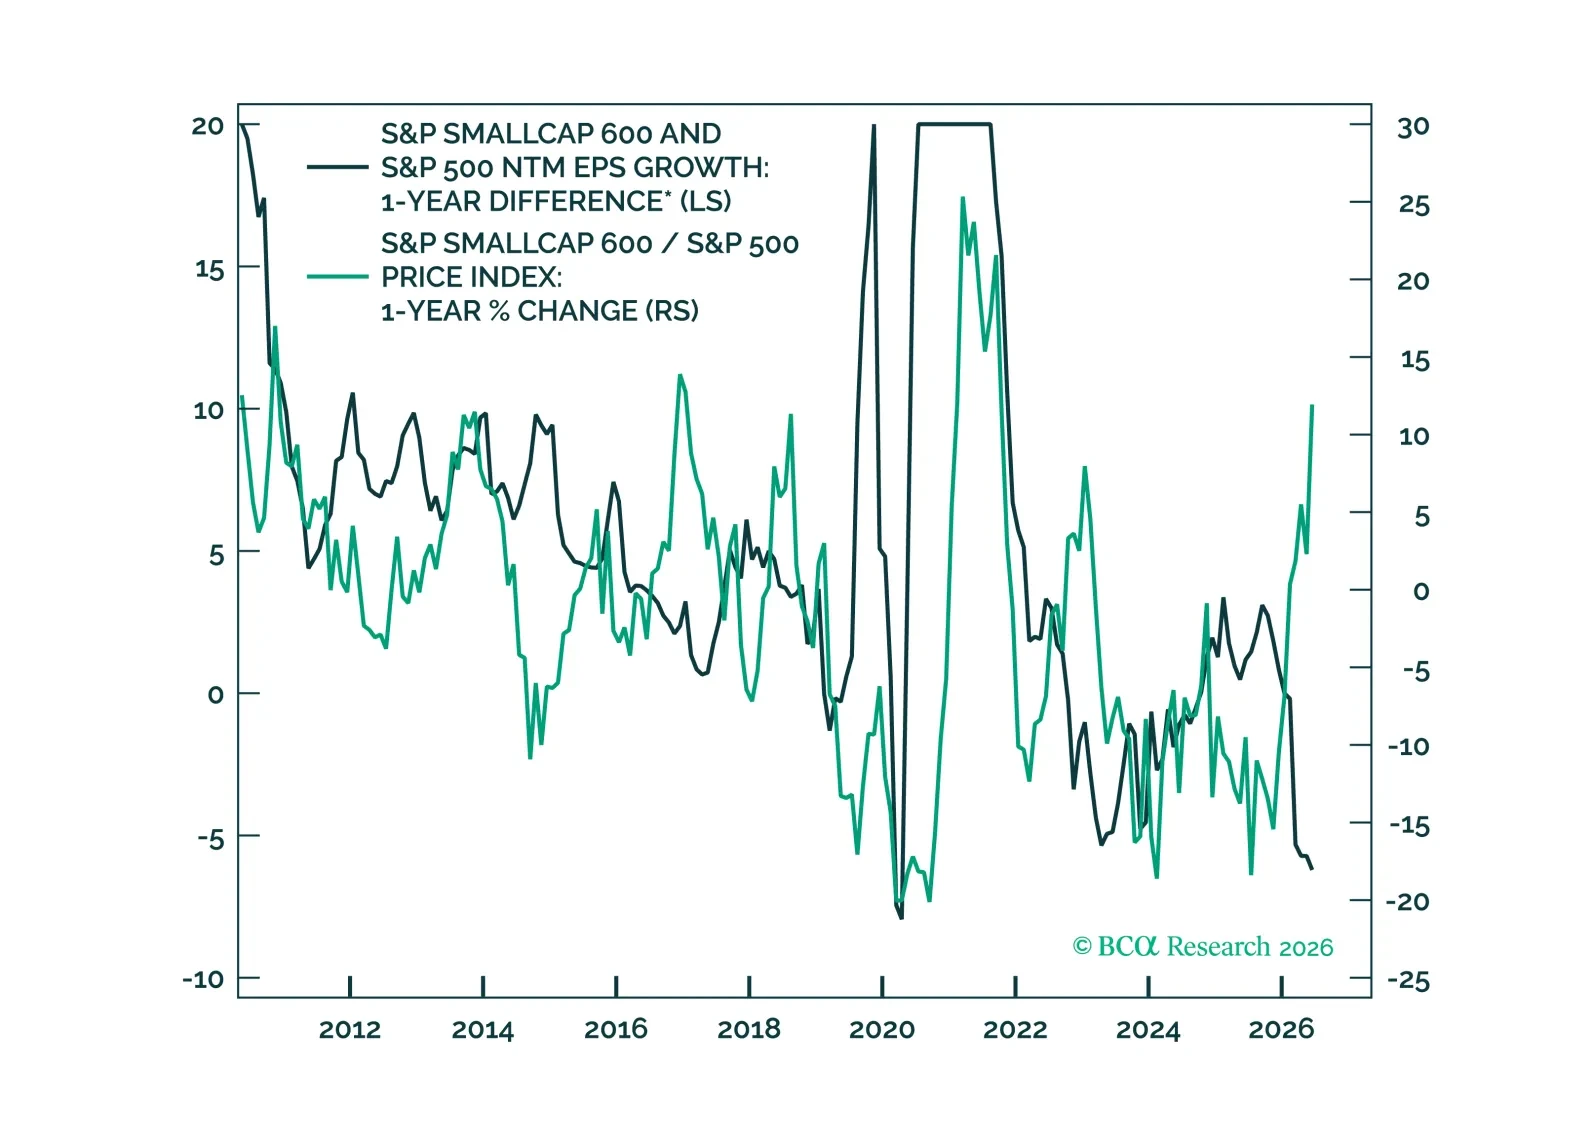
Small-cap outperformance has been driven mostly by within-sector stock selection, not differences in sector weighting. With the small-cap earnings catch-up reversing and leverage rising, we would fade the low-quality small-cap rally. We still want cyclical and AI exposure, but through higher-quality large caps rather than highly levered small-cap Tech. We are also opening a small-cap Health Care trade as an idiosyncratic way to gain exposure to the M&A cycle.
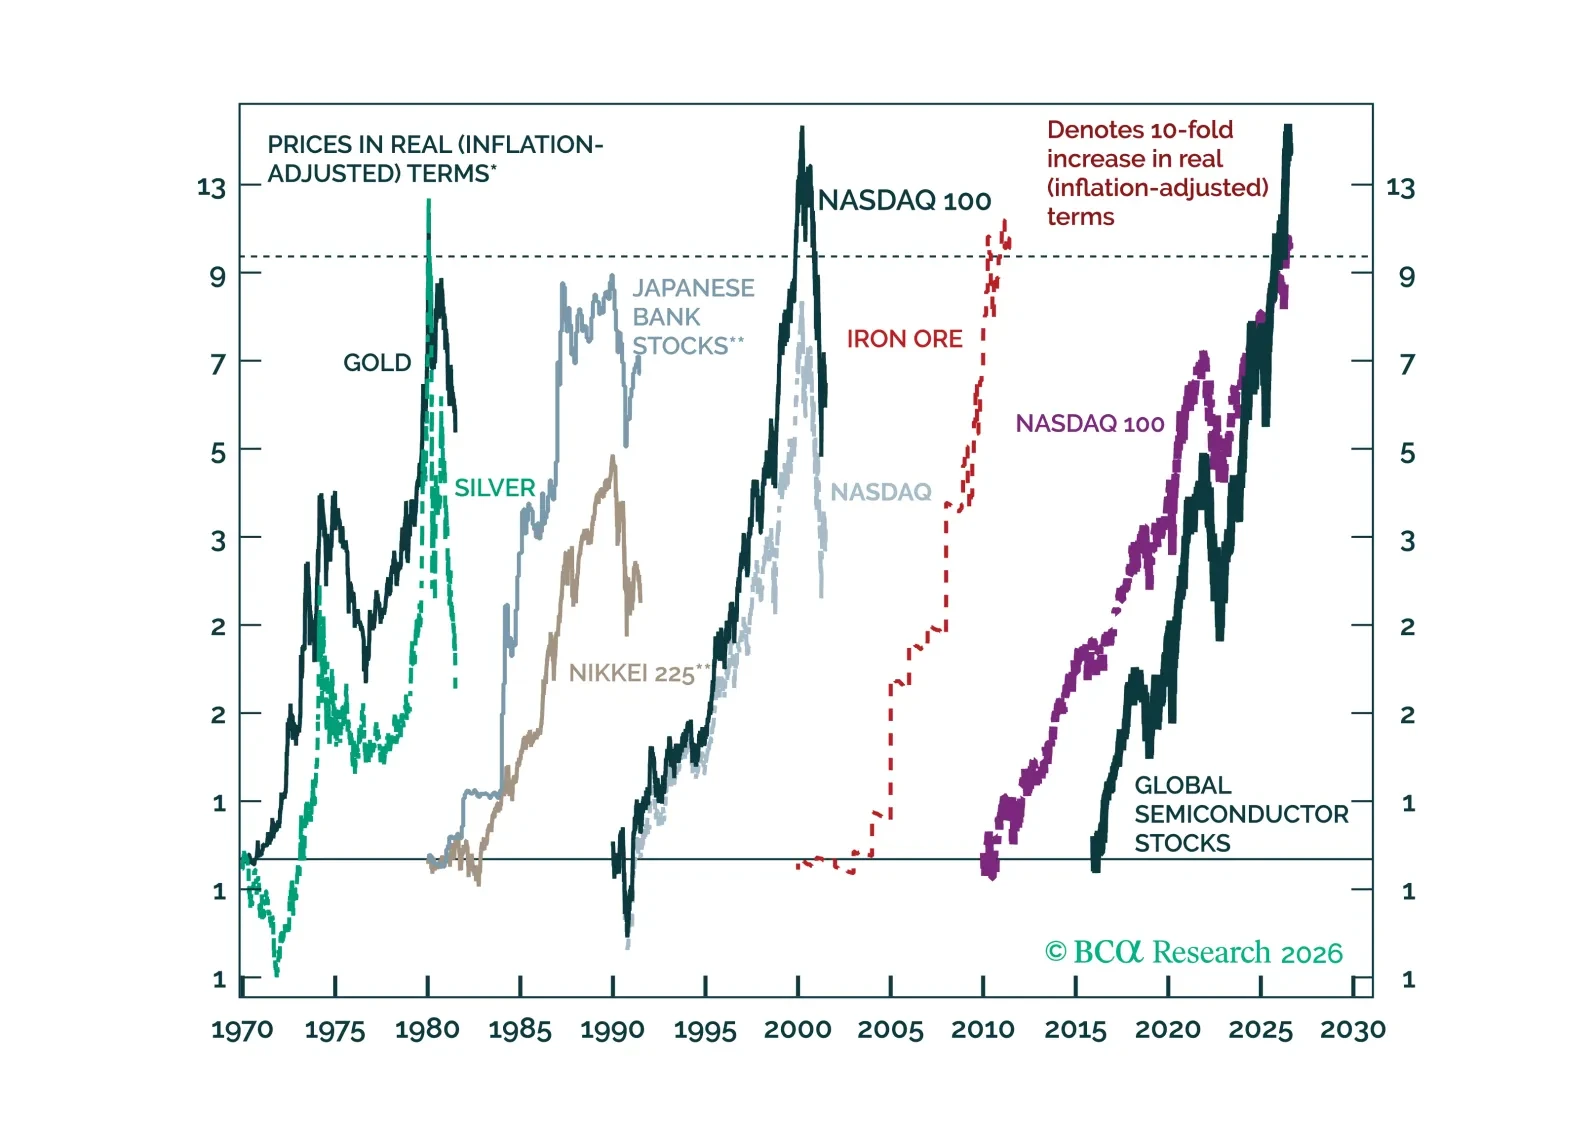
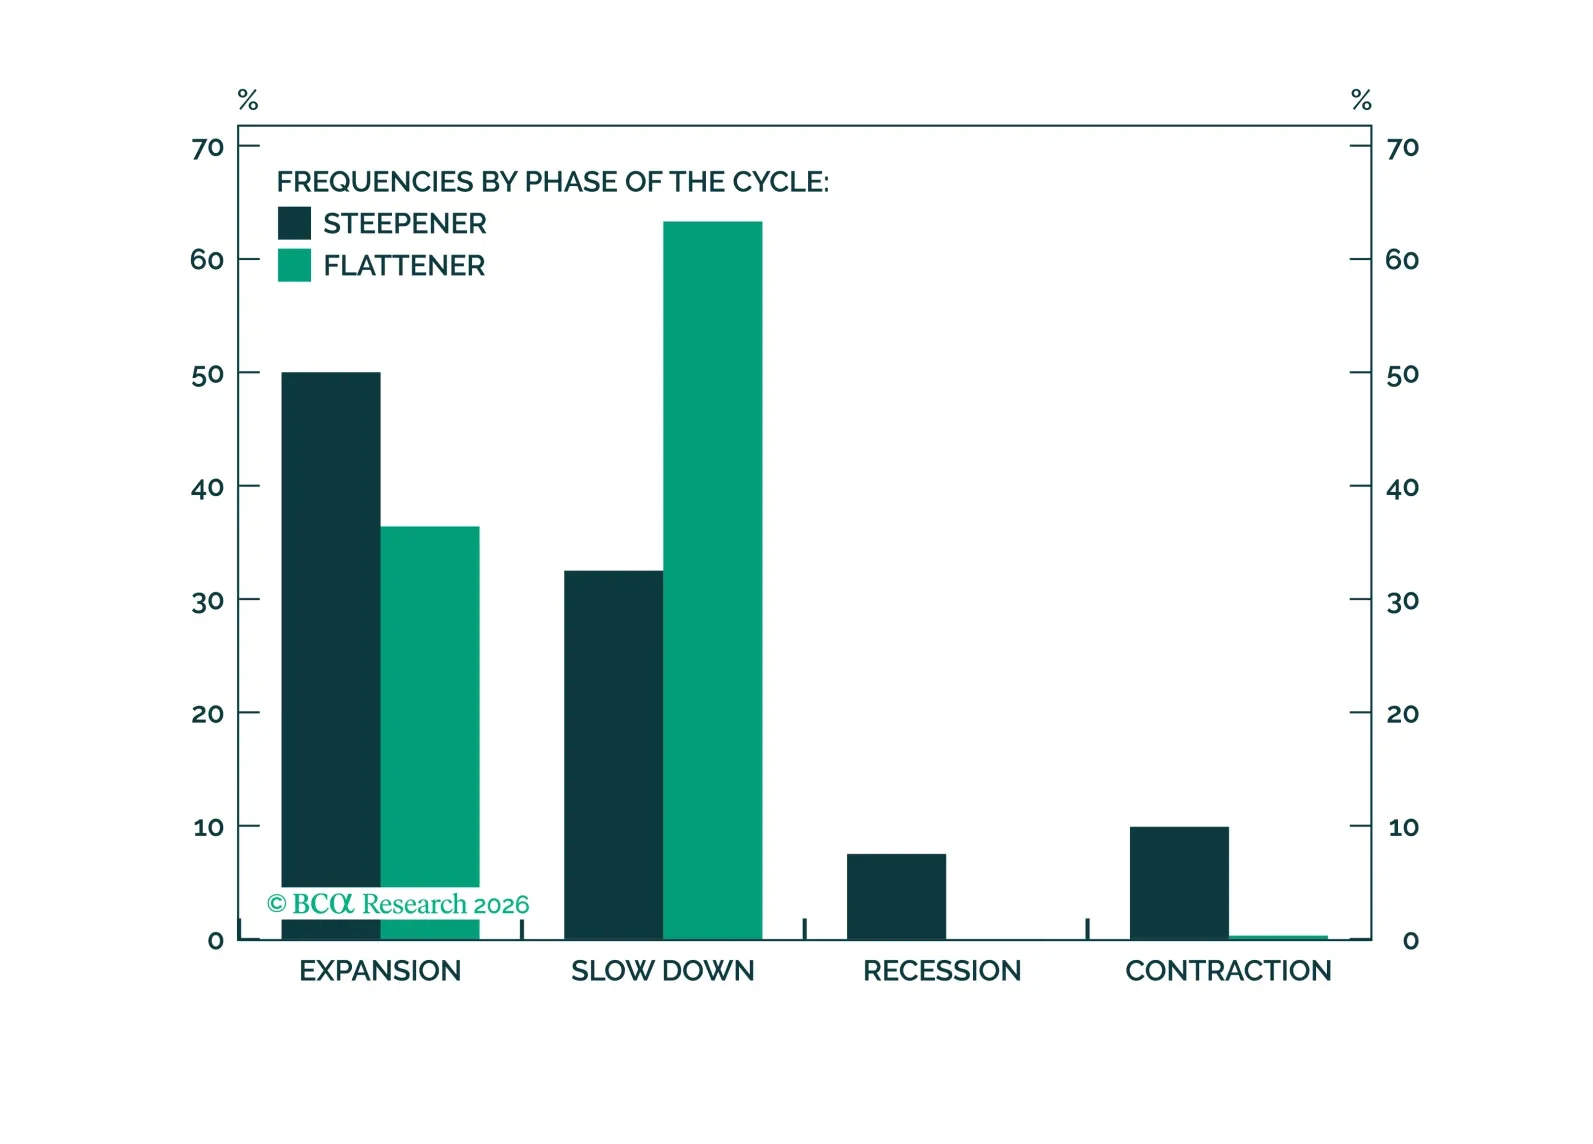
History suggests that the equity impact of rate moves depends heavily on the stock/bond correlation regime, and today’s positive correlation regime leaves the bond market as the main risk to equity multiples.
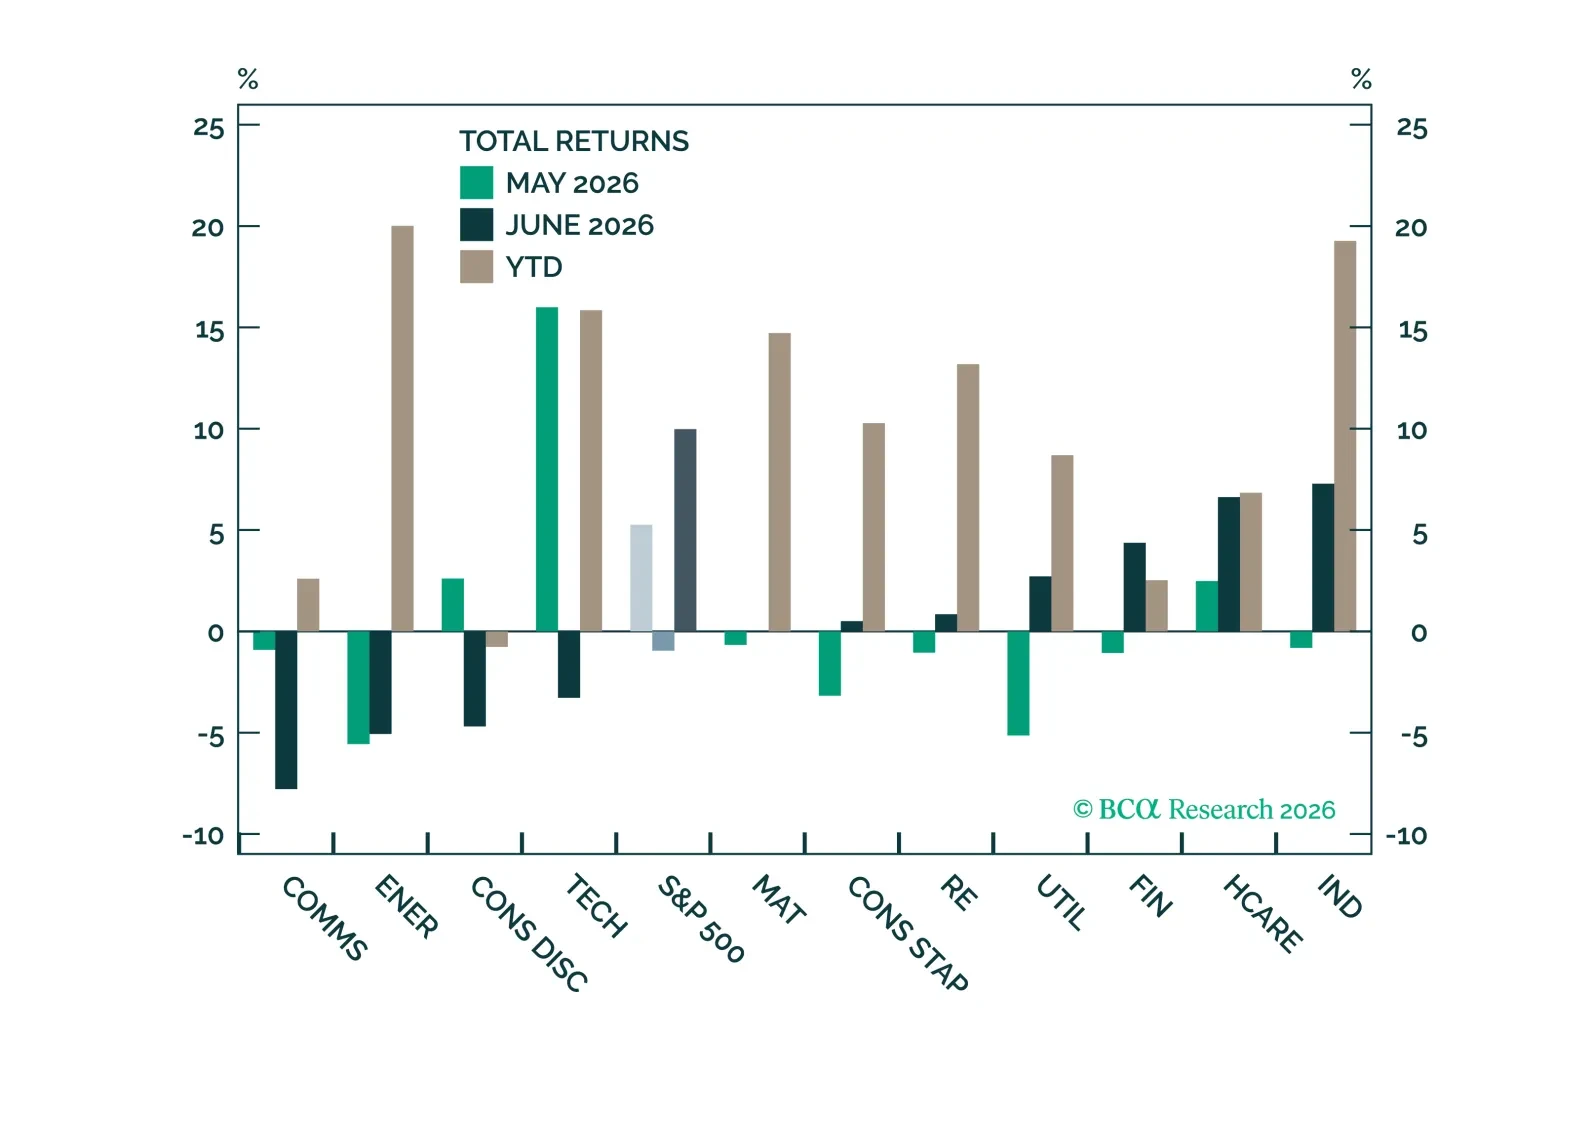
S&P 500 performance rotated in June, but fundamental growth remains strong across sectors, with earnings and revenue growth extending well beyond the largest mega-cap companies.