 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
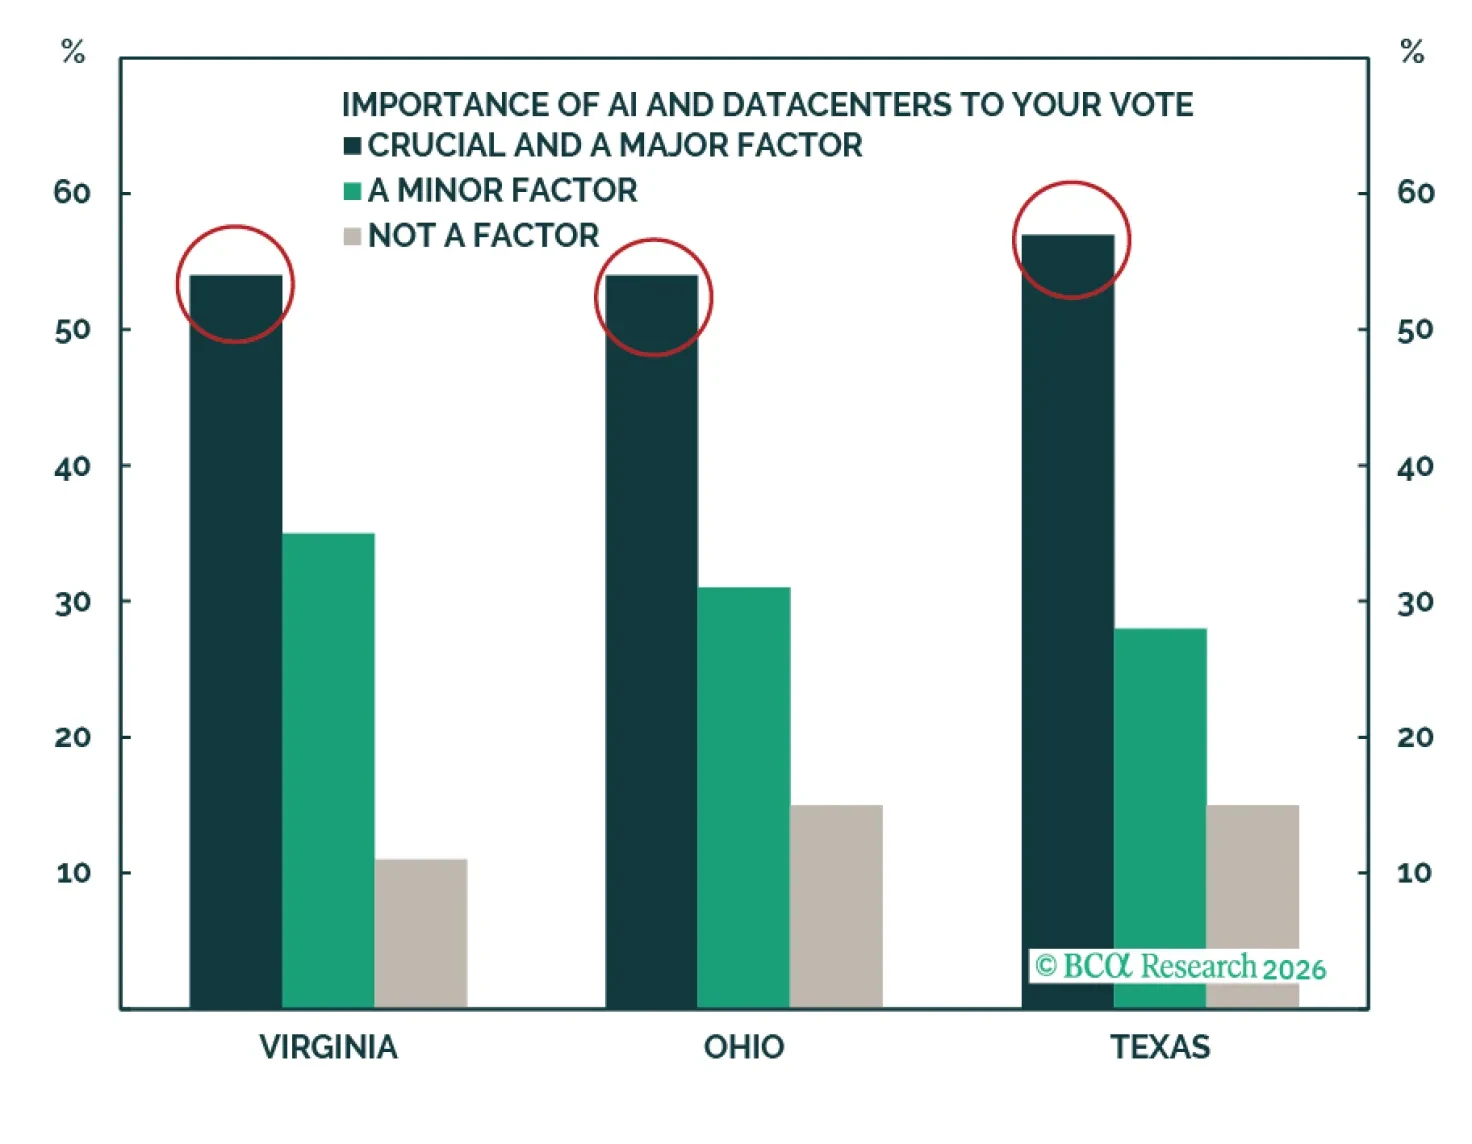
Fears of AI regulation are overblown after the US midterms. But some regulation will pass – and data centers will need to generate their own electricity.
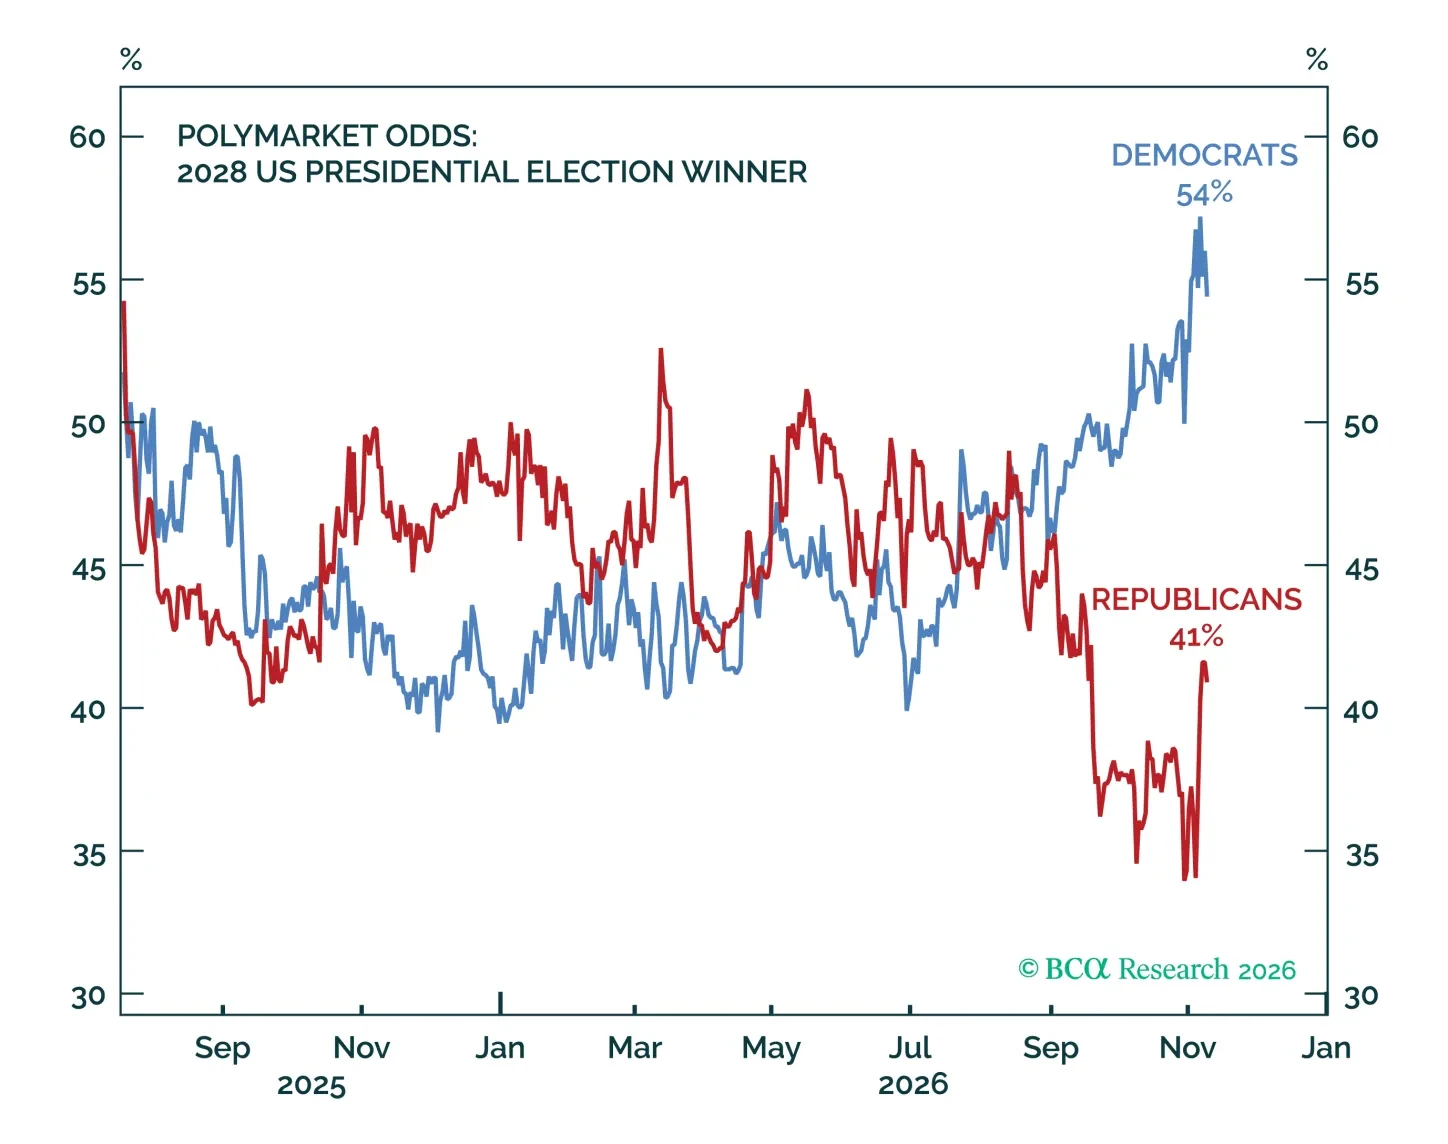
The massive Democratic sweep we were concerned about, from the market perspective, has arrived. In the long term, the move towards more regulation and higher taxes complicates the US equity bull market. In the short term, it also complicates President Trump's war in Iran. As such, we are short oil, long bonds, and long equities, for the time being. But the AI capex story, which remains strong on fundamental ground, is getting tougher to cheerlead with political headwinds ahead.
On October 13, we asked what would happen “if Gina wins?” Gina Hinojosa, a Democratic state legislator from the traditionally Republican-voting Texas, was at the time given only a 1-in-5 chance of winning the state’s governorship, despite being tied in the polls with the conservative incumbent.
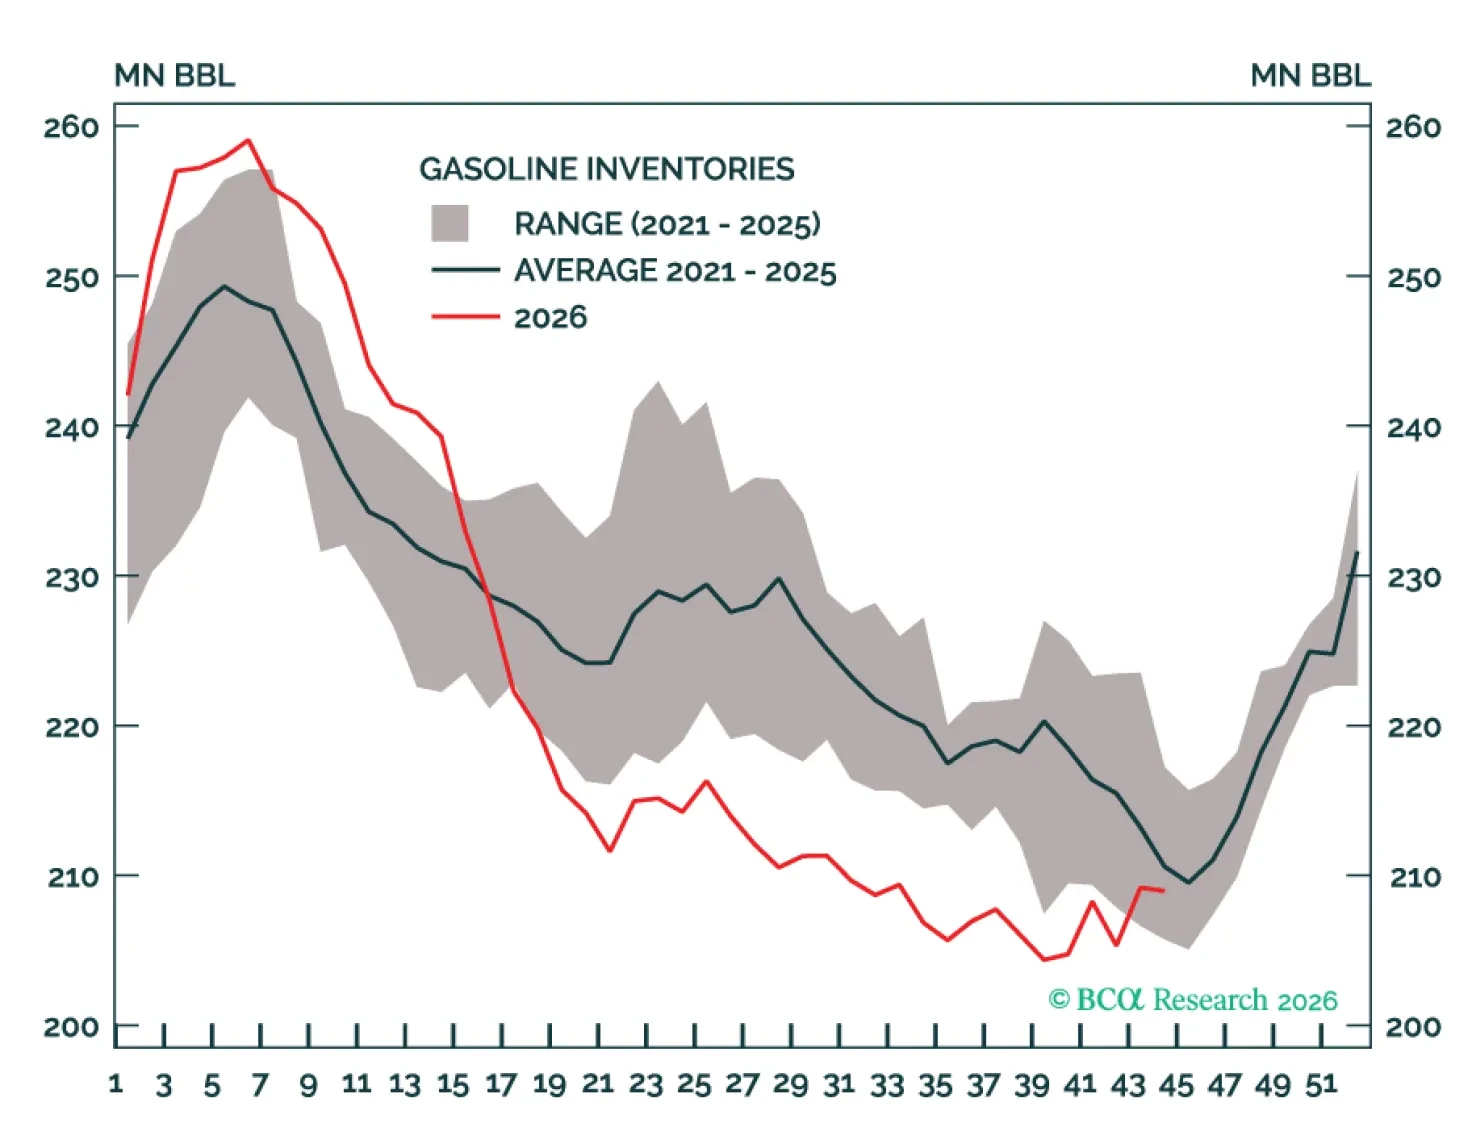
US institutions are prevailing over an unorthodox personality, implying policy adjustment and a decent backdrop for equity markets. But the Iran war is an immediate and acute risk to the global macro and market outlook.
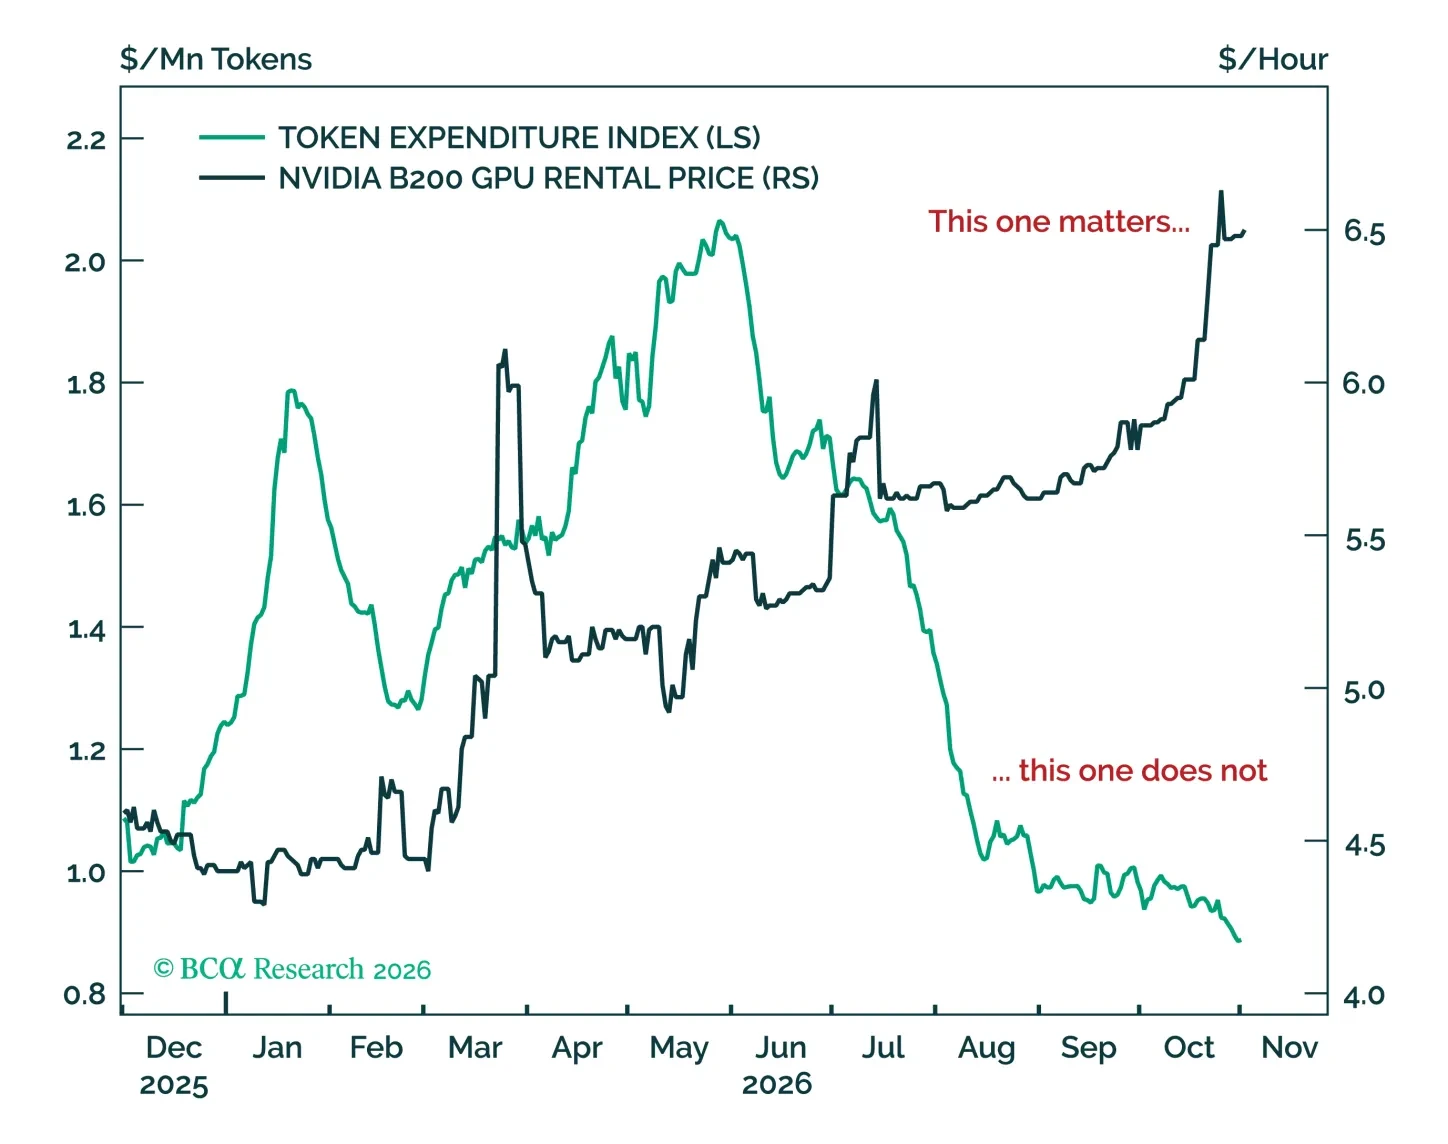
October has been a bad month for equities — particularly AI/tech ones — and a great month for oil. We do not think that the AI supercycle is ending, it has more room to go. Token price decline is a sign of a price war between LLMs, not a decline in demand. In fact, that price war is what is driving datacenter profitability, which is what the bull market is actually based on. As such, what matters on a tactical time horizon is whether Trump capitulates on Iran. If he does not, the market will have to correct. We take the bullish side and expect oil prices to decline imminently, forcing a short squeeze and powering equities higher.
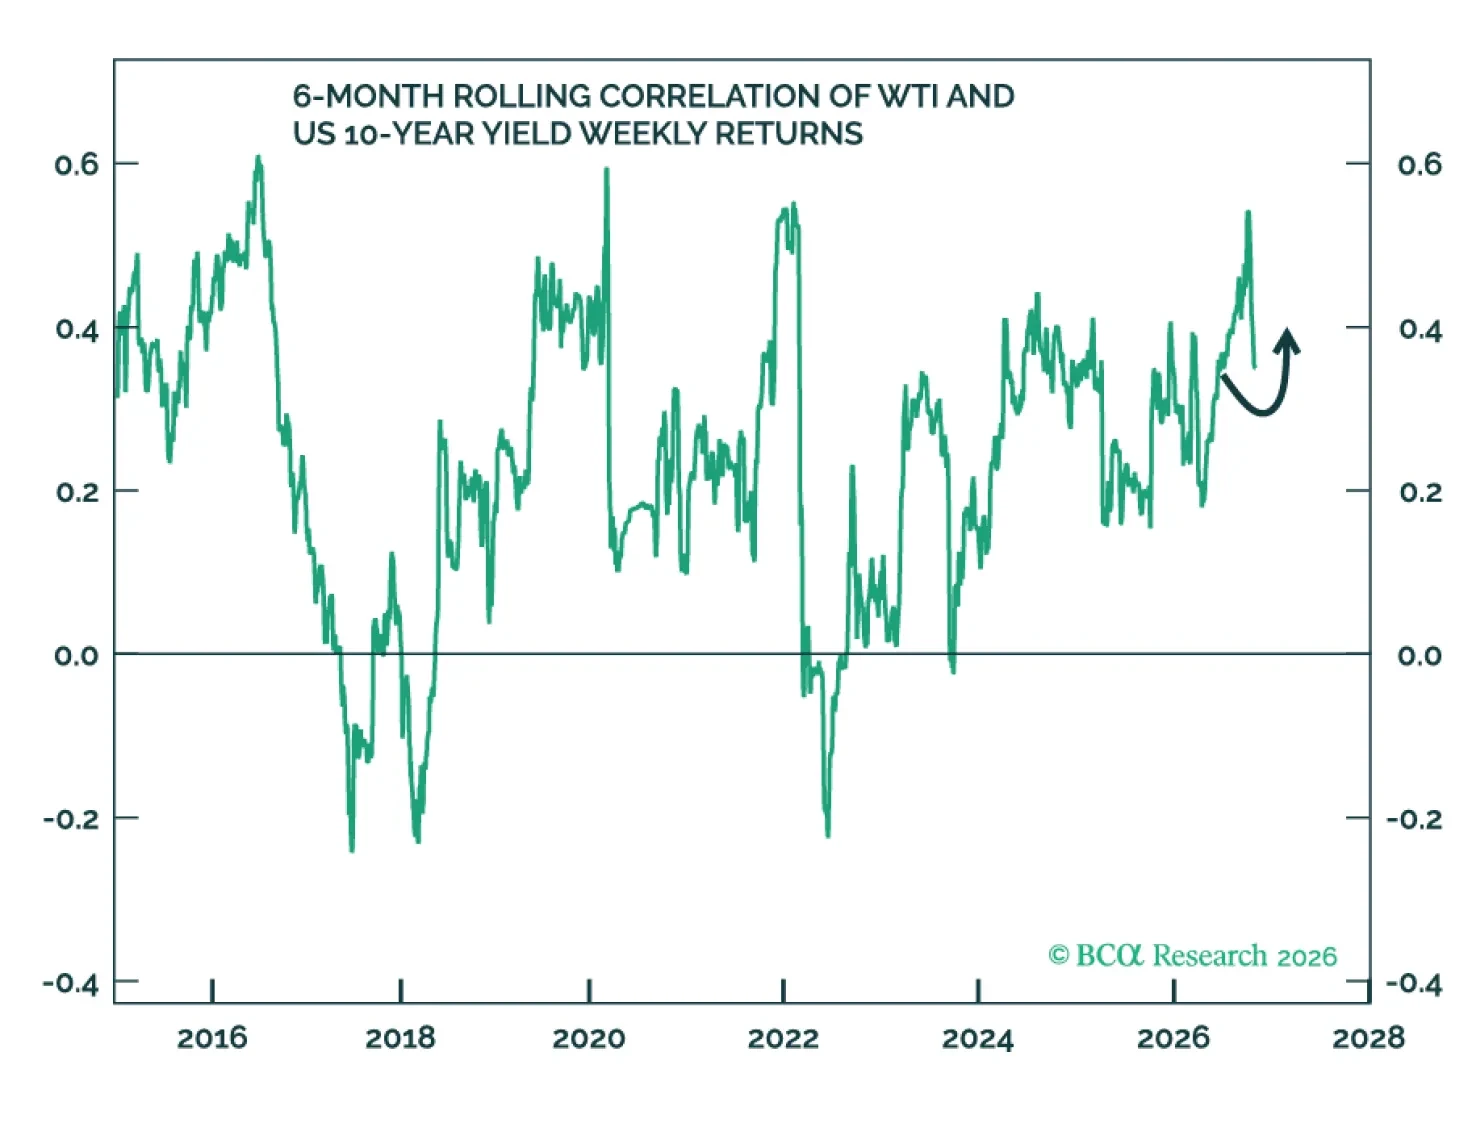
Democrats look to be clinching a Senate victory in the final day of the campaign, but Iran, not the Senate, poses the real risk.
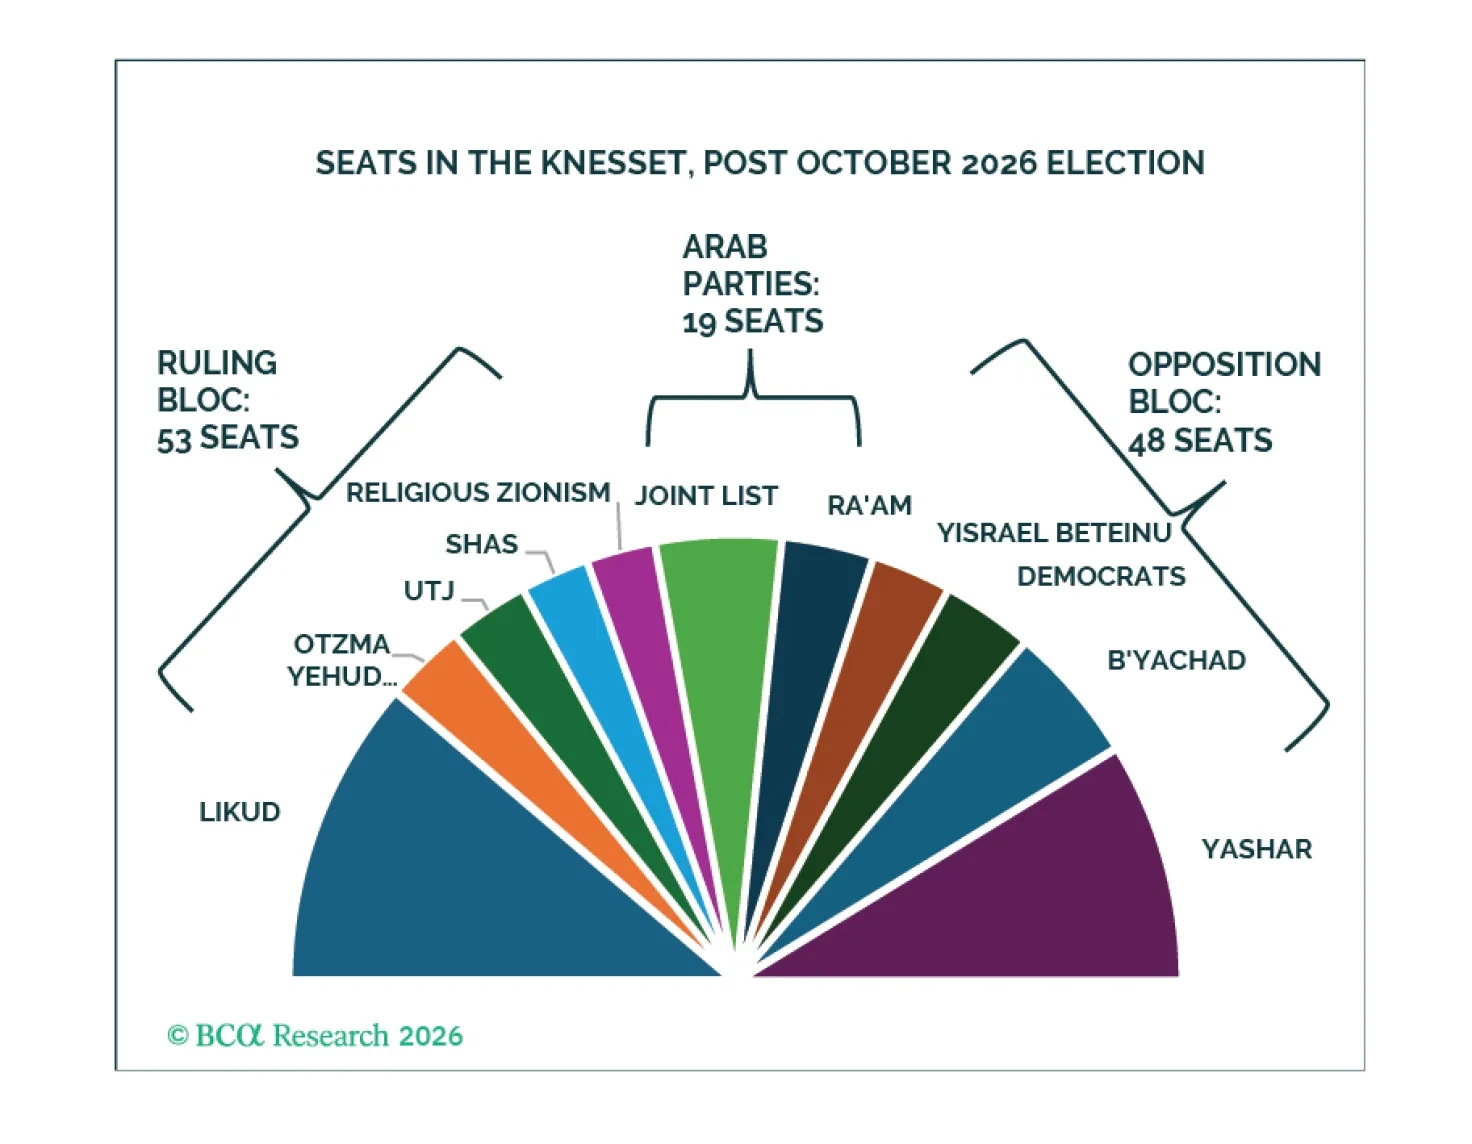
Another Netanyahu-led government would raise the risk of Israeli escalation and a major oil supply shock, while an opposition victory would reduce, but not eliminate, this risk due to its greater coordination with and deference to the US.
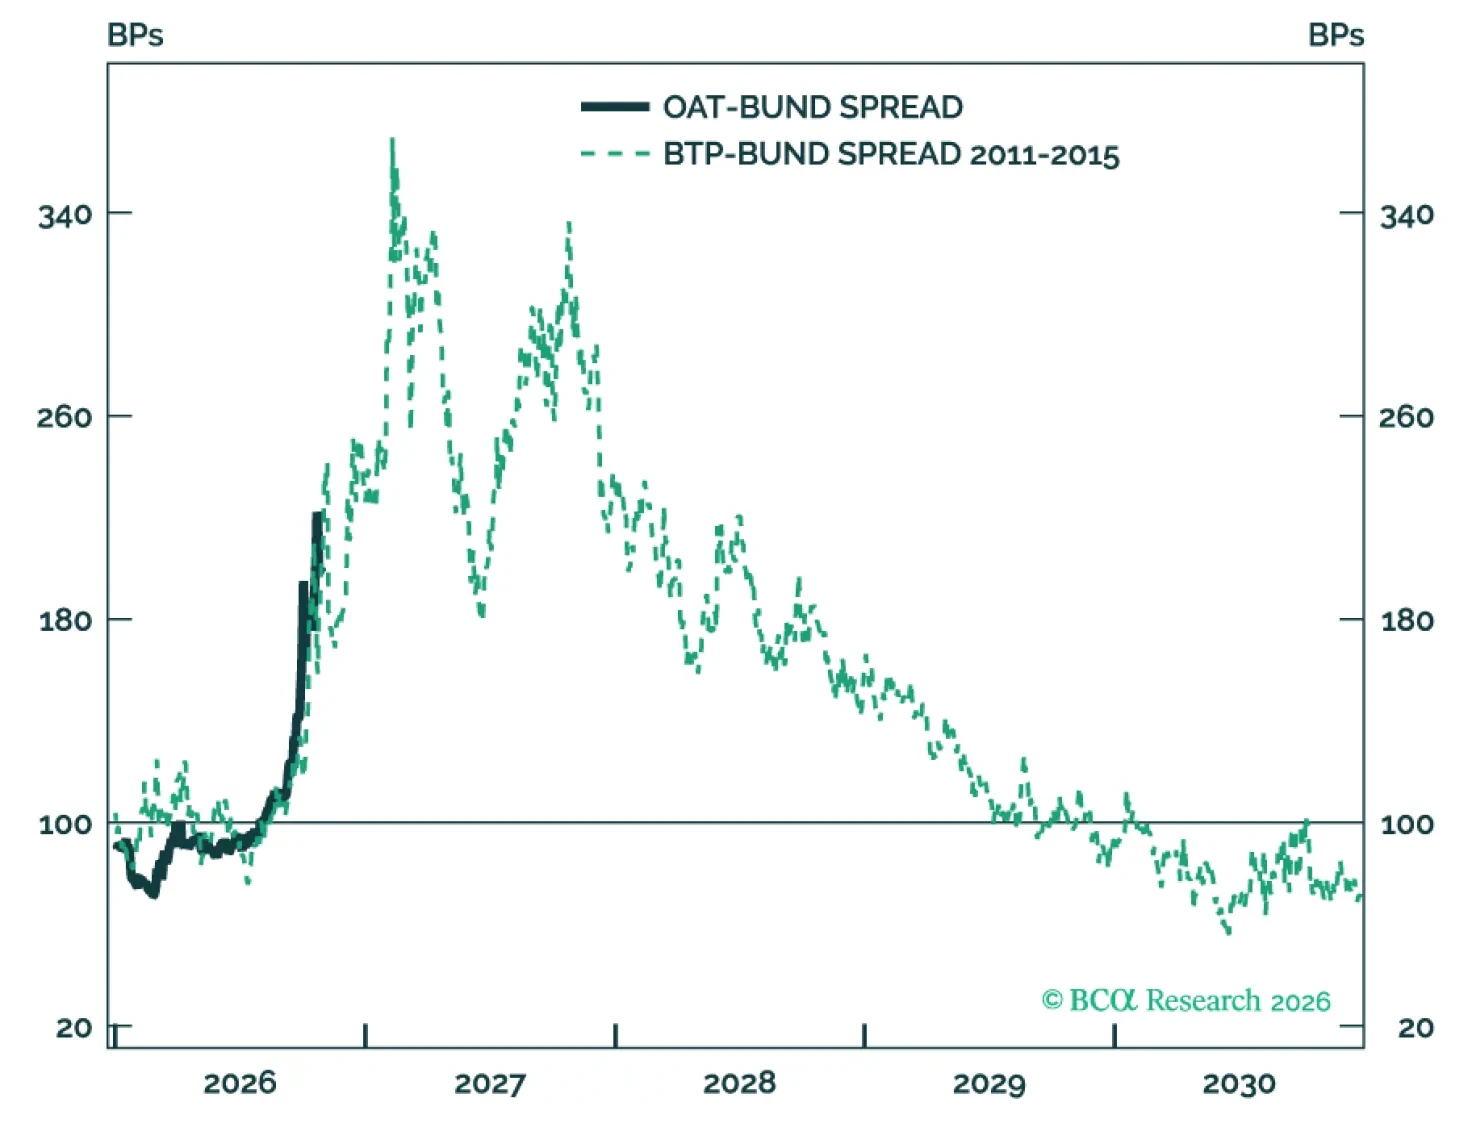
France’s fiscal mess is far from over, but the bond vigilantes may have gotten ahead of themselves. We book profits on short OATs, eyeing another opportunity in early 2027 as election risks resurface. Meanwhile, French equities are too cheap to ignore. We tactically buy on depressed valuations.
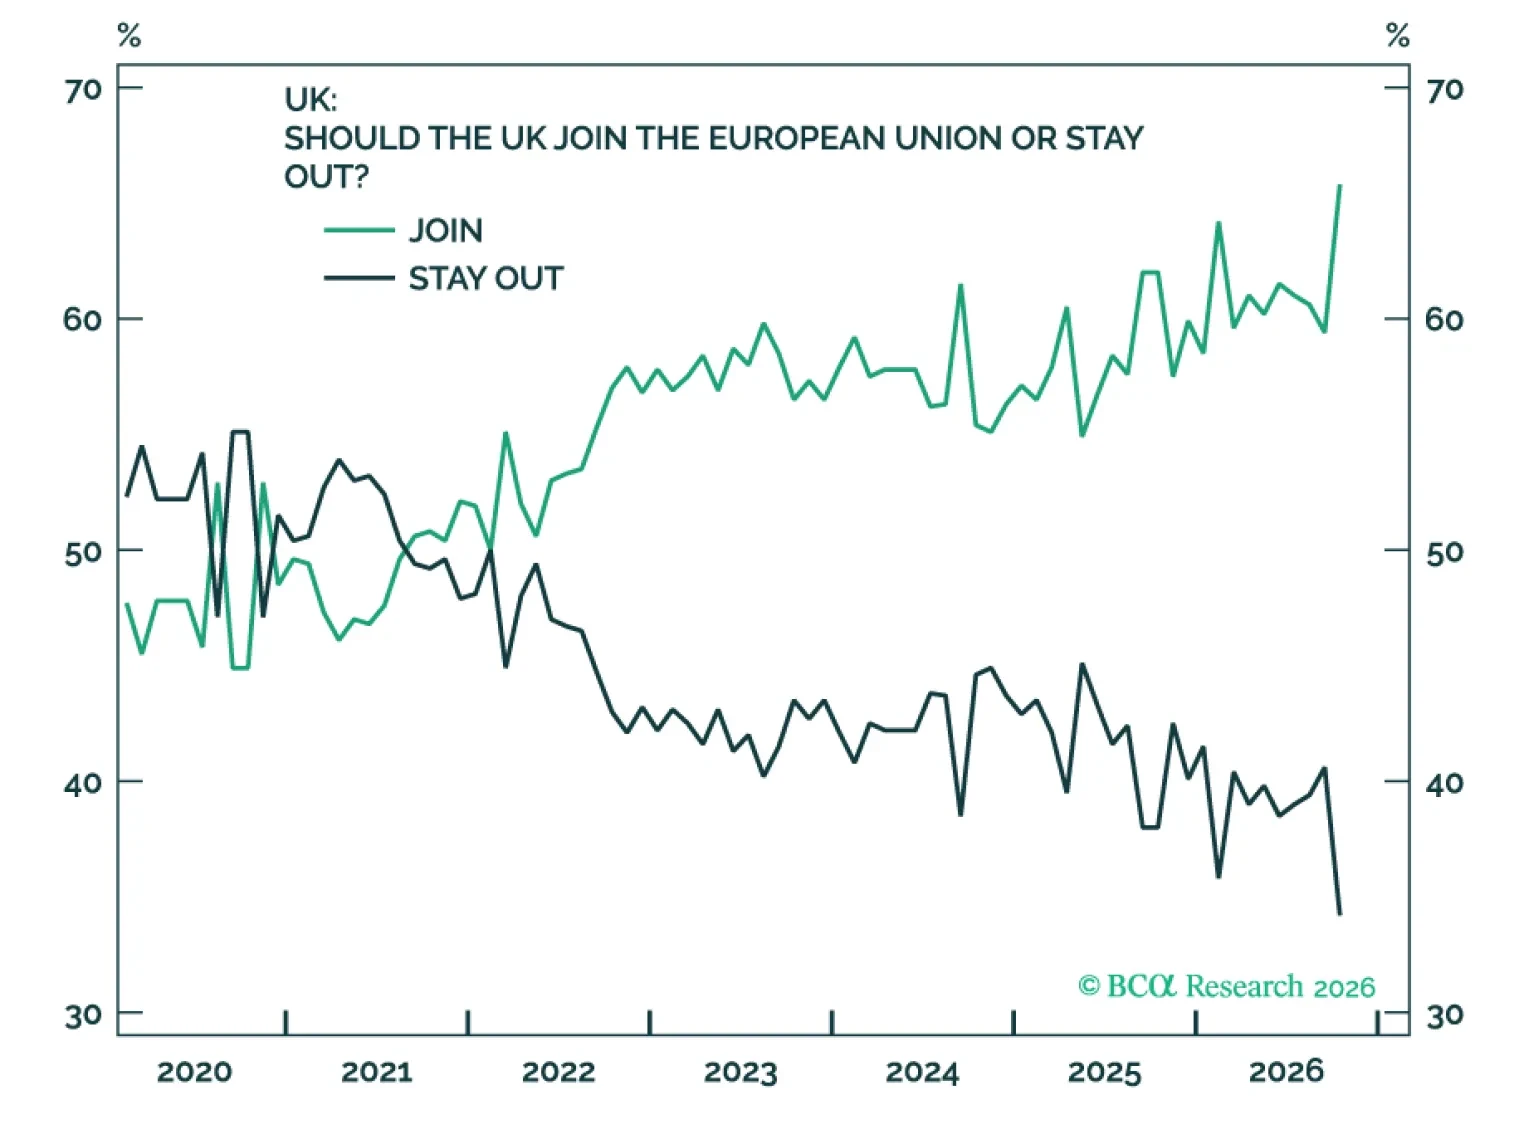
The UK faces many challenges but secessionism can be contained.