 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
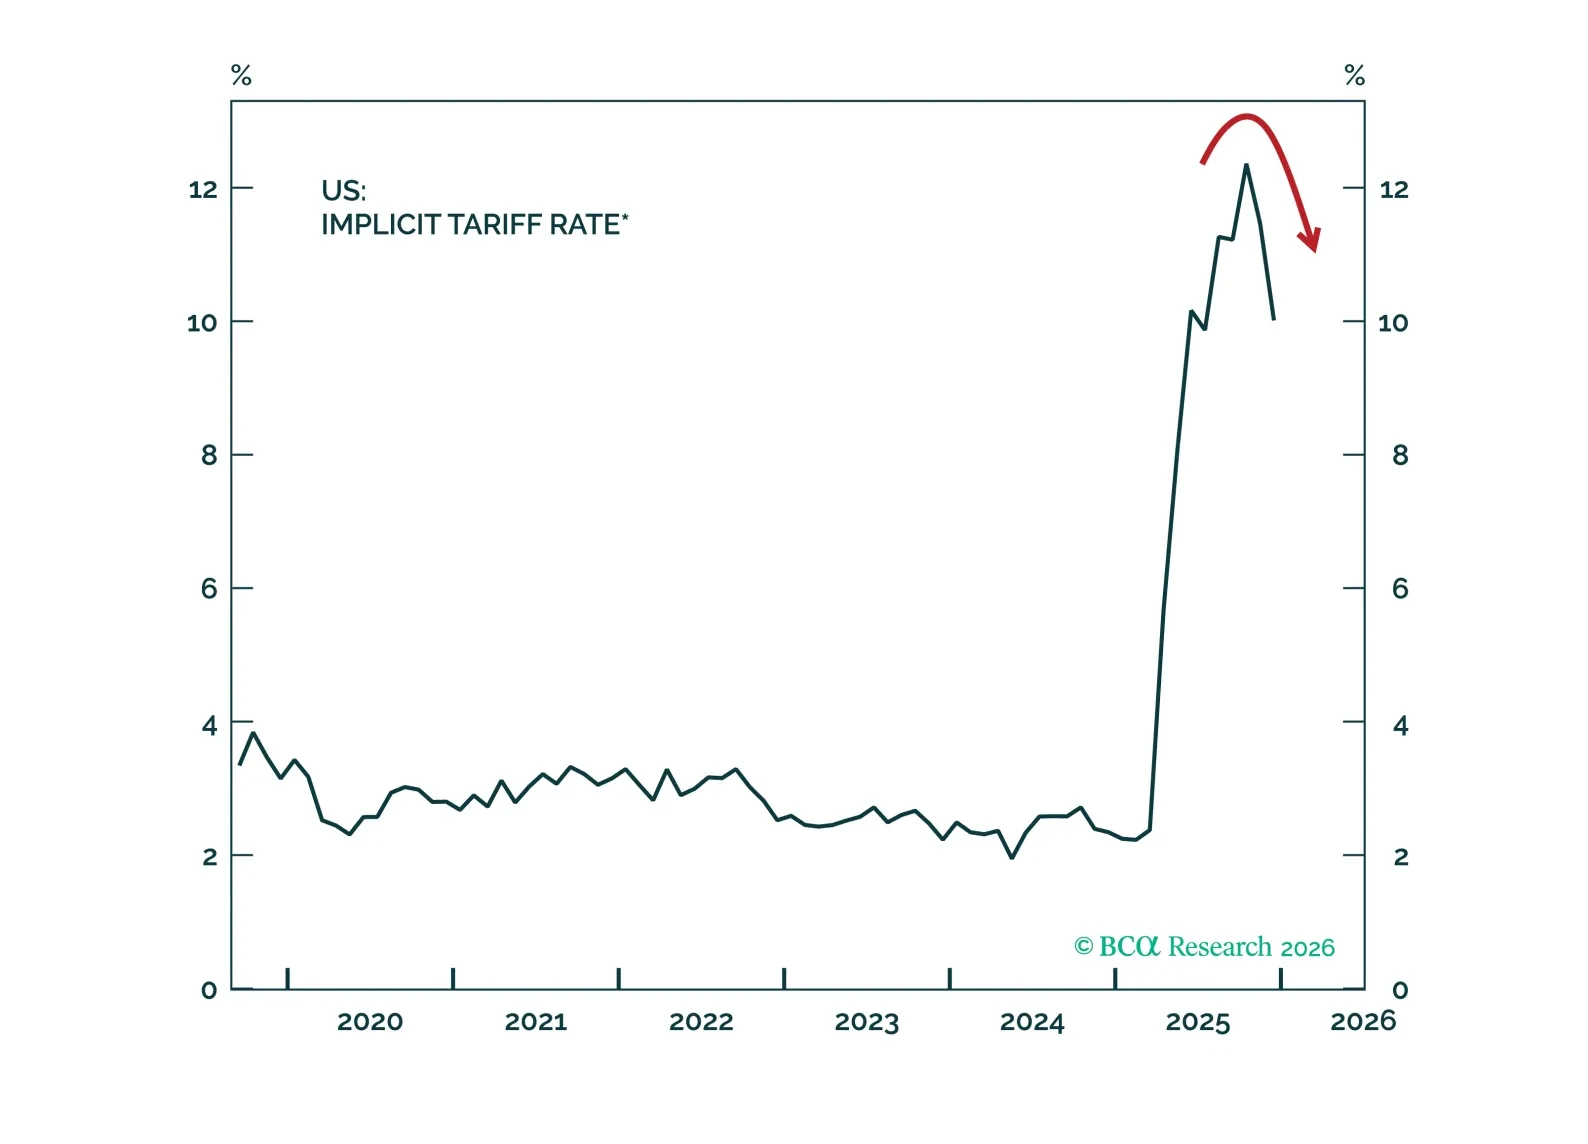
The Section 122 tariffs under the US Trade Act of 1974 are more favorable to Europe; the trade-weighted tariff rate falls to 10.45%, from 11.74% pre-ruling. This positive development does not change our overall views on Europe, as we expected lower tariffs ahead of the US midterms.
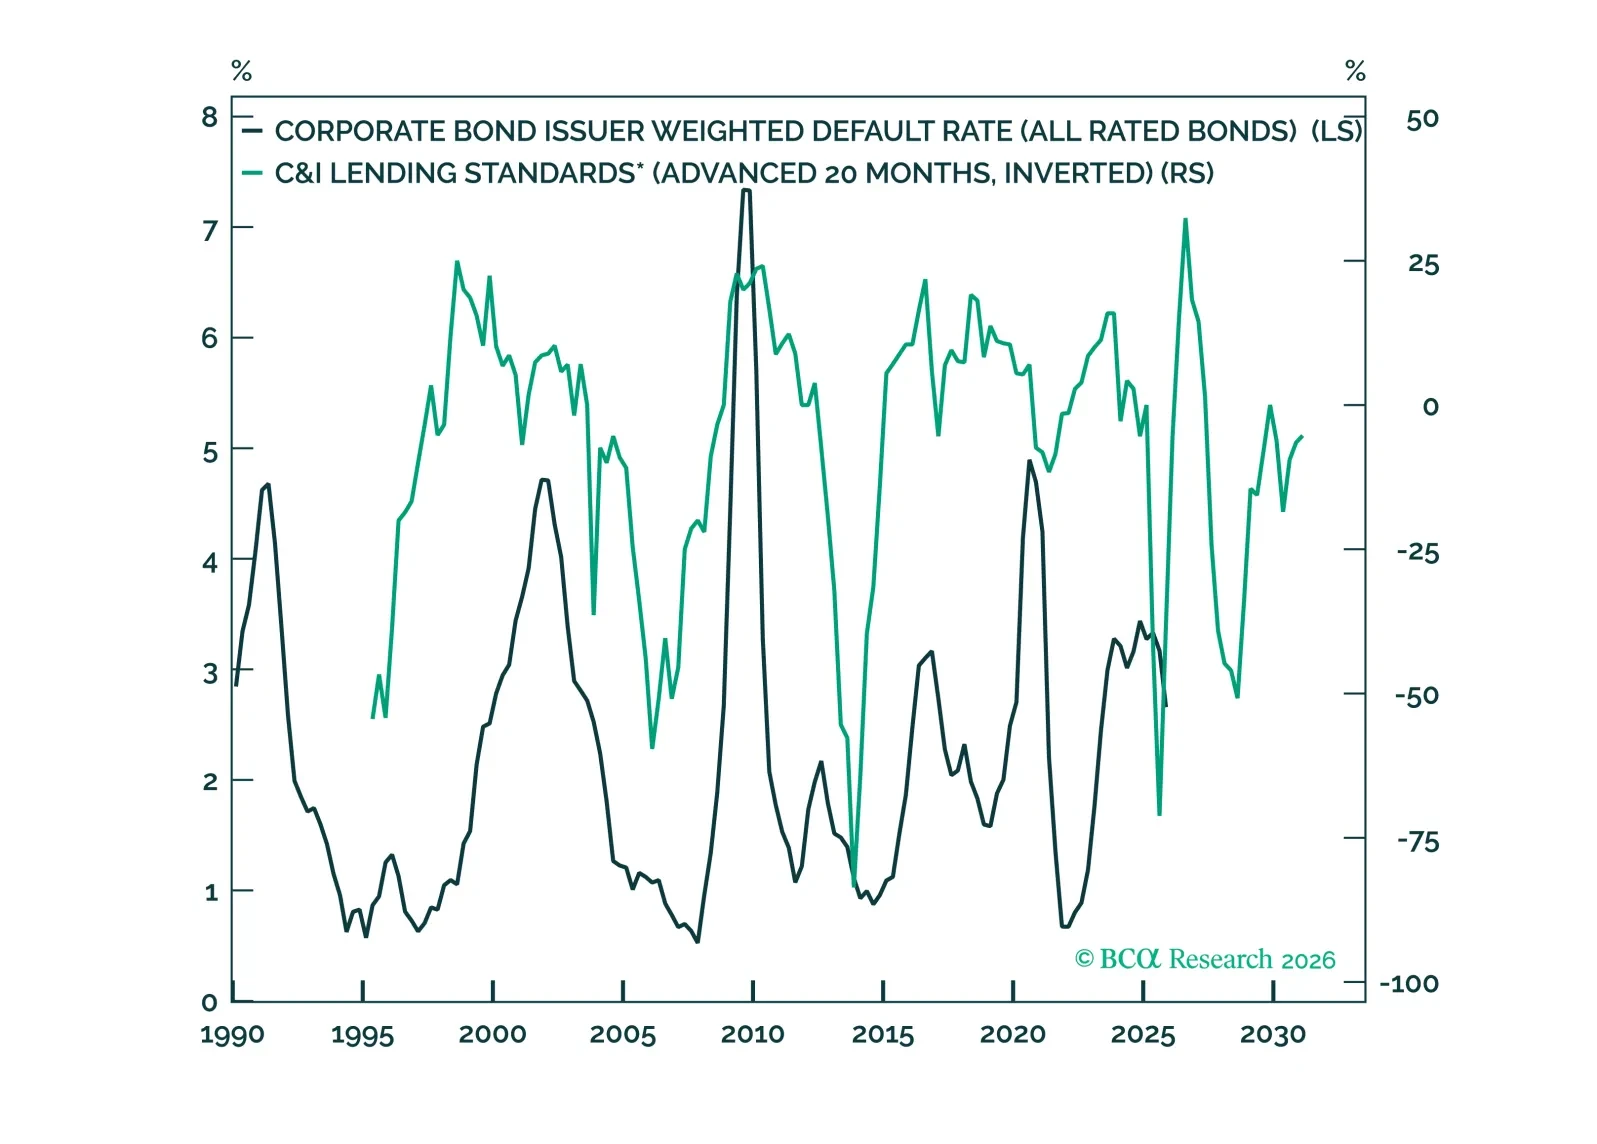
The turmoil in private credit is a wild card, but our traditional suite of credit cycle indicators does not point to an imminent spread-widening episode. We reiterate our benchmark weightings on Treasuries, investment-grade and high-yield corporate bonds.
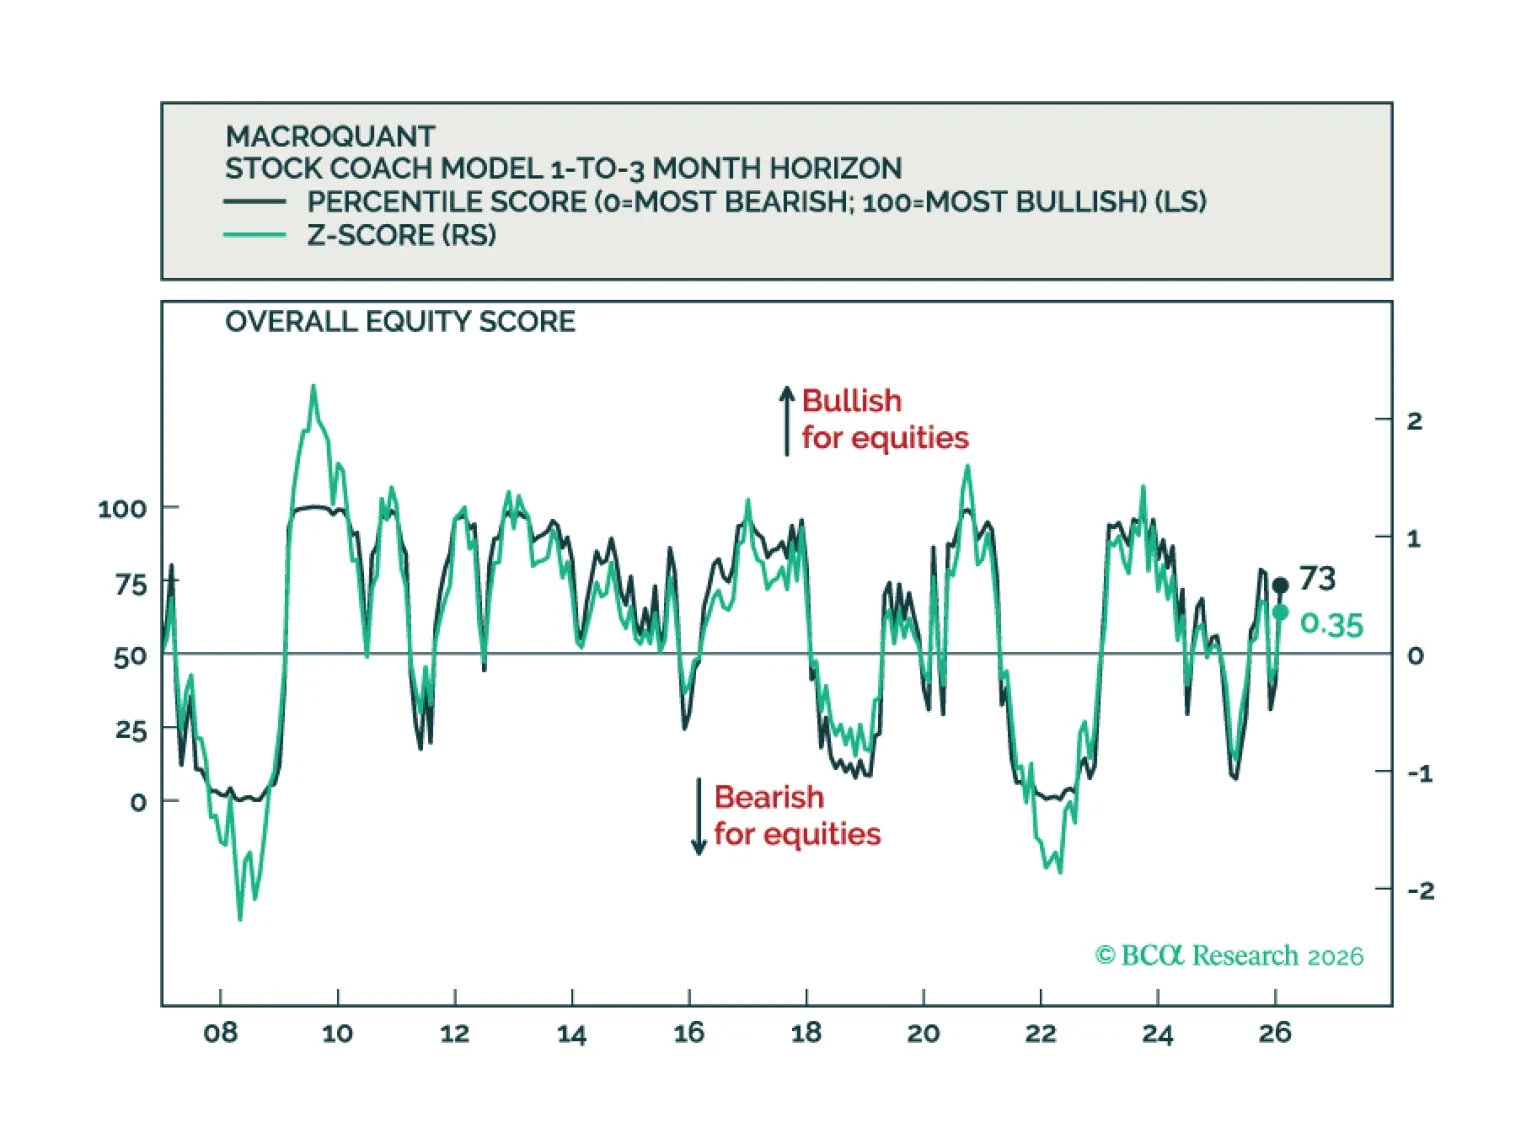
MacroQuant recommends a modest overweight position in equities, favors an above-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, has downgraded oil to neutral, and is bullish on copper and gold.
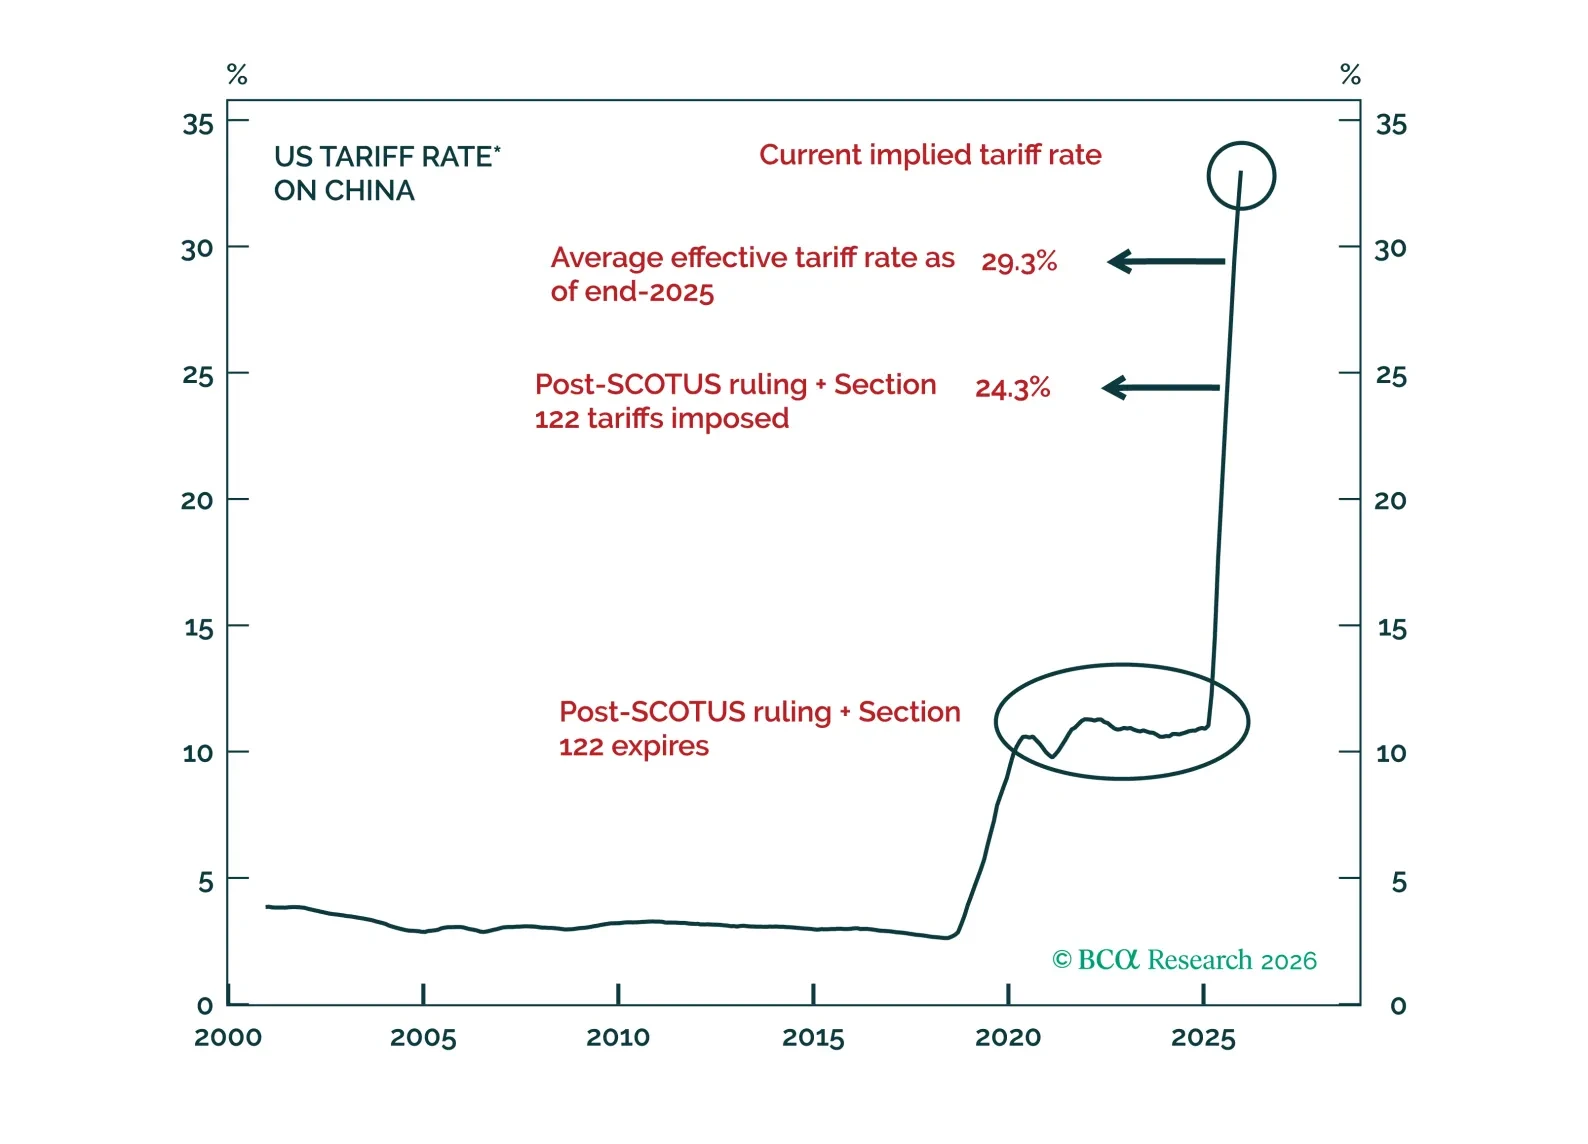
This report examines the implications for Chinese exports and global trade in light of the US Supreme Court’s ruling on tariffs.

Fourth quarter US GDP growth clocked in at 1.4%, well below consensus expectations of 2.8%. We are not too troubled by the miss. The government shutdown weighed on the economy, with government spending subtracting 0.9 percentage points from growth. Real private final domestic demand – a clean measure of GDP growth that excludes government expenditure, net exports, and inventories – rose by a respectable 2.4%.
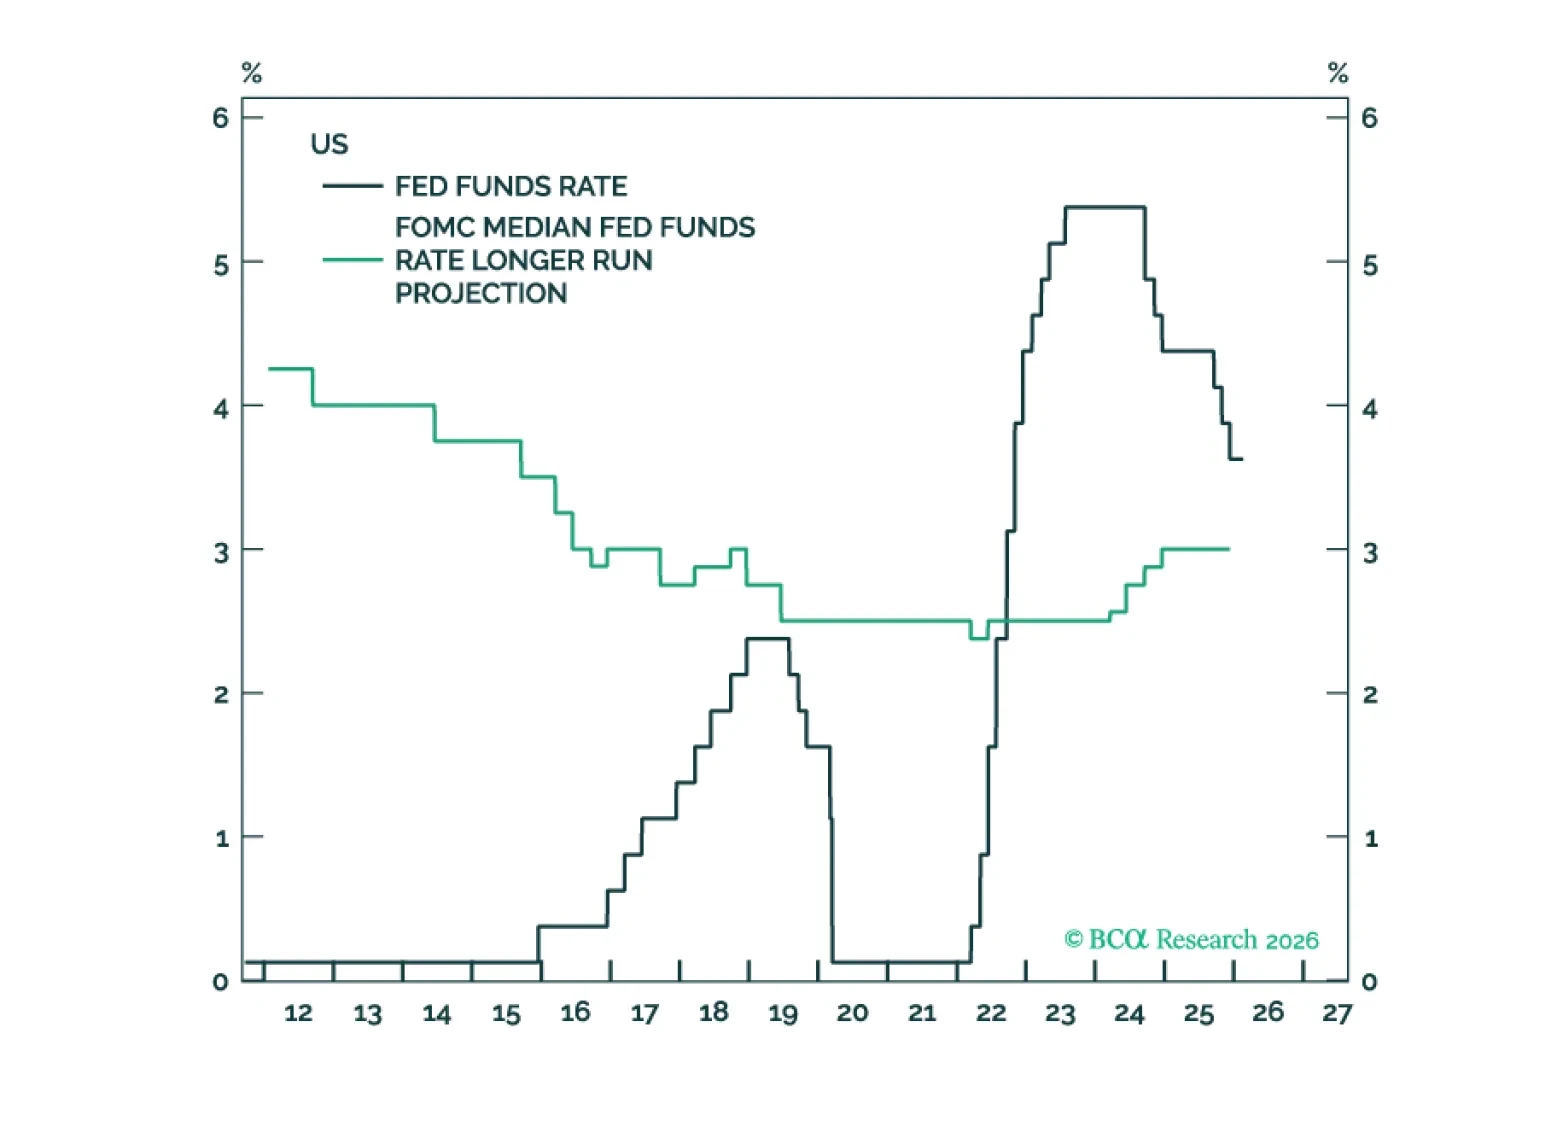
The neutral rate in the US is being propped up by a variety of forces that are at risk of reversing. These include the AI capex boom, large budget deficits, and the extraordinarily high level of household wealth. As such, interest rates are likely to surprise to the downside over the next few years.
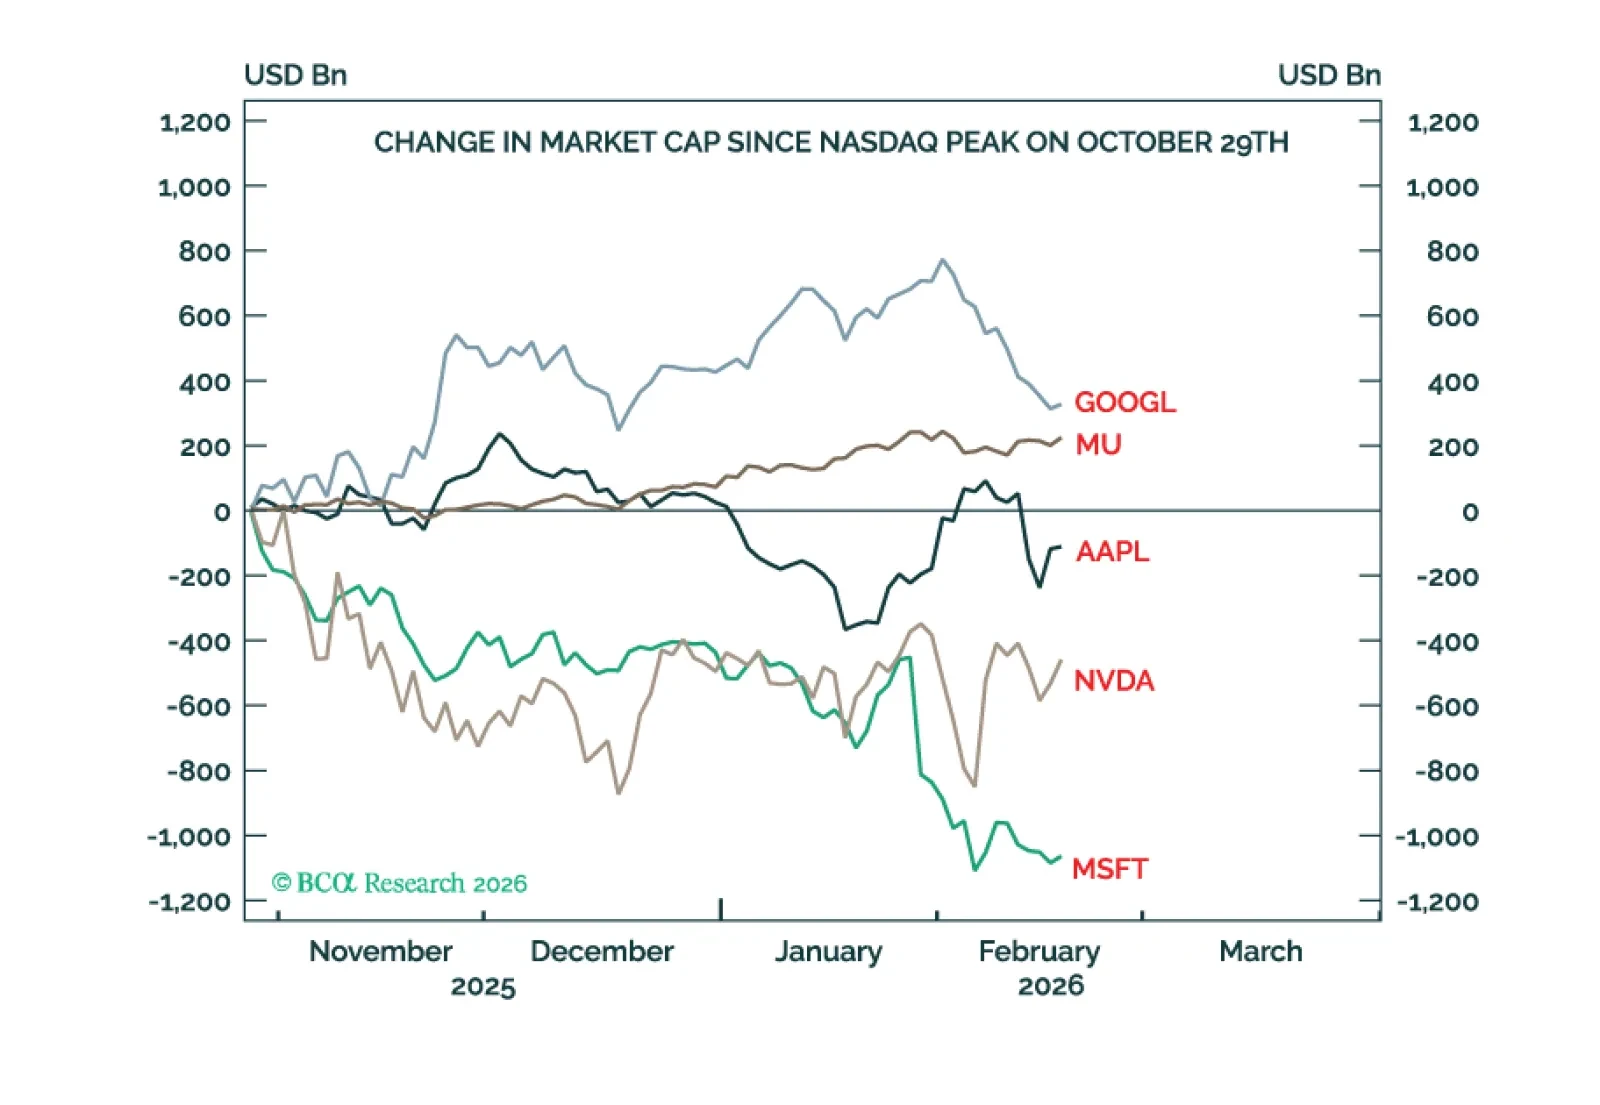
Tech has starkly underperformed other equity sectors and the tech-heavy US market has underperformed non-US markets, but global stocks are up and have comfortably outperformed bonds. This pattern of performances is likely to continue through the rest of 2026. Plus, two new tactical trades are: long coffee; and long ETH.
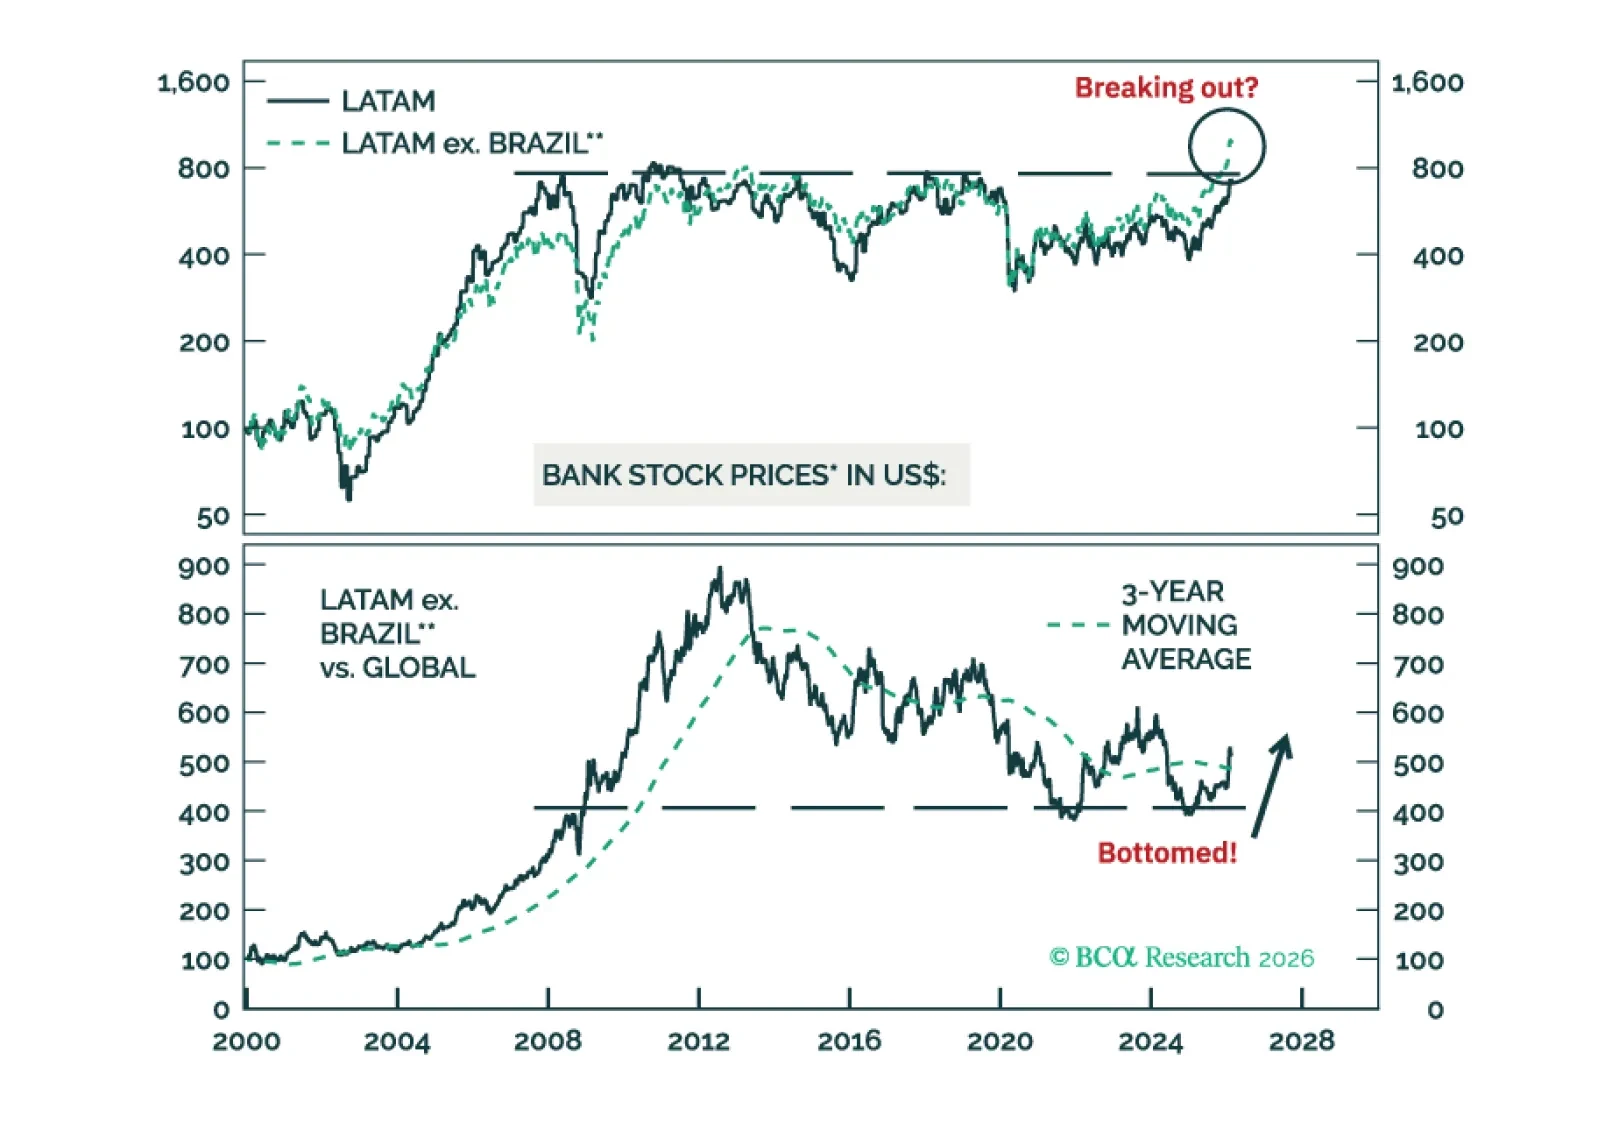
Go long LATAM ex. Brazil banks / short global bank stocks. Brazilian bank equities will underperform due to poor and worsening macro fundamentals.