 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
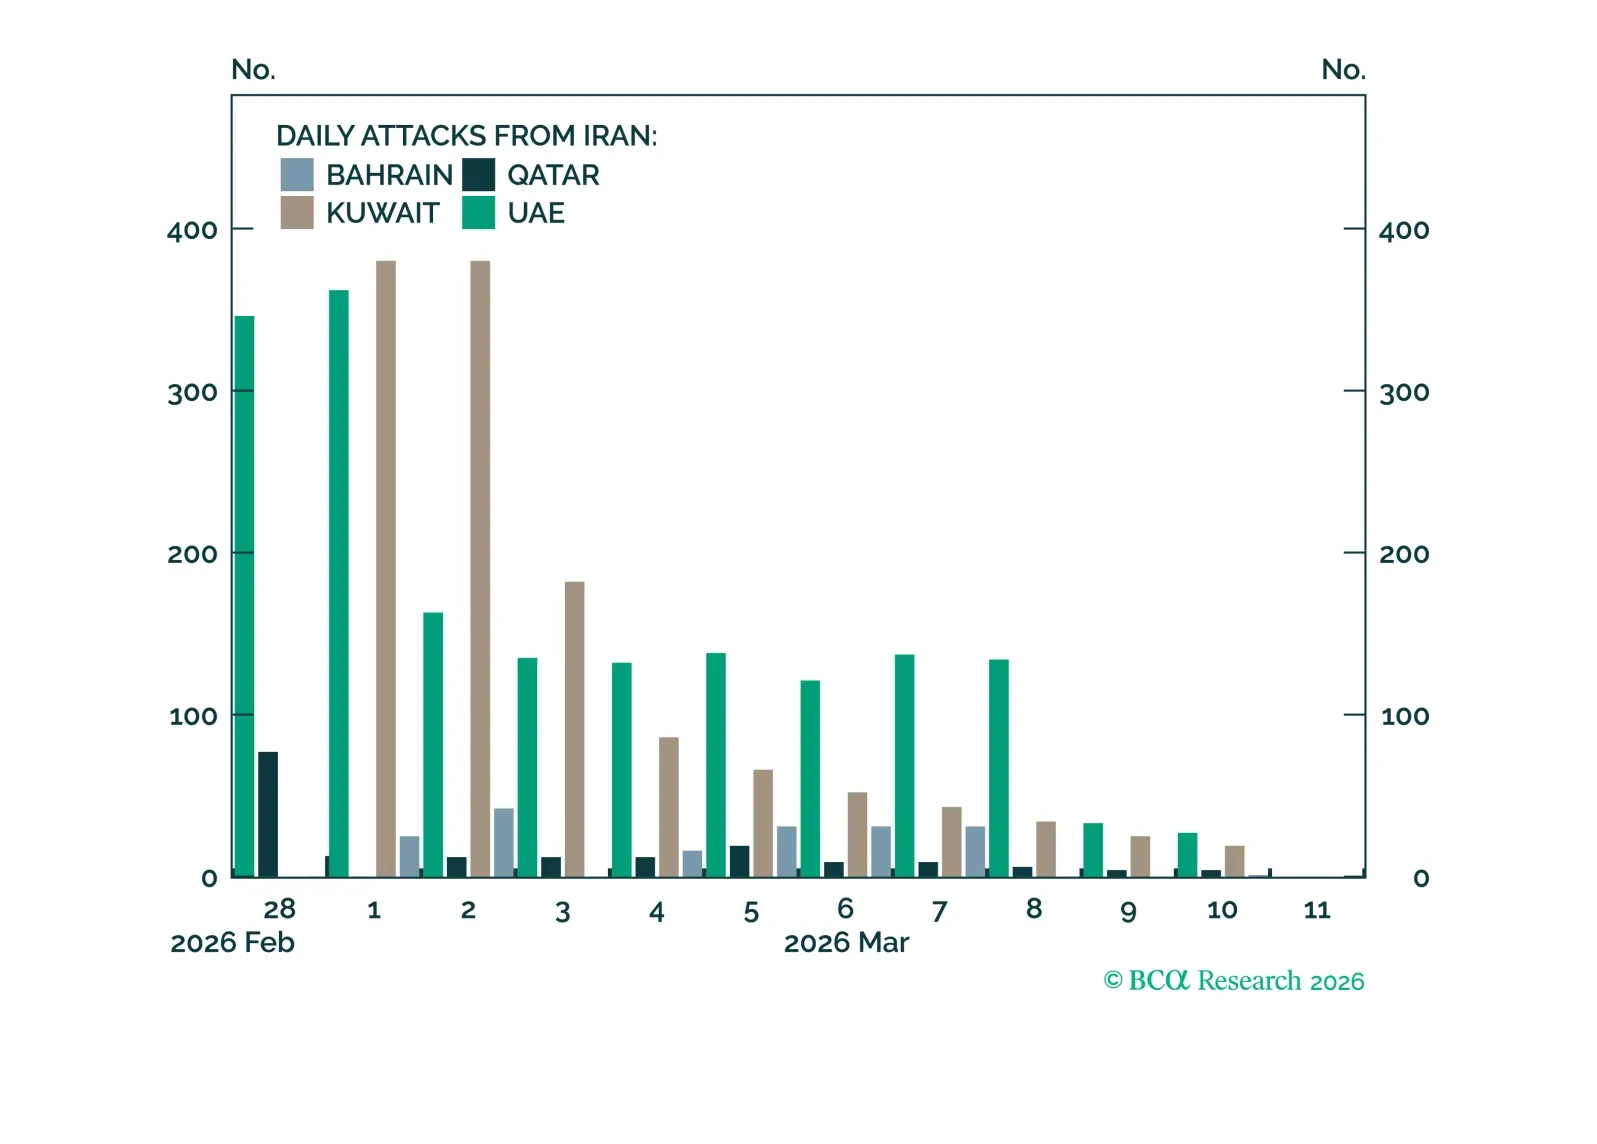
With all eyes on the Strait of Hormuz, BCA Research has created a dashboard of data for your convenience.
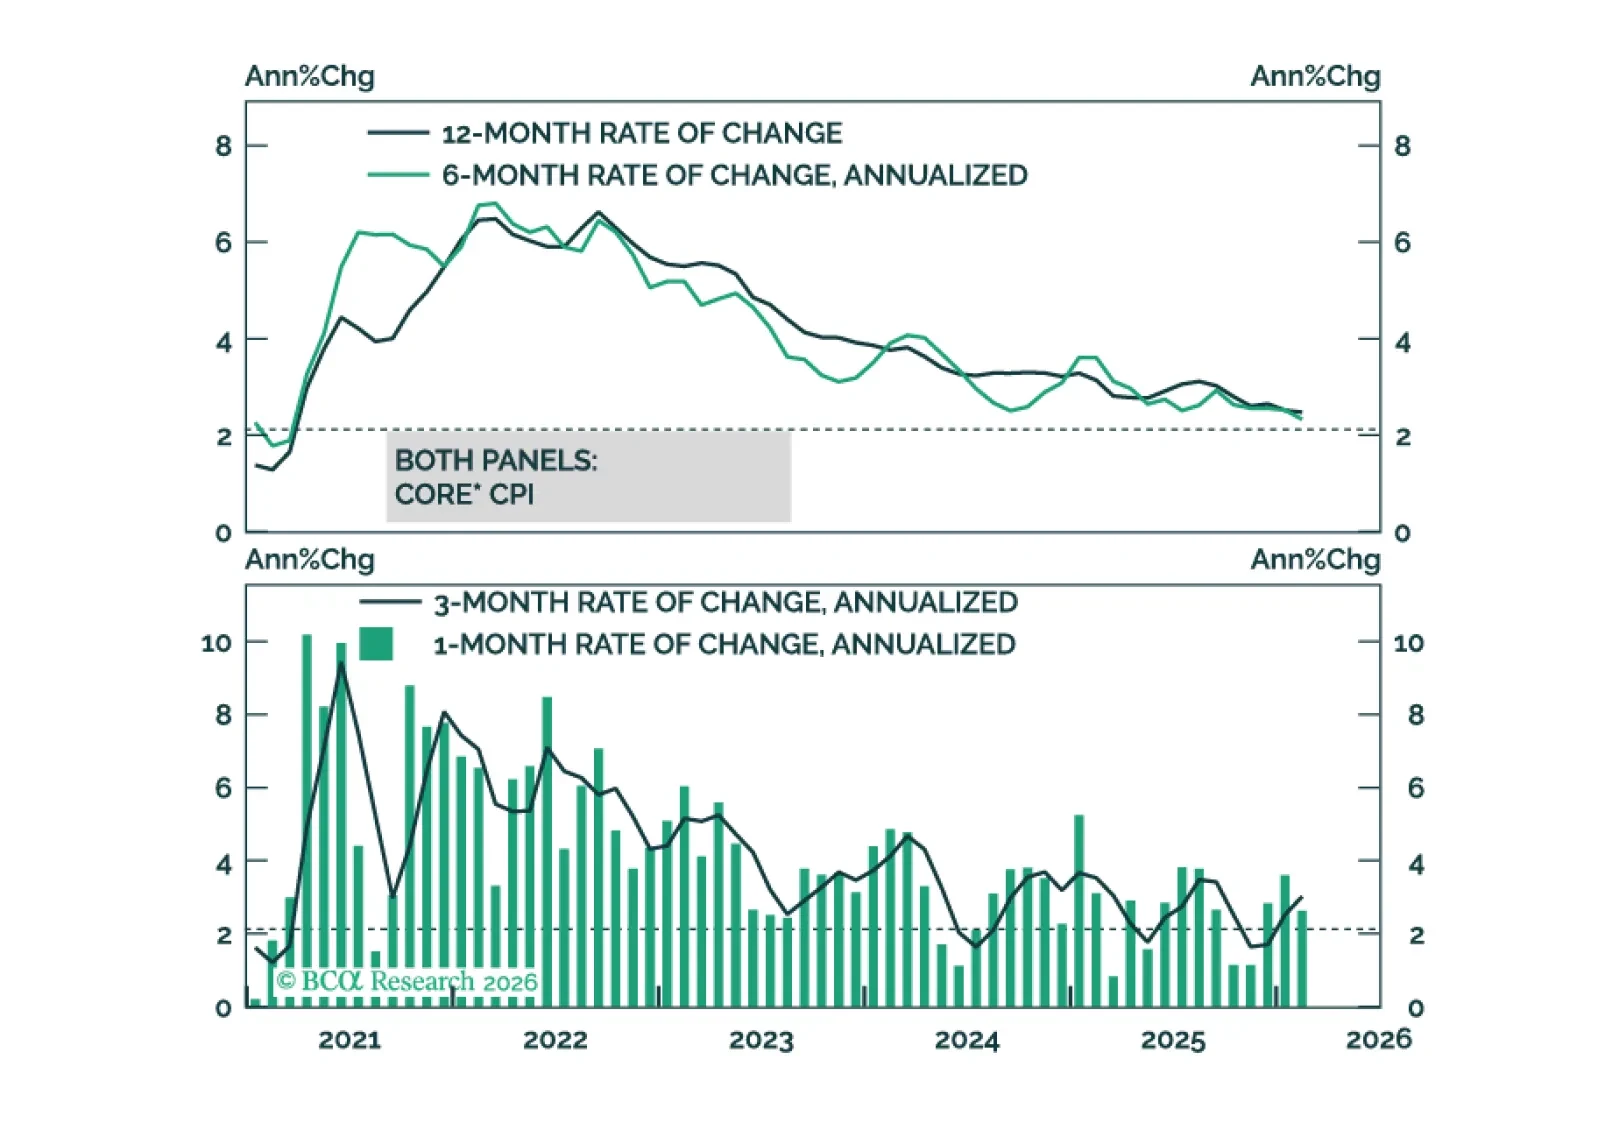
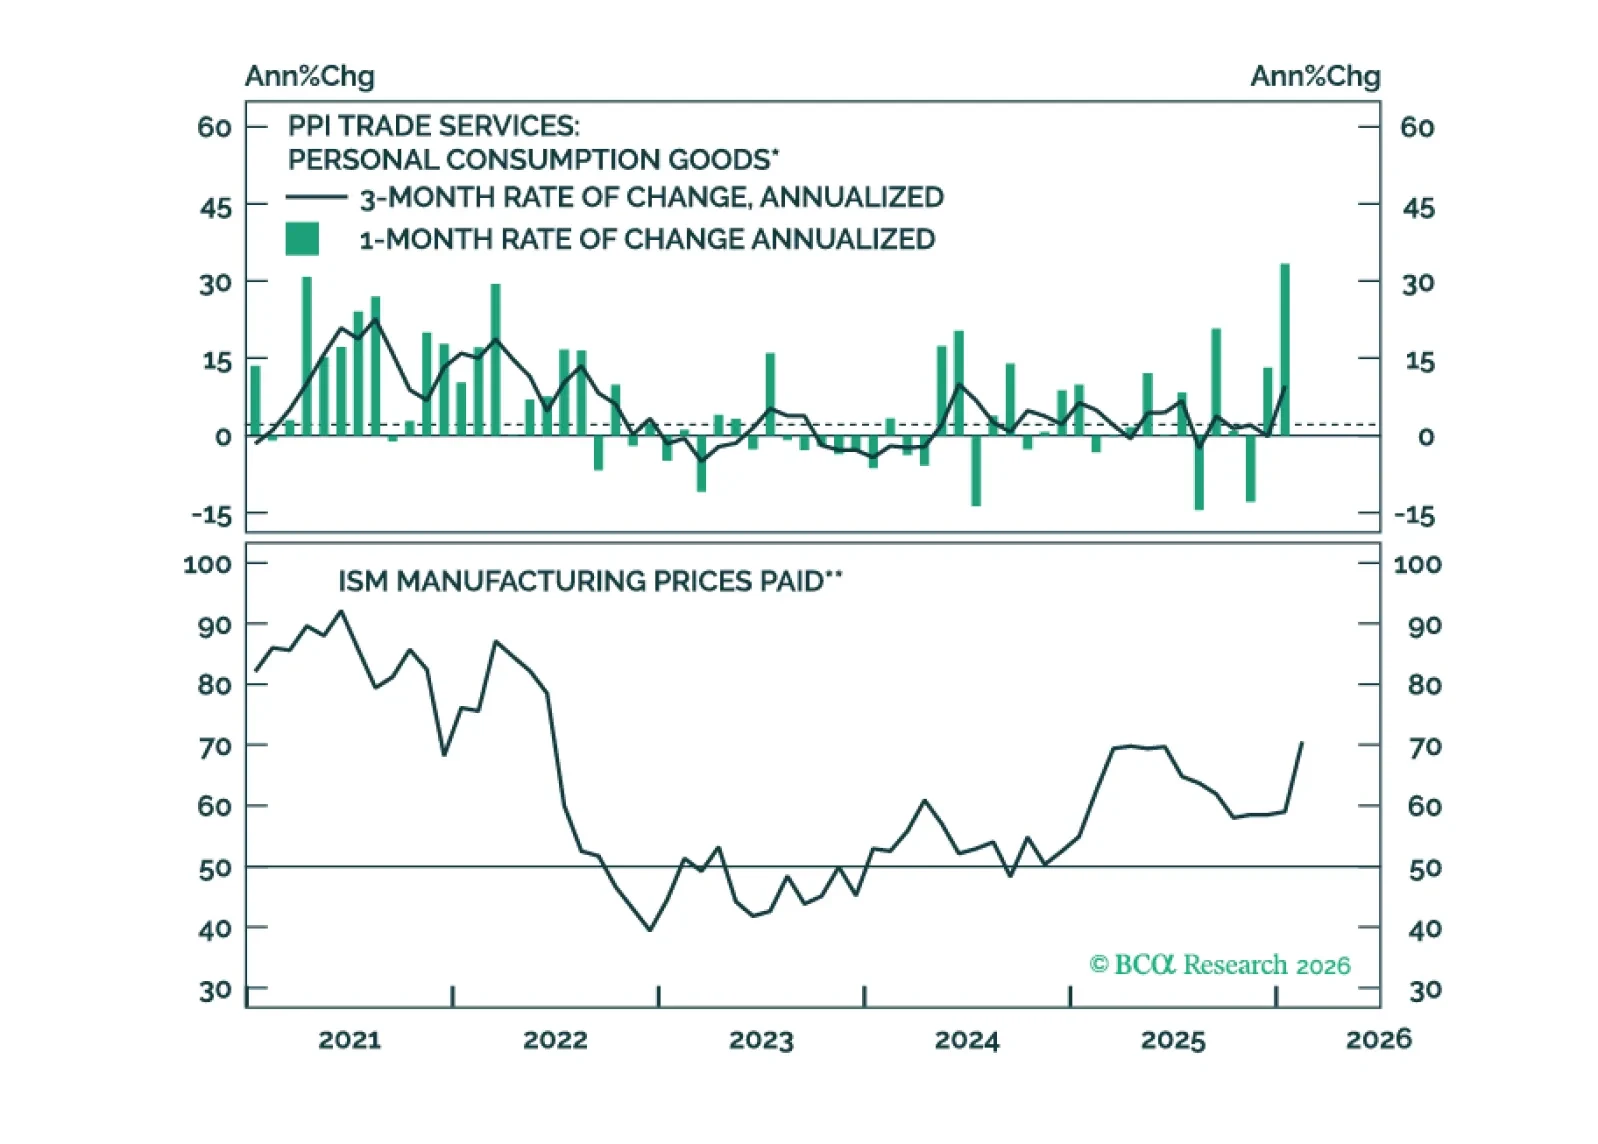
The recent oil price shock reinforces our view that inflation will surprise to the upside during the next few months but fall rapidly in H2 2026.
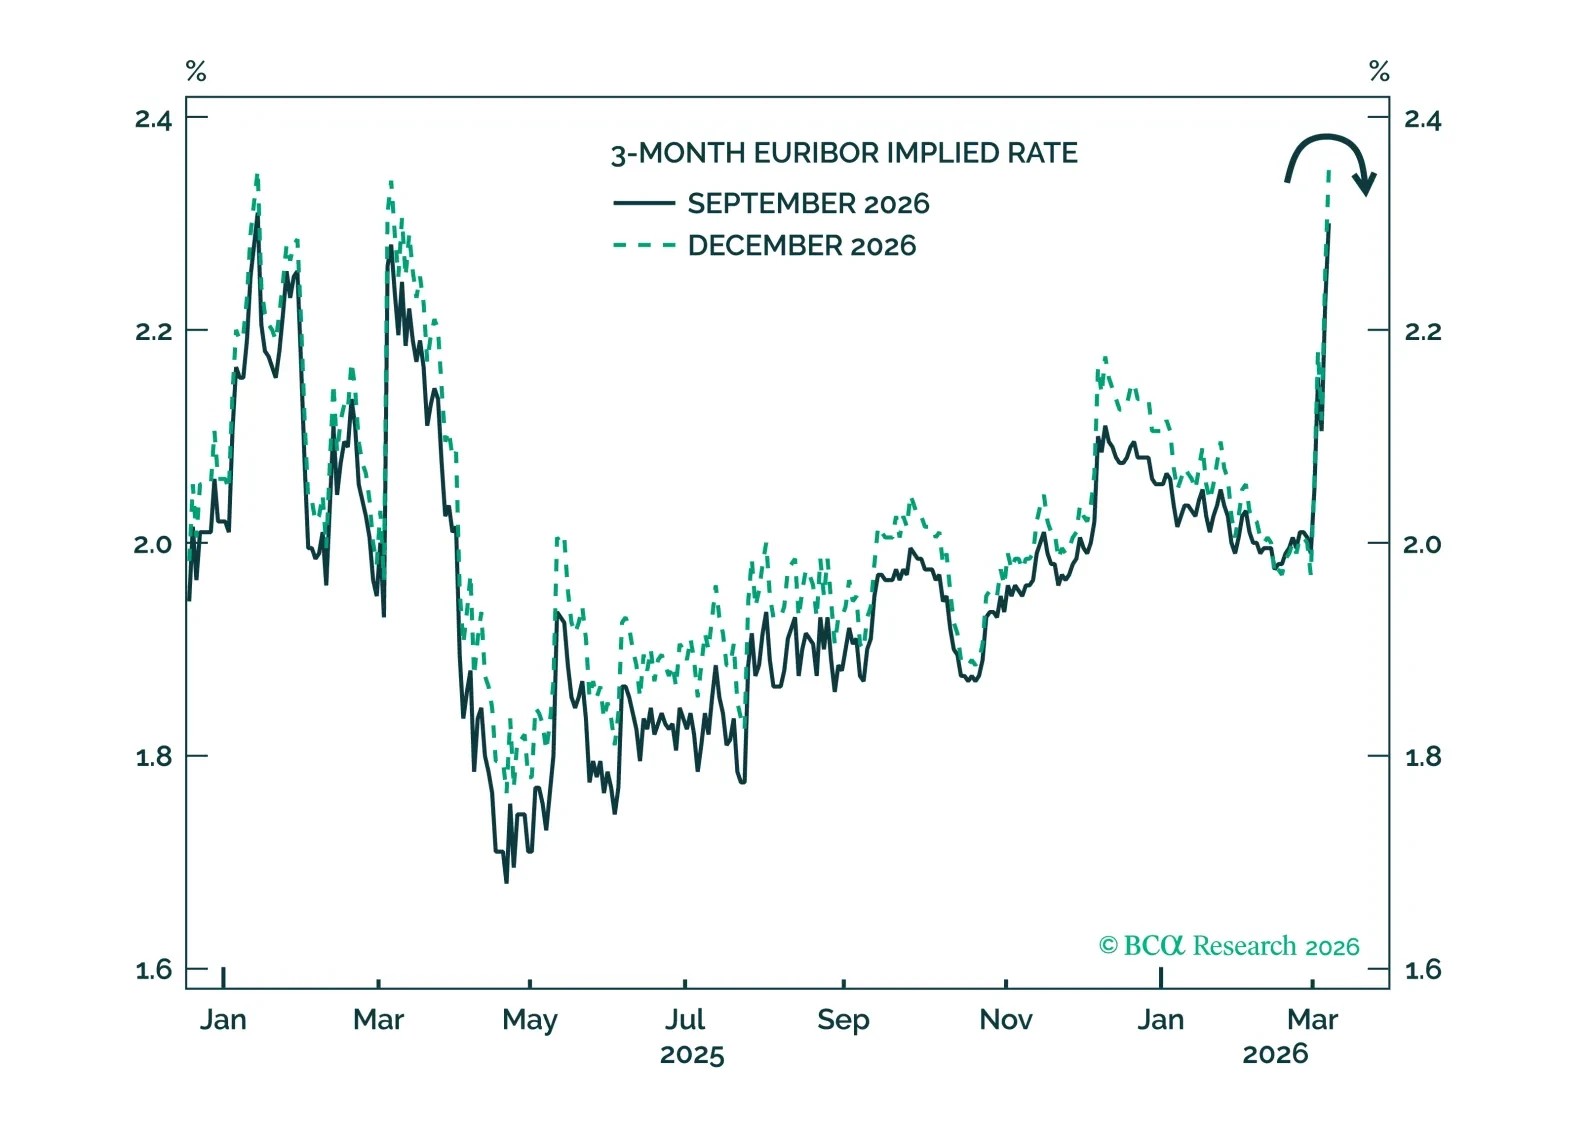
If the 2022 roadmap is any guide, equity markets and cyclical currencies will trough only after confirming that the peak in energy prices is in the rearview mirror. In the very near term, investors should focus on P&L preservation. Reduce exposure to equities, and seek refuge in gold, and inflation-linked bonds (ILBs). Amid a very different demand side than in 2022, today’s supply shock is unlikely to generate lasting inflation, and investors should fade rate-hike odds.
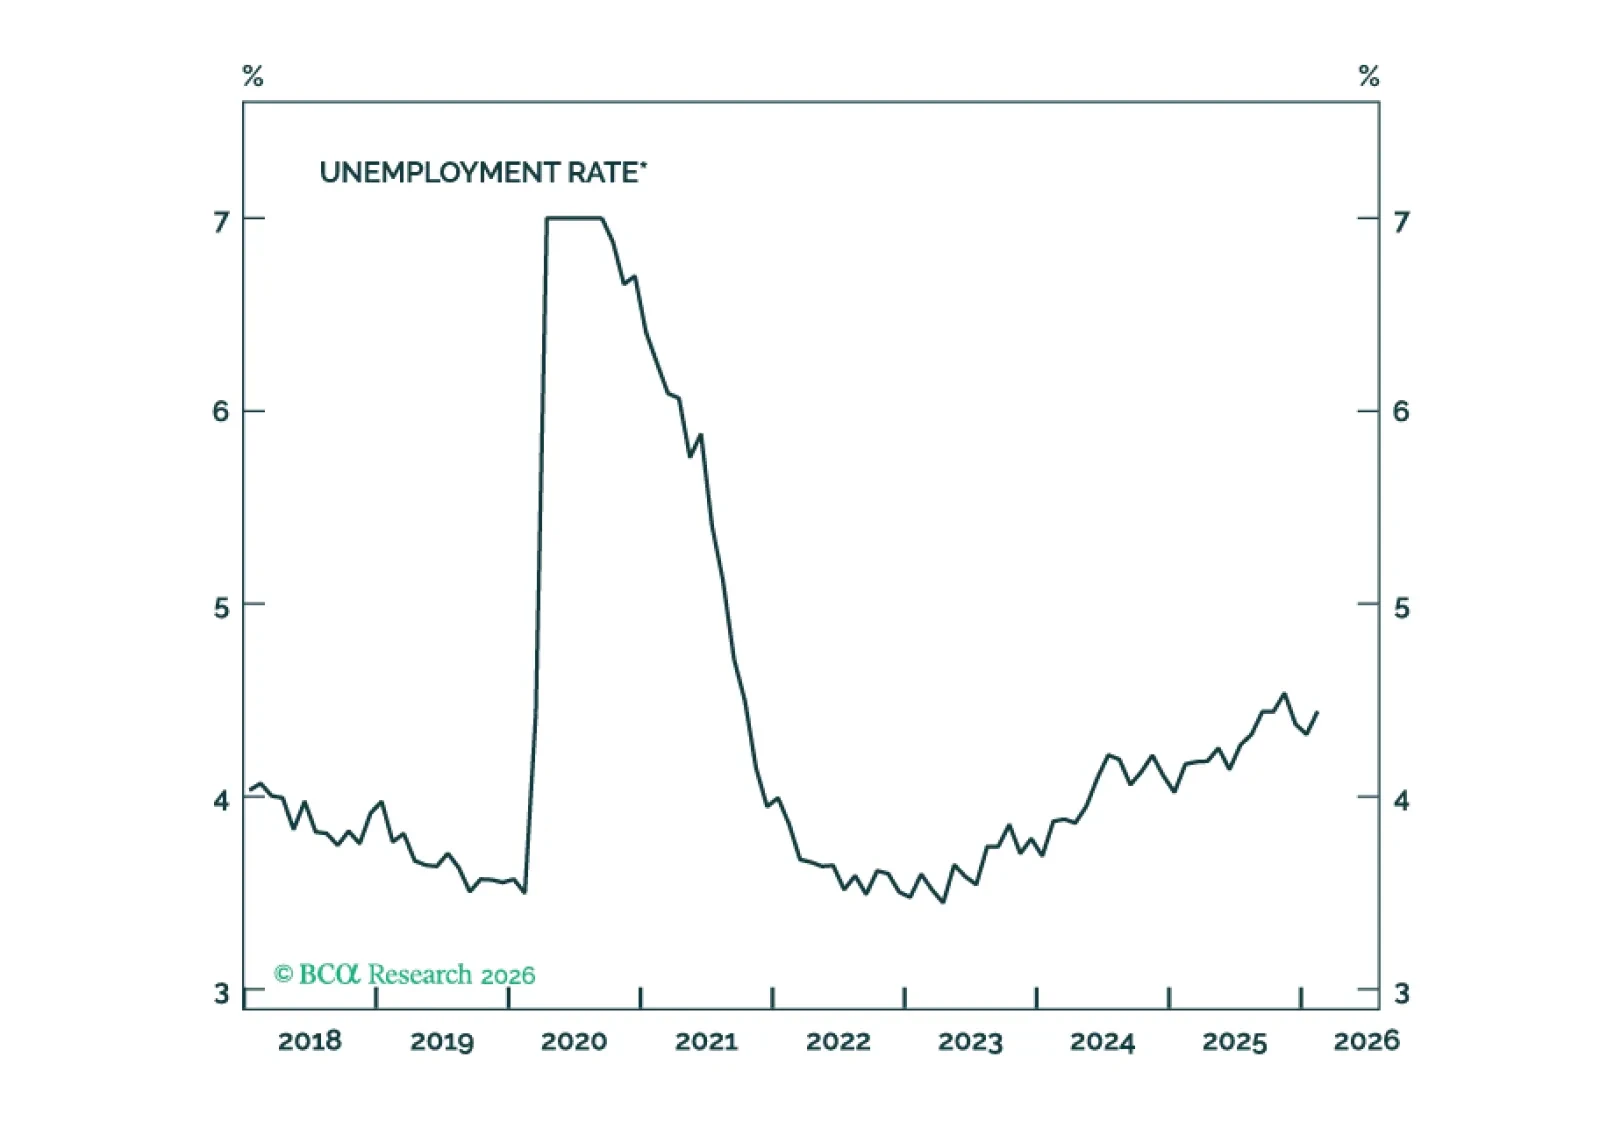
Looking through month-to-month volatility, job growth’s underlying trend is stable and consistent with a flat-to-slightly higher unemployment rate.
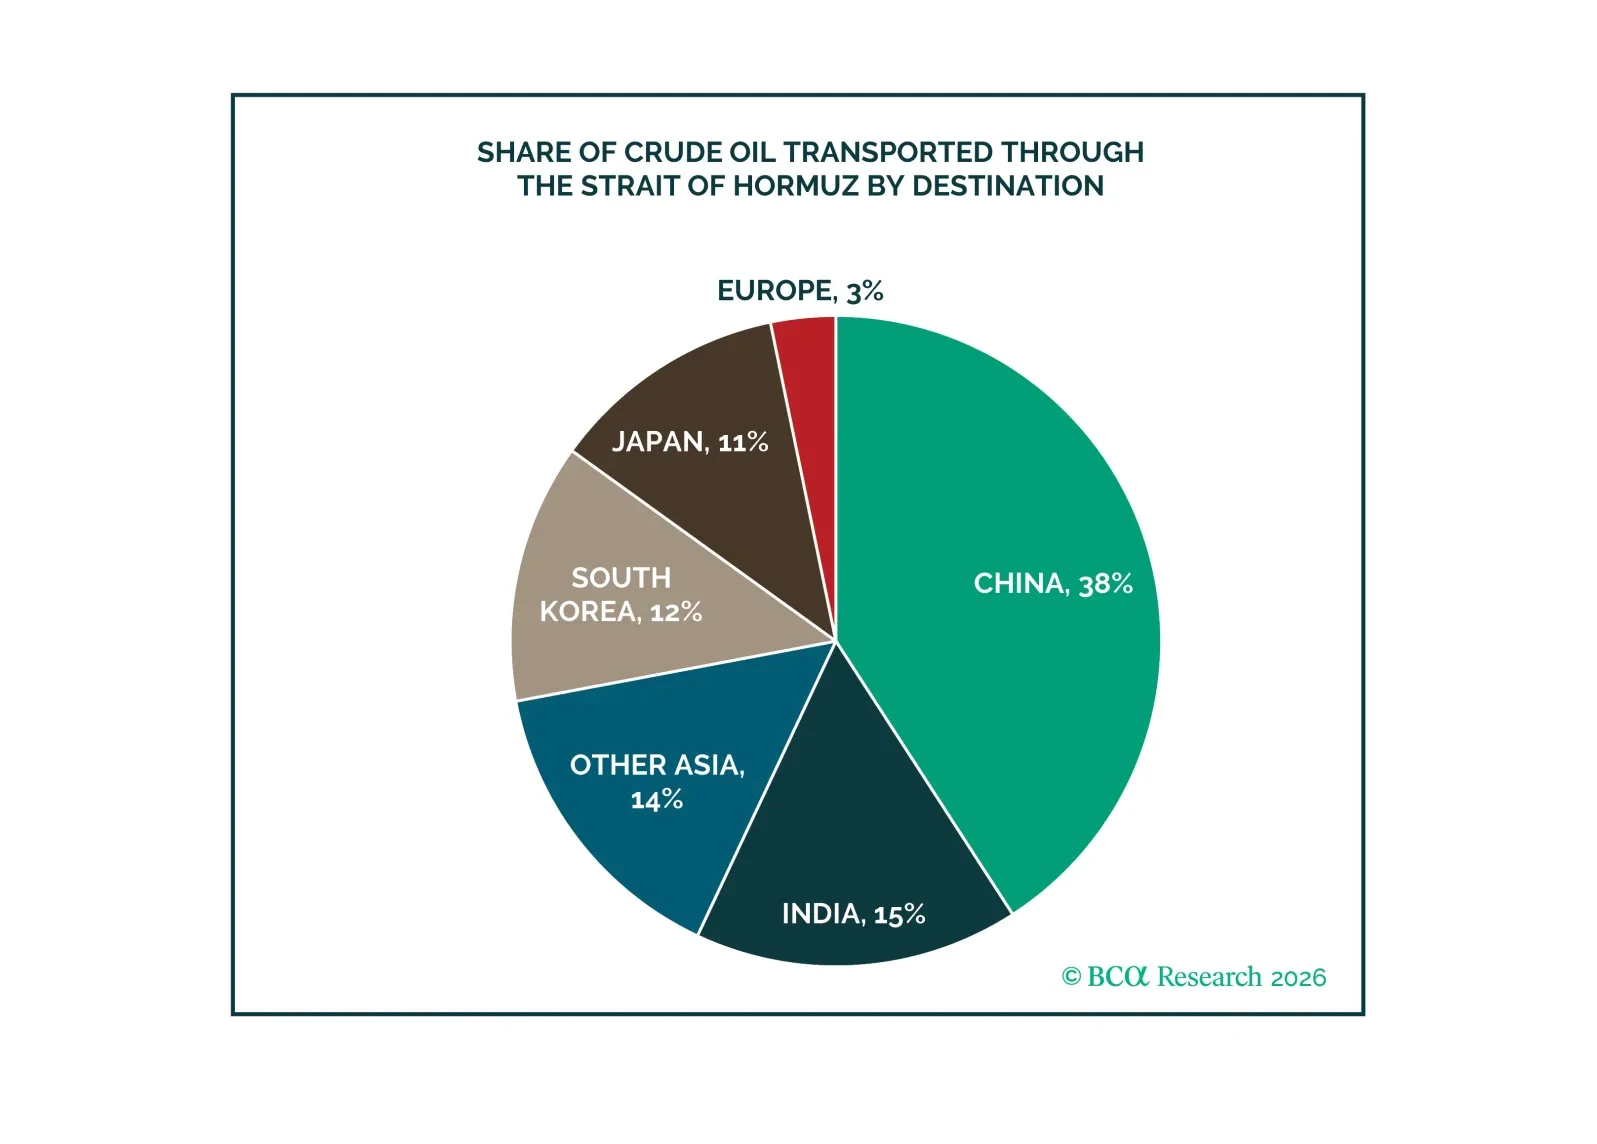
The war in Iran is disrupting global oil and LNG flows and remains a threat to regional energy infrastructure. Energy price risks remain skewed to the upside over the near term.