 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
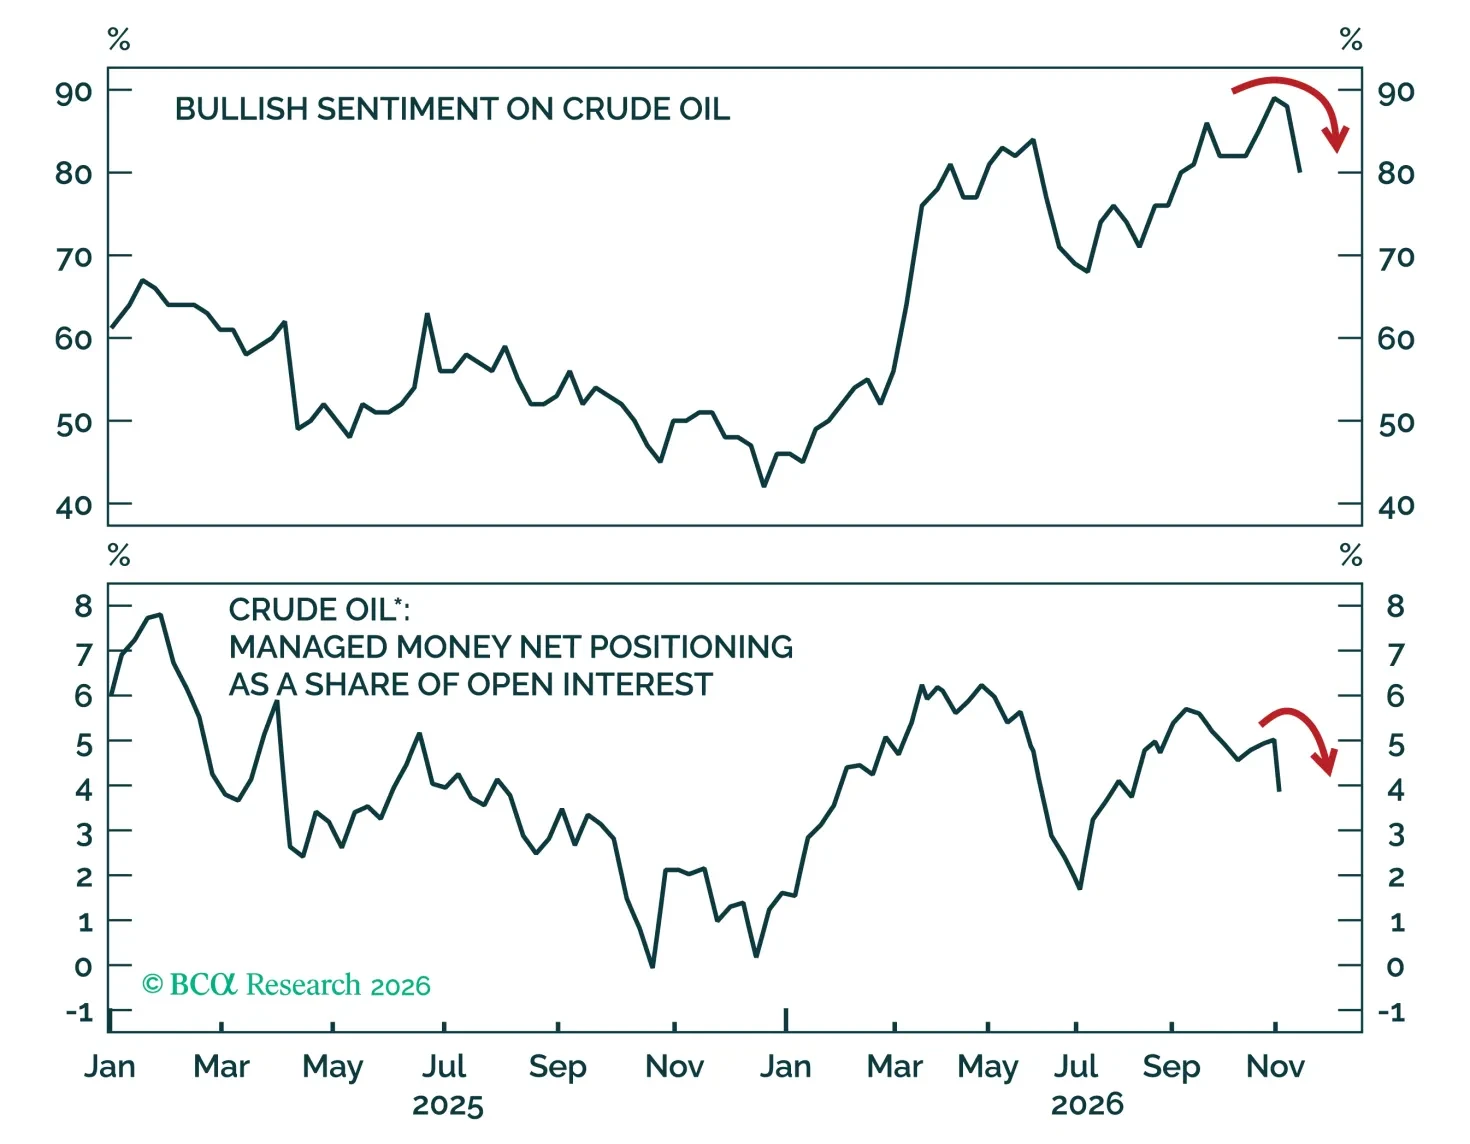
Oil’s recent price slide suggests markets are increasingly pricing in peace. But a swift US-Iran deal is far from assured, and depleted inventories leave prices exposed in the event of a renewed supply disruption. We explain why price risks now tilt higher.
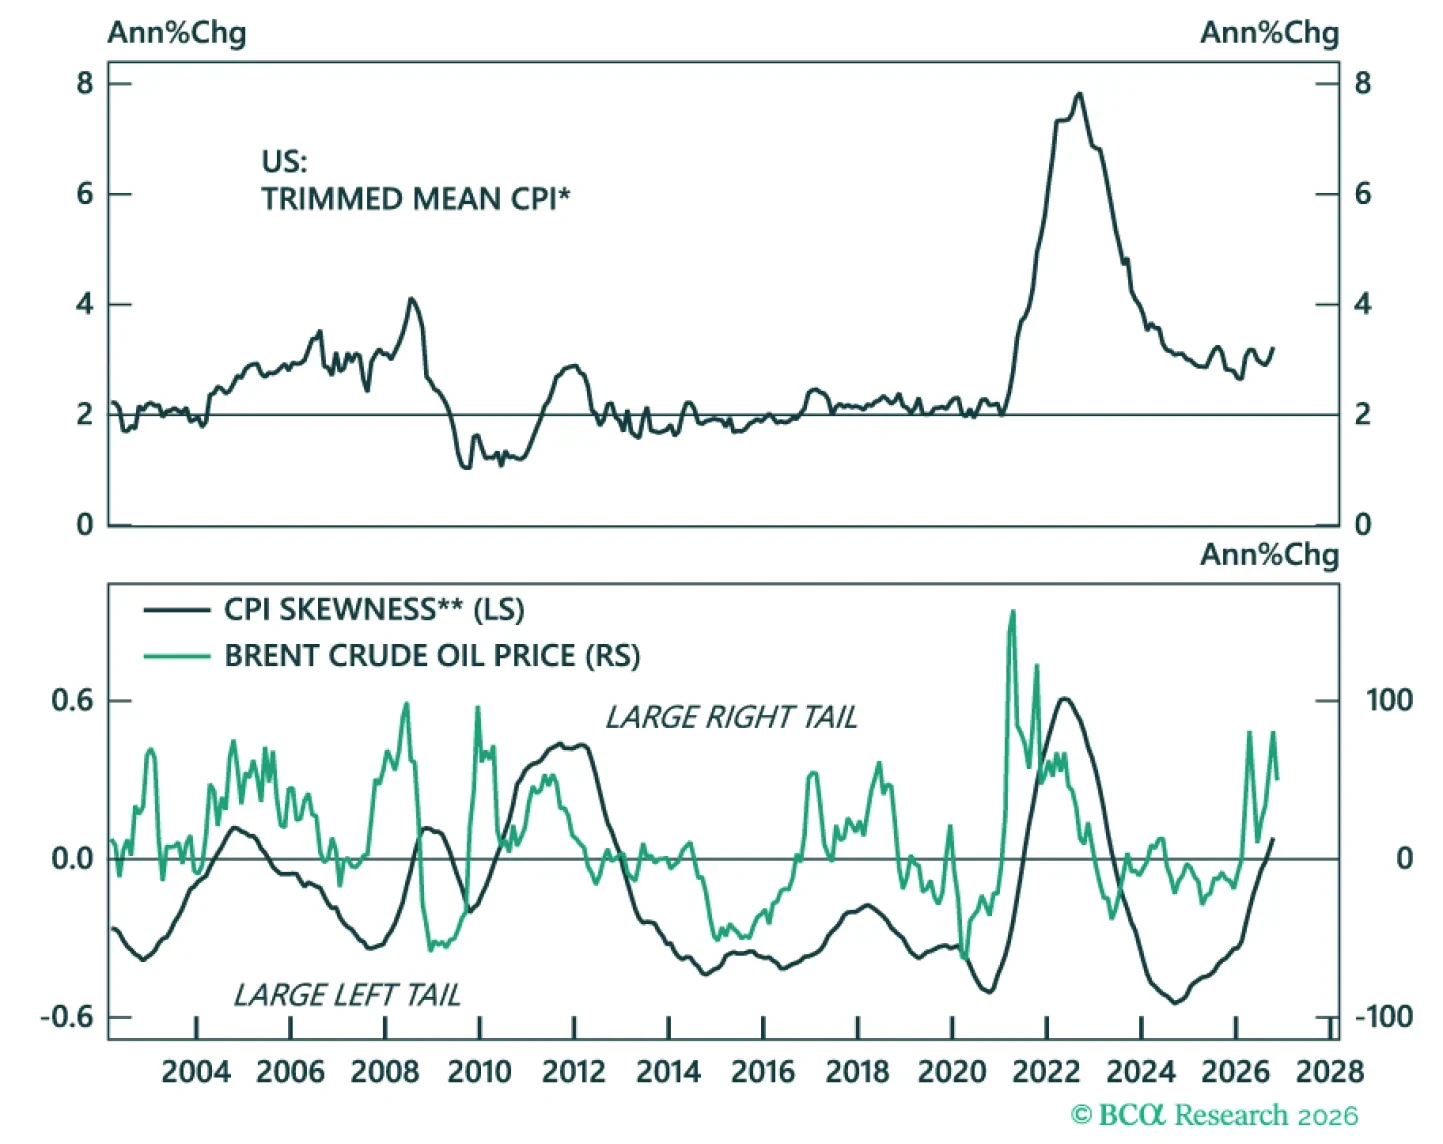
Central banks are trying to separate a narrow energy shock from broader inflation pressure. We introduce a trimmed mean, skew, and breadth diffusion measure to make that distinction across seven developed economies, and assess what it means for policy paths and bond positioning.
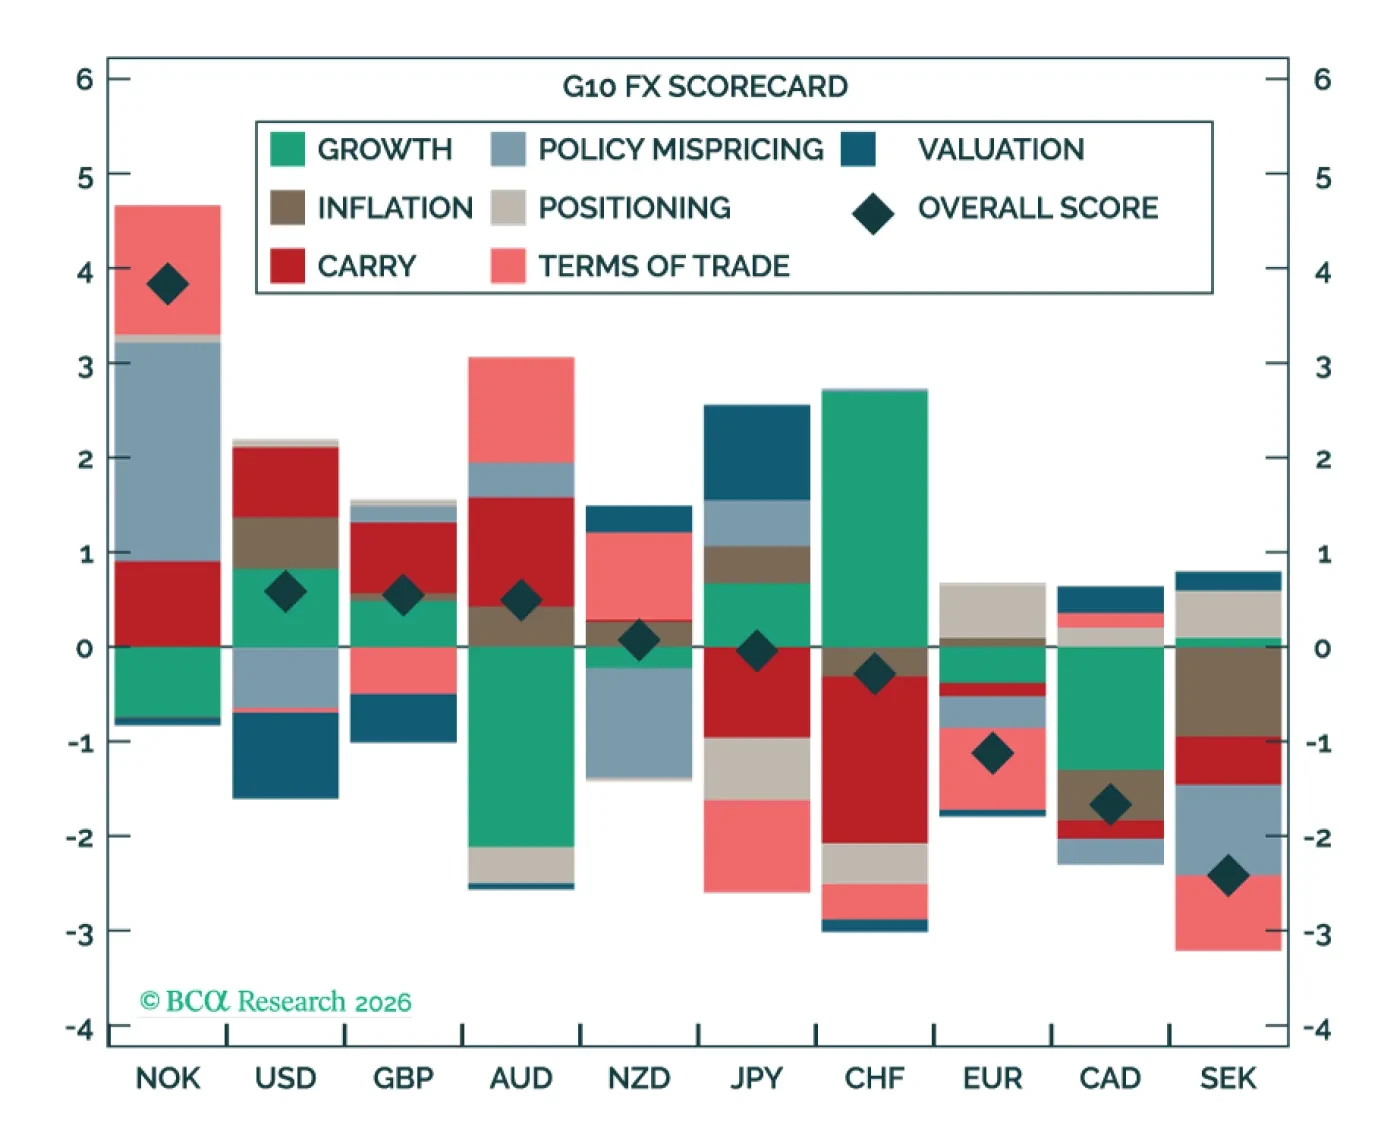
Carry still leads the G10 FX Scorecard, but diverging growth, inflation and rate signals suggest the cycle that drove returns over the past year may be nearing a turning point. We are shortening our horizon and watching for rotation opportunities in 2027.
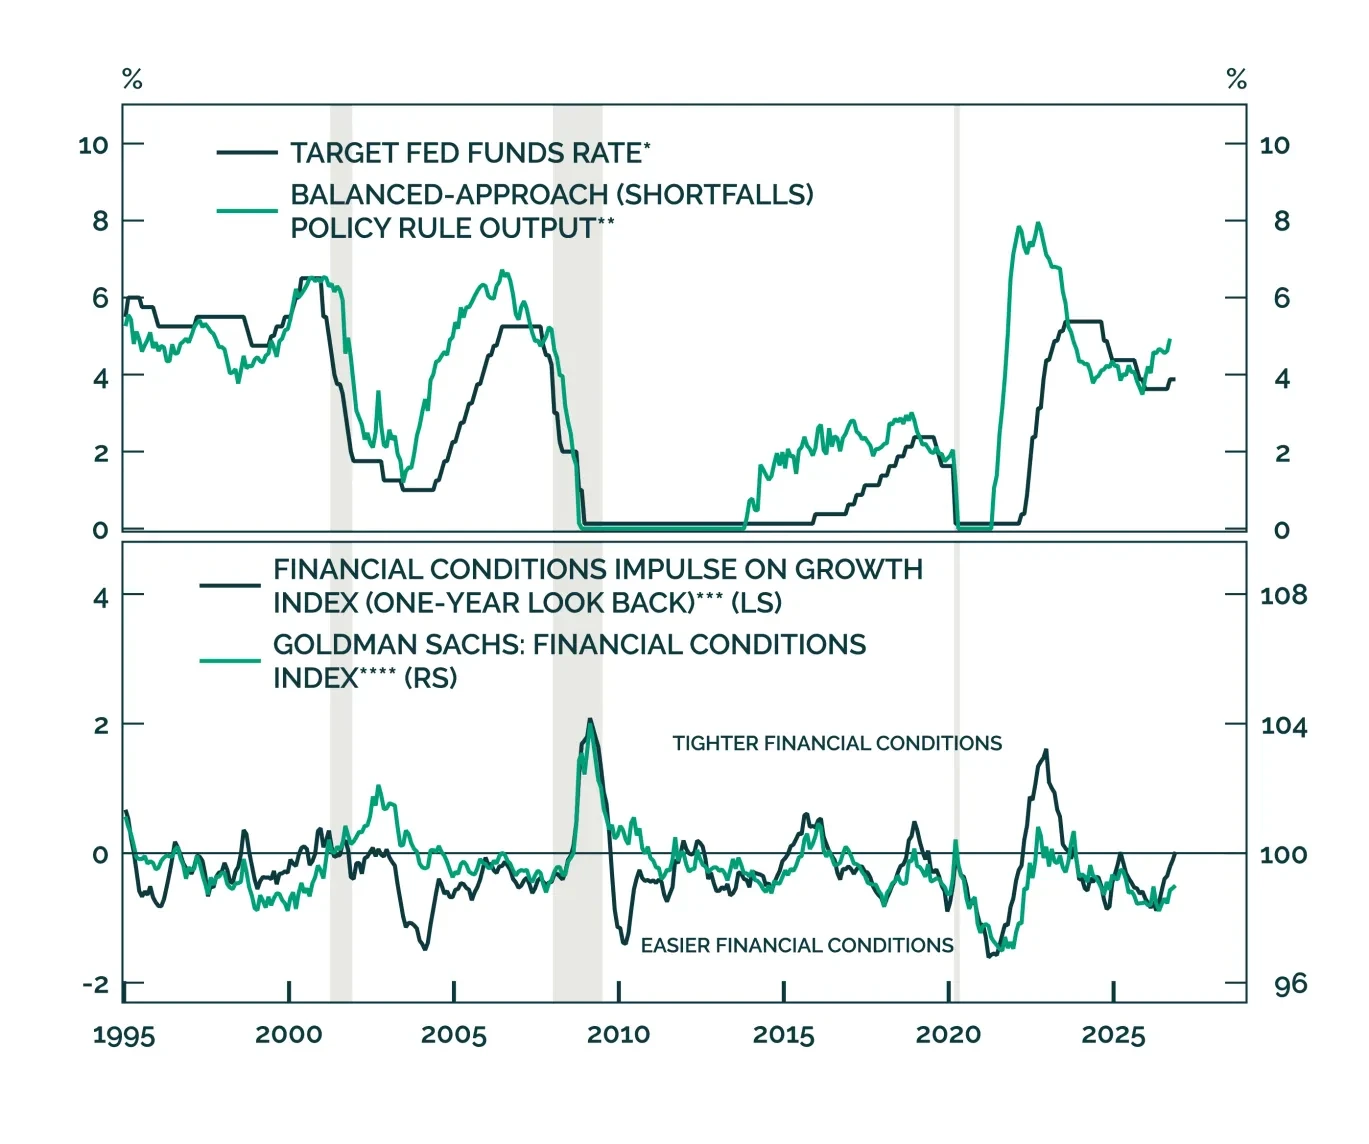
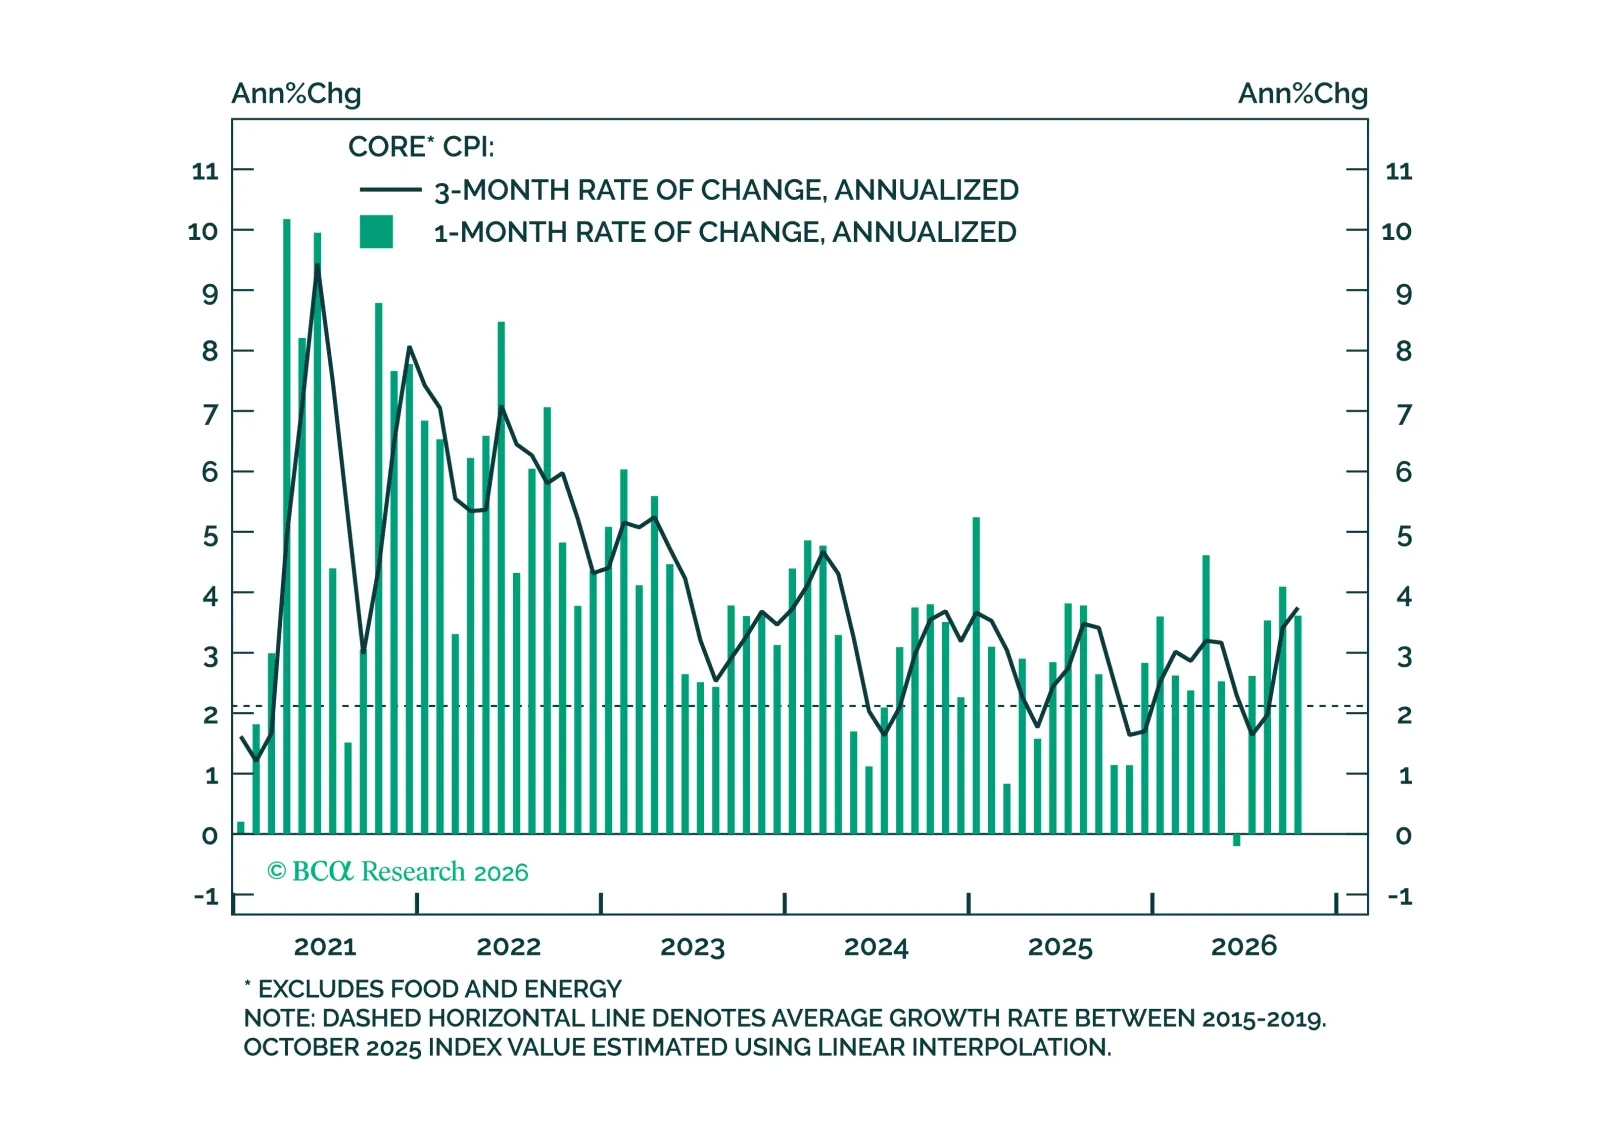
The US economy is not overheating, but shocks related to tariffs, energy and computer chips are keeping core inflation above target. These shocks will eventually fade, but likely not in the next few months.
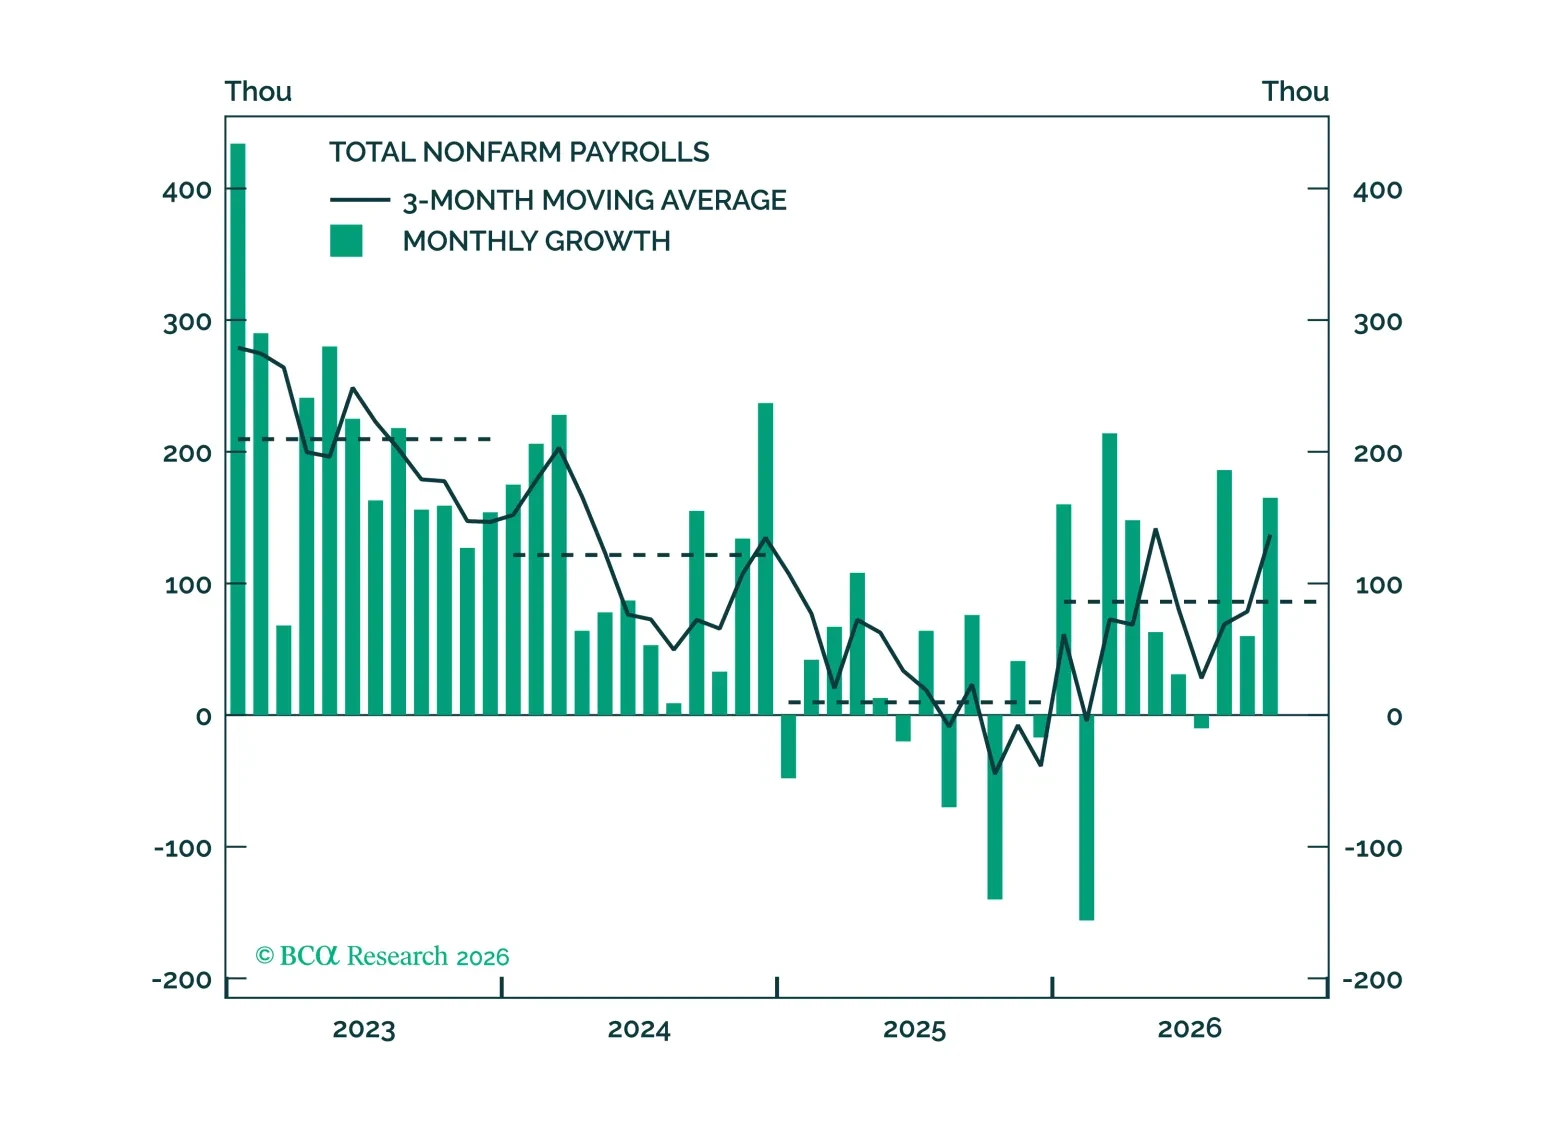
Please note that going forward we will no longer send email alerts when we publish our regular US labor market and inflation chartpacks. These chartpacks will still be published on the website on days of US employment report and CPI releases.
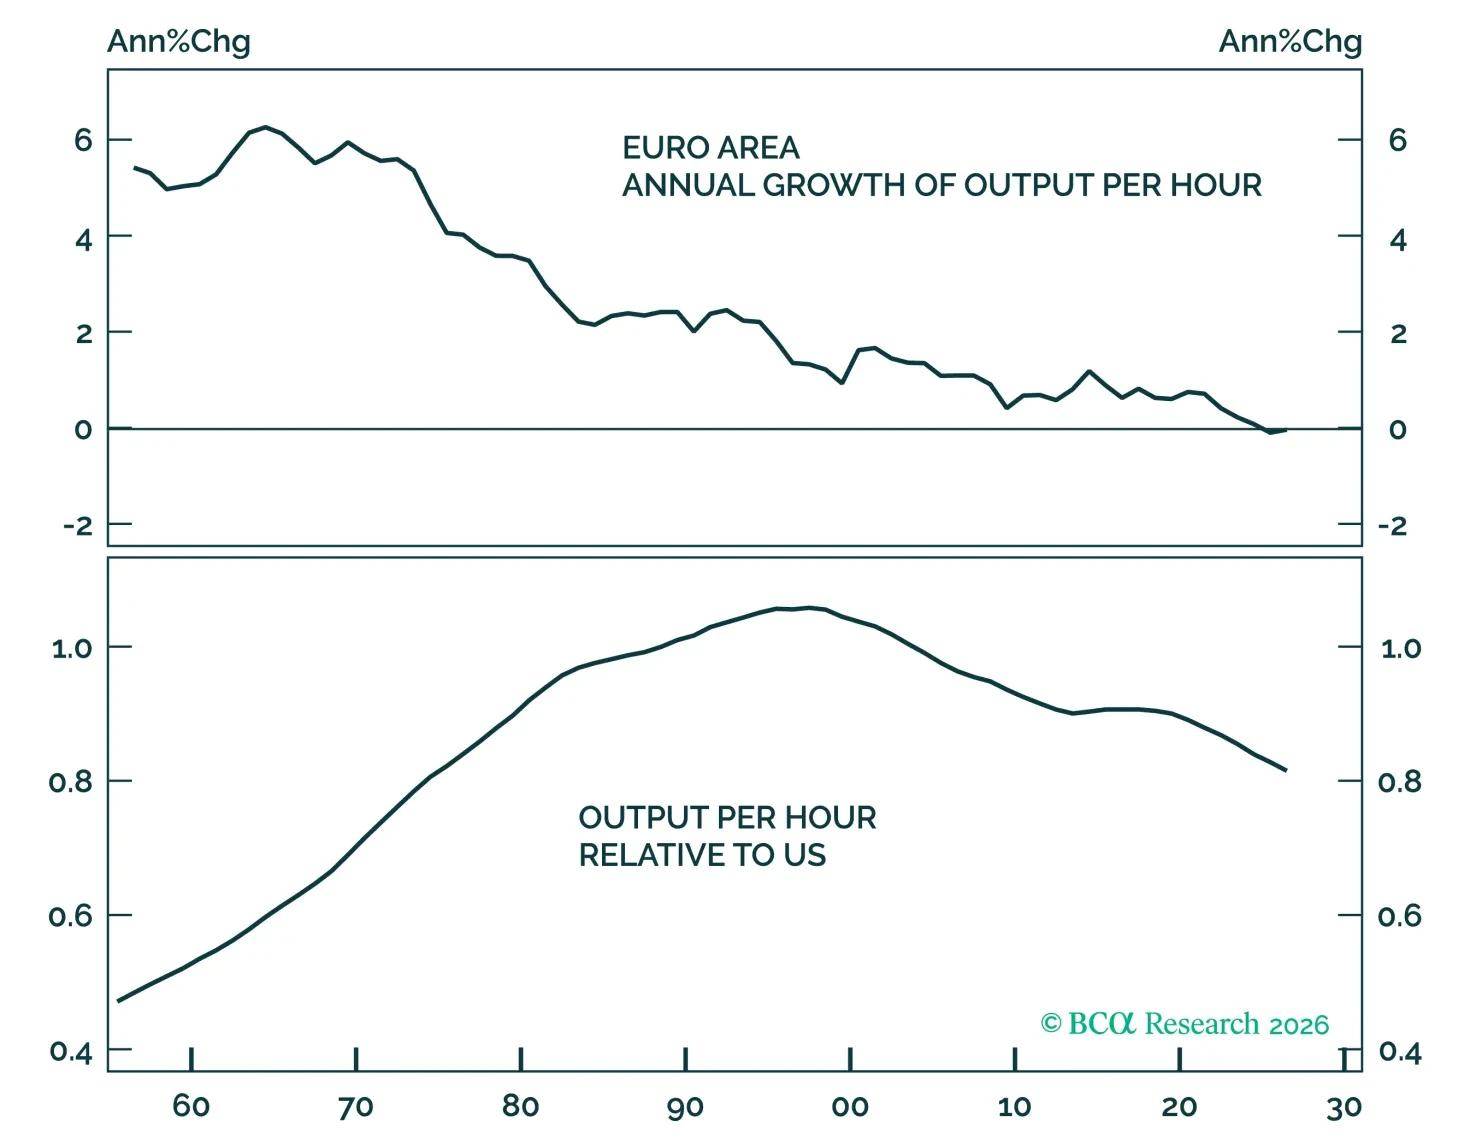
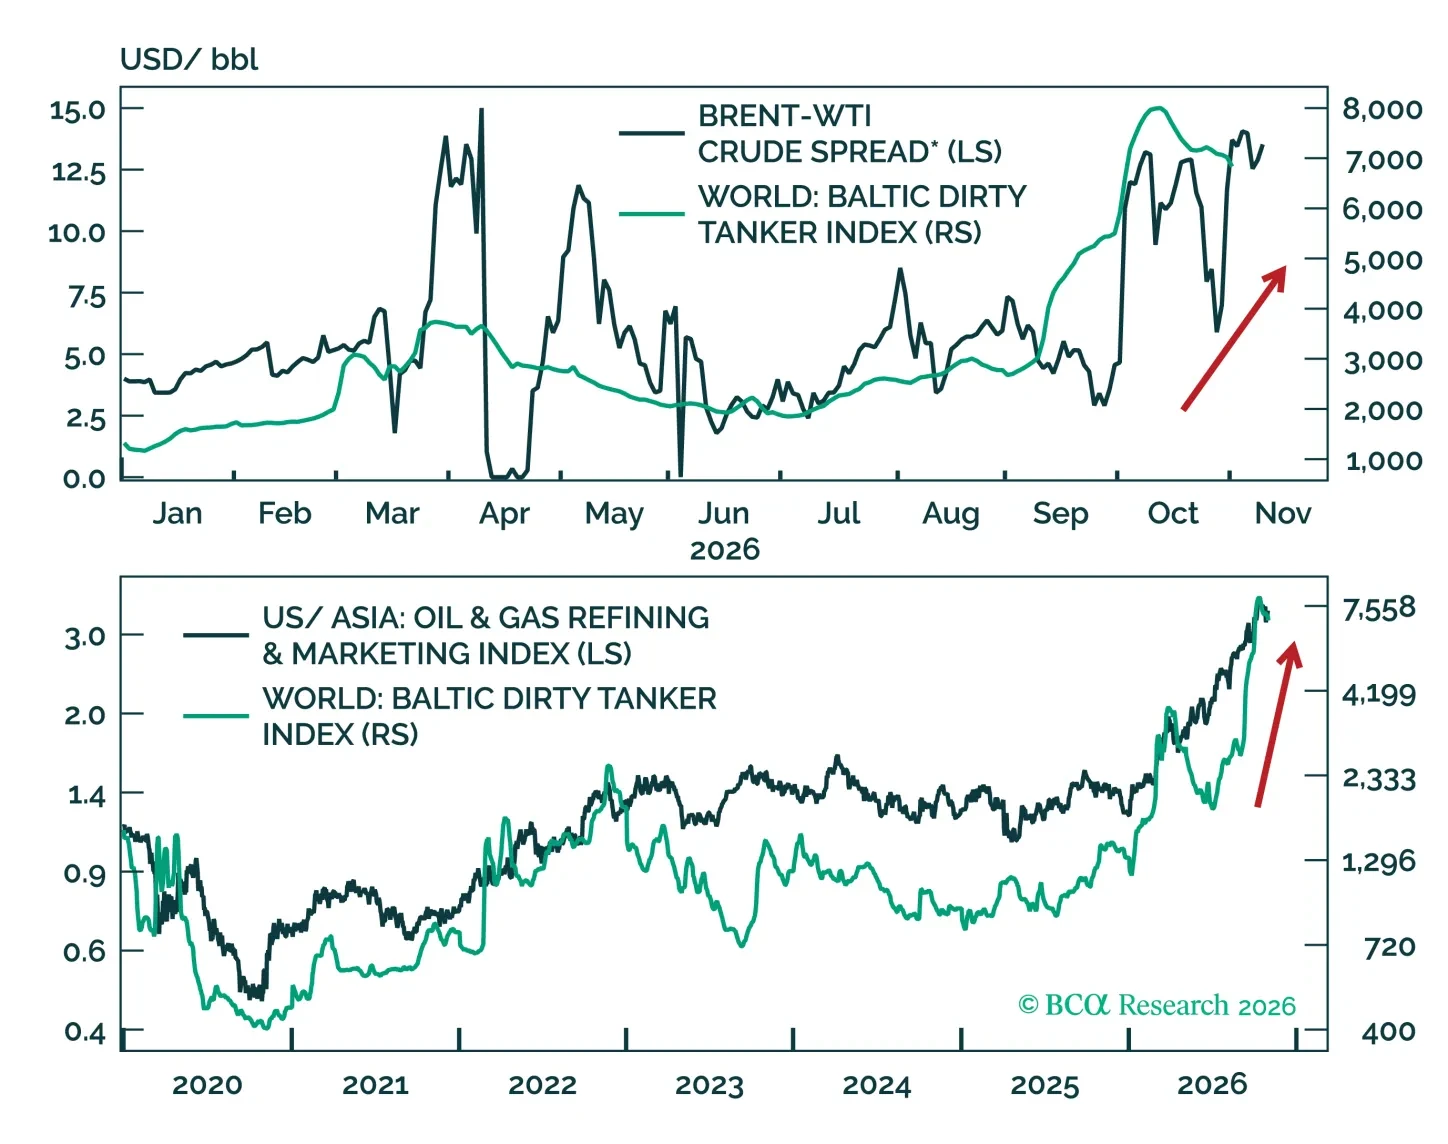
Commodities have diverged sharply in recent months. We explain why energy prices are likely to stay elevated after the US midterms, why gold’s slide should prove limited, and how we are positioning for the months ahead.
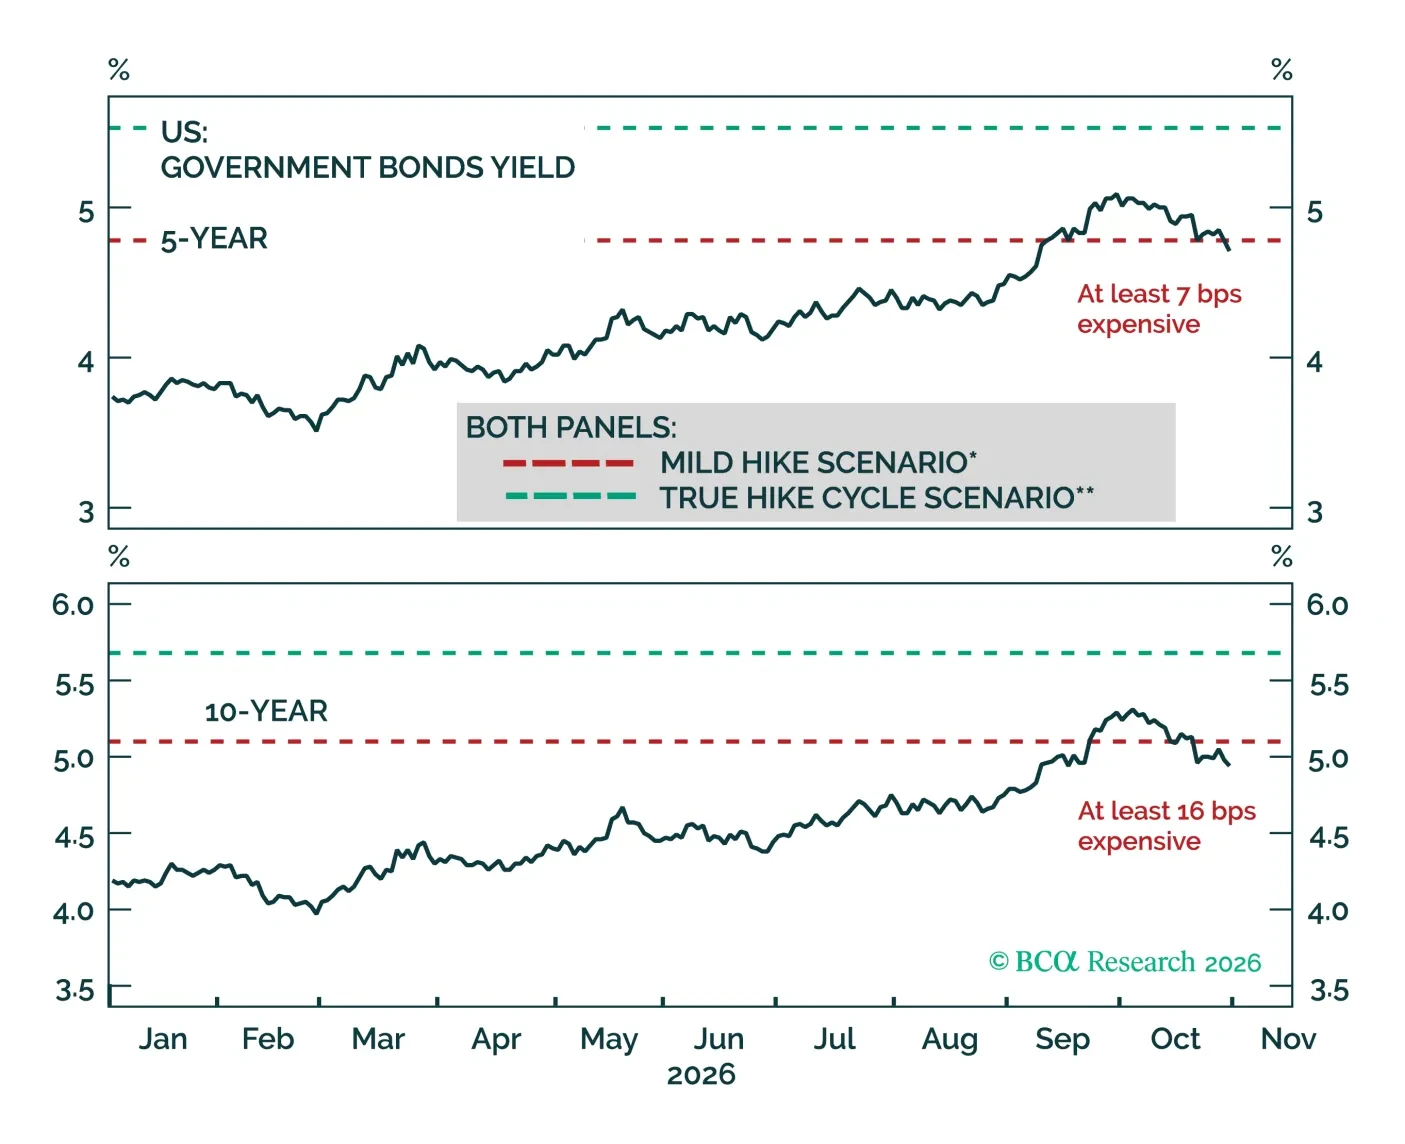
US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.
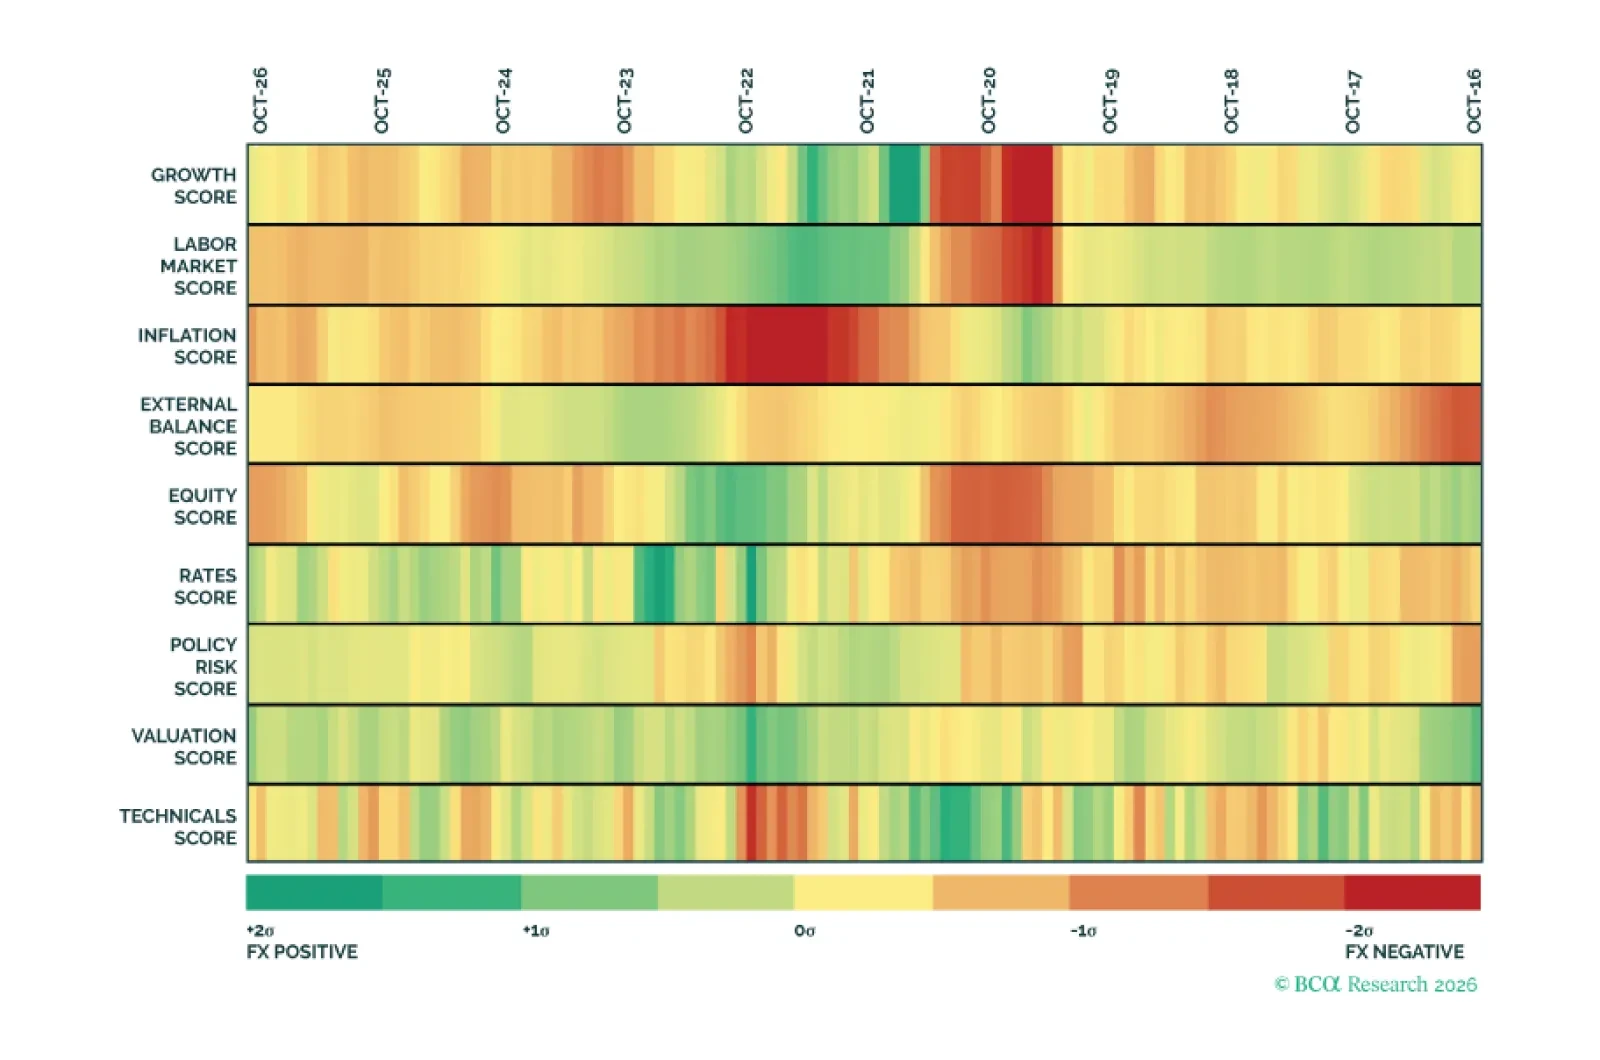
GBP offers attractive carry today, but the market’s aggressive rate hike pricing is likely to turn into a headwind within 12 months. Our latest Currency Chartpack examines the valuation, growth, rate, and policy drivers of the pound, showing why the long-term outlook is less rosy than near-term data implies.