 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
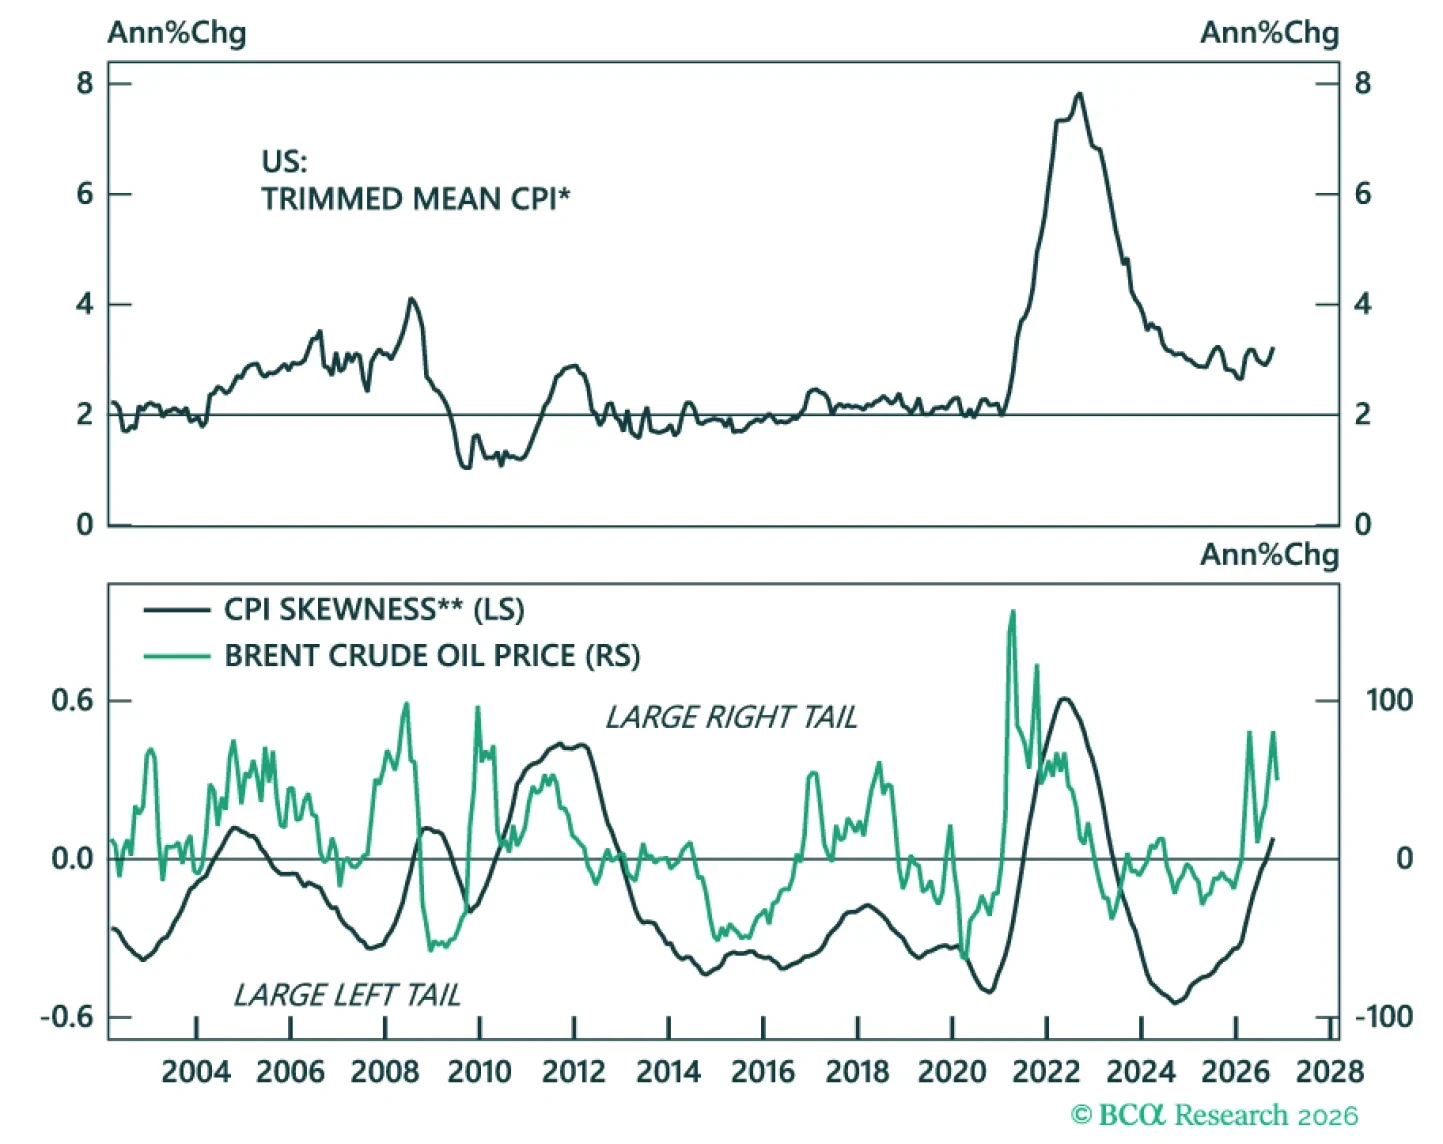
Central banks are trying to separate a narrow energy shock from broader inflation pressure. We introduce a trimmed mean, skew, and breadth diffusion measure to make that distinction across seven developed economies, and assess what it means for policy paths and bond positioning.
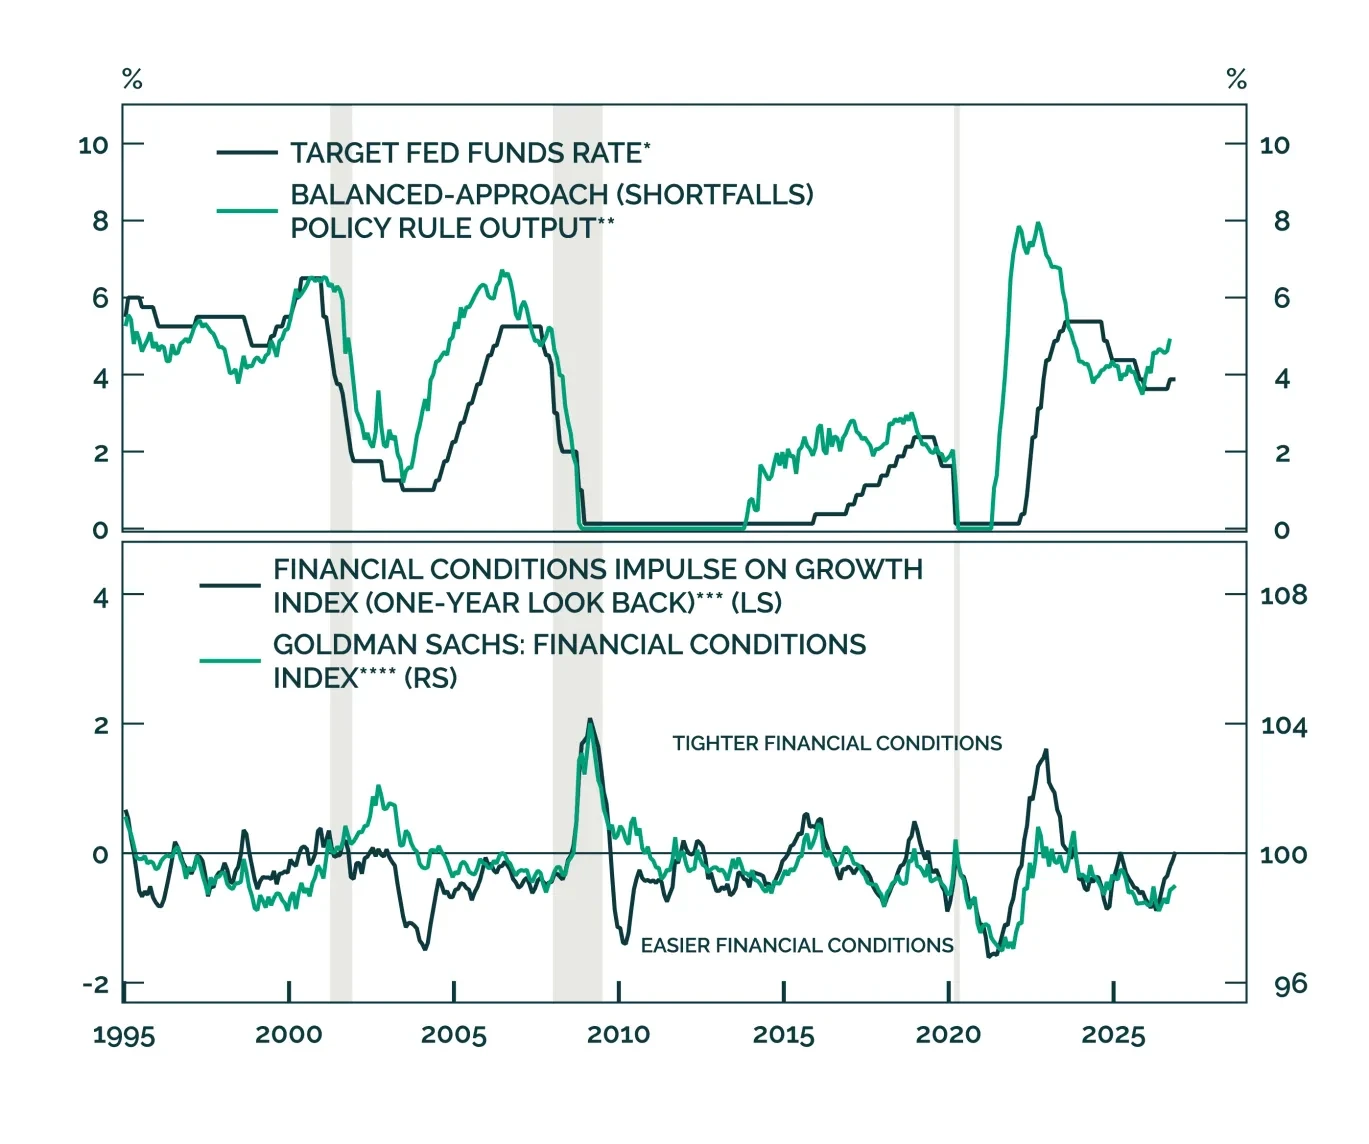
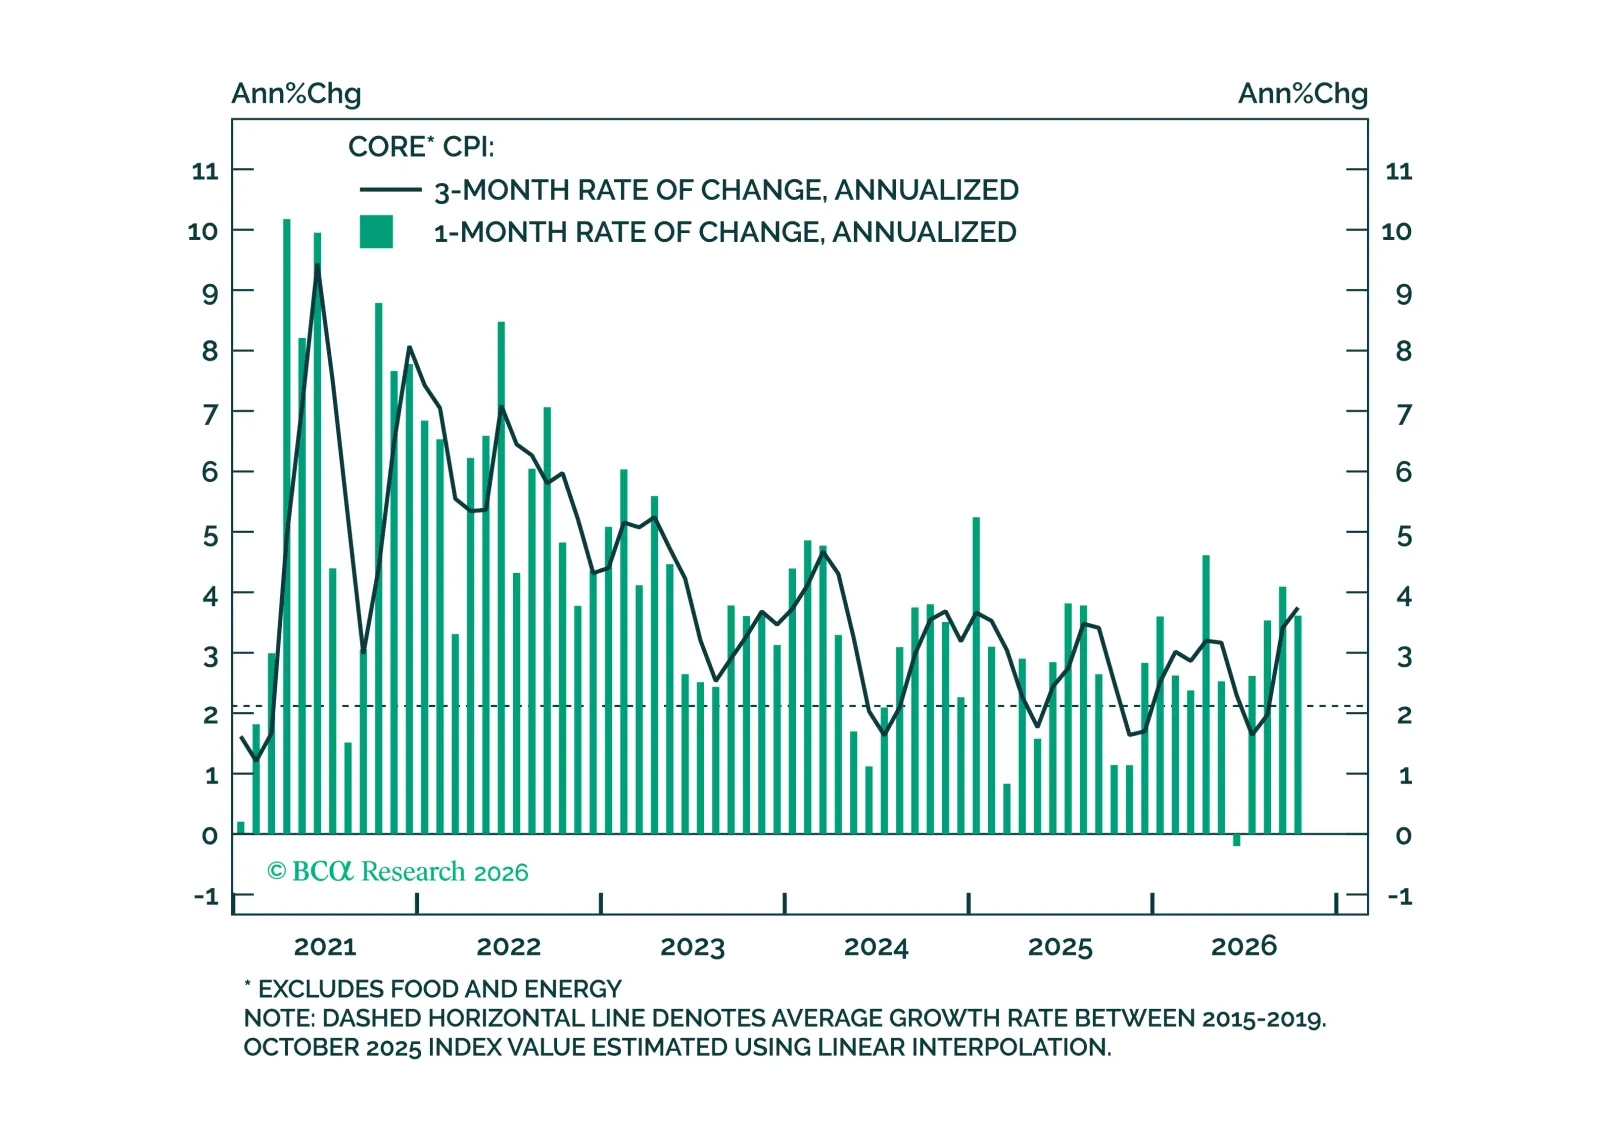
The US economy is not overheating, but shocks related to tariffs, energy and computer chips are keeping core inflation above target. These shocks will eventually fade, but likely not in the next few months.
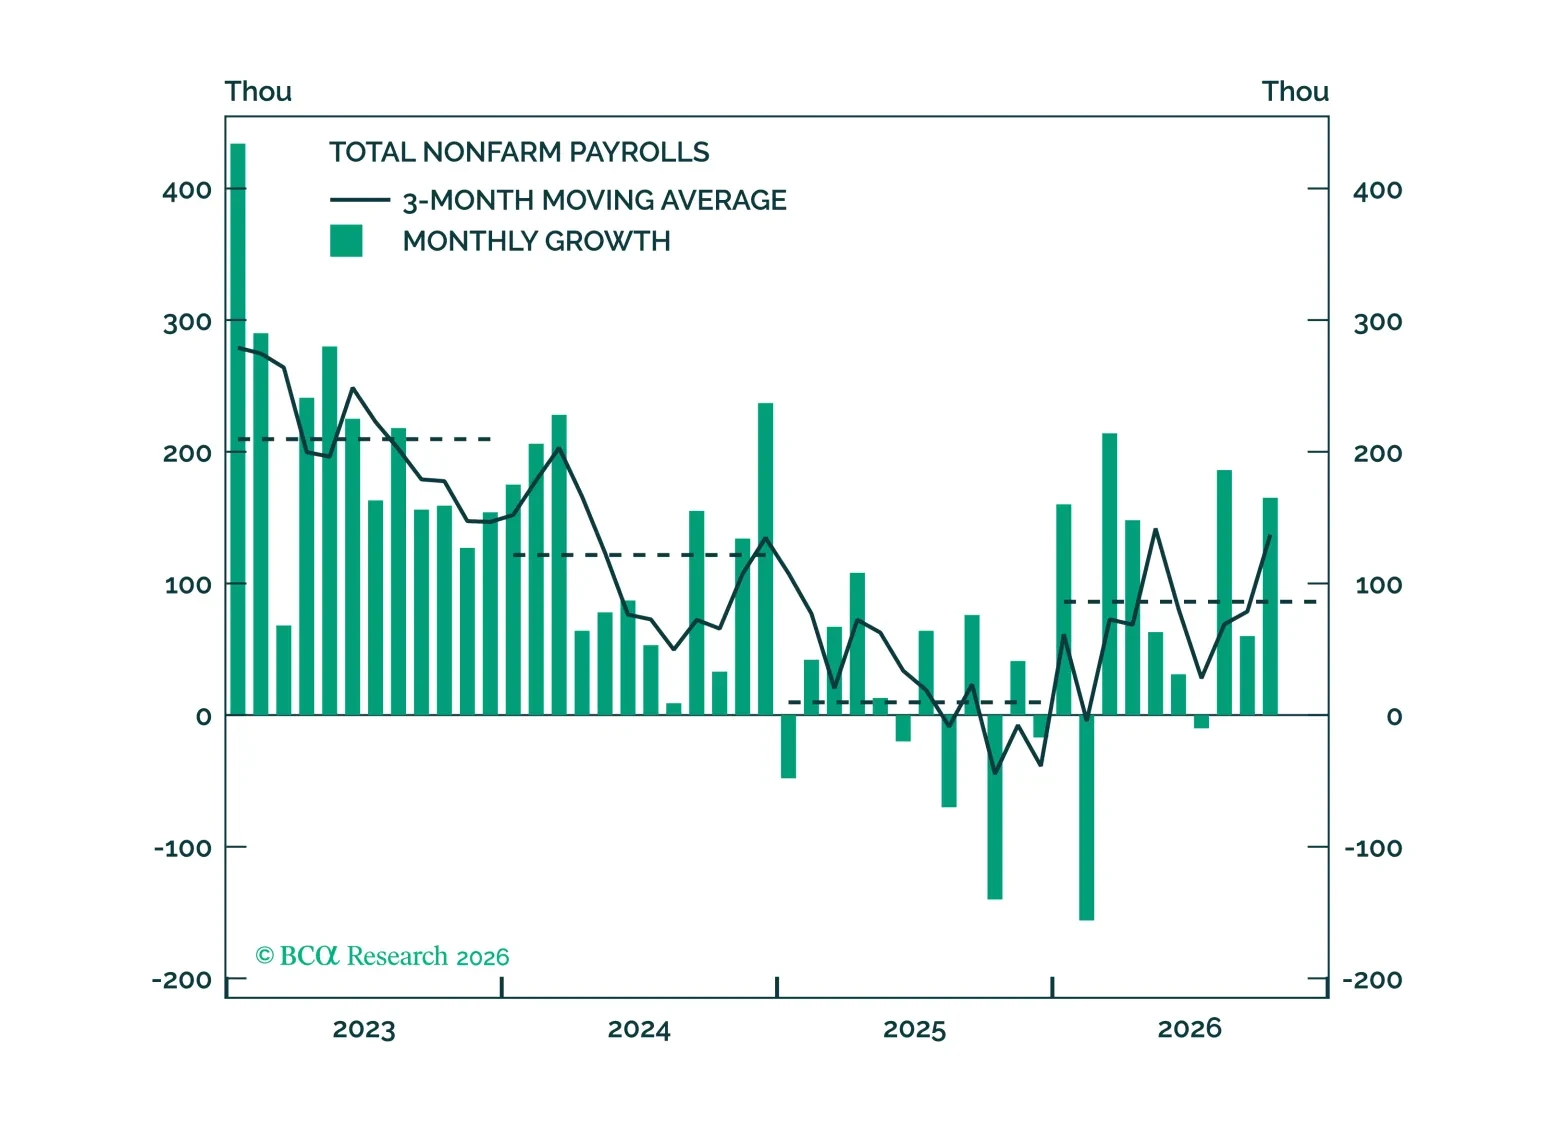
Please note that going forward we will no longer send email alerts when we publish our regular US labor market and inflation chartpacks. These chartpacks will still be published on the website on days of US employment report and CPI releases.
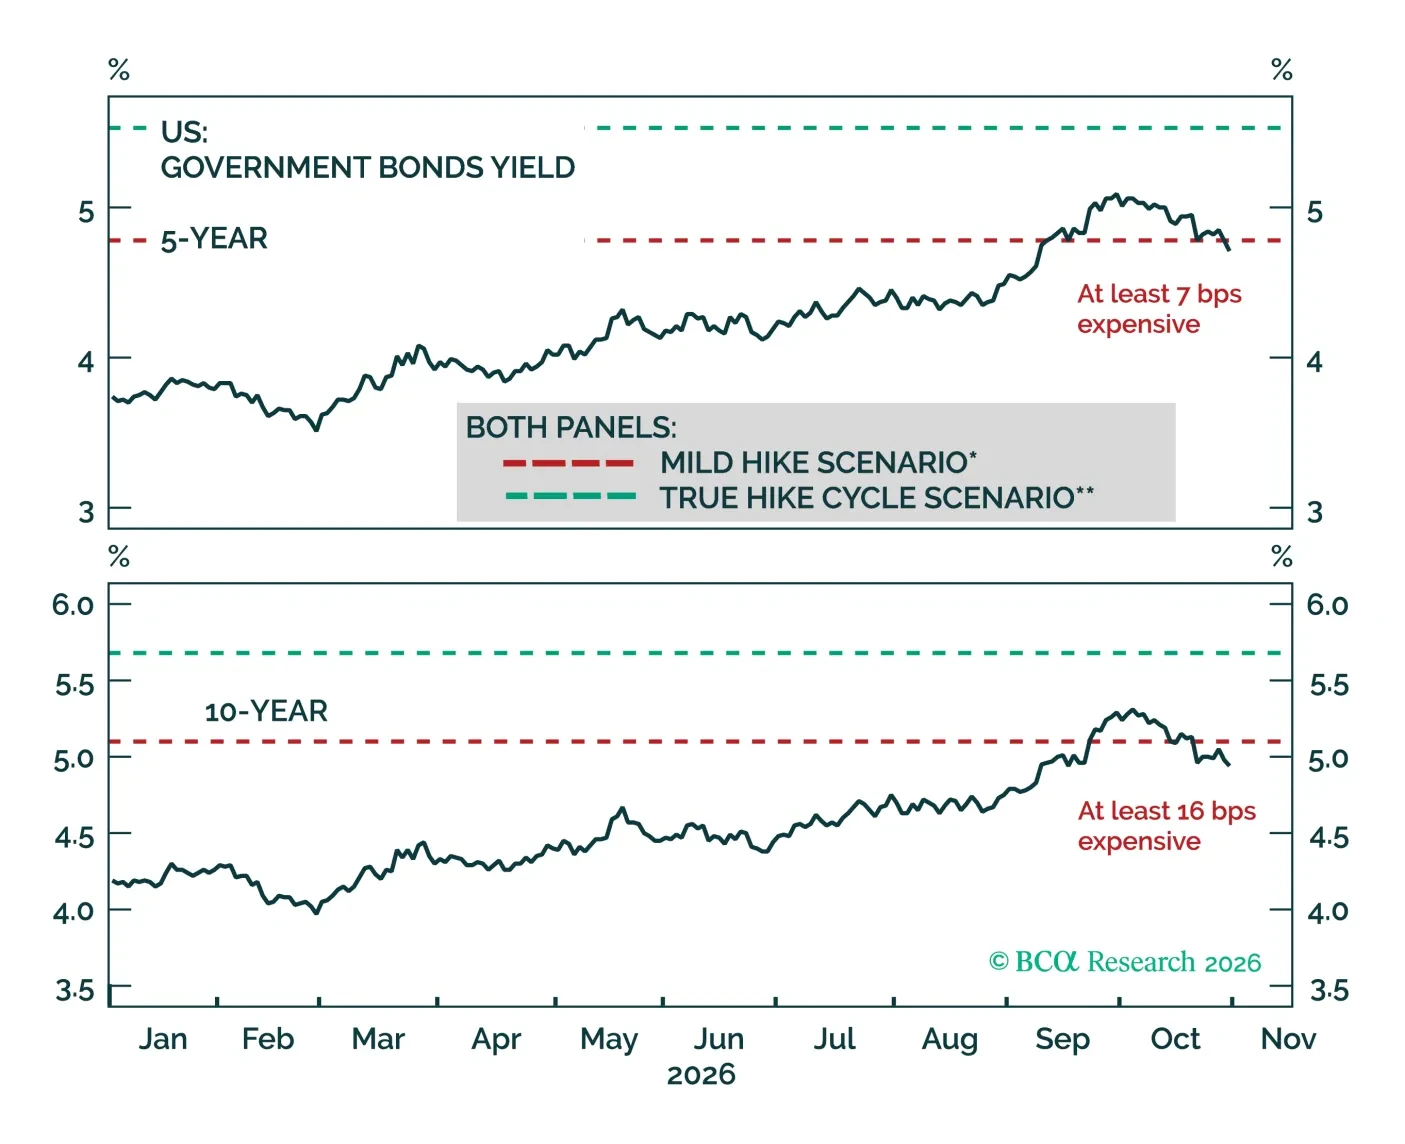
US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.
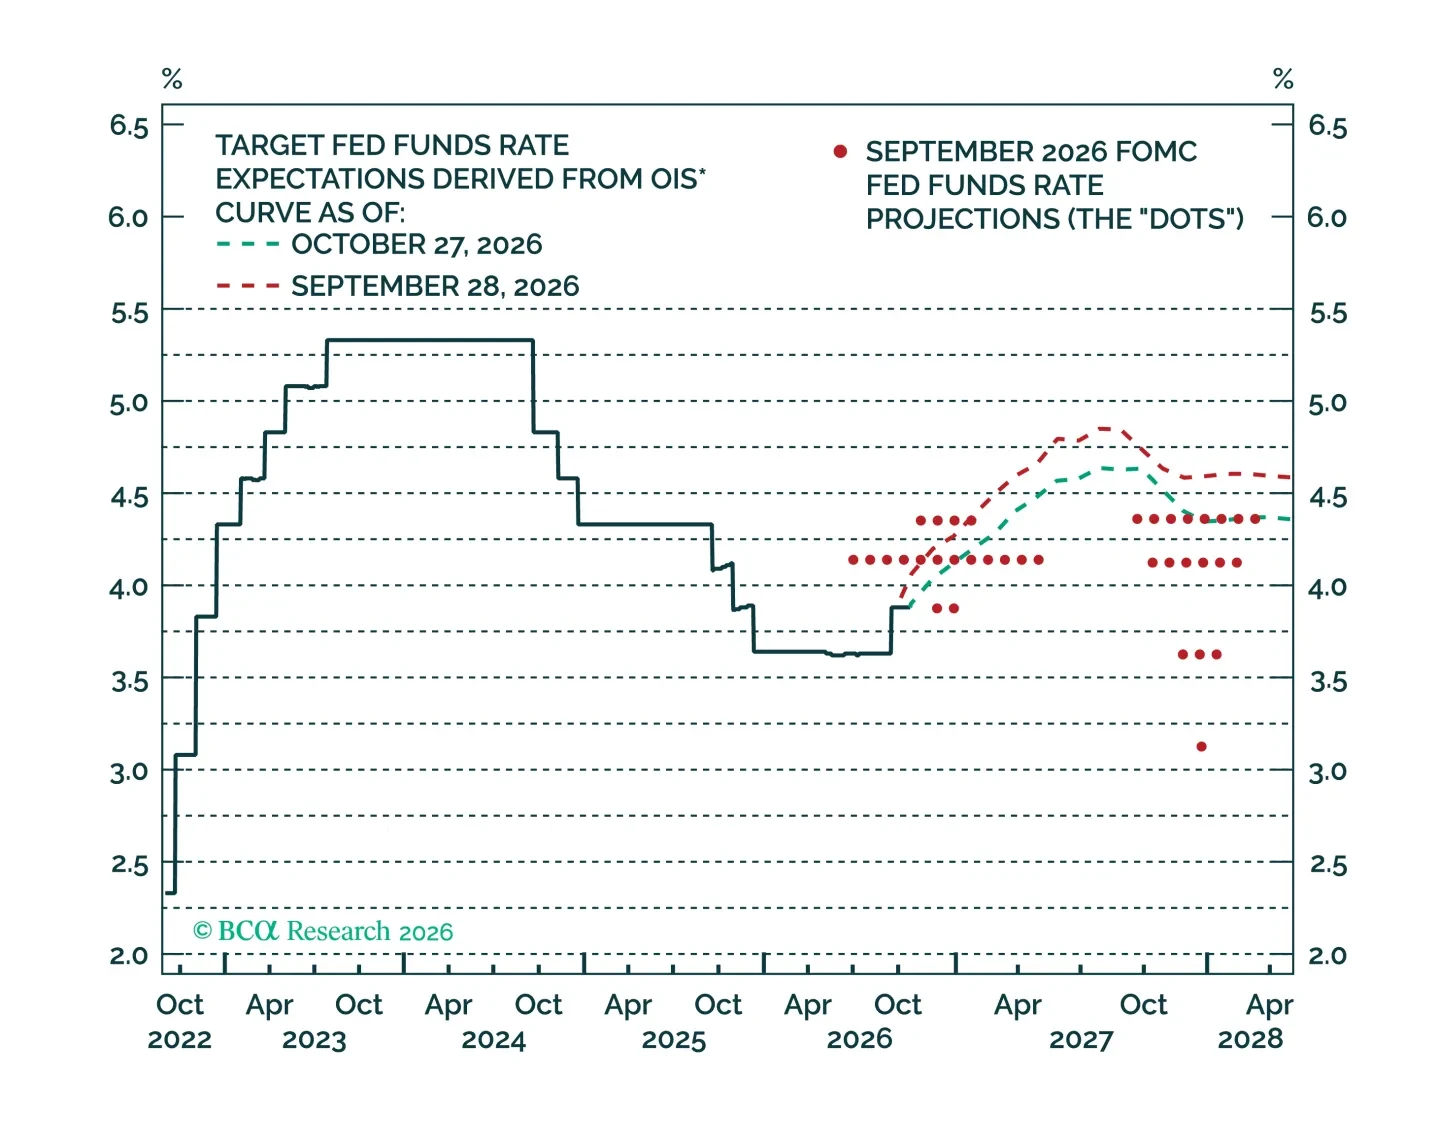
The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.
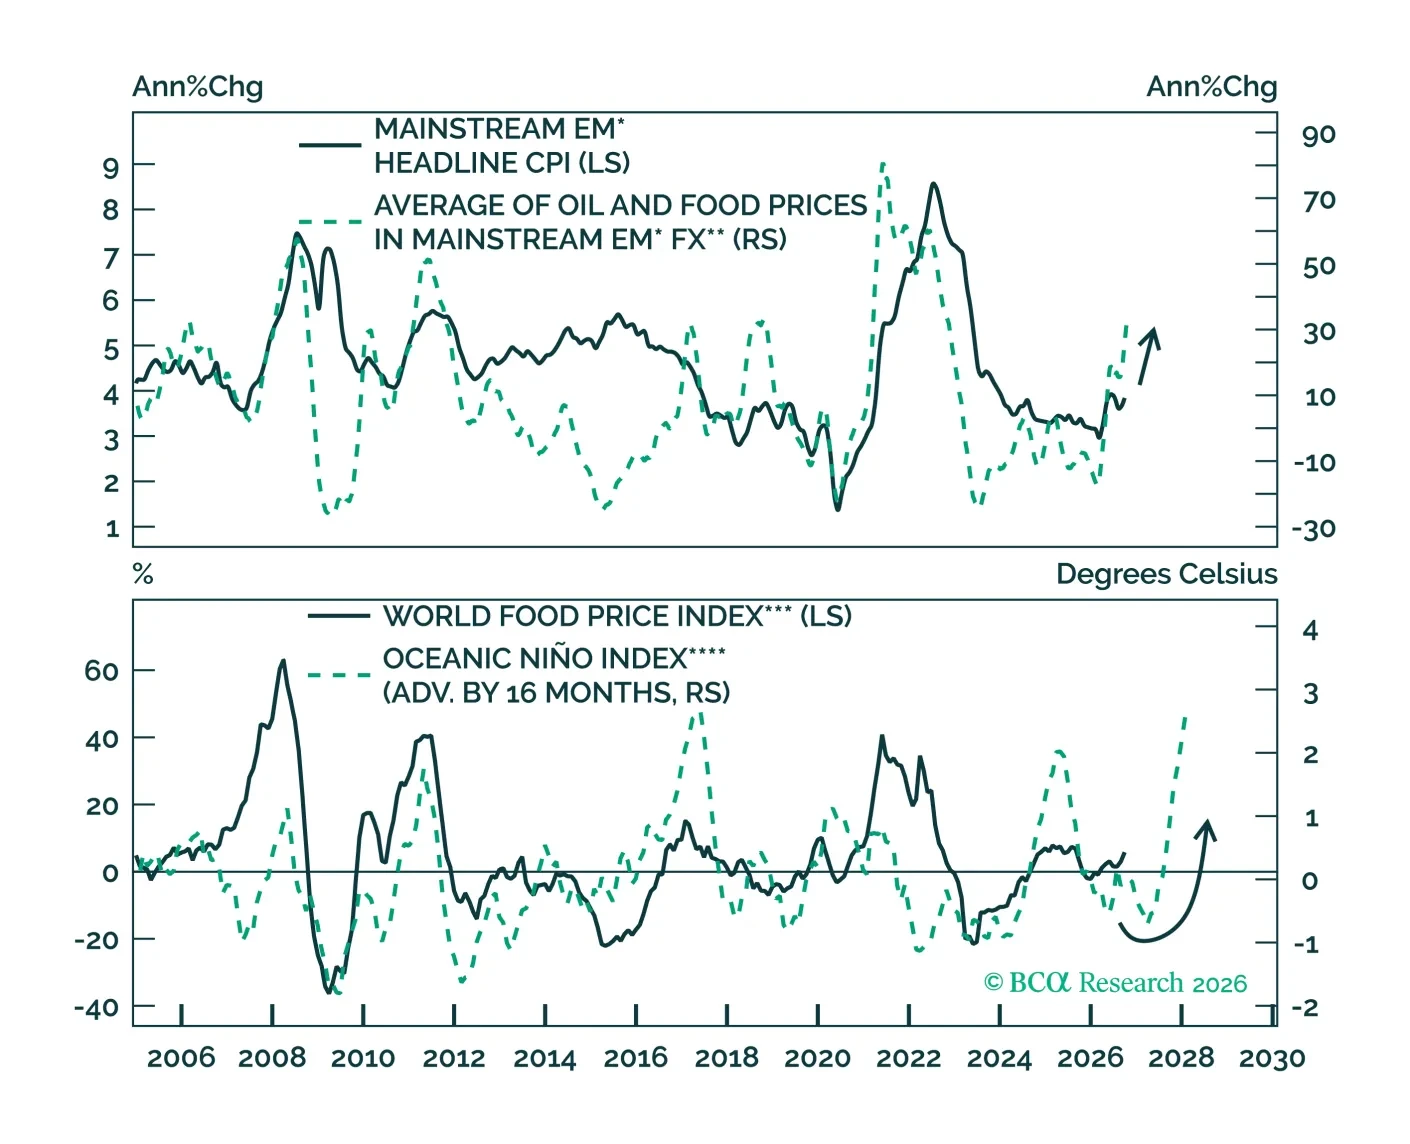
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.