 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
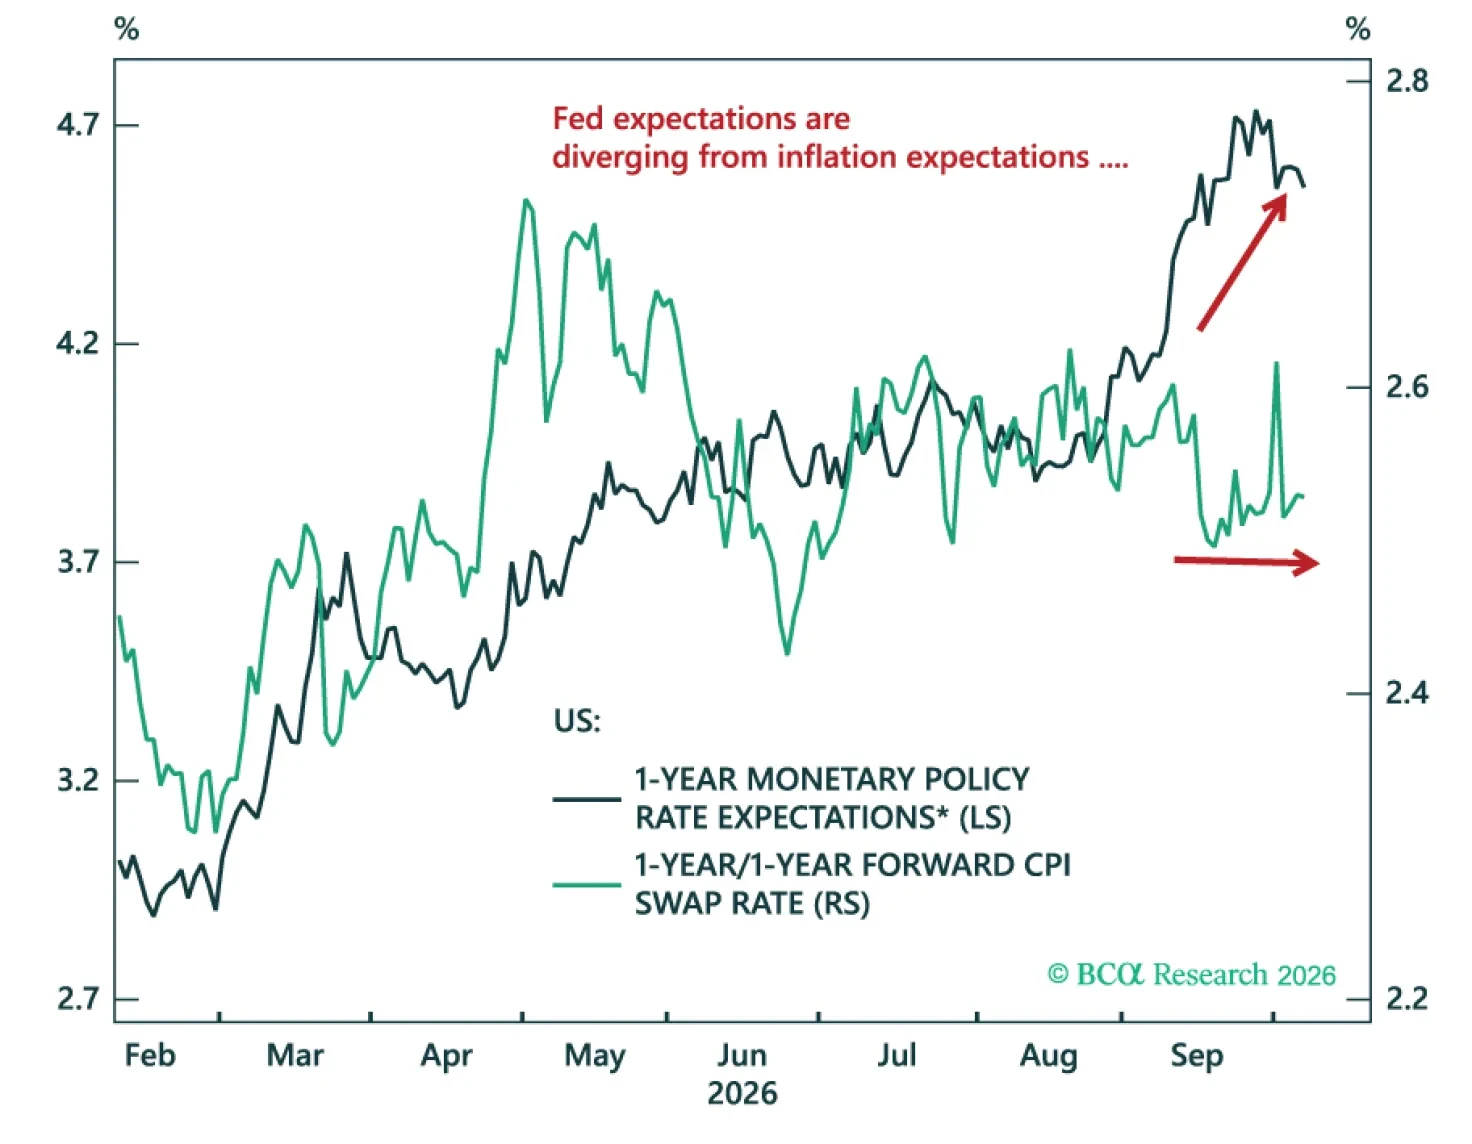
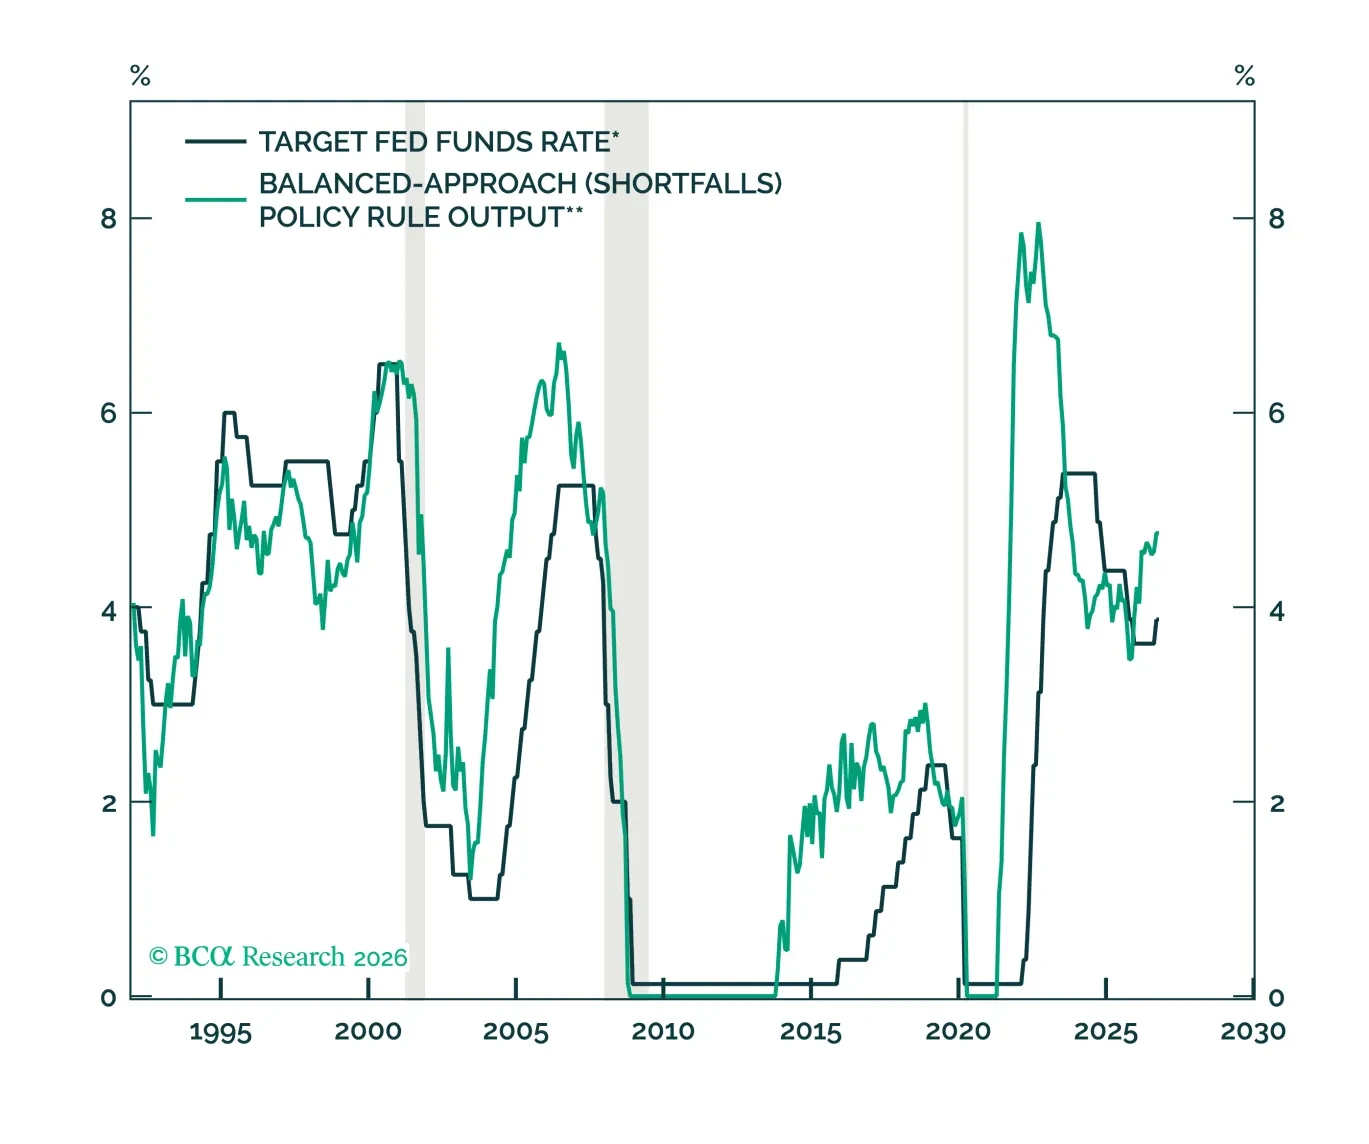
We review our Model Bond Portfolio performance for Q3 and look ahead as energy prices continue to drive fixed income markets. Balanced labor markets point to a mild tightening cycle, creating opportunities in government bonds and credit, while inflation-linked bonds continue offering protection against persistent energy risks.
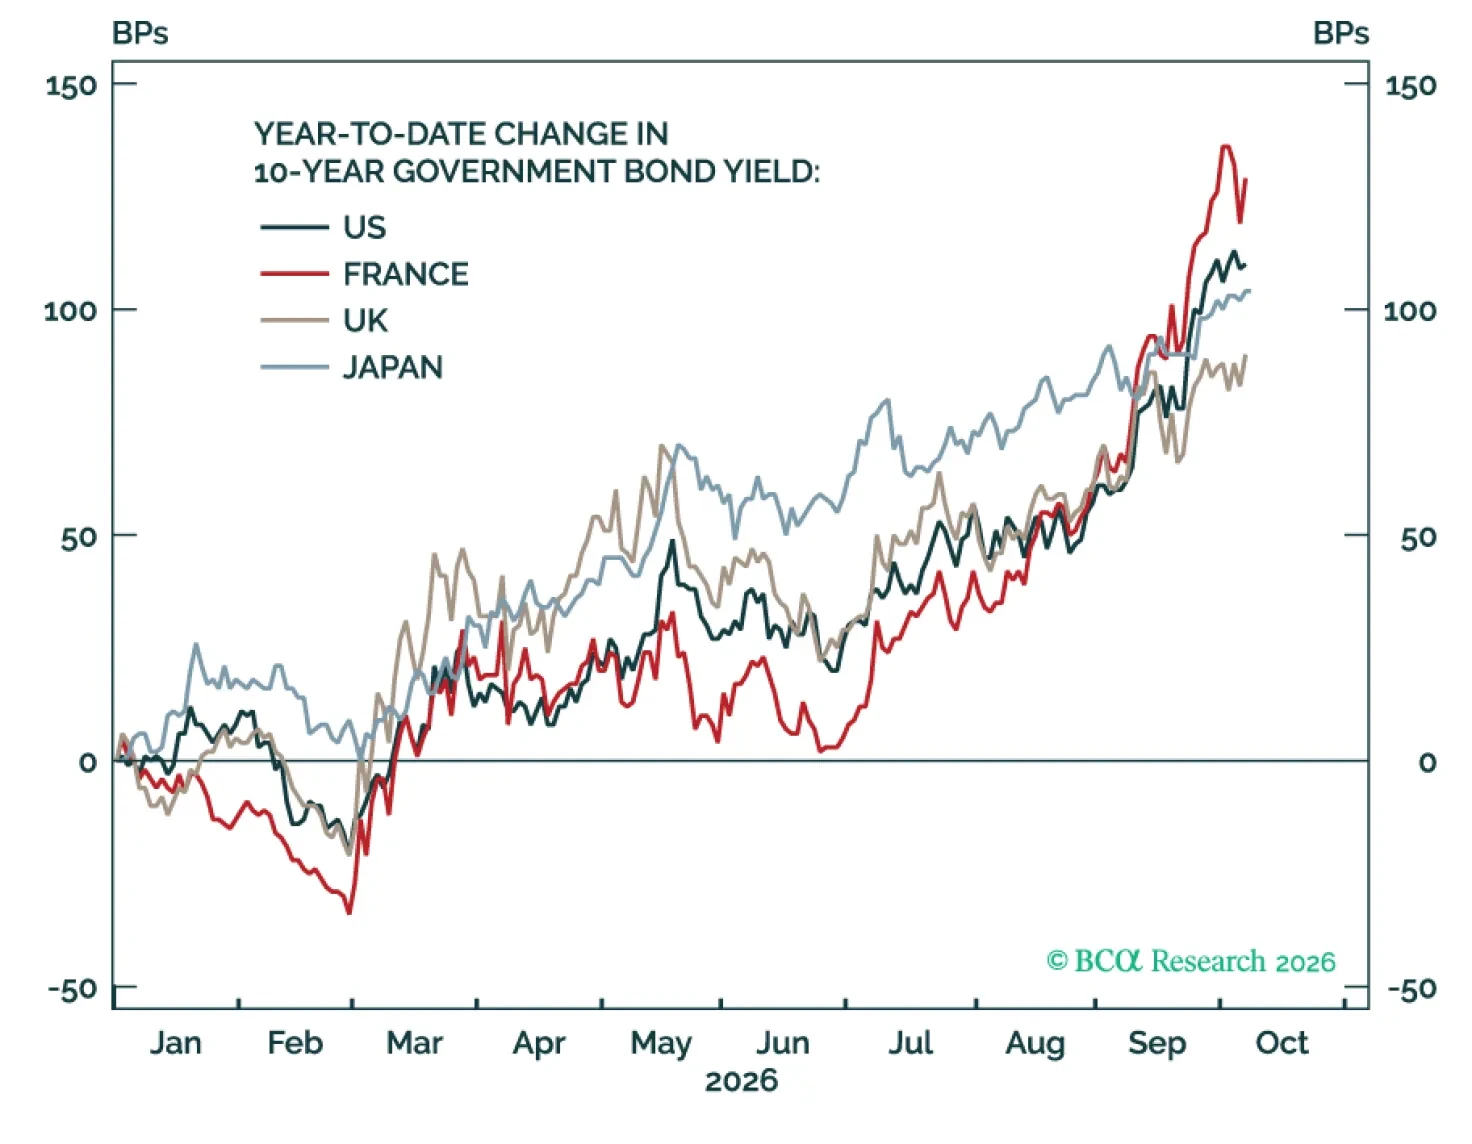
The global bond selloff is not over, but opportunities are emerging. US Treasuries and French OATs remain vulnerable to further selling, while other European government bonds look increasingly attractive. Investors should favor German Bunds and peripheral bonds, particularly on a currency-hedged basis.
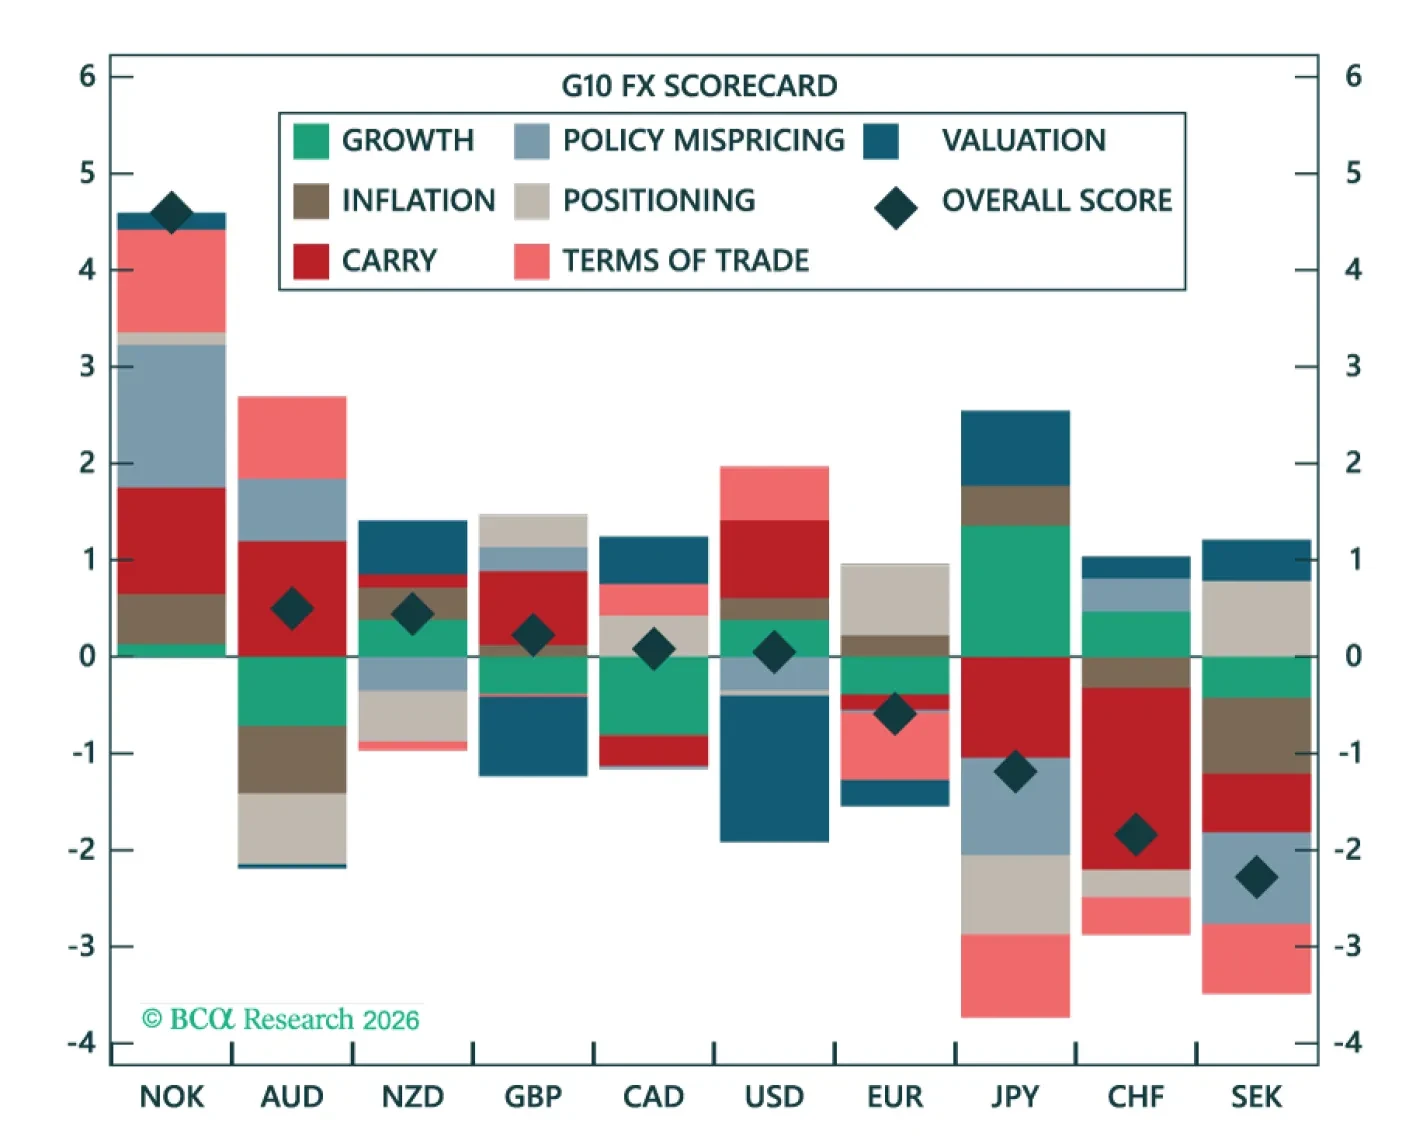
Our G10 FX cyclical scorecard still favors high-carry currencies over low yielders, suggesting patience should continue to pay. We break down the factors driving each currency and highlight the most appealing relative-value opportunities.
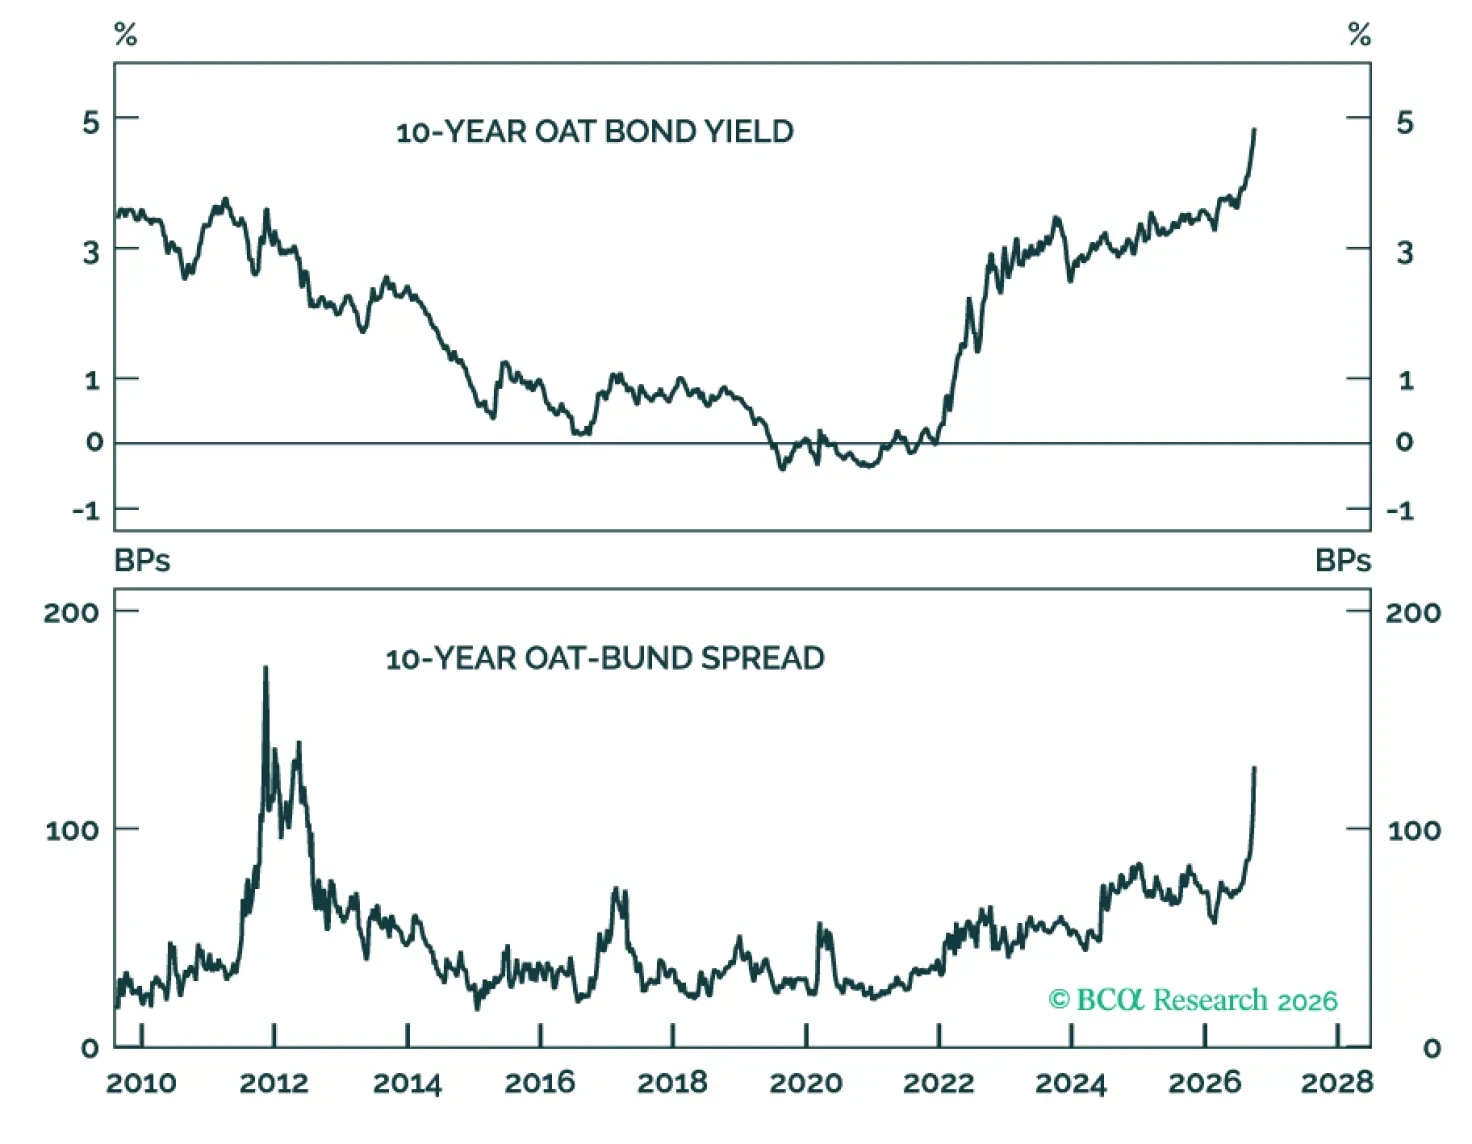
Forced selling may be approaching a pause, but France’s fiscal and political adjustment has barely begun. Maintain an underweight in OATs and use relief rallies to reduce exposure. Contained contagion is reassuring for Europe; it is not a buy signal for France.
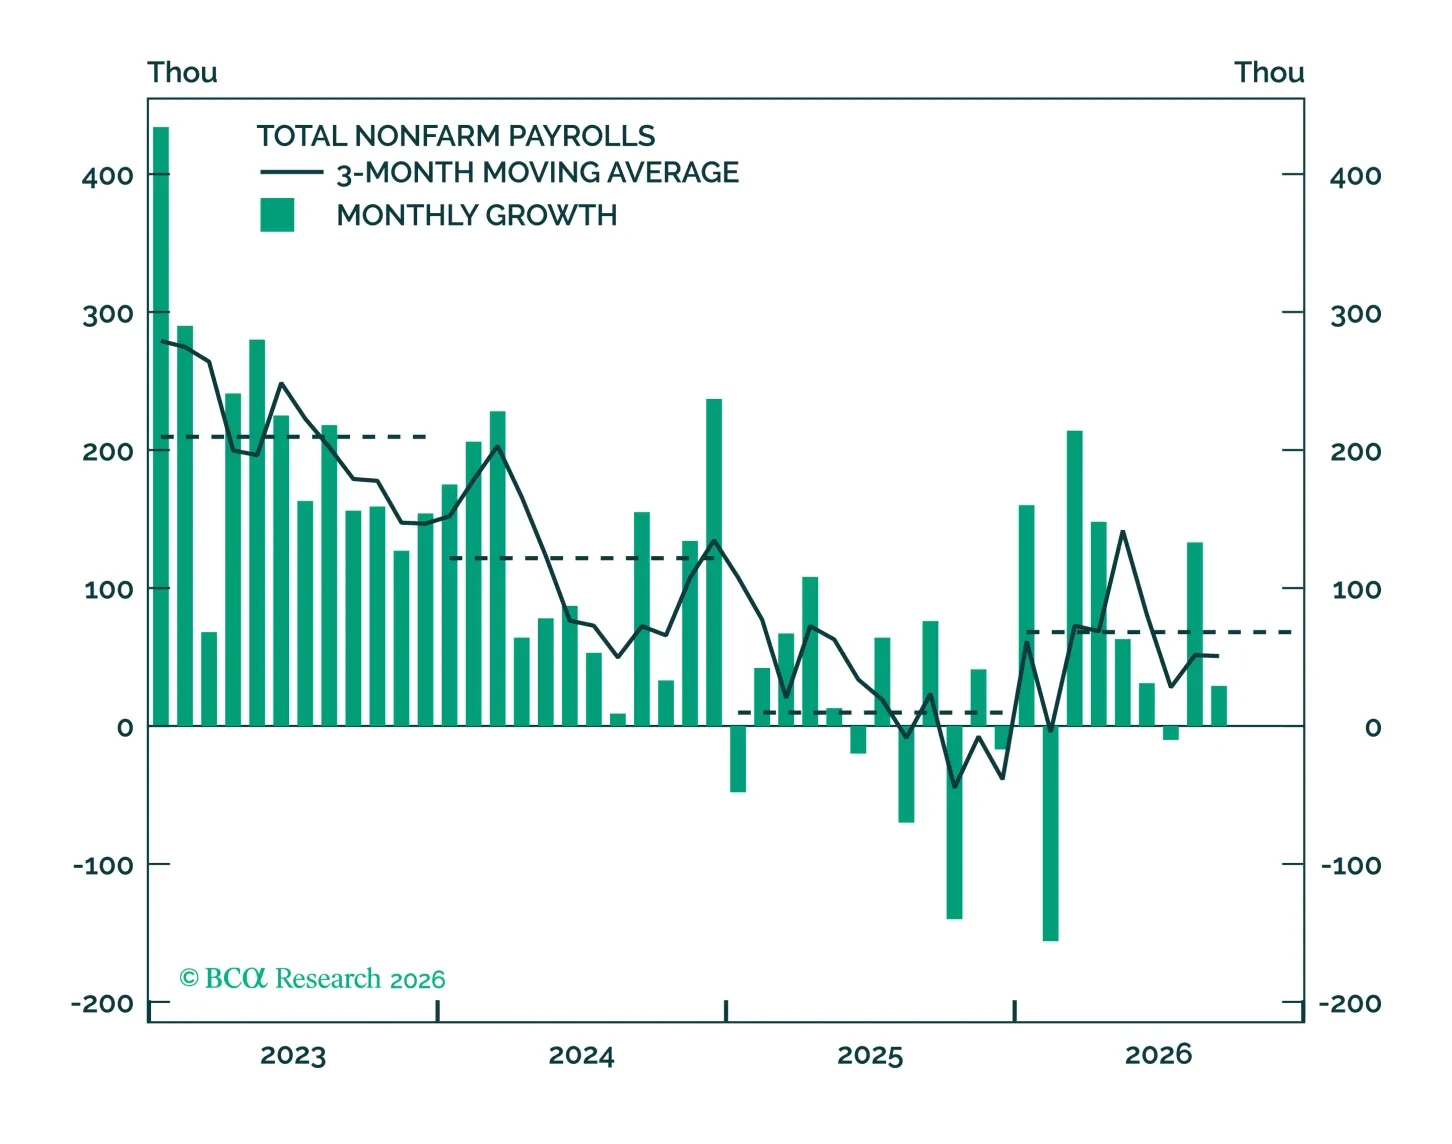
This morning’s jobs report serves to underscore that the labor market is not a source of inflationary pressure and therefore of second-order importance when it comes to the Fed’s near-term decision making.
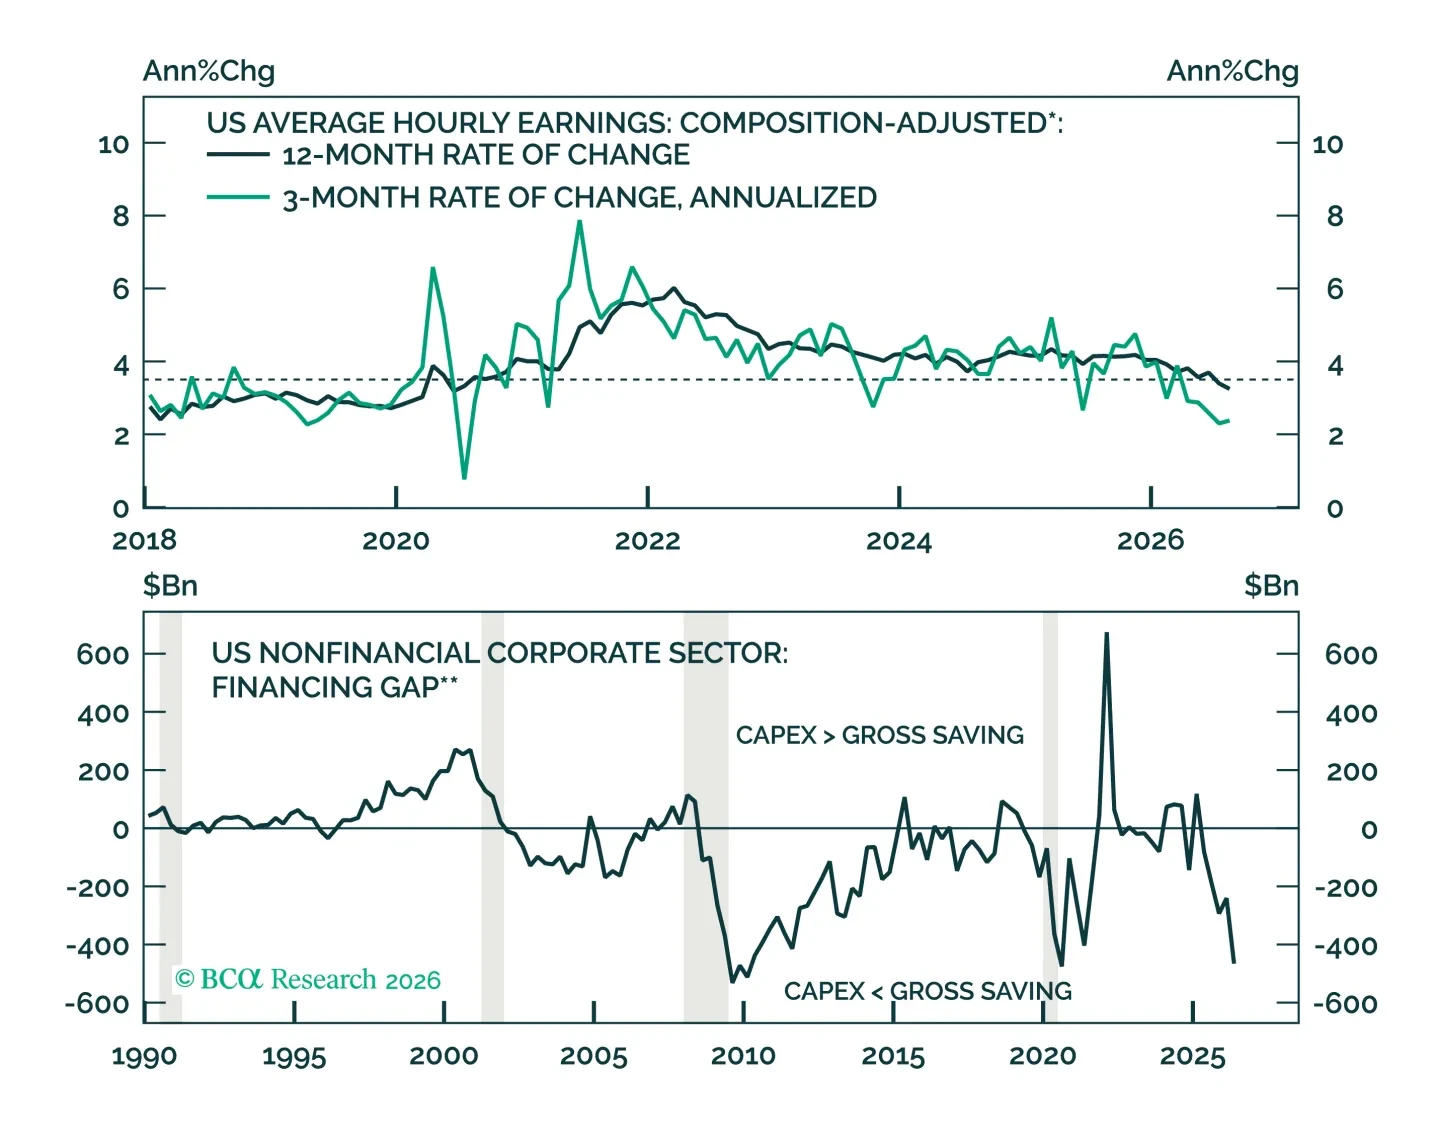
Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.
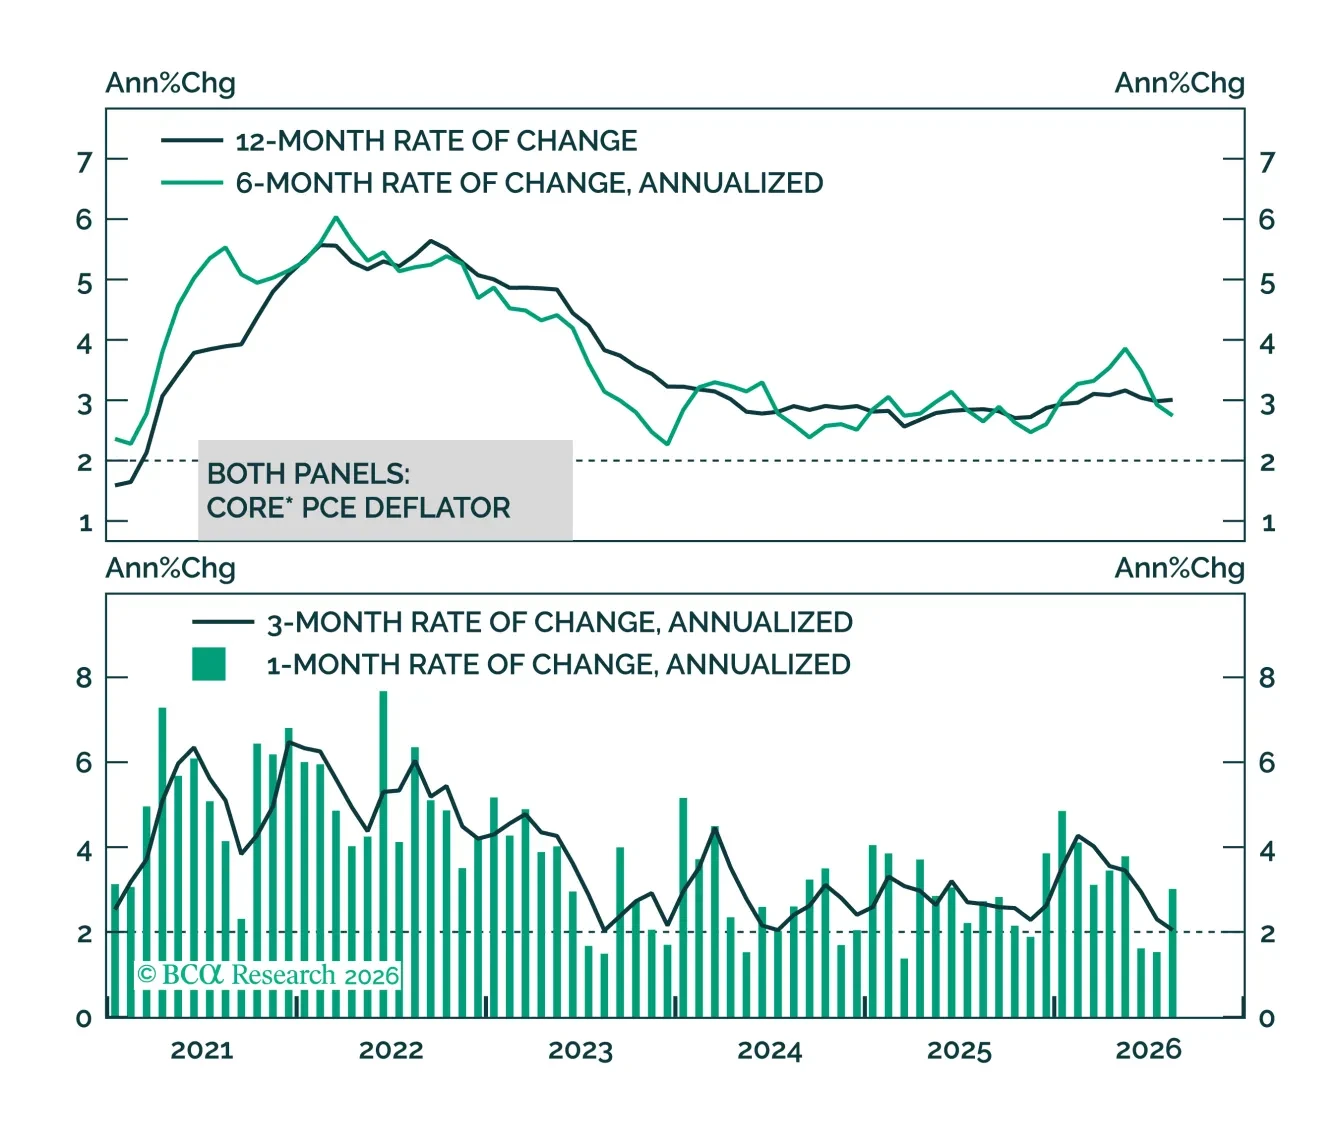
Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.
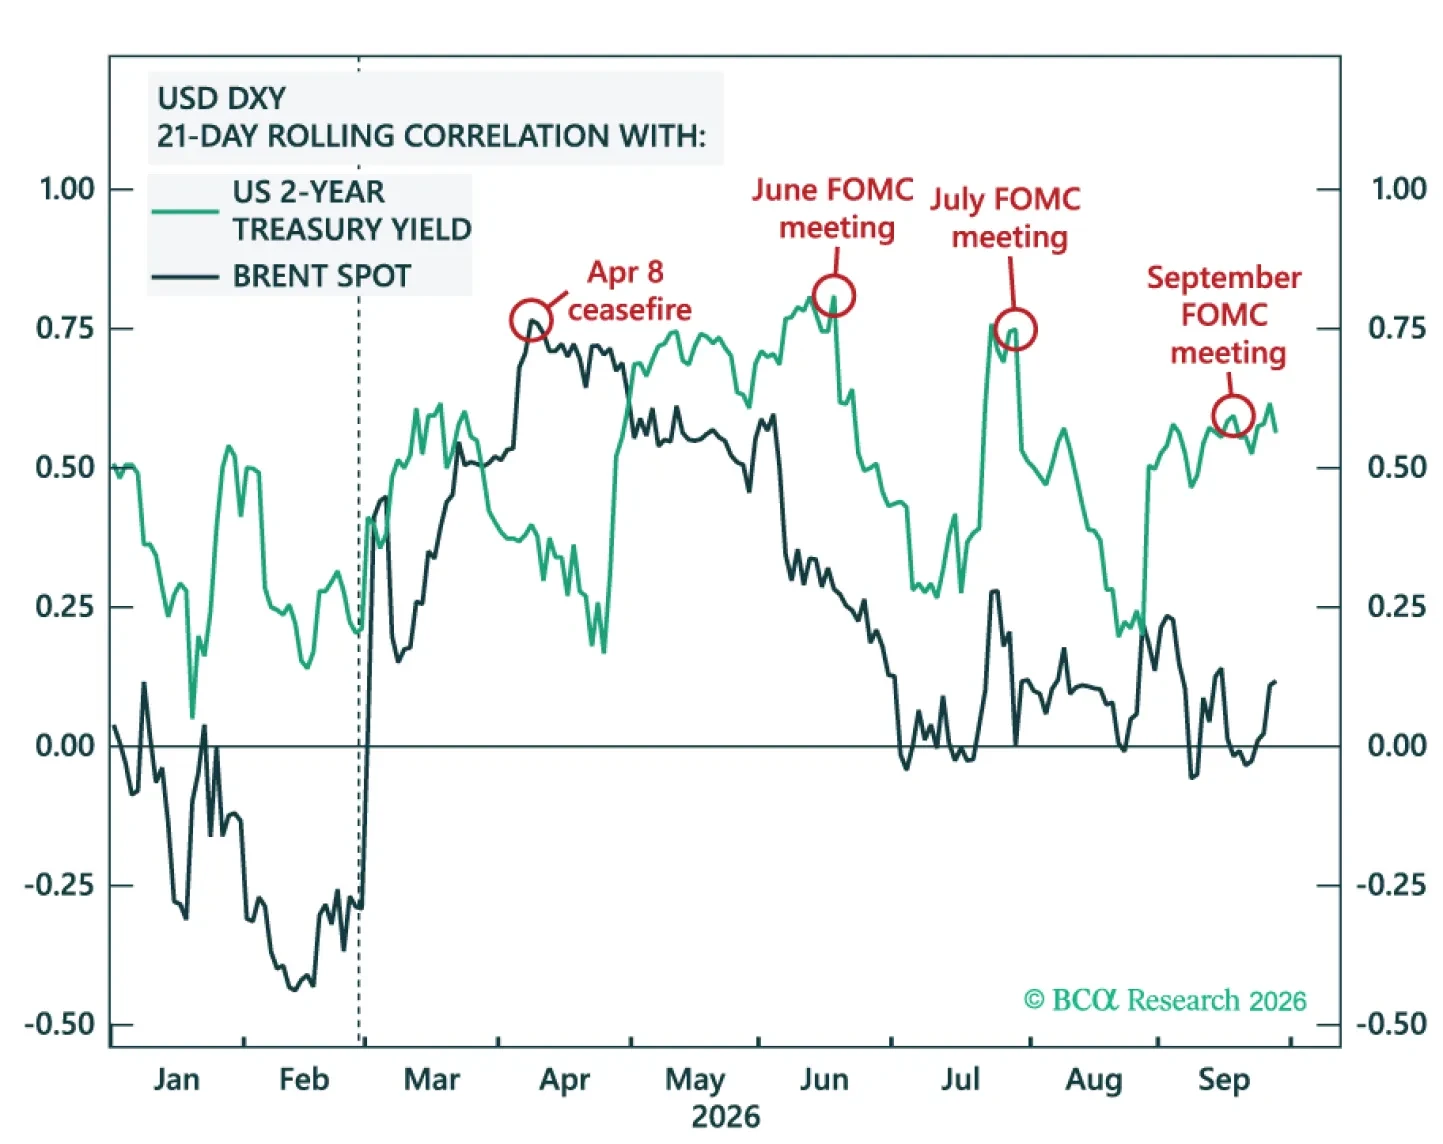
Global capex is driving the strongest industrial cycle since 2021. The US is best positioned to capture the gains and to weather near-term risks, supporting widening real-rate differentials and favoring continued upside in the dollar in the coming months.
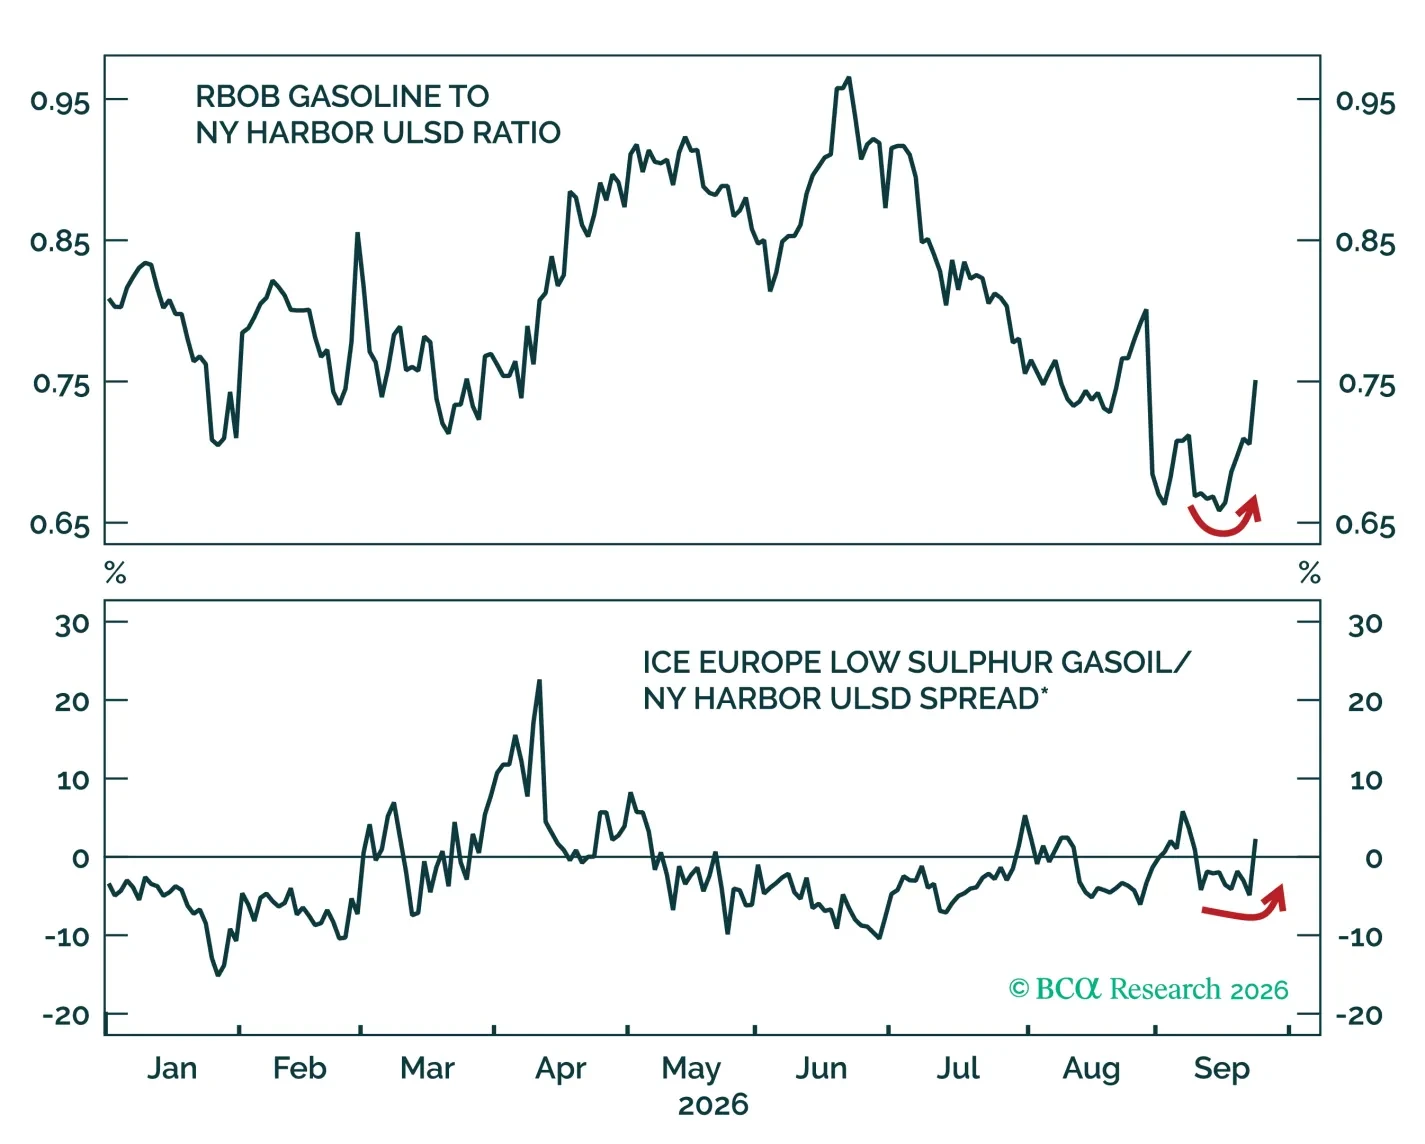
Record diesel prices and mounting political pressure make some form of US export restriction likely. But it wouldn't be a clean solution. We reveal why relief would be fleeting, who would pay the price, and how to trade it.