 Equities
| US Equities
US equity research, from the S&P 500 to sectors and factors, on where stocks are heading next.

Markets are pricing out the worst trade policy fears, and while tariffs will still dent earnings, the impact looks smaller than initially feared. With sector rotation gaining traction and oversold names rebounding, we are adjusting our portfolio to reflect the rotation thesis.
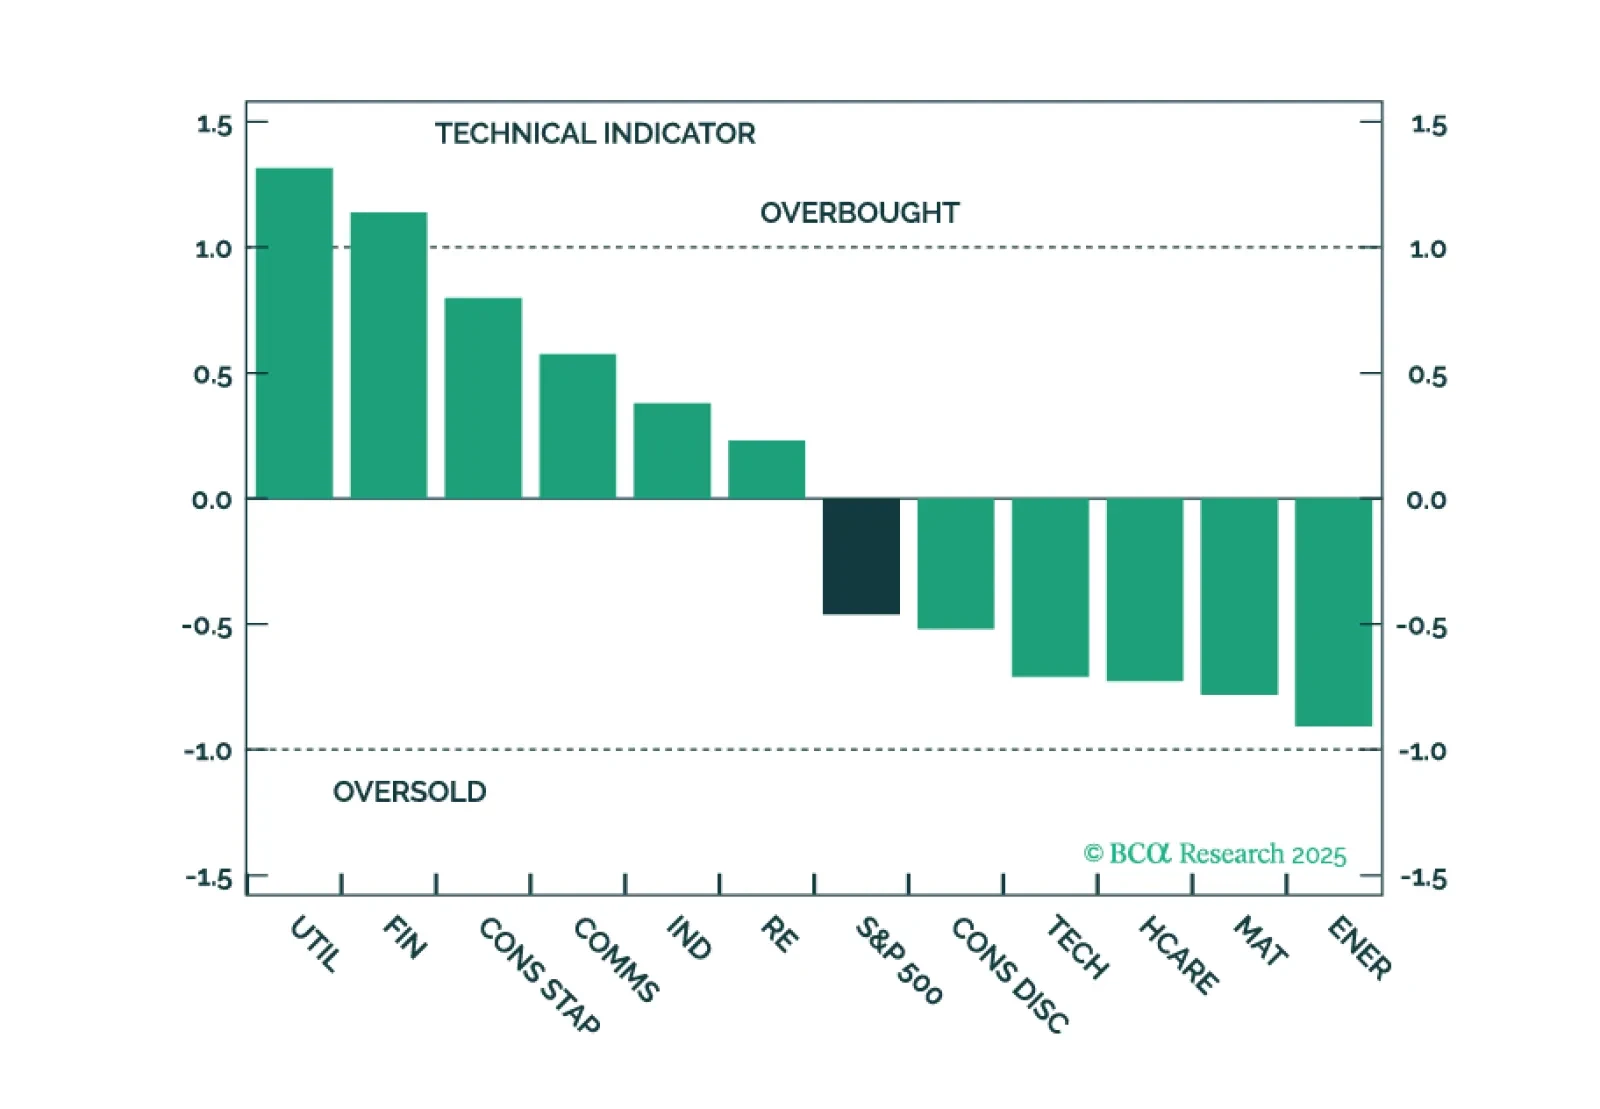
Utilities remain a long-term structural investment theme thanks to the tailwinds from GenAI, EV, and onshoring. However, there is little upside left over the tactical investment horizon as all the positives are priced in. We close our overweight and book profits.

In the front section of the chart pack, we review April and YTD market performance, provide an update on the Q1 earnings season, examine the outlook for the Magnificent Seven, and adjust portfolio positioning.
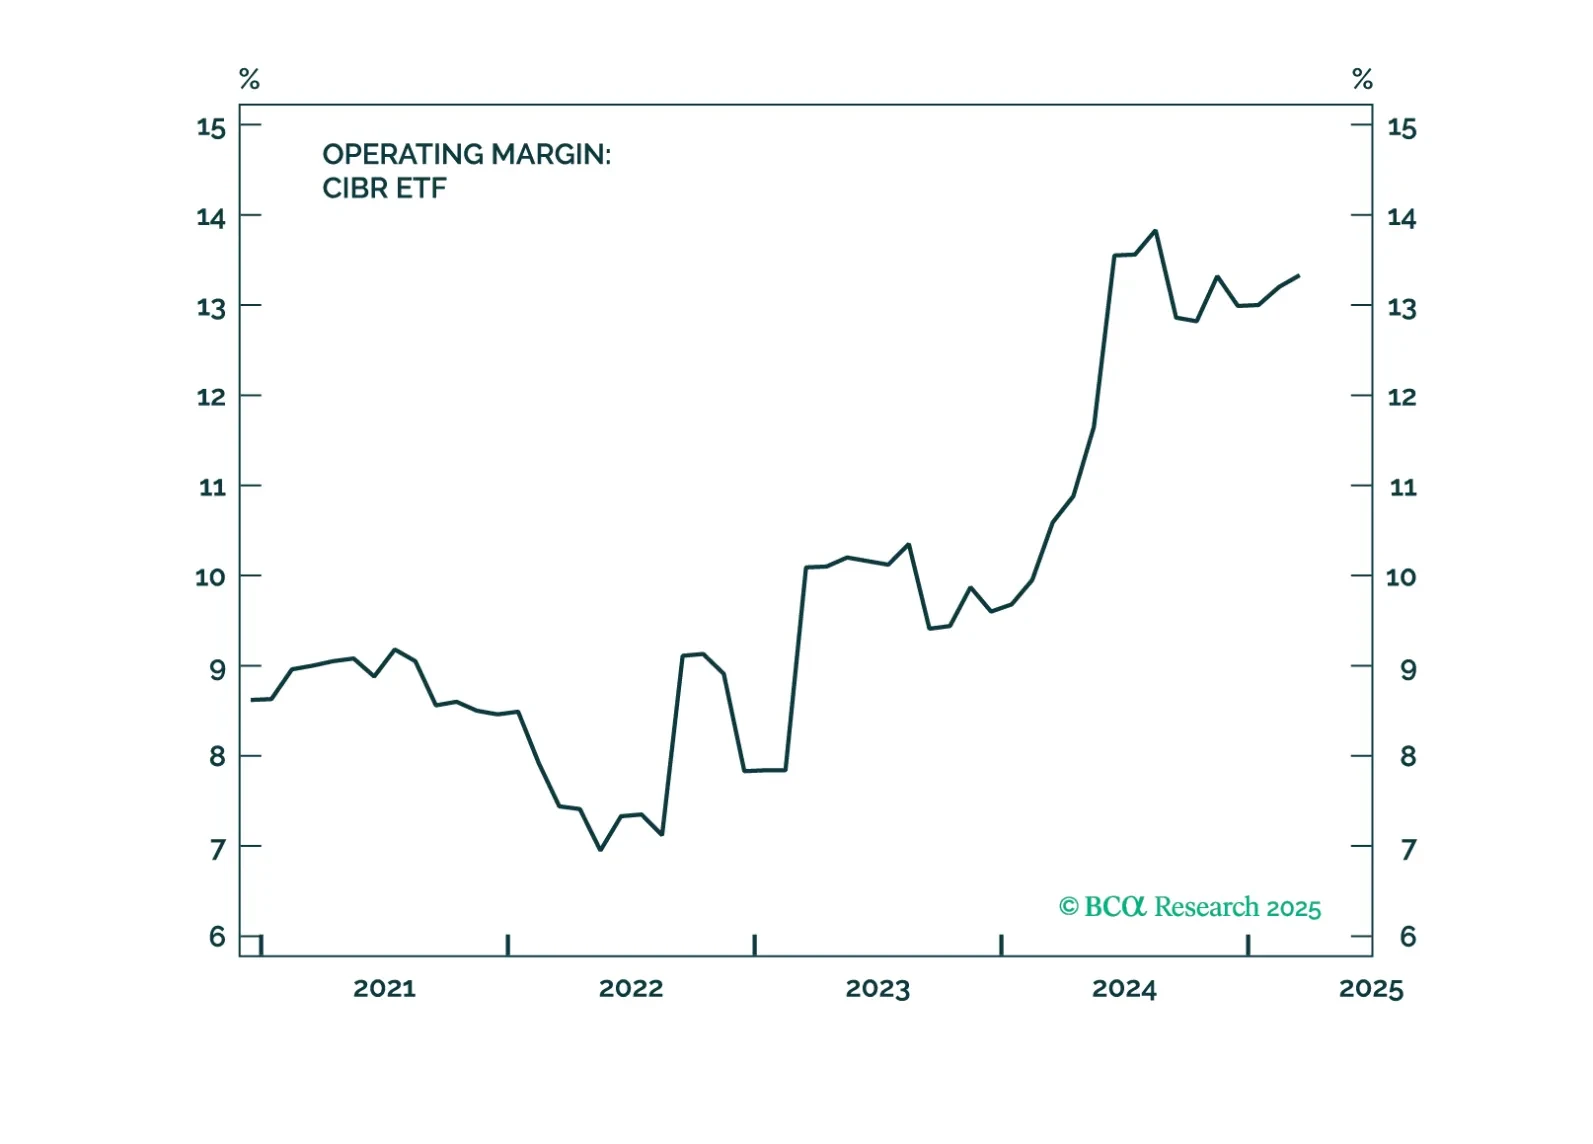
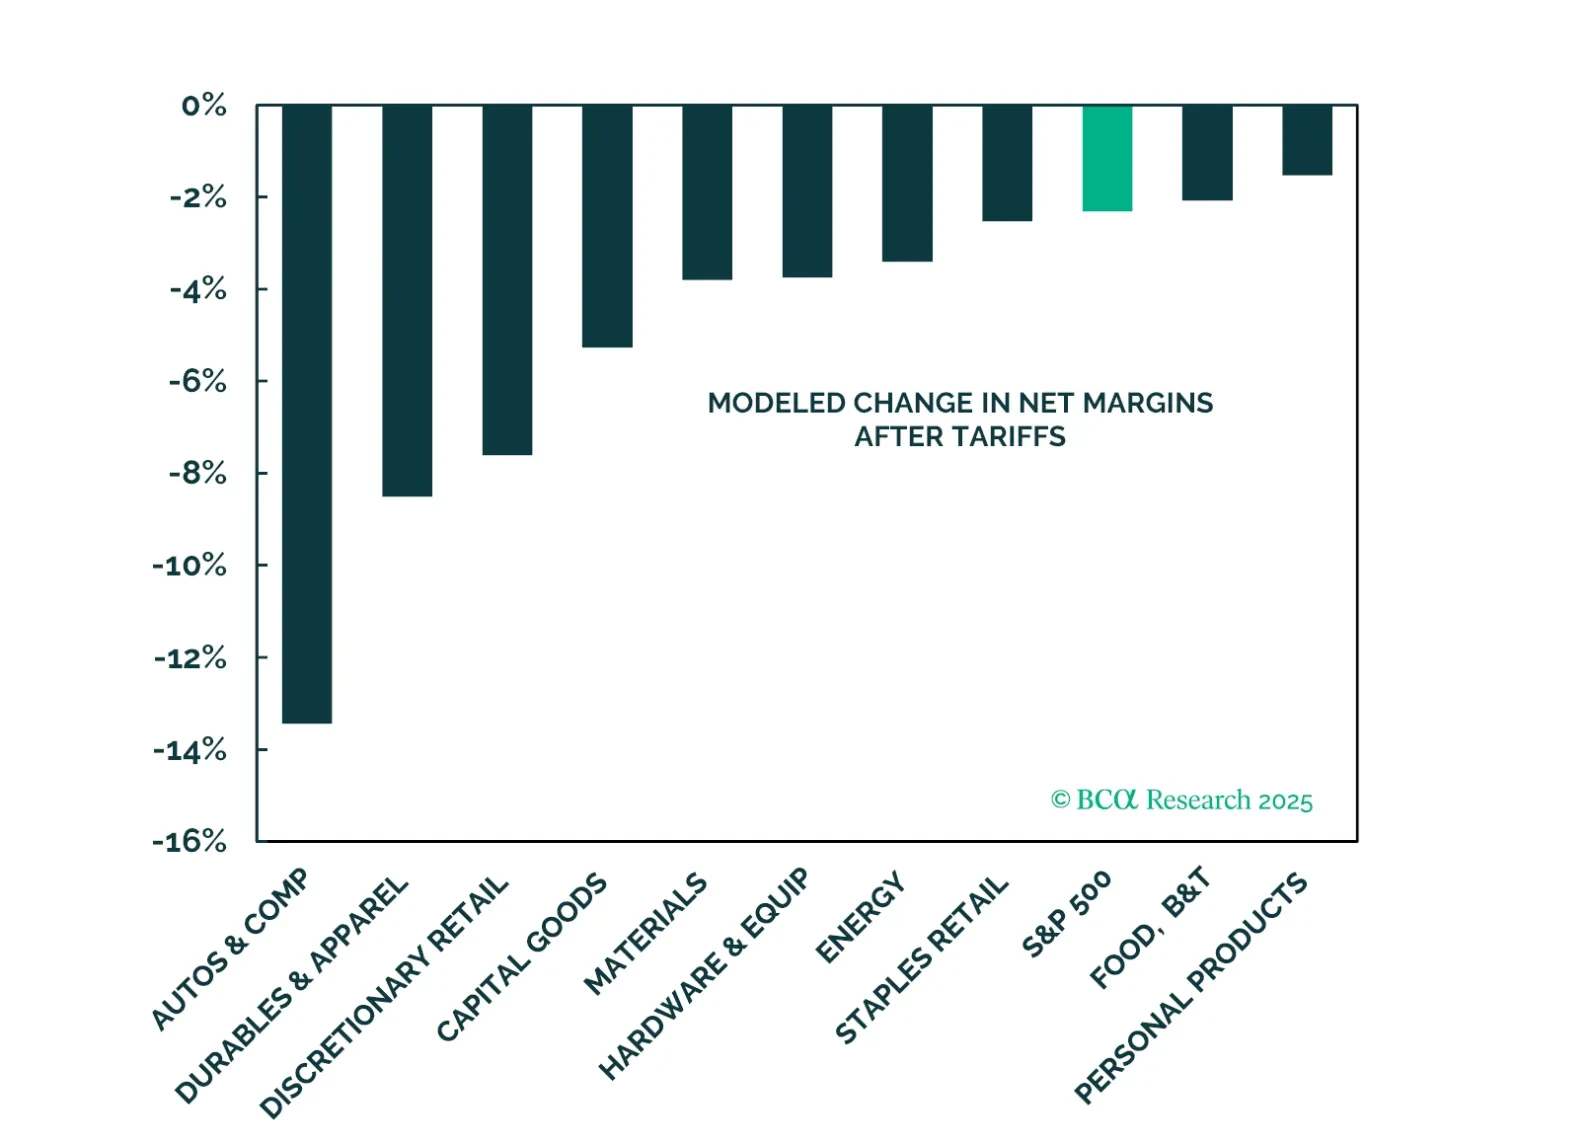
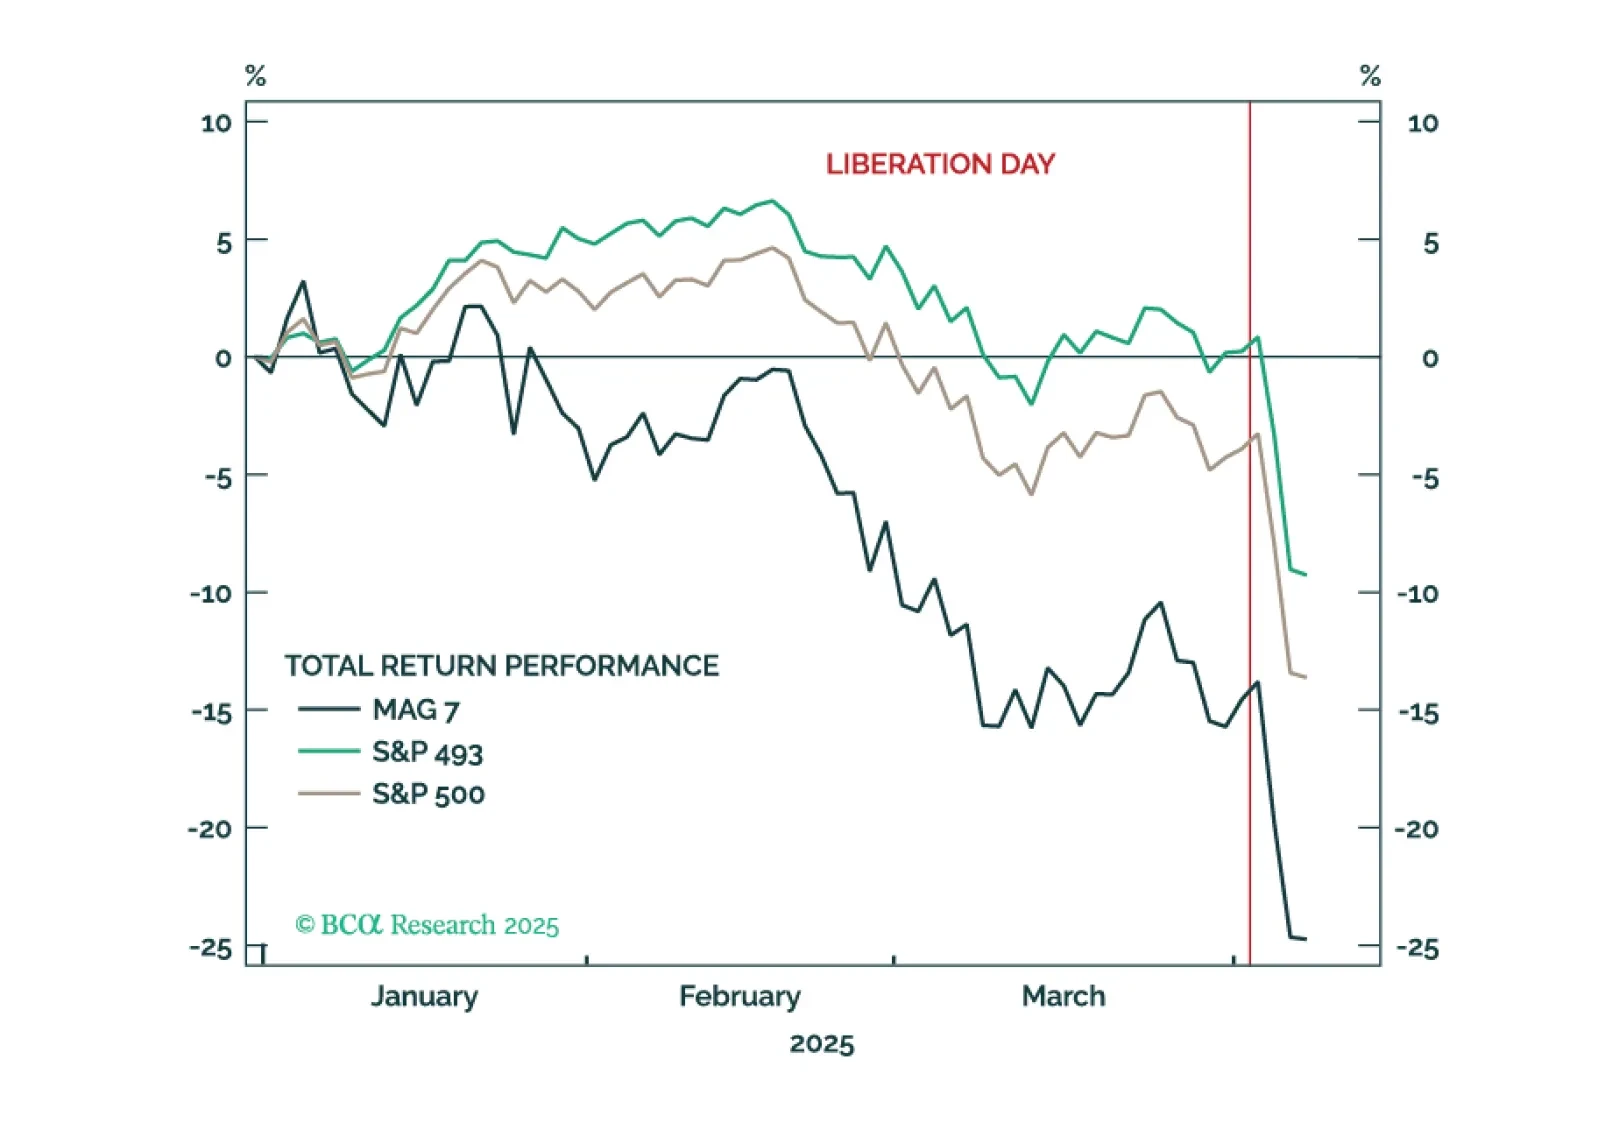
In the front section of the chart pack, we review March’s performance. We will also recommend the portfolio positioning for downward protection.
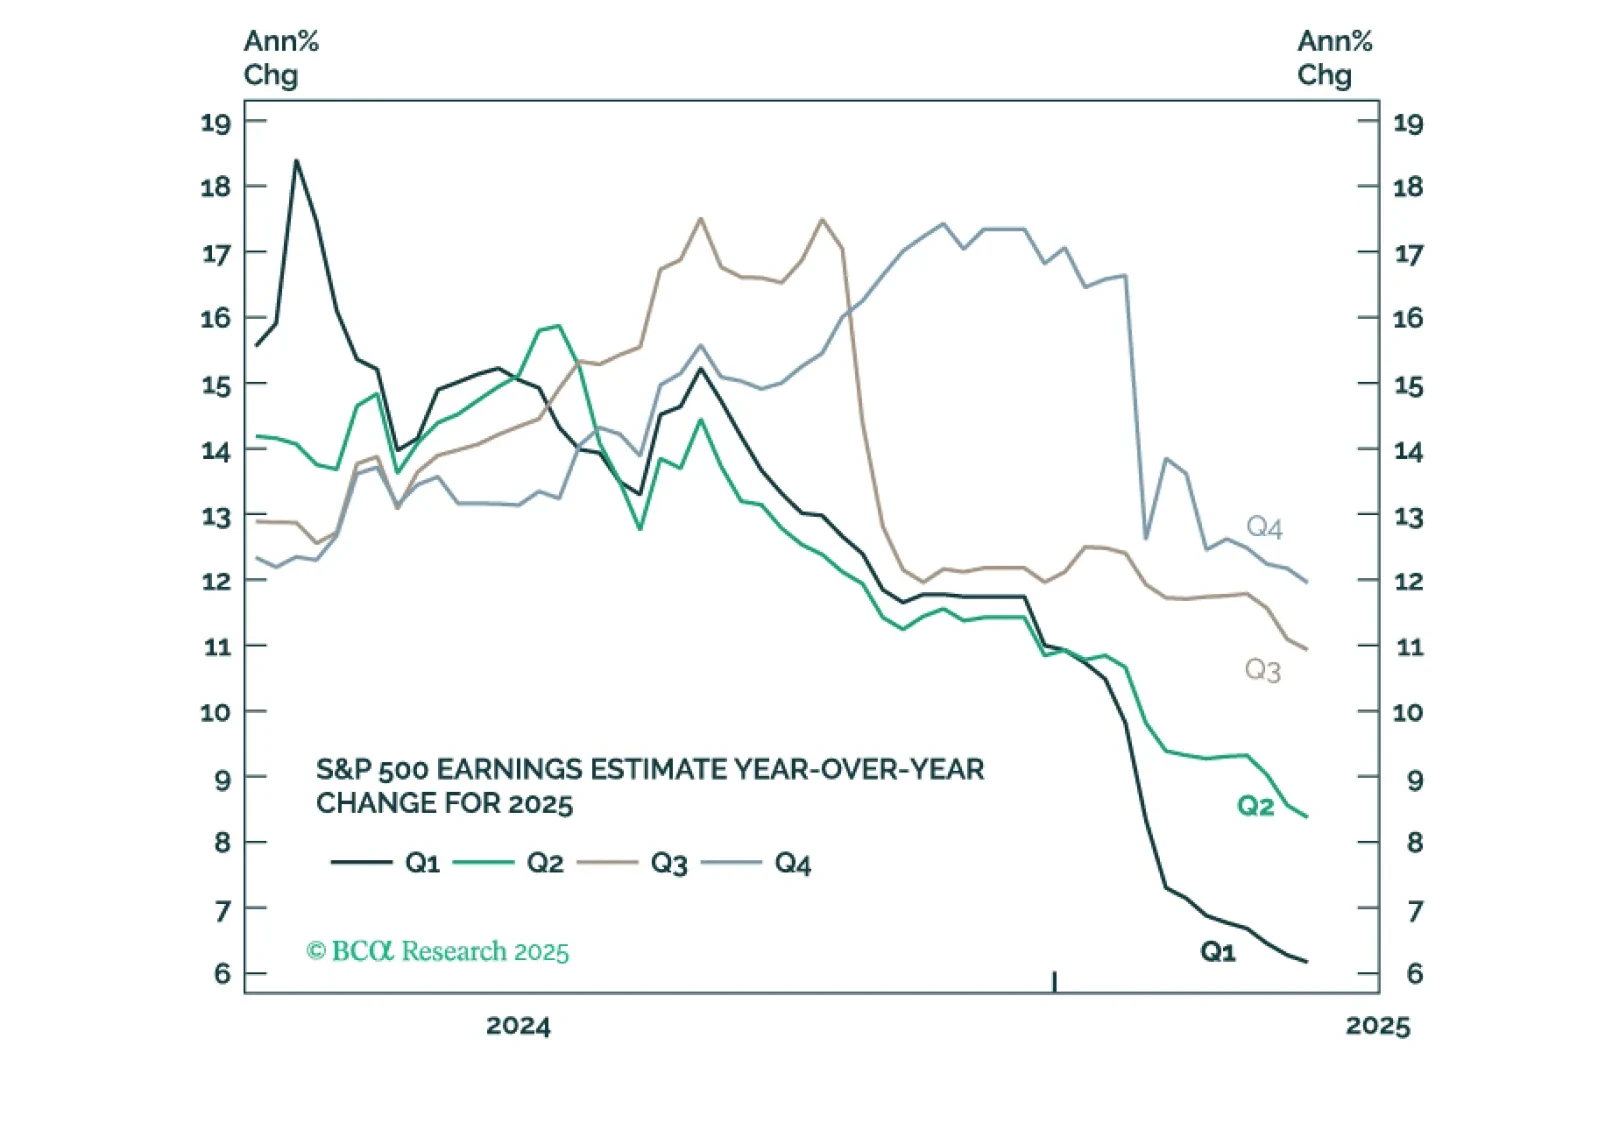
Equities will find a bottom when the full effects of tariffs on earnings and economic growth are priced in. The bottom of the market appears a long way away, and the S&P 500 may end up as low as 4,300, barring any reversals in trade policy that could undo the damage.
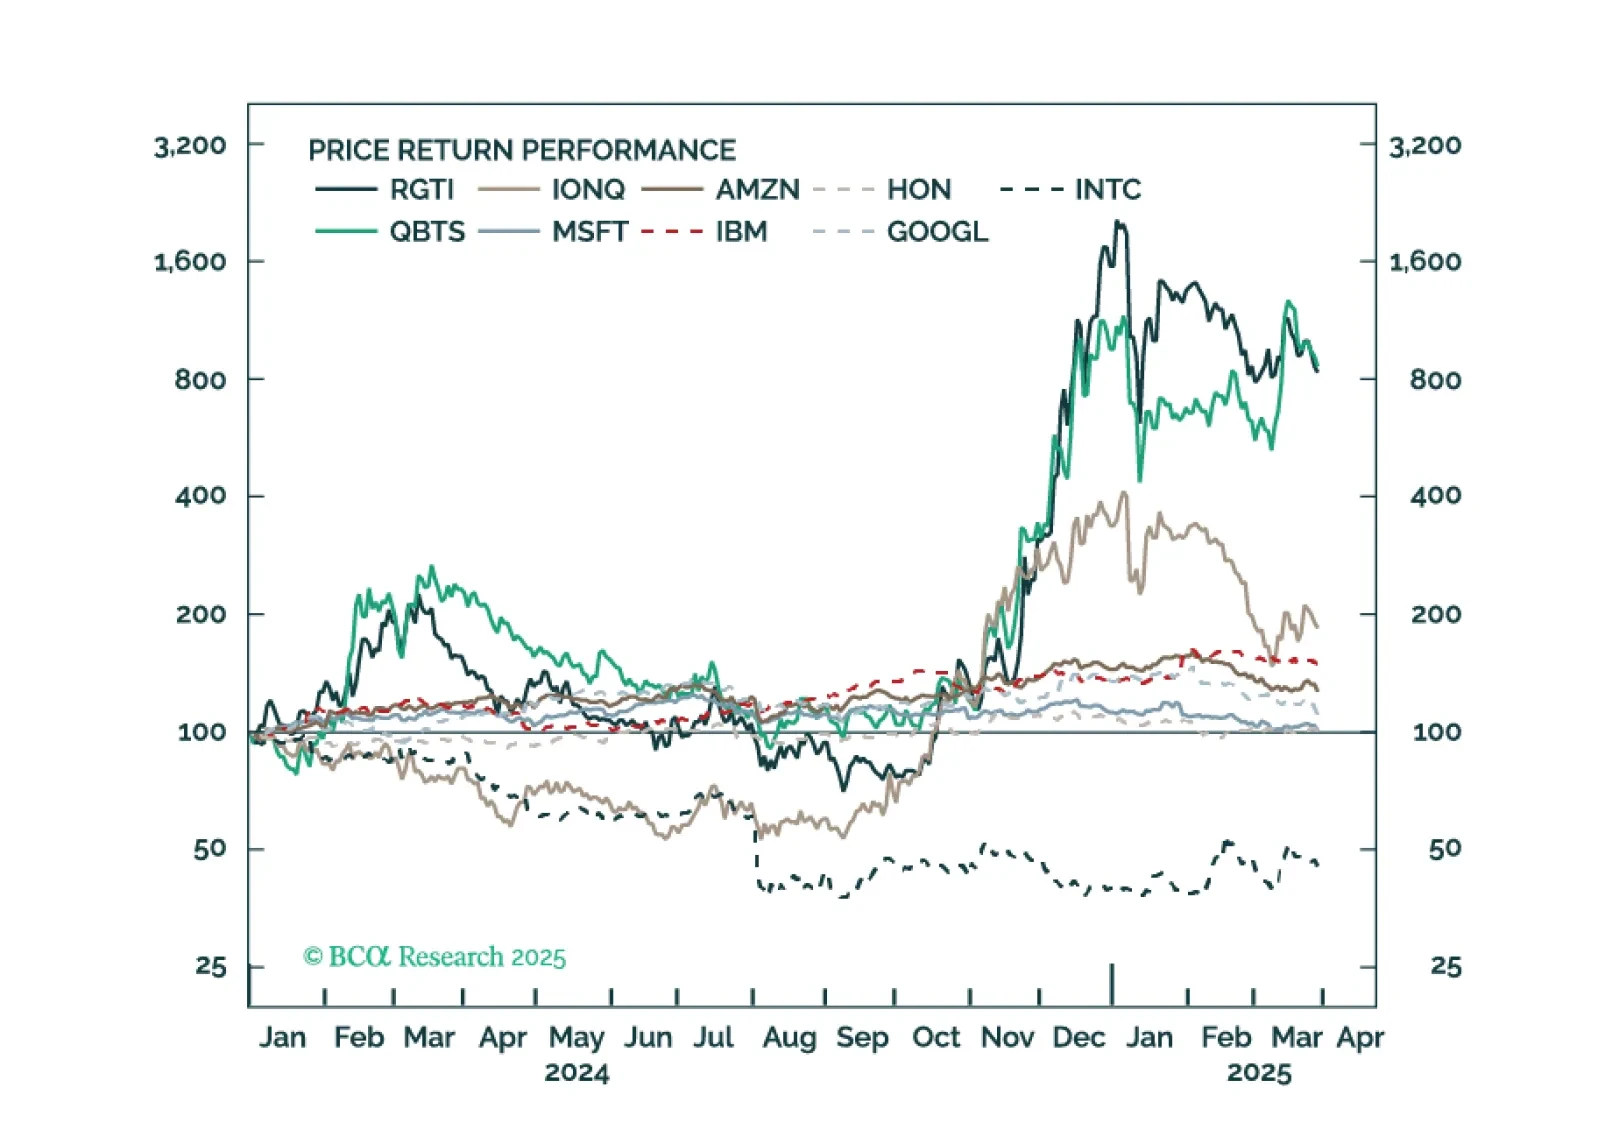
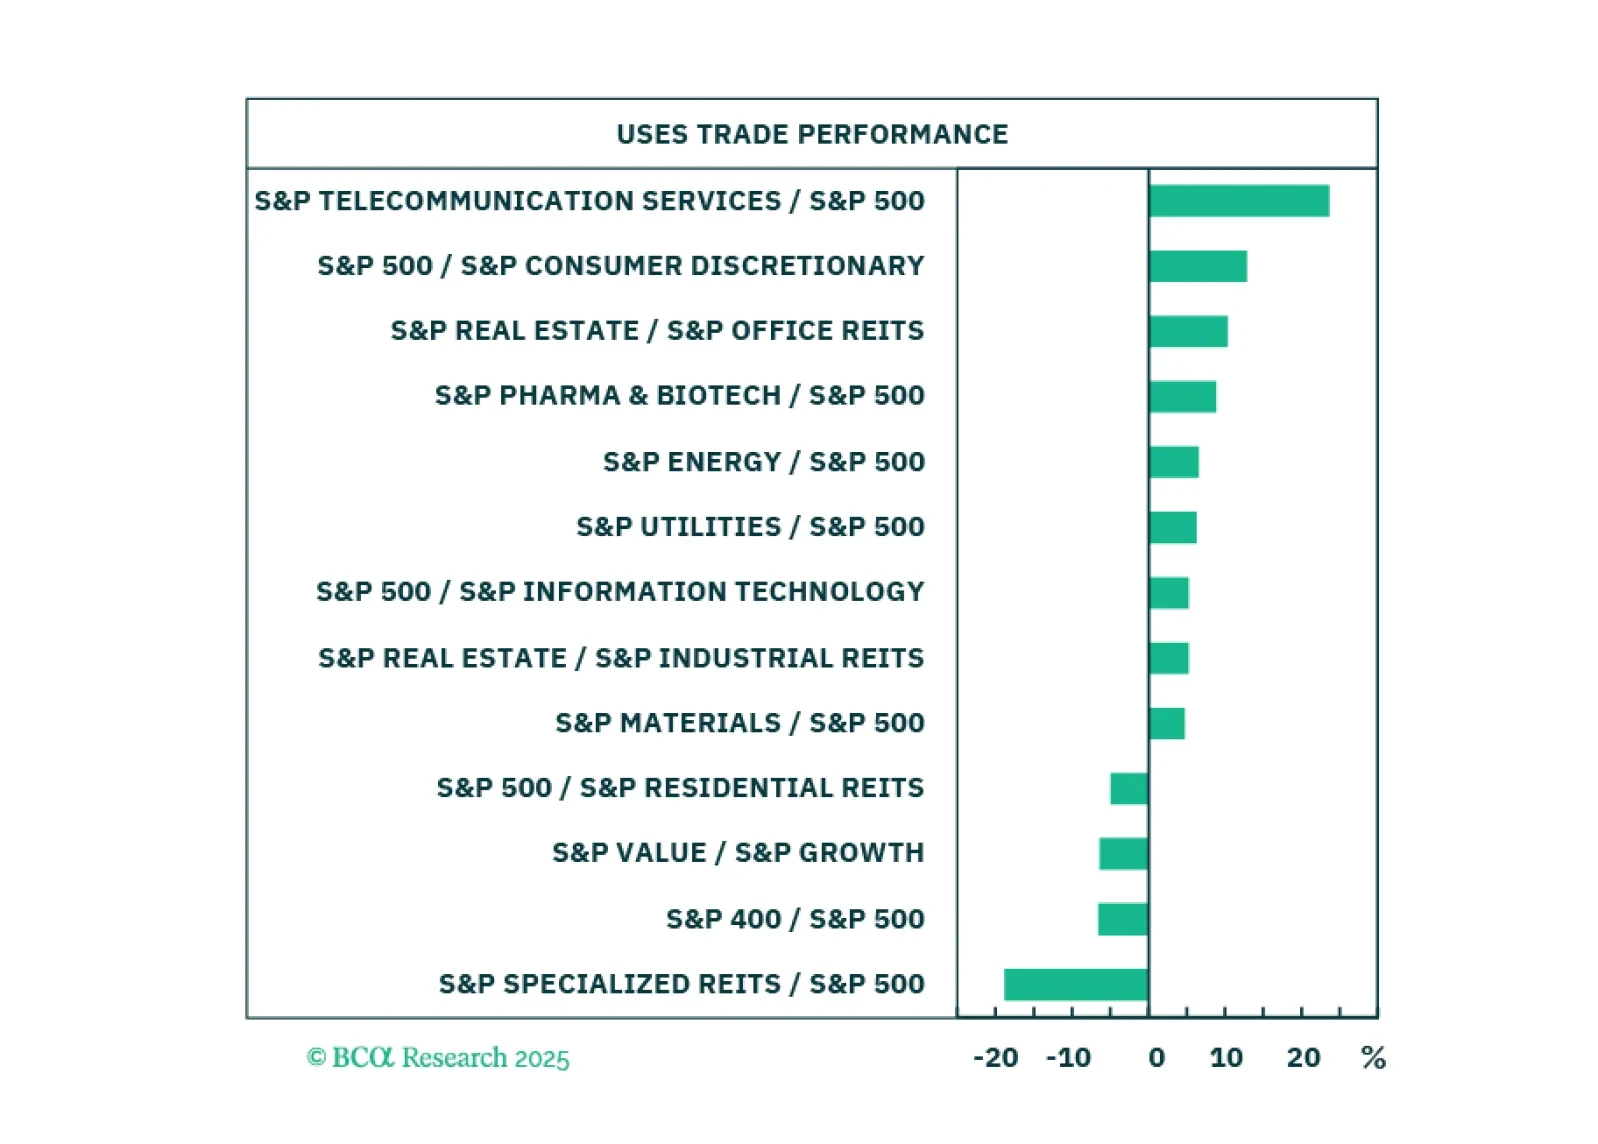
The US economy faces a new investment regime characterized by tighter fiscal and easier monetary policies. The market corrected fast, and a short-lived equity rebound is likely. However, over the long term, US equities face economic headwinds.
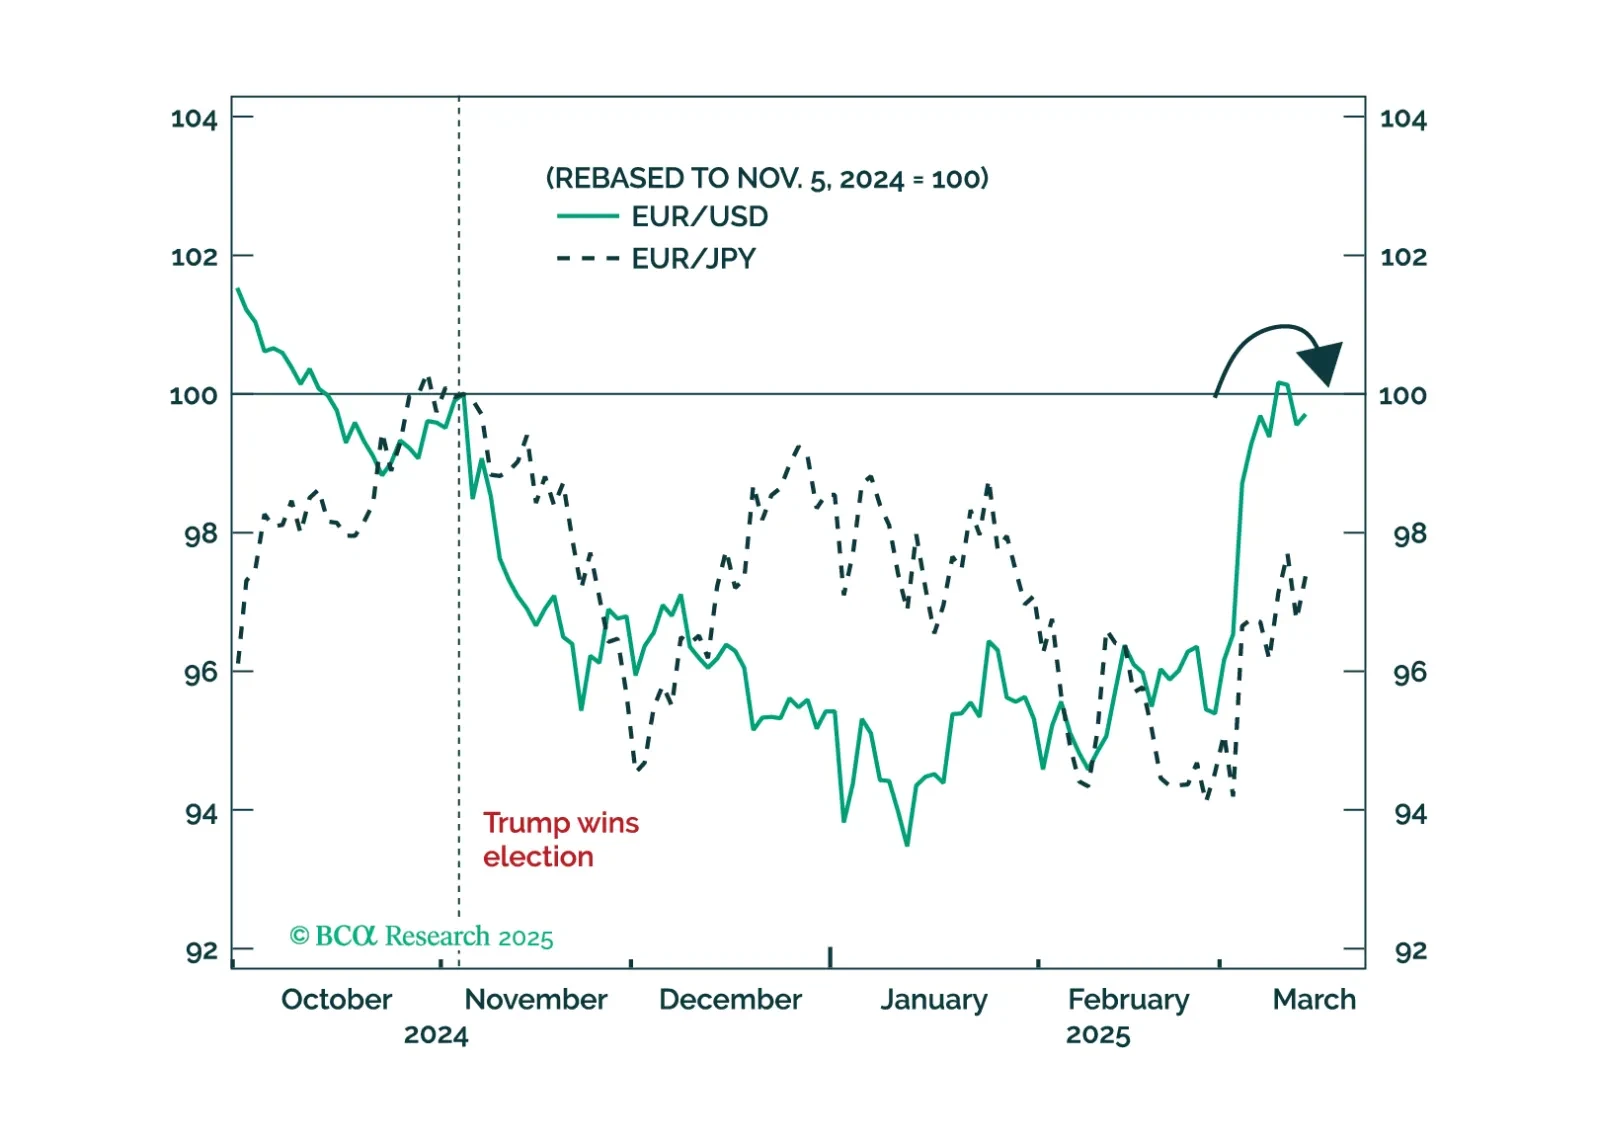
Trump’s foreign policy can be explained by rational US interests, but it requires settling the trade war with allies sooner rather than later. Book gains on EUR-USD for now.