 Equities
| US Equities
US equity research, from the S&P 500 to sectors and factors, on where stocks are heading next.
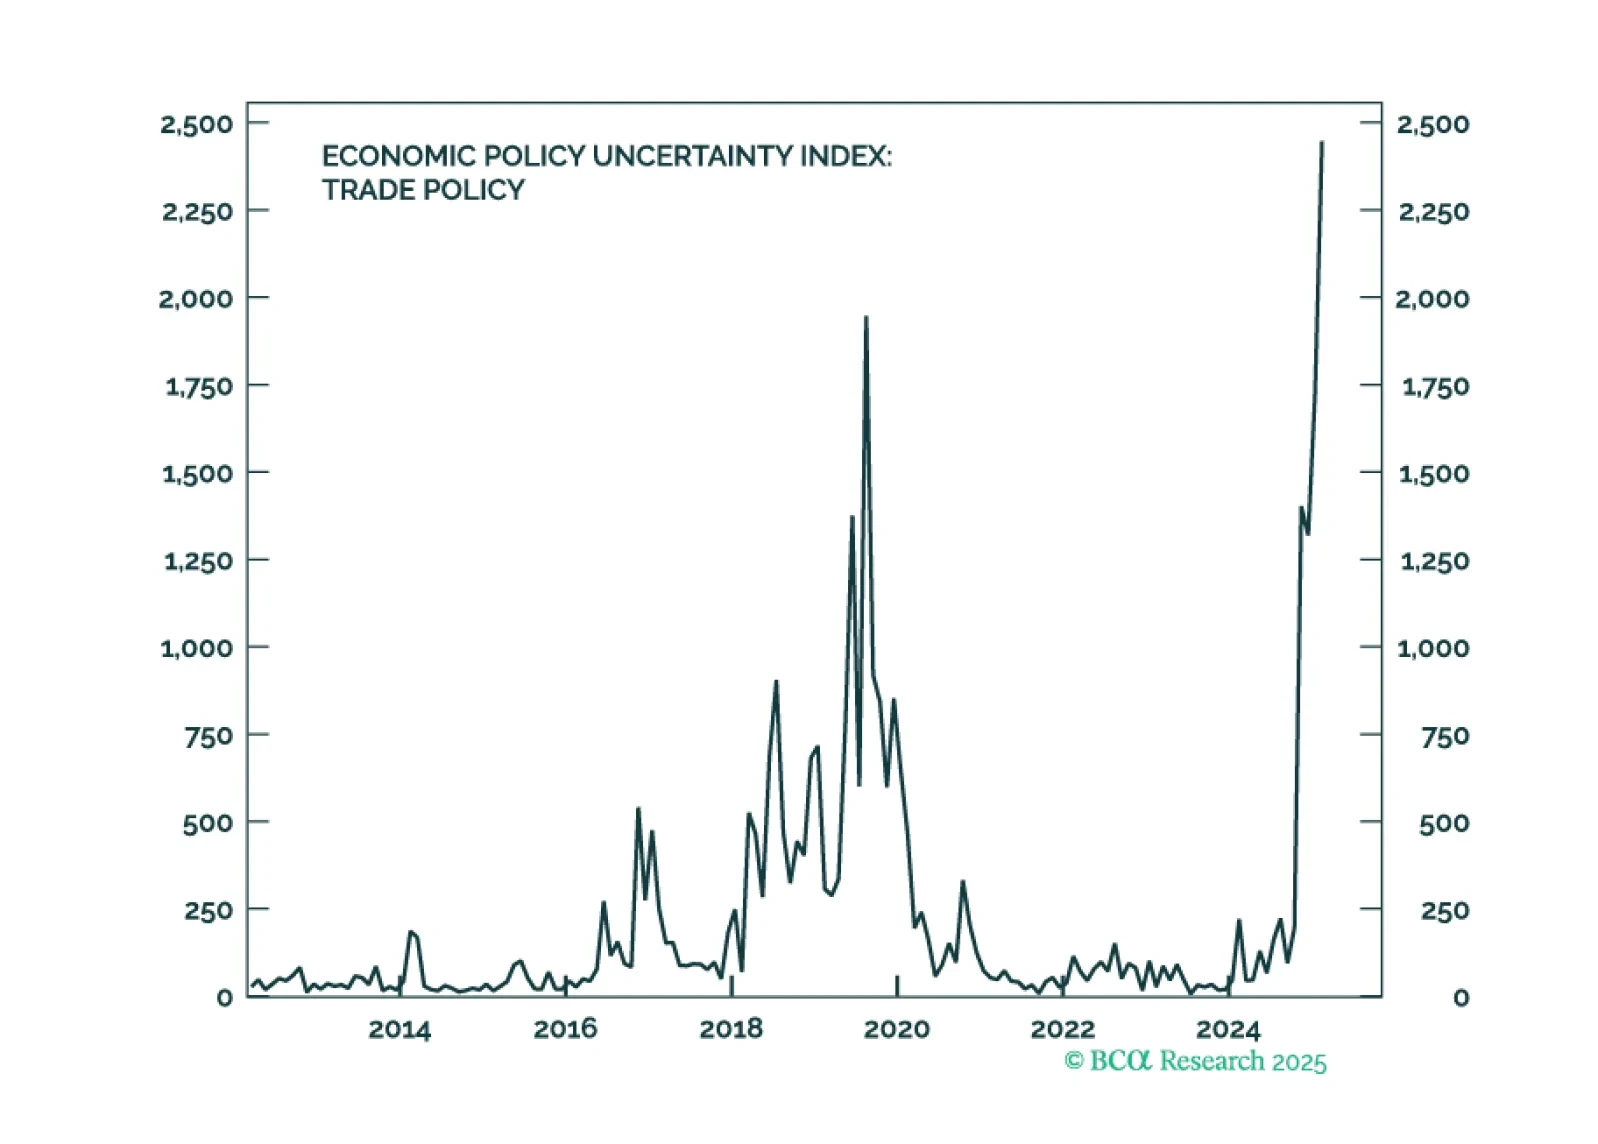
The Q4 earnings results were spectacular but are now in the rear-view mirror. Now, investors are laser-focused on tariff threats, earnings headwinds brought about by a stronger dollar, and an unhappy consumer. Our analysis of earnings commentary found that, while companies often refer to tariffs during their earnings calls, most are perplexed and still in a “wait and see” mode. A strong dollar is negative for earnings, but the recent dollar retrenchment will bring relief. Wealthy consumers are still spending, but there are early signs of stress.
This week we are sending you a sector chart pack. In the front section of the chart pack, we review February’s performance, take stock of the recent macroeconomic developments, and examine whether market rotation will continue. We also review whether the US valuation premium relative to Europe is justified.
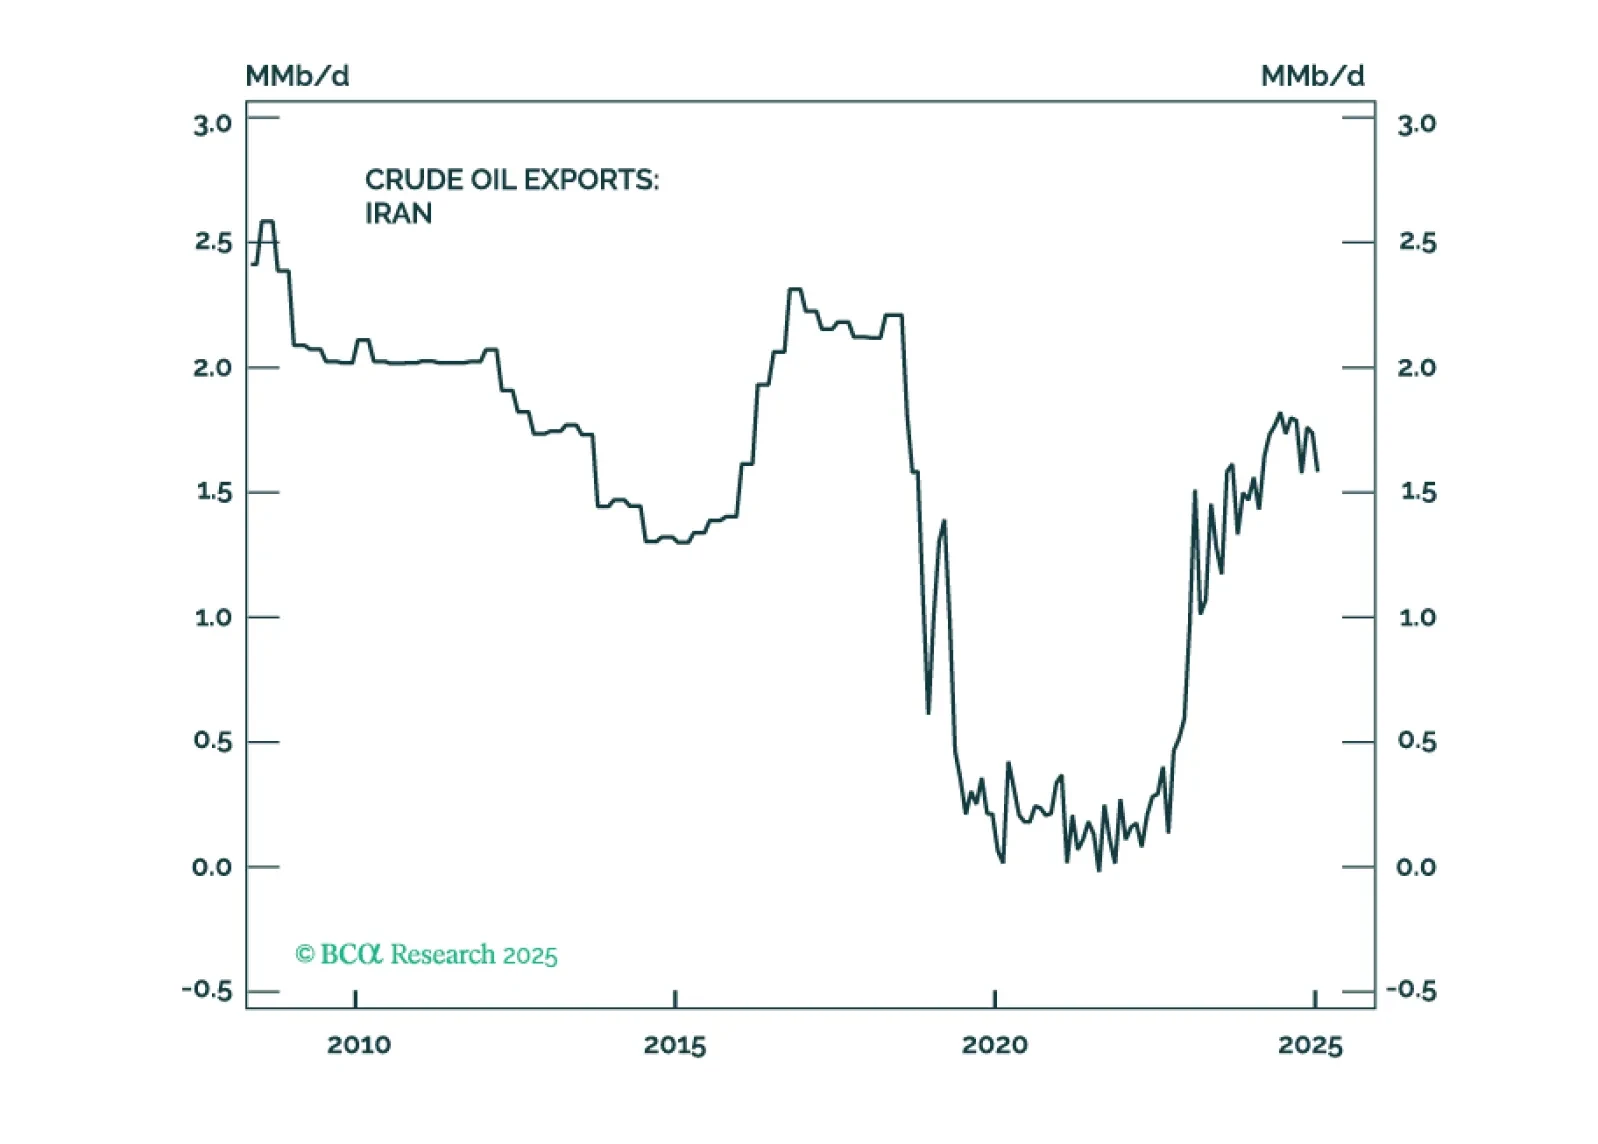
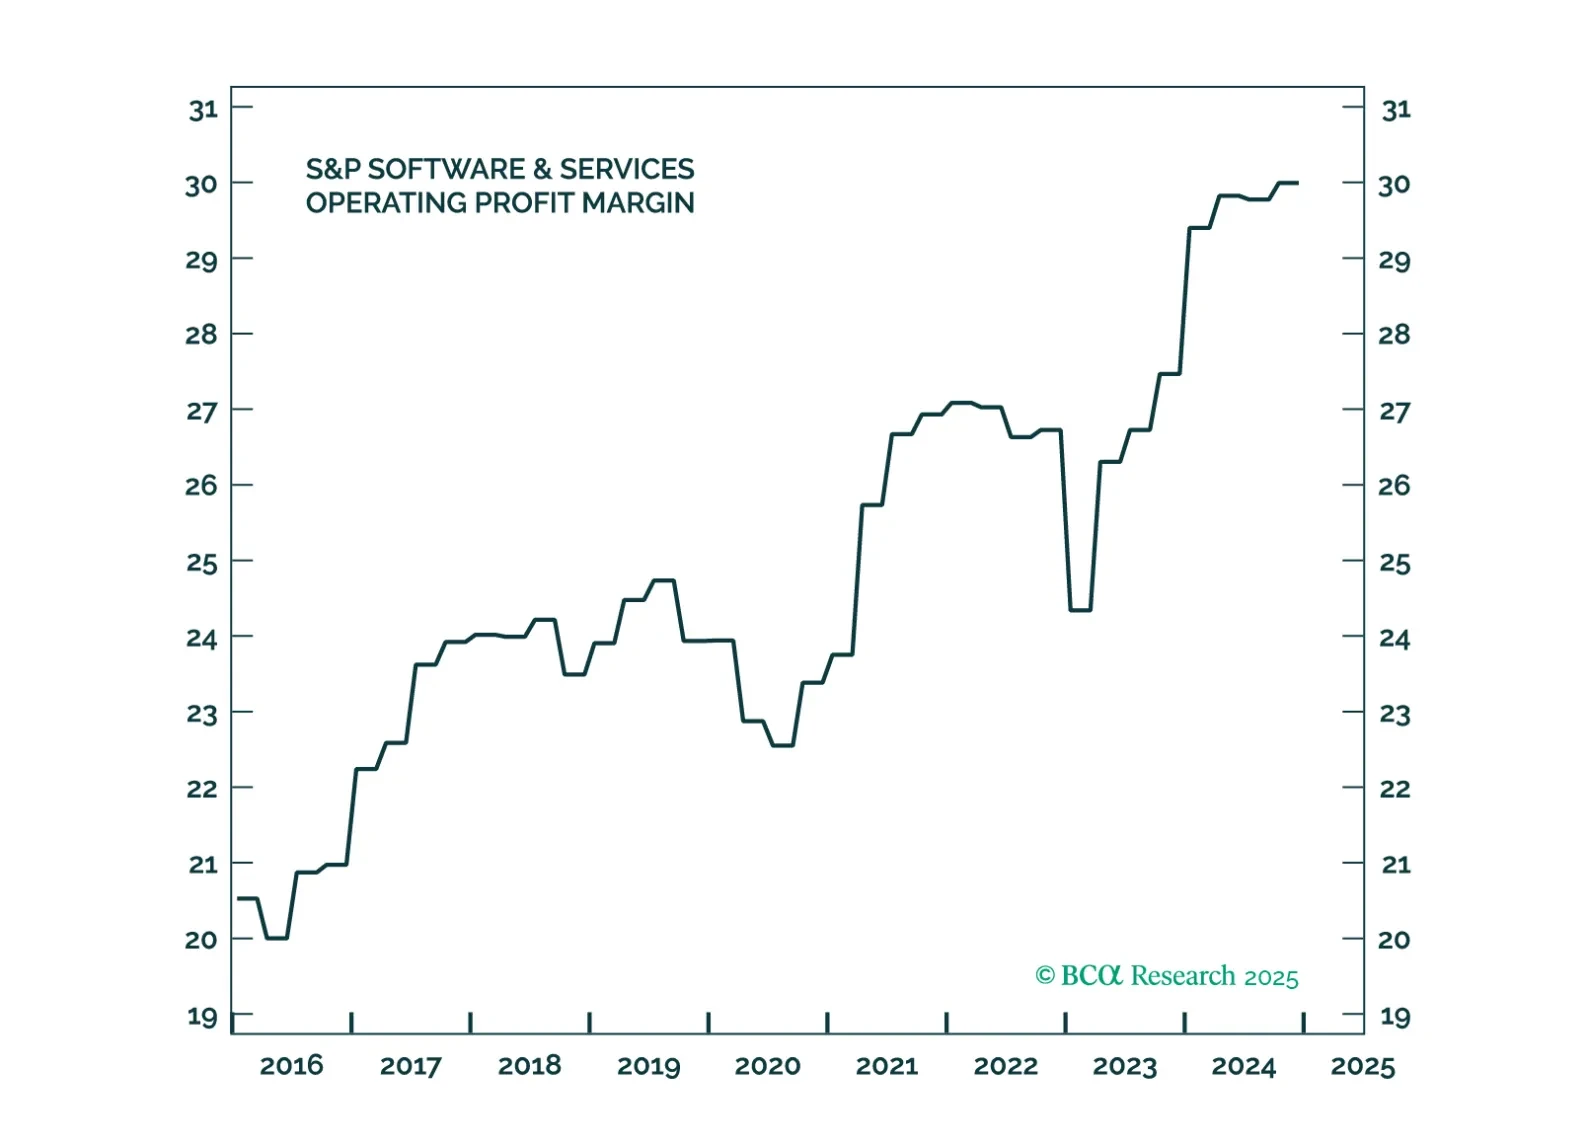
Interest rates will decline if the disinflationary trend continues, deficits are reduced, or economic growth falters. Oil prices are likely to spike over the short term, but the long-term outlook is unfavorable. Not all GenAI investments will pay off, and GenAI-induced productivity improvements do not justify current valuations.
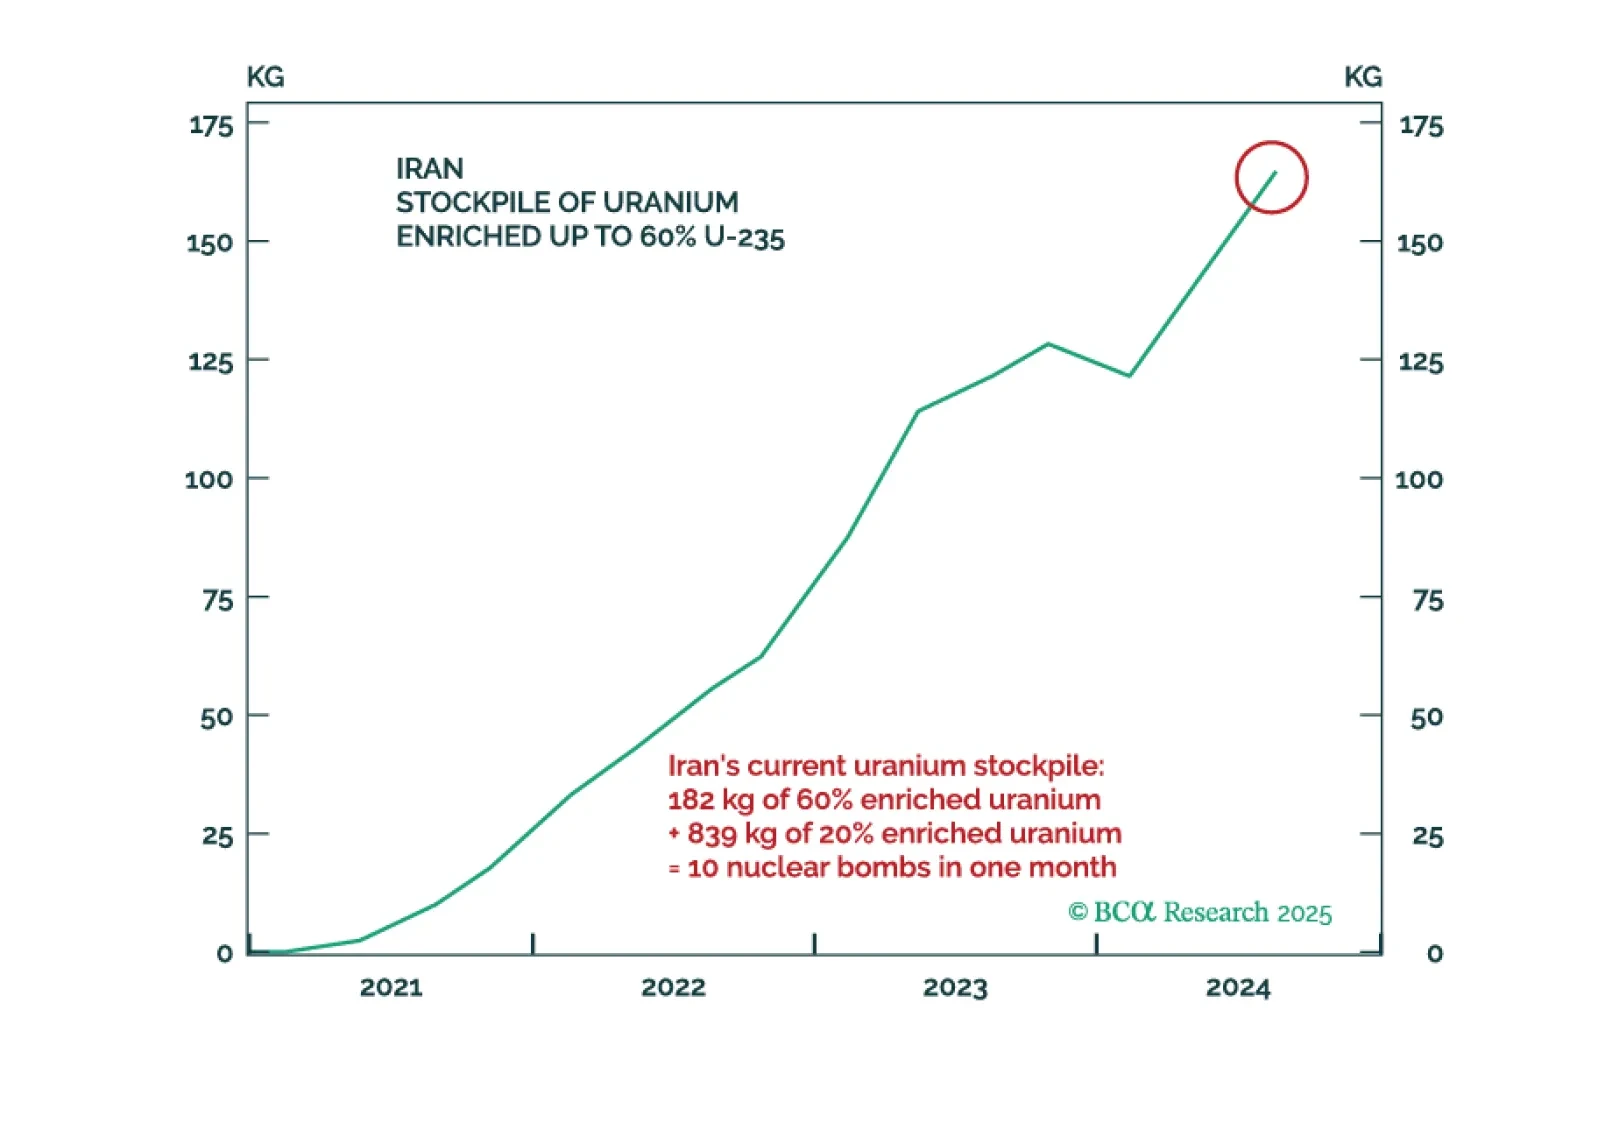
The budget process and debt ceiling will cause stock and bond market volatility. US trade policies will provoke foreign pushback at a time of stretched valuations. Hence US politics and geopolitics will be bullish for US energy, but bearish for the internationally exposed US tech sector.
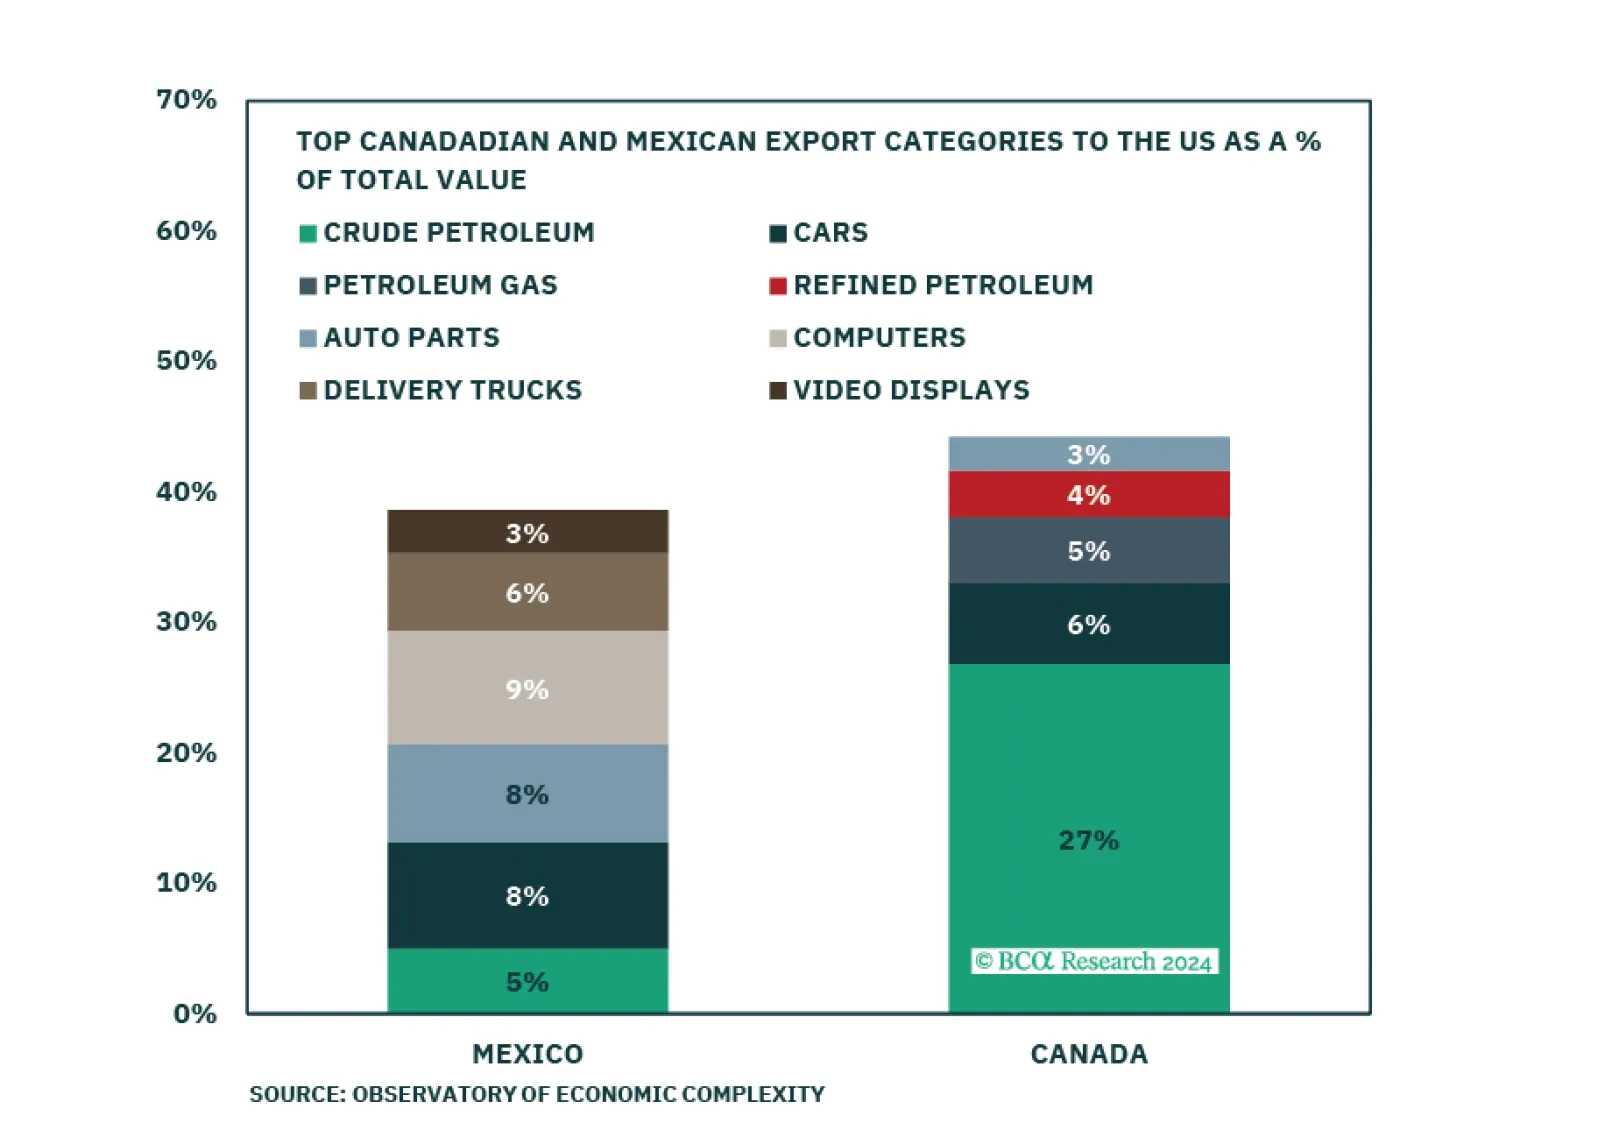
We expect market volatility to remain elevated due to uncertain economic, monetary, and trade policies. Barbell is the best portfolio strategy at this time. We recommend boosting defensive allocations to lower portfolio beta. We downgrade Industrials to equal weight and upgrade Pharma to overweight.
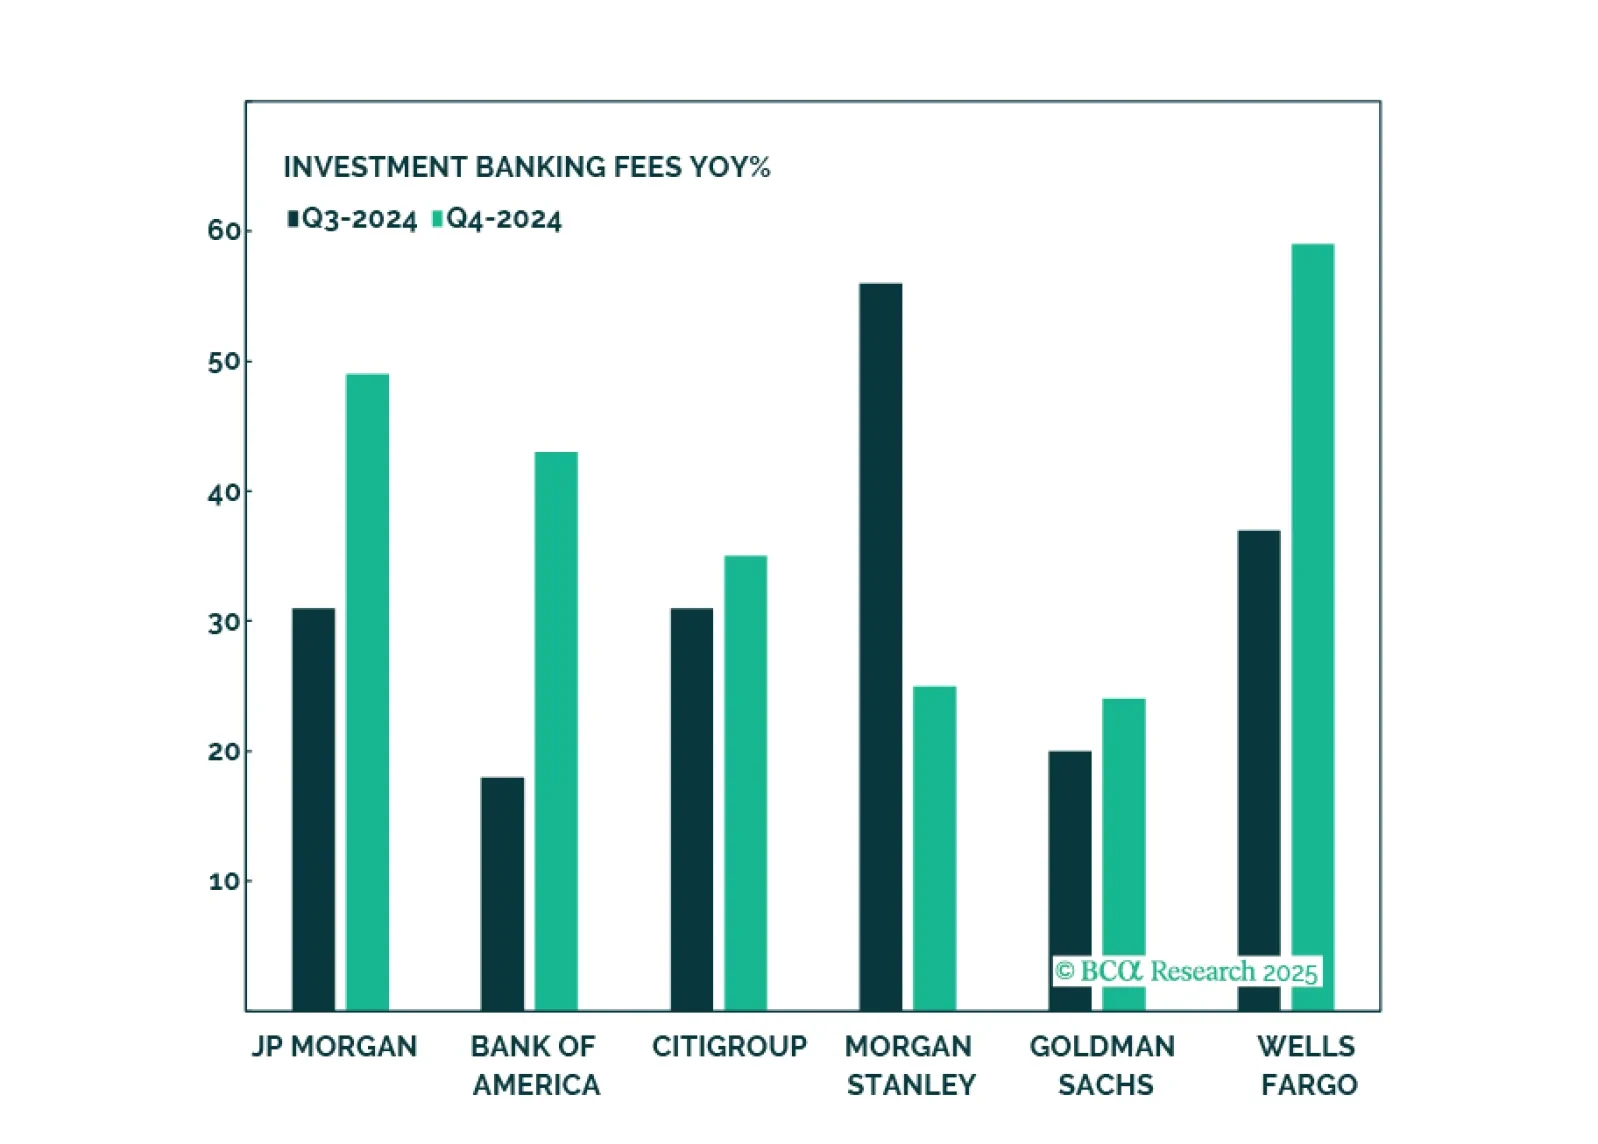
Banks have had an amazing run, and while such strong performance is unlikely to repeat, there is still oomph left in the trade thanks to a more favorable regulatory environment, stronger demand for loans, a steeper yield curve, and a strong pipeline of capital market activity. Key risks are further tightening of monetary policy and an increase in bad loans. We reiterate our overweight on Capital Markets, Diversified Banks, and Regional Banks.
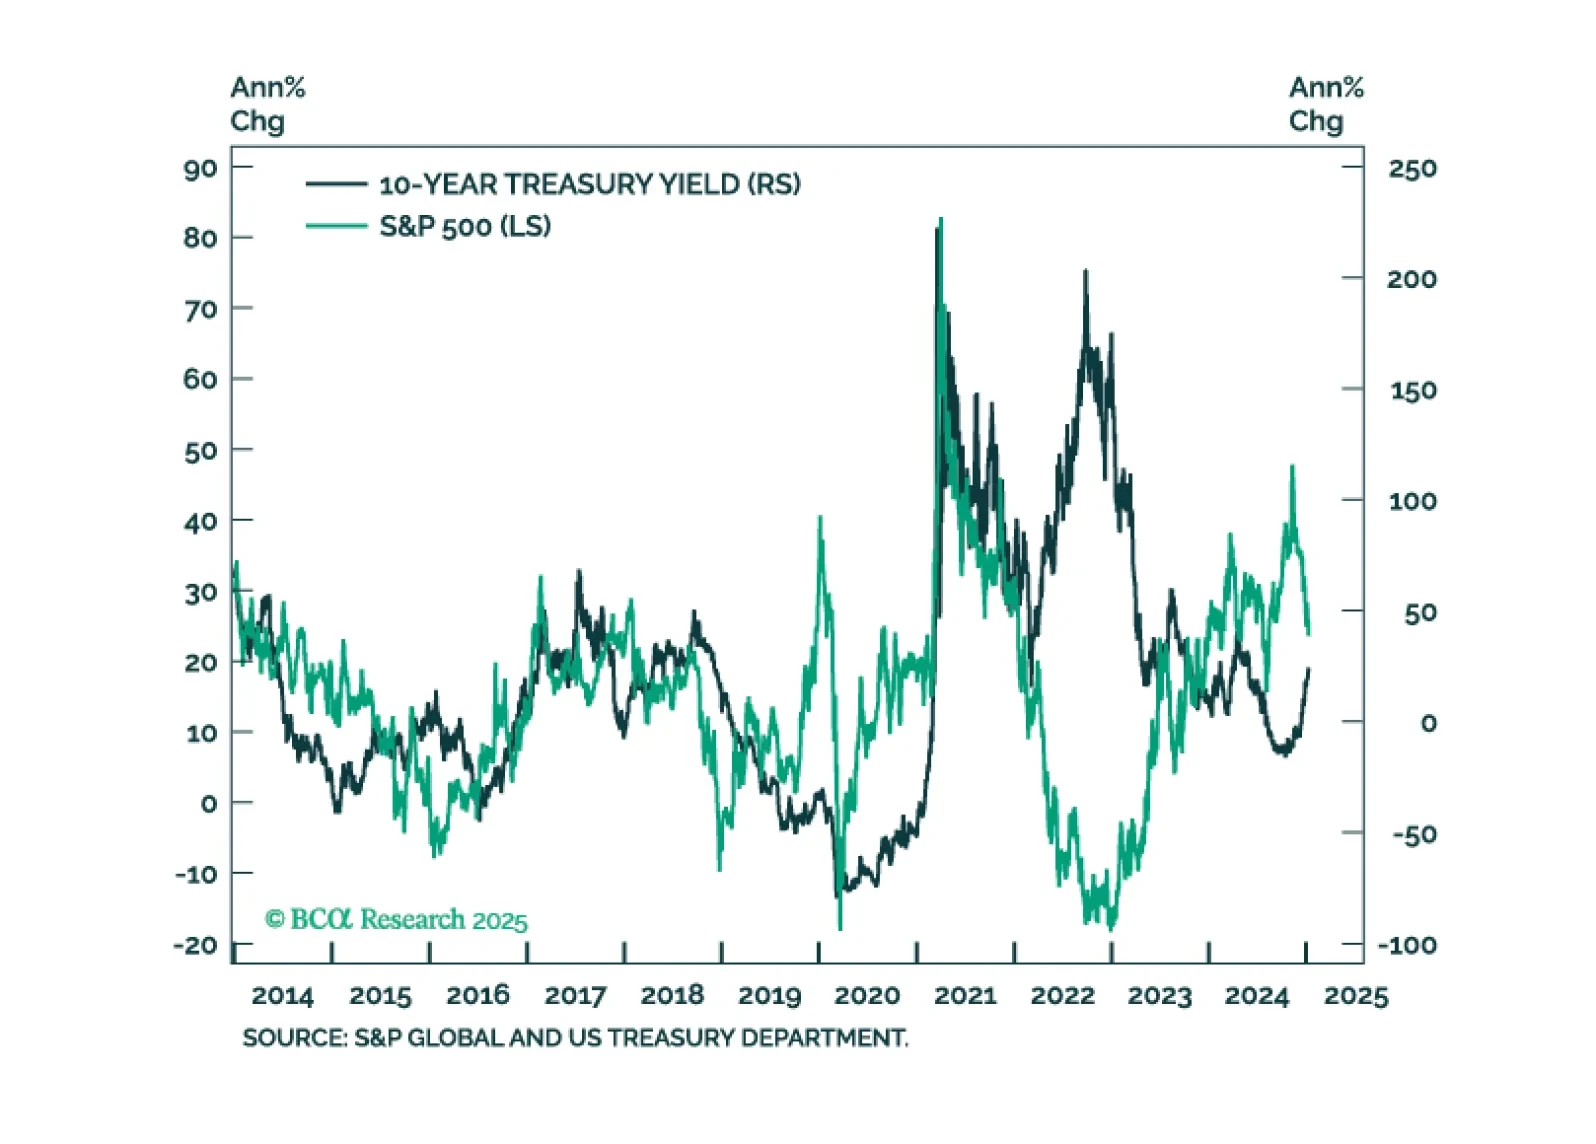
In this first presentation of 2025, we start with an overview of the 2025 outlook webcast polls, and a brief post-mortem of the 2024 market performance. Then, we shift gears and examine what is behind the recent surge in bond yields and its implications for equities. We also review market technicals and positioning and conclude with a list of trades to prepare our portfolio for continued moves in yields.
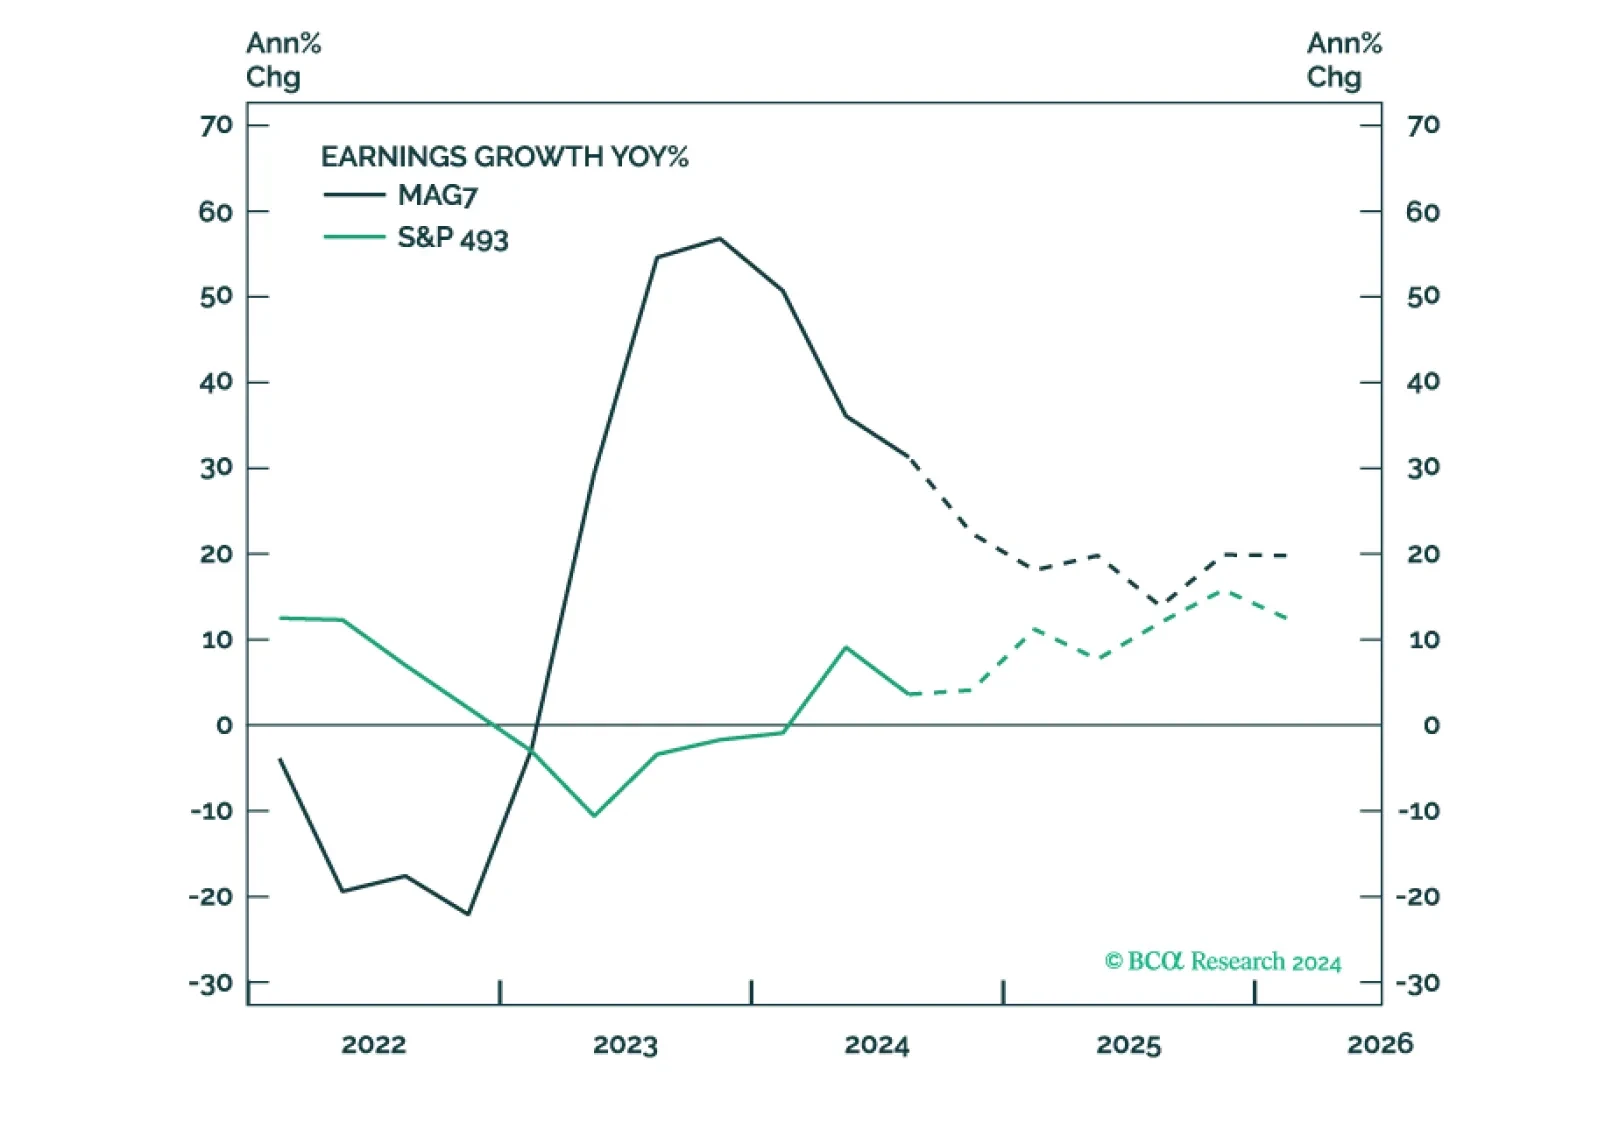
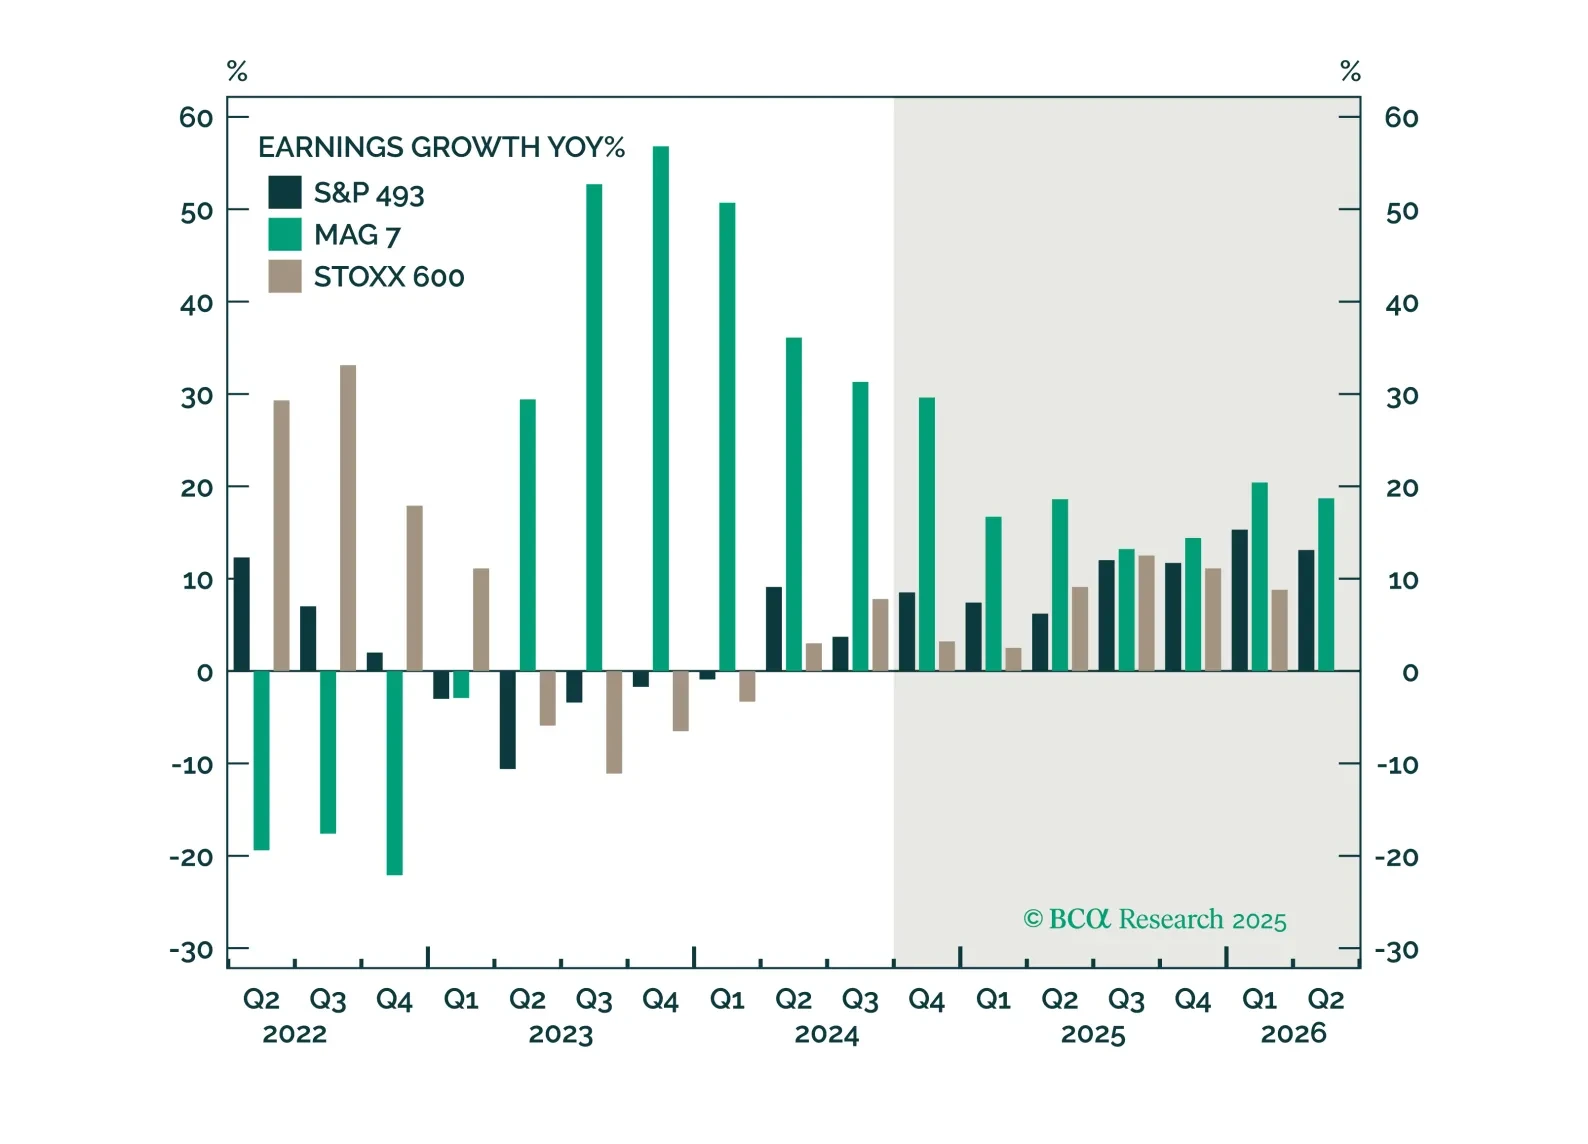
Trump's policies aim to support domestic producers and will be pro-growth and inflationary, at least initially. This environment is supportive of equities. Earnings will likely be strong, but elevated valuations make equities prone to a correction. Earnings growth broadening will translate into performance broadening – the S&P 493, Cyclicals, Value, Small and Mid are likely to outperform.
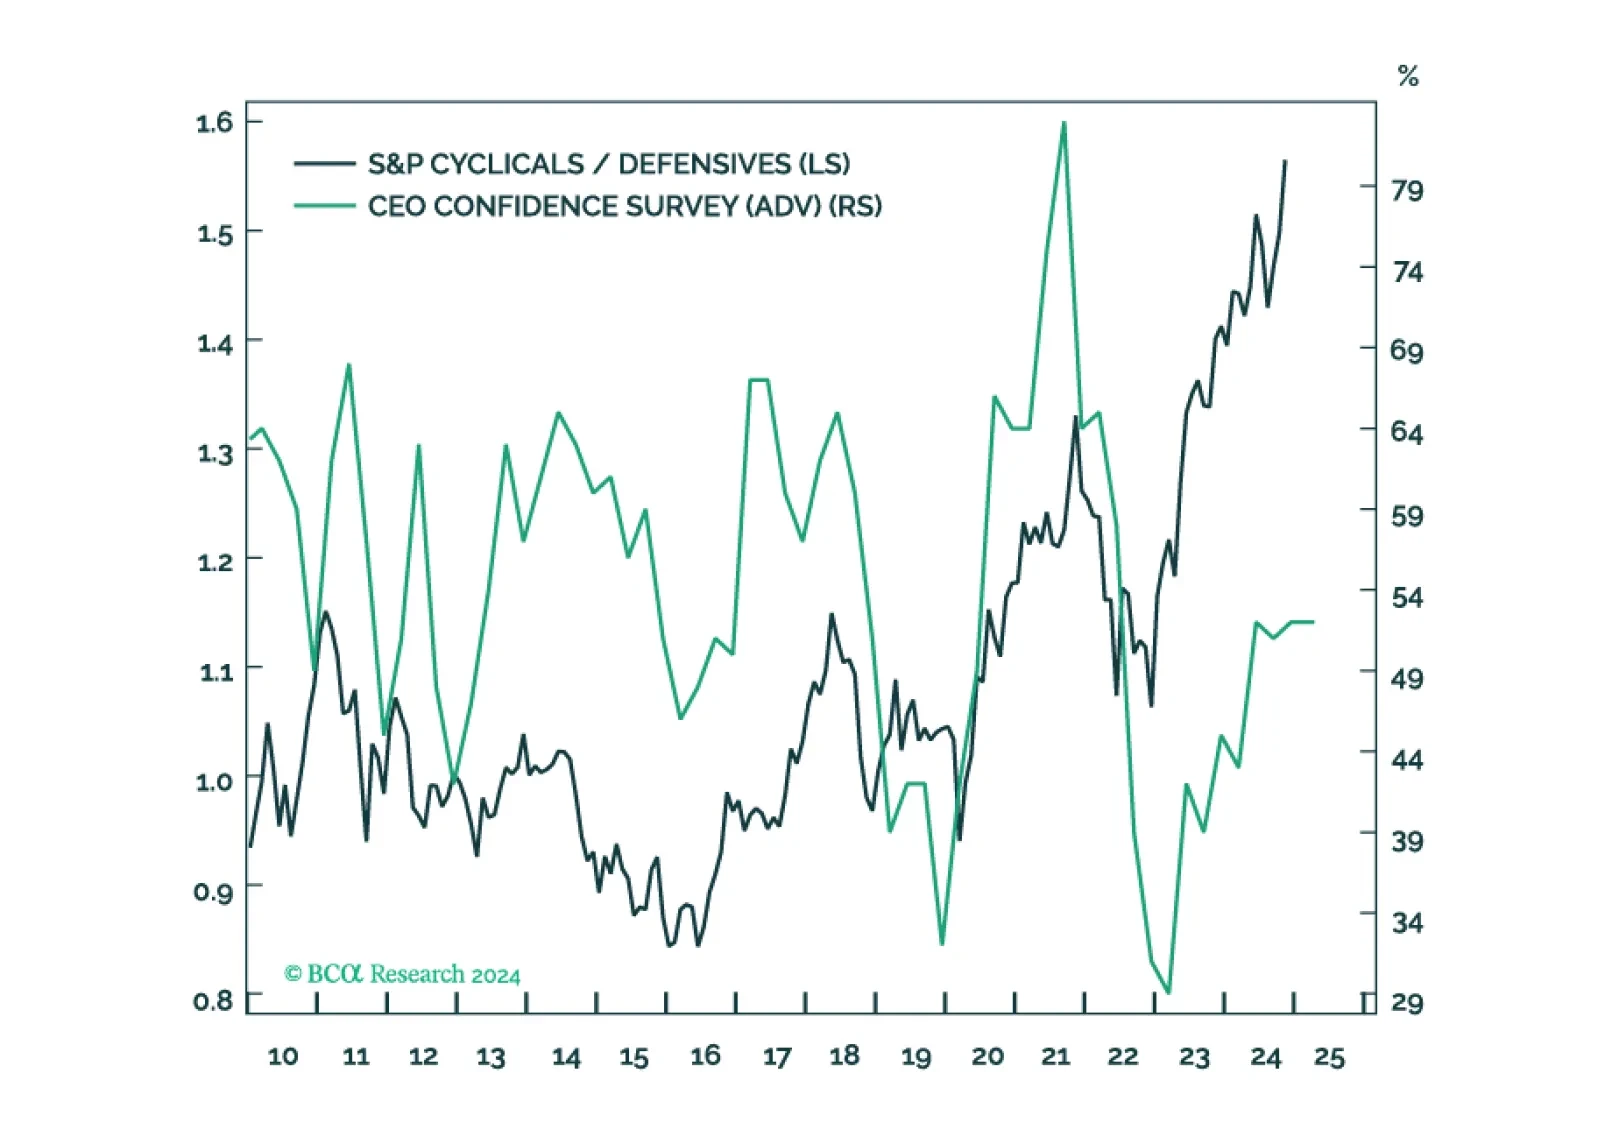
This week, we send you a Style Chart Pack without a front section. We are currently working on the 2025 outlook, which will be released on December 9.