 Equities
| US Equities
US equity research, from the S&P 500 to sectors and factors, on where stocks are heading next.
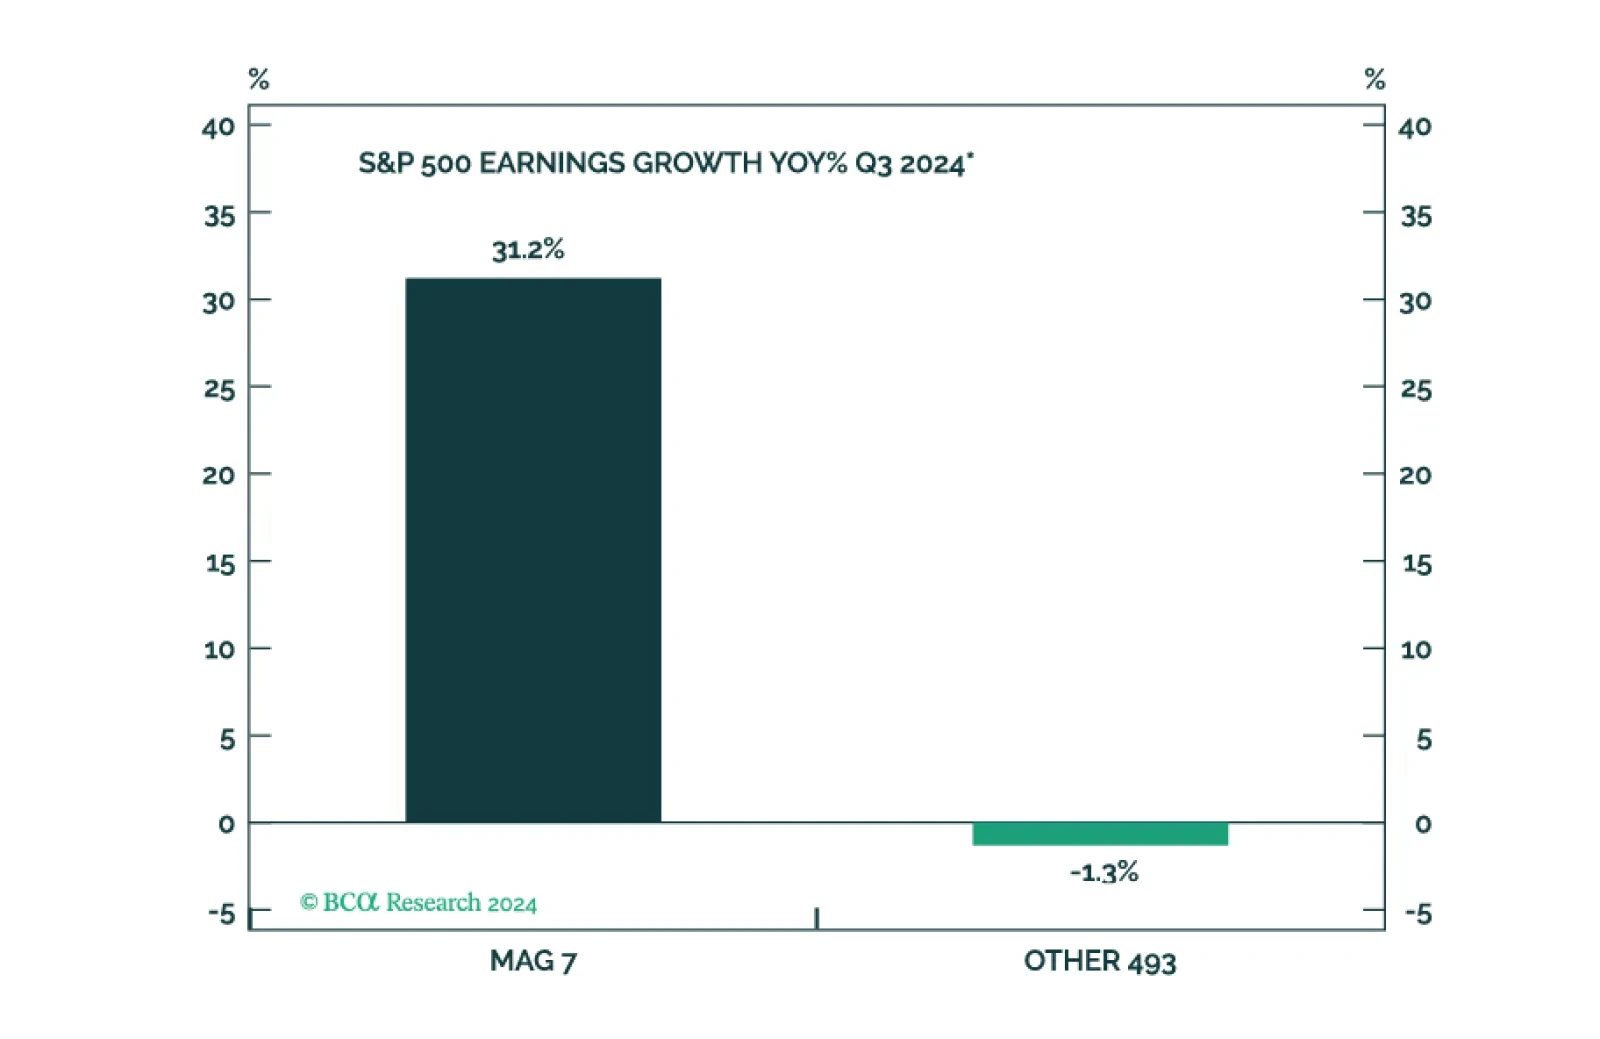
The earnings season was good but failed to assuage investor concerns that earnings growth remains concentrated. Tepid earnings and sales beats were somewhat concerning. However, based on company commentaries, the US economy remains sound. While challenges remain, such as slowing global growth, a strong dollar, and weakness among lower-income consumers, companies see them as surmountable. The market expects earnings growth to broaden in 2025. We concur as long as there are no major disruptive events.
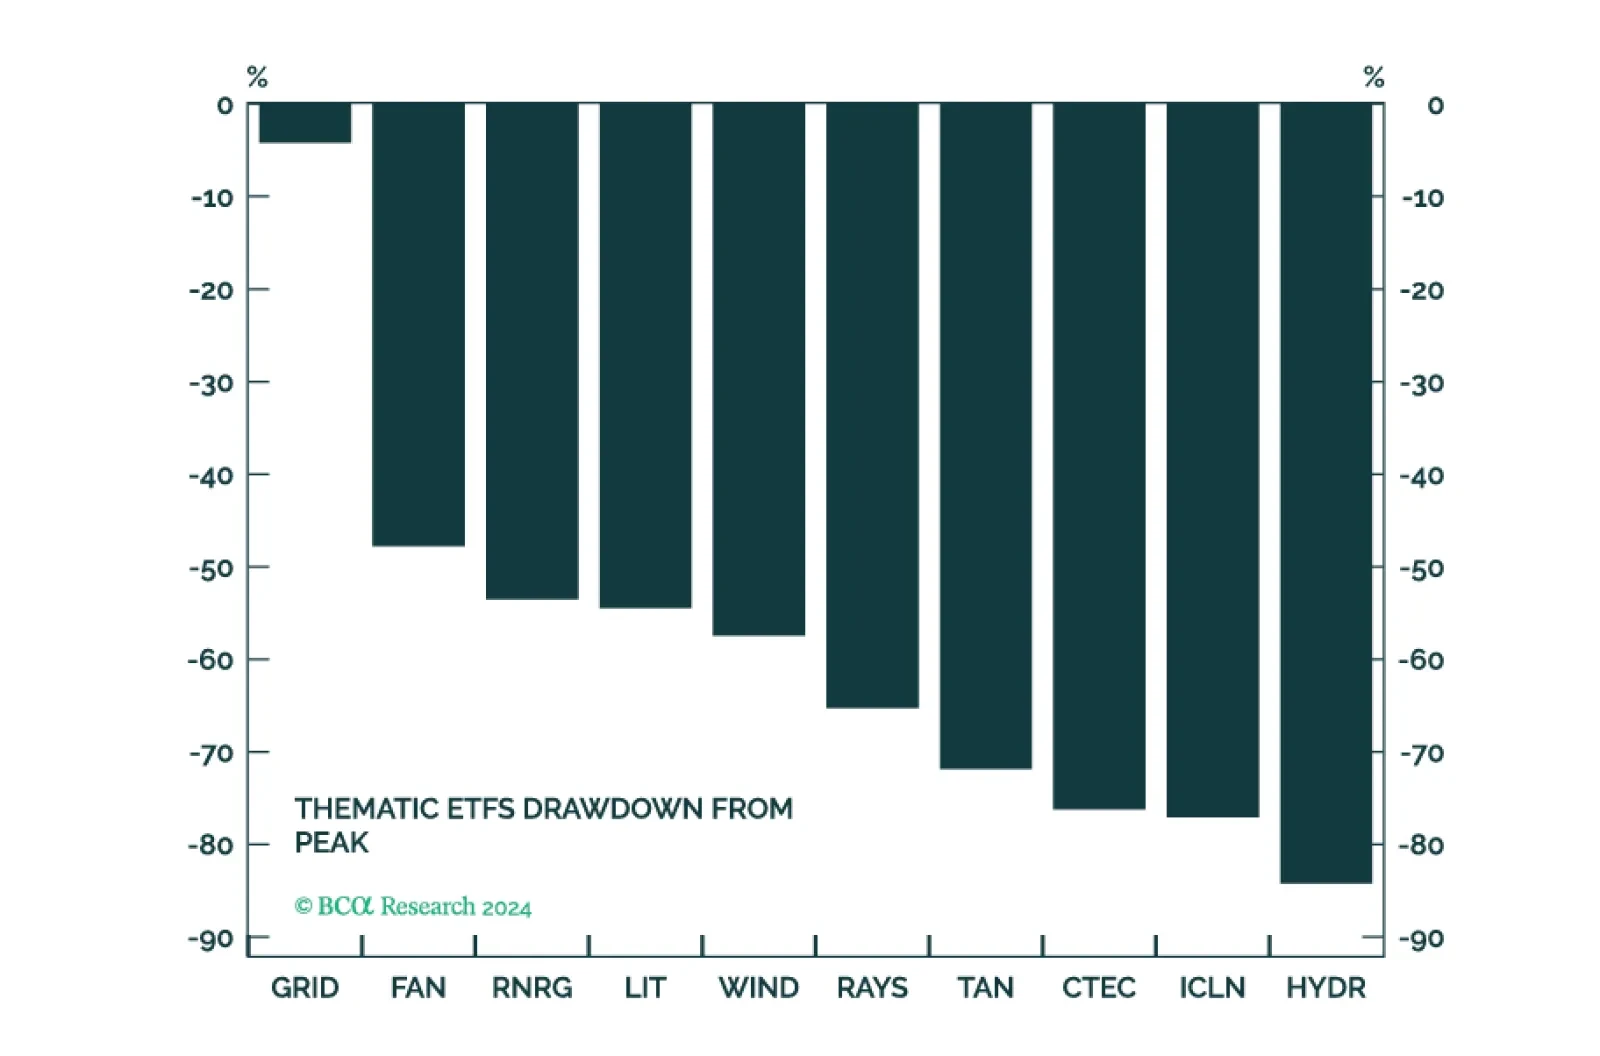
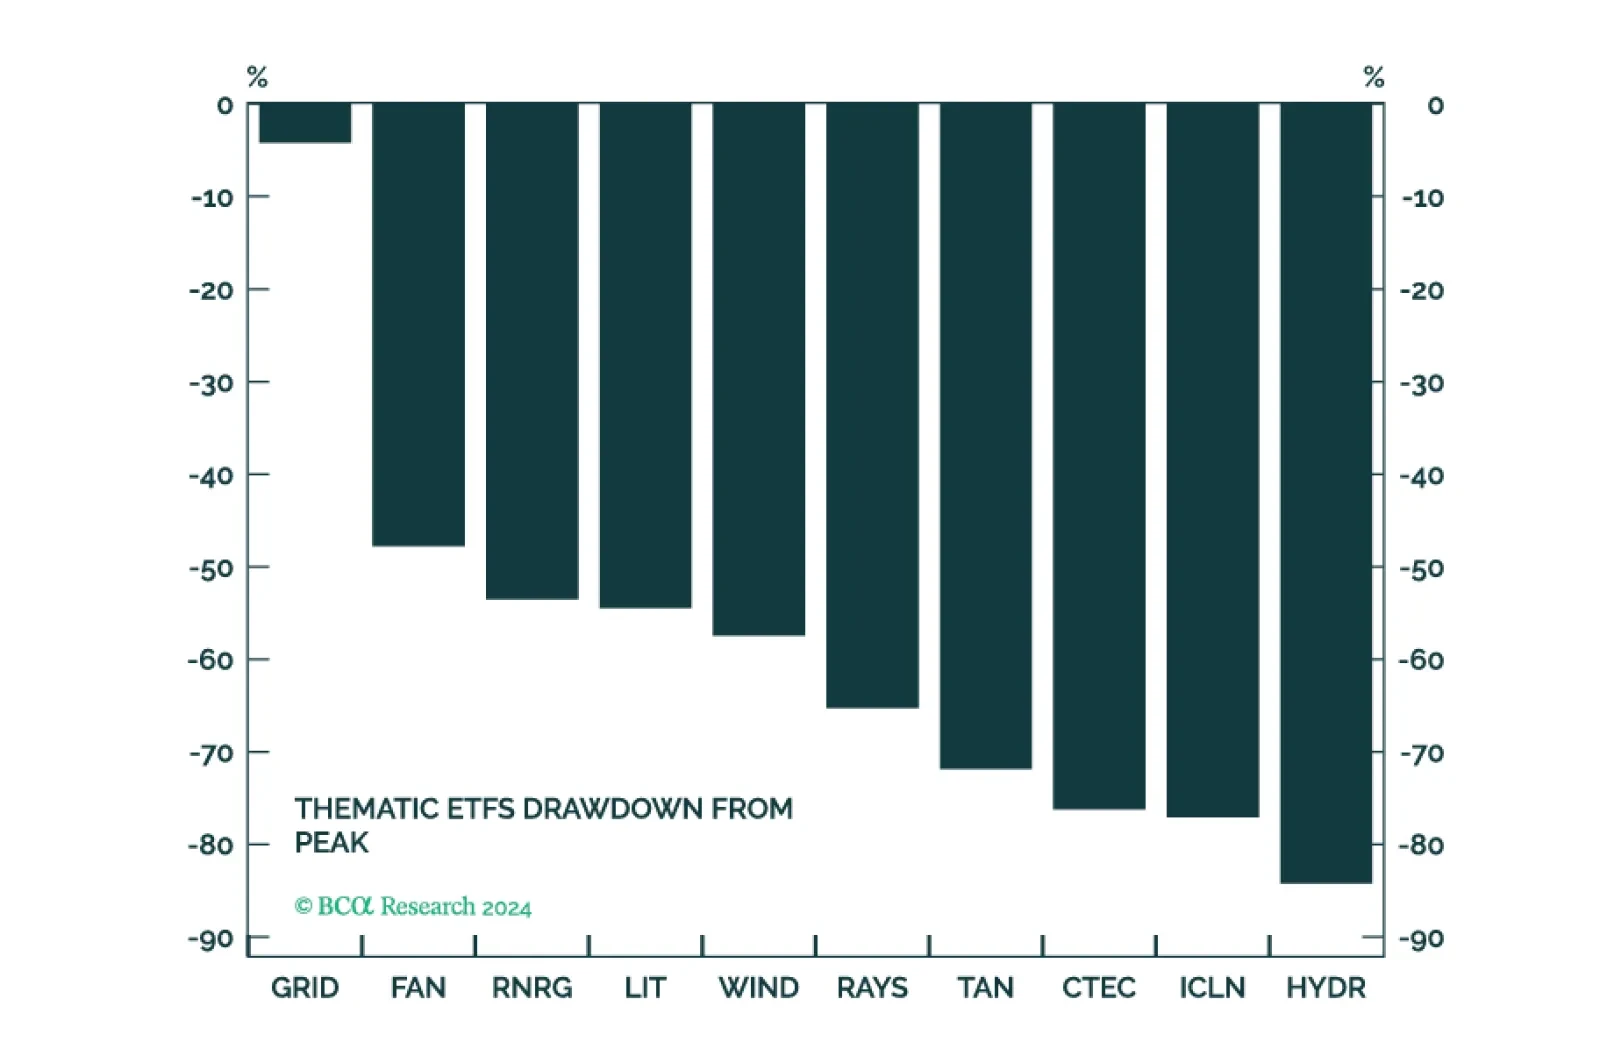
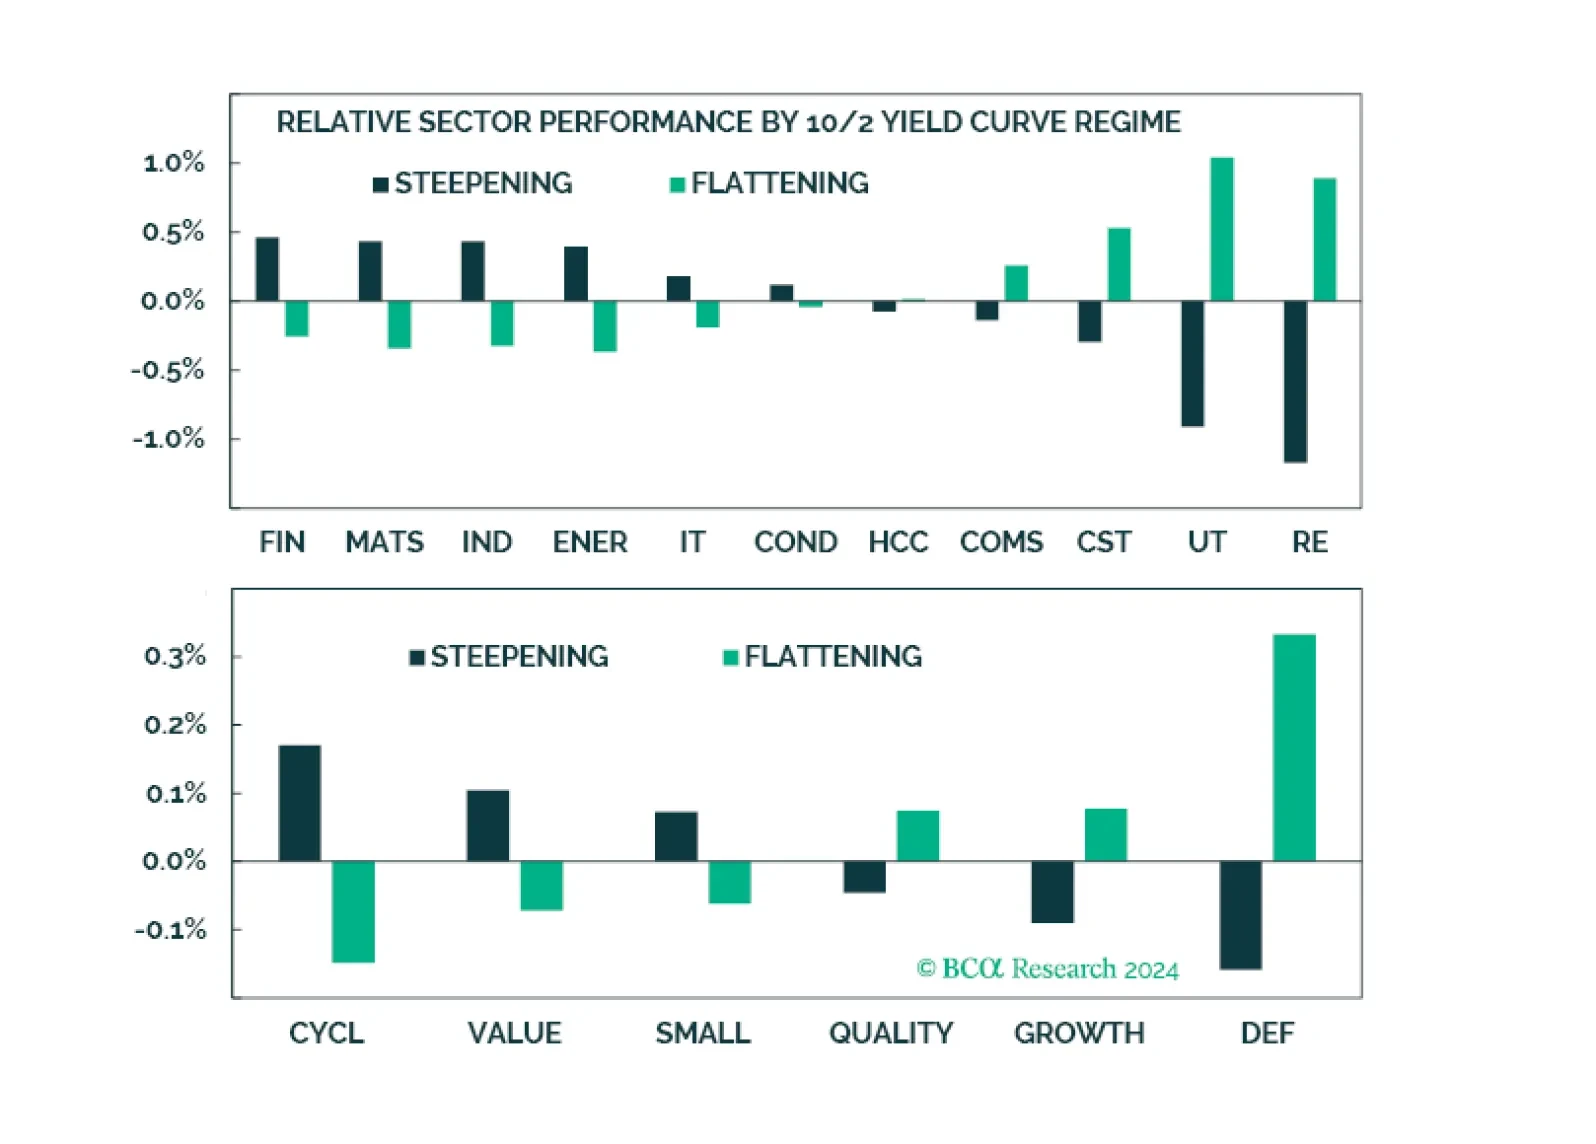
The market is celebrating the prospect of deregulation, lower taxes, and Fed rate cuts, for now ignoring the dangers of wider budget deficits, inflationary pressures, and trade wars. The rally can continue into the year-end and reduced uncertainty, seasonality, and positive momentum will benefit recent laggards such as Small, Value, and Cyclicals. We downgrade Energy from overweight to underweight. We downgrade Telecoms and Consumer Staples to underweight. We upgrade Insurance from underweight to overweight. We upgrade Utilities to overweight.
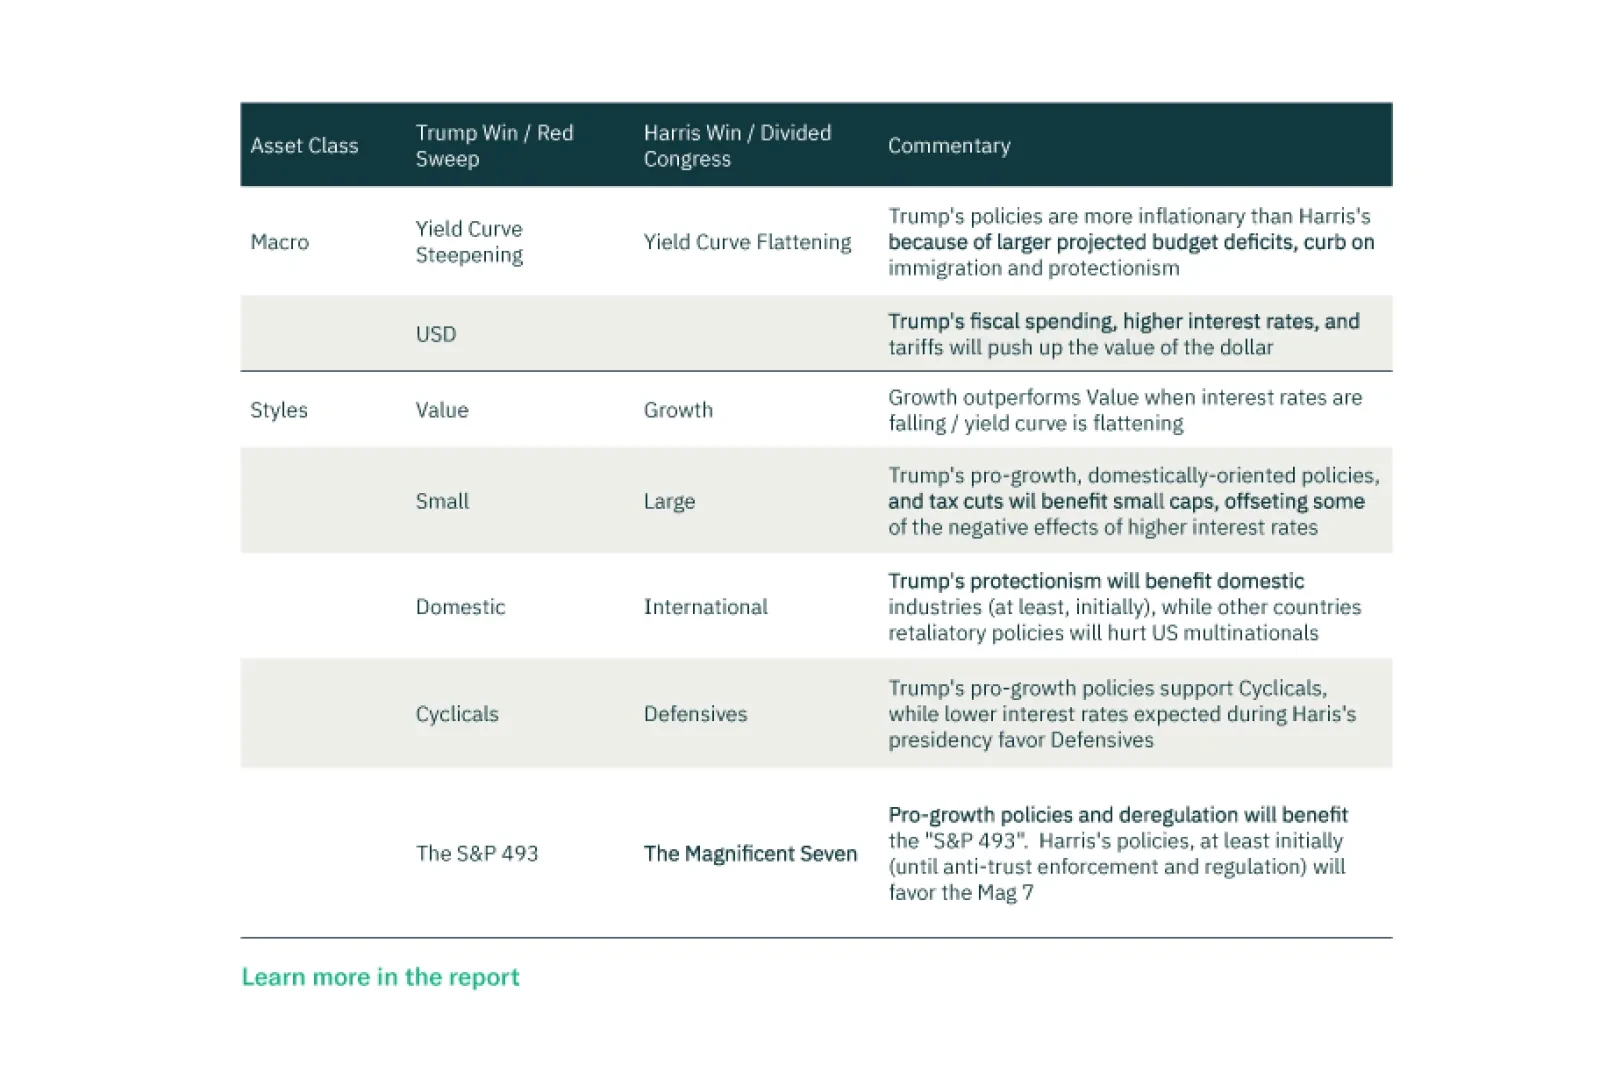
The most likely outcomes for the US elections are a “Red Sweep” and a “Blue Gridlock.” The following is a brief discussion of likely policies associated with each election outcome. We also present a post-election US Equities Cheat Sheet, in which we summarize winning trades for each scenario over the tactical investment horizon.
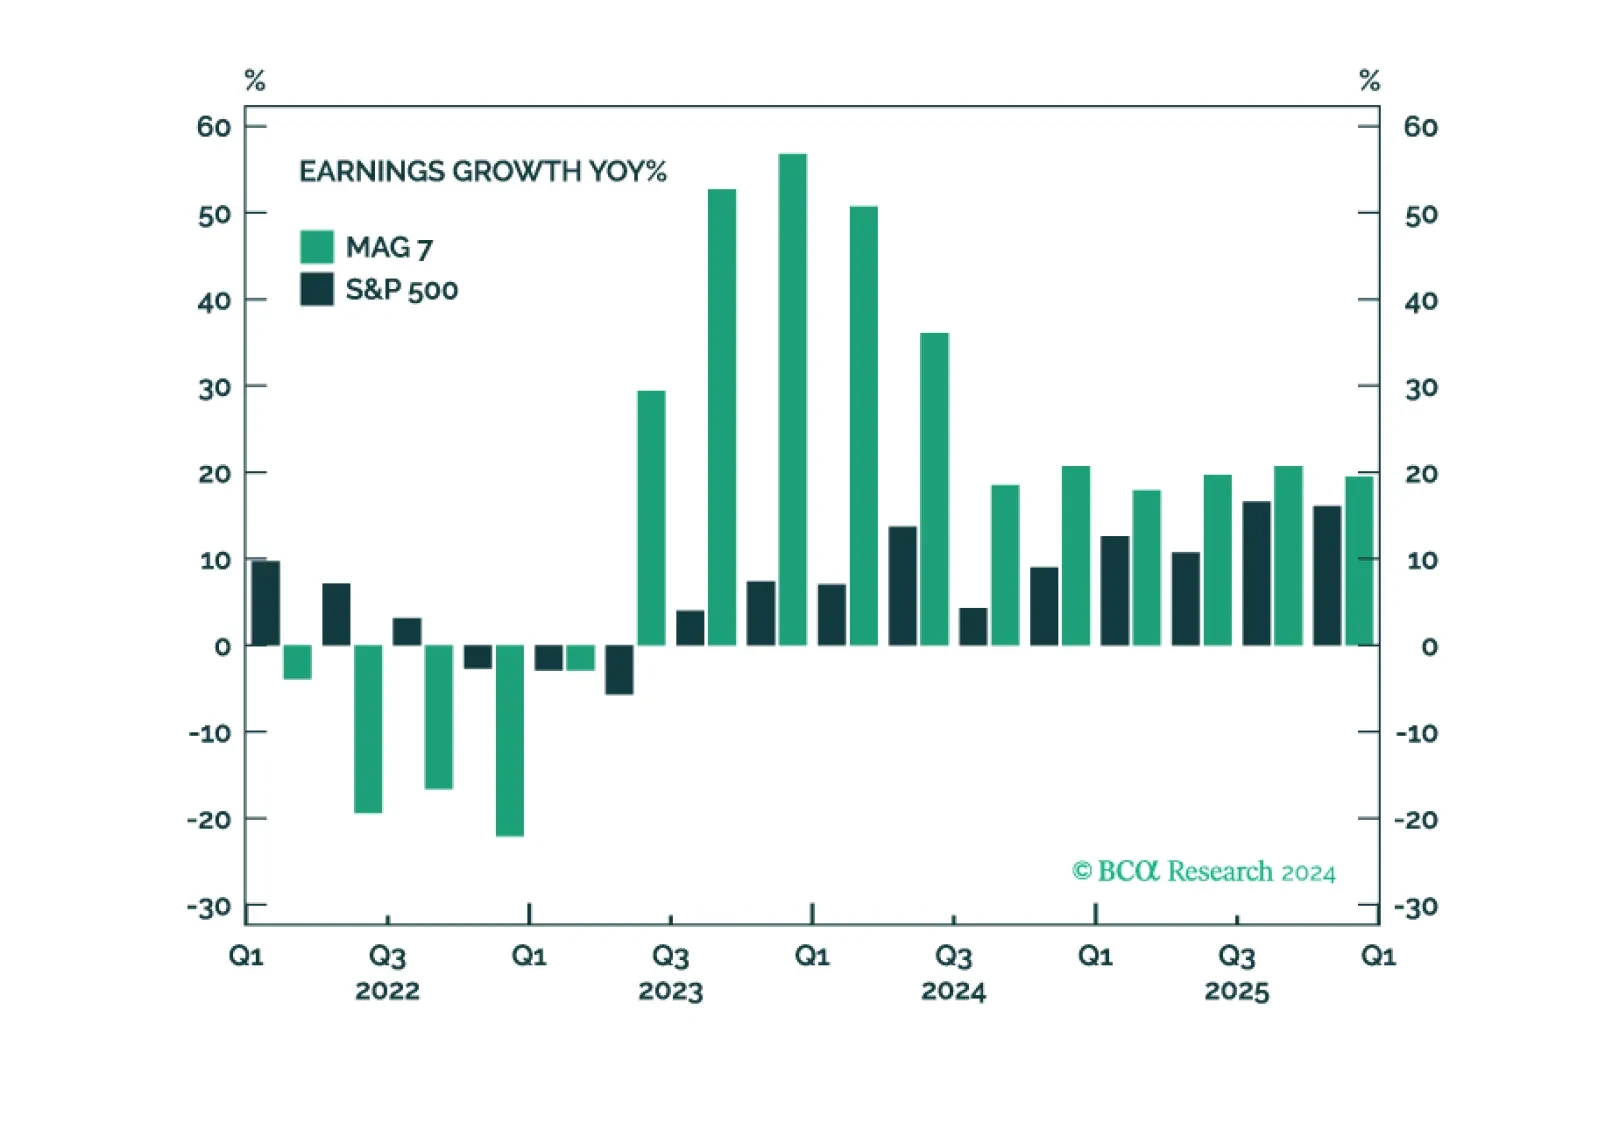
This week, we are sending you a sector chart pack. In the front section of this publication, we briefly review October's performance and then switch our attention to the earnings season and outlook for the Magnificent Seven.
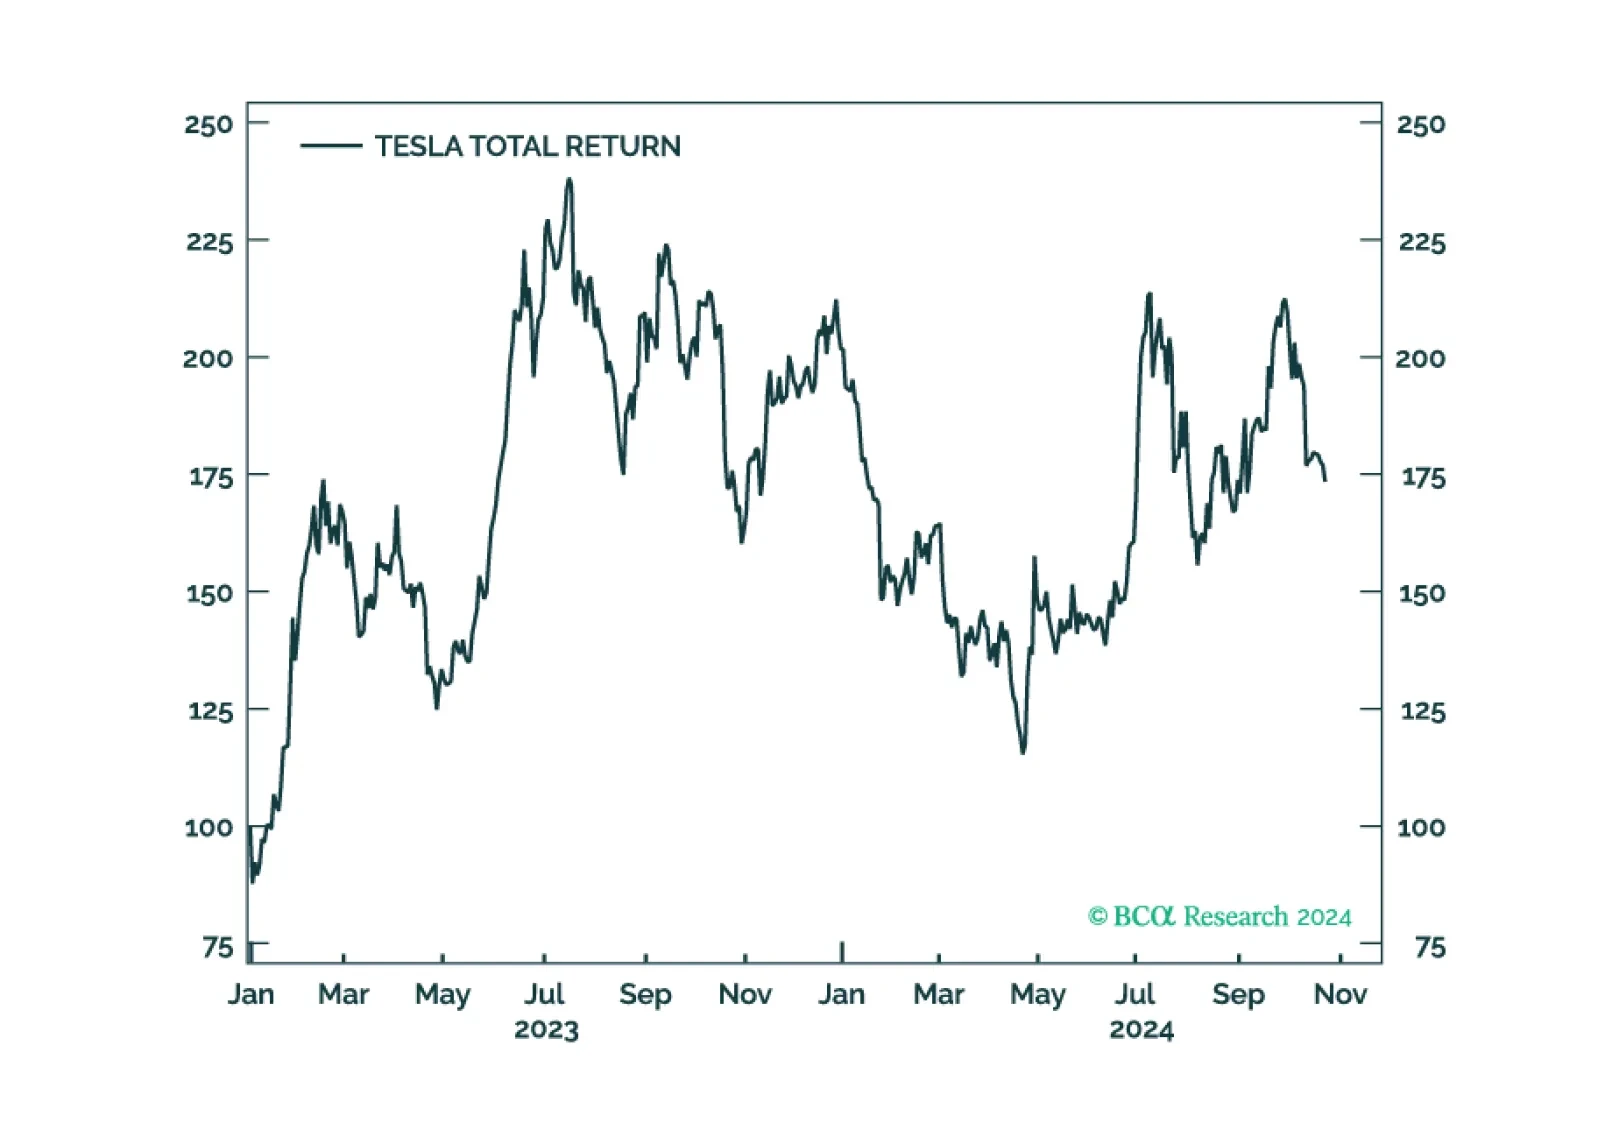
Upgrade Auto & Components Industry Group from an underweight to an overweight as it is dominated by Tesla, whose outlook has brightened.
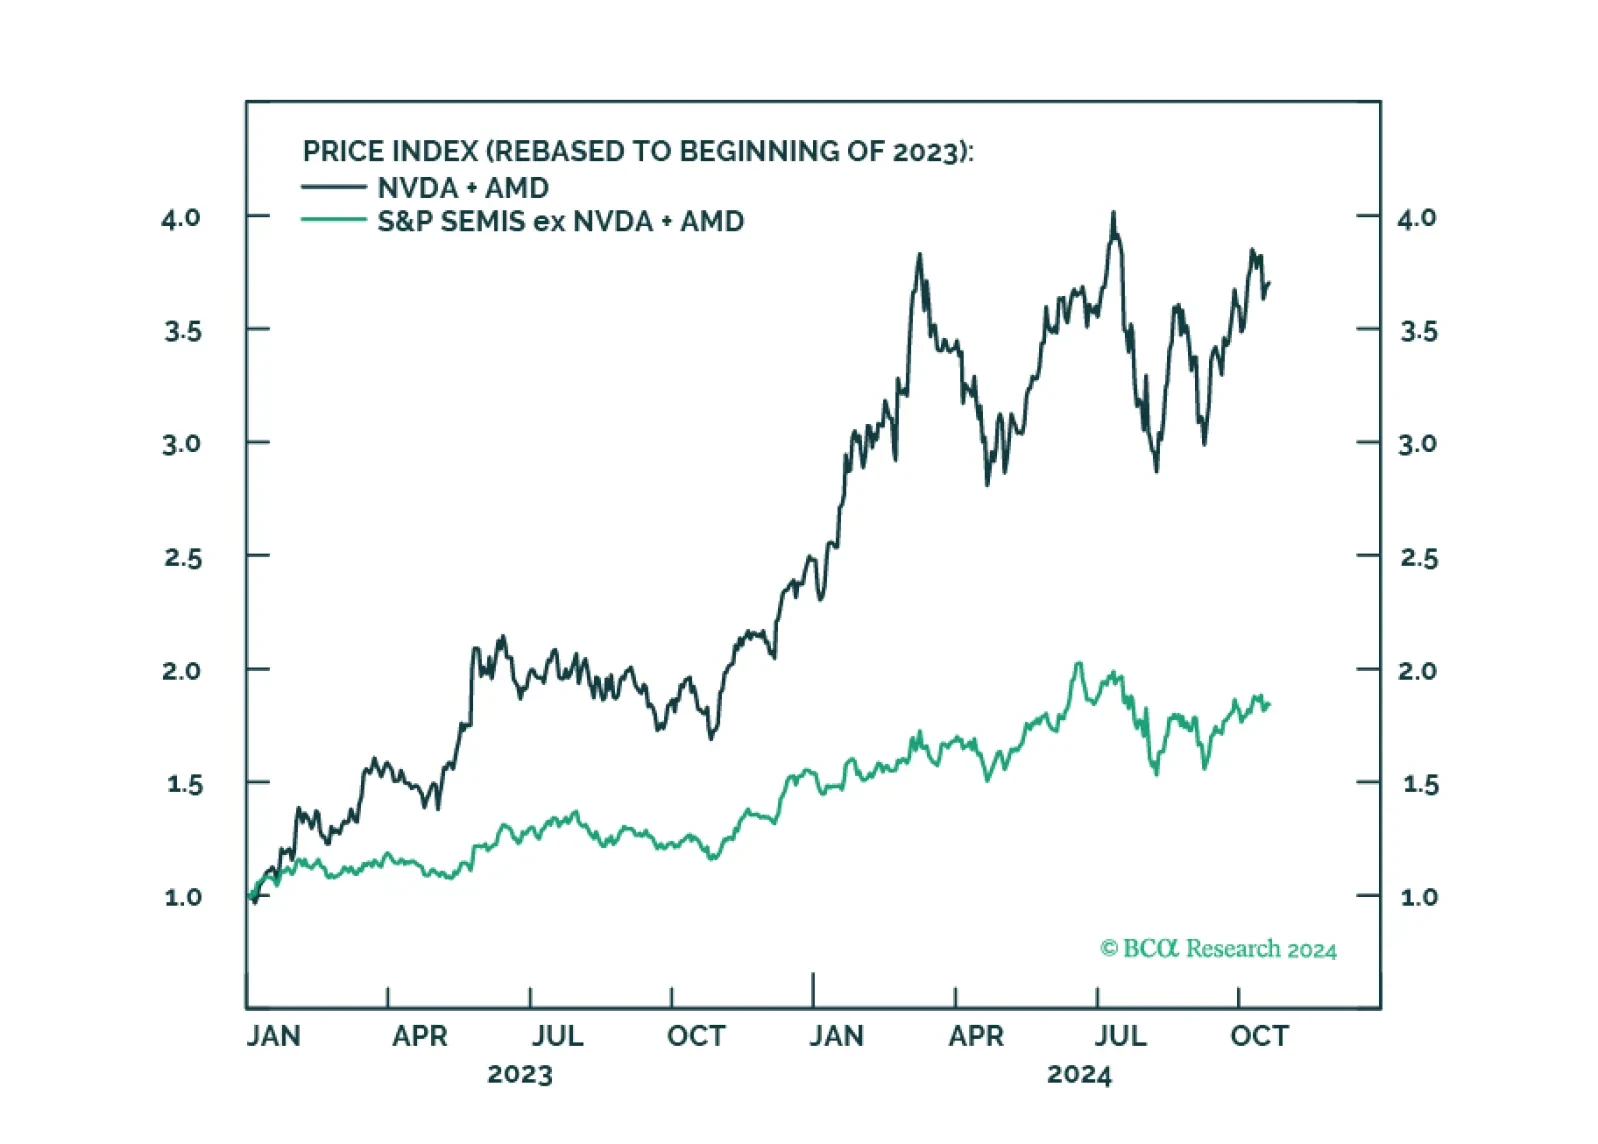
The semiconductor industry has decoupled: Demand for AI and advanced chips is booming, while the outlook for legacy and non-AI semiconductors is downbeat. We upgrade the US semiconductors to overweight on a tactical investment horizon as Nvidia’s good fortunes will drive the performance of the entire industry. We also reiterate overweight in Diversified Financials and Capital Markets as the resurgence in capital market activity is still in its early innings and will continue to drive the outperformance of the nation’s largest investment banks.
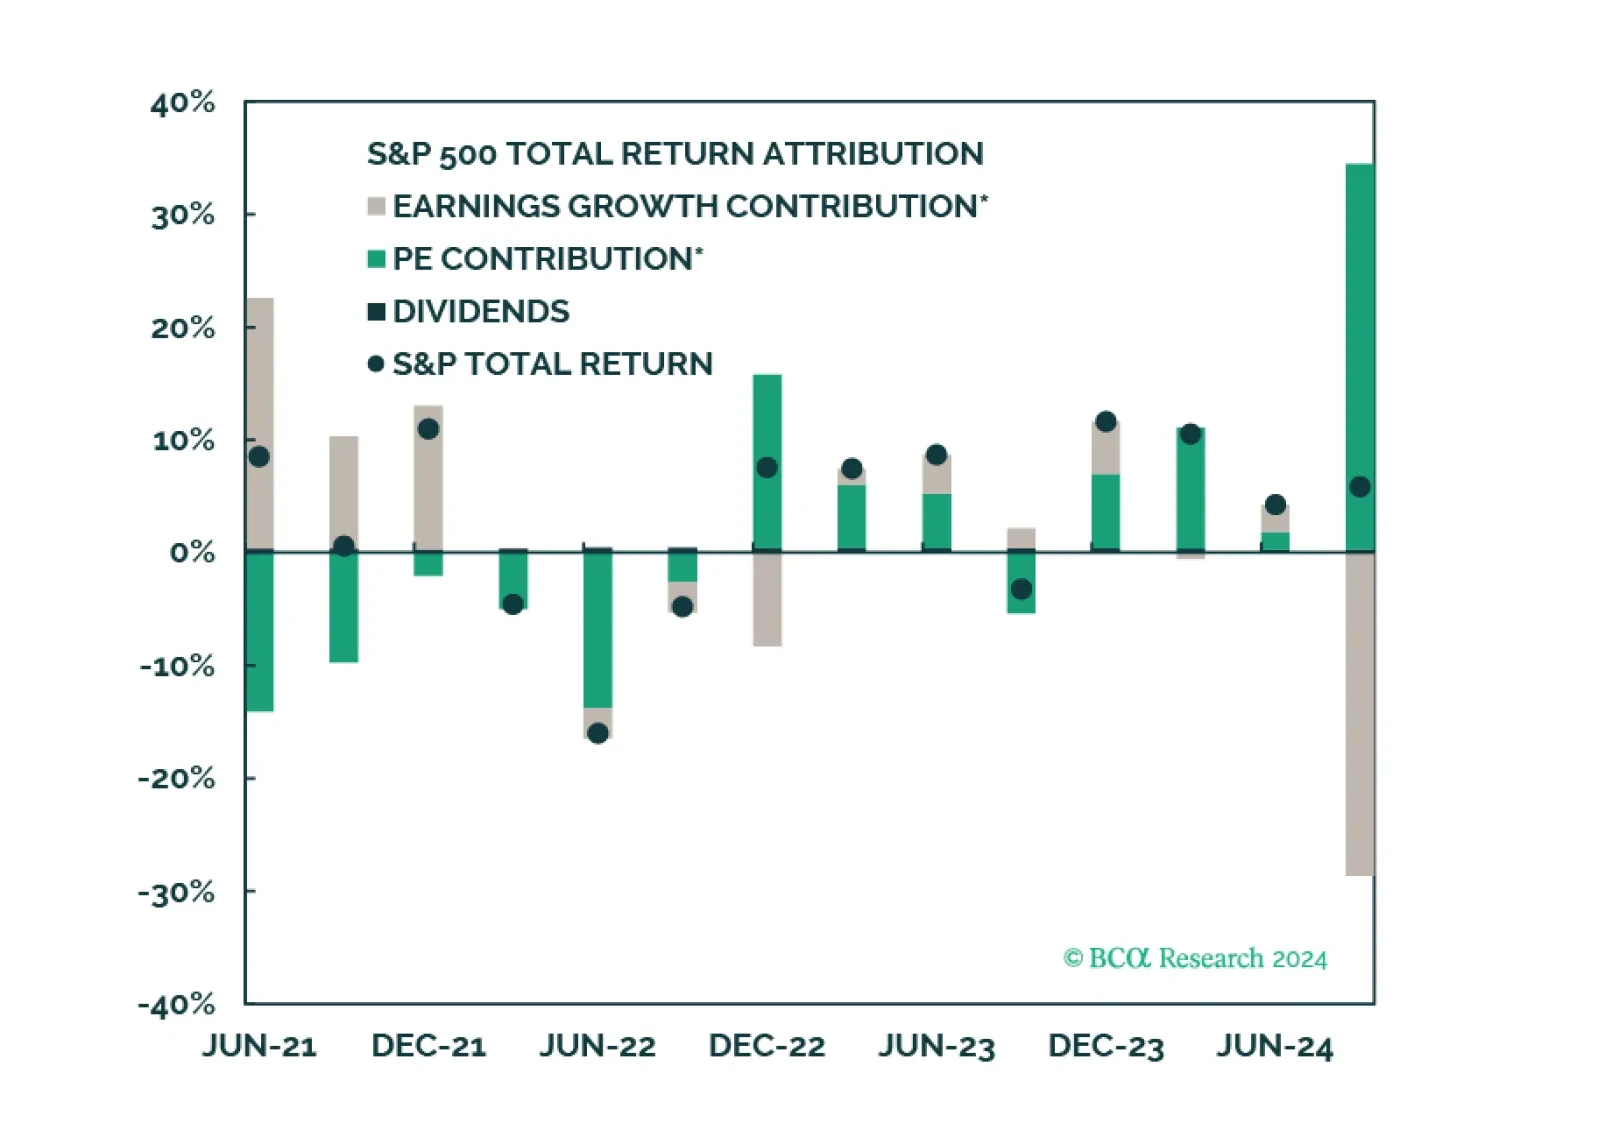
Earnings growth is expected to be strong enough to assuage investors' fears that recession is not yet imminent. Q3 earnings expectations have been revised downward over the past three months, and the bar for the beats has been lowered. Operating margins are also expected to expand.