 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.

In this report, we present the quarterly review of our Model Bond Portfolio. Rebounding growth and political instability led to slightly negative portfolio performance in Q2/2024. As global growth starts to moderate, we continue to favor government bonds over credit. Maintain a defensive portfolio stance.
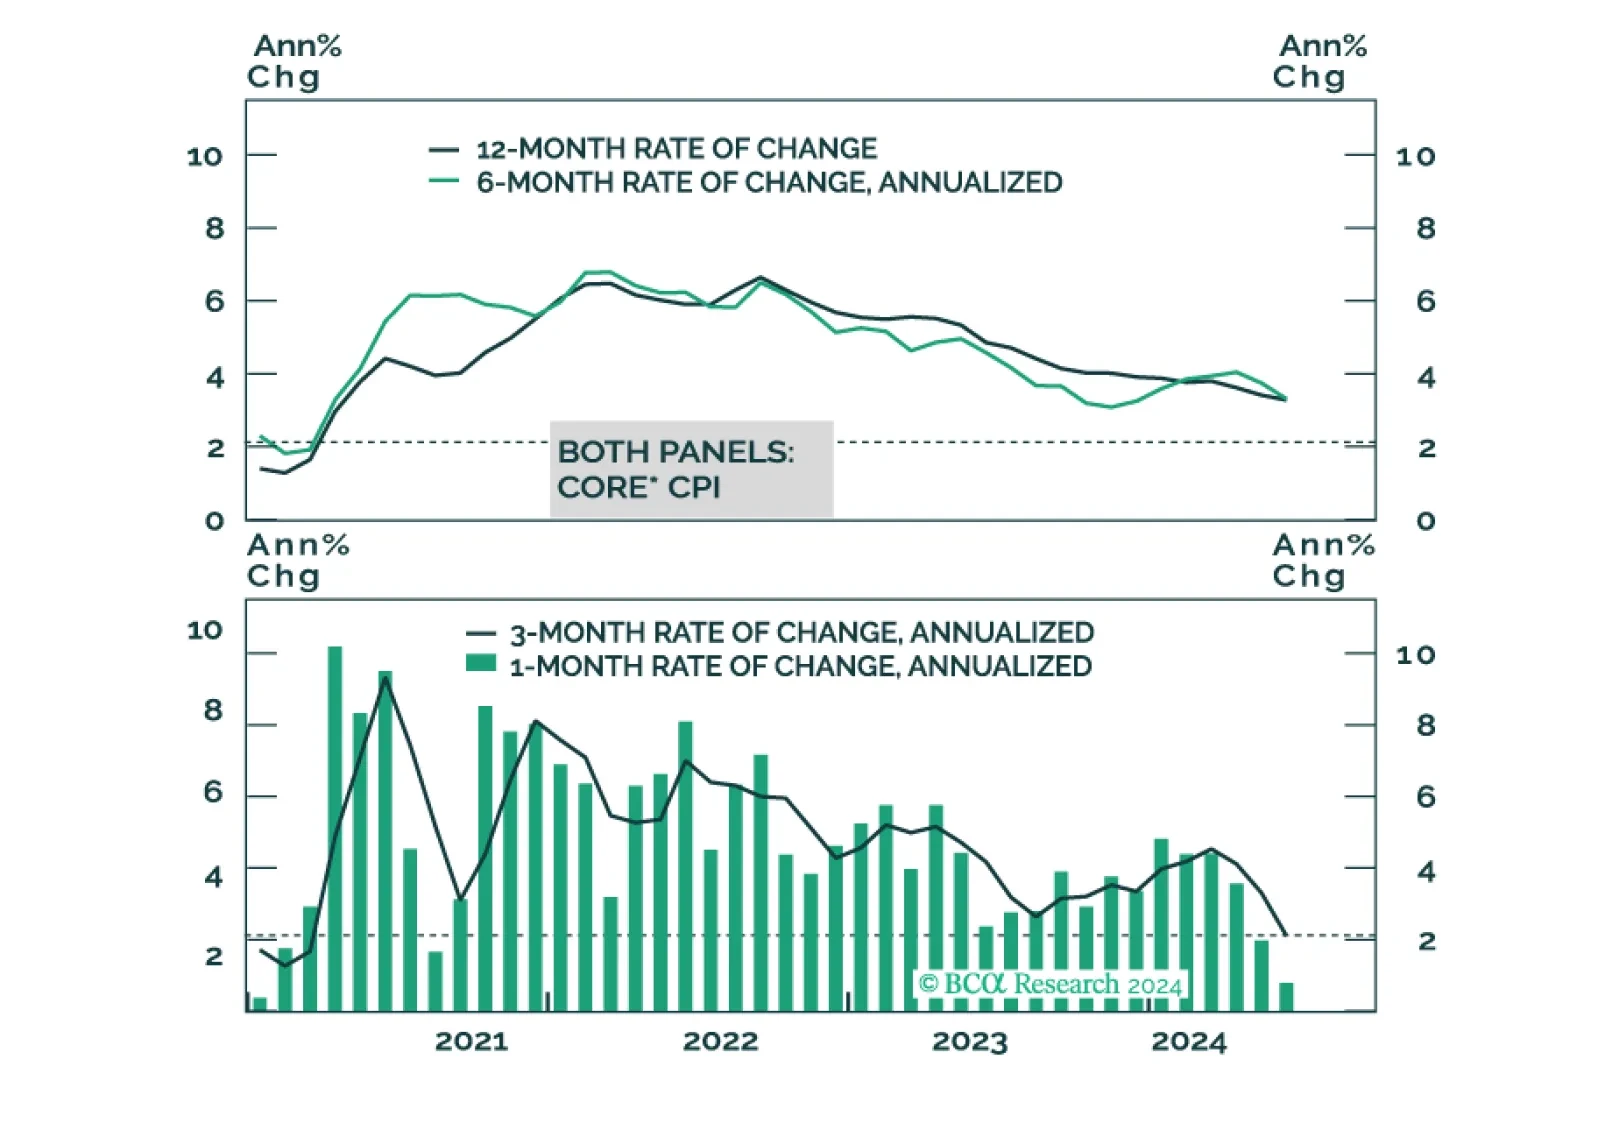
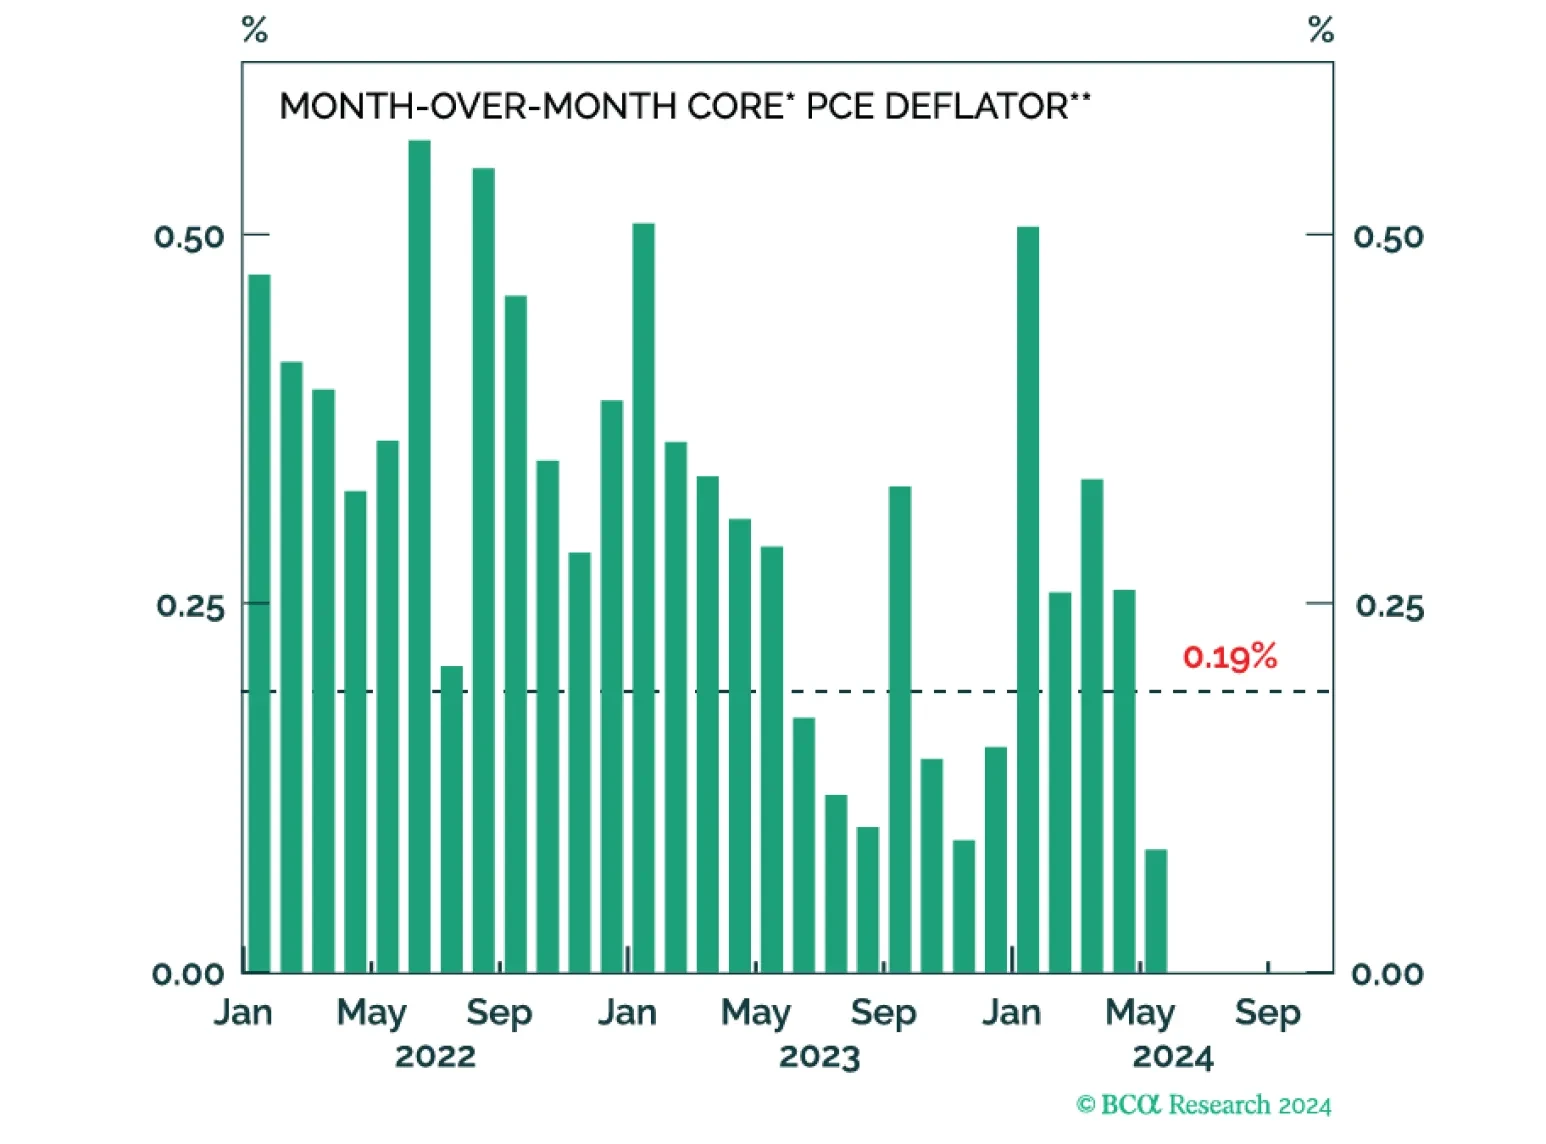
In light of last week’s employment report and this morning’s CPI, it’s time for the Federal Reserve to cut rates.
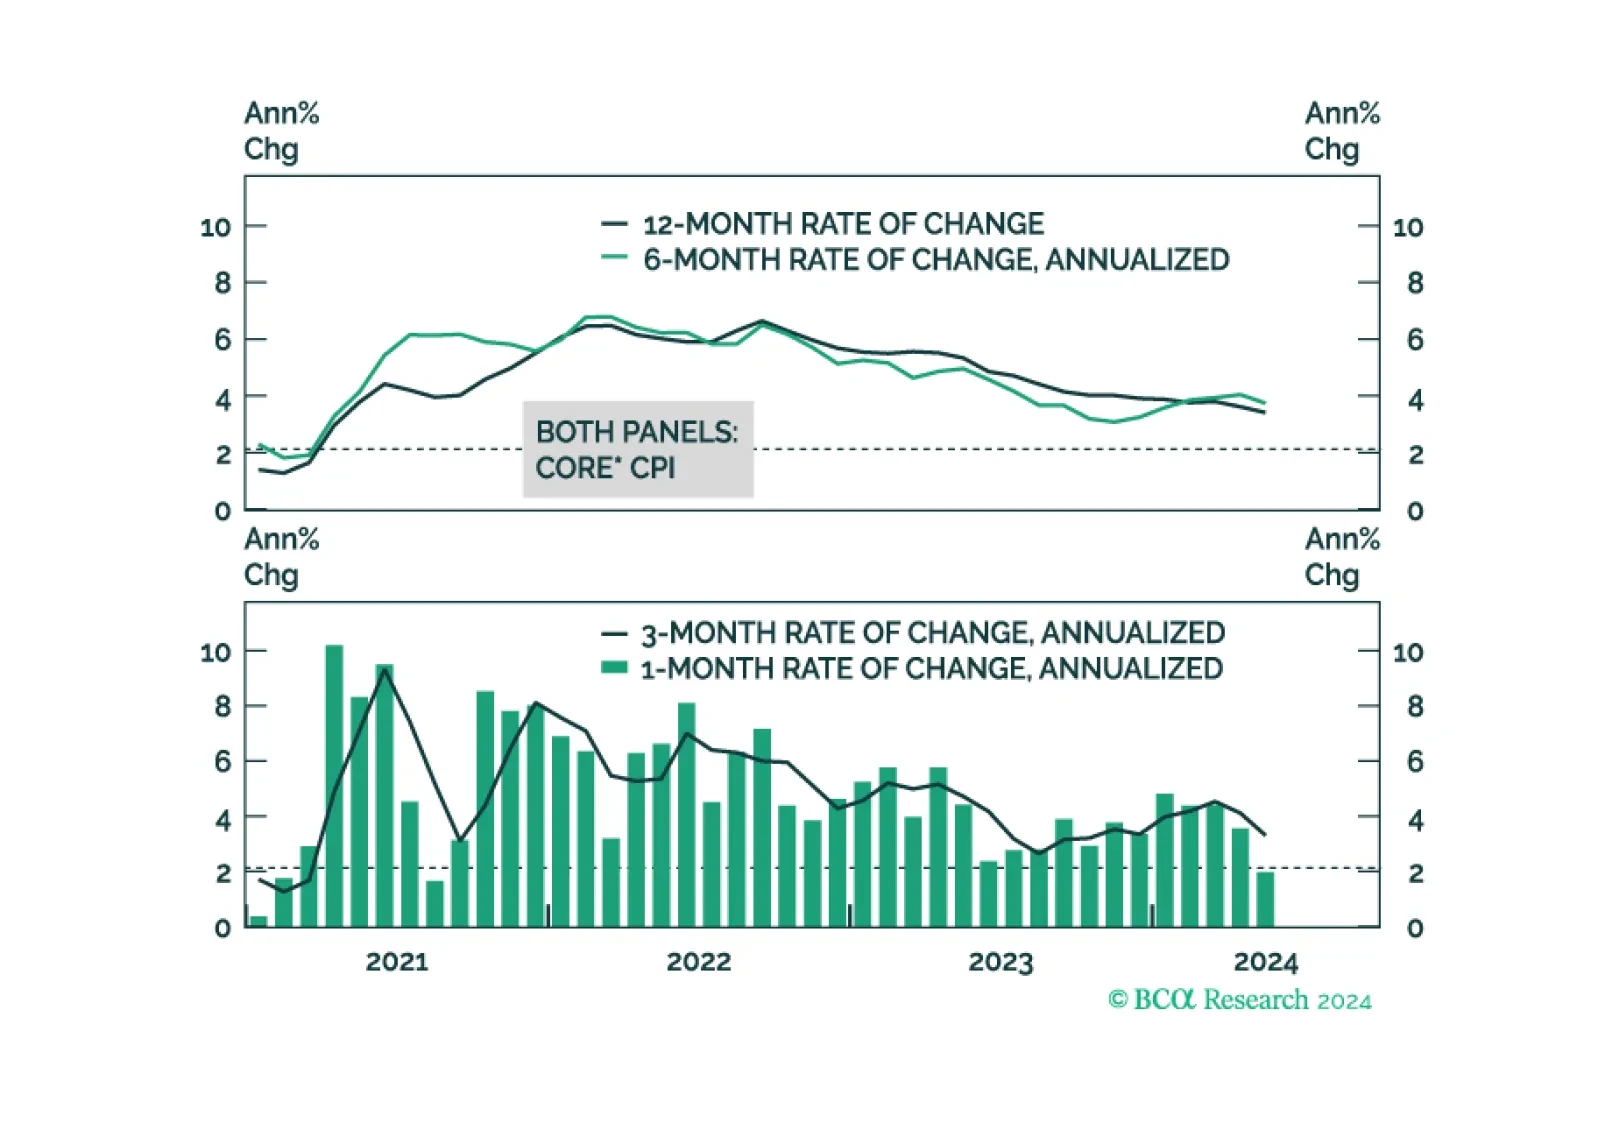
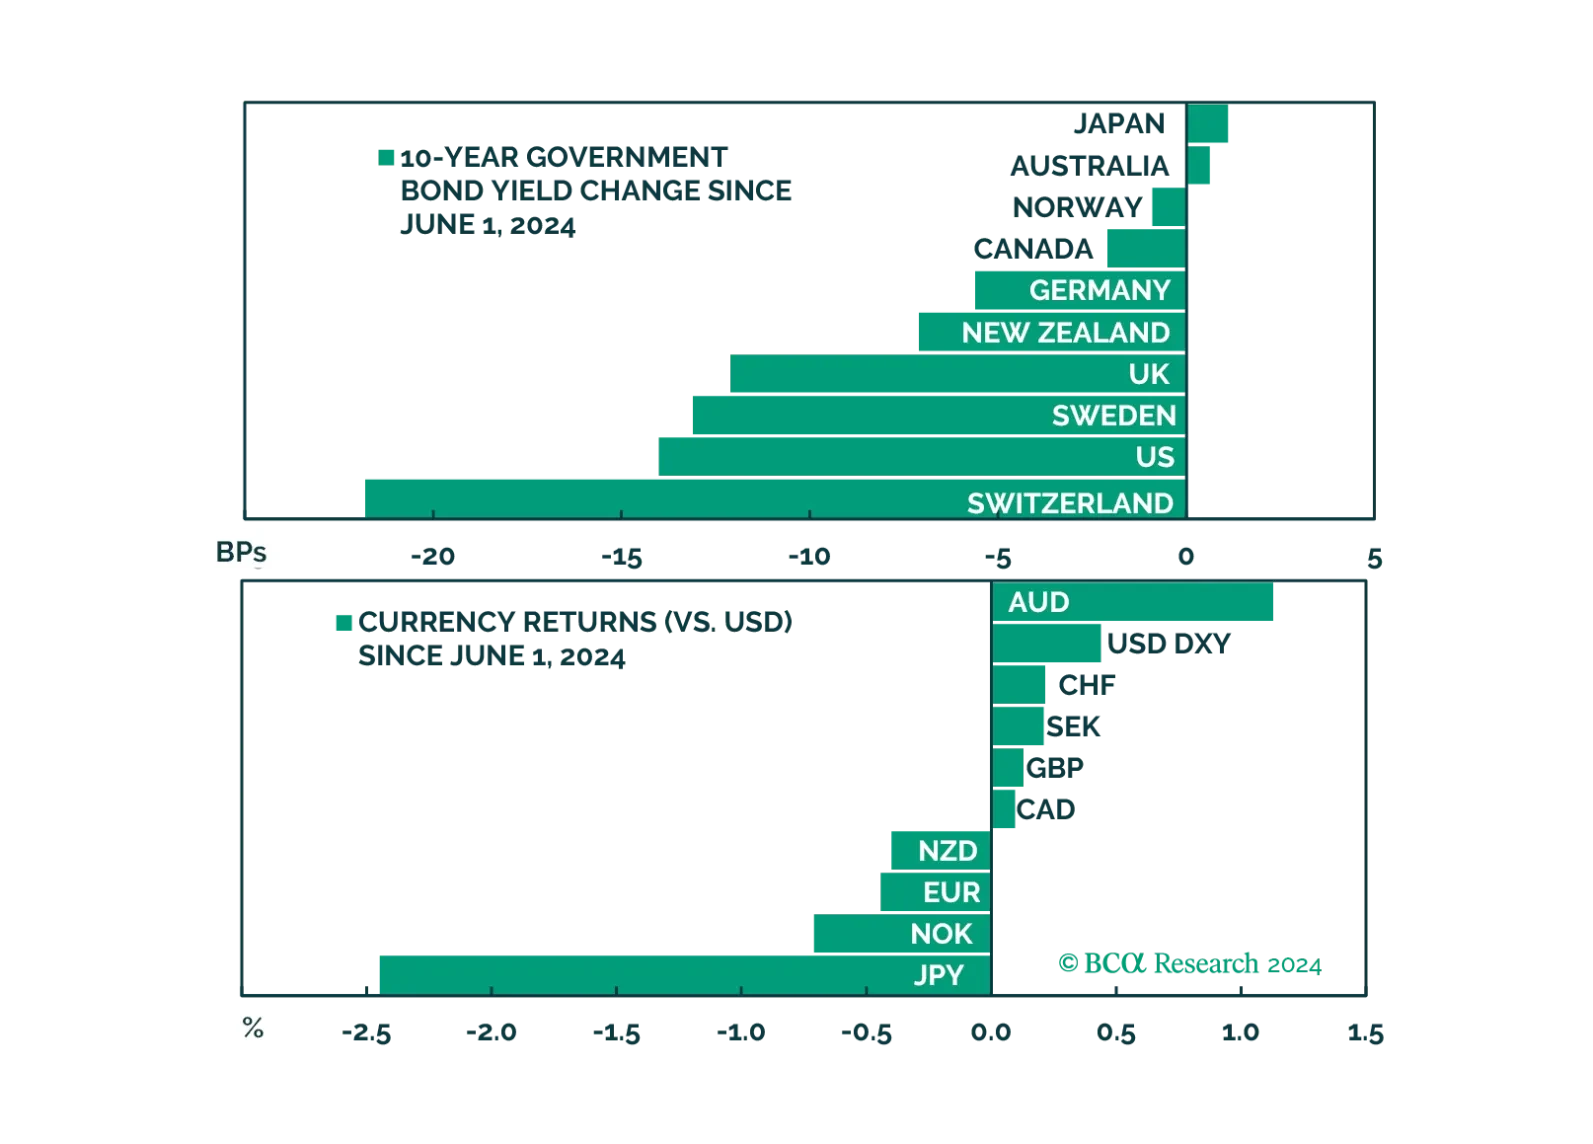
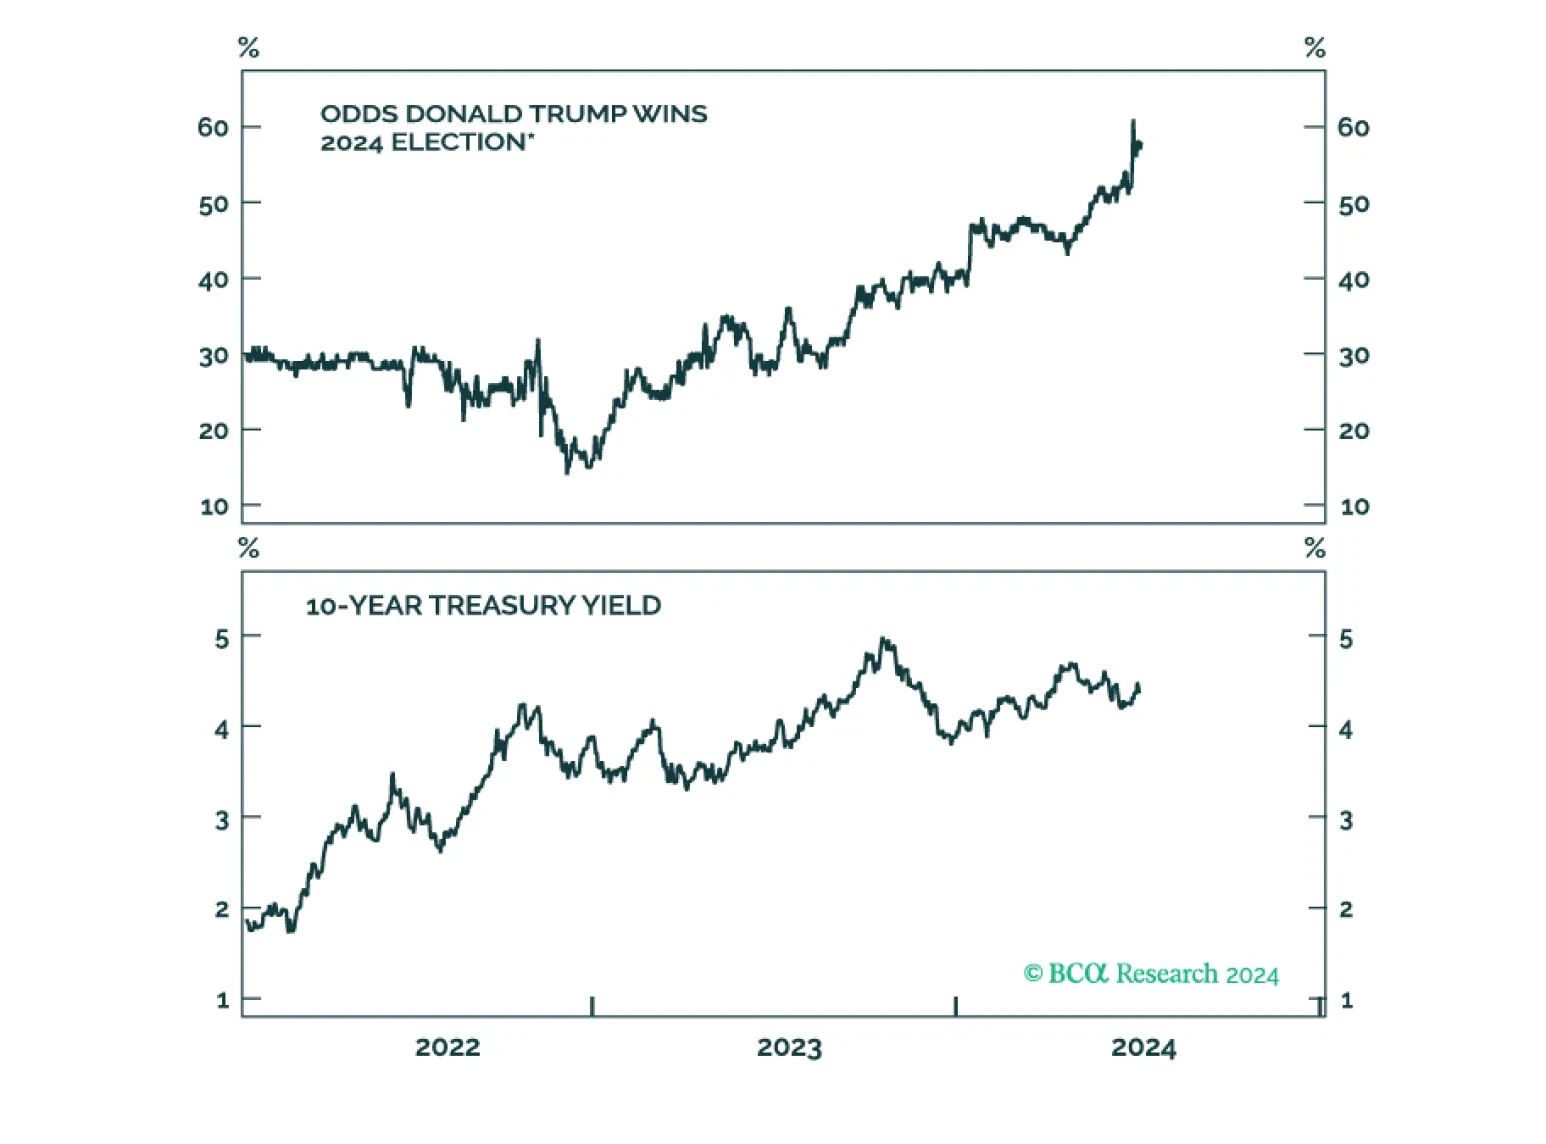
In this week's report, we review the impact of political developments, as well as incoming fundamental data, on our positioning.
Our labor market indicators have softened meaningfully during the past month but aren’t yet signaling an imminent recession. That said, the Fed can no longer ignore the labor market with the unemployment rate above 4% and rising.
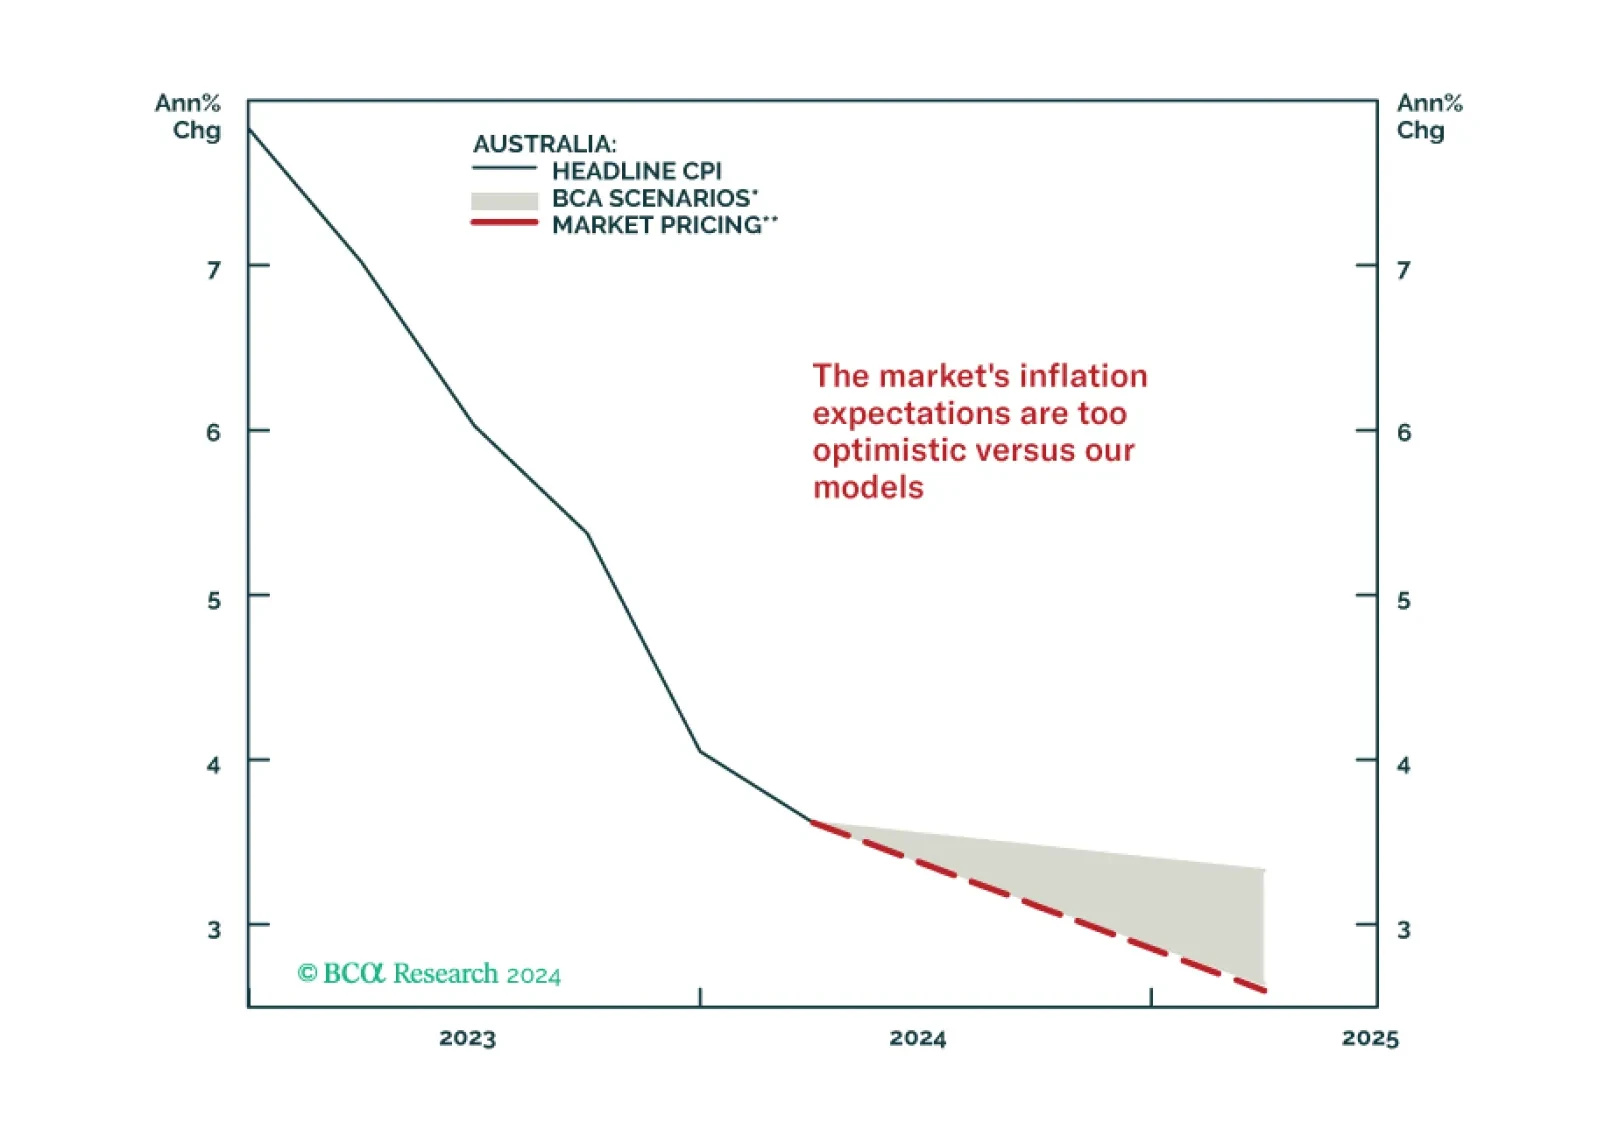
In light of this week’s RBA decision to keep policy on hold, we look at the best possible trades in fixed income markets. In our view, inflation-linked bonds, relative to nominals remain a good bet.
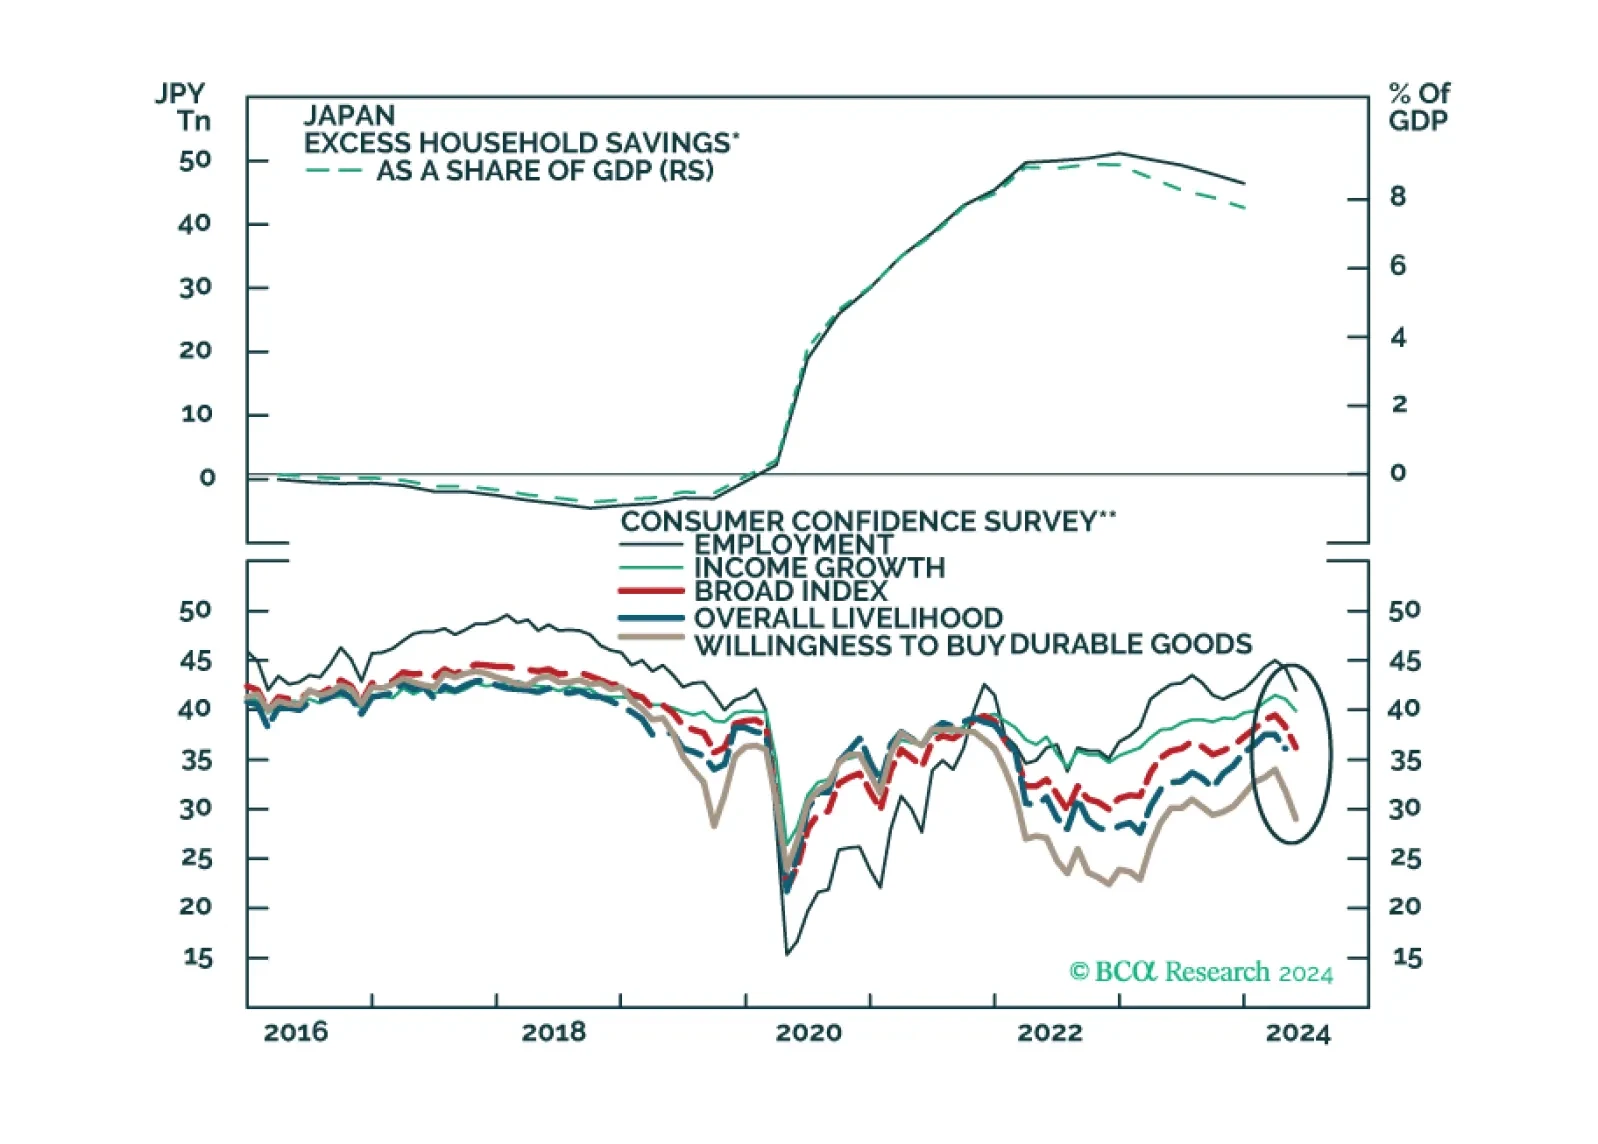
In this insight, we update our thinking on the recent BoJ move in terms of positioning for the yen and JGB yields.