FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
So far, there is no evidence of second-round effects from the oil price shock showing up in the US economy. Fed rate hikes are off the table unless those effects emerge.
FOMC participants are coalescing around the idea that the funds rate will stay on hold for some time, an outcome that is now well priced in the bond market and that will not materially change under a new Fed Chair.
The BoJ held rates overnight, but the direction of travel hasn’t changed. We discuss how stronger wages, rising inflation, and a weak yen point to further tightening ahead.
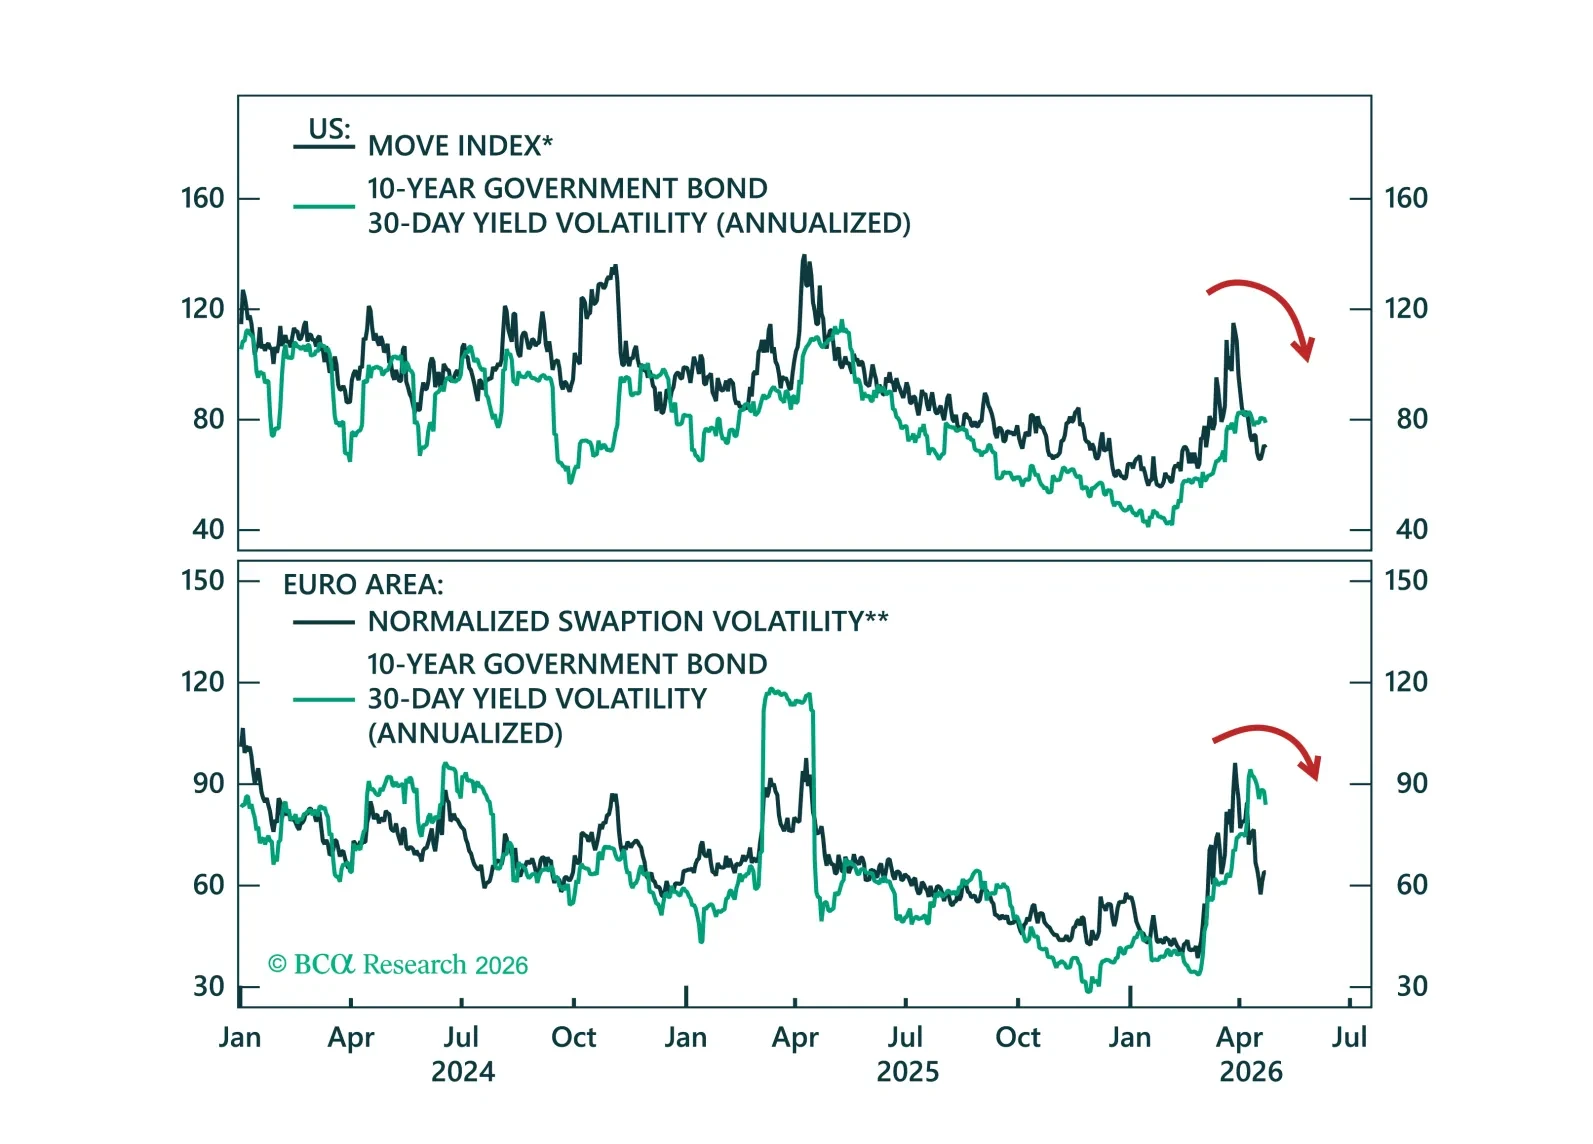
With central banks largely on hold, the return of a lower volatility environment is bringing carry trades back into focus. We outline the most attractive carry opportunities across global fixed income markets.
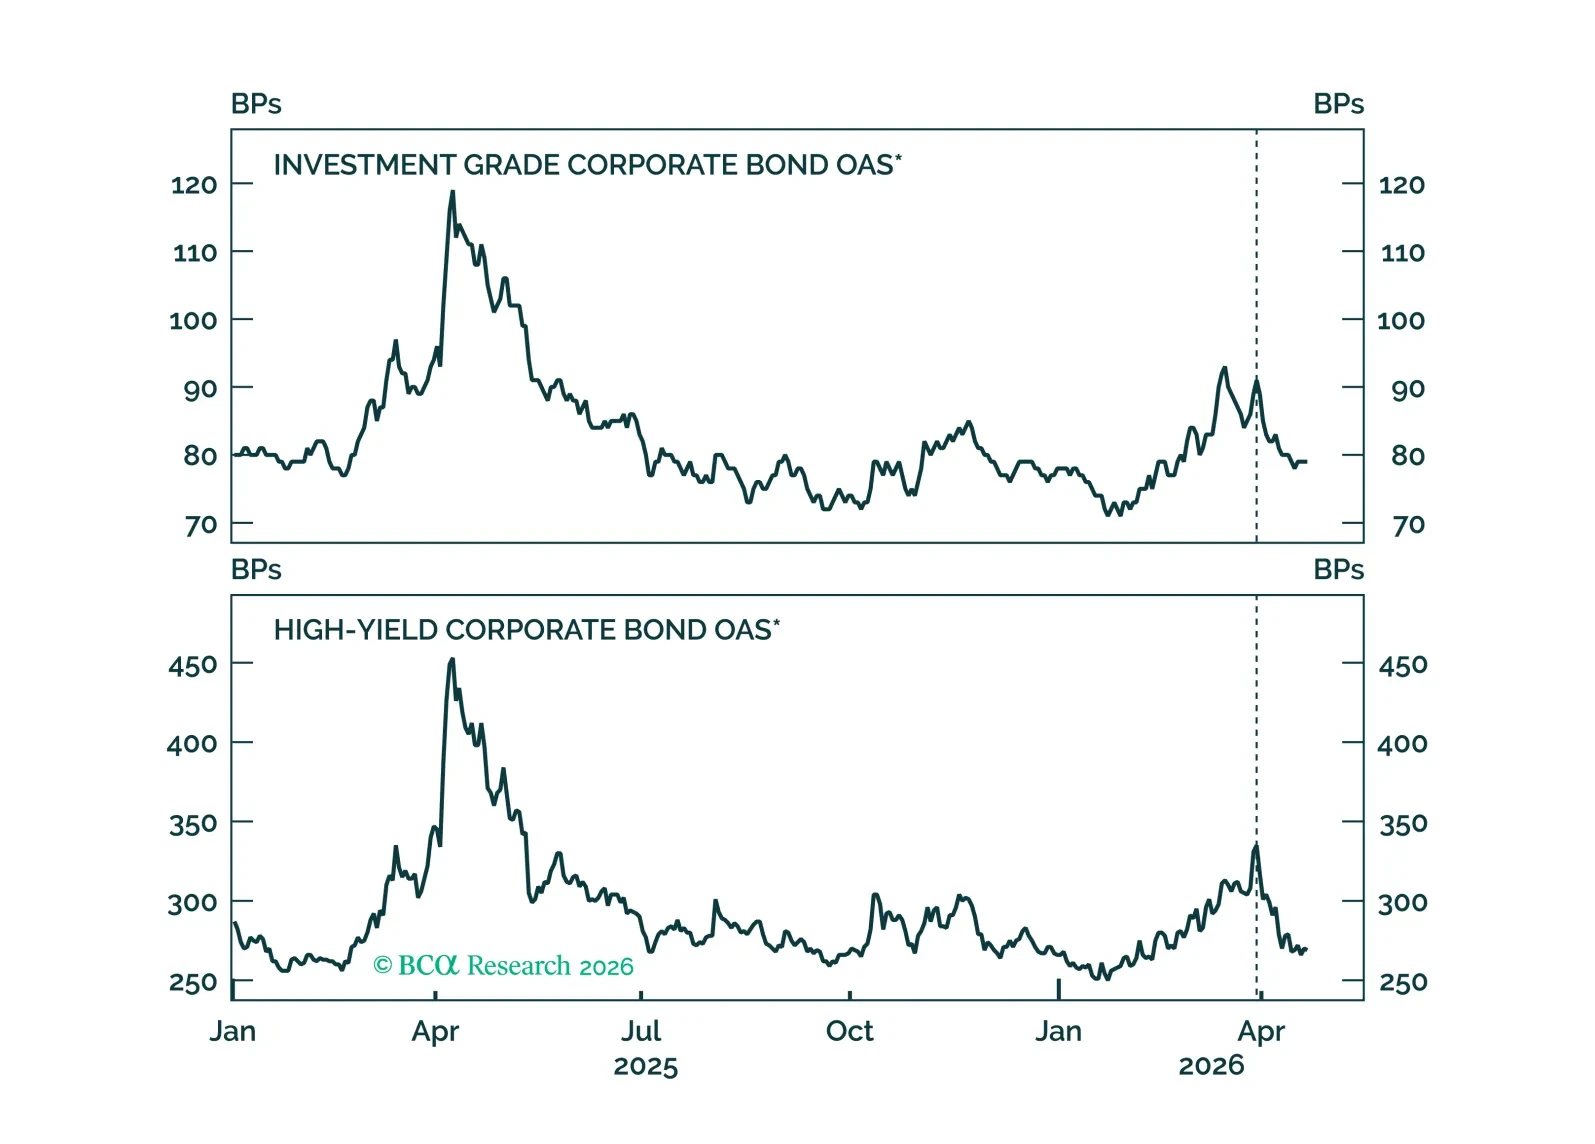
We recommend increasing exposure to spread product as the US economy transitions back into a low rate vol regime.
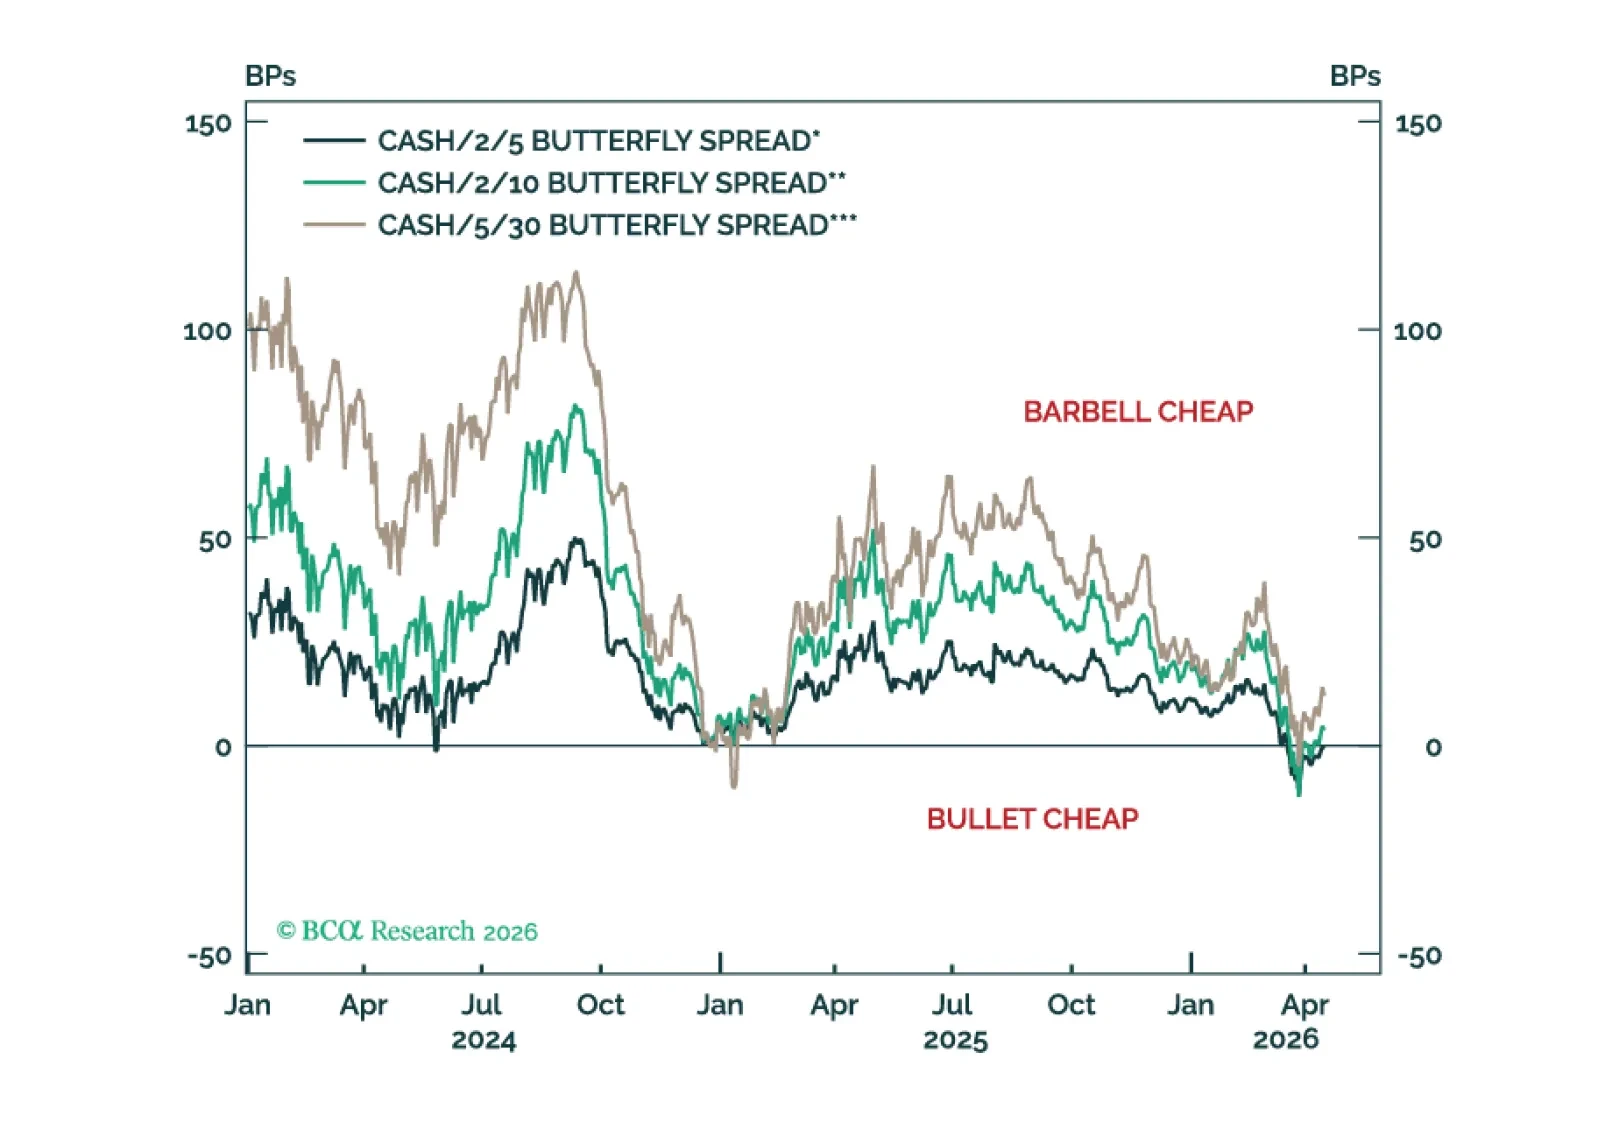
The rates market is moving back into a low vol regime, but with yields at a higher level. This argues for maximizing carry across the Treasury curve.
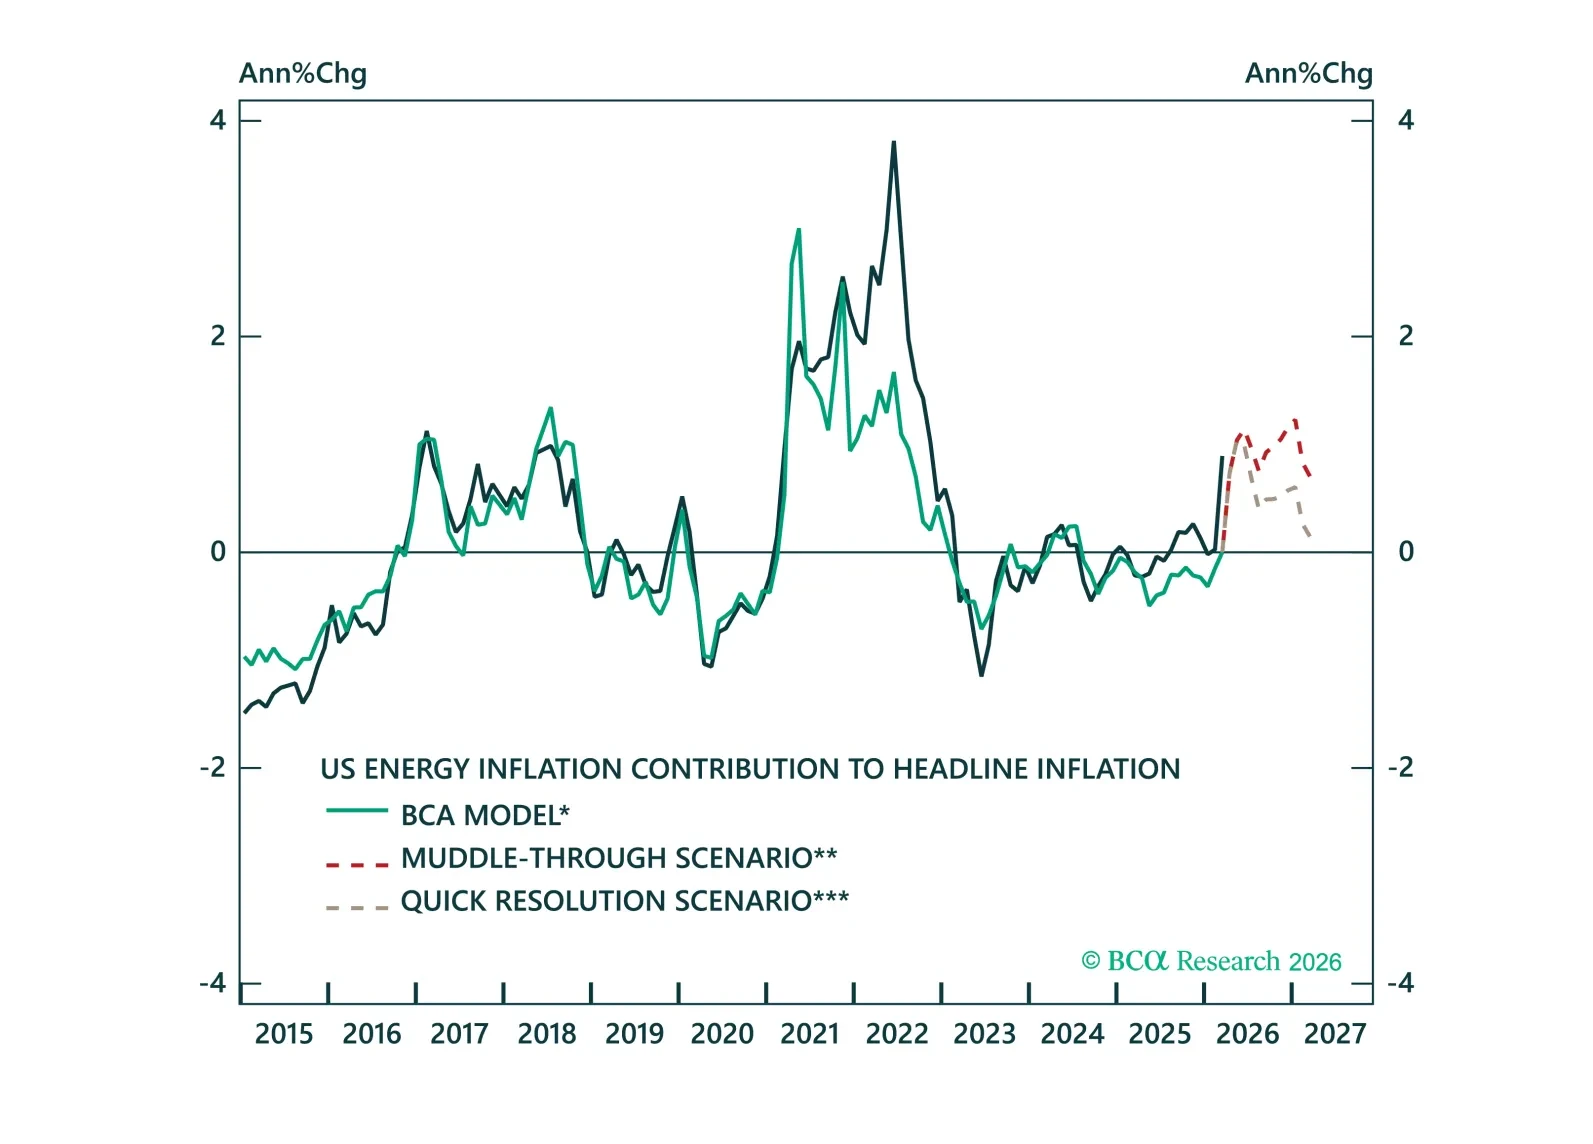
Volatility is high, but the path for yields is clearer than it looks. Across three oil scenarios, we show how policy responses shape fixed income markets and why the balance of risks still points to lower yields.
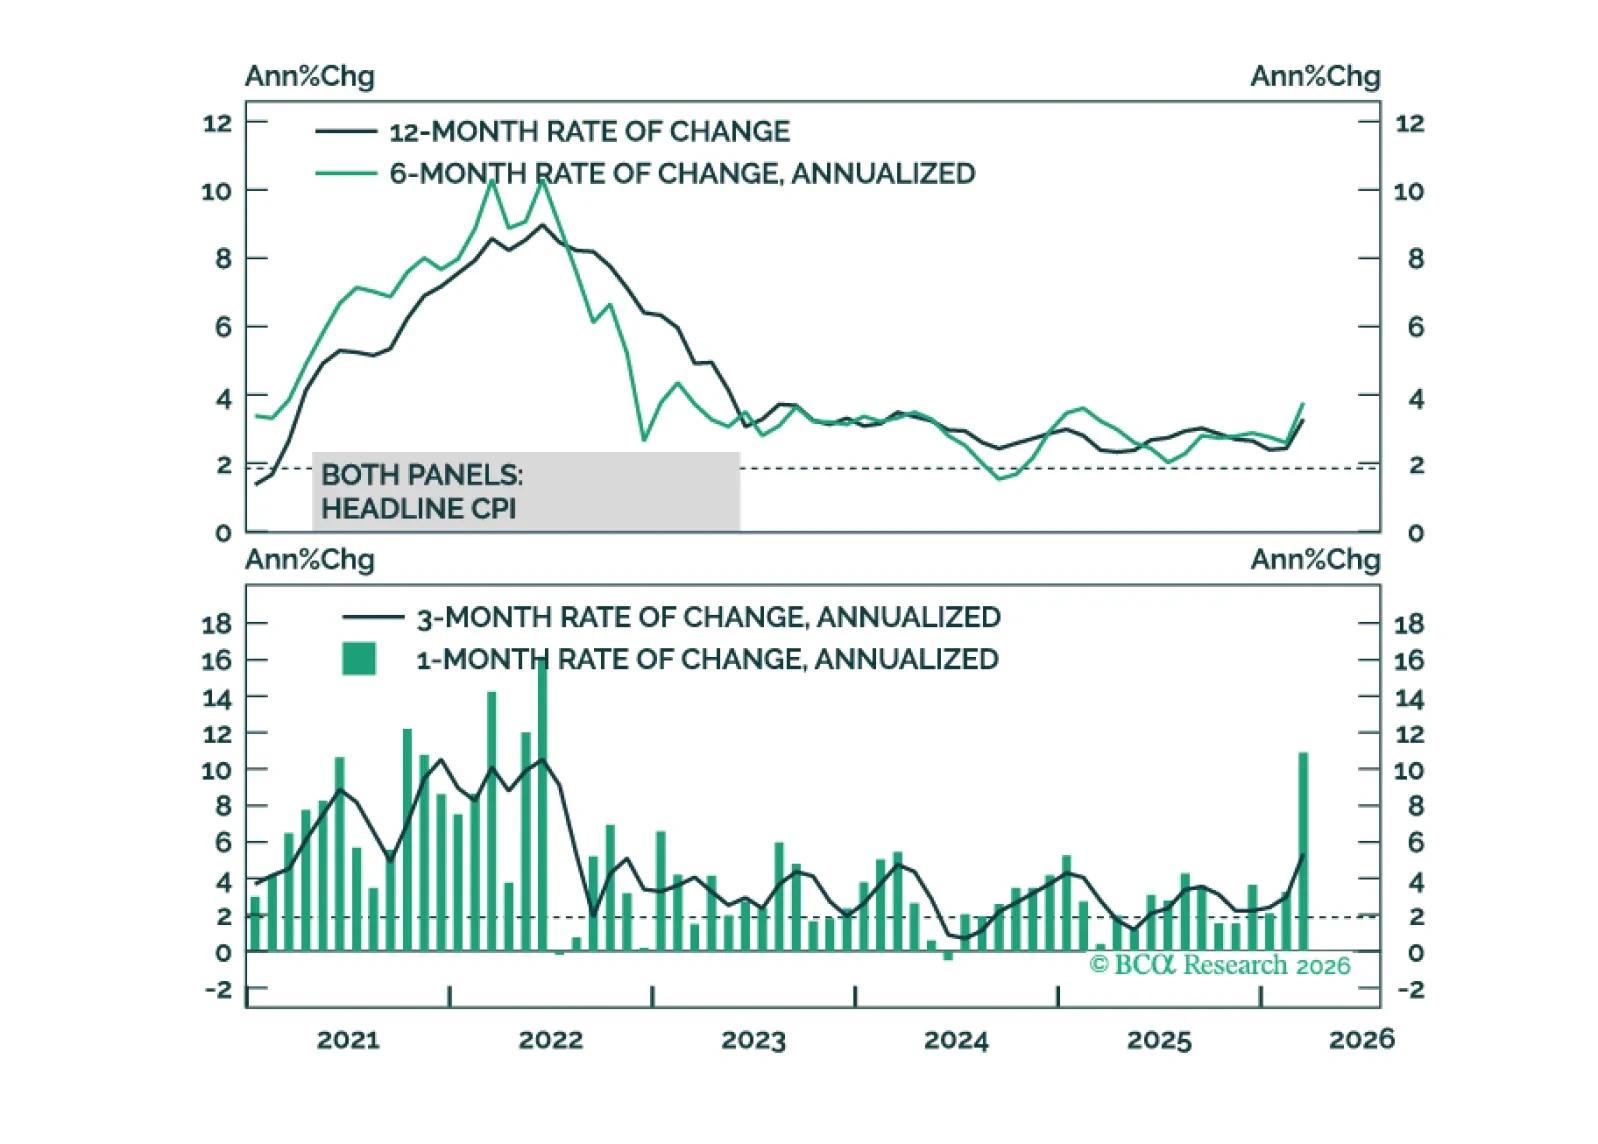
Inflation’s underlying trend was headed lower prior to the Iran war. This makes the recent back-up in bond yields look like an attractive buying opportunity.
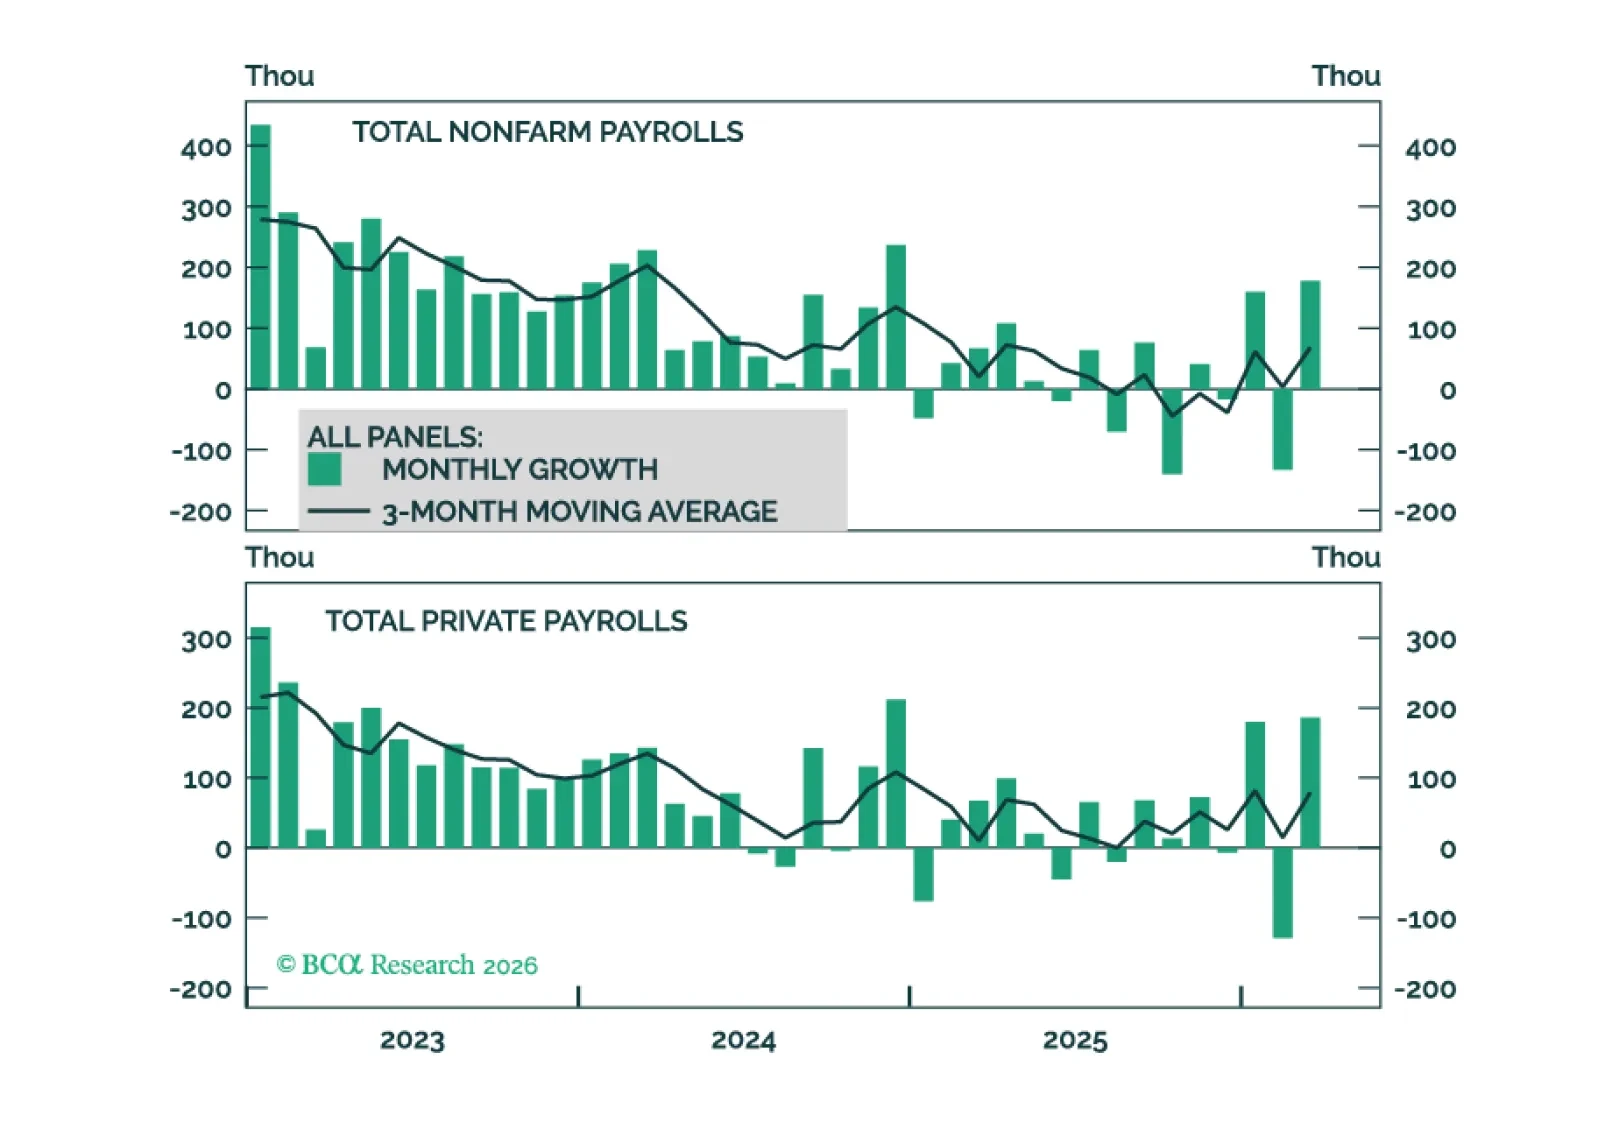
US employment data show some tentative signs of job growth acceleration and stable utilization. We see breakeven monthly job growth as closer to +30k per month than zero.