FICC
| Commodities
Oil, metals, and the wider commodity complex, analyzed from the global macro picture down to physical supply and demand.
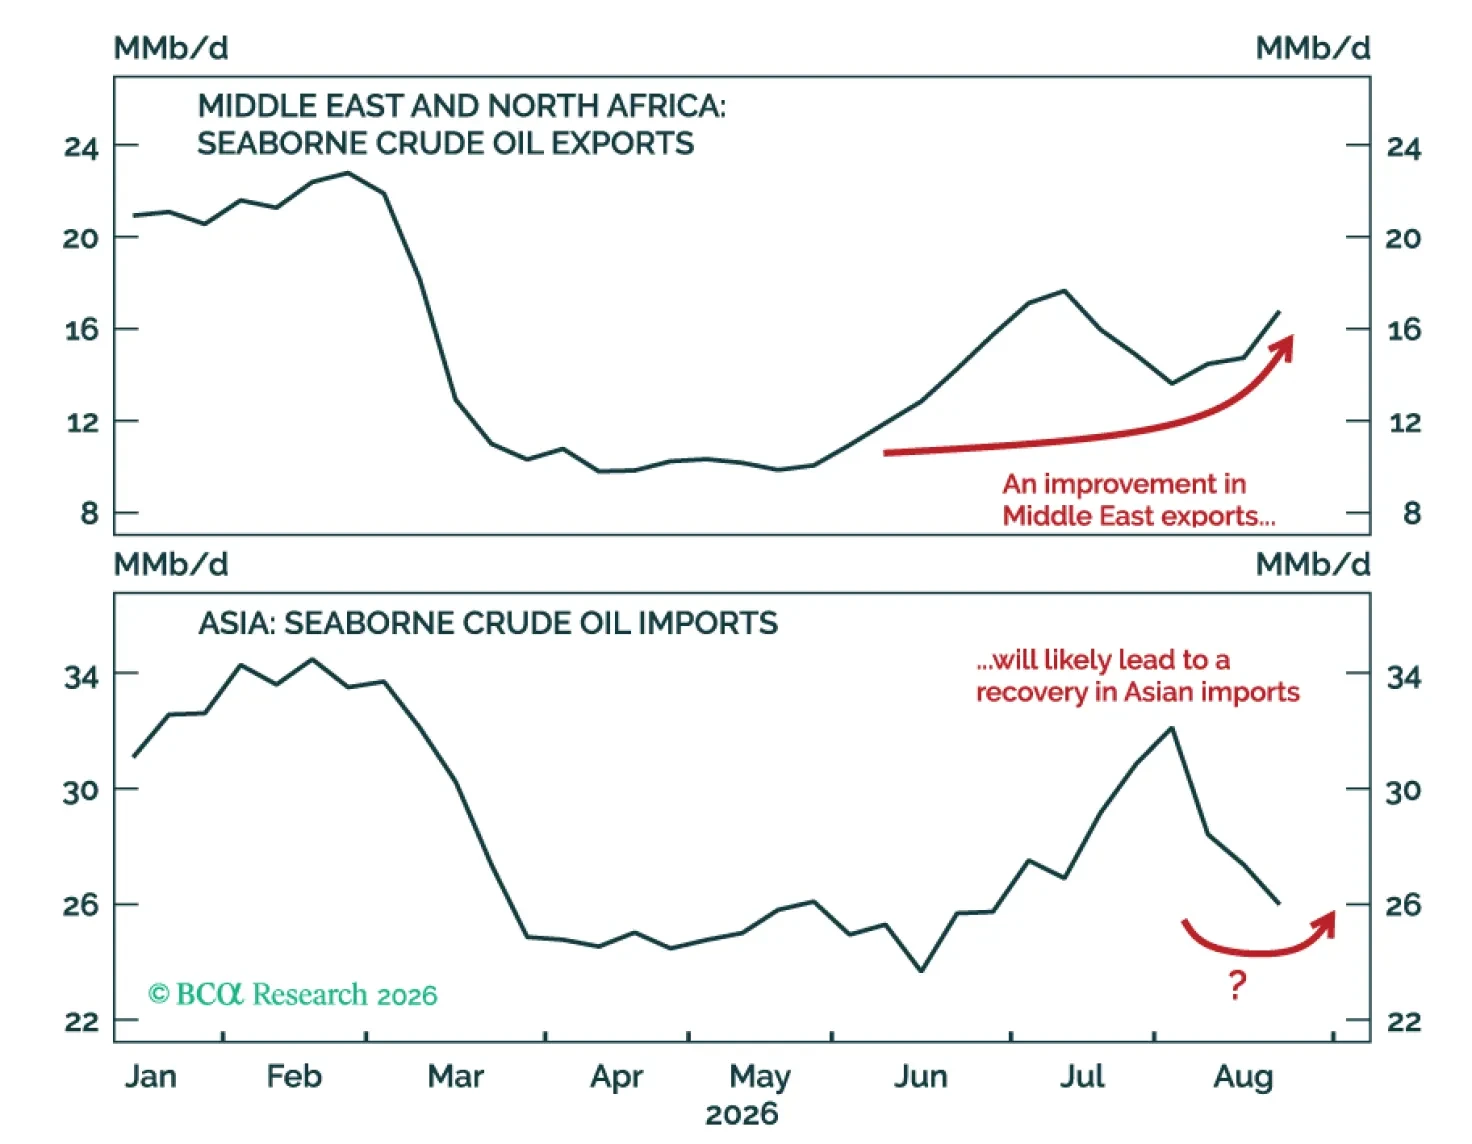
The wide crack spread reflects a bifurcated oil market. The severity of the crude oil disruption has recently softened, while the US-Iran and Ukraine-Russia conflicts have created a perfect storm for refined product markets. Going forward, even though conditions are not yet in place for the crack spread to return to its pre-conflict level, it is likely to narrow over the coming months.
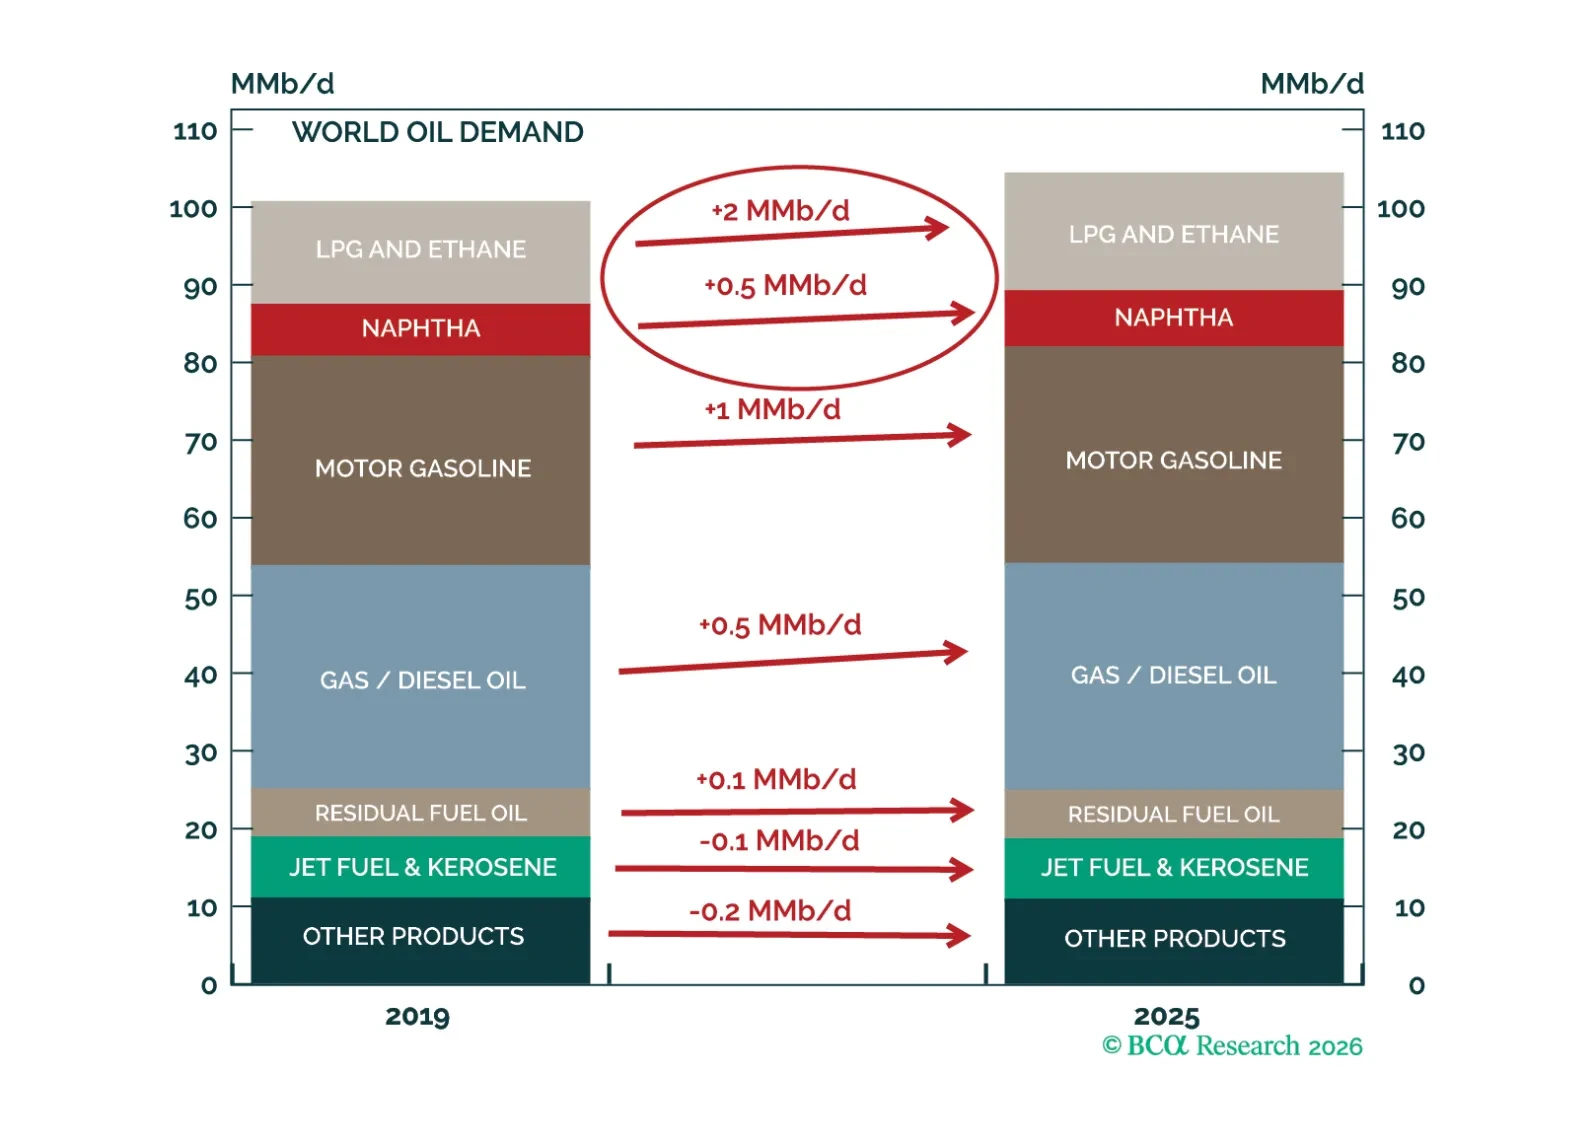
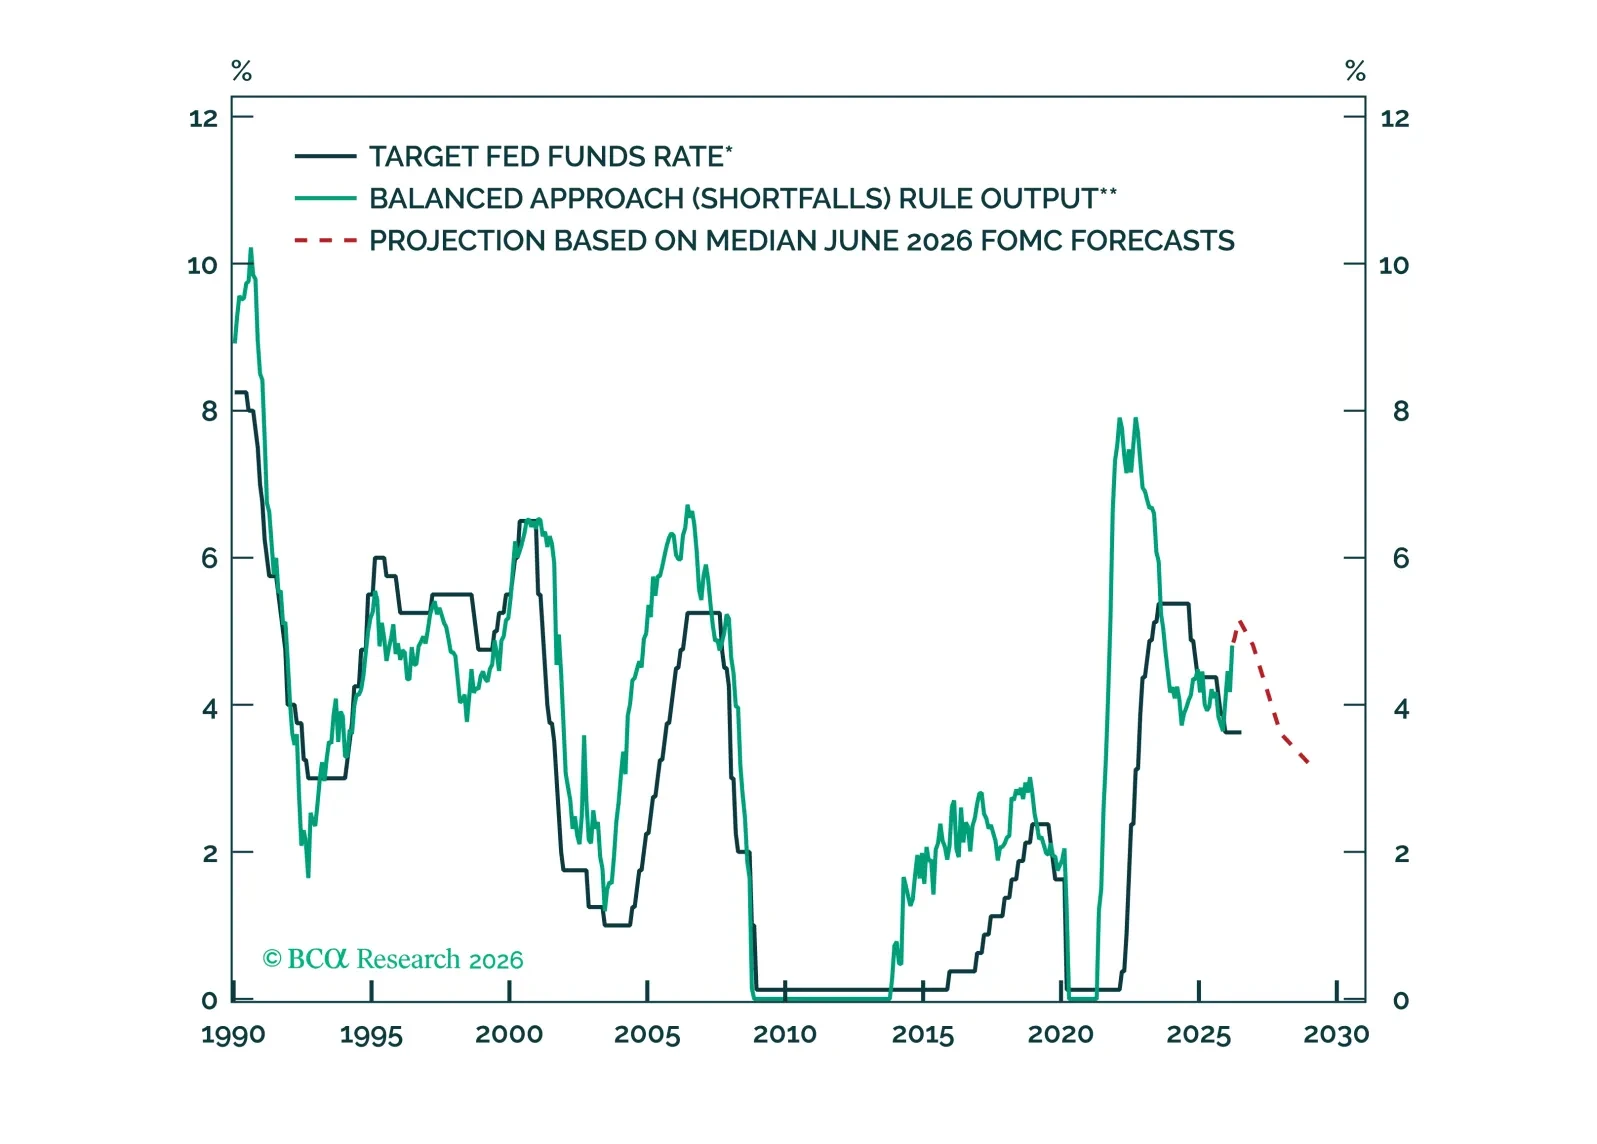
Goldilocks, with fault lines underneath. Our first joint FICC outlook lays out where growth, inflation, and policy are headed this quarter and where the calm could crack.
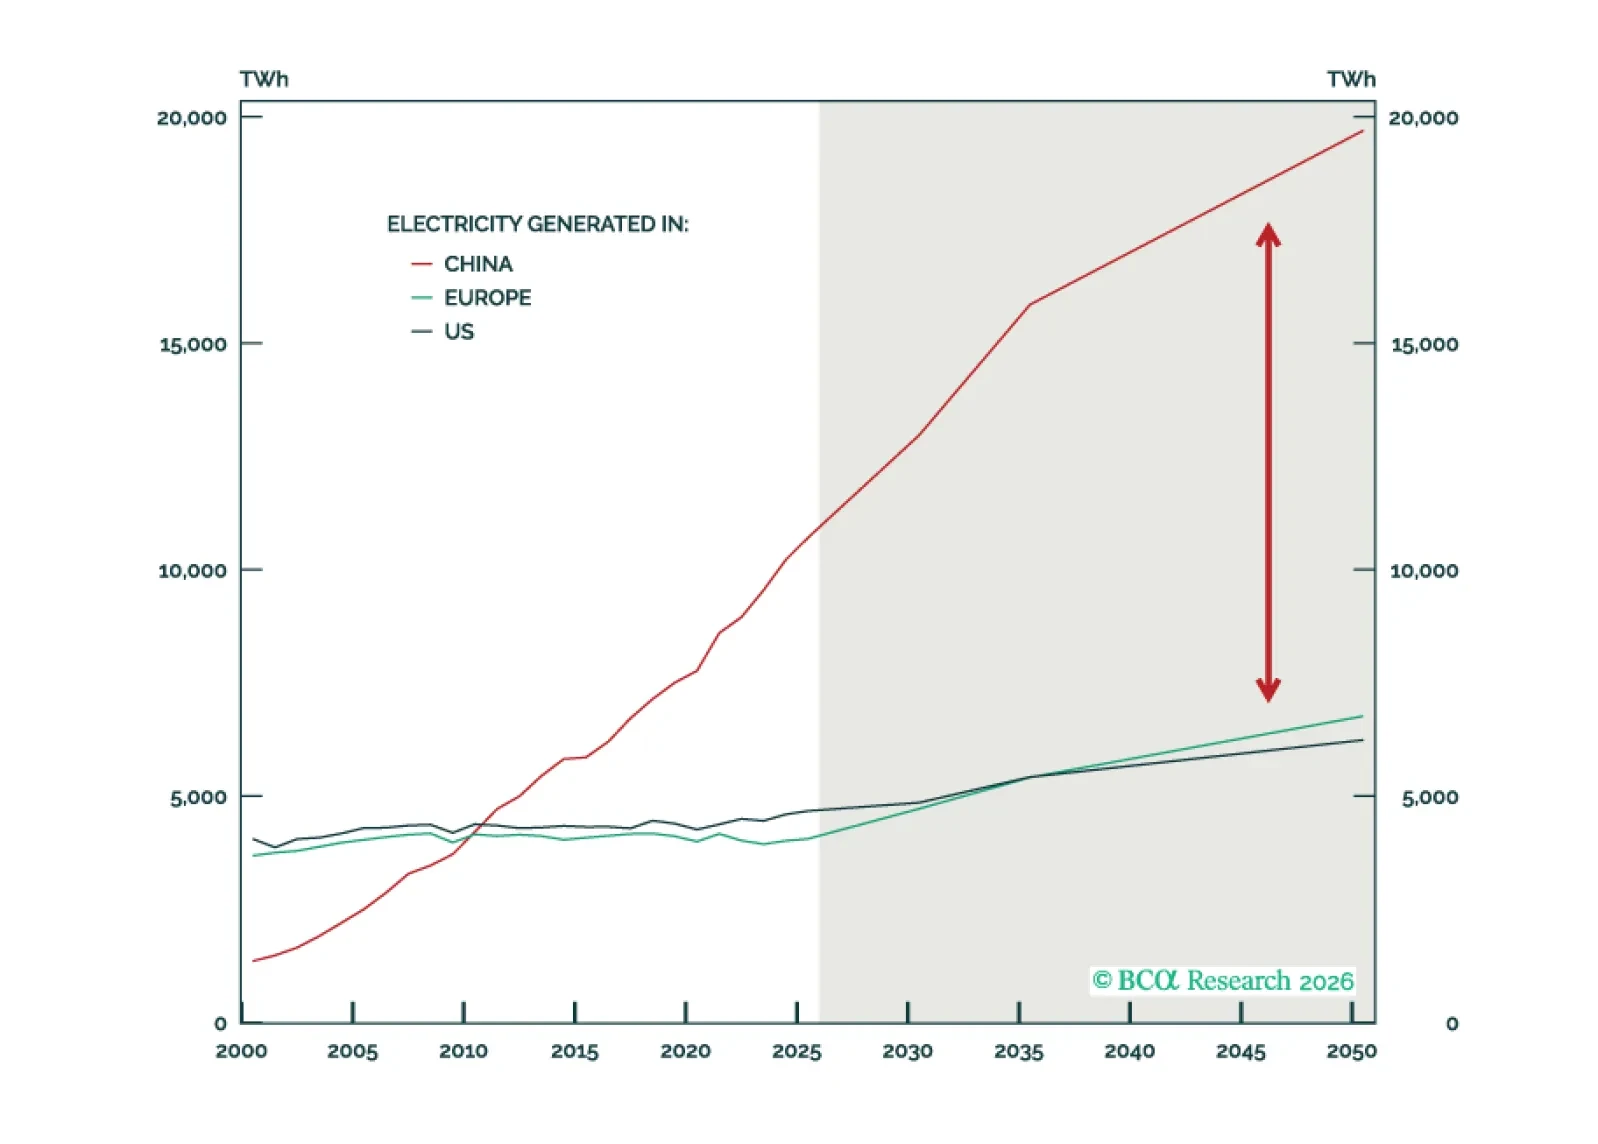
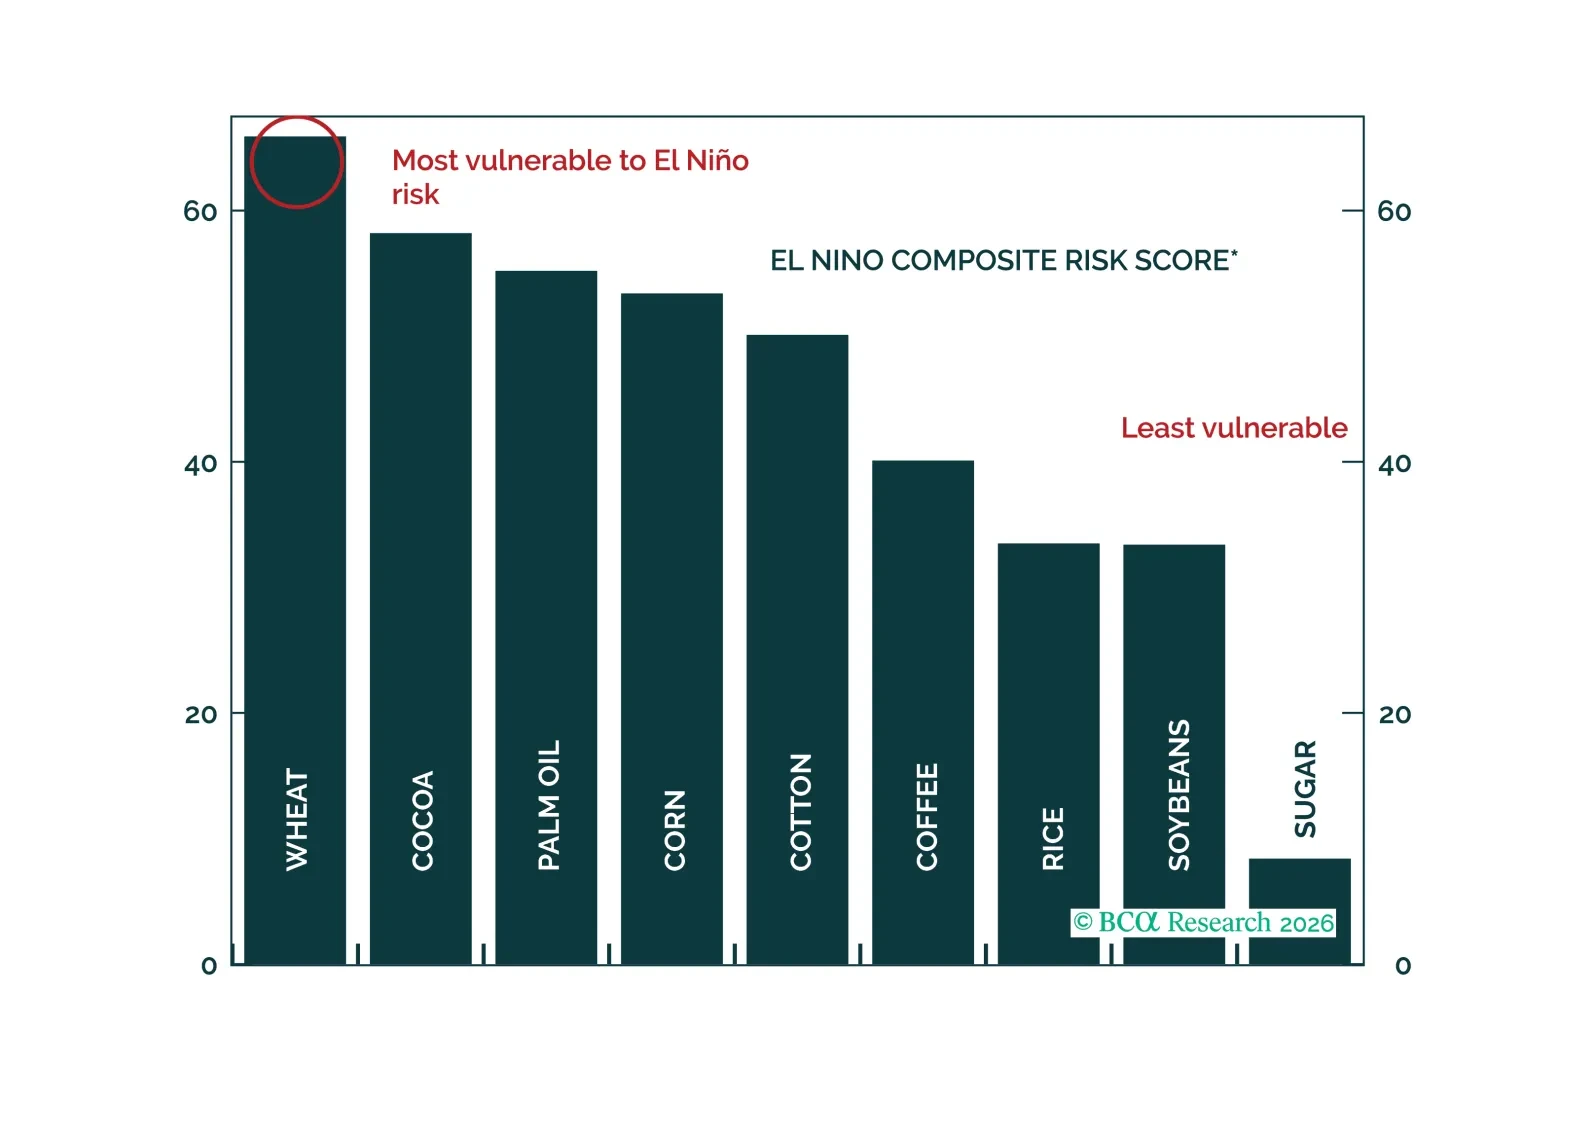
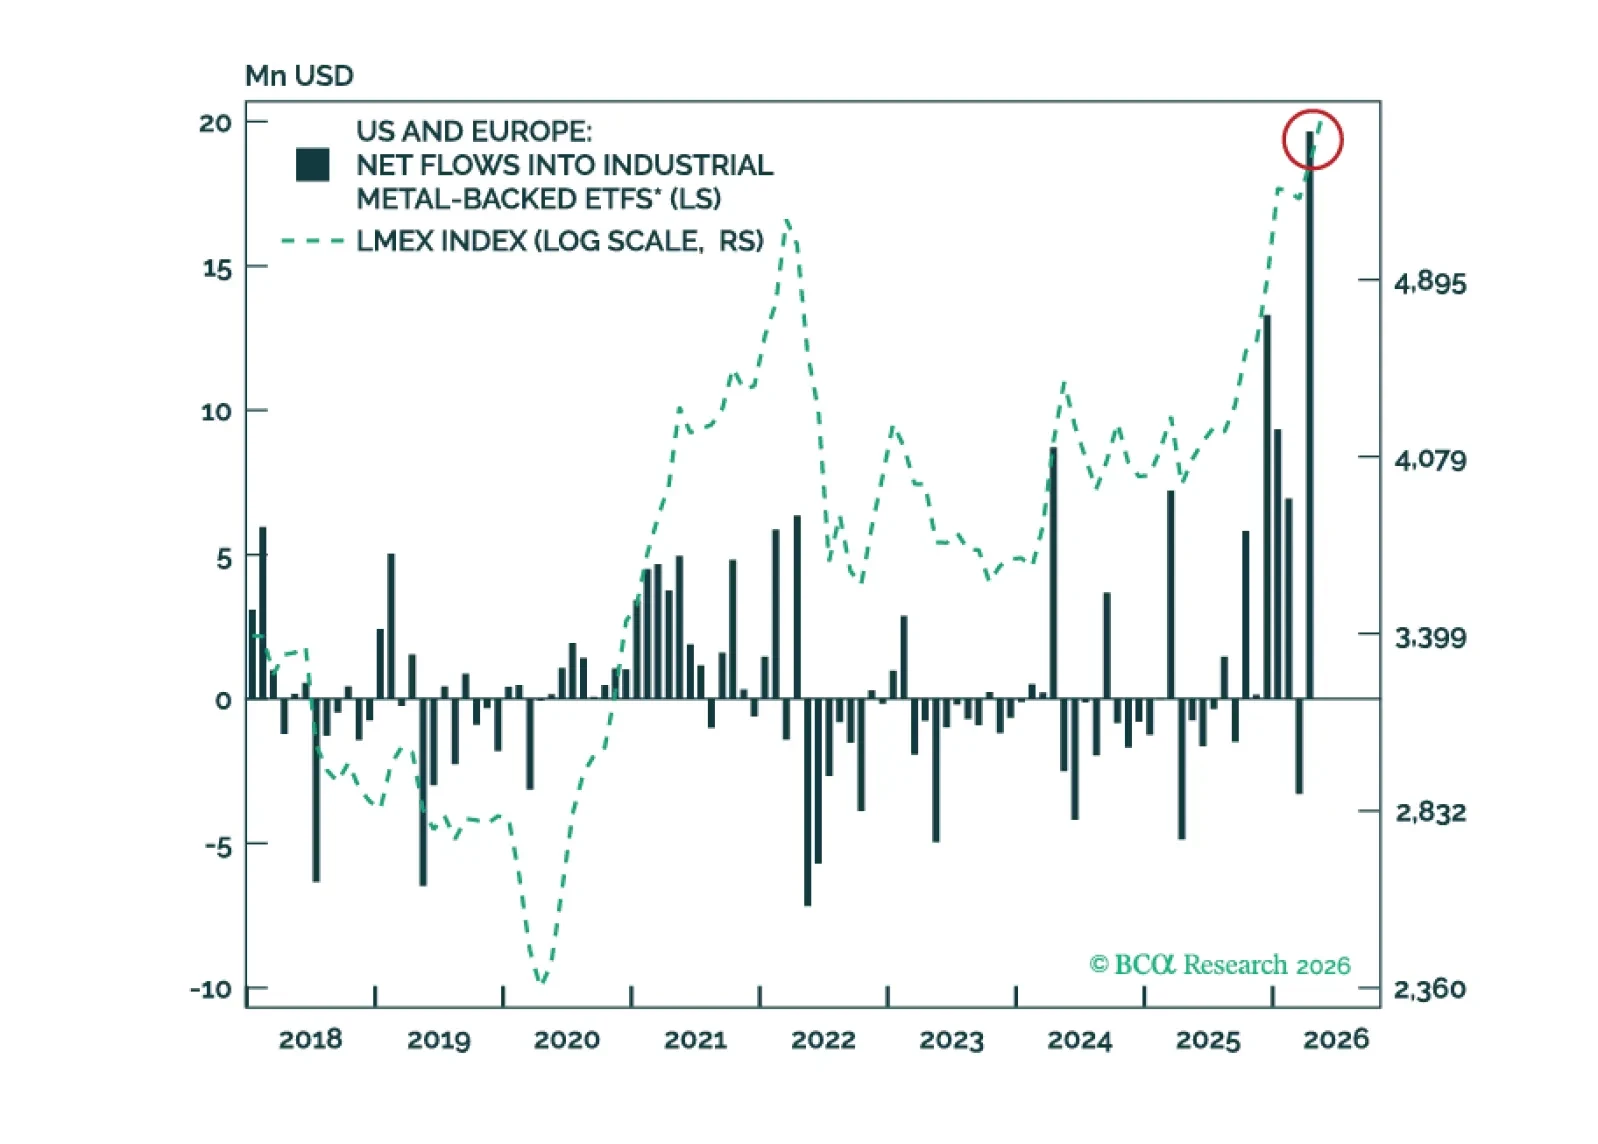
Copper prices are surging again after a brief pullback in the first quarter. What is driving the renewed strength, and can it persist?
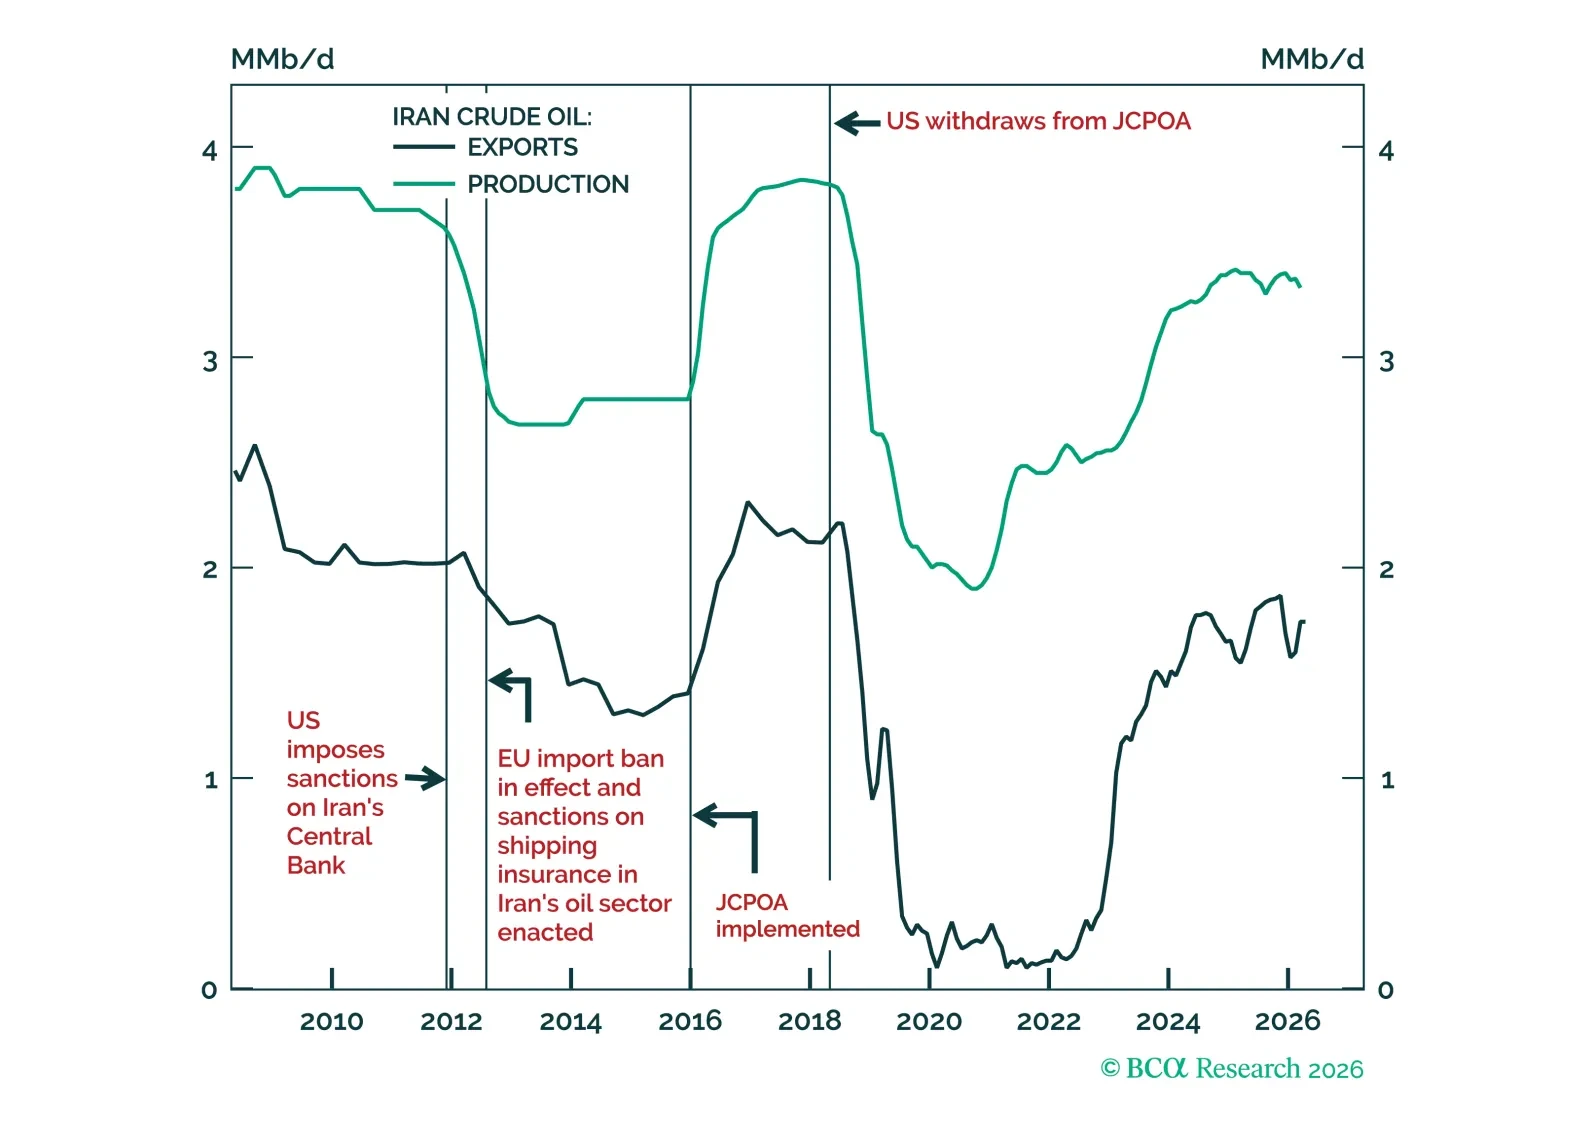
Hopes for an imminent Middle East de-escalation have capped oil prices in recent weeks, but that restraint may soon fade.
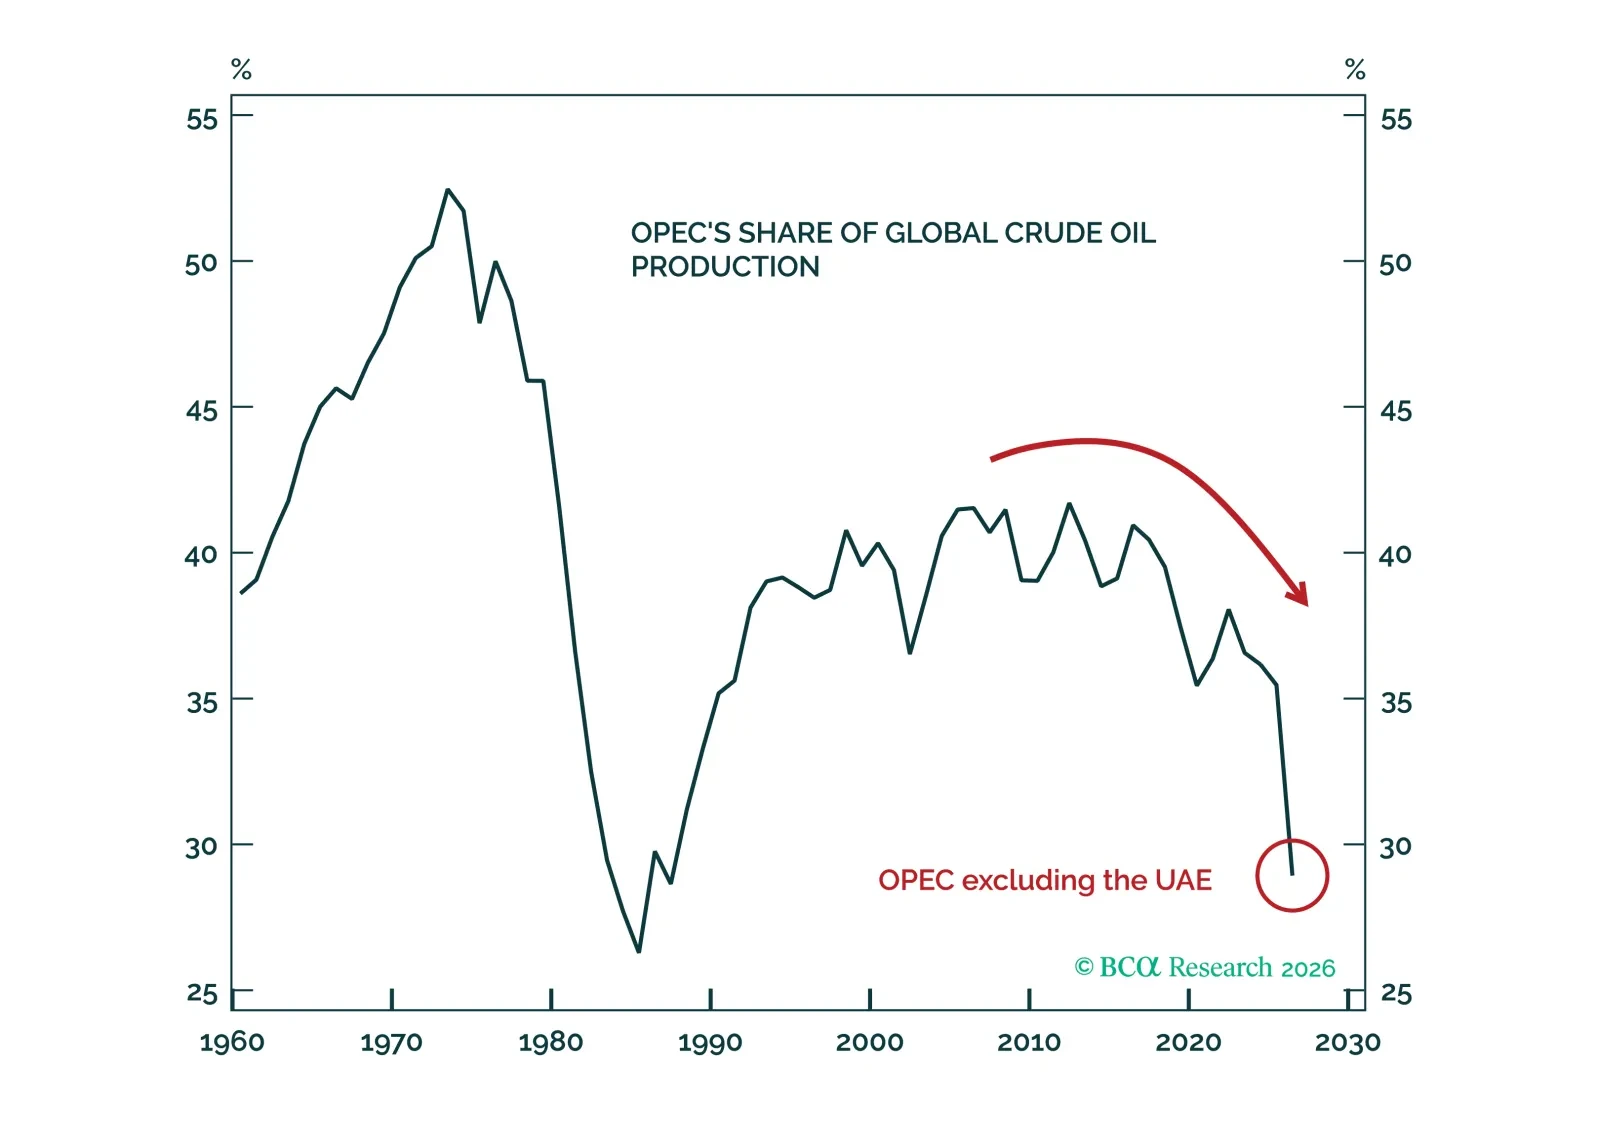
The UAE’s exit from OPEC is unlikely to impact oil markets in 2026. Over the longer term, however, the emergence of an “anti-OPEC club” of producers favoring unconstrained oil output growth would create a headwind to crude prices and weaken the price floor that OPEC seeks to defend.
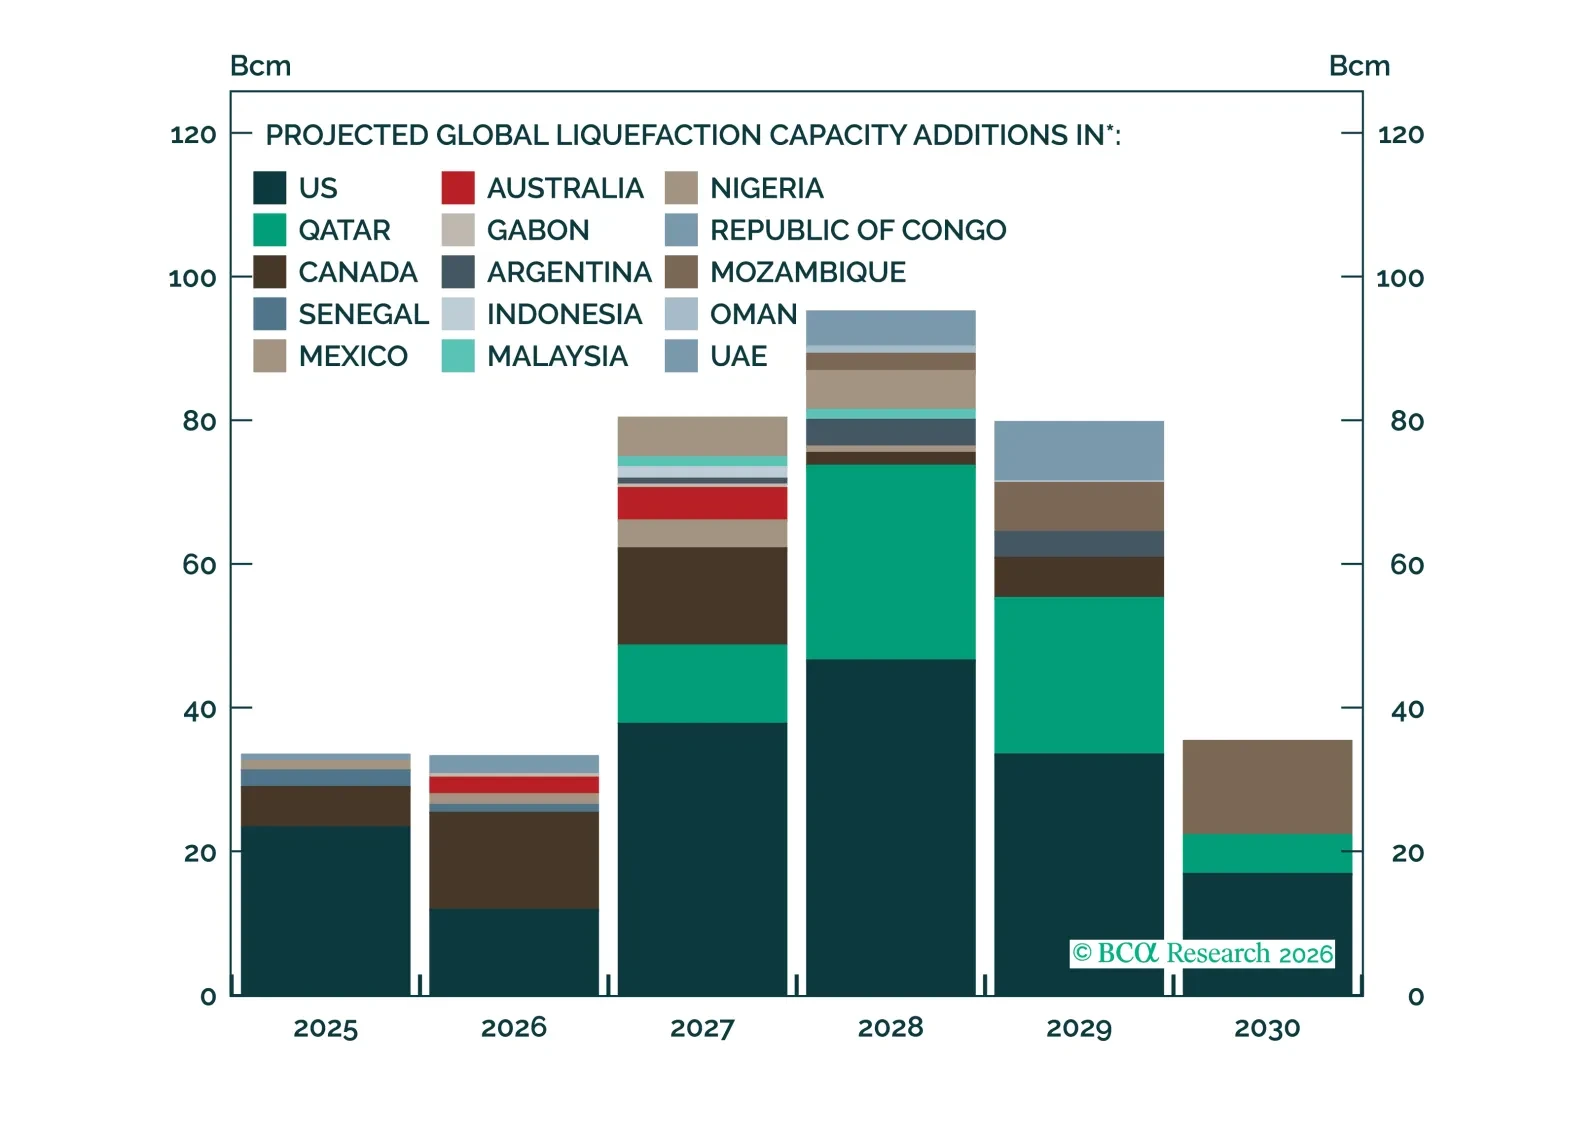
The Iran war has damaged LNG production capacity and halted tanker flows through the Strait of Hormuz. We assess the conflict's impact on LNG markets over cyclical and structural horizons.