 FICC
| Currencies
Near-term trades and longer-term views on every major developed and emerging market currency.
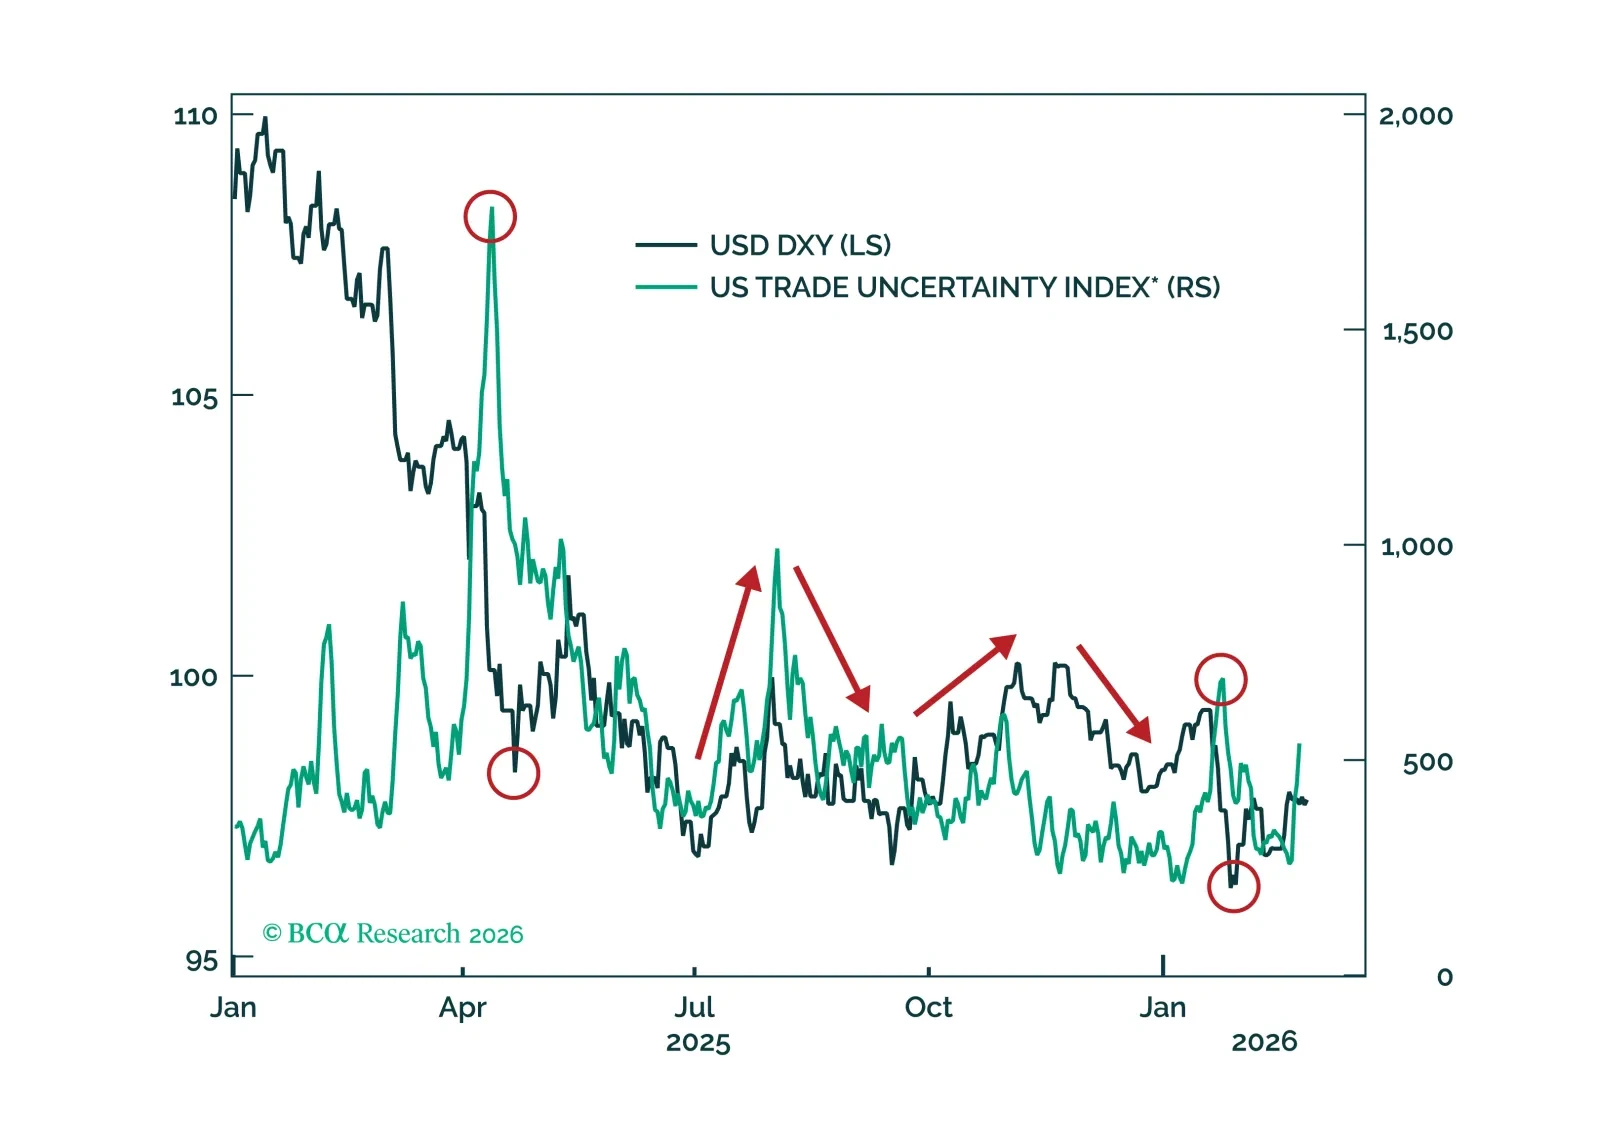
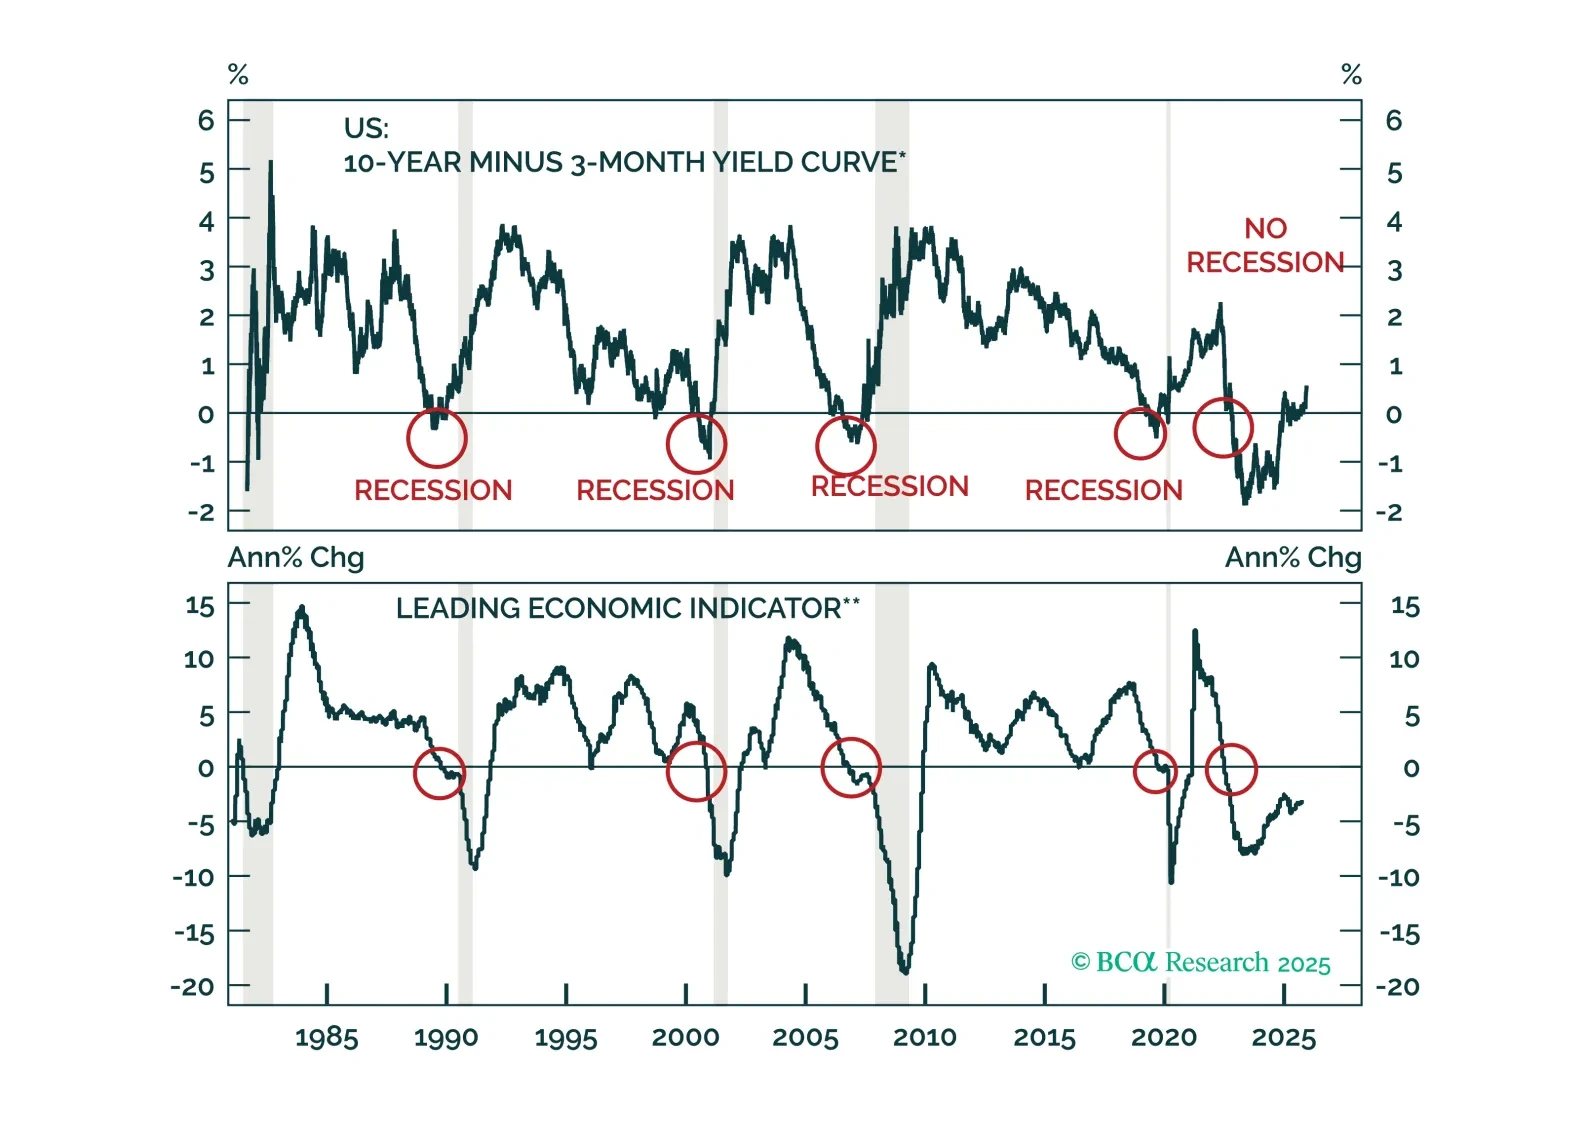
Policy risks are set to fade just as markets underestimate hawkish Fed repricing and crowd into short-USD positions, setting the stage for a tactical dollar rebound into the election cycle. Go long USD/CHF to capture the rate differential and receding policy uncertainty.
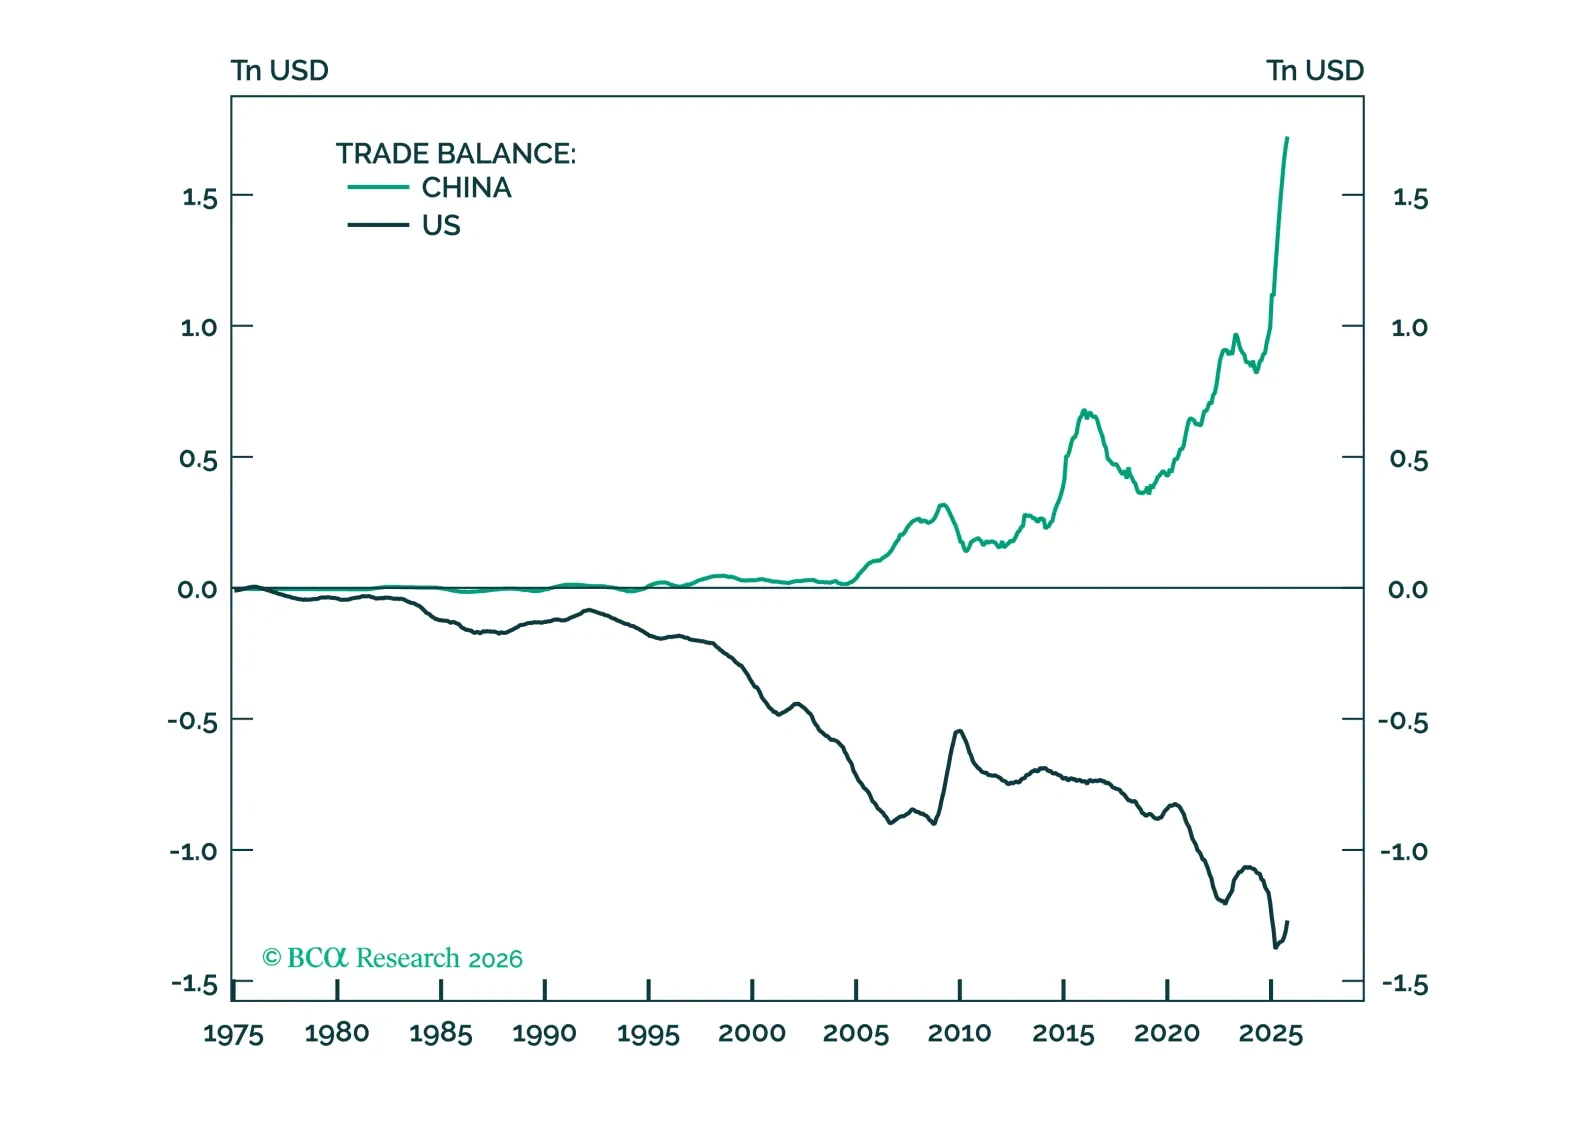
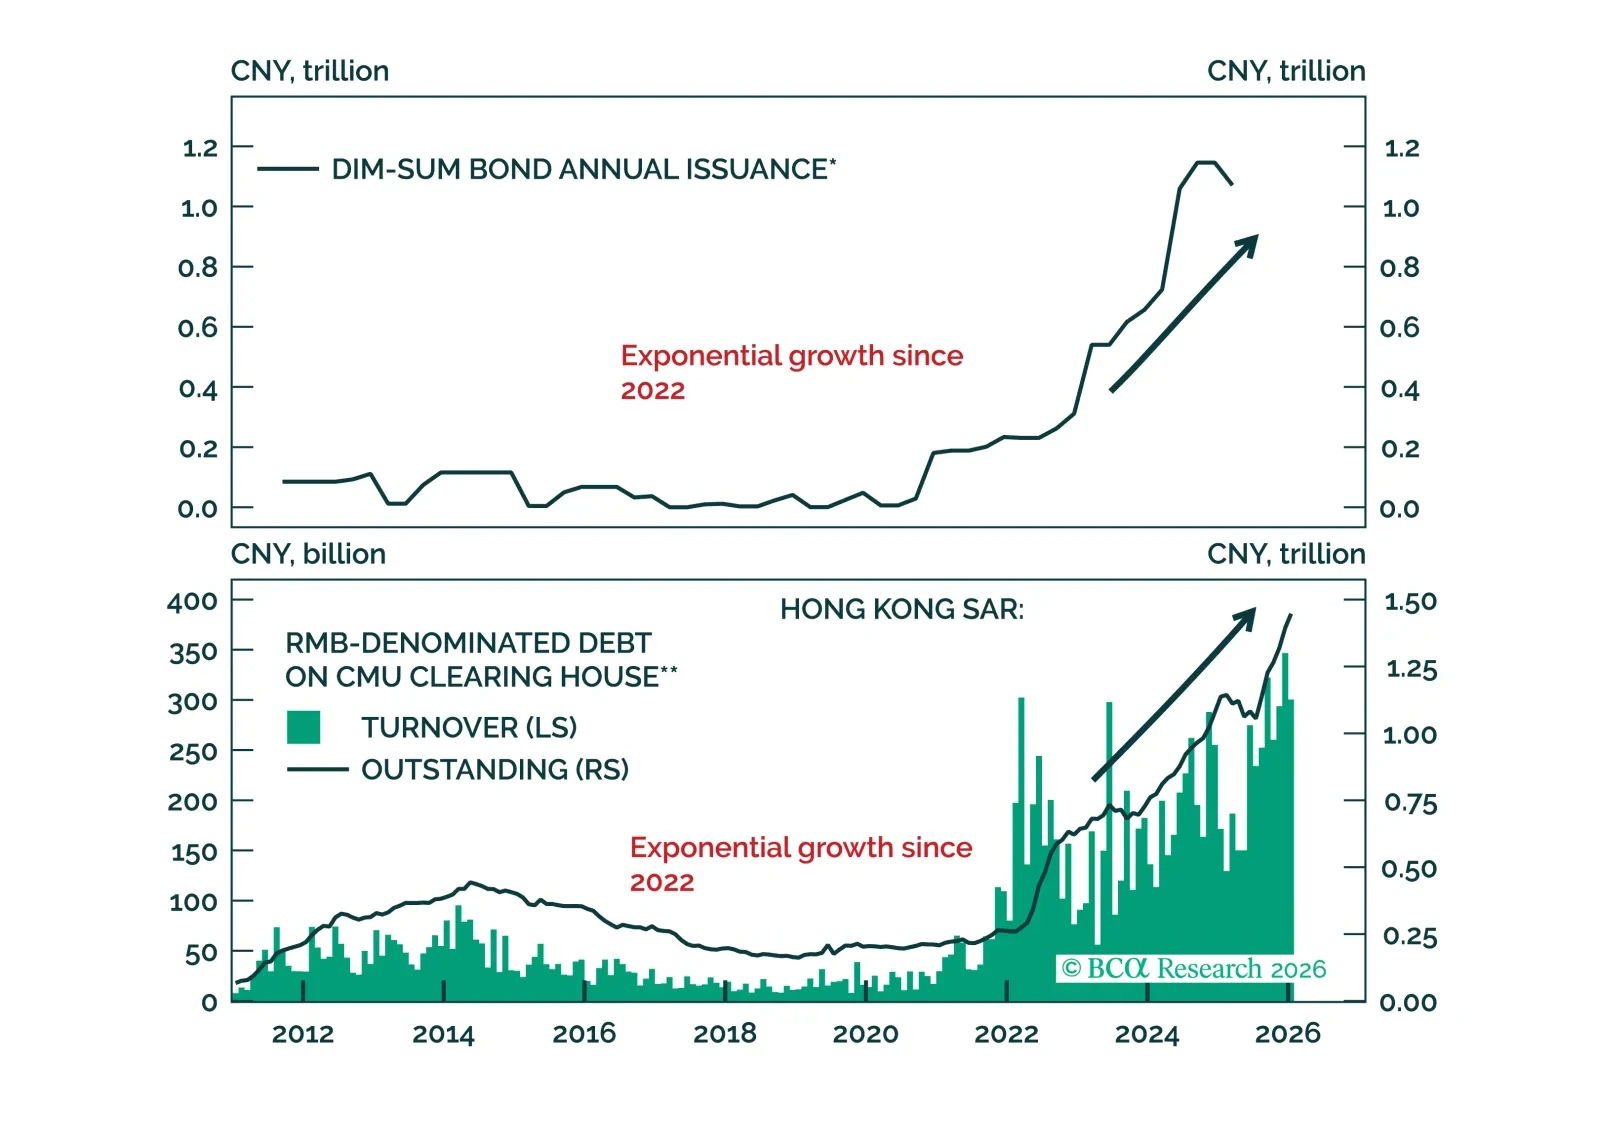
The CNY is undervalued and highly competitive. This gives China room to let the currency appreciate while remaining an export-driven powerhouse, gradually shifting from export intensity toward stronger domestic consumption. This achieves two objectives. First, it narrows the capital account deficit and strengthens the CNY’s role as a global anchor. Second, it enhances Beijing’s geopolitical autonomy by reducing reliance on foreign final demand.
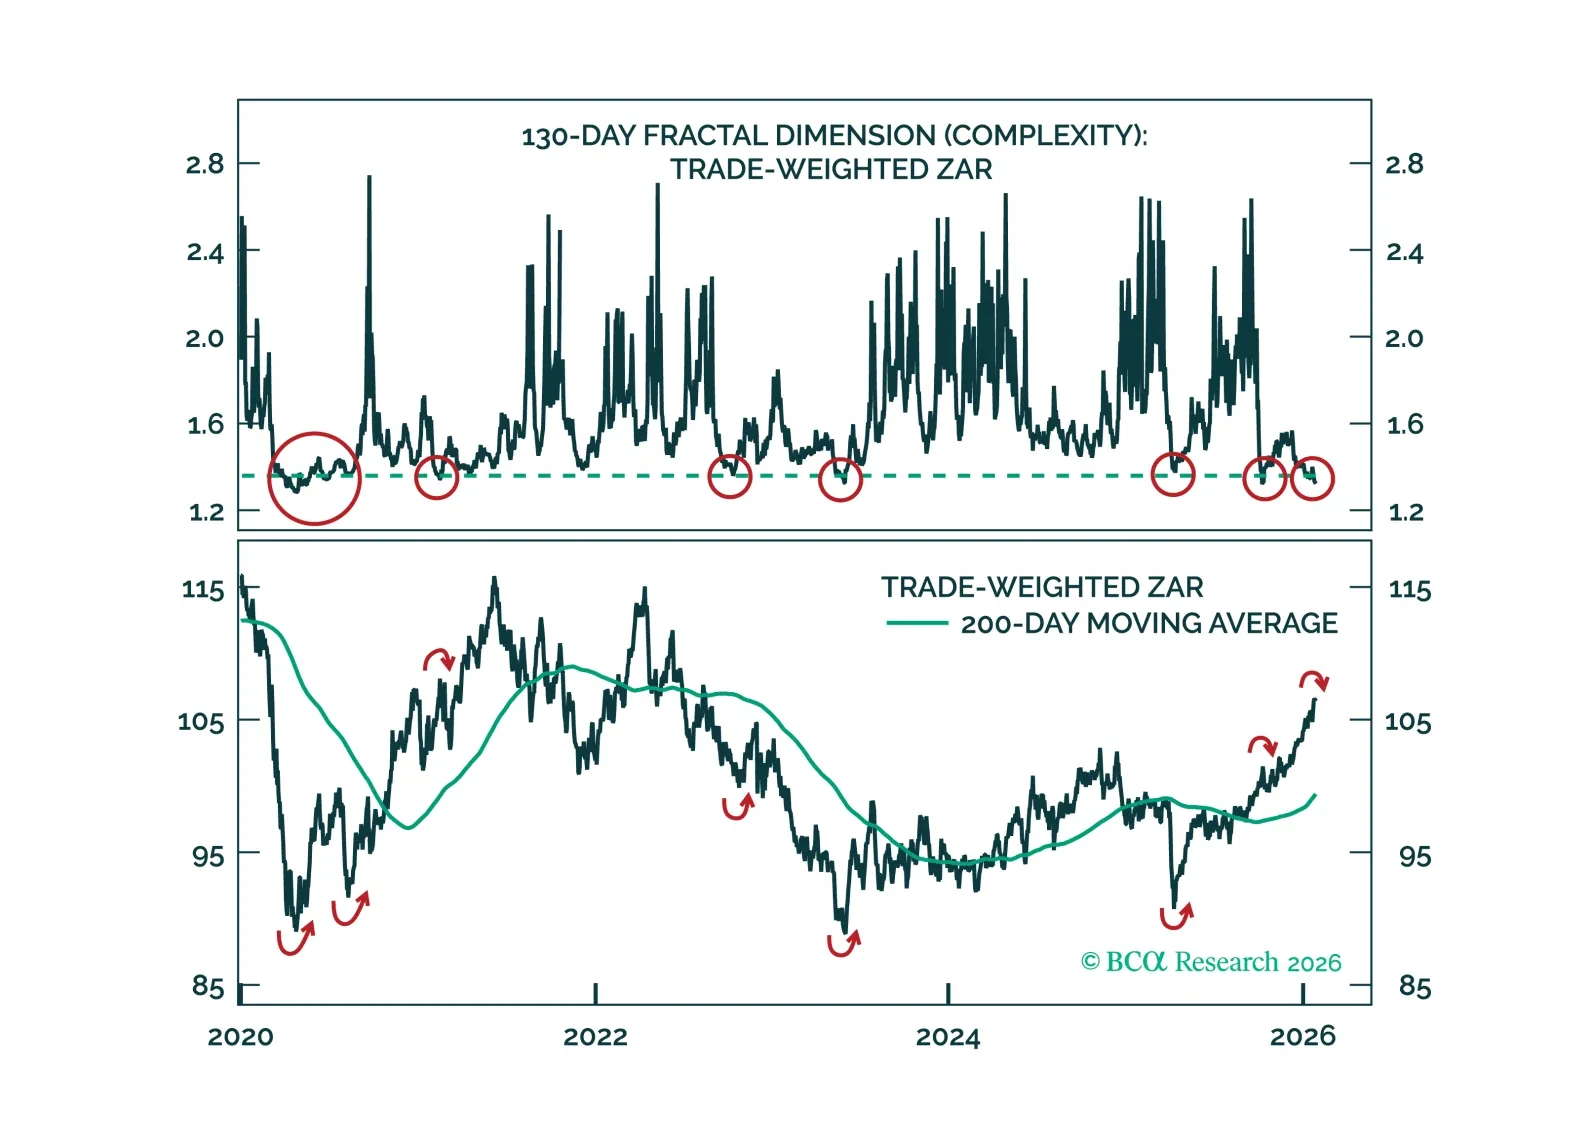
South Africa’s commodity boost is fading, but its cyclical headwinds remain. As growth weakens and capital inflows dry up, the rand looks increasingly vulnerable to a reversal.
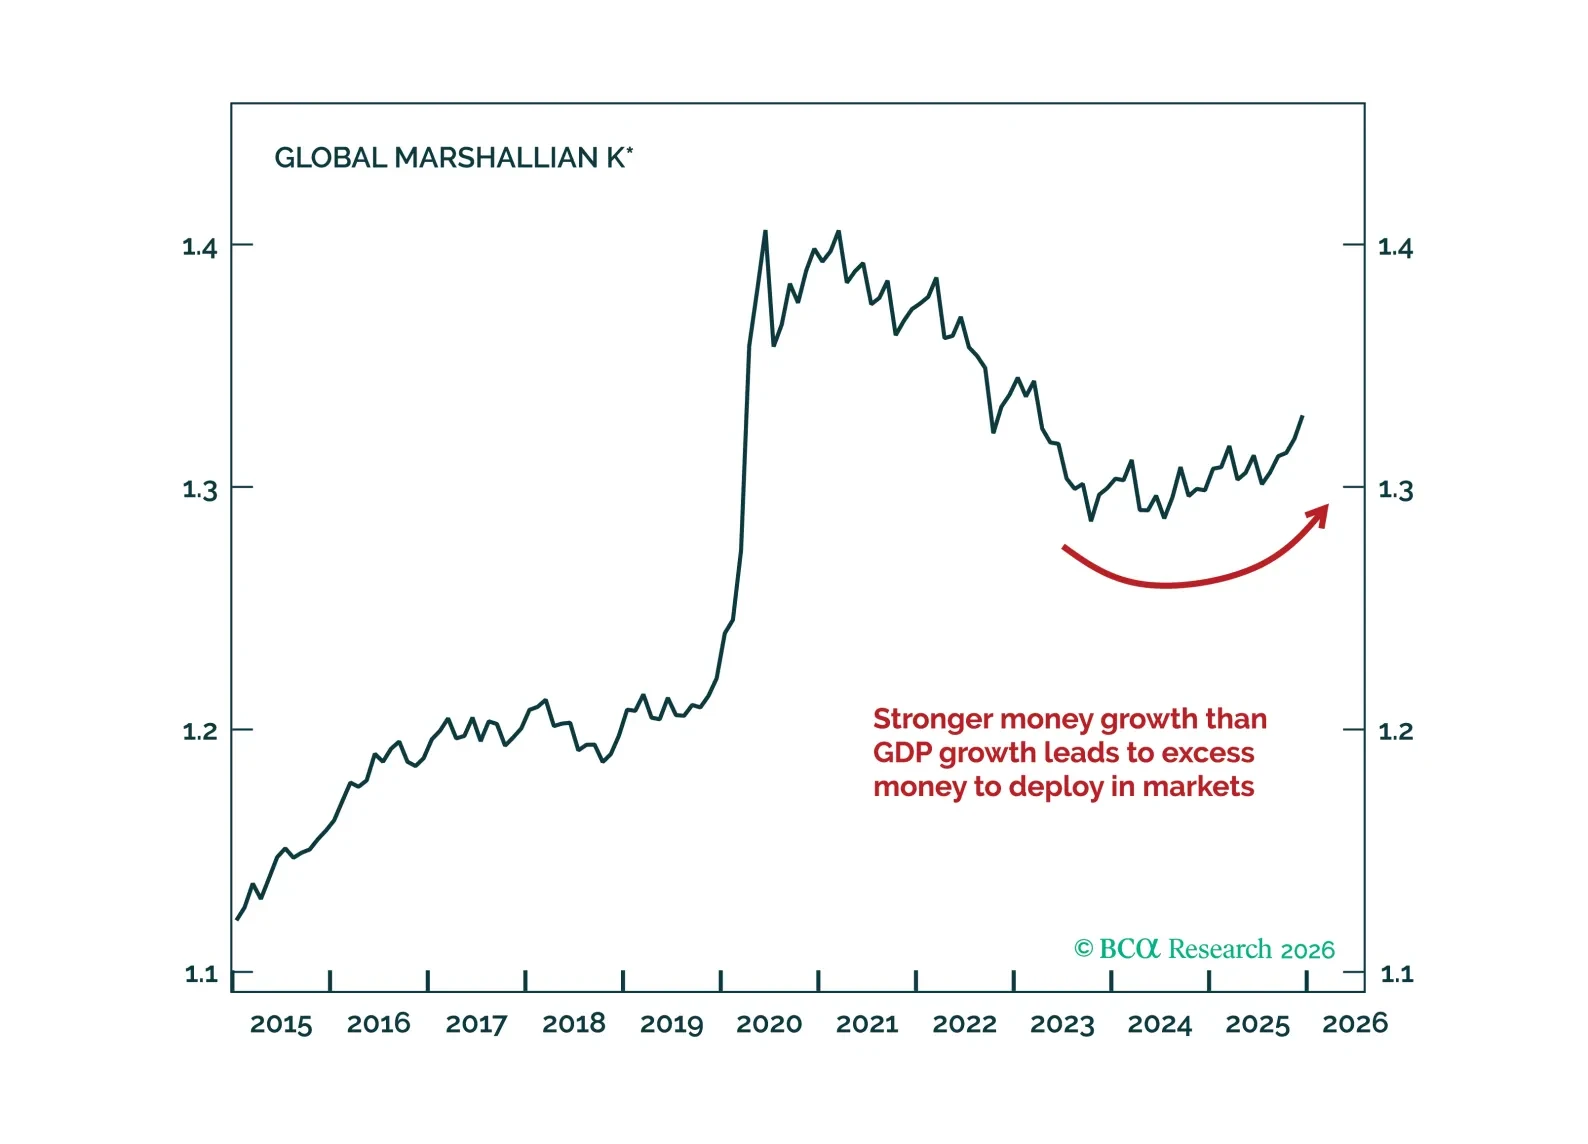
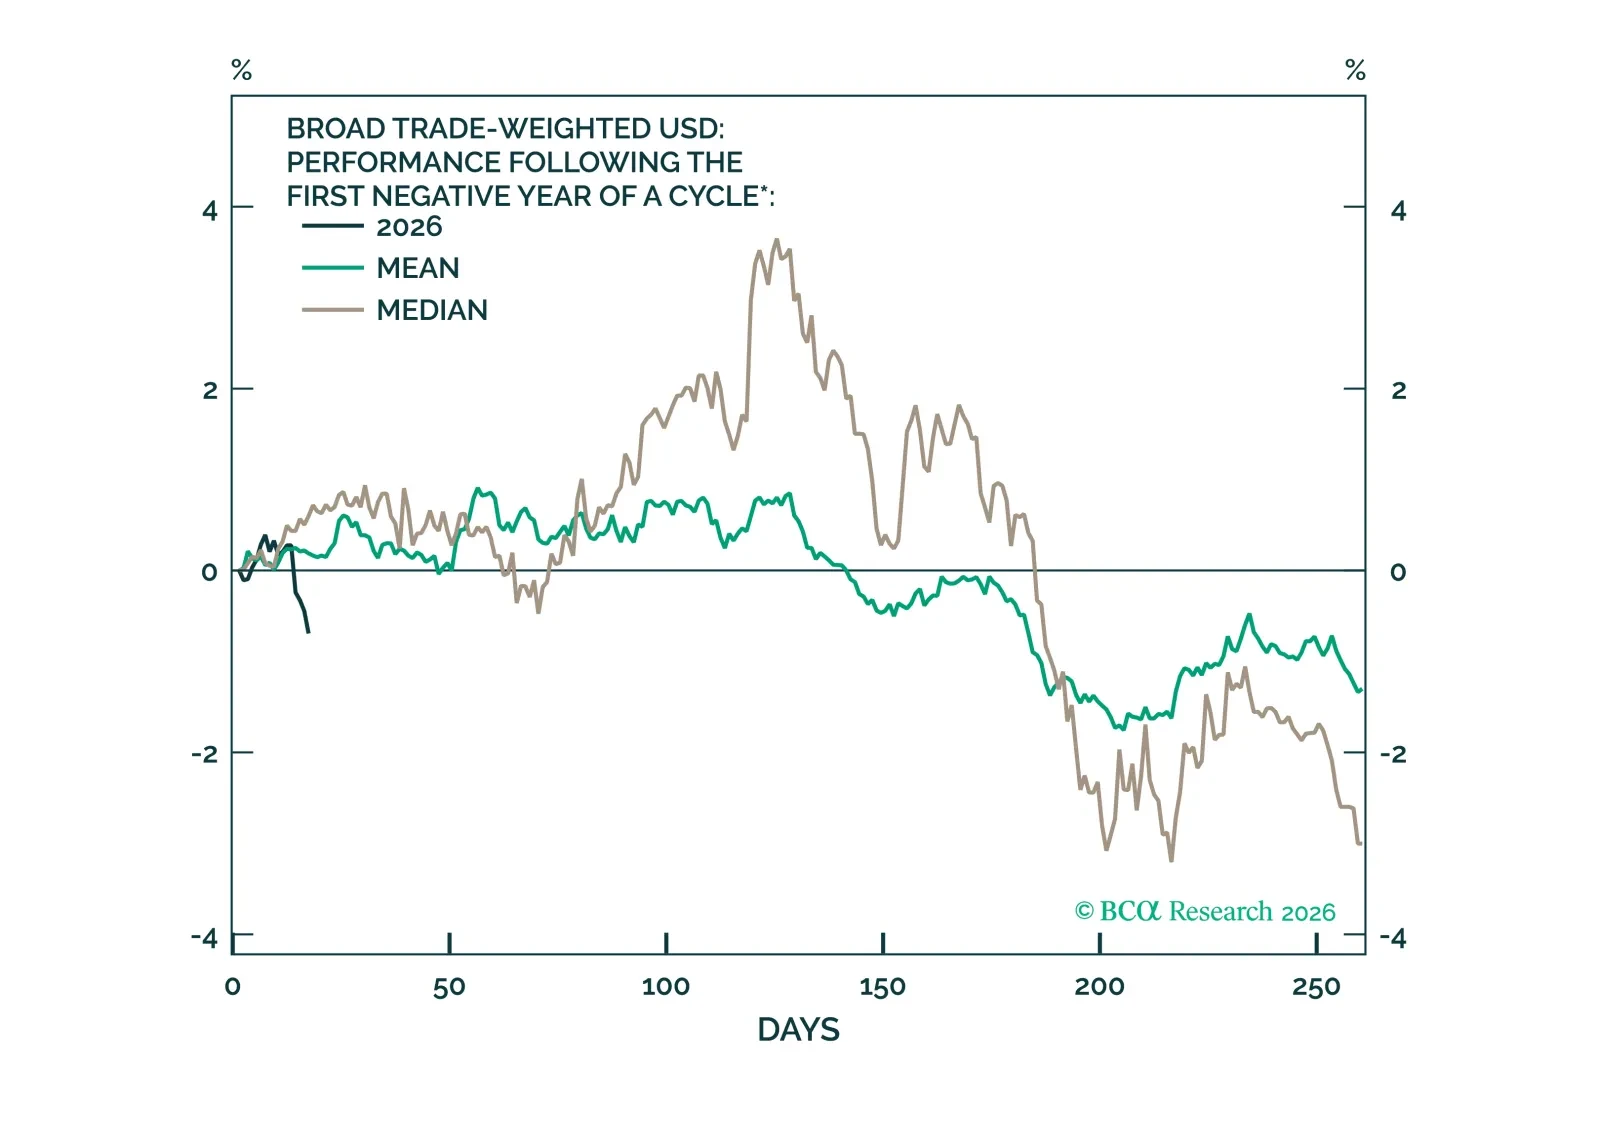
FX markets have dominated headlines over the past week, with a meltdown in the dollar and a surge in the yen. This week’s note unpacks the forces behind these moves and assesses whether recent price action marks a temporary dislocation or the start of a more durable FX shift.
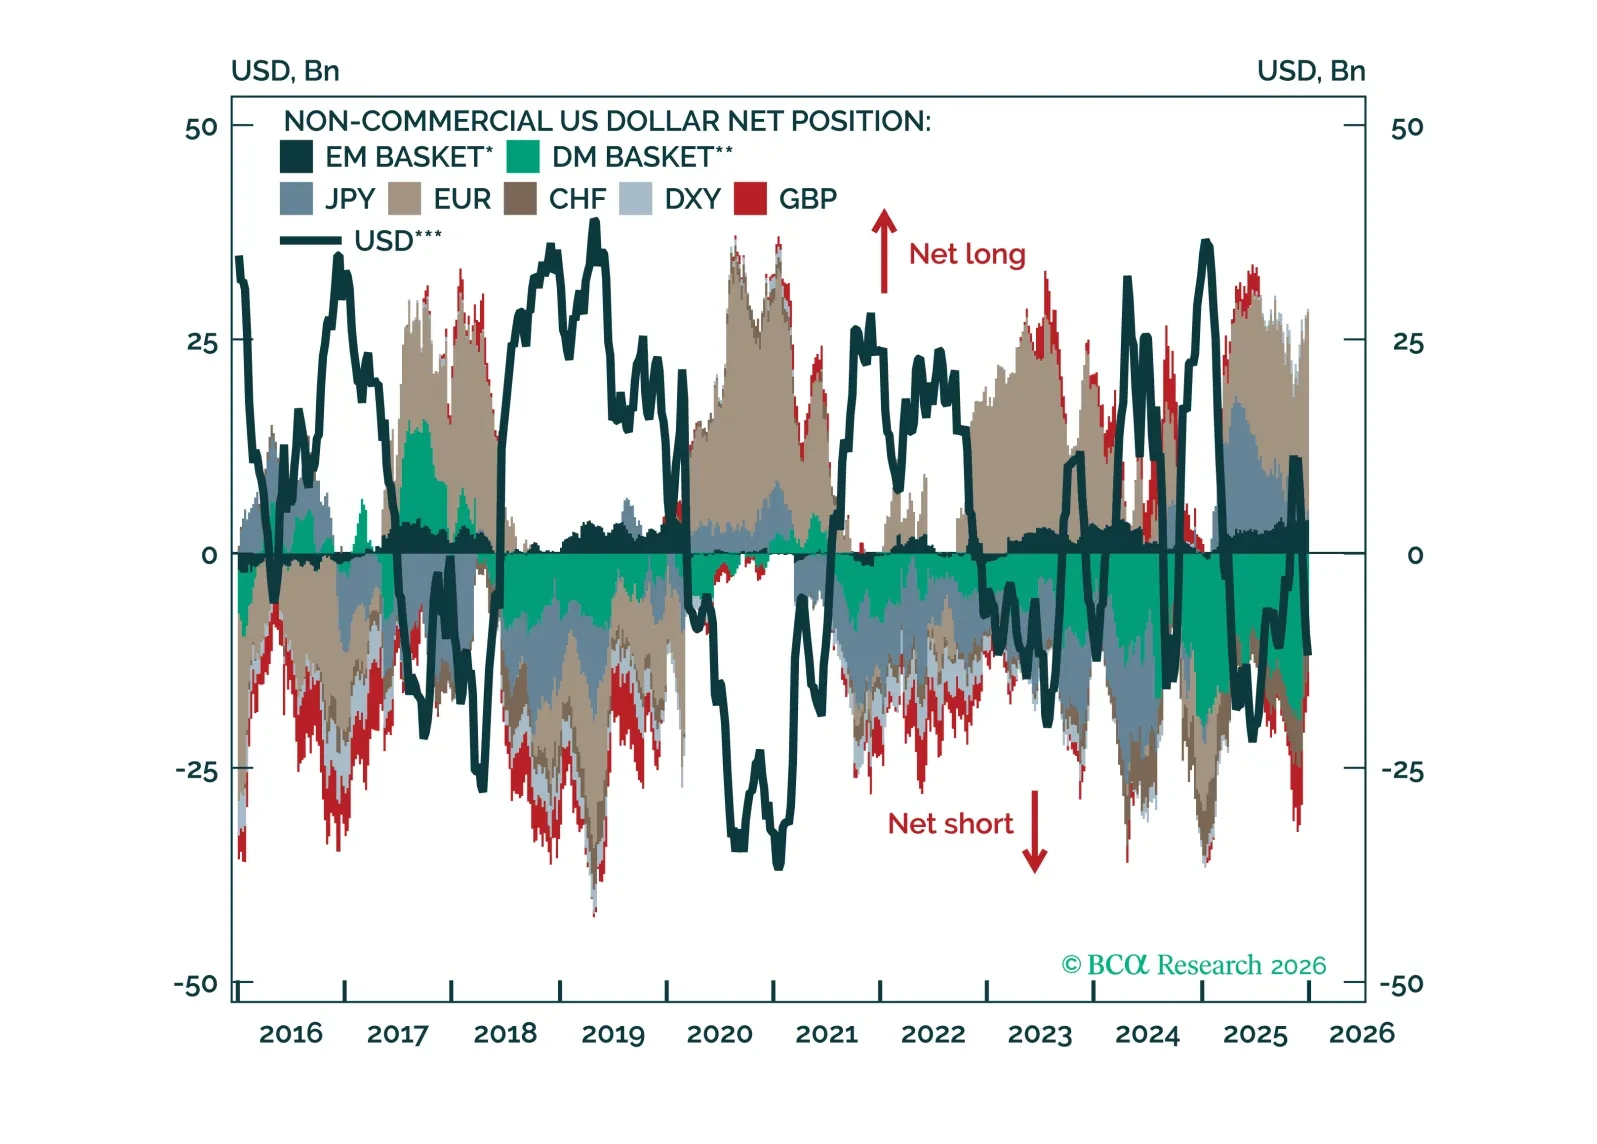
With FX volatility near cycle lows, this Insight examines where positioning has become most stretched across G10, EM FX, and precious metals – and what that implies for near-term moves and reversal risks.
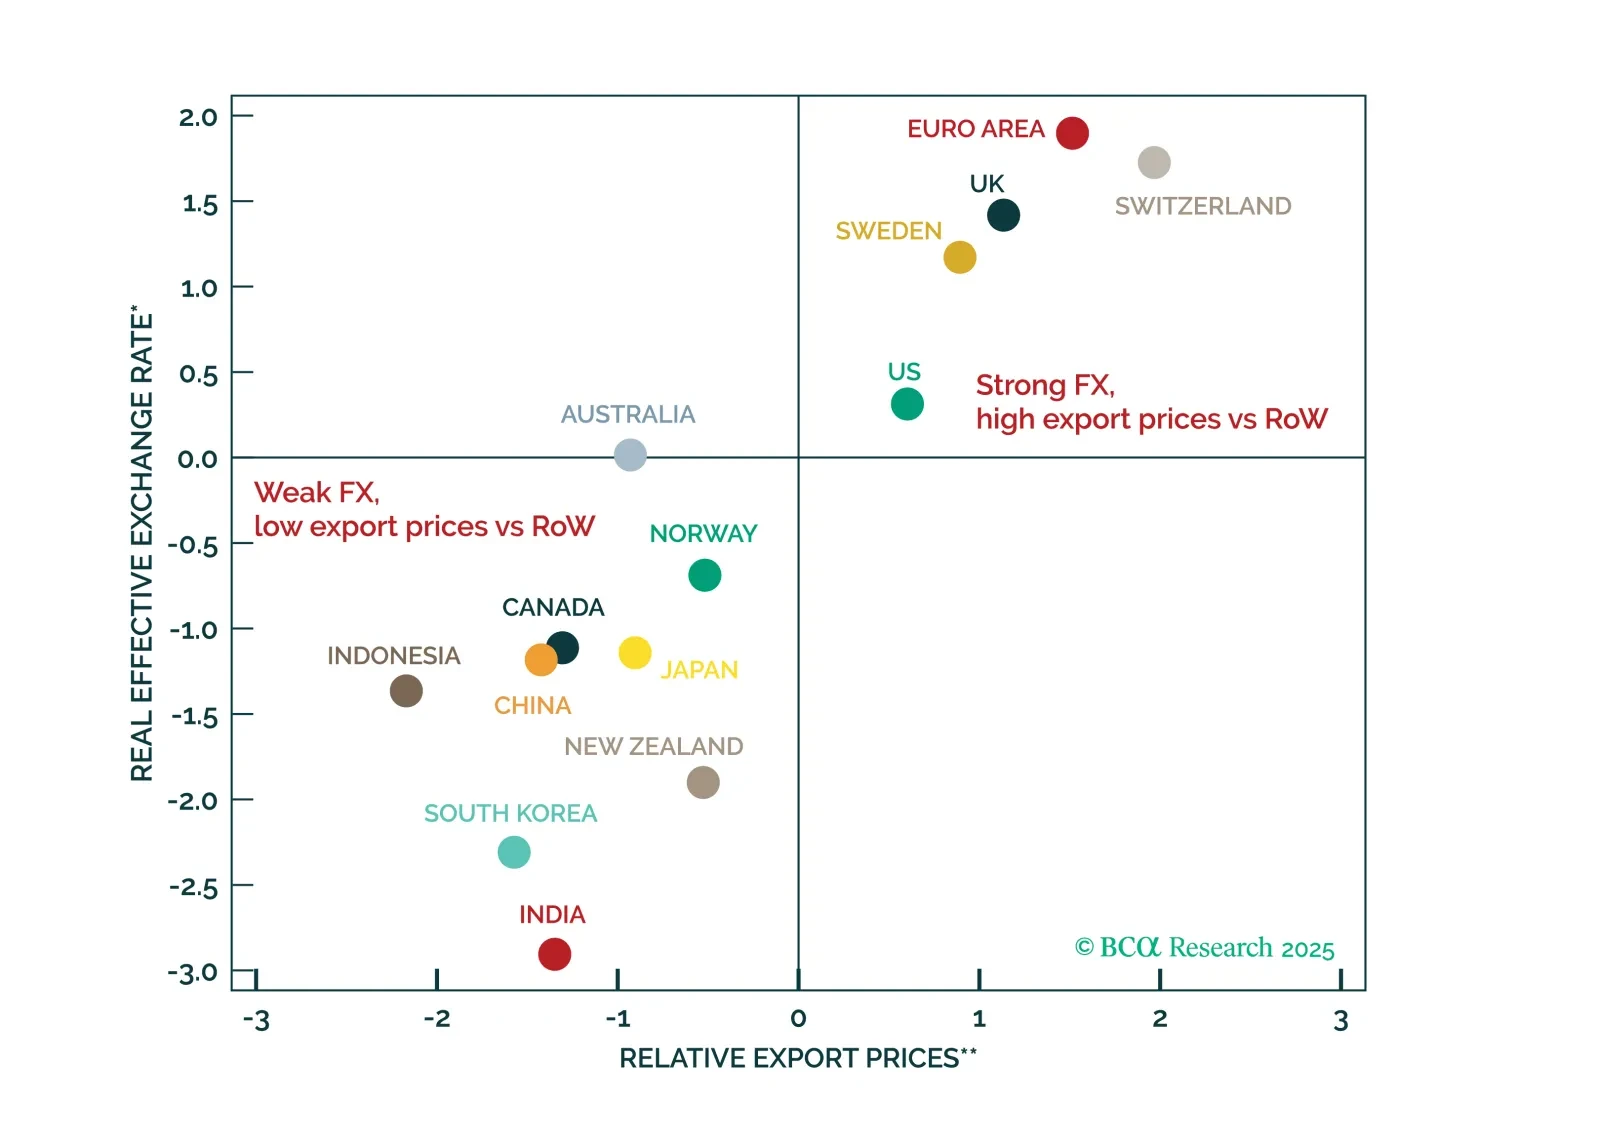
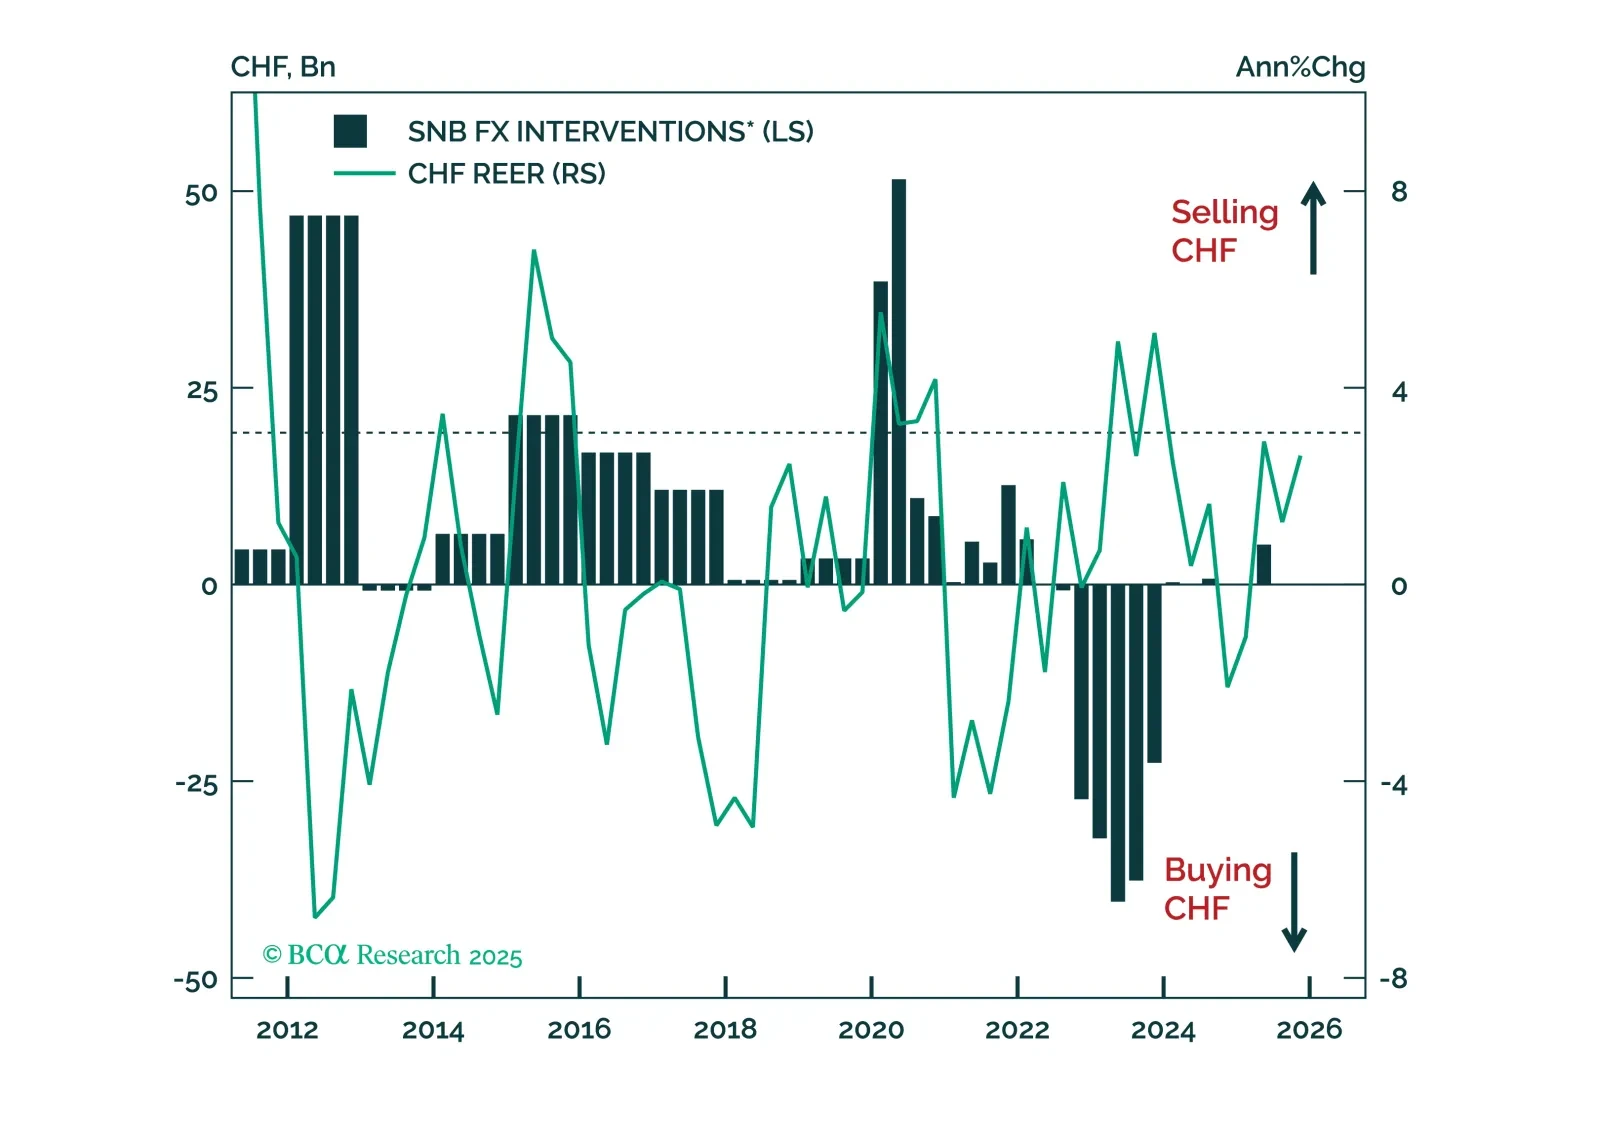
The SNB remains on hold, but the bar for further easing is falling quickly – even as Switzerland secures a breakthrough trade deal with the US. With CHF now pressing against a policy ceiling, the franc looks increasingly attractive as a funding currency.