 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
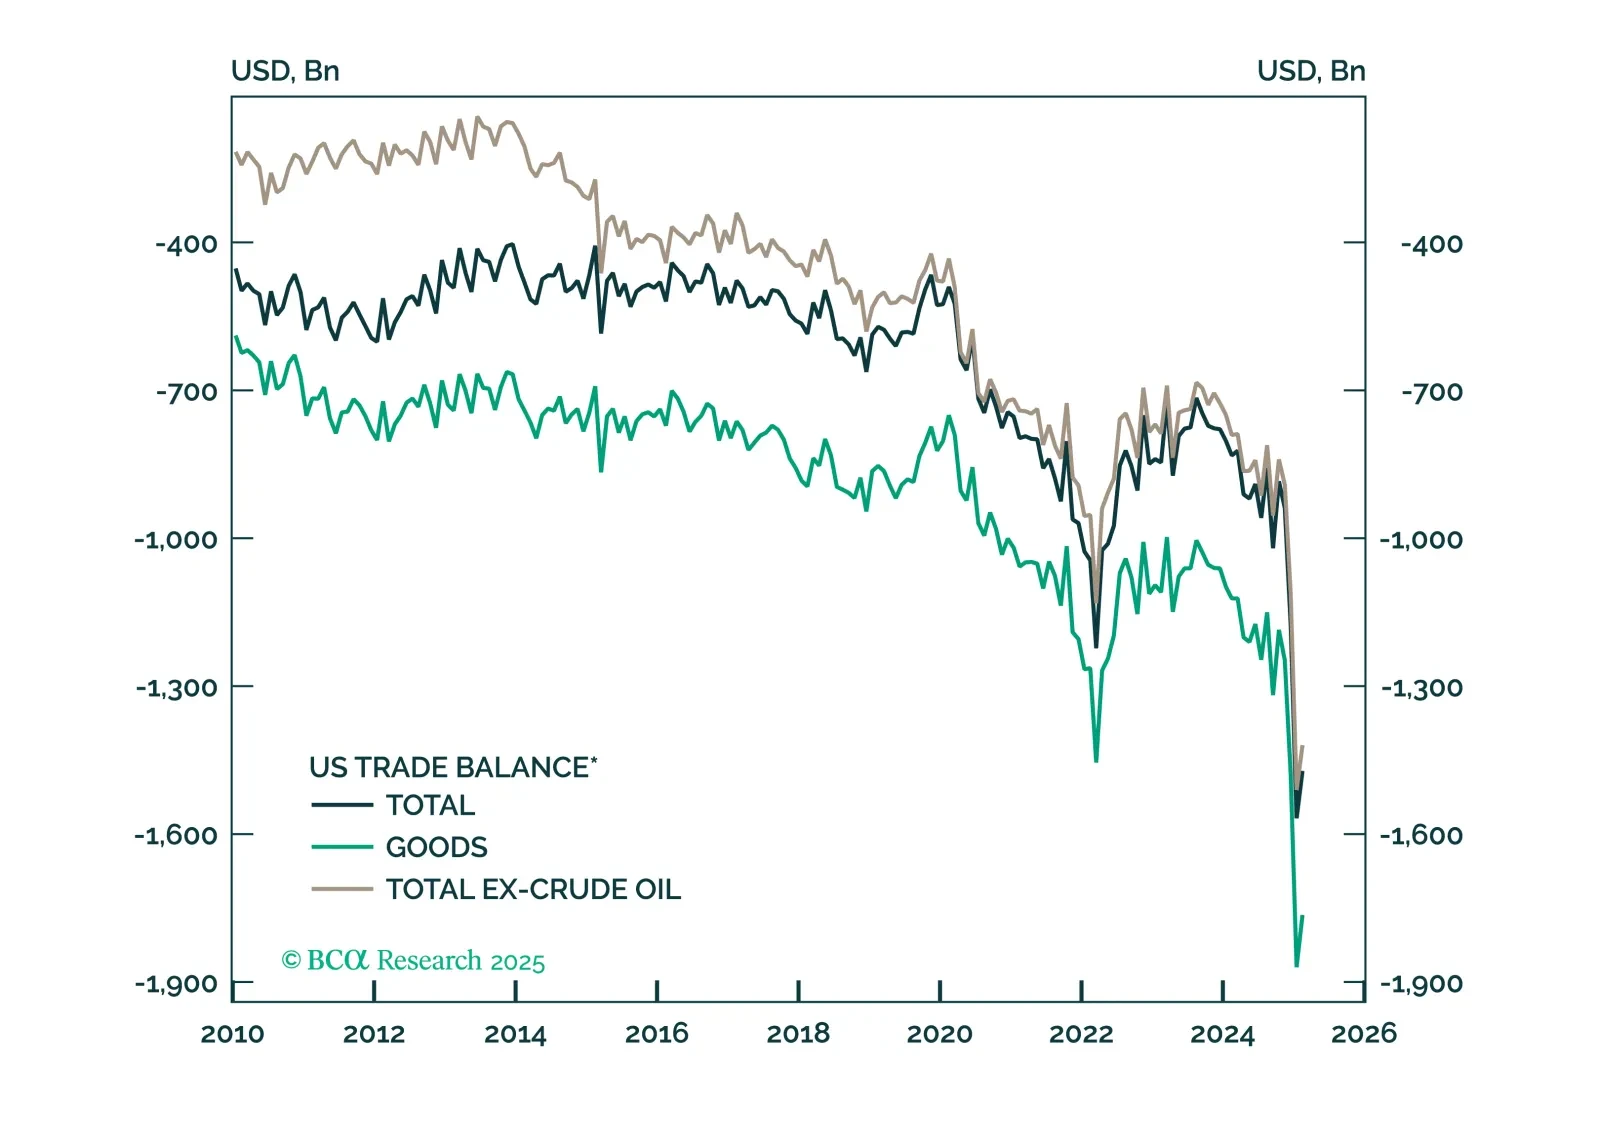
This report looks at the FX implications of the Trump tariffs, and the review of our Q1 trades.
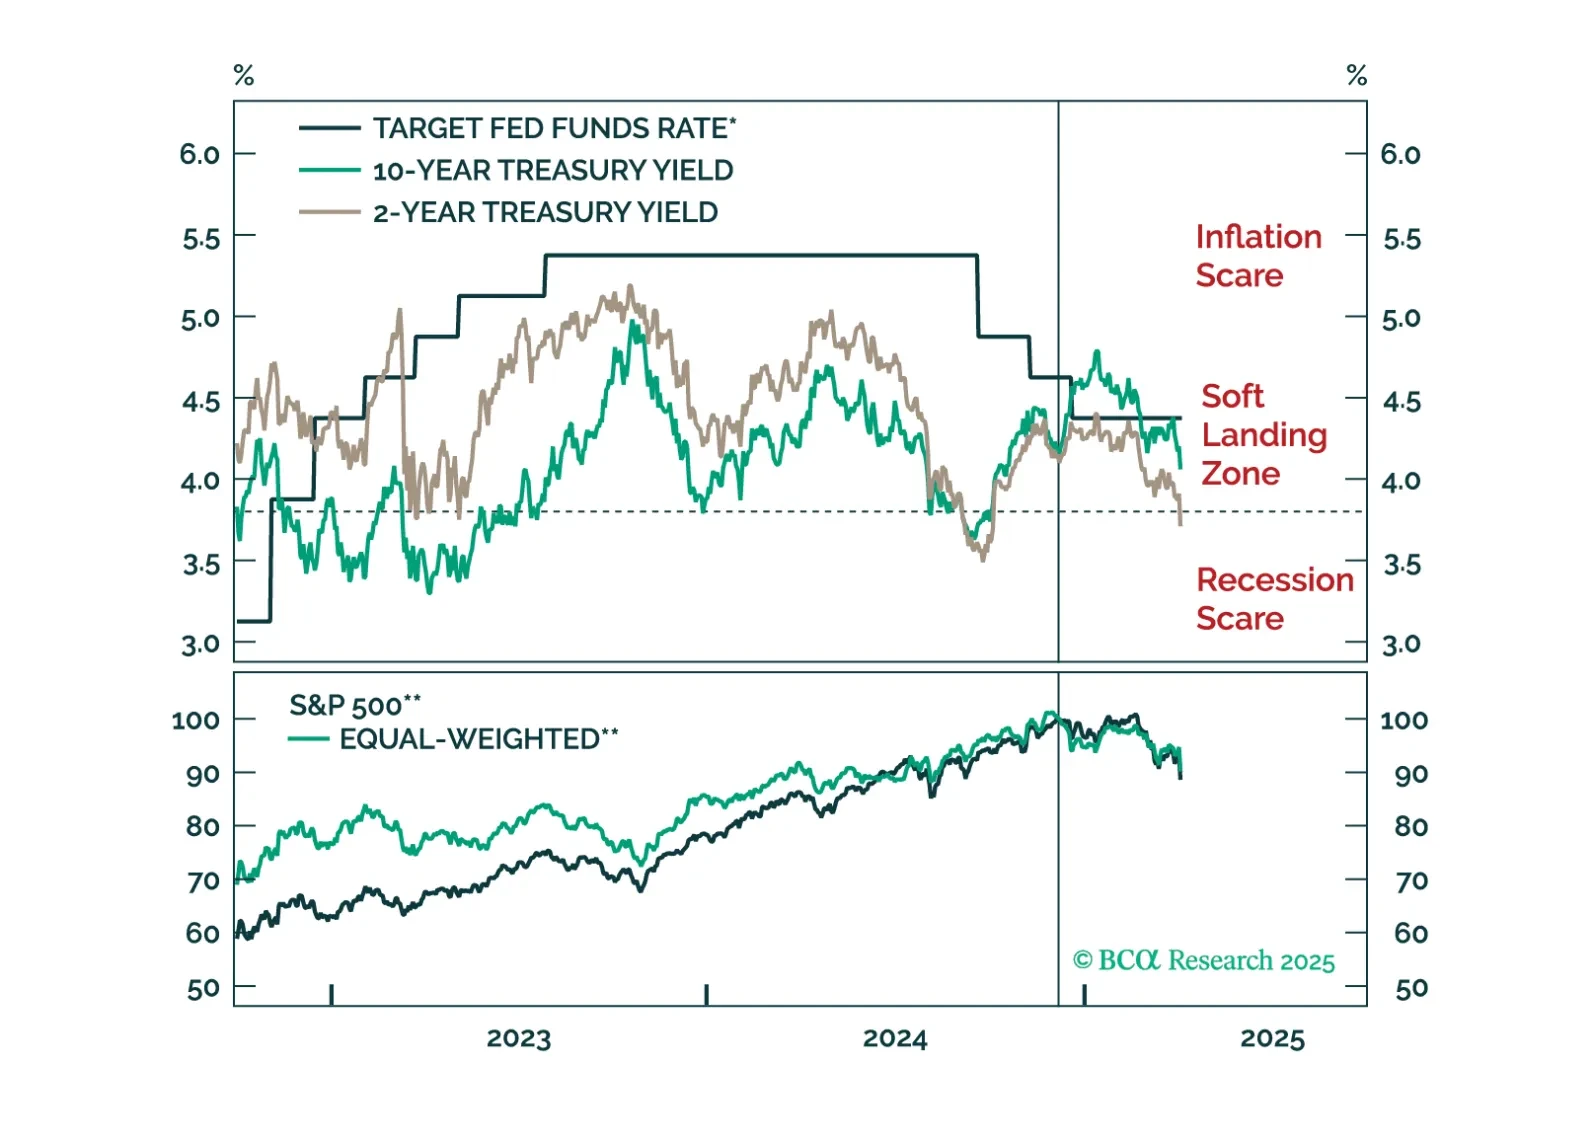
The March employment report showed strong job growth, but the labor market remains in a fragile state and the demand shock from tariffs could be the catalyst that tips it over the edge into recession.
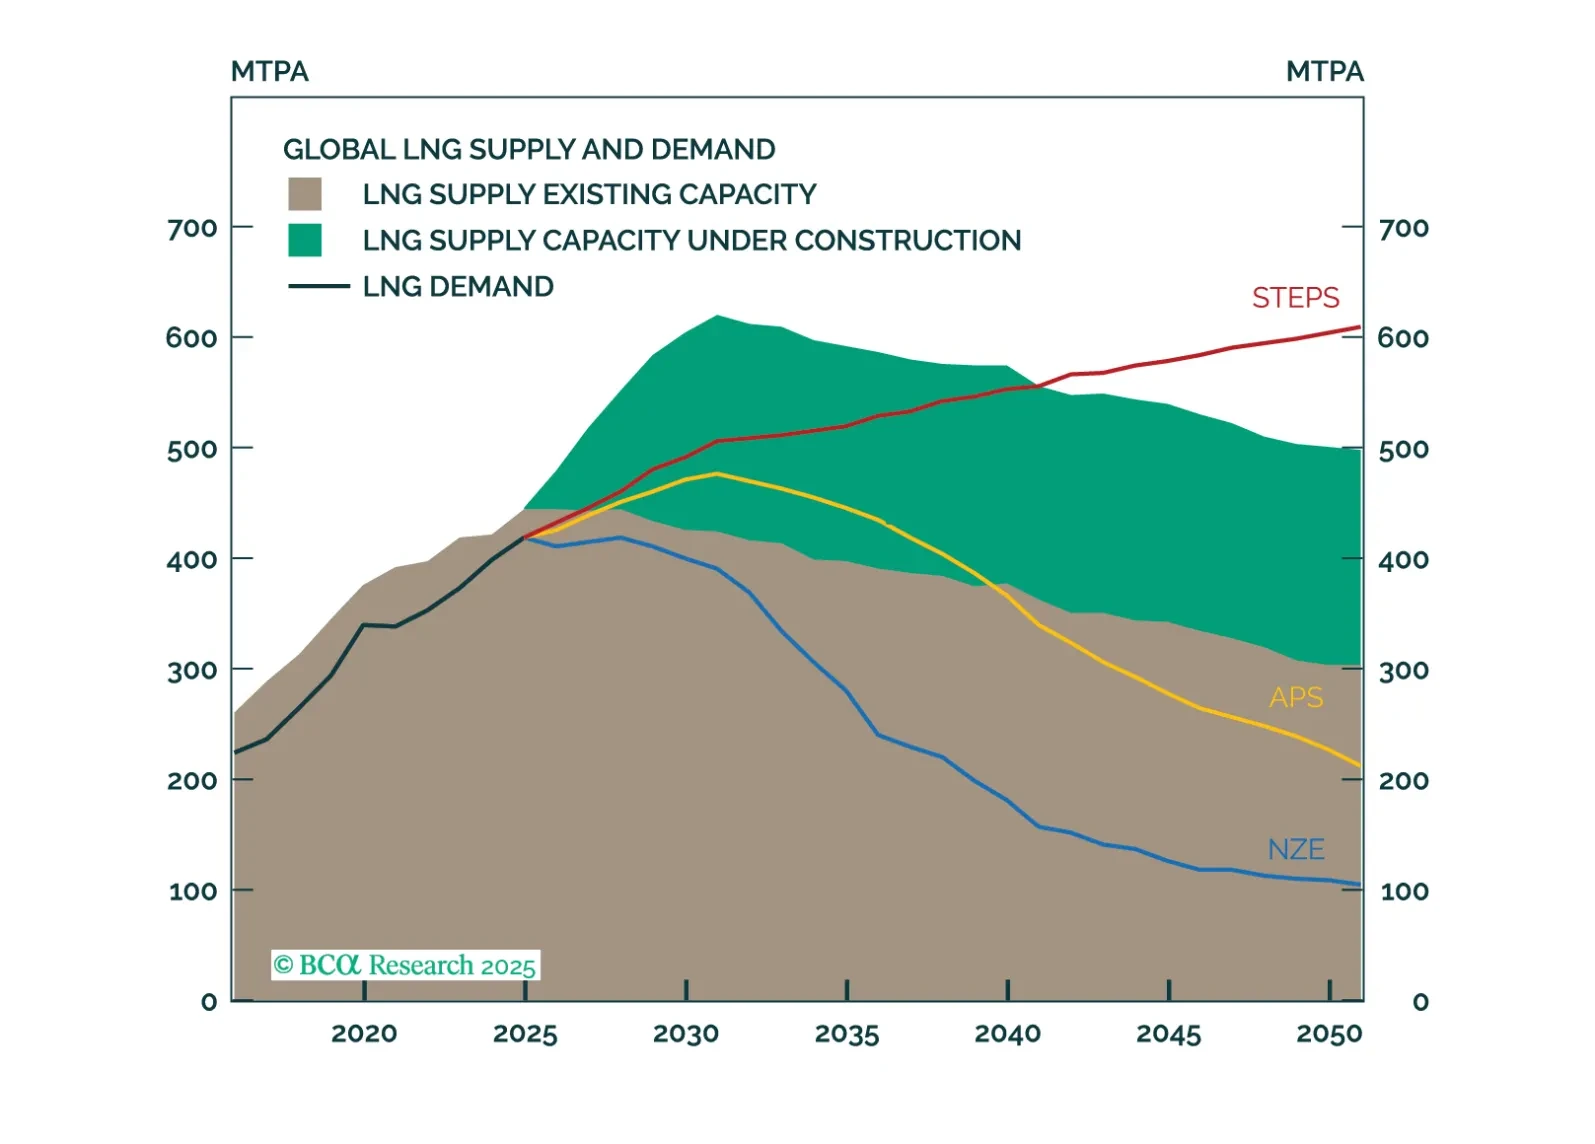
In this month’s Beta report, we continue our series supporting our bullish thesis on Europe. We take a deep dive into the aftermath of the European energy crisis – dispelling the myth that Europe faces risks of imminent deindustrialization – and evaluate the impact the approaching LNG wave will have on European industry and the global natural gas market.
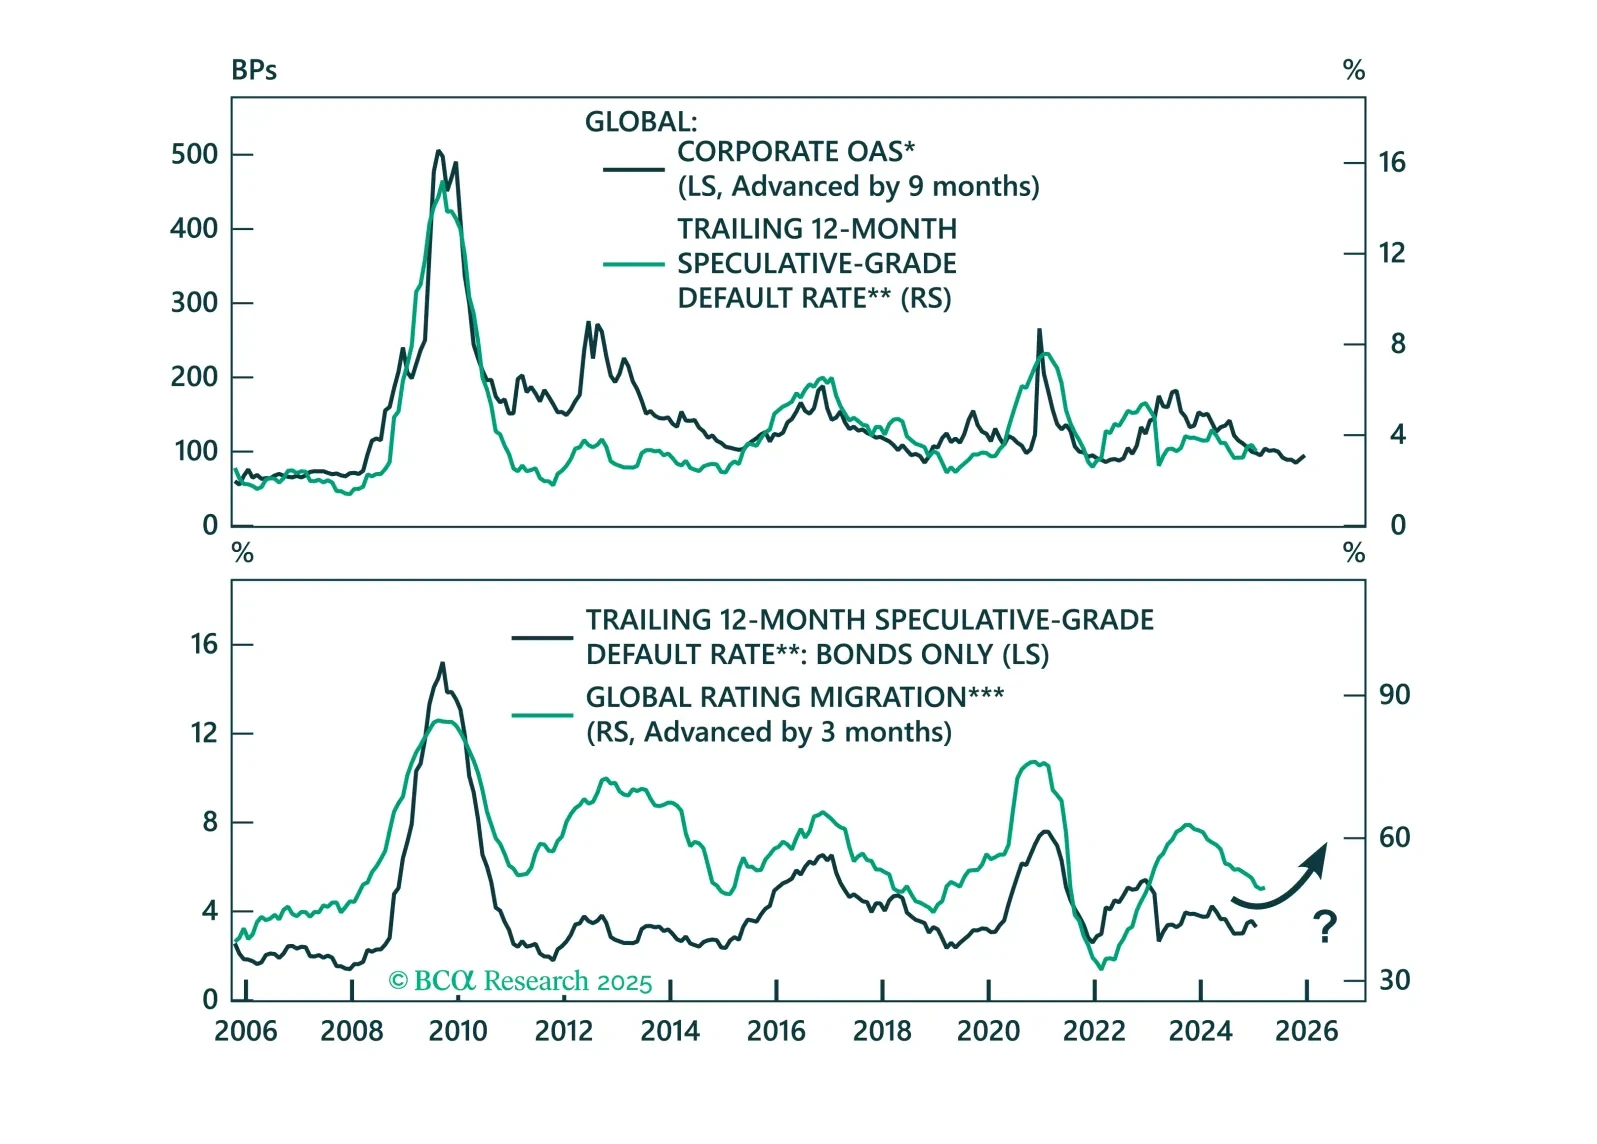
Corporate bond spreads are tight around the globe and do not adequately compensate for the risk of a deterioration in credit quality. We examine the global corporate credit landscape to identify which markets are best equipped to perform in the current environment.
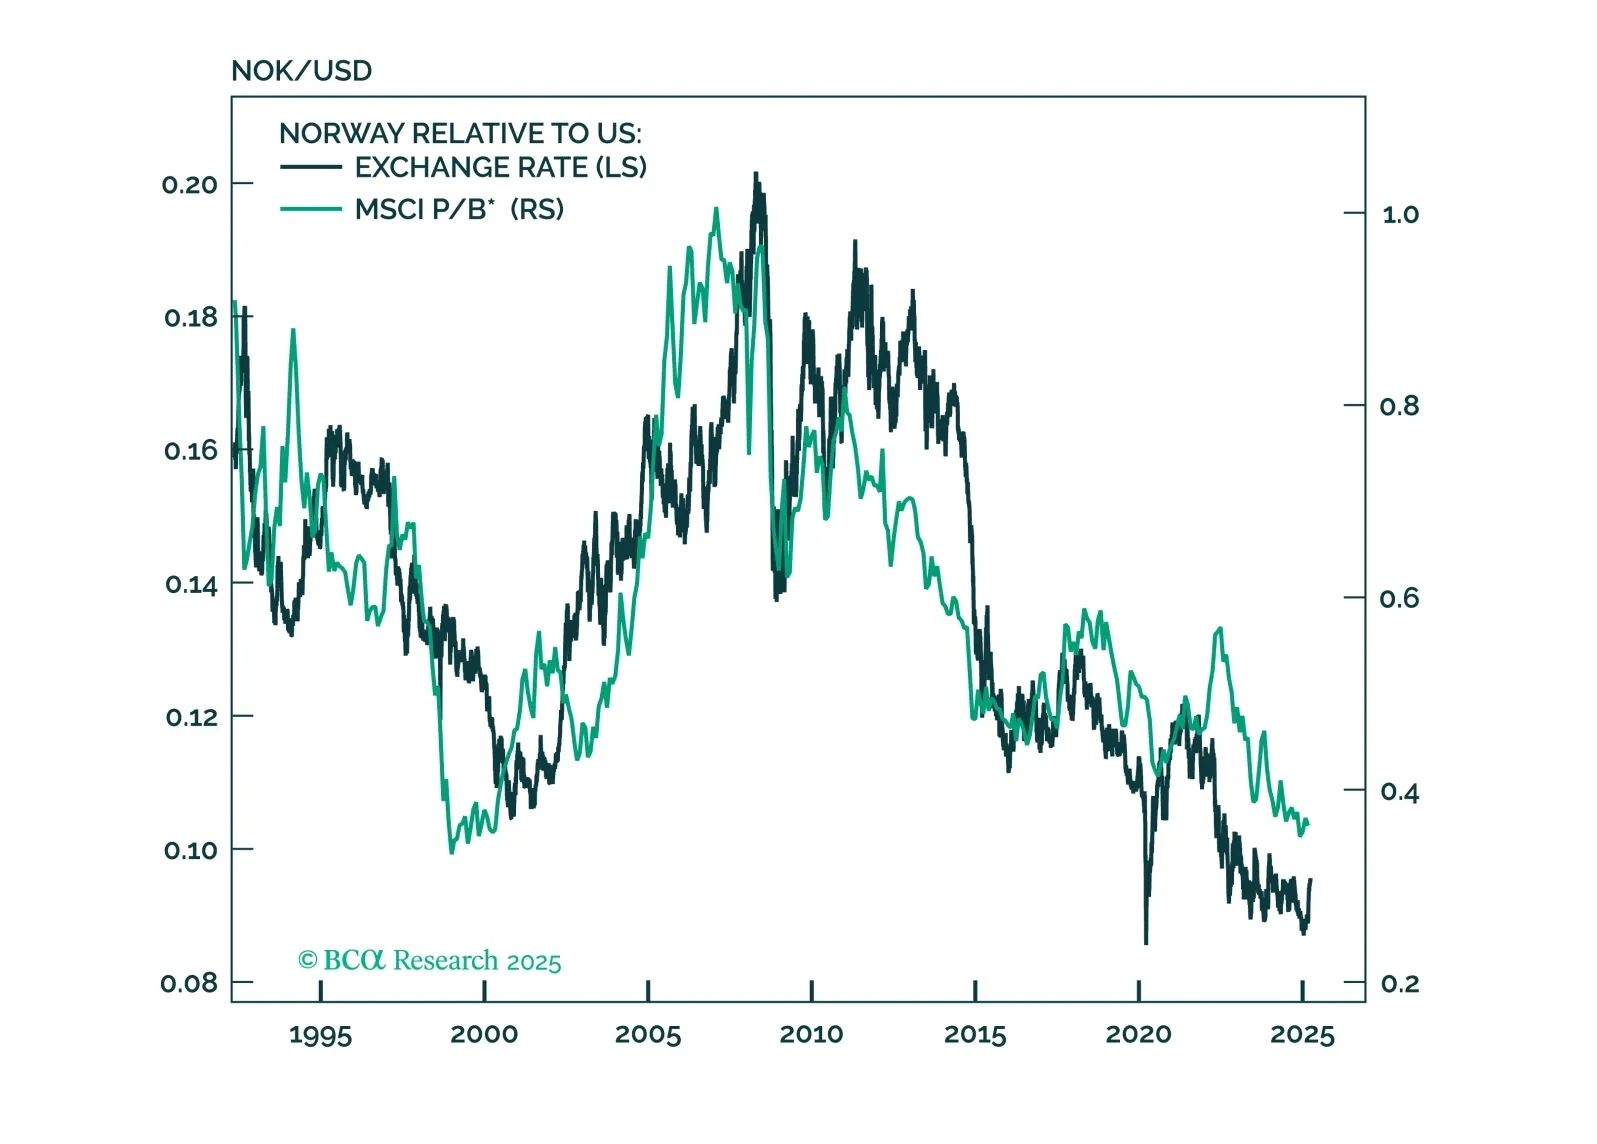
This report looks at investment implications, for Norwegian assets, given the recent meeting, from the Norges Bank.

This morning’s weak consumer spending and strong inflation data reinforce our sense that the US economy is heading toward recession.
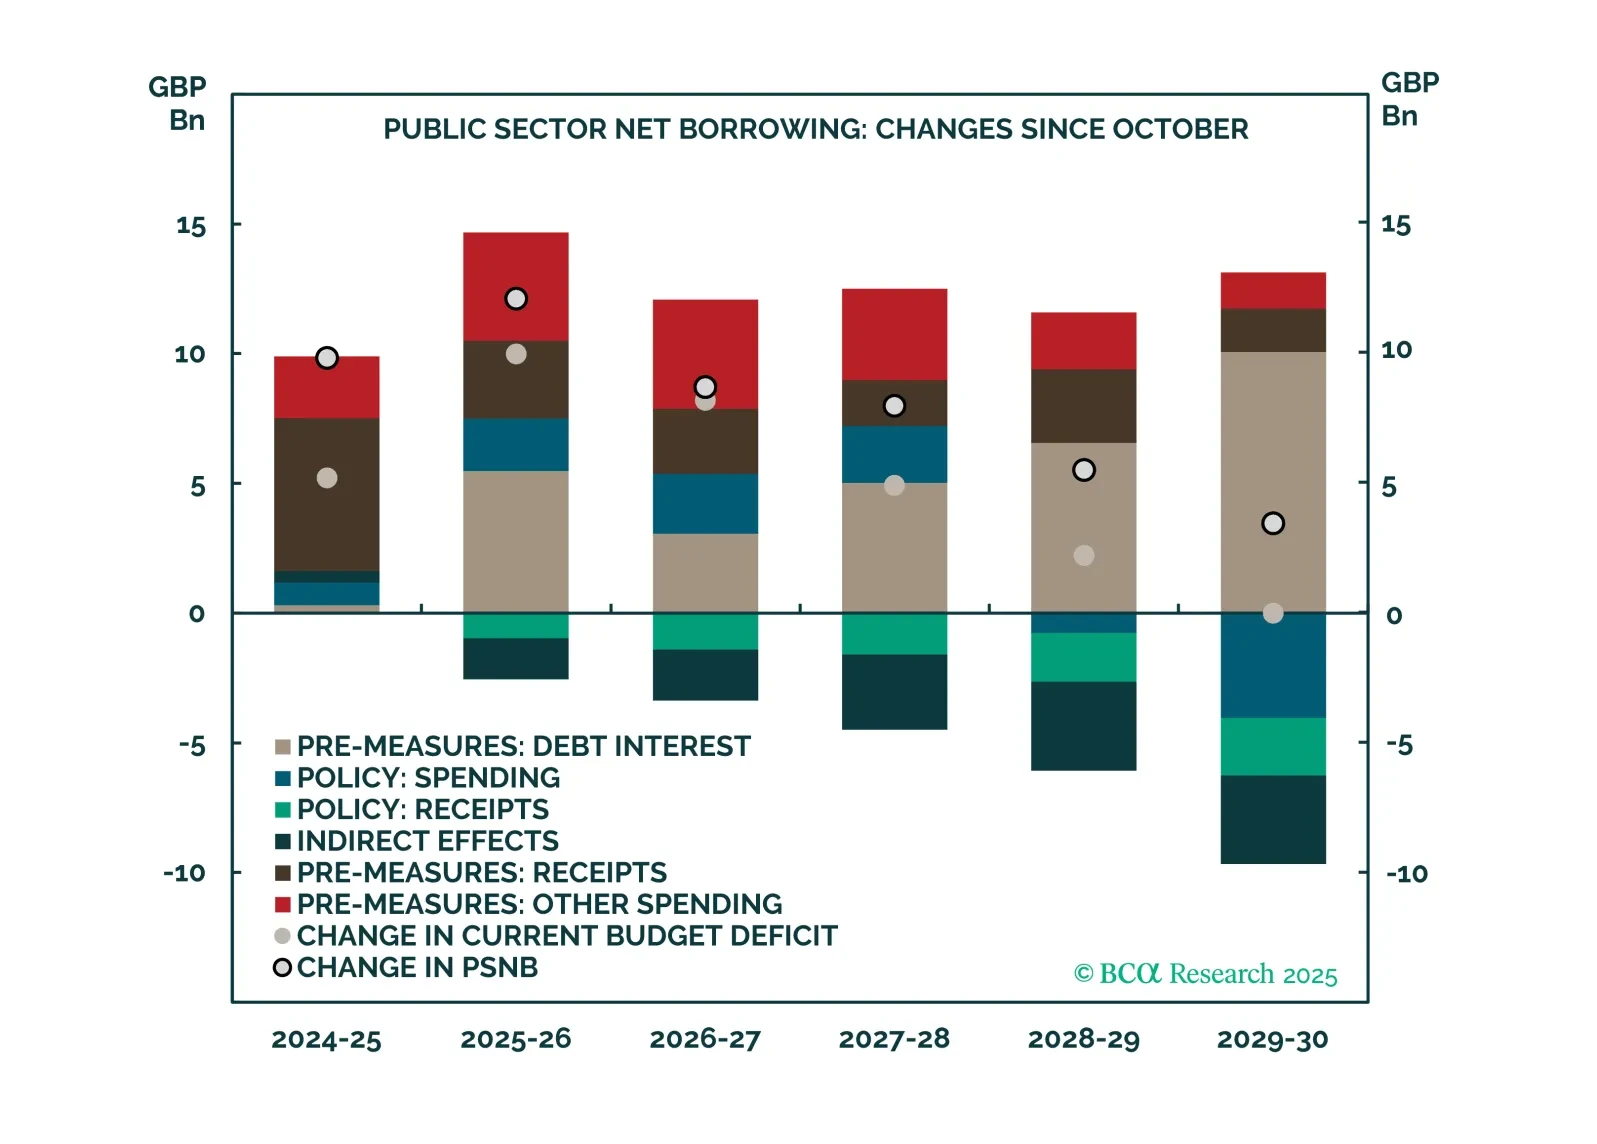
This report is a quick take on our views on UK bonds and FX, given the recent budget.
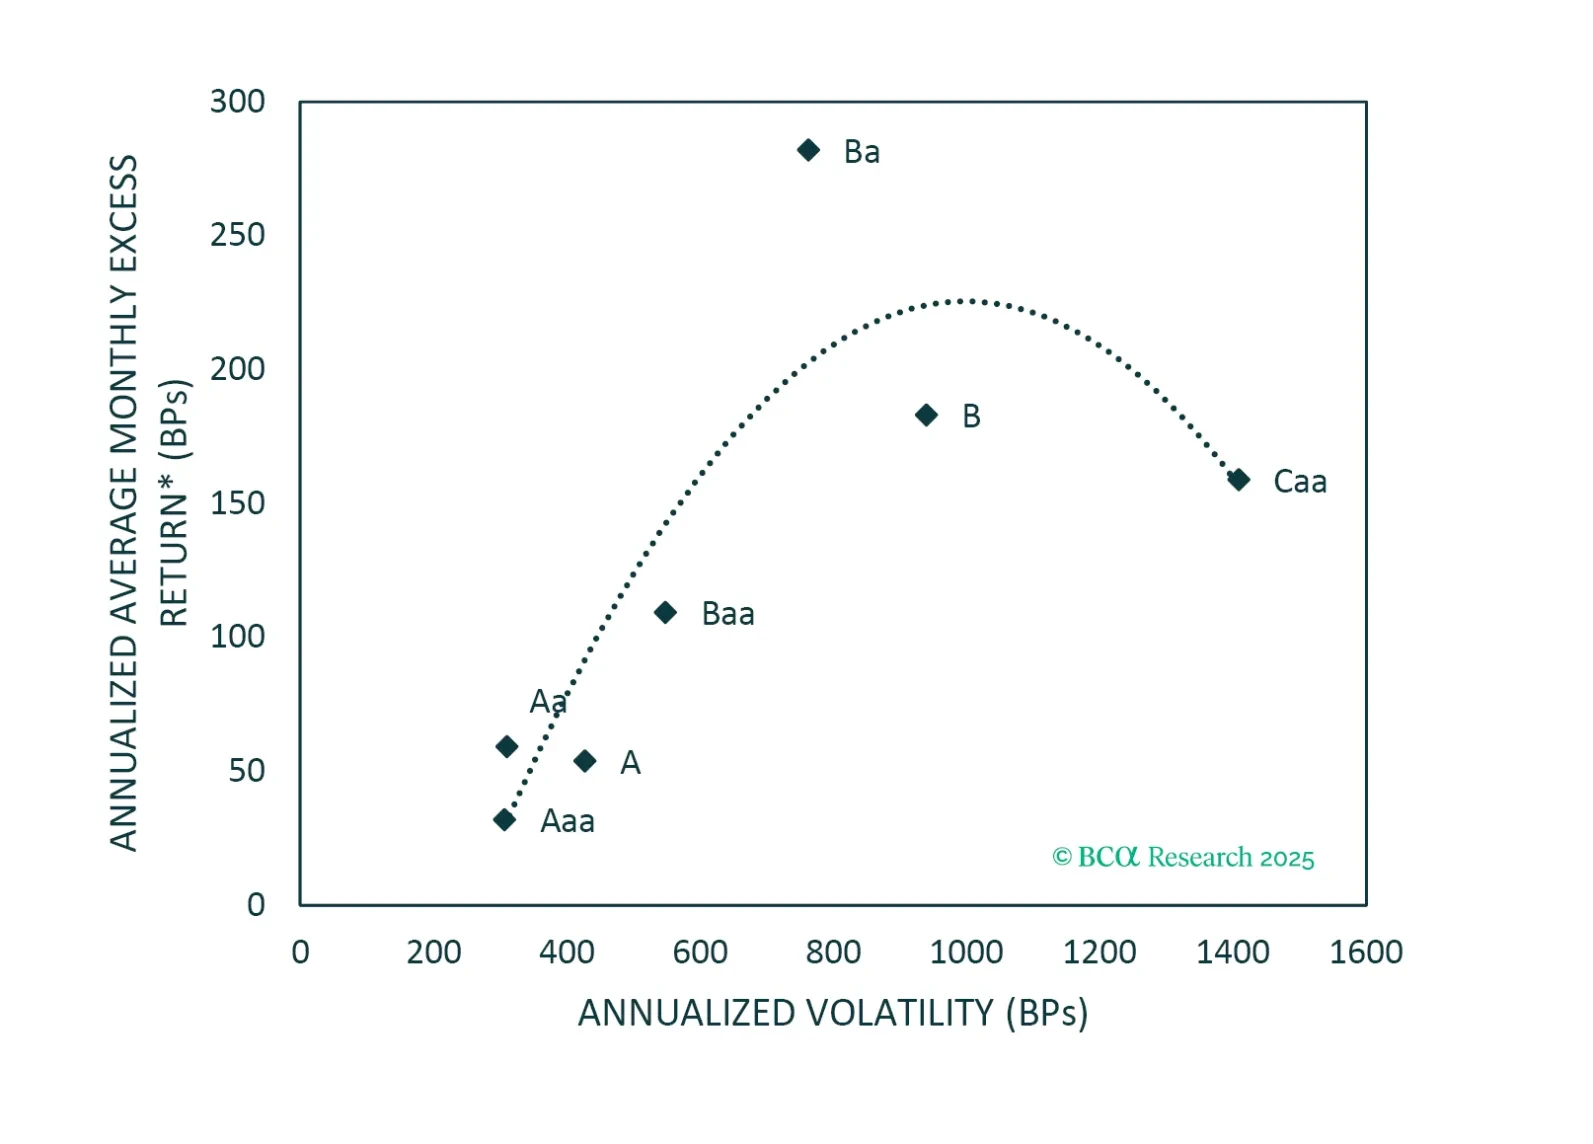
An analysis of historical data shows that Ba-rated bonds outperform other corporate credit tiers in the long-run on a risk-adjusted basis. That said, today’s fragile macro environment warrants a more cautious allocation.
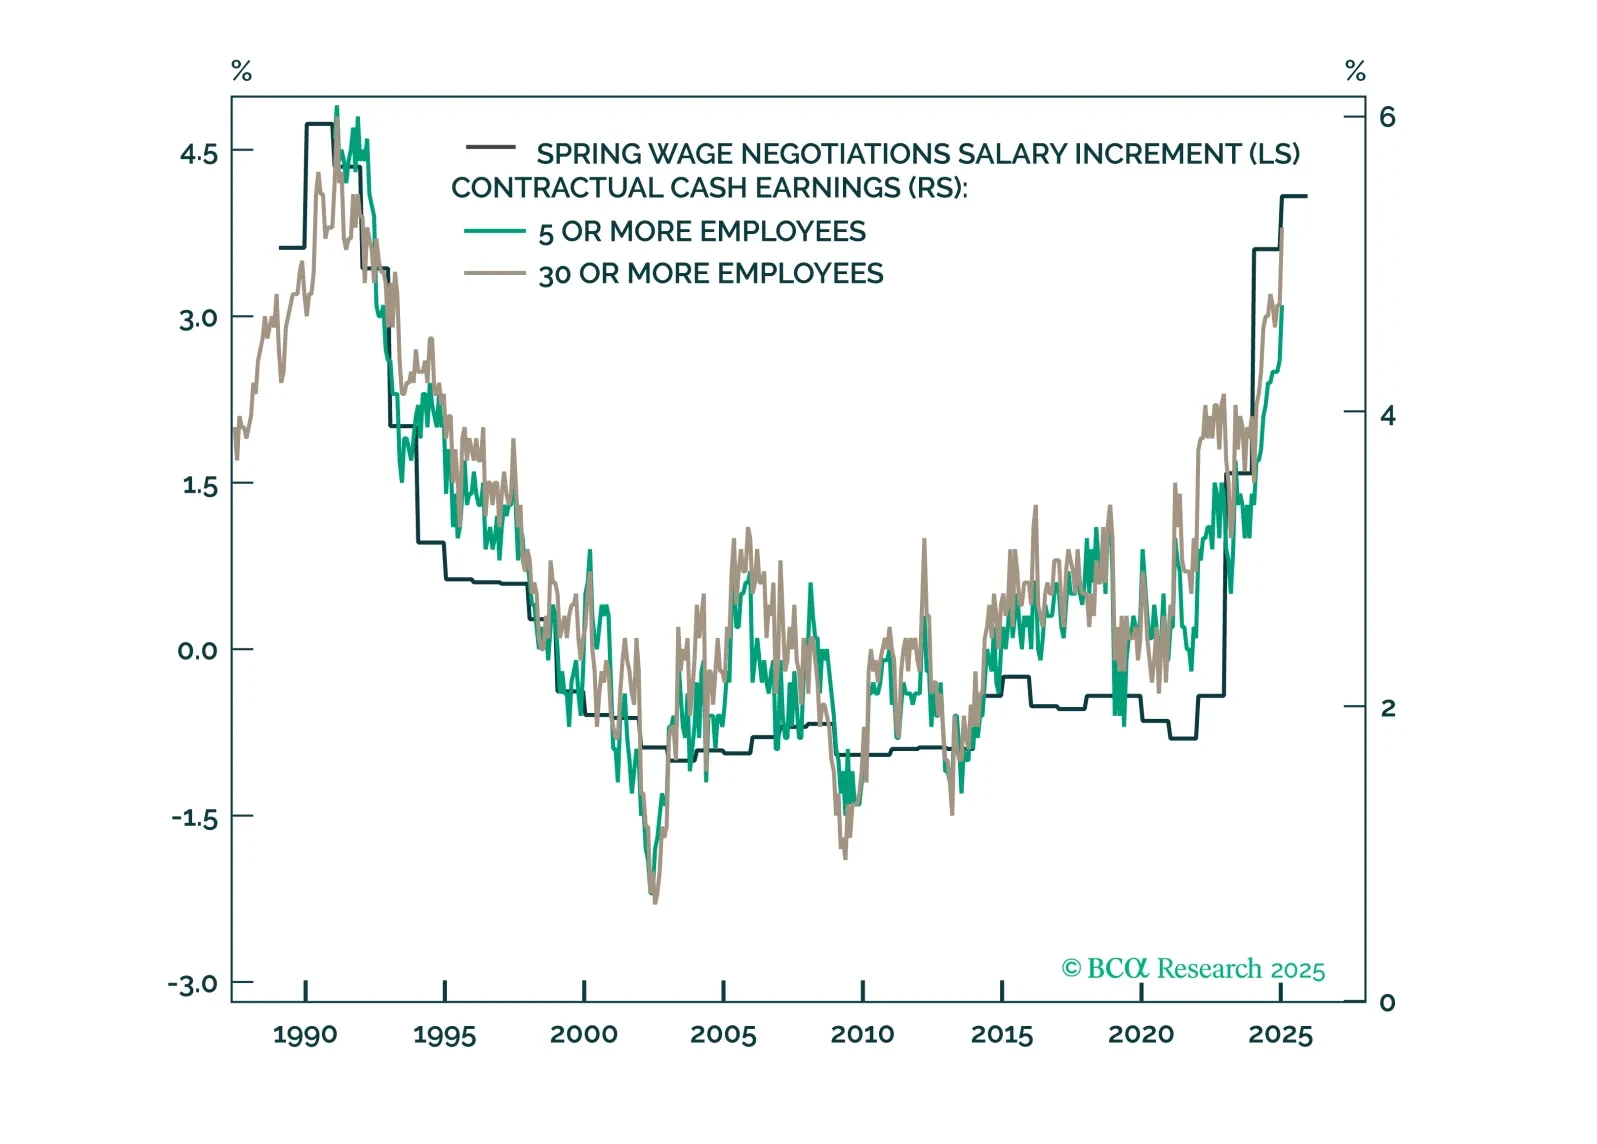
Given the meetings between the Bank of Japan, the Bank of England, and the Swiss National Bank, our highest convictions views are: Overweight UK Gilts. It is also time to sell sterling. We are short sterling, as of 1.30. Underweight JGBs. Correspondingly, be long the yen. A short CHF/JPY position remains a core holding. Selling GBP/JPY is also a great trade.